Small Cap Value Report (Wed 5 June 2024) - RFX, VP, N91, CHH. Brief: 4BB, STVG, RTC, BME, TAST, AGL, IMM

Good morning from Paul & Graham!
I've added 3 more sections to yesterday's report (ELCO, VLG , and CHG) - apologies for these being late.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
Graham and I are wondering if I've created a monster with this multi-coloured, multi-functional list?!
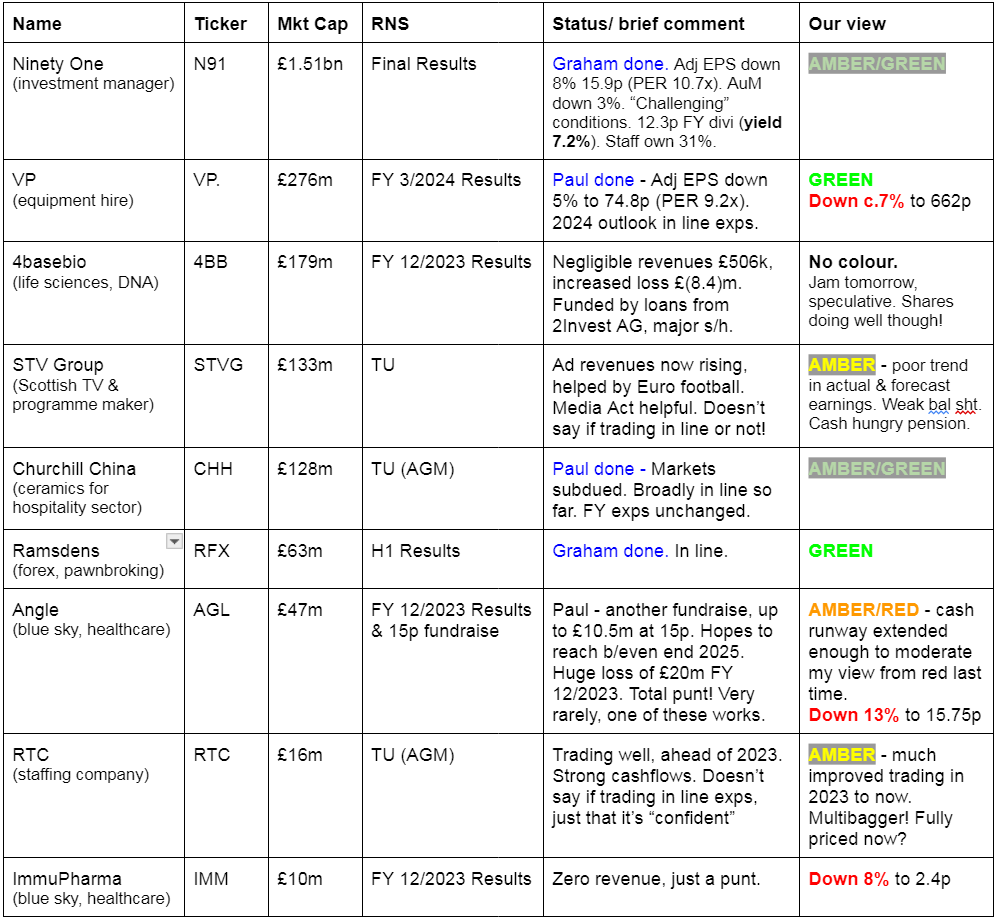
Other mid-morning movers (with news)
B&M European Value Retail SA (LON:BME) - down 6% to 513p (£5.14bn) - Negative market reaction to today’s FY 3/2024 results & outlook. Adj EPS is up 1% to 36.8p (StockReport says consensus 37.9p). Higher tax charge seems to have blunted the bigger improvement in PBT.
Excellent long-term track record. I’m not sure what disappointed the market today?
Tasty (LON:TAST) - up 29% to 1.55p (£2m) - Court approved restructuring plan yesterday. Ditches loss-making restaurants. Now has 38 sites trading, from previous 54. Mgt state that a £0.9m loss in FY 12/2023 should improve to a £1.2m profit in FY 12/2025. Interesting to see that creditors may participate in an “upside fund” if company recovers. No divis to shareholders in 2024 or 2025. Seems fair to me - creditors agreeing to a hefty haircut should get some of the potential upside too. De-listing risk must be significant at £2m mkt cap, or would the Kayes have done that by now if they intended to do so? Could be a vehicle to rebuild, try out new formats, who knows?
Summaries
Ramsdens Holdings (LON:RFX) - down 2% to 193.2p (£61m) - Interim Results - Graham - GREEN
Trading is in line at this diversified financial services provider (pawnbroking, travel money, jewellery retailing and gold purchasing). Nearly all metrics are moving in the right direction with a favourable macro backdrop and good execution of its growth strategy. At a PER of 8x, I continue to like this one.
VP (LON:VP.). - down c.3% to 670p (£269m) - FY 3/2024 Results - Paul - GREEN
Profit dropped a little, but I think that's acceptable given tough macro, also one division has needed a sort-out after disappointing. Valuation seems modest, and there's a lovely reliable 5.8% dividend yield whilst you wait for recovery in macro, and the chance of a takeover bid given the 73-year old Chairman has already indicated in 2022 that he would be amenable to a sale (he owns 50%). Shares still look cheap to me, even after a decent bounce lately.
Ninety One (LON:N91) - down 6% to 160.4p (£1.44 billion) - Final Results - Graham - AMBER/GREEN
This fund manager has been seeing large net outflows and its AuM is on the decline. However, as is often the case in this sector, profit margins remain high and the company can still afford to pay large dividends. I’d like to study this one in more detail but for now I’m happy with a moderately positive view.
Churchill China (LON:CHH) - down 4% to 1,115p (£123m) - Trading Update (AGM) - Paul - AMBER/GREEN
Broadly in line so far this year, but reckons it can hit the FY 12/2024 forecasts. Nice business, reasonably priced, and with strong balance sheet. Bid target? I think it could be.
Paul's Section
VP (LON:VP.)
Down c.3% to 670p (£269m) - FY 3/2024 Results - Paul - GREEN
Vp plc, the equipment rental specialist, today announces its audited Final Results for the year ended 31 March 2024…
Unremarkable numbers below, with adj EPS down 5.3% (although macro has been tough in the building sector) - note that the adjustments are large this year, with statutory PBT only just above breakeven at £2.8m, so I’ll have to look into those.
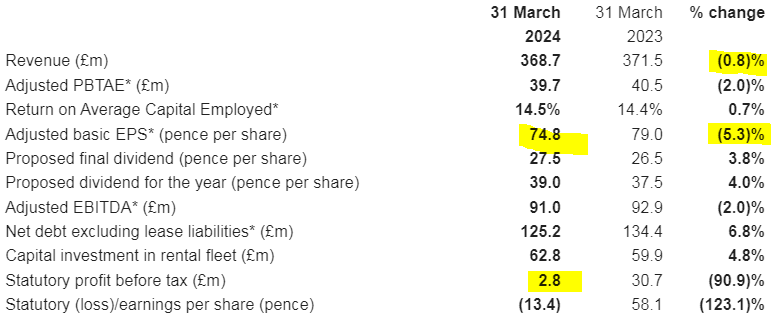
“Challenges in some end markets”
Borrowings - VP secured some really cheap private placement notes (£93m) during the zero interest rate period (kudos to management for being shrewd). We need to factor in higher finance costs when these expire & have to be replaced with more expensive funding. It also renewed the £90m RCF this year.
Owner/managed - is usually a good thing. VP is 50.3% owned by Chairman, Jeremy Pilkington. He mooted selling his stake back in 2022, but that was abandoned. He’s 73 now, so I would guess the exit here is likely to be an agreed takeover bid, with a major holder who is highly motivated to get the best price for everyone.
Dividends - are generous at just over half of earnings. 39p total divis for the year is a lovely 5.8% yield, probably capable of rising further in future years as the construction sector recovers. VP boasts a 30-year uninterrupted track record of paying divis - although there was a blip during the pandemic, but it caught up with a special divi instead of the usual pattern, which is splitting hairs -
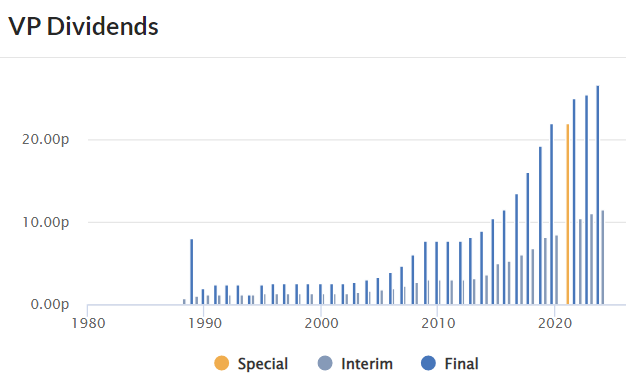
Adjustments - mainly a £27.7m impairment re Brandon Hire Station. New management in place, “starting to have a positive impact”. As a goodwill write-off, this is non-cash, so not a concern.
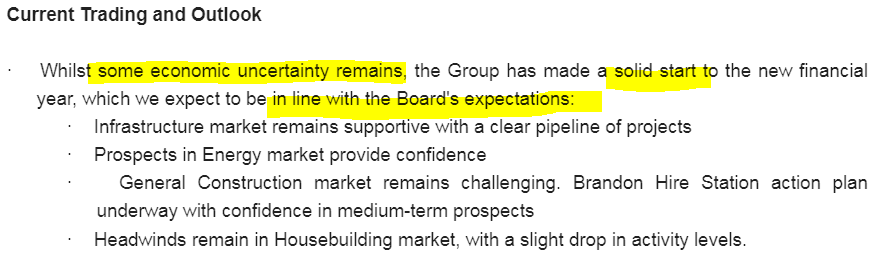
Outlook - sounds consistent with what we’re hearing from other companies, so no particular surprises here, and there’s obvious upside once general construction & housebuilding markets improve (probably in 2025) -
Audiocast - this is a nice touch. A recording of the analyst meeting will be available as an audiocast at 10:30.
Balance sheet - NAV of £153m becomes NTAV of £124m. Adequate rather than particularly strong, I would say.
Interest-bearing debt is £131m, which is 51% of its hire fleet (property plant and equipment of £257m), which feels about right to me - funding its fleet half equity, and half debt.
Everything else looks as I would expect for a hire company, including lease entries that reflect its branch network.
Cashflow statement - again, all looks as I would expect. Strong cash generation at the top, almost unchanged from the previous year. Negative working capital movements last year reversed into positive this year, which reassures me.
Hefty capex of £71m, to replace hire fleet items, partly offset by £25m sale proceeds of older items.
It paid down a bit of debt, and spent £15m on divis.
This all looks fine to me, perfectly healthy.
Paul’s opinion - I’ve always had a positive impression of VP shares. The stock market doesn’t seem to take much interest in VP, with the shares often very thinly traded, with a ridiculous quoted bid/offer spread, which has put me off from buying them on a number of occasions.
I think it would be better off as a private company, so let’s hope the 50% owner/manager can find a buyer prepared to pay a nice premium for it, that’s the most likely exit route and could be lucrative for shareholders. If it doesn’t sell, who cares, as you get a nice 5.8% dividend yield. Once construction markets improve, there should be further upside on this share as earnings are likely to rise. I much prefer the more reliable VP to riskier, accident-prone Speedy Hire (LON:SDY)
Equity Development has a modest increase in adj EPS to 75.9p for FY 3/2025, and 81.7p the following year. If construction markets are in full swing again by then, I imagine there could be upside on these fairly modestly set forecasts. I’m thinking maybe 90-100p adj EPS could be on the cards taking a say 2-year view. Put it on a PER of 10-12x and I get 900p-1200p as a share price target. Actual price today is 670p. Unless I’m missing something here, this share looks a bargain to me, for patient investors. One to go on my “buy the dips, if you’ve got any spare cash” list! It’s got to be GREEN. It was a gift at last autumn’s c.500p, but has risen a fair bit since.
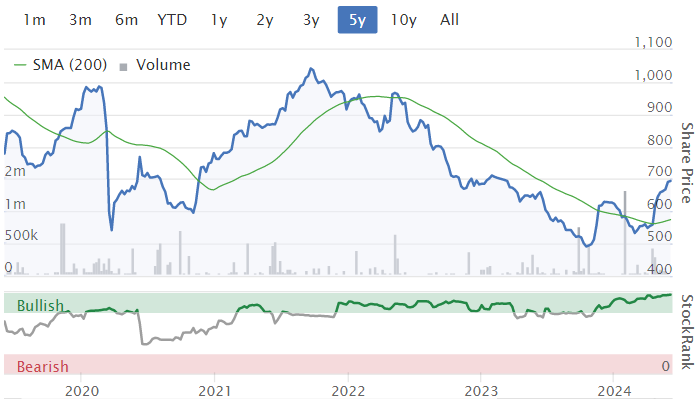
Stockopedia agrees, with a green StockRank for the last 3 years, and it’s classified as a “Super Stock” -
Churchill China (LON:CHH)
Down 4% to 1,115p (£123m) - Trading Update (AGM) - Paul - AMBER/GREEN
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide…
This is another share (same problem as VP) where the quoted bid:ask spread is ludicrously wide, putting people off trading the shares. Often the actual prices are well within the quoted spreads, so why on earth do the market makers do this? There must be a reason, but it’s unhelpful anyway.
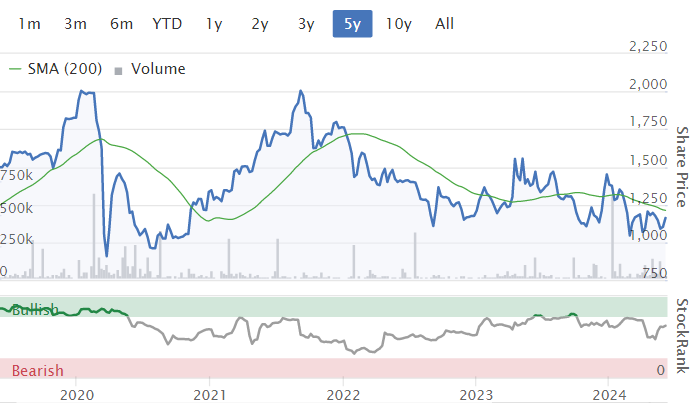
I’m surprised this share isn’t down more than 4% today, at this less than stellar update - is it glass half full, or half empty?! -
"Whilst markets remain subdued, trading remains broadly in line with management's expectations. Productivity and yield continue to improve as a result of activities in manufacturing.
The Board's expectations for the year remain unchanged."
That sounds to me like they’re a bit behind plan, but hope to recoup it later. Not the ideal situation.
No broker notes available to plankton like us!
Consensus is about 80p, for a PER of 13.9x - quite reasonable compared with the inexplicably high PERs this share historically traded at. Although I think the risk of it not achieving that number could be a little higher after today’s update.
Superb balance sheet is strongly positive I feel. This gives me comfort that there’s plenty of financial reserves in the event of anything going wrong, and we don’t have to fear dilution. Also it increases the chance of a private equity bid, because they could self-fund the bid premium using CHH’s own surplus capital. After I’ve licked clean my dinner plate in restaurants, I flip it over to see who made it. The answer is usually either Churchill China, or Steelite. Note that the latter was bought out by Arbor Investments in Dec 2019.
I was AMBER/GREEN on CHH last time, on 12/4/2024, and think I can just about hold onto that again this time.
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Down 2% to 193.2p (£61m) - Interim Results - Graham - GREEN
I’ll be chatting with management later this morning - and thanks to everyone for submitting questions to help me with that!.
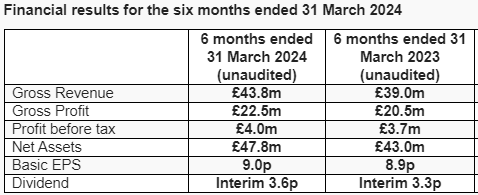
Before that, let’s quickly review the interim results to March. Many positives in the highlights:
Revenue +12% to £43.8m
PBT +8% to £4m
5 new stores bringing the total to 167. 4 additional stores are opening in H2.
Interim dividend up 9% to 3.6p.
Current trading/outlook: trading is in line with expectations. New websites launching for pawnbroking and gold buying.
CEO comment excerpt:
…We are continuing to invest in our long-term growth including opening carefully selected new stores, investing in our exceptional team, and further developing our customer proposition. This includes our new service-specific websites that will launch in the second half as well as the recently launched pre-paid travel card. These investments are ensuring that we continue to provide the best possible service to our growing customer base irrespective of which Ramsdens service they choose and through which channel they come to us…
Financial review: admin expenses grew 9%, a little slower than revenue growth of 12%. Entry level salaries were re-based in line with the increase to Real Living Wage.
Balance sheet has net assets of £47.8m (almost entirely tangible), with a net cash position of £3.8m.
FX Service: currency exchanged up 6%, gross profit up 3%. The mismatch is explained by foreign currency sales growing at a faster rate than foreign currency purchases (lower margins are earned on foreign currency sales).
Pawnbroking: loan book increases 12% to £10.8m. There is a 67% rise in the amount “past due” (from £700k to £1.2m), and RFX says this “is impacted by one customer with high value lending which had expired at the Period end”.
If this customer defaults, I’m sure that Ramsdens will be absolutely fine, but I must say I’m a little concerned that I may have underestimated the company’s exposure to high-value loans.
Jewellery retail: revenues only up 1% here, but gross profits up 6%. “The economic conditions have had an impact on our retail operations”.
Precious metals purchasing: revenues up 35%, gross profit up 25%. Some interesting comments here:
The economic conditions have positively impacted our purchase of precious metals. The gold price is higher and there has been more media coverage generating greater customer awareness of the service. This has led to the weight of gold being bought increasing.
Ramsdens has an overall “strong stock position”, and is therefore smelting a higher percentage of the gold it’s buying.
Estimates: Liberum leave their profit estimates unchanged with the proviso that H1 PBT is higher than expected, with positive implications for the full-year result. They do increase their net-cash estimate for the full year. The EPS estimate is 24p for the current financial year, rising to 25p next year.
Graham’s view: I see little reason to change my positive view on this one, as the company continues to benefit from various tailwinds including tourist demand (albeit fewer people have foreign currency to sell back to Ramsdens after their holiday), a high gold price and sturdy demand for pawnbroking loans.
I am slightly concerned about the “past due” number in the loan book.
The store expansion continues at an evolutionary pace, with the company giving itself plenty of time to see how its new stores are doing.
Valuation remains attractive:
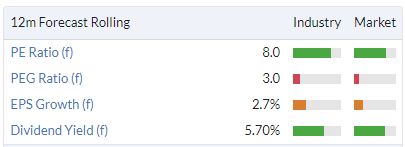
It’s true that the shares are trading at a premium to book value (market cap higher than balance sheet net assets), but this can readily justified for a company earning these sorts of returns:
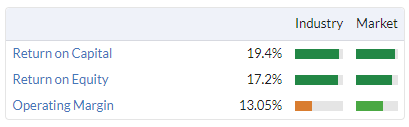
Overall, I’m happy with these interim results, and I intend to post up my notes from management Q&A for you tomorrow.
Ninety One (LON:N91)
Down 6% to 160.4p (£1.44 billion) - Final Results - Graham - AMBER/GREEN
We don’t normally cover this one, and it's a little too big for this report, but I’d like to take a look at this fund manager.
The three-year chart isn’t too encouraging. It has paid out quite chunky dividends during this period at least (over 40p in aggregate).
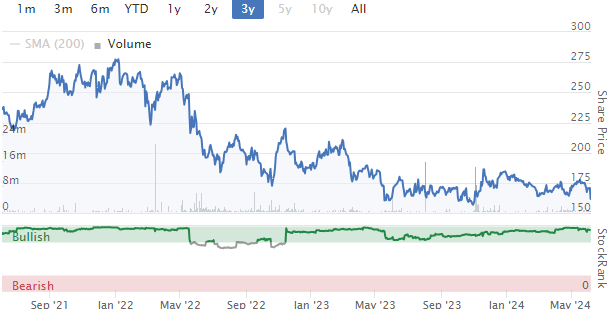
For 2024, it is distributing another 12.3p to shareholders, not quite matching the 13.2p paid out in the previous year.
Key financials:
AuM down 3% to £126 billion
Net outflows £9.4 billion, not quite as bad as £10.6 billion the previous year. However, outflows in H2 were higher than outflows in H1.
PBT up 2% to £216.8m
The 12.3p dividend is covered by earnings per share (18.4p actual, 15.9p adjusted).
Comment on the outflows:
The primary driver of net outflows was equities, particularly from global strategies, followed by European and UK equities. Notwithstanding this, there were net inflows into some of our focus areas such as sustainable and international equities. Fixed income net outflows were driven largely by emerging market sovereign strategies, which countered net inflows into inflation-linked, liquidity and income strategies…
Founder-CEO comment excerpt:
"Ninety One, and many other public-markets-centric active investment managers, faced headwinds over the reporting period. Despite these conditions, we delivered robust financial results. Looking ahead, we remain confident of the underlying strength of our business and the long-term relevance and quality of our proposition to clients….
Asset classes: equities are nearly half of AuM (£58.4 billion, down 2%), with Fixed Income in second place (£31.9 billion, down 3%).
Client locations: this is an “Anglo-South African” business, and the largest client geography is Africa (£51.3 billion, +0%). The second is the UK (£24.2 billion, down 3%).
Most AuM is from institutional clients (£80.5 billion).
Fund performance seems disappointing in the short term and medium term, only 43% of portfolios (measured by value) having a positive active return on a 3-year time horizon. However I will give the company a lot of credit for reporting in this way, instead of only reporting their performance against other funds.
Most of N91’s mutual funds (61%) are outperforming other funds on a 3-year timeframe.
Graham’s view
£1 invested in N91 stocks gives £87.50 of AuM: for me, this suggests we are looking at a cheap fund manager stock.
The value metrics were quite good last night:
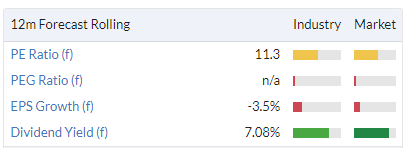
Of course the problem is that the company is currently in reverse gear, in terms of AuM and flows. It’s also going into reverse gear in terms of adjusted profits:
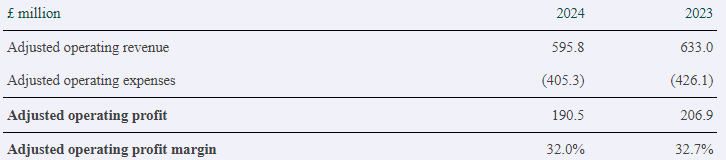
I note that even in a difficult year, the adj. operating profit margin remained very impressive at 32%. Another reminder of why I like the fund management sector: even in tough years, profit margins can be far higher than you’ll ever see in some other industries!
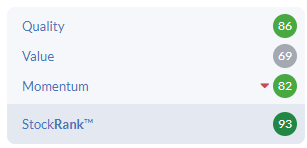
At this stage, I still need to study N91 in more detail before I can take a stronger view. But for now, I’ll take an AMBER/GREEN stance. The StocksRanks like what they see, too:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
VP (LON:VP.) - Video Presentation now available post FY Results
Anna Bielby (Chief Executive) and Keith Winstanley (CFO) of Vp plc conducted an Investor Presentation covering Final Results for the year ended 31 March 2024. The team discussed the solid overall performance despite challenges in some end markets, and the strong Return on Average Capital Employed, slightly ahead of prior year. The opportunity around both bolt on and strategic M&A across their different sectors was explored, along with ongoing digitisation to deliver enhanced procurement and cross selling. Management provided a detailed Financial and Operational review, and took investors through the different components of refreshed strategy. There was also a wide-ranging Question & Answer session at the end of the presentation.
Revolution Bars (LON:RBG)
https://www.blackpoolgazette.c...
Ninety One (LON:N91) Graham- I cannot see N91 remaining listed given the shareholder structure and reaction to recent announcements. I hold and feel it is well undervalued. So unless the div is cut dramatically looks cheap in my opinion. To be fair many fund managers do-I have bought into a few recently.
Discoverie (LON:DSCV) , reporting today, gets only intermittent interest in this site, probably because it seems a bit boring, but I hold and am happy that Nick Jefferies the CEO continues to manage company to higher ground. The use of “underlying” can be a smokescreen for unsatisfactory results but on this occasion I think correctly points in the direction of progress. Of course if the market doesn’t agree I have to accept a knock on the price. But as add—ons and disposals reposition the company I think value is building in a solid tech company which I fear will be spotted by a savvy buyer before current shareholders get sight of the full growth potential here.
Thanks for taking a look at Ninety One (LON:N91) Graham your pearls has reinforced my view that Polar Capital Holdings (LON:POLR) and Liontrust Asset Management (LON:LIO) look safer bets without the possible political issues.
Timarr's thread on Abrdn (LON:ABDN) is also interesting terrible company but looks cheap assuming someone in the building can halt the decay or the parts are split up and sold off piece meal, by all counts the db pension also has a rare 700 mil surplus they are trying to unlock to drive the business forward.
Caveat there's plenty wrong with the business so be aware but flip side it wouldn't be cheap if it was any good.
I belevie ABDN own the ii platform which must be worth a fair bit.
Hi Bowden - I reckon Abrdn (LON:ABDN) is worth more than double on a sum of the parts basis but frankly imo it has been run terribly ever since the merger.
They would be better breaking the whole thing up now in my view
List the ii platform and give shareholders an in-specie
Strip the massive db surplus out and pay to shareholders as a capital distribution / tender offer
Take the core asset mgmt business back to basics. Restructure the teams and focus on cost/income ratio and the business development side.
That would create a lot of value for shareholders I think but wont appeal to the megalomaniac empire builder………so let’s see whether the new CEO actually understands how to run an asset mgmt business.
Check out Tim's thread on this if you haven't already David he explains and understands it all way better than me.
For my two pentheth I work in wealth management and the Standard Life platform offering is poor and expensive they bought the old Elevate platform which they didn't need and ever since buying it they don't really know what to do with it.
They have recently cut platform costs so that will hit profits they are losing money on outflows faster than a piano off a cliff but there is a heck of a lot of value in there also.
Very rough top of the head figures they own 10% of Phoenix group (LON:PHNX) so must be worth 500 mil they have 300-350 mil cash (not sure if thats customers or companys money), as I mentioned theres 700 mil in db pension surplus, div yield is over 9% but not covered and they are still forecast to make 200 mil odd profit.
II platform they overpaid on but got to be worth £200-£250 million.
Just needs some major changes to stop continued value destruction or some predator to buy it sell off most of the parts and try and revamp the fund management side of things.
I have put a few long limit orders in 15-20p below current price just in case we get any summer volatility.
Regards
Andy
Insig Ai (LON:INSG) I benefitted from your post, so thanks very much Yiannos. What an absolutely splendid thing this board is!
Safestay (LON:SSTY)
Currently trading around 20p-21p.
Market Cap £13.57m.
I believe that with the new financing in place until 2029 and the repayment of the CBILS loan this has an upside to at least +30p.
Existing brokers estimates will be beaten as the group now has another two properties in its portfolio and a further management contract.
Trading at about half of its NAV , with an EBIT of approximately £3m , and an operating margin of 14% (normalising at pre Covid levels) , Safestay (LON:SSTY) seems to undervalued.
Not very liquid though.
All the best
My personal calculations of "Boon's adjusted true" TNAV (excluding fittings, fixtures, etc) for Safestay (LON:SSTY) comes out around 30p. I believe it should be trading above this, so I concur with you that 30p+ should be where this trades. I have a long writeup on why I'm invested for more details.
Definitely not liquid, and definitely not very frequent newsflow, with results delayed by 3+ months after each period end.
Execution will be key over the next few months. Edinburgh is opening on schedule it looks like.
(I hold in the Boon Fund).
Is this Chart of Lindsell Train Investment Trust (LON:LTI) correct? Why were people paying 90% above NAV in 2019?
Edit:This is from the May 2019 fact sheet. Even they were trying to talk the price down-
"Consider also this scenario: a 25% fall in LTL’s FUM on account of declining markets, underperformance or client withdrawals or a combination of all three might result in a similar 25% fall in LTL’s value. The quoted shares held by the Trust are essentially the same as those held by our clients so you might expect a similar fall in the value of the Trust’s quoted portfolio. If the Trust’s share price premium to NAV at the same time fell to zero (as it did 11 years ago when markets last fell significantly) then the resultant fall in the share price from today’s elevated level could be as much as c.60%.
In summary then we continue to caution that the shares in the Trust represent a risky investment if bought at a premium, and certainly at today’s approximate 90% premium.
Michael Lindsell, Lindsell Train Ltd"
Got to give him credit. From the moment this was written in 2019 to today the price is down 60%
Hi Wolf, yes I believe it is correct. If I remember correctly there was a frenzy around this investment trust at the time and it's long term performance. Nick Train of Lindsell Train Investment Trust (LON:LTI) even said at the time the premium to NAV was crazy and it was not a good time to buy this (his) share/fund. Covid triggered a reality check, like more recently with Scottish Mortgage Investment Trust (LON:SMT) where the price has become more realistic. I've been very casually monitoring LTI for about a year due to the discount and the yield on offer. However the heavy weighting to its biggest holding, its own management company, puts me off.
The value investor in me wonders though if their style has a return, and AUM pauses or even starts to grow again... it could be very cheap right now.
One wonders how long both Lindsell and Train will go on though, and the AUM losses when one (Train particularly) retires. James Bullock is clearly the heir apparent but will he garner the same attention?
Similar to Fundsmith really, when Terry Smith retires what will the flows there be like!
Yes, that's true CV, this is from the same fact sheet in May 2019. If its nothing more than a personality premium then what's the point, you'd certainly want a good discount of 20%+. Apart from the unlisted Lindsell Train Limited it would be easy enough to replicate the top 10 holdings yourself.
"Investors must weigh up this valuation against the obvious succession risk at Lindsell Train. Nick and I hope to be involved in the business for many years and have been taking important steps to ensure that the rest of the investment team are motivated and incentivised to take on significantly more responsibility (as they have been increasingly doing in the last five years); but, faced with the unlikely scenario that Nick or I will not be around for whatever reason, it’s clear that we have some way to go to engineer a smooth and seamless transfer of responsibilities."
Just wanted to add my 2 cents here as Lindsell Train Investment Trust (LON:LTI) is a large position for me. I think what people sometimes overlook about Lindsell Train (the fund manager in which Lindsell Train Investment Trust (LON:LTI) has the stake) is its exceptional profitability. A bit like with Fundsmith it’s a relatively large AUM managed by a small team. With the founders taking much of their return in dividends rather than purely salary / bonuses it results in high margins at LT. Compare LT with, say, Liontrust Asset Management (LON:LIO), which sometimes gets a mention on here. In its last accounts filed with Companies House I.e. the ones which have attracted comments in the press in recent days. So for the year to Jan 2024 at LT you have Net Profit of £44.6m on revenue of £86m. That’s a 52% net income margin. On AUM of £15.9bn. For the year ending March 2023 Liontrust Asset Management (LON:LIO) made £39.3m net profit on revenues of £243m and AUM of 31bn. That’s a 16% net income margin. Which one would you rather own?
Given that it’s unlisted LT is periodically valued using a formula that takes into account AUM and net profits. Given the negative trend in both (in common with most of the rest of the UK sector) this has been trending down. The latest valuation at 30 April 2024 values each LT share at £10,215.45 per share. With 26,660 LT shares outstanding that ascribes a value to LT of £272m. That’s a historic P/E of 6x. This does not factor in the £75m of cash that sits on LT’s Balance Sheet. Net asset value is £103.5m Nor the fact that LT pays a super generous dividend. Basically most of net profit is dividended out. So £39m in the last year. Lindsell Train Investment Trust (LON:LTI) owns 6,378 shares in LT or roughly 24%, which in turn represents 33% of its NAV.
I would humbly argue that at a 20% discount (slightly narrowed in recent days) is a fantastic way to play the (hopeful) eventual upturn in the UK fund management sector. You get tangible exposure to a super profitable UK AM business. In addition you get a basket of select quality compounders (many like Diageo and Unilever that are arguably trading at temporary, unfair discounts to intrinsic value). And you get paid a 6% yield whilst you wait - those generous dividends from LT are pro-rata paid to Lindsell Train Investment Trust (LON:LTI) via its 24% share.
Yes there is key person risk. Yes there is style risk. But at this level I personally think it’s an excellent punt on a mid term view. And btw the founders seem to agree. Michael and Nick have been steadily hoovering up Lindsell Train Investment Trust (LON:LTI) shares (have a look on the Director Deals tab) if you think I’m exaggerating. Presumably they see the LT value at these insanely depressed levels and believe that Lindsell Train Investment Trust (LON:LTI) is a great place to reinvest those LT dividends.
Very fair points Phil quite rightly correcting my sweeping statements, and agree at an almost 20% discount along with the other well argued positives you make it looks a decent entry.
I took a quick look at the director dealing half expecting to see selling when it was at such a high premium, but fair play to them they haven't been selling , with some decent sized buys along the way.
Not the time to be bearish at a 20% discount, tho if it got to a large premium again may be a useful sentiment indicator.
I remember this huge premium - the rationale was that the value of the unlisted asset manager (which I think made up around half of their NAV at the time) was hugely understated given its strong growth at the time. Have never held but do keep an eye on it from time to time.
Spread can be lumpy for an investment trust also Lindsell Train Investment Trust (LON:LTI)
3i
this is the only company I own with nearly 40% premium . I sold some when at a Mello meeting David said he would not want to own such a company. The chart is amazing though.
4Basebio (LON:4BB)
Hi Paul - in my view the IPR they have around synthetic dna is extremely valuable. Last years results are irrelevant - what is key is that they are now expecting some serious commercial traction over FY24 and beyond and importantly have funding runway with very supportive partners. It is a jam tomorrow stock granted but I suspect a private deal would pay much more than the current price to take the IP and manufacturing capability. Certainly when I spoke to the FD a while back about how to value said business he pointed me in the direction of a number of PE type deals that were as close a comparator as they could show given that the IP they have created is pretty unique. Those comparators suggest some serious value creation by 4Basebio (LON:4BB) management, who do also have a track record of building serious businesses in this space and selling them on at the appropriate time (check the boards history).
I think I’d argue this may have been better as a private company up until about now when commerciality takes off but am actually quite grateful it wasn’t since it meant I got to participate.
I managed to get some when they de-merged at around 200p - nowhere near what I wanted (MMs wanted a 50p above market price and stupidly, with 20/20 hindsight, I refused to pay that so I think I got a 1/4 position in the end).
Around the 1500p+ mark I may top slice just a few to lock in my original investment and a bit more but I feel as though they could have a very long way to go yet so I will run the position whilst the commercial case plays out. My best guess is they get bought by a much bigger fish within the next 3 years as the synthetic dna market takes off. (Synthetic dna has massive advantages over lab grown dna - firstly for the latter you need something akin to a football field size lab to produce it versus a much smaller normal lab for synthetic, so you can produce it for a lot less. Secondly the results of traditional dna production can be patchy - ie its not consistently replicable and thirdly synthetic dna has the benefit of no impurities (which can be fatal/toxic) and/or invalidate results). Given 4Basebio (LON:4BB) are a global leader on this synthetic dna production and now have it being used by some serious partners my personal opinion is that this is a prize asset for someone.
Wouldn’t surprise me if they raised £20m equity if they get to a £200m valuation but management and shareholders appear fiercely protective of any dilution which I love to see. They always said they would only raise equity if the valuation was supportive so of course I am guessing at the £200m mark and might be completely wrong - but 10% dilution to give them a very long runway feels like it may be acceptable.
Highly illiquid stock - its almost a private vehicle with a facility to trade so daily volumes are very small and tightly held.
IMC meeting scheduled for 2nd July I think
Hi Paul, thanks for the write-up on VP (LON:VP.) today. I was looking hard at it last October/ November when it was around the 500p mark, but held-off as I was uncertain the low was in. Hindsight suggests it was the ideal buy point! I do agree with your assessment that there is a lot to like here.
Could I ask regarding your comment regarding the impairment where you say, "As a goodwill write-off, this is non-cash, so not a concern."
The business was bought in 2018 (after CMA clearance) for £41.6m cash & assumed net debt of £27.2m. The write-off today of £27.7m reflects 67% of the cash purchase price and 40% of the EV purchase price. I find the update today a little light on detail on what has gone wrong, why and how it led to such a large write-off. Has the business been mis-managed? Has another competitor eaten its lunch? How could so much value disappear in just one year? Replacing management is an easy answer, but I would want more detail. What has been learnt from this whole saga? How will it be avoided in future?
£27.7m of real shareholders money was spent on this acquisition 6 years ago and this is a nasty write-down and I would have more scrutiny of it if I held.
Thanks for the coverage of VP (LON:VP.) Paul. Another of my December cyclical basket that mostly haven’t disappointed (apart from Topps Tiles and US solar plays where it seems patience will be required)
RTC (LON:RTC) The Agm statement today sounds very positive. There are no forecasts so one can only compare to last year which in itself was a record year.
The last interims they moved from a loss per share to 5.2p positive and this statement suggests at least 6p with the second half from July always even better. I predict eps at least 14.5p (12.7p in ‘23) for the current year and the order book is growing.
They are about to pay a 4.5p final dividend for 2023 which added to the interim payment gives 5.5p so this year including an increase it should be around 7p overall and not to be sniffed at. The Agm is in Derby at noon if anyone is attending.
Love the new Comment/Status/View section at the top of the report. Really neat, simple format.
GETB (Getbusy) I hold. Paul last looked at it on April 23 (Amber). It has come up on my radar that Daniel Rabie CEO / Director has bought over the last couple of weeks over £380,000 worth of shares. It's a small cap of £35 million, debt free with 1.9 million in the bank. Audited accounts in March see below.
Financial highlights
· Recurring revenue growth of 12% at constant currency to £20.3m (2022: £18.3m)
· Recurring revenue comprises 96% of total revenues (2022: 95%)
· ARR growth of 10% at constant currency to £20.5m (2022: £19.2m)
· Gross margin improvement to 90.1% (2022: 89.9%)
· Adjusted EBITDA up 51% to £1.1m (2022: £0.7m)
· Cash of £1.9m (2022: £3.0m) remains strong, underpinned by an undrawn committed £2.0m facility giving a total of £3.9m available growth capital.
GETB Bought in April SmartPath LLC, which is a pricing intelligence and revenue optimisation platform for the accounting industry. Given such a substantial amount of director buying, I was wondering if something might be happening. It is fairly illiquid, but there have been some biggish buys over the last few days.
I was hoping that Paul or Graham might have time to give us their thoughts on this one. - Thank you.
For what its worth: - We have GetBusy - Virtual Cabinet software in use at work, its pretty decent compared to the alternatives. Its plugged in as an add on to the OpenGI Broker system which is how we came across it and - OGI now have their own similar product which they recommend instead. However we would not change from one to the other and personally the support + ease of use means I would be very unlikely to recommend a change to an OGI product ! That said I am now sure how the pricing compares if you have a large number of users.
STV (LON:STVG) has released a trading update today. I was alerted to this opportunity in an interview with Richard Staveley of Rockwood Strategic (LON:RKW), Mark Slater is also a big holder (20%)
It is the number one broadcaster in Scotland and advertising seems to be picking up and is expected to be up 15-20% in Q2, due to the Euros.
They have STV player, which does roughly £10million of sales and £5million profit - a 50% margin!
The production unit seems to be winning lots of new deals recently with the likes of Netflix, BBC, Warner Bros Discovery and Sky. The secured order book for studio revenues is currently £86m
Their productions include Criminal Record, Blue Lights, The Victim, Bridge of Lies, Catchphrase, Antique Road Trip, Murder Island. etc.
They do have a pension deficit and net debt is fairly high still.
Nice bowl on the chart!
I've always thought that ITV (LON:ITV) would take them over, although I've always thought that ITV (LON:ITV) would also be taken over, so what do I know.
All that is true. But they are also a price taker from ITV - ITV pays for the drama production, Ant & Dec etc and STV has to pick up its share of the tab. Thus ITV is the only likely purchaser. And they're not buying!
I understood that the excellent "Blue Lights" was made by STV. BBC runs that one.
Morning does any one have experience with Open offer ? Superdry (LON:SDRY)- I only have a small holding - thank you
Just wondered if any chance of Paul or Graham having a look over Ninety One (LON:N91) i believe they are part of Investec and South African based. Yield over 7% which is covered, Stocko shows billions of net cash but presumably this is actually investor/policyholders funds not the companies ?
Operating margin north of 25% and Stocko showing forecast profit of £137 mil for March 2025 which looks decent against market cap of £1.5 billion.
Numbers of shares in issue declining (all be it slowly), I already hold Polar Capital Holdings (LON:POLR) and Liontrust Asset Management (LON:LIO) at the moment so not really looking to add a third fund manager but I do think there's going to be value in this area when/if fund flows reverse but I don't think Ninety One (LON:N91) has been looked at often on the SCVR.
Obviously if anyone else has any comments on top of the two big guns, that would be welcome.
Regards
Andy
Status/brief comment box above for Ninety One (LON:N91) states that staff own 31% but I see that the director H. J. Du Toit, founder and CEO, has been making numerous additional purchases and his holding alone is now 33%!
Phoenix Andy, Investec Asset Management was previously a subsidiary of Investec Group but there was a demerger and listing of Ninety One from Investec Group in March 2020. Investec own 15%.
Freight rates now 10k a container .
Freight rates are now 10k a container from China with shortages of actual containers .
That’s going to be a direct hit to importers shipping low value bulky items .
50k ysd in a container , So 40k sterling , increase is 20%
So maybe 10-20% increase in landed cost .
Going to expose a few importers who can’t raise prices .
Not likely to drop and zero incentive for the shipping lines to do anything other than bank the profits .
Why are prices up so much? Does this mean that China is shipping a lot more?
I assume it does not mean there are fewer boats.
some due to shipping avoiding the Red Sea, I cannot believe this is all of it though. The shipping volumes are graphed at some key locations, this is the southern entrance to the Red Sea
left it too late to edit the last post, but I notice that Panama canal crossing are also lower, and when I look into it there seems to be restrictions on the Panama canal crossings due to local droughts. So this is two main choke points that are having problems.
I sense... a potential big increase in inflation coming again?
Instead of being demand-driven for shipping, this time it looks like supply-driven (ie each shipment taking longer = tying up capacity, extra fuel and labour costs).
Hi planetX,
Freight rates now 10k a container .
Freight rates are now 10k a container from China with shortages of actual containers .
Where can I read about it? tia
I received a notification from my forwarder , I’ll try to dig out the email .
FEWB MARKET UPDATE
04 JUNE 2024
FAR EAST WEST BOUND RATES SPIKING
Further to our May 13th update, the situation in Asia continues to deteriorate.
Demand is outstripping supply causing ocean rates to surge and space on vessels sailing towards Europe is becoming even scarcer.
This problem is compounded further with a lack of empty 40ft High Cube containers, particularly in Northern China.
Industry analysts are predicting ocean freight rates for a 40ft to reach $10,000 by July, although this is only a prediction, we are seeing all carriers increase their rates on an almost daily basis now.
Today ALL carriers are >100% booked and therefore rolling containers, with various carriers confirming they already have roll pools in excess of 5000 containers.
With the surge in demand and the roll over containers this is compounding the problem further as the main gateway ports are becoming overwhelmed, with vessel berthing times increasing further and effecting schedule reliability.
There is no doubt that these issues are not going to be resolved in the short term and we would continue to encourage all of our customers to book as far ahead as possible, with a minimum of 4 weeks notice.
Future Forwarding will do everything we can to mitigate the problems and delays, but please understand this is an industry problem beyond our control.
We will continue to keep you informed with any developments and once again, thank you for your continued support.
With kind regards
Future Forwarding Co. Ltd
FAR EAST WEST BOUND RATES SPIKING
Thanks planetx. Supply side inflation spike later in the year then.
Surprised ARB is not down more on these numbers (I am short).
I had modelled a best case scenario of $5.6 million, and based this on 3 EH/s (the company has 2.7 EH/s) and an average of $60 hashrate (the hashrate was well below $60 for the month of May).
Even at those numbers the company isn't capable of operating without the begging bowl, and revenue for May was $2.9 million. It's entirely possible I've missed something so certainly open to hearing it.
Argo Blockchain (LON:ARB) Remember the bloke in the Kevin Keegan wig and sunglasses on YouTube/twitter loving this
Didnt he interview management dressed up? Peak froth territory.
Ah yes, Funky Finance! He disappeared as quickly as he came about.
I'm short as well. Patience required I think, it does have weird rallies every now and then. Surely a 0 in time. Investors wont recapitalise it again will they?!? Surely not.
Bitcoin's up today!The US based miners aren't following btc's moves as much as they used to i think due to the halving thing.Microstrategy is my play for bitcoin and tends to trade at a range of premia to btc's price.Boom or bust there!But i do want the extra potential leverage here.Hoping for a stock split sometime too.Whether that will be good for increased retail interest/demand, neutral.. or the opposite, no idea!ButTesla did well after their splits and btc is surely in a bull market (currently).
Splits often do well because people anchor the newly split price to the old price and tend to buy thinking it's cheap!
Hi SD,
Microstrategy is my btc proxy too, together with Cleanspark in the miner realm. I follow Invest Answers on YouTube, who seams to have a thorough knowledge of the crypto world. Check him out, if you haven’t already.
VP (LON:VP.)
I have a modest holding based on my view that this is the best of the 'hire' companies, notwithstanding the difficulties at its subsidiary Brandon Hire and non cash impairment announced this morning. The reasons for my view are the breadth of the company's operations spanning oil and gas, rail, water and even IT. Techrentals its Australia subsidiary specialises in test equipment, communications and audio visual.
The housebuilding and construction orientated divisions are finding life challenging at present but at some point these end markets will recover, in the meantime activity in infrastructure remains buoyant and offsets the former.
Whichever party wins the general election spending on infrastructure (rail, road and especially water) will in my view continue and the political incentive to improve house building should revive the fortunes of the Groundforce and UK Forks divisions.
I will wait to see what Paul makes of the various adjustments in this mornings prelims.
I would add that the share is very illiquid and the price bounces around like a rubber ball, not helped by the fact that the founder and Chairman, Jeremy Pilkington holds 50% of the equity. However to my knowledge he has not made any significant sales and is, it appears open to selling the company, if an acceptable offer is forthcoming, as evidenced by the fact that the company was offered for sale previously but was subsequently withdrawn.
WH Smith (LON:SMWH) I like at these levels. Similar to Pets at Home (LON:PETS) in terms of secular growth prospects and remarkably closely valued on most metrics other than FCF, where the former is pricier but expected to see the greater improvement. Which, given the depressing effect of the CMA investigation into the latter, suggests an undervaluation. Debt is higher than ideal but strip out leases and borrowings look more manageable. Good, rising and well-covered dividend. Absent another pandemic, this might be a good entry into a long term proven travel stock that does not bring the same cyclical volatility as airlines and holiday companies. My fair value is north of £16, some 40% higher - not that I would want to sell at that level, all else being equal, as earnings ought to compound from there. I completed my position following this morning’s TU.
Angle (LON:AGL) - as usual with this management team, plenty of talk about activity, much less talk about hard revenues (and costs). Shareholders continue to need very strong binoculars to see profitability. "Cashflow breakeven on a monthly basis by the end of 2025".
Angle (LON:AGL)
grumpy5
I’m a holder and am very disappointed another fundraise is necessary – but it does seem to have been a fairly close run thing. The offer price is better than many would have expected and there does seem to be support. I think I’m looking through the correct end of my binoculars when I quote from the results :
Revenues for the full year more than doubled to £2.2 million (2022: £ 1.0 million)
Revenue for H1 2024 is expected to be between £1.0 million and £1.3 million with a total of c.40% of FY24 market expectations for revenue already contracted year to date.
Current consensus revenue is £6.45m for FY24. (Source: Bloomberg)
I’m sure they wouldn’t accept a tripling of revenue forecast unless they were pretty confident. Also, I’d expect several new contracts with large pharmas to be announced in the near future.
Digits crossed.
Jim McLad, Angle (LON:AGL) I am a v small holder, having sold down a while back. I agree with your expectations, but Newland & Co have been guilty of over-optimism in the past. They seem to have been economical in the past with what cost base was necessary to get to viable levels of revenues.
Berenberg upgrades Future
Berenberg has upgraded media group Future (LON:FUTR) as the ‘overhangs’ it faces are ‘clearing up’.
Analyst William Larwood upgraded his recommendation from ‘hold’ to ‘buy’ and increased the target price from 850p to £13.10 on the Citywire Elite Companies + rated media company, owner of Marie Claire and a number of more specialist titles, which gained 1.3% to £11.14 yesterday.
Positive first-half results indicated that ‘its organic growth has troughed’ and Larwood noted the ‘positive commentary from its US peers regarding first quarter advertising trends, Google’s decision to delay third-party cookie deprecation, and evidence that artificial intelligence (AI)-enabled search will likely benefit market leaders.’
‘With improved clarity on these perceived overhangs, we remove our discount to our fair value estimate and our price target increases to £13.10,’ said Larwood.
‘The shares trade on a full-year 2024 price to earnings of 9 times, which we think is attractive given that we could be at the start of an upgrade cycle and bearing in mind chief executive Jon Steinberg’s comments regarding portfolio optimisation.’
Insig Ai (LON:INSG)
Very interesting new shareholder here.
All the best
Insig Ai (LON:INSG) on a PSR of 7! Sucker Stock says Stockopedia.
Why is it so richly valued?
By who? Some users like to buy sucker stocks, good luck to them but I don't have the capital spare to waste on punts.
Insig Ai (LON:INSG)
Nathaniel Rothschild and John Wilson are not famous for being shareholders in sucker stocks!
Anyway I have shared this last week as well that some interesting people are buying this stock.
All the best
Cool. Will put it on the watch list and dig a bit deeper.
Insig Ai (LON:INSG)
Who dat?
Insig Ai (LON:INSG) Nat Rothschild
Interesting discussion yesterday re raising funds from a portfolio started by PlanetX.
Institutions have money in/out every day..... but it's only when the flows are meaningful ie approaching 10% this becomes important. The easiest thing to do is add/take the funds proportionally to/from every position and trade the entire list as a block. An institution would get a good deal for trading like this. Obviously you remove anything from the list that has immediate catalysts etc.... but I would say in general reactions to results are somewhat random so you have to be careful what you define as a catalyst. It would be fair to keep a stock trading below a cash bid for example. The danger of removing shares you think are a little overbought/oversold is you just dilute your positioning. Clearly for smaller flows, the timing may just suit as you were about to get shut of something anyway.... or feel like some surgery was necessary. If you over raise or under invest you are simply diluting returns.
These trades are particularly important in directional markets with net inflow outflows.... so as the money keeps coming in its the same stocks rising every day as the popular stocks that are widely owned receive disproportionate flow. Hence momentum works mainly in your favour but not the last couple of years when everyone exited the UK. If the direction is down and the flows are out then its the reverse....which is why it's often the shares that rose the most that fall when the tide turns.
Chemring (LON:CHG) being quoted in the news today:
The firm wants sales, which are already hovering around record levels, to quadruple to nearly £1bn by 2030.
“The increase in geo-political tensions around the world is driving a fundamental rearmament upcycle which is expected to last for at least the next decade,” said Chemring chief executive Michael Ord.
Full article here.
Great if you are a shareholder. Not so great if you are in one of those conflict zones.
The BBC is not covering itself in glory here. Sales would double not quadruple if Chemring (LON:CHG) reached c £1bn of revenues in 2030. (Can't compare interim figures for 1H24 with a full year forecast for 2030.)
As a holder of CHG I'm not keen on setting a revenue aspiration without pairing it with a profits, return on capital and/or cash generation target because of the risk that the management makes an investment with a low return in order to meet the revenue target.
CHG's current investments look like very attractive capital deployment -- investing a net £110m (£200m gross less £90m grant funding) to earn forecast incremental profits of £30m in 2028 -- but the usual cliches about being careful what you measure still apply.
I asked about the setting of a long term target focusing on revenues only on the call yesterday, but it wasn't put to management by the IR team who were monitoring online questions.
Bloomsbury Publishing (LON:BMY)
There were a large number of comments here on both of two recent statements. This is a reminder that they are presenting at noon today on IMC and you can ask questions.
Home - InvestorMeetCompany
My morning smallcap tweet: Crash runway
Angle (LON:AGL) Roadside Real Estate (LON:ROAD) Insig Ai (LON:INSG) Churchill China (LON:CHH) STV (LON:STVG), Ramsdens Holdings (LON:RFX), RTC (LON:RTC)
◄Angle (AGL)► £8.5m placing + £2m OO at 15p, a 17% discount, for its commercialisation plan and working cap. In April 2023 it said the cash runway ran into H2 2024. Well I suppose it did, only to need another placing. Fundraise.has allowed it to publish FY-Dec. Guides H1-June rev £1-1.3m. [SP=18 Cap=47m]
◄Roadside Real Estate (ROAD)► its Cambridge Sleep Sciences division gets second purchase order from Mammoth giving £100k royalties. [SP=11.9 Cap=17m]
◄Insig AI (INSG)► £0.8m subscription at 12.5p, a 2% discount, for sales and marketing and working cap. [SP=12.92 Cap=14m]
◄Churchill China (CHH)► AGM stmt - "trading remains broadly in line with management's expectations. Productivity and yield continue to improve." FY exp unchanged. [SP=1166 Cap=128m]
◄STV (STVG)► guides H1 Total Advertising Revenue up 10-12%, driven by Euro 2024. Co "remains on track to deliver its ambitious growth plans out to 2026". [SP=283 Cap=132m]
In line: RFX, RTC
VP (LON:VP.) - Vp’s FY’24 results confirm a solid performance and an impressively resilient outturn on all key financial metrics. Revenue and adjusted profits are a shade below the prior year, whilst return on average capital employed, the final dividend and year-end net debt all show a year-on-year improvement. The results are in line with our expectations and are, once again, sector-leading.
We nudge our Fair Value estimate up from 1090p to 1110p. We see attractions in a 5.6% dividend yield and significant scope for earnings growth over the medium term as management initiatives take effect and, ultimately, market recovery takes hold.
Vp’s shares have performed well in recent months (+c.30%) alongside improving sentiment towards UK-focused shares. Despite this, the shares remain attractively valued and trade at a discount to the immediate peer group. In our view, Vp’s consistent outperformance of sector peers and long-term track record of earnings and dividend growth warrant a premium rating.
Link to research: https://www.equitydevelopment....