Small Cap Value Report (Wed 6 April 2022) - SOS, AVON, MOTR, EPWN

Good morning! It's Paul & Jack here for Wednesday's SCVR.
StockSlam - I was really sorry to hear that tonight's StockSlam (register here) is to be the last for a while, due to lack of interest from private investors. What a great contrarian signal though! People were queuing up to enthusiastically talk about their favourite shares last year when they were over-priced, but now many shares have dropped in price by half, or more, people are in hiding! In my experience, when investor sentiment is this negative, it lays the groundwork for excellent future gains. Remember BLASH (buy low, and sell high) - easier said than done of course.
Director buying - something I've noticed of late, is that lots of smaller caps are putting in strong rebounds, often after some Director buying. There have been lots of examples recently. Just yesterday, Victorian Plumbing (LON:VIC) (which is on my watch list) shot up about 17%, after a Director bought a decent amount of shares. It was immaterial to his total holding, but seemed to trigger a stampede of buying from other investors. I reckon this is a nice theme right now, and worth taking note of. Buying on the opening bell, after a big Director buy, could be lucrative, either as a trigger for a possible turning point, or just for a short term trade, whatever floats your boat & makes money! So it's worth scrutinising the RNS for Director buys right now, as they seem particularly price-sensitive, more so than usual I think.
Agenda -
Paul's Section:
Sosandar (LON:SOS) - a cracking trading update, ahead of expectations, moving into EBITDA profits in H2. Plenty of cash, so another fundraise looks unlikely. I think this is looking very good as a long-term hold.
Motorpoint (LON:MOTR) (I hold) - an in line update for FY 3/2022. This car dealer is differentiated, in operating online, and from physical car supermarket sites, selling nearly new cars only. Fwd PER pf 12 looks cheap, considering its ambitious expansion strategy.
Jack's section:
Avon Protection (LON:AVON) - another hit to investor confidence with a profit warning today as a result of weaker sales mix and increased manufacturing costs. The Ukraine conflict is leading to more customer enquiries, which could boost FY23, but FY22 will likely come in below expectations. I view the shares as uninvestable right now. Where’s the director buying? Management was happy to commit company funds to a buyback ahead of today’s update.
Epwin (LON:EPWN) - record revenue and adjusted EPS slightly ahead of Stocko’s consensus normalised expectations. Epwin qualifies for the Free Cash Flow Cows screen and the valuation is undemanding. It appears to be winning market share and investing in growth opportunities and, while inflation is a concern, the outlook seems fairly positive.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Sosandar (LON:SOS) (I’m not currently holding)
24p (yesterday’s close)
Market cap £53m
Trading Update (and new third party arrangements)
For full disclosure, I don’t currently hold SOS. It was held in a spread bet account, but unfortunately the account plummeted in the big market sell-off triggered by the invasion of Ukraine, which meant I had no option but to close lots of positions. Disappointing, but there we go, it’s my own fault.
This update looks good today -
Sosandar, the online women's fashion brand, is delighted to provide the following trading update for its financial year ended 31 March 2022. FY22 ahead of market expectations. Revenue +138% yoy and every month EBITDA positive in H2…
… it now anticipates reporting revenue and EBITDA for the full year ended 31 March 2022 ("FY22") ahead of recently upgraded market expectations*.
*Prior to the release of this announcement Sosandar believes that current market expectations:
(i) for the year ended 31 March 2022 are revenue of £27.1 million and an EBITDA loss of £0.9 million
(ii) for the year ending 31 March 2023 are revenue of £38.5 million and EBITDA of £1.7 million
(iii) for the year ending 31 March 2024 are revenue of £52.5 million EBITDA of £2.6 million.
That’s seriously strong revenue growth, well into triple digits, you don’t see that very often. All organic too.
EBITDA is very similar to profits at this company, so I don’t understand why they always report EBITDA, which a lot of private investors (rightly) are suspicious of.
EBITDA in H1 was £(1.0)m negative, so moving into positive EBITDA in H2 is encouraging.
Actual revenue for FY 3/2022 is £29.0m, well ahead of £27.1m forecast noted above in a helpful footnote (above).
The FY 3/2022 EBITDA loss is c.£(0.6)m (down c.80% on LY). That implies a £0.4m positive EBITDA in H2. It’s great to see the company break through into profitability - many investors didn’t think it would happen, but it has.
Also noteworthy, is that many online fashion retailers saw terrific growth in the pandemic, which then stalled. Sosandar has continued very strong growth, so there’s something very good happening here - the brand is clearly gaining strong traction with customers, and taking market share.
Net cash of £7.0m at 31 March 2022 looks healthy. The last fundraise was in May 2021, and it’s increasingly looking as if no further fundraising will be required.
Supply chain - as mentioned by the company before, it seems to have managed this well, and margin gains (from placing larger orders with suppliers) have offset other cost increases. The gross margin of 56% is strong, and much improved.
Third party sales - the key partners for Sosandar seem to be M&S, Next, and John Lewis, as we already knew. The relationship with Next is obviously going well, as it’s being extended to include “Platform Plus” -
'Platform Plus' allows Next customers to order items picked from Sosandar's own warehouse, which are then delivered via Next's distribution network. This agreement builds on the success of Sosandar's existing relationship with Next, which has gone from strength to strength since it was established 18 months ago. Sosandar will launch its new activity with Next Platform Plus during Q1 FY23, allowing for an extended Sosandar product range made available to Next customers and accelerating Sosandar's sales.
Popular website “Very” has approached Sosandar to buy SOS products, commenced in Mar 2022 - good news that should help drive growth - which is doing well -
… with strong sales and quick repeat orders being placed.
My opinion - another superb update from Sosandar. This share now looks largely de-risked, in terms of solvency.
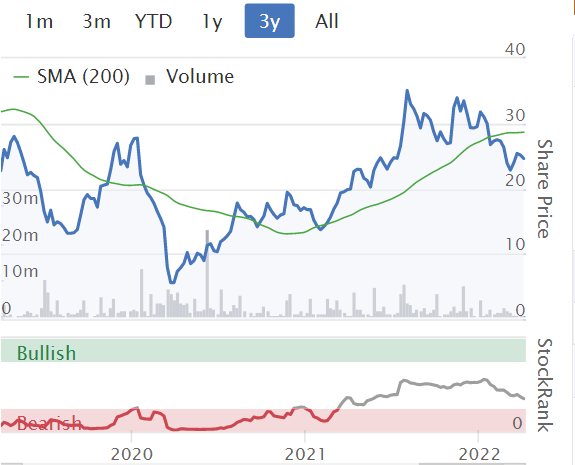
How do you value it? PER isn’t appropriate, given the extremely rapid growth (which is bound to moderate in % terms). Given the stellar growth, and move into (modest) profits, I think a £53m market cap looks undemanding. Sosandar looks set to grow into a much bigger business, and is now a really credible, differentiated brand. This could be a multibagger long term from here, in my opinion, providing nothing goes wrong. In a bull market, I could see this being a £100m+ share.
.
.
Motorpoint (LON:MOTR) (I hold)
265p (down 2% at 09:19)
Market cap £239m
Year End Trading & Strategy Update
Motorpoint Group PLC, the UK's leading independent omnichannel vehicle retailer, provides the following update on its performance for the full year ended 31 March 2022 ("FY22").
Revenue growth of +82% vs LY (last year) is strikingly good.
Grown market share of nearly new cars market to 3.0% vs 2.6% LY - impressive considering all the me-too internet-only competitors (e.g. Cazoo, Cinch, and others)
Higher spending on growth initiatives, but despite that -
… the Group anticipates reporting Operating Profit and Profit Before Tax for the year in line with the Board's expectations.
Strategy update - is reiterated, “making good progress”.
The plan is to accelerate growth, and reach >£2bn sales “in the medium term”, through increasing online sales to half the total, and opening 12 new branches (car supermarkets)
Outlook - sounds cautious, but we’re hearing similar caution from other car dealers too -
The impact of rising inflation and worldwide vehicle supply challenges is likely to affect our markets and our company performance, but its extent is difficult to predict in the short term. However, we expect rising inflation will place further pressure on discretionary spending power and consumer sentiment. In this uncertain environment Motorpoint will continue to invest in revenue and market share growth, in strategic future capabilities and in providing an exceptional omnichannel customer experience.
"Despite the uncertain consumer outlook, the Group's continuing confidence allows it to invest in its future growth strategies across multiple initiatives. The expansion of our technology team dramatically increases our capability to innovate and scale our Motorpoint.co.uk and Auction4Cars.com platforms which both have huge future growth potential.
My opinion - I think MOTR has an excellent business model, combining a successful online business, with a physical car supermarket business. Most people want to see & test a car before buying. So online-only business models strike me as fundamentally flawed. MOTR seems much better, combining online with large physical sites in cheap, out of town locations.
I wonder which online-only competitor could go bust first, once they’ve burned through all the private equity or VC cash provided for saturation marketing (which generates a tiny conversion rate apparently)?
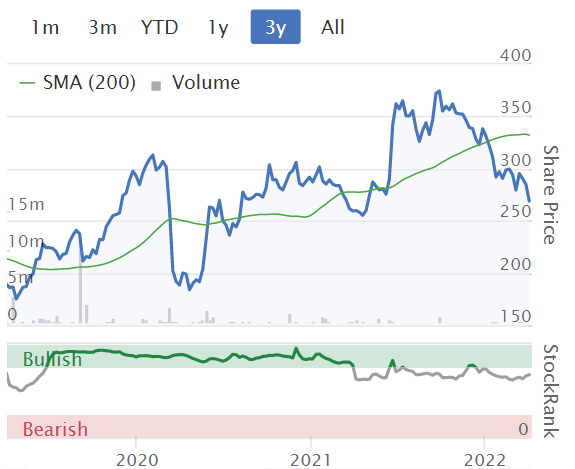
Stockopedia shows the forward PER as only 12.0, which strikes me as good value for a company which is growing fast. Recent data from the trade body SMMT, shows there are still serious supply constraints for new cars, thus secondhand values (and high margins) could continue for some time.
.
.
Jack's section
Avon Protection (LON:AVON)
Share price: 1,056p (-20.12%)
Shares in issue: 30,449,775
Market cap: £321.5m
Half year trading update for the six months to 31 March 2022
Stockopedia has Avon aptly classified as a Falling Star. This formerly well-regarded stock shocked the market with news of its poorly performing recently acquired armor business line which, in my view, calls into question the company’s due diligence procedures, capital allocation policies, and transparency with the market.
The collapse in share price suggests to me that a sense of loss of trust is shared by others. The company has since been buying back stock, but in light of today’s update, that only casts further doubt on the group’s capital allocation abilities, and I note that directors haven’t been so generous or confident with their own money.

Trading in the first half reflects a continuation of some of the challenges seen in FY21, but with performance accelerating through the second quarter.
In light of recent developments, I’m taking talk of an improving Q2 with more than a pinch of salt.
Revenue for the Period was in line with expectations and ahead overall by c. 4%, with organic year-on-year performance broadly flat… Profitability has however been impacted, in broadly even proportions, by a weaker than expected sales mix in the first half and additional manufacturing costs, notably in the helmets business, due to supply chain and process inefficiencies. As a result, the adjusted EBITDA margin for the period is expected to be approximately 10%.
Another profit warning, then.
Progress has been made on the implementation of a $15m overhead cost saving programme (half of which relates to the armor business and half to the rest of the group). Regarding the armor business:
In the period, as expected, armor revenues were in the low single digit $m pending final sign-off of first article testing of the DLA ESAPI body armor product. Combined with overheads, this business therefore operated at an EBITDA loss in the first half. We have continued with our steps for an orderly exit of this business once existing contracts are satisfied.
Avon was awarded the US DLA contract for the second-generation Advanced Combat Helmet in February and delivered the next-generation Integrated Head Protection System for first article test, scheduled for Q3. So the business hasn’t totally stopped in its tracks, some parts are still performing and armor is a small part of group revenue.
Outlook
Ukraine is resulting in an uptick in customer enquiry activity, although the benefits of this won’t be seen until FY23:
While these discussions remain ongoing and the quantum and timing of resultant orders are still to be determined, the impact of this growth in demand is most likely to be seen in FY23 and beyond, and as such the Board continues to have a range of expected full year revenue outcomes for FY22 consistent with market expectations.
No mention of what those expectations are. Edison has FY22 revenue of $278.4m penciled in but I’m unsure of others, so it depends on the range of outcomes across analysts.
Profitability in H2 is expected to improve versus H1 but will not offset the weakness experienced in the period. Full year underlying earnings will therefore be lower than previously expected.
Conclusion
I could well believe there is renewed interest in Avon’s products in light of the Ukraine conflict.
But events at the armor business cast a long shadow, and the fact that the group is coming out today with a profit warning, having been busy buying back shares, does not particularly allay my concerns over capital allocation.

This unfortunate episode must be put into context, I suppose. Future growth rates are diminished with armor facing a managed closure over the next two years, which obviously impacts valuation, but there is still a healthy, functioning business responsible for the lion’s share of group revenue that is winning contracts from customers.
There’s a major rebuilding job to do though in terms of regaining investor trust though.
Edison has EPS forecasts of 85.1 cents in FY22 rising to 116.3 cents in FY23, valuing the shares on a prospective PER of 20.2x falling to 14.8x. Does Avon warrant such a punchy growth projection given the armor business and today’s profit warning? I’m skeptical for now but management does note increasing interest in its products.
Surely now is a good time to see heavy director buying if management is correct in its assessment.
Ultimately, I view the shares as uninvestable for now. I was wary before today’s update, and that stance has (at least for now) been vindicated, so I’m not compelled to jump in. The issues, in my view, stretch beyond valuation.
Epwin (LON:EPWN)
Share price: 88.8p (+1.49%)
Shares in issue: 144,917,993
Market cap: £128.7m
Final results for the year to 31 December 2021
This is a leading manufacturer of low maintenance building products, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors.
I’m using 2019 as the comparative period in the figures below.
- Revenue +16.8% to £329.6m,
- Underlying operating profit -12.7% to £18.5m (underlying OP margin down from 7.5% to 5.6%),
- Statutory operating profit up from £6.3m to £17.7m,
- Basic earnings per share +15% to 8.61p,
- Total dividend up from 1.75p to 4.1p,
- Pre-tax operating cash flow has recovered to £34.9m, with 189% underlying operating cash conversion,
- Covenant net debt to adjusted EBITDA down from 0.6x to 0.4x.
The tax charge seems unusually low for now. Taking the adjusted profit figure and using a 19% tax rate (noted as the standard in the group’s accounts), gives an adjusted normalised EPS of 7.66p, ahead of the Stocko consensus normalised FY21 EPS figure of 7.41p.
Net debt has reduced significantly year-on-year, from £18.5m to £9.4m, and revenue is at record levels. The group is implementing price increases and surcharges to negate the ‘significant inflationary and availability pressure on material and labour costs’, but these measures lag cost inflation.
That aside, Epwin is progressing with business. Construction has been completed on a new Telford distribution and finishing facility, with inventory to be relocated to this facility this year. The group has also acquired three well-established regional independent distributors of plastic building products, has invested in new product development (with aluminium window systems and PVC decking sales growing ahead of expectations), and ‘continued market share gains’.
Current trading and outlook
Strong RMI demand expected to continue in 2022, albeit at slower growth rate than last year
Epwin will continue to focus on actively managing supply chain and inflationary pressures. There’s a pipeline of further M&A opportunities and ‘positive medium and long-term RMI market drivers’.
Current trading is in line with the board's expectations, with 2022 revenue to date ahead of 2021.
Conclusion
The valuation here looks attractive - Epwin qualifies for the Free Cash Flow Cows screen and appears cheap across a range of multiples, making for a Value Rank of 84. Not bad, when coupled with a Quality Rank of 92.

FY21 was a difficult year for many businesses but Epwin looks to have performed well. Inflation is having an impact on profit margins - the group is passing on costs, but is lagging, so margins are affected. Top line growth in FY22 might be harder to come by as people return to spending money on holidays, although cost headwinds could subside at some point as well, which would be a tailwind for profitability.
It’s the leading player in its market with market share of around 20%, and the valuation has come down. There’s a strong forecast dividend yield too, of 4.95%, and cash generation could see the group return to net cash over the next few years.

I’m not up to speed with Epwin, but research from Edison suggests that it ‘has quietly gone about enhancing its manufacturing/logistics platform and increased its distribution presence over recent years’, with much of this progress obscured by external events such as Brexit and Covid-19.
The share price performance doesn’t reflect such progress, so it could be worth putting on the watchlist.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
I hold Avon Protection (LON:AVON) and am pretty bullish about the outlook for this company. Granted, costs have sharply risen recently which will reduce margins for existing contracts but given the specialised and market leading product they sell (I’m thinking of the respirators here), the company should be able to pass on costs in future sales and recover margins. Given that chemical, biological, radiological and nuclear warfare is high on the agenda of military thinking at present, sales can only go North from here.
Re: future stockslams cancelled.
I think the reason for lack of private investor interest is not because the market conditions have killed them off - I think it is because the online format is unappealing. In the days of covid being a dangerous threat it was great. But things have moved on.
I think it is time to reinstate a real live event with an actual venue and meeting real people. So much more fun.
I haven't done the online version - but I'd sign up in a second to the real life event. Just my thoughts.
It's like the doctors only giving telephone consultations.... it's probably time to change back to face to face.
Just my opinion : )
Hi dfs12, Agree that it would be good if a live event was reinstated, and great if it was streamed too so that people who couldn’t attend the event in person could still be part of the buzz (I’d be one of them).
By the way, do you mean future ones have been cancelled? I haven’t seen anything about tonight’s.
Ooops - yes tonight's event is on - it's just the future ones. I have adjusted my post accordingly - thanks for pointing out my mistake!
Tamzin just told me that 1,200 people have registered for tonight's StockSlam, which is pretty impressive, so hopefully they'll continue.
I also like real life meetings, but it takes up the whole day for me to travel into London, so online is vastly more efficient in terms of time & ease (and cost).
Lots of organisers of events are struggling with this issue at the moment. Most people find online so much more convenient, that it's unlikely to return to having physical meetings to quite the same extent as before.
P.
Spot on Paul, live is totally impractical nowadays and incredibly inefficient
I’ve just watched the event and apparently the reason it’s ending is because of a lack people willing to do the pitches rather than lack of interest from attendees. There were 1200 registered to attend today which seems pretty high. Face to face is ok if you live or work near the event but that will never happen for me unless I move areas.
A tough gig especially after a hard day at the real job.
Mello Monday are doing a 3-day live event in May. Trusts & Funds 1-day and small Co's the 2nd & 3rd day (those are not the dates). The website has the details, but think it is in West London.
I would be interested in doing a pitch in future if there is a change to them being held. I'd try and do it more around a particular investing theme as my one bit of feedback on the stockslam is some of the pitches seem a bit random rather than linked to an individual's investing strategy. I've held off from volunteering before because I am a bit shy about exposing my ignorance to a mass audience, but with some additional company research beforehand I'd hope to be OK!
Om Motorpoint (LON:MOTR) isn't there a risk to their stock sourcing later this year or next year?
As they specialise in nearly new (less than 3 years?), doesn't that mean the huge shortage of new cars atm, means less stock available at some point down the line for Motorpoint?
Fast-expanding Chinese fashion e-tailer Shein is looking to raise fresh funds and its reported $1 billion target would give it a market value of close to $100 billion.
Further headwinds for Boohoo (LON:BOO) with Shein continuing to capture the market share at a break neck speed. Surprisingly no boohoo brands in Top 5 websites for Fashion and Lifestyle in the UK.
Wonder Boohoo can continue to grow.?
https://www.similarweb.com/top...
Re £BOO...wouldn't the Shein valuation give a favourable read across for BOO? One argument that never seems to be aired with regard to pressure on disposable incomes...doesn't it mean that many will trade down to the cheaper end of the retail spectrum thereby boosting sales. Suppose the key issue at present for Boohoo (LON:BOO) is margin pressure.
I sold out of Inland Homes (LON:INL) in Feb 2021 at a loss after I lost confidence in the Board.
It was always jam tomorrow but the Results were invariably disappointing and as far as I can see nothing has changed.
What's happening at Inland Homes (LON:INL) ? The CEO has left with immediate effect and no explanation. Did he jump or was he pushed? (No position as I sold at 61p in March 2019 when the CEO was awarded what I felt were too many options.
Inland Homes (LON:INL), Terminated with immediate effect looks like he was pushed. I sold out years ago, this share has gone nowhere, yes share options too generous.
You'd imagine the lack of share price appreciation had something to do with it! Inland Homes (LON:INL) has a TNAV of some 100p odd and trades at 0.4 book value versus other builders who tend to trade on 1 - 2 times depending on the cycle. Let's see who replaces him - might be a good opportunity to unlock some value
Mr Thompson is maybe licking wounds.
StockSlam - I was really sorry to hear that tonight's StockSlam (register here) is to be the last for a while, due to lack of interest from private investors.
Paul, I wholeheartedly agree with you. As a fairly new investor I love watching these pitches. It's amazing how much you can learn about different companies and what sort of research investors are doing. I don't think I've missed one yet and most of the time there is at least one company pitched I either hold already, or have under consideration.
I really think we need to get behind this superb resource - it would be a massive shame if it were to come to an end.
Its the madness of crowds. Youd think there would be even more demand with previous favourites now trading on PE of 10 or 12 rather than 25x
Many here will have been through the dot com bubble, 2008 crash and 2020. Personally speaking each time its the holdings Ive built during a bear market that've been the multi baggers for me.
Even if not ready to buy anything yet I believe this is where you do the hard yards by keeping track of potential investments and searching out new ones. Easy when everyones back slapping but harder to do when negativity is everywhere.
It is surprising. I pitched last year and enjoyed the discipline of it a lot. When I speak to private investors, I increasingly find people looking at overseas, particularly US companies. There are literally hundreds of US companies that you could take a 10k position in on a spread bet for perhaps a £50 spread, whereas if you tried to do that with UK companies the spread would often be £300+ may explain it. There are huge spreads and a chronic lack of liquidity in the UK markets. As a result, it has alienated quite a lot of its potential audience. In my experience, lots of people, particularly those more interested in trading than long term investing, use it as a springboard and quickly move on. Which is sad really.
Hi Donald any chance of your podcasts with Dave returning at some point ?
I think it would really rejuvenate the Stockslam to have a few overseas pitches, particularly US. I think part of the problem is that most of the regulars must know most of the UK small caps by now.
Restaurant Costs / Availability / Zombie eateries..
Just met my friend who owns a chain of restaurants plus has a fish wholesale business .
Head in hands time for him .
No sunflower oil in UK for 2 weeks and he's busy trying to find alternative , price through the roof too and they almost cant cook.
All round huge price increases on virtually all ingredients , increased gas and electricity and a softening in demand .
His wholesale side also down significantly and his remaining customers starting to both stretch their credit terms and all are looking for lowest price now.
The restaurants etc that were doing badly pre covid were then propped up by government loans and have had a brief respite in the post covid bounce when everyone was free again.
These are surely the walking dead now and we will see a raft of closures this year of the Zombie restaurants.
Longer term maybe heathy as will result in the good surviving ?
Tough times for some.
I was chatting with my local fish and chip shop owner at the weekend. He said he is seeing huge increases in his cod prices because it all used to come from Russia. I think he said £20 per tray extra - I don't know how that relates to a serving. His immediate reaction was to say that's too much and try to shop around but it's the same with all his suppliers.
He's not talking complete cod swallop either. 85% of our cod is imported and approx 10% of that comes (came) from Russia. It's not only fossil fuels where the lack of Russian supply will continue to drive inflation.
Yes it's many things, such as fertiliser which has sent prices up 3x, this will affect food prices.
Also some building materials such as plyboard, much of that came from Russia and Ukraine.
All fish comes from Billingsgate Market not Russia.
Good point regarding director buying Paul, last 10 days or so probably the most Ive seen in a long while.
Ive been trading a few like Watches Of Switzerland (LON:WOSG) Greggs (LON:GRG) for a quick profit after a director buy. Well, you have to take whatever scraps are on offer right now! Was heavy director buying in Polar Capital Holdings (LON:POLR) just before it broke its downtrend, its had a good bounce since.
Victorian Plumbing (LON:VIC) has been on my watch list since IPO. Looked to be bottoming out in the 50p area so started a position. I like the business, may yet disappoint short term but I believe long term it should be OK so risk reward looks much better now than the crazy valuation when it listed. Young, ambitious CEO with a large share holding and good return on capital/free cash flow.
A lot of stocks have seen a bounce in the last month, even without director buying. Just look at moment on your folio, I was quite surprised by some of the gains. Maybe we should be selling the ones that have not bounced rather than taking a quick profit?
I agree. Id be having a cull of anything which hasnt risen in the last month, some momentum is important in price and newsflow. Some small caps are drifting because large holders dumping stock even tho business is fine, such as Somero Enterprises Inc (LON:SOM) and Science (LON:SAG) so its a balancing act.
Generally Id rather risk my money in a company with a director willing to put his hand in his pocket tho. Im avoiding anything with large director sells recently such as Luceco (LON:LUCE) and Robert Walters (LON:RWA) . If they thought it overvalued enough to sell millions why would I want to buy it?
Director sales is a tricky one because we don’t know the reason, maybe to buy a property? There have been studies on this subject. I have followed director selling in the past with mixed results. If several directors are selling I will usually get out. Robert Walters (LON:RWA) recent sales were all share options, there maybe tax reasons sell before tax year ends.
Robert Walters (LON:RWA) has a trading update this week so we'll soon find out how they're doing...
Personally, significant Director sales or purchases are a big marker for me deciding to buy or sell. This comes from experience of what I see before my own eyes with the share price movement after a large sale in particular.
Its totally fine for Directors to want to cash some in to buy a property/pay tax/ convert paper to cash/fund a divorce etc etc.
What interests me is the timing they decide on when doing that. That timing one would expect would be totally under their control. Why would you sell any of your shares ( for any of the above reasons) if you thought the prospects for those shares were particularly good over the next few months and you would knowingly miss out on more gains ? Answer : you wouldnt.
So my conclusion is that there is always a reason for a Director to sell at a particular time - and it is never because he/she thinks the share price will be shortly rising.
Just my take - Im sure I could be wrong !
I think there are timing issues of when directors can sell. Also they always get it right, I have followed some directors sales years ago only to see the shares go up and up. I have found that they tend to sell too early. Buying is probably a better indicator than selling. Some selling is shares options which some directors treat as bonuses. As I said if several directors start selling I will take more notice. I also top slice some of my shares, too many have peaked and fallen back. There was a study about directors selling, it was not clear that the shares did underperform what what I recall. Solid State (LON:SOLI) was the only one that saved me by selling after several directors did.
If you are holding quality companies why would you sell when valuations are depressed. If they are not quality companies why are you holding them.
I have sold some when the price has gone up, so I have taken some profits, not because they were depressed. Things have changed considerably in the last few months, so need to review this situation. I think some sectors will have a difficult time over the next year or so, I have been reallocating some of my investments. Yes if I believe in the stocks I will keep hold of them.
By quality are you talking about Stockopedia high quality scores? Yes I do hold some that are low Q scores, I just sold AV. which has done quite well recently and I hold Legal & General (LON:LGEN) because I think it is good value and Stockopedia is not always right.
You could debate quality v momentum investing.
Hi
The other day SCVR discussed EVs (some interesting perspectives, I must say).
Battery swapping versus charging is a topic of interest in the EV space. This short article by SeekingAlpha might interest some.
Disclosure I hold TESLA stock.
Regards
Howard
On the subject of battery swapping I didnt realise it was already happening in Asia for electric scooters. Seems a great idea,
https://electrek.co/2021/05/18...
Only came across this when looking to buy Saietta (LON:SED) last month. The market here is huge. Im not normally interested in jam tomorrow shares at all but think Saietta (LON:SED) has a better than average change of making it.
Well the thing about Saietta (LON:SED) (which is my favourite share btw - I am long) is that it isn't really jam tomorrow. It has already started revenues and has sold out of its initial onboard motor EV offering, so it has underpinned revenues already.
Coincidentally when looking into First Light Fusion yesterday I saw that a neighbour of theirs on the same industrial estate in Oxford is an axial flux motor company called Yasa. They were acquired last July by Mercedes Benz and now operate as a wholly owned subsidiary so clearly it's an area of industry interest.
Sosandar (LON:SOS) Partner Plus approval by Next is a good sign they have their fulfilment in good order. While it’s not the most difficult thing to obtain Next do want assurance you aren’t going to trash their marketplace with poor service
Re margin pressures I suspect they are being agile in using raw materials, managing where their source from to balance exposure to ocean freight rates and also pushing prices where they can.
Does anyone know how Sosandar (LON:SOS) are able to maintain their margins right now?
I don't remember seeing any retailer recently, either on the high street or online, or in the US or in the UK, that hasn't put out some sort of update highlighting margin pressure.
What's Sosandar's secret?
I'm merely a spectator here so any insight from those more in the know would be appreciated.
A
It's scale. Revenues are growing so fast that volume discounts kick in absorbing any margin pressure. Prices are forward fixed so they know when any price rises might need to be increased or come into effect. Then their marketplace platform business is growing and thus as a now "known" brand you have to spend proportionately less per customer on marketing.
Net net this allows them to be more efficient.
Re Sosandar (LON:SOS) - The difference vs other retailers is probably largely going to be that rapid growth on a small base ie scale is able to balance out cost pressures at this moment (plus a bit of a category mix effect as higher margin dresses come back as a bigger share of the total). Next year, it maybe a more normal retailer. The scale gains are probably biggest as you emerge from small to medium orders/item.
However, much bigger than the margin up or down a few %ppts at this point is the absolute cash margin growth from selling more. This covers fixed costs and funds increasing inventory. Revenue growth and re-orders says the product demand and loyalty is there.
I missed the investor call but would have hoped there is a break out of sales by platform and vs own site. In the future this will be as important a split as the old physical store / digital divide was for traditional stores.
Getting properly into bed with Next is fantastic as this is expansion across Europe fixed from a logistics point of view, with no loss of focus on product. Brilliant strategy by both parties.
It is a joy that at least one of my buy and hold for 5 years shares is coming good.
Interesting update from Lookers (LON:LOOK) today. Looks overall very positive despite challenges from fall out from Ukraine, inflation and pressures on consumer spending etc. Reinstated the dividend and a confident outlook. Wondering if after a great run while so many small Company shares have struggled even after issuing upbeat updates (e.g Somero Enterprises Inc (LON:SOM) Onthemarket (LON:OTMP)) whether from share price angle this is as good as it’s going to get for Lookers (LON:LOOK)?
Hope Paul or Jack will have time to update on Lookers (and perhaps brief reference to Vertu Motors (LON:VTU) as well) today. I hold both.
Sorry to read of you having to sell Sosandar (LON:SOS) Paul. In this market where so many small company shares are falling back again after gaining on upbeat updates there’s a chance you’ll get another good long term buy opportunity. I hold, based largely on your quality updates Paul and it’s proving to be a great winner. Just need Boohoo (LON:BOO) to turn the corner now!
Boohoo (LON:BOO) is up 34% in the last month up to yesterday, so there is some hope.
I agree with Ken that Lookers (LON:LOOK) seems to have topped for now, at least as a continuing stand alone business. It's the fear of missing out on any takeover potential that stops me taking my profits here.
Motorpoint (LON:MOTR) - does anyone know why its SP action is not matching its peers Vertu Motors (LON:VTU), Lookers (LON:LOOK) (PDG has a TO bid)? Its SP was higher in Aug 2020 than now (despite the excellent progress made) which strikes me as bonkers.
On the point about feeling and seeing cars before buying. I went into a local Audi dealer to buy a new A3 as my old one is worth c£18k being 4yrs old, so seemed like a good time to trade up (I like new cars). Anyway the nice show room man had no cars to show me and not even an example of the colours available. It seemed like a joke so I walked out. He said we are selling things directly from the website which didn't go down well with me. I need to see the colour in natural light to buy anything.
However, there are probably desperate buyers out there who are willing to buy an Audi A3 unseen, untested. Such is the shortage of new cars available at the moment.
I have a new car on order (and has been since early Oct), but no sign of its arrival yet. The garage tells me that the factories are no longer providing one-month-order-plans, but deciding a week at a time as they get parts.
This made me decide to sell my holding in Vertu Motors (LON:VTU) as I feel that without a regular flow of new cars the 2nd hand market will dry up. We will all simply stop buying until the taps come back on.
As another aside, a fiend of mine works for a big manufacturer and is used to getting a new company car every 6-months. It's 18mths now since the last change as every new car goes to customers (they don't have enough supply to furnifsh their staff), which again leads me to believe the peak must be some point soon. If the industry cannot keep liquid (and high resale prices) going then the conveyor belt must stop at some point.
Sosandar (LON:SOS) great trading update. I won't repeat the numbers others have already posted but I note that it is now trading on broadly 20* FY22 earnings and only 12* for the following year. That is with extra caution in the numbers based on household income squeeze. Surely that is far too low for a company growing at this scale. Looks like international expansion isn't too far off either. The Next Plus update is big in terms of their ability to put up a full range and pick stock from their own warehouse (rather than ship it to Next and hope it sells) and the approach from Very suggest the brand is now known and in demand from the marketplace platforms. Yet only 33% of sales currently come from these platforms so loads of scope for that to grow too.
I hold and intend to keep them. Think the next 3 years could be pretty exciting and would like to think they can do very well from here.
yes looks great from sos, the turning point seemed to me when they got a new fd a year or so ago, he immediately seemed to focus them on what expenditure was creating the most traffic and sales, and since then they seem to have grown much faster and more consistently. Obviously he's just one cog in a big machine, but the whole company seems to be performing better now. This gives me more confidence in going forward. I hope the team sticks together and grows this into a large profitable company, and reap the rewards due to them.
Wentworth Resources (LON:WEN)
Good Morning Jack
Will you be able to take a look at Wenworth Resources today? Excellent results and forecasts for coming 12 months
Good Morning all,
On director buying, Fireangel Safety Technology (LON:FA.) (FireAngel - I hold) has gone up after two director buys and posting a loss (I imagine less than the market expected). I think it is early days and the road to recovery will likely see more dips than peaks, but I think that things are turning around.
For the stockslam - I think it is a shame as well. I would be willing to take part .. once I think that I know what I am doing !! Only started investing middle of last year - trust me to pick the top of the market to dip my toe in the water. I have learnt alot from this site including Paul & Jack - so from my side, many thanks and keep up the good work.
Stocko says Fireangel Safety Technology (LON:FA.) has 181mn shares in issue now, up hugely over the past few years. Have they made good use of the money raised?
I only looked at this company recently. It has to be bad for the shareholders that supported this company at £2 per share only to see their cash disappear. I dont know the answer to your question, but I suspect the answer to be no. From the little that I have gleaned on the internet, and from watching the presentations, and if it is true, then perhaps there are some positive prospects for the company. I do value the fact that a UK company is being paid to develop products for the german market - not a common occurrence in my experience.
On the note of research, I am still looking for pointers. Everyone seems to say - DYOR, which seems to me a little facile. Sure, the balance sheet and cashflow statement are good starting points, but they are only a very small part of the big picture. Your question (if it was to me) only reinforces my doubts on the ability to really be a true investor, rather than an informed trader.
Full disclosure - I exited my position today with FireAngel. In my very limited experience, I 'guess' that the market will be lower in the next few months than it is at the moment, and so any small gains should be taken awaiting the inevitable dip.
And yes... I have two holdings that I have watched from buying (inexpertly) at the peak and watched them dwindle. On the Shearwater (LON:SWG) website, it seems to be full of pictures of the directors enjoying champagne that I have paid for at their various awards.. (rant over !)
Tentatively came out of some cash last week based on FTSE All Share gains which seemed to indicate that my cash position was leaving my portfolio behind.
So far that seems to have been the wrong call. Despite the FTSE All share indicating continued growth, it appears skewed by a few companies, as Paul said, reacting violently to News of one form or another, or companies benefiting from geopolitical conditions.
This very small snapshot from me still makes me feel that at this moment 'cash remains king', which with inflation so high is uncomfortable, but its purely folly to throw additional money at equities right now, and longer term safe havens have yet to live up to their status,
Choosing the right share at this moment seems to be nothing to do with how good the company is or how well it is performing, but more about whether the boss is going to buy some shares, or a snap rise on decentish results.
With so little good news ATM, and glimmer of news is pounced upon by the masses, and then the computers.
Maybe of help to someone who is thinking of diving back in....am not so sure its the right call ATM, just the weight of bad News seems to be overwhelming the market as a whole.
Any other thoughts?
Commodity stocks are still going up. Cash is losing value by the month with current inflation rates.
Strong read across for all motor groups from Lookers today, we hold Vertu. Note warnings on new car supply and inflation costs but trading still strong.
I put a tight stop loss on Vertu this morning, after a strong months performance (up 16% in the last month), my gut feeling is discretionary spending reduction will counter this perfect storm dealers have enjoyed.
I am sorry you are not still in SOS Paul. A bit unlucky given you tipped it for all of us on this site. I like to pride myself that my portfolio is all my own work but I have a little section (not allowed to be more than 2 shares) which I call "Paul's picks" (intended to sound a bit Smashy and Nicey!!) Currently SOS and BKS. Just wanted to say "thanks".
camtab reminder of the disclaimer that is always present !!
"A quick reminder that we don’t recommend any stocks"
Fair play rmillaree. I do always do my own research just felt a bit for Paul as if there was ever an injustice him not being in SOS as they go into profit is one. So for the "ledge" that is Paul, Smashy and Nicey in much less politically correct times (258) Harry Enfield & Paul Whitehouse's Smashie & Nicey piece (Comic Relief, 1991) - YouTube
I agree about monitoring director purchases (and sales) Paul, I hope they get their buying right more times than I do!
I have a curate's egg this morning with what to me is a strong performance by Epwin -- lots of promises from Getech, and a Terminated Group director from Inland Homes. I don't have your balance sheet skills and do appreciate your comments whenever you cover one we hold, my wife has always been our admin department and after my 1987 options debacle is included in all financial decisions. Apologies for long winded message.
Thanks Paul; quite agree about director buying, but why haven't the directors of Boohoo (LON:BOO) splashed out with the share price being so low. Any thoughts, seems strange?
Sosandar (LON:SOS)
Top marks to the clarity provided with regard to current market expectations - really there is no excuse or hiding place for companies that refuse to tell us shareholders what their current view are ref trading. (Recent stonewalling by saga for them to later backtrack and give a nod and a wink on an investor call was example of unacceptably pooor conduct by directors)
*Prior to the release of this announcement Sosandar believes that current
market expectations:
(i) for the year ended 31 March 2022 are revenue of £27.1 million and an
EBITDA loss of £0.9 million
(ii) for the year ending 31 March 2023 are revenue of £38.5 million and
EBITDA of £1.7 million
(iii) for the year ending 31 March 2024 are revenue of £52.5 million EBITDA
of £2.6 million.
Note even saying nothing and presenting these numbers is a vast improvement over a situation where a company wont reference if there are current expectations are. So top marks to sosandar current FD as in then past their updates used to be very sketchy. Looking at the 2024 expectations (prior to todays update) looks like they are confident of continuing to acheive fantasic growth - mightily impressive near doubling sales from 2022 to 2024 if they can hit those numbers.
I remain on the sidelines here.
Wow Avon Protection (LON:AVON) management showing their quality. I guess we should look at LTIP rewards being reset to make sure they can motivate themselves to recognise ongoing mistakes and find someone with the skills to address them.
Further to Paul's director buying comment above it'll be interesting to see £IGP's share price reaction to CEO's purchase yesterday of £50k worth at 48.1p
https://www.investegate.co.uk/...
re Director buying. Following yesterdays fall,, Intercede (LON:IGP), on 5 April 2022 that Klaas van der Leest, CEO of the Company, purchased a total of 104,700 ordinary shares of 1 pence ("Ordinary Shares") at an average price of 48.1 pence per Ordinary Share. Following this transaction, Klaas van der Leest is beneficially interested in a total of 168,106 Ordinary Shares, representing approximately 0.3% of the Company's issued share capital.
Epwin (LON:EPWN)
Solid set of results here with positive outlook for the current year. Epwin seem to be good at what they do and reasonably well organised company - they seem pretty confident ref inflationary and supply issues albeit slight timing issues ref increasing prices.
Share price trend seems to directly contradict the the positive murmurings coming from the company i summise that this is a sector no one wants to be currently investing in as no one knows where the next profit warning may come from.
I will continue to be a content holder for now, not a company I ever expect great things from but if they can continue to grow sales and profits and keep paying decent divi that’s enough for me here.
Good morning, Paul
Sosandar (LON:SOS) have released a very positive trading update today, together with new Third Party agreements.
It would be great to hear what you think. It seems they have reached a number of milestones in the last financial year. But will it continue?
Morning mcav82,
Thanks, I'll take a look at Sosandar (LON:SOS) update.
Unfortunately, I'm not currently holding, as it was in my spread bet account, which got massacred over the last 3 months downturn, so I had to close lots of positions that I would rather have kept, due to humongous margin calls. Still, can always buy back, when funds permit.
Regards, Paul.
Hi Paul, appreciate a look into Motorpoint (LON:MOTR) if you can - cheers
Sure, Motorpoint (LON:MOTR) (I hold) is a nice company, so I'll look at that next. Jack's working on Avon Protection (LON:AVON) as we speak!