Small Cap Value Report (Wed 6 Jan 2021) - QE, HEAD, TPT, CLG

Good morning, it's Paul here with the SCVR for Wednesday.
Timing - I've started early again today, so should be mostly done by 1pm. Today's report is now finished.
Agenda -
Headlam (LON:HEAD) - operational update - business as usual
Topps Tiles (LON:TPT) - Q1 (13 wks to 26 Dec 2020) trading update
Clipper Logistics (LON:CLG) - slightly confusing trading update
.
US Senate Elections
I was up most of the night following the US Senate elections in Georgia, because that could be important for the US market, determining whether President Biden is able to push through massive stimulus & infrastructure programs, and tax rises for companies & the wealthy. Or whether a Republican Senate could block or tame his policies. Opinion seemed to be divided amongst US commentators, on which outcome would be good for the economy and stock markets, so I ended up retiring rather confused.
Monthly GDP - UK
Whilst browsing the ONS website last night, waiting for something to happen in America, I happened to come across an interesting graph (see below) re UK GDP, measured monthly. This runs from Jan 2007 to Oct 2020.
You can see the first dip for the financial crisis from mid-2008 to mid-2009. Compare that with the unprecedented stoppage of the economy due to covid/lockdown 1, in early 2020, with a massive plunge down in GDP, with about a quarter of GDP vanishing from high to low.
.
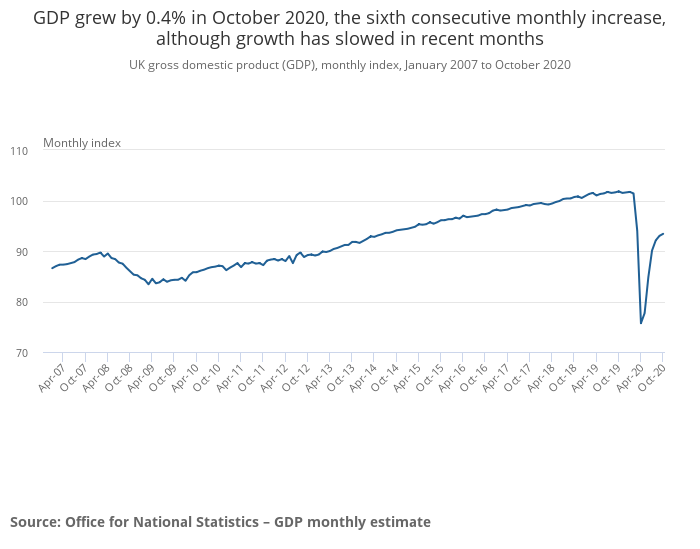
However, the graph then more recently clearly shows a V-shaped recovery in GDP. It wasn't all the way back up by end Oct 2020 (where the data runs out), but it had recovered most of the way.
I admit to being sceptical about the possibility of a V-shaped recovery, back in mid-2020, but I was wrong, and a V-shaped recovery is what has actually happened. That's what the stock market recovery told us would happen, and the market was right. I wish I'd looked more closely at GDP data last summer, as that might have stopped me continuing to fruitlessly short the indices over summer 2020, which was an expensive mistake (albeit funded by profits from earlier very effective hedging).
As mentioned yesterday, it's always better to focus on what is actually happening, rather than having a theory as to what should happen, and blindly sticking to that conviction.
Lockdown 3
Is bound to have some negative impact on GDP early this year, before it should bounce back again as restrictions are eased. I'm not at all convinced by the prophets of doom. To my mind, mass vaccinations are such a game-changer, that my base case scenario is for an easing of restrictions in Mar/Apr 2021, and then a strong recovery as pent-up demand is released. That comes with the caveat that I reserve the right to change my mind at any time, if the facts or probabilities change.
The big danger is a virus mutation that negates vaccines. We need to keep alert to that. If virus numbers start going up again after having initially fallen by say March/April 2021, then I wouldn't hesitate to put on another index short, as a hedge, and ask questions later.
It will be very interesting to see what companies say about how they are handling lockdown 3. As mentioned yesterday, aside from sectors which are most distraught (hospitality/leisure, non-essential retailers, and travel), most other sectors know the drill by now, and should be able to continue trading without too much disruption. Hence this really should be a lot less severe than lockdown 1, when stoppages were much more widespread.
Quantative Easing & MMT (Modern monetary theory)
Government is continuing to throw money around in an astonishing way, all funded by QE of course. Hence the many people saying that we are cursing future generations to huge debts, are completely wrong, if you check the facts.
.
.
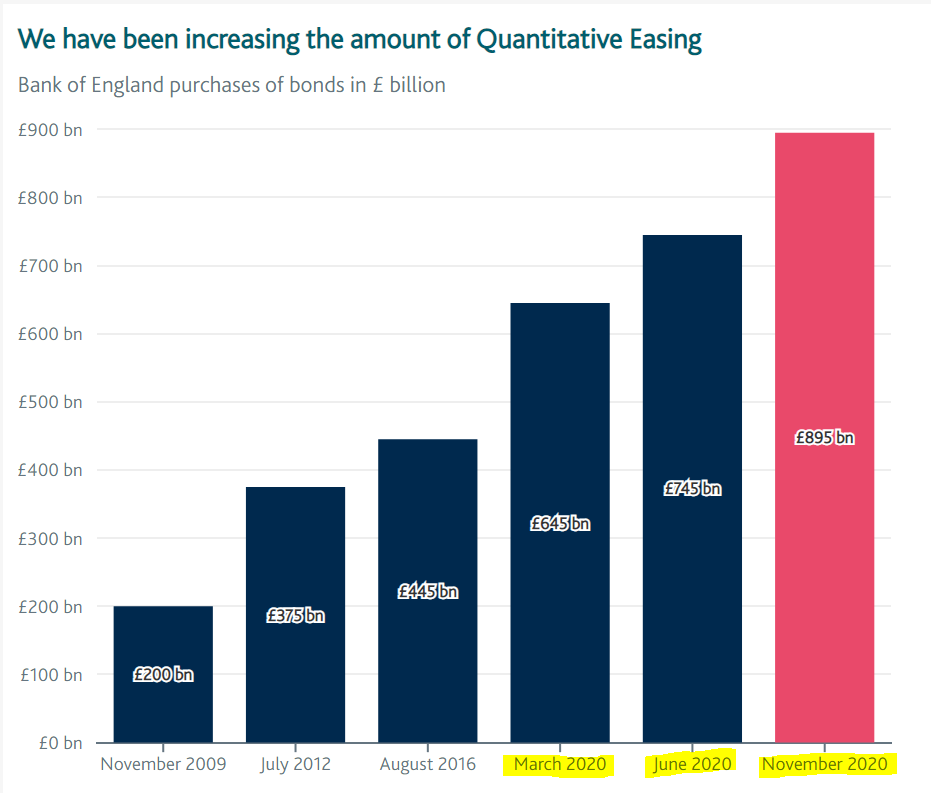
This graph from the Bank of England's website shows all QE to date (electronic sterling created out of thin air). It shows a steady progression, but that's misleading because the x-axis has been compressed. I've highlighted the dates. As you can see, the BoE did £450bn of QE in 2020, after covid had emerged. That's roughly the same as forecasts for the current fiscal year's deficit. In other words, the massive covid spending has cost future generations precisely zero. All Gilt issuance have been funded by money printing.
Hardly any journalists, commentators, or politicians seem to understand this, but it's utterly crucial. At this point in time, we do not have to worry about the National Debt at all. In fact, it is not £2,100bn, or almost 100% of GDP as reported in yesterday's papers. If you take off the £895bn of Gilts owned by the Bank of England (a branch of Govt, since it was nationalised just after WWII), then Gilts outstanding are actually relatively manageable at £1.2 trn, or about 60% of GDP.
The servicing cost is getting cheaper all the time too, as new Gilts are issued to roll over old ones, the interest rate on the new ones is ultra-low. Given that the Govt is buying up all of its own newly issued debt, then it can set the interest rate at whatever it likes. Market sentiment towards Gilts doesn't actually matter. Therefore, as long as QE keeps working, then we don't have to worry about interest rates rising either. What a bizarre situation, but that's the current reality. I might as well throw away all my old economics textbooks, because something different is happening right now.
It's quite obvious from their actions that the Treasury, Bank of England, and Rishi Sunak all understand Modern Monetary Theory, and are happy to print as much money as is needed. I'll come back to the topic of MMT in future reports, as it's fascinating. The boss, Ed, got me to read "The Deficit Myth" by Stephanie Kelton, as an introduction to MMT. It's a riveting, and sometimes infuriating read! Hence highly recommended, as it challenges everything I thought I knew about economics.
I'm not yet a convert to MMT, but Kelton makes a very strong case for it, and so far, it is working in the real world. She's right that the entire National Debt could be extinguished instantly, by creating enough QE to buy up the whole lot! That is undeniably true. I had already worked that out myself, and pointed it out here last year when commenting on QE. Hence why should we worry about Govt debt?
I do worry about future inflation though, as that could bring the whole thing down in ruins, as reckless money printing has in the past (e.g. Weimar Germany, Zimbabwe, and many others).
More on the topic of MMT & QE in the future, as it's fascinating, and very much sets the scene for continued bullish stock markets. Who knows, at some point maybe mainstream journalists might start to understand the subject matter they write about? No sign of that yet though. Alarmist headlines & articles about supposedly ballooning national debt play to the crowd better maybe?
Kelton makes this point very well in her book, describing a meeting she had with a US Senator, in her role as an economic adviser. After much effort, she persuaded the Senator of the reality that currency-issuing Govts could run deficits without having to worry about how to fund them, within reasonable limits (the productive capacity of the economy being the limiting factor - go beyond that, and it triggers inflation). The Senator agreed with her analysis, but then bluntly told her he couldn't possibly sell that message to the electorate! Hence the narrative has to remain about being careful in managing the finances, not being reckless, balancing the books, etc. That's what electorates want to hear. What Govts are actually doing, is the complete opposite of what they're saying! MMT is clearly already Government policy in most major economies now, but Govts don't dare to tell their electorates! I wonder if we'll see some highly publicised, but economically trivial tax rises, to keep the narrative of fiscal prudence going for electoral purposes?
.
Headlam (LON:HEAD)
Share price: 372p (up 4%, at 08:17)
No. shares: 85.1m
Market cap: £316.6m
(I hold)
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor, confirms that its operations in the UK and Continental Europe affected by current lockdowns will remain open for the duration of the lockdown periods.
There's a bit more detail in this announcement, which can be summarised as saying that the business will continue operating as normal.
Trading update - to be published on 21 Jan 2021.
My opinion - this is a smashing value share I reckon. See the archive for my previous comments. In a nutshell, it has a lovely balance sheet with tons of freehold property. Also the business model is sound - an outsourced warehouse/distributor for carpet retailers, which can't possibly carry large ranges of carpets themselves. It should return to EPS of pre-covid levels, c.30-40p with patience, which makes the shares look cheap at probably about 10x recovered earnings. At this valuation, I can imagine a bidder might try to grab it, so it's high up my list of possible takeover targets.
I'm generally ignoring broker forecasts at the moment, and instead valuing companies usually on their pre-covid earnings, because I think there's likely to be a full recovery in time. Or adjusting those historic earnings, if something has changed (e.g. disposals/acquisitions, deep cost-cutting, etc).
Historically, Headlam has paid generous dividends. Hence buying now should lock in a good, growing, sustainable yield. A good share for income seekers I reckon.
As always, I've no idea what the short term share price is likely to do, but I give this share a thumbs up, for people who want to own a solid business long-term, with secure finances, at an entry point that I still view as attractive. As always, that's just my personal opinion, it's up to you to do your own research.
In the short term, I imagine that HEAD's customers are likely to be impacted by lockdown, but that's probably only a few months, and we've seen that home improvements are an area that has been boosted by previous lockdowns.
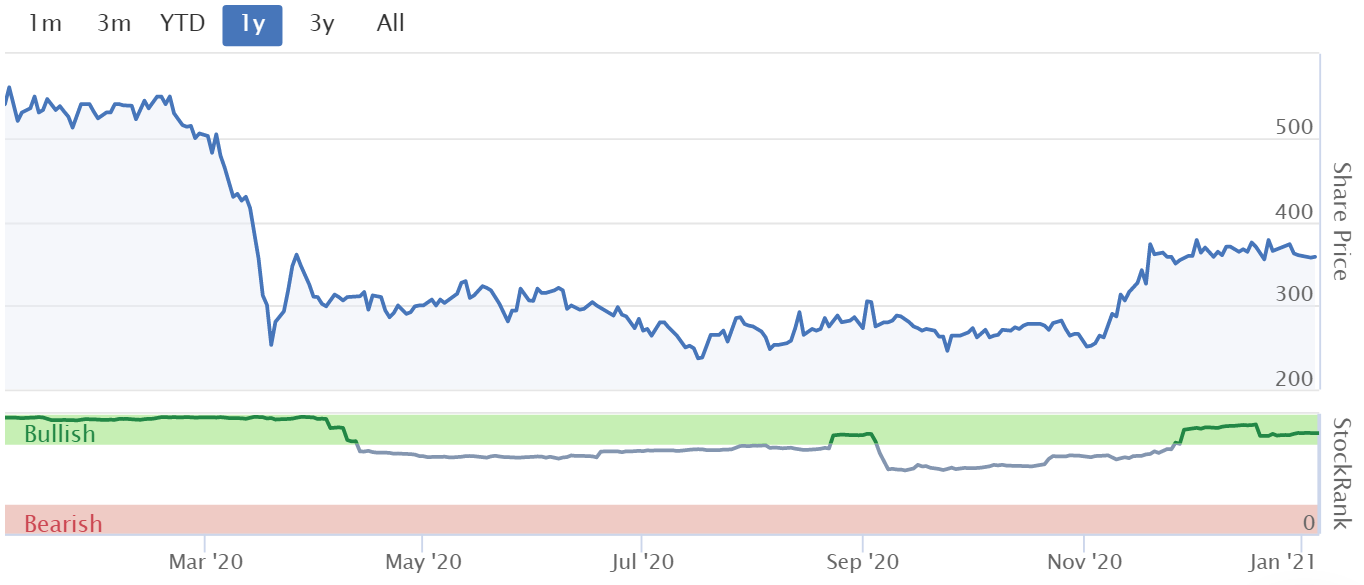
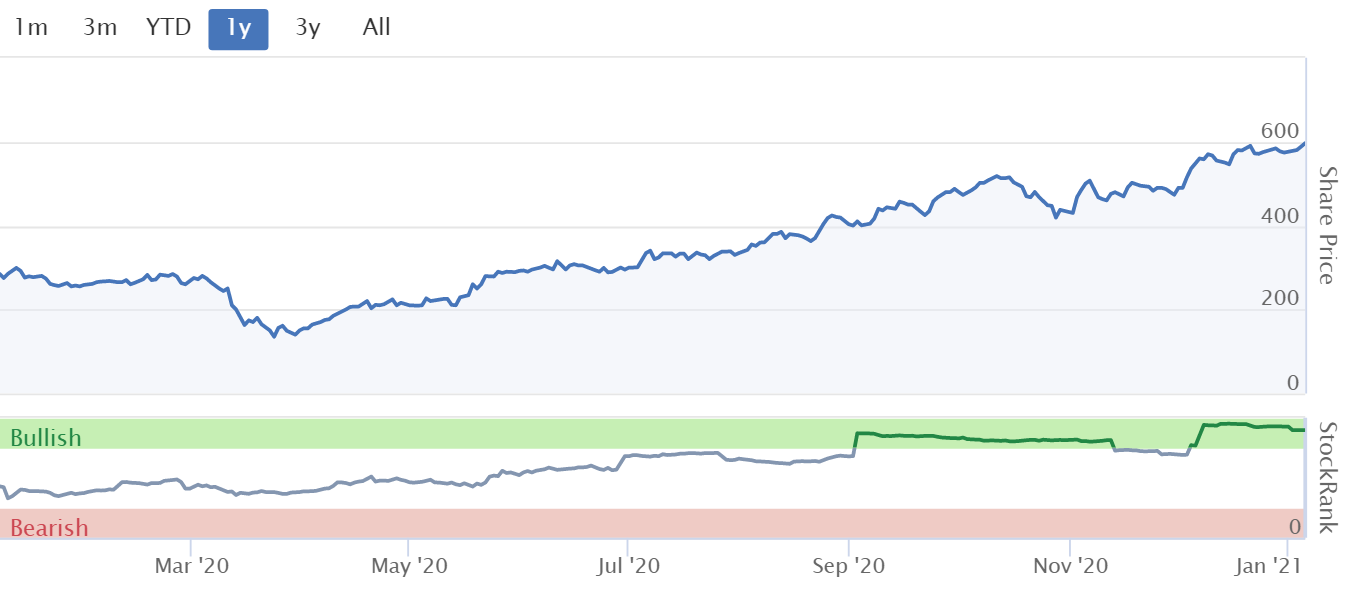
It seems to me that this share should, in time, recover to pre-covid levels, which could give us 50% upside from here. I really don't understand why it has lagged behind other cyclical shares, with a rather muted recovery, as you can see from the 1-year chart below. Possibly some catching-up might occur at some stage?
.
.
Topps Tiles (LON:TPT)
57.6p (flat, at 09:27) - mkt cap £112m
Topps Tiles Plc ("Topps" or the "Group"), the UK's leading tile specialist, announces a trading update for the 13 week period ended 26 December 2020.
To refresh my memory, here are my notes from the year end (FY 09/2020) trading update, published on 30 Sept 2020.
It’s so difficult to interpret trading updates at the moment, because of lockdowns coming & going, different in various regions, etc. Closures then may result in pent-up demand, hence a rebound in trading afterwards.
Q1 (Oct, Nov & Dec) trading reported today looks strong -
Retail like-for-like sales increased by 19.9% in the first 13 weeks of the current financial year (2020: decreased by 5.4%), with good growth in sales across both of our main customer groups, professional fitters and homeowners
Current lockdown -
TPT can continue to trade, as its products are exempt from closure - good
Although this bit worries me, as it sounds a bit over-zealous. I wonder who has given them the advice? Surely letting customers browse the aisles, but restricting numbers, would be safe, but not damage business so much?
However, under the current lockdown rules for England we are currently being advised to close our tile aisles in stores to prevent browsing. Customers can transact at the trade counter or through our online channel with direct delivery or click & collect.
We expect to see an impact on sales during the period of tighter restrictions and trading margins will come under some pressure due to the additional delivery costs associated with higher levels of online sales….
While the latest lockdown restrictions will impact sales, at this stage it is very difficult to estimate the level of impact or how long this may last.
Commercial sales - “more protracted recovery” than the core business. Performance is in line with plan, and expecting to make progress in 2021. Optimistic medium term. So this potential growth area doesn’t look madly exciting for the time being anyway.
Balance sheet update sounds quite good. I’m happy with the balance sheet at Topps. It’s not brilliant, but I think it’s adequate to get through another tough patch likely in Jan-Mar 2021. Last reported NAV was only £14.1m, but that’s hurt by IFRS 16 entries which net off to a deficit of £(17.9)m. Eliminating the IFRS 16 entries, takes NTAV up to £32m, which I think is adequate.
My opinion - I’m not sure about TPT. I’d say there’s no insolvency risk, so it’s safe, and it has demonstrated the ability to trade through more difficult conditions in lockdown 1. It didn’t need to raise fresh equity in 2020, which is an important point, unlike some others (e.g. Dfs Furniture (LON:DFS) ) which had to dilute shareholders in order to keep going.
Its target of increasing market share from 17% to 20% by 2025 doesn’t sound very ambitious to me. Maybe it’s a mature business, that could be near to the maximum market share it’s realistically possible to achieve?
Are online competitors a threat? After all, buying tiles just needs a sample of 1 tile sent through the post, tiles are not really like a sofa where customers need to touch & sit on it, to feel the quality.
It’s got a strong Q1 in the bag (Oct-Dec 2020), and it sounds like Q2 is likely to be poor. Then probably a rebound in Q3 & Q4, possibly? That seems a likely outcome to me.
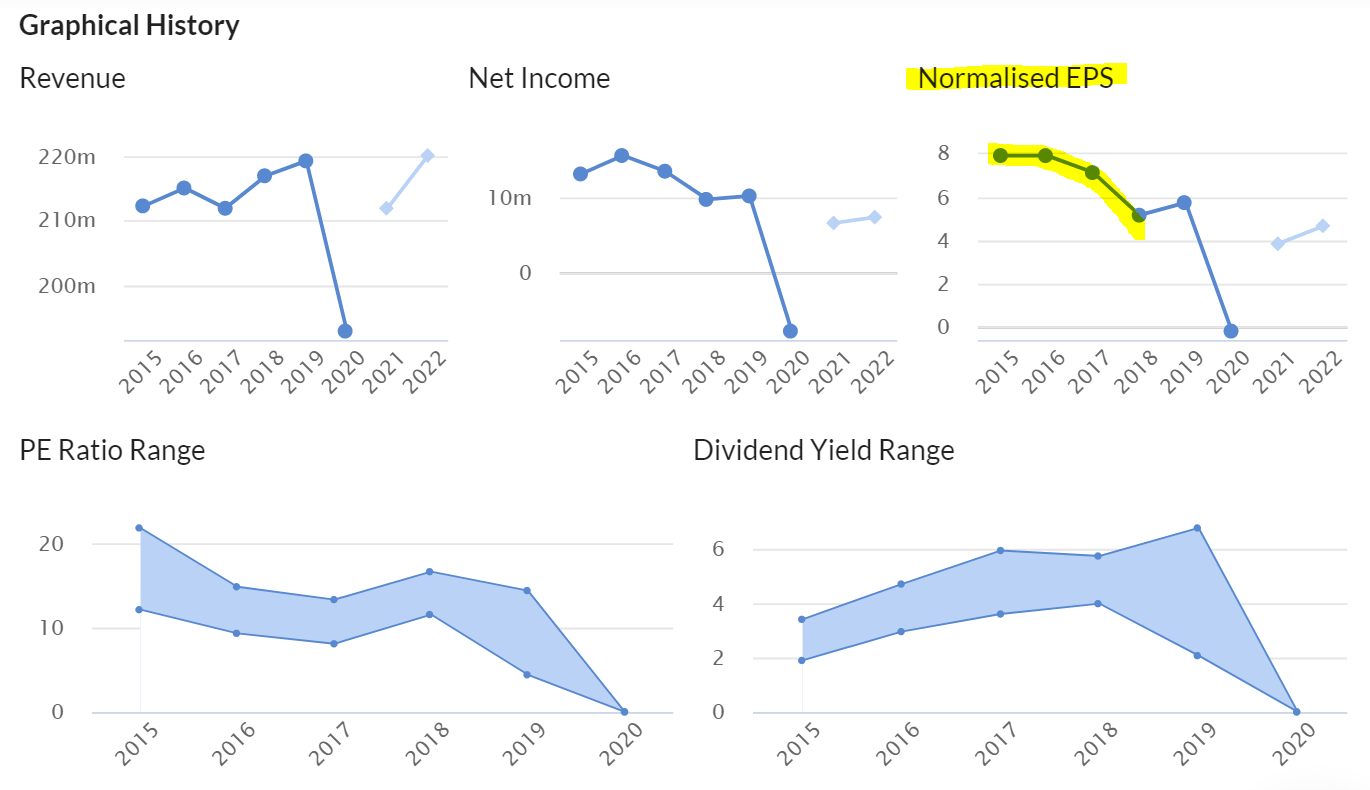
The trouble is, TPT was under pressure before covid, EPS was declining. Therefore it’s difficult to get excited about it. Sure, earnings should recover from the losses of FY 09/2020, but I don’t see anything much exciting happening after that. Possibly back to 5-7p EPS in future if we’re lucky?
There could be some medium term upside on the share price, but I think there might be better opportunities elsewhere. Hence I’m fairly lukewarm on TPT, unless something changes for the better.
.
.
Clipper Logistics (LON:CLG)
594p (up 1%) - mkt cap £604m
Clipper Logistics plc ("Clipper", the "Company", or the "Group"), a leading provider of value-added logistics solutions, e-fulfilment and returns management services, is pleased to announce that it has experienced unprecedented levels of activity in its logistics operations in both the UK and continental Europe over the Black Friday and Christmas periods.
Revenues up 50% on LY, for Nov & Dec 2020 - faster rate of growth than +27.9% in H1 (6m to 31 Oct 2020)
Ecommerce fulfilment doing well as expected, but so is conventional business
Strong pipeline of new business opportunities
Outlook - “Excellent level of confidence in the year ahead”
This bit has confused me somewhat, and I think should have been explained more fully;
Whilst additional revenue will not necessarily have a proportionate impact on operating profit given Clipper's contract mechanisms, this level of activity gives Management an excellent level of confidence in the year ahead.
Can any readers shed light on this? I’ve put a call in to the company’s advisers, so will report back if I’m able to get any clarification. I wonder if some contracts might have fixed monthly pricing, regardless of volumes, or use volume estimates?
Nothing is said about performance relative to market expectations, which usually implies that trading is in line. The tone of today’s announcement, and the rapid growth, does suggest to me that it could beat expectations possibly, for FY 04/2021?
Valuation - I can’t find any broker research notes, so can only use the 20.6p broker consensus forecast shown on the StockReport. That implies a PER of nearly 29, which looks a bit pricey for a logistics company, even allowing for the fact it operates in a growing area of eCommerce fulfilment. Holders must be anticipating that it’s likely to beat that forecast by maybe 10-20%, to justify the current price.
My opinion - the valuation looks well up with events, maybe a bit ahead. But that depends what the FY 04/2021 results end up looking like.
There’s also the issue of whether 2020 has been a bumper year due to covid lockdowns? Could that have brought forward some growth from future years? I wonder how much profit has been made on the covid-related PPE contracts? Press reports indicate that little cost control seems to have been applied by the authorities!
Personally I’m not interested in chasing CLG shares any higher. I think it’s had a great run, and a PER of about 20 is as high as I would pay, not 29 times current year earnings. A good business, but too pricey for me.
.
.
All done for today. Troubling scenes on TV in Washington.
See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

164 comments
Democrats have won Georgia. I assume green energy stocks to go gang busters up?
Viewpoints from experts on the macro side - if anyone is interested
https://www.voxmarkets.co.uk/m...
Are online competitors a threat? After all, buying tiles just needs a sample of 1 tile sent through the post, tiles are not really like a sofa where customers need to touch & sit on it, to feel the quality.
Regarding Topps Tiles (LON:TPT) - from experience, Topps TIles is great for physically looking at ranges of tiles and getting advice on adhesives, edging, etc (their sales people are very good)...I personally then went online and bought from Tile Mountain and Tiles Direct at less than half the price...saved a fortune even when adding delivery.
Am I alone in thinking there's something a bit sleazy about going into a shop, looking at the product, getting advice from the sales staff and then going home and ordering the product from an online competitor?
No, you’re not alone.
However, in the case of Tile Mountain they do have three very large stores. So, they are a physical retailer too but the prices are more like an online only business. I wouldn’t buy without seeing the product displayed. Although Tile Mountain were a long drive away for me the saving more than covered that cost.
Oooooo! Bank stocks are sexy
Hi Mojo
This would not have anything to do with your wager last week would it?
Tommy...
Ha ha...yes! No-one took me up on my one whole pint bet.
And my point wasn't that the banks are obviously fantastic...it was more putting the crapiest of the crap up against the shiniest of the shiny for 2021 -> Lloyds Banking (LON:LLOY) vs £THG
But I do have a piece of a number of banks with a view to them being a really strong decade bet (I'm up near 50% as bought near lows!). It's partly value, neglect and that they have cleaned up a lot...and its partly ebb and flow of markets over time and a vibe that banks will find themselves useful again. Its quite hard and costly to disintermediate their credit-money creation and if they don't create money then we will struggle to grow.
No-one took me up on my one whole pint bet.
Dang i live for one pint wagers - i hate the nightmare distraction of tax returns in Januarys - i miss all the good things in life - a free pint from mojomogoz would have been nicely savoured - ideally chocolate orange marshmallow plum porter please,
Its open...you can take Thg Holdings (LON:THG) side if you wish....despite today's bank fireworks THG does have ytd (2 day!) lead.
I feel more foolhardy than truly confident...but that's not uncommon
Ah, so you’re the reason Thornabian accused me of being a bank stock buyer :D
Crushing accusation for many...
I make no statement about whether he’s right or wrong.
But I have plenty of racey stocks in the punts portfolio even if I did have some “boring” stocks
Completely agree with Pauls notes on Clipper update. To me it reads "we have hade a great boost on revenue but don't expect to see the corresponding profits". Its certainly enough to prevent me from adding to my holding as I am no good with puzzles, like when is good news not good news, answer when its a confusing DNS. Will hold for now.
TRMR are we seeing another Director sell off
Lots of director selling at Hollywood Bowl (LON:BOWL) also.
You are going to see more director selling at Tremor International (LON:TRMR) as the remuneration has been structured in that way....a very American tech remuneration for US based managers in what is a US growth stock (note that insider selling to buying is historically ratio of approx 10:1 stateside I think...could be 20:1 but I think that's just the elevated level right now).
I don't know what it sold off today but my guess is due the aggressive short term growth stock sell off we've seen in US with dramatic value spike
MMT is great so long as you are a sovereign currency issuer and borrowing in your own currency - so it is a problem for both Eurozone countries and also for countries outside the USA and which borrow in USDs
Lockdowns too late, end the lockdowns, why are we locking down again, why did we lift the lockdown over X-Mas
We won't get a vaccine in a year, the vaccine is being approved too quickly and I am not taking it, why don't we have enough vaccines, I want the vaccine now.
Governments (and multinational Banks) are bureaucracies. For those that expect them to do things quickly / rationally then you may benefit from adapting your expectations.
FWIW and I am loathe to defend the government, my sister (NHS)) got 1st dose Pfizer vaccine on 23rd December.
Of course if I am personally impacted, I will not be quite as philosophical!
And in the interest of fanning more flames, has anyone noticed, markets are up and UK is outperforming.
Billions wiped on UK Plc in post Brexit shock!!
Happy New Year everyone
I am not sure why this has got so many down votes. It seems to be saying that half the country wants one thing and the other half wants something else which has often been the case over the last nine months. Also seems to be saying that any forecasts about the market are worthless which again seems to be the case.
Thanks doublelutz
As my wife might say, maybe its not what I said but how I said it - thought people would be more tolerant of Glib on a day when the market was up.
TBH, down votes don't bother me, prefer up (not quite a sociopath) but it is the ignominy of nothing that really grinds my gears!
"Are online competitors a threat? After all, buying tiles just needs a sample of 1 tile sent through the post, tiles are not really like a sofa where customers need to touch & sit on it, to feel the quality"
As I am in the middle of using Topps Tiles (LON:TPT) for my bathroom renovation I thought I would share insights. Is online a threat? For me the short and straight answer is no.
We have ordered samples through the post as well as picking up samples from their stores. Samples though the post are not ideal because the are so small, and your not left with a defining decision because the patterns on some of the rustic looking tiles can vary so wildly you never get a true appreciation of how they will look.
So we have decided to buy full size samples through the store on sale or return basis, and I am glad we did because some of the colours that you see on the website are not even slightly close to what you would expect, lighting is big factor in this as well which reinforces the need for store.
Their lockdown model looks like it can work in the meantime, just buy plenty of samples to save your self a few trips.
I was listening to a US investment program and I was a bit taken aback at the suggestion that the UK is a prime place to invest ...partly because of its government's response to the Covid vaccine. Really? Yes it seems. Both France and Germany are way behind. France has apparently so far administered just 500 doses to its population and Germany has woefully underordered having left the matter initially to the European Commission. A vision of red tape and bureaucracy fills my mind. The UK, on the other hand, has impressed by ordering as many of the various vaccines as it could and as early as it could...and the Oxford vaccine is seen as potentially leading the way in the World. Cheaper, easy to use, no minus 70 degrees issues etc.
The UK government has got a lot wrong (oh woe the education issues) in my view but on the vaccine it can claim rather a success that gives us the opportunity to be mainly protected from Covid much earlier than most of Europe. That is how others are seeing it and the UK is being held up as an example by many overseas politicians disappointed by their own government. Politics sure is strange sometimes!
Interesting fact: To date the UK has vaccinated more of its population than the whole of Europe has vaccinated put together.
A great recovery play potentially here. Fantastic TU from Equals (LON:EQLS) today. 20% circa up. I hold.
Big change of biz model from them from a B2C (i.e. Fairfx currency cards that gave too many freebie incentives to entice individuals like myself to use them - they were giving out something ridiculous like £50 freebie for a top up of £200 on their Fairfx card a few yrs back !) to primarily a B2B (with Fairfx (B2C) now on the backburner (and rightly so because B2C marketing expenses are significant).
Today's RNS :
The Group's recent trading update on 1 December 2020 noted continuation of positive trading into H2-2020. Since then, the strong performance has continued with revenue for FY-2020 now expected to be around £1.0 million ahead of market expectations at £29.0 million, reflecting a strong performance in the Group's B2B products in December 2020. Adjusted EBITDA is now expected to be around £1.0 million for FY-2020, which again is comfortably ahead of market expectations*.
* The Group believes that current market expectations for adjusted EBITDA average £0.55 million with net cash averaging £6.75 million for FY-2020. (Yay even shows u the market expectations!)
Last time when they posted a positive TU a few months back, PIs were still a bit dubious of the management having overpromised. By now, this should have receded to some extent. What I am delighted about is :
- great financials during covid ;
- loaded with dosh (even more than expected !)
- the strategic direction of where the company is heading (B2B) appears to be so much more higher profit margins than B2C model and is working;
- costs control
- management have got the message of over promising in the past and now appear to focus on under promise and over deliver with a recent new CFO.
- Big contract won with Homesend in the B2B2B market (I think Nov 20)
- Strong market positioning B2B - Their main clientele base are SMEs i.e. I recall the management saying their site gets loads of SMEs and traders from ebay and Amazon. Given the pandemic, I am sure the trend is for people, with loads of time on their hands at home, to start up their own biz and come up with things to sell from. So structurally, they are bang on trend (I suppose the bigger and med-sized companies are with banks or are with the likes of Argentex (LON:AGFX), Alpha Fx (LON:AFX) ).
- Having been a holder a Argentex (LON:AGFX), I was aware that Argentex (LON:AGFX) took a big hit during H1 2021 because businesses deferred their forex due to Brexit and Covid. I'd imagine that likewise this impacted Equals (LON:EQLS) too. Given that Brexit sorted and Covid - hopefully well on the way to recovery, sme's will have more certainty + confidence to buy forex. So therefore I'd expect for Equals (LON:EQLS), H1 2021 will be a strong performance.
- Once travelling overseas and vaccinations sorted, currency demand from B2C will shoot up.
Product wise, their real time FX system can compete with comparable if not better fees than up and comers like Transferwise (Transferwise is a fintech worth something like $5bn pre-ipo)
- Likely to engage in some M and A - could be buying the independents at relatively good suppressed prices.
- Most importantly, despite this big hike in SP today, huge upside in the SP - take a butchers at the SP in Jan 20 (hence I added more to my position first thing this morning).
If anyone is seeking further research, I suggest voxmarkets videos and see the 2 interviews between Paul Hill and the chairman a few months back - extremely insightful.
Clipper Logistics (LON:CLG) valuation doesn't seem so excessive when measured using FCF. P/FCF = 7.1 and PEGY = 1.2 seems quite good for such a high quality and growth company. On a blended basis a tad expensive, yes. Value Rank 44.
Somewhere (I don't remember where) I read that when the shareprice punches through a well rounded number, and stays above it, then it will leave this number behind. This could happen to Clipper if it punches through 600p. I hold.
Guys can we tone down all the political stuff. We seem to be getting loads today.
Its all very well saying skim past it, but it does make the thread cumbersome and longer to click through, and I'm sure the majority is not really relevant to small caps
If by "political stuff" you mean QE and MMT then you are dismissing what might turn out to be the most important post from Stockopedia - ever! It's MMT that is holding everything together at the moment.
Good Morning,
The analysis I read every morning continues to enrich my intellectual capabilities.However the concept of shorting a stock is difficult to understand.Is it beneficial to the economy which intern is beneficial to us.Why are companies shorted?In a recession what can stimulate growth other than QE.A candid piece on Why are companies shorted? Advantages Dis advantages of shorting.What happens to the companies after they have been shorted?Do they rebound or remain stagnant for a very long time.
A piece written on shorting can be very helpful.
Best wishes for the New Year to all Stockopedia Staff and Subscribers.
Hi Sady. Unless the kind folks at Stockpedia oblige and write an article on shorting - may I kindly suggest you google shorting coz there are tons of articles regarding it on youtube and on brilliant websites such as investopedia etc.
Companies that have shorted in the recent past that springs to mind would be Manolete Partners (LON:MANO) - a shorter released a report whilst they took a short position - you can see what happened to the SP, Boohoo (LON:BOO) , Burford Capital (LON:BUR) - a shorter did something similar to Manolete Partners (LON:MANO) - u can see the big fall in SP in 2019. As for unsuccessful shorts TESLA would spring to mind, - perhaps this will enlighten you https://edition.cnn.com/2021/0...
Cairn Energy (LON:CNE)
I hold mainly on the prospect of the tax arbitration payment from India
Although this is about CNE I guess it applies whenever there is a special dividend.
They go ex div for a special dividend 32p per share on 8th with a share consolidation after the special div to get the share price back to where it was.
Irrrespective of the why and where for from the company's perspective, when a company pays a special dividend do you think that it is better to stay in, receive the dividend (with the income tax hit), watch the share price fall to reflect the dividend no doubt by the same amount then reinvest the dividend or sell before then buy back in after.
Ditto with a share consolidation. This is not a 10 to 1 or anything like. Still not sure why they are doing it, but again as a general rule...stay in or dip out then buy back in? It is not clear from the RNS whether the pre dividend price relates to the ex dividend date or the payment date by the way
Millbank - IMH - the fundamentals are the most important - regardless of whether SP goes ex-div / consolidation. BTW, GL with the Indian arbitration - I reckon it's going to take another 3-4 years for outcome of a future appeal by the Indian gov.
Paul, as you say it is not that easy to get ones head around MMT (not sure I fully understand all the ramifications of it), but when you say balancing the books etc. is what the electorate want to hear, is it not that politicians tell them that because they know most of electorate won't understand MMT. Easier to tell the public what they want to hear, than to try to educate them! Particularly when politicians are equally certain that journalists won't understand MMT, so will mislead the electorate if politicians do try to educate them
I also doubt that many politicians understand it!
Hear Hear! Very unlikely they do. Given the complexities of the economy and its many internal and international interactions I doubt many will fully know its consequences even among the would-be experts.
It is better to be humble and alert to hubris, than plough on regardless. All ideologies, even the dismal ones of Economics end in relative failure.
I hear people speak about moving to a high taxation environment. Sorry, but we are already there in my opinion.
Pension contributions reliefs for higher earners have been eroded to very little. National Insurance levels for employees and companies is extremely high. Top rates of tax are stuck at 50%.
Dividend income tax allowances have been slashed. VAT is at 20%
Top rates of Stamp Duty are at 12% , and rates of 15% will apply in circumstances where property is non residential.
The one bit of sunshine has been CGT rates, but that is on the table for potential slaughter. Maybe another wealth tax is also on its way.
Yet the Govt has struggled to finance it spending plans until relatively recently, as a much larger tranche of society is supported through Govt income aide in various forms.
In a low growth environment all these impositions take their toll, and may be argued to self seed further economic growth restriction issues down the line.
Maybe this will lead to a greater and more appropriate income equalisation, but it is also likely to also to a Govt knows best mentality, with an endless queue of requirements.
Like the proverbial frog in the simmering vat, we don't fully realise the destination. Growth is the saviour, and if we don't get that, we will gradually silt up the UK economic machine.
I'm old, and probably my economics is less flexible than most. But i remain convinced that belief in money is a fragile thing - weaken it and it will disappear in a flash. Already savings are nigh on valueless and money is readily available to many people in large quantities. It is a short step for people to act on the knowledge that they ought to be in assets other than money. By calling it QE and telling people that printing money is really borrowing, Govts are getting away with it, but when realisation does dawn, inflation will happen very quickly and exponentially - and I can see very few defences.
It's scary just how quickly this kind of thing can happen if it does eventually go boom.
£MWE just announced contract wins of $1.7m in their defense wing. This share has been on a crazy ride the last couple of years increasing by over 250% fueled by its irrigation and 5G antenna businesses probably to the point of running ahead of itself and where it is now.
I am still long on it and see it has a long term hold for me but I expect a lot of choppiness this year with traders bouncing in and out of it. Oh to the days 2 years ago where no one even traded it in a week
Do you really want that lack of liquidity in your holdings? I don't!
It was more in jest, do I want it back at 25p with no liquidity no. I'd much prefer it where it is today
I have always been worried about money printing and how to protect my wealth. Against my previous doubts I have been converted to the benefits of Bitcoin to hedge my portfolio. Initially I was reluctant to buy directly so bought Argo Blockchain (LON:ARB) . However after listening to Michael Salford CEO of Microstrategy who has invested over $1bn in Bitcoin I bought my first direct Bitcoin in early November. See https://twitter.com/michael_sa... for an interesting read. Also checkout some of Michael Saylor's interviews. Yes, like me in the past, I was very sceptical but this guy is the real deal. He wrote the book The Mobile Wave in which he predicted the benefits of investing in the great compounding stocks like Amazon etc
Great idea! Are you also buying gold or silver too? All three for me feels safest and provides diversification against me being an idiot and having one of the three stolen.
NEWSTART. thank you for bringing the Stone Ridge letter to our attention, it was outstanding and worth reading every single word, to gain an idiots' understanding of Bitcoin.. and how we should view its implications for so many of us..Tony
When I checked about 4 years ago, getting on for 50% of Bitcoin mining capacity was in China. What's the position now? With control of >50% of mining, one could rewrite the Bitcoin blockchain.
Same story here. I really can recommend the book "The Bitcoin standard" which has some chapters about the history of money and the shortcomings of MMT.
Thanks Paul. More side commentary on MMT and where it might lead us would be really good. As far as I can tell the issue will be whether governments can control inflation when it does come (and it must) with either rates or taxes or both. In the meantime I have been upping my gold exposure as an inflation hedge.
"...as the democrats want to make institutional changes which would effectively guarantee them winning the next elections".
It's about time the Democrats did something to negate the decades of voting district gerrymandering that Republicans have engaged in! Take a look at the shape of some of the voting districts highlighted in this Guardian article, where Republican governors have ensured that separate areas with rising minority populations are lumped into a single voting district, even when they are nowhere near each other, so as to maximise the number of Republican voting districts and minimise the number of Democrat voting districts in a state.
https://amp.theguardian.com/us...
https://www.salon.com/2020/11/...
(And let's not get started on Trump's sustained effort to bias the courts in Republicans' favour by appointing huge numbers of Republican leaning judges)
Hi Paul, I hope you won't mind but I have forwarded your message on Quantative Easing and MMT to my MP as here in here in her Wiltshire Constituency we are bedevilled by the running out of funding for the completion of the electrification of the GWR and lack of a train station at Corsham. It made me wonder if David Cameron was short on savvy to ward off the critics of HS2 who have been so damaging, MMT being the tool near at hand.
Silver
Hi Paul,
I totally agree that current governments are effectively running MMT policies without informing the electorate and have in effect been doing do since 2008. What I’m not clear on is what will be the outcome of these policies. I do think the results will be the defining issue of this generation and that the acceleration in scale caused by COVID will make this clear in the next couple of years (rather than decades).
As you say above in another section, we have to look at what’s actually happening rather than what we think should happen and there is enough evidence now to make some conclusions.
MMT doesn’t seem to cause inflation at a consumer level. There is some reasonable debate whether that is only because of technological changes (ie the internet has effectively made the marginal cost of things like books, learning, music, entertainment zero which has huge effects on the basket of goods used to calculate CPI) but either way, it seems likely to hold into the future as the pace of technological change hasn’t slowed down over the past 30 years.
However, MMT causes huge inflation at the asset level and in fact in any scarce resource. This intuitively makes sense to me - there has to be a supply imbalance to cause prices to rise so effects are only seen in those goods where there is a fixed supply.
The problem with this is it creates an enormously imbalanced society. Those who have capital and can buy scarce resources accumulate more and more of the wealth of society but in effect it is at the expense of those who don’t. The only way to counter this is to raise interest rates (looks currently impossible but note recent changes in yield curve starting to angle upwards) or redistribution of wealth by taxation. I don’t know which way this will go but I do note the Wealth Tax Commission recently reported back recommending a 5% blanket tax for everything above £500,000 with no exceptions. I doubt this is coming soon but it really needs watching.
The only contrary factor for the UK is Brexit. There is likely to be some supply shocks to the UK over the next few months as they change their current trading structure. The exchange rate is key determining factor (import prices rise and prices rise) and for the UK it is that which now determines the amount of QE the UK can or should do. They have to balance the pound with currencies of EU and US. Too weak causes import pricing to rise and prices rise for consumers and inflation starts, too strong and UK exports become too expensive and growth recovery stalls.
Anyway, my base case is boom times for UK shares this year with enormous volatility. It is going to be fascinating to watch.
I do agree re growing inequality. This from ADVFN morning email ''Bosses of top British companies will have made more money by teatime on
Wednesday than the average UK worker will earn in the entire year,
according to an independent analysis of the vast gap in pay between
chief executives and everyone else. The chief executives of FTSE 100
companies are paid a median average of £3.6m a year, which works out at
115 times the £31,461 collected by full-time UK workers on average,
according to research by the High Pay Centre thinktank. - Guardian''
A one-off wealth levy makes eminent sense. Though in practice it might be better at 3+ yrs to defray the huge admin costs of devising and implementing a fair system. For too long the UK has stuck with the quaint concept of taxing money only when it 'moves'. (Rates being the exception, though they were originally designed to cover current expenditure on local services.)
I can't see this taking root with the current gov't. But instead they could tackle some of the main loopholes/exemptions - eg IHT, CGT rates. They've missed many opportunities to raise the ridiculously low multiplier applied to DB pensions for LTA purposes as interest rates have tumbled. But this would be seen as a stealth tax on impoverished public sector pension millionaires so likely won't happen. Really just requires some boldness from the young Chancellor!
I'm not convinced by the idea that we haven't seen inflation at the consumer level. Over the past 10 years pints have got way more expensive, chewing gum is 55p - I think it was about 20p 10 years ago. Items in supermarkets might be the same price but only because of the introduction of "low cost" (e.g. Sainsbury's Basics) items, so really quality is being lowered for the same price. Packets of crisps and chocolate bars have got smaller. I think the CPI methodology disguises real inflation and doesn't account for quality changes.
Professor Jonathan Portes' rebuttal of MMT - one of various -which is notable for his also being a left-wing economist:
Nonsense economics: the rise of modern monetary theory
MMT is increasingly popular among left-wing economists. Unfortunately it is a mixture of the tautological and the tendentious
https://www.prospectmagazine.c...
Above all, MMT is being used to support a “big state” agenda. It would mean that the government plays a much larger role in the economy, for good or ill, and in good times as well as bad. Higher public spending would also still mean higher taxes, even if the rationale is to prevent overheating rather than balance the books.
In short, MMT is simply a repackaging of some old ideas to appeal to a new audience. There really is no such thing as a free lunch – even from a magic money tree.
https://iea.org.uk/beware-the-...
The funniest thing about the left supporting money printing to raise money for governemnt - it just makes the rich richer and pulls up the drawbridge so those who can’t currently afford assets to back their wealth, but could as they get older and their life situation changes, will never be able to afford assets to back their wealth. It’s just a huge transfer of wealth from the poor to the rich and as someone who is benefitting from this right now, it pretty much sickens me, but no, I won’t be giving it all away - I’ll find a way to live with my conscience. More champers anyone?
I do not particularly believe in MMT either. That does not make the alternative right.
Personally, I thought the value of a share reflected the value of the company (roughly)
So
the value of a currency reflects the value of the country (roughly) - which could be roughly the ability of that country's governments ability to repay debt (I am not an economist).
At the moment, the govt can issue currency / sell gilts that yield 0.625% until 22 October 2050 at 94.545. So we can borrow 100, pay 65p pa, pay 100 in 2050 that at 2% inflation in real terms is ~52.
It is so tempting to fill your boots.
But only if that money is used sensibly - a public transport system as good as Londons for Birmingham / Manchester / Newcastle / Leeds etc would be a wise investment as there is evidence that the reason Birmingham's per capita GDP is about 25% less than Lyon's is the lack of a mass rapid transit system that allows people to get to work.
Compared with HS2... ...at this point politics - how do you know money is well spent?
The theory I choose to believe is articulated by Steve Keen
https://www.forbes.com/sites/stevekeen/2015/02/28/what-is-money-and-how-is-it-created/
"Banks create money by issuing a loan to a borrower; they record the loan as an asset, and the money they deposit in the borrower’s account as a liability. This, in one way, is no different to the way the Federal Reserve creates money ... it is simply the nature of a monetary economy: money is simply a third party’s promise to pay which we accept as full payment in exchange for goods. The two main third parties whose promises we accept are the government and the banks."
who thinks we may be looking in the wrong place
"That’s simply the nature of money: it is not backed by anything physical, and instead relies on trust. Of course that trust can be abused—and frankly that’s done more often by the banks than by the government. ... we continue to ignore the main game: what the banks do (for good and for ill) that really drives the economy."
Moving on
Two things seem to be true:
The stock market seems to be supportive of any old bubble at the moment
The mirror of this is that gilts buyers are willing to pay an awful lot to be sure as possible that they can get their money back.
Something is not right
very good overview andrewdb!
I guess the elephant in the room is when will inflation start up, next year, five years time or a century away - no one has a clue really.
MMT sounds like a policy with some credibility, ie expand money supply to account for expanding GDP with zero (ish) interest rates. But it also sounds like one in which it would be very easy to overshoot and then introduce inflation. Of course individuals tend to dislike inflation, but Governments with enormous debt, not so much. So from Sunak’s point of view it may be fine either way.
The IEA is a right wing think tank which receives funding from the tobacco industry. What they are not doing is providing objective impartial analysis but merely doing what those funding them expect.
why has this investment site become a home for those seeking to communicate political propaganda.
Interesting article, thanks EdmondJ. It echoes my view on reading the Kelton book, that it's wide-eyed revelation that Govt spending comes first, and taxation is just used to keep inflation under control, struck me as pretty ridiculous. As your article points out, Govt spending and taxation occur in lockstep, all the time. Neither happens before or after the other, they happen at the same time!
I feel that Kelton's book is inconsistent. The main message of the book is that Govts can spend on anything they want, with no limits. Then she contradicts herself by saying that QE has to stop if inflation takes hold. The problem with that, is if you look back at what actually happens when inflation takes hold, it becomes almost impossible for Govts to reduce spending & stop money-printing, because the automatic stabilisers kick in, and public spending inevitably shoots up once inflation takes off - e.g. public sector payroll costs go through the roof with inflation-linked pay rises, workers go on strike if they are not given pay rises, unemployment rises as businesses go bust. etc. Hence it seems very naive of Kelton to imagine that Govts could just stop money-printing at will. History shows us that simply doesn't happen.
I've been reading the (very heavy going!) Charles Moore 3-volume authorised biography of Thatcher. The battles her Govt experienced from 1979-82 to control inflation & rein in Govt spending, were very severe. All MMT supporters should be encouraged to read up on that!
My view is that, given we don't know where the limits of QE actually are, then it should be used with caution. If inflation is set moving, it becomes self-fuelling, and the consequences are catastrophic. Since my trip to Zimbabwe in 2019, the currency there has devalued to only 1/25th of what it was worth at the time I visited. Apparently now, the situation is unthinkably bad, with a lot of the country in semi-starvation, and reduced to begging.
Is it really worth risking hyper-inflation here by being aggressive about QE? I'd say not. However, using QE in emergencies, for limited periods, seems very sensible.
Regards, Paul.
I've ordered the book on your recommendation as I've seen it being referenced a lot lately and to see if it dispels my ignorant view that it's just a belief in magic or alchemy.
One of my Stockopedia Challenge picks, Bidstack (LON:BIDS), is going nuts today on no news.
Anyone have any idea why? I’m thinking pump and dump but would appreciate a wider community view.
It was on a website called ShareTalk this morning. Doubt that's been enough for the rise though. I think it's a case of people looking for lockdown benefitting shares and gaming related ones are all on the up. It's the right sort of company and if it was listed in the US it would have gone to the moon and beyond by now (in r/wallstreetbets language).
Bids did announce a couple of weeks back that they expect 2020 revenue targets (£1.5m) to be exceeded, but that's the only 'news' that I'm aware of.
I'm in this share as a speculative punt, and still underwater having invested last year.
I like the concept, its easy to 'get' - mix a high revenue industry (advertising), with a high-growth market (gaming) and first mover advantage. Sounds great.
But communication from the company over the last 12-18 months has been poor in my opinion and at times misleading. But I still believe they have a chance of scaling up and becoming 'the' go-to gateway for in-game advertising.
They also have a good relationship with Codemasters, who it seems (at the moment) will be taken over by EA. Perhaps EA would look at taking over Bids as well, or at least further incorporating their platform into games with huge markets like FIFA and NFL (Bids already have some presence in FIFA, sponsoring the NFG esports team).
Pure speculation, but at the moment I'm not aware of any material news for the rise over recent days, It's been on a rip for the last week.
EA already do in game advertising in the NBA franchise. There was a bit of a revolt over it iirc.
I remember a backlash recently in a UFC game, but if anything it helped the case for Bids.
The ads that got the negative reaction were pop-up ads between games, which the gamer is forced to sit through. They are generally disliked, as it interrupts the gaming experience. Like sitting through ad breaks during a film. Can make it unwatchable.
However, Bids specialise in 'native' advertising which is part of the game environment, so unobtrusive and can even enhance the gaming experience. Billboards, floor mats, advertising hoarding, shirts etc. No popups.
My bad, is was 2k Games, not EA, but yes, exactly the same thing - unskippable ads in a premium game. No wonder the gamers are miffed, I would be too.
I’m long £BIDS , also in my ‘punts’ portfolio with a small holding that’s rapidly turning itself into normal position without me having to buy more.
Same SP rises with Gaming Realms (LON:GMR) and Gfinity (LON:GFIN) (not so much)
All I want for Christmas - Hipgnosis Songs Fund (LON:SONG) announces yet another song catalogue purchase, this time Neil Young's.
www.londonstockexchange.com/news-article/SONG/acquisition-of-music-catalogue/14815572
That's the third one this week - and it's only Wednesday.
Hipgnosis Songs Fund (LON:SONG) bought a 50% interest in Neil Young's catalogue. I think it's smart of him to retain 50% so he gets his share of the upside if and when they do deliver on their promises to extract more value from the songs they buy.
Hipgnosis Songs Fund (LON:SONG) bought a 50% interest in Neil Young's catalogue. I think it's smart of him to retain 50% so he gets his share of the upside if and when they do deliver on their promises to extract more value from the songs they buy.
I also noticed there was no gushing quote from Neil Young as you do with other artists in Hipgnosis Songs Fund (LON:SONG) acquisition RNS'es! Great to see he's still a smart, bs free old curmudgeon! :)
All the best, Si
I see Neil Young has just removed most of his albums off Tidal because of dispute about MQA.
Wonder if Rod Liddle knows about Hipgnosis?Rod's frequently written that 'Tonights the Night' is his favourite album with 'On the beach' a close second.Maybe he should also buy shares in 'On The Beach' Personally i think Young only writes 2 types of good song and his backup band Crazy Horse sound is too samey .Youngs best songs are though some of my favourites which leads to a question as to whether he is overrated or not?
BBC Parliament Channel has had on over the last few days a very interesting parliamentary session with MPs keen on music quizzing Musicians and Promoters about the dismal future of working musicians earnings and what a disaster Brexit will be for professional musicians who are not mega-stars .About time we saw those Brexit bigmouths like Rod Liddle and Gove who profess to like culture get quizzed about it ?
Hi Paul, great article as usual - thanks! I’m looking forward to your review of your own portfolio performance in 2020. I sincerely hope it was a successful one for you and that the shorts didn’t nullify your gains.
Hi barrywp,
I did a quick over view of my own portfolio in 2020 with Tamzin on piworld, so thought there wasn't much point in repeating it here.
In a nutshell, hedging with short positions in Feb-Mar 2020 made a ton of profit, and my retail/hospitality longs lost money, but not as much!
A couple of big winners, including Best Of The Best (LON:BOTB) & McCarthy Stone takeover bid.
More recently, heavy buying on extension of furlough scheme & Pfizer vaccine approval has worked out very well, but followed a poor performance over the summer & early autumn.
Overall - a miserable year, but very successful for my portfolio overall. Although I did badly in 2018 & 2019, so needed a good year to repair the damage.
Since everything was affected by covid, then it's not really worth looking at all the individual stocks I held this time last year, particularly as I made a deliberate decision to hold the individual stocks, but hedge overall with shorts.
Regards, Paul.
Thanks, Paul, and glad you had a good year overall!
"As mentioned yesterday, it's always better to focus on what is actually happening, rather than having a theory as to what should happen, and blindly sticking to that conviction."
So so true. Just by following this simple mantra there is money to be made (and money to be saved). I need to get this tattooed on my arm to stop me making the same repeated mistakes! Thanks Paul
Try not to get too political on here, but as I understand the US senate elections could have a profound impact for generations to come, as the democrats want to make institutional changes which would effectively guarantee them winning the next elections.
They want to give up to 10m illegal immigrants the right to vote, and to make washington a 'state', which would basically guarantee them 2 more senators and 5 seats in congress.
The senate vote in Georgia is important, beyond its implications for the upcoming Biden presidency.
Similar to what the Tories have just done here then. I suppose one way to 'Level up ' is to take away MPs from Wales and the North and put more in the South East.
https://www.thelondoneconomic....
Indeed, same kind of move.
Flawed analysis.
Several parts of the country are over represented with MPs.
It’s an economic and political fact that those who live in the region that on average people earn the most, have the most wealth, are responsible for most of the GDP generation get the least political say.
The three non England nations even have their own tiers of government yet their MPs are fully entitled to have a vote on items that only affect England.
Another Labour mess. Americans should be wary of vested interest gaming the political process, it’s very hard to balance it back.
Not all what the "Tories have just done here then", unless you have a problem with fairness.
Details of the current review can be found at https://boundarycommissionfore...
That’s complete nonsense and a myth peddled by the left echo chambers on social media.
The constituencies here are not set by the government or any political party they are set by the Boundary Commission who are independent.
This is a necessary process as over the years population changes create imbalances where some constituencies have far too few voters and some too many resulting in some areas being over represented and some under represented.
Thanks, Paul for your relentless efforts on this blog, it's been a huge help for myself personally to see how you analyse companies and the thoughts and mistakes that are made as part of that process.
On the vaccine front, the current 45k per day will need to rise to 343k per day in order to vaccinate the 30m , vulnerable people, by end of June.
Given the scale of the NHS and robust distribution networks through the UK I believe this is possible but its a huge task that's worth keeping an eye on. Hopefully, we will see drive-through vaccination centres in the very near future.
I am a retired vet given literally 10,000s of vaccs over the years. I have volunteered. Deathly silence in response. Not the only one I might add
Thank you for volunteering.
I think people need to show some patience, this is a huge logistical challenge and takes time to spool up :)
I think people need to show some patience, this is a huge logistical challenge and takes time to spool up :)
You say that, but what have "they" been doing for the past many months. It's not as if the possibility/probability of a vaccine is much of a surprise to anyone.
What have ‘they’ been doing?
Apart from ramping up testing.
Trying to sort out track and trace.
Sorting out the PPE mess.
Concentrating on getting a Brexit deal.
Trying to make schools safe.
Trying to get the economy moving.
Trying to clear a backlog in routine appointments and elective surgeries.
Not much.
Lots of "trying"s in there.
"Not much."
I'm not saying it's been easy - but at least they've had quite a bit of notice to get things right as far as getting the vaccine distributed and into people's arms. Plenty of time to get things "spooled up".
If you think you can do a better job, feel free to volunteer your services to government.
I personally know someone helping to organise the vaccination programme, she said they weren’t expecting vaccines to become available until Spring, so they were concentrating on shooting the closest crocodiles to the boat, testing, test and trace and keeping schools safe.
I find it frustrating, there’s little praise for things that have been done well, just sniping at things, with no idea how hard it is, saying it’s taking longer than it should.
They could probably get loads of people vaccinated quickly by doing it in geographical areas, but then everyone would complain “it’s not fair”.
The government can’t win.
I think you mean creating the PPE mess
There was a worldwide shortage.
But as I said recently in reply to a very polite post - we all view the world through our own prism. If you want to believe it was all this government’s fault, I doubt I will change your mind,
As far as I can tell the program is currently vaccine limited rather than manpower limited at the moment.
My wife is a GP at one of the 2 practices running the program in her PCN (primary care network) area. PCN size approx 100,000, so assume 50,000 to vaccinate at the current government 50% target. They're currently receiving 1 vaccine delivery per week, alternating between the 2 distributing practices, which is approx 1000 doses per week. Which implies 100 weeks, or 2 years, to double dose the target population.
Each delivery takes 2.5 days to get through. The jabbing staff are shared between the 2 practices. So they can easily double throughput in the area with no additional staff if they could get the vaccine. With overtime and weekend rota they could probably triple throughput on current staff. After that then a volunteer army could be useful. But that comes back to needing more vaccine delivered!
As far as I can tell the program is currently vaccine limited rather than manpower limited at the moment.
The current supply issue is a lack of the glass vials needed to transport the vaccines according to JVT. Basically the entire supply chain is stretched and fragile.
Still, you'd hope they'd spend the time preparing by getting volunteers ready. We have to scale up vaccine delivery to reduce NHS load. Kings has already stopped urgent cancer operations because there are no critical care beds available. This is going to be a very close run thing.
timarr
On Covid vaccinations, the number 1 issue for the country, is the lack of transparency about the limiting factors not tragic. Why are we having to speculate on what should be a clear timeline.
Is it a vaccine supply issue - if so what are the impediments? Remember the rally to make ventilators? I am seeing rumours around glass vial shortages. I absolutely do not know but the fact this is rumour vs published fact. This where parliamentary scrutiny and ministerial statements are needed
Is it the ability to inject the vaccine? If this is the constraint, mobilise and retrain pharmacists, diabetics (!) not just say call in the army.
If Logistics is required do we want Tesco and Amazon or squaddies doing the job.
Israel has a pioneer/war mentality : we lack similar boldness from our political leaders. Boris should remember his hero Churchill replaced Chamberlain during the war to prosecute it more effectively. The end may now be in sight but lets get there sooner.
Every day of delay costs millions and this is one of the rare cake-and-eat-it moments. If we move fast we save lives AND we save money/protect the economy. If we move slowly....
Gaming Realms (LON:GMR) posts an encouraging update today regarding the granting of provisional i gaming license in Michigan. This will now complement their license in New Jersey and could potentially add a similar sized revenue stream to their business (as the state populations are very similar). I have a small position having seen their presentation in December's Mello event, see decent business momentum and the possibility of being a takeover target. Anyone else hold on here?
Morning Oldschool. I also hold a small position after a particular PI podcast (thanks Tamzin!)
An interesting little company which has potential to sell off the shelf games to US casinos or very possibly be bought outright. I like it quite a bit but don't personally go to a full position on pre-profit stocks.
Hi OldSchool05,
Re Gaming Realms (LON:GMR) - I think it sounds potentially interesting, and I've dug into the numbers in a fair bit of detail. The crux for me is whether revenues are recurring/repeating, or one-off licensing wins? The company seems a bit vague on this. This is such an important point, but nobody I've spoken to seems to know!
If revenues are set to keep rising strongly, then it could generate nice profits.
I think it needs to do another placing, as cash looked thin last time I looked.
Cashflow statements look quite grim, as it capitalises a lot of development spend.
However the games themselves are an interesting twist on slot machines, and are clearly popular judging by the impressive client list & contract wins.
Potentially interesting, but I need to get more clarity on the revenues model.
Regards, Paul.
Hi Paul,
Just re-watched the Gaming Realms (I hold) presentation from one of December's Mello evenings. Here is a question and answer re licensing which may help:
Q: How do you charge for your content licensing? Are these fixed, monthly annually one off fees or is it linked to the operators take?
A: All performance based, based on player spend per game per operator, the more successful the game the more the license fee.
Regards, Ian
If the Democrats win control of the senate then Biden should be keen to show "going green" creates jobs in wind power, electric cars etc. In contrast to Trump who was keen to protect jobs in the old fossil fuel industries. It is a pity that the only major sustainable environment investment trust in the UK is £IEM.
Stevenlondon3 - There is an i-share etf £ICLN that is Clean Energy that seeks to track the investment results of an index composed of global equities in the clean energy sector. I Hold.
Another Ishrs ETF is £ INRG. I hold
I think they are the same thing except £INRG is priced in pounds and £ICLN is priced in US dollars?
The next sun spot activity low in the mid 2030s is going to create some real challenges for climate change theorists. We’re already starting to see the impact of the reduction in sun energy output.
To the haters, I didn’t say pollution isn’t bad and I do think we should look to reduce poisons in the atmosphere but the sun activity is falling.
Don’t take my word for it :) Here’s a couple of links to get you started, it hasn’t been widely reported yet. I’m sure this freezing winter will get people more interested in what’s happening to sun activity.
https://www.sciencetimes.com/a...
https://spaceweatherarchive.co...
Re, Solar Decline theory
That's going to bugger up Climate Change theory, The BBC/Guardian, X.R., Greta's green agenda.
Well, the NASA blog states that the solar minimum will merely delay man made global warming, which is why I say it will cause challenges for man made climate change theorists. Some people think the solar minimum could lower temperatures by over 1 degree (not NASA though which thinks 0.3 degrees is the maximum benefit according to the linked blog), which would give us more time to develop less polluting technologies but we shouldn't be relying on that - we'll get lucky if that does happen.
My personal view is pumping the atmosphere full of poisons has to be inherently bad, whether or not the CO2 leads to global warming, so I am an emissions reductionist either way.
Or you could look at some real science - https://climate.nasa.gov/blog/...
Sure, but none of that negates what I said, you just found another blog.
From the NASA one you kindly linked.
“Some scientists speculate that this may be the beginning of a periodic solar event called a “grand minimum,” while others say there is insufficient evidence to support that position”
And
“These studies have suggested that while a grand minimum might cool the planet as much as 0.3 degrees C, this would, at best, slow down (but not reverse) human-caused global warming”
Which aligns quite nicely with me saying “The next sun spot activity low in the mid 2030s is going to create some real challenges for climate change theorists. We’re already starting to see the impact of the reduction in sun energy output”.
Regarding Headlam (LON:HEAD) ,
I used to hold but got tired of waiting for the market to recognise its virtues and sold 2.5 years ago. I agree with Paul that there’s a strong upside. Anyone who’s been doing home improvements since the end of the first lockdown probably knows that all the supply chain companies are busy, many very busy (e.g. kitchen fabricators, window companies, door companies etc.). The three main drivers for this appear to be working from home, spending the money saved by not taking foreign holidays and the frenzy in the housing market caused by a number of factors.
Now this is all a bit reminiscent of the frenzy that was caused by the end of mortgage interest tax relief. It caused a large amount of economic activity but then an almighty hangover when the music stopped. So, I see a boom and bust cycle for companies linked to home improvements, a strong run up but then a bust rather than a return to normal. The housing market will cool and people will spend their disposable income on catching up on the travel they’ve missed (holidays or seeing distant relatives). Timing will be crucial.
Totally agree with boom and bust hypothesis for homes and said improvements, but my counter argument for Headlam (LON:HEAD) is that they are one of largest in Europe and bust will hit smaller competitors with worse balance sheets harder. They could pick up market share as others falter. In addition, they were putting finishing touches to massive freehold (I think) UK distribution centre near Ipswich prior to COVID and were on the up and up prior.
(I hold)
The historical figures for Headlam (LON:HEAD) don't suggest boom & bust. It tends to be a steady performer, so I don't see any reason why that would change.
Also, I agree that the Govt has stimulated the housing market with Stamp Duty reductions, and there are worries about cliff-edge effect. However, we're seeing time & again that they extend these support schemes. Hence I would say a very high probability that some kind of Stamp Duty stimulus continues throughout 2021. It should be scrapped altogether in my view, as it doesn't raise much tax revenue anyway, and probably more tax could be raised via VAT & payroll taxes, if Stamp Duty were permanently abolished, due to abolition likely permanently stimulating the house moving market. We should be encouraging people to move house, as it stimulates the economy in lots of different ways.
Regards, Paul.
In terms of boom and bust - I'm expecting the trading update to look very rosy on the 21st, likely for the good results to continue through to the June 2021 results but then normalising. So I'm expecting the market to look very favourable on Headlam over the next 6 months - and share price rises along with that. I hold and will probably look to sell after the June results, but before the December results.
A buyer has a budget to buy a house of say £500k. Pre-holiday that would have included £15k for stamp duty, so the price limit of the house itself was £485k.
With the holiday it means the buyer can now afford to pay up to £500k for the house, so prices rise accordingly to meet demand. A house that would have been on the market at £500k now sells for £515k. This isn't just theory - house prices in the affected ranges have risen strongly since the holiday.
So all the holiday has achieved is a diversion of much-needed funds from the Treasury into the pockets of house owners who were already sitting on vast, unearned and tax-free profits, whilst at the same time causing still more inflation in the housing market to the detriment of first-time buyers.
One of the most stupid and regressive fiscal measures ever.
I think you're forgetting that the £15k stamp duty has to be paid upfront when purchasing. The stamp duty holiday means buyers dont have to the burden of finding an extra £15k on top of their deposit. If the house price increases by £15k this can be added to the mortgage e.g. on the basis of a 10% deposit the buyer only has to find an extra £1.5k. Quite a big difference and definitely beneficial to the buyer.
Indeed the recent historical numbers for Headlam (LON:HEAD) don’t show it has suffered boom and bust before but I didn’t say that they had.
The case I was making is that the market they are in is going through a boom and if there is a cliff edge ending to the factors that caused that boom, as there was with the end of mortgage interest tax relief, then that potentially causes a bust in the market that they can do nothing about.
The Stamp Duty holiday may be extended but that is only one factor as I pointed out.
The pivot from discretionary expenditure being on home improvements to being on travel is going to happen at some point as travel reopens. That is potentially a very rapid process.
There is a certain inevitability that a substantial amount of future sales are being pulled forward to the present and that will cause a slump in sales at some point in the future.
Now this is all a bit reminiscent of the frenzy that was caused by the end of mortgage interest tax relief. It caused a large amount of economic activity but then an almighty hangover when the music stopped. So, I see a boom and bust cycle for companies linked to home improvements, a strong run up but then a bust rather than a return to normal.
I think you have to remember that interest rates are very different now to those in April 2000, when they were 6%. So I'm not sure there's going to be quite the hangover this time, if at all. Money is cheaper than it's ever been whether you're a government or consumer.
I don't really have a view on this. Just making the point that that the landscape in 2000 was very different to that of today with 0% interest on cash deposits meaning there is little incentive to save when consumers can "invest" money into home improvements.
All the best, Si
I agree Si. The cliff edge effect back then was compounded by the interest rates being high making the tax relief more valuable.
The factors are different this time. What isn’t really in doubt is that there’s a boom in home improvements going on right now, with a range of factors behind that. Whether that boom results in a slump/bust remains to be seen. As someone else said, selling out before the autumn could be a good way to protect against a bumpy ride in this type of stock later in the year.
Dear Paul, I joined Stockopedia in the spring having just put a good chunk of my savings into investments to try and capitalise from the massive market fall. I put 1/3 into a global fund, another 1/3 to a independent investment specialist and the final 1/3 i put into a GIA and invested myself. I have had winners and losers, I am making mistakes, I am still not sure when to sell some shares i have (i now have 40+ stocks with £2-6k in each - probably far too many).Biggest Winner = Menzies 105% up - biggest loser Loopup 35% down. but I am beating the professional fund managers! I am not sure why I am sharing this waffle when all I really wanted to say was thank you. I really look forward to your wise words and calming influence everyday. Today's blog re national debt is another example of you educating and commenting on financial news to us novices in a concise brilliant way. You are the Prof Karol Sikora of the Covid Investment world (I hope you like his messages!). Many thanks, please keep up the education and insights. PS how many shares should I sell to buy more BOO? haha
Very kind, thanks Mark!
Many thanks from me too Paul. Been subscribing about a year now and have had great success following some of your "tips" . Today was pleased to see your comments about Topps Tiles as I had been wondering whether to sell (always the hardest decision I think) having made 22% and 33% on the 2 purchases I made earlier this year. Not the best investment I have made this year, but that alone has paid the cost of subscription (and a couple of short holidays when they become a thing again).
There are some great books out there giving an insight into different strategies for when to sell (and buy). Ive read a couple over the Xmas period which I really enjoyed, and there are plenty of on-line articles from some of the well-known FinTwits which will also provide plenty of thought provoking views.
My personal learning experience from the last 9mths is "run your winners". Ive sold out of a few stocks that I thought had made me a tidy packet to then look back and realised I'd got out way too early. Ive missed at least 3 or 4 multi-baggers.
Interesting comments on MMT Paul, thank you. The book looks interesting.
Although December seems an age away, we have now published the Ra International (LON:RAI) investor presentation given on 17.12.20 by management. A rare opportunity to 'meet' them all. It provides a really comprehensive overview of what they do, the strategy they're pursuing and why they IPO'd. This illustrates how it's coming together, evidenced by the order book. At the end lots of investor questions (all those frequently asked, and more.) Video or Podcast.
Forthcoming, on Friday 15th January, 1.15pm Accrol Group (LON:ACRL) will present interim results, (which are being announced on 12th January). This will be a full presentation followed by Q&A. Register here.
Finally, if any of you missed the 8 short 2020 round up interviews, of learnings and 2021 picks with top investors including Paul, Leon Boros, John Rosier, David Thornton (Growth Company Investor), Mark Slater, Slater Investments, Cockney Rebel, Richard Leonard & Stephen English, Stellar Asset Management, they are all here, video & podcast.
Paul the big boys must be following you into Boohoo (LON:BOO) and rightly so - some hefty trades into close last night.
As it stands it looks like the Democrats have, extraordinarily, taken control of the Senate by winning both Georgia runoffs so we should look forward to an entertainingly exciting day on the markets (and, no doubt, on Twitter). Alternative energy and infrastructure spend look like winners, probably bad for big oil, tech stocks and drug companies?
On Paul's comment on a V-shaped recovery, Andy Haldane of the BoE was making this point really strongly back in Q3, 2020. The problem for a lot of investors is that the rebalancing of the economy away from face to face businesses is invisible. When you think a thriving economy equates to busy High Streets then you're less likely to accept the data rather than the evidence of your own eyes.
But it's true - the Clipper Logistics (LON:CLG) update today, for instance:
The Company is pleased to report that, for the months of November and December, revenues in its logistics business were 50.0% higher than in the corresponding period of the prior year, with strong growth in both e-commerce related activities and non e-fulfilment services.
The longer lockdown measures continue the more permanent this change will be. However, where online services can't substitute for face-to-face ones - say in cruises or leisure activities - then when reopening can occur the rebound is likely to be strong.
timarr
what I don’t get about that update - revenues 50% up, but profit remains unchanged. Are they running a business or a charity?
what I don’t get about that update - revenues 50% up, but profit remains unchanged. Are they running a business or a charity?
I don't hold, so I don't know for sure, but I think their supply contracts are fixed term, fixed price. Presumably when they were negotiated that meant that they were guaranteed income regardless of volume, but obviously they couldn't predict the pandemic.
No doubt future contracts will be on more favourable terms.
timarr
timarr, re £CLG are you perhaps confusing revenue with volume? Increased revenue must lead to increased profits unless costs increase in lockstep with revenue. Increased volume alone would lead to increased costs and therefore almost certainly a decrease in profits. Your hypothesis of increased volume but fixed price/term is inconsistent with the trading update, which clearly identifies increased revenues. The RNS does not in fact say that there will be no increase in profit arising from the increased revenues. It says: "....additional revenue will not necessarily have a proportionate impact on operating profit..."
timarr, re Clipper Logistics (LON:CLG) are you perhaps confusing revenue with volume?
I don't hold, so I'm not really exterting brainpower into trying to understand it :-)
The trading update refers to "contract mechanisms" as the reason for increased revenue isn't leading to increased earnings. So, hypothetically, increased costs due to bonuses to staff or something?
Dunno, it's not really a sector I have any expertise in. Maybe someone with logistics knowledge could opine?
timarr
I read the following two sentences together, and thought the additional revenue with no impact on profit related only to PPE ordered online via eBay, not to the rest of operations. No I don't think they are a charity, well, I hope not. (I Hold)
Of particular note is that Clipper has fulfilled its one-billionth item of PPE ordered online through the portal established with eBay in the spring of last year. This service has now been extended beyond local health care providers including GP surgeries and nursing homes, to educational and other communal establishments.
Whilst additional revenue will not necessarily have a proportionate impact on operating profit given Clipper's contract mechanisms, this level of activity gives Management an excellent level of confidence in the year ahead.
Ah, I’ll go read it again. I only skimmed it through bleary eyes. Probably a case of me needing to engage brain before keyboard.
Thanks
ok, I think the Zipmanpeter response makes most sense, the contracts are of a sliding scale nature.
Clipper Logistics (LON:CLG)
IGotPoesJacket
what I don’t get about that update - revenues 50% up, but profit remains unchanged. Are they running a business or a charity?
I read the announcemnt this morning i couldnt find any indication that profits would remain unchanged despite the 50% increase - what made you presume profits would not be higher due to these higher sales.?
It is rather unhelpful that they have given NO update with regard to year end numbers compared to any forecasts - specifically not even going to the trouble of advising whether any forecasts are in place at present - i kind of presume they are though for this company so perhaps the lack of "ahead of prior forecasts" indicates they are only on track. Note they may have expected above mentioned volumes so it could be that profits are higher in this period "as has been expected" due to expected higher sales.
Looking at what they did say
Whilst additional revenue will not necessarily have a proportionate impact on operating profit given Clipper's contract mechanisms, this level of activity gives Management an excellent level of confidence in the year ahead.
I would take this is being mildly positive with regard to profits - my interpretation here is that profits won't be up in line with volumes however this wording as i read it gives the imprression that profits might be up at a lower marginal level "perhaps". I would agree their use of wording here is somewhat vague and probably leaves it up to the viewer to decide what they mean which aint ever much use.
Re Clipper Logistics (LON:CLG) - I suspect that another reason why volume may not be driving profit short term may be the detail of the Clipper-Client contract. : it is likely to be of the "I do 100units with you I pay X/unit, if I do 150units, I pay X*95%/unit" variety, with the buyer able to drive a hard bargain short term because Clipper wants the extra volume. That's because longer term, this enables them to scale up and cut their cost eg through more automation. However, short term, the extra volume must be met and is achieved by extra labour - my son is working the night shift with Amazon and making a fortune for an 18yr old AND he reports lots of extra labour costs due to COVID prevention eg rigorous control of 2m social distancing, PPE etc. When these costs drop out (from end April?), margins will improve even on current contracts.
I would love someone with real insight to indicate what incremental cost they think COVID costs are having on operational costs in labour intensive industries that are ongoing ie not hospitality but manufacturing/logistics . A year ago an extra 2% GM swing would have been seen as huge! So H2 2021 may see a big volume AND margin recovery.
However, as Paul said in his preamble, we should make decisions on what we can know, not assume. I know volume is up 50%; I almost certainly know that there are economies of scale long term for Clipper style logistics which they will share with their customers so Mgt are probably right with "this level of activity gives Management an excellent level of confidence in the year ahead".
None of this of course answers the question: are they good value at current price. At 26x forward earnings and 2% forward yield they are not for me but probably a decent return on a LT basis.
Great points, thanks timarr! I agree with you on all of that. I wonder if the US markets are likely to look negatively at tax rises on earnings, or positively on massive economic stimulus now being more likely? Could go either way!
I think it now has to be said that these down ticks are ridiculous and should be withdrawn. Everyone is entitled to an opinion , if you don’t like it then ignore it, but down arrows are tantamount to bullying really and only create disharmony.
Hi Peter,
I believe the down ticks are going to be abolished, it's work-in-progress with the developers. The intention of down ticks was to flag up to people posting codswallop that the community doesn't like their comments, and to deter them posting similar things. But it seems to have the opposite effect, and inflame some people, often triggering a deluge of additional codswallop about the down ticks!
I agree with you, better to ignore things you don't like (easier said than done sometimes!) ;-)
Regards, Paul.
That might work if "the community" were a pool of independent rational thinkers, but unfortunately they aren't. Instead we have a lynch mob mentality.
I've given you your first downtick. Not because I'm a bully but as you said "Everyone is entitled to an opinion". Removal of the option of expressing an opinion in Hong Kong isn't exactly creating harmony.
I like the tick system as it helps me gauge what the wider community think. The type of person who doesn't take on board downticks are often the type of people who are not good at listening to other people, ie defending themselves.
The mind of people who don’t worry if the odd post gets down ticks are those capable of independent thought and don’t use likes as a measure of their self worth.
They also indicate to oneself when one is swimming against the tide. Sometime that can be a deliberate conscious choice, other times it might indicate one needs to do some self reflection.
So yes. I too am a fan of downticks even though I often get them.
As ever the market moves in mysterious ways, with the Democrats prospective win probably bad for big oil, tech stocks and drug companies?, and yet £BP. and Royal Dutch Shell (LON:RDSB) both up in excess of 6% as I write. It would appear, in the UK at least, the recent Saudi decision at the January OPEC meeting has more weight than UK national lockdown 3 and the prospect of US government completely controlled by the Democrats... well that is until a different market perspective emerges tomorrow no doubt!
Hence, my dip of my toes into Eddie Stobart Logistics (LON:ESL) , comes with a lot of baggage but surprisingly the company appears to have made a strong turnaround with strong figures out recently.
My morning smallcap tweet:
Equals (LON:EQLS) Fulcrum Utility Services (LON:FCRM) Topps Tiles (LON:TPT) Gresham Technologies (LON:GHT) WANdisco (LON:WAND) Microsaic Systems (LON:MSYS) Shearwater (LON:SWG) Gaming Realms (LON:GMR) Conygar Investment Co (LON:CIC) Seeing Machines (LON:SEE)
Equals (EQLS) guides FY(Dec) rev £29m, £1m better than mkt f/c. Adj EBITDA c.£1m cf f/c £0.55m. Cites strong B2B product sales in Dec. [SP=NA Cap=NA]
Fulcrum Utility Services (FCRM) CEO resigns 'due to personal reasons'. He is thanked. [SP=NA Cap=NA]
Topps Tiles (TPT) Q1 retail LFL up 20% and Commercial business 'on track'. "The markets served by our Commercial business are seeing a more protracted recovery from the impact of Covid-19 when compared to that witnessed in domestic." [SP=NA Cap=NA]
Gresham Technologies (GHT) guides FY(Dec) rev down 2%, adj EBITDA at least £4.4m (up 7%). Forward-looking Clareti Annualised Recurring Revenue up 29% to £12.3m, ahead of market expectations. [SP=NA Cap=NA]
WANdisco (WAND) guides FY(Dec) at least $10.5m. "Strong momentum in Q4 through Azure and AWS channels. Expanding new business pipeline supports Board expectations for FY21." [SP=NA Cap=NA]
Microsaic Systems (MSYS) re SP rise: "no new information required to be disclosed." [SP=NA Cap=NA]
Shearwater (SWG) wins supply agreement with a global fashion retailer. First contract is £860k, majority expected to be recognised in the current full year. [SP=NA Cap=NA]
Gaming Realms (GMR) granted provisional iGaming supplier license in Michigan. Will allow Slingo Originals game licensing to online casino operators after Gaming Control Board approval, expected imminently. [SP=NA Cap=NA]
Conygar Investment Company (CIC) InterContinental to build hotel on Nottingham site. [SP=NA Cap=NA]
Seeing Machines (SEE) sells Occula Neural Processing Unit license to OmniVision Technologies. Follows MoU. No £££. [SP=NA Cap=NA]
Wandisco (LON:WAND)
"new business pipeline supports Board expectations" Hardly demonstrated by the massive director sales. £10M worth by the CEO Richards over the years while tapping the market for new placings. A lot of good news in the price already.
Equals (LON:EQLS) Trading update released this morning with revenue, EBITDA and cash all ahead of expectations, affirming my view that this looks to be a very good recovery play for 2022/2022 with significant potential for upside.
Paul - I’d imagine this is worth a look - You will like the inclusion of current market expectations in the footer at the bottom of the statement. Good to see this practice being adopted by more companies.
Formerly FairX, the company was very good to be a customer of, but Brexit and then Covid were very damaging in my own view. What happens next is anyones guess.
That's the key element - You were a retail purchaser of FX previously. The business model has now shifted from B2C to focus on B2B.
See the note in the trading statement today about strong performance in the Groups B2B products in Dec-20.
Agree, the change from B2C to B2B focus is potentially the recovery catalyst. Numbers are good although wish the focus wasn't on adj EBIT. The amount of intangible assets on the balance sheet is a concern.