Small Cap Value Report (Wed 7 August 2024) - MORE, GDWN, TPFG, SDG, FOUR

Good morning from Paul & Graham.
That's all we've got time for today, see you tomorrow! I want to circle back to Keller at some stage, but am too tired now.
FTSE 100 futures are showing we could be in for nice bounce today. Has this been a "flash crash" I wonder? Hope so, as I did some buying yesterday for 11 shares that had been on my watchlist, but were put on mid season sale earlier this week! After all, the idea is to buy low and sell high (BLASH), something that's easy to forget when caught up in the drama of a sudden sell-off.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
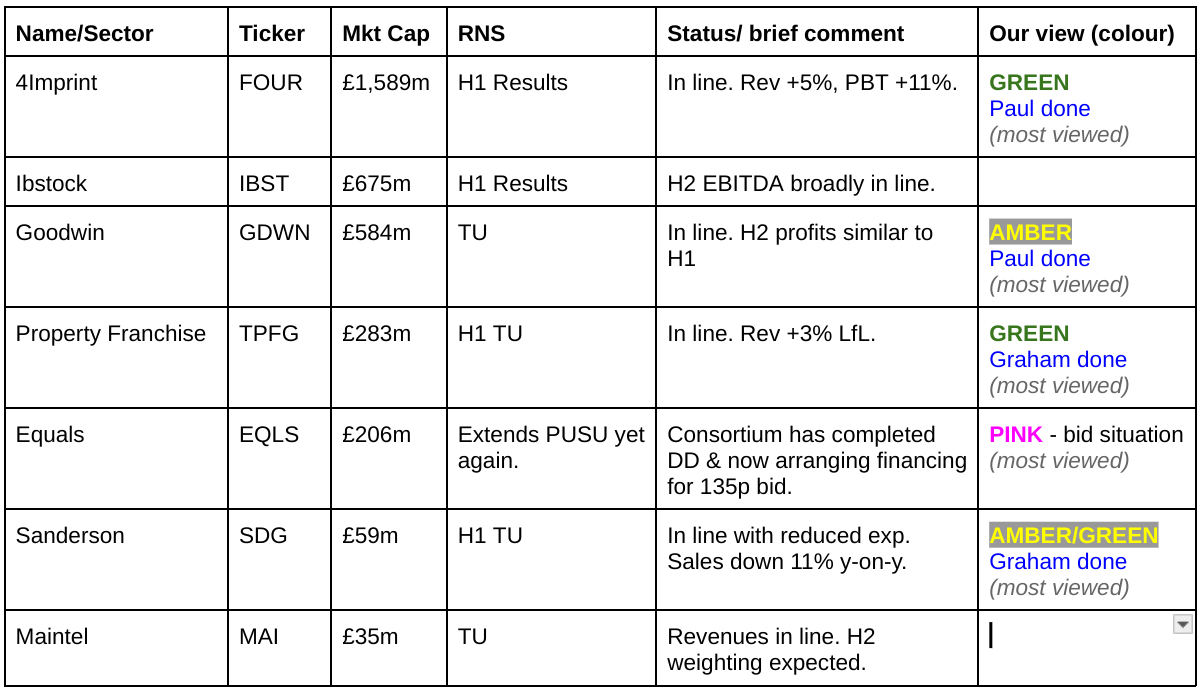
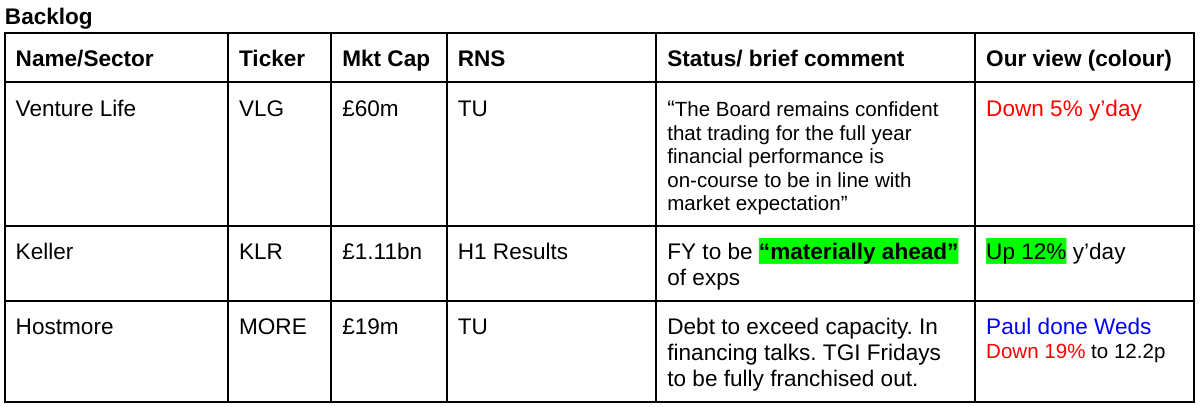
Summaries
Hostmore (LON:MORE) - down 19% to 12.2p y’day (£15m) - Updates on Corporate Actions and Trading - Paul - RED
Mgt are trying hard to salvage the situation here, but I suspect things might be slipping out of their control, with worsening recent trading, and the bombshell yesterday that it's seeking additional financing to prevent a breach of its existing borrowing limit imminently. Way too risky to get involved, is my view. So I'm sticking with RED.
Goodwin (LON:GDWN) - 7,780p pre-market (£584m) - FY 4/2024 Results - Paul - AMBER
Good results, but as always the stretched valuation limits how enthusiastic I can be. As before, I really like the company, and am impressed by performance, but the share price is now way above what I personally would be prepared to pay. Cashflows are not great, and it glosses over the reality of increased net debt year-on-year, by instead focusing in the commentary on an H2 reduction in debt.
Property Franchise (LON:TPFG) - up 2% to 465p (£291m) - Half Year Trading Update - Graham - GREEN
A very pleasing trading update with the outlook for the company to achieve full-year results “at least in line with expectations”. The merger with Belvoir and a subsequent cash-purchase acquisition have left the company with a modest debt load. I’m still excited about TPFG’s future but a significantly higher market cap is now starting to price in the company’s excellent prospects, in my view.
Sanderson Design (LON:SDG) - up 2% to 84p (£60m) - Half Year Trading Update - Graham - AMBER/GREEN
I don’t normally cover this fabric/wallpaper group but can understand why it has received positive commentary here before. The company is now seeing some signs of improvement after a very challenging period of trading, particularly in the UK, and it is trading in line with reduced expectations. The market cap strikes me as undemanding given the company’s many attractions, with the main drawback being the lack of top-line growth over the long-term.
4imprint (LON:FOUR) - down 2% to 5,505p (£1.55bn) - Half Year Results - Paul - GREEN
Good H1 results, despite challenging market conditions. A spectacular multibagger over the long term, and I remain enthusiastic about many aspects of this share.
Paul's Section:
4imprint (LON:FOUR)
Down 2% to 5,505p (£1.55bn) - Half Year Results - Paul - GREEN
I tend to briefly cover this mid-cap here because it’s a wonderful company, that has 50-bagged over 15 years!
Previously here -
19/1/24 - Paul - GREEN - 4635p - slightly ahead exps TU.
13/3/24 - Paul - AMBER/GREEN - 5940p - in line TU.
FOUR sells promotional goods with customers’ brands printed on them, mainly in the USA, so a huge market. Funnily enough, on my recent trip to meet extended family in Washington DC, I usually leave the TV on in the background in my hotel room, and was pleased to see 4Imprint TV ads appearing frequently. Which tells me they’re on the front foot, but also that they would have scope to dial down marketing spend if required, eg -
“with the reshaped marketing mix demonstrating the efficiency and flexibility that we expected against a softer economic backdrop.”
H1 figures today - this is very quick reporting, just over 5 weeks after the half year end.
“4imprint Group plc, (the "Group"), a direct marketer of promotional products, today announces its half year results for the 26 weeks ended 29 June 2024. The results for the half year and prior half year are unaudited.”
“Strong financial performance; taking share in challenging market conditions”
Some nice numbers in the H1 highlights, note this is US dollars/cents -
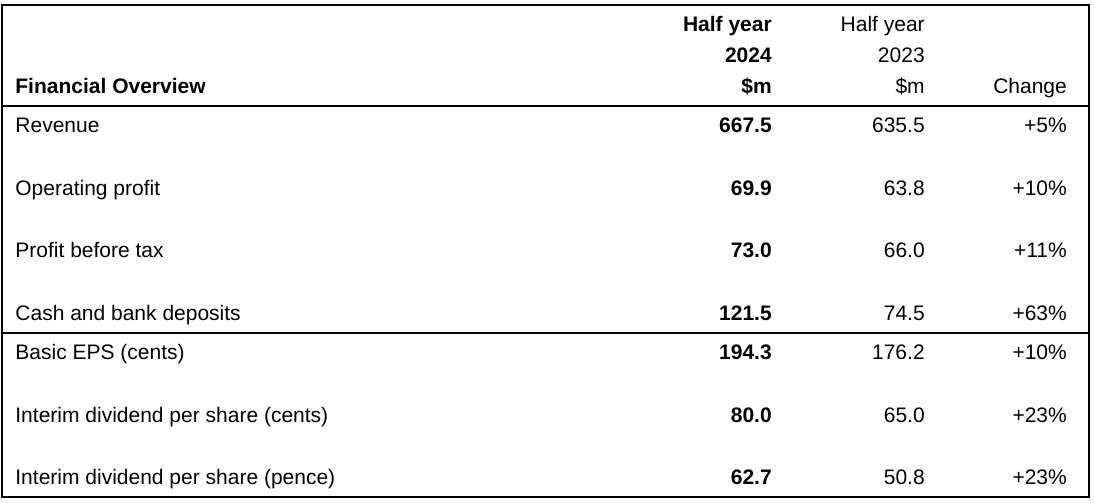
Outlook -
“Based on our first half financial results and recent internal forecasts, the Board expects that 2024 full year Group revenue will reflect a growth rate similar to the first half of the year. As a result of improving financial dynamics in the business, particularly higher gross profit percentage and the flexibility of the marketing mix, it is expected that profit before tax for the 2024 full year will remain within the current range of analysts' forecasts.
The Board is confident in the Group's ability to manage through the current market conditions, blending resilient near-term financial results with attractive prospects for significant further organic growth over the medium term…
In summary, our strategy remains the same - to deliver attractive organic revenue growth by increasing our share of the fragmented yet substantial markets that we serve.
We take a long-term view of the business and its future development. This includes making necessary investments in the people, marketing resources and infrastructure required for success, regardless of the immediate market conditions. Experience has taught us that if we remain diligent in looking after the business in more difficult times, a market share opportunity tends to follow.
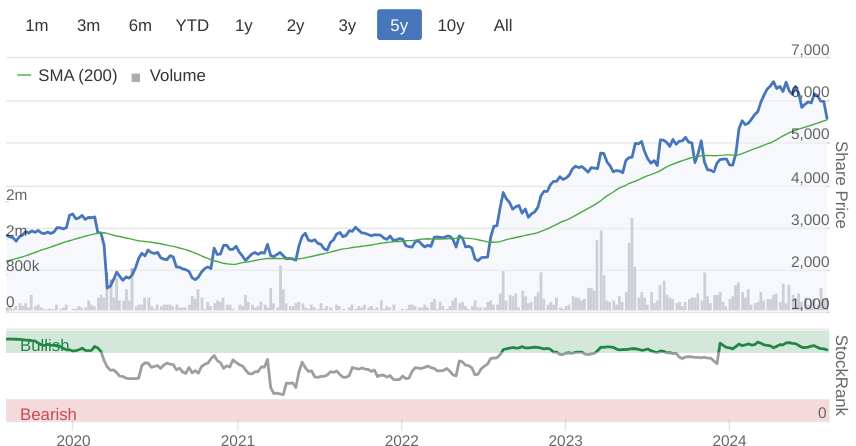
Brokers - there are 3 broker updates available on Research Tree. I’ll look at Edison, as that’s directly commissioned by FOUR. It trims revenue, but slightly raises profit for FY 12/2024, to 405 cents. Convert at 1.27, and that’s 319p. So at 5,505p, that’s a 2024 PER of 17.3x, which I think is reasonable, given that this is a year where market conditions are seen as challenging. Hence there could be upside once an economic recovery is (hopefully) more established in the USA, currently an unknown factor that markets are trying to figure out.
Balance sheet - is very healthy. It’s a strikingly good business model, with hardly anything in inventories, and quite modest receivables too. So it looks as if they possibly drop ship products, and/or send things out as soon as they arrive. That makes sense, since product will be personalised to each customer’s brand. Hence it’s sitting on a healthy & rapidly growing $121.5m net cash pile, and can safely pay out most of earnings as divis, with the yield c.3.7%.
Cashflow statement - really impressive, it’s just a cash generation machine, which it pays out to shareholders, exactly what I like to see!
Paul’s opinion - this looks excellent, it’s a thumbs up from me again. Not obviously cheap, but I think if you take a long-term view, you should do well with this share. Providing nothing unforeseen goes wrong of course, as with any share.
I’ll put this on my watchlist, and might have to consider dipping in my toe if the current downtrend continues.
Goodwin (LON:GDWN)
7,780p pre-market (£584m) - FY 4/2024 Results - Paul - AMBER
From Goodwin’s website -
“Goodwin PLC is a group of established mechanical and refractory engineering companies, specialising in the design, manufacture and supply of high-quality products and solutions.
Goodwin PLC’s subsidiaries manufacture and operate in over ten countries worldwide, enabling the Group to capitalise on local market growth and take new products to market quickly, in both the established and emerging markets.”
Why can’t companies give examples of the main products that they make, instead of general descriptions like the above?
We’ve reviewed GDWN here 3 times in the last year - you can see a consistent querying of the valuation, but approval of performance, and me being more positive than Graham! Despite the high valuation, this has been a case where running your winner has played out well so far -
11/8/2023 - 4745p - Paul - AMBER/GREEN - Good FY 4/2023 results, fully priced maybe?
20/12/2023 - 5424p - Graham - AMBER - Profit up, large order book, but looks expensive.
14/3/2024 - 5240p - Paul - AMBER/GREEN - In line TU.
This share was also one of my top 20 shares ideas in 2023, and has been a star performer, currently up 128%.
That’s set the scene and refreshed my memory, so let’s move on to the FY 4/2024 results out today.
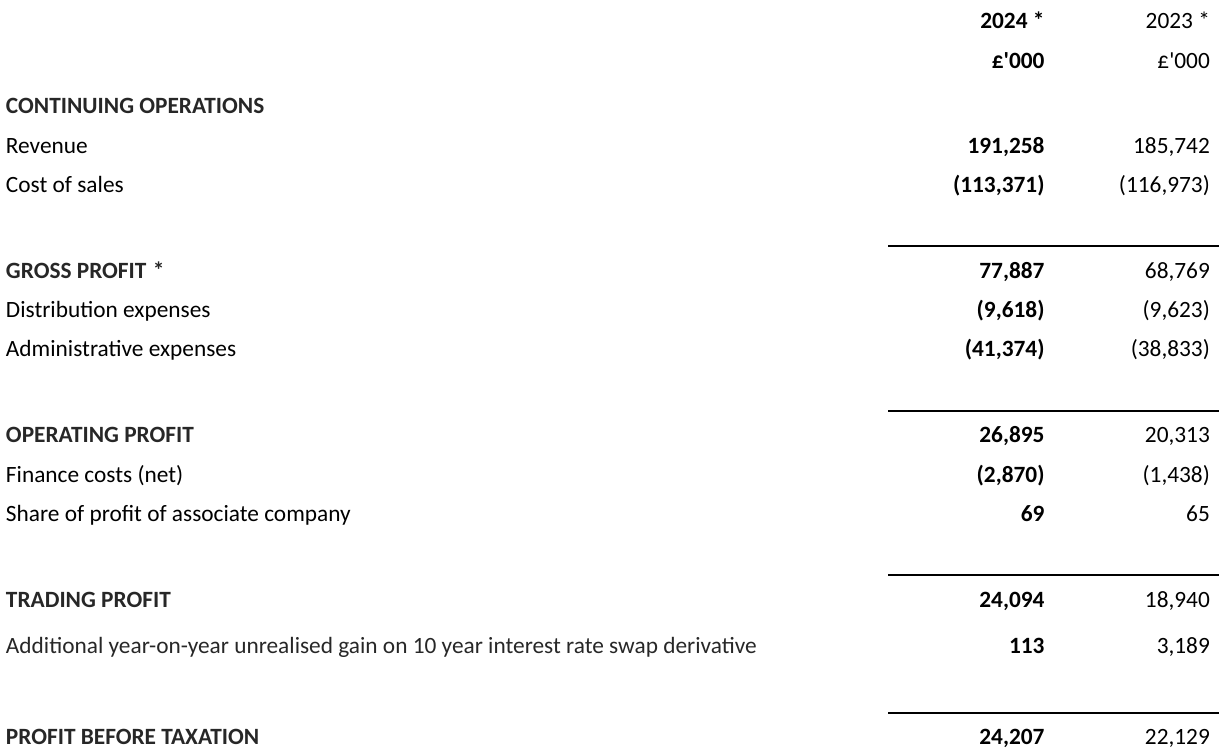
Decent figures here, with PBT up 9% to £24.2m.
Note that last year was boosted by a derivative gain of £3,189k, so the better comparative of underlying performance is the “Trading Profit” figure below of £24,094k, up a much more impressive 27%.
How does this compare to forecasts? I can’t find any broker notes, a consistent problem with Goodwin, which is run like a private company unfortunately. However, it’s moving in the right direction, with the recent introduction of quarterly trading updates. Shore Capital said previously it intended issuing a more detailed research note, but I can’t see that as yet on Research Tree. Hopefully it’s gestating, maybe they wanted full year numbers published before committing to forecasts?
EDIT: a one-pager has just come through from Shore, but it just summarises the RNS, and doesn't contain any forecasts.
Guidance from Goodwin itself on 14/3/2024 allowed me to simply work out a 231p EPS estimate here in the SCVR on 14/3/2024. Today’s actual of 224.5p is slightly below my estimate, but not enough to make much difference.
Valuation we already knew was high, and at 7,780p/share the 231p EPS gives a PER of 33.7x - I know we keep saying it’s expensive, and it keeps rising in price, but surely there has to come a point where people bank profits? What level would be too high? A PER of 40, 50, 60? Remember that it’s an engineering company, not a tech exponential growth story!
Balance sheet - NAV is £127m. That includes £26m in intangible assets, so £101m NTAV - a healthy position.
As you would expect in the engineering manufacturing sector, Goodwin is capital-intensive, with £105m fixed assets (property, plant and equipment). Working capital is strong, with £74m net current assets. However, this is funded with £62m of non-current borrowings.
Overall it’s OK I think, but Goodwin doesn’t have the substantial surplus capital of Castings (LON:CGS)
Cashflow statement - looks similar to last year. Net operating cashflow (post tax & finance costs) was £27.1m this year, vs £29.1m last year. Near enough to make no difference.
Capex was considerable, at £16.9m this year, consuming 62% of cash generated. A reminder that this is a capital-intensive business, meaning that there’s little scope to pay out much in divis.
After capex, cash generation was only £10.2m, less £2.9m lease costs, gives £7.3m cashflow remaining.
It then spent £8.9m on buybacks, and £8.6m on divis, which was really an overspend, funded by increasing net debt.
These full year cashflow figures are completely at odds with the company's commentary, which talks about having reduced net debt, and absorbing heavy capex whilst also paying out divis and doing a tender offer. However, net debt actually rose year-on-year, from £34.3m in April 2023, to £45.3m at April 2024 (I think that might include leases, as they're not shown separately on the balance sheet). What they’ve done is highlight that net debt fell in H2, from £54.6m at end H1. So I find the “Cashflow” section of the commentary misleading, since it ignores the net cash outflow, and increase in net debt, for the year as a whole.
Overall then, cashflow is not great, and they’ve paid shareholder returns out of increased net debt - the opposite of what their commentary says!
Interest rate swap - I’d forgotten about this, but GDWN made a very shrewd move to lock in low interest rates, thus boosting profitability now -
“The interest rate swap continues to benefit the Group as it locked in a very preferential borrowing rate of less than 1% up to 2031 on the Group's first £30 million of debt.”
Order book - is similar to last year at this stage - but the commentary says big contracts are multi-year, repeating type orders. So the likely order pipeline could be a lot larger than the published order book figures.
“Currently, as of the date of writing this report, the Group's cumulative future orders stand at £264 million (August 2023: £271 million)”
Dividends - increased to 133p (LY: 115p) but due to the very high share price, this is only a 1.7% yield, and as flagged above in the cashflow section, I question whether GDWN can afford even this fairly modest payout?
Outlook - there isn’t a section on this, but details are scattered through the fairly detailed & useful commentary.
A couple of interesting excerpts -
“The continued increase in the performance of the Group in the financial year just ended is a result of the hard work and strategy to break into new markets coming to fruition. The profits have again taken a step forward as a direct result of the strategic investments that have been made over the last decade, and particularly the supply of mission-critical, high integrity components to the nuclear waste storage industry and key components for the naval propulsion and hull construction markets from the Mechanical Engineering Division…
The majority of the Division's forward order book relates to advanced solutions for the nuclear waste storage industry and key components for the naval propulsion and hull construction sector. From the discussions that the sales teams of both Goodwin International and Goodwin Steel Castings have had with their key customers, it is expected that there will be more orders for the same components in the coming years. Furthermore, a significant proportion of this workload consists of repeat orders for components where we have already overcome many of the manufacturing uncertainties, allowing us to realise future production efficiency gains on these repeat components.”
Paul’s opinion - I’m a bit concerned the valuation is now looking too stretched, but we say that every time!
From talking to bulls in GDWN shares, their main interest seems to be in the potential for nuclear waste related orders to be highly lucrative over a long period of time. The outlook excerpts above do seem to back up that view.
Cashflow has underwhelmed me, and I take issue with the commentary glossing over the increased net debt by only focusing on the improvement since the H1 results.
Short term, I can’t justify being anything other than AMBER, due to a stretched valuation. However, on fundamentals, it sounds like the company is likely to keep doing well. So with a say 2+ year view, I’d be looking at this as AMBER/GREEN. On balance, I think for now it has to be AMBER, and then I’d move back up to amber/green if there’s a pullback in price to something more sensible, say 20x earnings, suggesting a price target of 4,620p for me. The existing price of 7,350p (it’s down about 5% today at 09:52) is 59% above what I see as a fair valuation today. Bulls may well be proven correct longer term, but they’ve chased the price a long way above a reasonable level in the short term, in my view.
The company highlights its superb long-term track record - so it could well be the case that patience could remain a virtue with GDWN shares -
"the Total Shareholders Return including the dividends paid over the last 20 years is 4,632% (versus FTSE100: 282%)."
Shares have joined the FTSE 250 recently.
While I've been writing the above, the share price has had a pullback - it's a thinly traded share though, as I suspect most shares are locked away by long-term holders.
Hostmore (LON:MORE)
Down 19% to 12.2p y’day (£15m) - Updates on Corporate Actions and Trading - Paul - RED
This is the financially distressed UK franchisee of TFI Friday’s casual restaurants. A replacement management team are fighting hard to keep it afloat, strip out costs, etc. Debt is dangerously high, although the bank gave it some breathing space in an extension of the borrowing term. More recently it announced a surprising proposal to reverse the US franchisor into this UK listing, in a reverse takeover, that still seems to be work in progress.
I can’t see the point in getting involved here, when the risk is so high, so I’ve been negative on this share 3 times in the last year -
8/9/2023 - RED
3/5/2024 - RED
3/6/2024 - RED
Although as with everything, we keep an open mind, and change our view if the facts change.
As a reminder, RED is reserved for situations where we see substantial risks of insolvency or dilution, and a struggling business model.
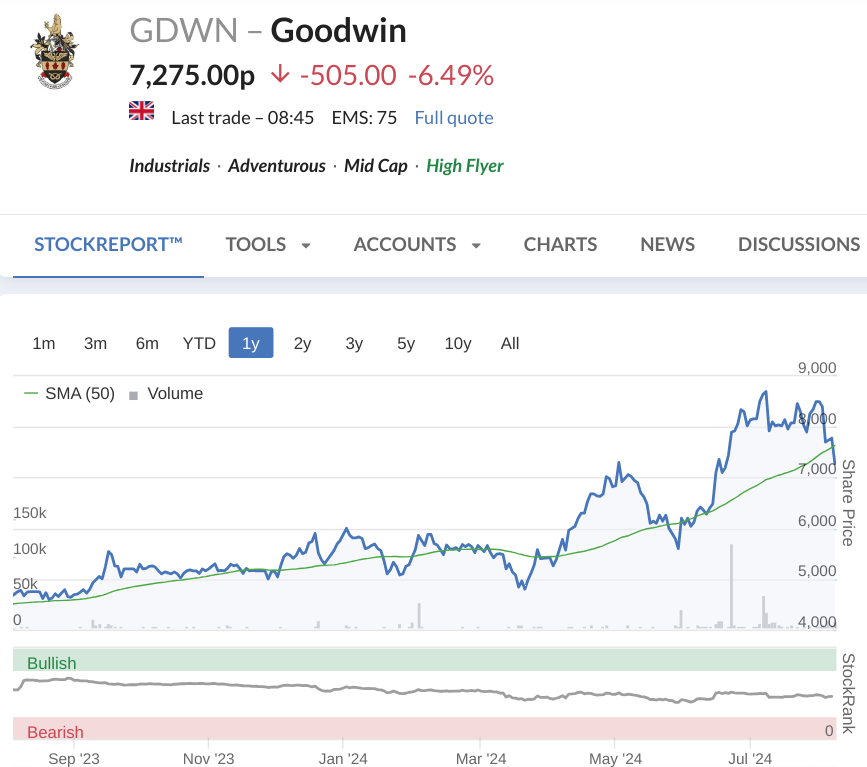
Reverse takeover - they still haven’t agreed terms. Given that MORE’s share price has been significantly falling recently, it’s becoming clearer that this deal may not happen at all now, and if it does, the dilution is likely to be much larger than originally anticipated.
It says the existing 87 corporate stores will be sold off to franchisees, moving to a capital light model. Note that the c.$40m from disposals mentioned relates to the US company, which is not currently part of MORE.
Funding requirement from lenders will be less, thanks to the newly planned capital light, franchising model.
It’s not clear who these “related parties” are - possibly the US TGI's group it's trying to merge with?
“Instead, the parties are in discussions with their lenders and other stakeholders to repay or reduce existing indebtedness using proceeds from the sale of corporate stores and/or new facilities from related parties.”
Delay - the deal will not now complete by end Q3 2024, as previously intended.
Strategic review - is being undertaken to look at other options, in case the reverse takeover does not complete. What would this entail, it is not stated. Maybe a sale of the company, or a CVA perhaps (me speculating here).
Trading update - LfL sales were down c.10% YTD to late May 2024. Things have worsened in June & July, such that YTD LfL sales are now down 12%. That’s very bad, since costs will be higher. So I don’t see much future for this company unless it somehow manages to turn things around into rising LfL sales from now onwards.
H1 trading was loss-making, even at EBITDA (old basis), albeit not as bad as in 2023 -
“EBITDA (FRS102) in H1 2024 delivered a loss of £1.2 million, which was £2.6 million better than the £3.8 million loss in H1 2023. It is noteworthy that this improvement in EBITDA was after a reduction in revenue of £9.5 million for the period and, therefore, the EBITDA delivered underscores the positive impact of the cost reduction programme implemented in 2023 and the Group's ongoing strong operational discipline.”
Given the big depreciation charges on the stores, and heavy finance costs, this means the real profit (PBT) will be a heavy loss.
I don’t have access to any broker notes. Also the broker consensus figures on the StockReport don’t look right to me, as I think it’s clear MORE is heading for a substantial loss this year, not a profit.
The last balance sheet is a disaster area. Although most of the deficit on NTAV is due to negative lease entries. If these can be disposed of to franchisees, then that could help, although I imagine landlords would insist on a guarantee, in order to allow assignment of the leases. So leases on problem sites could revert back to MORE if a franchisee subsequently went bust.
Bank debt has risen in H1 - again, not the plan, it was supposedly going to quickly degear according to a previous presentation -
“As a result of trading in the period, H1 2024 ending net debt (FRS102) was £29.7 million as compared to £25.1 million at 31 December 2023.”
This is the worst bit below - it’s set to breach borrowing limits soon - this is a serious problem, and anyone still holding this share should be seriously asking yourselves why, when this risk is large, and imminent -
“The Board continues to expect that the Group's standalone peak net debt for the year, without giving effect to the closing of the Acquisition or any sales of the Group's corporate stores, will occur around the end of Q3 2024 due to routine working capital outflows, lower revenues in the period, and payment of transaction fees relating to the Acquisition. Borrowings during this period are likely to exceed the Group's existing borrowing capacity and so, as a part of the Strategic Review, the Board is in discussions with various parties regarding additional financing.”
Paul’s opinion - I think we could be witnessing the death throes of this share.
Casual dining is a horrible sector, where it’s difficult to make any money in the UK. There’s still far too much capacity, and the TFI Fridays format feels dated now. Costs have shot up in the last two years, especially wages, and cost-cutting can only go so far, before any further cuts would impede the ability to keep operating.
I suspect the reverse takeover deal might not happen, and even if it does, MORE shareholders are likely to be very heavily diluted.
Then we have the worst news that it’s about to breach its borrowing facilities.
Let’s hope they can salvage the situation, but I think it’s best to work on the basis that this share could easily end up a zero. So why get involved? The idea that this share could multibag seems potty to me, given how poor current trading is, and that the bank debt is rising, and dangerously high.
So with risk:reward looking unfavourable, I have to remain at RED. Very high risk, could be on its way to zero.
Graham’s Section:
Sanderson Design (LON:SDG)
Up 2% to 84p (£60m) - Half Year Trading Update - Graham - AMBER/GREEN
Note that SDG’s year-end is in January:
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, announces its trading update for the six months ended 31 July 2024.
The company already issued a trading update (a profit warning) in late June, when it warned that trading conditions in the UK had deteriorated. Brand product sales were down 9% year-to-date, and down 14% in the UK.
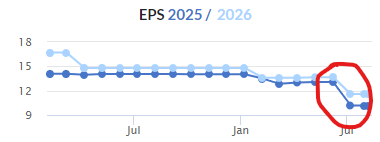
It cut its underlying PBT forecast for FY Jan 2025 to c. £8m. Here’s the impact on the EPS forecast. The EPS consensus forecast on Stockopedia was reduced from 13.1p to 10.2p:
Today’s update is in line with the revised expectations:
…trading has showed [sic] some signs of improvement in July with brand product sales up 6% at constant currency compared with July last year. As a result, total brand product sales in the six-month period to 31 July 2024 were down 7% in constant currency, an improvement compared with being down 9% at the time of the June trading update and driven by North America.
Brand product sales aren’t the entire story here - we also have external manufacturing sales (£9.3m) and licensing sales (£4.1m).
H1 licensing sales are down by a noteworthy 41% which the company attributes to a strong H1 last year when there was accelerated income from deals with NEXT and Sainsbury’s. Full-year licensing is expected to be about the same as last year.
In aggregate, total sales are down 11%, or down 10% at constant currencies.
Highlights: Disney Home x Sanderson and Giles Deacon products for the Sanderson brand have been well received and the brand is selling well in North America and Northern Europe.
New licensing agreements include Zara Home and John Lewis.
Net cash has fallen from £16m (Jan 2024) to £10m. Cash outflows arose from the transfer out of a pension scheme, a temporary inventory build, and capex that is not expected to recur in H2. This all sounds reasonable and I’d expect a much better cash performance in H2.
Outlook: trading conditions remain challenging, but “expectations for full year cash and profits remain unchanged”.
…The previously announced initiative to deliver a more efficient sales model in the UK has recently been completed, achieving annualised savings of approximately £0.6 million of which £0.3 million will be delivered in the current financial year.
At the same time, the Company remains focused on the growth opportunity in the US market and has recently signed a five-year distribution agreement with Kravet Inc. for the distribution of Scion fabrics and wallpapers in the USA. Kravet Inc. already distributes the Clarke & Clarke brand in North America and this new exclusive agreement for the Scion brand is expected to drive the profile of the brand in the USA.
Graham’s view
I think Paul normally covers SDG but I’m glad to have had the chance to take a look at it.
My overall impression of the company is positive - it has great heritage, a nice track record of profits and dividends, a net cash position that still covers a chunk of the market cap, and a growth opportunity in North America. And I always sit up and take notice when I see licensing deals, as they have the potential to create a stream of risk-free pure profits.
The main drawback is that apart from the US-driven growth story, SDG’s other markets appear moribund. The overall growth picture is not great. Indeed, there has been hardly any top-line growth in recent memory.
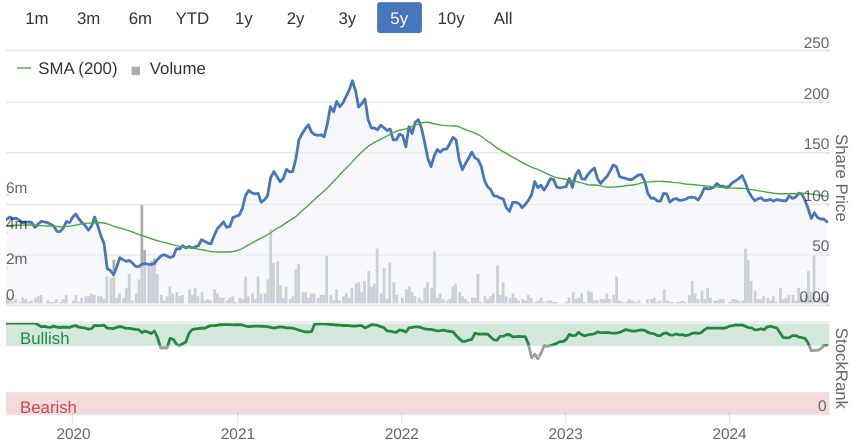
Is everything priced in at a market cap of £60m? Given the exposure to licensing income and hopefully some growth in North America, I’m happy to give this one the benefit of the doubt and go AMBER/GREEN on it. The enterprise value is only £50m once we deduct cash, and the cash balance should hopefully see a nice bounce in H2. That’s not a very demanding enterprise value to my eyes, vs. underlying PBT of c. £8m in a tough year.
Property Franchise (LON:TPFG)
Up 2% to 465p (£291m) - Half Year Trading Update - Graham - GREEN
Readers will remember that a merger took place between TPFG and Belvoir in March. This means the H1 numbers (to the end of June) are going to require a little more work to understand.
At the end of May, another £20m acquisition took place as TPFG picked up The Guild of Property Professionals and the Fine & Country brand. This gives TPFG some foreign operations for the first time. It has been a busy year!
Here are the highlights from today’s H1 update, which is at least in line with expectations.:
(Like-for-like figures exclude the impact of Belvoir and the more recent acquisition.)
Revenue +3% like-for-like, or up 104% in total to £26.9m.
Management service fee (the royalty charged to franchisees) up 8% like-for-like, or up 60% in total to £12.3m.
Rental properties under management rose 2% like-for-like, but have nearly doubled in total to 152,500.
Outlook for H2: the sales agreed pipeline is up 16% like-for-like compared to a year ago, “which bodes well for H2 trading despite lead times remaining high”. The recent interest rate cut is also a positive factor.
Integration of Belvoir and Guild/Fine & Country “is progressing well with the restructuring of the senior leadership team largely completed”
Net debt: £14m after £20m was borrowed to fund the acquisition in May. It should be straightforward to pay this down.
CEO comment:
"The first half of 2024 has been transformational for our Group, building on our track record of growth and completing two significant acquisitions which has created a substantially larger group with an international presence. We are delighted with our organic revenue performance in the first half year and the contributions from each of our new businesses.
"We have a very resilient and focused franchise model and multiple income streams across 18 brands including a significantly enhanced, exciting opportunity in financial services. With an improving pipeline and at least one interest rate reduction behind us, the Board is confident that trading remains at least in line with market expectations for the full year."
Graham’s view
I’m a long-term fan of this company. I never predicted a merger with Belvoir (although I liked that company, too), but the merger seems to have helped push the share price higher year-to-date.
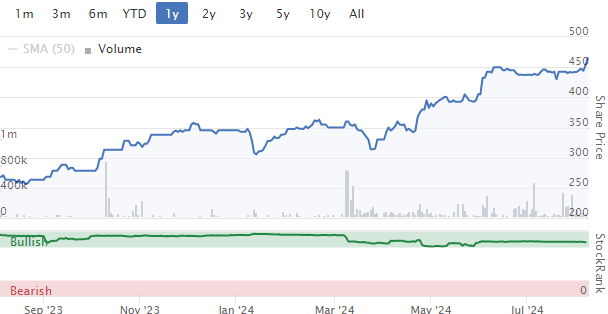
Indeed, the share price is up by 100p or 27% since I last reviewed this stock in April.
After being bullish for so long, we may be approaching the point where I need to temper my expectations with a downgrade to AMBER/GREEN. Perhaps not quite yet?
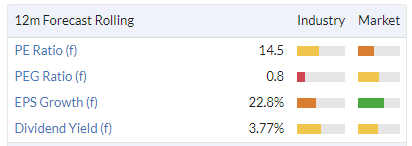
I always argued that TPFG deserved earnings multiples that reflected its quality and resilience. It has come a long way towards achieving that, and Stockopedia now only gives it a ValueRank of 14.
If the share price were to suddenly rush to 500p+, for example, that could be the trigger for me to downgrade my stance. This is a high-quality company and I’m excited to see what it can do if the property sales market returns to health. Its M&A activity has been truly transformational, and I applaud it. But at the end of the day I’d still be reluctant to overpay for this stock - so let’s keep an eye on this valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Sarah J Maas books being banned in some US states. Could impact sales.
https://www.theguardian.com/bo...
…. normally an incentive to get hold of copies.
Its one State (Utah, quelle surprise), not States, and only banned in public schools and libraries.
Does banning not increase sales?
Far more likely to sell more books from the publicity than losing the custom of Utah’s 140 public libraries who’ve already bought their copies and now have to destroy them.
Hi Paul
Re Goodwin (LON:GDWN), I must admit I laughed when I read
"I know we keep saying it’s expensive, and it keeps rising in price, but surely there has to come a point where people bank profits? What level would be too high? A PER of 40, 50, 60? Remember that it’s an engineering company, not a tech exponential growth story!"
Two reasons for this:
Time will tell as to whether this happens or not.
Best wishes, Martin
Keller is listed on the SCVR backlog today and I have been doing a bit of research on this company. Normally a jump in share price may not be the best time to buy but I have compared it with some US companies working in the geotechnical field and it still looks significantly undervalued by comparison. Admittedly it is "only" a contractor but it does work in a specialist field and some fund managers believe that legislative changes in the US (its main market) will help support an infrastructure renewal boom which will last for many years. I could see a p/e ratio of 12 looking quite reasonable bearing in mind its growth prospects and improving financials, so I wonder if it might be due a further re-rating.
In relation to Keller (LON:KLR) they have undergone a transformational H1 improvement in operating margin from 4.6% to 7.6% which increased H1 EPS by 86%. But is this margin improvement sustainable going forward? Digging deeper I can identify 3 significant changes:
Needless to say I hold.
The market panic has subsided as fast as it came……for now. Does the quick bounce back reinforce the case for not panic selling on a big down day, and to have portfolios we’re happy with and then just ride out the falls? And then to sell when a share we hold issues a profits warning and if there are hints of a profits warning to come. Key point is to buy quality at bargain prices (and if we must have unwise punts, and I can’t resist them) then to keep stakes in those small.
Two shares updating today to back his up:-
Hostmore (LON:MORE).
I swallowed the investment case after the demerger from Electra Investment Trust and continued holding as the share price fell. Convinced the market was wrong (despite knowing the market usually knows something) I decided to hold for the next update. It was awful and I cut a big loss in March 2022 at 60p. Better than continuing to believe and hold all the way down to current 12p? And after reading Paul’s comments today is it best even now to cut the loss before possible 100% loss? Even if selling only raises a £100 or so it’s better than nothing.
I used to have 100% losers and a portfolio with too many big losers but eventually learnt from the mistake. Now it’s a portfolio full of big dividend paying shares. There are still some quality shares as well as Investment Trusts paying extraordinarily big dividends as high as 10% starting yield. So it’s not too late.
Now to TP Icap (LON:TCAP) as an example of the benefits of the buy quality at multi year lows/bargain prices when news doesn’t justify such exaggerated share price falls.
TP Icap (LON:TCAP) was a lucky one in that I bought at what turned out to be right at the bottom at £1.05p 2 years ago. It’s just luck timing the buy that well! The dividend yield at that £1.05p price was 10% and with no signs from updates that it would be cut.
The update today was solid but it was a bit disappointing there was no increase in the 4.8p interim dividend. Even so that dividend is over 4% at my buy price and if they only hold the final dividend at 10p that’s another 10% to give 14% annual yield. And if there are further dividend increases ahead then the yield alone gives a great return. And the share is up over 120%.
Arguably TP Icap (LON:TCAP) is still worth buying and the yield is over 6% at current price. And this bit hints at further useful share price upside to come:-
“We are progressing strategic options in relation to Parameta Solutions, as previously announced. They include a potential offering, which might entail a listing in the United States, with the Group maintaining a majority stake. There is, of course, no certainty about either a public offering or its location. We will update on progress, as and when appropriate".
Buy now perhaps? But it was a much better buy as the share price started to bounce from that multi year £1 (and 75% fall from the peak) than it is now.
I have learned from long experience, that trying to panic sell when the market is in panic sell mode is near to impossible. You can't get an online quote for any quantity, especially for anything mid-cap or smaller, and a 'sell at best' order is an invitation to be taken to the cleaners. You have to ride it out until the tide turns and then take stock. I did think about selling my modest holding in POLR yesterday, but couldn't get a quote. Glad I still have them.
Just because the market is having a meltdown, doesn't mean that your stocks have turned to dust. The trick is to get out before the meltdown happens. If you are prone to panic, panic early. If anyone has a meltdown indicator, I'd be pleased to borrow it.
If anyone has a reliable meltdown indicator to sell, I'd gladly double mortgage my house to buy one off you...
I thought you'd been peaking at our portfolio ken mitchell! Not exactly but if I say Boohoo you get the picture. I would also agree that selling for whatever you can get is much better than 100% losers as you can use the capital losses to offset gains. I'm not suggesting Boohoo is heading for oblivion but Inland Homes did and my inaction means I can't use the resulting hefty loss. I'm still learning too thanks to Stockopedia analysts and subscribers, we're steadily going green.
Surely to all intents and purposes Boohoo (LON:BOO) is close to oblivion . For anyone who bought at the 150-300 level it may as well go under . Fortunately I sold a while back but it was still by far my worst performing stock of the last 2 years or so.
Thanks Ken- I have traded TCAP in the past successfully. Will have another look. Charles
Goodwin (LON:GDWN) I’m obviously hopelessly biased as it’s my largest holding & has been so since 2018 but I’d suggest this is a business at the start of some rather exciting times ….as ever the clues are in the narrative rather than the numbers eg;
‘It is satisfying to note that even with this improvement in divisional activity, there remains room for further growth across all companies, especially as the integration and alignment with our key customers continues to develop and evolve”
‘From the discussions that the sales teams of both Goodwin International and Goodwin Steel Castings have had with their key customers, it is expected that there will be more orders for the same components in the coming years. Furthermore, a significant proportion of this workload consists of repeat orders for components where we have already overcome many of the manufacturing uncertainties, allowing us to realise future production efficiency gains on these repeat components”
‘Easat Radar Systems now has a forward order book that should see it return to profitability this coming year. The pipeline of opportunities continues to grow, with the level of engagement with customers getting stronger as theyrecognise what Easat is capable of delivering. Taking a keen interest in what is on the horizon for Easat, I have attended multiple Easat meetings to satisfy myself we have the right contingent planning in place to deliver multiple simultaneous opportunities that are likely to transpire in due course. We cannot influence customer timings, but can only reiterate that the Board continues to have confidence in Easat to deliver respectable results it is capable of in the near future.“
‘Other than capital expenditure that is fully funded by customers and is cash flow neutral, for the next three to four years the Board's focus is on operational efficiency and obtaining output from the substantial capital investments that have already been made on new product production lines and increases in manufacturing capacity rather than embark on additional capital expenditure”
“ With full production expected to occur in the near future, Duvelco is actively having commercial discussions with established distributors and end users”
In summary perhaps the easiest way to think about Goodwin (LON:GDWN) is as 3 significant ~start up businesses Duvelco, AVD & EASAT (in its new total ATC system guise) where the Capex , physical footprint & development spend have suppressed performance of the wider group over recent years but are now going to deliver high margin turnover growth from here.
Couple that with the ramp up of the newly doubled capacity foundry (biggest customer is US Navy vessel supply chain) and the higher margins being flagged in the mechanical engineering division & I feel comfortable that a long period of rapid profit growth is well underway.
I think a lot of the excitement is around Duvelco & its Polyimide polymer which could displace Dupont and Victrex . If you haven't seen this research before it is worth a read https://sweetstocks.substack.c...
Goodwin (LON:GDWN) thanks for the link Ternheim, an interesting read.
Re: Goodwin (LON:GDWN, I do believe Goodwin shows promise with exciting prospects ahead. I have topped up (now my largest holding). Brokers fair value estimate is 8,706.52p.
Agree with you that Duvelco, AVD, and EASAT are now set to drive high-margin turnover growth, and Goodwin is poised for a long period of rapid profit growth. A share I feel comfortable to hold for the long term.
Hi Turbo
Goodwin (LON:GDWN) - my largest holding too. I wasn't aware of any brokers covering the stock - wonder if you could point me in the right direction. They have a remarkably precise target price! Unfortunately, reminds me of the actuaries in my previous life - 3 decimal places, but frequently the number preceding the decimal point was wrong........
Cheers
Andy
Great to have your input, thanks Rhomboid :-)
GDWN looks great. The only question is valuation.
Indeed . A ranking of just 8 does not exactly thrill me
Venture Life (LON:VLG)
I see this company is on Paul's backlog list from yesterday. Here is the other Paul talking to VLG's CEO yesterday (VLG are a VOX client):
I doubt we'll go back to VLG, as it's in line. And a pretty rubbish company.
Hostmore (LON:MORE) Presumably, a capital light model can only work if the franchise is seen as adding value to the franchisee and the fees paid for the brand name bring in diners to the restaurant, otherwise some may abandoned the franchise as has happened recently in one jurisdiction:
https://dailynewshungary.com/a...
Agree I don’t see how this works they can’t make the business model work themselves so why would someone want to take on franchise with even higher costs
Terrific article, thanks 1JAmes1n1
Detailed initiation report on Speedy Hire (LON:SDY) published today by Equity Development - link is here: https://www.equitydevelopment....
During a period of less favourable market conditions, Speedy Hire has taken a progressive approach to strategic business improvement and this programme is gathering momentum. As a result, we consider it to be much more than a cyclical recovery story.
Having traded at or below its 34p per share NAV for much of calendar 2023, Speedy’s share price broke through this level in the last month and has since sustained this momentum. It is now up c.14% YTD (versus c.3% for the FTSE All-Share Index).
On our estimates, Speedy is trading on low conventional forward multiples, particularly so by FY27, and that is before factoring in more ambitious company goals. With a 6.8% dividend yield, Speedy shares offer both income and growth. Taking a simple average of selected peer group multiples and our hybrid DCF/JV approach gives a mid-point fair value of 51.1p per share for the company which is c.34% above the current share price.
I think 4imprint (LON:FOUR) is worth a look today for long term investors. Shares have quietly shed 15% during recent turbulence, nothing dramatic, and today’s TU points to limp conditions and continued market share gains while margin improvements raise eps forecasts by about 3% (Panmure Gordon). Shares are currently off a few percent. This is a quality buy the dip compounder and I’ve raised my stake 25% on this slump*. Shares are not expensive relative to history.
* Beware the curse of BnB
FOUR I bought some shares on Friday. I'm feeling far from clever at the moment.
I owned FOUR in the past, and did very well, but I got scared out of them in 2020 IIRC. If I had held onto them to this date, it would have been a 10-bagger for me (very probably). I guess the market isn't liking the 5% revenue growth; coupled with negative economic outlook.
The shares aren't cheap, at a fwd PE of 17, but that's likely OK if the company continues to prosper.
The fact that it's taking market share is a real positive. Companies that can take market share in tough conditions are likely to be really good long-term winners, even if they're going through temporary pain.
FOUR I bought some shares on Friday. I'm feeling far from clever at the moment.
It happens to all of us. I topped up Daikin Industries (TYO:6367) yesterday morning just before the close, ignoring the pending TU half an hour later. Cue 10% fall today. I hope you’ll be happy with the purchase in the near future. Price has recovered somewhat after the initial half hour fall.
4imprint (LON:FOUR) I bought too but I'm sat on a loss. Hopefully the 5000p mark acts as strong psychological support for buyers to step in.
Unilever (LON:ULVR) Thought this was worth a little mention ... Twitter is suing Unilever, Mars, and some others, over an "illegal advertising boycott." https://www.bbc.co.uk/news/art...
I can't imagine this going anywhere. A company is not compelled to buy a product or service, for whatever reason.
Agreed, which is why I don't think he is wanting to win. I think it is more about exposing it and reaping the rewards of all the free publicity it will generate.
You're right.It's probably to play to all the big business, corporate, bill gates, 'plandemic', 5g, wef, etc.. conspiracy based theorists.Not that i think big corporations and business are whiter than white!Musk is in his own words very 'anti-woke' now and has seemed to double down on it, especially after his purchase of x.I was surprised to find out he has a 20 year old transgender daughter who has medically transitioned and documents to do so signed by him when younger though.
Property Franchise (LON:TPFG)
Confident update this morning with the synergies from the acquisition with Belvoir starting to come through.
According to Gareth Samples, CEO, trading remains at least in line with market expectations for the full year, which suggests that they might be exceeded.
Not sure if Graham is on the SCVR this morning but his view or Paul's would be welcome
Chief Executive Officer, Gareth Samples, commented: "The first half of 2024 has been transformational for our Group, building on our track record of growth and completing two significant acquisitions which has created a substantially larger group with an international presence. We are delighted with our organic revenue performance in the first half year and the contributions from each of our new businesses.
"We have a very resilient and focused franchise model and multiple income streams across 18 brands including a significantly enhanced, exciting opportunity in financial services. With an improving pipeline and at least one interest rate reduction behind us, the Board is confident that trading remains at least in line with market expectations for the full year."
Morning all, the FTSE 100 has a high dividend payment today at close, 4:30pm. It's not uncommon to see a rise on a Wednesday when the dividend payment is high. Todays payment is 19 points, so if anyone is trading the FTSE index today, beware if you are short or long that it will drop 19 points on close but also take off 19 points worth of dividend payment if you are short or add 19 points if you are long. Better imo to close any spreadbet of the FTSE before 4:30.
UK stocks generally go ex-div (and it is ex-div rather than a payment) on a Thursday, so index providers (and spread-bet platforms like IG) will adjust after the prior evening close.
However most spread/ derivative providers apply an adjustment to compensate & you should be no better or worse off for holding overnight?
https://www.ig.com/uk/help-and-support/spread-betting-and-cfds/products-markets-and-trading-hours/how-do-dividend-adjustments-affect-my-spread-betting-of-cfd-posi
Yes there may be some tiny distortions because they will be hedging with futures (the fair value between futures and the underlying physical can move around a bit) but that's well beyond private investor territory....
You can also get the underlying stocks themselves bouncing back after an ex-div (because the equity market doesn't always accrue dividends in the linear fashion that accrued interest picks up in the bond market, and you get dividend reinvestment flows - the DRIPs), but if that was a reliable seam to mine you can bet every hedge fund out there beat you to it and got in there first.
Yes in theory you should be no better off. The main thing to watch for would be if you set a stop loss that could be triggered by the fall at close. I generally find it easier to not trade through the close of the market on the Wednesday when a large dividend is that day. I am basing the dividend on IG. I’m unsure what the other spreadbet firms do. What I have noticed over the years is on these days of a higher dividend the ftse generally rises, at least until the US opens. Never a certain though and can be hard to predict so I tend to avoid theses days.
Property Franchise (LON:TPFG) 6 month trading update today
Was GREEN in review in April at 365p, now 470p
One of the few established findings in financial research is that current volatility is a good predictor of future volatility. It has a lot of continuity. Of course it doesn't go on forever, but personally i expect it to continue for the next 3 to 4 weeks. Sorry Paul, i don't think this was a 'flash crash'. P.S. by volatility i mean of course large moves both up and down but with a trend down.
Agree ... this bounce is an opportunity to sell anything you are not 100% committed to. JP Morgan is saying the Yen carry trade is only about 50% unwound .... there is more to come. On top of that, the macro data is pointing to a recession in the US.
Interesting, also noted that Ed Croft’s market sentiment indicator (AIM Allshare vs 120 MA) gave a sell signal on Monday, the last buy signal was mid Dec ‘23.
Hello Snowbum
Where do I find this indicator?
Thankyou. KBR
You could try entering ‘Ed Croft sentiment indicator’ into Google…
https://www.stockopedia.com/co...
To follow it, I use ticker ‘AXX’ on TradingView with the 120MA added.
On the other hand, maybe BOJ Deputy Governor Shinichi Uchida has saved the day, and the remaining unwound positions financed by the yen carry trade will remain unwound .... for now?
Results out from TP Icap (LON:TCAP) today, I hold.
TP Icap (LON:TCAP) results are always a bit opaque, with a blizzard of different numbers. My reading of them is that revenues and DPS are broadly flat, whereas EPS is improving, due to cost control and share buy backs. The company is becoming leaner. I would choose EPS of 11.6p as my worst case number. There is still some legal risk, mostly associated with a past acquisition.
The above is achieved against a market headwind of low volatility (!), and increased and significant investment in IT. But out of this will emerge a more relevant business that should chug along with modest growth. Some of the new business areas are quite interesting; data and commodity broking for example.
Low volatility = lower profit. The converse also applies.
A Hold for me. Hardly expensive. Surely a USA listing to come at some point (sadly).
Other feedback or perspective is welcomed.....
TP Icap (LON:TCAP) (I hold). IMO the results couldn’t be more detailed. What might make the results “opaque” for many of us (including me) is the ability to analyse them.
Surely the listing of its subsidiary Parameta in the US will unlock some of the benefits of a total US listing for LON:TCAP ?
TP Icap (LON:TCAP) (I hold). Probably beyond the scope of SCVR.
Half year report looks very positive on the surface. Remarkable detail and clarity in the reporting. I think I leave it to the analysts to decipher the full detail.
TP Icap (LON:TCAP) Hi Revs8 I could not agree more, market cap is above the threshold but on fundamentals on Stockopedia looks an excellent investment and cheap, to be honest better prospect that most small cap shares which have either traded sideways or backwards in the last 5 years, a lot of rubbish on the AIM market, which at least Stocko and team attempt to identify, but even a lot of the better fundamental ones haven't performed well. The crash at the start of the week was a typical example whereby a lot that looked already cheap got cheaper across the board practically, not sure where the end or bottom is. I think for this one the profit guidance for full year needs upgrading?
TP Icap (LON:TCAP) Lo and behold an initial sharp increase in the share price this morning as a positive reaction to £2.40, but currently scaling back to level it was at pre monday's crash, what does it take to get any upside maintained nowadays, if there was a slight decline in profits would be over 20% down by now, its a ridiculous state of affairs and imo market makers are destroying the UK stock market and eroding private investor confidence and interest.
Profitparr
Market makers destroying the UK share market including TP Icap (LON:TCAP) today. Really? Why would they want to do that and could you explain please how they are doing that and how does it benefit them by doing it?
Hi Ken, thanks for response, maybe I am using in wrong context but I consider that with shorting mechanism and from what we saw on Monday when virtually all stocks were down - why is this when not all are affected by overseas developments surely, private investors get nervous and bale out and have no confidence in investing just my opinion. So I consider the Market Makers are just using any opportunity to drop the prices, suck small private investors into selling. IMO as you will appreciate but I have been investing for a long while now and back in the day you didn't get such crazy movements in shares (only when global crashes on significant days in the past) as you have done in the last few years.
MM’s are very savvy and simply price according to demand. Trading causes the fluctuations IMO. TP Icap (LON:TCAP) classics trading pattern today. Let the hype drive the price up. Then the traders step in and take profits. Once the price stabilises and traders are out (volume drops) then we find out a more realistic price.
Please feel free to call me a "Dutchman", but I suspect after >9 months, Equals (LON:EQLS) strategic review is now in the end game.
Today news came that the bidding consortium (ie TowerBrook & Railsr) had "substantially completed its due diligence" and is in discussions with a preferred funding partner wrt financing its proposed 135p/share offer (worth £277m fully diluted) for #EQLS.
Plus given today's PUSU deadline has also been extended to 5pm Tuesday 4th Sept - coming of course after Monday's equity volatility - then I suspect the odds of an agreed takeover completing at 135p/share are 70%+.
Obviously though that's just MY view as a long term shareholder. Please DYOR.
Paul van Hill
There are no Hills in the Netherlands
I see that the share price has hardly moved today - up ~1%, and 25p short of the proposed offer price. You'd think that the availability of finance would one of the first considerations, even if conditional?
Well, there is at least one :). The Vaalserberg is a hill with a height of 322.4 metres (1,058 ft) and is the highest point in the European part of the Netherlands. The Vaalserberg is located in the province of Limburg, at the south-easternmost edge of the country, near the town of Vaals (after which it is named). Source - Wikipedia
Hostmore (LON:MORE) (I own) all fair, I tend to think anything can be turned around with the right strategy but good people seem to be making a right Horlicks of this one.... it's not rocket science is it to chuck a few TV screens in for major sporting events and stop the punters going somewhere else. Big falls on small holdings still hurt but more pride than the financial cost.
Hi Paul,
"I did some buying yesterday for 11 shares that had been on my watchlist, but were put on mid season sale earlier this week! "
Would you mind listing the 11 companies you bought? No worries if you don't wish to. tia
Hi eParo,
Would you mind listing the 11 companies you bought? No worries if you don't wish to.
Sure, on the usual basis - ie just as an ideas list, essential to DYOR, here are my (smallish) purchases yesterday, all companies we've discussed here, so my rationale will be in the "Discuss" tab of each share. I think they're nearly all GREENs, so there shouldn't be any surprises here - in each case they're shares I already consider good, and have dipped recently, giving a more advantageous entry price.
No Warpaint?
Morning alex,
"No Warpaint?"
No, I've been waiting about 2 years for a proper pullback...!
Regards, Paul.
Good luck with that Paul!
bargain shares after the heavy falls
Small caps and Aims are not the place for looking for bargains after the crash. The well run, family managed and less liquid shares have not dropped as much as you expected over the last week. The best bargains are among the mid and large caps, mainly banks and financials. Asset management companies are at the forefront: POLR, LIO, IPX, JUP and so on.
Banks have equally been punished, : PAG, Barc, Lloyds ,Hsbc
Steady as they go groups: Legal and General and Aviva ,MNG
Polar Capital Holdings (LON:POLR) sold off with the tech rout. Top holdings in their main tech fund include Nvidia, Meta, Microsoft, Alphabet and Taiwan Semiconductor.
Quite a bit of Director sales in July too.
Most of the Polar Capital Holdings (LON:POLR) directors sales were from share options.
That's very helpful Paul. Thank you! Would you consider posting your full portfolio with regular updates at all?
"That's very helpful Paul. Thank you! Would you consider posting your full portfolio with regular updates at all?"
In a word, no!
We've got quite enough on our plate with the existing workload. And, to be blunt, why should I? Do you demand access to my ear wax and hair cutting records too?
As Michael Caine would say “you were only supposed to blow the bloody doors off” I do worry with some of the requests here (and the brilliant weekly podcasts) that you are (understandably) getting frayed with the work and imho daft requests. You are very open every day / each week. Regular readers / listeners know what your top 5 are & what you have bought. As you repeatedly say “no one cares”. I dont care what you, Harwood, Paul Hill, Musk, Taylor, Cockney et al buy. I do like to understand WHY. Then I can agree or bark in agreement / remorse. So please stop posting the “what” everyone. We are only interested in the “why”!!! Keep it up Paul and Graham - and remember you can never please everyone! (PS I bought #GMS yesterday but if I told you why I would have to kill you)
My morning smallcap tweet: =10x record
Equals (LON:EQLS) SIMEC Atlantis Energy (LON:SAE), Property Franchise (LON:TPFG), Sanderson Design (LON:SDG), Maintel Holdings (LON:MAI)
◄Equals (EQLS)► PUSU extended for an Olympic record tenth time. Due diligence substantially completed and The Consortium is talking to its preferred financier. [SP=109.75 Cap=208m]. I hold.
◄SIMEC Atlantis Energy (SAE)► takes full ownership of the Battery Energy Storage System project at Uskmouth for £300k plus £3.85m deferred. The estimated capital cost of the project is £65m, which includes the deferred consideration and transaction costs. [SP=2.24 Cap=16m]
In line: TPFG, SDG, MAI
The take over panel have agreed to an extension of the 4th of Sept for the bid offer or decline of offer with regards to Equals (LON:EQLS)
Equals (LON:EQLS)
"The Consortium has substantially completed its due diligence and is progressing in discussions with its preferred party with respect to the financing of the Proposal."
So 135p offer still on the cards.
https://www.investegate.co.uk/...
Casual dining is a horrible sector, where it’s difficult to make any money in the UK. There’s still far too much capacity, and the TFI Fridays format feels dated now
TFI Friday? A fat finger error?
"TFI Friday? A fat finger error?"
I was wondering who would spot that! Initially a fat finger, but when I edited it, the devil in me left it in, to give u a chuckle! ;-)
Peel Hunt raises YouGov (LON:YOU) target price
Polling company YouGov (YOU) has scaled back its pessimism since a profit warning in June and announced that full-year results should be better than expected, while also launching a cost optimisation plan that is targeting £20m in annualised savings.
YouGov expects full-year revenues of between £327m and £330m with operating profit of between £43m and £46m, which are respectively 1% and 5% higher than June’s guidance.
In an effort to cut costs, the company is reducing support functions, discontinuing underperforming products, scaling back in certain non-core regions and cutting third-party supplier costs.
YouGov has also acquired generative AI-powered data analytics tools provider Yabble as it accelerates investment in the much-hyped sector.
Peel Hunt analyst Jessica Pok said it had not been an easy year for YouGov with a softer trading environment increased competition and internal inefficiencies leading to the significant downgrade in June.
‘Having said that, we now have a clear plan set out by management to address these issues, with the launch of the cost optimisation plan, improvements in the sales process and an acquisition to accelerate AI investment,’ Pok said. This gives us confidence and underpins growth for FY25E.’
Pok increased the sum of the parts (SOTP) valuation target price from 630p to 720p based on the updated 2025 forecasts, while continuing to use Peel Hunt’s target multiples that assume a haircut to peer multiples.
‘The shares have declined close to 50% since the profit warning,’ she said. ‘At 11 times [2025 estimated price to earnings], we believe the stock remains undervalued, given the strong capabilities, data assets and IP within the group.
The shares jumped 18.5% to 520p on Tuesday
Well said Paul! fingers crossed for mears group!
Unusual weakness recently, hopefully put to bed tomorrow!