Small Cap Value Report (Wed 7 Jun 2017) - FREE, SHOE, SRT

Good morning! It's Paul here.
Ed's charity bike ride
The boss here at Stockopedia, Ed, has signed up for a remarkable charity challenge, which is happening this Friday. Ed is attempting to cycle from London to Paris - in 24 hours - that's 300km. He's not even a keen cyclist, although has been putting in some serious training. It's a mind-blowing challenge, and would probably kill most of us just attempting it. Therefore this project clearly warrants our full support.
The charity concerned is raising money to find a cure for a disease called Duchenne. Friends of Ed's have a son with this condition. The explanation on Ed's charity fundraising page is very moving - one can only imagine what this child's parents (and others) have gone through, watching helplessly as their young child's health deteriorates.
As I haven't done a charity fundraiser myself for some time now, I'm feeling rather guilty. Hopefully SCVR readers will swing behind Ed, and donate generously. After all, Ed has paid me a fee for 4 years now to write these reports, which are free to read (not part of the subscription). So supporting this amazing charity challenge would be a nice way to give something back, to a very worthy cause. And most of us have done very well in this bull market!
So, good luck Ed! I hope he emerges in one piece from something so physically gruelling. I very much hope he doesn't injure himself, so fingers & toes crossed.
Here's the online donation page link again.
On to the markets. It's General Election day tomorrow, 8 June 2017, so I'm almost wondering whether it's worth reporting on individual companies today! - will anyone bother reading my article on a day like today?!
We're seeing quite a few erratic price movements, and profit-taking in small cap stocks which have done very well in this bull run. I'm wondering how many of the sellers are intending to buy back on Friday, if the election result looks positive for the markets? (i.e. a workable Tory majority, which the markets perceive as equating to stability & generally more business-friendly policies)
These violent price moves in some small caps are a timely reminder that you can incur a hefty percentage loss very quickly, when there's a rush for the exit. A lot of small caps are hideously illiquid. Combine that with market makers who like to run a neutral book, and it's a recipe for extreme volatility. When bearish conditions do kick in eventually, then I think a lot of people will get a nasty shock at how quickly big profits can dissipate - especially if you're using gearing.
A strange phenomenon I've noticed with myself is this - often when I sell something due to general market jitters, I find it difficult to buy it back. It's almost as if an emotional attachment to a stock has been broken by selling it. Then when you look at it later, with a completely fresh eye, with a view to buying it back, it doesn't actually look so attractive after all.
The lesson to be learned from that is clear - that we should assess our current portfolio holdings with the same critical eye which we would use to assess any new purchases. Easier said than done though - we humans like to think we're very rational, but a lot of the time, we're not.
As regards the election, I've come round to the view that a Tory win is by far the most likely scenario. Although I've got some hedges in place (mainly a Put Option on sterling:dollar) just in case there's an upset.
I'll recap on a couple of companies which reported yesterday, but I was too tired to write about at the time.
FreeAgent Holdings (LON:FREE)
Share price: 111.4p
No. shares: 40.7m
Market cap: £45.3m
Full year results - for the year ended 31 Mar 2017.
This is an accounting software company, which floated in Nov 2016. Its software is cloud-based, and is specifically designed for micro businesses - i.e. sole traders, and tiny companies with up to about 10 employees. FreeAgent is simpler & more user-friendly than Xero (I use both FreeAgent and Xero personally), and is a very good product for one-man bands, freelancers, etc. The closest competitor is probably QuikBooks, which looks very similar.
FREE is still loss-making, however that's deliberate, as the company is spending money on customer acquisition. The rationale being that once a customer starts using FreeAgent, then a stream of sticky, recurring revenues is secured.
The CEO of a SaaS business told me that the key metrics for a SaaS business are;
Churn rate - i.e. how many customers are lost each year. This looks extremely low (which is a very positive thing) for FreeAgent, at just 1.6% for direct customers, i.e. people like me, who sought out the product, and signed up directly from the company's website. As opposed to the other sales channel - which is customers who have been sold the product through their accountancy adviser - where the churn rate is slightly worse, but still outstandingly good, at just 1.9%.
What this ultra-low churn rate is telling us, is that once people start using FreeAgent, they like it, and stick with it. So the beauty is that FREE is adding new subscribers each year, and retaining nearly all their existing customers too. Each additional customer revenue stream is almost pure profit, which applied to a fixed cost base, is obviously an attractive business model, with massive operational gearing if sales really take off.
LTM/CAC - what on earth is this?! It's what FreeAgent call "LifeTime Margin" - i.e. the estimated gross profit from an average customer, over the expected lifetime. Or LifeTime Value (LTV) as some other companies describe it. That is then divided by the Customer Acquisition Cost - which I guess would mainly include marketing costs, social media advertising, sales teams, etc.
Given the low churn rate mentioned above, then LTM should be pretty high. There was a sharp deterioration in LTM/CAC from 3.8 to 2.9 for direct customers. That seems to imply that it's getting a lot more expensive to recruit direct new customers. However, it's still a reasonable figure.
The LTM/CAC for customers recruited via accountancy practices, is much better, at 6.1, which has shot up from 3.2 last year.
The only problem with these stats, is that the LTM is not knowable with any great certainty. If some new, killer product were launched (e.g. if Amazon or Google start giving away brilliant cloud-based accounting software for free, in order to harvest our personal data some more), then FREE's LTM/CAC figures would go out of the window, and the business would probably wither away to obscurity as customers drifted away.
The key P&L numbers are;
Revenues up 41% to £8.0m - very impressive, but remember this is being driven by heavy spending to recruit new customers. Of this, £0.4m was revenue from recharging development costs to RBS, so that has flattered the revenue growth figure somewhat.
Run rate of monthly recurring revenues is currently £8.6m p.a.
Admin expenses rose from £5.8m to £9.0m, which was a planned move to expand the business
Loss from operations rose from £1.0m last year, to £2.4m this time - again, as planned
Finance expense of £601k must relate to pre-IPO debt, which has since been cleared, so I think this should disappear in the 3/2018 figures.
Balance sheet - is OK, rather than great. The company has net cash of £4.3m, but its cash burn is fairly significant.
Cashflow - note that the company capitalises development spend. That was £969k last year. It fell sharply to £379k this year, but that was due to a chunk of costs relating to the RBS deal going through the P&L. So I suspect this line is likely to go back up again next year.
The trouble is, with this type of business, they have to keep spending on development, or the business would wither away. So it's up to you how you view that. Some people are happy with capitalising & amortising, whereas others prefer to adjust the accounts manually to write off all development spending as incurred (my preferred treatment, as it's ultra-prudent).
RBS deal - this could provide exciting upside - the idea is to give away FreeAgent to all of RBS's 665k micro-business customers. If the take up rate is decent, then this could potentially drive a big increase in recurring revenues. I've not seen any forecasts, but it would be interesting to model this, and see how the numbers drop out.
R&D tax credits - this is an interesting point, and has read-across for other companies claiming tax credits. How secure are they in the future?
The income tax credit for both the current and prior year relates to Research & Development tax credits. We continue to invest in Research & Development activity and, while this is an area of ongoing review by HM Revenue & Customs, we expect to be able to claim these tax credits for the foreseeable future, albeit at a reduced level.
My opinion - the Stockopedia computers chuck a bucket of water over us, reminding us that this is speculative, to a certain extent. It's classified as a "Sucker Stock", so really needs a lot of thought before taking the plunge.
A lousy StockRank too, although that's to be expected for a loss-making company in the growth stage. I think this obviously overlooked the quality of recurring revenues, and the discretionary nature of marketing spend;
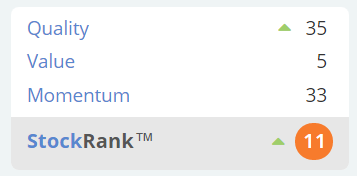
Therefore, in this particular case, I think there are good reasons to look through the current poor scores.
Overall, I do quite like it. It's a stock I've held before, but don't currently hold. I'm moderately tempted to buy back in at some point. The quality recurring revenues, and low churn are very attractive. Also the RBS, if it goes well, could be a nice catalyst for a re-rating. So, quite an interesting company overall, in my view.
Shoe Zone (LON:SHOE)
Share price: 177.5p (down 5.3% today)
No. shares: 50.0m
Market cap: £88.8m
Interim results - for the 6 months to 1 Apr 2017, from this discount shoe retailer (mainly in its own shops, but also a relatively small online presence).
These figures are only of passing interest, since the business is very seasonal, making nearly all its profits in H2.
Revenue fell 2.3%, due to "rationalising the store estate" - total store numbers fell from 518 a year earlier, to 504 stores at 1 Apr 2017. Note that the mix is leaning towards opening more larger stores, and closing some small to medium stores.
Underlying profit before tax in H1 fell from £1.7m last year, to £1.3m this year. Whilst clearly not positive that it's declined, this has to be seen in the context of last year's full year profit before tax being £10.3m. So a £0.4m deterioration in H1 this time isn't of much overall significance.
Dividends - the interim divi has been raised from 3.3p last time, to 3.4p this time. Divis are the main reason for holding this stock, as it's yielding about 5.7% - well worth having. Note that it also has a history of paying out special divis on top.
Outlook - "broadly in line" since the end of H1. Note that the company says it will benefit from the new business rates regime.
EDIT: Broker forecasts - I forgot to mention earlier, that FinnCap has reduced its EPS forecasts today, by 6% for the current year, and 4% for next year.
Balance sheet - is solid, with cash of £4.6m, and no interest-bearing debt. There is a pension deficit of £7.9m though.
Rents - a key advantage of this company, compared with other retailers, is that it generally takes quite short leases, and has very low shop fit-out costs. Therefore it is unusually flexible in its property arrangements. This avoids the risk of becoming lumbered with highly rented stores, and no means of exiting the lease - a problem which kills off many retailers.
Therefore ShoeZone can be opportunistic, and take advantage of cheap, empty shop units. Note that rents on lease renewal fell by 21.4%.
Total rents are 14% of turnover, which is actually quite high.
So the business model here is probably lots of fairly low turnover shops, but with high gross margins (due to directly sourcing product from Chinese factories), few staff & other store costs, and minimal capex needed to open shops, (and hence little depreciation), and short leases removing risk. Put that together, and it makes quite a nice, decently profitable business, which avoids a lot of the conventional risks in retailing. I like the business model, and also the entrepreneurial management.
As the High Street trading environment gets more & more difficult, it doesn't really affect these guys, as they can just relocate to cheaper & cheaper rented shops, hence remain profitable.
The Stockopedia historical graphs are interesting, and as usual give us lots of useful information at a glance;
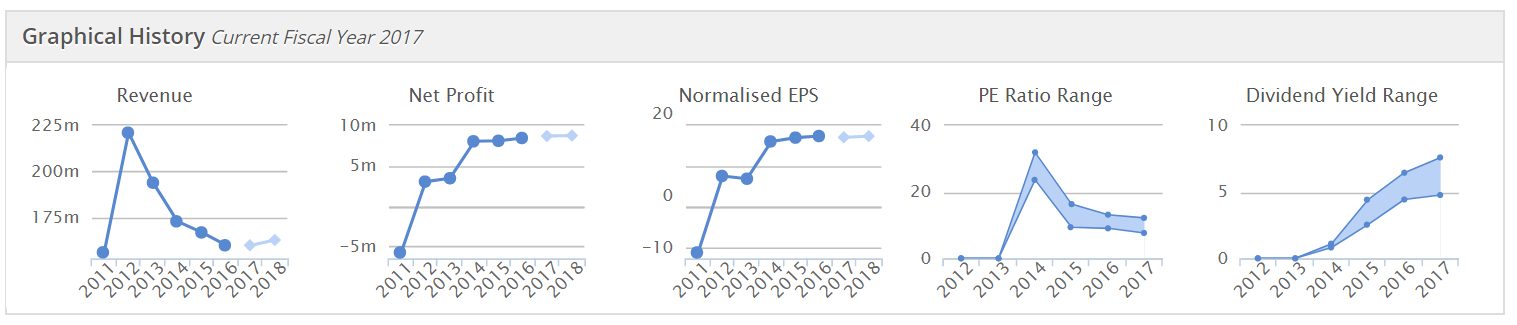
Graphs 1 & 2 - note how resilient profitability has been, despite declining revenues (presumably as non-viable shops were closed & handed back to landlords).
Graph 3 - as this mirrors graph 2, that tells us that the company has not been diluting shareholders with share issues - something I like to see, and is often the case at family-controlled businesses like this.
Graph 4 - the PER has traded within a range of c.10-14 in recent years. This suggests to me that buying when the PER is about 10 is probably not a bad option.
Graph 5 - a lovely progression in divis, and I think this omits special divis, so it's better than this graph suggests.
My opinion - as a boring, old-fashioned value share, I quite like this.
Trouble is, we're in a bull market, where people are chasing sexy growth stocks up, and big profits are being made on those. So why buy something like this, which could get cheaper? One reason would be for the divis. Although my worry is that the share price could fall further, thus negating several years' worth of divis.
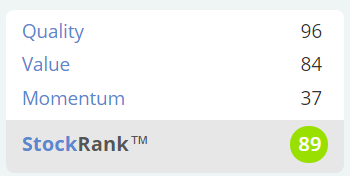
The StockRank is excellent at 89:
In terms of StockRank Styles, this company is rated by Stockopedia's computers as;
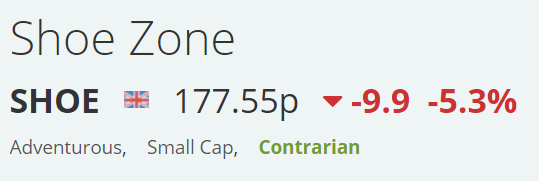
I'm enjoying the new StockRank Styles - it's an interesting sense check. The green texting of "Contrarian" means that it statistically fits with an investing approach which, on average, works well for a basket of shares.
I need to refresh my memory about the StockRank Styles, so here is the link to the explanatory notes on it. It's another neat tool for our stock-picking toolbox.
In conclusion then, I don't think SHOE is cheap enough to tempt me to buy any at the moment. This type of stock would probably need to be on a PER of something like 8, or below, to look attractive to me.
Also, remember that the broker forecasts are coming down again today, so the PER will go up. Therefore, I can't see that this is the right time or price to get involved in this share. Although if it dropped say another 20%, then I'd be tempted.
I'm finding it so difficult to concentrate at the moment, with so many things going on.
So, let's round off with some quickfire comments;
SRT Marine Systems (LON:SRT)
This is a small technology company, specialising in marine location products.
Figures for y/e 31 Mar 2017 look quite good;
- Revenue up 3% to £11.0m
- A big improvement in gross margin - gross profit is up 40.1% to £7.2m - so even though sales have not increased much, the company has made much bigger profits on each item sold. It would be interesting to find out if that's sustainable, or due to some one-off lucrative sales?
- Operating profit up from £320k last year, to £1.3m this year - pretty good.
- Note that the company benefits from a negative tax charge, which would obviously flatter EPS.
Balance sheet - trade debtors looks extremely high - this needs explaining. Ah, I've just found an emphasis of matter note from the auditors, as follows;
The auditors, in forming their opinion on the financial statements, which is not modified have included in their report an emphasis of matter on the recoverability of trade receivables of £2.166m, which have been outstanding for fourteen months and remain unpaid.
Due to the length of time that has passed, there is a potential risk to the recoverability. Based upon information provided by SRT's customer, the directors are confident that this balance will be paid in full, however the exact timing is uncertain due to the end customers internal project deliverable sign off processes. The financial statements do not reflect any additional provision that may be required, if the £2.166m is not recoverable.
Hmmm, that's not great. It's a material exposure, which makes me wonder why the company extended credit, rather than requiring payment up-front? All sales are a gift, until they're paid for, as the saying goes.
It also highlights the risks of dealing with overseas public sector bodies, where bureaucracy can be painfully slow, to get sign off on orders, and payments.
Outlook comments are always unrelentingly upbeat from this company, and today is no different;
" SRT Marine Systems now sits at the centre of the growing global market for maritime domain awareness technologies, products and systems. We end the year having increased our profits over three times and start the new year with a £77 million contract order book to deliver over the next three years and a validated pipeline of new sales opportunities worth up to £270 million."
These figures certainly excite investors, and imply a big increase in future profitability.
The trouble is, we've been hearing that sort of thing for years now, but the company never seems (yet) to make the big breakthrough in sales & profits that is promised.
This is shown by the Stockopedia historical history;
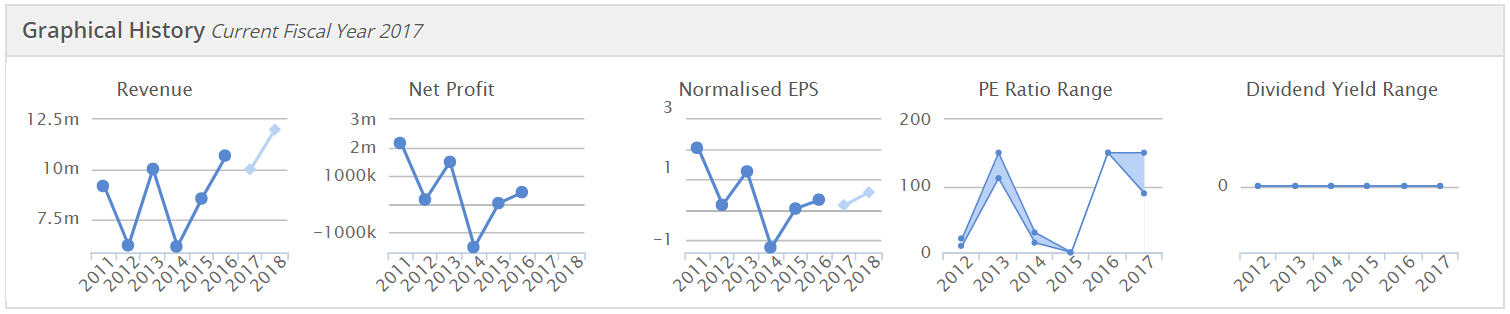
My opinion - I think the company has promise, and an apparently bursting order book & pipeline. However, given the history, personally I wouldn't be willing to pay a market cap of almost £70m, at the current share price of 54.2p. That strikes me as rather rich.
However, if the company does deliver a big increase in future sales & profits, then the market cap might make more sense.
For me though, based on what we currently know, I'd say risk:reward doesn't look particularly brilliant.
All done for today!
I'm out & about in the City tomorrow, including meetings with Revolution Bars (LON:RBG) and Best Of The Best (LON:BOTB) Directors. So I'll report back with my impressions.
Then of course it'll be an all-nighter for me with the election coverage. So I'm not sure whether I'll be up to doing a report on Friday.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Thursday 8 June:
SCISYS (LON:SSY) (which I hold) issued a positive trading statement this morning as its AGM statement. SSY appears to have fiully recovered from the project overrun that led to a profit warning over a year ago and to be making further progress. They have a good set of customer relationships and a strong track record in space applications in particular. Mike Love has always been cautious in his forecasts (which is why I still hold Dillistone (LON:DSG) and I'm thinking about buying more after the price fall) so I expect broker forecasts will improve after today's statement.
I was about to make the modest default donation to the editor's charity ride.
1 I clicked the Paypal option, on the assumption it would be quicker. They came up with a sheet offering credit at 17%. I think the button at the bottom was just to pay with cash from my bank account, but it was not completely clear, so I backed out of that option. [Slightly alarming to see such confusion, since Paypal is my largest US holding]
2 The debit card option has 5 pages to register. Virgin Money need to streamline their process.
Think you need to look at the adjustments on the SHOE results. PBT has gone from £1.9m to £0.3m if you add these back.
Seadoc, I disagree - the question is "when will SRT start getting paid for its big national systems?" When it does, there's a good prospect for a significant upward move in the share price. The current debtor issue, however, is a sobering reminder that it may not all be plain sailing. B2V
B2V,
" big national systems"
If they shore-based then I stand corrected, Belgium does have a lot of canals.
" it may not all be plain sailing"
Did a bit of that, hence my (misguided) comments.
Hi Paul, if you are feeling like it tonight, I'd really appreciate your thoughts on Ramsdens Holdings (LON:RFX) as they released finals today. Thanks
Boohoo.Com (LON:BOO) The second RNS is interesting, the sale of additional shares is presumably already agreed with institutions but after such a good update why would the directors want to sell 36m shares, worth nearly another £100m in the next 16hrs? Been watching for some time, Mr Market will probably disagree, share price may/will and hopefully Paul will comment in the morning.
I wouldn't worry too much about this. The CEO and biggest shareholder, Mahmud Kamani, has given himself the leeway to sell up to 11.3m of his 199m shares. That's less than 6% of his holding so I think it's safe to assume this relates more to his desire to start living like a multi-millionaire and less to do with him thinking the shares are over valued. Fair play to him (and the other directors) if you ask me. They have created a truly revolutionary and successful company, along with a lot of wealth for their shareholders. I think they deserve to enjoy some of their hard earned spoils. They have plenty of skin left in the game to stay motivated.
2 interesting RNS issued by Boohoo in the past half hour.
Paul,
SRT Marine Systems (LON:SRT) The proverbial question is "Where are the customers yachts?" If they are still in the builder's yard or on sea trials then 14 months would be the norm. But: can the buyer get the mortgage on his yacht to stump up the cash and take delivery? Of course (and not obvious from AR) they may sell mainly to commercial fleets, but these are also struggling. I do see AR shows that nearly half business is in middle east, including biggest customer and that second biggest is in Belgium, well known as a leading maritime nation (at least it does border the sea!)
I cannot fault your conclusion: "For me though, based on what we currently know, I'd say risk:reward doesn't look particularly brilliant." which sums it up well.
Seadoc
SRT is clearly not a stock that everyone understands well.Talk of sales to yacht owners and Belgium misses the point. Yes, SRT does sell equipment to boat owners but all of it will be sold via a dealer who buys the stock from SRT. Belgium is not so far as I know a major buyer of SRT kit although perhaps some European dealers are registered there. It's also possible that the Inland Waterways mandate has some connection with Belgium but it's certainly not the Belgium government shelling out.
The Middle East is a major territory for SRT sales but it is governments not boat owners driving sales. Bahrain unlike many of SRT's customers has been prepared to go public and have been very helpful as a reference for other buyers of which we know that Saudi is one of 3 others. The total value of these country specific projects was estimated last year by SRT at $95m.
It is important to note that SRT is no longer just a box seller although individual AIS units are sold via dealers. Many of these are not branded as SRT but will be sold under a number of well known marine electronics brand names. This is just one facet of a business that has become the leading supplier of complete systems which include the boxes that are fitted on boats, coastal station equipment to receive signals, buoys that not only transmit an AIS signal to alert shipping but which also signal weather and tidal data amongst other information.
Key to SRT's success in winning business from governments is its ability to supply all the elements that make up the system including the innovation display software called GeoVS. Half of all SRT R&D is now focussed on adding functionality that allows the operator to identify targets of interest and fuses AIS date with radar, sea charts, weather and tides. This allows SRT to provide a package of equipment which also includes the ability to feed the system with AIS data detected by satellite far out to sea, well beyond the reach of shore based stations.
Last year a contact was announced to supply a complete marine domain awareness system to a country in Asia. This project was subsequently paused to allow the end customer to redefine the scope of the project and we have been told this is now in the sign off stage and could lead to an increase in the size of the project which was previously in the region of $100m. This led to a significant outstanding payment which SRT believe will be paid once the scoping revision is complete as it reflects the definition of the project targeted in phase 1. Although the identity of the country involved has not been disclosed by SRT, keen SRT watchers are convinced it is Indonesia.
Increasingly national authorities need to be able to monitor their waters to prevent illegal fishing and to defend themselves against sea born terrorism. This has led to a number of potential projects which SRT calls the VSO (verified sales opportunities) which have progressed far enough to be considered realistic and warranting active involvement in pre contract planning. At least 3 other Asian countries are part of the VSO pipeline along with 2 in Latin America.
Large projects do not come to fruition overnight. Bahrain spent a year trialling equipment and another 6 months in contract negotiations. This causes investors to become impatient and lose interest but the work going on out of sight is real and we have been told significant progress has been made this year.
Basing an investment decision on SRT's EPS today overlooks the significant future revenues that are implied by the project pipeline being developed. Of course there's no guarantee that all of of the pipeline will occur but I'm convinced that SRT are the only company capable of supplying an end to end system that meets the needs of national authorities. To me that means that if a country wants to monitor its maritime domain, SRT will be the company they talk to first.
alterego,
The point you make about the anticipated revision of the major contract, assumed to be Indonesia, is exactly what I was anticipating in this post in the SCVR of 13th April:
"I agree with you kalkanite about the potential future workload for SRT. In particular, I think everyone tends to concentrate on thinking about "new" contracts with "neighbours" generated by the success of installed systems in regions, whereas I'm also interested in the potential for huge extensions to existing work.
The contract with Indonesia is a particularly interesting one to me. I very much doubt if the contract as currently issued covers more than a small fraction of the coastline and territorial waters of a nation with more than 18,000 islands stretching over thousands of miles in both directions, and a history of internal unrest. So, my hope is that this contract provides an extremely impressive system to Indonesia, leading to a series of similar contracts to increase national cover. The Philippines is a very similar country - don't know if SRT are involved with them at all, but hope they are.
Regards."
IMHO, the downside to all this potential, is the fact that two of the best potential state customers (Indonesia with 18,000+ islands and Philipines with 13,000+ and I gather that the latter is well along the path of verified potential contracts), both stretched out on a huge scale, are among the world's most corrupt countries.
Regards
Philippines has about 7,600 islands (only about 2,000 are inhabited) Indonesia has about 13,000 islands.
But terrorism is a real problem in the Philippines, quite a few terrorists were recently killed on Bohol in attempted kidnapping.
IIRC doesn't IFRS require you to capitaslise development spend subject to meeting the required criteria? We used to report under IFRS and moved to FRS following an acquistion - the year after acquistion the newly owning UK company required us to write off all the capitalised amounts but the ultimate parent who reported under IFRS required us to write them back on again. This was despite a change in auditor - I guess the view is that if you've justified that you meet the criteria to one set of auditors, the next set are unlikely to change their view however much you try - & we did try a little to get them to agree if only to stop the lunacy of writing it off for reporting in one jurisdiction and not doing this for the ultimate parent a/cs in another!
Thanks Paul for the kind write up and everyone for the support. It's incredibly motivating to have so many in the community backing me ! I will post some pics on twitter on Friday / Saturday.
I am very happy to back a great cause and best of luck for the ride.
I was disappointed that in giving, even through PayPal, Virgin Money Giving has its sticky information collecting hands all over it (and their terms and conditions suggest that they are not going to be shy about using and passing on the data collected).
I think they should be paying commission to Duchenne rather than charging them!
Hi any Boohoo.Com (LON:BOO) holders
You might like to read this article
http://uk.businessinsider.com/fast-fashion-is-getting-faster-2017-5?utm_content=buffera2eeb&utm_medium=social&utm_source=linkedin.com&utm_campaign=buffer&r=UK&IR=T
Regards
Howard
Thanks Howard, interesting, although, the final paragraph,
"Lastly, these online retailers use Zara's tactic of keeping production close to the headquarters and in key customer markets. According to the report, Inditex, the parent company of Zara, sources 60% of its products in Europe. Boohoo similarly sources over 50% of its products from the UK. "
Can it really be true that boohoo sources over 50% of it's products from the UK? seems unlikely, perhaps Paul will know more ??
K
I spoke to the Boohoo.Com (LON:BOO) FD on their stand at last years Investors Show and he told me that most of their product is sourced in the UK, much of it produced in the East Midlands.
He pointed to a picture of a signature piece that included a lot of hand sown decorations as an example of a high labour content item that would be sourced abroad - he didn't say from which countries but I suspect more likely to be Bangladesh or Vietnam than China. But I do believe that the simpler fast turn round items are from the UK.
Yup. Mainly from suppliers in Leicester.
Intercede (IGP) released prelims today. A world leader in its area of government grade identity management software, but sales still to really break out. Lots to like - IP, gross margins, very sticky, big company partnerships - but may be seen as a sucker stock by some? It's certainly in a growth sector so may be of interest...
Off subject, I have been following Ian Casell on Twitter of Microcapsules club, I believe Paul must have mentioned it on Twitter at some point :)
Can someone point me in the direction of a UK platform that you can trade UE micro caps on?
I know you can't trade them in your ISA, and my ISA provider only seems to allow Nasdaq etc and with a foreclosure risk.
Ideally I would like to open UK based dollar account to trade us Microcapsules and I am struggling to know where to look!
I have a USD account with TD Direct. It's a trading account and not an ISA. I only hold large caps in it so not sure about micro caps. If you name a couple of companies I can take a look for you to see if I would be able to buy them.
Thx a lot John
The two on microcaps front page are WLDN & STRP
Best regards
Ajay
Ajay,
At first sight, those both seem to be buyable on TDD. I can't be sure without buying some, but they come up on the search with Buy buttons next to them. You can search investments on their website without an account.
https://www.tddirectinvesting.co.uk/share-dealing/search
Thanks a lot John, gives a place to start :)
John, is your USD account with TDDirect any different to their normal trading account that allows purchase of US stocks ?
I severely dislike their 1.5% spread on forex. This is somewhat mitigated by the ability to sell US stocks & keep the money in USD for the next purchase.
However, even there they pull defeat from the jaws of victory by only allowing us to purchase stocks to 90% of the currency value, just in case of forex movements.
It's complete nonsense, considering the total funds I have with TD Direct are always about 20 times even the largest trade I tend to make. I have enough assets to cover any liabilities, so they should allow me to spend at least 98~99% of the cash. This is never a problem with domestic stock purchases.
Hi jonesj,
I haven't run up against that issue so far. I only hold US stocks in my account, which I opened earlier this year because of the high forex fees trading US stocks in my existing SIPP or ISA. I was looking for an account that lets me keep my funds in USD which is not allowed in an ISA.
I paid in GBP to my account and then transferred them into USD, which wasn't cheap (and it took a few days before the funds were available to trade) but I'm hoping it will be a one off hit as opposed to every trade. I then bought my US stocks. I only have about $300 left in cash so possibly I didn't hit the 90% barrier because my funds were already in USD before I started buying?
I haven't sold anything yet because they've all been doing OK even in sterling terms so can't comment on that aspect.
It's a stock I've held before, but don't currently hold.
What was your reason for selling Paul, as you have commented positively previously and again here, and I have not noticed any particular reason why anyone would sell so far, unless I have missed something!?
I too am a holder, and a user of FreeAgent software and have a similar opinion as you. I love the product, far better than other small business accounting software I have used, with its simplicity and impressive levels of integration being the deciding factors for me. Having direct integration to the company bank account, HMRC and so on makes life much much simpler, and when they develop the integration for personal Y/E tax returns (already there, but still a bit rudimentary) then it will be the icing on the cake.
As a holder, I hopefully will be for some time to come, as I do not see this as a share to trade.
TT
Hi TT,
I'm struggling to remember why I sold my FreeAgent Holdings (LON:FREE) shares.
I think it was general nervousness about holding shares in a loss-making company, and worries about whether the market cap could go much higher in the short term.
Also worries about competition under-cutting on price.
Overall though, on reviewing the numbers today, I'm toying with the idea of going back in at some point. Let's see how the GE pans out first though!
Regards, Paul.
I can relate to the psychological difficulty in buying back a share that you recently sold. It's something that has cost me quite a few opportunities over the years.
The way I am trying to deal with this is to borrow from Terry Smith's concept of an investable universe. So when I sell I ask myself is this a share I would be prepared to buy again, or is it one to stay away from. If it's a potential buy again, it goes in my "investable universe" portfolio which I review when I next have some cash to invest. Often the shares in there are better than my latest bright idea.
John, I'm probably (overly) interested in this, purely from analyzing my own actions over the years, and like you, have a propensity to avoid re-investing in shares I've previously owned.
From a logic perspective, this is crazy. After all, the chances are you've already done the research and know the company already. So why chuck the baby out with the bathwater, just to invest in something new and unknown?
From my own investing over the years, it's abundantly clear that every dog has its day, some will go on to great things, some will come crashing back to earth and lose money. Timing, is of course, everything. But you might catch a stock you've lost money on, that's 'on the up'. I've lost count of the stocks that I've sold out of, only to see a few years hence that they recover and then surpass the price I sold them at. Or they go bust! So in my view, it's heavily skewed towards a binary result.
Anyway, this long-winded waffle from a night-time in LA, is purely is to say that:
1. Never discount a stock you've owned previously, you may well be able to make money off them, after all, you've already have done the research
2. Don't confuse this with catching a 'falling knife'. I'm not talking about averaging down. More revisiting old strategies, back testing them and see if they still hold true.