Small Cap Value Report (Wed 8 Jan 2020) - RFX, GRG, MPAC, TPT, SHOE

Good morning, it's Paul here.
Please see the header for the shares I will be looking at today.
Estimated time of completion is 1pm.
Edit at 12:17 - I want to spend more time on MPAC and SHOE, so am going to continue until 3pm. Hopefully there will be enough here to keep everyone happy in the 1pm email. Update at 15:09 - today's report is now finished.
Early snippets - no doubt MrC will cover these in his usual (very helpful) morning comment below, but this is what caught my eye on my first scan of the RNS today;
Ramsdens Holdings (LON:RFX) - strong Xmas trading, "comfortably ahead of market expectations" for FY 03/2020. Higher gold price helps pawnbrokers.
Greggs (LON:GRG) - exceptionally good year. FY u/l profit "slightly higher" than previous (already raised) expectations. Tough comparatives from now on. Cost inflation - wages & pork. Popularity of new vegan products. A remarkable success story, priced accordingly (PER of 26!)
MPAC (LON:MPAC) - trading ahead of upgraded forecasts
(all 3 of these companies are covered in more detail below)
Ramsdens Holdings (LON:RFX)
Share price: 249p (up 6% today, at 08:52)
No. shares: 30.8m
Market cap: £76.7m
Background - Graham normally covers this one, but I'm trying to broaden my coverage a bit as a 2020 aim, so I'll have a go at interpreting this. It's a pawnbroker, with additional focus on other financial services, especially forex. Today's update is for the FY 03/2020.
Stockopedia likes it, with "Super Stock" classification, and a very high StockRank (before today's update);
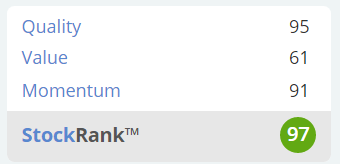
One of the things I like about the StockRank system, is that it picks up on companies with improving trends, which we might otherwise miss, e.g. in this case note the steadily rising earnings forecasts;
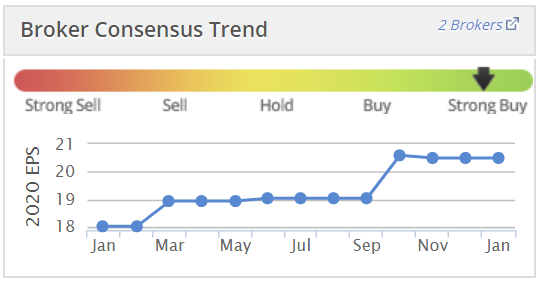
Anyone who was buying companies with earnings upgrades in the autumn, whilst all the political shenanigans was keeping many other people on the sidelines through fear, will have done spectacularly well in the last couple of months, as money has flooded back into this type of share.
For more background on Ramsdens, here is our archive of Graham's extensive coverage of it. If I'm short of time, I tend to just read the most recent couple of articles, including the most recent results. This interesting review of its interims, from Graham, is particularly helpful in getting me up to speed.
Trading update today sounds very good;
... the Group has delivered strong trading during the Christmas period, with each of the Group's key business segments performing ahead of the prior year. As a result, the Board now expects the Group's full year profit before tax to be comfortably ahead of market expectations.
Comfortably ahead - what does that mean? Materially is usually 10%, so I would guess that comfortably ahead probably means about 5%. Isn't it ridiculous that we have to guess like this? I know it provides wiggle room, but surely they could have given a range of percentages, e.g. 3-7% or something like that? We need more clarity & standardisation when it comes to trading updates, instead of coded wording, then the brokers being told the actual numbers, to put into their forecasts.
Thankfully there's a good quality update note today, available on Research Tree, to guide us. The broker has upgraded forecast for FY 03/2020 from 20.6p EPS to 22.6p EPS, so a rise of just under 10%. I was too low with my 5% guess!
At 249p per share, the updated PER is now 11.0 - which looks good value - although this type of business tends not to attract a particularly high rating.
Another positive factor is the rise in the price of gold this year, which boosts profits for pawnbrokers.
Outlook comments sound positive.
Balance sheet - as usual, I always have to check the financial strength of every company here.
Looking at the last interim accounts, its balance sheet looks excellent - very strong, so no issues there at all.
Dividends - the yield of 3.3% is well covered, about 2.7 times, and importantly, the company has a strong balance sheet, so has the capacity to pay more generous divis if it wishes - investors often overlook this important point. In an ideal world, I like to see not only a decent yield, but plenty of capacity to not just maintain, but to grow future divis. That can work out better than chasing very high, but unsustainable yields.
My opinion - on a purely financial basis, this share looks excellent. But do you really want to own shares in a pawnbrokers? I don't.
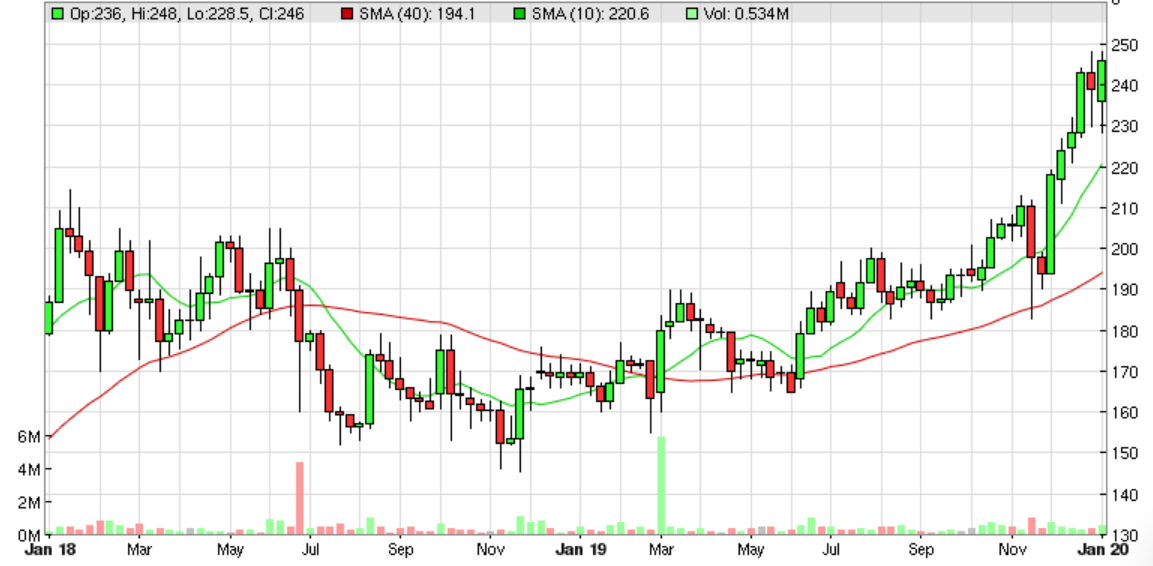
The shares would have made an excellent value buy last year, and despite a decent rise recently, are not expensive even now, on fundamentals;
Greggs (LON:GRG)
Share price: 2403p (flat on the day, at 11:46)
No. shares: 101.2m
Market cap: £2,432m
This is such an interesting stand-out company, I have to cover it, despite it being a mid cap.
It does strike me as odd that Greggs is doing so well, when practically everything else on the High Street is doing so badly. Although as we discussed here before, a lot of its business is probably repeat business for people who live & work in town centres, so need to be fed every day. Many of us are creatures of habit, and buy lunch from the same place every day, when working nearby. Greggs is quite cheap, and tasty food. Also, in many towns there's not much competition for properly fresh, cheap food.
Then there was the brilliant razzmatazz & strong sales that Greggs managed to create around its vegan sausage roll. They're sensibly continuing that theme, with a vegan steak slice being launched imminently, I believe. I'm looking forward to trying one of those, as like a lot people, I'm interested in reducing my meat consumption.
Even so, I'm staggered at the +9.2% LFL sales that Greggs achieved in FY 12/2019.
It's already increased forecasts repeatedly upwards in 2019, and despite this, still finished the year with a little extra;
Full year underlying profit before tax expected to be slightly higher than our previous expectations
Outlook - cost headwinds, and strong comparatives are an issue.
My opinion - the company's track record is superb, and I certainly wouldn't bet against it.
As the now firmly established leader for affordable food on the go, I could see sales continuing to rise. That said, with cost headwinds, profit growth might be harder to achieve, and given that Greggs are now ubiquitous across the UK, how much profit growth is there left in the tank?
Forecast profit growth for next year is only about 6%. So the PER of 26 looks very expensive. To justify such a rating, Greggs will need to substantially out-perform again in 2020, just to stand still (in terms of share price).
Overall, terrific company though it is, the shares look far too expensive to interest me. I'd be tempted to bank profits today, if I held, on valuation grounds. Then buy back on any future dips, if the PER fell to something more reasonable, like 20 times.
But it depends what you think is likely to happen to interest rates. If they stay permanently low, then a PER of 20 (earnings yield of 5%) for a great business, is actually not expensive. Particularly as recession risk for the UK seems to be receding. Tricky one, isn't it? Do we pay up for quality, or play it more cautiously?
MPAC (LON:MPAC)
Share price: 238p (up 15% today, at 12:18)
No. shares: 20.2m
Market cap: £48.1m
Mpac Group plc, a global leader in 'Make, Pack, Monitor and Service' high speed packaging and automation solutions, provides a pre-close trading update (unaudited) for the year ended 31 December 2019.
This used to be called Molins, making tobacco packing machines. Presumably the name change, and more generic self-description, was intended to put PC/ethical investors off the scent! EDIT - I'm told that the tobacco machinery division was sold some time ago, so looks like that isn't relevant any more. End of edit.
Continuing the theme of companies out-performing & getting repeated earnings upgrades, look at this! Earnings forecasts (broker consensus) has almost tripled in the last year - spectacular stuff;
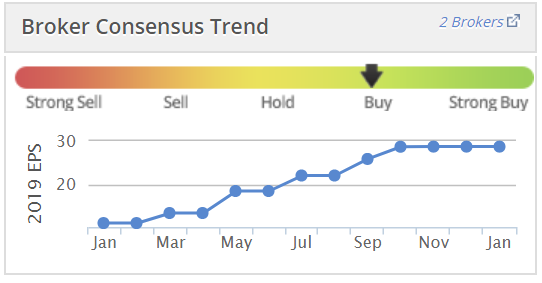
This begs 2 questions;
1) What's going on to drive such an outstanding improvement in profitability? and,
2) Is it sustainable, or just a one-off good year? (EDIT: or maybe a large customer programme with a finite end point?)
I won't have time here today to drill down to that level of detail, but am certainly going to be printing off some broker notes, and doing some deeper research, and will report back at a later date.
Positive update today - this sounds great, coming on top of the very substantial forecast increases already;
On 5 September 2019, the Group reported that its profits for FY19 were expected to be significantly above the Board's and market expectations, with the momentum gained earlier in the year continuing throughout the second half of the year.
The Board is delighted to announce that since that date, momentum in the business has continued to accelerate and we expect to report a full year trading performance ahead of these upgraded expectations. This is primarily as the result of a strong Q4 order intake and accelerated project execution.
Outlook - this sounds positive for continued strong performance in 2020;
"I am pleased with the overall business development and the high level of performance delivered by our global colleagues which has enabled us to report a further trading performance upgrade for 2019.
Order intake and revenue growth have continued for both Original Equipment and Services and the Group will close the year with a strong order book for execution in 2020.
I am confident that we will be able to report an excellent financial performance for 2019 and improved outlook for 2020 which gives us confidence for the future progress of the business."
Pension deficit - is large still, so this needs to be factored into the valuation - i.e. it's the reason the PER is low. That said, if the underlying business is now trading its socks off, then the pension deficit becomes far less of an issue.
My opinion - I've not looked at this company properly for over 3 years, so am not going to rush out an ill-informed opinion today (that doesn't usually stop me, I hear you cry!).
However, today's update, and the latest note from Equity Development, sound very interesting. Therefore I'm going to flag this as definitely worthy of a closer look. It's tempting to buy a few shares straight away, and then do the detailed research later, when something crops up that has such strong earnings momentum as this.
There's an excellent summary from davidjhill in the comments section below, many thanks for that.
Topps Tiles (LON:TPT)
Share price: 76.6p (up 1% today, at 13:36)
No. shares: 195.0m
Market cap: £149.4m
Topps Tiles Plc (the "Group"), the UK's largest tile specialist, announces a trading update for the 13 week period ended 28 December 2019.
This tiles retailer has a 30 Sept year end, hence why it's reporting Q1 figures today for Oct-Dec 2019.
At first sight, the LFL sales of -5.4% in Q1 sounds bad. However, the trend is improving;
First 8 weeks: -7.2% (previously reported)
Next 5 weeks: -1.4%
Q1 total: -5.4%
It's still a poor overall result for the quarter, but this was a period of exceptional political turmoil, so I'm prepared to look through one bad quarter. The company's track record is that it sometimes has one bad quarter, so that's probably why this hasn't scared the horses.
More detail is given. The most interesting thing about this share, is its entry into commercial tile sales, which potentially doubles the addressable market. That's doing well, with sales up 250% from a low base.
Outlook - doesn't really say anything;
"As we enter 2020, we remain confident that our market-leading retail offer and growing commercial operations give us a strong platform from which to deliver sustainable growth over the medium and long term."
Valuation - the main attraction of this share is the decent divi yield, and the hopes for longer term growth. Having said that, I can't see any particular reason why the share price should be any higher than it is now.
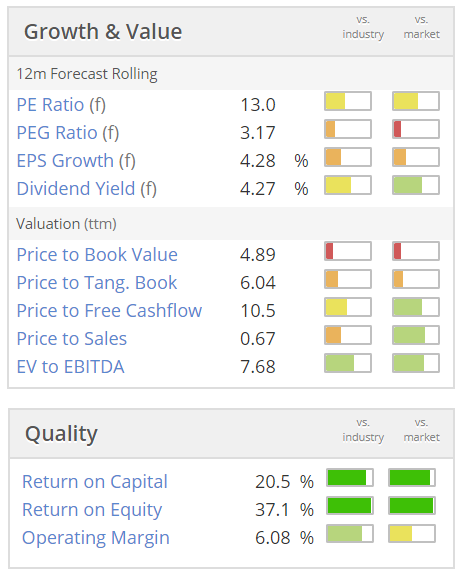
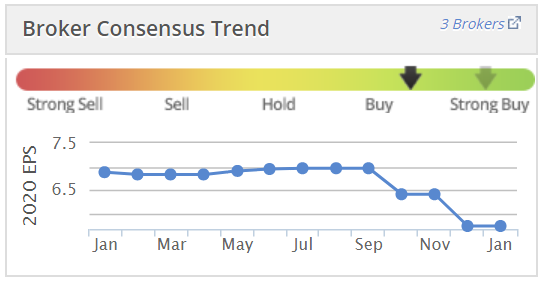
Unlike the other companies I've written about above, Topps Tiles has seen its earnings forecast fall over the last 12 months (see below). Note also that its EPS this year is lower than it was 6 years ago. What's likely to change, to trigger a sustained increase in EPS in future? Maybe if the commercial tiles division really takes off in a big way?
My opinion - looks priced about right to me. There could be possible upside from a recovery in consumer confidence in 2020, and earnings upgrades. So I certainly wouldn't bet against it.
This seems a well managed business, but the shares don't have enough upside potential at the moment to get me excited. Although having said that, I think Topps Tiles definitely goes in the category of retailers that are weathering the storm. Hence it's likely to not only still be around, but likely to be a bigger business in say 5-10 years' time.
Shoe Zone (LON:SHOE)
Share price: 157p (down 3% today, at 14:08)
No. shares: 50.0m
Market cap: £78.5m
Shoe Zone PLC ("Shoe Zone"), the UK's largest value footwear retailer, operating in Town Centres, Retail Parks and Online, is pleased to announce its Preliminary Results for the 53-week period to 5 October 2019.
Background - as you can see from the chart below, this company had a wobble in Sept 2019, with a profit warning. That turned out to be a nice buying opportunity, and enabled buyers to lock in a fantastic divi yield. Of course, we didn't know that for sure at the time, unfortunately! It could have been the first in a series of profit warnings, but wasn't.
This is what I like about ShoeZone;
- Entrepreneurial management, with large personal shareholdings
- Short leases, and low fit-out costs, so very flexible - rent reductions
- High gross margins
- Expansion of big box format
- Cash generative & generous divis
- A High Street survivor - no question of it going bust
- Strong balance sheet
Results - per the profit warning in Sept 2019, profitability has reduced, but is still fairly good.
- EPS - underlying (i.e. pre-exceptional) EPS of 16.45p - giving a PER of 9.5 - good value.
- Divis - maintained at 11.5p, to demonstrate confidence in future growth. Yield of 7.3% - I reckon that's sustainable too, so very nice indeed.
- Balance sheet - very good. Although note there is unusually for this sector, a pension deficit, which has grown to £9.7m, and is a cash drag (recovery payments) of £890k p.a. I believe this is not accounted for within earnings, so needs to be adjusted for when valuing the shares.
- Cashflow - excellent, although not enough to cover divis and capex this year. Both of those are discretionary, so this is not a problem. Note the plans to open new stores & refurbish old ones, so capex looks ongoing (although it's far from excessive).
Property costs - note the comments on excellent deals being achieved from landlords, and that rent-free periods typically recoup half the capex spend over time. The company is only signing 5 year leases, and has average lease length of 2.1 years - hence ShoeZone management has completely side-stepped the main problem which has brought down many other retailers - namely uneconomic leases. That's the best evidence you can get of a really switched-on management team, in my opinion.
This is a great time to be expanding, as the lease deals available are so good. Rents are falling by nearly 24% on renewal too. That helps to offset other cost increases.
The company belly-aches about business rates, with some interesting stats in the commentary. Whilst I sympathise with them, the reality is that business rates are really a tax on the landlord. but paid by the retailer. When deciding whether to open a new shop, the procedure at all retailers is to estimate the revenues, and costs, part of which is to put the rent, service charge, and business rates into a spreadsheet model.
Therefore, if business rates go up, then the landlord won't be able to let out an empty unit to a new tenant, unless they reduce the rent down to a level where rent+rates are sufficiently attractive to sign up a new tenant.
Business rates is a significant part of overall Govt tax revenues, which they cannot afford to forego. So if they were to reduce business rates, then other taxes would need to be hiked.
Anyway, the comments from SHOE are very interesting, and worth considering.
There is an argument that online retailers benefit unfairly from operating out of warehouses, which have much cheaper business rates. That would carry weight if online retailers were making massive profits, but they're not. BooHoo is one of the few that makes a decent profit margin. Many other online retailers struggle to get into profit at all. So I feel the reality is that online retailers just have different costs (marketing & high product returns rates) which offset any benefit they gain from lower business rates on their premises.
My opinion - of the 2 retailers I've looked at today, Topps Tiles (LON:TPT) and Shoe Zone (LON:SHOE) my view is that SHOE is by far the better bet at the current modest valuation. Its >7% dividend yield looks great, and should be sustainable.
I see the dip in earnings this year for SHOE as probably being a temporary glitch, rather than a more worrisome trend. There's plenty of positive stuff in the narrative today, to imagine that profits should stabilise or recover in future.
That's it from me today, thanks for tuning in!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Greggs (LON:GRG)
To be honest greggs probably have enough room to triple the stores they have in the uk before they reach full market saturation.
If we look at the experts on greggs cuisine the bods from newcastle clearly lead the way - in newcastle they average 10 shops per 100,00 of population (rumour is there are over 31 greggs stores in newcastle/gateshead area alone - thats probably compared to less than 5 maccy d's)
ok 65,000,000 / 100,000 * 10 = 6,500 units once everyone reaches the level of greggs consumption currently being seen in newcastle.
Dang - can't believe i sold my shares before doing that calc - sigh.
Shoe Zone (LON:SHOE) - I hold
I think the point re Shoe Zone v Clarke's from my local observations are:-
Clarke's expensive shoe, sites & customer retail experience (the type of customer who invests in shares?)
Shoe - Cheap site, look feel sells volume "Adequate" product continually at cheap price point - KNOW which end of town to be and how to make money (JAM individuals as customers?)
Yes I agree with you but the ShoeZone were not that cheap around £20 but the quality is poor, for hardly anymore in the sale I can buy better looking and seem much better quality elsewhere. The choice of styles I found rather limited in ShoeZone, so I have not been impressed. I also find the chinese shoes to be too narrow for my british plates of meat. I have read that chinese shoes are narrow from someone who works in shoe manufacturing. I find generally many shoes are not wide enough now. So I have bought 2 pairs of Clarks and will see how they go.
I'm pretty sure Clarks manufacture in China too
Yes it seems some are.
I think there shoe products are pretty hideous to be honest , am amazed they are doing so well .
I bought a few pairs of shoes from shoe zone a few months ago, I was quite impressed with the shoes and I have been watching the share price for a few months whilst doing some research into the company. I personally think the company is a good buy, as everyone always need shoes!
There are no real broker out there, they're all out for fraudulent act. Don't waste your money on any broker. Am pleased to and grateful to Mr McGregor for helping me to recover my lost funds from a scam broker. You can also reach out to Mr McGregor via his email mcgregorsteven19@gmail.com or whatsapp him on +79209471789 if you need help
For Ted Baker LON:TED fans only.
Sky News
Is anybody still holding?
Bonitabeach
Hi Paul,
Any idea if Sosandar is still advertising? I have been looking at the latest web stats for December released today and its difficult to analyse without that key fact.
Before advertising they were getting approximately 70k hits per month, which jumped to 130k in September then 180k in October and November. It was back to 130k this month. How I see it is if they are still advertising this 25% drop could be a concern, however if they have stopped the TV ads and tube advertising this could purely be organic and repeat customers. In that case their base without advertising has gone from 70k up to 130k which would be very good.
The stats are coming from similar web which obviously needs to be taken with a pitch of salt, but does still give a base to compare against.
Any idea?
Thank you
Re Sosandar (LON:SOS)
Hi Lewisbabbage
I personally wouldn't read too much into the similarweb numbers or trends.
I tried to do a similar exercise with another retailer a few years ago (I forget which one) and the online traffic from similarweb had pretty much no correlation with the final results.
As an aside, if you look at boohoo.com on similarweb you'll see a similar decrease in "web traffic" between November and December.
Cheers
A
I don't eat there much, but I love Greggs (LON:GRG) as an investment (although I missed the boat on it).
At 2,000 locations I think there is actually room for some more - this is not like a Card Factory which has probably reached saturation point. By contrast there is a case for Greggs on every secondary retail street, or train station having a certain amount of passengers.
At the moment they seem to have a big advantage over the competition. Outside of independent/small chain bakers, Subway might be the closest in that they offer hot savouries but they seem to have lost their way a bit.
So if I were a shareholder I wouldn't want a special dividend, but re-investment: for the cash to accelerate roll-outs of differing store formats, I know that some of the newer ones are doing this, offering seating areas, drive-thru or 24-hours.
Anyone know if there are plans for expansion? It would seem terribly difficult to start from scratch but an acquisition of another chain in Europe could be great; no reason why their business model would not work there.
I like Greggs (LON:GRG) too - food and company - also missed the boat - there have been opportunities in the last year to 18 months.
Re expansion to Europe - I am not sure - Europe does not really rate UK culinary skills all that highly and bakeries are quite literally everywhere and your bog standard caf will have a reasonable offering (my sample is Barcelona where I spent some time).
Then again, they also speak ill of McDonalds and KFC, yet they usually had the longest queues (probably all tourists!)
I don't doubt that there is still room to grow especially in travel locations - service station stop, was clear that McDonalds and Greggs had by far the most customers.
My concern is on whether they can increase pricing to absorb cost rises - when you are known as the low cost operator, it creates an expectation among the customer base
MPAC (LON:MPAC) - nice write up Paul - share the sentiment - looks attractive on the face of it, but something stopping me pushing the button - does anyone have insight into their history - performance is far from consistent and that raises concern around stability - interims elude to legacy loss making contracts. Also I think at least part of the growth in US reported at interim was driven by tax benefits of CAPEX, which I don't think repeat (or at least not to the same extent).
Anyone have any insights into the history of the business - the volatility in earnings - view on sustainability going forwards.
Happy New Year Everyone.
But the cost rises that might hit Greggs (LON:GRG) will also hit their competitors so they should be able to raise prices to cover. As regards possible foreign acquisitions, as a holder I would not be enthusiastic about that. The key to remember is that they are vertically integrated. Might be better to build from scratch in big urban centres but it would be risky to try that in Europe. While there is opportunity remaining in the UK I see little point.
Mpac
I am a long term holder and have been buying many more from mid December from 173 to 200
The company is much changed with new management . The purchase of Lambert ( just up the road in Tadcaster ) looks like it’s fitting in really well.
With several upgrades behind us there are more to come.
The market is still well behind the curve of increased Eps here and 350 looks fair on what we know.
I think 40 p could be made in current year and with 35% of the share price in cash the shares in my opinion have much further to run.
It may look as if the price has jumped but that’s because the market missed this . Similar to Dart group that again is not understood by the market.
Advfn has some good posts.Paul I look forward to your detailed report.
Mpac (LON:MPAC) / Pensions
IAS 19 valuations of pension liabilities are 'best estimate', whereas the 'technical provisions' used in the actuarial valuation for funding the liabilities have to be prudent. In addition, IAS19 liabilities have to be discounted at rates based on corporate bond rates (which was purely pragmatic decision by the accounting bodies as they couldn't agree on a sensible basis) even if this makes no sense at all. Technical provisions are usually based on gilt rates, adjusted upwards to reflect the make up of the liabilities between members and pensioners and the profile of investments held by the scheme. It's a complex topic, so I'll stop there!
IAS 19 surpluses are largely mythical in my view as the pension scheme trustees would simply use any large (real) funding surplus to fund the additional (and hefty) cost of buying out the liabilities with an insurance company. How could any sane trustee justify continuing with the covenant of a corporate sponsor as guarantor of scheme funding compared to the covenant of a major insurer?
Thanks 12barblues - that's a useful summary. Whilst I had always been aware of the "best estimate vs "prudent" distinction I hadn't appreciated that IAS19 liabilities discounted on corporate bond rates, so the difference is starting to make more sense now.
Yes, I'm looking at MPAC now, should be a section on it up by 1pm-ish.
The ticker is in the article's header, which usually means I'll be writing about it, subject to time constraints. As it's been requested, I'll move it up the priority list!
Shoe Zone (LON:SHOE) Please Paul as even if you note it - if I ask for it it moves up your list apparently
Interesting their take on Business rates effect on their bottom line
Just went passed a Shoe Zone shop, empty, Clark's up the road had quite a lot of customers and were busy selling shoes even though probably well reduced in the sales. I tried a pair of Shoe Zone shoes once, rubbish, made in China, will not last very long, will buy Clarks for a bit more money and will last many years if my old ones are anything to by.
Interesting experience there herbie, the last time I bought shoes from Shoe Zone I wore them everyday for work and they lasted me 2 years! Either I got lucky or you got unlucky.
Looking forward to your write up on Shoe Zone (LON:SHOE) Paul, I note the pension deficit has increased notably since the prior valuation however I feel this is in control. Also interesting to read the potential impact of accounting for leases which comes into play next year. Overall it is a tightly held and well managed company with no debt.
Paul just to clarify - MPAC sold its tobacco machinry business in 2018 (I think roughly) it is no longer operatimng in that sector. It had a packaging business for many years and this is now its main activity.
Paul just to clarify - MPAC sold its tobacco machinry business in 2018 (I think roughly) it is no longer operatimng in that sector. It had a packaging business for many years and this is now its main activity.
Oh blimey, I didn't realise that! Thanks for flagging, I'll amend the text.
Regards, Paul.
Another vote for Mpac (LON:MPAC) if you're able to Paul
MPAC (LON:MPAC)
davidjhill
Certainly looks like a decent recovery play here based on what you have posted - any chance of some comments ref this company Paul?
Mpac (LON:MPAC) anyone else think these look interesting after todays announcement?
Expectations have now been upgraded 5 times in a row. Research on RT this morning shows expectations now of 34p EPS for the full year with 60% of next years revenues already in the order book of £50m+. Net cash for full year now expected to be circa £18m or 90p per share rising to £1 worth or £20m next year (after pension deficit payments).
So trading on PE of 6.5 or adjusted for cash a meagre 4*
There is value in its owned land as well so if it ever gets planning permission could add a large chunk as well (£1 or so I understand).
Statement was pretty bullish - taking a leaf out of Gromleys book company language around next year was much more bullish than the last time they upgraded just a couple of months ago.
I guess the main detractor for people has been the pension. Can't do much about the size (it is large in absolute terms no doubt about it but maybe an opportunity to outsource it once deficit eliminated?) In the H1 statement the company said the actuarial deficit was reduced to a level now where it will be eliminated 5 years earlier than planned in 2024 so that's only 4 years away. Post that the company should generate £8m+ of cash every year for shareholders (20% of its current value).
The IAS19 valuation shows a surplus of £30m though. Maybe someone can help explain why the actuarial and IAS19 differ so widely given both are recent?
As the company is adding to a cash pile that is already 40% of its market cap even after paying the pension deficit contributions I would also like to see a dividend introduced at the 2-3% level as I think that would help encourage holders.
All in all though it feels undervalued to me.
My morning smallcap tweet: You cannot be Sirius!
MPAC (LON:MPAC) Rosslyn Data Technologies (LON:RDT) Asimilar (LON:ASLR) Sirius Minerals (LON:SXX) Intelligent Ultrasound (LON:MED) Ramsdens Holdings (LON:RFX) Shoe Zone (LON:SHOE) Shield Therapeutics (LON:STX)
Mpac Group (MPAC) ahead of expectations upgraded in Spet.
Rosslyn Data Technologies (RDT) wins two contracts worth £0.9m min.
Asimilar Group (ASLR) £6.8m placing at 40p, a 23% premium! That's 8x SP a year ago. Will be invested in the latest bandwagons ie big data, machine learning, telematics and IoT. Not CBD and quantum computing? Slackers.
Sirius Minerals (SXX) mooted offer at 5,5p, a 34% premium, from Anglo American. SP rose 12% yesterday. Looked like a bust to me. I'm short.
Intelligent Ultrasound (MED) guides FY rev £5.7m-£5.9m. F/C £6.5m yet CEO trills "This has been a strong year for the Group."
Ramsdens (RFX) guides FY pretax comfortably ahead of market expectations.
Shoe Zone (SHOE) FY U/L pretax marginally ahead of our revised expectations following revaluation of freehold property.Current trading in line.
Shield Therapeutics (STX) deal for development and commercialisation of Feraccru/Accrufer in China. $11.4m upfront licence payment, up to $51.4m development and sales milestones, double-digit royalties.
ASLR was my tip I mentioned a coup,leg of weeks ago - there are warrants as well being given out at 130pm so clearly the new investors feel there is a long way to go yet