Small Cap Value Report (Wed 8 Mar 2023) - RTN, SOM, CTO, HEAD, BUMP, MMAG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
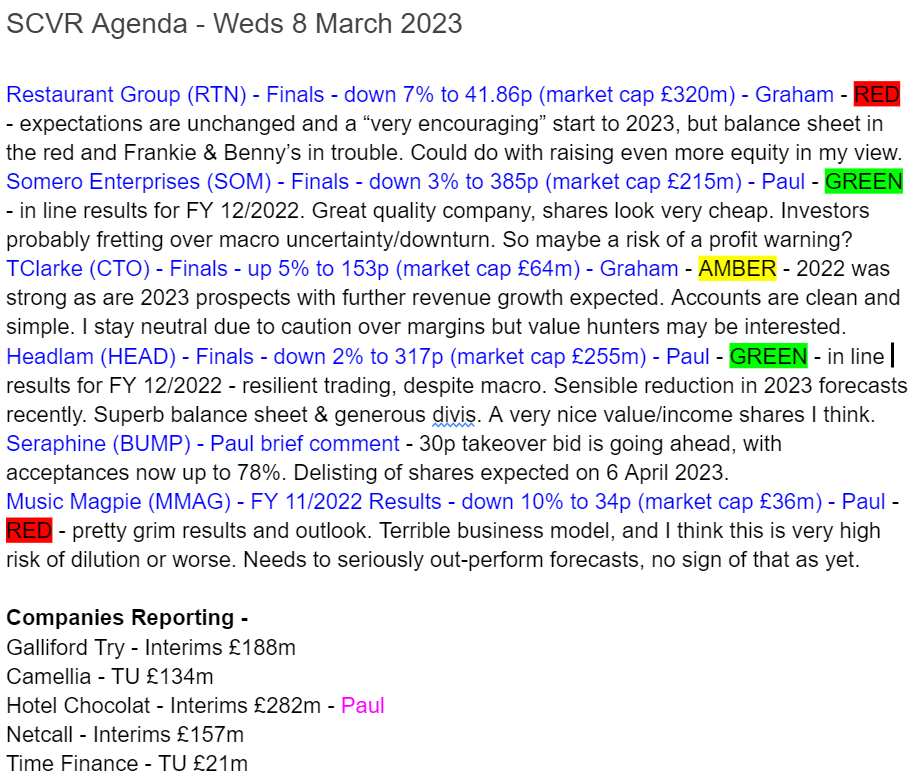
Paul’s Section:
Somero Enterprises (LON:SOM)
385p (down 3%)
Market cap £215m
Somero sells & supports laser-guided concrete screeding machines, to lay perfectly flat floors, for use mainly in warehouses.
Finncap says these results are in line with expectations.
Revenue of $133.6m - matching the outstanding performance of the prior year.
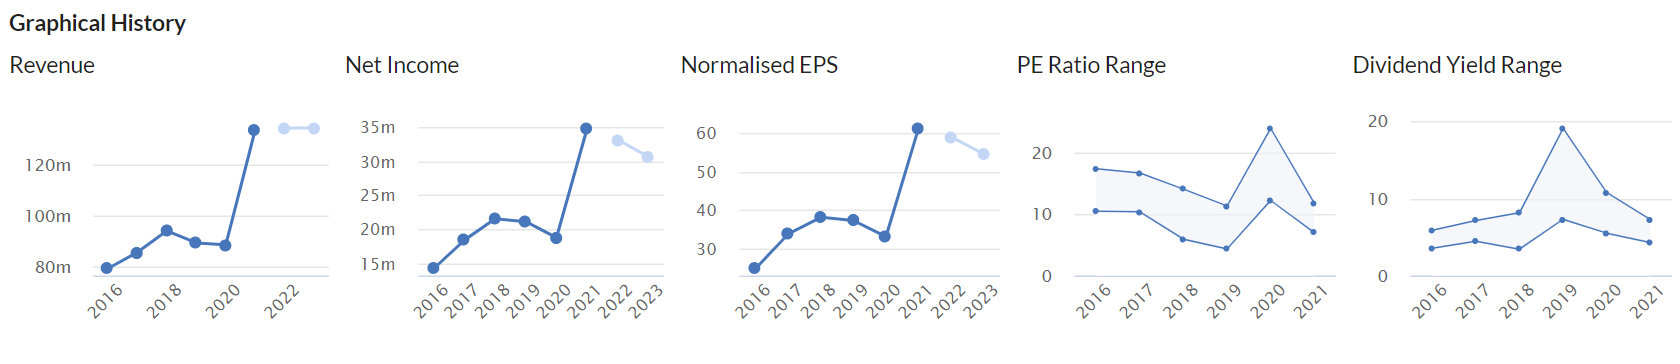
Profit before tax fell to $40.8m, down 9%, due to higher overheads (already known) - note the very high profit margin.
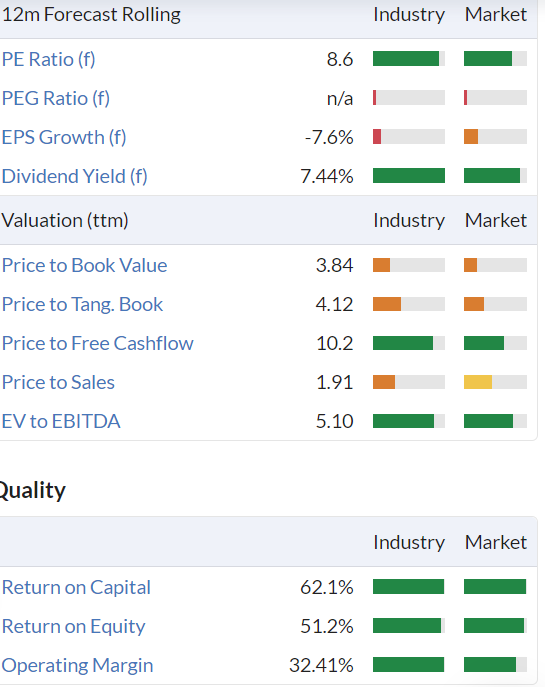
Adj diluted EPS $0.55 (down from $0.61 prior year) - converts into sterling at £1 = $1.183 to 46.5p = PER of only 8.3x which looks strikingly cheap to me, for a high quality business generating a high profit margin, and copious cashflows.
Dividends - are generous, with the ordinary divi $0.2778, and a supplemental divi of $0.077. The StockReport is showing a forecast yield of 7.4%, which is clearly very attractive.
Buybacks have also been done, reducing the share count slightly.
Outlook - there’s more detail, but this is the key part -
…With all factors considered, 2023 revenues are expected to be comparable with 2022, and with targeted added resources 2023 EBITDA is expected to be down modestly from 2022, and with 2023 working capital investment expected to remain elevated, year-end 2023 cash is expected to be at a comparable level to year-end 2022.
It also mentions shortages of concrete in the USA, which doesn’t help for a company selling concrete screeding machines, but is probably only temporary.
Forecast - many thanks to Finncap for updating us. It has trimmed its FY 12/2023 EPS forecast down by 5%, to $0.532, which converts to 45p = PER of 8.6x which looks strikingly cheap, if forecast numbers are achieved. I think Somero has a good track record of usually being quite conservative in its outlook comments.
My opinion - another excellent set of numbers, from this high quality company.
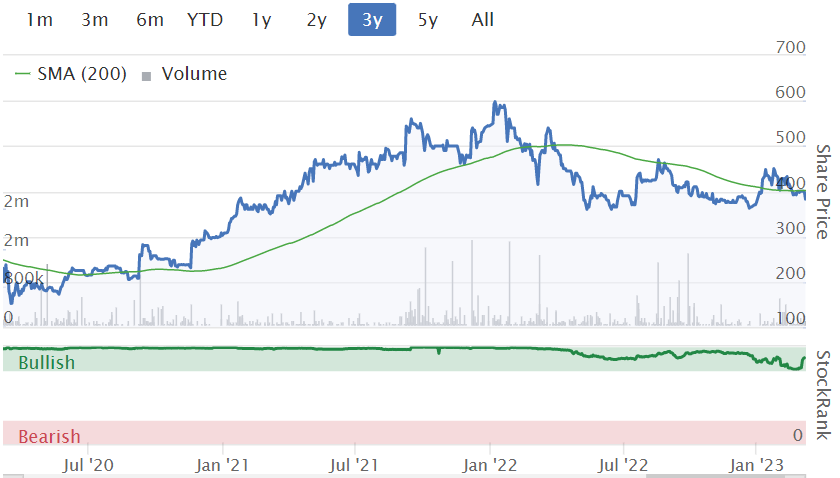
The main downside risk is that we might have seen peak earnings, and the future may see lower profits, and maybe even a profit warning if demand slips as 2023 progresses. The worry is obviously that higher interest rates in the US especially (Somero’s main market) could cause a recession in construction. My argument would be that a PER of 8.6x is already pricing in a significant fall in earnings, but that probably wouldn’t stop the share price falling lower still, if a profit warning were issued. That could also trigger a reduction in divis.
Overall, I don’t know what the future holds, but I can see strikingly good value in this share, if current forecasts are met. Therefore it has to be a thumbs up from me, but it’s up to you to decide whether you want to play it safe, watching from the sidelines, depending on what your macro view is. Or whether you’re happy to just hold this share long-term, and collect in the generous divis whilst you wait to see how performance pans out. That involves accepting the risk of a possible profit warning, as with all shares. Other announcements this week do seem to be pointing towards a slowdown in activity in some sectors.
Lots of attractive numbers here, and look at the quality scores below!
.
Headlam (LON:HEAD)
317p (down 2%)
Market cap £255m
Headlam (LSE: HEAD), the UK's leading floorcoverings distributor, today announces its Final Results for the year ended 31 December 2022 (the 'Period'), and an update on current trading.
Many achievements despite very challenging industry headwinds in the year
I’m impressed with the profit figures in the table below, given that macro conditions have been quite tough in 2022, with inflation surging, and the cost of living challenges, especially in the final quarter (mini budget chaos).
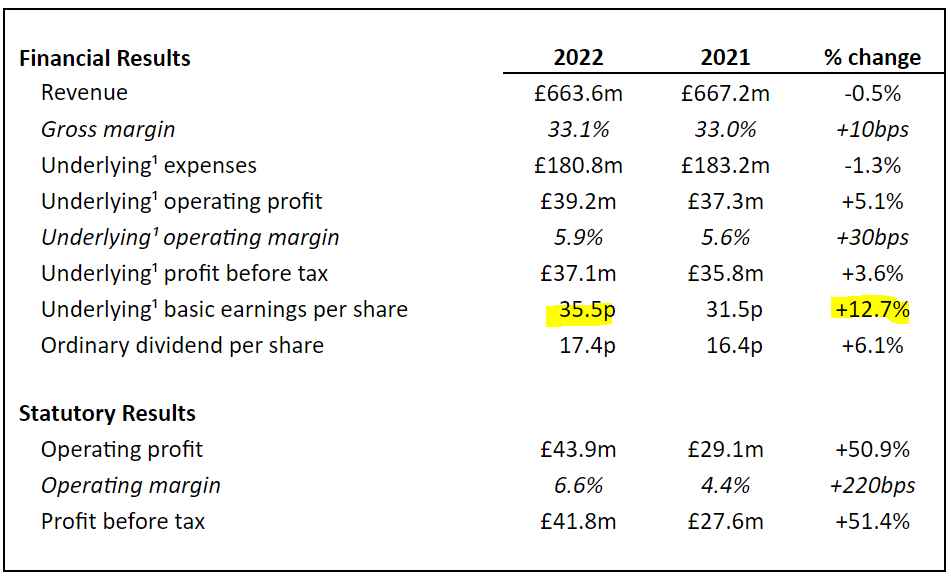
Note that the adjustments actually reduce underlying profit, which is unusual, as they’re usually stripping out costs and boosting profits. This is explained in the commentary as being a net credit from an insurance claim following a fire.
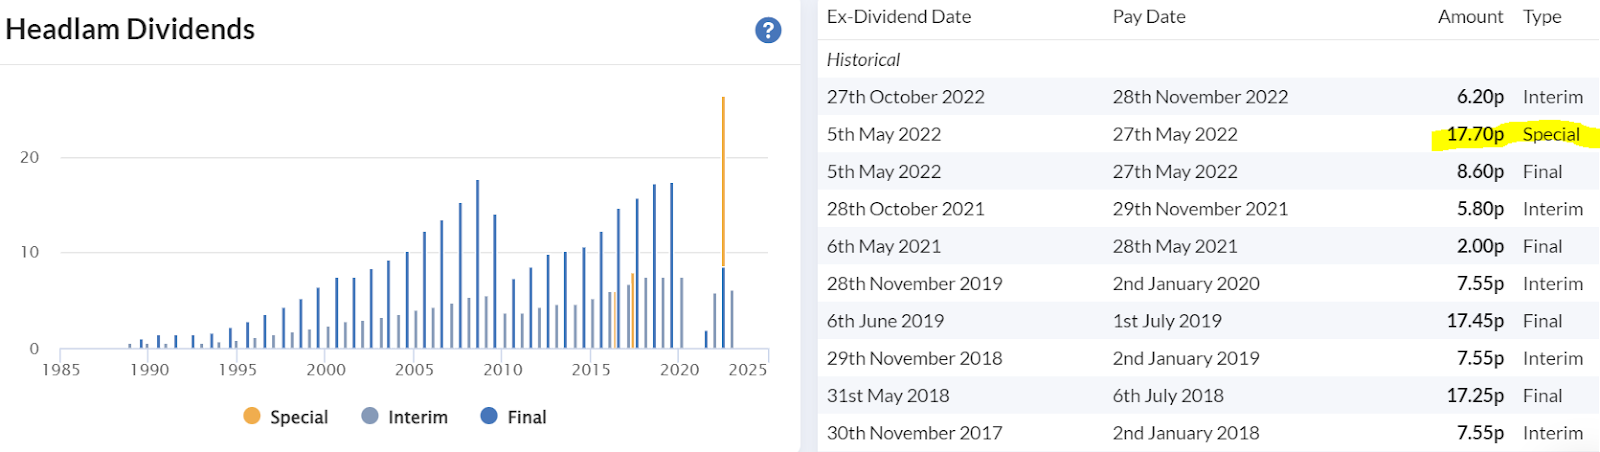
Dividends - this is a nicely cash generative business most of the time. Note below the interesting pattern of rising divis, interrupted by each financial crisis (in 2008, and then again from the 2020 pandemic).
I’ve also highlighted the generous 17.7p special dividend, paid in May 2022 -
So this share is mainly of interest to value/income investors, and I’ve always liked it for that reason. Also the balance sheet is lovely, with lots of freehold property assets, and little to no debt most of the time.
It’s a simple business, distributing carpets & similar, with obvious attractions for smaller carpet retailers effectively using it as an outsourced warehouse, to give them a wide range of products that they couldn’t possibly store themselves. Plus buying power from the considerable scale that HEAD benefits from.
HEAD is the UK market leader, although there is a fast-growing competitor Likewise (LON:LIKE) run by HEAD’s former CEO. I am a bit worried that LIKE could curtail HEAD’s further growth, by taking market share, and maybe eroding margins too. I had a chat with LIKE’s CEO recently, and it seems a credible competitor.
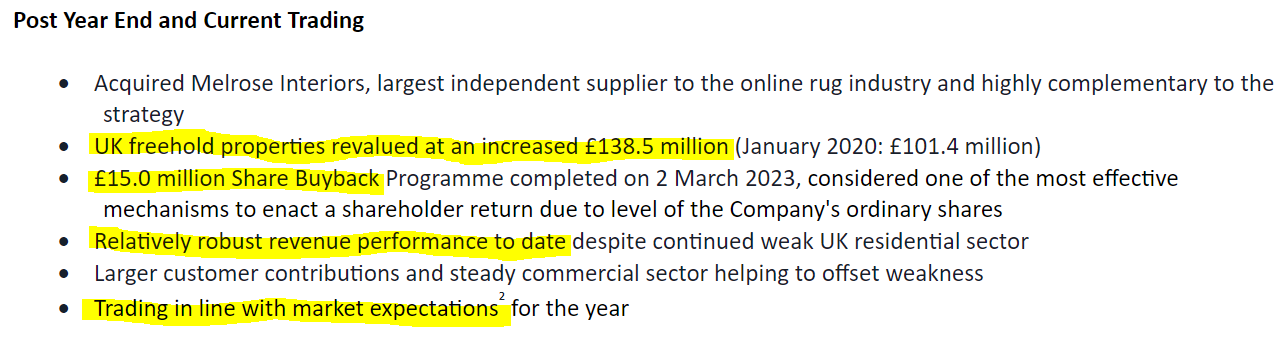
Outlook/current trading sounds OK, and I particularly like the big freehold property asset backing here -
²Company-compiled consensus market expectations for revenue and underlying profit before tax, on a mean basis, are available on the Company's website at www.headlam.com.
Balance sheet - looks fantastic, with over £200m NTAV, so a double tick in this box! This supports most of the market cap, excellent downside protection for investors, and this means that solvency or dilution should not ever be problems.
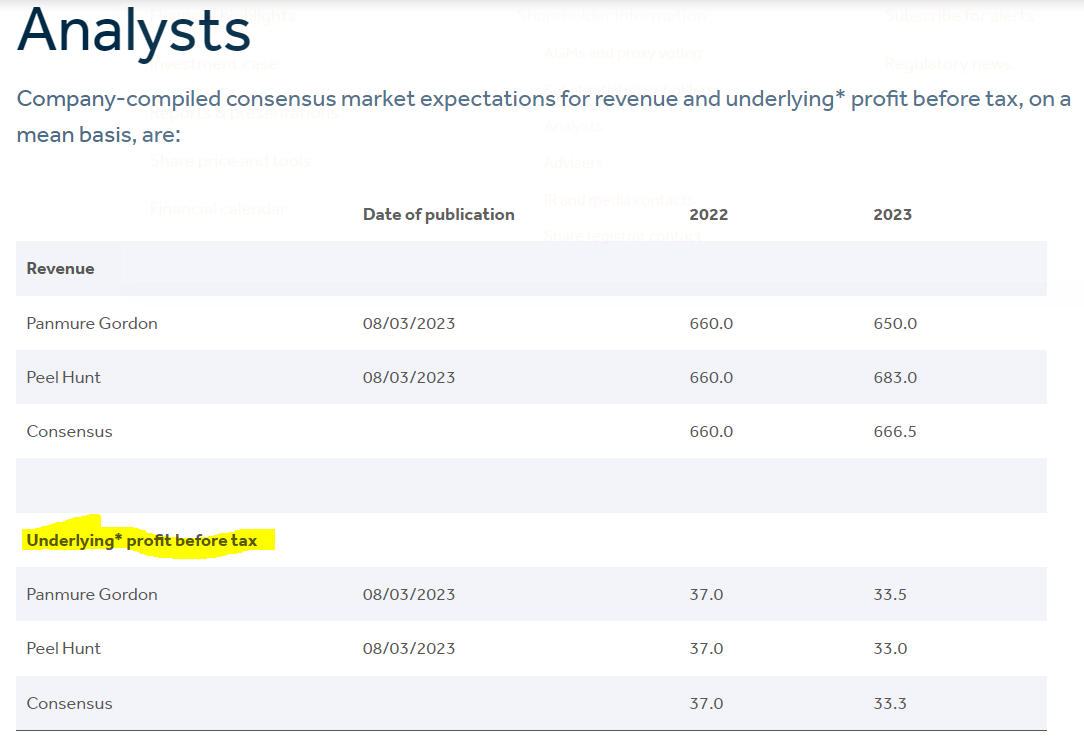
Broker forecasts - annoyingly, there’s nothing available to me. This really does need to be addressed by the company, as it’s an obvious oversight.
Although to be fair, this page on HEAD’s website is helpful to private investors -
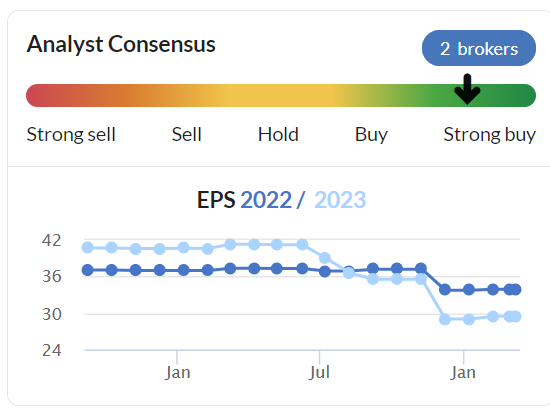
Also, the Stockopedia broker forecasts graph is (as always) tremendously useful, and it shows a recent moderation in forecasts, which I like - as this means a lower target, hence less risk of a profit warning in what is likely to be another challenging macro year in 2023 -
Valuation - how should we value HEAD shares? That’s part art, part science! Personally I would use a PER of say 10-12 times, and 2023 forecast EPS of about 30p. So I arrive at 300-360p range for this share, which is on a pretty prudent basis, and ignores future upside from a recovering economy.
At 317p per share, the share price is near the bottom end of my price range, which indicates to me that this share is attractively good value, but not amazingly cheap (as it was last autumn).
My opinion - it’s a thumbs up from me. This is a nice business, with attractively cheap shares in my opinion. Not madly exciting, but it should continue to provide a decent income via a generous dividend yield.
To summarise -
Bull points
- Decent 2022 performance despite macro headwinds.
- Fantastic balance sheet, almost fully supporting the market cap with NTAV
- Could attract a financial buyer possibly?
- Good self-help measures in recent years, to make it more efficient.
- Generous divis/buybacks (forecast yield c.5.6%) - good for income seekers.
- Has demonstrated resilience in recent years, and pricing power (passing on cost increases).
- Modest valuation.
Bear points
- Competitive threat from fast-growing Likewise (LON:LIKE)
- Continuing cost pressures, eg 6% staff pay rise, and energy cost price fix expiring.
- General macro pressure might suppress demand, possibly?
If I've missed anything from those lists, then post a comment below! Thanks.
Musicmagpie (LON:MMAG)
34p (down 10%)
Market cap £36m
musicMagpie, a circular economy pioneer specialising in refurbished consumer technology and disc media in both the UK and US, announces its audited full year results for the year ended 30 November 2022 ("FY22").
I’ve previously been very sceptical about this share, and perplexed as to why the shares have more than 4-bagged from autumn’s 10p lows. Maybe there was something good going on behind the scenes?
Today’s poor figures reinforce my scepticism. A few key numbers -
EBITDA almost halved to £6.5m. But EBITDA is meaningless here, since the company is a heavy capitaliser of internal costs, with £4.6m development spend capitalised in the year.
Loss before tax of £(1.5)m.
Heavy tax charge (when it should be a credit), which is mainly due to tax on excessively generous previous share options.
Debt rising, due to a horrible business model of buying up old phones, paying for them, then renting them out. So it requires cash spending up-front, which is being funded by bank debt (very unusual to see a bank prepared to lend like this).
Notes to the accounts show that quite a lot of customers default, which then results in handsets being written off. Hardly surprising, after all this must be a service for people who can’t get hold of a phone any other way.
Debt rising, as more bank debt is drawn down to fund the purchases of more mobile phones, and the legacy business is not generating a return.
Inadequate equity, NTAV is only £7m. So the bank is funding the capex, which is risky, if/when they get cold feet.
Going concern note reassures that it should remain within bank facility, and covenants, so gives itself a clean report on this.
Outlook is mostly waffle, but implies that Q1 (Dec-Feb) has been tough, but no figures provided. Short term outlook is described as “challenging”.
My opinion - this looks awful to me. It’s loss-making, and running up bank debt to buy old phones to rent out to customers who sometimes default on the agreements (and presumably keep the handset?)
There’s a weakish balance sheet, dependent on growing bank debt, no divis (or any likelihood of them), and weak outlook comments.
Overall, this strikes me as an accident waiting to happen, and I wouldn’t touch it.
What’s the upside case? It seems to be positive talk (but no actual numbers to back this up) about the business improving due to the rental income growing. If it does manage to move into decent profitability, then there could be an investment case here, but brokers are not forecasting profitability, so holders must be hoping that MMAG will beat forecasts. Otherwise there wouldn't be any case at all to buy or hold this share, on existing forecasts.
Maybe the business will do well in future, I don’t know? It did have a good burst of profitability in the pandemic, resulting in it listing in 2021 (possibly the worst year on record for over-priced, poor quality floats?). Profits have since collapsed, and it’s now loss-making.
There’s a webinar on IMC tomorrow, so I’ll tune in to hear the positive story, as maybe I’ve missed something in the numbers that is more encouraging?
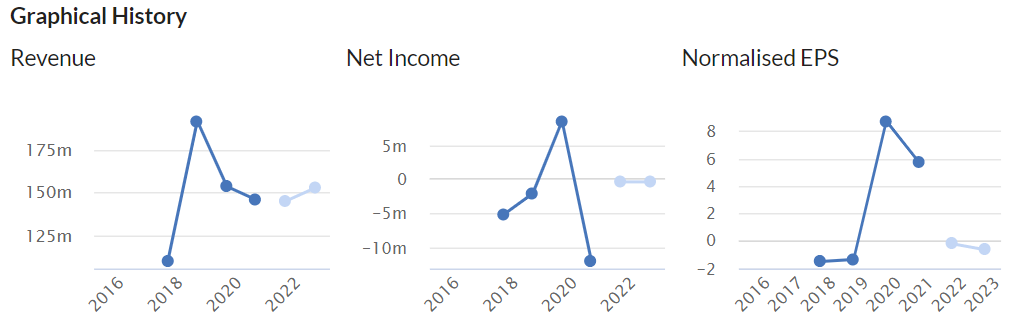
A typical chart below from a 2021 float!
Graham’s Section:
Restaurant (LON:RTN)
Share price: 41.86p
Market cap: £320m
This is the group behind Wagamama’s, Frankie & Benny’s, and a variety of other restaurants and pubs.
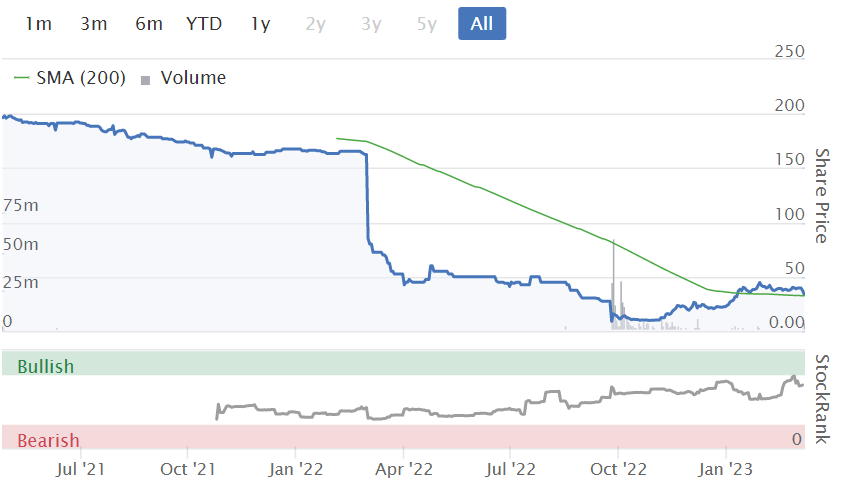
Shareholders have had a traumatic experience:

Let’s take a look at these full-year results for FY 2022, and see the outlook for 2023.
Results highlights:
Sales £883m (up from £637m)
Adjusted PBT £20m on a pre-IFRS 16 basis
The statutory unadjusted loss is £87m
Net debt (excluding leases) is £186m. Net debt including leases is £582m.
Which profit number to use? The company presents six different adjusted profit numbers, depending on which costs and expenses are included and whether or not IFRS 16 is implemented. This is before we even get into the unadjusted profit numbers.
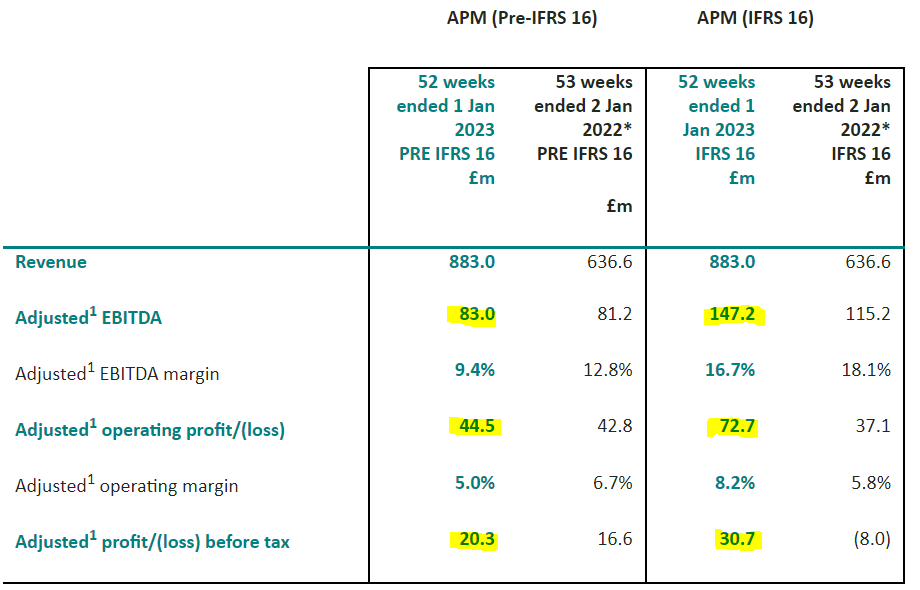
My suggestion would be to look at pre-IFRS 16 adjusted operating profit (£44.5m) or post-IFRS 16 adjusted PBT (£30.7m). Both of these numbers strike me as reasonable indicators of underlying profit.
Note that the first one is before interest costs, while the second one is after interest costs.
Then we have to find out what the adjustments are. By far the largest adjustment is a £114m impairment that writes down the values of both the company’s leases and its fixed assets. The other exceptional items, in aggregate, are of relatively little importance.
The impairment has been made necessary by lower forecast future earnings expectations, predominately in our Leisure division, due to significant inflationary and cost-of-living pressures in the near-term.
Trading performance - sales at Wagamama, pubs and concessions are all said to have outperformed their respective market benchmarks (vs 2019 comparatives).
Frankie & Benny’s, along with the other smaller restaurant chains, are included in TRG’s “Leisure” business - the one that has just seen a huge impairment.
This business saw no like-for-like sales growth in 2022, and was therefore 5% below the market:
The Leisure business is in a highly contested market segment and is the component of our portfolio most exposed to changes in wider consumer sentiment, and therefore Leisure's trading performance has been the most directly impacted by the cost-of-living pressures.
Current trading and outlook
Like-for-like sales in the Leisure business are down 4% in early 2023, compared to the same period last year. The other divisions are all doing significantly better than that:
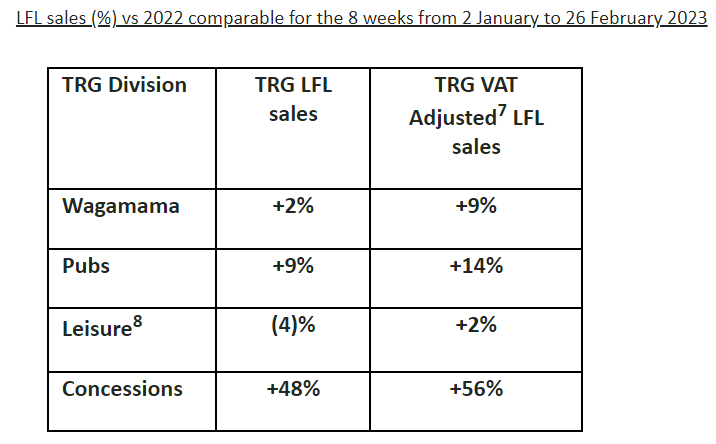
RTN says it has been “a very encouraging start to the trading year”, and they leave FY 2023 expectations unchanged.
Looking further ahead, they want to reduce net debt/EBITDA to below 1.5x within three years (it is currently 2.2x, using pre-IFRS 16 numbers).
Additionally, they are “continually reviewing our longer-term strategic options and will update shareholders as appropriate”. This could refer to anything, but my view is that they could perhaps think about raising equity.
CEO comment:
"We've delivered a strong operating performance for the year in a market which has continued to pose a number of headwinds for casual dining operators…
We have a clear plan to increase EBITDA margins over the next three years and deliver significant value for all our stakeholders."
Going concern note - the Directors say that sales would have to fall by 7.4% vs. their base case scenario before there would be a risk of breaching loan covenants, and that this assumes no mitigating actions taken to prevent the covenant breach.
The decline in sales would have to be double that amount, in order to cause a covenant breach that the company could not avoid through mitigating actions.
Balance sheet - the company officially has equity of £380m, but this includes intangible assets of £604m. Therefore, net tangible assets are negative £224m.
This figure includes the impact of leases, which are strongly negative after their “right-of-use” assets were written down.
Strip out the impact of leases on the balance sheet and we have net tangible assets of negative £66m.
Checking the footnotes, I see that bank interest paid in 2022 was £21m.
My view
I think this company should probably think about raising more equity.
It will be a bitter pill to swallow for shareholders, after already going through two equity raises (in 2020 and 2021) for the purpose of improving the balance sheet.
However, I suspect that the balance sheet still needs fixing.
The company has benefited from some interest rate caps but the interest costs are still very significant relative to their profitability, and I fear that trading is only going to become more difficult unless there is a quick turnaround for the consumer.
So I’m going to have to take a negative stance on these shares, primarily due to the horrible balance sheet and the lack of obvious competitive advantages (particularly for the Leisure business).
I also note the varied career history of Restaurant Group’s current CEO and I wonder how long it will be until he moves on to his next high-paid position.
Tclarke (LON:CTO)
Share price: 153p (+5%)
Market cap: £67m
I took a dim view of this company’s November trading statement, which was a serious profit warning despite the positive language used.
The January trading statement was again extremely positive, but the overall change to EPS estimates at the company’s broker was slightly negative.
Today, the company publishes full-year results for 2022 and the 2023 earnings estimates are unchanged.
Highlights from the results:
Revenue +30% to £426m
Operating profit +31% to £11.5m
PBT +32% to £10.3m
After battling through the complications at RTN, it’s a relief to find a company whose results are simple: no adjustments, and no “alternative” presentations of profits. Lovely!
This is a building services / engineering group. It's a sector which I have often described as being accident-prone (from a financial point of view) and so I look for companies in the sector to have a net cash position. TClarke has this with net cash at year-end of £7.5m.
It also discloses average month end cash of £2.6m, a much lower number but at least it’s an improvement on last year (2021: average month end cash of negative £2.9m).
I also think that we can give a small-cap company some credit for even disclosing this number, when many companies don’t bother. Usually, investors are left in the dark as to whether or not the year-end cash figure is unusual or has been window-dressed!
Data centres - TClarke has a particular emphasis on growing its work relating to data centres, and has seen data centre revenues grow from £39m in 2021 to £129m in 2022. This alone can account for the majority of net revenue growth during the year.
Forward order book - £555m, up 4% versus the prior year. It does look like the pace of revenue growth is going to slow down, which is inevitable if the forward order book isn’t growing very fast.
2023 revenues are expected to come in at £500m, which would be an important milestone and another record-breaking year for the group, but also a more moderate pace of growth (17%) compared to 2022 (30%).
CEO comment:
The Group is in fantastic shape. We have an excellent order book of high quality projects across a wide range of sectors. The business is supported by our strong balance sheet, which continues to grow, with net assets increasing by 46% compared with 2021.
Operating profit margin is 2.7%, a decent result for TClarke and a reminder of the incredibly low margins this industry generates.
The company’s goal is to increase this crucial metric further to 3%, and it appears that the CEO has an appropriate focus on margins over winning higher revenues at any cost:
Our order book has been replenished whilst maintaining our disciplined and selective bidding approach to opportunities, which is even more crucial in times of economic uncertainty; this business is not driven by winning projects that do not have the opportunity to return an acceptable margin.
I also note that 90% of projects are with repeat clients and/or principal contractors: a nice sign of customer satisfaction and loyalty.
Outlook is ambitious for the medium-term:
We see the period beyond 2023 as an opportunity to lay the foundations for an even stronger TClarke with the business ideally positioned and focused on delivering the most high tech and engineering rich projects for our clients, whilst building our existing balance sheet strength, enabling all stake holders to share in the continuing success of TClarke.
My view
There is a lot to like about this:
Net cash position
Focused on further improving its operating margin
Growth is organic
Excellent revenue growth
No “funny business” in the accounts.
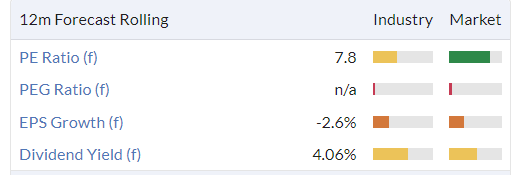
Cheap - see below.
So what’s not to like?
Personally, I still think that the manner in which November’s profit warning was announced was questionable.
Apart from that, it also comes down to how comfortable you are investing in this sector, and probably also your view on the industries served by TClarke: will data centres provide a reliable long-term revenue stream, or will the company need to find other sources of revenue growth before too long?
I’m tempted to give it the green light but I’m personally very wary of this sector, as I find that small changes in expenses can have huge effects on bottom line profits. So I’ll stay neutral. But if you like this sector, then you may like TClarke.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Headlam (LON:HEAD) full year 2022 results presentation & Q&A given this morning video & podcast. A great presentation by Chris Payne, Chief Executive, who presents from their Coleshill location. The questions are from investors who attended the webinar.
hi all
I have been getting increasingly irritated by the disappearing tags on daily SCVR's. I know Rusty also shares my frustration.
I have therefore sent a message to Stocko via the 'green blob' (my first one!). For your information I have copied my message below.
There is a problem with Paul & Graham's tags on company updates dropping off after being applied. This makes it almost impossible to find a comment at a later date as there is no easy way to locate historical SCVR's (even if you had the time and knew the date to scroll back to). This is a most irritating problem and is now almost a daily occurence. Subscribers are regularly pointing out missing tags to Paul. He must be fed up with this and it's not of his causing. Surely Stocko IT can sort this out with a fix? It needs fixing now, please.
When I receive a reply I'll post it on here.
Snazzy
Hello Paul/Graham, I noticed the tags apart from Musicmagpie (LON:MMAG) have disappeared. Can't Stocko fix this?
What a good thing you spotted the missing tags, really helpful, thank you Rusty2!
I've put the tags back in again just now.
Best wishes, Paul.
I think they recycle lots of things and the excitement is that they have a recycling deal with Wallmart.
Musicmagpie (LON:MMAG) I know people who buy used cds, some charity shops are virtually giving them away, 10 cds for £1, I have seen. Postage has gone up quite a lot recently. I used to buy from Musicmagpie (LON:MMAG) when cds were 1p plus postage but not anymore. They used to be popular seller on Amazon.
Also many people are streaming now, so don't buy cds anymore. The future does not look that bright for that part of business.
I must be a ludite. I've just bought a cd/dvd player. I've even got a sony Walkman floating around. Bought tax free while serving in Germany.
Thank you for your balanced observations on TClarke Graham. I don't particularly like the sector but imo the company is undervalued.
I’ve been looking at this one recently and have become more convinced of its attractiveness. Paul always dismisses the name on the basis of valuation. He’s thoughtfully endeavouring to protect his readership from excesses - like WAND ;-) . Yet he does so without reference to valuations across its sub-sector of ingredients, flavours and fragrances.
In defence of Paul and Graham, they can only compare valuation against other possible Small Cap investments. In which case, relative valuation within a particular industry is completely irrelevant. Each company should be judged on its own merits only and we should not expect them to be experts in sectors they are not familiar with. No-one has to have exposure to the flavour and fragrance industry.
Here, the products all being an essential, but largely inexpensive portion of a customer’s own products, revenues are largely predictable, on a par with traditional consumer staples, and more stable. However, unlike the staples businesses, which tend to be bond proxies, ingredients companies are more growthy, leading to high valuations across the board. Depending on your choice of comparison and preferred valuation measure, Treatt is up to a third cheaper than its counterparts, it offers better growth prospects, has excellent ESG credentials and, priced at only GBP335m, is an obvious M&A target.
One of my own preferred valuation measures is FCF yield, and it would be nice to see Treatt generating some. I have a pathological dislike of companies where earnings do not convert into Free Cash flow.
BTW the company is in Bury St.Edmunds, which is in Suffolk, not Cambs.
All the best, Si
In defence of Paul and Graham, they can only compare valuation against other possible Small Cap investments. In which case, relative valuation within a particular industry is completely irrelevant.
I want to be clear that my comment was not intended as a criticism of Paul. Rather, the intention was to encourage forum members to look beyond the name's overly hasty damnation as "expensive". And I think you'll find Paul and Graham habitually adjust for sector in valuing a carpet distributor as opposed to a software business. Let's do the same for an ingredients business.
One of my own preferred valuation measures is FCF yield, and it would be nice to see Treatt generating some
I have to agree. Brand new business operations on the scale realised in Bury do not come cheap but the benefit of the diversion of cash flow to capital is that debt is very low and still much lower than competitors. Forecasts anticipate progress but I would not blame anyone for waiting to see the evidence. I do think H1 is maybe too soon.
BTW the company is in Bury St.Edmunds, which is in Suffolk, not Cambs.
You're quite correct. I'm guilty of attaching the C-word to all sorts of locations in that vicinity as my son is moving there post-studies to marry his sweetheart, who always calls everywhere "Cambridge" despite actually living in Norfolk and moving herself to a job in Bury St E.
I have to agree. Brand new business operations on the scale realised in Bury do not come cheap but the benefit of the diversion of cash flow to capital is that debt is very low and still much lower than competitors. Forecasts anticipate progress but I would not blame anyone for waiting to see the evidence. I do think H1 is maybe too soon.
FWIW I held Treatt (LON:TET) until they mentioned they were going to build a new facility and move all operations to a new site back in 2017. Too much of a business risk for me. As such, I can't say the lack of free cashflow and the healthy net cash position (at the time) turning into a net debt position now has surprised me. These things always take longer and end up costing more than planned, and of course, a pandemic in the middle of the big move has not helped. It's a company I still follow, but to be honest I've never been happy with the relatively poor gross margin (the kind of margin I'd associate with a distributor rather than a manufacturer) which is not generally a sign of a high quality business with pricing power in my eyes.
All the best, Si
Good to have the thoughts of others. Thanks.
You're welcome, JASVFS!
Treatt (LON:TET)
I’ve been looking at this one recently and have become more convinced of its attractiveness. Paul always dismisses the name on the basis of valuation. He’s thoughtfully endeavouring to protect his readership from excesses - like WAND ;-) . Yet he does so without reference to valuations across its sub-sector of ingredients, flavours and fragrances. Here, the products all being an essential, but largely inexpensive portion of a customer’s own products, revenues are largely predictable, on a par with traditional consumer staples, and more stable. However, unlike the staples businesses, which tend to be bond proxies, ingredients companies are more growthy, leading to high valuations across the board. Depending on your choice of comparison and preferred valuation measure, Treatt is up to a third cheaper than its counterparts, it offers better growth prospects, has excellent ESG credentials and, priced at only GBP335m, is an obvious M&A target.
And a further point, accusations have emerged in Switzerland this morning of a fragrances pricing cartel involving all the big players, which comparison adds gloss to the investment case for Treatt. If the key thesis for Treatt’s acceleration is the extra capacity at its new facility in Cambridgeshire, then the thought that incumbents have been fleecing customers could send new customers its way.
As ever, potential success comes down to execution, but I feel a price in the range 500p - 550p serves to reduce that risk substantially.
Is Treatt (LON:TET) not big enough already in the fragrances market to be potentially part of that cartel? :)
Is Treatt (LON:TET) not big enough already in the fragrances market to be potentially part of that cartel? :)
It is not named in the list of firms, which are the big 4 of Symrise, Givaudan, IFF and Firmenich, all 50 - 100 times the size. Of course it is a supplier to some of them.
Is Treatt (LON:TET) not big enough already in the fragrances market to be potentially part of that cartel? :)
Apparently not. The companies named are a minimum thirty times bigger than Treatt. It's a huge market, they're a tiny player.
COMCO confirmedExternal link on Wednesday that dawn raids had been conducted at various locations in consultation with the European Commission, the US Department of Justice Antitrust Division and the UK Competition and Markets Authority.
Comco named Givaudan, Firmenich International, International Flavors & Fragrances and Symrise in the fragrances cartel probe.
https://www.swissinfo.ch/eng/s...
timarr
Held Treatt previously but sold as valuation didn't justify the growth and would have thought idea of breaking up a cartel is for lower prices generally.
Re Treatt (LON:TET) in 2019 they also completed an expansion in the US that was x4 "Others" and x2 "Citrus" capacity ie a really big increase. Together with the new UK base, these really were once in a generation factory upgrades which increased capacity, capability and also reduced their cost to make.
On the cartel issue, I used to be MD of a small soft drinks company. The ingredients they make are typically so deeply embedded in formula /manufacturing processes and critical to taste that they are very hard to shift - I think any action is more likely to lead to the big 4's customers demanding better pricing rather than to switching except over the medium to long term.
However, Treatt are so small that this might be a lever to get even consideration by some more players and they could double without the big guys noticing. Their expertise is in citrus and tea but they can do most things.
At some point, IMHO this business is likely to worth a lot more. I don't hold but wish I did.
Paul always dismisses the name (Treatt) on the basis of valuation. He’s thoughtfully endeavouring to protect his readership from excesses - like WAND ;-)
Never was a truer word said in jest - though I did not expect to be so prescient so soon. I hope most managed to avoid this fraud. I found the CEO far too bullish and I’d be surprised if he did not know about the cooked numbers.
hi Paul
All the tags have dropped off again (except for Musicmagpie (LON:MMAG) which you recently added).
Snazzy
Tanks for flagging, Snazzytime. I've put the tags back in now.
Any thoughts on TT Electronics finals? Look okay to me but were expected.
There's an interesting interview with Richard Stavely of Rockwood Strategic (LON:RKW) on Vox https://www.voxmarkets.co.uk/a... He's a small cap investor who owns a number of stocks that are often discussed on SCVR and he beat the market spectacularly last year. His views on the future are worth listening to. There's a guide to where in the interview he talks about each company and topic.
Do you know why he is claiming owning 20% of Pressure Technologies (LON:PRES) when it doesn't show that on Stockopedia? Does it have something to do with Christopher Mills?
Anyway, thanks for the link.
Pressure Technologies (LON:PRES)
Funnymoney - Harwood is the fund manager for Rockwood and if you look at the person Paul H talked to on Linkedin you will find:
Thanks
Super switched on posh bloke that Richard Staveley and Christopher Mills is even posher.
I follow them very closely.
Was looking at Pressure tech past months both as an investment and also physically out the window as they are bang opposite us .
They are sat on a cracking bit of real estate right by Meadowhall, very large site.
Plus the FD of forgemasters who is going there is very well thought of.
Just feels like things are happening and it is very cheap now with some strong investors holding them to account so Ill follow Rockwood .
Looks a very good acquisition for Avingtrans .
Hi planetX, Avingtrans (LON:AVG) from zero to hero, Mr Market capricious as ever. Plus ca change
On the matter of Pressure Technologies (LON:PRES) I have taken an opening position for reasons covered in my recent post on March 6th. See link below if you are interested. However Richard Staveley covers the investment case much more adeptly. Prelims soon, possibly tomorrow.
As you say it would be a good fit for Avingtrans (LON:AVG) , but Messrs McQuillan and King won't overpay and Christopher Harwood will want top dollar I suspect, but never say never.
I am currently trying to decide what to do with my holding in Somero Enterprises (LON:SOM). A good company but facing headwinds and currently out of favour. Any thoughts?
Stockopedia | Boon's Fund Recap – February 2023 - Which is Mispriced, Bonds or Shares? | By Boon
JONNO
Im trimming Somero from full position to half a position . Sold a lot today and took the pain. The loss offsets the CGT on crestchic .
I took half out of the market for new business just helping.
And put half in Pressure tech and half back into LDG
LDG looks good, I jumped in and out in January before the Simon Thompson tip , but fortunately put that to good use ons Avingtrans which has gone supercharged.
LDG own a chink of Finsbury food and and chunk of Alliance Pharma and have a mountain of cash almost market cap. With buybacks looks a bit of a no brainer.
Keep increasing on both Croma and Titon which are really too small for most people, think Titon is way undervalued and has understated real estate that is actually worth 7 million alone .
Croma are selling off their security division which should spit out cash plus they have a good business full stop
Other than that I topped up on Holders the other day and apparently according to ADVN forum Im about Ito launch a bid for it .
All these three microchips are very high risk so be careful if you like to sleep well.
Im happy to hold on Equals, Wynnstay, Vertu, Colefax, Hargreaves, Sureserve, Vertu.
Also like and am holding non AIM shares J Smart, Bloomsbury, Bank Georgia, Georgia Capital and National World though National world im waiting for update.
J Smart is a no brainer but illiquid .
Thanks planetX
I will decide on Somero Enterprises (LON:SOM) tomorrow, but selling 50% seems a plan. I shall also look at Logistics Development (LON:LDG) and talking of Simon Thompson bargain shares, I also like CML Microsystems (LON:CML) although no longer such a bargain.
I also hold Wynnstay (LON:WYN) Vertu Motors (LON:VTU) Hargreaves Services (LON:HSP) and Bloomsbury Publishing (LON:BMY) . The latter two I sold having bought much lower down but have recently bought back as they have come off their highs somewhat.
Will be interesting to see how Pressure Technologies (LON:PRES) evolves. Speculation Avingtrans (LON:AVG) sells Booth Industries and acquires Pressure Technologies (LON:PRES) fantasy me thinks!
All the best.
Hi planetX
Sold 50% of Somero Enterprises (LON:SOM) for a modest loss and added a few Pressure Technologies (LON:PRES). Not sure what propelled the latter this morning, although the prelims must be any day as the AGM has been announced for 31 March.
2yr treasury almost 5%,makes a lt of stocks look unattractive at the moment.Have been selling a lot of stuff into strength .
Hi Paul, Graham,
One of my favourite companies, and one of my largest positions TT electronics (LON:TTG) reported today. If I remember correctly I think Grahams write up sometime ago caught my eye, so thank you for this one.
re: TT electronics (LON:TTG)
Hi Lefty, I didn't get around to covering this on Wednesday but it has now been covered in Thursday's report. Thank you very much for reminding me to do this one! G
Breedon (LON:BREE) not small cap, but currently listed on AIM, had ahead of expectations results this morning. It also announced its intention to move from AIM to list on the main market. (I hold).
no inheritance tax relief my main reason to hold
Musicmagpie (LON:MMAG) under pressure post results. Loss making and taken on big debt which I assume will be costly to service.
https://www.investegate.co.uk/...
Any chance of a review Paul/Graham? tia
Bakkavor (LON:BAKK) Full Year results - revenue up, profits down. Any thoughts from the wise collective?
Headlam (LON:HEAD) full year 2022 results
Despite industry headwinds, they maintained revenue, and profit improved, although the insurance claim benefited them. So far, 2023 revenue is in line.
The CEO will host a webinar at 11am today, join us for a presentation and live Q&A. Register here.
Paul or Graham. I would be interested in your thoughts on Netcall (LON:NET) as decent looking half year results and positive outlook, but not cheap. I have a small position and from first glance happy to hold.
Best wishes.
Greyster
Hi Paul, would appreciate your thoughts on Somero Enterprises (LON:SOM) final results today. I have always been green on the share however reading the results I feel it could see a moderate sell off this morning, I am starting to question my position here. Is there any growth potential there to move the share price over the next couple of years, I am not so sure.
I think they are ripe for takeover by someone who can exploit SOM's export market potential.
Somero Enterprises (LON:SOM) were in line with expectations. They had a storming 2021, so it depends what you judge these results by. To keep revenues flat on 2021 is a pretty good result compared to FY22 ($88.6m). It's on a PE of just 9.4 and a dividend yield of 6.6% (based on finnCap forecasts this morning). They're investing for growth and have had cost headwinds of 4%.
Management are fairly open and are hosting a webinar next week 15.3.23 at 4.30pm. Register here.
Hi Tamzin,
Thanks for sharing the webinar date, I will give it a watch next week as I'd like to know a bit more about how their investments are expected to impact growth. You are right about 2021, unfortunately I bought in at around 500p just before the war (typical!) so didn't reap the rewards of that great run, probably influencing my less positive view this morning. Eggbacon - fingers crossed!
Cheers,
BenHazz
Somero basically a great company with great products making good profits and plenty of cash and a possible takeover target .
That’s the good bit .
Likeky to trade sideways and slightly down as a company next few years as hard to imagine the likes of Amazon building like crazy .
I’m on a full position here and I need to find some cash in the next weeks for other stuff going on so think Somero is going to be holding that gets the haircut.
Has the story / initial investment case changed ?
Well you have to say yes, the building boom has to drop off and cost increases have to take effect so whilst it is still fairly valued , spits our cash and shares it to shareholders and is takeover target I think reduce to half position is my choice .
Why doesn't Caterpillar buy them?
As its almost certain that the US is now heading for recession - see here from Jay Powel;
The latest economic data have come in stronger than expected, which suggests that the ultimate level of interest rates is likely to be higher than previously anticipated. If the totality of the data were to indicate that faster tightening is warranted, we would be prepared to increase the pace of rate hikes.
I reckon it is very likely that one will be able to buy SOM at a lower price later this year - something I hope to do!
Jim
I'm out for a similar reason. This is likely to drift, can't see an obvious reason to buy right now
My morning smallcap tweet: Deals on wheels
Journeo (LON:JNEO) Time Finance (LON:TIME) Camellia (LON:CAM) Vanquis Banking (LON:VANQ) Somero Enterprises (LON:SOM) £AMG Ovoca Bio (LON:OVB) Galliford Try Holdings (LON:GFRD) Roquefort Therapeutics (LON:ROQ) Redx Pharma (LON:REDX)
◄Journeo (JNEO)► £1m software and services contract from Transport for Wales. c. £0.5m will lie in this FY. [SP=140 Cap=23m]
◄Time Finance (TIME)► guides FY-May pretax £3.6m+, ahead of market expectation of £3.2m. Q3 pretax was up 172%. [SP=22.44 Cap=21m]
◄Camellia (CAM)► guides FY-Dec rev-cont c.£294m, adj pretax-cont only 10% down. Previous guidance was 50-55% down. CItes favourable backdated pay rise, higher net sales price, cost control. [SP=4800 Cap=133m]
◄Vanquis Banking (VANQ)► PRA cuts Total Capital Requirement to 11.9% from 18.3%.This will support the Group's focus on organic loan book growth. [SP=220.59 Cap=564m]
◄Somero (SOM)► FY-Dec in line. Guides FY23 rev flat, EBITDA down modestly due to "investments to add product development, global sales and customer support resources". [SP=402.5 Cap=225m]. I hold.
◄Amigo (AMG)► GM stmt: no material change in the trading activity for the run-off of the legacy loan book. Conversion rate for new brand is improving but remains challenging. Amigo has yet to secure commitments for £45m fundraise required and the situation remains extremely challenging. [SP=NA Cap=NA]
◄Ovoca Bio (OVB)► sells Russian assets for c.£1m. [SP=5.29 Cap=4m]
◄Galliford Try (GFRD)► H1-Dec. Guides FY adj pretax at the upper end of forecasts (£20.3m to £23.3m).. [SP=174 Cap=188m]. I hold.
◄Roquefort Therapeutics (ROQ)► develops new novel platform of anti-cancer mRNA therapeutics. Co working towards demonstrating efficacy of the mRNA therapeutics in specific cancer targets. [SP=7.75 Cap=10m]
◄Redx Pharma (REDX)► Phase 2 trial data not sufficient to support further development of RXC004 as a monotherapy in advanced biliary tract cancer patients. [SP=40.77 Cap=137m]
Not sure if Time Finance (LON:TIME) is too small for SVCR but lovely 'ahead' update today. PBT up 172%, revenue up 28%
I'll second that request. Time Finance (LON:TIME) Time looks like it's coming good after a stumble (says long suffering holder!).
There's a new note from Cenkos now out, and available on Research Tree.
It looks like management like to guide conservatively at Time Finance (LON:TIME) hence why there is a second profit upgrade in just a few months. It seems potentially likely that FY earnings will beat their current forecasts.
H1 PBT = £2m
9m PBT = £3m (so they have continued their quarterly profit momentum, +£1m in Q3)
One would say, given the increased unearned income stream they have already declared at HY and now at Q3, that Q4 should be sequentially more revenue than Q3, and therefore more profits.
I'm quietly optimistic that FY could come in at a minimum of £4m PBT, possibly as high as £4.25m, compared to the £3.6m that management are guiding today.
That would give an EPS of 3.2p to 3.4p this FY May23. Current share price is 27p to buy at the moment. Given the growth prospects here, markets will probably settle at around 10-12x historical PE after year end, which means 32p to 40p potential target SP. A nice 18% to 48% potential gain, within 6 months.
And don't forget - nicely tangible asset backed too so very little downside risk! NTAV is like 30p+ per share.
(I hold in the Boon Fund)
T Clarke prelims look good, profit up, revenue up, eps up, net cash up, div up. CEO Mark Lawrence claims the company is in fantastic shape. We hold and I'm tempted to add, if you have time Paul and Graham your comments would be appreciated.
Tclarke (LON:CTO)
T Clarke have always struck me as a well led good quality company, despite the low profit margin which always gets negative comment from Paul or Graham. My understanding of construction companies (although being honest it relates more to civils) is that they turn over their capital more times in a year than most other industries, which perhaps is a partial explanation of the low margin. My feeling is that the spectacular failures in construction are generally the result of management hubris, with spectacular examples like Laing, who were a brilliant company before their downfall, Costain, etc, but so far I don't see signs of this in Clarke.
One of the things which really impressed me with Clarke was the period about ten years ago, when Clarke struggled for a couple of years with minimal profits. They found a fraud of about 2 million, iirc, and pursued the culprit to get the cash back. But a year or so later, Balfour declared vast hidden losses (in the tens of millions iirc) incurred by their electrical subsidiary in London over those same bad years, when they would have been in direct, and no doubt fierce competition, with Clarke in Clarke's back yard. Since then Clarke has become less London centric, I believe, perhaps as a consequence.
I sold out of Tclarke (LON:CTO) a few years ago after comparing board remuneration with shareholder returns for a number of smaller companies. In 2018, CTO made net profit of £6.2m (or £6.4m adjusted), paid the board £2.8m, and declared £1.7m of dividends. In contrast, UP Global Sourcing Holdings (LON:UPGS) in 2018 made net profit of £4.28m, had a total board cost of £1m, and paid out £3.55m in dividends. CTO was consistently among the worst companies in my spreadsheet for board remuneration to shareholder return ratio. Additionally, IIRC the CTO board appeared to buy or hold very few shares with their own money.
The latest annual report is 2021, they paid around £2.85m in board remuneration, and around £2.3m in dividends. They also have a DB pension scheme, and are paying £1.2m p.a. in deficit recovery payments for the next 8 years or so. Very unusually, the DB scheme is not closed to further accrual, although new accrual is on a career average rather than final salary basis, and I'm fairly sure from a past company presentation that it's closed to new entrants, although I can't find that stated in the 2021 AR.
They seem like a very nice, well-run company. I'm sure they're great to work for. I just don't think shareholder interests rank highly enough to want to buy them unless they get really cheap again.
Morning Paul. Just to say your Podcast is fantastic. Many thanks for your effort much appreciated. Any research website other than ResearchTree?
Agree. Love it.
Agree - a highlight of the weekend, the take-stock
Agreed. Byyyee!