Small Cap Value Report (Wed 8 May 2024) - MBT, LST, OCTP, APH, JDW, BOO

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
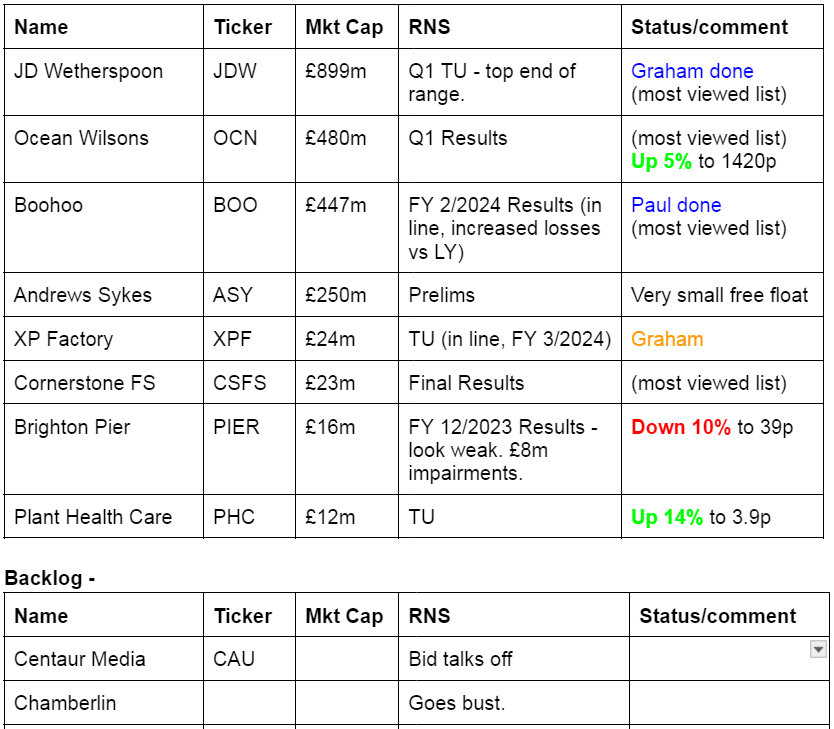
Other mid-morning movers (with news)
Mobile Tornado (LON:MBT) - up 42% to 1.35p (£6m) - Contract win in M.East - Paul - RED
Says that it has won a competitive tender process for specialist communications services. Reckons its software is better than the competition. No indications given as to the scale of this contract.
“This contract, in a key target market, is a testament to the changes we made early last year and the Board looks forward to increasing sales momentum as 2024 develops."
Paul’s view - I checked last H1 results to see if this is a possible turnaround? Mostly recurring revenues (good) but only c.£2.5m pa. Close to breakeven. BUT - huge issue - it’s got an insolvent balance sheet, with £10.5m of “borrowings” from 58% shareholder InTechnology. Therefore I see the equity as uninvestable until it sorts out the balance sheet, with a much-needed equity raise (or maybe a debt for equity swap?).
Light Science Technologies Holdings (LON:LST) - up 10% to 2.7p (£9m) - Final Results FY 11/2023 - Paul - AMBER/RED
Improved trading, and cost-cutting, reduces its loss before tax by 58% to £(1.1)m.
Outlook comments seem over-the-top. Cash looks tight, and NTAV c. zero. Almost doubled share count in a fundraise in April 2023 at just 1p/share. Probably won’t be the last fundraise in my view. I can’t see any evidence of a viable business here yet.
Oxford Cannabinoid Technologies Holdings (LON:OCTP) - down 66% to 0.12p (£2m) - Intended Cancellation of Listing - Paul - GREY (delisting)
This one only listed in May 2021. Says that the listing no longer helps it raise funds or develop its drug programmes. Says that it has “no near term cash flow concerns, and remains debt-free”.
I agree completely with this bit below - the stock market is no place for early stage, zero revenues, multi-year cash burning drug development companies -
"The UK capital markets are facing particularly challenging times and many biopharma businesses like ours are re-evaluating whether it is the right home for them. We believe that the market is significantly undervaluing OCT. This has a negative impact on our ability to raise the capital necessary to drive our programmes at a price that the Board believes would be acceptable noting the current market capitalisation.
Alliance Pharma (LON:APH) - down 10% to 28.8p (£155m) - Delayed Accounts - Paul - RED
Audit delays means it’s not ready to publish FY 12/2023 accounts today as planned (AIM companies have 6 months). This is the second time audited accounts have been delayed, but no explanation as to why, what are the audit problems? It keeps repeating this line -
Alliance reiterates that the details provided in the full year trading update on 29 January 2024 remain accurate.
CEO Peter Butterfield is stepping down, with a new CEO starting shortly, 13 May 2024.
Paul’s view - late accounts, and the CEO stepping down, is bound to spook investors. The forward PER is only 7, but one look at the last balance sheet shows a horribly negative NTAV, and way too much bank debt of c.£120m gross. This is expensive, costing about £6m in finance costs in H1. There was a CMA investigation mentioned in H1 results. Also 38% of shareholders voted against the interim dividend, preferring reinvestment in the business (and presumably debt reduction).
For the time being I think APH looks too problematic. I think it over-expanded using too much debt, and hence looks quite high risk to me. I wonder if the audit delays might be over going concern testing? That would be my guess.
Summaries of main sections
J D Wetherspoon (LON:JDW) - up 3% to 752p (£929m) - Trading Update - Graham - AMBER
It’s a positive update with profits for FY July 2024 expected “towards the top end of expectations”. I’m intrigued by the realisation that the company bought back £34m of stock in H1 for cancellation, and the suggestion that it made £271m of free cash flow last year. Will need to keep an eye on developments here.
Boohoo (LON:BOO) - down 4% to 33.9p (£429m) - FY 2/2024 Results - Paul - AMBER
Poor results, with a move into losses, even on an adjusted basis. Balance sheet relies on a fully drawn £325m borrowing facility, which seems odd considering it also held £230m in gross cash. Cashflow was poor in FY 2/2024. There are some positives in the outlook though, with cost-cutting and warehouse automation underway. So I don't see it as a basket case. Chinese competition now means it's very difficult to make any profit, so not a sector that appeals to me any more.
Paul’s Section:
Boohoo (LON:BOO)
Down 4% to 33.9p (£429m) - FY 2/2024 Results - Paul - AMBER
This share doesn’t really interest me these days, because it doesn’t make profits any more. That is because Chinese competition (particularly Shein) has undercut it on price, selling direct to consumers. All the other bear points on BOO were irrelevant as it turns out (ESG, etc), it’s Chinese competition that is the crux of why profits have collapsed, and hardly anyone spotted that when it began.
Can BOO get those profits back, is the key question? Personally I doubt it, but with many smaller competitors disappearing, maybe online fast fashion might end up a concentrated market, served by Shein, Boohoo, and maybe a few others?
Some key numbers for FY 2/2024 -
Revenue down 17% to £1,461m
Gross margin up from 50.6% to 51.8%
Adj EBITDA is not a reliable profit measure, but it’s down 7% to £58.6m
Adj PBT is a loss of £(31.0)m, much worse than £(1.6)m in FY 2/2023.
Statutory PBT is much larger at £(159.9)m, so very large adjustments of £103m, as usual in this sector.
There’s no way a positive spin can be put on these figures, they’re poor.
Share based payment charges are excessive, given that BOO is no longer profitable, at £17.5m in FY 2/2024, and £32.0m in the prior year. I don’t think management or staff should be given cheap or free shares when the business is loss-making.
Another concern is a big deterioration in net cash/debt, which was £5.9m net cash last year, and £95m net bank debt at FY 2/2024. Obviously growing debt at that pace is not sustainable, and we need to check the covenants on that debt. It says this increase in debt is due to capex and inventory growth. I would have expected inventories to fall, given that revenue is down 17%.
During the prior year the group secured a new £325 million rolling capital facility, increasing from the previous £100 million facility. The facility remains fully drawn at the end of February 2024.
Encouraging comments in the outlook -

Improving trend of revenue declines - is it approaching the bottom of this cycle, I wonder? -
I am particularly encouraged with the ongoing trend of improved performance in our core brands which saw GMV down 9% in H124 and down just 4% in H224 demonstrating increasing momentum and validating our strategy to focus on these brands which are much loved by our customer base…
The group is now well positioned to return to growth, and we are focused on ensuring that growth is both sustainable and profitable.
Balance sheet - NAV is £280m, less intangibles of £104m, giving NTAV of £176m.
The one item I’m not happy with is the gross borrowings of £325m, this seems too much. Why does it need this level of borrowings, when it had £230m in gross cash?
I need to see average daily net debt, which I suspect might be a good bit worse than the year end snapshot.
Cashflow statement - net cashflow from operating activities has dried up, £137m last year, only £2m this time FY 2/2024. Subtracting all the other costs (eg lease payments, capex, £32m capitalised development spending, £15m shares purchased for the EBT, etc), and the total cash reduction in the year is £(101)m. That is not good.
Paul’s opinion - poor figures, and if these trends worsen, then BOO could be in trouble. Although I think the actions they’re taking to improve performance, and stem the cash outflows, seem sensible.
We might end up with a business operating at about cash breakeven, but I don’t think there’s much realistic chance of a return to big profits.
How to value this share? The current market cap of £429m looks about right to me, so I’ll go with AMBER.
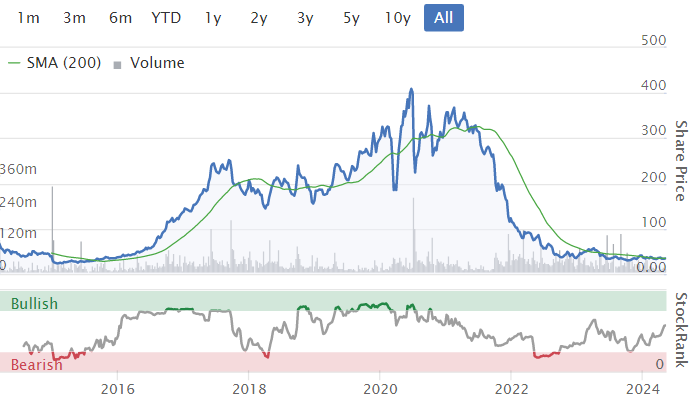
The sector has completely changed since the days of £4-5bn market caps for Asos, Boohoo, and THG. None of them make any profits now, and Boohoo was the only one that was consistently profitable in the good times. It’s probably dawned on all of us that this sector is just a lousy place to do business now that the Chinese are cutting out the middlemen. Intriguing potential upside if Western Govts ban Shein and others from selling direct to consumers, but how likely is that?
Things have completely changed in recent years, with profits and growth collapsing -
Graham’s Section:
J D Wetherspoon (LON:JDW)
Up 3% to 752p (£929m) - Trading Update - Graham - AMBER
This is an update for the “13-week period to 28 April 2024”, i.e. for the Q3 period. JDW’s financial year ends at the end of July.
The company is trading well and the bottom line is that profits for FY July 2024 are expected “towards the top end of market expectations”.
Headline growth number: like-for-like Q3 sales are up 5.2% year-on-year..
Adjusting the calculation to exclude a bank holiday which occurred in Q3 last year, but not in Q3 this year, the company calculates that the like-for-like sales growth was 6.0% - this is definitely the best measure of sales performance, in my opinion.
The interim results (to January) showed LfL sales growth of 9.9%, so Q3’s growth hasn’t quite matched that performance.
Property - exited 18 pubs and opened two new ones. The 18 disposals resulted in a cash boost of nearly £7m.
17 more pubs are on the market/under offer, representing just 2% of the estate (809 total pubs).
Net debt of £685m, down from £694m at the interim results.
Checking the most recent interims to better understand the financial profile, I see that this net debt figure only relates to bank debt: JDW also has lease liabilities of c. £418m.
71% of pubs are freehold.
So in summary: JDW does own most of its pubs, but it also has very significant bank borrowings on top of the lease liabilities for those pubs it doesn’t own.
Outlook statement provides lots of colour, e.g.:
"Traditional ales, which were very slow in the aftermath of the lockdowns, are increasing momentum, with Abbot Ale, Ruddles Bitter and Doom Bar showing good growth, as indeed are ales from the many small and micro brewers with which we trade.
"Also selling well among younger generations are Au Vodka from Swansea and XIX flavoured vodkas, the latter promoted by the hugely popular Sidemen.
"Wine has been on the comeback trail, with Villa Maria Sauvignon Blanc, from New Zealand, popular among Wetherspoon representatives of the chattering classes.
Graham’s view
Paul has been consistently “AMBER” on this for a while, on valuation grounds, and I’m inclined to agree.
The shares have had a great recovery run over the past eighteen months, although they do still trade below pre-Covid levels:

On simple earnings multiples, they are not obviously cheap:

No dividends have been paid since 2019, although I note that the company (with very little fanfare) bought back £34m of its own shares for cancellation in H1, equivalent to paying a 4.5% yield! A very interesting decision. The company argues that its free cash flow last year (FY July 2023) was £271m, but there is a lot to unpack in that calculation.
I’d be inclined to go AMBER/GREEN or GREEN if it was obvious to me that the company could afford to buy back a meaningful percentage of shares, or to start paying a regular dividend again. However, given the existing market cap (£900m+) and the debt pile, it seems to me that that stock is fully valued and that any regular dividend would offer only a modest yield. However, I’m open to changing my mind here if the free cash flow keeps flowing and if the quiet buybacks keep happening.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
On Boohoo (LON:BOO) on what draw people's attention to my comment a while back on the non-level playing field. https://www.stockopedia.com/co...
Governments don't need to ban imports of Chinese goods (that would be politically incendary) but leveling the playing field with a tarif which reflects how Chinese manufacturers are able to undercut non-Chinese producers through government support and probably sweated labour. Is it just me or has anybody else noticed how MG's there are on the road in the UK?
I generally have a sucked it up and get on with it attitude to business (I ran my own with no state help, in fact the opposite) but when industries face state manipulated market forces then something should be done to counteract it. That said UK businesses are not exactly helped by a business unfriendly government, over regulation, over taxation and a press that likes to put the knife in at any turn.
Regards
Michael
I know cheap chinese clothes and assorted clobber isn't exactly semiconductors.But the US banned Intel (NSQ:INTC) and Qualcomm (NSQ:QCOM) selling more semiconductors to Chinese Huawei.I say good on them as Xi is no fool like Putin and doesn't respect fair play and sees it as a weakness to be exploited if possible i'm sure.
Future (LON:FUTR) will announce its half-year results on 16 May 2024.
After the trading statement on 4 April 2024 Paul was GREEN on the stock. He couldn’t understand why it's so cheap! A few excerpts from the statement:
“…the Group is on-track to deliver on expectations for FY 2024, subject to impact of foreign exchange translation.”
"stronger performance in US direct advertising, a key strategic initiative, driven by the continued focus on premiumisation of advertising inventory benefiting from the Group's scale and first-party data."
AD09 highlighted the following points:
Boon also highlighted two issues:
Am mulling wether to buy some, any further thoughts on downside/upside appreciated.
Ascential (LON:ASCL) Announced the results of a tender offer priced 315-330 today with £300m being returned at 315. A success for the company. Following this £450m will be returned by special div... that's £750m plus £100m buyback to mop up stock post all the capital returns. I sold my stock as im uncertain how the dividend will be taxed and how the rump will trade. At present the rump Events business trades on about 13x EBITDA and therefore not much to say..... I simply put the stock on the blotter because firstly, it will be a large small cap. Secondly PMs either need to buy it sell it post special dividend. These situations can turn either way but my suspicion is it could be weak.... since their position has shrank significantly and the rump stock isn't sufficiently cheap to expect some sort of bid to be imminent. Famous last words no doubt.... but you have a situation where the small cap guys haven't looked at it and midcap guys have lost interest in a small position. Either way we will begin to find out in 2 weeks... since on May 17 it goes X the special and then consolidates at 10 for 17 to maintain the existing share price. The £100m buyback will help support initially. Worth keeping an eye on since any weakness will open a discount to Informa and potential M&A.
Ouch Argentex (LON:AGFX) down almost 10% again and no new rns\bad news afaik.I guess it will stay volatile for a while.Already done for 'averaging down' and 'topping up' for now.Soon the Argentex (LON:AGFX) and Cornerstone FS (LON:CSFS) market caps will be converging it seems.
John Wood (LON:WG.) just exploded higher :-). Possible leak of a new takeover bid?
yes, sidara (in dubai) pondering a bid
They have rejected a bid at £2.05
Thanks for sharing the bid details re John Wood (LON:WG.) I’d missed the connecting story
Not sure I would call up 13% "exploding higher", but yet more encouraging evidence of an undervalued UK market nonetheless!
John Wood (LON:WG.) was up over 20%, fallen back now.
Re Boohoo (LON:BOO), I find it extraordinary that the current govt has not closed the loophole that allows Shein, Temu et al to game the system on import duties. The only rational reason I can think of is that they are worried about the impact on inflation numbers. But the behaviour of these Chinese monoliths is accelerating the destruction not just of our manufacturing, but now our retailing base!
The government just don’t care enough .
Then again even more offensive is the “tax planning” of Amazon / google / Facebook with their trans movement of profits out of the country of sale .
How many people know about Amazon’s tax evasion yet still shop on Amazon ? Sometimes looking in the mirror is enough and each person can take the action yet no one bothers .
So easy to see how a government can’t get mobilised when we equally all do it everyday .
Even I do it by advertising on Facebook / Instagram and paying their invoices that all come from Dublin
We’re all part of the problem and no one cares enough to stop .
So Shein joins the list of robber barons that enrich themselves and we all contribute myself included .
And a reduction of vat intake from uk government meaning more borrowing.
re Mobile Tornado (LON:MBT) Just as background.... Intechnology is the vehicle of Peter Wilkinson, who set up and sold freeserve and is the founder and main backer of Mobile Tornado (LON:MBT. So yes, he has bank rolled it through debt and the equity has also been diluted heavily through time - although he has mainly accepted more equity in exchange for less debt. My point is he won't be bankrupting the company .... a lot of staff, friends and family etc are in this one.....I would view the EV as the business value .... but wouldn't be as sensitive to it being over burdened by debt as the balance sheet suggests. They have been working on this for nearly ten years and have had many bumps in the road..... the final one being covid which affectively put all plans on hold again for a couple of years. Their revenues from this will depend on take up etc and its early days but could be quite exciting. With so many disappointments in their past I can understand why it's too early to talk numbers.
Critical services is also an area they are keen on. Africa and South America may well also offer contract potential where bandwidth cost and availability are a real issue.
This has sat in the bottom draw for me for years.... so Im hopeful that finally a real business can be built but there is a long road ahead. This is the first step.... my guess is the market puts option value on the opportunity...and will include the debt in that valuation.
Very interesting background on Mobile Tornado (LON:MBT) , thanks RDH!
XP Factory (LON:XPF) 15 Month trading update inline. No interviews yet, hopefully Richard doesn't skip them because everyone said he was too rampy at the last update.
New brokers note from Singer, summary below. I continue to hold, hopefully.
"XPF’s 15m trading update illustrates a strong end to the year with c.12% LFL’s for the 3-month stub period of Jan-March. This follows an exceptional 2023 and results in the 15m EBITDA being in line with market expectations. Positive momentum has continued into April. Overall, the strength of the update caps off a transformative trading period which saw revenue up >80%, LFL’s in high double-digit territory (all volume) and margin growth. This highlights excellent operational execution by management and reinforces that the Escape Hunt and Boom formats offer a superior product in the experiential leisure space. We make no forecast or TP changes. Overall, the scope for roll out remains significant, the BS is strong, and execution / ROI has been exemplary. This is not reflected in a depressed 3.4x EV/EBITDA (vs the Leisure sector on 6.5x) and a 23% FCF yield. We reiterate our Buy and 32p "
I am coming to the conclusion that the only companies in the hospitality sector an investor can make money from, are those that can leverage economies of scale. There are no barriers to entry, new ideas seem to have a short shelf life and spend is falling. So I am sticking with Wetherspoons and Whitbread.
I hold Whitbread (LON:WTB) did not realise how far the Stockrank, had fallen recently, it is now only 28.
I hold Whitbread (LON:WTB) did not realise how far the Stockrank, had fallen recently, it is now only 28.
I’m scratching my head trying to work out why shares have fallen so much since the start of the year. Nothing much seems to have changed in the operating sphere – if anything UK economic prospects are improving – or have I missed something in the trading outlook? If nothing operational, then I guess we have to look at interest rates and the prospect for cuts to be pushed out further into the future and fewer. But other interest rate sensitive stocks have been picking up this last week.
for what its worth - I have looked at Whitbread (LON:WTB) this year - like the Premier Inns which are doing well, but put off by the debt figure - just too much for my liking.
Whitbread (LON:WTB)
bohenie
but put off by the debt figure - just too much for my liking.
Did you properly look into the debt ? where debt incudes future lease liabilities (ie future rent practicably speaking) its not excatly the same as normal debt.
I would "guess" that their asset values are understated too.
Thanks for that rmillaree - I just looked at the DEBT shown on Stocko £4397m and tbh - I don't know if thats with or without lease liabs - its too much for my liking
Whitbread (LON:WTB)
per the last acounts net debt exluding lease liabilities was only £298 mill - lease liabilities being £4.1 billion.
note i would guess that the £4.1 billion is simply future rent payments that are brought in on the basis that they have signed a say 10 year lease commiting to pay those amounts inn the future - that being the case not really debt , albeit worst case scenario they may havd to pay that rent. Practicably speaking they would probably want long leases on their properties so there is less chance of property being taken back by landlords.
Note they have the right of use aset on the balance sheet of £3.5 billion ref leases - so this seems to confirm that the lease debt is simply mostly future rent payments - albeit there may be some timing adjustments needed - the asset being less that the liability !
on this basis i for one am happy to ignore the lease debt completely
Hi bohenie,
Actually Whitbread (LON:WTB) is very well financed, with a strong balance sheet. Debt isn't a problem at all. I reviewed it here in Jan 2024.
Shares look even better value to me now, as they've dropped a fair bit since I liked the numbers back then.
The only negative I've heard about it, is the cost of living wage increases that have just gone through, same for all companies in the sector.
Regards, Paul.
Whitbread (LON:WTB) they are closing some restaurants and reducing staff by 1,500. The gross adj. profits were up but net profits on Stockopedia seem down. Not sure why the Stockrank has fallen by that much, though. They are doing a large buyback, so that should support the share price. I would have thought things would be improving this year. Guess we need to be patient.
Rusty2.
Buybacks (ignoring the strong case for and against them) don’t suppprt the share price. I held Whitbread (LON:WTB) in 2019 when Whitbread (LON:WTB) sold Costa, and they decided to “reward shareholders” by spending almost the entire proceeds from the sale on buybacks.
The share price then was about £40. The share price fell and has not yet ever reached £40 again. I sold on the news of that buyback and am pleased I did!
I often sell on news of a big buyback and it ofyen pays off. I sometimes buy again when that share looks an obvious bargain. E.g Isold Abrdn (LON:ABDN) as the share price fell away from £5 when they announced a big buybacks. Abrdn (LON:ABDN) have bought back heavily every year since then and the share price is now about £1.60! I bought again on the dip to the current price a couple of years ago, and have been collecting the annual 10% dividend, which unlike my Whitbread (LON:WTB) “ shareholder buyback reward” has genuinely rewarded me with real money.
Each to their own on this and Next (LON:NXT) buybacks, where they’ve now bought back more than half their shares, and only buyback when confident the share is good value, has undoubtedly proved effective.
But too many investors seem to fall for the flawed myth that buybacks will always support the share price. Ask anyone holding a share that bought back heavily that then issued a profits warning if they did.
Abrdn (LON:ABDN) has many problems, l had an account with them until recently. I sold my funds because of their useless system and their service, took them about 3 weeks to respond to emails, they paid me some compensation but it is too late. Read the reviews in Trustpilot. Some shares won't be saved by buybacks. The large US companies do them and they get larger. Apple (NSQ:AAPL) announced one and their shares went up around 10%.
In order to understand buybacks and their enchantment on the EPS you must look over the pond and how successful they are for the shareholders.
Buybacks are effective when the company has extra cash available every year (cash cow). One good UK example is Vertu Motors (LON:VTU).
You keep bringing up the buyback in Abrdn (LON:ABDN) but that was WRONG as the company was in declining revenues!
All the best
Whitbread (LON:WTB)
I held Whitbread (LON:WTB) in 2019 when Whitbread (LON:WTB) sold Costa, and they decided to “reward shareholders” by spending almost the entire proceeds from the sale on buybacks.
The share price then was about £40. The share price fell and has not yet ever reached £40 again. I sold on the news of that buyback and am pleased I did!
we are probably in danger here of repeating a prior spat - you are comparing whitbread shareprice directly pre covid with post covid situation . God knows how much company the money lost over the covid period (£600 mill plus per offfical numbers)
Obviously if they had known covid was coming and that their business model would be crippled for 18 months they would have done it different. they didnt and we shouldnt have expected physchic powers when judging history.
In summary the reason the the poor performace is pretty obvious and its the covid related hit they couldnt have seen coming .
Note compared to wetherspoons - whitbread haevnt done too bad overall ref sharepice directly pre covid to now and J D Wetherspoon (LON:JDW) didnt do a huge buyback pre covid - so the evidence is there that covid took decent chunk into value of many such businesses which they have not fully clawed back. Ok in hindsight the sharebuyback was poor timing but imho its a really unfair example to judge sharebuybacks by !
Ken. In your example, the buybacks did support the share price. They reduced the overall share count and therefore raised EPS. The problem was the operational performance. In the absence of the buybacks, the share price would have ended even lower!
That’s why I never see buybacks as a reason to buy a company. It’s all about the track record and likely future continuation of growing earnings. But, in that circumstance, I do prefer them to dividends.
Nice one!
BnB
Where’s the evidence that the Abrdn (LON:ABDN) buybacks supported the share price? The Abrdn (LON:ABDN) PE ratio is 12.Plenty of shares are on much lower PE ratios than that. Osb (LON:OSB) PE was 3 before recent share price gains. And buybacks don’t get considered when it comes to pricing a share.
It’s more likely, that it was the 10% dividend that put a floor under the Abrdn (LON:ABDN) share price rather than the buybacks. Agree though……. without buybacks, and with a much higher share count, the dividend would have been cut. I bought Abrdn (LON:ABDN) again when the yield got to about 10%, and also because there’s a potentially very good business there that might just appeal to a bidder.
It’s each to their own on this, but I’ve done well in sometimes selling shares on big buyback news, and buying back after subsequent big share price falls. And Abrdn (LON:ABDN) is an example where my selling around £4.60 and buying back at £1.50%ish worked well, and I’ve had 20% of my stake back via dividends.
And in answer to yiannos…..I’ve also made it clear that there are Companies that buyback successfully.
Also buybacks favour investors who want to sell as they’ve a willing buyer of their shares in Abrdn (LON:ABDN) or whoever.
Finally Mining sector Companies like Rio Tinto (LON:RIO) used to spend multiple £billions on buybacks, only then to suffer massive share price falls in the extreme Mining bear market that ended in 2015. Now they go for big special dividends in the more profitable years, and reward their shareholders with real money, and have stopped buying back.
Whitbread (LON:WTB)
its probably a combination of factors - i could be tempted to add here at the right price and 3000p does look kinda tempting . I just look at other companies like Jet2 and think they are cheaper at present (completely different risk profile so probably not fair to compare.
i suspect its simply headwinds here ref wage costs / interets rates remaining stubbornly high and the general outlook ref easy profits. Perhaps there was some expectation profits might be upgraded whereas now perhaps there are worries that 3estimates may be downgraded perhaps ? they are currently xepecting material increase from last year - perhaps the danger is that by the end of the year they may be closer to this years number at the real end of year bottom line.
I was pleasantly surprised at the low level of "net debt here " excluding lease liabilities when i looked. Perhaps we cant fully exclude the lease liabilities as we would do normally though? - their credit ratings factoring in leeses to certain degree and the lease adjusted net debt was up from 2.6x to 2.9x - ok they are allowed up to 3.5 - but perhaps for now storing cash may give more confidence to the markets.
i would say pe here is still 13.4 which does strike me as being screaming cheap - and the enterprise value is getting on for double the market cap - so anyone looking at that metric will probably be saying that aint cheap. Must say the lack of huge debt (ignoring leases) and chunky profits make me think standard pe multiple is fine and dandy and this is getting into decent value range.
I havent checked closely into the lease acounting so not sure if liabilities are plain future rent payments or if the numbers are complicated in some manner that could make this more akin to real debt - on an initial glance it all looks good as the bottom line profit all in last year was £312 mill which tallies exactly with stocky.
Possibly the bigger issue with Whitbread (LON:WTB) isn't the debt (lease adjusted or otherwise). It's the anaemic revenue growth rate at only half that of Accor, Marriot and IHG. In mitigation, WTB operates an asset-backed, rather than asset-light model, which makes comparisons somewhat harder.
Whitbread (LON:WTB) revenue growth looks better than Marriott International (NSQ:MAR) both in the past and forecasts. Whitbread (LON:WTB) took a bigger hit during Covid.
Intercontinental Hotels (LON:IHG) looks even worse.
Can't see Accor SA (EPA:AC) figures.
Whitbread (LON:WTB) revenue growth looks better than Marriott International (NSQ:MAR) both in the past and forecasts.
Not if you smooth out the pandemic distortions it doesn't - simply look over a 10 year period. And forecasts are much lower at least than half - at least they are on Sharepad, which I find more reliable than Stocko.
I'm looking on here, l don't have Sharepad. If you look at 2019 to 2025, Whitbread (LON:WTB) look better. The CAGR/Av is 7.65%, Marriott International (NSQ:MAR) is 2.7%. Intercontinental Hotels (LON:IHG) is only 1.29%
I'm seeing 3% CAGR for WTB over the next 3 years and a trimmed mean of 6% CAGR for MAR, Accor, IHG. Seems a lot lower to me.
As rmillaree says, that can be satisfactory if margins keep growing to push out high single figure eps growth. But the higher operational leverage this business model implies significantly increases the risk in a weak year.
Whitbread (LON:WTB)
its tricky - was watching tick tock the other day about how the asset light model works (marriot) and it seemed like they were practicably speaking getting franchise fees in some parts of the world - if that is the case and works then thats probably a completely different business model as the other party is doing the hard graft too ref ensuring profits are being driven up and sorting all finance issues (i may have missed something important here as being tick-tock it was all over and done in 4 minutes) - i sometimes wander with these listed companies whether the board cares more about salary than driving profitsforward. in theory i like the asset model if the debt isnt excessive. Anemic growth is kinda ok as long as margins are maintained - just look at the history of companies trying world domination - if its just tickover premier inn without much growth thats not necessarily worst thing in the world as long as they are doing the basics well.
XP Factory (LON:XPF) - You may be right Cambteb but Escape Hunt is 6 years in the UK now and the first ever sites are still growing revenue year on year, with most of the same games, they are modular so quite easy to change. The same growth rate appears to be happening for established BBB sites. I think it could be a good long term hold, they are in locations they could never have dreamed of 4 years ago.
Re XP Factory (LON:XPF) today’s RNS didn’t mention profits…or cash position…just revenue & some LfL numbers….they’ve also recently changed their year end & their depreciation policy…couple that with the recent substantial expansion & complexity around calculating LfL given the rapidly changing footprint & the acquisition of some of their previously franchised outlets & the scope for a variety of approaches to pre opening costs/landlord incentives (are any of their sites over-rented btw?) & you have a business I’d really find it hard to get comfortable with..f’casts are for negligible profit this year. Best of luck
XP Factory will be exhibiting and presenting at the Mello2024 conference in two weeks time Mello2024 – Mello Events Over 20 companies each day and lots of great quality speakers and BASH panel sessions with even more companies analysed
I'm surprised ECO Animal Health (LON:EAH) is up +7% this morning so far. The milestone for the vaccine, while substantial, still leaves quite a lot more left before the first revenues are realised. The company has previously guided that full approval of the Ecovaxxin MS will only come in Q2-CY25. Today's update gives Q4-CY25 as the "launch" in the USA.
Unsure whether they are indicating that there is a delay to Ecovaxxin MS timelines (ie approval is the same as launch, and therefore now pushed back to Q4-CY25). Or whether Approval and Launch are quite different milestones that needs to be separated by half a year...?
Nevertheless, today's announcement has been issued as an RNS instead of RCS, so the company believes that this milestone reached is significant...
(I hold in the Boon Fund)
ECO Animal Health (LON:EAH)
The problem with any share like this is that us private individuals know the least out of anyone that matters who is trading the stock. Eco animial is about as opaque a stock as you can get at the best of times so its really hard to get a handle on how well the company is doing. practicably speaking is the climb back up not simply reversal of spike downwards earlier in the year ? - it probably doesnt take much or anything for price to dip and presumably its the same the other way - if share is reasonably lightly traded it probably doesnt take much to move the needle. I doubt the news today is much about anything other than being "progressing as expected"but all i do know is that it would probably take specialist in the field to pass real informed commentary - having said that you appear to to way more up to speed than me here so . Perhaps the rns is necessary box ticking if the timeline has been pushed back - so it might appear good news whilst the reality is that delays probbaly mean extra expenses with delayed potential cashflow - even with delay one has to presume that good news is still good news or as you say if wording is sketchy anyway perhaps they are on track. It sensible to preume there coulkd very well be a delay between approval and launch.
You're right that it valuation of early-stage "pharmaceutical" type products is very difficult, and I concede that I have absolutely no knowledge or expertise in this area. Which makes this one of my more difficult shares in my portfolio.
What attracted me to ECO Animal Health (LON:EAH) is the underlying core business; the Aivlosin part. There's c2p EPS for FY Mar24, but going into the details, they're actually charging quite a bit of expenditure relating to the new vaccines to the P&L. It seems like £4m-ish a year? Which for me means that underlying profitability is actually around 6.5p, instead of 2p!
And then there's the potential recovery in sales to China of Aivlosin; after a year and a half of depressed hog prices, things have stabilised, and the official projections is herd sizes in H2 that are more balanced to demand. The future prices for hogs have firmed, but not as much as I expected yet. A full recovery in China sales, I estimate could add another 6p to the EPS.
So when I take an EPS of around 6.5p to 12.5p as a potential within 24 months, and what I think is the right PE ratio of 15x to 18x for this type of share, its almost like getting the vaccine development for free.
However, the share price has nicely gone over 30% since I bought at 89p, so I'm not quite sure there's much value to buy at the current price looking at only the core Aivlosin business; one would need to be comfortable assigning a value to the vaccine programme.
( I hold in the Boon Fund - full writeup on my investment thesis of EAH on my substack)
Ocean Wilsons Holdings (LON:OCN) - decent quarterly trading announcement this morning. Turnover/ profit at 57% Brazilian maritime services subsidiary, Wilson & Sons, up by 17.9%/29.3% respectively, versus Q123. Investment portfolio increased by 4.1% in the quarter. Overall NAV £27.75/share v price of £13.50...nr 50% discount. Ongoing strategic review announced in June 23 of Wilson & Sons. Look forward to hearing SCVR view as highlighted for comment.
Ocean Wilsons Holdings (LON:OCN) - yes, looking very positive for Wilson & Sons. The time is surely right for the sale of this prize asset over the coming months. That would potentially leave Ocean Wilsons and Hansa Investment (LON:HAN) to merge their investment portfolio's in Bermuda with a possible cash option.
My morning smallcap tweet: Boredom grinder
Oxford Cannabinoid Technologies Holdings (LON:OCTP) Proton Motor Power Systems (LON:PPS) Mobile Tornado (LON:MBT) Ocean Wilsons Holdings (LON:OCN) Light Science Technologies Holdings (LON:LST) Deltex Medical (LON:DEMG), Cornerstone FS (LON:CSFS), Boohoo (LON:BOO), Brighton Pier (LON:PIER), XP Factory (LON:XPF)
◄Oxford Cannabinoid Technologies (OCTP)► to de-list. No vote needed. Says it will be easier to attract new investment when private. Co did a placing only 3 months ago! [SP=0.36 Cap=4m]
◄Proton Motor Power Systems (PPS)► cutting costs, laying off 17% of staff. [SP=2.33 Cap=39m]
◄Mobile Tornado (MBT)► wins contract to supply technologies for a mobile network operator with 50m users in the Middle East and Africa. No £££. [SP=0.93 Cap=4m]
◄Ocean Wilsons (OCN)► NAV end March 1994p/sh. Wilson Sons' Q1 2024 net rev up 18%. [SP=1350 Cap=477m]
◄Light Science Technologies (LST)► FY-Nov. Material uncertainty going concern stmt. Outlook all sunny of course. [SP=2.6 Cap=9m]
◄Deltex Medical (DEMG)► AGM stmt - outlook positive. [SP=0.13 Cap=2m]
In line: CSFS, BOO, PIER, XPF
Ocean Wilsons Holdings (LON:OCN) NAV is 2775p/sh, not 1994p which is only the Wilson Sons holding.
Hi Paul and Graham -Thanks for the pointer to J D Wetherspoon (LON:JDW) - worth holding the shares just to follow this guy and better still, he turns in a nice profit and reduced debt with the prospect of a divi some time soon.