Small Cap Value Report (Wed 8 Sep 2021) - SOM, AUG, MEAL, WINK, ALT, ACSO, TRX

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Today's report is now finished.
Agenda -
Paul's Section:
Somero Enterprises Inc (LON:SOM) (I hold) - sparkling interim results, and Finncap raises full year forecast by 21% (and still seems conservative to me). Terrific business, generating loads of cash, and still looks cheap. That assumes a continuing positive macro backdrop of course, as this is a cyclical business.
My notes from recent webinars from Parsley Box (LON:MEAL) and Altitude (LON:ALT) - which I thought might be useful for anyone who is time poor, and can't watch the recordings themselves. Key points only, and my personal interpretation, so not intended to be a comprehensive regurgitation of the webinars.
Accesso Technology (LON:ACSO) - trading update. A strong recovery in revenues back to pre-pandemic levels, guidance raised. EBITDA also "significantly ahead" of market expectations. Guides that costs will rise. I remain sceptical about this company, but I'm not a tech investor, where different rules apply.
Jack's Section:
Augean (LON:AUG) - Solid results from Augean, whose business is highly regulated and discourages competitors. There is an ongoing tax dispute which has previously put investors off but the direction of travel here is positive. Two bids for the company has been received but the share price remains above these levels, so there is some hope of further offers.
M Winkworth (LON:WINK) - franchised estate agency active in the London property market. Business has been booming ahead of the halting of stamp duty but the company is well positioned longer-term and is sensibly managed. It's very small though - prohibitively so for those hoping to buy in scale - but useful readacross for the market.
Tissue Regenix (LON:TRX) - has a history of equity dilution but new management brings a greater focus on product commercialisation and cost reduction. There is a backlog of elective surgeries and the group has expanded capacity just in time to meet potentially strong demand in the year ahead. Cash burn remains a concern though, making this a high risk investment.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Somero Enterprises Inc (LON:SOM) (I hold)
512p (at 09:25) - mkt cap £288m
This US-based company (listed on AIM for 15 years), sells & supports laser-guided concrete laying machines, a niche where it is the market leader.
Interim Results for the six months ended June 30, 2021
Record H1 results due to strong US market, raising 2021 guidance
Revenues in H1 are strong at $64.4m, which is obviously up on H1 LY (covid impacted) of $35.3m. H2 LY was $53.3m, so the recovery has continued nicely into this year.
Good macro drivers in Somero’s main US market. The demand for warehousing looks like a long-term trend to me, what with eCommerce growing, rather than a flash in the pan -
H1 2021 trading in the US was highlighted by accelerated activity from customers working to catch up on projects previously slowed by COVID-19 restrictions and by healthy demand for new warehousing
Profitability has gone through the roof, with H1 PBT of $23.5m (H1 LY: $7.5m) against a weak pandemic hit comparative.
H2 LY was $16.3m, so there’s been another big uplift against the recovery period in H2 last year. Impressive, because Somero originally guided quite cautiously for 2021, saying it would be a year of consolidation & increased overheads to lay the foundations for future growth. Whereas it seems to actually be turning out to be a much stronger year than originally anticipated.
EPS is $0.32 in H1, converting to sterling at £1 = $1.376 gives 23.3p EPS in H1 - remember this is just a half year.
Seasonality - looking back at the Stocko sequential half year table here (very useful!) shows that pre-pandemic there was a usual H2 weighting to profits. If that happens again this year, then maybe we could be looking at up to c.50p EPS for FY 12/2021?
Broker upgrade - many thanks to Finncap for keeping us informed. It raises EPS forecast by a hefty 21% to $0.55 or 40.0p. That looks very conservative to me, it’s way below my figure above. So I’m inclined to expect further upgrades as 2021 progresses.
Finncap also raises its price target to 700p, which again doesn’t look particularly high to me. If Somero does achieve 40-50p EPS.
Sure, Somero is cyclical - so are lots of companies. It depends where we are in the economic cycle. If you think we’re in an unsustainable boom fuelled by QE and zero interest rates, then you might think we’re near the top of the cycle. Other people think a growth cycle has only just begun. So who knows?!
Balance sheet - looks fine, no issues.
Cashflow statement - I was wondering why cash hasn’t increased that much. It’s not because of working capital normalising (little overall impact), it’s because $17.37m was paid out in divis in H1. This business is a cash machine when trading well. So expect more generous divis.
My opinion - I’ll go through the commentary in more detail when time permits, but want to get this quick view up promptly, covering the main points.
This company is performing superbly, and the shares look cheap still, if you think the current level of business (let alone any further growth) is sustainable - which I do.
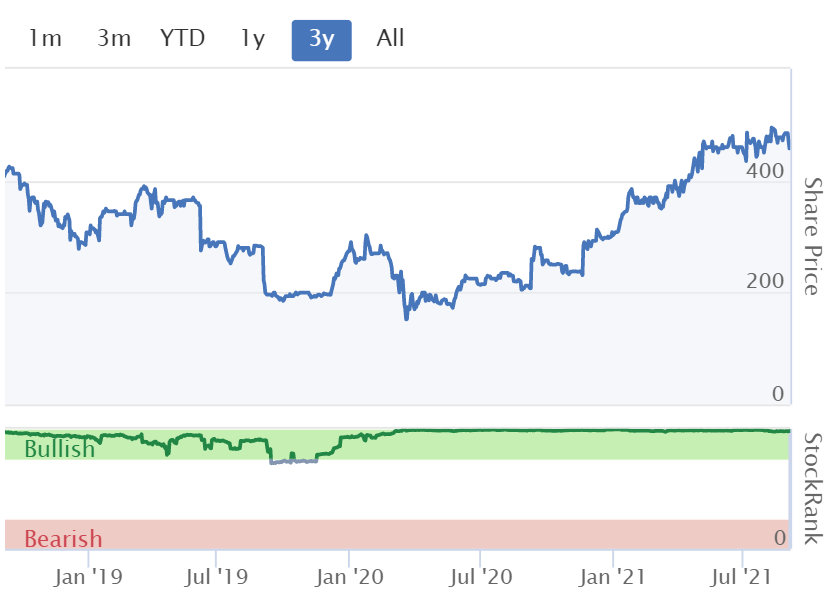
Note below that the StockRank has been jammed on maximum for over 18 months!
.
.
Webinars
Many thanks to InvestorMeetCompany, PIWorld, Mello, Equity Development, and others who are providing very useful company results webinars. All listed companies should be doing these routinely now, as all shareholders deserve to see the same presentations that the institutions see, and be able to ask questions. A level playing field for all should be the norm.
I enjoy webinars, as you can't beat hearing management talk about their companies in their own words. It deepens my understanding of companies (useful when we have to cover over 500 companies here, which is crazy really), and it gives a flavour for what management are like. I'm just looking for passionate, hard-working, hands-on entrepreneurs, from any background, not smooth-talking suits!
After yesterday’s deluge of results, I was too tired to visit the Malta At War Museum, so instead sat in the sun, listening to some webinars. Here are my comments, if you’re interested, which as usual are just key points that I jotted down, it’s not meant to cover everything -
Parsley Box (LON:MEAL)
Company has only existed for 4 years
23k reviews on TrustPilot (I must have a look at those)
H1 2021 was up against tough prior year comparatives (start of the pandemic)
Most revenues come from repeat customers, and are higher margin & larger order value than new business
Growth in active (at least 2 orders in 15 months) users from 100k to 178k at end H1 2021
CFO (John Swan) is retiring soon. New CFO (Holly) joining soon. All seems amicable
Product innovation explained, including new chilled range - positive early signs - appeal to a slightly younger (over 60s!) customer (but surely there’s little differentiation from supermarket ready meals?)
Capital-light business (production is out-sourced)
Main expense is marketing - £4.85m in H1
Contribution margin of £4.17m, but that’s stated before £2.9m general & administration spending. Then there’s the marketing spending on top
New orders are 35% gross profit (due to discounts), repeat orders 55% - quite good
Cohorts slide does show the cohorts declining over time, still not clear what LTV is, this was rather glossed over - I suspect many customers don’t re-order, but a lucrative few become regulars, that’s from reading between the lines not from anything specific the company said
Labour & raw materials cost inflation is evident - will pass on to customers with price rises
Double property costs, due to need for social distancing. Will save £480k p.a. from September, when surplus property is vacated. This struck me as very high, so I rewound the video to make sure I had noted it down correctly, and unless they mis-spoke this is what was said - so quite a big reduction in overheads coming through
Customer acquisition cost has been high, due to TV ads, will return to normal now - long-term benefit from brand recognition, which is up strongly
Customer churn is low, but CEO was quite vague about this, so dodged the question a bit in my view
Closest competitors are Oakhouse, Wiltshire Farm Foods
Headcount currently 120 people. Likely to rise by 10-15 this year
Call centre employs a lot of staff - looking to partially automate outbound calls
My opinion - I’ve nothing to add to yesterday’s report. I think it’s an interesting niche business, with some potential. Although the valuation still looks steep to me, now that growth has sharply reduced after the pandemic one-off boost last year.
Altitude (LON:ALT)
Another webinar (recorded) on IMC from yesterday.
Nicole Stella - American-sounding CEO, joined in 2017, has 17 years sector (promotional goods) experience. Talks well, a good presenter.
Peter Hellett - is a NED, standing in for outgoing CFO. Says departure of CFO is “all perfectly amicable”, he wanted to pursue some other passion apparently. Seems a credible NED, sounds a bit like Pete Waterman (slight Brummie accent!). His background is in turnarounds, tech companies mainly. Straight-talking, seems credible to me, not rampy - pointed out some negatives, very open.
Profit rose for FY 03/2021, went through the figures (see RNS)
Custom-built tech platform
6-12% transactional fees (peak at 18%)
“Opportunistic sales of PPE equipment” in pandemic of £1.9m, so revenue growth is not the main activity. PPE sold at only 17% gross margin, added £300k to gross profit, but has opened their eyes to opportunities to sell non-competing products direct, not just being an intermediary.
£400k benefit from US Govt grant in pandemic
Clean P&L for the first time - no acqns/disposals, or material exceptionals, so investors can see the steady state of the current business
Presentation of revenues will change under IFRS 15, I didn’t fully grasp this point
ACS & (something else) have great growth potential - ACS numbers will be much bigger this year (sounds interesting, but it wasn’t explained very well)
Big growth potential from selling direct (as above)
USA is returning to normalcy
Showed an interesting graph, that in previous crashes (e.g. 2008), promotional goods declined massively, but then enjoyed a multi-year, gradual recovery - expecting the same this time
Supply challenges - more inventory is needed earlier
Covid - not over yet, e.g. factories in China & Vietnam are cropping up still, but we’ve navigated through the worst
Outlook for FY 03/2022 - returning to pre-pandemic levels of activity
Optimistic as markets recover
Emphasised still in “cash conservation” mode - which makes me wonder if another placing may occur? (speculating there)
Q&A - receivables high - yes, quarterly invoicing is the norm, and delays happen when suppliers reconcile their numbers. Industry standard.
My opinion - it all seems a bit vague to me. I’ve never fully understood what the business actually does. Maybe they need to change the presentations, to give more basic examples of real world transactions?
It’s not clear to me if this is a good business with potential, or not.
Overall - might be worth a small punt, but at this stage that would be largely speculative. So not one for me, but I’ll follow with interest.
.
Accesso Technology (LON:ACSO)
895p (up 8% at 10:17) - mkt cap £369m
I hadn’t spotted how strongly this share has performed in the last year - market sentiment certainly seems very positive - I suppose it’s an obvious re-opening trade (theme park ticketing & queuing systems). My problem with Accesso, is that I’m not convinced it’s a good business at all, whether theme parks are open or shut! Nobody wanted to buy it (as far as we know) when it did a lengthy formal sales process a while back, and the company’s financial history is fairly poor - no meaningful or sustained cash generation for example (after taking into account the large payroll costs that were capitalised onto the balance sheet as development spending).

Let’s have a look with fresh eyes at today’s update.
accesso Technology Group plc (AIM: ACSO), the premier technology solutions provider to leisure, entertainment and cultural markets, gives the following trading update ahead of its interim results which will be released on 14 September 2021.
The current financial year is FY 12/2021.
This sounds positive - a return to pre-pandemic revenue levels -
Through July, August and the Labor Day holiday period, accesso has built on excellent first half performance and continued to capture high demand for its technology solutions. As a result, trading during this period was very strong.
The Group's ongoing momentum now leads the Board to revise upwards its expectations for full year 2021 revenues to not less than $117m. This represents full recovery to 2019 trading levels.
$117m is £85m.
What about profitability? We’re not told, instead they tell us about “cash EBITDA”, which of course is not profits (or cashflow) -
This rapid growth in revenue alongside a slower return to normal operating expenses will result in Cash EBITDA being significantly ahead of current market expectations for both the half and the full year.
However, in the strange world of tech shares, conventional valuation metrics disappeared ages ago.
Costs are rising - together with the comment above about costs increasing more slowly, then this implies that short term profitability might be short-lived? Do tech investors care about profitability though? Arguably not. In the current environment people seem to pay up for growth, and you can see why when we look at the many massive success stories in the tech area (mainly in the USA), where in many cases ignoring profitability in the short term has produced gigantic investment returns -
The Group is currently deploying additional resources across technology implementation, product development and customer support to calibrate for the new demand. As previously signaled, these investments will have a limited impact on Cash EBITDA in 2021; their full annualised effect will be felt in the 2022 financial year.
My opinion - doesn’t really matter, because I’m not a tech investor, and valuations in this sector mystify me.
With planned cost increases, it’s not clear to me that the business is likely to make any sustainable profits just yet, so for me that renders it impossible to value.
Maybe it will grow into a larger, and profitable business. Maybe it won’t. That’s the crux isn’t it.
We just review the numbers here, with a value/GARP approach, so I can’t form a view on Accesso, because there’s not enough to go on. There’s not much point in me reviewing tech shares, as it’s not my investing focus, and other people are more in tune with the sector, so can do it better. All I would say is that when bull markets end, tech valuations come back down to earth with a crash, and conventional valuation metrics do matter again (based on my experiences of the whole boom/bust cycle from 1998-2003).
The valuation is all about what investors think the future holds, and that’s for each individual investor to guess for yourselves. Nobody can predict the future with certainty, and there’s not much in the way of historical profitability to benchmark Accesso shares against.
Also, there’s been very little revenue growth in recent years (pre-pandemic), so it seems odd to me that ACSO has such a premium valuation. Is it really a growth company? Doesn’t look like it to me (see graphs below). Maybe growth is likely to improve in future? The share price is already anticipating that anyway.
.

.
Jack’s section
Augean (LON:AUG)
Share price: 335p (unchanged)
Shares in issue: 104,971,924
Market cap: £351.66m
Augean is a waste management solutions provider that disposes of hazardous waste for the oil & gas and nuclear & radioactive sectors. It’s a complex and legislation-driven market which acts both as a barrier to entry and a potential business risk to the company insofar as government intervention is always a possibility.
Back in May 2021 Morgan Stanley Infrastructure came forward as a bidder for the company at around 280p, followed by Eleia Ltd putting in a cash offer of 325p, which values Augean at c£341.2m.
This morning, Augean’s shares stand at 335p so there is a slight premium to the offer. Will there be more twists now that this company is ‘in play’? That’s what a share price above the most recent offer implies, although it can’t be relied on.
Financial highlights:
- Adjusted revenue before Landfill Tax -8% to £37.9m,
- Adjusted PBT +19% to £10.1m,
- Adjusted EBITDA +7% to £14.2m,
- Adjusted basic EPS +16% to 7.79p,
- Net cash of £6.1m excluding lease liabilities,
- Return on capital up from 44.9% to 46.2%.
The key market of Energy from Waste (EfW) treatment continues to trade well, with new contracted plants coming online. The application for an onsite EfW r-code solution at Port Clarence has been successful, which should increase the asset’s recovery capacity.
Treatment and disposal sales in total were also up 20% to £30.9m with strong growth across all waste streams. This was impacted by the pandemic so might recover further going forward.
North sea services (NSS) is in line with management expectations - but those expectations are for relatively subdued trading and revenue is down 55% to £7m. Total group revenue fell 8.5% to £37.9m.
HMRC - as noted above, the regulated nature of Augean’s markets are both an opportunity and a threat. While new entrants might be put off from entering this complex and highly regulated world, the flipside is that Augean is handling a long-standing tax dispute with HMRC.
To summarise:
- 10 December 2019, Augean paid £40.4m to HMRC to clear all outstanding Landfill Tax assessments. In 2020 HMRC subsequently repaid £1.4m relating to one aspect of the Landfill Tax dispute
- On 25 May 2021 HMRC issued a Landfill Tax assessment for £1.5m relating to time periods that had previously remained unassessed in relation to the Landfill Tax assessments. This was already factored in by management and had no impact on the income statement.
- On 23 June 2021, the decision of the preliminary hearing of the First Tier Tax tribunal heard in September 2020 was received, finding in favour of Augean.
- HMRC have subsequently applied to the Tribunal for a determination to extend or move the appeal period of the initial decision.
This kind of risk makes Augean uninvestable for some investors, understandably as it is a hard to quantify risk that falls to a degree outside of the company’s control. What can be said is that the direction of travel regarding this situation is positive. Perhaps it is the developments here that have sparked the bids, with some players now considering the tax situation suitably de-risked?
Balance sheet - looks healthy with consolidated net assets of £69m and net tangible assets of £49.2m. The current ratio looks to be around just 1x however, with £11m of cash set aside £28.4m of current liabilities. Perhaps you could argue that a larger cash pile is warranted.
Outlook - Augean is focusing on more growth in its core EfW and construction soils markets, although NSS will remain subdued for the rest of the year.
Conclusion
Full year estimates are for about 17p of normalised earnings per share in FY21, rising to 20.1p in FY22 as NSS business picks back up.
That would value the company on a PER of 19.7 falling to 16.7, which looks about right (but possibly even still cheap if the tax situation is fully resolved and the company sees good growth). It’s a strong business when it is not having to dispute tax cases, with barriers to entry and a portfolio of well located assets generating good returns on capital.
This tax has been paid but Augean is claiming it back and HMRC is looking to extend the appeal period for the initial decision. Compared to normal business operations that investors are used to, this looks like an extremely long-winded process. Overall though, the risk here has diminished.
Beyond that, there is no guarantee that a bid will go through - although this looks to me like the most likely course of action. In fact, the market thinks it is more likely that a higher counter-offer will materialise than for discussions to fall apart. Should Augean remain a publicly listed stock however, then it continues to be an interesting proposition in my view.
The shares are more expensive than they have been in the past, but there has also been good news regarding its tax situation and the fact remains that the group operates in generally attractive markets with scope for long term growth (in nuclear decommissioning, for example).

M Winkworth (LON:WINK)
Share price: 202p (+6.32%)
Shares in issue: 12,733,238
Market cap: £25.7m
(I hold)
We’ve spent a good deal of time discussing the franchised estate agency business model in the past but suffice to say it is a robust one, with high levels of cash generation, profitability, and returns on capital.
These companies have sailed through the Covid lockdowns much better than many expected and are currently going from strength to strength. All in all, these businesses look like solid long-term investment candidates. Stockopedia tends to agree.

They are exposed to the property market though of course, and so there are issues such as the withdrawal of stamp duty and future interest rate rises to take into account. It’s possible for the market to turn at some point, but it’s a very important market too, so the government does step in to support it.
While house prices and rental rates can fall, the latter in particular is sticky revenue that should ensure these businesses act as going concerns in the worst of times (assuming they do not take on overly onerous debt burdens, which has so far not been the case - they tend to be financially prudent).
Of the three listed plays often discussed, Winkworth is the smallest by market cap and is the most exposed to the London property market, so these are additional characteristics to consider.
In fact, the WINK spread reads as some 1,053bps and it looks like you’ll struggle to buy more than £2,000 in one go on the open market at quoted prices so I won’t spend too long on it. There could be some useful readacross for the rest of the market though.
Financial highlights:
- Network revenues +92% to £36.4m,
- Of this, sales revenue is up 195% to £24.6m and lettings is up 11% to £11.8m,
- Winkworth revenues +107% to £5.25m,
- Profit before taxation +330% to £1.98m,
- Cash up from £3.27m to £4.57m,
- Dividends of 8.3p declared (+169%).
Network sales revenue is up from 45% of total to 68%, so clearly this has been the star performer over the past six months. Management calls this part of the market ‘extraordinarily active’.
This upturn in sales started at the end of 2020 and carried through into 2021. It’s interesting to note that the uptick began, presumably, during the winter lockdown. A number of factors are at play here:
- pandemic-induced buyers searching for space and bringing forward moves to the country,
- record low interest rates, and
- government support, in particular after the release from lockdown.
Housing market transactions have been depressed since 2015, leading to the dominance of rental and management turnover over the last five years. Since the autumn of 2020, however, there has been a significant catch up in completed sales.
Peak activity for Winkworth was focused on the country markets. Outside of the internationally reliant central London market, the capital also performed very strongly though.
There was a divide in performance between houses and flats: the former more popular and the latter static, but there are now signs of recovery in rental which is expected to continue into H2.
Three new franchised offices opened.
Dominic Agace, Chief Executive Officer of the Company, commented:
While the first half of this year was marked by an exceptional level of sales activity, it also vindicated our strategic expansion in recent years into the country, enabling us to service clients not only in the buoyant London market, but also Londoners and country dwellers seeking more space or a change in environment. Our rental business remained strong, albeit on this occasion it was outshone by sales, and we are again encouraged by the number of applications from talented operators looking to work within our successful and well-balanced franchise model.
Conclusion
It’s a bumper set of results, not sustainable growth rates as it also reflects a flurry of activity ahead of changes in stamp duty, but investors will be more than happy nonetheless.
The company itself says:
The ending of the stamp duty holiday, the re-opening of foreign travel in August, and transactions due to complete in July having been brought forward to June will, inevitably, mean that some of the fervour will come out of the sales market.
The ending of stamp duty relief is being both phased and extended so the cliff edge situation some might have feared looks to have been avoided and sales applicants continue to track well ahead of 2019 levels.
Winkworth has made some recent moves away from the franchise model. I’d be wary of too sharp a shift but if it’s done in a controlled manner by the management team when it spots sites it can add value in, then it makes sense. Other franchise-heavy operators also split their business this way, selectively acquiring franchise units where appropriate.
More recently the group is ‘seeing a growing number of highly qualified, dynamic new franchisees joining us to take advantage of the opportunities presented by a revived market’.
It’s a great company and business model - probably too small for some and family-owned so it doesn’t really ‘behave’ like other stocks - but that might make it all the more appealing to the right kind of long-term investor.
The real elephant in the room, as ever, is interest rates. Underlying demand is supported by mortgage rates as low as 1%... But debating ultra low IRs could be turned into an entire book and many smart observers have got it wrong so far.
Tissue Regenix (LON:TRX)
Share price: 68p (-2.88%)
Shares in issue: 7,033,077,499
Market cap: £47.8m
(I hold - high risk)
This is a stock I hold but it’s not my typical investment - much more speculative, and with a dubious history regarding shareholder value creation under previous management. Attractive potential upside, with a greater urgency on product commercialisation and a strengthened management team, but persistent cash burn nonetheless.

As such, I took a small, high risk position with money I can afford to lose in the worst case scenario. I only stress that so as to give due consideration to the risks here, mindful that this is a widely-read blog.
Frankly, I’m not sure the level of risk to shareholders is being communicated in these updates. That’s not to dismiss the investment case, but it does make me uneasy. Shares in issue have ballooned from 743m in 2015 to over 7 billion today so the key risk is that the company reverts to type and further dilutes shareholders.
The group makes acellular tissue scaffolds for use in surgeries - it’s a potentially lucrative and highly regulated market with barriers to entry. TRX’s products are patented and well-regarded. Current applications for dCell address critical clinical needs such as sports medicine, heart valve replacement and wound care, while CellRight is used in spine, trauma, general orthopaedic, foot & ankle, dental, and sports medicine surgical procedures.
That bit’s good - patented products in highly regulated markets - but TRX must grow revenue for its shareholders. Covid disruption was unfortunate as elective surgeries have been put on hold. There are signs of improvement now - these surgeries will still be needed once hospitals are past dealing with Covid and so TRX is expanding its facilities just in time to capitalise on the backlog.
For now the key question is can TRX make it through this lean period without having to dilute shareholders further over the next 12 months?
Financial highlights:
- Revenue +12% to £6.8m (+21% at constant currency),
- Gross profit of £3.1m, gross margin steady at 46%,
- EBITDA loss down from £2.1m to £1.1m,
- Cash position down from £13.7m to £6.6m.
The key thing to look at here is the cash burn. Both government backed loans (part of the COVID-19 relief programme) have been forgiven, while a restructuring of US commercial operations provided savings of c.$350k in the first half.
TRX has a habit of realising significant cost savings, like pulling rabbits out of the hat, which is good from a cash conservation perspective but begs the question as to why these operational costs were there in the first place if they’re not needed now. A more positive spin is that this shows the more commercial focus of the savvier new management team, which is carving out a far leaner enterprise.
This quote stands out for me though:
Operating loss for H1 2021 reduced to £1.6m (H1 2020: £2.5m) and the group also has a strong cash position of £6.6m (H1 2020: £13.7m).
I would dispute that - this is the key risk for the group and it can’t be stressed enough in my view. Management might as well be upfront about it. There’s no shame in investing in products that can improve surgeries and quality of life but it’s often high risk so why don’t we just call a spade a spade?
Assuming that sales don’t grow and similar levels of cash burn are reported going forward, cash on hand would last for another year or so. That’s not a strong cash position, it’s a risky position, and that’s been known for some time.
Obviously investors are hoping for a significant pick up in sales, which is what management is guiding towards, but even so it will be a close-run thing. Also, included in the cash burn over the last 12 months is £2.1m spent on the completion of TRX’s Phase 1 capacity expansion, which is expected to meet production demands over the short and medium term.
So assuming no growth in revenue and similar levels of cash outflows is, hopefully, a pessimistic interpretation with scope for management to beat. Looking the other way, a pick up in revenue and reduction in growth capex following Phase 1 completion could quite quickly drive cashflow breakeven.
I note Hardman anticipated free cashflow and operating cash flow to both be close to zero in 2021. That was back in June. I struggle to reconcile that with today’s interims though, so will be interested to see if a new note is forthcoming.
Balance sheet - net tangible assets of £15.2m is fine, but, as above, with cash down from £13.7m to £6.6m, cash burn is the key point of focus.
Trading - signs of recovery in the Orthopaedic and Dental division, revenues up 26% (37% constant currency) to £4.3m, driven by the US market. US product shipments increased by 44% in H1 2021 year-on-year. BioRinse sales +26% to £4.3m (37% constant currency), again with improving conditions in the US. Germany, by comparison, remains more subdued due to lockdowns and a slower vaccine rollout, with sales flat at £1m. dCell sales were down 12% (4% constant currency) to £1.5m. Some positive signs in there but this needs to continue.
Two additional products were added to the Biosurgery portfolio, DermaPure Mesh and VNEW®. The DermaPure Mesh is a meshed dermal graft and VNEW® is a pre-shaped dermis graft. New product development and commercialization is encouraging.
Conclusion
I don’t mean to be too negative here, I just think management should be framing these results with a focus on cash burn and how the company hopes to manage its finances depending on various scenarios over the next year or so. Much more detail could be provided in this regard.
There’s an Investor Meet Company presentation at 4:30pm today: https://www.investormeetcompan... - I’ll be tuning in if there’s time to see if more detail is provided around prospects and upcoming cash costs as we are entering a critical period.
In fairness, my view here is due to the group’s track record of equity dilution under old management. The new team has gone a long way in cutting costs. Administrative expenses have fallen from £5.4m to £4.4m after cost restructurings at the end of 2019 and in January 2021.

Note: Interim Admin expenses
And there are good things here, namely:
- Sales up in US with improving outlook,
- UK vaccine rollout boding well for H2,
- Successful expansion of facilities and capacity,
- Ongoing product development and focus on commercialisation,
- Senior hires and greater depth of management,
- Patented products in a highly regulated market with strong barriers to entry.
Covid was a bad bit of luck for a company like TRX, obscuring underlying progress and temporarily halting revenue growth at a time when the company is loss-making and investing for expansion. Historically, growth has been hampered by capacity issues which have now been addressed. The upcoming 12 months could be strong for TRX - but they also need to be.
The focus now must be on driving revenue, broadening the product portfolio, and increasing market penetration. There’s a decent chance of this happening - Europe continues to be disrupted, although the UK should show better figures in H2 and the US is already recovering strongly, with US product shipments up by 44% - but even then it might be a close run thing with the existing cash pile.
The group says it expects ‘a significant increase in elective surgeries globally during H2 2021 and beyond’. It’s well positioned to capitalise on any such recovery following its capacity expansion, but it does need to happen otherwise another fundraise is on the cards.
I continue to hold, but it is high risk. Comparing it to M Winkworth above, for example, is like comparing night and day.

Again, that’s not to dismiss the investment case but just to draw attention to the risk profile here. Anecdotally, I feel as though this has become a bit of a trader’s stock (certainly more so over the time I’ve held) so I’m braced for volatility over that timeframe as well.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Previously described as having a "solid balance sheet and steady growth"(Simply Wall St) in 12/2020I have long held LON: SOM Somero Enterprises. This company has a very strong economic moat with hundreds of patents. The product is better than traditional concrete screed floors, more level, and takes less time to install, therefore a cost advantage. I watch the huge number of mainly internet commerce warehouses being constructed and it is these which require the laser levelling which Somero supplies. A 1 cm imbalance at the floor will topple a pallet at a 6 metres height. It seems to me that this is a strongly protected business in a growth market! And I particularly like the ROCE and ROE, the P/E ratio is higher than I would like at 19.2 but is forecasted at 14 for 2022. A class act with a strong future. Definitely good value for the longer term. methinks..
Morgan Stanley have upped their offer for Augean (LON:AUG) to 340p per share just before today’s close. Recommended all cash - no 20p contingent stub as per their initial offer.
https://www.investegate.co.uk/...
Over to you Eleia.
Gus.
I am not too happy with the way that the Board and Rothschilds have handled this. When you look at the Board's reason for recommending the original MSIP offer they seemed to me to be saying what a great purchase Augean would be for MSIP. Yes, we know that. What I am looking to be told is why I, as an Augean shareholder, would be better off selling out now rather than remaining independent.
Many thanks Jack for the write up on Tissue Regenix (LON:TRX) totally agree it's going to be an all or nothing investment but as you allude to the new management seem to have a good hand on cost.
If they ever get to the 68p you quote I'll buy you a beer, in fact at that price probably buy you the pub
Spectra Systems (LON:SPSY) (I hold)
For anyone interested in hearing from the CEO, here is a 6 minute video following Monday's interim results:
I notice there's been quite a big drop in the forecast EPS numbers showing in Stockpedia for Belvoir (LON:BLV) today. Does anyone have any insight into who these forecasts are from - it doesnt seem to tie with the Finncap numbers put out a couple of days ago?
Belvoir (LON:BLV), this does not look correct, might be worth reporting this to the helpdesk, as there is only 1 broker then it should tie up with Finncap's forecast? That is quite a fall, around 20%.
Here's the reply I got from the helpdesk regarding Belvoir (LON:BLV) forecast changes -
"It can be a little confusing, but the number shown for Analyst Consensus is for the recommendation (ie buy/hold/sell). There can be more analysts providing forecasts that don't provide a recommendation. For Belvoir, it looks like there are two brokers providing estimates.Unfortunately, due to a change in our licensing, we no longer get the broker names from our data provider Refinitiv (something we used to be able to do). Otherwise, I might be able to tell you who the other broker was apart from Finncap."
Thanks for that.
I can only find 1 broker covering Belvoir (LON:BLV). If the EPS has dropped to 16.6 is that the average for both or just the latest broker forecast? This information is less reliable now, as we don't know if the previous forecast has been downgraded or if it's just from another analyst.
I agree that Belvoir (LON:BLV) data looks off. The broker is forecasting a smaller drop but the CEO made the point in his Monday presentation on InvestorMeetCompany that the broker forecast assumed no further developments in acquisitions or partnerships which is very unlikely to be the case.
The Stocko page has 1 broker so odd response from their helpdesk.
I think FWIW full year 2021 EPS is likely to be 21p. It's cheap here for a reliable growth business in the world of TINA
The Stocko page has 1 broker so odd response from their helpdesk.
Talking of which, I had an exchange with the helpdesk yesterday about the P/B value showing for Urban Logistics Reit (LON:SHED) that I think is worth sharing, since it is another anomaly caused by how the StockReport numbers are updated.
The Urban Logistics Reit (LON:SHED) P/B shown in the SR is much higher than it is in reality. BTW This could potentially affect any company that has recently done a share placing to raise cash. I was told the number of shares used to calculate the Book Value per share is based on the current number of shares in issue, not the number of shares at the last report date, as shown in the Financial Summary section. Fair enough.
However, for Urban Logistics Reit (LON:SHED) the StockReport shows the current P/B as 1.51 when it should really be approx. 1.18. This is because the current number of shares in issue increased (from 219m to 325m) through a placing since the FY21 results, which raised £108m in cash. The SR calculation ignores the £108m increase in Book Value (it uses the last reported value) but it does use the new increased number of shares (325m) to calculate the Book Value per share. This means the BVPS is lower than it really is, which means the P/B calculated is higher than it really is, and this situation will only be corrected when the enlarged Book Value is updated at next interim results which are not until November.
I hope this makes sense and is useful.
All the best, Si
Pebble Beach Systems (LON:PEB) results i thought were strong.
PBT for H1 was 1m, but the FinnCapp broker note only has 1.4m for the FY. this is despite the fact that they say sales and momentum are strong and in H2 LY they made 0.5m. so me thinks that the fcsts have a high chance to be beaten. The broker already has a target of 20p.
The b/sheet here looks weak becasue they were lumbered with £12m of debt from the old vislink, if one looks at the underlying business it has been very CASH generative since 2012 (c.£1m p.a. and now is entering a growth phase). the company itself notes that PLC costs are c.£1m p.a.!!
interestingly the RNS states that because underlying sales momentum is strong, they are able to look at ways to 'now further accelerate further'.
disc i hold.
Regarding Somero - I've been an investing for several years (thanks to Stockopedia) and now hold a substantial (for me) position. So the results and Paul's comments can only be sources of delight.
However! Anyone who wants to plunge should check out the daily volume. As of now, I hold a position which often exceeds that figure. In other words, if I were to cash out, I would never come close to attaining my paper profits. I'm not worried because this looks like a winning situation, but my parachute is the belief that before too long, Somero will be the object of an aggressive and remunerative buyout offer. The volume risk will thereby be eliminated.
In the meantime, the returns are terrific.
dmcarver - re Somero and your own holding size - v - daily volume
Great investing point succinctly made
I think from reading several investors here on Stock that point is worth ANY investor researching and understanding fully, not just the newbies who may well learn it the hard way!
Good news from UAI £770m development project secured,should put a floor under their nav which according to Ennismore are significantly undervalued after clearing the decks & focusing on cutting costs.
Pebble Beach Systems (LON:PEB) - Good Interims this morning from Pebble Beach Systems which shows order intake strong, revenue back to growth, decent cost control and profits (PBT) for the half year almost at the level of FY 2020.
Importantly, net debt is fast reducing, as the company continue planned loan repayments and now are able to build some cash reserves also, which could be deployed in new growth opportunities or to accelerate debt repayment.
finnCap retain their 20p PT, but see potential for upgrades, along with a strong set-up for FY22. My take is that the company were already demonstrating they were at the tipping point in 2019, as debt started to look manageable and the business was developing. Covid set this back somewhat, but I see in today's Interims, the promise again that I saw in 2019, and with decently lower net debt.
Concur with Paul, Somero Enterprises Inc (LON:SOM) superb results and upgraded forecasts. They are giving a results webinar next Monday 13th September at 2.30pm. Register here.
Property Franchise (LON:TPFG) acquires an 80% stake in mortgage broker The Mortgage Genie. Total consideration £490k. Last year they achieved Rev £950k PTP £71k they are confident of exceeding this for the next full year. Hear more at H1 results webinar next Wednesday 15th September at 12.30. Register here.
Reminder, £RAI H1 webinar with management at 10am this morning 8.9.21. Covers H1 and hopefully more on the on $249M US Navy Support Facility Construction Contract, or more like a framework agreement. Register here.
Here's the Headlam (LON:HEAD) H1 results presentation given last week by CEO Steve Wilson and CFO, Chris Payne. Video & podcast.
A new IPO is Blackfinch Renewable European Income Trust (BRET), closing 30th September. They are raising £300m to invest in renewable energy infrastructure assets. In this video they outline its strategy and target dividends.
Shortly to follow an overview video on £IES.
Bango (LON:BGO)
Would love it if Jack or Paul or Roland gets time to comment at Bango if they get a chance later in the week perhaps when it is quiet . Not really looked at this one before but yesterdays results piqued my interests. I had a quick look in the middle of the night when i couldn't sleep.
Plus points
Great growth
Top quality A+ customer list
Potential for fantastic operational gearing here.
It looks like the fact Apple have reigned back their insistance that apps cant use third party payment providers may be a boon for them if app sellers can use their services rather than apple pay.
Solid balance sheet.
I suspect they may have great anlytical data that has good value for others - selling this data may be the goildime for this company.
Negatives
Sales still modest relative to market cap - 7 mill this 6 months compared to market cap of £152 mill.
Based on value of transactions they deal with they make a ridiculously small amount - it is waht it is here.
Do they have a moat ? i know not - they do seem to be doing decent deals though so it seems like what they do does work.
As someone mentioned yesterday they have had funding from third party which has resulted in joint venture of which they only own 40% - are there dangers that the entity that is Bango here could be muscled out of the picture onm the cheap? Nothing to make me preume this could happen but as an uniformed person would be interested for more gossip.
How they earn their wonga is kinda opaque - its probably not scammy seo stuff - but payment providers are 10 a penny soo do they have what it takes to not get muscled out of their marekt by stronger bigger competitors.
summary
Would be interested what chartists have to say here - it does seem to have been bumbling along with nice 200p as a base for 6 months plus - that makes it a tempting punt play based on the newsflow near term continuing to be positive. No idea what MACD is (other than double cheesburger) but its red and minus 1 (ouch). I quite like that there doesnt seem to be any current ramping with regard to this share anywhere - its the kind of share i would expect would be ramped to high heaven - perhaps its had its day in that regard previously.
If nothing else it does seem like this company has the potential to go nice places - albeit its not really an area where i can judge how good their buisness model is froma robustness and future potential point of view. I am tempted to have a dabble i must admit so thanks to mcav82 yesterday for flagging this one up for further attention.
Would love it if Jack or Paul or Roland gets time to comment at Bango if they get a chance later in the week perhaps when it is quiet
If you take a look at the last comment on yesterday's SCVR I think you'll get a pretty good idea of what Paul thinks of Bango (LON:BGO) ...
timarr
I enjoyed Paul’s comment but it (mostly) amounted to “we don’t do growth companies on here”. That’s not strictly true since Pci- Pal (LON:PCIP) was enthusiastically covered only Monday and its financials are “worse” - from a value investor standpoint - than those of £BGO!
Nevertheless, it set me wondering why we can’t have a growth stock daily thread - most likely because of the relative dearth of growth in UK. This means that great performers like Alpha Fx (LON:AFX) and Bango (LON:BGO) close competitor Boku Inc (LON:BOKU) are under-covered on here (I hold both for some time)
As for Bango (LON:BGO) - it’s a BUY for this growth investor on my metrics and I added this morning. Not only is the valuation substantially below the sector but this is not just a payment play. Bango (LON:BGO) provides rich customer data alongside the payment processing to improve ad performance for its customers - hence the importance of Apple’s data clampdown for which Bango (LON:BGO) offers an alternative source. In this regard it is more like an adtech or social commerce provider, think Tremor International (LON:TRMR) or Dotdigital (LON:DOTD) (again, long time holder).
BnB
"Nevertheless, it set me wondering why we can’t have a growth stock daily thread - most likely because of the relative dearth of growth in UK."
I think the best thing is really simply to add some comments on the daily thread and hopefully that will generate some interest. I think there are plenty here that like growth ata reasonable price which may not exactly be cheapo if well into double digits.
As far as the specifics of flagging up future prospects quickly when news is released for growth companies its so much harder to do quikc formal writeup as most of the value aint in the numbers - albeit i am always super keen to see where the trend lies in next years and the year after thast (if available) expected change in figures - is growth matching expectations.
Ref Bango thanks for your comments.
Bango (LON:BGO)
" In this regard it is more like an adtech or social commerce provider,"
That was slightly my worry as i am not really a fan of these companies where revenue is opaque and profits can disappear down a rabbit hold rather quickly depending on how facebook/google and apple feel. Would you agree that with their payment platform thingymabob that they at least have something useful and tangible as far as their customers are concerned - there does seem to be something more to bango that simply being clever as seo type nina stuff.
Revenues from data monetisation (launched 2019) are only now becoming material for £BGO. What you are seeing in the numbers, especially historical, are revenues from payments and, especially, subscriptions, where more services are becoming bundled into bigger deals. The core service that Bango provide here is to broaden the addressable market for its customers, be they OTT broadcasters (eg Amazon Prime), games developers (Microsoft), digital wallets or online trading platforms, into the "under-banked", which is a lot of the developing world and a good proportion of the under 18s - not just sub-prime customers,
Meanwhile, if you are nervous about data monetisation as a revenue source then I suggest you look at the stock charts of Alphabet and Facebook!
Bango (LON:BGO)
Thnaks for your added thoughts BnB
"Meanwhile, if you are nervous about data monetisation as a revenue source then I suggest you look at the stock charts of Alphabet and Facebook!"
I am not worried about that as you say its a great niche !!!- my worry was more with regard to companies that may be "directly" over reliant on google/apple or facebook for their income streams - for example XLM went into meltdown when their websites were black marked by google. It does seem that Bango does not seem to be as directly reliant on the generosity of the big boys as a company like XLM so it all looks reasonably good in that regard - ultimately they are providing a service that should be in high demand by their customers more direct B2B necessary services rather than benefiting via thir part individual random passthrough skimming off the bottom line kinda stuff (well not so much anyway).
Hi - I think the more relevant aspect to the data monetisation aspect for Bango (LON:BGO) is that they are anonymised and aggregated and do not rely on cookies. So in a post cookie world, which is where we will be in short order they should be a material winner.
The moat is pretty big though never insurmountable, it costs a lot and takes years to develop a platform that processes transactions reliably and quickly and able to rapidly scale. The fact that so many blue chips now use them tells you they are highly regarded and this in of itself make the moat bigger and deeper. They are still winning business at a clip.
I really like them and have owned since sub 100p. I still consider plenty of upside as I think they have now firmly moved into positive cash generation and very high operational gearing. Looks like brokers are penciling in 260p as 12 month target. Personally I am looking for closer to 300p.
I heavily suspect they will be on the end of a bid at some point, which I also suspect means I may not see the ultimate upside so I hope that doesn't come to fruition any time soon, but its probably a great fit for a US IT or data aggregator alas.
Hi BnB,
I enjoyed Paul’s comment but it (mostly) amounted to “we don’t do growth companies on here”.
That's not what I meant. We write about companies that we can understand readily, and have a meaningful stab at valuation. That includes some tech companies.
Say with Pci- Pal (LON:PCIP) as you mentioned it - the business model is very simple - winning lots of recurring revenue, long-term sticky contracts. So a very predictable and rapid rise in contracted recurring revenues. Hence very simple to see a route to profitability. I can understand that, hence I can form a view on it.
With £BGI I feel less confident about analysing the future of the company, because I don't know anything about payment intermediaries taking a tiny slice of pass-through revenues. Are those contracts sticky? Could a competitor offer an even lower % fee to take the business away? Its much more complex, and I think needs more specialised knowledge to understand the business. Hence why I don't feel able to add much value, so would have preferred not to have been sucked into commenting on Bango at all, but Derek poked me with a stick, and I rose to the bait LOL! ;-)
I can't tell you how frustrating it is when Jack & I are both busting a gut to get through loads of company updates, trying to find the most interesting things (e.g. profit warnings, ahead of exps updates), lovely GARP shares (like Somero - I hold), then we get to the reader comments and find people belly-aching about why haven't you covered this or that random share that I happen to hold, etc. It's demotivating & really winds me up, which is counter-productive because then the temptation is to just walk away and enjoy the sunshine instead.
We can't cover everything! So we write about things we understand, that look interesting from a value/GARP investing perspective.
Good idea about setting up separate threads for tech/speculative type shares, because I don't want to suppress any discussion of shares you might find interesting. It's nigh-on impossible already trying to cover 500+ companies in the SCVRs, so we do our best, but it will never please everyone. For comprehensive cover, we would need at least 5 people, with different sector specialisms.
Thanks, rant over!
Paul.
Thanks for taking the trouble to reply, Paul.
It's entirely logical, as you say, that poring through the reports of pre-profit growth companies - my field of interest - doesn't play to the well-honed skills and instincts of a value-focused analyst. It's more about assessing the market opportunity. Is the TAM expanding (Alphawave Ip (LON:AWE))? How good is the product and what need does it address? Is the service supported by regulation (Pci- Pal (LON:PCIP)) or unusually sticky (Darktrace (LON:DARK))? Can management execute?
It'd be great to have a regular thread as lively as the SCVR for the discussion of such names. "UK Growth Report" or some such, but it would need an analyst/moderator of your capabilities and energies and there's only so much time in the day and, presumably, money in the budget.
Thanks BnB, I appreciate your reply :-)
Best wishes, Paul.
Hi Rmallee. re BANGO. I think I mentioned Bango and BOKU as being a couple of interesting plays when I first joined Stokopedia 18 months ago. I said not to be confused with names of dogs in 101 Dalmatians. They both have nearly tripled in value since then. On the plus side neither have debt, but neither do they have much in the way of assets. I think the time for a punt was then at 85p not so much now with pe of 45 and 65 respectively. I don't think there was much ramping going on then, they just looked an interesting play at that time. Bango I remember did a very good deal with a big Korean telecom who bought a chunk as part of the partnership. They have both done extremely well. The question is where do they go from here? Bango have already touched these dizzy heights once a few years back. This sort of telecom technology is very much a here today gone tomorrow sector. I got out because I felt they have done the going places pretty well. May go further, but the the higher you go the bigger the fall, as they say. I wouldn't be tempted to buy back at these prices
Interesting comment. I top-sliced Boku Inc (LON:BOKU), having enjoyed the ride up from 80p, to buy Bango (LON:BGO) which I believe is relatively undervalued. I think the opportunity persists because of three factors. In the developed world telecom carriers are bundling services to enable platforms to expand their reach, eg O2 bundles Disney+ in the UK, in ways that fit those for whom the smartphone is the epicentre their life, ie the young, of whom there are rather a lot. Secondly, the developing world is bypassing the journey through banking and credit to a smartphone-centric financial identity - and there are a lot more consumers there than here! Thirdly, reports suggest that the data monetisation is proving more valuable than anticipated to Bango's partners, particularly as cookies are retired and Apple seals the vault on your data.
I could be wrong, and for that reason I'm not an all-in type of investor. I have more than 10 holdings just in payment processing.
Bango (LON:BGO)
I think the time for a punt was then at 85p not so much now with pe of 45 and 65 respectively. I don't think there was much ramping going on then, they just looked an interesting play at that time.
I tend to avoid like the plague (NOW) companies at too early a stage in their development - i may well have missed the boat on this one in that regard with regard to the rise from 80p to 200p - but generally i am happy to pay a fuller price for a company that i know is likely to be at cashflow plus position + indication of real profits in the next 18 months - Bango appear to be well beyond that now.
Looking at the price over the last 2 .5 years they have mostly been trading at 130p plus on average - they may have spiked down once or twice (didnt everthing in covid) - but the 50% increase from the average level seems justified now the company has proved its on track for £14 mill of sales this year.
For companies morphing into profit the high notional p/e doesnt put me off in the slightest if i think the EPS can grow quickly - we have seen plenty of companies that have been well rewarded for churning out reasonably positive momentum in the last 18 months - don't know what forecasts are for 2023 but if its EPS in the 7.5p - 10p range then 400p shareprice wouldn't seem unreasonable to me if sales growth is well in double digits and margins are good. It seems like they have enough partnerships going on that there is plenty of potential in that regard .
So on a punt basis while the news is good i am now in it to win it (or lose it as the case could be) . But i may not hang around long if they don't show evidence of continued good progress - lets hope there is no brick walls soon in that regard.
This might be of interest as it gives more background.
https://www.proactiveinvestors...
Frontier Developments (LON:FDEV) may be outside scope of coverage here now, but finals today show net profit and EPS levels are way ahead of the forecast shown here on Stockopedia. Profit after tax for FY21 grew by 36% to £21.6 million (FY20: £15.9 million) and basic earnings per share increased 34% to 55.4p (FY20: 41.3p).
Always encouraging to see forecast turnover growth for next 2 years at this stage clearly stated. Forecast growth levels for 22 and 23 continue to be outstanding.
Re. Frontier Developments (LON:FDEV) , I agree - it's unusual to get such forward visibility from a company, but the issue here (as with most companies in this space) is the valuation: Their forecast range for FY23 implies a P/E range of 27-30 if my back of a napkin calculation is correct. I do hold but think I'll wait for the next downturn before adding.
Good interims from Pebble Beach Systems (LON:PEB)
Highlight for me was the free cash flow enabling a reduction in net debt - down £1.1m in last six months to £6.6m at 30 June 2021. (Pebble Beach Systems (LON:PEB) was the only part of the old Vislink to survive and has been carrying the debt of the collapsed parts).
Inventories have almost doubled in an attempt to mitigate worldwide shortage of semiconductors
Morning Paul
Can you please look at Inspecs (LON:SPEC) interims out today - lots of figs but need interpretation please.(I hold)
Morning bohenie,
I've not come across Inspecs (LON:SPEC) before, it's a new one to me. Seems to have floated on AIM in Feb 2020. Makes spectacle frames in Vietnam by the looks of it?
On a very quick skim of the figures today, I've seen enough to want to take a closer look at some stage. There's a fair bit of debt, it seems to have made an acquisition last year that's greatly boosted revenues. EBITDA has a fair few adjustments that need looking into
I'm on holiday at the moment, working mornings, but seem to have timed it badly, as a deluge of trading updates & results have come out. So I'm trying to rattle through the companies I'm familiar with, to save time (as looking at completely new things takes at least several hours).
I'll try to take a look at SPEC some time later this year, maybe on the next trading update. It's lodged in my mind though, so thanks for flagging.
Regards, Paul.
Somero Enterprises Inc (LON:SOM) I was worrying that the global supply chain problems would slow Somero Enterprises Inc (LON:SOM) down after an amazing run. However, the management are very bullish about their ability to manage the supply side. I am more impressed by this than the spectacular results that have already been achieved. This company is in a sweet spot with super management. It’s tech for the construction industry. One for the connoisseur!
Bakkavor (LON:BAKK) half year report reads well, but is it just carefully worded? They make fresh prepared food in the UK, US and China, so they’re happy that the UK is out shopping again, but have labour and supply chain challenges.
Significant improvement in revenue, margin and profitability, and a positive outlook for the full year
Edit: I hold
Private label manufacturing? No thanks!
Raw material inflation and wage cost inflation will hit their margins hard. They're not big enough to have clout over their raw ingredient suppliers. Not like the huge branded food companies. Nor do they have clout over their customers, which are large chains / supermarkets.
Similar to Mcbride (LON:MCB) but doing food instead of toiletries, but both private label and IMO likely to get very badly squeezed in the middle.
Strong set of interim trading results for small cap South East based estate/letting agent M Winkworth (LON:WINK) .
https://www.investegate.co.uk/....
Exceptional residential sales growth reported up 195%. Illiquid share that can be difficult to build a decent stake in but consistently decent results.
May also be worth picking the bones out of mid cap Dunelm (LON:DNLM) final results as a bellwether for the wider U.K. household retail sector and commentary on impact of supply issues etc..
https://www.investegate.co.uk/...
Gus.
My morning smallcap tweet: Eviscerating the cadever of copy
IXICO (LON:IXI) U and I (LON:UAI) accesso Technology (LON:ACSO) Ten Lifestyle (LON:TENG) Avon Protection (LON:AVON) Somero Enterprises Inc (LON:SOM), Halfords (LON:HFD)
IXICO (IXI) contract to support trial worth over $500k. [SP=78.16 Cap=38m]
U and I (UAI) planning granyed for Morden Wharf, U+I and Morden College's £770m Gross Development Value project. [SP=81 Cap=102m]
Accesso Technology (ACSO) ups FY21 rev guidance tp at least $117m and 'cash EBITDA' (?) significantly ahead of market expectations. [SP=828 Cap=341m]
Ten Lifestyle (TENG) guides FY(Aug) net rev down 21% (in line) and adj EBITDA only marginally below previous year's £4.8m, despite significantly lower net rev. [SP=105.01 Cap=86m]
Avon Protection (AVON) US Army 2 year contract worth up to $87.6m. [SP=1793.71 Cap=556m]
Somero (SOM) strong H1. Div 9c up 125%. Guides FY(Dec) rev $120m and adj EBITDA c.$42m. [SP=475 Cap=266m]. hold,
In line: Halfords (LON:HFD)
Jack put me onto Tissue Regenix (LON:TRX) a few months ago and it looked interesting at the time.
The SP has not done a lot, sub 1p, and way off its pre Woodford days of around 20p.
Todays half year report does not appear to have much substance to the untrained eye
Revenue up 12%
Profit up slightly
New products launched
increased business in the US
Worryingly money in bank 6.6m Vs 13.7m last year.
Is it jam tomorrow or egg on face time
Thoughts appreciated Jack if time allows.
I see that Tissue Regenix (LON:TRX) cash reduction is after two US Government backed Covid loans were forgiven. I don’t see the amounts listed but clearly the cash bleed would have been worse without them.
Hard to see them funding more growth without some more cash.
https://www.proactiveinvestors...
Interview with CEO and CFO, looking for 4Ss, they seem pleased with progress even if the market isnt
Somero Enterprises Inc (LON:SOM) record interim results out today and they have also raised full year guidance.
Somero Enterprises Inc (LON:SOM) - Great set of results. Revenues upgraded again, from a previously upgraded US$110 to US$120 and EBITDA to US$ 42m from previously upgraded US$35m.
So, EBITDA margin increasing significantly with scale.
They are also very positive on outlook. Expanding both by virtue of a broader product set (now 18 products) and expansion into new geographies,
I love the emphasis on sustainable long term growth.
With an EV of approx US$ 326m, the EV/EBITDA for year end works out at about 7.8, which seems very cheap.
I think the tailwind from the demand for warehouses and data centres (where level floors are of great importance) will help sustain growth going forward.
RE: Somero Enterprises Inc (LON:SOM) interims
EPS for first six months has matched that for whole of FY20! Impressive increase in Gross margin too. Very pleasing results.
All the best, Si
Somero Enterprises Inc (LON:SOM)
You have to say these are a barnstorming set of results here , well done managemnt and employees alike for putting in the hard graft when they have been super busy.
Being honest they have probably had a perfect set of tailwinds in their favour here regards everything - they have even benefited (presumably) from prior pre covid backlogs that probably related to the really wet winter that delayed everything in the US winter 2019 or was it 2018. I must admit its probably impossible to project the future here but they will doing very well to keep this momentum up going forward - thats beyond their control somewhat though and all they can do is run their business sensibly as they do do (ron).
Shoutout to the legend that is Jack Cooney - well done sir. He sensibly (he is 73 now) cashed in most of his shareholding a couple of years back - to his credit he has since then driven the business forward and increased the shareprice. One always worries when main bods cash in their chips but he did not cash out at an opportune peak. I would guess all the pillars are in place for this company to be well run when he eventually hangs up his boots - hey ho plenty of time left yet as he is 12 years younger than the non executive chair - Perhaps he can take that role in 12 years and the non exec chair can hang up his books 2033 if he so choses.
One slight disappointment was that only one sky screed has been sold - they have the new sky strip and the as yet unamed new product that is now developed and will launch soon. I must say they do seem to generate the vast majority of revenue from the core old skool machines they have. So progress into new lines is slow and gentle at best i think.
Nice to see they have upped their game seo wise too - last time i did google search for "somero sky strip" the lovely lines i got from the first facebook page linked were not those of the skystrip itself. Ms Skystrtip does not now make page 1 on that search - although that may be google marking me down as soomeone who goes looking for building machinery plant pictures rather than the other kind of you know what.
What is fair value here ? i did accidentally sell earlier this year as i had a limit order in at 470p and they released an ahead of expectations update that caught me out. I did manage to buy back in same day though (luckily costing no more). so whilst i previously had this as a sell at 470p having bought this as a bottom fishing exercise i think for now something around 550p seems a reasonable valuation as they have upped upped and upped again. Somero is currenly my 12th largest holding so could end up with a bit of trimming round the edges if it does continue to appreciate in value. In the meantime i have a nice dividend coming my way with no nasty us tax deductions (sipp is the way to go here if you provider lets you)
Somero Enterprises Inc (LON:SOM) is certainly an interesting business. It’s always labelled as being cyclical but, as you point out (others - Paul etc. too), the need for large warehouses with flat floors for high racking to serve the e-commerce market is not going away in a cyclical downturn. I think that Mr Market has not yet fully taken onboard this effect on SOM’s business prospects.
It’s not quite a “selling shovels to Yukon gold miners” scenario but it is a good way to get another angle to the e-commerce trend in my view and less risky than try to pick the next big thing in e-commerce retailers.
Generally a good dividend payer too (although as previously mentioned on here it’s a good idea to take care how you hold it so as not to lose tax to the US government unnecessarily on those dividends).
So, I remain a long term happy holder here and plan to continue to do so.
Somero Enterprises Inc (LON:SOM) - a growth note is they are increasing capacity at their Houghton facility by 50% at a cost of $9.5 million, which should expand the group’s revenue capacity to around $175 million.