Small Cap Value Report (Wed 9 Aug 2023) - BWY, LOOK, D4T4, TIFS, RM., HSP, PCIP

Good morning, it's Paul & Graham here!
Today's report is now finished. Sorry we didn't get all the stragglers done in the time available.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Rather a large wish list today of things we'd like to look at, so we'll do our best to cover as many as we can, but it won't be everything -
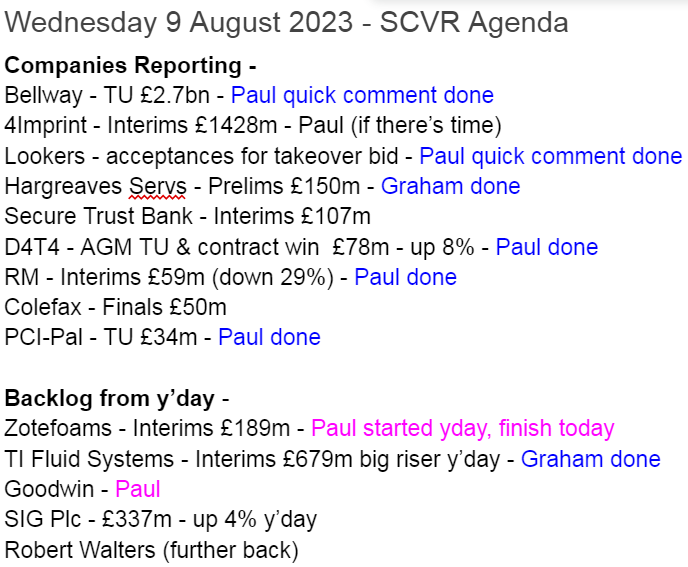
Summaries of main sections
Hargreaves Services (LON:HSP) - down 0.4% to 458p (£149m) - Preliminary Results - Graham - GREEN
This diversified group publishes a good set of results. Raw material profits are lower after commodity prices eased, but investors can celebrate a 12p special dividend on top of a 9p ordinary dividend. Management here strikes me as shareholder-oriented. Cheap valuation.
D4t4 Solutions (LON:D4T4) - Up 8% to 210p (£84m) - AGM trading update & contract win - Paul - AMBER
A low margin delayed contract has now been won, moderately reassuring. Outlook comments are vague, but sound confident, mentioning a strong pipeline. Overall, I think this company looks potentially interesting, but there's not enough to tempt me into buying any shares just at the moment.
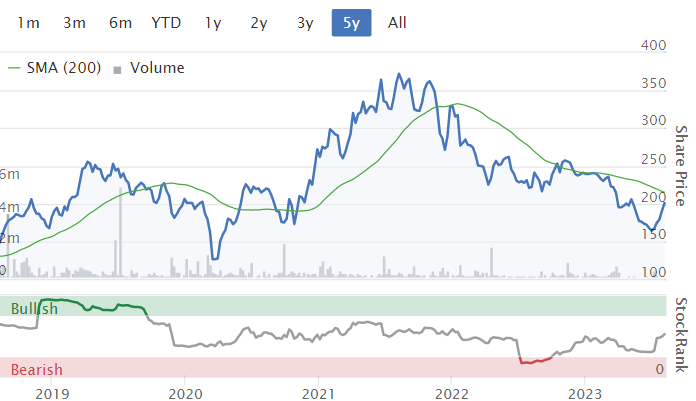
RM (LON:RM.) - Down 30% to 49.5p (£41m) - Interim Results - Paul - RED
Sorry to any holders of this share, but the 30% drop today looks fully justified. It's a worrying profit warning, combined with a very weak, overly geared balance sheet, and a going concern warning of "material uncertainty". I'd steer well clear, this looks way too risky.
£PCIP Down 1% to 51p (£33m) - Trading Update - Paul - AMBER
~A reassuring trading update for FY 6/2023, in line with expectations, but still loss-making. The ongoing patent case is consuming a lot of the cash, but a UK judgement is due shortly (the case being held in June). I like the good organic growth, and closeness to underlying breakeven, but I can't judge the shares until the Judge has spoken, and patent case is behind it.
Paul’s Section:
Some quick comments first -
Bellway (LON:BWY)
(mkt cap £2.7bn)
For read-across to other housebuilders, suppliers, and the economy generally. Key points in today’s trading update -
- Current trading impacted by higher mortgage rates.
- June & July - reservations fell back to similar levels as last autumn (28% down on LY)
- Pricing robust.
- Accelerating building of social housing, to partly offset weakness in private.
- Cancellation rate has risen from 13% LY to 18% now, rising trend.
- Good availability of mortgages, but problems with higher loan to value (LTV).
- Forward order book is down a lot, at £1194m, vs £2114m LY, down 44%.
- FY 7/2024 results, expect “material decrease” in completions.
Paul’s opinion - the market knows about these factors, and has priced-in weaker performance, which is why Bellway is one of several housebuilders now trading significantly below its own balance sheet NTAV. I’m taken aback by the 44% fall in closing order book though, which seems worse than the broker consensus of a 19% drop in revenue for FY 7/2024. So I’m worried there could be another round of downgrades for housebuilders, which might mean the recent rally could be short-lived perhaps? I’ve not seen any updated broker notes yet though.
It’s starting to feel as if a sustained recovery in housebuilding shares is looking premature, so I’ll continue to sit on the sidelines for now.
Lookers (LON:LOOK)
Another update today on the level of support for the 130p recommended takeover bid. It’s at 24.8% now, following further sales in the market by J O Hambro. The market price of 128.6p again looks attractive as a point to consider following Hambros and bank some profits, since the level of acceptances isn’t high enough to make this a done deal. As we saw last time, the downside risk is c.20p+ if the deal falls through, but there’s only 1.4p upside from hanging on for the full 130p payout. Is another, higher bid likely? Who knows.
I’m cooling a bit on the car dealers sector, because the impact of higher interest rates can in some cases be quite serious for profits. The stated net debt is usually not high, but in some cases they rely on large additional borrowings for funding inventories (vehicle stocking borrowing facilities), which could become a lot more expensive perhaps? Also freeholds have probably fallen in value a fair bit. Disclosure: in this sector I hold Vertu Motors (LON:VTU) personally.
D4t4 Solutions (LON:D4T4)
Up 8% to 210p (£84m) - AGM trading update & contract win - Paul - AMBER
D4t4 Solutions Plc (AIM: D4t4, "the Group", the "Company", "D4t4"), the AIM-listed data solutions provider, is pleased to announce a contract win with an existing banking customer.
The contract was one of the two contracts previously mentioned which were expected to have closed in FY23, and includes a high proportion of low margin hardware which is expected to be substantially delivered in the first half of FY24. This contract win accounts for a large proportion of the revenue shortfall from FY23.
That’s reassuring rather than exciting, I think. I like it when delayed contracts are announced, as then you know it was indeed just a delay, and not an undisclosed cancellation.
It’s a March year end, so FY 3/2024 currently. I wish everyone would use the month and the year when referring to financial years, it’s so much easier and clearer, and would save us having to remember them all, or look them up every time.
Outlook - too vague to place any reliance on this, I think -
At the Company's AGM at 9am this morning, the Chairman will confirm the Group has a strong pipeline and is highly confident in the Group's strategy to deliver growth and create significant shareholder value in the coming years.
It would be interesting to go back and compare the tone of the above with previous outlook comments.
Paul’s opinion - as we’ve commented here before, D4T4 does look an interesting company, prudently financed with plenty of cash, interesting-sounding services, churning out good profits most years.
The problem is the rather erratic performance, and it’s not clear if the company is able to generate structural growth or not. So how do we value it? D4T4 always strikes me as having a lot of potential, but leaves me uncertain about what’s likely to happen in future. I’d need to consult someone who knows the sector, uses the product, and understands how it works vs competitors. Without that detailed knowledge, investing in this is little more than guesswork. Nothing wrong with that, with a portfolio approach of similar shares, the odd one could be a big winner, and if we only pick things with solid balance sheets including net cash, then there shouldn’t be any complete disasters.
I see forecasts have been nudged down this summer, which doesn’t seem to suggest any immediate excitement. Forward PER of high teens doesn’t seem demanding for a tech company with plenty of cash. Could it become a takeover target perhaps? That’s possible I think.
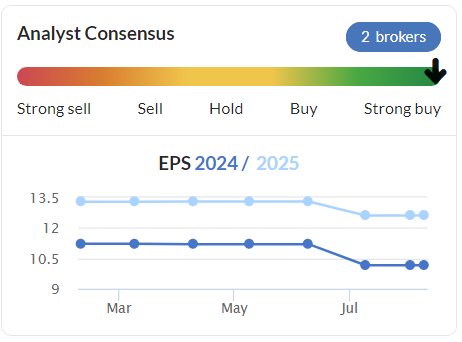
There’s been a strong recent rebound since July. For me, I don’t see enough here to want to get involved at this stage, the moment might have passed to pick up a bargain for now?
New management from 2021 seem to have negligible shareholdings. I prefer entrepreneurial, founder management, with big stakes.
RM (LON:RM.)
Down 30% to 49.5p (£41m) - Interim Results - Paul - RED
RM plc (“RM”), a leading supplier of technology and resources to the education sector, reports its half year results for the six months ended 31 May 2023.
I don’t really want to spend too long on this one, as it’s not very interesting.
Previously in the SCVRs here we commented -
29/12/2022 - AMBER - Asset disposals announced, helps lower debt. Worth a closer look?
29/3/2023 - AMBER - up 8% to 70p - FY 11/2022 prelims, profit down 65%. Wobbly balance sheet. Disposals. Possible turnaround? Special situation, quite risky.
H1 key numbers, for 6 months to end May 2023 -
Revenue £87.6m (down 10.5%)
Adj loss before tax of £(6.7)m, very much worse than a profit of £3.7m in H1 LY.
** Red flag ** Going concern statement indicates “material uncertainty” over banking arrangements.
Balance sheet looks awful to me. Take off the £74m intangible assets, and NTAV is negative £(13)m. Although it has raised useful cash from some disposals of intangible assets, so maybe we should include some value for these?
NAV also includes a supposed pension surplus asset of £19m, which note 14 indicates is an actuarial deficit, requiring £3.2m pa cash overpayments until end 2024. So we really should be manually adjusting the balance sheet further into the red, for the commercial reality as opposed to the nonsensical required accounting treatment that shows a liability as an asset!
The long-term bank loan of £53m is way too high, and increasing. Expensive now, too, given higher interest rates.
Outlook - the problems seem to be mainly in its “Consortium” business -
As we work to recover sales and win back the trust of our customers, we expect Consortium trading to continue to be below where we would expect it to be, impacting our expectations for the Group’s full year adjusted operating profit.
We now expect to deliver Group adjusted operating profit on or around breakeven for the full year, and in excess of £10million of identified annualised cost savings to benefit in FY24.
That’s a huge amount of cost savings, which makes me wonder what that money was being spent on, and why wasn’t it cut earlier?
Paul’s opinion - this looks a real mess to me. Turnarounds are fine when there’s a sound balance sheet with plenty of net cash. However, in this case, the bank is clearly breathing down their necks, and that puts equity in a very high risk position. At some point, I imagine a placing is going to be necessary, but on what terms, if they can get one away at all? Banks aren’t so accommodating, now that interest rates are higher.
This is a bright RED situation to me, I wouldn’t go near it, at any price - it looks far too risky. Institutions are high & dry, unable to sell, but private investors can get out - you may not like the price though, but sometimes it’s worth bailing out even if you have to take a few % points haircut on price. This would be one such situation I think.
PCI- PAL (LON:PCIP)
Down 1% to 51p (£33m) - Trading Update - Paul - AMBER
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, is pleased to announce a trading update for the year ended 30 June 2023 ("FY2023").
PCIP is only small, and has a significant (in terms of cost) patent infringement case ongoing. However, I keep an eye on it because I’ve been impressed with the decent organic growth, finally making inroads into reducing its annual losses - it could be near the tipping point where it becomes profitable, perhaps?
This is the latest today - the company’s headlines say -
Strong growth momentum continues - driven by excellent H2 new business
sales performance and continued high retention rates
My summary of the other points -
FY 6/2023 results expected to be in line with the Board’s expectations.
Revenue growth c.25% to £14.9m.
“Significant sales momentum” noted in the USA.
Still loss-making though, guided today at £(2.3m) at the adjusted PBT level, a tad smaller than £(2.9)m LY.
H2 was “very strong” for new contract signings.
Net cash looking tight at £1.2m (down from £4.9m a year earlier), with £2.0m of that due to the patent case - that’s a big financial burden, so a material issue.
Bank facility of £3.0m is undrawn, giving hopefully adequate headroom, although a small top-up placing of say £3-5m wouldn’t surprise me, at 10-15% dilution that wouldn’t be a disaster, but I would allow for that possibility when valuing this share.
Patent case - described as “unfounded”. UK trial happened in June, and now waiting for the judge’s ruling. Fingers crossed! I can’t remember whether there’s a USA patent trial too? Let me know if you’re more up-to-speed on this than me!
"We remain highly confident in our position on the unfounded patent claim being brought against us by a competitor, and we look forward to the UK court's ruling in the near future.
Paul’s opinion - I like the business, but don’t want to speculate on what might happen with the costly patent infringement case. As it’s a material issue potentially, I’m forced to remain at AMBER, as we have been the previous 4 times I’ve looked at PCIP this year. So investors buying or holding, are by implication taking a favourable view of the likely outcome of the patent case. The rest of us will be asked to pay more for the shares if a favourable patent case outcome is announced, or might get them cheaper if an unfavourable outcome arises.
Graham's Section
TI Fluid Systems (LON:TIFS)
Share price: 151.1p (+1%)
Market cap: £785m (€912m)
TI Fluid Systems plc ("The Group"), a global industry leader in highly engineered automotive fluid storage, carrying and delivery systems and thermal management products and systems for light vehicles, announces its results for the six-month period ended 30 June 2023 (the "period").
This large automotive parts manufacturer has been listed since 2017, starting life in mid-cap territory before dropping back to small-cap land:
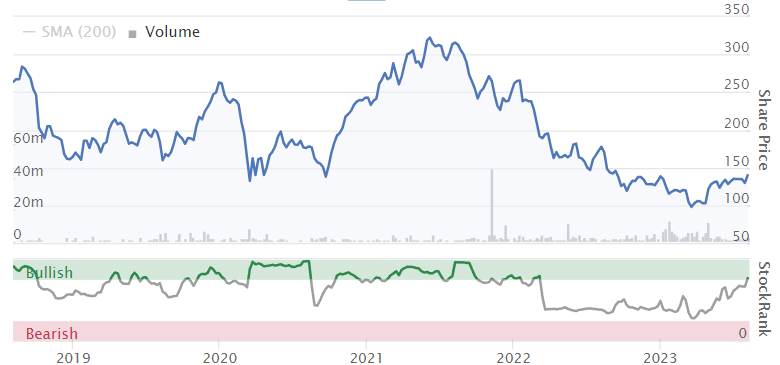
I’ve been positive on it (see articles in May and last November), arguing that its price to sales multiple was unusually low and that it had the potential for margins to recover. It had fallen into unprofitability during the Covid-related car production slowdown:

Here are the highlights from yesterday’s interim results:
Revenue +15% at constant FX to €1.8 billion
Adj. EBIT +58% to €132m
Actual operating profit almost doubles to €95m
After-tax net income €33m (H1 last year: breakeven)
So we have a modest increase in revenue plus an improvement in margins resulting in substantial profits.
As it has done before, the company says its revenue growth is outperforming wider trends in light vehicle production.
Cost recovery agreements were achieved with “a significant majority of customers”.
Cash/debt
One of the factors I identified as possibly dragging on the share price here was the substantial net debt being carried.
The company finished H1 with €440m of cash and €1.1 billion of borrowings.
But it has now made some very confident announcements regarding its financial plans:
1) it plans to pay €35m in dividends, similar to what it paid to shareholders pre-Covid;
2) it also wants to repurchase €40m of its own shares;
3) it plans to reduce gross borrowings by making a €100 loan prepayment, which will help to take a small bite out of its large interest bill.
It does have the cash to do these things, but is it wise?
Checking the latest cash flow statement, there is little sign of any free cash flow being generated.
However, the company must be feeling confident if it’s willing to take the three actions mentioned above. It says that it expects adj. free cash flow “to increase significantly as automotive markets recover and the Group's margin expands towards its medium-term target level”.
The outlook statement is bearish on global vehicle production, but is positive on the company’s ability to outperform the wider market and to generate cash:
We now expect full year adjusted EBIT margins to be above 7%, benefiting from operational improvements, ongoing cost recoveries and volume enhancements, notwithstanding continued cost pressures, especially from labour inflation. Adjusted free cash flow conversion is expected to be at the rate of approximately 30% of adjusted EBITDA.
Electric Vehicles - a key question mark for the company is how it responds to the transition to EVs. It maintains that it’s “well positioned to be a leader in the transition to electrification”. It is opening “e-Mobility Innovation Centres” across Asia and winning large deals, especially in China, relating to BEV/PHEVs (Battery Electric Vehicles, and Plug-in Hybrid Electric Vehicles).
I suspect that the risks around electrification are still substantial for this company, but it doesn’t sound like it is shying away from the challenge!
Graham’s view
I’m going to remain positive on these shares, as I think the bull thesis is playing out.
Revenues are recovering as vehicle production stabilises and price increases have been passed on with acceptance by customers. During this inflation, it has been a key theme that profit margins can be depressed in the short term, but can recover on a lagged basis as prices later adjust. That seems to be what is happening here.
The balance sheet could be healthier and perhaps it’s a leap of faith to believe the company’s claims that free cash flow will improve. But again, the bull thesis is not really looking for anything more speculative than a pre-Covid performance level.
The move to electric vehicles is a complicating factor and could be researched in greater detail.
On balance, I’m going to remain positive on these as I continue to suspect that the risk/reward on offer could be attractive. Worthy of further research.
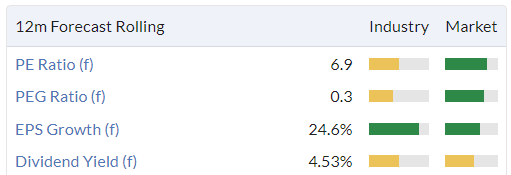
Stockopedia puts it on a PER of only 7x and a price to sales multiple of 0.28x. I think it’s reasonable to hope that this could get back to its 255p IPO price.
Hargreaves Services (LON:HSP)
Share price: 458p (-0.4%)
Market cap: £149m
Roland gave this one a comprehensive overview in January. It’s a group of many businesses - “Services” (earthmoving/construction), “Land” (brownfield regeneration) and “European Raw Materials”.
Today it has published full year results: revenues are up, but profits are lower. Last year’s results were boosted by very high commodity prices for the Raw Materials division.
Here’s the divisional breakdown, with the result at Raw Materials (“HRMS”) highlighted in yellow:
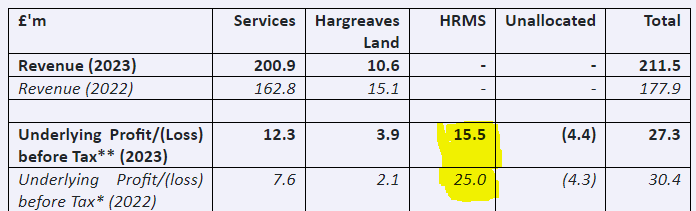
The table above shows profit growth in both the Services and Land division, despite a reduction in revenues at Land.
Delays have been experienced in this division, which are “reflective of the wider slowdown in the housebuilding market and therefore will only represent a timing delay”. Its flagship project has exchanged contracts and will generate £18.5m of revenues over three years.
Growth in Services is “due in the most part to the increase in activity on the HS2 contract”. This division has also signed various term and framework contracts with customers, giving it some visibility over future revenues while also protecting it from fuel inflation.
Comment by the Acting Chair (excerpt):
The growth of a robust recurring revenue base in Services is particularly pleasing and has provided the bedrock of performance for the Group. The outlook for the Group's operations for the coming year and beyond is strong with over 60 term and framework contracts and 70% of revenue for the year already secured.
Presentation: there is a presentation on Investor Meet Company at 4.30pm today. Here’s the link.
Undervalued land: land on the balance sheet suitable for wind farming and solar farming has a historic value of £6m, but has been valued by Jones Lang Lasalle at around £22m-£23m.
Balance sheet: the company is asset-rich with NAV of £201m, before adding on any gain from the undervalued land. Cash is comfortable at £22m. However, £15m may be needed to sell its pension scheme liabilities to an insurer.
HSP’s financial condition is neatly summed up by the Acting Chair:
“The Balance Sheet remains free from bank debt and third party security and continues to provide a strong and stable platform for growth.”
Dividend: the full-year dividend is 9p (last year: 8.4p). Thanks to cash coming back from the Raw Materials division, there will also be an “additional dividend” (why not call it a special dividend?) of 12p.
Graham’s view
This isn’t a company I look at very often (for sector reasons). It’s also not very straightforward to analyse, given the range of different activities in which it’s involved.
Nevertheless, I am coming away from these full-year results with a positive view of the company and its management. They strike me as shareholder-oriented, e.g. by sending surplus cash back to shareholders in the form of a special dividend, after temporary profits were generated by the raw materials division.
The CEO owns 8% of the company, so that might help to explain why it’s being run for the benefit of its shareholders: safely, without leverage, and with a focus on paying dividends.
The stock is also quantitatively very cheap, with a ValueRank of 90:
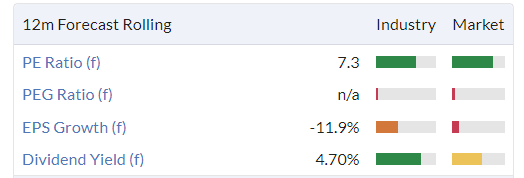
It passes five stock screens, including two which I really like: the Ben Graham Enterprising Investor Screen and the Neglected Firms Screen.
Are there any reasons for concern? Well, I would go back and consider the sectors it operates in. The HS2 project will not last forever. Raw material prices will rise and fall. House prices will remain volatile. The company itself might be high-quality in its approach, but the earnings it generates aren’t particularly high-quality, in my view.
Overall, I’m going to give this stock the thumbs up because I think it probably is worth a second look at this valuation, considering both the earnings multiple and the discount to tangible book value.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Paul, I didn't invest in GLOBO so I didn't lose money. Your articles helped me avoid the fraud.
Thank you!
Here you are! All my 29 articles on GLOBO fraud
https://docs.google.com/docume...
GLOBO results - all my articles -
https://docs.google.com/docume...
PCIP - I am a long term holder. The most reassuring part of the statement today was that they are already cash positive excluding patent case fees.
Well, who's paying for the patent costs then?
Hate this time of year, low liquidity, wide spreads, no buyers, distressed sellers. If you manage to catch a good one, the low liquidity can help. They are few and far between at the moment!
This time of year? In small caps that been the case for 18+ months without much sign of easing
Secure Trust Bank (LON:STB) H1 results today. Here is David McCreadie's, CEO overview video & podcast. There was a one off impairment of £7.2m which is said to relate to a 'long-running problem debt case with Consumer Finance', which has hit PTP which is £16.5m. (PTP before impairment +14.6% at £39.3m) but they do say that the aggregate cost of impairments for Commercial Finance since inception including this impairment is just 0.6%. The loan book growth is ahead of expectations at £3.2bn (22: £2.9m). New lending is at a record level at £1.16bn +2.4% driven by Consumer Finance where new lending is +16%. Dividend per share is 16p (22:16p). The broker still maintains CY23 PTP forecast of £43.9m and NAV per share of 1781p and TNAV per share of 1746p.
I know there is the odd Gulf Keystone Petroleum (LON:GKP) watcher on here although we don't normally cover O&G plays.
Their RNS this morning said that they had now embarked on local oil sales whilst awaiting the pipeline being switched back on (dependent upon government negotiations), with daily sales now up to nearly 12k BOPD. There is no timeline on the resumption of flows in the pipeline.
With a monthly burn rate on their ongoing overheads of some $6m per month then by my calculations the 12k BOPD would easily cover their ongoing expenses and hopefully recover much of the lost revenue since the shut-down in March.
This is obviously dependent upon the price they are getting, the risk that the daily sales may not continue and that the regulatory environment allows for this and that the up-front cash continues to be paid.
Basic maths on 12k BOPD and $6m per month burn rate means that even on a 20-day per month operating regime they only need to make $25 per barrel to cover their costs. (No idea if this is anywhere near accurate).
For me, its too late to bail out now, so I may as well hang-on and try to be positive about the situation.
Here's hoping it gets resolved soon and the SP recovers. I hold.
K
I replied to a post on this yesterday Kevin. I'm like you I guess in being stuck with my holding, albeit quite a small one in Gulf Keystone Petroleum (LON:GKP). I thought the RNS was re-assuring in that some on the forums seemed to have assumed that BOD were doing nothing except for holding up their hands shouting woe is me. It may take a while but the SP will surely fly when/if the oil starts flowing big time again. Cash is king in this type of situation and the company has enough to keep them going especially with the new small local sales which BOD did say they were trying to get going. I guess we just watch this space as IMO foolish to bale out now. This is when I cross my fingers!
I'm always in and out of O & G -depending on the cycle. GKP is always going to give an exciting/terrifying ride .Serica is starting to look even better value as nat. gas starts its dance
FUM: Futura Medical has gained commercial approval to sell its ED product in Saudi Arabia. Potentially a lucrative market. Wealthy consumers with more then one wife.
I'm waiting for Pauls green light on this one...
I've still got a couple of tubes left in my medicine cabinet.
If this share fails the skeptics will rub it in and say we told you - never buy jam tomorrow shares. If it succeeds it will be because plenty of users ARE rubbing it in!
More than one wife ?? blimey ones enough ! especially during the menopause !?
Steady! Let's not cross a line - this is the 21st century after all, not 1973.
Please remember we want more women subscribers here, so we don't want it to sound like an outdated elderly boys' club, if that's alright.
That'll be the 21st century where humour is banned
That'll be the 21st century where humour is banned
Your comment wasn't just misogynistic, it wasn't remotely funny
"outdated elderly boys' club " I think we've arrived. Is this really what I'm paying for ?
No idea what you are paying for. Only you can know that. But if you think you are paying for a space where people laugh at bad mysoginistic "jokes" you may find that's not what many of us are here for, or pay for.
On the car dealers, also wondering whether might be time to take profits. Have done well on Lookers (LON:LOOK) and Vertu Motors (LON:VTU) but they you née to remember they are very thin margin and cyclical, and also exposed to wage costs, so profits could vanish quite quickly. Continue to hold VTU mainly for the possibility of a bid, but strangely this one has never received any interest. Not sure what acquirers find attractive in the others but not VTU?
My dilemma as well. A slow down in car sales seems inevitable and yet a takeover is a real possibility
Don't forget that the dealers have a massive order book as a result of the chip shortages.
D4t4 Solutions (LON:D4T4) AGM and trading update (I hold)
Short but reassuring update. One of two delayed contracts has been signed. The contract accounted for the bulk of the shortfall in the last FY, much of which is low margin hardware (as opposed to high margin ARR software licences) and will be substationally delivered in the current period.
This is not a value share on current trading. 20x current year eps on todays 207p price.
The contract should help to underpin the forecast 32% (adj dil) eps growth in the current year.
The contract signing reassures that their products do sell but also that they don't have the ability to control when customers sign up.
The company is sitting on £17m of cash at year. Likely more now. And is highly cash generative. Margin and ROCE have dived but are now recovering whilst the company has transitioned to an ARR business model and new products have been launched. There is a lot of operational leverage here. Should the new products achieve traction as management expect based upon their sales pipeline, the shares will look to have been good value currently. But then again it may prove to be jam tomorrow, and sales traction disappoints. In which case the shares are probably fairly valued on current cash, cashflow and improving margins.
Personally I think that the products will gain considerable traction - which is why I hold and have been adding - I just don't know when and it always takes longer than I expect,
cheers
Mark
I'd be interested in the comments on RM (LON:RM.) I was looking at it primarily as its Richard Staveley's Rockwoods' largest holding and has just taken a dive down 21% on the day.
Obviously I DMOR - but Ive found that Richards is generally a bit better - so interested in thoughts.
I seem to recall Stavely's approach to RM was very much a "sum of the parts", taking each part of the business and applying a sector-relative multiple to each bit. This approach can highlight potential value, but there was an implicit assumption that each business would be fixed first and be operating on steady margins.
It is the old RM Resources (now called "Consortium") business where the "fix" is taking longer than expected (late platform deployment) and while they are fixing it, they are experiencing "a more challenging trading environment in schools".
Looking at the detail some of this is self-inflicted:
"Revenue in the UK decreased by 26% to £31.8m (H1 2022: £42.9m) driven by lower trading volumes in the Consortium business where revenues were impacted by lower customer volumes and decreased spend following the disruption of last year’s IT implementation."
I can vouch for the "trading environment" with 2 kids in primary. With teachers striking morale is low, budgets are still in disarray post-COVID (many schools in deficit) and in some parts of the country you have a population shift such that primary schools are under-subscribed (in London some boroughs are closing/rationalising schools). It is not an environment where schools are going to spend any more than they absolutely have to.
With a new CFO joining, his first priority will be to focus on the banking covenants. The Going Concern section contains the following:
"If the Group were unable to mitigate sufficiently the reasonably plausible downside scenario case and were also unable to execute further cost or cash management programmes, in addition to breaching the EBITDA covenant as noted above, the Group would also be at risk of breaching its hard liquidity covenant during FY24."
Turnarounds are risky and you usually lose money before you make it!
RM (LON:RM.) I annotate my charts and I wrote "Paul: "debt looks a problem", "sum of parts = £2 (Rockwood)" "new FD soon". Paul kept me out of this (thanks Paul!), but I just wonder whether the new FD is kitchen sinking the figures. Any thoughts?
Thanks Funnymoney.
A point I want to keep drumming home, is that banks didn't bother much about overly indebted companies when interest rates spent 15 years at zero.
The banks could just sit back, and let the zombie companies trade their way out of trouble.
Investors got used to this, and forgot about risk. Often the highly dangerous investments multibagged.
Things are very, very different now. Base rates have gone up from nothing to 5%. With lending margins, we can see problem companies now having to pay their lenders c.10-15%, just to stand still.
Equity holders could get some really nasty shocks.
Please be VERY careful - the lazy assumptions about excessive debt over the last 15 years, now are badly wrong.
The SCVR will become an increasingly useful tool for you to avoid, or at least be aware of, dangerous debt, in the coming months. Make sure you listen to us! Then it's up to you to decide your own risk:reward.
But a big hike in interest rates from nothing, to 5%, is exactly what you need to be careful of.
I've already heard some horror stories of banks pulling in lending, and leaving equity wiped out. Remember that equity ranks behind debt. They can pull in the security, and equity can be left with nothing.
Please be careful! Indebted companies are now very high risk.
Regards, Paul.
I see Harwood Capital are one of the top shareholders in RM (LON:RM.)
This makes me stay away as they have form in the past to be a bit predatory when companies are in a weak situation. I wouldn't be surprised if they pushed for a deeply discounted fundraising, only institutions allowed in (ie Harwood).
Harwood are shrewd investors. I'd rather have money in their funds, rather than alongside their funds in RM.
That's a very good point, Boon.
Small shareholders in RM (LON:RM.) could well be left high & dry, with a refinancing whereby Harwood strip the cupboard dry for themselves in an emergency - as you say, they've done it before.
Small shareholders can get out and take a haircut.
Harwood can't sell, so they might shaft you! Why take the risk?
He can't sell! We can.
Volex (LON:VLX)
Interesting announcement regarding its relationship with Tesla. Not sure whether it adds anything to the investment case, which I consider to be very positive.
"Volex plc (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, is pleased to announce it is a licensed partner of Tesla for the North American Charging Standard ("NACS") EV Charging system. Volex is a selected global manufacturer of the authentic NACS coupler and is stocked and ready to immediately supply automotive OEMs and charging infrastructure suppliers.
Nat Rothschild, Executive Chairman of Volex, commented:
"As a selected supplier of the NACS coupler, this further validates that Volex continues to be the trusted manufacturing partner of Tesla's charging system technology to the world's leading EV manufacturing companies and suppliers who utilise the NACS EV Charging system."
"Volex" All legacy auto makers in the US have stated that they will be changing to this standard (NACS) from 2024. Tesla developed this standard. I see this play a bit like Beta Max v VHS. It seems this standard will be the way forward in the US at least. Given the number of Tesla's on the road in the UK and Europe I would be very surprised if it was not adopted this side of the Pond.
Market seemed to like it for a bit and then didn't, I assume because, as you say, it didn't add anything to our database of knowledge so, to some degree, it was factored into the SP. Great to see it confirmed though.
Volex (LON:VLX) (I hold). IMO this is a retest of the previous resistance. The price jumped up to the resistance at 324p. Traders taking profits. I’ve just added at 306p. It may retest 298p but my price target is 396 as shown.
Ps. Low volumes in the selling in the last few hours.
Interesting that the drop in price of Bellway (LON:BWY) is very limited so far. A trading update with a fair few negatives in my opinion - one that had me braced for quite a fall (and elsewhere in similar shares in my portfolio). But instead we get a knowing shrug from Mr Market and a circa 2% fall. Admittedly on a day when everything else is up. But perhaps the indifference suggests that all the bad news is fully priced in to this sector.
Really encouraging results from Hargreaves Services (LON:HSP) . Lots of moving parts but lots of value. Trading at a significant discount to NAV with cash of £21.9m, no bank debt. Overall debt of £36.4m relates solely to leasing arrangements for earth moving equipment involved in HS2 contracts. This should unwind over time.
Appear to have found another £50 note down the back of the sofa in the guise of leases/rent from its land used for renewable assets recently valued at £27.2 to £28.9m but held on the balance sheet at cost of £6.6m. The intention is to realise the value from these assets and return the proceeds to shareholders over the medium term.
Lots more detail in the results including the proposed buyout of the two legacy defined pension schemes
I hold.
Thanks for your comments on house builders Paul. I have been looking at brick makers and the current prices of Brickability (LON:BRCK) and Michelmersh Brick Holdings (LON:MBH) are tempting but I haven’t taken the plunge because of the steep rise in mortgage costs. Once we see a possibility of rates being reduced I feel that buyers will be reassured to complete and there will be a strong rebound. However at the moment there is a great deal of uncertainty and prices could reduce further.
I'm watching them too, but feel a recovery in housebuilding (and therefore brick demand) might be premature. See some brick statistics from the UK government below.
Deliveries might be at the start of a recovery (the slight uptick in July 2023), however inventory/stocks are at significant highs relative to previous levels and therefore you might expect prices to have negative pressure for a prolonged duration as brick manufacturers clear that inventory.
Would be interested to hear if anyone has first hand knowledge about how brick prices are holding up in the market.
What worries me (as a previous holder of Forterra (LON:FORT) who would consider getting involved again at some point) is that both Forterra and Ibstock have new factories coming on line.
These are more efficient than the old ones, which they are closing down/mothballing. What is not clear to me is what additional capacity is hitting the UK market into a downturn. Yes, UK manufacturers should be able to supplant European imports as bricks are heavy things to shift.
But clearly if demand was there they could have kept the old factories running....and were the old factories not producing at a cost that was low enough to replace European imports (well over £100m in previous years I believe)? Yes - I know this is simplistic given different types of brick etc, but it does worry me.
What worries me (as a previous holder of Forterra (LON:FORT) who would consider getting involved again at some point) is that both Forterra and Ibstock have new factories coming on line.
Unlike all you big brained value investors I don't have the confidence to buck the market. In my experience, the market is the best economist/investor in the world and it took a good look at Forterra's profit warning recently and decided, amidst some volatility, that all the known problems were priced in already, ie the productive capacity of the brickmakers is well understood.
As for unforeseen troubles, that's another matter.
Forterra was one of those stocks I exited some years back when I decided to lower my portfolio exposure to energy-intensive companies, as hedging only protects you temporarily. I try to avoid trading in & out of companies, and I don't think many individuals buck the market consistently by doing so (firms with a systematic approach like Mashall Wace's TOPS may do for a while, but usually become a victim of thir own success).
In stocks with high liquidity I don't necessarily disagree, although I note Terry Smith had a pop at the efficient market hypothesis recently when discussing his holding in Philip Morris International (NYQ:PM).
In mid/small caps the marginal buyer or seller in tiny volume can still drive the price for quite a long time. If the most knowledgable buyers can't buy more (can Rockwood buy more RM?) and the marginal seller is an index fund, or a small cap fund forced to sell by investor flows, then supply & demand at a narrow point in time may not reflect any stock specific "view" at all really (other than any correlation with people buying or selling the market as a whole).
This is one of the areas where the private investor has an advantage over the institutional fund manager.
Thanks for the brick stats post ar7268 and for the other good posts. I have spent an hour or so researching this sector further, so thought I would summarise some thoughts.
Ibstock (LON:IBST) (was listed a long time ago and floated again in 2015 after PE ownership) are the #1, Forterra (LON:FORT) (originally Hanson and owns London Brick, refloated from PE owner in 2015) the #2 and Michelmersh Brick Holdings (LON:MBH) a fair way smaller at #4 in the UK. Wienerberger AG (who purchased Baggeridge Brick, if anyone remembers this) are #3 but Austrian owned and not listed. Turnover for the top 4 is c£500m, c£400m, c£300m and <c£100m. These are the brick producers.
Personally, I wouldn't touch Brickability (LON:BRCK) as its only a distributor and it was floated by Cenkos (which is often a bad sign). It also seems a tad over keen to promote itself.
Anyway, it looks like brick production was about 2.5bn bricks when housebuilding (55%) and repair, maintenance and improvement (45%) was going well. Worst case, it could probably drop to 1.5bn or so, or 40%+ if we compare with 2009. I'm going to keep Ibstock (LON:IBST), Forterra (LON:FORT) andMichelmersh Brick Holdings (LON:MBH) on my watch list from now on as they are good and very well established businesess, generating reasonable attractive returns over the cycle with barriers to entry and not over indebted. Gut instinct is that they have a little further to fall, as trading momentum is very bad, but Q4 or Q1 2024 could be a good time to get on board if and when recession is confirmed.
Hi topvest
Good post.
I listened to the recent Brickability (LON:BRCK) IMC presentation yesterday and found it most insightful. If you skip to the Q&A they'll answer why they have a place in the market.
Also just to let you know that Wienerberger AG (WBAG:WIE) are listed in Austria.
Cheers
A
This sector does look interesting and I will be looking closely at an entry point on FORT or / and MBH over the coming months. These are the types of cyclical sectors that I think (unlike many service companies for instance) are easier to back for an eventual recovery, underpinned for a long time in the future by supply and demand dynamics (and its essentially an oligopoly controlled market by the big players).
As you mentioned, Brickability is a different consideration, as they are just a distributor. However this could be a strength not a weakness. It seems that brick producers are somewhat reliant on Brickability's distribution channels and have struggled when attempting to cut out the middleman (this is according to the Brickability CEO - so perhaps taken with a handful of salt / or perhaps not). Brickability obviously add on a commission, but really they are not exposed as much to the market pricing forces like the brick makers are.
Having watched their recent presentation I was surprised to hear that bricks is now only about 50% of the business (they also said they are the market leader). So really it seems to me that they are more of a logistics company than anything else.
The ability to get the right materials delivered safely and on time at very short notice is a huge part of the business model. If the brick producers do struggle then there is nothing they can do but ride it out. Brickability will probably have less and less reliance on bricks in the future and therefore are more diversified - i.e. less exposed to just the brick market.
They are also able to grow the business via many other product areas and are not just reliant on growth in the brick market - this does seem evident by the numbers - Brickability have grown significantly in recent years compared to the brick producers (who are imo a lower potential return but a much safer bet). I think it may be useful to look at other building product supplier businesses to get an understanding of how successfully Brickability operates. I think comparing Brickability to some of these other building materials suppliers may be a more useful comparison than just comparing it to the brick producers.
cheers
Matt
Hi richardo ,
Research Tree have a new note on Michelmersh Brick Holdings (LON:MBH) from Canaccord. Sales of bricks exceeded production for 1st time in 11 months. I have held MBH for many years.
More good news for Volex (LON:VLX) as they are selected by Tesla to manufacture a NACS coupler. Not sure how big this is but it is certainly a vote of confidence.
Seems good to me. The North American Charging Standard (NACS) is how Tesla have charged their cars for many years but it was opened to other companies in 2022. In recent weeks several major manufacturers (Mercedes, GM, Ford) have announced they are taking it on as well for their cars from 2025. It’s going to be the preferred system for the US and significant expansion will be required.
I don't believe this is a new contract for Volex (LON:VLX) which is a longstanding supplier to Tesla. I read it more as a sales pitch and reminder to the other manufacturers who are now adopting NACS and to analysts.
"Volex is a selected global manufacturer of the authentic NACS coupler and is stocked and ready to immediately supply automotive OEMs and charging infrastructure suppliers." In other words: among supply chain uncertainties and shortages, we are your trusted partner as you convert to this new standard that your management team has just decided you will be using from now on. Choose us and you will look good, we know this tech and we're stocked up and ready to go.
Perhaps I am over-interpreting, but that's how I read it. There's no doubt it's good news and means more organic growth for Volex. They have a decade-long opportunity as the global auto industry electrifies. One of my top 5 holdings.
I agree, I think it's more of a sales pitch. Consolidation around the NACS standard is both a threat and an opportunity as standardisation potentially leads to commoditisation, lower margins and increased competition. Over to Volex management to show they can win in this growing but increasingly competitive market.
I wonder how many of subscribers first google this morning was ‘what is a NACS coupler !’
Volex (LON:VLX) - key component presume is Copper. Being in Turkey they may have local supply or at least access to supply from Russia. Long term when supply gets tight then the ability to deliver may trump cost.
On a random - you will know when the copper price is rising when they start nicking the cables connected to lampposts (remember old TV's were in demand and some risked railway lines). Sorry for the negs but the coffee needs to be smelt.
No longer really a small cap, but used to be. A few months ago I shared my success story of my second largest holding and now a 20+bagger in 4imprint (LON:FOUR) . Half year results out today, Revenue +23%, profit before tax +50%, profit margin now increased to 10%, interim dividend +54% (after a special dividend at year end as well). Very cash rich, free cash flow more than doubled on the prior year interim to $80.8m although helped by a notable movement in working capital. The defined benefit scheme has now been subject to a "Buy-in" for more future savings.
I acquired my current holding in 2011 which shows the value of patience in investing and finding a good company with management who delivers on their targets, which FOUR have.
But what do I know, I lost thousands on Globo! Lesson I learned is to always check the cashflow statement.
I actually sold on the latest surge as I was concerned that it might now or shortly run out of steam. But I won't be out for long if the SP drops back a few points as it's a great company and well done for getting in all those years ago. Maybe the coffee jar system does work!
I applaud you ! To be able to hold onto and get to that magic 20 ! .Ive had loads .....on paper, sold way too early
Hi wildshot,
You're probably the first to say you lost money on GLOBO
Most people tried to get me sacked.
Nobody apologised.
Paul.
Results out of TCAP today, I have a substantial holding. Slight increase in EPS, significant $£ headwinds, increased divi, long list of litigation risks from the acquisition of ICAP.
This is a bargain share with a huge yield, hence my holding. I think the results are OK, perhaps a fraction ahead of expectations. A takeover target, but the litigation risks may put people off. A Hold for me.
Thanks for your thoughts on TP Icap (LON:TCAP) , I agree; also have around a 10% position here. Rare to find a global leader in the UK mid cap range too. Previous interviews by Paul Hill showing institutions valuing Parameta at more than the current mcap of the company also gives some comfort for the long term prospects.
If there’s time for a review from Paul or Graham that would be much appreciated please? Mcap slightly over the upper limit for SCVR.
Colefax CFX
Ok results
Valuation remains silly
50 million m cap
20 million cash
9 million PBT
With the slight annoyance factor of well paid directors the share buyback and reduction in share count is starting to make this a bit silly valuation .
Might be headwinds but still think this is wrong price and the share buybacks will out the value at sone point .
I hold
Decent company, lousy dividend. Share buy backs don't appear to creating additional EPS. I would argue that the board needs to think more about shareholder interests. But you are right about value. One day the EPS should improve strongly.
Morning all,
Yes, nice announcement from Volex (LON:VLX) this morning. The good news flow continues!
Also from Warpaint London (LON:W7L):
The new leases mean that the Group now occupies the entirety of units A to E at The Ridgeway Trading Estate, enabling its head office, southern operations and the majority of the W7 warehousing to be housed in one location, considerably improving the Group's logistics.
Not material but interesting!
Looking at the futures, could we be in for a blue day today?!
Sylvania Platinum (LON:SLP) (which has taken a hammering recently) teams up with another mining company to do their tailings for them. Additional 6,500 4E PGM annually which is not insignificant to their total output. 2 out of 2 good news (hopefully) for me this morning.
The other major upside from this deal is Sylvania Platinum (LON:SLP) share of chromite concentrate amounting to 200,000 tons
https://swapx.co.za/chrome-ore...
Which as shown above is priced at around $300 a ton I’m not sure of the purity
Which unless I’m missing something could be up to $60,000,000 pre costs
Also Sylvania Platinum (LON:SLP) will be funding the whole project from its cash balance $32,000,000 and will receive 11.75% on the $16,000,000 it will lend LMC from the proceeds of the sale of production from the plant once operational
Working costs $5 million will also be financed by SLP on the same basis
Volex (LON:VLX) teams up with Tesla (NSQ:TSLA) , couldn't see any financial value attributed, but got to be good news
I vaguely recall Nat Rothschild saying in a webinar a while back that Volex (LON:VLX) (I hold) supplied Tesla already, and it was highly profitable he said. I don't really understand the significance of today's news from Volex about Tesla, they could have spelled it out better - does this mean more orders are expected?
The North American Charging Standard (NACS), currently being standardized as SAE J3400 and also known as the Tesla charging standard, is an electric vehicle charging connector system developed by Tesla, Inc. It has been used on all North American market Tesla vehicles since 2012 and was opened for use to other manufacturers in 2022. Ford, General Motors, Mercedes-Benz, Nissan, Polestar, Rivian, and Volvohave announced that starting from 2025, their electric vehicles will be equipped with the NACS charge port.
It looks like it could be a much bigger opportunity if they could get into some of the other manufacturers as well - dependent upon if they are limited in other commercial agreements or not.
Volex (LON:VLX)
Some discussion here today on what the Volex (LON:VLX) announcement may or may not imply for profitability. I think the intraday chart implies that initial excitement may have been overdone:
Probably more realistic to look at the move since Thurs/Fri last week, so +8% or so, rather than the days move. Looking at a weekly/monthly chart it looks pretty likely that some hints of the news (at least) had escaped. Quite likely some quick profits being taken.
Strange it offers no potential numbers but a vote of confidence if nothing else.