Small Cap Value Report (Wed 9 Feb 2022) - MNZS, SYS1

Good morning, it's Paul & Jack here with the SCVR for Weds. Today's report is now finished - quiet news day, and I'm off for an investor lunch.
Agenda -
Paul's Section:
John Menzies (LON:MNZS) - a cash bid approach, from a Kuwaiti infrastructure company at 510p (52% premium) looks very appealing. However, the Board rejects it, saying it's opportunistic & undervalues the company.
System1 (LON:SYS1) - Q3 trading update looks OK (in line with expectations), but a broker downgrade has taken the shine off things this morning. Difficult company to value, but there might be something interesting here, time will tell.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
John Menzies (LON:MNZS)
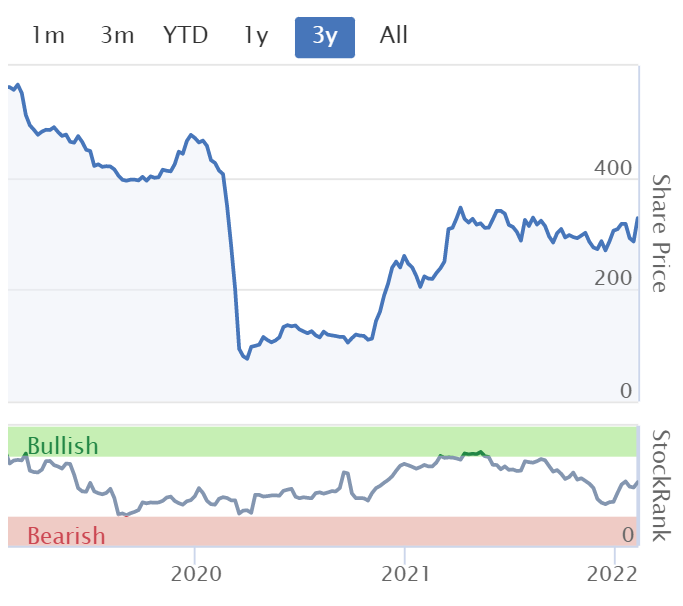
335p (pre market open) - mkt cap £294m
Rejection of Unsolicited Approach
Big news here for MNZS shareholders - the company has received a 510p cash takeover bid (up from previously, apparently undisclosed 460p cash bid) from a Kuwaiti infrastructure group called Agility. Agility’s shares are listed on the Kuwaiti & Dubai financial markets.
Having a quick look at the investor relations section of its website, Agility looks a credible bidder - and offering a full cash bid for MNZS, it’s not mucking about. 510p is a generous 52% premium - likely to be very tempting for MNZS shareholders.
I can’t see any previous announcements about a takeover approach, so it’s surprising that MNZS does not seem to have informed shareholders about the previous bid at 460p. This once again highlights how unsatisfactory the UK rules on takeover bids are - where shrouding bid approaches in secrecy seems to be the Takeover Panel’s main objective, with disclosure to shareholders only required if someone leaks it to the press. How ridiculous is that? Lord Lee recently tried to engage with the Takeover Panel on this matter, but they swatted away his valid concerns unfortunately.
Like many (probably most) investors, I think companies should be required to reveal to their shareholders, immediately, if they receive a credible bid approach. It should not be up to management to make a decision behind closed doors, whilst a false market in the shares exists (if the market has not been informed that a bid approach has been received).
The rest of today’s announcement from MNZS gives a spirited defence against the takeover approach, saying it’s opportunistic & undervalues the company - quite surprising, given that a 52% bid premium would normally look rather generous.
Here is what MNZS says, which does sound interesting. On the historic numbers I would say the bid premium looks very generous indeed - particularly when you take into account that MNZS has a very weak balance sheet, with NTAV negative at nearly £(200)m, with too much debt.. But if this turnaround information is correct, then maybe there could be better upside from MNZS remaining independent? Or maybe management just want to hang on their jobs & share options?!

My opinion - well done to MNZS shareholders. There’s obviously hidden value in the company, and ignoring the terrible, overly indebted balance sheet was risky, but has paid off in this case.
It’s likely to be a very lucrative day for shareholders! I imagine the share price is likely to rise vertically to close to the 510p bid price, as the bid looks credible. I imagine many shareholders would be happy to bank the profits at that level.
There's a lot of value in UK small caps right now, after some brutal price falls in the last 6 months or so, so I'm expecting plenty more takeover bids.
.
.
System1 (LON:SYS1)
375p (down 14% at 09:03) - mkt cap £48m
System1, the marketing decision-making platform, intends to issue quarterly updates for Q1 and Q3 of each year based on unaudited numbers. These updates are intended to keep investors informed of the Company's performance between the interim and final trading updates and results announcements. System1 today issues the following update on trading for the quarter ended December 2021 (Q3).
Bravo to that. Investors want to receive updates about how their companies are performing, so I like the concept of a regular, quarterly update.
It’s an in line trading update -
Profitability was in line with management's expectations and reflected an increase in expenditure on people and platform as highlighted in the interim results announcement.
Cash remains healthy -
Period-end cash, net of borrowings, was £8.1m
Broker update - readers were discussing this share below, in the comments, and wondering why it has fallen c.14% today? I think the answer seems to be an update note from Canaccord Genuity, which lowers revenue forecast (but profit unchanged) for FY 3/2022, and also lowers its recommendation to “hold” (broker code for: sell).
My opinion - both Jack and I are intrigued by this company, and think it might be interesting, if its data products take off. In the meantime though, it’s very difficult to value. Should we take a traditional PER approach? That’s not always relevant for growing companies, but in this case forecast EPS is 11.3p for FY 3/2022, and 13.2p for FY 3/2023.
At 375p per share, the PERs are therefore 33 and 28 - not a bargain then, on an earnings basis.
So holders must think the company’s likely to beat forecasts, and/or has a bright long-term future.
I don’t have any insights on what might happen in future, so take a neutral view - but it’s worth following this company, as a potential buy if revenues/profits really start to take off in future. The decent balance sheet, with plenty of cash, and management with lots of skin in the game, appeal to me too.
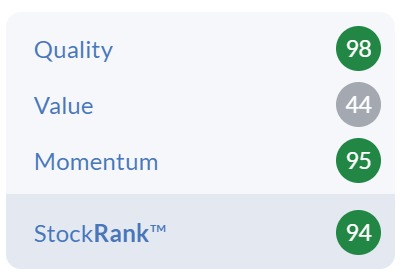
There's an unusually high StockRank too -
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Hi Paul. Re MNZS - What the co say about another £200m in sales in the short to near term would double sales and on much better margins. Also Philipp Joeinig bought 1.2m shares @ 390p in Sep 19 just before Covid when he tookl over as exec Chair which is a lot of skin in the game, he bought a further 1.2m @ 290p in May so an ave of 2.4m @ 340p - I think he fully understood the value he could create here, coming from Swissport. I think there's much better value in MNZS staying independent rather than 510p. During the pandemic they have gone around acquiring on the cheap, winning loads of contracts and now Australia, Sweeded and lots of other countries they serve are just starting to fly again. I've seen estimates of £7 being the value here and in the added sales are correct they will justify thsat on a PE basis before long imo. I'm obviously biased and long from 130p so I would say that.
Respect Richard! You foresaw the turnaround here, I remember us discussing it a while ago. Well done :-) Banking the profits? Must be tempting. I'm surprised it didn't rise more early doors.
Pretty please. So many posts today giving no clue as to what company they're rabbiting on about. Generally I just move on as clicking on the post they're replying to takes several seconds to load up and then I lose my place in the main thread. What's so difficult about including a tickr, guys n' gals?
I would seriously hope that threads for individual stocks could be observed and developed further, otherwise threads like this one become a bit of a mess.
Saying that, but the SCVR thread has a shelf life of less than half a day and all the stocks mentioned are topical. I note that a Stocko thread for any particular company is dated for when it was raised and as such doesn't attract much attention being considered old hat at first glance.
Saying that, but the SCVR thread has a shelf life of less than half a day and all the stocks mentioned are topical. I note that a Stocko thread for any particular company is dated for when it was raised and as such doesn't attract much attention being considered old hat at first glance.
Well, I for one find revisiting old discussion threads useful but with the new website and no search facility they just naturally disappear into the ether. However, if the last 20 years on BB's has shown me anything, it is that single company threads just end up becoming echo chambers with very dangerous group think. So, best avoided anyway.
I wish Stockopedia would make it easier to search through old threads, or even find older discussions you contributed to in the past. It is completely impossible to find many of the most useful and interesting discussions which take place in the comments section of posts.
All the best, Si
Completely agree. I would also add that many experienced posters who contributed greatly to the board seem to have disappeared and their content now very difficult to find.
Boohoo (LON:BOO) down to 93p - at this rate it won't be long before we're allowed to talk about it on the SCVR again - just as well as the separate thread idea hasn't really worked.
I'm enjoyed the Boohoo (LON:BOO) discussions on the SCVR and agree that it hasn't been the same since the new thread.
N Brown (LON:BWNG) on a quiet day I was revisiting a few bombed out retailers and just took another look at the trading update and interims for these guys. I had forgotten quite how much value there is here.
Net Cash of £34m
Customer loan balances of £600m secured against debt of £300m. Provisions of £88m or 14.7% means net assets = £212m + net cash = £255m
But loans in arrears are actually only 4.7% so the provisions appear way too conservative. In reality provisions will probably work out at £30-40m so there is another £45m to come back to the b/s at some point.
So Net assets in cash and financing book are fair value around £300m
Market cap is £178m so trading at 60% of NTAV with zero value attributed to brand or trading business.
I know there is an uncertainty around the insurance dispute litigation but the total amount claimed by Allianz is £66m so this appears to be the worst case scenario, though if N Brown (LON:BWNG) win then it will be a positive cashflow. So lets strip this out to be conservative and we get a realistic £235m NTAV against a market cap of £178m with the online retailer and brands thrown in for free. But the product (ie ignoring loan book) EBITDA is circa £60m (15% margin on £400m sales) - this then gets battered by depreciation but is real cashflow coming into the business offset by capex of around £25m but nonetheless £35m. Stock looks heavily mispriced to me. Have I missed something?
I think you missed about £300m of bank loans
No I didn't. Thats the £300m of debt offset by the loan book of £600m
Yes you certainly did.
They pay £7m finance costs every year.
£14m per year and not £7m
No - I didn't Yiannos. They have two businesses a product business and a finance business.
The Finance business has the debt of £300m and a loan book of £600m (before provisions). This Book makes £230m of revenue p/a and the interest comes off that as a finance cost.
The product business makes £60m of Ebitda but has no debt. In fact it has net cash of £34m.
The EBITDA of the two businesses combined is £106m less the £14m of interest = £92m before depreciation. Again this is positive cashflow less ongoing capex.
We agree to disagree.
It’s like the SCS net cash that some people think that it is shareholders cash ( quite laughable actually ).
Anyway good luck with N Brown.
As I always say I truly hope I am wrong.
No it isn't like SCS at all Yiannos. You are just plain wrong on this one I'm afraid and you need to look at it properly.
N Brown (LON:BWNG) have a loan business like a bank where they have debtors who owe them £600m. They finance this through bank debt and have been paying that down to de-risk the business. That financing is £300m. There is NO other debt in the company but there is net cash. The one minus the other is real Assets (minus any bad debt provisions).
SCS takes prepayments and holds this money against goods to be produced in the future. That is a very different model.
I said you are absolutely wrong but good luck with this one.
You don’t need to convince me that they haven’t got a massive debt.
They do and they pay £14m per year in finance costs.
This is a company that has been capitalising its costs for years.
This is a company that it’s revenue it’s falling and will continue to do so.
We agree to disagree so let’s move on.
ok - I give up. You have an attitude of "I am right don't correct me with the facts!"
If someone shows you something that is black you will swear blind it is white, so never mind. It's a waste of my life discussing anything with you so I won't bother anymore.
No it’s not like that at all.
Do you have a mortgage?
If you have then you do not owe money on your mortgage ( this is what you are trying to persuade yourself ).
N Brown has a massive debt and without that debt wouldn’t be able to finance its customers.
It wouldn’t be able to operate unless it had net cash of around £400m , something that will never be achievable.
This is why they pay £14m of finance costs per year.
If you looking for a dirt cheap value share though , try Coral Products plc. Around £8m cash , and I am talking about real shareholders cash ,and another £2.5m of property on sale. A profitable business and a 7% dividend yield. Market cap around £13m. Directors are buying and there is an ongoing share buyback programme.
Good heavens I despair. This is my very last try.
N Brown (LON:BWNG) operates a finance house. It is basically acting as a bank. It has already lent £600m to its customers in loans who are paying that money back over time. But because it had built up £300m of cash it only needs to go to the wholesale market and borrow £300m. This debt is secured borrowing against the loan portfolio. On the £300m it has borrowed it pays interest of £14m, or 3%, but it lends that money to its customers at a much higher rate. The difference is called the NIM (net interest margin).
This is the same for every finance house. The business therefore has real net assets of £300m. In other words if they just let the book run off and not continue to lend to new customers then they would be left with £300m sitting in cash (less any defaults).
I don’t think that could’ve been explained more accurately, more clearly and more patiently!
You are a patient man Mr Hill!
Sounds like an interesting special situation N Brown (LON:BWNG) will need to take a closer look. Trading at discount to net tangible assets, so appears market is ascribing a negative value to the actual trading business - this would normally only occur when the underlying business is expected to be persistently loss making and suck all of the value out of the balance sheet.
Re the valuation of N Brown (LON:BWNG) .
There are quite a few UK listed companies with a P/Tangible Book Value < 0.6 that have seen FY1 upgrades in the past three months including Barclays (LON:BARC) Kenmare Resources (LON:KMR) Seplat Energy (LON:SEPL) Petra Diamonds (LON:PDL) & Virgin Money Uk (LON:VMUK) .
All of these names have market cap > £100m.
Moreover, the first three of these companies enjoy a StockRank in excess of 90, compared to the 69 of N Brown (LON:BWNG) .
yep Bouden - Having gone through this in detail today I agree. They've stopped the recurring "one off" exceptional items that had been a feature previously so no dodgy adjustments, which is positive to see. I calculate the EBITDA of the product line (online apparel retail) at circa £60m less Capex of £22m so £38m appears a reasonable ongoing number of actual FCF. The residual £35m EBITDA (£92-96m guidance) is from the finance book less the interest of £14m so that appears to throw off £20m profits after impairment write downs.
Hence, as you say the online retail trading business is basically valued at nothing but should generate £38m positive cashflow. There will be chunky depreciation for a few years to work through the accounting numbers but obviously this is sunk cost borne by previous shareholders. I prefer to look at cash generated going forward.
Taken them a while to get their house in order but I have them at FV of around 75p assuming the Allianz claim goes against them in full and around 90p if not. But trading at a significant discount to TNAV that looks like a good risk/reward skew. Dividend is mooted to be back on the table too.
Wynnstay (LON:WYN) gave a very comprehensive full-year 2021 results presentation on Monday (7 February 2022). CEO, Gareth Davies & CFO, Paul Roberts presented. Record results with a significantly improved trading environment. They outline the growth plans and the prospects for future positive development. Trading for the new financial year has begun well, in line with expectations. I thought it was interesting how well the sector is doing, the moving parts with inflation and how Brexit is playing out. Video & podcast.
Separately we have the next Stockopedia/PIWORLD StockSlam is on 6th April, 6pm. Register here to hear a 3 minute top stock pitch by 10 private investors. PLEASE contact me here if you'd like to do a 3 minute slam. I have 3 places left and we'd love some new faces. It's fun to take part and always great to hear different stock ideas and investing styles of this great PI community.
I thought the Wynnstay presentation was really good. Happy to hold this steady and old fashioned company.
Reports that rents are now soaring, increasing at 8.3% in last 3 months of 2021. Should be good for the likes of Belvoir (LON:BLV) (if not for the poor tenants) who are mainly focused on lettings. Possibly another good way to play the inflation theme, alongside recruiters and royalty companies such as £DUKE
Just need a £6 bid for Saga (LON:SAGA) now ;) I'd be more than happy with that.
oh yuck - no thank you very much. I expect much more over the next couple of years for Saga (LON:SAGA) I would be mortified if it went for £6 !!!
We shall see David but hopefully you're thesis is right. I have a Boat load of these so the more the better.
Out of interest what is you're say 2 year price target for Saga (LON:SAGA)?
Hi James - I think Saga (LON:SAGA) can be doing £150m profit from the insurance business, £100m from travel (inc cruise) and £20m ancilliary over the medium term of 2-3 years. Thats EBIT so conservatively call it £150m after tax. Should trade on maybe 12* in normal conditions so up to £1.8bn market cap.
So if they execute well and get some normalised conditions that equates to anything up to 1500p. I'm not saying they will get there but I think that's the potential. Personally I'm looking for north of 1000p on eps of around 80-90p in 2 or 3 years. Looks like broker has a 1 year forward eps of 50p.
Agree with dahokolomoki and Dicktrade too per below : I think they will be a big net beneficiary of the new "price walk" insurance quote rules and should have very strong pricing power on travel insurance.
The dark horse for me in Saga (LON:SAGA) is not the cruise, as that benefit is already well known, but the huge uplift in travel insurance sales for the next few years. If Covid has taught people anything, it is to prepare for the worst on holidays, and I bet we'll see huge travel insurance sales in the years ahead.
A pity there's no easy way to get direct exposure to travel insurance on the UK markets.
£SAGA ( I hold)
Also the insurance companies not being able to "price walk" existing customers I see as a benefit to Saga , as their demographic is now even more likely NOT to shop around at renewal time and will renew on what has to be said are usually very expensive premiums.
I too would not be happy to be taken out at £6, I see a lot more upside here.
Our beloved Gattaca Gattaca (LON:GATC) is up 16% today with no news that I can find...Does anyone know why please? Could there be some good news at last?
No wonder Menzies directors are not keen on takeover with their self rewarded executive pay at such ludicrous levels especially for such dire underperformance .
Any credible buyer will have those self serving clowns straight out the door , put in proper professional management team and save themselves around 2 million a year with a senior team that represents the owners not themselves .
Not revealing a previous bid approach only re-enforces this .
All pretty embarrassing really, I have no idea how they look in the mirror every morning whilst wearing their Dick Turpin masks and taking shareholders for such a ride .
Good luck to them I guess if AIM companies are there to enrich senior management at the expense of shareholders they are truly a world class team .
Their executive pay “rewards” for
The only thing is that Menzies is not listed on AIM.
Director enthusiasm has overflowed from AIM, it's as catching as Covid.
Good point .
That makes it even more outrageous that previous takeover attempt not disclosed .
And salaries/remuneration still ridiculous whether it’s AIM or LSE .
I agree on more takeovers happening in weeks/months ahead.
Investors have become so short term in their thinking that its leaving many companies dangling like fruit ready to be plucked. I'm part of the problem as I use stop losses, but to limit losses I guess you have to play the game.
Thg (LON:THG) looks like it's being lined up by private equity. Too many names mentioned for it to be the usual gossip in my opinion.
Air Partner (LON:AIR) taken out last week and John Menzies (LON:MNZS) looking likely. Senior (LON:SNR) rejected 200p.
Who will be next?
Evraz (LON:EVR) ...... completely off topic. These are going ex a share issue in a subsidiary coalmining business called RASP these new shares cannot be held by most platforms as they will be quoted only in Russia, holders will receive the cash when they are sold though not until November. Does anyone have any idea of the approximate value of the RASP shares ?
On John Menzies (LON:MNZS) it'll be interesting to see where the share price decides to settle ultimately. Perhaps I am too narrowly focused on the shares in my portfolio and watchlist but it often seems that where a company rejects an offer as being "speculative" or "too low" the share price tends to significantly underperform the actual offered price on a short-medium term view. For my portfolio, I'm looking at Senior (LON:SNR) and Elementis (LON:ELM) most recently, but can think of plenty of others. Perhaps the shareholders should get more say if they want the cash now or not...
Back to John Menzies (LON:MNZS), Agility have plenty of financial resources so it wouldn't surprise me if they will come back with a higher bid. Good luck to all holders. Ps - if you want to feel better today about your performance, know that I sold out of John Menzies (LON:MNZS) yesterday afternoon (oh well...). All the best, Will
Presumably forced to disclose based on share price move yesterday. John Menzies (LON:MNZS) share price today , around 450p currently, assuming a third bid or other suitors. Often it takes around 3 bids , this seems to be the accepted protocol. So maybe another 5% on top of 510p offer? Move from 1st to 2nd offer was 13.3%. I'm a holder and have sold 50% (hedging my bets!).
John Menzies (LON:MNZS) My thesis was that the management have been successful before in the same industry, covid would eventually subside and the directors were buying their own stock in the market with their own money. My target was 600p+. I don't think the bid changes any of that, so I'll take the risks it bobbles about a bit with a view to getting >30% more in the next 18 months. It beats inflation!
The John Menzies (LON:MNZS) management must have been sitting on this for a few days, as they managed to put out a 12 page defence presentation at the same time as revealing the (2nd) bid. https://menziesaviation.com/wp...
It appears to me from today's Expected Timetable of Principal Events that the takeover of Air Partner (LON:AIR), as far as HMRC is concerned, is highly likely to happen before April 5th. Is that the understanding of interested others?
disclosure: held...in a taxed account
re: Air Partner (LON:AIR)
Mercifully I hold this in an ISA but I sympathise with you for the uncertainty as to which tax year it will fall in. I would be very surprised if the t/o became effective in this tax year. The reason is that application to the High Court will not be made before various conditions are satisfied and these will include clearance by competition authorities who tend to proceed at their own pace. In this case the delay is likely to be in the USA - the bidder, Wheels Up. is the second largest air charter company there (NetJets is first) and just under a third of Air Partner's revenue in H1 this year was in the USA so I suspect that will set off competition concerns.
Example - I held SUMO (games maker) which announced a bid in July last year. The Scheme was approved in meetings on Sept 10th but it did not become effective until Jan 17th this year because of competition clearance.
If there is a similar delay with Air Partner (LON:AIR) and you have spare CGT allowance to use you have the option of selling in the market.
System1 (LON:SYS1) an odd -10% reaction to an in-line trading statement. Cash going up despite the buy backs too.
I'm looking for reasons behind the drop - Keep thinking i've missed something. In line profitability but expenditure up.... but revenue increase offsets this?
I'll look at System1 (LON:SYS1) next.
I hold System 1 . Management are very strong - definitely an intelligent fanatic iconoclast (using Ian Cassel language!) running the show. I am not surprised by the price pull back today as the quarterly results looked a tad disappointing. Maybe some COVID-19 negative impact. I guess the potential is enormous if their data revenues keep accelerating. The path forward will be bumpy, as nothing grows in a straight line. For those following System1 its worth subscribing to their daily ad. email - keeps you abreast of the top TV Ads and how their system works. It's free.
”Management are very strong - definitely an intelligent fanatic iconoclast (using Ian Cassel language!) running the show”
I don’t think I would agree with that. Kearon botched the name change from Brain Juicer.. They don’t even own the www.system1.com domain! Net profit for 2023 is forecast to be substantially lower than it was in 2016 and 2017.
In my book the Auto Data revenue was disappointing, I would have expected growth to be better, however, the consultancy revenue was much better than I expected. Um...........
Keith A-L's reports on January for the Buffettology and Free Spirit funds are now available. They had "worst month of relative underperformance since June 2016" and "worst monthly relative performance since inception" respectively. His detailed thoughts on the market gave me some crumbs of comfort for my own miserable drop in portfolio value - click on 2022 and then January:
https://www.sanford-deland.com...
https://www.sanford-deland.com...
what's going on with Boohoo today?
downgraded by barclays
lol talking of beating them when they're down!
EV now only 58% of sales - barking!
Re Boohoo (LON:BOO) , there are plenty of rapidly growing UK listed companies with superior margins to Boohoo (LON:BOO) , yet on lower EV/Sales multiples.
Trust Stockopedia to find them for you.
Looks like the institutional selling overhang in Joules (LON:JOUL) (I hold) is rapidly clearing - as we thought, judging from the very high daily volume in the shares since last week's profit warning.
Blackrock held 10%, but were selling. Announced this morning they are now below 5%. Not sure of the exact rules, but I have a feeling overseas shareholders have to disclose over 5%, not over 3%? I would imagine the c.£60m market cap of JOUL is now not of interest to Blackrock.
Canaccord was another seller, and they can often be brutal if they go off a small cap - just dumping the lot.
I can understand why instis might have lost confidence in JOUL management - I'm not exactly enamoured with their performance myself.
But for me, the only thing that matters is what happens to the share price from today. The past doesn't matter, because we can't change anything in the past. Whereas at 60p, I think there's decent rebound potential. My average buy price is now down to 109p, which should be achievable.
Regards, Paul.
According to TUI their summer bookings are now ahead of pre-pandemic levels with people booking more expensive holidays. Bodes well for travel stocks which are still off their 2021 highs - e.g. Saga (LON:SAGA) and On The Beach (LON:OTB) (I hold both)
https://www.thetimes.co.uk/art...
I think I also read Ryanair changing their tune today and being super positive about spring and summer?
I note that Ergomed (LON:ERGO) is back on the M&A front.....buying a consulting services businesses called ADAMAS to broaden its global service offering. I am not a fan of buying consulting businesses on seemingly high EBITDA multiples, but they say this is being funded from cash and immediately earnings enhancing. I do have high regard for this management team - they know the industry so well and are seasoned at building businesses. I trust that the "strong synergies and strategic benefits" will flow through into 2022/23 earnings.
Photo-me International (LON:PHTM) - ahead of expectations. A real kick in the teeth for those who risked buying the share in return for improved profits when Covid receded. Share price now pretty much fixed at 75p
Just shows that small PI's need to be aware of corporate structures and takeover potential. You don't always get a premium when a company is taken private.
Why is the share priced "fixed" at 75p?
I see it started trading at 77p+ this morning at the open.
Takeover by the CEO. He controls 37% of company and has made an offer of 75p.
It will be interesting to see if the other significant shareholders can force a higher bid but prior to today there appeared to be little resistance. Will be interesting to see if the share price moves significantly. Should be 100p in my opinion.
He can't force you to sell your shares, unless I think it goes to like 75% or 90% of votes cast for it?
And he has made a statement he does not intend to try to take the company private at this time.
He could always increase his bid too at some point.
I think your assumption that Photo-me International (LON:PHTM) share price will "stick" at 75p because one has to sell to him at that price is not correct. But happy to hear the counter argument as I've only been involved in a few takeover situations and not an expert.
The rules mean the £PHTM CEO had to make the offer. There's nothing forcing shareholders to accept. If he wanted the bid to succeed he would have offered a premium. Just reject the bid and I think everyone will be happy.
The Photo-Me International (LON:PHTM) takeover bid was discussed in the SCVR a few weeks ago here.
Hi Michael
How do you insert a link to a previous article (using the word "here")?
Hope that is not a dumb question.
I noticed from the form 8.3 that are being submitted that several of the institutional shareholders are selling at around 75p. I didn't know that Tibergest had stated they do not wish to take the company public, its not on the RNS. Could someone point me to it?
Share price jumped to 79p this morning but now back to just above 75p.
Re the Photo-me International (LON:PHTM) bid and the stock remaining publicly traded.
It's in section 7 of the announcement:
If the Offer becomes unconditional, Bidco does not intend to procure that Photo-Me makes an application to cancel trading in Photo-Me Shares on the London Stock Exchange or the listing of Photo-Me Shares on the Official List. However, the FCA has authority to cancel the listing of Photo-Me Shares in certain circumstances (for example, due to lack of free float in Photo-Me Shares as a result of the Offer).
Hi Michael
How do you insert a link to a previous article (using the word "here")?
Hope that is not a dumb question.
I noticed from the form 8.3 that are being submitted that several of the institutional shareholders are selling at around 75p. I didn't know that Tibergest had stated they do not wish to take the company public, its not on the RNS. Could someone point me to it?
Share price jumped to 79p this morning but now back to just above 75p.
Hi Revs8 - When you click the link icon (looks like links in a physical chain) above, there is an option to "Insert Link". If you click that as well a pop-up appears showing a place to put the URL (the link itself) underneath that there is a box that says "Text". If you leave that blank the URL will display as the link. But if you put something into the text box then the display will show what you put in the text box and the link will still work. Hope that helps.
Associated British Foods (LON:ABF)
Greggs (LON:GRG) Alliance News today
High street bakery chain Greggs PLC is to launch a fashion collection in a first-of-its-kind collaboration with Primark.
A limited-edition range of 11 clothing items will go on sale in 60 Primark stores from February 19.
What's next? Joules selling Waitrose clothes?
Their all XXXXXL.
The Greggs garment will be a "muffin top"? :-)
The Greggs garment will be a "muffin top"? :-)
Paired with a "Sausage"Roll necked jumper?
John Menzies (LON:MNZS) Rebuts an unsolicited offer of 510p per share. Not only this, but they had previously batted off a lower offer - which I don't think was ever disclosed. This perhaps explains the shares' rather strong performance this week. Sniffy. Still a great recovery stock IMO. I hold.
I do think £MNZS is capable of attaining a higher valuation over the medium term - they are doing all of the right things in my view (I hold). But I must confess I would have accepted a 510p offer today, rather than waiting - especially with the extent of post-Covid travel still unkown. I would welcome getting one positive result in 2022 for my battered portfolio! We will see what the share price does......this may be the start of an interesting process.