Small Cap Value Report (Wednesday 7 June 2023) - FA., MORE, RFX, VP., CPC

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries
Ramsdens Holdings (LON:RFX) - 259p (+5%) (£82m) - Interims - Graham - GREEN
This financial services provider and retailer continues firing on all cylinders. We already knew that H1 figures would be very good but the company confirms today that the positive momentum has continued so far into H2. Valuation remains attractive in my book.
Hostmore (LON:MORE) - Down 3% to 22.4p (£28m) - AGM Trading Update - Paul (I hold) - RED
So far, the market doesn’t seem to have spotted that the “broadly consistent” messaging today on LFL sales is untrue. There’s actually been a sharp slowdown in the last 6 weeks, from -1%, to c.-8%. I think a profit warning is building, as forecasts don’t look realistic in the current climate. Very high risk of dilution, as bank debt is too high. Possible speculative turnaround maybe?
FireAngel (FA.) - down 27% to 4.75p yesterday (£8m pre dilution) - various - Paul - RED
Publishes poor FY 12/2022 results, sacks its CEO, replaces Chmn & CEO with former Directors from Universe Group, and launches a fundraise at 5.05p, with additional potential dilution from 3.0p warrants. So lots to take in here. I wouldn’t waste any time on it.
VP (LON:VP.) Up 4% to 670p (£269m) - FY 3/2023 Results - Paul - GREEN
I have a good rummage through the annual results, and come away impressed - this diversified equipment hire group looks decent quality, but shares seem cheap. 6% dividend yield, and a likely takeover bid at some stage when the 72-year old 50% shareholder wants to retire? Lots to like, so it's a thumbs up from me.
City Pub (LON:CPC) - 100.7p (+2%) (£103m) - AGM statement - Graham - AMBER
A pleasant update from CPC as like-for-like sales are up 13%. They argue that sales would have been even better if not for rail strikes, but as the Italians say, “If my Grandmother had wheels she would have been a bike”. This is a good company at a fair valuation.
Paul’s Section:
(I did this section below while waiting for the 07:00 RNS feed to start)
Fireangel Safety Technology (LON:FA.)
Down 22% to 4.75p yesterday (£9m before fundraise dilution) - Fundraise & new management - Paul - RED
A flurry of announcements yesterday from this financially distressed maker/distributor of fire safety alarms. It announced accounts for FY 12/2022, showing an underlying loss before tax of £5.0m. Also a £6.1m fundraising is announced, which sounds like it’s backed by existing shareholders, at 5.05p, plus warrants priced at 3.0p. I’m not clear if the £6.1m placing is in addition to the £6.1m open offer, or instead of, as a clawback is mentioned.
The company also announces it’s for sale, which has triggered an offer period.
The CEO is ditched, and replaced immediately with a new Chairman and CEO formerly of Universe Group, where they achieved a good exit at a premium price for shareholders, I remember covering it here for a few years.
Interestingly, a key supplier that is owed £2.1m, is subscribing for new shares for that amount plus another £0.7m, which looks encouraging.
Paul’s opinion - this company looked really good years ago, when it was called Sprue Aegis - profitable, financially secure. But it’s gone horribly wrong since, with repeated profit warnings, and increasing financial pressure. This deal looks a credible attempt to turn the company around, so I wish it well. With a lot of potential dilution, and the warrants priced at 3.0p, I wouldn’t personally be interested in paying much more than 3p for the shares in future, and only if there’s a credible turnaround plan underway. So it’s best seen as a special situation for now, and in the last chance saloon as a listed company. I’ve only skimmed over the detail above, it would need a closer look for anyone considering buying or holding the shares.
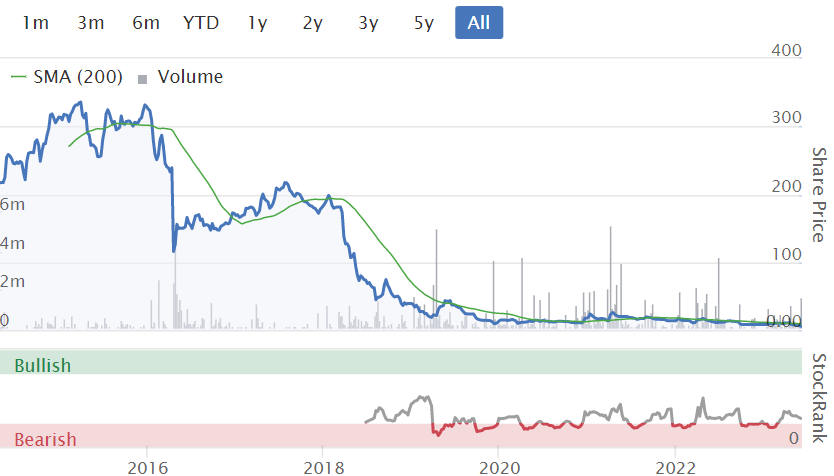
An absolute disaster for shareholders -
Hostmore (LON:MORE) (Paul holds)
21.8p (pre-market open) (£28m) - AGM Trading Update - Paul - RED
I picked up a tiny position in this TGI Fridays restaurant chain, based on an upbeat recent presentation from new management lately, but that’s looking like a mistake now.
In my opinion, today’s update seems deceptive. We’re told that LFL sales in the first 16 weeks were down 1% vs LY. This they claim today has remained “broadly consistent” at -3% for the first 22 weeks. Doing some simple number crunching, which ignores seasonality, I calculate that this actually means the most recent 6 weeks saw LFL sales down -8.3%, which is not in any way “broadly consistent” with the previous 16 weeks. It’s actually a big lurch down. On 77% gross margin, that has a nasty leveraged impact on profit. Yet the company doesn’t mention anything about performance vs market expectations today, so we’re meant to assume it’s trading in line with expectations, but I don’t see how that can possibly be true when the last 6 weeks have seen such a sharp deterioration in sales.
On the plus side, it says EBITDA is seeing an improvement from cost savings, as planned. Also it’s seeing an additional £1m saving in utilities costs, from delaying its hedging arrangements. This is an interesting general point actually - companies which benefited from hedging last year, might now be suffering if they hedged at high prices during the energy crisis. Taking the risk of not hedging at high prices is paying off at the moment.
Guest scores are improving we’re told. I’ll mystery shop the Bournemouth site shortly, to see if they’ve managed to work out how to carbonate the sodas yet?!
The Chairman is stepping down at the AGM today, which sounds planned.
Paul’s opinion - this update looks more like a PR release than a trading update, and it commits the sin of not commenting on trading versus expectations. The latest forecast suggests adj PBT for FY 12/2023 of £(0.6)m. Given weak sales in the last 6 weeks, I struggle to see how it’s likely to meet forecasts, so in my opinion a profit warning is probably in the pipeline. With higher mortgage costs likely to gradually hit working families (probably MORE’s core customers), then it’s difficult to imagine trading is going to improve any time soon.
Which leaves the risk of bank debt, which we already knew was much too high for a company not likely to be making a profit this year. Banks are more interested in EBITDA though, especially now that new site openings have been stopped, in order to generate cashflow, and hence reduce debt. Management said recently that they have an aspiration to reduce net debt by £10m pa. If that can be achieved, then the shares could multi-bag from here. However, after today’s update, I think there’s a considerable question mark over how realistic this plan is? Hence I have to maintain my “red” view of MORE shares, from a value investing point of view. It’s more of a speculative, high risk situation, as we’ve mentioned here several times before. It might work out, but I think there’s a very high risk of a dilutive equity fundraise being required to keep the bank on side.
UPDATE - a short note from Finncap has just come through, saying it's too early in the year to revisit forecasts. That seems odd, given that we're just over 3 weeks away from the half year. Finncap's assumption of +2% LFLs for the year looks way too optimistic, so I think we can just ignore existing forecasts as being unrealistic.
This has been a disaster for shareholders, since demerging from Electra Private Equity -
VP (LON:VP.)
Up 4% to 670p (£269m) - Final Results - Paul - GREEN
I’ve got a favourable existing impression of this diversified equipment rental group, which is owner-managed, with Chairman Jeremy Pilkington owning slightly over 50% (maybe a little too high for comfort?) Note that Mr Pilkington put the business up for sale in spring 2022, but no acceptable offers were received. He’s 72 years old, so I think this is very interesting, as it seems clear he wants an exit, but won’t sell it on the cheap. I like that very much, and long-time readers will remember that we cleaned up here with a bumper sale of Avesco, in similar circumstances a few years ago. So I’ve been on the look out for another value share where a retirement sale for the major shareholder is looking likely. Plus shareholders get an attractive dividend yield of c.6% whilst they wait for a sale in due course.
I’ve briefly reviewed the accounts, here are my notes on the main points -
Revenues up 6% to £371.5m, generated 90% in the UK.
International division is small, but showed strong profit growth.
Adj PBT £40.5m, with statutory PBT lower at £30.7m.
Exceptional costs of £5.0m include £1.7m aborted sale costs, and the balance is restructuring costs - a little bit questionable for the latter, as businesses like this often have to restructure depending on circumstances.
Other adjustments to profit include £4.5m of goodwill amortisation, which is fine to exclude.
Overall then I’m reasonably OK with the adjustments.
Finance costs have risen, and of course hire companies use a fair bit of debt, so finance costs are likely to rise further. Although VP has private placement notes (bonds) of £93m, which I seem to recall are at fixed, low interest rates.
Adj basic EPS is 79.0p, up 11%. Note 3 shows that there’s hardly any potential dilution from share options, which I like.
The PER is only 8.5, which strikes me as a bargain. That’s an earnings yield of a healthy 11.8% - attractive, when cash deposits are earning say 4-5%.
Year end net debt of £134.4m looks OK to me, in the context of £252m fixed assets. I generally like to see hire companies own about half their fleet, and the other half funded through debt, which is roughly the position at VP.
ROCE is 14.4%, it’s quite unusual to see this disclosed, and usually indicates management are prioritising good capital allocation (ie. only buying stuff that they can earn a good return from renting out).
Gearing & interest cover are “well within covenants”, so no sign of potential financial distress in any of these numbers or commentary.
Balance sheet looks OK to me - NAV £175m, less intangibles of £57.7m, so NTAV is £117m, which is pretty solid I think. There is a small pension accounting surplus, which would need careful checking to ensure it’s not a nasty actuarial deficit.
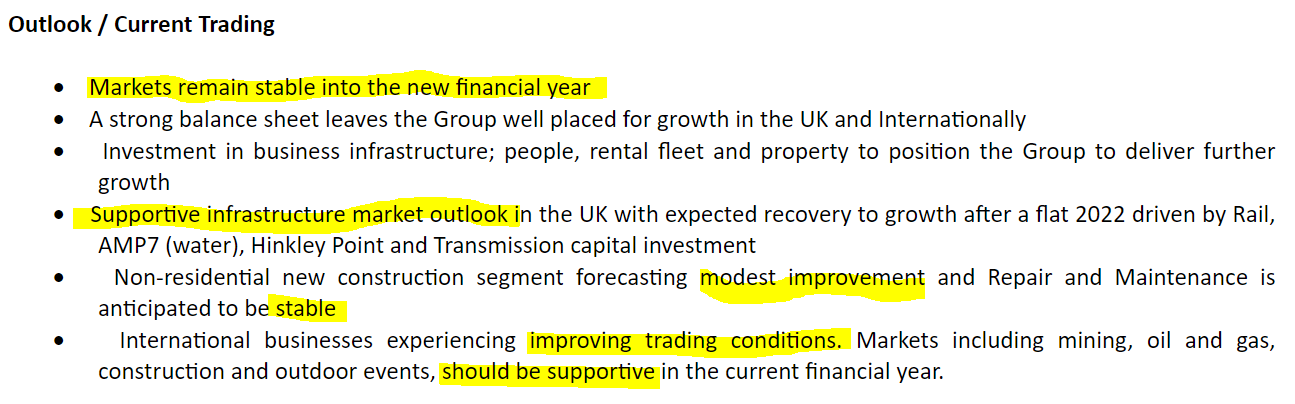
Outlook & the commentary generally sound good, with a nice mix of activities evening out performance. This bit below is interesting for wider read-across possibly -
After a period of little change within the wider UK construction market, some adjustments to recent trends are forecast in the coming 12 months. Housebuilding which has been relatively buoyant for the last two years is forecast to experience moderate contraction in 2023 before recovering in 2024. Infrastructure will recover to modest growth after a flat 2022 driven by Rail, AMP7 (water), Hinkley Point and Offshore Wind capital investment. The non-residential new construction segment, comprising Public, Private Industrial and Private Commercial output is expected to see modest improvement overall and the Repair and Maintenance sectors are anticipated to be stable. This market backdrop remains positive for Vp.
Forecasts - Singers (many thanks) is forecasting 79.7p adj EPS for FY 3/2024, which I think sits comfortably with the commentary in today’s results. So I suspect the risk of a profit warning is probably quite low.
Paul’s opinion - I think this looks very good. VP strikes me as a good quality business, priced attractively cheaply at the moment - I think this could be a buying opportunity for medium to long-term investors.
It seems well-managed, and I like the catalyst for a takeover bid being received (retirement sale for the 50% shareholder).
So a thumbs up from me!
Graham’s Section:
Ramsdens Holdings (LON:RFX)
Share price: 259p (+5%)
Market cap: £82m
Ramsdens, the diversified financial services provider and retailer, today announces its Interim Results for the six months ended 31 March 2023 (the "Period").
This company raised expectations in April as every service it provided was booming: jewellery retail, foreign exchange, pawnbroking and precious metal buying.
Here are the interim highlights:
Revenue +33% to £39m
PBT +68% to £3.7m
Net assets up £5.4m year-on-year to £43m
Current trading - “positive momentum has continued so far into the second half of FY23”.
New stores - six new stores opened in H1, and another six are planned in H2, as the company continues its expansion into the South of England. I do consider this to be a risky move, as they are clashing head-on with H & T (LON:HAT) but hopefully they will move slowly enough to manage the risks involved. Total store estate is 158 stores.
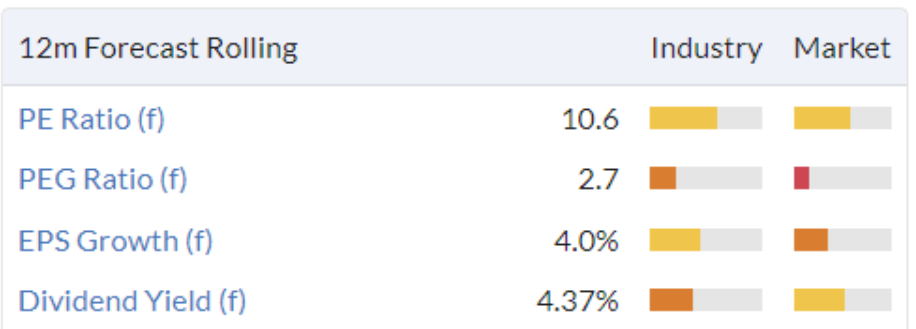
Dividend - it’s worth mentioning a significant increase in the interim dividend from 2.7p to 3.3p. I don’t always bother mentioning dividend increases in this report but that’s a chunky increase!
Stockopedia is forecasting 10.4p of total dividends this year, giving it an attractive yield:
Foreign currency exchange - this remains a very popular service and continues on its post-Covid recovery. In addition to the core service, Ramsdens will launch a new multi-currency card this summer to assist holidaymakers. CEO comment:
We are looking forward to the summer period with optimism supported by positive commentary by airlines and travel agents, albeit we do not currently anticipate that the total volume exchanged will exceed the levels seen prior to the pandemic in summer 2019.
Pawnbroking - also very strong right now, due to the cost-of-living crisis (and in my opinion a hostile regulatory environment for payday lenders).
With restrictions in the availability of other forms of small sum credit, and the continued squeeze on household incomes with higher bills, we believe that demand for small sum loans will continue to be high for the remainder of 2023.
New website - Ramsdens has an attractive new jewellery retailing website which delivered sales of £3.7m in H1 (up 89% year-on-year).
Outlook
With our diversified income streams, strong brand and growing customer base, we believe we are well positioned to further grow our profitability in this financial year and in coming years, and continue to deliver on our progressive dividend policy.
Graham’s view
I gave this stock the thumbs up in April (share price: 230p) and there is little reason to change my stance today! The share price is up over 10% since then but positive momentum continues to build and the valuation remains, in my view, very reasonable.
I tend to think of H & T (LON:HAT) as a mini-bank, because its loan book is so large and so important to its financial performance.
Ramsdens Holdings (LON:RFX) is different because its loan book only accounts for about a quarter of its gross profit. So it can be thought of more as a retailer or a retail service provider than a bank.
This isn’t good or bad, just different. I calculate the return on equity for the company in H1 as circa 6.7% (so double it for an annual figure), which is very good - and Stockopedia agrees that this is a quality outfit:
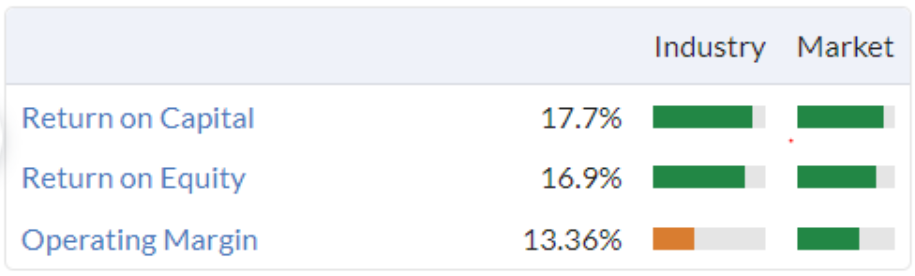
For a “retailer” to generate these metrics shows that it is doing things right, and it’s reasonable to expand when it’s able to generate these sorts of returns - it will just need to be very careful to do so responsibly.
In this regard, I am comforted by the CEO’s statement that “we continue to value flexibility in our lease portfolio. Lease renewals have generally resulted in rent reductions and / or greater flexibility. On occasion, we have relocated to take advantage of lower rents in a much better footfall location.”
Overall I remain very impressed by this company and its performance.
City Pub (LON:CPC)
Share price: 100.7p (+2%)
Market cap: £103m
Roland provided an excellent analysis of this company at the time of its full-year results in April.
Today we have an AGM trading update for the first 23 weeks of the new financial year (I’m pretty sure there is no significance to that number of weeks - it’s purely a function of when the AGM falls!).
Trading continues to be “strong”, with total sales up 20%:
LFL sales improved by 13% on 2022 and would have been higher if not for recent train strikes. The strong LFL performance is being driven by our strategy to further premiumise the estate and a continuous focus on customer service. We expect this trend to continue through H2 and we will also benefit from the new openings from 2022 which have performed well to date.
Rail strikes have been an issue for some time; I noted in relation to Q4 2022 that the World Cup had boosted revenues while rail strikes had held them back. The bottom line is that there is always some issue beyond a pub’s control that is affecting performance - if nothing else, then it’s the weather!
Inflation - “Costs have remained in line with expectations and there is now clear evidence of abatement in some areas, although food inflation remains high”. Excellent news.
Net debt is considered “low” at £8m although this does represent a doubling from the year-end figure. Still, the main point about CPC is that it’s a mostly freehold estate, which greatly reduces the financial risk associated with the stock (and puts it in a different league to many other pub investments).
According to the full-year results for 2022, “the company’s portfolio is 61% freehold and these pubs account for over 90% of our investment”. The balance sheet showed less than £20m of lease liabilities.
Additionally, they have claimed to hold “very strict criteria” for acquisitions, and they continue in that vein in today’s update:
Whilst we are looking at acquisition opportunities carefully, we still believe that in the short-term pub prices will fall and we are therefore in no rush to go out and acquire. We will continue to focus on organic growth from our existing estate.
Mosaic pubs
CPC has gradually increased its level of investment in “Mosaic Pub and Dining Group”, paying another £0.7m to bring its total investment to £7m. It now has 52% ownership and is taking operational control of the 9 pubs in this estate.
Chairman comment
The strategy that we have pursued over that last couple of years is now manifesting itself in our out performance. We have an excellent estate of high-quality premium pubs, well invested, located well and trading strongly… Our estate is growing through cost effective acquisitions and we have reached a landmark moment for the City Pub Group as we now own and operate more than 50 premium -predominantly freehold - pubs in the south of England and Wales
Graham’s view
Whenever I see the word “freehold” in relation to pubs I am far more comfortable, as I don’t need to worry about landlords extracting most of the value from the business or (worst-case scenario) becoming a nightmare creditor.
Instead, this business is largely its own landlord, and its post-Covid recovery expansion and expansion look set to result in some nice profits:
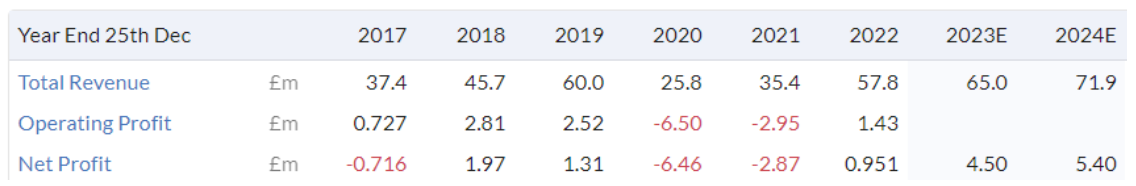
Is it worth £100m+? Perhaps, but I’m not sure it’s worth much more than that; balance sheet net assets were £94m as of December 2022 so it is trading at price/book and price/sales multiples both in excess of 1x. For pubs, I don’t think that’s cheap. Price/earnings is also at the higher end of the spectrum.
Therefore, while I like everything I’ve read about this company, I have to agree with Roland and I wouldn’t personally be in any rush to buy the shares at this level.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
My write up of the Oxford Biodynamics (LON:OBD) HY results webinar is available now on the Stockopedia discussion page.
If you know anyone who has had a PSA test or indeed had one yourself you will know that it has many issues and is disliked by patients and doctors alike. A false positive score of 86% should be unacceptable in this day and age. If OBD are able to bring their PSE test to the market later this year it has real potential for the company. Lots more about this in the webinar here and write up.
VP (LON:VP.) - a reminder to all that this Friday (11am) we're hosting an investor webinar presentation with CEO & CFO - you can sign up to register here: https://www.equitydevelopment....
Spaceandpeople (LON:SAL) is down 9% today on zero trades it seems. Any idea why?
Hostmore (LON:MORE) ( I hold) ... and averaged down at 17, mainly after seeing the cost action plan and the proposed cash flow generation. On the face of it today is a step backwards. Obviously a sensitive stock and some strong opinions out there.... so I thought it might be back down at 20p or less this morning.
You can't polish a turd and the revenue outcome is poor...so is it all over? Maybe, no-one wants to get suckered twice.... having said that there is rather a lot going on. And some pretty wild comps I would suggest from 2022. The turnaround plan is not predicated on revenue growth. However the forecasts do have revenue growing... so understandably today is disappointing. A 1% drop in overall revenue is probably offset by the £1m cost saving that came through from hedges not in place. Hmmm you can't keep pulling that rabbit out of the hat....but the over all plan is one of margin improvement and cashflow generation.
So should the shares be discarded today.... When they announced previous cost measures they had already been implemented. There is still more to go for as highlighted.... they obviously got hit in a perfect storm of covid-inflation-utility costs....and a fair amount of price-service-hedging reconfiguration needs to happen. Im inclined to continue to give them a shot. Its still early days for the plan...I haven't met the CEO but she is buying stock...all the comments re TGI etc are more than fair, they were when it "de-merged" from Electra ....they were when Electra bought it too. It's not rocket science, but it is leveraged.... I'll be the Black Knight (Monty Python) on this one...perhaps foolishly trusting the team to sort it out.... it is still a pretty small position even after averaging in and subsequent recovery...so Ill roll the dice. We aren't been asked to believe it can be something it isn't..just something it was.... we will see.
With regards to the Hostmore (LON:MORE) CEO buying shares - as far as I can see she has un undertaking to buy shares each month but there doesn't seem to be info regarding how many shares?
Hostmore (LON:MORE) I read the announcement about the CEO buy shares in the future. I couldn't see how many/ or what value. What have I missed?
Rua Life Sciences (LON:RUA) (I hold a slightly embarrassingly large stake) things continue to progress at a snail's pace. But I take heart at three things - increased profitability and growth on the manufacturing side; potholes on the road to 10 bags being steadily filled (guess meaningful share price uplift put back to summer 2024); management value IP at £7m on a sensible DCF basis (current market cap £8.8m). So I rate the potential really quite solid now, and even if the wheels fall off, the IP is a protection against price collapse. I expect a small new dilution with the results next month - but Rua Life Sciences (LON:RUA) got the last one away at a premium, so no great fears.
'This has been a disaster for shareholders, since demerging from Electra Private Equity'. Yes it certainly has been and I suspect there will be many Stockopedia subscribers who have suffered significant losses on both Hostmore (LON:MORE) and Unbound (LON:UBG). My holding is now worth little more than the commission it would cost to sell! Perhaps some miracle will happen but I am reconciled to a total failure. When (rather than if!) this happens at least I can remove them from my portfolio review and move on.
Hostmore (LON:MORE)
The threat of dilution here is the main risk other than the obvious one (is it a viable buisness) -in that regard at least today they left you with your chip and a chair - practicably speaking you possibly are all in with a 7-2 to boot. At least the mop has not flopped to take away your chair and they have some time to hopefully prove this businsses can stand on its own two feet. How much time i know not - per earlier release they said they had a plan to July 2024 - that isnt that great though if from 1/8/2023 onwards they may not be in a positition to confirm they are a going concern for the next 12 months after that point without further ongoing support. They are in the game though and if they dont need to expand then hopefully for them cashflow should be decent if they dont rack up "real" losses. I think the reality is its a business of dubious quality metrics as things stand.
today
The cost reduction initiatives announced on 28 April and 2 May 2023 are
benefitting EBITDA in line with the quantums and timings as previously
communicated
In line with the revised capital allocation policy announced on 28 April 2023,
the Board's focus remains on cash flow generation to repay Group borrowings,
following which there will be an evaluation of shareholder distributions.
and per company 28/4/2023
Covenants recently reset with lending banks at revised levels
to accord with the Group's business plan with an extended term to 1 January
2025
·
Agreement with brand franchisor to defer all further new
store opening obligations until FY25, saving an estimated total £13m in
capital expenditure over the two years FY23 and FY24
The forecasts show that the Group has sufficient liquidity from its restated facilities to finance its operations for the next fifteen months to the end of July 2024, including the requisite compliance by the Group with its banking covenants and debt amortisation as it comes due under those facilities. The Directors are confident that the business will continue
to trade for a period of at least 15 months following the signing of these financial statements and therefore that it is appropriate to prepare these financial statements on a going concern basis.
I agree that many Stockopedia subscribers will have lost heavily on Hostmore (LON:MORE) and Unbound (LON:UBG) and I did too. But (at risk of offending those who do this) why hang on to shares once knowing they are going wrong? I used to do that and it meant a portfolio with too many failures dragging it down. Now I want and have a portfolio where I’m confident about every holding in it …and just get rid fast when it’s becoming clear that the confidence on a share was unjustified! It’s worked wonders for portfolio performance.
Also a share that has fallen 50% from £1 to 50p needs to double just to get back to break even, and if falling much further it needs to multi bag,
Isn’t it better to cut the loss immediately we think we’ve made a mistake or a trading update that confirms we have and look to invest what’s left more successfully? That way we run our winners and cut our losers quickly before the losses turn from a nuisance to very costly. e.g I cut a big percentage loss on modest HOSTMORE stake inMarch last year at 80p and was relieved to be rid of it. Even that sale should have been sooner! But HOSTMORE would need to quadruple now just to get back to the price when I cut the loss.
With cheap online Brokers it’s so easy to act when we change our minds too, both when buying and selling.
That's a fact!
I hope you don't mind me adding my meandering thoughts to this discussion, as a relatively inexperienced investor (or speculator acc. to Mr Graham). I get the feeling that investing is very character dependent, and certain styles suit different people.
I guess that you are talking about stop losses here, so a conscious decision to cut a position at a certain loss (and probably better to define this criteria in advance to remove the timing issue that is implied). I have found this to be useful myself, in fact I still have one holding in the portfolio that I will not sell as a reminder what happens when things go wrong (down 74.9% as I type RBG Holdings (LON:RBGP). It wasn't a very big position, and is certainly alot smaller now !! As a reminder - it works wonders (and I can picture Ms Foulston enjoying every drop of the champagne).
I would say however that it suits a certain style of investing, and perhaps even that it suits particular market conditions. Alot of my current holdings would have been a good 20-30% higher only a few months ago - does that make them bad investments ? I didnt buy them at those prices, but there is no guarantee that they wont be a further 20-30% lower in another few months. So is the answer that I sell all of them and take the loss, only to watch the market recover a few months later ? Of course I could define an exit position based on overall market sentiment... along with its own set of complications.
I agree with the conviction based approach - but unless a direct piece of news prompts action, a company share price can drift down over time to prompt a stop loss on no news at all. For me a recent example was Volex (LON:VLX), which I considered to be a reasonable company priced too cheaply, where I sold as it hit a predefined stop, only to have it go up 30% since I got out. Well them's the breaks, as someone said recently (not that I'm a fan..)
I think that using stop losses almost implicitly requires a certain amount of market timing for that sort of strategy to work very well. Of course, as Prof Damodaran says, everyone is market timing to some extent, even if they don't admit it. I wonder however whether the buy and hold strategy works better over much longer time frames, with the caveat that some of the holdings will inevitably go to zero.
Anyway, enough of my rambling, got to get back to some work !
cheeky_minnows
I’m not a fan of stop losses. I much prefer selling for news reasons. Also my main investment style is value/dividend type shares and I also hold a lot of Investment Trusts which enable Investment all round the World as well as sectors like commercial property, renewables, private equity etc.
And for those, just selling because an arbitrary stop loss price has been hit doesn’t make much sense. E.g if a share is cheap when bought and the sector or markets drop further, and the already big dividend yield and where that Company or Trust is confident of maintaining or increasing the dividend, then it’s an even better bargain and a buy and not a stop loss sell.The same applies with some of the quality smaller Companies covered here. They are already bombed out so why sell if they get even more bombed out as long as news etc looks good.
A warning sign is when a share we hold is falling while others in the sector aren’t or are going up.
I look to hold my successful investments for multiple years. I.e the same style as Lord John Lee, but he has done that for most of his Investment life, whereas I only cottoned on a few years ago,. So whereas John Lee is getting 100% and more a year just from dividend every year, I’m nowhere near that stage yet.
If you or anyone reading this wants to know more about John Lee then if you haven’t seen it there’s an excellent account of his talk at a recent Mello event posted by ShoeShineBoy a few days ago.
Here’s the link to it:-
https://www.stockopedia.com/co...
Hi Ken Mitchell, thanks for the reply, I understand your comment a bit better now. I think that there is a whole discussion about levels of conviction ! but that is for another day :o)
I too hold quite a few Investment trusts in my portfolio but even here there appears to be an increasing litany of impending disaster! Just in the last few days there have been further negative developments in quite a few of my holdings (Digital 9 Infrastructure (LON:DGI9) , Thomaslloyd Energy Impact Trust (LON:TLEP) , Warehouse Reit (LON:WHR) , Impact Healthcare REIT (LON:IHR) ). These were all bought as income plays but there is little doubt that like many investors clearly did I should have run for the exit when gilt yields and inflation started to climb. I am hopeful that in a few years time(!) inflation and BoE interest rates will fall back and if they survive these income plays will be back in favour.
Hi ACounsell
Just a brief reply as the SCVR threads get so few viewings beyond the first day, so it’s not worth the time taken.
But just in case it helps , my tactic with Investment Trusts and often with shares too is to buy after big falls like the recent one for many shares and Trusts. Except in extreme situations these big drops are usually buy opportunities and not the time to sell.
I hold over 20 Trusts and the worst performer is Henderson Far East Income (LON:HFEL) down 20%. Dividend is now 10% and they’ve increased it for 16 years running, albeit so far at the expense of capital gains. My other losers are all down less than 10% and those losses more than covered by the dividends. The biggest winners, bought on a big Mining Sector dip in 2015 and topped up in covid crash are up between 140% and 325% and that’s excluding very big dividends.
BRWM is now the best of the 3 for dividends and for investing in THE big Miners worldwide.The other 2 are CQS Natural Resources Growth and Income (LON:CYN) Blackrock Energy and Resources Income Trust (LON:BERI) as well as Blackrock World Mining Trust (LON:BRWM) All 3 have dipped recently and now could be a good time to check them out.
Even my Commercial Property Trusts bought in the covid falls at rock bottom prices are up now and Aew UK Reit (LON:AEWU) is up over 100% with dividends added, and that’s after the big recent sector falls. So the buy low tactic for Trusts often works.
I also use Investment Trusts to invest all over the World and to diversify and in more obscure UK sectors, like Commercial Property and Renewables, Private Equity etc. So I hold Japan, Vietnam, Europe, US, Asia, and other Countries or regions too.
Of course you might well do all of this and more already!
Vietnam looks especially interesting and have already been very big winning Trusts this Century. E.g check out VinaCapital Vietnam Opportunity Fund (LON:VOF) and VietNam Holding (LON:VNH) . Big plus with VOF is the dividend on top. Both are at undeserved discounts.
That was more than intended but might be a useful starting point to cash in on the many Trust bargains now available.
Check them out here. This page is for the Vietnam Trusts. DO read their very good monthly updates:-
https://www.theaic.co.uk/aic/f...
Nice move up by Ten Entertainment (LON:TEG) this morning, about time too! Valuation anomaly compared to £BOWL.
Hi Paul, would it be possible to get your thoughts on ME International (LON:MEGP) latest results please if you have time? Still seems to be on a reasonable valuation to me despite increase in SP over last year as well as highly cash generative. I hold. Thank you!
Hostmore (LON:MORE) has long had some dreadful reviews online…I’ve asked mgt about it previously & been told it’s non meaningful compared to their own internal CSI scores….they’ve now been joined by some surprisingly fulsome 5* reviews that read as if written by the staff who’ve been lavishly name-checked therein..but not enough to offset the 59% of 1* reviews that carry the stench of a failed restaurant format.
yes it’s cheap…but a restaurant with unhappy customers & poor sales numbers doesn’t strike me as a natural home for investment monies
As we've said before on here you really shouldn't be reading TrustPilot if you want an accurate view of customer satisfaction.
If you imagine how many hundreds of thousands of people pass through TGI Fridays over time and Trust Pilot has 706 reviews in total that should tell you just about all you need to know. Basically Hostmore (LON:MORE) doesn't pay TrustPiot so they have a low score.
I think it was Planetx who can give you a run down of their business experience with TrustPilot
This is not a point about Hostmore (LON:MORE) per se - it's a general point about using TrustPilot as an investment case insight tool.
Fair comment….but I wouldn’t feel it sensible to totally ignore it either…especially as they seem worse than any of the peer group eg Wagamama ..which could be a clue as to something underlying?
I accept the small sample size is potentially skewed but some of the details..if as reported…seem to indicate a potential explanation as to why LfL growth is so elusive .
Actually having now looked more widely at reviews on other sits eg Trip Advisor & Google reviews are far more numerous & less poor than Trustpilot….not great…& Trip Advisor looks suspect as most 5* reviews are from new reviewers…& middling to poor reviews are from established reviewers….so in essence it looks impossible to adjudge as to whether TFI’s are pleasing customers or not
almost certainly false if the review is along the lines of naming staff by name. 'we were met by the smiling manager, Nina' or 'Jacob our waiter chatted to us all evening' 'brian made the most delicious cocktails'
how many reviewers bother to get to know their serving staff. all those look overtly false to me.
eg Served by the amazing Nicholas ( alias Spider ) today at the Norwich store.
Saxon at Halifax branch is the best barman in Halifax!
The food was served quickly and was lovely.. our waiter was called Harrison.
Our favourite waitress is Laura who always goes out of her way
any review that is not 5* doesn't mention a name.. the reason..., because any low and scathing review is realistic and genuine !
Hi rhomboid1
Agreed. The problem fundamentally is you need to ignore 1* reviews as these are written by people with an axe to grind and likewise 5* reviews as these are written by disciples (friends/staff etc.), so both are unreliable indicators in my view.
2/3/4* are more representative but the sample size is just 150 so again I'd just ignore as it is far too small to judge.
Unfortunately I would also ignore reviews from companies with very large numbers of reviews because these will inevitably be paid for subscriptions and that comes with active management of your rating to make sure you're seen in a positive light.
In this case I'd agree with management that their internal customer satisfaction scores are probably far better and much more accurate. However, whilst we might get told those scores we can't effectively audit them ourselves, which doesn't help!
So many fake reviews on Tripadvisor. Someone even got his garden shed to be the top restaurant in London, a few years ago. He used to write fake reviews for businesses, he wanted to highlight the issue.
Ramsdens Holdings (LON:RFX) excellent interim figures, out today: "PRETAX PROFIT ROSE 68 PERCENT TO 3.7 MILLION STG"
Was H2 pre tax profit 6.1m, so reduced?
Gross profit also down from 22.5m h2 22 to 20.5m h1 23?
Hi Anders,
Ramsdens Holdings (LON:RFX) have a H2 profit weighting as they make a significant amount of their profits from exchanging foreign currency for summer holidays. If you compare H1 22 with H1 23 you'll get a more accurate and favourable indication of their performance rather than H2 22 to H1 23 :-)
This also included additional expenses for opening 6 new stores, compared only 2, in the same period last year.
Great, thanks
Ramsdens Holdings (LON:RFX) have a H2 profit weighting as they make a significant amount of their profits from exchanging foreign currency for summer holidays
I know some people are slow to adapt to progress but I haven’t taken cash abroad for more than a decade. It’s easier and cheaper to use a cash point in the resort and even easier to pay digitally. I’m in France right now for over a week and haven’t touched a Euro note except to tip a waiter.
So I ask: how long will this revenue steam last?
Ramsdens Holdings (LON:RFX) I take £s and change in countries I visit in Asia. ATMs nearly all have fees, even with a credit/debit card, which does not have any forex fees, it is still cheaper usually to change cash, but many uk banks do charge around 3% forex fees. Many places don't take credit cards or they may charge a 3% fee, cash is still king in many countries. I do occasionally buy some US$s, which are required for some visas on arrival and is the easiest currency to change, some areas only change $s. If I did want to buy a larger amount of foreign currency, say over £750, I would buy online from dealers like AlfaFX, who have competitive rates and free delivery.
I agree that this will be a declining part of the business, many younger people use cards or digital payments all the time.
Yes, I agree BnB, think cash in the medium / long term will decline. Assume that's why Ramsdens Holdings (LON:RFX) are introducing a multi-currency card this Summer.
Terrible for waiters prospects of a tip!
Hostmore
See Rockwood building again up to 9%.
Always keep an eye on Richard Staveley and Rockwood .
Valuation is certainly bombed out compared to the carnage of the Electra debacle .
What is the latest with management ? Has the shower of shit PE crrowd that dumped their dross onto “us” gone or are trees self serving self enriching clowns still running the show ?
If there was a new motivated management in charge backed by a new set of activist shareholders might be worth a look .
But can’t back that previous crowd .
Sorry I’m too lazy to look this morning I’m sure there are some Hostmore experts on here .
Hostmore (LON:MORE) Guest Opinion Score improved to 83 in June from a dismal 74 in Dec and 68 in Dec 21. Shareholder Opinion Score has declined from Poor to Total Crap. [SP=21.8 Cap=27m]
Loved Mr Contrarians comment this morning - laughed out loud.
I guess these are the bombed out opportunities for the brave amongst us, but I remain too sore after the last debacle currently. Good luck to holders and those brave enough to give it a go.
Hostmore (LON:MORE) Just as another aside/scuttlebut......... I often meet up with friends from my old workplace and we sometimes go for a burger - quick, easy & convenient to meet at an out-of-town shopping complex due to everyones complex travel arrangements. On the last 6months of sampling I would say that TGI has lost a lot of its customers to other similar places - for example Bread-Meets-Bread which offers a far superior quality offering (probably the best quality burgers & fries I've had in the last 10-years).
I for one won't be returning in a hurry to TGI - there are way too many other alternatives and it needs to somehow differentiate itself.
Its a competitive market with a consumer discretionary product. Two thumbs down. A no from me.
Another point I forgot to mention which concerns me about Hostmore (LON:MORE) is that it has the additional cost of renting the brand name from the US owner. Can anyone remember what the % of revenue fee is for this? I think it was disclosed at the time of its demerger. The problem with this, is that it's a leak of cash out of the business, paying for the brand name, that probably hardly any competitors have. Hence putting TGIs at a significant cost disadvantage. Fine in the good times, but a lot more problematic right now. Also, is the brand name actually worth anything now? I know some readers here have questioned that in the past, perceiving TGIs as dated.
I've long held the view that TGI is a poor, dated brand and the fact they have to pay for it makes it even worse! Surely would be worth ditching TGI and coming up with a fresh, new brand from scratch?
Don't hold back planetx !
Thanks Paul, I see you'll cover Gusbourne (LON:GUS) here's a video/podcast of the results presentation by Charlie Holland, CEO & Katharine Berry, CFO. (Katherine just promoted to the board today.) Links: Video & Podcast.
Of the outlook, Charlie says:
"With these strong results, a fantastic harvest in 2022, the purchase of new land during the year and healthy inventory levels in our cellars, the Board continues to look to the future with great confidence as we further strengthen our position as one of the UK's most significant fine wine producers."
Good morning Paul and Graham, we hold a very mixed bag on RNS announcements today. Ramsdens I'm quite excited about, we had cause to be in Derby at the weekend and I was amazed to see a queue inside Ramsdens waiting to pawn or sell, and plenty outside looking at the shop window, quite a few upmarket expensive second hand watches there. It can't be just Derby can it? Also hold Hostmore/Concurrent and whisper it, Loop-up, the latter still hanging on in there but is their mention three times of the repayment or renewal of the £6 million to the bank of Ireland in September, rather ominous? I can see Graham has Ramsdens listed but all quick comments always appreciated.
Morning JASVFS,
I had a quick look at Loopup (LON:LOOP) and am amazed it's still trading actually. As always they make positive noises about orders, etc, but until the net debt position is sorted, then it's uninvestable to me. As you rightly point out, the clock is ticking on the bank debt, and I imagine the bank manager is likely to be having kittens about how they're going to get their money back here. Hence equity dilution very, very likely, and could be on horrible terms, or it depends on how much existing shareholders want to preserve the remaining value in existing shares. I recall the last fundraise was cornerstoned by one individual, who's sadly lost a packet on that trade.
LOOP is only £5m market cap, so too small & high risk for the main report. I might revisit it once it's got a placing away, I reckon it probably needs £10m+ fresh cash, in order to repay the bank, and continue trading with heavy cash burn.
Regards, Paul.
I think Loopup (LON:LOOP) is interesting with strong growth on the Teams side. Obviously the problem is the balance sheet and this makes it uninvestible (for me) at present.
The results which have been announced are “unaudited”, with no going concern statement, which my guess would be that that the auditor will not sign off the accounts until the Bank of Ireland loan is extended/ repaid (which presumably would need another placing).
However, the directors are expressing confidence (hopefully based on something) that the talks with the bank will end successfully. This is enough for me to decide to allocate some time (not money) to see if there might be a business worth investing in once the going concern issue has been kicked far enough into the future. Cenkos has a new note out today - raising FY23 forecasts and giving estimates for 2024 (for the first time).
The only interesting thing about Loopup is that it will soon go to a big Zero.
Thanks
My morning smallcap tweet: Contains a brain of truth
Niox (LON:NIOX) Rua Life Sciences (LON:RUA) DX (Group) (LON:DX.) Hostmore (LON:MORE) First Property (LON:FPO) City Pub (LON:CPC) Argo Blockchain (LON:ARB) Concurrent Technologies (LON:CNC) PCI- PAL (LON:PCIP), UP Global Sourcing Holdings (LON:UPGS)
◄NIOX (NIOX)► 2.5p special div. Co expects to pay further dividends from ongoing cash flow. [SP=62.4 Cap=265m]
◄RUA Life Sciences (RUA)► guides FY-Mar rev £2.2m up 34%. Pretax loss c.£2.3 to 2.4m, similar to FY22. Cash at hand £1.5m [SP=39.7 Cap=9m]
◄DX (DX.)► full and final settlement with Tuffnells Parcels Express Limited in relation to its claim against the Company. Terms are confidential. No impact on expectations. [SP=25.5 Cap=154m]
◄Hostmore (MORE)► AGM stmt - recent 22 weeks rev (adj for adjusted for VAT changes) 'broadly consistent' with the first 16 weeks of FY. But LFL has declined from -1% to -3% (last 22 weeks) so the last 6 weeks LFL must be c.-8%! TGI Fridays Guest Opinion Score improved to 83 in June from a dismal 74 in Dec and 68 in Dec 21. Shareholder Opinion Score has declined from Poor to Total Crap. [SP=21.8 Cap=27m]
◄First Property (FPO)► to make commercial property loans up to £20m. "With interest rates increasing and banks retreating from the commercial property lending market, the returns available in making relatively safe loans are potentially more attractive than investing in the underlying property." [SP=27.3 Cap=30m]
◄The City Pub Group (CPC)► AGM stmt - trading continues to be strong with recent 22 weeks rec yp 20% and LFL up 13%. Costs in line but starting to fall. [SP=98.5 Cap=101m]
◄Argo Blockchain (ARB)► mined 16% more Bitcoins in May than Apr. Has sold 33 Bitcoins. Maybe it should pivot to making bargepoles. [SP=9 Cap=55m]
◄Concurrent Technologies (CNC)► adds distributor for UK and USA, and additional territories. [SP=68.97 Cap=51m]
◄PCI-PAL (PCIP)► re patent dispute with its competitor, Sycurio (was Semafone). "Sycurio's US lawyers confirmed that Sycurio had illegitimately shared confidential information with Sycurio personnel." PCI Pal's confidential information "may" have been used at board level. [SP=55.48 Cap=37m]
In line: UPGS
"Maybe it should pivot to making bargepoles"
On fire Mr C! :-)
I see that Mike Ashley's Frasers (LON:FRAS) has continued buying more shares in troubled ASOS (LON:ASC) - it announced an increase from 7.4% to 8.8% yesterday. It'll be interesting to see how this pans out.
As mentioned in my weekend podcast, a press report suggested that Asos turned down a bid at £10 in Dec 2022. It's now 356p! Looks an interesting situation, although I remain of the view that the recent fundraise probably won't be the last, it looks in a real mess I think. But if a fight for control develops, and shorters close, then anything could happen to the share price! I'll get some popcorn :-)
Regards, Paul.
‘Asos’s suppliers began cutting their ties with the retailer after cover was withdrawn. “Lots of suppliers aren’t delivering as insurance has been lost,” one supplier said on condition of anonymity.’ From today’s Times bearish article re ASOS (LON:ASC) suppliers
Paul It is actually Wednesday today not Thursday in your header.
I hope you do not mind me pointing this out.
Thanks portugull! Why did I type Thursday, when I knew it was Wednesday?
Still I got the month and year right.
Now corrected, many thanks for pointing it out.
You might have been thinking of adding a 'sweet' to today's header and that made you muddle up the days
My first thought as well :)
VP (LON:VP.) - Vp, the specialist equipment rental business, today released ‘in line’ final FY’23 results & a positive outlook - despite experiencing softer conditions in some of its end markets (e.g. commercial real estate, HS2, rail strikes and new build housing). Indeed impressively, FY’23 revenues, adjusted PBTA, EPS & ROCE came in at £371.5m (+6% vs LY), £40.5m (+4%), 79p (+11%) & 14.4% respectively. This reflects solid performances in UK infrastructure (e.g. energy, rail & water) and RMI, augmented by a bounce back in International (AirPac & TR), where EBIT margins expanded to 8.1% (+4.9%) on sales up 23.9% to £38.1m. This puts the stock (at 650p) on attractive trailing EV/EBITDA, EV/EBIT & PE multiples of 4.3x, 8.6x and 8.2x – whilst similarly paying a generous 4.2% dividend yield. We believe this is simply too cheap for a best-in-class, GDP resilient business with a proven track record. Link: https://www.equitydevelopment....