Small Cap Value Report (Weds 1 Feb 2023) - DX., RCDO, WIX, INS, CODE, BLV, RBGP, WYN, TND, GMR, MTEC

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Thankfully a bit quieter for news today. This all looks a bit boring, and in-liney, so I might start with Porvair (LON:PRV) from the backlog -
Paul's Section:
First, some short sections left over from yesterday, which I did last night -
DX (Group) (LON:DX.) - Trading Update - £173m - Paul - GREEN - 29p (down 2%) - H1 trading in line with expectations. Confident in FY 6/2023 outlook. Net cash £36.4m. Good pipeline & new business. My view - looks a convincing turnaround, and valuation seems attractive value.
Ricardo (LON:RCDO) - Trading Update - £339m (in line) - Paul - AMBER - 517p (down 5%) - H1 to Dec 2022 traded in line with expectations. FY 6/2023 guidance unchanged. Strong order intake & closing order book. Net debt £31m. My view - shares have a had a great run, and now look sensibly valued (fwd PER 15x) instead of cheap.
Wickes (LON:WIX) - Trading Update - £395m - Paul - GREEN - 152p (down 4%) - FY 12/2022 in line with expectations (£72-76m adj PBT). Impressive 3-year LFL sales growth of +23%. Cost headwinds - bringing forward staff pay rise will cost extra £3.5m. Also energy will be £10m more in 2023 than 2022. Not clear if those costs are in existing forecasts or not. My view - an attractive value share, with reasonable PER, good yield, and nice balance sheet.
Instem (LON:INS) - Trading Update (in line) £143m - Paul - GREEN - 630p (up 7%) - FY 12/2022 says profit was “materially in line” with consensus adj PBT forecast of £7.9m (H1 was £3.2m, incl £0.9m forex gain). Strong growth, helped by 3 acquisitions. Salary inflation hit H1, but recouped in H2 from price rises & contract wins. Closing cash £13.7m. Last bal sht looks adequate - relying on up-front cash from customers (like many software cos). Outlook upbeat, further growth, strong order book. My view - this looks good, worth a closer look I think.
Northcoders (LON:CODE) - Trading Update £24m - Paul - AMBER - FY 12/2022 in line with expectations. Tiny IT training company. Small recent placing at 300p done. Going for rapid growth, and good visibility for 2023. Might be worth a look, but £24m mkt cap seems steep for the early stage, and small size.
Belvoir (LON:BLV) - Trading Update - £69m - Paul - GREEN - 183p (down 2%) - Reports that profit (PBT) for FY 12/2022 is expected to be slightly ahead of management expectations. Finncap lowers 2023 forecast by 13%.
Net cash of £1.1m at Dec 2022.
H1 2023 expected to be impacted by more expensive & tighter availability of mortgages.
Signs of a recovery starting in Jan 2023, expected to “build slowly over the year”.
Lead times of up to 5 months mean improved performance not expected until H2 of 2023.
Overall guidance is for FY 12/2023 profit “to be slightly below 2022”, then return to growth in 2024.
My opinion - this is absolutely fine, I think, given well-known macro problems. Finncap’s revised forecast is 18.2p EPS for 2023 (PER 10.1x), with a 9.5p divi (5.2% yield). I think that’s an attractive entry price, for long-term holders. A softer H1 in 2023 won't matter longer-term, so I see it as a buying opportunity rather than a threat. Plus you collect in a >5% yield whilst you wait for earnings & the share price to recover.
RBG Holdings (LON:RBGP)
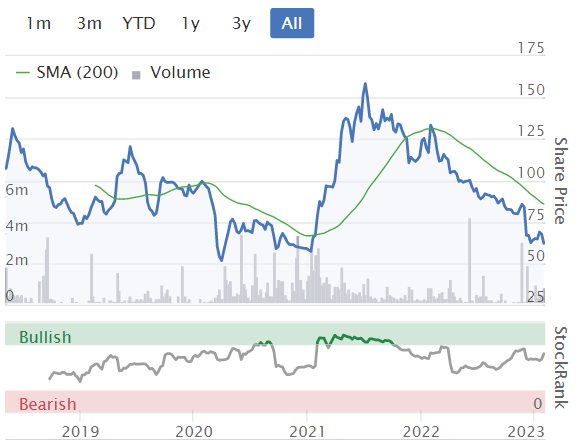
58p (yesterday's close, down 12%) - mkt cap £55m
Trading Update & Board changes
This is very unusual indeed - a CEO (also major shareholder) being fired, acrimoniously -
The Board has lost confidence in its Chief Executive, Nicola Foulston, as a result of cultural concerns and the execution of the Group's strategy; her employment contract has been terminated with immediate effect.
“Cultural concerns”? What on earth does that mean? It annoys me in situations like this, that private investors are in the dark, but behind the scenes no doubt word is spreading about what’s actually been going on.
It wasn’t long ago that the (now former) CEO was being lauded by everyone (including me!) as seeming impressive, and having a strong track record. She came across really well on webinars for example. Although I know there were objections to excessive Board remuneration amongst some shareholders.
Moving on from this shock, the trading update for FY 12/2022 strikes me as pretty solid.
Key points being -
Trading in line with expectations, and a footnote gives the numbers (very helpful) -
(1) RBG understands that consensus market expectations for the year ended 31 December 2022 are for revenues of £49.5 million, Adj. EBITDA of £11.2 million and Adj. PBT of £6.9 million (Source: FactSet)
It says the balance sheet is strong, which it isn’t by my calculations. NTAV is only about £7m. Given that a lot is tied up in receivables, normal for lawyers, that leaves the business dependent on bank debt.
We’re not given a figure today on what net debt is now. Just that it is within facility agreements. Net debt was £17.3m at 30 June 2022, and at a guess I imagine it’s probably higher now, hence not being disclosed today! Confirmation that a second interim divi will be paid suggests that there’s probably not a problem with debt (or the divi would have been pulled).
Divisional performance seems to be saying that the main legal services businesses are doing OK. The problem division is litigation finance, called LionFish, which we already knew was problematic. The news today sounds upbeat on that, saying that a number of potential offers are being assessed for its disposal. Potential upside there, I wonder, although we don’t know the terms of any potential deals, which might have to come with a dowry, who knows?
My opinion - it’s a shock to see the CEO being booted out on obviously a big falling out. Although things were looking a bit wobbly after the previous bombshell announcements about the LionFish subsidiary going wrong, which we already knew about.
At this stage it’s just guesswork whether more bad news is lurking.
If the balance sheet were more solid, I’d be tempted to have a little flutter here, as a speculative recovery situation, but don’t feel I’ve got enough information to make a rational decision at the moment. The main thing is that the core business seems to be trading OK, which could make it worth considering. Hence I’ll go amber on it.
What do readers think? Is the glass half empty, or half full? I'm not sure.
I'm not keen on the whole sector - as mentioned many times before, there's a conflict of interest between the big fee earners, and outside shareholders. Generally the lawyers who floated have not been good investments for outside shareholders. The main purpose of the floats, is for the partners to cash out, in part, or on a deferred basis. They'd be better off remaining private businesses, I think, as traditional partnerships or LLPs.
Made Tech (LON:MTEC)
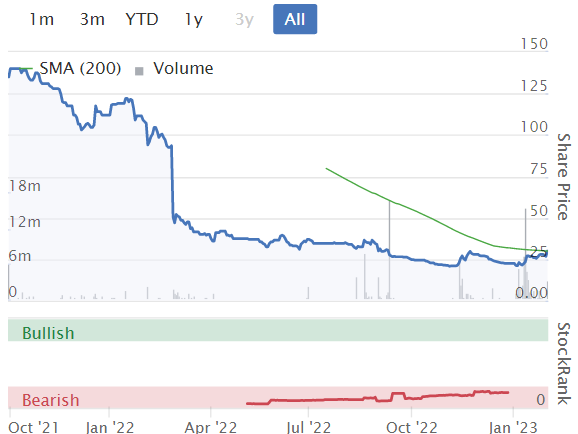
30.25p (up 11% at 11:58) - mkt cap £45m
H1 adj EBITDA only £0.5m, but it claims this is in line with exps, and says on track to hit £3.9m for FY 5/2023, a big H2 weighting.
Recent large contract wins from public sector.
Record contracted backlog of £48m.
Balance sheet is indeed strong (I’ve checked!), with net cash of £9.0m (down from £12.3m in May 2022).
FY 5/2022 accounts - I’ve briefly reviewed - big share options charge of £2.4m LY, and no divis. Capitalised £1.8m of payroll into intangibles last year, which inflated EBITDA.
My view - investing here is a leap of faith that it will be able to start making genuine profits. That didn’t happen in H1, so there’s a heavy reliance on H2 delivering better performance. Growing this fast, things are bound to go wrong along the way.
The over-priced Sept 2021 float was mainly to allow existing shareholders to sell shares, banking £70m. CEO & COO are still the 2 largest shareholders, might they be tempted to buy it back on the cheap? (as Mayfair Capital is doing with £BUMP , at one tenth of the IPO price)
I quite like some aspects of this share, but as we’ve recently seen with Tpximpact Holdings (LON:TPX) the wheels can come off quite easily with these high growth, hyped up IT contractors, when things go wrong. MTEC looks a lot safer though, as it has sensibly avoided taking on debt, which is what has killed TFX’s share price. Speculative flutter might have some attractions, but on balance it's too speculative for me, and risk:reward doesn't seem that great. I’ll go amber on this one.
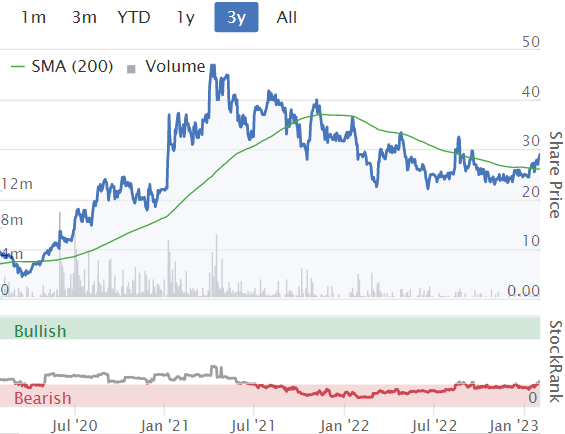
Stockopedia isn't impressed, with a low StockRank -
Graham’s Section:
Tandem (LON:TND)
Share price: 275p
Market cap: £15m
This is a small company, even by the standards of this report. But I know that many micro-cap value investors, including myself, have previously bet on it. At one stage this was the largest position in my portfolio. I’ve owned it twice, but currently have no position in it.
What is it: it’s a designer, developer, distributor and retailer of sports, leisure and mobility products.
When I think of Tandem I immediately think of the classic bike brands Claud Butler and Dawes, but there are many other bike labels in the group.
There’s also the classic golf equipment company Ben Sayers, the outdoor equipment company Hedstrom, and a wide range of licences for children’s toys and bikes:
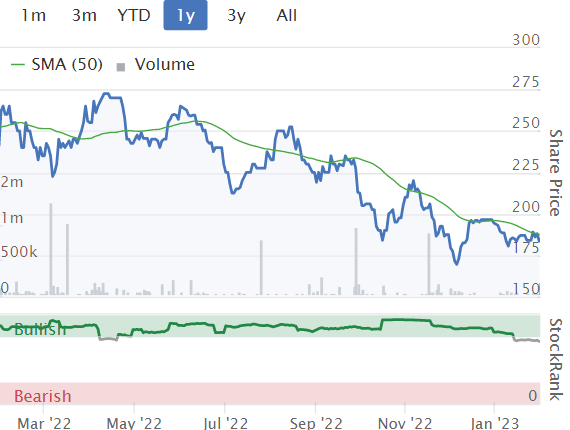
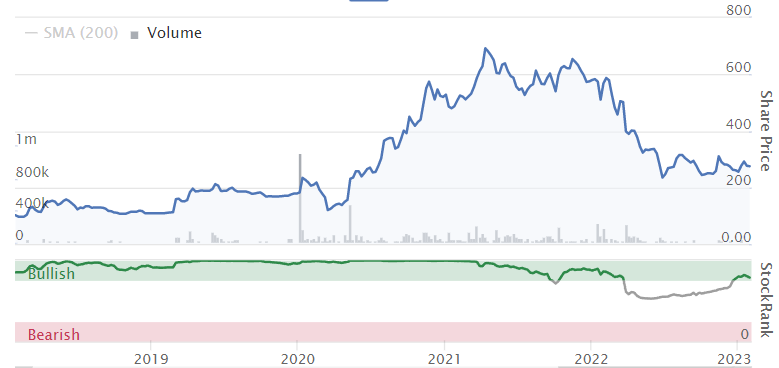
The group’s share price has calmed down after a Covid-related surge:
My first experience owning Tandem was traumatic. Not just because of the losses I experienced, but because things always seemed to go wrong for them. They were the unluckiest company I ever came across. Then at some point I started comparing the value of the dividends to the value of management remuneration, and decided I’d had enough.
The second time I owned TND shares, things went much better. It was the 2019-2021 period, when they started treating shareholders properly. I managed to sell out during the Covid spike, thereby recouping most of my earlier losses (see comments in the archive, e.g. here).
Let’s check in on today’s trading update for the full-year 2022.
Key points:
Revenue at £26.7m is in line with market expectations but note that this is down 35% versus 2021. Stockopedia reports that the consensus revenue forecast was £27m.
PBT is also in line with expectations (according to Cenkos, 2022 PBT is expected to be £0.9m).
Stock inventory levels closed the year down by 40% compared to 2021, so that should at least provide a cash flow boost. Cenkos expects that net debt is £2.7m.
Toy, Sports & Leisure - this division had a strong December but full-year revenues were still down 11%.
Bicycles - revenues fell 52% as Covid-related demand evaporated.
Home & Garden - revenues down 55%, as people no longer have to spend so much time at home or in their garden!
eMobility - this division includes eBikes and eScooters. Sales rebounded and were very strong in November and December. Perhaps Tandem are right that this division has good long-term potential. But full-year sales are down 46%.
Outlook
As we expected, 2023 has begun slowly for the Group with a slowdown in our Free-on-Board (FOB) sales as a result of an early Chinese New Year, and as consumers remain cautious with their purchasing. However, we expect to see a different trading pattern this year, and will be targeting between 8% and 12% like for like growth on the full year.
In case you haven’t heard it before, Free-on-Board is a term in shipping - Tandem’s products are typically manufactured in China and shipping arrangements/distribution are a key element of Tandem’s expertise.
Reading further, children’s licences sound promising this year. Gabby’s Dollhouse has been added to the portfolio (I’m familiar with this show, unfortunately). Also:
“...there are several high-profile movie launches based on our existing license agreements such as Barbie, Spider-Man, Paw Patrol, Trolls, Transformers and Baby Shark, all of which will provide additional sales opportunities.
Other initiatives:
New e-bike models being launched
The Jack Stonehouse website has been modernised
They are finally making a real effort to use social media (Facebook, Instagram).
The new warehouse in Birmingham will be ready “within the next few weeks”.
My view
I am going to have to very reluctantly take a positive view on this share.
For a company that has been around for so long, and had so many false dawns, it feels wrong to take an optimistic view on it.
However, there are three reasons I’m going to take this positive view:
They shook up the management team with a new CEO in 2022.
Using websites and social media to their full potential is a no-brainer and has the potential to transform performance over time.
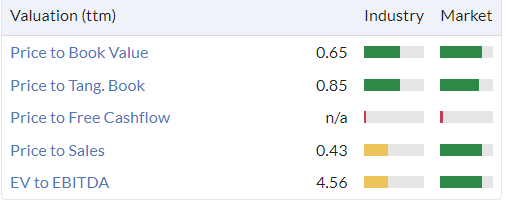
Valuation: they aren’t cheap against FY 2022 earnings, and formal FY 2023 estimates are unavailable. But if you consider the price/sales multiple and historic profit margins, I think it once again looks like a bargain.
Price to sales and price to book, according to Stockopedia:
Historic profitability:
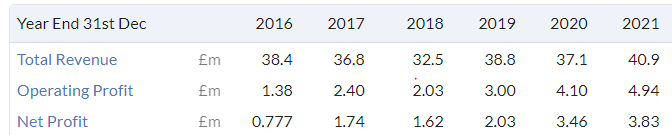
Don’t be fooled by its cheapness, however - holding TND shares can be a stressful way to live, and any profits made by shareholders are hard-earned!
Gaming Realms (LON:GMR)
Share price: 28.9p (+2%)
Market cap: £84m
This is a “developer and licensor of mobile focused gaming content”, and it also brings us a trading update for 2022:
The Company is pleased to confirm that it expects to report FY22 revenue of c.£18.7 million and adjusted EBITDA* of c.£7.7 million, up 27% and 36% respectively year-on-year.
What it does: Gaming Realms owns Slingo, a cross between slots and bingo, that is licensed by a wide range of partners in the gambling industry.
The impressive growth rates are explained by its expansion into new markets across the US, with partners such as Draftkings, Caesars and 888 (in which I have a long position).
It’s also expanding in Europe, e.g. with Pokerstars (owned by Flutter Entertainment (LON:FLTR) ).
Board changes - the CFO becomes CEO, and the young FD becomes CFO.
Comment by Exec Chair:
The Company has delivered another strong, full-year performance with growth coming from both existing and new markets… with the release of new Slingo formats during the period, which have proven to be very popular. We are seeing good momentum, and backed by an exciting commercial pipeline and new games, we are confident that we will achieve further progress in 2023.
With respect to the outlook, note that “the Group’s expansion into further new markets during Q4 FY22… has continued into Q1 FY23”.
My view
This strikes me as interesting. The company appears to have turned the corner to profitability, and has paid off an outstanding loan with cash so that it is now debt-free.
The abbreviated income statement numbers from Stocko are copied below. Note that the revenue number announced today is below Stocko’s consensus revenue forecast, so perhaps it came in below expectations. But the RNS does not make any reference to prior expectations, so I’m not sure.

I should also remind readers that we can expect an enormous gap between adj. EBITDA and reported net income, as is the case with many companies
But I think the key point is that Slingo, GMR’s primary asset, appears to be growing in popularity and is in very strong demand from major players in the betting industry. That’s what really matters here.
The price tag of £84m for the company’s market cap does look like a stretch at first glance, but I’m open to the possibility that it’s justified by possible earnings momentum over the next few years. So I’m going to take a neutral view on this stock for the time being, pending further information and research. Could have potential.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
LON:BLV fundamentals look very interesting. The chart isn't looking positive so I'll hold of a little - one to keep an eye on for the long term!
Sorry if this is a too small micro. Technology Minerals (LON:TM1) has been trading over 20 times the usual volumes today. I hold as a high risk battery recycling and Lithium play. No news for such volumes. Any other holders?
Anyone ever cast their eye over Pollen Street Pollen Street (LON:POLN)? After their restructuring quite a SP decline and significant discount to net assets which have held up.
I have spent a few hours researching Pollen Street (LON:POLN) and opened a position today. It is a little complicated. They have merged (via a reverse takeover) a credit portfolio (previously the Honeycomb Trust) and an asset manager - Pollen Street - which manages private equity and credit funds. So you have a credit portfolio which is quite short duration and cash generative and an asset manager which earns both management fees and performance fees. So pretty similar, but much smaller than, Intermediate Capital (LON:ICP) which I also own.
Under the reverse takeover they issued new shares to the Pollen Street shareholders. Half of those shares are ineligible for dividends until 2024 so the dividend per share calculation is more complex than usual but on my workings it yields 10.8% today, moving down to 9.5% in 2024.
It currently trades at close to NAV for the credit portfolio - so if you believe the valuation of the portfolio you are effectively getting the asset manager for free. Assets under management have grown fairly quickly over the last few years so if this is sustained then it could be a very attractive entry point. I would like to do some more work on the investments made by the fund management business to understand the business model better but their track record in the presentations relating to the restructure looks impressive.
My summary buy note for my records was:
As always - DYOR.
Thanks Tristan, I am hoping your analysis holds good to recoup some of my losses in the Honeycomb Trust (now Pollen Street (LON:POLN) ) which I had bought for the dividends.
Thanks for sharing your thoughts Tristan. I share some of those, and the valuation/discount essentially swings on the value of the investments, with all PE-related assets being discounted down across the market. In terms of re-rating this might revert to a "normal" level of discount but may take time but there is the dividend to pay compensate for patience. I also hold ICP.
I had a look at this a while ago and from what I could see the Honeycomb shareholders got a very poor deal as part of the merger with Pollen Street - from memory they effectively gave up half their company for a stake in a fund manager (Pollen St) which I suspect has very little value (I don't think it's making a profit but might be wrong). I suspect it may take a while to regain the trust of markets so I decided not to get involved, but good luck if you decide to take a position. I generally don't like these hybrid investment company-fund managers as there could be obvious conflicts of interest in my view (Intermediate Capital which I do hold is slightly different as most of the value of company is in the asset management side - the investment company is really just a vehicle to help launch new funds).
LDG Logistics Development Group .
Anyone following ? or invested .
They hold big chunks in Finsbury food and Alliance Pharma , are sat on mountains of cash and smart investor Richard Griffiths has jumped on.
Ill attempt a sum of the parts valuation tonight but they seem to be on big discount to NAV with a few major holdings having rerated .
I did jump in and out a month ago, only jumped out because it was all bit confusing with dbay and LDG .
Yes have a small holding Logistics Development (LON:LDG), nearly sold out this week but will wait and see what happens. I don't know Richard Griffiths.
Logistics Development (LON:LDG) I also have a small holding after Simon Cawkwell flagged it a while ago.
Following on from your "leftovers" from yesterday I felt compelled to comment on the analysis from Graham on the Trading statement from Somero Enterprises (LON:SOM) ( Ihold ) yesterday . I realise that the stock market is a ruthless place when it comes to a "slightly " below expectations report but I feel that on this particular stock a more long term approach is justified - to say that Graham is sitting on the fence would be an understatement which in my opinion and if you look at comments from Paul Scott(29/12/22) , Mark Simpson -twice in the last 3 months (28/12/22 and 2/11/22) and Edmund Shing (25/9/22) and numerous others over the last few years is not justified -if anything it is a buying opportunity . I am not a trader and my investments are designed to provide an income from my SIPP and since I have held the shares Somero has been a share "hero" from both a capital point of view ( the share is up aprox 40%) and revenue (I have received dividends in the region of £7k .) In view of the constant negative that it is a cyclical I constantly review my position and so far I have concluded that I would be crazy to sell the shares and should be looking at adding to my holdings ( problem is that I am at the maximum from a diversification point of view) . Following the TS Finncap issued a research note and I quote " We lower the TP price from 808p to 760 p, with a F/Y 23 target P/E of 16.9 * and a dividend yield of 3.7% . This points to significant upside to the current P/E of 9.5* and a yield of 6.6% " This kinda reinforced my thinking and hopefully it will help in getting Graham off the fence !!!!!
The shares are trading at around 400 today.
Petrotal (LON:PTAL) I think a few others follow this oil producer in Peru so be interested in others views. Great increase in reserves released today with a risked NAV now closing in on 140p verses a 45p share price and based on oil price in the $80 range.
Positives -
Negatives
timarr I found your post this morning on Companies with increasing dividends over 19 years very thought provoking.
I hold 1 Company GB (LON:GBG) which currently has a Stock Rank of just 22. Only James Latham (LON:LTHM) of the 11 Companies you highlighted has a Stock Rank in the 90's at 93.
I am looking more and more at Companies with a really good track record of paying ever increasing dividends.
Interesting conversation on dividends. There are a few Stockopedia dividend screens but they seem to stop on 10 years. I hold about half my portfolio in investment trusts. The dividend achievers list on AIC is highly impressive www.theaic.co.uk/income-finder/dividend-heroes - 56 years and City of London Investment Trust plc City of London Investment Trust (LON:CTY) is the clear winner, I believe!
I find this topic v. interesting too.
For me, the interesting part is the assumption that because a Co. has increased its dividends for n years looking back, it is more likely to be a reliable dividend payer in the future than another Co that has no such track record.
Looking at humans you see there is increased mortality amongst the young and the old.
From the performance of recent IPOs I think there is evidence of the unreliability of newly listed Cos.
I am not sure if there is data to suggest that older Cos are less reliable divi payers,
but it feels sensible to me.
Clarkson (LON:CKN) has increased theirs for 19 years also I think
Tandem
I would be very careful in next 12 months with tandem .
The bicycle sector market is in capitulation mode with huge orders sat in Taiwan with all manufacturers trying to cancel .
This can only cause margins erosion, stock build, and cash drain.
No sign of a market uplift just warehouses filling up with stocks in both UK and Taiwan.
Incoming CEO I am led to believe is not particularly good .
Probably at least 12-24 months for the situation to unwind.
Halfords confirmed the headwinds, Specialised laid off 8% of its workforce, its tough out there on the two wheeled front.
One positive freight rates have normalised.
It is also pretty poor form in this day and age they dont have credible websites and social media, the chances of Tandem doing something credible when compared to the competition is pretty low, there are some sharp brands out there with great websites, social media and engagement.
Dawes is good historic brand, as is Claud Butler but getting momentum into a brand requires a concerted effort, cash negative on these brands for a year or so to really build these back up strongly and that needs a brave CEO to commit .
I acquired Holdsworth from tandem a few years ago for an unbelievably low price but relaunching that and finding momentum was much harder than I thought, took a huge company wide effort and we even ended up with the Holdsworth team riding the Tour de Yorkshire against the worlds best pro teams, complete with 1974 ford escort . Nightmare on the inside but looked good externally.
Anyway , big sector wide red flags and brutal headwinds, if Specialised are under the cosh the industry is under the kosh
Interesting insider insight from planetx, thanks.
The situation is very similar in the Golf and Fishing Tackle trades. The post Covid unwind is still hurting both, long lead times have created havoc in terms of UK retailers and wholesalers having to place orders a year ago when they couldnt get enough stock and now dont need it cos the demand has dried up. Angling Direct (LON:ANG) may well survive and if they do will end up with a much larger share of an albeit shrinking market but it could be a rocky road.
Morning.
I'm a shareholder at RBG Holdings (LON:RBGP) and was shocked to read the RNS yesterday. I'd love to know what really happened and what they mean by "cultural concerns"?!
Nicola Foulston, holds 12.5% of the shares, so I wonder if she will dump them in the market?
I thought that she always came across well on webinars and had quite a direct and no-nonsense approach.
I'm not sure what i should do with my holding but I am underwater (I know.... I'm anchored to the price I paid) - I think a lot will depend on the communication from the new CEO and board and their strategy (or change in strategy) - I'd like to see them get in front of investors ASAP and take questions!
Love the podcasts Paul.
Adios.
Tricky one - short term I'd expect the share to be under pressure. I'd imagine Nicola will want to maximise her return from her 12.5% so I don't expect a fire sale (unfortunately - as I'd pick some up if they got really cheap :) ) but I do expect any upwards momentum to be held back by the perception (or reality) of an overhang.
A sale of the litigation business might be a positive catalyst and a PE of 7 is certainly cheap but personally I'd want more information on the debt position before being persuaded to invest. As Paul says the payment of dividends suggest debt isn't an issue but then you can never quite tell. Boards have taken stranger decisions! If Nicola can offload to an institution that might also act as a positive catalyst but they will want it at a discount so it depends on her mindset.
I guess the question always has to be if you took the loss and reinvested the proceeds would that look a better investment than holding on and waiting for a re-rate. I know I have been guilty of waiting for shares to rebound that has taken forever and so that effectively becomes dead capital that could have been much better served elsewhere. In fact I've probably still got a few of those!
Dont forget also the new incoming CEO will probably require a gazillion free shares with no deliverables .
RBG should actually be RBGT , Real Big Gravy Train,.
The red lights were flashing to anyone that cared to look when the FD was gifted I think a million shares at zero cost for reaching the stunning achievement of, err, turning up to work .
Its a bonkers investment gravy train, shareholder theft and blue collar crime right before your eyes .
Run for the hills like Nicola although no doubt her shares were probably free .
We as shareholders should be offended by companies like this.
Perhaps we need a readers poll of what "cultural concerns" means and then if anything comes out in the wash later we can award the person closest with a prize. I feel this statement is the corporate equivalent of a "spot the ball" competition.
I interpreted the RNS to mean "Nicola proposed a change of strategy that the Board vetoed and she called us a load of ******s".
There must be the slim chance that she has the motivation, contacts and firepower to mount a hostile takeover of RBG Holdings (LON:RBGP).
(disc: no position)
Hi Graham,
Will you be covering XLMedia (LON:XLM) today? The stock is close to a multi year low and i'm wondering whether its now in value territory. Don't worry if not !
Suggest you look at some of XL Media's websites and decide if you believe they are quality or not.The investment website has some interesting articles.Do not understand why XL Media shares fell so much and have struggled to recover and that worries me that insiders might know something private investors do not.
You have to think of XLMedia as a bit of a gamble. They are basically completely re-inventing the company. The old business involved getting their websites (there were many) on the first page of Google searches and earning fees re-directing to gambling websites. Google stepped in and manually adjusted their algorithm to cast their sites into the pit of obscurity. XLMedia tried but only a very few were allowed back by Google. So they've been spending their money buying up sports betting sites in the US to create a new business. It relies on a relaxation of anti-gambling laws in the US which is happening on a state by state basis.
I have a holding, but because of the risks it is a small one.
Made Tech (LON:MTEC) looks incredibly good value following the H1 results, so hopefully Paul will help explain why it warrants such a low valuation.
Made Tech (LON:MTEC) looks incredibly good value following the H1 results, so hopefully Paul will help explain why it warrants such a low valuation.
It’s a combination of factors including:
The discrepancy between EBITDA and actual reported profit, owing to share based compensation. The SBC is scheduled to reduce in the future but investors will be looking for proof of that. Until then, the share price reflects the small loss rather than the adjusted earnings.
A profit warning last year caused by difficulties hiring sufficient staff to meet the resource plan has rocked confidence. These issues have been resolved in the short term by the use of contractors - but at the expense of margin. However are reported to have eased now with an increased complement of permies, which should produce higher margins in H2.
Tech is a bargepole sector still and MTEC is a recent IPO floated at too high a price
Ultimately, after the above, it’s somewhat of a show-me stock, which needs to demonstrate greater profitability.
However, I’ve met the CEO and worked personally on government digital transformation over decades. I like the theme and am a holder of a sizeable (loss-making) position.
Morning BnB. May I ask your impression of the CEO? I had formed the impression, having looked at Made Tech earlier, that the company was more of an enrichment vehicle for the selling shareholders
I had formed the impression, having looked at Made Tech earlier, that the company was more of an enrichment vehicle for the selling shareholders
That certainly seems to have been the case at IPO. Since then the market has schooled the BoD that profits are required and targets are to be met. How they will react over the long term remains to be seen. Important to watch directors’ SBC medium term. I’m resigned to the recent tranche provided it doesn’t become a deluge.
In principle I have no problem with my co-shareholders maximising our gains!
Accrol group (LON:ACRL) interim results presentation given last week is worth a watch. Management ex DS Smith, have done an excellent job automating production/increasing efficiency, labour has been dramatically cut. Quick to act on inflationary pressures, 4 price rises in the last year. The last major capex spend within the strategy is the new mill, c £10m. Video & podcast.
SThree (LON:STEM) Full Year results presentation given to analysts. Revenue £1.64bn vs £1.33bn, Record Profit at £77m vs £60m. Proposed final dividend of 11p, up 38%. Trading continues to track in line with expectations. Video & podcast.
Then, SThree (LON:STEM) gave a second Investor Briefing on their Technology Improvement Programme, which sounds excellent. Video & podcast. Interestingly, I thought their new superduper CRM system described is very similar to the Getbusy (LON:GETB) Workiro. (But I'm not an IT person and those more IT literate might disagree!)
NWF (LON:NWF) interim results presentation given to analysts (with Q&A). Record results with revenue and headline profit ahead of expectations. All divisions are ahead with good trading since the period end in the seasonally busier H2. They are in line for the full year. Video & podcast.
Forthcoming webinars:
Wynnstay (LON:WYN) Full Year 2022 webinar on Friday 3rd February, 12 noon. Register here
Today they've announced record results:
Rev +42% £713.03m
PTP +92% £21.12m
EPS +86% 82.72p
Cash +53%
Divi +9.7%
They say they are well positioned for FY23
Made Tech (LON:MTEC) H1 Trading Update today, will achieve H1 rev of £20.6m, they are trading in line. They've been awarded three new contracts in recent weeks, worth £27m. Results webinar 24th February 12.30. Register here.
Smashing output, and always such high quality too, thanks Tamzin, I find these videos extremely helpful! Also I find your podcast channel excellent, as it means time away from being glued to my screen, whilst still learning about companies when out & about :-)
I remember still when we were in the Lord Aberconway having a debrief after seeing some company at Finncap, and you first floated the idea of starting PI World, and I loved the idea. So it's great to see it has worked out so well, producing all this worthwhile content for the community. Nice quality companies too, which is a big plus, as I know you're ethical, and won't promote any old rubbish ! :-)
Thanks Paul! We could never keep up with your content, I don't know how you do it. Love the CEO interviews, they get to the nub of the business model, extracting the vital information. Keep up the good work. Big thanks.
Wynnstay (LON:WYN) - great results this morning. Boring the company may be, even if it had an 86% EPS increase, but its such a solid performer with 19 years of dividend growth (10% increase this year). Odd how dependable companies like this, with net cash, get overlooked by many investors for story stocks! Any other holders here? There is a presentation from management on Friday at mid-day.
Wynnstay
Couldn’t agree more .
NAV now over 6 pound per share also
There are not too many AIM companies with 19 years of dividend growth .
Anyone know of other AIM companies with 19 years increasing dividends ??
Has cash and trading below NAV, and a couple of nice acquisitions .
It ain’t going to 10 bag but it’s for widows orphans and farmers .
Anyone know of other AIM companies with 19 years increasing dividends ??
Off the top of my head Young & Co's Brewery (LON:YNGA), FW Thorpe (LON:TFW), FD Technologies (LON:FDP), Concurrent Technologies (LON:CNC), RWS Holdings (LON:RWS), GB (LON:GBG) and Mattioli Woods (LON:MTW) have never cut their dividends, as far as I know.
Nichols (LON:NICL), James Latham (LON:LTHM) and James Halstead (LON:JHD) have also got a pretty good record, but I think all have had at least one cut over the years.
If you wanted a list of buy-and-forget AIM stocks that bunch plus Wynnstay (LON:WYN) would be a pretty good start.
timarr
Young & Co's Brewery (LON:YNGN) is cheaper than Young & Co's Brewery (LON:YNGA) so gives a slightly higher yield. Not a high yield though regardless.
Clarkson (LON:CKN)
Clarkson (LON:CKN)
RE: dividends
If you go outside AIM the obvious quality stocks pop up - Halma (LON:HLMA), Diploma (LON:DPLM), Rightmove (LON:RMV), Renishaw (LON:RSW), Spirax-Sarco Engineering (LON:SPX), Diageo (LON:DGE) ...
UK investors do like dividends, probably a cultural thing built on long experience of high inflation and financial repression. The problem is not the dividend record, it's that they're usually expensive, and buying expensive shares, even quality ones, is generally not a good investment approach.
timarr
Wynnstay (LON:WYN) Forecast earnings for 2023 are -43%. Is that due to a post-pandemic reversion? Apart from that forecast I can't understand why the share price has come off recently.
HARL is now looking very interesting, with a tiny market cap considering the FSS contract win alongside the investments being made in long term capabilities which will support further wins across multiple sectors. This could be my share of 2023.
Morning JonBeddell,
Yes, interesting announcement from Harland & Wolff group (LON:HARL) confirming winning a big contract, previously announced I think. It's difficult to assess this share. £34m mkt cap doesn't seem much, but it's a total punt really, since the company's taking on large, complex projects, which could be lucrative, or could be an investors graveyard (as this sector has been in the past).
Looking at the share price, it's already attracted gamblers, with volatile & large price movements, so could be an interesting speculation. Difficult to see it as a regular investment though.
Multibagger glory, or dismal failure? Or both, after a time lag?! Who knows.
Harland & Wolff group (LON:HARL) CEO bought ~£50k at 21-24p, i.e. more than today's price of 20p.
My morning smallcap tweet: Arresting language
Argo Blockchain (LON:ARB) Ecsc (LON:ECSC) Made Tech (LON:MTEC) Harland & Wolff group (LON:HARL) BSF Enterprise (LON:BSFA) Aurrigo International (LON:AURR) Foresight group (LON:FSG) Gaming Realms (LON:GMR) £TINE, Tandem (LON:TND), Wynnstay (LON:WYN)
◄Argo Blockchain (ARB)► CFO scarpers. He is thanked. "I am very proud of what we have achieved over my time with Argo." His sense of humour will be missed. A "Look on my Works, ye Mighty, and despair!" moment. [SP=15.6 Cap=95m]
◄ECSC (ECSC)► £690k of contracts. [SP=21 Cap=2m]
◄Made Tech, (MTEC)► guides H1-Nov rev up 76%. Adj EBITDA £0.5m, in line. Guides FY in line. [SP=26.88 Cap=40m]
◄Harland & Wolff (HARL)► big contract announed in Jan now formally signed. [SP=20 Cap=35m]
◄BSF Enterprise (BSFA)► has successfully produced the UK's first steak fillet of structured cultivated meat. [SP=18.5 Cap=16m]
◄Aurrigo (AURR)► £0.7m grant to provide three self-driving zero-emission Auto-Shuttles. [SP=81.25 Cap=34m]
◄Foresight (FSG)► appointment as sub-adviser to the Cromwell Foresight Global Sustainable Infrastructure Fund. a newly formed partnership between Foresight and Cromwell. [SP=461 Cap=536m]
◄Gaming Realms (GMR)► guides FY-Dec rev up 27% and adj EBITDA up 36%. In line? CFO becomes CEO. [SP=28.4 Cap=83m]
◄Crimson Tide (TINE)► £0.25m+ inaugural subscription contract in USA. "This contract win is a landmark in its own right." As opposed to just a landmark? [SP=NA Cap=NA]
In line: TND, WYN