Small Cap Value Report (Weds 1 May 2024) - CGS, JSG, CNC. Briefs: RNO, SEE, MORE, RAI, AFM, AWE, ALT, NXT, DOM, ANX

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
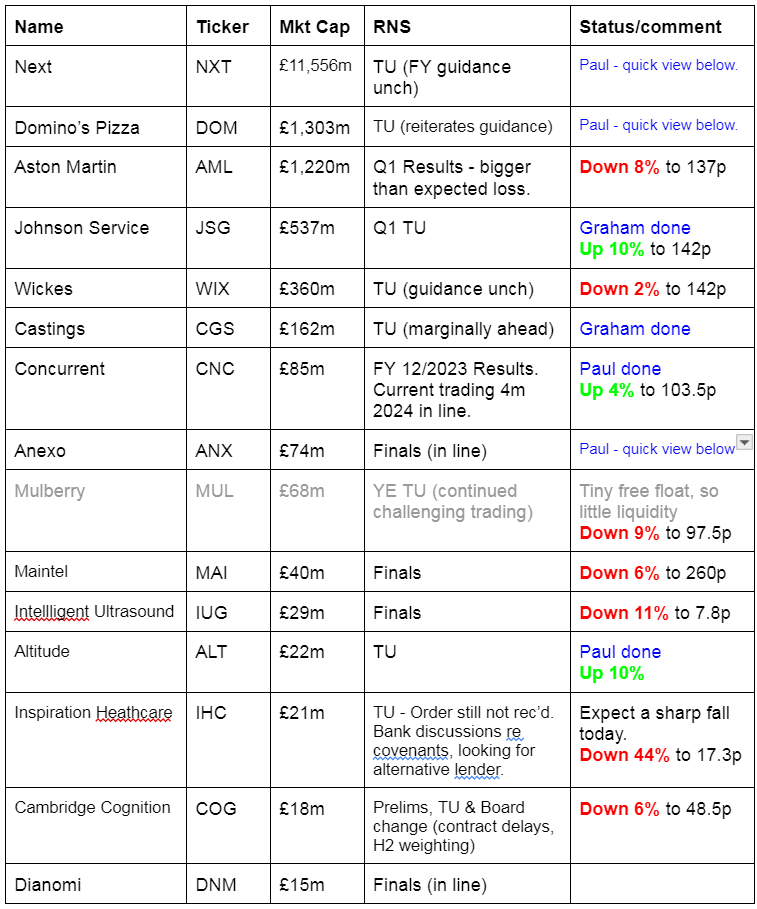
Other mid-morning movers (with news) -
Alpha Financial Markets Consulting (LON:AFM) - up 36% to 455p (£521m) - Possible offer - Paul - PINK (bid approach)
AFM is a specialised staffing group in the financial sector. As usual, Sky News breaks the story, and the company has since responded, as required.
Potential buyers are named by AFM as being Bridgepoint, a London-headquartered international investor managing £41bn according to a google search. Its website says it’s “Europe’s leading middle-market growth investor with E27bn of assets under management”. There’s another potential buyer mentioned, Cinven (global private equity, similar size to Bridgepoint), but no indicative offer has been received as yet. This could get interesting, if it becomes a bidding war. Bridgepoint has not yet done due diligence, so things are at an early stage. Takeover panel rules have kicked in, so it’s now in an offer period.
AFM names the parties without their consent -
“This announcement is being made without the consent of Bridgepoint and Cinven.”
Price - nothing mentioned, so it's now either guesswork or insider dealing.
Paul’s view - doesn’t really matter, but we’ve only looked at AFM here once, on 8/2/2024, when I concluded AMBER/GREEN, that it looked pretty good, and worth a closer look at 335p after a trading update. The 4.2% dividend yield, and growth plans impressed me.
Alphawave IP (LON:AWE) - Down 11% to 114p (£829m) - NEDs clearout - Paul - RED
A bizarre announcement today says its Board doesn’t have adequate expertise in AI or datacentres.
However, it’s not as bad as it sounds, as they’re only ditching 4 of their existing NEDs, 3 of whom are female, so that’s a blow for diversity & inclusion! Poor communications here, as the RNS should have made it much clearer that this is only a change in NEDs, not the operational management.
Paul’s view - as recently covered, I don’t like the numbers here at all, hence stick with RED. A clearout of unsuitable NEDs doesn’t really change anything in my view. Although there might be a background worry that NEDs might have asked awkward questions and didn’t toe the line, perhaps?
Altitude (LON:ALT) - up 16% to 36.5p (£26m) - Trading Update - Paul - AMBER
Altitude Group Plc (AIM: ALT), the leading end-to-end solutions provider for branded merchandise is pleased to provide this pre-close trading update, showcasing continued scale, growth and momentum.
Expects to “at least meet consensus expectations” for FY 3/2024. Helpful footnote says forecast is £26.1m, and adj EBITDA of £2.2m. Zeus kindly translates this into real money, it’s adj PBT of £1.2m. Zeus forecasts a rise to £2.0m in FY 3/2025. So the £26m market cap looks fair, providing ALT can achieve forecasts. The downside is ALT has been around a long time, and its business model has never really got off the ground, including several false dawns (look at the chart 2016-19!).
Cash has slightly improved, to a modest £1.3m, but it has an enlarged unused borrowing facility of $3.3m.
Outlook - says it’s early days, but confident trading will be in line for FY 3/2025, with a good start.
Paul’s opinion - I need to see the full accounts, due out on 30 July 2024. In the meantime I’ll sit on the fence. I doubt whether ALT has stellar upside potential, as it’s been trying for so long to commercialise the core product, and it hasn’t really worked. Although to be fair, there is strong revenue growth, and it has now broken through into the first year of profits. To a certain extent it’s trying other stuff now, like branded goods for colleges, which seems to be where the growth is coming from. That could be a nice niche. Why is it stock market listed? Doesn’t make sense to me. Hence on balance, I’ll sit on the fence with “don’t know”, AMBER.
Contract Wins/ Quick Comments
Renold (LON:RNO) - Military order book risen by £13.1m over recent months, mainly a £10.6m contract (over 6 years) to make flexible couplings for Canadian Navy. Already working on British & Australian naval programmes. “... further reinforce our Couplings business performance and shows the on-going benefits of our product development strategy combined with our manufacturing & engineering excellence”.
Paul’s view - sounds helpful, but doesn’t look material to c.£243m existing forecast revenues. So I’d say reassuring news, rather than significantly share price moving. Still one of my favourite value shares. GREEN.
Seeing Machines (LON:SEE) - extension of existing programme with N.American tier-1 customer. Will expand to 19 models and extended to 2023 (what was it previously? Not stated). Lifetime value estimated $26m - not a lot over 8 years, but high margin I believe (royalties from each unit manufactured by third parties). Mentions key European legislation which will force fitment of these safety devices (eye scanning cameras & software) where SEE is one of only c.3 significant players.
Paul’s view - much more positive after speaking to management (a dangerous thing sometimes!), who explained to me that the game-changer is this forthcoming safety legislation in Europe (and possibly elsewhere, eg America), which will force manufacturers to fit SEE’s technology. Very little credible competition, and deals are long-term once signed. Hence I think this share could do well, if expected demand does appear, as there’s now a catalyst to grow demand. Cash/debt position not great, but mgt reckon they can manage without another raise, so I’m now AMBER/GREEN.
Hostmore (LON:MORE) - temporary, immediate suspension of shares due to auditors requiring more time to “review non-cash items” in FY 12/2023 accounts. No reassurance on the figures being as previously indicated. Still nothing anyone can do, as the shares are suspended now.
Petrofac (LON:PFC) - shares also suspended, as previously announced, so no surprise there. Some other nano caps are suspended today, as they miss the end April deadline for publishing accounts.
Ra International (LON:RAI) - FY 12/2023 Results - improved from very bad in 2022 to just bad in 2023! Breakeven PBT of $0.2m, but that’s been boosted by $5.2m one-off income (see note 9). Underlying operating loss of $3.15m, and finance charges of $2.0m. Very low gross margin. Balance sheet is OK, but almost all the $16.8m cash is offset by $15.8m loan notes. Outlook comments vague, talk about new contracts, but order book is well down at $49m (2022: $83m). Says it has tenders in the pipeline. Paul’s view - looks a low quality business, why get involved? EDIT: the market likes it more than me, with a 17% rise to 8.75p at 11:49.
Next (LON:NXT) - unch at 9,022p (£11.45bn) - Q1 Trading Update - Paul - AMBER
Q1 sales slightly ahead of guidance. Interesting that all the growth came from online, and finance income, with physical stores sales flat vs LY.
Maintains FY 1/2025 profit guidance at £960m, equivalent to 606p EPS, a PER of 14.9x
Paul’s view - looks priced about right to me. Amazing business as we know, but in a very tough sector, hence EPS growth is fairly modest despite buybacks. I wouldn’t be a buyer at this level. It’s a great share to buy when there’s some big financial shock to the markets, as it always recovers!
Domino's Pizza (LON:DOM) - unch 326p (£1.31bn) - Q1 Trading Update - Paul - AMBER
This strikes me as a lacklustre update. It’s struggling to meet, let alone beat LY sales on an LFL basis. Although it says Q1 is in line with expectations, and leaves FY 12/2024 guidance unchanged. £4 lunch deal looks a bit desperate, I’ll mystery shop it & report back! Says April 2024 trading is “slower given the very strong comparative” LY.
Paul’s view - DOM has been growing revenues in the last 6-7 years, but EPS has been static. Hence a PER of 15x and yield of 3.5% looks high enough. Speaks highly of DP Poland (LON:DPP) where it’s taken a 12% equity stake.
Anexo (LON:ANX) - 63p (£74m) - FY 12/2023 Results - Paul - RED
Same problems as before - reports huge profits, which then just sits in debtors on the balance sheet, uncollected. Receivables absolutely absurd, at £234m. Gross borrowings of about £62m are fiendishly expensive, as I think it borrows from anyone at any price. Hence finance costs on P&L more than doubled to £17m.
Paul’s view - probably doomed to eventual collapse, in my view. Very similar to Quindell and Accident Exchange. They should try to sell it to some dumb Aussie lawyers! ;-)
Summaries of main sections
Castings (LON:CGS) - down 2% to 365p (£158m) - Trading Statement - Graham - GREEN
FY24 is set to be “marginally” ahead of expectations (estimates upgraded by 5%), but the FY25 outlook is unchanged given limited visibility over demand and the likelihood that temporary factors boosting demand may no longer be in force. However, Castings continues to seem a high-quality candidate for investment.
Johnson Service (LON:JSG) - up 3% to 134p (£555m) - AGM Statement - Graham - AMBER/GREEN
An encouraging update from JSG with the company flagging that based on current energy prices and the fixes it has in place, it sees upgrades to expected profitability. I review the history here (Covid & inflation) and come away with optimism that the future is bright. Plus, it’s always nice to see a falling share count.
Concurrent Technologies (LON:CNC) - up 5% to 104p (£89m) - Results FY 12/2023 - Paul - AMBER
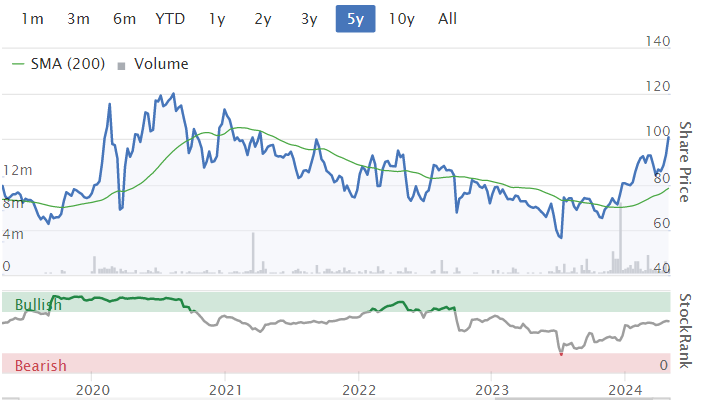
Fantastic headline numbers, but closer scrutiny raises question marks over how real the profits and, and negligible cashflow. Strong balance sheet after a placing. I can see why people like it, and the future could be bright if strong growth continues. For now though, I think the price looks up with events, and I can't judge how likely the (necessary) out-perform updates are likely to be in future, so it goes in my "don't know" tray.
Paul’s Section:
Concurrent Technologies (LON:CNC)
Up 5% to 104p (£89m) - Results FY 12/2023 - Paul - AMBER
Concurrent Technologies Plc (AIM: CNC), a designer and manufacturer of leading-edge computer products, systems and mission critical solutions used in high-performance markets by some of the world's major OEMs, is pleased to announce its results for the year ended 31 December 2023.
Flagged by readers as something good that we should look at, thanks for that.
My first step with every company update is to quickly check my previous notes using a (CTRL+F ticker) on my summary spreadsheet. This shows I liked CNC shares last year -
17/7/2023 - forecasts raised 29%, bulging order book, I went GREEN, and made it a podcast mystery share (ie best idea of the week).
27/11/2023 - in line (previously raised forecasts) trading update. Very upbeat pipeline/orders. I moved down slightly to AMBER/GREEN due to news of some orders slipping into FY 12/2024. Noted to carefully check cashflow & bal sht when 2023 results come out.
Some terrific numbers here - but we were expecting impressive numbers, which is why the shares have almost doubled from July 2023 lows, and the market cap is now £89m -
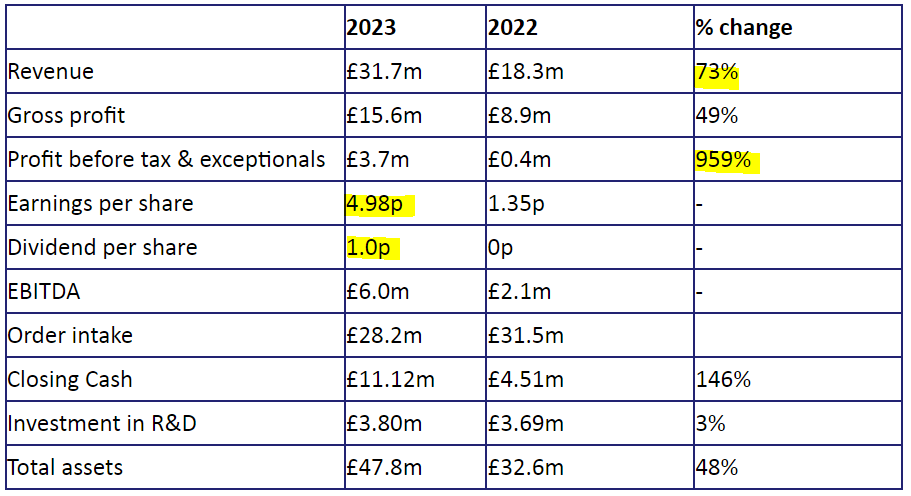
Broker Cavendish had previously (17/1/2024) forecast 4.8p adj EPS, and its latest note today (many thanks) has upped the actual to 5.0p, so this looks like a handy beat against (previously raised) forecast.
Tax - bear in mind that 5.0 EPS is boosted by a negative tax charge of -£400k. If I normalise that to a 25% charge, it would be a £875k cost, so a £1,275k boost to PAT from the negative tax charge. I wonder if that’s R&D tax credits, brought forward losses, or a bit of both? Cavendish’s model shows zero tax charge in 2024, then a £0.7m tax charge in 2025, which suggests it’s currently benefitting from previous tax losses maybe? This needs more work, and should really be adjusted for in our valuation of the shares (ie. the PER in reality is higher than it looks, since EPS is being boosted by temporarily low tax charges).
Important point here - impressive profit growth achieved…
“...notwithstanding a significant investment in the cost base throughout the year to accelerate future growth.”
Headcount is up 18%.
Acquisition of Phillips Aerospace helped growth, and only cost £2.8m. More acquisitions planned.
Supply chain problems have eased.
Equity of £6.8m raised in Aug 2023.
Outlook - too vague, I would have liked clearer guidance -
We have achieved remarkable success in FY23, marked by a record financial performance, and have put in place the building blocks that will enable us to deliver long-term, sustainable growth. This is driven by significant design-in wins and strategic investment in the Systems divisions, including the acquisition of Phillips Aerospace.
During the year, there was a step change in how the Group invests in marketing, sales and partnerships to expand our market opportunities. Looking ahead, we will remain focused on leveraging the knowledge and the long-standing relationships the Leadership Team has developed to invest in a measured way to design boards and systems for a range of applications. FY24 will be about balancing our investment and mobilising to win and deliver systems to achieve our short-term financial targets.
Ah, there’s another outlook bit, which confirms current trading in line, but also includes the uselessly ambiguous “profitable growth” nonsense phrase that PRs like to think fools us! -
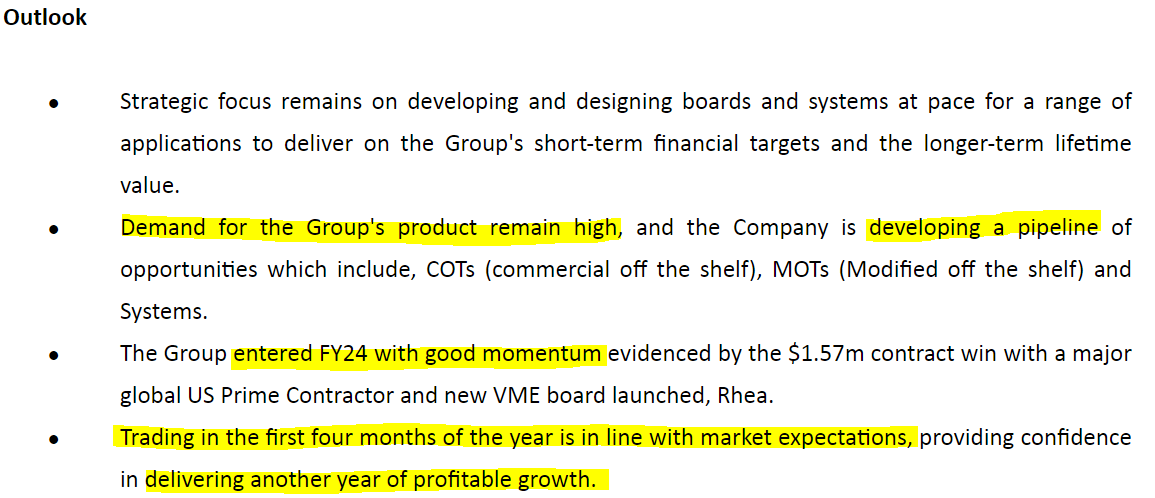
Forecast for FY 12/2024 from Cavendish is a modest increase in profit, but a slight fall in EPS from 5.0p in 2023, to 4.9p in 2024. Despite adj PBT forecast to go up from £3.7m to £4.4m. The reason must be increased share count from the equity raise in 2023. Sure enough, the share count used to be c.73m, and it’s now 85.6m, which has strengthened the balance sheet, but weakened the EPS due to dilution.
On a normalised tax charge of 25%, I calculate 2024 EPS at 3.86p. Put it on a PER of 20, and I get c.77p target share price. We’re well ahead of that, at 104p, so I’d say the share price has already run ahead of a conservative valuation (not that PER of 20x is particularly conservative)!
So the bull case will need to rely on CNC smashing forecasts for 2024. That’s possible, given the upbeat commentary, the stunning profit growth achieved in 2023, and that some quite large orders slipped from 2023 into 2024, giving 2024 a boost. I would have preferred an ahead of expectations current trading update though, given that the 2024 forecast is only for modest growth (versus a very strong LY).
Balance sheet - inventories stand out as being way too high, at £12.0m (up 20% on an already high 2022 year end). That’s huge actually, as cost of sales for the whole of 2023 was £16.0m, which implies is has inventories of 9-months sales. I would expect a figure of 1-2 months. So this is the no.1 area to query on any webinars from management. There could be a reasonable explanation - possibly hoarding scarce components due to supply chain problems (but they said that’s easing now). Note 15 gives more detail, and confirms it does have a problem with slow-moving inventories, with the provision having been increased by £544k in 2023. We need to know what the slow-moving stock is, and what management expects to sell it for? Write-offs are only required by accounting standards if the resale value is below cost. However, reducing inventories might involve sales at lower margins in future. Note that of the £12.0m inventories, £8.4m is raw materials, so hopefully that stuff can be used up in future production, releasing cash tied up in excessive inventories?
Cash has shot up, thanks to the equity placing during 2023, and sits at £9.1m (Dec 2022: £1.7m). There’s no debt. Working capital is very strong. Which does raise the question whether it really needed to do the equity raise last year? I’d say no it didn’t, which is a pity as it caused an unnecessary 17% increase in the share count from dilution.
Overall, at £23.5m NTAV, the balance sheet is strong, and could I think absorb more small acquisitions. Maybe they could take on a little debt too, for funding more small acquisitions without further dilution?
Cashflow statement - post-tax cash generation of £5.6m is much improved from 2022 (which suffered from adverse working capital movements, unlike 2023).
Physical capex was much lower in 2023 at £0.5m (2022: £1.5m), but the stand out number is a very large £4.0m in capitalised development spending.
After taking off lease costs, that means free cashflow is almost nothing, despite there being hardly any physical capex. That’s not good. The company is investing its cashflow in product development, which could pay off nicely in future, but as things stand now, this is not a cash generative company at all.
The £6.6m increase in cash all came from the placing which raised £6.4m after costs.
Am I saying that the profits aren’t real? In a way, yes. The main contentious area is capitalised development spend. £3.94m costs were shifted onto the balance sheet in 2023, but only £1.38m was amortised through the P&L, a net boost to profit of £2.56m. Given that adj PBT was only £3.7m, most of that profit came from this development spend policy.
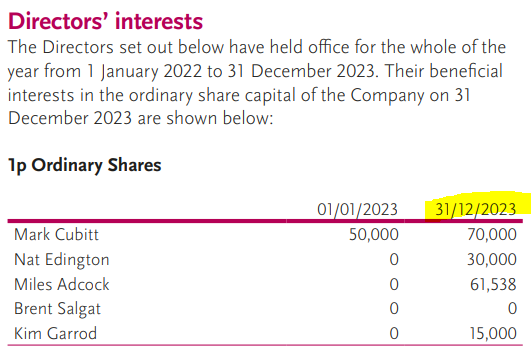
Directors pay & shareholdings - see note 9, has risen 52% to £1.2m, which is a big chunk of the profits £3.7m adj PBT, so £4.9m before Directors pay - they’re taking 24% of the profit for themselves! That’s unreasonable. Highest paid Director got £571k, which is much too high for the size of company.
People moan about FTSE 100 Directors getting millions, but as a proportion of profit it’s not much. It’s these smaller caps where Director pay can often be a gigantic % of profit, as it is here.
Directors own miniscule amounts of shares, no wonder they want big pay packets instead. This needs to be addressed, they should be embarrassed to have so little personal commitment in the company’s shares, so their interests are clearly not aligned with investors -
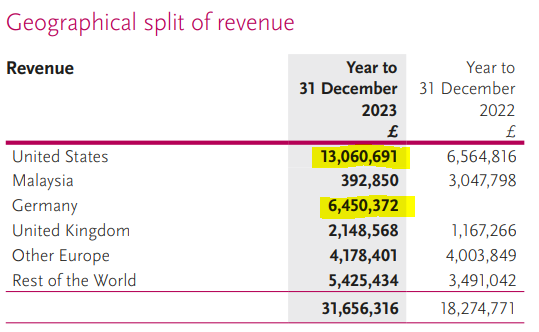
Geographies - the FY 12/2023 Annual Report is already published, so I’m having a rummage through it, and this caught my eye - the stellar growth in 2023 came mainly from USA, and Germany, so it would be interesting to ask management for more colour on what these deals were, if they’re repeating or one-offs, etc -
Paul’s opinion - this section is likely to make me very unpopular with some readers, who might even go nuclear on me and say I haven’t done enough research and know nothing about the company! (that’s the usual one).
Remember I’m not trying to predict what the future holds, I’m just reporting the facts and figures as things stand now. It's your job to do a much deeper dive, and find the exciting future potential.
Positives -
- Superb growth in both revenues & profit.
- Bullish commentary.
- Strong balance sheet.
Negatives -
- 2023 profits have mostly come from capitalising internal costs for product development.
- It didn’t generate any cash in 2023.
- Directors took 24% of the profit in their own pay, and have negligible shareholdings.
- EPS flattered by negative tax charge.
- 17% dilution from an unnecessary placing in 2023.
Overall then, you have to weigh up whether these factors matter to you, or whether you’re happy to run with the momentum of rapid revenue & profit growth - which can often be the right thing to do. We often quibble over valuation here, only to see subsequent out-performance, and continued share price rises.
CNC shares have had a great run, and now look if anything a bit over-valued to me. But I also like the rapid growth, and investment in R&D that could pay off in future growth. If 2024 sees more upgrades to forecasts, then the future could be bright. Although for me, not knowing anything about the products or competitive landscape, this would just be guesswork.
Hence I think it has to be AMBER for me - in the “don’t know” tray for now. Good luck to holders!
Graham’s Section:
Castings (LON:CGS)
Down 2% to 365p (£158m) - Trading Statement - Graham - GREEN
Castings is “the leading iron casting and machining group primarily focused on the European heavy truck market”.
Paul reviewed its interim results very favourably in November.
Today's update for FY March 2024 says that the result is expected “marginally ahead of market expectations”.
Perhaps the company could consider disclosing market expectations in its RNS?
Fortunately, the company’s broker notes are available on Research Tree.
At Canaccord Genuity, the various profit estimates for FY 2024 are all upgraded by mid-single digit percentages, e.g. the adj. PBT estimate is now £21m (previously £19.9m).
They have not changed estimates for any other financial years, including the current financial year (FY March 2025), “given visibility on order intake is (typically) limited”.
This is what Castings has to say:
The underlying demand for heavy trucks (approximately 75% of group revenue) was particularly strong in the first half of the year. The backlog demand from the Covid period, and the well-publicised supply constraint issues, appears to have now been absorbed by the OEMs and forward schedules are now at a lower level.
In other words, this seems to be a temporarily heightened level of demand. So we shouldn’t get too excited about the prospects for FY 2025. Broker estimates suggest that revenues for FY March 2025 will be down by a few percentage points compared to FY March 2024.
Other points:
Input prices are “relatively stable”
“Balance sheet remains strong” - as discussed by Paul in November, the Castings balance sheet includes net assets of £127m and cash of £31m.
The update concludes:
The level of investment has been higher than in recent years and will continue to be so as the new foundry line progresses. Other investments have been focused on replacement equipment, robotics and AI, and sustainability initiatives including solar panels and energy efficient chilling systems in the machine shop.
Graham’s view
I’m happy to maintain Paul’s GREEN stance on this one as it continues to trade at a modest multiple despite having that very strong balance sheet and a proud history of profitability.
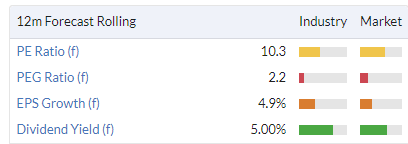
The StockRanks approve:
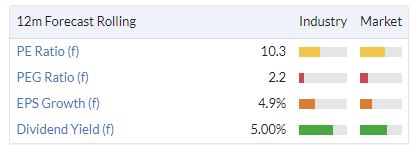
It also passes no fewer than seven bullish stock screens, including several which are personal favourites of mine: the Ben Graham Defensive Investor Screen, the Best Dividends Screen, and the Neglected Firms Screen!
In the short-term, we might now see Castings have a quiet year due to the previous backlog of demand having been met and with forward schedules currently “at a lower level”. But for long-term investors who are willing to wait that out, I expect that Castings remains a high-quality candidate for investment.
Johnson Service (LON:JSG)
Up 3% to 134p (£555m) - AGM Statement - Graham - AMBER/GREEN
It has been a little while since we last covered this textiles rental group.
The two categories served are workwear and protective wear (collectively referred to as “workwear”), and linen for hotels, restaurants and catering (this is referred to as “HORECA”).
Key points from today’s AGM statement:
Q1 revenue growth 16% to £114m
Organic growth is 8.9%: 0.5% in workwear, 13.5% in HORECA.
Workwear has traded in line with expectations, and HORECA volumes are in line with a predictable seasonal pattern.
The company’s new HORECA site in Crawley “remains on budget and is expected to begin test processing in the next few weeks”.
The transition to Crawley will negatively impact profits by £3.7m in 2024 (this was already known), but the site is expected to reach breakeven “during 2026”, and to ultimately generate a return “that comfortably exceeds the Group's weighted average cost of capital”.
Energy costs: transporting, cleaning and maintaining textiles is energy-intensive work and the cost of energy has been a hot topic for JSG during the inflationary period we have just experienced. The company’s approach to hedging is to use what they call a “little and often” strategy.
They have great news for investors on the energy front, with upgrades to expected profitability:
Based upon the market rates above and the energy fixes currently in place, we estimate that the impact on our forecast energy cost when updated for these figures, together with the benefit of ongoing operational efficiencies, would result in a potential positive effect on adjusted operating profit in each of 2024, 2025 and 2026 of £3.0 million, £7.0 million and £9.0 million, respectively.
JSG saved an aggregate £15.4m thanks to energy hedges from 2021-2023. With energy prices now lower than expected, hedges are currently expected to cause a total drag of £12m on profits from 2024-2026.
In aggregate, therefore, it looks like JSG’s hedging activities are likely to have boosted profitability over the entire period from 2021 to 2026. But that’s really not the point - the point is to manage risk and increase the predictability of financial results.
Changes in market prices in 2025 and 2026 could still change the above calculations.
Broker notes for JSG are not readily available to private investors but here are Stocko’s existing revenue and profit estimates:
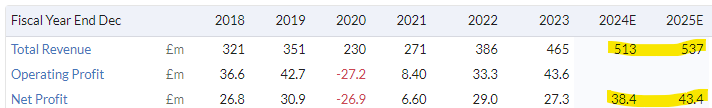
Balance sheet: net debt increased by £11m in the three months to March 2024, to £73m. It is expected to grow further to £85m by June, before falling to £55m by December. Some nice transparency by the company to outline this expected path!
Given that after-tax net income for 2024, per the StockReport, is anticipated at £38.4m, plus the upgrades announced today, this quantity of debt wouldn’t particularly concern me.
I should mention that the company repurchased £35m of its own shares across 2022 and 2023, a move which I applaud.
Another factor that could impact debt levels is further M&A which can’t be ruled out:
We continue to see exciting opportunities to deploy capital organically and have a good M&A pipeline.
Last August, JSG bought Celtic Linen for €31.5m (about £27m). This is Ireland’s largest linen supplier to healthcare and the second largest linen supplier to HORECA.
Outlook statement is positive, here’s an excerpt:
…we expect to exit 2024 with strong progression towards previous levels of adjusted operating margin.
Furthermore, the Board is confident that, as energy costs stabilise at lower levels and Crawley builds volume and reaches its potential, combined with further operational efficiencies across the wider estate, divisional margins will continue to return towards those achieved in 2019, with an overall Group adjusted operating margin of at least 14.0% being achieved in 2026.
Graham’s view
This is another example of a stock which was battered first of all by Covid’s impact on the hospitality sector, and then by rampant inflation (particularly with respect to energy).
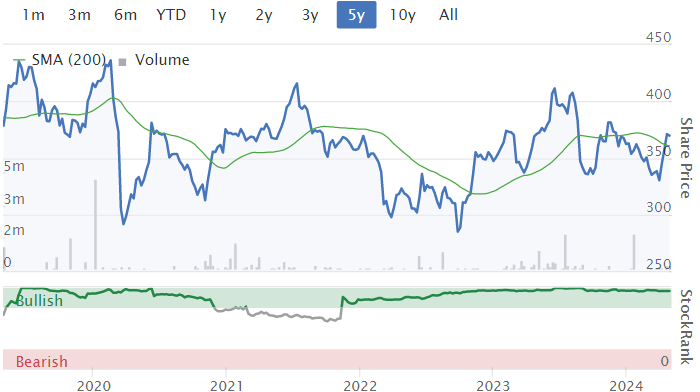
The stock still hasn’t recover to its former glory:
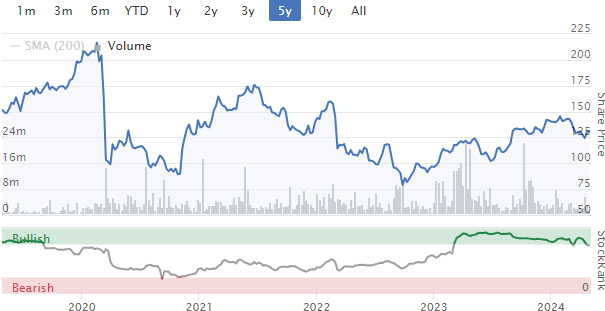
During the Covid era, the company raised £85m at 115p, to shore up its finances.
The resulting 20% increase in the share count will have been a drag on any possible recovery, but this has now been partially reversed by JSG’s buybacks.
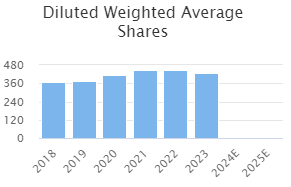
I’d love to see the share count reduce further, but I’d also be inclined to trust the company’s M&A abilities. If it comes down to a choice between M&A and buybacks, they should be able to make the right decision.
While the stock’s pricing might be about right here, I do view this as a better-than-average business with the chance of some positive catalysts over the next year or two. Take your pick: clever M&A, more buybacks, or falling energy prices.
I will therefore upgrade my stance on this one to AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
There was a good IC interview with the CEO of Concurrent Technologies (LON:CNC) back in February. Some of the comments around supply chain may help to explain the year on year reduction in inventories and receivables on the Cashflow Statement.
https://tinyurl.com/2p9n8bd7
# Company formed in 1985, primarily to fit Intel chips into PCs.
# Sep-22 acquisition transformed the company.
# 2022 was Miles Adcock's first full year in the job. He was previously at BAE Systems (LON:BA.) and Qinetiq (LON:QQ.).
# Previous CEO died in 2019.
# Difficult supply chain issues from Covid discussed (6 mins).
# Supply chain back to normal in 2024.# 2/3 of employees started after the CEO.
# Expect revenue for current year to exceed 30m.
# Sales cycles are very long.# CEO says Concurrent Technologies (LON:CNC) have hired some of the best sales people from competitors.
# 80% of sales in 2021 were for last time buy products so the company had no option but to develop new products.
# This situation was turned around in 2022 (SSB: presumably only 20% of sales were for last time buy products).
# Investors have previously queried the concentration of customer base (10 mins).
# John Lee says he first invested in 2009 because he was attracted to a cash rich company in a niche area that was also paying a dividend.
# Customers are large defence companies eg: BAE Systems (LON:BA.) and Lockheed Martin (NYQ:LMT).
# US Defence Dept have recently said they don’t want to be locked into proprietary tech architecture which is good news for companies like Concurrent Technologies (LON:CNC) (20 mins).
# Concurrent Technologies (LON:CNC) now securing 8 times the number of design wins which should lead to higher revenues in 2025/26.
# New CFO joined from Qinetiq (LON:QQ.).
# Prior year accounts had been mis-stated and had to be re-issued.
# Concurrent Technologies (LON:CNC) is nimble & able to make quick decisions but lacks the breadth & depth of larger competitors.
# No profit or cash generation in 2022 so no dividend.
# Equity raise was over-subscribed. Concurrent Technologies (LON:CNC) raised more than needed.
# Generally, lots of interest from potential investors who are not yet invested in the company. No debt facility being used.
Surface Transforms (LON:SCE)
Good prophecy by Paul on 17th April:
No rabbit so after close today announced
Proposed Placing and Subscription to raise approximately £6.5 million (before expenses) via an accelerated bookbuild, and Open Offer to raise up to a further £2.0 million (before expenses).
https://www.investegate.co.uk/...
At a quick glance the new shares (at 1p) will more than quadruple the number of shares in issue.
Edit: Paul - you beat me to it by posting while I was writing this! I might as well leave it up.
Another placing/open offer at Surface Transforms (LON:SCE) as we thought, and was bleedin' obvious from recent updates. At 1p per share.
In other news, I mystery shopped Dominos Pizza £4 lunchtime offer this afternoon. Verdict:
£4 pizza is absolutely delicious, and a surprisingly OK size, more a light lunch than a snack I would say, big thumbs up from me (occasional unhealthy treat, not a regular thing).
£4 wrap - thumbs down. Very disappointing, I would say worth £2 tops.
(Sound may not work on video below, so expand it into YouTube, where the sound does work. Might be temporary, it did that the other day at first)
?si=L4iM_CRd77cmdgYx
P.
Crap wrap, £4 -
Excellent small pizza for £4 -
Surely Papa Johns closing a whole bunch of outlets in the UK would be a boon (no pun intended! :p) to Domino's Pizza (LON:DOM) ?
After all, pretty much a commodity product between Domino's, Papa John's, and the other one whose name I forget.
Or is their lunch being eaten by the new crop of sourdough pizzerias, epitomised by Franco Manca, all of whom do deliveries (and many on the delivery apps like Deliveroo, Just Eat, etc)...
Or changing taste buds? Sudden pizza and a hollywood movie becomes fancy tex-mex burritos from Tortilla Mexican Grill (LON:MEX) and an indie foreign film!
Kitwave (LON:KITW)
SP has been on a tear, up 15% in past 8 days (up 4% today) to an all time high of 402p. H1 trading update covering 6 months to 30/4/24 is due any day now.
Share price movement suggests someone is expecting a positive update.
FY'24 f/c PE is 13.2 so perhaps further to go despite being a lowish margin wholesale business.
One of the very few 2021 IPO jewels.
Snazzy
Kitwave (LON:KITW) was looking at these around 250p maybe a year or so ago. Liked them but wasn’t sure of growth so slightly kicking myself as they are up 60%! Feels like a PER of 13 or 14 is about right. From memory not dissimilar to how the old Booker was rated before Tesco bought it. So I’m not overly inclined to buy now personally but a bit miffed I didn’t act earlier!
Kitwave (LON:KITW)
At the risk of sounding smug, which is not my intention I had the good fortune to make several modest purchases during January and February. My blended buy price being 283p.
I summarised the reasons why I like the company and my reasons for investing in a post on 28 March. Link below.
All the best
https://www.stockopedia.com/co...
Made Tech (LON:MTEC) CFO buys £30,000 shares. Great endorsement following recent £19m contract. Mkt cap only £21m and plenty of cash.
Thank you for your comments on Concurrent Tech Paul, your facts and figures analysis are good enough for me, we've sold and are pleased to take a modest profit, good luck to holders. Thank you Graham for your Castings comments, we continue to hold on balance sheet strength and good dividends as noted.
My thanks too for a well balanced write up on Concurrent Technologies (LON:CNC) , Paul. Good point about the cash flow but it is worth noting that the statement mentions £5.4m of revenue from 2023 where cash will be collected in Q1 2024 and so the underlying picture may be better than headline numbers suggest.
Hi Sparkler,
Paul. Good point about the cash flow but it is worth noting that the statement mentions £5.4m of revenue from 2023 where cash will be collected in Q1 2024 and so the underlying picture may be better than headline numbers suggest.
Thanks, but I think that looks a red herring. The reason being that it's normal for about 60 days sales to be collected in the following financial year for any business that sells on invoice (as opposed to cash up-front, eg retailers).
CNC reported £31.7m revenues in 2023. So it would be normal for about 60 days revenues to be waiting to be paid by customers on the balance sheet - receivables. That's therefore expected to be about £6-7m here.
Sure enough, receivables are £6.4m on the 31/12/2023 balance sheet at CNC. Note 16 shows that of this, £5.4m is trade receivables. So that's very much in the normal range of what I would expect.
Trade receivables were £4.8m a year earlier.
These numbers don't show any evidence at all that an unusual amount of cash collection is due in Q1 2024. It all looks completely normal.
So I'm correct on this point. I did check it all quite carefully you know, I spent about 3 hours on the CNC section, but it's fine to double-check things if you think I might have got something wrong.
Checking the numbers again, I'm definitely right on this. There's no cash generation in 2023, and the working capital movements actually net off to almost zero, as you can see from the cashflow statement excerpt here -
Regards, Paul.
Good afternoon
FacilitiesbyADF (LON-ADF) - I hold
For those of you who are shareholders in ADF, you may have seen an announcement yesterday morning confirming the intention to pay a final dividend of 0.9p in July 2024 on top of the interim dividend of 0.5p already paid at the half-year.
When ADF announced its annual figures to end-December 2023 on 26th April, no mention of the proposed payment of a final dividend was made either in the Chairman’s statement, the CEO’s statement or the Finance Director’s statement. I queried this with the PR company and received the following reply:
‘In ADF’s final results announcement of 26 April, the company confirmed that total dividends of £1,130,004 had been paid or proposed re FY23. With 80,907,419 shares in issue and an interim dividend of 0.5p per share paid at the half year - a proposed final of 0.9p had therefore been settled upon to be proposed to shareholders.
With the timetable for that proposed final dividend now finalised and cleared with the London Stock Exchange - the company has been able to make the follow up dividend timetable announcement today’.
If someone can explain to me why none of the directors chose to mention payment of a final dividend, so leaving shareholders to work it out for themselves, I would be most grateful.
Kind regards
Phillip
UK stocks coming back into fashion?
https://twitter.com/John_Stepe...
"Some other nano caps are suspended today, as they miss the end April deadline for publishing accounts".
Why does this happen so often ? surely as a listed company they have a duty to the shareholders for due care and attention to what they do, am I wrong to allege it as a conspiracy sometimes to avoid putting out bad news ? some of them have to eventually delist altogether because they don't get the accounts out
just blame the auditor and its not your fault
Hi threeputt,
Why does this happen so often ? surely as a listed company they have a duty to the shareholders for due care and attention to what they do, am I wrong to allege it as a conspiracy sometimes to avoid putting out bad news ? some of them have to eventually delist altogether because they don't get the accounts out
A couple of points here I can think of. Several people in the sector have told me that there aren't enough trained auditors (an overhang from lockdowns, as with almost every sector) , and also that the complexity of their work has increased (eg working out the IFRS 16 numbers, and trying to avoid getting sued). So fees have gone up a lot, and if the numbers are late, they're late. Whereas in the past, it was a resigning matter for the CFO if the figures were late.
I've also heard that some smaller companies are changing year ends to quiet times for auditors, so they don't have to compete (and fail) to get scarce resources from the auditors at times they're overloaded by larger & more important/lucrative clients. Sounds sensible to me actually.
Another point is that, in the past, scam companies (like all the Chinese AIM frauds) just used not filing accounts as a convenient way to get the shares de-listed, with no vote required.
So in the past, I would have seen late accounts as the worst thing imaginable, we are seeing some cases now where companies do actually come back from temporary suspension and the market accepts late accounts.
Generally, I run a mile if there's even a sniff of problems with filing accounts, going concern, bank covenants, etc. You can then take stock of the situation on the sidelines without any stress, and buy back in later if you want (nearly always cheaper).
P.
Zotefoams (LON:ZTF) has today entered the 405-410p range. On several occasions over the past few years this has acted as a really strong resistance, with it often drifting back down to 300p after failed attempts to break through. If it is able to break through in the next few days that could be a really bullish sign for Zotefoams (LON:ZTF) having not reached beyond these levels since late 2021. The results of the Rezorce packaging trial should be presented in the next few months which is likely the cause of the recent gains. Should these results be positive the shares could rerate significantly imo. (I hold)
Zotefoams (LON:ZTF) think this new Design Blue contract, has lifted the shares, before that they were drifting down, this could be major change. I hold also.
Zotefoams (LON:ZTF) has something leaked from the cartons trial?
Sorry for my negative post, forgot about drink cartons. Not sure what is wrong with the existing products - maybe easier to open without spilling it all over the kitchen counter.
Zotefoams (LON:ZTF) It is to with recycling, the problem with existing cartons, is they can't be or it is very difficult to recycle them, because they're made from mixed materials.
For us 'mystic meg tealeaf readers' on the Weekly chart below yes it 'on a bullish move' but it got to 530 in 09/2020 and has since languished.
What is going to make this bust the 550p and then power through the 700p regions in 2019.
Running shoes, airplane seats, er.. Sorry for the negs but never understood their moat.
Wear every day a pair of plastic shoes from Temu which are cheap, comfortable, washable and look more expesive than their £35. Ok the 'youf' won't be seen dead in them but then perhaps buying a car, house and having kids will become an issue at some point whilst grandad buys shoes for daily work from Temu. Maybe change name to grumpygrandad.
Many thanks for the Concurrent (LON: CNC) write-up, Paul. As always, you spot vital details that I've missed, such as the ridiculous management remuneration (big red flag for me). So, given the recent spike up (RSI chart shows it's well into the red zone) I think it's a good time to sell, book a decent profit, and monitor it for future developments.
Alphawave IP (LON:AWE)
Jan Frykhammar said: "Boards must evolve as businesses evolve, and that is why we continuously assess our needs so we can serve shareholders effectively.
Unbelievable that they can spout stuff like this bearing in mind how poor their efforts have been up to now !
each time they update and come up with "reason" as to why its been botch job up to now they seem to have this ability to continuously create more new red flags than they are solving. Albeit their prior method of solving seems to be to ignore what they have done before and flip to doing something new. more red flags than there is in China on China National day here .
Could all this turmoil present buying opportunity - deffo for the brave / gambling / heedtheball investors this one.
Does anyone still think this is a real business making the profits they say they have been making with enough repeat business for this income to not stop tomorow with some random explanation?
Back in 2023 I wrote the below in the SMCR (good luck searching for it) & little seems to have changed - I eventually got quite a negative impression. I'm sure Mr. Hill will provide the arguments on the other side if he is still keen on this one.
But for anyone who is interested in Alphawave this article is a useful refresher:
https://www.fabricatedknowledge.com/p/ride-the-wave-alphawave
I have no exposure and haved mixed emotions on this one - the technological opportunity is intriguing but the company appears at best to be careless, and it rarely ends well when you find yourself having to assume the best of someone......
Alphawave IP (LON:AWE)
It's not really that unbelievable if one understands what this business is up against, which evidently many don't.
As for buying opportunity, it is definitely not for the faint of heart. The risk is high, their business is in an extremely competitive market that requires significant development expenditure to stay in the high end product market. Nevertheless, they have manage to grow revenue by 300% (admittedly mostly achieved via acquisition) in three years despite having to make an early exit from their Chinese JV.
The JV generated approximately a quarter of the last three years of revenue albeit at a slight loss, though if they do exit their stake this year as they have said they intend to, it should add another $40 million or so to the cash balance ($100 million at end of 2023). The fact that there will be no more (or minimal) revenue from the JV for 2024 and they are guiding 2024 revenue at about $350 million indicates they are growing the OpenFive (custom silicon) aspect organically. Also, revenues from the recently developed connectivity products are expected to scale up significantly from 2025 onward, their first two main customers being AWS and I believe Tesla is the other.
The gross margins will improve. As long as the cash balance doesn't dwindle (the burn rate reduced significantly over the last 6 months) then there's a realistic chance of moving into cash flow positive territory by 2026 or 2027.
Hi - sorry for the off topic. A couple of months ago, a contributor here posted that they had written a novel with Stockopedia subscribers in mind. Does anyone happen to have the details?
Thanks in advance.
Hi - it may be Pigs get Slaughtered by J.D. Vaughan - I seen that mentioned the other day and got it for around a 5er on Kindle. Not sure who the contributor is, if they go by JD Vaughan or another username though!
This is an interesting point BL I’m wondering how easy it is for the search facility in the discussions section to be made better? I’d like to search comments by poster too in addition to specific words. Any tech gurus or Stockopedia experts out there?
Hi BL - yes, that is the book - Pigs Get Slaughtered. I enjoyed it.
I believe you can track people and their posts by clicking on their name and then in their bio clicking on the about/posts box - bottom left of the page.
Hope that helps.
It is just three weeks to go before the start of the Mello2024 investor conference and Stockopedia will be there plus Paul Scott and all the BASH regulars. Do come and join us....another six companies that are attending will be announced tomorrow and six were released on Monday and it will be another six next Monday.
We want to keep this important face to face engagement with companies going and it has been tough since Covid as many directors just want to do webinars as their only token offering to investors. If you want to ask private questions or check out body language it is impossible on webinars and investors need to network with each other too.
Please support us and encourage companies/ management teams you are in contact with to come along to Mello2024 in Chiswick on 22nd or 23rd May
Mello2024 – Mello Events
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24 BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
Full info on this thread Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
Alpha Financial Markets Consulting (LON:AFM) is being stalked by P/E according to Mark Kleinman (Sky) expect announcement anytime soon I imagine.
Bridgepoint/ Cinven and New Mountain Capital said to be sniffing.
Interesting to see FTSE100 is still hovering on green when it's European peers are reeling heavily! Is this a sign UK small caps will have some decent rise soon?
I think Europe is shut for May Day
still, recently it is doing well comparing others and VIX is so high. It was the opposite not long ago
Completely agree but I think the more salient comparison is that the UK seems to be outperforming the US and its current weakness and that is a real achievement, historically they catch a cold, we… etc…etc
Cornish Metals (LON:CUSN) have today published their PEA:
There is an emerging shortage of Sn and prices have responded from a low of US$17,272/tonne to today's US$31,216/tonne. Note the PEA does use a bullish Sn price, but prices are headed higher over the next 5 years (in my view).
The Geopolitical import of the South Crofty mine owned by Cornish Metals is interesting. Total global production of Sn is around 253,000 tonnes of which 110,000 tonnes is mined in China. The Chinese are seeking to control all strategic metals involved in our electric future and control much of what is produced in the DRC only really leaving Indonesia and S America as free from Chinese control.
I have held in the past and will pick up a small holding today. Who would have thought Cornwall have produced what might yet turn out to be a globally material Sn producer? The SP looks like it has turned a corner before publication of the PEA. Well ... it is listed on the Canadian TSX Venture Exchange as well as AIM, so what do we expect?
Hope it is successful.
Thanks for this, v interesting. I hold Alphamin Resources (CVE:AFM), the highest grade tin producer in the world at @ 4.5% tin grade. They produce 20kt a year, @ 7% of annual tin market and have a resource of 145kt tin with prospect of discovering further deposits in North Kivu in DRC to create a tin region. As you say, the base case tin price used in the Cornish Metals PEA is quite bullish, the average tin price over the last few decades is $25k/t. I prefer to see conservative metal prices used in PEA's, which is usually the industry norm. In most PEA's, the metal price used is usually at or below the average historical price in order to ensure the findings are robust. I wonder if they'd used a more conservative price then they'd be closer to or even below the magical minimum cut off IRR rate of 20% that most investors are looking for in PEA's. I'm impressed by the low AISC. Alphamin's AISC is @ $14,500 but would need to compare what costs are included in the Cornish AISC. I'd caution that, in my limited mining investment experience, PEA's are preliminary, the clues in the title, and are often subject to quite substantial revision by time of more detailed feasibility studies, and are often treated by investors as more marketing documents than serious pieces of work. Cornish certainly has less jurisdiction risk than DRC. I totally agree that we could be facing a serious tin shortage, especially as we need to compete with China for critical metals, and that it's use (mainly in solder for electricial devices) is just going to increase as we electrify everything, internet of things, solar panels etc. I'd differ slightly with you that China control most of the tin production in DRC. Alphamin produce most of the exported tin in DRC and they're a publicly listed co on TSXV, their largest shareholder is a US mining private equity house and their offtaker is Gerald Metals, a US metals trading house. Valuation ? I'd argue Cornish is probably priced about right for now. Most pre-construction, pre-financing mining co's trade at around x 0.2 - 0.4 NPV with best prospects around x 0.5. Cornish's current mkt cap is @ US$65m, or x 0.3 NPV. The use of an 8% discount rate for the NPV is also quite bullish. In the current high interest rate environment I've seen some NPV's use 10 or even 12% but also some try and get away with 5%. Anyway, good luck, would be great to see the mine open again.
Thx Joe ... great response. The PEA is certainly painting a flattering picture using 8% and in today's cost of capital environment 10% would be more appropriate. In the other hand, the jurisdictional risk is very low and permitting risk is very low, so one could argue a case for a lower discount rate. I am re-crunching their figures using DF at 10% and USD27,500 Cu price. I will try to remember to post the results.
You are quite right on Alphamin Resources (CVE:AFM) which I also hold being a Sn bull. The Chinese are very active in the DRC. For example, Robert Friedman's copper operations in the DRC are held in partnership with Chinese company Zijin Mining and Crystal River Global. I also hold Friedman's company Ivanhoe Mines (TSE:IVN) which has 6 bagged in 5 years.
Commodities and mining assets are at multigeneration lows compared to financial assets and I particularly like U, Sn and Cu. I think U mining assets are up with U3O8 pricing and actually a little over valued, but Cu and Sn assets looks undervalued to me.
Stocko could really do with a dedicated commodity thread as I know a lot of investors avoid the sector like the plague., but there are a few afficionados around!
What is the best way to get into Canada exchange in the UK.
IKBR, IGG all no good. Have AJB but specialise in safety ETFs etc.
Ref - unusual liquidity / tight spreads / fund selling down
Someone asked yesterday which companies I had noticed with unusually high liquidity (and tight spreads). Indicating a small cap fund winding down .
Pennant -
Transrnse
Both nornally quite illiquid and any buying normally spikes the price .
I’ve been biting away at pennant only for more shares to become available and price unchanged
Same on Transense
Two fairly strong sellers which I I understand is Canaccord at Transense
Canaccord seem to have increased in Pennant march 2023 so that doesn’t make sense
anyway tighter spreads and increased liquidity is a good sign of market sentiment improving
I think it was me .... thx for this planetX.
Looks like another profit warning at Inspiration Healthcare (LON:IHC).
Three TU's for us today, two Amber Green (Concurrent and Wickes) and one Green, Castings. I'm hoping they keep their traffic lights on go if Paul and Graham have time to look at these reports.
Transense / HSS / Georgia capital
Transense
Decent director buys yesterday from chairman, CFO and MD , 41 thousand shares sf 100.63
I did ask the new MD why he hadn’t bought many shares and he explained the open periods when he is allowed to buy are quite limited as of course he is always in possession of commercially sensitive information , all makes sense now so following the airbus RNS yesterday everyone is released to buy shares as they are not sat on priveleged information .
HSS
Results look ok not like a company on the ropes so it’s relatively lowky trading below NAV yet making profits in a tough economy looks wrong .
Sold half my holding few weeks ago at the top of the spike .
Read across to speedy hire also .
Both look sitting ducks for a takeover , it’s like buying a million pound house for 500k that gives pays you 30k a year income and you get to live in the house as well
Georgia capital
NAV up 9% in a quarter due to BofG rise .
that’s a serious rise which most followers had worked out .
simce I raised the discrepancy between Bank of Georgia rising 10% and Georgia capital falling 2% in the past month this has somewhat corrected and Georgia capital is normalising moving from 1290 level to 1360 so that opportunity has passed .
I put all my available cash just to catch fhis arbitrage gain , puts me very overweight on Georgia capital so now it’s jumped 5% am unwinding this, having to sell in small chunks though as it’s not the most liquid .
5% in a week better than a poke in the eye so that was nice
So you are the annoying seller Planetx !!
Georgia Capital (LON:CGEO) now with a NAV of £26+ versus a £13 share price. 50% discount which would be understandable if this was full of loss making jam tomorrows. But of course it isn’t…… almost all of market cap in listed Bank of Georgia (LON:BGEO) and most of the rest in the likes of profitable pharmacies, hospitals, infrastructure etc. Would think this will eventually trade at a more reasonable 25% but who knows when.
Yes, no one has been able to explain why there is this big discrepancy. I get that political risk means that Bank of Georgia is lowly rated but then a second discount is applied on top to Georgia Capital. A PER of 3 implies it is insolvent or there will be a highly dilutive fund raising, as far as i know this is not the case. I hold.
To be fair Epitychia Georgia Capital (LON:CGEO) is not the only PE/VC type share that trades at a significant discount so some of this is market malaise. A lot of that though was based on valuation concerns of underlying companies, and I don’t think you can really throw that at Georgia Capital (LON:CGEO)
Thus I would expect a premium to be applied for quality of assets and a discount to be applied for geo political risk broadly coming out at a 25% discount to NAV. That would put the shares at £20 which feels like a fairer reflection and a 50% increase from here. But wtfdik :D
I’m only selling as and when I need the cash .
Sort of using Georgia capital instead of a bank account .
Just bough a 40 foot container of roof tents so that’s todays sales explained !
Morning planetX
From my viewpoint VP (LON:VP.) is the best of the plant hire companies. Although not unaffected by the economic climate, it remains substantially profitable, in large part thanks to the diverse range of industries that it serves. Haven’t checked recently but PE and yield are similar around 7/8
It is financially stable and founder led by Jeremy Pilkington who continues to hold 50% of the equity, which admittedly some may see as a risk, but he put the company up for sale a few years ago and withdrew it when an acceptable offer was not forthcoming. So I am sanguine with his holding.
Just my view. I have a modest holding.
All the best
Re HSS Hire (LON:HSS)
I have held long term but have not enjoyed the ride... the incessant falling share price has had me increasingly concerned over the last few months.
Obviously the construction industry has been quiet and that will have been the major factor. But many other construction related shares have started to turn round now that the first interest rate fall is not too far away. Yet Hss just keeps falling.
I read the results this morning as considerably below expectations, but perhaps the market had expected worse. They looked below the forecast eps on stocko. Although there were quite a few adjustments so hard to tell.
The killer for me today was the follow up rns announcing that CFO is leaving to spend more time with his family (in the short term). Sounded like he'd rather have no job than be at hss. Maybe I've got that wrong too?
Anyhow, i sold out this morning at a considerable loss and i have to say i was quite pleased that Mr Market offered me the same price today as he was offering yesterday.
Shame as i quite like the idea of having plant hire services in builders merchants... seems sensible.
Other holders shouldn't worry too much by my analysis. Usually my sells are a good catalyst for a change in direction in the share price.
Re HSS Hire (LON:HSS) and Speedy Hire (LON:SDY) , you should look across to VP (LON:VP.) too. That's been on the move recently too...
Any chance of a look at Concurrent Technologies (LON:CNC), please Paul? This looks to be an interesting turnaround story under new management. Full year figures are very strong, with good revenue growth, operating profit and cash generation. Defence markets are obviously buoyant right now and the outlook statement is positive. Dividend reinstated too.
Hi sparkler,
Thanks for the synopsis of Concurrent Technologies (LON:CNC) - I'll do that one next, as it sounds interesting, and I see is on the most viewed widget here on Stockopedia. Section should be up by about 09:30 hopefully.
Regards, Paul.
I'd suggest adding Concurrent Technology (LON:CNC) to your list. I always like to read that companies are "pleased" when announcing their results. Concurrent are, and with good reason - 73% increase in gross profit, dividend reintroduced etc - new CEO Miles Adcock is turning this previously rather conservatively run company into something with really exciting growth prospects. Broker TP released today of 165p (currently about 100p).
I asked Lord Lee about Concurrent at the last in-person Mello event - he predicted that good news was to come! I hold, so great to see it happen.
Aston Martin Lagonda Global Holdings (LON:AML) Q1 results - if they have turned the corner, they have missed the apex.
Not a holder at the moment of Aston Martin Lagonda Global Holdings (LON:AML) but I believe that the new CEO (given time ) will guide the company to much better days.
All the best
I hope you are right yiannos .... love my old DB6, but have never found any compelling reason to buy the shares.
I think holding onto the DB6 for the next few years would be a better investment!
Why?
Its not electric, its not eco, its not green, it has no longer parts available, its noisy, its uncomfortable, its brakes are poor at best, its suspension is a a beefed up tractor, it does not have sat nav installed or bluetooth and maybe a small tree is established in the gap between the bonnet and the wiper blades and rust is ever present.
Long may you be able to drive said DB6 on British roads and through our great city of London without encumbrance.
My morning smallcap tweet: Inspiration Healthcare gasping
Intelligent Ultrasound (LON:IUG) Seeing Machines (LON:SEE) Altitude (LON:ALT) Springfield Properties (LON:SPR) Narf Industries (LON:NARF) Renold (LON:RNO) Mulberry (LON:MUL) Novacyt SA (LON:NCYT) Poolbeg Pharma (LON:POLB) Castings (LON:CGS) Global Ports Holding (LON:GPH) Cambridge Cognition Holdings (LON:COG), Next (LON:NXT), Dianomi (LON:DNM), Anexo (LON:ANX)
◄Intelligent Ultrasound (IUG)► FY-Dec in line with rev £11.2m. Outlook - guides FY rev £14-17m. "UK market is experiencing tougher trading conditions due to the current reduction in NHS capital expenditure spending but anticipate growing revenue from high margin AI-related products and non-UK related simulation markets". Still expects to reach profitability with its current cash resources [SP=8.63 Cap=28m]
◄Seeing Machines (SEE)► expands programme with with an existing North American Tier-1 customer to 2032. Will cover 19 vehicle models. Worth estimated $26m. [SP=4.29 Cap=177m]
◄Altitude (ALT)► guides FY-Mar at least in line with F/C of rev £26.1m and adjusted EBITDA £2.2m. Outlook: very strong start in Apr. [SP=31.5 Cap=22m]
◄Springfield Properties (SPR)► wins £10m affordable housing contract to be delivered over next 18 months. [SP=93 Cap=110m]
◄Narf Industries (NARF)► thin news as it trumpets accelerating work on "cutting-edge capabilities shown to be uniquely effective in battling a new generation threat to the global open-source software supply chain". Needs to work on some new buzzwords. [SP=1.08 Cap=18m]
◄Renold (RNO)► wins Canadian Navy order worth £10.6m over 6 years. [SP=49.46 Cap=111m]. I hold.
◄Mulberry (MUL)► warns FY-Mar rev down 4%. Blames broader downturn in luxury spending in recent months. Outlook "trading environment in the UK and China remains challenging and we do not expect this to change in the short term". [SP=115 Cap=69m]
◄Novacyt (NCYT)► court has dismissed the application by the Department of Health and Social Care for summary judgement in the defective tests case. [SP=72.65 Cap=58m]
◄Poolbeg Pharma (POLB)► gets fully granted US patent for Immunomodulator II patent application, as expected. [SP=12 Cap=60m]
◄Castings (CGS)► guides FY-Mar marginally ahead of market expectations. Outlook - "The backlog demand from the Covid period, and the well-publicised supply constraint issues, appears to have now been absorbed by the OEMs and forward schedules are now at a lower level". [SP=376.98 Cap=164m]
◄Global Ports (GPH)► has begun operations at Saint Lucia Cruise Port. [SP=217 Cap=165m]
◄Cambridge Cognition (COG)► FY-Dec in line with rev £13,5m. Outlook - increased contract wins in Q1 but with several major contract delays, the majority of new business is expected to occur in H2. Guides FY rev £13-15m. [SP=51.1 Cap=18m]
In line: NXT, DNM, ANX
Any thoughts on Eenergy (LON:EAAS)
It looks really good to me, but maybe just missing something
Expecting revenue of 25-26m - the Energy services was 17m last year, significant uptick
Profit was -200k but year before was -3m so totally in the right direction, cutting costs, bigger contracts should be even better next year.
Much stronger balance sheet now as well post the sale of their other division.
Net Zero such a big topic great place to be. Seems cheap to me
Quote from report: "Over the last three years since listing on AIM, we have delivered a 58% compound annual growth rate in revenues " -- that should be flying, surely.
Renold (LON:RNO) £10.6m contract win with Royal Canadian Navy. Is this one on Paul's list, you'll be passing Graham soon :-)
Renold (LON:RNO) shares are down today, this is a very small contract, over 6 years.