Small Cap Value Report (Weds 10 April 2024) - HVO, MERC, TET, THG, XPP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
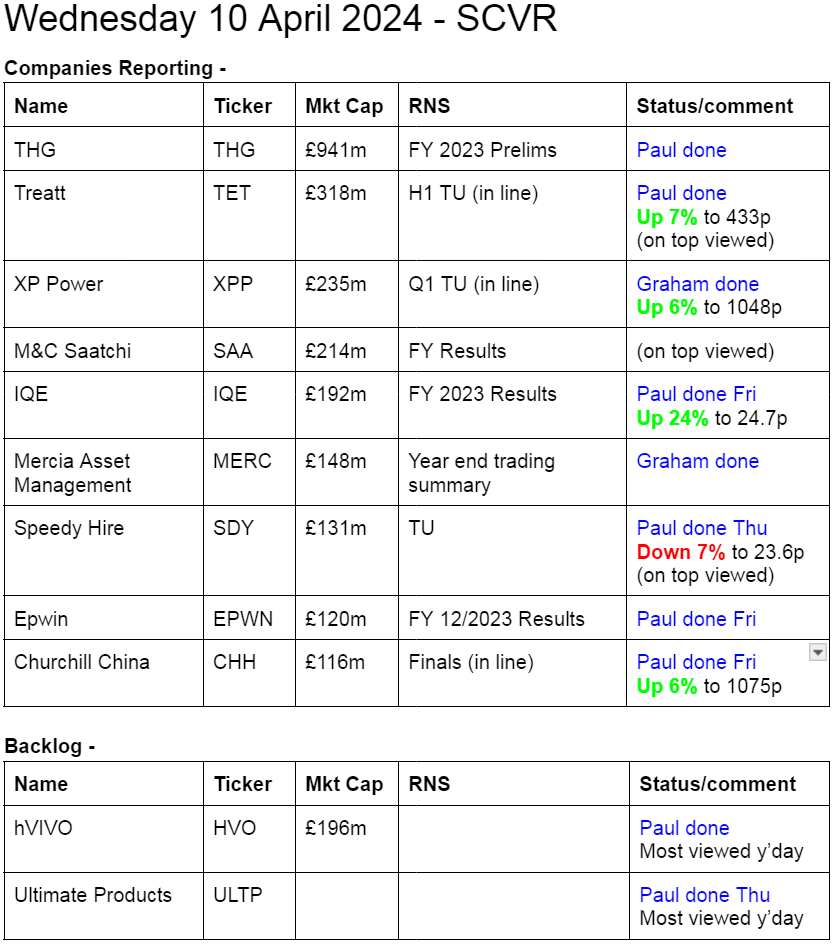
Summaries of main sections
hVIVO (LON:HVO) - 29p (£196m) - Final Results - Paul - GREEN
As this share is popular with readers, I've circled back to its impressive 2023 results, published yesterday. Strong growth, as expected, a reassuring outlook section, and sound balance sheet & cashflows - all pass my testing! Valuation still looks reasonable to me, and there could be further upside if it continues the trend of beating expectations with positive trading updates. So I remain positive on HVO shares.
Mercia Asset Management (LON:MERC) - up 6% to 35.95p (£157m) - Year end trading summary - Graham - GREEN
A good update shows Mercia hitting and possibly exceeding its targets and estimates: FY March 2024 saw £0.5 billion of organic fund inflows and zero redemptions. A subsidiary has hit its two-year target with eight months to spare. NAV per share should still be around 45p.
Treatt (LON:TET) - up 8% to 436p (£265m) - H1 Trading Update [in line] - Paul - AMBER/GREEN
An in line H1 trading update, shows a return to growth in Q2, after a tough Q1 due to customer destocking. On balance, I take a moderately positive view.
THG (LON:THG) - down 1% to 66.8p (£930m) - FY 12/2023 Results - Paul - RED
Terrible numbers for 2023, with another hefty loss. It dresses up the results by focusing on meaningless adj EBITDA. The valuation looks nuts to me. Although the leverage on £2bn revenues is such that if margins do improve in future, then it might become a viable business possibly.
XP Power (LON:XPP) - up 13% to £11.20 (£265m) - Q1 Trading Update - Graham - AMBER
An in-line update, after a nasty profit warning earlier this year. The market is relieved but I’m still concerned by the lack of stabilisation in the company’s trading trajectory. The company suggests that Q2 orders will tell us whether the customer “destocking” trend has ended.
Paul’s Section:
hVIVO (LON:HVO)
29p (£196m) - Final Results - Paul - GREEN
Results were published yesterday, and most viewed by readers here.
hVIVO plc (AIM & Euronext: HVO), a rapidly growing specialist contract research organisation (CRO) and world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces its audited results for the year ended 31 December 2023.
Company’s summary -
A record year across all financial and operational metrics
On track to deliver future growth targets
Initiating annual dividend policy
Impressive headlines, including good revenue & profit growth, large order book, big cash pile (from up-front client payments), and commencement of (modest) annual dividend (note it did pay a special divi in 2023) -
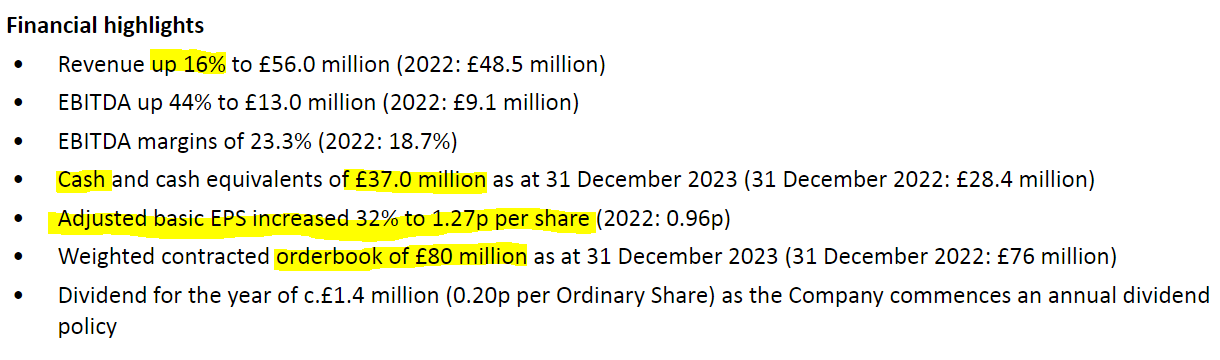
Profit before tax is missing from the bullet points above. It was £11.1m in 2023, up 69% from £6.6m in 2022 - very impressive.
Note the growing cash pile is providing a helpful income now interest rates are higher - net finance income rose from £617k in 2022 to £1,055k in 2023.
Tax - note there is a large tax credit of £5.0m, turning PBT of £11.1m into PAT of £16.1m, with a corresponding boost to EPS which is 2.35p (diluted), but adjusted EPS is 1.25p - with the main adjustment being to normalise the tax (£8.1m adjustment - see note 11). So obviously it’s the adjusted EPS we should be using to value the shares - a PER of 23.2x - which strikes me as about the right price for an impressive growth company.
It depends on where you see future growth heading - it might still be cheap if revenues/profits grow faster than forecast. Note that HVO has surprised on the upside quite significantly in the last year or two, and often companies that out-perform continue to out-perform - and brokers are often too cautious with successful growth companies (as we saw y’day with W7L) -
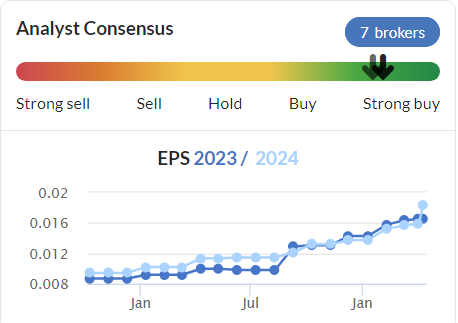
Broker update - Cavendish says the 2023 results are in line.
It has 1.6p forecast for FY 12/2024, which would bring the 2024 PER down to 18.1x, which seems reasonable to me.
Outlook -
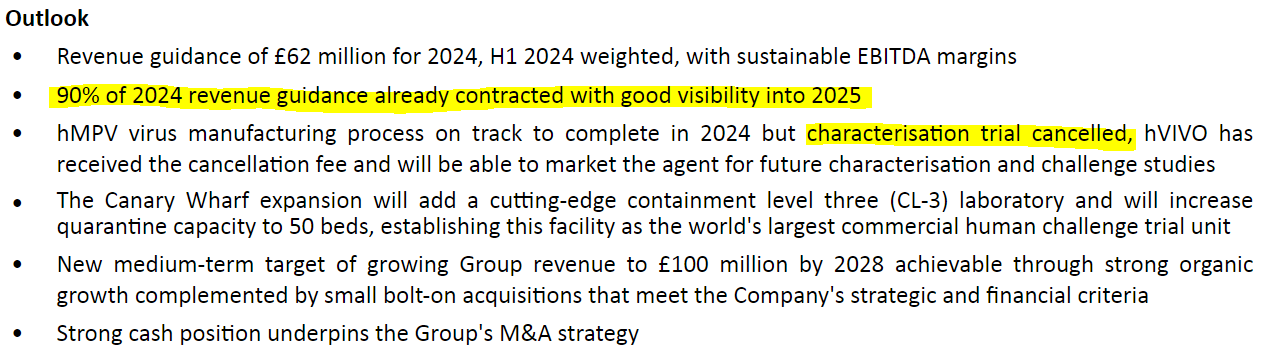
…Q1 2024 trading in line with expectations and the Company remains confident that 2024 will be another year of significant growth.
Detailed guidance below is useful. I’m not sure what, if any significance there is for the cancelled trial? -
Balance sheet - looks good. NAV of £34m becomes NTAV of £29m, which is plenty for a company that gets paid up-front by customers, hence doesn't need a lot of capital.
Note the big jump in lease entries, which must relate to its new facility at Canary Wharf which is coming on stream around now - and presumably the additional capacity should help further revenue increases, but with some extra costs too.
Cash of £37m is ample, although remember it’s come from getting paid up-front, so if there was an unexpected slowdown in order intake (eg another pandemic lockdown, or a competitor winning new business), then the cash pile would reduce - always worth bearing in mind. Bulls always like me to point out that the customer deposits are not refundable. That’s true, but it’s still getting paid up-front, which means a lot of the costs of providing the service have not yet been incurred.
Overall, it’s a very comfortable financial position, so no issues here.
Cashflow statement - note the £2.4m benefit from R&D tax credits, which is material to the overall profit, let’s hope this generous scheme remains in place.
Note the £5.2m in 2023 (and £11.2m in 2022) boost to cashflow from increased payables - this is recording the benefit of up-front customer payments.
Capex rose from £1.3m to £5.2m, presumably for fitting out the new facility in Canary Wharf, which is fine, this is not excessive at all.
Overall this all looks good - it’s a genuinely cash generative business, albeit with most of the cash increase coming from increased receipts up-front from customers. Don’t shoot the messenger in the comments section please! I’m just pointing out the facts.
Paul’s opinion - I remain positive on this share, it’s been a remarkable turnaround in the last few years, and now seems to be exploiting a lucrative niche. I’m still perplexed as to why there doesn’t seem to be much competition? Does HVO have any long-term moat? So increased competition (which tends to happen when other people also spot the lucrative niche) is probably my main downside worry.
Valuation stacks up, and still looks reasonable, especially if HVO continues its track record of beating expectations.
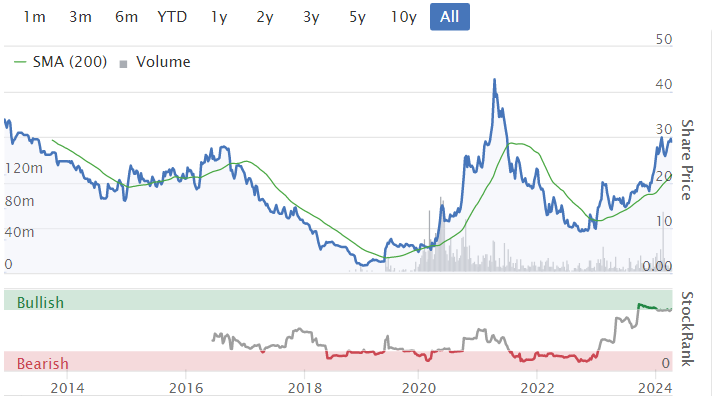
So based on how things stand now (I can’t predict the future remember!) it has to be a continued GREEN view from me. Well done to bulls, it’s been a star performer - tripling in price since the late 2022 lows.
Shares have been very volatile, but the business fundamentals are now far better than at any time in the past, so I think the recent bull run has been justified -
Treatt (LON:TET)
Up 8% to 436p (£265m) - H1 Trading Update - Paul - AMBER/GREEN
The financial year ends 9/2024.
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, announces the following trading update for the half year ended 31 March 2024 (the "Period").
Company summary -
Solid performance in H1 2024, with sales accelerating in the second quarter and year-on-year profit growth
H1 revenue down 5% to £72.1m, but within that the trend is positive - a weak Q1 due to customer de-stocking (previously indicated), then a rebound to +5.1% in Q2.
Profit before tax slightly up in H1 to £7.5m (LY H1: £7.3m) - not bad considering revenues were down 5%, suggests to me that margins are OK and overheads under control.
Outlook - seems reassuring -

Valuation - no broker research is available.
Broker consensus on the StockReport shows 24.0p for FY 9/2024, up c.9% on LY. That’s a PER of 18.2x, which strikes me as generous considering TET’s lacklustre track record. Although it does now have a spangly new factory in the UK, so hopefully the additional capacity and efficiency might see performance improve?
Paul’s opinion - the bull case for TET seems to rest on its European competitors being highly valued, so TET should be as well. TET is capital-intensive - it’s spent a lot on capex in recent years, but as yet there’s not been any increase in profit.
On the upside, it’s now showing an improving trend in Q2, so looks as if customer destocking has ended. The valuation seems more reasonable than in the past, and there’s little debt.
On balance then, I’m happy to stick with a moderately positive view of AMBER/GREEN.
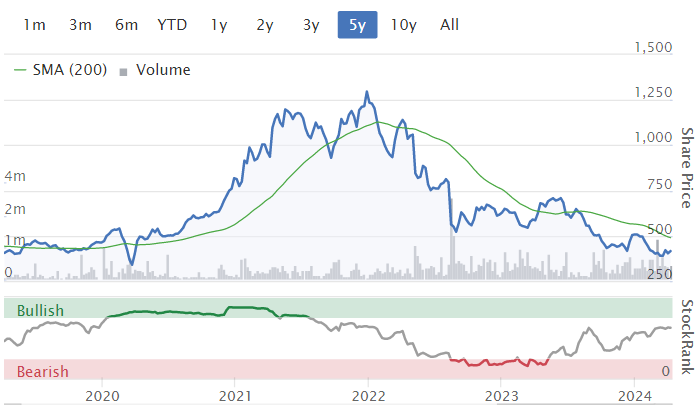
Sentiment has really plunged, so I wonder if a turnaround might be on the cards? -
THG (LON:THG)
Down 1% to 66.8p (£930m) - FY 12/2023 Results - Paul - RED
Very quick notes, due to time constraints today. If you want an example of how adj EBITDA can be used as smoke & mirrors, then these accounts are a great example.
There’s no growth (revenue is down).
Adj EBITDA us up 48% to £120m.
However, the operating loss is £(185)m, and the loss before tax is £(252)m!
Why such a huge difference? It’s due to heavy capitalisation of development spending (£79m), large depreciation charges on its expensive automated warehouses, massive finance costs (remember it has c.£650m of expensive bank debt, although partially offset with cash, so net debt was £218m) - I’d like to know the average daily net debt.
Weak balance sheet with negative NTAV of £(185)m.
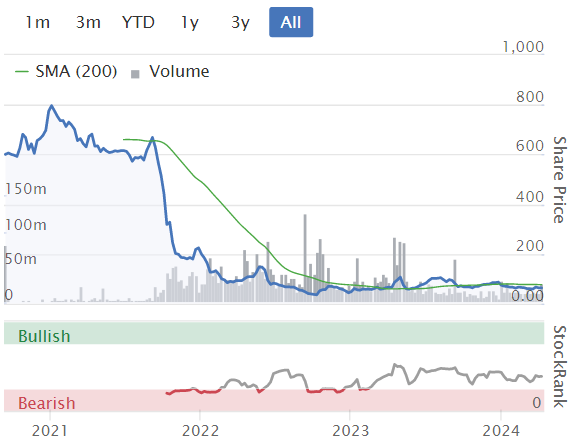
Paul’s view - I don’t see any sign of a viable business here. Unless it can drastically improve performance, then I think THG could end up going bust. So quite why it’s still valued at almost £1bn, I have no idea. The figures are awful, although not quite as awful as last year.
Obviously I don’t know what the future holds, and on big revenues of c.£2bn pa, it doesn’t take much of an improvement to transform profit & cashflow for the better. That must be what bulls are hoping for, but there’s no evidence at all so far that this is actually happening. Management worry me greatly too, I wouldn’t have any confidence backing the current team, who I think got wildly carried away with tech mania, and would be better suited working in the USA.
Graham’s Section:
Mercia Asset Management (LON:MERC)
Up 6% to 35.95p (£157m) - Year end trading summary - Graham - GREEN
Mercia Asset Management PLC (AIM: MERC), the proactive, regionally focused specialist asset manager with over £1.5billion of assets under management, is pleased to provide a trading summary for the financial year ended 31 March 2024 ("FY24").
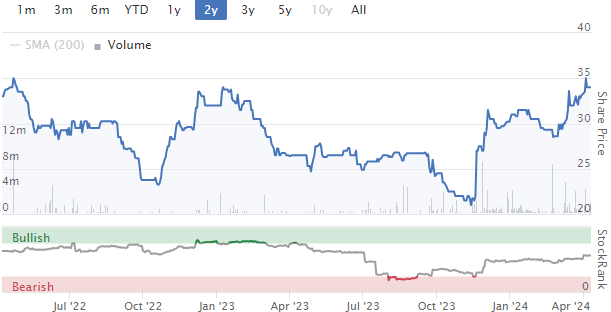
This one has made it onto my best ideas list for two years running. Share price performance has been OK overall:
Today’s short trading update is as follows:
Organic fund inflows for FY24 as a whole exceeded £0.5billion, which is a record for Mercia and represents a c.40% increase in Mercia's third-party funds under management, since the beginning of the financial year. There were no redemptions. As a result of these substantial inflows, Mercia has begun the new financial year in a strong position.
There is no shortage of doom and gloom in the fund management industry. But Mercia is one of those rare fund managers seeing inflows and zero outflows. Granted that it’s starting from a low base, but in my view it is clearly offering something different and attractive to fund investors, and deserves its success.
Other key points:
Frontier Development Capital (link) (acquired by Mercia in late 2022) has raised over £100m of institutional 3rd party funds. This two-year target has been reached with eight months to spare, triggering defcon payments.
Mercia’s direct investment portfolio “continues to make overall technical and commercial progress”.
Cash at the end of March 2024 is £47m.
Although not mentioned in today’s update, the company has been buying back its own shares since the announcement of a £5m buyback last November. So far, it has bought back around 11 million shares (this still leaves 435 million shares outstanding).
CEO comment excerpt:
Mercia's record year of organic fund inflows for FY24, which exceeded £0.5billion, is testament to our investment performance, together with the operational teamwork of everyone in our Group. It also reflects Mercia's ability to effectively deploy equity and debt funding across the UK, through our established regional footprint..
"Our significant closing debt free cash position as at 31 March 2024 of c.£47million, means that Mercia enters the new financial year in a strong financial and liquidity position, across both its managed funds and balance sheet…
Graham’s view
As a fan of this business for some time now, today’s update is unlikely to change my mind! Mercia is in rude health and appears to be going from strength to strength as a manager of third-party funds.
One point that is worth a mention is that the majority of the new flows have been sourced from the State-owned British Business Bank. I’d like to see more diversity in the sources of new flows: maybe that’s something for the company to work on in the new year.
Estimates: an excellent note from Canaccord Genuity this morning suggests that the new financial year (FY March 2025) will see AUM hit £2 billion and revenues increase from £30m to £34m. They haven’t changed their estimates today, but they do see upside risk to forecasts as the company appears to have beaten their AUM estimate for FY March 2024.
Please note that the profit result here tends to be volatile:
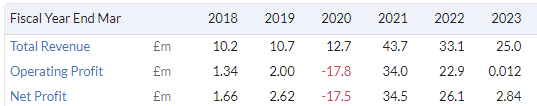
This company does tend to look expensive relative to earnings, but remember that it’s carrying a large cash balance and a direct investment portfolio. NAV per share is still likely to be in the region of 45p.
XP Power (LON:XPP)
Up 13% to £11.20 (£265m) - Q1 Trading Update - Graham - AMBER
This is an “in line” update.
XP Power, one of the world's leading developers and manufacturers of critical power control components to the electronics industry, is today issuing a trading update for the first quarter ended 31 March 2024.
The company’s numbers continue to move in the wrong direction.
The “book-to-bill” ratio stands out to me: it’s not often that you ever see a reading as low as this one.
At 0.68x, it means that for every £100 of billings (or revenue), the company only took in £68 of new orders. This doesn’t augur well for future revenues:
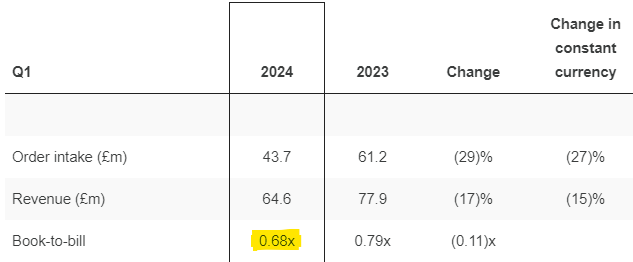
However, this 0.68x level is actually a slight improvement on the book-to-bill in the most recent quarters.
The reason? It’s not because orders have picked up in recent months, but because revenues started to fall faster.
Falling revenues are another way for the book-to-bill ratio to stabilise or improve:
XPP’s Quarterly orders: fell from £54.5m (Q2 2023) to £43.7m (Q1 2024)
XPP’s Quarterly revenues: fell from £82.3m (Q2 2023) to £64.6m (Q1 2024)
Divisions: sales and orders from the Semiconductor manufacturing equipment sector are similar to H2 2023. But the Healthcare and Industrial Technology sectors have “slowed as customers continued to destock” (the dreaded word!).
Net debt fell by £9m in the quarter to £103m.
Outlook: expectations unchanged.
As expected, revenue in Q2 is likely to be slightly lower than Q1 due to ongoing customer destocking, and we continue to expect trading to improve during 2024 as channel stock levels reach equilibrium and as demand for Semiconductor Manufacturing Equipment begins to increase. Order intake in Q2 will provide greater clarity on the timing and trajectory of this improvement.
We are confident that our market positions remain strong and that the Group is well positioned to prosper as our key markets resume their trajectory of healthy long-term growth.
Graham’s view
This company still appears troubled. We have extensive coverage in the archives, including a recent profit warning, interim results and a fundraising last November.
Today’s news shows the company’s downward trajectory continues. Even if the market likes today’s update, I can’t say with confidence that XPP has stabilised. It would be great if we could make the argument that at least visibility has improved, but I don’t think that’s true either as the company itself acknowledges that order intake in Q2 is needed to provide clarity.
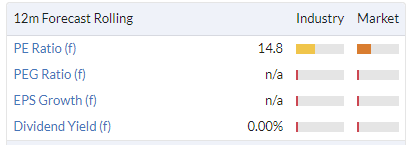
Net debt remains high, although probably not distressed: net debt/EBITDA is probably somewhere around 2.5x.
Paul has been putting this at AMBER/RED. I’ll maintain my AMBER stance on this one: hopeful for an improvement in trading soon, but not expecting it. Some bravery is required to get involved here, I think.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Does anyone still hold NB Global Monthly Income Fund (LON:NBMI) ?
A big fall today so now showing a buy price at 51p to NAV 76p last night
Appreciate in the later stages of wind down but I still have a small holding which is at a loss at SP but profit at NAV.
I had previously reinvested the payout but I had held off as after the last couple of redemptions there had been a larger fall after a while and now debating do I buy more and wait for the next redemption day.
Ta Tommy
I have been trawling through the family trust portfolio and have extracted all the shares the trust has held a long time, the newest having been purchased on 20th July 2010. The trust also holds other tangible non securitised assets like farmland, property and a few investment trusts which are of no interest, here at least. In just under 14 years, by doing precisely nothing, these shares have produced a total return of 426%. Returns vary from 1958% for Intuit down to -70.2% for Schroders. The CAGR calculates at 12.6%. I am happy to post the complete holdings if anyone is interested.
There are several lessons here:
1] Imagine the beauty of doing nothing;
2] My family's inactivity / laziness reminds me of the "coffee can" portfolio and also the story of the best performing private investors in one of the big US brokerages were the dead;
3] We are a Scottish-Scandi-German family and some of the portfolio is listed in Sweden, so look outside the UK. If there is a SEDOL number with an attendant CREST certificate, you can buy it. There is a lot of research showing that Sweden is the best market in the world in a per capita basis for producing 100 baggers, better even than the USA's NASDAQ.
4] The important metrics are ROCE and free cashflow. Beyond that it is low debt, market position and the quality of leadership and governance.
5] There is a remarkable lack of volatility ;
6] These results exclude dividends which are about 2% per year;
7] The holdings are all medium and large cap shares ;
8] We should have chopped out Schroders and one or two others earlier?
Maybe 12.6% CAGR (+2% dividends) through two big draw downs (GFC and Covid) is sufficient ... maybe not.
Apologies if this curious case of the benefits of inactivity is of little interest. For myself and my own portfolio, I will endeavour to be a lot less active in future!
Hello jamesalastair, it is of interest, thank you for posting. I try not to tinker and must stay strong, especially when bored.
If you want to read more on coffee-can success probabilities, then I would recommend Long-term stock market winners and losers by Mark Simpson, which shows that over 30 years, about 8% of global stocks nine-bagged or greater. It really is worth taking a moment to fully understand the graphs from this Bessembinder et al study, which show what percent of stocks make what return after a month, a year and 30 years. Mark also refers to his earlier article, Screening for 100 baggers, which goes through the history of the coffee-can idea in the section 'Portfolio management and risk'.
In the comments section of the first article, Mark says, "I don't think a pure coffee can approach works. You are right, we only hear about the winners, not the people who had a coffee can full of poor investments. The Bessembinder study shows that the longer the time horizon, the fewer stocks make the grade so the chances of having a winning coffee can declines."
I'm glad your trust was one of the coffee-cans that came good.
I suppose it depends also on your view as to whether 14 years - just under 14 years - is long enough to qualify as a "coffee can" portfolio. It is interesting looking at the non-performers as well as some of them only did a bit better than double in that time and this underperforming group contains some well-known titans: Nestle SA (SWX:NESN) + 148%, Heineken NV (AMS:HEIA) + 149%, Coca-Cola Co (NYQ:KO) +166% and of course Schroders (LON:SDR) - 72%.
Like you, I adopt a more active approach, but have not really done any better and there has been a lot more stress along the way.
Nearly forgot to thank you for the book recommendation, Indie.
Trading fees can really add up, just like those regular Starbucks or cheaper coffees every other day ,and affect the overall portfolio results and cause overthinking sometimes in my opinion, which can cause me to sell a good share longer term.I think i remember reading about that in Graham's Intelligent Investor.I'm not a great trader really, but it's fun occassionally for engagement.But not great if i either lose week to week interest and want to go off and do some other hobbies for a while.Just need to find a way to get rid of the bad ones earlier.
To add my own 2c ... Short holding periods will have a lot of noise in them. Long holding periods increases the signal to noise ratio. The fundamentals assert themselves. Over short periods, both good and bad companies can fluctuate wildly.
Indian investor Pulak Prasad observed that even for great long-term performers, share price returns are often lumpy over shorter time-frames. Big jumps often occur in short random bursts. It's not possible to jump in and out of a stock trying to predict the moves. Only a long-term perspective will capture them.
Great post 14.6% per annum (including divi's) for pretty much doing nowt is a great annual return long may it continue.
Out of interest James is that return just relating to the equity part or the entire portfolio including the alternative assets you mentioned ?
Hi Pheonix. Yes, it only relates to the equities part which is smaller relative to the farm, property, and forestry. I have no idea what the farm is worth ... it is now farmed in a farming partnership with a young fellow who supplies the machinery, the enthusiasm, and the energy. I am semi-retired and just run my own small farm, go fishing and tinker too much with my own portfolio. I mention the size in case the word "trust" creates a vision of multi-million-pound trust funds, St Tropez and Monaco; actually, we are a modest family of engineers, scientists, teachers, and farmers.
Thanks James sounds like you have the work life balance sorted, I'm coming more round to the idea that with this investment lark your better off in quality dividend paying mid/large caps, or investment trusts, plus a bit of gold and a dollar tracker.
Rebalance monthly and avoid any major asset tinkering unless its obvious you have got something really wrong but I do believe top slicing profits and not constant chopping and changing is the way forward.
Only took me two decades to come to this conclusion enjoy the fishing as we all get older you start to realise that your time left on this planet might be only 20-25 years which will go in a flash, spend time with family, try and help others and don't get to stressed when things go wrong are my mantra.
Centaur Media (LON:CAU)
I hold
The shares have spiked by 38%. On checking the RNS feed
"The Centaur Media Plc board of directors (the "Board") notes the recent media speculation in the Centaur Media Plc share price and confirms it has received a highly preliminary expression of interest from Waterland Private Equity Investments B.V. ("Waterland") in relation to the proposed acquisition of the entire issued, and to be issued, share capital of the Company."
While out for a run this morning I was pondering my portfolio of 27 UK small caps and thinking that I hadn't received a bid since the takeover of Air Partner in early 2022.
Centaur Media (LON:CAU) came to mind, especially its ownership of the specialist publication 'The Lawyer', which thought he, is a must have in the legal profession and is therefore a valuable asset, worth a large percentage of the then 40p share price. Christopher Mills and the Harwood stable, including Richard Staveley own close to 30% of the company and have held it for quite some time. Harwood will not sell unless the price is right. Hopefully from a personal perspective the sale goes through as it will provide funds for adding to existing holdings or a new addition to my ISA.
My original purchase was at around 40p, during which time I have benefited from some good dividends
Well done Jonno .
Congratulations on sitting tight it was always worth far more on a sum of the parts so hope you get 65p plus
Thank you planetX. Yes 65p would be a nice return, whether Harwood will accept such an offer should it happen is another matter.
Hi
US CPI higher than estimated ... US futures taking a dip. Nasdaq 100 down over -1.40% as I type. FED rate reduction in June 'off the table' now (Bloomberg )
Howard
Spirent Communications (LON:SPT)
The bid has fallen to 194p today, as Spirent is the subject of competing bids, the best at 199p plus a 2.5p dividend, does this suggest fear of the second, higher, bid dropping out or investors selling out of Spirent because of the limited upside to invest in more attractive stocks? The volumes dont really suggest the latter is the case but it makes sense to me.
Any one have any thoughts?
Spirent Communications (LON:SPT) Any one have any thoughts?
Once a share is bid within 5% of an agreed takeover price, I always sell. Chances are, I can get the same return or more over the usually 6-9 months it takes for a deal to close. And I don't run the risk of the deal falling through and losing 40-50% (assuming a c.30% takeover premium)
Except that if you had done this with Spirent Communications (LON:SPT) on its first bid approach you would have missed out on a further 15% from the rival offer! I suspect that the market is now pricing in some risk of a referral of the Keysight deal to the competition authorities, which the other bidder suggests might happen.
Except that if you had done this with Spirent Communications (LON:SPT) on its first bid approach you would have missed out on a further 15% from the rival offer
Indeed. I did just that, sold for 172.5. And will do so again. Why? Because the theoretical loss of even the extra 15% will be eroded by the time value of the money reinvested while waiting for the deal to close. And the risk of it falling through is eliminated. I'm a very disciplined buy and hold investor, but a "take profits and move on right away" trader as soon as the name looks poised to fly the nest. With nearly 200 stocks in the fund, takeovers are a reasonably common occurrence - most recently Shockwave Medical (NSQ:SWAV) by Johnson & Johnson (NYQ:JNJ) - so I've almost always got a new replacement ready, or a temporarily fallen name to top up.
If I ran a more concentrated portfolio, I'd probably split my strategy.
You have a point BnB. I remember selling Revolution Bars at just under 200p per share rather than waiting for the bid to go through a few years back! However, I'm not sure that it is quite the 'no brainer' that you suggest. I was lucky enough to wait for the second bid for Spirent before selling recently but conversely I spooked myself out of DS Smith after the initial Mondi approach and now they sit some 25% higher after Intl Paper entered the fray.
You're quite right, it's more nuanced than I initially articulated. Each takeover situation is different and holding on definitely can pay off. It's just not my style!
Possible takeover of Centaur Media (LON:CAU) announced today by private equity group Waterland . The usual nice problem to have, take the money or see whether a bid does eventuate and at what price. Up about 27% presently !!
From a personal perspective I will hold and watch. If you own Centaur Media (LON:CAU) shares you have Christopher Mills and Richard Staveley on your side. You would be hard pressed to name two more canny investors.
Also Centaur Media (LON:CAU) is hardly expensive at 40p, or thereabouts, this morning opening price. So even if an offer fails to materialise it is worth continuing to hold. I would also add that the company is now in play and their may be other potential suitors in the wings.
Just my thoughts.
For what it's worth for Eagle Eye Solutions (LON:EYE) holders, this report came out in The Daily Telegraph an hour ago:
https://www.telegraph.co.uk/ne...
I don't know if it's behind a paywall but this is the headline:
"Pret app in chaos after subscription crackdown leaves customers threatening to quit
Coffee drinkers unable to claim their free beverages after being forced to log in to ‘terrible’ app several times a day"
Obviously not good news for Eagle Eye, maybe just a blip, maybe something more serious. I pass it on for holders to make their own decisions.
Eagle Eye don’t provide the apps for their clients. They provide the system which connects the front end to the databases and personalises any offers in real time. Sounds more like an app provider issue than an Eagle Eye issue.
I rarely look at any small company share that doesn’t get a green rating from Paul or Graham, but THG (LON:THG) is a rare exception. It’s a junk share as Paul’s update today makes so clear, so should be in “don’t buy it’s bargepole” category. And I’m a cautious investor looking for quality shares and Investment Trusts at bargain prices. So why buy THG (LON:THG) ?
Well…….note that final comment from Paul. THG (LON:THG) Directors “would be better suited working in USA.” That’s why I bought again at 60p last week. US market seems far more tolerant of rubbish and there has already been a rejected bid at 170p because Moulding (ludicrously) thought it undervalued the true value. And Apollo made a bid approach that again came to nought a few months ago, but that sent the share up to 95p. Even if no bid materialises the volatile share price also provides trading opportunities.
Small Company Sharewatch plug THG and it’s in their portfolio but their write ups sugar the figures or ignore them. And LIBERUM have a 220p share price target….on a share making huge losses and already with a market cap around £1 billion.
THG (LON:THG) is a punt with money we can afford to lose and as Paul said today it could go bust. Equally it could double in a day if there is a bid, or just bounce short term on rumours of a bid or that someone like Apollo is looking to bid.
Share price is well down today as sensible investors see through the latest flannel. I can’t recall when last holding a share that went bust as it’s SO long ago. Hope THG (LON:THG) doesn’t spoil that record!
I’ve done similarly with Ocado (LON:OCDO) .Try to buy technical lows and try to sell for 50% + as it’s very volatile too with quick movements in both directions!
hVIVO (LON:HVO) does have a moat in the form if its regulation approvals for clinical trials from the Food and Drug Administration (FDA) in the United States and the Medicines and Healthcare products Regulatory Agency (MHRA) in the UK. I doubt these are easy to come by and are likely one of the key reasons why Cathal Friel bought Retroscreen Virology Group plc
Hi Paul - Moat comes from a few areas
1) Regulatory and safety record
2) Database of volunteers - this is very expensive to replicate and build a database. Most trials run into problems because of a lack of suitable patient volunteers (only around 1% of those signing up are suitable)
3) credibility - doing this well over a long period of time. Pharma cannot afford mistakes so being the global leader why would you go to a smaller competitor with little track record. Mistakes can be hugely expensive for the trials. So the only reason you might go for someone else is hVIVO (LON:HVO) having insufficient capacity or location specificity.
4) End to end model : create challenge agent, characterisation study and trial. This is hard to replicate and as hVIVO (LON:HVO) build a library of challenge agents there is a time saving for end client
In essence if you are a pharma why would you go anywhere else. That makes it hard to break into and expensive for someone to replicate - you’d have to invest tens of millions to break into a niche are of the market and even then you would be unlikely to win business. Much easier areas to go after imo with a better ROI and certainty of result for a potential competitor.
davidjhill and Paul - a further moat is their claim of a high barrier to entry on the basis of the number and diversity of trials that they have done, and extensive data that they have now collected.
re the Moat: among the slides attached to their IMC presentation last night was a graph of cash received and work done/revenue recognised; I need to review the dynamics to be sure, but I understood that, with a large pool of volunteers already on their books, the deposits, which seem to be justified on the basis of having to recruit volunteers, don't require a great deal of effort/cost
apologies, not the Moat, I meant re " getting paid up-front, which means a lot of the costs of providing the service have not yet been incurred".....
hVIVO (LON:HVO) Having reviewed it, it's much easier to look at slide 10 [it's on their website as slide 9] of the presentation, but Paul is right that in HVO's case study the first 13 months are paid substantially in advance (about 75% of the contract value), and only then does the effort match the payments, and then in the last 8 months payments lag the work done. In their 2023 accounts cash etc of £37m is somewhat balanced by trade payables etc of £34m. Going by their published 2022 Report, a lot of 2023's payables [£23m?] may be the net amount of advance payments ahead of revenue recognition.
Any thoughts on the Ramsdens Holdings (LON:RFX) sp increase today? Cant see any news
Ever increasing gold price? Gold miners have all been rising, so hopefully it's Ramsdens Holdings (LON:RFX) turn..
Would you happen to know what percentage of their revenues are generated from gold?
000's
FY23
FY22
Revenue
£23,522
£15,847
Gross Profit
£9,161
£6,626
Percentage of Group gross profit
20%
17%
hi smatthews1
Ramsdens Holdings (LON:RFX)
Precious metals segment represented 27% of total revenue and 20% of gross profits for FY'23 ended 30/9/23.
Snazzy
Ramsdens Holdings is our top holding by value right now stay humble so I'm biased and think it's cheap anyway, it's well off it's top, still growing and paying a decent dividend. Look up Paul's and Graham's discussions for their much better opinions.
I don't own Ramsdens now but have just been listening to someone telling me on Youtube that consistent high return on capital tends to produce good l-t performance. This is, crudely, a big part of the credo espoused by Charlie Munger (Berkshire Hathaway) and Terry Smith (Smithson IT) amongst others. If you look at the Stockopedia T Rowe Price screen - predominantly a GARP screen - Ramsdens is one of the select few. If you look at the WD Wombat Value Mid to Large screen - which has pretty tough RoCE criteria and includes growth in book value and decent dividends - you only get 2 stocks - Severfield and Ramsdens. That covid-induced hiccup really was a one-off.
It seems to me Ramsdens is really investing well in its business and is jolly cheap after a pretty bad 12 month share performance. Last year's figures were very good and the trading update was cautious but OK. I sold the stock at 78p in March 2020 after it had halved in 18 months - a great example of horrendous timing. I panicked at a trading update that month which highlit the impact of covid on travel.
Specifically on today's move there is no volume so no stock for sale at these levels. That must be a good sign? It isn't really liquid enough for most big funds. But I think it looks really good here, not without risk but in highly competent hands.
That screen has performed quite poorly. Rightmove (LON:RMV) used to have the highest ROCE by far but it has only just doubled in the last 10 years. Not saying it is a bad feature but I think some put too much emphasis on it. Maybe it is different in the US
I think ROCE suits some businesses more than others. Online will favour high ROCE, no surprise that Rightmove (LON:RMV) and Auto Trader (LON:AUTO) score highly.
I hold Ramsdens Holdings (LON:RFX) I don't know why it has fallen so much recently, looks overdone to me, considering the price of gold, people still take out loans or pawning and people are travelling again. I think there is some risk as they expand into the south.
I've updated our Week Ahead article from Monday (https://www.stockopedia.com/co...) with an analysis of Tesco's results this morning. Things are still looking pretty encouraging.
The E-Therapeutics (LON:ETX) delisting announced today has a couple of interesting points.
Firstly, it councides with a £28.9m fundraise from the the two largest shareholders (M&G and Richard Griffiths) at well above the pre- delisting valuation. Secondly, the company says it will explore relisting on Nasdaq after the delisting. Thirdly, it follows right on the heals of some other AIM biotech companies eg C4X Discovery Holdings (LON:C4XD) and Redx Pharma (LON:REDX) . Richard Griffiths is also a major shareholder in C4XD. I wonder if others know more than me about Richard Griffiths’ strategy? I would definitely pay attention if I were a shareholder in an AIM listed company, where he was a large shareholder.
The RNS today by E-Therapeutics (LON:ETX) is quite hard hitting. A cynic might say well that would say that but still I think it is worth reading. The following is a flavour:
“For over a year, the Board has been contemplating delisting from the AIM market. However, given the dramatic rise in the US biotech indices in Q3 2023 which has seen record amounts of capital being raised, we decided to remain on the AIM market and embarked on a capital raise roadshow in February-March 2024. Despite the firm commitments given by our two largest shareholders, the Board was extremely disappointed by the lack of institutional UK interest in our innovative, technology-driven value propositions. Importantly, ETX struggled to get sufficient engagement from the vast majority of the institutions who were approached, reflecting the risk appetite of the UK markets. “
I have bought a few ETX today (a punt) on the basis that I am buying cheaper than the two largest shareholders. An exit depends largely on the company succeeding on a potential future Nasdaq listing. Be aware delisted shares cannot be held in an ISA and can cause a problem in a SIPP - hence some of the forced selling on a delisting announcement.
Will look forward to the Ultimate Products (LON:ULTP) report. Have held on and off for a few years for a small profit. Cannot work out if the promised land is about to arrive, or it's run for the benefit of staff. The graph looks like a mountain range but never stays on the summit for long.
A Super Stock with a stockrank of 98 keeps me chained in, but seems to be going nowhere, do I deploy the resources elsewhere?
Ultimate Products (LON:ULTP)
Patience required I think, always difficult. A very good management team, capex light, excellent investment metrics and founder led with the main players holding a shed load of shares plus a handsome dividend. It fits my investment approach.
I hold and will wait to see how the year unfolds.
All the best
I have held Ultimate Products (LON:ULTP) on and off since 2017. It has been a frustrating hold, I should have sold early last year, when it was around 170p. People say giod things about the management but look at the charts, this has not really gone anywhere, in fact it well down on it's peak.
I do not hold Ultimate Products (LON:ULTP) but you raise an interesting point. I too have a number of stocks that I am “holding”, I am exercising “patience”, “expecting good news” and other worthy feelings that as a “long term holder” I am being a responsible supporter of the companies aims etc, etc, blah, blah. I have taken some time to realise that this is absolute horsefeathers for a tiny holder.
A decision to hold should be a proactive one quite as much as a buy or a sell. While I have been holding there are other companies that are sprinting away and always looked like they would. For most of my patient holds there may be a moment when my original thesis comes good, but on most of these there will be time to buy the turnaround. There will be occasions when you miss an explosive move, (mostly takeover bids) but not very often. If your thesis is to spot takeovers fine and good luck. But for me I believe I have to be much more critical of my “holds”, particularly those that are difficult to analyse - where I am resolving to pick some easier ones!
Ultimate Products (LON:ULTP)
HODL
Its obvious
(And clearly run for shareholder benefit)
Really good announcement from 4Basebio (LON:4BB) this morning in my view. The fact that their synthetic dna appears to be sufficiently well validated to now be included in a Tier 1 pharma drug program and that commercial traction in accelerating client acquisition and revenues is occurring gives me a lot of confidence going forward.
Horribly illiquid and really behaves more like a private asset though - very tricky to value too. Clearly the synthetic dna market is taking off given the benefits and as one of the only players 4Basebio (LON:4BB) clearly has a lot of very valuable IPR value. Certainly private valuations suggest that.
Anyway possibly not one for here - too illiquid and very specialist niche. I’ve owned since before it was spun out and bought more on the day it listed so fingers crossed for me :D
Does anyone else follow?
I follow 4Basebio (LON:4BB) but do not hold. It is clearly in the jam tomorrow category and although I think there could be a lot of jam, tomorrow could be a long (expensive) way off. I am also not happy that two Directors have sold recently along with an overhang of a large selling institutional holder. It floated too early in my view, and is going to be a cash consuming company for a while in an AIM environment which regrettably does not appear to have the liquidity (or cohones) to willingly support. It seems more like a mid-stage venture capital investment .
Not sure what you mean Aislabie
Re 4Basebio (LON:4BB) No director sales : they had some options that were exercised and some were sold to pay the exercise price and tax. Other than that they have held and increased.
Major shareholder is not a seller either - there is no overhang. He was increasing overall. The reduction was because of issued options.
It is funded but AIM is not really doing its job either from a liquidity perspective so agree it is more like a mid stage VC. Would probably be better in US tbf.
This business will be sold imo. The founders have a track record of that. They won’t do it early as the IPR has a lot of value.
My apologies, I misread the share sales on 4Basebio, you are quite correct.
Re 4Basebio (LON:4BB) today's news is rather meh in its near to mid term significance...a gnat on its bloated £110m market cap...
Why bloated?...there's a plethora of UK listed biotechs with similar claims to interesting...most of them you'll get for less than a 1/5 of the price of 4Basebio...and all have the same low odd high payoff. So probabilistically punters would be better off with other things...maybe a basket?
All biotechs sound good if you go down the rabbit hole...FYI I do take risk here...but fully aware its high risk and I have limitations
no one said 4Basebio (LON:4BB) wasn't high risk..... but it is neither "meh" nor bloated........ Mojo - you are better than this - go away and do some research not drive by banalysis
tho I do agree with the "basket" approach from a probabilistic perspective
M&C Saatchi (LON:SAA)
I hold.
The prelims are encouraging with a confident outlook statement, despite the challenging economic backdrop. Significant increase in operating margins in H2 with the divestment of loss making businesses and continuing simplification of the corporate structure.
"We delivered a materially better financial performance in the second half of the year, following the more challenging start to the year. This was partly led by impressive contributions from Issues and Passions. The biggest drivers of improvement were our own proactive actions on costs, accelerating our structural transformation, and closing or divesting a number of loss-making businesses which drove operating margin up from 8.3% in the first half to 16.9% in the second half."
Confident in meeting FY24 expectations with future margin expansion anticipated.
"Current trading and outlook
· Our confidence in meeting FY24 expectations is underpinned by encouraging Q1 momentum, despite continuing macroeconomic uncertainty
· Improved free cash generation in 2024 with the expected settlement of the majority of the remaining put option liabilities
· We are confident that the structural changes we are making to our cost base alongside our new operating model are increasing our operational leverage potential which will help support future margin expansion."
Together with Galliford Try Holdings (LON:GFRD) , which I also hold, M&C Saatchi (LON:SAA) appears to be one of Richard Staveley's more successful turnaround investments. at present. M&C Saatchi (LON:SAA) was subject to two opportunistic bids both rejected, one from Vin Murria at around £2 and Next 15 (LON:NFG) at 247p or thereabouts. The latter comprised cash and shares. Rockwood Strategic (LON:RKW) think the company is worth around £3/share. We shall see.
Worth a look at Vin Murria's new software solutions roll up AdvancedAdvT (LON:ADVT) [I hold] which holds around £19M in M&C Saatchi (LON:SAA) stock which is a bit of an outlier to the rest of the business where I think the true value lies given her track record.
Speedy Hire (LON:SDY) - big downgrade to EPS from broker yet small downgrade for the SP suggests to me the market feels it’s near or at the bottom. Whatever its operational dead-ends, this company is still profitable and very cheap.
Treatt (LON:TET) I thought this trading statement was quite good, a few green shoots emerging ahead of the new CEO taking over in the summer. Margins still on the low side for such a 'quality' business so room for self help, but looks like their major capex is all complete now. I increasingly like it and am trying to buy today. I welcome Paul's thoughts on this as I know he likes Treatt too.
Treatt (LON:TET) I thought this trading statement was quite good
The second good update in a row. Shares are expensive for SCVR but cheap for global competitors to swoop. Look at Symrise or Givaudan on double the multiple for lower growth. I’m happy with progress and prospects.
Been a shareholder for some 20 years and have attended some AGMs,including tour of new facility in January. There is an energy and enthusiasm about the people there which I really like - and many staff are shareholders who have suffered the pain of the last couple of years. FD and Interim CEO Ryan Govender has done a great job in my opinion on improving efficiency post the move to state of the art production facility at SkylinerWay and should make a strong team with incoming CEO in June. Record month for revenues in March and encouraging comments about order book leave me feeling very comfortable with it, but always dyor
It's the monthly US CPI update today.... A summary of all the banks expectations has a medium of 0.29% which is a little high...and a top of 0.38% from Citi. As usual, the talented highly paid forecasters expect broadly the same outcome... which is a little weaker than Jan Feb but a little strong to be consistent with a rate cut thesis. Who am I to disagree.... I doubt much changes today and the market willingness to believe cuts are coming, and the economy is ok will most likely continue. Watch the 30 year bond yield for signs things are changing.
There are two classes of talented highly paid forecasters: those who don’t know and those who don’t know they don’t know.
Sounds a great area to work in paid loads and just hug the herd to avoid getting the boot.
...as J.K.Galbraith might have said.
Good to see your still about RD I always look out for your macro posts, hopefully Wolf is still about somewhere seems a few of the top table posters have gone quite (ish) recently hopefully they haven't jumped ship to Sharepad.
Still here, in a bit of a waiting game portfolio wise ( a sluggish start) and not doing much....but it feels like it might get a bit more interesting. I have paid for another year of stock charts which I use in combination with stockopedia. I wonder whether this is the right combo esp when stockcharts lost my list on renewal ... 500 fresh charts to rebuild didn't please me.
TradingView an option. Has all the styles for a lifetime of play. I like ichimoku at the moment with MACD but fairly safe indicator so miss the big rises.
US news and can link to a platform to trade off the chart.
Wolf already was using Sharepad. He may be lurking in his lair, equally he may have left after his comment, and mine, and many others were 'moderated' some while ago.
Thanks Rogerh hopefully he's just hibenating , Timarr seems to have left also and he was a superb poster on macro stuff.
Thanks Rogerh hopefully he's just hibenating , Timarr seems to have left also and he was a superb poster on macro stuff.
Too kind. Reports of my demise are greatly exaggerated ... but very busy with more important life related stuff.
Although a lack of attention seems to have worked wonders for my portfolio :-/
timarr
Great to see your still about, I remember when Truss blew up the bond market you were the first person I followed (ahead of all the press) who highlighted she had nearly brought down the final salary pension industry.
As an aside I met a top Legal & General (LON:LGEN) strategic bond fund manager in 2023 and he pretty much admitted he had missed ldi as an issue and highlighted how his own company had been badly hit by it .
So it just shows how some of these left field curve balls are so hard to spot even by those who should be at the front line of the watch tower.
My morning smallcap tweet: Don't go loco with FOMO
Iqe (LON:IQE) E-Therapeutics (LON:ETX) Team Internet (LON:TIG) Speedy Hire (LON:SDY) Chamberlin (LON:CMH) Enteq Technologies (LON:NTQ) Mercia Asset Management (LON:MERC), Treatt (LON:TET), XP Power (LON:XPP), Churchill China (LON:CHH), M&C Saatchi (LON:SAA)
◄IQE (IQE)► to supply its customer AWSC with wafers for the manufacture of smartphone power amplifier devices to be supplied to its key customer Lansus, the Chinese RF technology supplier. [SP=19.75 Cap=190m]
◄e-Therapeutics (ETX)► proposed subscription of £28.9m at 15p, a 30% premium, for R&D. Intends to delist from AIM then list on NASDAQ. [SP=12.5 Cap=73m]
◄Team Internet (TIG)► has begun trading on the US OTCQX Best Market. [SP=140.8 Cap=363m]
◄Speedy Hire (SDY)► weedy but not dire - guides FY-Mar towards the lower end of mgmt expectations with rev down 5%. Outlook - "encouraged by the commercial progress in the business and the outlook for FY2025 given the recent contract wins". [SP=25.35 Cap=117m]
◄Chamberlin (CMH)► warns Q3 weak with underlying demand lower than previously forecast by customers and impacted by delays with the startup of certain new programs. Q4 looking better. Cost cutting. [SP=1.6 Cap=3m]
◄Enteq Technologies (NTQ)► guides FY-Mar rev c. $0.9m representing the final revenue following the sale of the XXT business. Adj EBITDA loss c. $2.9m. [SP=9.24 Cap=6m]
◄Mercia Asset Management (MERC)► guides FY-Mar organic fund inflows over $500m and no redemptions. Net cash c.£47m. [SP=34.17 Cap=149m]
In line: TET, XPP, CHH, SAA
Speedy Hire (HSS)
Predictably rubbish results but they’ve FCF of 20 million reducing debt plus 40m of long term contracts .
Results are backward looking and so nothing unexpected .
Lots of flowery management tech and some pre warnings of ongoing costs . Strikes me management at Speedy is being led by trying to please as opposed to running the business like a true owner would .
Lots of initiatives and actions plans and a big investment into electric hire has cost a lot. These burn cash and don’t sort the issue of debt .
Much prefer HSS who are taking a much more northern pig farmer approach to reducing debt by selling assets .
I’m honestly sometimes staggered but apply the northern pig farmer management technique to any business with too high debt but trading below NAV you have to simply
- sell some assets for NAV or above
- reduce the debt or even eliminate it
- and by definition you suddenly have a profitable business making an EPS that you then have a quantifiable decision to make
- pay a dividend
- build up the cash balance
Talk is cheap
Cash buys houses
So said Bill Smith .
Nice summary on Speedy Hire (LON:SDY) Planetx. The tie up with AFC Energy (LON:AFC) seems to fit the profile too, great idea, looks great on paper but they are just so expensive. AFC has been a money pit for years and still hasn't produced anything commercially viable.
Maybe the Hydrogen generator will be the turning point and finally we will finally see a commercially viable product. Kind of doubt it though.
NI1972
The speedy / AFC deal is a classic example where speedy has cocked up and shows a CEO led by fashion and woke ESG .
You can understand the wish to be “first mover” into being able to supply hydrogen hide equipment as seemingly it is going to become a regulatory requirement (I’m sure it will Simply get delayed if no one has generators ready ) and makes a great headline .
Back in the day Dave Brailsford who was working for me having just left muddy fox bikes (this is a long time ago). And I always wanted to be creating brand new stuff and all the costs incurred said along the lines
“Dave pull back a bit we don’t want to be Man Utd we want to just below the top 5 , let the big players blow their brains on risk and development we simply need to let them make all the first mover mistakes and then come in first wave after at half the price with no flaws and these 2nd wave companies are the ways we find our niche “
Not sure if that makes sense , but anyone at the cutting edge is going to taking the development costs and big risks and those that follow can learn from their mistakes .
Anyway quite funny as he’s ended up with Man Utd and they’re definitely not a cutting edge outfit .
AFC Energy (LON:AFC) are dire do not touch. Decades of failing to create a viable product.
Any business that talks up hydrogen should have a match applied to the emitting orifice and the output flared
Brilliant.
https://www.voxmarkets.co.uk/r...
Any Team Internet (LON:TIG) holders would be interested in this news. Will it have an effect on the sp?
Team Internet (LON:TIG) to summarise rather than link ..
Domain name business. Now trading on US OTC market. Should provide significant liquidity.
On line domains generated $179m while on line marketing generated $657m so it is slightly more than just a domain name business!
Team Internet (LON:TIG) As now also trading on a US Exchange I think it disqualifies it as a IHT exempt AIM share?? I would be grateful if anyone could confirm.
KBR.
KBR,
I am fairly sure I am correct in saying that the reason some/most AIM listed shares are exempt from IHT after a 2 year holding is that HMRC treat them as unlisted, so if they then list on a recognised foreign exchange this would then invalidate their exemption. So if the US OTC exchange is recognised then yes it would.
But OTC Markets is not on the HMRC list of recognised Stock Exchanges. OTCBB (which has closed) is specifically not recognised as a stock exchange, so I would expect the same to apply to OTC Markets.
HMRC Recognised exchanges by country
Edited to add that the HMRC list is incomplete but the SEC has a list of recognised exchanges Here which does not include OTC Markets. On that basis I would expect Team Internet (LON:TIG) shares to remain IHT exempt.
Team Internet (LON:TIG) . Hello Helvellyn and DWit199. Thankyou for your responses to my query. Confirms TIG is exempt for IHT purposes. Thanks again.
PS.Last up Hellvellyn 3 years ago!!Trouble was it seemed to have 'grown'from the time before!!
Team Internet (LON:TIG) . Confirmation (I hold)