Small Cap Value Report (Weds 10 Aug 2022) - FOUR, SUS, HSW, DBOX, CML

Good morning, Paul & Graham here today. Today's report is now finished.
Agenda -
Paul’s Section:
4imprint (LON:FOUR) (£941m @ 3350p) (no section below) - FOUR sells promotional goods to companies, for marketing purposes. Its operations are almost all in USA. It briefly popped into our universe in June, but has since risen c.50%, pity as I had it on my agenda to take a look just before the shares soared. Interim results today look very strong, with a major bounce back in profits post pandemic. 118.9c EPS in H1 looks like it’s heading to smash full year forecast of 179c, because I checked back and pre-pandemic it had a seasonal weighting to H2. Hence if that pattern plays out again, we could be looking at 250c+ for FY 12/2022. Liberum has just raised to 216c forecast for FY 12/2022, expect that to be beaten I think. Outlook comments are vague, but positive. Balance sheet looks fine to me. Well-covered divis, scope to increase. Smashing company, performing really well, but there is US recession risk of course. What a pity I missed the irrational sell-off earlier this year, would have been a lovely buy in that panic sell-off.
Hostelworld (LON:HSW) - interim results are poor, due to only a partial recovery in travel, but heavily increased marketing spending. The cash pile is more than offset by high cost debt from a US investment firm, and large payroll tax arrears owed to the Irish Govt. HSW was declining before the pandemic, and I cannot see the point in its business model of chasing low value customers, with heavy marketing spend, against major global competitors. I wouldn't go near this share, and the >£100m market cap looks irrationally high to me. Terrible risk:reward in my view. There must be much better opportunities elsewhere in the bombed out travel sector.
CML Microsystems (LON:CML) a positive, if somewhat vague in places, trading update at its AGM. I have a rummage to see if I can put a value on the surplus property. Also there's a very large cash pile, even after the 50p special divi paid last autumn. This is a hybrid investment - being about half backed by surplus cash/property, and the rest being the business itself. So copper-bottomed for assets, but that also dilutes the upside if the business out-performs, since the business is only about half the valuation.
Graham's Section:
S&U (LON:SUS) (£273m) - an ahead of expectations update from this motor and property lender. S&U is a family enterprise owned and managed by the Coombs family, and the current business combines both a long-standing business (founded 1999) and a newer venture (founded 2017). Both are performing extremely well and this is a stock that I would back to survive a recession, based partly on my understanding of the company’s financials but also to a large degree on the character of the Chairman and the culture of the business. After rising today, the stock now trades at a more meaningful premium to book value (around 32%), which I consider to be easily justified by the attractiveness of the stock.
Digitalbox (LON:DBOX) (£13m) - This trading update has been interpreted as a profit warning, even though the directors are confident that market expectations for the year will be met. The problem is that H1 is very strong, while H2 requires caution. Digitalbox owns three entertainment websites, and is soon to complete the purchase of tvguide.co.uk. It has over £2m in the bank and has earned nearly £2m in revenues over the past six months. The websites have impressive numbers on Facebook although we can’t value them purely based on that success. Corporate advertising budgets are likely to pose a headwind in the short-term but I’m open to the possibility that this company could turn into a success story for shareholders.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Hostelworld (LON:HSW)
91.5p (down 4% at 08:51)
Market cap £107m
Hostelworld, a leading global Online Travel Agent (OTA) focused on the hostel market, is pleased to announce its interim results for the six-month period ended 30 June 2022
The H1 numbers reflect partial resumption of travel.
HSW reports in Euros, and is based in Dublin.
H1 revenues E28.0m (almost 10-fold increase on H1 LY, which was hit by lockdowns)
Steadily improving revenues trend, but still well below 2019 pre-pandemic comparatives.
Heavily loss-making in H1, with the best view (adj EBITDA) of E(5.2)m loss, and the worst view being E(14.7)m PBT unadjusted loss.
Note 4 shows the culprit is a large increase in marketing spend, at E20.1m in H1. I understand that they’re effectively re-starting a travel business, but heavy marketing spend seems to be the achilles heel of many eCommerce businesses at the moment. Online marketing costs having risen so much, I wonder if they are viable, having to spend big now, to generate new business, or even stand still? The winners are likely to be the companies which can drive the best results from their marketing budgets, and not run out of cash, as competitors fall by the wayside. Maybe marketing rates could drop again, if things continue to be this tough?
Average booking value is strikingly small, at just E15.82, is it worth chasing this business? Especially when marketing spend per booking was E9.46.
Balance sheet - looks very weak to me. If we write off E76.4m intangible assets, then NAV of E54.0m positive, turns into NTAV of negative E(22.4)m.
The depleting cash pile is E22.6m, but that’s more than offset by borrowings of E29.8m - note 9 gives the detail, it’s provided by HPS Investment Partners LLC, and is expensive at 9.0% p.a + EURIBOR. It looks like some interest cost is being rolled up, thus increasing the debt.
The lender, HPS, is a very substantial US-based investment firm, seeking high returns from “creative capital solutions”. There’s a clear risk here that, if terms of the borrowings are breached in some way (e.g. covenants), then it could hand control of the business to this lender. Or they could force HSW into heavy dilution, to raise fresh equity. I don’t like this arrangement one bit. It looks desperate, so I would want HSW to refinance in some way to eliminate this debt at some stage before I’d want to invest.
Payroll tax arrears - the Irish Govt has been very helpful, in allowing E9.4m in payroll taxes to be deferred - see note 12. This is in non-current creditors, as the company says it doesn’t have to be repaid in the next 12 months. But it will have to then be repaid, which would bring the cash pile down from E22.6m to E13.2m. That’s before we take into account further trading losses too. Hence I reckon the cash pile is probably spoken for, and HSW then has to worry about how it’s going to repay the expensive HPS debt.
Outlook - the way I read this, as long as nothing bad happens, we might scrape into breakeven in H2 (before interest costs) -
The Board remains confident in the long-term resilience of our business model and the potential of our differentiated growth strategy. The trends in H1 2022 are encouraging and indicate that where markets open up for travel, demand will recover to 2019 levels and that we can gain our share of that growth. In the absence of any further deterioration in the macro-economic climate, disruption to airline schedules, or escalation of the conflict in the Ukraine, we expect to be EBITDA positive in H2 2022."
My opinion - as you’ve probably gathered, I’m not at all keen on this share. The market cap of £107m looks over-valued to me, because it’s blowing the cash pile on marketing spend, to chase after an unattractive, low spending niche in travel. Against major global competition.
Remember that HSW was declining before the pandemic hit too. Since then, marketing spending has become a lot more expensive, and travel generally is taking longer than I expected to recover, due to lingering impact of the pandemic on infrastructure like airports. Plus it looks as if we might be going into a recession, although that's not necessarily certain.
Then there’s the high interest debt, and the tax arrears to repay.
So for me, the bear case is overwhelming here, and I’d say the equity could end up being worth little to nothing. It would need a stellar improvement in performance to justify anywhere near the current share price - it could happen, but why take the risk of betting on a low probability outcome? And over-paying at the starting point for an unlikely outcome. Thumbs down from me, I’m afraid.
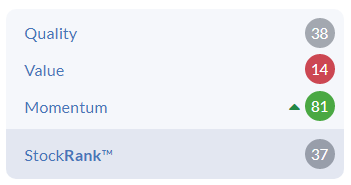
Stockopedia isn't keen either, with a lowish StockRank, propped up by a high momentum score that could easily wither away -
.
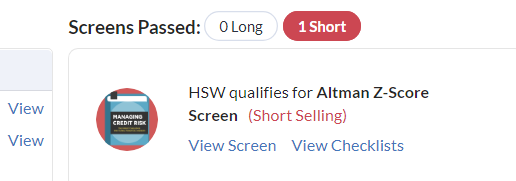
The only screen passed is for a short -
.
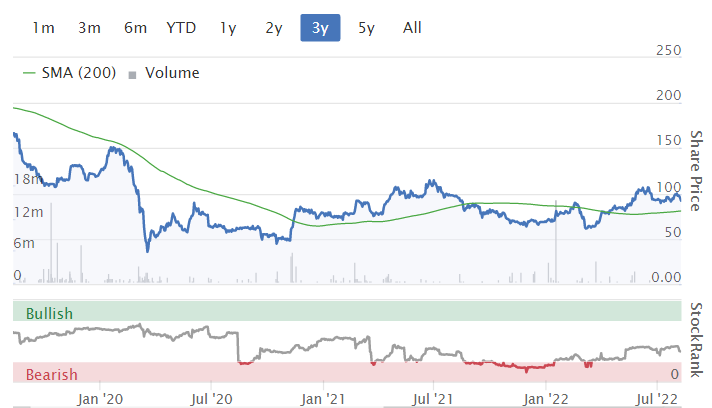
The only uncertainty here is why the share price has held up so well? There must be buyers, otherwise it would have tanked along with the rest of the travel sector, so maybe I've got something wrong?
.
CML Microsystems (LON:CML)
421p (up 5% at 10:27)
Market cap £67m
AGM Statement (trading update)
CML Microsystems Plc, which develops mixed-signal, RF and microwave semiconductors for global communications markets…
The current year is FY 3/2023.
Trading is up on last year, but it doesn’t say anything about market expectations, which is the more usual (and useful) reference point that we need, to judge for ourselves how it’s performing -
We entered the new financial year with a healthy order book and a strong pipeline of future opportunities. We have made good progress so far, with trading for the opening four months comfortably ahead of the prior year comparable period.
This bit below is also a bit too vague for me - “firm improvement” against what? Last year, or market expectations? It should be more precise -
After experiencing an encouraging start, the Board remains of the view that full year trading to 31 March 2023 will show a firm improvement, both operationally and financially.
Strategy -
Our enhanced strategy to widen the addressable market is gathering pace and activities to capture share of new market application areas remains a priority focus. In support of this, several new product releases are scheduled across the coming months that are projected to start contributing to revenues during the following year.
Property - we already knew about surplus property. It would be useful if the company could give an indication of the likely size of this windfall. Again, “significant cash inflow” is far too vague. There should be specific numbers, even if it’s a range of possible outcomes -
As expected, planning applications have now been submitted for the commercial development of excess land at the Group's 28-acre Essex headquarters site and, if successful, this could generate a significant cash inflow for the Group.
With things like this, scrutinising broker notes can often provide more detail. There are 2 out today, from Shore, and Progressive. They don’t say anything on property, other than there could be material upside.
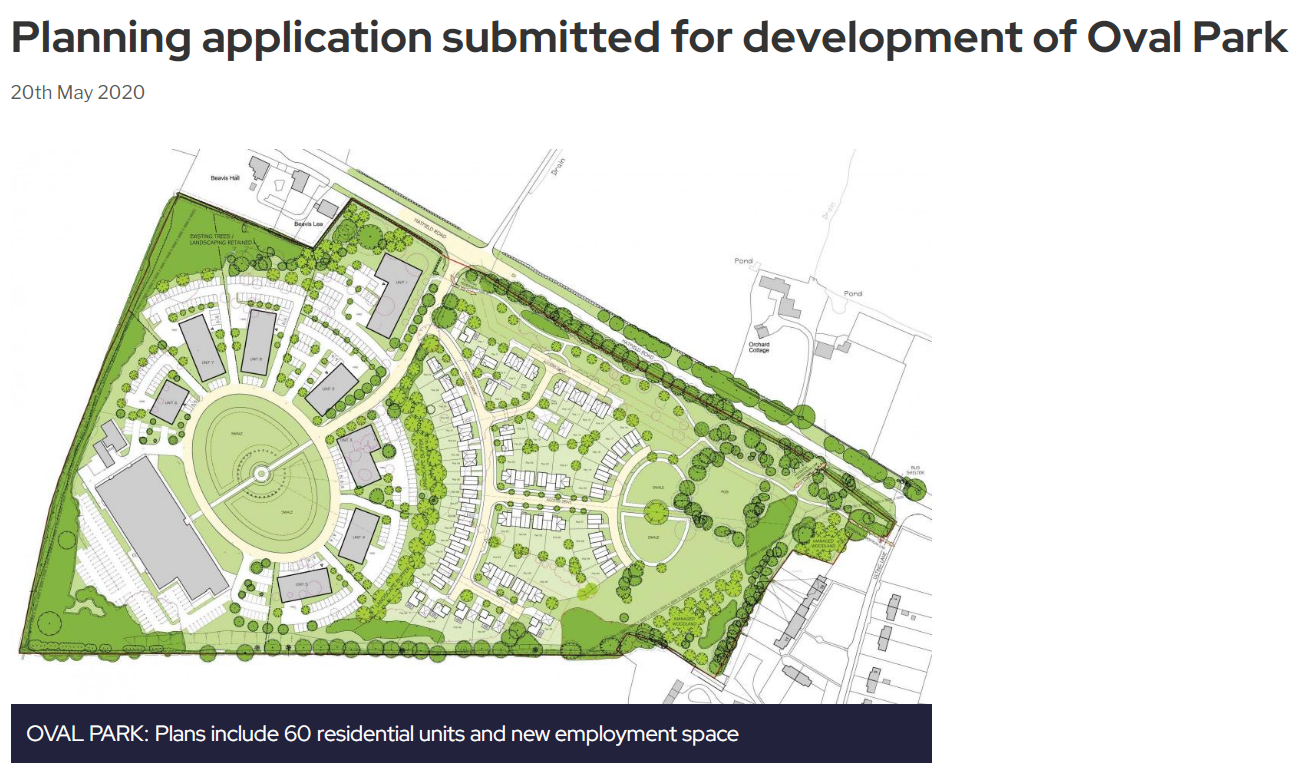
I’ve done some googling, and this seems to be CML’s existing site below, called Oval Park, looks very nice (from google maps), and mostly surrounded by countryside, with a small village nearby. It’s about 5-10 miles from Chelmsford, Essex -
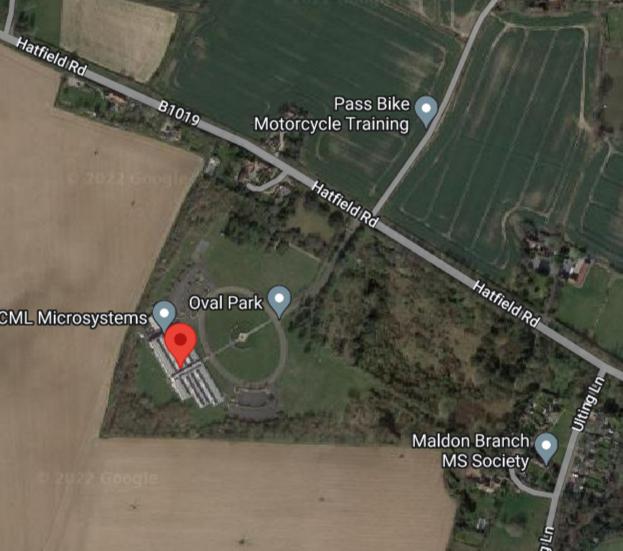
Next, I stumbled across a relevant article in the famous Maldon & Burnham Standard, which refers to a planning application for Oval Park, to create 60 new homes, and new “employment space”, which looks like 6 new offices/units, in a ring around the existing oval shaped road. This is said to be 7,100 sq.m, so fairly smallish units, not big warehouses. It’s definitely the same site, due to the name, and the recognisable shape -
.
Further googling provides other articles, saying that CML has been trying to get planning permission on this site for many years (e.g. planning application in 2012 was rejected, and an appeal in 2014 also rejected).
Given that we know the planning system is slow, then it’s probably best to see upside from the property as a long-term benefit to shareholders. Problems with infrastructure are also mentioned in another article.
How much profit could CML make on this? No idea, but if it’s say £100-200k overall profit on each of the 60 houses, then that would be £6-12m. Plus whatever the profit would be on the industrial/office units. This would be split somehow, as it’s being done in conjunction with a local developer called Aquila.
All quite interesting, and it’s reasonable to add a bit on to CML’s valuation to account for this property upside potential.
Broker forecasts - Progressive leaves forecasts unchanged, but reckons that the next move could be upwards - a key thing we need to see right now, to avoid profit warnings.
Balance sheet & divis - CML has a lovely habit of accumulating cash! It paid out a 50p special divi in Aug 2021 (£9m cost) but still ended FY 3/2022 with £25.1m in net cash, which is way too much. Although perhaps management might be retaining this big cash pile to help fund the property development work?
Overall, the balance sheet looks remarkable, e.g. current assets £31.9m (incl. Cash & deposits of £25.1m), whilst current liabilities are just £3.1m!
There is a £2.4m accounting pension deficit, but the last results show that the actuarial valuation was better, in a small surplus. So aside from admin costs, it sounds as if the pension scheme shouldn’t need much funding from the company.
My opinion - what an interesting little company, I’ve enjoyed digging into this, it’s like doing a puzzle!
The logical way to value a share with material surplus capital, is to adjust the market cap down, to take into account a big pile of surplus cash (at least £20m is surplus I think), and surplus property - no idea how to value that, maybe £5-10m, we’d need more detail, and would need to discount it to reflect that this could take years to turn into cash, given the history of rejected planning applications.
Even so, the cash and surplus property are probably adding up to around half the market cap. Therefore the apparently high PER (Stockopedia is showing 27.1 times, blended between this year & next year). Progressive is showing a PER of 33.3x this year, and 27.0x next year, but also saying there’s potential upside on its current year forecast.
I would halve those PERs, to take into account the cash & property, taking us down into the mid-teens for the PER - which looks reasonable value to me.
The challenge will be to grow revenues and hence profits - which are currently still a long way below 2016-18, when the business made c.£4m p.a. profits.
The next step for people to research would I think be looking into its products, including the pipeline, with the big question being are there any potential blockbusters in there? That’s beyond my pay grade, I just look at the numbers, which overall I think look good.
I quite like these hybrid shares, where you have a good business, plus a great pile of surplus assets. It’s nice to get the assets in for free though, which is not the case here.
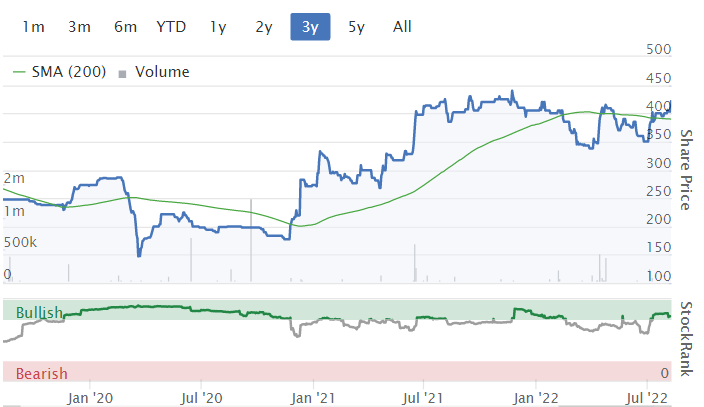
CML has been remarkably resilient in the recent small caps bear market. Nice high StockRank too -
Graham’s Section:
S&U (LON:SUS)
- Share price: £22.46 (+8%)
- Market cap: £273m
This is a family business with a history stretching back to 1938. Its activities have changed over the years, but the family remains very proud of their traditions. In addition to being heavily represented on the Board, they have meaningful stakes in the business.
In 1999, S&U launched Advantage Finance, a non-prime car lender. In 2017, it launched Aspen Bridging, a specialist property lender. S&U borrows at 4%, and lends at 25% (see the 2021 Annual Report, footnote 21!).
I’ve interviewed Chairman Anthony Coombs in the past, and this cemented my view of the company as having a strong culture of stewardship. That’s always highly reassuring from an investor point of view - and particularly in this case. We are talking about a subprime/non-prime lender, after all.
Some great news in this update:
Although it is only just over two months since our last trading update, S&U is pleased to report that both its motor and property bridging divisions continue to outperform its expectations, both in transactions growth, and in the quality of its book and the new business it is writing
Growth is being achieved without any signs of excessive risk-taking by S&U: “debt quality is reflected in strong collection rates and supported by low levels of default” at both subsidiaries.
Anthony Coombs is an excellent writer (I’d guess that he wrote this update with little PR input) and offers some remarks on the weak economic prospects - including inflation, rising interest rates, low consumer confidence and a technical recession. He says there is now a “manically depressed view of the future, particularly in the UK equity markets”.
The conclusion from Mr. Coombs is that underwriting standards must remain infused with caution; there have been some “adjustments” to take into account the possible pressure on household incomes later this year.
Changes include “a revised scorecard and the introduction of further credit reference information, as well as strengthened buffers on customer affordability”.
In property bridging, which is still a very young business in the context of S&U’s history, net receivables are up by more than 50% compared to last year and now stand at £90m.
The company is building its track record in the market, which bodes well for the future:
Aspen's growing reputation and the introduction of new products mean that it is attracting more experienced and expert borrowers, which have seen average gross loan size increase to around £875,000 so far this year, helping both the receivables and revenue growth.
Gearing and borrowings
A brief look at S&U’s January balance sheet shows the company with £207m of equity supporting total assets of £327m (with no intangible assets).
Putting it differently, S&U’s equity accounts for 63% of its assets. In mortgage terms, the LTV is 37%. The LTV at something like Lloyds Banking (LON:LLOY) is 94%.
So we can understand what Mr. Coombs refers to, when he talks about S&U’s “low level of gearing”.
The large equity cushion provides comfort that S&U would survive a historically unprecedented wave of defaults.
If I had any concern on the balance sheet, it would be a growth-oriented concern: the company has used up most of its medium-term banking facilities. Net borrowings are £154m, while the facilities only stretch to £180m. S&U claims there is still “ample headroom” for growth, but surely it will want to increase the amount it can borrow before too long?
The 2021 Annual Report said that the facilities “may be augmented within the next financial year as further growth occurs, and the macroeconomic landscape becomes clearer” - perhaps the fact that the facility has not increased yet has as much to do with the risk appetite of S&U, as it does with the risk appetite of the bankers.
My view
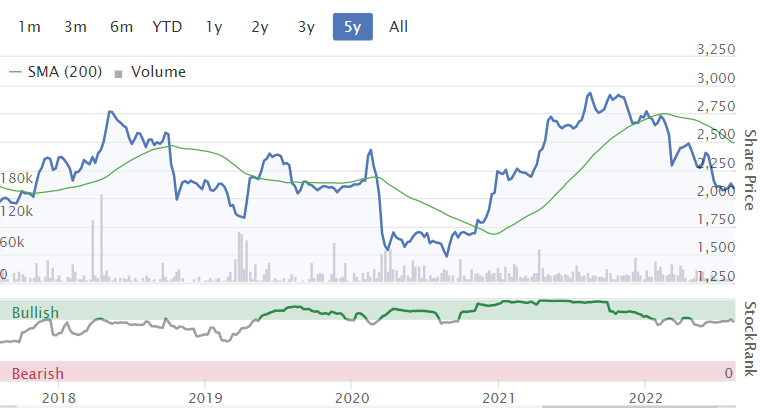
I’m a big fan of this company, and I’m very interested by the fact that the share price has made such little progress in recent years:
This is a company with a terrific track record when it comes to growing book value (and also book value per share, because the share count barely moves):
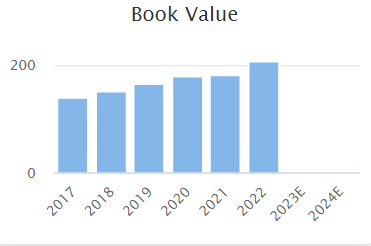
As of the last balance sheet (January 2022), book value per share was £17. At this morning’s share price, the shares are trading on a 32% premium to this amount.
For a company which usually earns double-digit ROCE and double-digit ROE, that still strikes me as potentially offering good value. The S&U Chairman naturally agrees, saying:
S&U's performance and its prudently planned prospects for the future, are inadequately reflected in stock market commentary and valuations dominated by uncertainty and pessimism.
I’m as much of a bear on the economy as anyone else, but I’m still perfectly happy to back good companies to get through what’s coming.
And if S&U’s bank facilities were ever withdrawn, I suspect that there would be more important and urgent things to worry about than share prices!
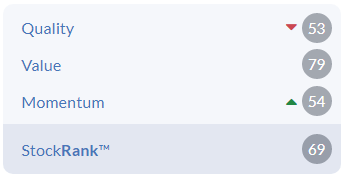
The StockRanks really like this one, too: Edited to correct error, our apologies. The correct StockRank is now below, as you can see it's upper-middle -
Digitalbox (LON:DBOX)
- Share price: 11.4p (-5%)
- Market cap: £13m
This is a collection of consumer websites: Entertainment Daily, The Daily Mash and The Tab.
I’ve occasionally seen The Daily Mash pop up on my Twitter feed. Having a closer look today, it is clearly a British version of The Onion. It has 1 million Facebook followers.
Entertainment Daily offers celebrity and TV news and has 2.4 million Facebook followers.
The Tab is pitched as a student publication and has 300,000 Facebook followers.
So each website has had a lot of success on Facebook, assuming that we can trust the numbers (unfortunately we can’t trust these numbers in every case).
Websites like these depend on the advertising budgets of larger companies, which are of course very sensitive to economic conditions.
For example, the advertisers listed on digitalbox.com include various travel companies, along with the likes of John Lewis, M&S, and Sky:
- P&O Cruises
- Thomas Cook (!)
- Jet2holidays
H1 trading update
Here are the key points from today’s update, which initially reads positively.
- Revenues are up 40% on last year, rising to £1.9m.
- Net cash rises £600k to £2.4m.
Explanation:
The performance is a result of exceptionally strong traffic for Entertainment Daily, and ongoing improvements in the monetisation of The Tab and is significantly ahead of the Company's expectations for the Period.
In H2, the company will complete the purchase of tvguide.co.uk (price: £550k), and more acquisitions are being studied.
Then at the very end of the statement, we get this warning around prospects, which explains why the stock is trading lower today:
The Board anticipates that the challenging macro-economic conditions are likely to adversely impact advertising revenues in the second half of FY 2022, but given the exceptional performance in H1 2022 the Board remains confident of meeting market expectations for the full year FY 2022.
It makes for an unusual profit warning: H1 was better than expected, but H2 will probably be worse. Net it out and the Board thinks that expectations will be met.
Estimates
The market expectations, according to Stocko, are for revenues of £4.1m and net profit of slightly less than £1m:

The estimates have been unchanged for several months, and at no point were they revised lower:

Shareholders must have been hoping that a strong H2 would enable the company to hit these estimates, but they weren’t promised it. Instead, they’ve been given a strong H1, which they are probably less interested in!
However, when the market cap and the free float are this small (the free float is 59%, according to Stocko), it might be best not to read too much into share price movements.
In this sector, everybody knows that advertising budgets suffer in tough economic conditions. For most large corporations, advertising is a type of luxury purchase, and it gets scaled back quickly whenever cash is tight.
So at the end of the day, it is not major news to hear that advertising revenues might be impacted in H2, given the economic backdrop.
My view
Overall, I find this an interesting little company. This is a sector (websites/online media) I feel comfortable analysing, and I’m open-minded as to whether or not these websites could turn out to be worth something substantial.
The purchase of tvguide.co.uk looks like a great deal, at this price. Search “tv guide uk” and see what comes out at #1 on Google.
Whether or not these websites are worth £13m together, I’m unsure: the price to sales multiple (after subtracting the cash balance) is about 2.5x, which is not too high. I’m most comfortable when this multiple is in the range of 1x-2x. There is the possibility that Digitalbox could build synergies and systems to make them worth more than the sum of their parts, but that’s far from certain!
Unfortunately, content creation is expensive and audiences can be fickle. The audience can also simply grow up: if you have a website targeted at students, for example, like Digitalbox does, how many of the readers will still want to read the same student publication in five years? You constantly need to find new eyeballs, and that’s not so easy.
On top of that, you are always vulnerable to the decisions and the policies of Google, Facebook and Twitter (full disclosure: I own shares in Alphabet ($GOOGL)). So there are big investment risks that you don’t suffer if you simply buy one of the tech giants instead.
In conclusion: I’m not certain that these shares are overvalued, but I also wouldn’t be in a rush to buy them here. At a price to sales multiple somewhere below 2x, I’d reconsider it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Hi Paul
One interesting point is that they only acquired The Tab about 16 months ago and achieved 70% pay back in one year
https://pressgazette.co.uk/the...
Also the CFO bought 600k in June so if things then perhaps going fwd now look quieter then that likely only happened in the last 6 weeks. If markets are rallying now perhaps they are being a little too cutious.
The sum of the parts monetising The Tab and acquiring TVGuide plus they have another series of the Mash on Dave says to me they definitely don't look over-valued when you take the cash into account too imo.
I hold so obviously readers need to accept I'm biased
Saga (LON:SAGA) - some large trades today and SP up 5% as I write. This is on a Bonkers Valuation imo. Chart curving up. There must be a huge pent up demand from the over 50s for cruises after such a long lull. Doubt Saga (LON:SAGA) customers are too worried about inflation / energy crisis. Also have a decent insurance business. Sporting a mkt cap of just £230m and a PSR of 0.61! Airlines and Cruise liners are up in the US after the CPI number. Ofcourse I'm biased as topped up recently :-)
Jupiter Fund Management seem to be panic selling every major faller I look at recently. They were suckered into many of the 90%+ IPO club and a quick scan of recent major holding RNS show some of the beauties they bought and now dumping at any price.
£REVB
Works co uk (LON:WRKS)
THG (LON:THG)
CMO (LON:CMO)
Seraphine (LON:BUMP)
De La Rue (LON:DLAR)
Synthomer (LON:SYNT)
S4 Capital (LON:SFOR)
Workspace (LON:WKP)
They must be the worst 'fund' out there. Why lose money yourself when Jupiter can take care of it for you.
At least shareholders have been rewarded in the last 10 years.
Jupiter Fund Management (LON:JUP) are probably seeing huge outflows (quite rightly) and have therfore become forced sellers of these positions. This can sometimes create opportunities to buy at cheap levels, although can't say anything on your list particularly appeals!
Jupiter Fund Management (LON:JUP) are probably seeing huge outflows
Yes, £3.6 billion at the interims. One of the problems with active fund managers is that private investors will tend to sell at the bottom and force them into sales at exactly the wrong time. But they hold stakes in so many listed UK companies it's hard to draw any firm conclusions about what they've sold.
Frankly, it's a terrible company. On the other hand it looks like a sitting duck of a takeover target. It's pretty much in SCVR territory, having fallen about 80% since 2017. Wouldn't be too confident of the dividend being held, mind.
timarr
I think the debacle at Chrysalis Investments (LON:CHRY) has also damaged their reputation. Agree it could be a takeover candidate, but why would anyone want to buy? If a quality outfit like Schroders came in, I'm not quite sure what they would do with them. Integrating fund management businesses can be tricky as you're often dealing with different cultures and big egos (star fund managers). A lot of the funds would also overlap so you could end up with several similar funds.
RE: Jupiter Fund Management (LON:JUP)
Agree it could be a takeover candidate, but why would anyone want to buy?
As the byline on the recent IC article on them read: Jupiter’s results have all the morbid fascination of a space shuttle crash.
I don't think Schroders (LON:SDRC) would be interested - although they may merge with M&G (LON:MNG) once the shareholder enfranchisement is sorted out.
If Jupiter is sold it'll probably be to an overseas buyer. Despite the fact it's been terribly managed it does have significant assets and at the current price losing some of its "star" managers would probably be no great blocker. As for different cultures, they've made a fetish out of not having a house style - well, other than the fact that all of their managers have managed to lose money recently.
Frankly I can't see why anyone would want it, but it's a perennial takeover rumour target. Perhaps its best defence is that its major shareholders are sitting on whacking great losses.
timarr
Hi gringo,
That's a really useful list of Jupiter fire sales, thanks.
I'm gradually working my way through the 90% club, as I reckon there could be some lovely bargains in there amongst the dross. But I'll only be able to tell you which are bargains, and which are not, in about 2 years! ;-)
Regards, Paul.
Paul I don't agree with your HSW analysis and would like to present the alternative hypothesis if I can. I think it answers some of the questions as to what you might have been missing given the relative outperformance of HSW versus other OTA's.
22 was always the recovery year and the investment case is not about 22 but about 23 and beyond.
Given the continued Covid disruption in Q1 22 and the gradual unlocking it is unsurprising that H1 EBITDA was negative but inline with broker forecasts. The booking trends continue to improve and they have guided that H2 will be EBITDA positive but only time will tell if the H2 recovery is enough to mitigate the H1 losses. The 22 exit run rate could be in line with 2019.
Despite your comments on cash the burn has been extremely modest despite the increased marketing spend. The company has E23m of cash versus E25m on Jan 1. The increased marketing spend has been justified and well explained if you look through the presentation.
The addressable market is c.$5 bil and it's estimated that HSW has a market share of c.8-10%. Hostelling is a travel niche. Their customers are typically 18-30 year old single people so arguably form a disposable income standpoint less at risk than with other mainstream OTA's customers focused on family holidays in hotels.
At the peak they had 8m bookings which at c. E20 ABV implies E160m of revenues. The question is what do booking levels return to in 23 and 24. Given the strong FCF characteristics, even taking into account the additional marketing spend, the EBITDA forecasts of E12-16m for FY23 do not appear to be too much of a stretch especially given the horrific airport disruption that has affected all airline travel (obviously dependant on the geo political and Covid 19 outlook). The repeat booking characteristics of hostellers are very attractive and compound growth over future years especially as the marketing spend is all offset on the first booking.
Should the booking recovery continue into 23 their EBITDA will put them in a strong position to refinance/remove what admittedly is costly (but undillutive debt). Admittedly marketing spend has risen this year but the reasons were well laid out and are expected to normalise back to 55% from the current 70%.
If you take the broker forecasts of E12m to E16m of EBITDA for 23 then at 10 times that would imply a market cap of E120m- E160m.
So I don't think for one minute the equity will be wiped out. That would imply a catastrophic prediction about future travel patterns for such a specialist niche.
The key question for me is not the recovery, which is a question of when not if, but the execution of the growth story beyond the recovery which is why their differentiated social media strategy is an exciting and differentiated development and one that is likely to maintain their economic moat vs. mainstream OTA's more focused on hotels.
The beauty of investment is that we can all take different views and in the end the ones that are wrong lose money those that aren't don't. So you may be right. I appreciate you taking the time to explain your view. Would be good to know if you are an existing holder which is always useful.
I am not a shareholder but I do follow the company closely.
Hi jvb68438
Interesting points, well made! :-)
Thanks for posting, we like getting different perspectives from bulls & bears (and neutrals).
Just to clarify one point, my fear of equity wipeout (downside scenario, not necessarily the most likely scenario) at £HSW is specifically because of the high cost debt structure. So in a downside scenario, if it runs out of cash, or just breaches the terms of the high cost debt, then that could trigger the lender taking control of the company, or forcing heavy dilution if that downside scenario coincides with dismal equity markets (like we have now).
Key information would be to research the detailed terms of the US debt, what the covenants are, etc. Good luck with it, sounds like you're a shareholder! (I have no position personally)
Regards, Paul.
Terms of the HSW financing deal are here: https://www.investegate.co.uk/...
This could become onerous, if HSW is not able to generate rising EBITDA as planned.
I checked back to pre-pandemic earlier, and it's true that HSW was a nice cash cow, and paying big divis (albeit ex-growth). We covered it here in the SCVRs from 2019, so worth a look. I think jvb68438 makes a good point that if HSW is able to return to pre-pandemic trading, then that might justify the current share price. We were worried about competition from e.g. Booking.com though, pre-pandemic. I wonder what the competitive situation is right now, and with high digital marketing costs, it's not a given that HSW would be able to return to pre-pandemic profits & cash generation. But it might do. So a good debate.
Thanks again, Paul.
Thank you Paul.
The princIple EBITDA covenants kick in from Dec 23
so that gives 18 months for the market to recover before there is a question over those covenants.
If the market shows any signs of stability and preferably a positive trajectory they have stated that the expensive debt will be restructured prior to term and in all likelihood H1 23.
Thanks for posting your alternative view - very helpful to see.
However, look at the pre pandemic revenue at Hostelworld (LON:HSW) - it was essentially ex-growth:
Yet at today's closing price we are being asked by the market to pay over 20x next year broker EPS estimates. This doesn't stack up given the debt and low growth pre-COVID.
On Beach group (LON:OTB) seems like a much better bet. It was growing strongly pre-pandemic, can mop up some of the business from the failure of Thomas Cook (though I see it has been re-incarnated), has net cash on its balance sheet, and is trading 6.7x next year estimates.
All fair points and it’s clear the market agrees with you that the return to growth is by no means a given.
The CEO Gary Morrison joined in 2018 from Expedia as a direct response to the company being poorly run. There is no doubt that prior to Gary joining , the company was leaking market share to competitors.
The current CEO’s recovery and growth strategy is well articulated so now it’s all about the execution.
I would say that at 90p the risk is largely priced in and the reward trade is 150 and beyond when the travel market recovers.
Only time will tell. I have enjoyed the discussion and reiterate I am not a shareholder.
S&U (LON:SUS)
Graham, I don't see the same Stock Rank figures you quote above. My page shows 33, 79,54 and SR 79.
Certainly reads up well.
I hold.
I’m seeing Q 56 V 78 M 58 culminating in a stock rank of 71….how can this be?
S&U (LON:SUS) - Ditto. would be good to have an explanation.
S&U (LON:SUS) - I get a Stocko reading of 69 with Q53, V79 and M54. What is going on ! :)
Under settings there are 3 choices for ranking set: Local, Regional or Global. The ranks will change depending on which setting you have since by definition they are a rank in a series.
thanks ISAallowance….I’ve been blissfully unaware of that forever…much appreciated
S&U (LON:SUS)
Me too, much appreciated.
That is news to me also. Fortunately the default is “local” which is good for me.
Hi GN, I've asked for this to be removed as it looks like an error on my part - my apologies. With the setting at "UK Focus", S&U currently has a StockRank of 71 for me (Q56, V78, M59).
Great write-up on S&U, Graham, thank you.
They grew profits through the financial crisis and I'm confident they'll continue to grow profits over the next few years. S&U, and the quality of its underwriting and collections, is perennially under-rated.
I also note that they have taken a huge amount of provisions through their books already for potential future impairment, primarily as a result of COVID. They never actually needed it, as folks got back to paying their loans off without any issues. This gives them a big buffer for any stress they do see going into H2 and 2023.
(should say I hold a boatload of this so I am obviously v. biased)
You're welcome, EV - as soon as I saw the update this morning, I guessed that you'd be reading my report today :)
Good morning Paul,
Thanks for your piece on S&U (LON:SUS) , i spent sometime looking at this a few months ago, and while it ticked a lot of boxes the worry of customer defaults going into a possible recession etc. and the fact that it just seems unloved ultimately put me off. I would add the fact that S&U (LON:SUS) offers around a 4% yield , Stocko figures say 6+% but im not sure this is correct .
Richard
Check frequency of dividend
Whoops,
I have just seen it was Graham's piece, apologies !
R
no problem Richard! G
Just a reminder ME International (LON:MEGP) formally £PHTM goes Ex tomorrow for 6.5p. It did not flag on my Stocko alert.
Would not want anyone to be stopped out unintentionally.
If you get time Paul/Graham I would value your thoughts on Hostelworld (LON:HSW) results today. I don't like £HSW's expensive debt and it wasn't performing that well pre COVID so it is not for me but the travel sector is still pretty beaten up so interested in any read across generally.
Morning Patrick L, yes I'm working on Hostelworld (LON:HSW) as we speak!
Best wishes, Paul.
Thanks v much Paul. Maybe Hostelworld (LON:HSW) would make a good candidate for shorting (as per the screen it's been identified for) - I've never done this before but I'd be tempted here although it is peculiar that the share price has held up so well.
Crestchic
Update on my post yesterday when I seemingly had been on the wacky baccy, apologies for some fake news
Chairman is Peter Harris not Peter Hook, thought it strange that the founder of New Order and Joy division would end up chairman of an AIM loadbank company .
Capacity increase they are quoting is 60% not 300% - thought has to be more than 60% when they get it running correctly .
'Maybe I've forgotten the name (and the address)...'
Regret - New Order
‘Maybe I've forgotten the name (and the address)...'
Regret - New Order
Good to see some love for New Order here. One curiosity that might be of interest to fans is that I was (am still) the very first owner of the classic 12” Blue Monday, which marks me out as somewhat of a superfan. And a lot trendier as a student than I am today. I still treasure it of course and it’s probably worth more than some of my stocks after this year of pain. But it would be worth a lot more if I hadn’t left it lying around on the floor of my student accommodation out of its sleeve for most of my student days. What an idiot!
I still have some bootleg cassettes of New Order live from various gigs in the North. Of course, there are lessons to be learned from the band in how not to do business. They had the biggest selling twelve inch single of all time with Blue Monday , but the fancy packaging for it cost 10p more than the income from each copy. Cumulative loss around £50k if memory serves!
The poor profitability of Blue Monday was of course compounded by the financial disaster that was their bankrolling of the Haçienda. But their close association with those two cultural high-points (debatable if you ever had to fight past the needles and unholstered weapons in the gents’ loos at the Haç) sees them headlining the biggest festivals worldwide some 40 years later.
Apart from the acrimonious split with Peter Hook who left to take up a board seat at Northbridge Industrial Services, it’s worked out all right for the band members.
Hi planetx
Crestchic
The previous CEO was called Eric Hook. I thought that might have been the root of the error.
Hi planetx,
Chairman is Peter Harris not Peter Hook, thought it strange that the founder of New Order and Joy division would end up chairman of an AIM loadbank company .
How disappointing!
I was dreaming about turning up at the Crestchic AGM, and shrieking, "Take it away, Hooky & the boys!" - I do a brilliant Mrs Merton impression (who was of course married to Peter Hook, and his band did the backing music for the Mrs Merton Show - one of my all-time favourites comedies).
Best wishes, PAul.
Crestchic (LON:LOAD)
Planted, thanks for your excellent write up yesterday.
I can add some additional clarity. From my understanding Peter Harris has given market expectations of a 60% uplift in productivity from the new factory and resulting increase in productivity in the existing one. However he has since suggested the result may actually be nearer to 100%.
I am a high conviction holder from under £1 so biased.
Michael
Interesting announcement from Redde Northgate (LON:REDD) headed 'Update on Share Buyback Programme', but on reading it also appears to be a trading update, inferring continued strong trading?
Redde Northgate (LON:REDD) is doubling the amount committed to its share buyback programme from £30m to £60m. All in all very positive I would suggest. I hold
Redde Northgate (LON:REDD)
jonno
but on reading it also appears to be a trading update, inferring continued strong trading?
Nope - albeit the reiteration of what they have said previously suggests to me (off the record kinda) that things have not worsened in the last month. They clearly said today the strong trading bit was "as announced on 6th July" - so all they are doing he re-hashing what they previously said.
per update today
As announced in Redde Northgate plc's full year results announcement on 6 July
2022,
I am chompingly happy the company has upped the sharebuybacks at current price - some peeps really hate share buybacks and there is always the danger the may end up with "egg on their face" at a later date if the future results are less rosy than the recent past . If they are raking in pots of cash and they are genuinely trading on p/e of 8 whilst maintaining profit levels (ignoring covid spike upwards) - seems a no brainer allocation of capital - alongside decent divi.
I notice 2024 expectations are up on stocky (30/4/2024) - they show a drop in net profit from £108 mill this year to £102 mill in 2024 (next year) - thats how it should be done sensible forecasting ref managing future expectations. They have had some fantastic tailwinds with high used van prices that one should not expect to last - the fact they expect to deliver more in 2024 than they did in 2022 is pleasing even if that will be a yoy drop of 10%. Thats still 50% above 2021 and previously (ok they did merge 2 comapnies to get where they are) .
Obviously the future is uncertain and profits will be subject to vagaries of van supply and demand and pricing - so no guarantees that they will get anywhere near expectations for 2024 - all we can do with any company is hope they give us reasoable best guess clear expectations and regular updates - none of your "we are only 3 months into the year" its so hard to put a finger in the air brigade (you know who you are saga board). I think the market does expect that things are more likekly to worsen from here than get better due to prior tailwinds - with such bouyant recent used van prices i would agree that they will be doing great job if they hit current targets - no biggie if they fall slightly short.
Hi rmillaree,
I have no problem with your interpretation. All in all management appears to be doing a good job and I am more than happy to hold.
It will be interesting to see what acquisitions if any, Redde Northgate (LON:REDD) makes.
All the best.
And not just 'van supply and demand and pricing' but also their pricing power for rentals is key to watch. Margins are higher at the moment and the company has said it thinks 15% is a sustainable long-term margin on hire, but if demand softens a lot with a recession then we might see margins get squeezed a lot. I think this has been weighing on the share price of £REDD plus it never seems to be on more than a single digit multiple. For those reasons I downsized my position recently although I am hoping some decent M&A deals might provide a bit of a catalyst.
From the S&U update today.
"However, these results do not mean that S&U has become either hubristic or
Panglossian."
That's a relief.
S&U (LON:SUS)
An even better relief is the some 6% up lift in the SP this AM.
Panglossian
Definition: Blind optimism despite the circumstances and surrounding evidence
Example: I was panglossian about Norwich City's chances in the Premier League last season