Small Cap Value Report (Weds 11 August 2021) - RST, GDWN, RPS, WBI, HSW

Morning all, it's just Paul here today, with the SCVR for Wednesday.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Sectioon:
Restore (LON:RST) - (from yesterday) - RST has successfully fought off a semi-hostile takeover approach from Marlowe (LON:MRL)
Goodwin (LON:GDWN) - results for FY 04/2021, look good. The valuation has come down to a more reasonable level. Sound balance sheet & cashflows. This share looks interesting to me on a quick review of the numbers, and could be worth readers doing your own more detailed research.
Rps (LON:RPS) - Interim results are nothing to write home about, with increased profits coming from cost-cutting rather than revenue growth. Balance sheet still quite flimsy, although helped by a placing last year which increased the share count by 20%. One for sector experts I think, as there's nothing much in the figures or outlook to excite me.
Woodbois (LON:WBI) - poor interim results from this AIM-listed African timber company.
Hostelworld (LON:HSW) - multiple issues with this share, so I'm steering clear.
Restore (LON:RST)
490p - mkt cap £669m
Bid talks off
Marlowe (LON:MRL) announced yesterday that it does not intend to make an offer for Restore, as acceptable financial terms could not be agreed. RST mounted a spirited defence of its independence, with most of its major shareholders supporting RST management.
Given that the proposed deal was mostly offering new Marlowe shares, with only a small cash component, then the possible deal was highly dependent on Marlowe shares being buoyant. In reality, Marlowe shares were slipping in price, thereby making a takeover deal funded mainly in Marlowe shares less attractive.
This was certainly an interesting situation, and unusual, in that Marlowe went semi-hostile by appealing above the heads of RST management, to shareholders directly & publicly. That’s very unusual these days, but was more common in the 1980s I think - who can forget the Guinness-Distillers case, where share prices were manipulated in an attempt to get a deal done, leading to jail sentences for the "Guinness Four". Including famously Ernest Saunders, who was released after only 10 months, due to suffering from incurable Alzheimers. He subsequently made medical history with a full recovery [source]. You've got to admire his ingenuity in a way, that must have been a tough thing to pull off convincingly.
RST made the point that whilst superficially similar, there were in reality few synergies between RML and RST. Anyway, they’ve lived to fight another day, there must be considerable relief at RST headquarters! It’s provided a nice boost to RST’s share price, so anyone minded to sell has had a good opportunity to bank an extra 20% from this bid situation. RST looks quite good, but priced about right now I think.
RST seems to be good at making multiple acquisitions.
.
Goodwin (LON:GDWN)
3010p (up c.1%, at 08:33) - mkt cap £232m
To refresh our memories, here is my review of the last interim results from this engineering group, published in Dec 2020.
Today we have results for FY 04/2021. The company doesn’t seem to put out trading updates between results.
Overall this looks a respectable results, given that H1 saw PBT (profit before tax) of only £5.8m, implying a rise to £10.7m PBT in H2 (although sometimes year end reconciliations, and audit adjustments can muddy the water in H1 vs H2 comparisons) -
The pre-tax profit for the Group for the twelve month period ended 30th April 2021, was £16.5 million (2020: £12.1 million), an increase of 36% on a revenue of £131 million (2020: £145 million). The Directors propose an increased dividend of 102.24p (2020: 81.71p) per share.
Profit margin - £16.5m profit on £131.2m revenues is a healthy margin of 12.6%, so this is a quality business, in a difficult year (impact of pandemic). Note there is a non-controlling interests line, so just under 4% of the profits (£512k) don’t belong to group shareholders. This is adjusted for in EPS, making EPS the better measure to use for profitability.
EPS - diluted EPS is 164.2p, up 59% on last year.
This gives a PER of 18.3 - that’s much improved (i.e. a lower multiple) than when I last looked at this share, when the PER was nearer 30. So providing this higher level of profitability is sustainable, then the valuation is now looking much more attractive to me, and I like the fact that the company has delivered a strong H2 & overall decent full year result.
Divis - that’s a yield of 3.4% - not bad. I’ve checked the Stockopedia dividends summary page, to see if they pay interim divis too, but no, it’s just final divis. As you can see below, the divis were rebased upwards significantly in the last 3 years, which looks like a strategy decision, and it’s impressive these have been sustained despite the pandemic. Also note occasional special divis previously.

.
Order book - down on last year, but still referred to as “healthy”. I assume that “workload” is the same as order book?
...the Group's workload as at the time of writing remaining healthy at £165 million (2020: £183 million).
Outlook -
Armed with a strong balance sheet and a renewed set of bank facilities we are well placed to benefit from the recovery of the global economy and deliver strong returns on the capital that has been invested to date. The Board remains confident of the Group's ability to continue to develop new and existing activities that will deliver additional sustainable growth in the long-term.
Balance sheet - it’s a fairly capital intensive business, as I would expect for an engineering group, with £77.1m of tangible fixed assets.
I’ve checked note 12 of the 2020 Annual Report, which shows £33.5m of land & buildings. I assume this is freehold property, because leased property is a separate line, Right of use assets. It is not stated whether the land/buildings are included at cost or valuation. Family-run, traditional businesses like this often have a treasure trove of hidden assets, with freehold property often in the books at a lot less than current value, thus providing investors with strong downside protection, which they may not even be aware of.
NAV is £118m, less intangible assets of £24.8m, gives NTAV of a healthy £93.2m.
Working capital looks very good, at a current ratio of 2.11 (anything above about 1.5 is very good, for this type of business).
There’s £34.7m in bank borrowings, partially offset by £15.2m in cash, so net debt of £19.5m. The narrative says net debt was £17.4m, so let me double-check what the discrepancy of £2.1m might be. No, I’ve drawn a blank on that, there’s no breakdown of the net debt figure, but they’re in the same ballpark, so let’s move on.
Overall, given the freehold property assets (which I usually offset against net debt), the liquidity and overall financial strength of the business looks very good. I have no concerns about the balance sheet at all, it passes with flying colours. I can’t see a pension deficit either, which is good. Double-checking by doing CTRL+F for “pension” produces zero results. So it looks clean in that regard, apparently no pension deficit, which can often be a big problem for this type of traditional business.
Cashflow statement - is impressive, for both years, this is a decently cash generative business. Although note just over half of cashflow was spent on capex. This seems to include building a new freehold facility, which was transferred from assets under construction, into property. Hence that temporarily inflates capex, which should be lower in more normal years.
Note also it capitalised development spend of £1.4m (£1.1m LY) which is fine, as it’s not excessive by any means.
Dividends paid were more than covered by the free cashflow, which is good to know, as that suggests divis are sustainable at this level.
My opinion - please remember that in the time available, and the large number of companies covered in the SCVRs, we’re only really reviewing the numbers. It’s not feasible for us to go into detail about the company’s products, markets, and hence future outlook. That’s your job!
Overall though, I’m impressed with the numbers, the valuation looks reasonable, and think this share looks worth a closer look by readers, if you like the sound of it.
I seem to recall we had a good discussion about this company last time it reported, and it might have been Rhomboid, who posted comments saying that he’s done detailed research, and believed the outlook for new business (e.g. nuclear decommissioning containers, I think?) looked very good.
I’d like to hear more about this company, from readers who have researched it in depth. From my brief review of the numbers, I think Goodwin looks potentially interesting.
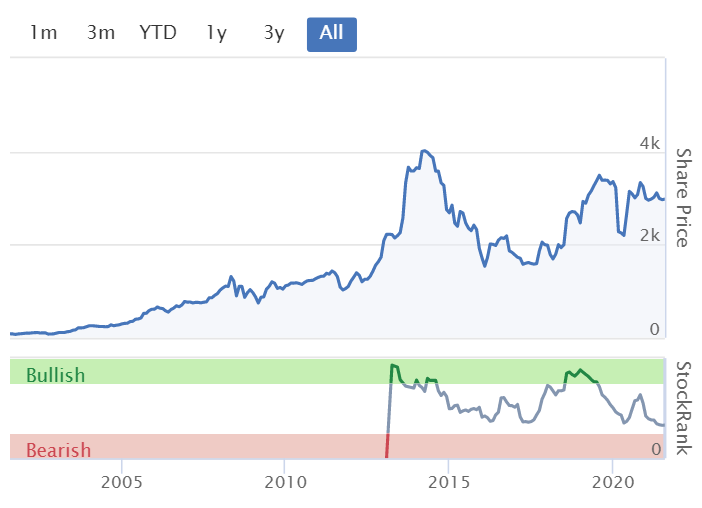
See the long-term chart below, which I've zoomed out to show the spectacularly good long-term track record. A decline in the oil & gas sector, on which Goodwin used to be very reliant, is the driver of the dip from 2015, but new markets have since been expanded into. Also the price of oil has been rising more recently.I wouldn't be surprised to see the share price working its way back up to former highs, if current good performance continues.
.
.
Rps (LON:RPS)
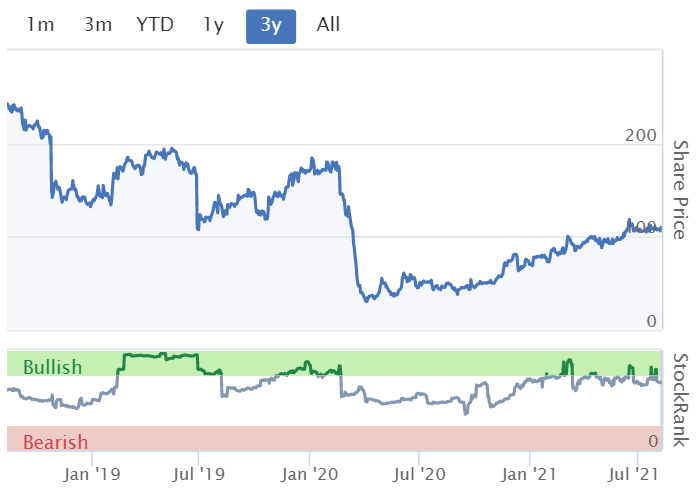
108p (down c.2% at 10:24) - mkt cap £295m
Preamble - I’ve only ever reviewed this company once, just before the pandemic began in Feb 2020, reviewing RPS’s calendar 2019 results here. They weren’t great, with 2019 adj profit before tax (PBT) of £37.3m, down 26% on 2018. So something seemed to be deteriorating even before the pandemic struck in 2020.
I also noted that the balance sheet showed negative NTAV, and net debt was also a concern to me at end 2019.
Looking quickly at FY 12/2020 results, adj PBT fell heavily, to £13.4m, down 64%. Exceptional costs were heavy at £39.2m in 2020 (mostly goodwill write-offs), and £23.4m in FY 2019, as a reader points out in the comments section. Exceptionals are minimal this time, in H1 2021, pleasingly, so it looks like restructuring is out of the way now.
Cashflow in 2020 was strongly positive, due to squeezing working capital, and paying down debt.
A placing was done in Sept 2020, noting that some of the favourable working capital movements would unwind in future. £20.2m in gross proceeds were raised by issuing 45.88m new shares at just 44p (price now 108p), so they raised at a really bad time, and enlarged the share count by 20%, which obviously detracts from the % upside in future, per share. That’s the trouble with running a lean balance sheet with too much debt - it can force the issue of new equity, at the worst time & price, when something unexpected happens - as we saw for many companies in 2020.
That’s set the scene, so clearly the attraction of this share is whether it can recover to pre-covid trading, or better, in recovering economies around the world?
RPS, a leading multi-sector global professional services firm, today announces its interim results for the six months ended 30 June 2021 ('H1 2021').
Company summary -
'Strong financial performance, proven ESG credentials, significant opportunity, and reinstating dividends'
Revenues unchanged at £232.4 (up 0.5% to be precise) for H1
Adj PBT up 128% (from a low base) to £9.8m - achieved by cost-cutting
Adj diluted EPS 2.54p - only up 25%
Net debt reduced considerably from £57.8m at 06/2020, to £27.8m at 06/2021 (helped by the placing of course)
Commentary says H1 trading was in line with expectations
Interim divi reinstated, of 0.26p - very small, so nothing to get excited about
Contracted order book up 7% in last 6 months, but no figure given
Outlook - a couple of key excerpts (there’s more detail in the RNS) -
The good momentum achieved in the first half of the year has continued into H2 2021...
We remain focused on building a business that can deliver mid-single digit rates of organic revenue growth and a double-digit operating margin in the medium term and are confident in our ability to do so.
Balance sheet - NAV £348.2m, less intangibles of £343.2m, leaves a sliver of £5.0m NTAV. Still not great, despite a fundraising last year.
Cashflow statement - not good, it consumed £15.2m cash in H1 2021.
My opinion - I’m not impressed overall. The recovery so far seems quite slow, maybe that’s because providing consultancy on capex projects has a time lag?
Outlook comments don’t sound particularly exciting either.
Overall, I think this is one for sector experts, who have a better handle than me on the longer term prospects. Even before covid, profitability at RPS was too erratic for my liking (see graphs below).
On the upside, there was a spate of takeover bids in this sector a while ago, and with UK companies being bid for left, right, and centre, that could be an outcome here too maybe?
Overall then, I’ll just say I’m neutral. It could rise further, as the recovery in business hopefully gathers steam?
The valuation looks quite reasonable, based on an update note from Liberum (many thanks!) this morning. Forward PER of about 15-16 looks about right, but holders must be hoping the company can beat fairly undemanding forecasts? Although bear in mind there are 20% more shares now, compared with pre-covid. There looks to be an H2-weighting to profitability.
.

.
.
Woodbois (LON:WBI)
5.0p (unchanged) - mkt cap £93m
I’ve not looked at this share before, but have had a quick skim through its interim results today for the 6 months to 30 June 2021. It seems to be a timber company, listed on AIM, operating in Africa. Probably not much more needs to said, given AIM’s track record on speculative overseas companies - it seems to be a magnet for duds. There’s always the slim chance this could be a needle in a haystack though.
I can’t see anything of interest in the numbers -
H1 revenues only $8.2m (down slightly on LY H1)
Very weak gross profit margin (20%), only $1.7m gross profit, albeit better than even worse figures last year
Loss making every year, apart from a prior year profit which came from revaluing its assets upwards
My opinion - why take the risk? How is it worth £93m? Maybe the story is all about future growth, and biological assets maturing over time? It’s just not the sort of thing I would go near, having seen so many speculative, loss-making overseas stock promotions on AIM go horribly wrong over the last 20 years.
.
Hostelworld (LON:HSW)
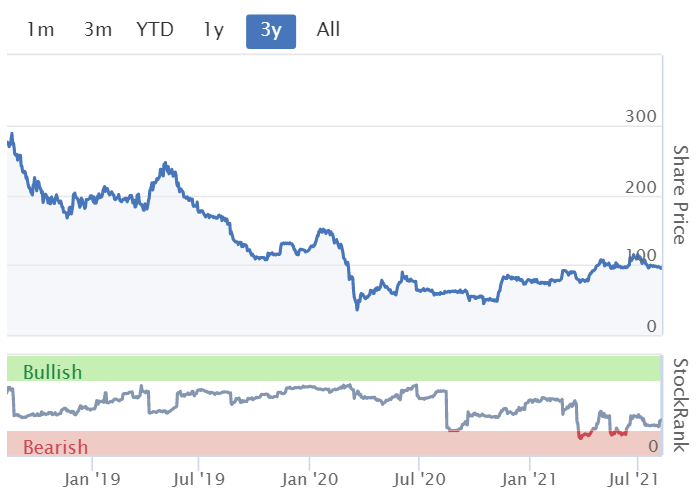
96p (up c.1%, at 12:34) - mkt cap £112m
Travel-related shares are obviously in varying degrees of mothballing, or stop-start operating, so the only reason to look at the figures is trying to work out the recovery potential, and how solvent the company is. In that regard I would have thought internet businesses like HSW should have an advantage, in having a flexible cost base.
Key numbers for H1 (HSW reports in Euros) -
Negligible revenues of E2.9m (down 76% on H1 LY) - not a surprise given travel restrictions
Marketing costs also slashed, from E7.5m H1 LY to E2.4m H1 this year
Administrative expenses down 43%, but still substantial at E13.5m
Adj EBITDA loss of E9.7m for the six months - that strikes me as worryingly high
Is it likely to go bust? Liquidity looks OK, with E33.7m gross cash, but that’s come from taking out borrowings. Old facilities were repaid, and a new facility of E30m, a five year term loan, with E28.8m drawn down on 23 Feb 2021. This is an unusual, and expensive, borrowing facility, carrying interest at 9.0% + EURIBOR (floor of 0.25%. This facility also has covenants which kick in, in 2023. The lender has also been granted warrants over 3.3m effectively free new shares, 2.85% potential dilution - not a disaster, but it needs to be factored into calculations.
This looks a sensible deal to ensure survival, but it does reinforce that HSW is probably too high risk for conventional banks to get involved at the moment (and I don’t blame them, given the uncertainty).
It also raises the question of whether HSW tried to get equity funding, and didn’t see much appetite from shareholders?
Anyway this deal has largely avoided dilution, so if the business does recover strongly post pandemic (a big “if” - will enough people want to stay in hostels, where distancing is near-impossible?)
Overall then, I think the debt arrangements are clearly unusual, and a very important point for investors to properly research before investing. You can argue either way, bull or bear, on this point. Non-standard debt facilities tend to worry me though, it’s a warning flag. Risk factors are often glossed over by investors (guilty as charged!) so I’m trying to train myself to read them. Here is the one about the new loan facility -
Our term loan facility contains repayment obligations and covenants, reporting to the involved brokers and lenders and requires constant monitoring of the Group's leverage position and liquidity metrics. Without a return to growth it is not certain that the Group can meet the minimum liquidity covenants set out under the terms of the term loan facility agreement.
The risk warnings about competition & search engine algorithms are also worth noting.
Balance sheet - given the current level of cash burn, I do have concerns about balance sheet weakness. NAV is E81.0m, of which E79.7m is intangible assets. Leaving only E1.3m in NTAV. That’s not enough, for a company that’s currently heavily cash burning. Even when travel returns, the cash burn probably won’t stop immediately because increased marketing spend will be necessary to re-start the business.
Hence I suspect a placing might be needed at some stage in 2022, depending on how things pan out.
Note 11 shows some creditors look stretched, especially payroll taxes. That would eat into the cash pile when they normalise.
My opinion - I’m wary of this share. The finances are now totally dependent on an expensive borrowing facility. Also I think overheads look too high, and in my opinion maybe were not cut enough over the pandemic. Although it has dragged on a lot longer than most of us imagined, so it’s difficult to criticise judgements made on whatever information was available at the time.
Probably my biggest concern though, is how much recovery potential is there, given that the business has almost been shut down for 18 months? HSW was losing ground to competitors in 2018 & 2019, pre-covid, with the previous bumper profits under pressure. Add onto that the impact of the pandemic, which could carry on internationally for a while, who knows? Hostels might not be people’s first choice once travel does normalise.
Put all that together, with a share price that seems to be factoring in recovery already, and HSW shares look distinctly unappealing to me, on my personal assessment of risk:reward. I think there are much better, and safer ideas for travel resumption. Although actually many of them look to have already overshot on the upside, so it’s really not a sector that draws my attention at present for new investments.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Re:Goodwin (Goodwin (LON:GDWN)). Agree with all of the commentary by Paul and Rhomboid1. Goodwin is one of the hidden jewels of the UK engineering industry. It has been going since 1883 and still remains a family controlled business employing over 1100 staff and generating 70% of its revenues overseas.
True, its level of disclosure does not match that of many of its rivals, it does not cultivate media attention, and it does not take much notice of fashionable corporate governance rules. However, unlike other family controlled businesses it does not seem to have run out of well qualified family members to head the business, although there was some uncertainty when the next generation of the family took over a couple of years ago. Judging by the latest results, Goodwin’s new young top management team is performing well, with margins returning to more normal levels on lower revenues, promise of good growth ahead, and a hefty dividend increase.
At a time when the media loves highlighting the problems facing business as a result of Brexit, it was encouraging to read Goodwin’s latest comment that “ Brexit has not been seen as a significant issue to the Group, the previously identified risks have been managed or mitigated and the Board no longer consider this as a significant uncertainty”.
Re Angle (LON:AGL) JimMcLad. Just thought would bring to your attention the small but significant study RNS from yesterday from a research centre in Slovenia. I may be accused of cherry picking - I regularly am - but the figures that jump out at me are as follows:
*What specific area of application are the FDA considering the Parsortix process for right now? Yes, breast cancer. Angle (LON:AGL) point out breast cancer is the leading cause of cancer in women worldwide. The National Cancer Institute estimates that 282,000 women
will be diagnosed with breast cancer in the US in 2021. A further 3.7 million US women are living with breast cancer. Despite a 5-year relative survival rate of 90%, up to 30% of women will develop metastatic disease. MBC patients where a tissue biopsy is not feasible. The figures are huge, the key word is metastatic, which means that the cancer has spread. It is desperately sad.
*Results from this study showed that the Parsortix system was able to harvest CTCs in a greater proportion of MBC patients (64%), compared to the antibody-based system (57%), not significantly different. What is hugely different is that 99% of the
cancer cells recovered by the Parsortix system had preserved morphology,
allowing morphological analysis, whereas less than 1% of the cells recovered by the antibody-based system had preserved morphology.
*CTCs were identified by their morphology (as opposed to biomarkers) using light microscopy which is universally available in pathology departments. This method of CTC identification is the standard laboratory practice for cytopathological and histological examination of tumour cells from tissue biopsy. Yes, the system can be used in virtually any standard laboratory.
*This is a small sample, but this follows on from a large series of similar results from many different institutes across Europe, UK and the US. Perhaps this had something to do with the 8% rise in the SP today/yesterday combined. Lets hope for the sake of many 000s of patients that the FDA give approval sooner rather than later. There’s much more to life than Covid 19.
Sosandar (LON:SOS) jumped 9% this morning. Anyone know why?
Re. Sosandar (LON:SOS) price spike today, maybe because it fell 14% from 36p to 31p last Friday? Seems to be the silly season for a lot of small caps at the moment with big moves up and down (and back again) for no apparent reason. Bored brokers playing silly bu**ers?
Gus.
Goodwin (LON:GDWN) - just a point on the dividend.. indeed it was a strategic decision in 2018 to increase the dividend - the formula is to pay 38% of (net income + depreciation + amortisation) which does build in a certain degree of payability with perhaps the downside of not necessarily smoothly increasing payouts..
Hi Paul,
I totally agree with you with £WBI.
The company has been listed for quite a few years with a few different names in that time and it was not always about timber either. IMO, this company is more of a shell company allowing money to be moved around and duping investors. Anyone interested in investing here you research back quite a few years to get a better picture of things.
Any views on Atalaya Mining Atalaya Mining (LON:ATYM) interims out today? (Pitched by Jack recently). I bought a small holding, and am still thinking that copper is going to be increasingly in demand for EVs and more and more tech equipment.
Re Atalaya Mining (LON:ATYM), I thought the results were impressive although they were well-flagged in advance. What troubles me is: (i) the permitting issues with Touro - the Spanish authorities have shown themselves not to be a pushover when they have environmental concerns and the lobbying powers that be are well entrenched and powerful in mothballing projects; and (ii) the rising All in Sustainable Costs (AISC). These are set to rise to US$2.50-2.65/lb, which is in the high quartile for copper producers. This may be fine now with elevated copper prices, but is a big issue if prices revert back to closer to US$3/lb. For those reasons, I don't own it and see better long term upside elsewhere but that is purely my view (which likely is wrong...). All the best, Will
Atalaya Mining (LON:ATYM) is currently presenting their Q2 results on InvestorMeetCompany. Some highlights:
- considering re-domiciling the company from Cyprus to London
- hoping to move to main listing from AIM
- dividend being discussed and an announcement likely "sometime this year"
Lots of detailed information on the various projects and status of Touro etc - well worth listening to in my opinion (it is being recorded).
I agree…. Today’s Atalaya Mining presentation was rather insightful, and definitely worth visiting - if you are convinced on Copper (which I am)
Currently slightly over the SCVR limit is my long term holding in 4imprint (LON:FOUR) with half year results out today. I've held this for just over 10 years and it has > 10 bagged for me.
Results show improving order books particularly in the US which is the prime market and benefiting from a return to normality in the business world post Covid. Order levels and new customer acquisitions are getting close to pre-pandemic levels, especially running into the 2nd half of the year. The dividend has also been restored and they have paid special dividends in the past. The business is net cash and lending facilities in place have not been used.
The share price has recovered a fair bit from the lows of the last 12-18 months so clearly a recovery play. A disappointment for me is that the net margins are still very low compared to historic standards, I guess not helped by an uptick in marketing spend. However the marketing spend does seem effective as they have historically been increasing their market share each year in a massive market. If I remember correctly, up until Covid they were well on track to beat their deadline of reaching annual turnover of $1 billion. Covid was the black swan which scuppered that target but recovery is coming. After holding this for so long I know the management tend to deliver on their promises and seem very capable.
It might be of interest to some, but if I remember correctly (I don't have notes going back that far) but when I first invested > 10 years ago the share price was very lowly rated due to a pension deficit. They had a clear plan to reduce this, which in my view, along with the business growth has helped re-rate the share. The defined benefit pension plan (closed to new members) now only has a deficit of $2.24m, very manageable for a company with this great cashflow management. Kudos to the company for managing this.
If you know little about 4imprint (LON:FOUR) they provide marketing products for companies; think of branded pens, mugs, umbrellas, notepads etc. They have minimal stock holdings and outsource the branding work. This has been a successful business model for them. With the return of exhibitions on the general business agenda I think the recovery in the trading for FOUR will continue.
Renewables Infrastructure (LON:TRIG) H1 21 results presentation to analysts and investors, given last Friday. Interesting that it was less windy in January! Video & podcast.
The Vertu Motors (LON:VTU) investor webinar to be given next Tuesday 17th August at 4.30 seems really popular. Register here.
Paul, I could not believe your comments on RST. Yes its a quality stock but don't you think its growth prospects are relatively dull vs MRL? Share price performance suggests this over 1, 3 and 5 years: RST +38%, 2% and 41%. MRL: 59%, 65% and 380%.
Restore shareholders will regret this as a missed opportunity to return to being a great growth stock. As a MRL shareholder I'm impressed that the MRL decided not to overpay for a business whose best days are behind it!
Hi Chasbas,
If you read my comments again, perhaps more slowly & carefully, you would see that I think RST is fully priced, and suggested that the recent 20% pop on takeover talks could be seen as a good opportunity to sell! I don't have any particular view on the merits of MRL vs RST, but thank you for your opinions on that.
I do agree though that the core business at RST is "mature" as the CEO said recently. i.e. ex-growth, presumably why they're doing so many acquisitions.
Neither Marlowe (LON:MRL) not Restore (LON:RST) are shares that I would want to buy. Both look fully/fairly valued, so where's the upside?
Regards, Paul.
Restore (LON:RST) and Marlowe (LON:MRL)
don't you think its growth prospects are relatively dull vs MRL? Share price performance suggests this over 1, 3 and 5 years: RST +38%, 2% and 41%. MRL: 59%, 65% and 380%.
This cherry picking of data reminds me of the famous quote
Lies, damned lies, and statistics
If we look at Marlowe it looks like it was a basket case that made no money prior to 2021 - obviously the shareprice is gonna rerate if they righted the ship and now make money when previously they didn't . To me the recent shareprice appreciation simply makes me wander what they were doing wrong previously rather what they are doing right now !
Ref the RST shareprice appreciation - doesnt look bad - but the trend in numbers ref profits looks better long teerm than MRL to me albeit they also had a dodgy spell.
Shares in issue has risen materially too ref Marlowe in last 4 years or so - up over 50% - makes me wander if they might have lucked out on an acquisition that actually was making some moeny rather than making their own business profitable.
Note i dont know much about either company so i may have also used cherry picked stats - but on an initial glance restorre looks like the more liablle operator of the two over the last 5-6 years. I know nothing about future prospects - in some respects the past doesnt really matter here.
Morning Paul & Jack. Please could I second fwyburd's request that you take a gander at Rps (LON:RPS) 's half year results out today? You last reviewed them back in February 2020 and you noted the substantial exceptional costs of £23.4m so it's reassuring to see that they are reporting exceptional items of just £0.6 million for H1 2021.
I hold in part because of the takeover potential here especially given the history of the CEO, John Douglas who was CEO and MD at an Australian Consultancy (Coffey) when it was acquired by TetraTech in 2015. TetraTech went on to purchase another UK consultancy, WYG in 2019 and TetraTech's CEO Dan Batrack has repeatedly alluded to their desire to add more UK consultancy capacity in areas such as water and renewables so Rps (LON:RPS) would appear to be a good fit and both CEO's are familiar to each other having done the Coffey deal before.
Simon Hedger wrote an excellent and very detailed article discussing the reasons why this scenario might play out here: https://cube.investments/rps-g...
OK, I'll take a look at Rps (LON:RPS) next, although not sure I'll have any particular insights. Simon Hedger is excellent in this sector, so he's more knowledgeable than me, so do read his post before mine!
Just a nod (not a small cap) to Norton‘s takeover/merger of Avast (LON:AVST) announced today.
https://www.investegate.co.uk/...
More U.K. plc retail therapy for Uncle Sam.
Gus.
Morning Paul and Jack, please could you take a look at Goodwin (LON:GDWN) if you get time. A lot to like in the results in my opinion, with H2 profits almost doubling over H1, margins much improved, and a large dividend increase.
It looks like the move away from reliance on the oil and gas sector to defence and nuclear industries may finally be starting to pay off.
Morning Northender,
I've just published my review of Goodwin (LON:GDWN) results. Looks excellent, I like it a lot!
Regards, Paul.
Many thanks Paul, much appreciated.
Hi Paul
Well remembered …I am indeed a big fan of Goodwin (LON:GDWN)
In my opinion this a snapshot of a business in transition…for instance new machine shop costs were incurred in these results (new property plant & equipment investment was £11.8m in the year) but turnover and profit from this factory will only start to materialise in the current financial year, the new facility is significant in size and capability and will generate a sizeable contribution to profits in the current financial year and into the future.
This facility is primarily utilised for a major nuclear submarine defence order for the US Navy this contract is very long-term in nature and has been years in gestation.
Goodwin steel castings has been loss-making, it lost £0.7 million last year & continued to be loss making in these results but going forward is likely to be significantly profitable with the all important baseload being provided by the Magnox nuclear storage box contract which will run for over a decade.
Easat Radar lost just under £1 million in financial year 2020 and probably lost a not dissimilar amount in the current year …however the commentary in this RNS suggests that in future this will become a significantly larger and more profitable business The reference to the system values being 10 times what they have historically been involved in gives a good indication of what the future holds in my opinion.
Supplying radar systems to secondary airports in the Middle East and Africa during a pandemic and the associated shutdowns on the aviation sector will have been a thankless task, however the commentary here is reassuring in my view.
the refractory engineering results were notably strong ..especially as the silica free product has yet to roll out, this enables them to supply the US market for the first time so is both margin accretive in non US markets & incremental in respect of the US market.
Soluform
https://www.soluform.co.uk
https://youtu.be/GFcDj7en2fw
and LithEx
https://www.avdfire.com
https://youtu.be/DBKbXOExydk
are both attractive niche products that have very large potential end markets, these markets will increasingly be regulation driven and specifier driven which creates a decent tailwind for the future
In summary Goodwin are mid way through a transformation from being a predominantly O&G industry supplier to a much broader based higher margin business with leading positions in some very attractive end markets.
I hold rather a lot of shares here because I like the culture & the ambition of this extraordinary business…so apologies for my bias
Hi Rhomboid,
Fantastic post on Goodwin (LON:GDWN) very much appreciated!
Regards, Paul.
My morning smallcap tweet: Downing the dregs of dispatches
Pipehawk (LON:PIP) Minds Machines (LON:MMX) Advanced Oncotherapy (LON:AVO) Quadrise Fuels International (LON:QFI) Northbridge Industrial Services (LON:NBI) Mail ru (LON:MAIL) Woodbois (LON:WBI), Inspiration Healthcare (LON:IHC)
PipeHawk (PIP) guides H1(June) rev £4.1m (£2.6m). "Order intake at the Group's three principal subsidiaries, QM Systems, Thomson Engineering Design and Adien is very healthy and the sales pipeline is strong." [SP=7 Cap=2m]
Minds + Machines (MMX) sells most of its top-level domains for $114m + $13.3m paid into escrow. Will wind down ops. Guides NAV 9.6p/sh. Tender Offer totalling $80m to be completed in early autumn. [SP=7.08 Cap=62m]
Advanced Oncotherapy (AVO) £37.4m placing at 40p, a 13% premium, to continue development. [SP=34.53 Cap=121m]
Quadrise Fuels (QFI) tests of bioMSAR completed on a Wärtsilä 4-stroke engine show greater than expected calculated CO2 saving, engine efficiency increased by up to 7% and "highly efficient combustion evidenced by low NOx, CO, particulate and soot emissions." [SP=3.35 Cap=47m]
Northbridge Industrial Services (NBI) guides H1(June) rev and pre-exceptional pretax ahead of mgmt exp. Rev up 22%. Restructuring the Tasman Oil Tool Division to return it to profitability and, in parallel, are actively negotiating with potential buyers Guides FY ahead of mgmt exp. [SP=102 Cap=30m]
Mail.ru (MAIL) provides $60.3m additional capital to AliExpress Russia JV. [SP=NA Cap=NA]
Woodbois (WBI) H1 rev as guided. Outlook " The additional capital items acquired and efficiencies made during H1 serve to strengthen our springboard to accelerate our growth, further improve margins and move into positive operational cash generation. However, the continuing uncertainties created by COVID-19 and the logistical difficulties in the shipping industry make it difficult to fully see the benefits of our operational progress being reflected in H2." [SP=4.99 Cap=93m]
In line: Inspiration Healthcare (LON:IHC)
Good morning Paul and Jack,
Would love to read your views on Rps (LON:RPS) HY results. Revenues back to where they were HY2020; margin improvement turns previous year loss into profit; debt at very manageable levels and reduced from prior year; reinstates small 0.26p dividend. Looks like the return to profitability is going well... I hold
Cheers
Francis
Hi Paul, Jack, is there a chance either of you might look at Rtc (LON:RTC) this morning?
Silver
Hi Silver Moon,
Rtc (LON:RTC) is a bit too small, market cap was below our usual low point of c.£10m, but I see it had a huge spike up yesterday on a contract win announcement with Network Rail -
The Contract will run from the 1st October 2021 for a minimum period of 5 years, up to a maximum period of 8 years and has an estimated order book value of between £100m and £150m over the term. This contract award confirms Ganymede's position as one of the UK's leading suppliers of frontline labour to the rail industry.
So that's £20-30m p.a. revenues, a big contract in the context of a company producing historic revenues of about £70-95m p.a.
Although we do have to bear in mind, it only generates c.£1-2m annual profit on those revenues, because most is "pass through" revenue, being the contractors' wages. No doubt this big contract will have been in competitive tender, so probably also low margin.
Personally I can't see any reason why RTC would be listed, it's too small for that to make sense. In a recovering economy, staffing companies tend to do well, which has been reflected in higher share prices for many of them.
Regards, Paul.
Many thanks for your reply Paul, I see now why £RTC doesn't appear in your appraisals. I have held since 2016 and along with a holding in Petards (LON:PEG) have gotten nowhere. Still, diversification is the name of the game, always adding to the learning curve:)
Regards,
Silver
On Petards (LON:PEG) it is on my watchlist. My big worry is the escalation of war in Ethiopia. Do you have a view on that?
Dahokolomoki - I think you mean Pittards (LON:PTD) not £PEG........