Small Cap Value Report (Weds 12 Jan 2022) - PMP, GTLY, MPAC, ACRL, FDEV

Good morning, it's Paul & Jack here with Wednesday's SCVR.
I'm pleased to see that, so far, we haven't got the year wrong. It's remarkable that I manage to remember that it's 2022, pre-caffeine at 07:00 every day. Even Jerome Powell, Chair of the Federal Reserve, got the year wrong in his Q&A session with Congress yesterday.
Agenda -
Paul's Section:
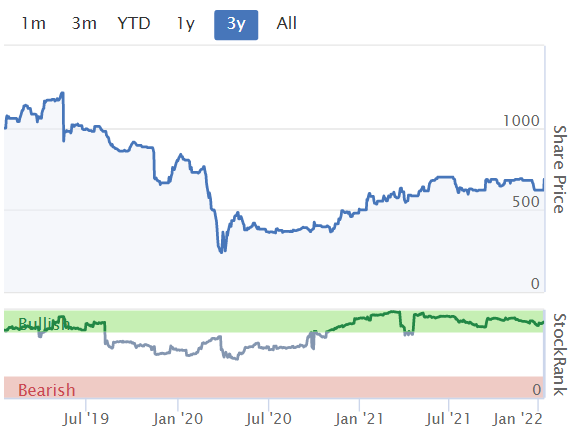
Portmeirion (LON:PMP) - an impressive FY 12/2021 year end trading update. Sales are well ahead of expectations, which has allowed the company to absorb cost increases and still deliver profit 9% above market expectations. The turnaround, and digital-focused growth strategy seem to be paying off. Looks good value to me, as future profits should rise once shipping costs normalise.
Accrol Group (LON:ACRL) - profit warning - repeated waves of input cost increases are running ahead of customer price rises. So guidance revised down. Not a disaster, the company is still profitable, but not by much when you account for heavy depreciation & finance costs. So valuing it on (much higher) EBITDA is erroneous I think. Strategic review has been launched - good, because the current business model results in unstable profitability, and repeated profit warnings. In my view, ACRL needs to move to open book contracts with customers, if they will stomach that.
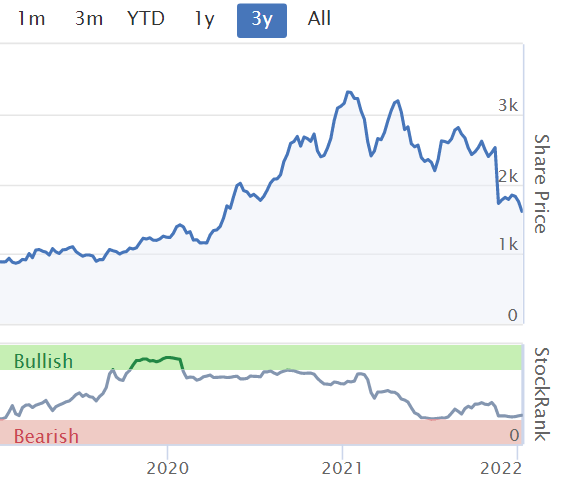
Frontier Developments (LON:FDEV) - another profit warning, down about 26%. The interim results are poor, and the outlook glosses over the financial hit from delays to future games releases. It's left to Liberum to deliver the bad news - a 38% reduction in forecast profits for FY 5/2023. This is not a proper way to report to the market, as not everyone can get hold of broker notes. Despite the lack of visibility, and 2 profit warnings, I'm tempted to have a little punt.
Jack's section:
Gateley Holdings (LON:GTLY) - mgmt is confident of meeting FY expectations, which suggests the valuation is fairly modest for what appears to be an established, well run, and growing enterprise with a long operating history. We can expect salary costs to rise in H2 but the group has a solid balance sheet that should allow it to execute on its acquisition strategy.
Mpac (LON:MPAC) - strong order book recovery bodes well for the upcoming financial year, and the diversification into clean energy could be an interesting development longer term. The shares have rerated strongly but the valuation is still not expensive on a forecast earnings basis. The large UK pension scheme is an issue, but one that would presumably benefit from rising rates.
Preamble from Paul
I listened in to Chairman Powell of the Fed, in his Q&A session with Congress yesterday, and was greatly reassured that all the talk of higher interest rates in the USA looks very modest. He talked of perhaps 3 interest rate rises in 2022, but they're only 0.25% rises, which would still leave interest rates at historically negligible levels.
The markets seem addicted to low interest rates now, and I can't see them returning to historic levels any time soon, or maybe ever. Base rates don't have to be linked to Govt bond yields any more, and in any case Govts have now discovered they can manipulate bond yields to any level they like, using QE. Where it ends, nobody knows.
Powell admitted that the Fed's response to the next proper recession (i.e. 2 quarters of economic contraction), as opposed to a major crisis (e.g. 2008 banking meltdown, or 2020/1 pandemic), would be more QE - money printing, and artificially low interest rates. So even if they rise a bit this year, they're likely to go back to zero when the economy turns down.
Remember also that in 2019 (I think?), the Fed (under Powell's leadership) tried to raise interest rates, then reversed course when financial markets went haywire. So Powell doesn't have a lot of credibility when it comes to raising interest rates, or being tough. Where the US goes, the UK is likely to follow suit, hence why this is relevant.
We need to draw a distinction between inflation (which is high, and could be persistent), and interest rates. In the old days, these were closely linked. They're not any more. Therefore, with real (after inflation) interest rates now heavily negative, the only sensible place to invest is equities and property. Cash and bonds look the worst places to be, for more than a few months anyway, because the yield is now lower than inflation, eroding value over time.
I've been looking closely at the US markets in recent days, and doing a bit of trading (which surprisingly, has gone quite well). One of my aims for 2022 is to be a bit more active, and trade some positions a bit more, as well as my existing buy & hold strategy, because markets are too volatile to just sit there and absorb large drawdowns when things turn bearish.
It amazed me that many speculative, wildly over-priced, trendy US shares (e.g. Peleton, Coinbase, Robinhood, Cazoo, Docusign, Gamestop, Beyond Meat, just to give a few examples) have absolutely crashed in price. Many are 50%+ down. So whilst I've been complaining about UK small caps suffering big falls, there's actually been a savage bear market in many speculative/tech shares across the pond. I think that's very healthy for markets - scrubbing off obvious over-valuations.
I've also been looking at US mega-tech (FAANGs, etc), and it dawned on me what amazing companies they are, and reasonably priced. So I've used the recent dip to load up with big positions in Facebook (now called Meta), Amazon, and Google (Alphabet), plus a few others. Looking at the StockReports for those companies, which dominate the internet, it does make me wonder why we bother with many low quality UK small caps? It makes much of the UK market look complete dross, when you look at American companies. I'm likely to focus my personal investing a lot more on US markets going forwards, as well as UK small caps, not instead of! As we still have the occasional nugget of gold over here too.
Overall then I'm feeling reasonably bullish about the markets. Especially for re-opening trades (retail, leisure, hospitality, travel, etc), as the outlook there looks better than it's been for a while. Maybe the public might refocus on leisure activities in 2022, and less on home improvements?
There were more interesting points in Jerome Powell's answers to questions from Congress, which I'll try to type up later today, or maybe on quiet Friday. I don't pretend to be an expert on macro stuff, but I find it very interesting to follow, and it often helps me put my individual company investing into context.
We're pretty good at spotting turning points in the market here at the SCVR - e.g. we warned about covid in Feb 2020, with Graham Neary and I discussing strategies to cope (well before the big market falls) - he decided to hold throughout (which worked), and I hedged with big shorts (which also worked). Plus we spotted the market low in March, a week early, and began buying heavily. And we started buying heavily on the vaccine news c.Oct 2020. All of those things were discussed here, it's not easy to find though as the index for old reports has gone. I've asked for that to be reinstated, as I'd like to re-read the old reports around the time covid started.
For balance, what I got wrong last year, was not believing the rally, after the initial big rebound in the spring, and I lost money over the summer, by persistently (and wrongly) shorting indices, expecting another leg down, which didn't happen. Also, we didn't see the big small caps sell-off this summer/autumn coming, although we did warn many things were over-priced in H1 of 2021.
So overall, I think we've got a pretty good track record here of commenting on general market themes, so we'll keep doing it. As always though, each investor has to make up their own minds, and we're all sometimes right, and sometimes wrong. The important bit is recognising when we're wrong, and taking remedial action - with individual shares, and general market view. Being adaptable, and willing to change your mind quickly, when the facts change, is a vital skill for investors.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Portmeirion (LON:PMP)
£87m mkt cap pre market open
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands, updates on full year trading for 2021.
Revenues - a strong performance here -
We are pleased to report an excellent Christmas seasonal trading period, with very high demand for our consumer homeware brands around the world and strong sell-through across our key channels.
We therefore now expect sales to be at least £104 million or 10% above current consensus market expectation forecasts for FY21. This is 18% above 2020 sales of £87.9 million and 12% ahead of pre-Covid sales of £92.8 million in 2019. This represents the highest ever level of sales for the Group driven by strong progress on our strategy in developing new sales channels, particularly online.
Profitability -
As a result we expect our profit before tax for FY21 will be at least £7.0 million, an increase of 9% over current consensus market expectations and a multiple increase compared to £1.4 million in 2020.
What a superb statement - crystal clear, giving precise numbers, and linking performance specifically to market expectations. This is the gold standard of announcements, I wish all companies would report like this, instead of all that silly coded messaging that has historically been done. PRs and brokers reading this, please take note, and follow this simple, clear format. Clarity is what investors want. Then we're more likely to buy the shares, if trading updates are honest, clear & unambiguous.
Summarising the commentary, it says -
- 2021 sales were +12% above pre-pandemic highs - impressive.
- Profits of c.£7m are not yet at pre-pandemic highs (c.£9-10m PBT), so clearly the business has had to absorb additional costs (freight & energy, wages, I would imagine being the big ones)
- Covid still presenting “many challenges”
- Seasonal trading peak came later than usual, but “finished very strongly, particularly in the US market”
- Becoming an increasingly digital business - "opportunities for strong growth and improve margins in future".
- Key markets of UK, USA, and S.Korea all “grown well”. Remedial measures taken in S.Korea have worked.
Outlook - cautious, but sounds encouraging to me -
We are mindful of ongoing Covid risks and their potential impact on sales markets, global supply chains and the associated cost inflation, particularly in container shipping.
We expect further growth in 2022 and with the current uncertainty will wait to update the market with detail on the outlook for the current financial year at the time of the preliminary results in March.
Looking forward we continue to navigate these uncertainties and remain confident in our ability to improve margins over the longer term and grow the business strongly in the future."
Diary date - 17 March 2022 for FY 12/2021 results.
Valuation - I can’t see any broker updates yet, but working from the Stockopedia consensus figure of 37.3p, if we add 9% to that, it’s almost 41p EPS for FY 12/2021.
At 620p per share (pre market open) that’s a PER of 15.1
Given that 2021 is suffering from unusually high costs, then I think future earnings could rise well above this figure, once supply chains normalise. Combined with strong demand, maybe we could be looking at 50-60p EPS in future years? Put that on a PER of 15-20, and I have a target price of 750-1200p, thinking medium term (c.2 years). Fairly good upside from 620p now, if that bullish scenario plays out.
My opinion - this update is much better than I was expecting. I’m currently sitting this one out, as I was worried about the impact of freight costs (some product is made in the Far East), raw materials, and wage/energy inflation.
What’s good about today’s update, is that the strong demand has enabled profits to be protected, despite what must be considerable additional costs. I remember the company saying on a webinar that shipping was costing something like $20k per container, and each container had about $100k (or £100k, not sure?) of product in it. Pre-pandemic rates were about $1,500. So that’s a massive hike in cost, for product made in the Far East. Hence I was worried, and feared a profit warning - which was a logical stance at the time.
Today’s update is strong, and I’m inclined to buy back in (am not currently holding). The cost headwinds should at least partially subside, when supply chains normalise.
The turnaround strategy at PMP looks really good, especially the focus on digital.
Note there was dilution with an equity raise in the pandemic, so the share count has risen from 12m to 14m.
Overall then, a thumbs up from me, and I’ll add this to my list of things to buy on any dips in future. Although today, I would imagine a strong move up looks on the cards.
.
.
Accrol Group (LON:ACRL)
25.2p (down 18% at 09:14) - mkt cap £80m
Trading Update (profit warning)
Accrol (AIM: ACRL), the UK's leading independent tissue converter, today provides the following trading update for the current financial year ending 30 April 2022 ("FY22").
Inflation is hurting -
In the period since the Company's last trading update of 20 October 2021, the Group has experienced further inflationary pressure on input costs including pulp prices, supply chain costs and most significantly energy costs.
Action taken -
Further cost efficiencies (What? Why not done before?)
Another round of “substantial” price rises achieved with “all customers”
The company says it was on track to meet latest market expectations for FY 4/2022.
However, it’s now been hit with another wave of input cost increases, but supply chain sounds OK -
However, unavoidable surcharges to parent reel prices, relating to exceptional energy price increases, have very recently been levied on the Company, which will significantly impact margins. The management team has experience of successfully managing inflationary pressures and the Board is confident that this is a timing issue and that further cost increases, including these recent surcharges, will continue to be passed on successfully to Accrol's customers. The underlying business is in good shape and the Board remains confident in the medium-term prospects for the Group.
Despite continued supply chain disruption, particularly at ports, around the world and specifically in the UK, the business continues to manage customer supply well, having secured and maintained additional stocks in paper and finished goods.
Revised guidance - well done to the company and advisers for providing us with clear, specific profit guidance (although we prefer profit before tax & EPS, not EBITDA, here at the SCVR) -
In FY22, revenue is now expected to grow by 17% to c.£160m (FY21: £136.6m), generating adjusted EBITDA1 of c.£9.0m (FY21: £15.6m) with margin recovery anticipated in FY23.
Bear in mind this is quite capital-intensive business, so EBITDA is fairly meaningless. For example, the depreciation charge was £4.8m last year, and net finance costs were £2.0m, which if repeated this year would take EBITDA of £9.0m down to PBT of only £2.2m. The market cap is still £80m, so it doesn’t look cheap, even after the share price tanking in the last year.
Liquidity - it worries me when companies mention bank covenants, even if they say they’re in compliance, as it could be a flag that debt might become a problem in future, if trading continues to deteriorate. To be fair though, they’re damned if they do mention covenants, and damned if they don’t -
The Group continues to operate well within its existing banking covenants and has more than sufficient liquidity to meet its existing and future needs.
Strategic review - again, this makes me a little queasy -
In light of the above and the short-term but inherent volatility of earnings experienced in the current year, the Board has concluded that it is now appropriate for Accrol to conduct a full strategic review of its business. Such review will be designed to capitalise on the evident strength of the business' market position, its balance sheet, and its solvency, underpinned by significant banking support, to ensure that the shareholder value is optimised.
That’s too vague to draw any conclusions. Are they saying a placing could be on the way to reduce reliance on the bank? Or that they’re happy with significant bank debt?? I’m not sure. So I’ve checked the last full year accounts, and net bank debt was only £14.6m at 30 April 2021, which looks OK. So panic over I think. The much larger "borrowings" figures shown on the balance sheet contain lease liabilities. The company needs to split those out on the face of the balance sheet, it's a mistake to lump them together, as it scares off investors, making the company looking a lot more indebted than it actually is.
Diary date - 18 Jan 2022, for H1 results to 10/2021.
My opinion - as mentioned before, I don’t think ACRL’s business model is currently much good, because -
- Low gross margin - so there must be lots of competitors - hardly surprising when the main product is toilet rolls, a basic product where outside the main brands, competition is going to be on value (price:quality)
- Volatile input prices
- Capital-intensive - plant & machinery fixed assets were £40m book value at 4/2021 (excluding lease right of use assets) - which has to be updated/repaired/replaced over time
- Ruthless, cost-minimising customers (e.g. supermarkets)
- Mismatch between input costs & selling prices - causing wild swings in profitability
- Poor investor perception - due to opportunistic float, when unsustainable profits were being made, forecasts repeatedly missed, and big restructuring/refinancing needed soon after floating on AIM
It seems obvious to me that ACRL needs to change its customer contracts to an open book basis - i.e. a cost-plus arrangement, where selling prices mirror input costs, plus an agreed margin (and whatever cost savings can be hidden from the customer!). That would stabilise profits, and lead to the shares becoming investable.
The trouble is, why would supermarkets agree to that, if they can shop around to get the best deal, from competitors desperate to win orders and keep their factories running efficiently at full capacity?
I don’t see any attraction to this share, as things currently stand. That could change though, if the strategic review & implementation of changes, are able to give better visibility over future profits. If it got down to say 10p/share, then I might be tempted to have a dabble, but not at the current level.
.

.
Frontier Developments (LON:FDEV)
1337p (down 25%, at 11:06) - mkt cap £527m
I’ve only looked at this computer games developer once, here on 22 Nov 2021, when it warned on profits. Looking back at my notes, sales of 2 games were disappointing, and the outlook for peak trading over Xmas being uncertain.
It’s lurched down again today, so it must be another profit warning. Bad luck to holders here.
Frontier Developments plc (AIM: FDEV, "Frontier", the "Company"), a leading developer and publisher of video games based in Cambridge, UK has published its unaudited interim results for the 6 months to 30 November 2021 ('H1 FY22') and provides a trading update following the important Holiday season.
As you can see, the H1 results look poor compared with H1 LY, but I don’t know what investor expectations were for H1. The full year comparative for last year suggests a strong H2 bias to profits.

.
H1 revenue is up 33%, but profits have vanished. Looking at the detailed P&L, this is due to large increases in costs, some of which might be timing issues, reading the commentary -
.

.
Balance sheet - looks strong to me.
Writing off all intangibles (which actually do have some value in this sector), NTAV is £39.8m
Liquidity & working capital look very good, with a current ratio of 2.79
There’s plenty of cash £33.6m, and no interest-bearing debt (just lease liabilities, which are quite high at £21.4m, but only £1.4m is a current liability, suggesting it has long lease(s) that are not actually very much in annual rent (as only £1.4m in current liabilities for leases).
So a clean bill of health for the balance sheet, nothing to worry about here.
Cashflow statement - the big item is obviously capitalised development spending on new games, which is running at about £32m p.a..
For this reason, EBITDA is totally meaningless.
It burned cash in H1, despite receiving a £4.0m tax receipt, because development spending in H1 exceeded operating cashflow. The commentary says cashflow improved in early H2 as customers paid up.
Other items on the cashflow are small.
Headcount - a stand-out item, with >250 new joiners, taking headcount to 745.
That’s a lot of extra cost. Let’s hope they produce a good economic return in due course.
Outlook - provides details about the pipeline of new games, sounding positive.
But, FY 5/2022 revenue guidance is nudged down from £100-130m last time, to £100-120m now. That seems a wide range, considering peak Xmas trading has already happened.
Guidance for next year, FY 5/2023 is also reduced, due to a key game being delayed -
As a result of this scheduling adjustment, the Board have revised the revenue guidance range for FY23 to £130 million to £160 million, implying 18% to 45% annual growth from the mid-point of FY22 guidance.
Revised broker forecasts - the update from FDEV is of limited use, as it only talks about revenues. Profits matter more, but are ignored in the company’s outlook comments, which strikes me as ridiculous.
Many thanks to Liberum, for providing an update note on Research Tree.
Forecasts come down a lot -
FY 5/2022 is reduced by 19% to 28.1p EPS.
FY 5/2023 comes down 37% to 55.1p (a PER of 24 times)
The question is, should we be valuing the company’s cashflows to perpetuity just on short term earnings? That’s the big question for all share ownership.
I’m struck from the broker note how dependent FDEV is on one game - the Jurassic Park game being almost 43% of this year’s revenues, and a similar £ amount (but lower percentage) next year.
The F1 management game in the pipeline (sounds a bit like a football manager strategy game, but with Formula 1 cars/drivers) is forecast to be a hit in FY 5/2023, and would then be an annual franchise with new releases.
My opinion - I don’t know how to value this share. Earnings seem lumpy & unpredictable.
You could value FDEV on some notional value on each game franchise, so a sum-of-the-parts valuation perhaps?
Overall, this is way outside my area of expertise, but I do find falling knives difficult to resist, and am tempted to have a little punt here. Even though I don’t like the business model. Somebody give me a slap!
.
 .
Jack’s section
Gateley Holdings (LON:GTLY)
Share price: 223.5p (+2.76%)
Shares in issue: 119,153,923
Market cap: £266.3m
Following on from Knights Group (LON:KGH) yesterday, we have the Gateley Holdings (LON:GTLY) half year results this morning. Compared to Knights, Gateley has a much better track record so far of maintaining operating margins and generating strong returns on capital, with steadily increasing profitability.
Recent updates have also been encouraging, and Gateley has Knights beaten on every Rank.

Without knowing the two companies closely, that strikes me as a much more attractive selection of metrics and news flow from which to justify further research.
The group operates a ‘platform’ strategy, adding businesses to four areas:
- Corporate - corporate, financial services, and restructuring.
- Business Services - commercial agreements, managing risks, resolving disputes, protecting assets.
- People - dealing with and developing human capital, personal affairs.
- Property - focused on client activities in real estate development and investment.
This legal and professional services group was founded in Birmingham in 1808, so it presumably knows its sector very well.
Highlights:
- Revenue +23.5% to £62.3m (‘predominately organic’),
- Underlying adjusted profit before tax +14.1% to £8.5m,
- Profit before tax +19.5% to £7.3m,
- Underlying diluted EPS +16.6% to 5.76p,
- Net cash down from £9.3m to £8.8m (due to reinstatement of bonuses and dividends),
- Interim dividend up 20% to 3p.
Revenue from consultancy work has increased by 33.9% to £8.3m. Two acquisitions reported in the period: Tozer Gallagher (quantity surveyors, Property) and Adamson Jones (patent and trade mark attorneys, Business Services).
Average fee earner headcount is up from 785 to 794, with 75 new roles mandated for H2. Personnel costs were 64.1% of revenue in the period, up from 60.9%, and are expected to return to historic levels in H2.
Expected wage inflation:
In April 2020 the Group cut pay by up to 20% and froze all existing salaries until activity levels returned in the second half of FY21. However, in H2 21 all previously deducted pay was returned to staff and in H1 22 a comprehensive review of salary rates was implemented to address wider market trends in, what has now become a challenging recruitment market.
Something to think about for all of these professional services companies, which tend to have high salary costs.
Trading margins are ahead of pre-pandemic levels and operating costs remain lower, with adjusted underlying profit margin of 13.7% (H1 20: 13.3%, H1 19: 13.2%).
It is now evident that there is a permanent change to our traditional ways of working.
Momentum is expected to continue into H2 and Gateley says it is on track to meet expectations, with a healthy acquisition pipeline going forwards.
Property - H1 like-for-like revenue growth of 24.3% to £27m (43.3% of total revenue). Transactional activity has been strong and the core markets of house building, warehousing, and distribution and supported living remain strong.
People - H1 LfL revenue growth of 21.5% to £9.4m (15.1% of total).
Corporate - H1 LfL revenue growth of 47.4% to £15.2m (24.3% of total), with the legal services team in corporate, banking and tax ‘extremely busy’.
Business Services - H1 LfL revenue growth of 20.2% to £9.7m (15.5% of total). Litigation teams remain busy on long-term mandates for both UK and overseas clients.
On whether or not these Legal Services businesses should be listed companies or remain partnerships, it’s good to see the following:
Since our Admission to AIM, the Group has established a number of share-based schemes that variously offer all staff the ability to participate in early ownership of Gateley and share in the rewards of that ownership as they contribute to the success of the Group. I am delighted that 72% of current staff are now existing share or option holders in the Group. Our ability to incentivise people through plc share ownership provides an attractive alternative to traditional professional services ownership models.
COO to step down as planned, to be replaced by Head of HR Victoria Garrad.
Diary dates - Gateley is preparing a new accounting system set to go live in June. As a result of the anticipated disruption it has agreed with auditors to delay financial results until September 2022, with a full year trading update scheduled for May.
Poor cash conversion in the period - cash generated from operations was just 40% of net income (£2.4m) compared to 271.1% last year. Free cash flow fell from £10.6m to -£1.9m. The difference comes from paying bonuses after a period of reduced pay and dividends. Cash flow from operations before changes in working capital was a much better £11.4m.
The group says it has returned to its usual cash generation profile and remains debt free.
Platform strategy - the group’s four Platforms are now ‘the established growth vectors’ of the business and financial reporting is now aligned with these. Work continues to further integrate each platform in order to realise operational advantages.
Balance sheet - Net cash ex-leases of £8.8m. Intangibles and goodwill are a modest percentage of total assets (14.6%). Current ratio of 2.9x is good. Trade receivables has increased from £33.1m to £41.4m, presumably due to the active conditions. Net tangible assets are £42.3m.
All in all, a solid balance sheet that leaves the group well placed to further invest in its Platform strategy.
Conclusion
From this quick look through the half year statement, all seems well at Gateley.
The three negatives that stand out are the delayed full year results, which are well flagged (but investors have an instinctive wariness of such developments), the reduced cash conversion, which should normalise in H2, and likely wage inflation.
The group is growing with a clear strategy, and conditions are strengthening, but the shares trade on around 14.5x forecast rolling earnings with a 4.17% dividend yield.
It strikes me as decent value, particularly when set against the long trading history of the group and its habit of (so far) steadily increasing profits and dividends to shareholders, barring a bit of turbulence over lockdown-affected periods.
There’s a clear H2 weighting here, so there should be more to come in the next six months.

Management only says it is confident in meeting full year expectations today, so I’m not expecting fireworks from the share price. But potentially a decent small cap to look into in more detail.
Mpac (LON:MPAC)
Share price: 515p (0.19%)
Shares in issue: 19,894,138
Market cap: £102.5m
MPAC has an impressive 5Y share price chart, with the stock rising from 72p to today’s 514p, so no surprise to see a period of consolidation at the moment.
The Covid rebound is particularly notable.

It looks like the group’s ‘One Mpac’ strategy is bearing fruit post-Mollins disposal, with an increasingly integrated and joined up enterprise focused on organic growth in resilient markets, and complementary acquisitions.
The Board is pleased to announce that the Group has had a strong FY21 and expects to report revenue, underlying profit before tax, and closing cash in line with market expectations.
Order intake, revenue, and underlying profit before tax have all increased despite global supply chain challenges and Covid-related labour availability issues.
The strong order intake continued in H2, delivering full year growth and a closing order book of c£77.0m (December 2020: £55.5m). This, along with a healthy prospect pipeline, gives MPAC confidence on the outlook for FY22.
Contract with FREYR Battery - announced in July 2021, MPAC is developing and building a clean energy casting and unit cell assembly line. This is on track to be completed in Q3 2022.
The Group remains focused on executing its long-term strategy of developing Original Equipment order intake growth and improved margins through our Digital Services customer offering, together with increased operational efficiencies. This has led to an improved financial performance and cash generation by operating as a single entity business model.
Full year results are scheduled to be announced in the week commencing 14 March 2022.
The group has a pension scheme, which must be accounted for. At the half year stage, MPAC reported £1.6m of deficit recovery payments despite the UK scheme being in surplus to the tune of £26.8m. It’s a very large scheme for the size of the operating business - £429.4m of assets and £402.6m of defined benefit obligations.
The US pension scheme is much smaller, with total assets of £10m and a deficit of £2.3m.
Conclusion
The earnings multiple has risen slightly from what it was a couple of years ago. Back in late 2020, I recall you could buy the shares on c11x forecast earnings following its acquisition of Switchback, compared to today’s 14.5x. Meanwhile, Mpac retains that worryingly large pension scheme.
The flipside of this is that rising interest rates would be beneficial and pension contributions could decrease should the UK scheme remain in surplus. The scheme could even be offloaded at some point if the surplus is secure. Either could be a catalyst, but the sheer size of the scheme remains a financial risk.
That aside, the group has struck upon a successful strategy (‘One Mpac’) and has fairly resilient business lines. More acquisitions can be expected and the order book is up strongly, so the outlook is encouraging.
Mpac itself has had a phenomenal share price recovery and it looks like its renewed strategy is working well, while the diversification into clean energy with the FREYR battery contract win is an additional point of interest. There’s an Equity Development note out on the company this morning, which has a fair value target of 660p.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

127 comments
That's a great pre amble Paul.
Couldn't agree more on American world class businesses, have for the last few years come to that same conclusion regarding uk plc . I have read all the classic books over the years & am an avid Warren Buffett fan reading many of he's books & if i was to give any advise to the younger generation starting out it would be to focus on long term US quality companies,there's ample ETFs & Funds out there. I like to think of the FAANGs as monopolies without the regulation.
Thanks for the great pre-amble Paul. I agree entirely about the FAANGS and US stocks in general but have always thought the FAANGS looked expensive. What a mistake and my buy and hold in UK small caps last year has it worked out with very large draw downs in all the stocks I hold with the carnage helped along by Novacyt Sa (LON:NCYT) and Best Of The Best (LON:BOTB)
Where as my son’s small JISA invested in the likes of BRK JPM Fundsmith DIS V Paypal trots along nicely and returned about 16% last year with absolutely no effort.
I was looking at the S&P from when I started investing and it is up six fold and that is probably where I should have stuck my money - I’d certainly be a lot richer than I am now.
It is my intention to continue to be invested in UK small caps but halve my exposure over the next 12 to 18 months and increase my US exposure through S&P trackers and some individual large caps.
I see no point in going through the emotional (for me) roller coaster U.K. small caps when the returns from the S&P are in the end simply better.
This was published by Charlie Billello in late November so a bit out of date but gives an idea of the carnage in a lot of tech stocks.
Regards
Michael
Hi Michael, couldn’t agree with you more about the US. Compared to must I am a novice but felt for 2022 exposure to the S&P 500 via an ETF a good point to jump off. Can I ask which junior ISA did you select for your son? I have been thinking some time for my seven year old.
Volex (LON:VLX) - sorry to upset the fine china and hand sanitiser chat - but why is a supplier to EV future and bullish here sinking like the Titanic.
Hi Garry
On Volex (LON:VLX) I hold and my 8th largest holding. I can only assume that it has just been hit by the general sell off in small caps over the past 3 months/one year. All of my holdings except Somero Enterprises Inc (LON:SOM) (which I only bought a few weeks ago and is my smallest holding) are off between 19% (Mpac (LON:MPAC)) and 68% (Boohoo (LON:BOO)) from their one year highs. Very painful for me but I believe also irrational.
Volex I only started buying in January 2021 but Volex probably needs in the context of its overall performance. It is up, even after the 37.4%, fall from its one year high, 554% in the last five years.
I am not selling as I believe the sell off in all Small Caps has been over done. The drawdown has dented my confidence but being 20.4% cash I am in a position to buy some of the stocks that have been hit over the past few months.
I just need to find the courage to press the buy button!
Regards
Michael
I just did a dummy buy of a USA share on Youinvest and was quoted a price @ 6:40pm
IKBR - trade for $1d and spreads are cents and instant fills. Tiny trades so a newby. Play more than one or two platforms and markets to spread the risk - it's all about TIME. Protecting your Capital is your prime responsibility - with some fun attached.
Hi slopsjon
I did the same. I was wrong when I commented earlier. I’ll update the comment.
Dear SCVR,
Well, are USA markets all that cheap.
No is the answer according to Bufferology indicators from https://www.gurufocus.com/glob...
The USA is expected to return an average of -2.9%, the best returning developed market is Singapore, and the best Emerging market is Egypt. Hell Good old UK is better than the USA for an investment today. The USA looks like a crowded trade and a bit long in the tooth now
I do like the look of Egyptian returns and decided to open a long position recently.
As always DYOR.
BSV
Isn't that only if you're buying the whole market by buying an index? Individual companies represent different intrinsic values and analysing a company to find value is what this blog is mostly about. The indicator highlights that finding companies in the US could prove difficult - and most of what I am watching is too expensive for me - but there are many rocks to look under and something will be there. I just think I have to turn over a lot of rocks.
Yes, you can buy Etf for the whole market, Vaneck Egypt Index. Link below.
https://www.stockopedia.com/et...
BSV
My favourite budget cornflakes have gone up 20% in the last few months, from 50p to 60p per box, via. 55p. That would make me very nervous about exposure to Egypt, which seems to be prone to outbreaks of disorder when basic foodstuffs go up in price.
"I do like the look of Egyptian returns and decided to open a long position recently.
As always DYOR."
Well hopefully you've done your research on all of the constituents of The Egyptian Exchange.
Out of interest, what ROCE does Cairo Oils & Soap earn? And what is the 5 year Sales cagr of El Shams Housing & Urbanization?
Thanks in advance.
I've gone long on the whole market. not looked at individual share. Looking at the UK market takes a long time. Stock picking in another market would take twice the time, and I'm not sure it would improve returns.
BSV
Hi Paul, more enjoyable reading today from your reports as always. I've not had time to read all yet, so apologies if I've repeated anything someone else may have said.
I've only read the Frontier Developments (LON:FDEV) report so far and upon reading the initial header notes for it, I immediately thought about a slap for you, then saw your final note saying to slap you. S here goes.
First off I am not invested in Frontier Developments (LON:FDEV) though I have been in the past. My attention was bought to this company quite a few years ago and I was an initial funder, via the funding to get the game Elite made. You may remember this game originally released back in 1984 on the BBC computer. The CEO of Frontier Developments (LON:FDEV) David Braban was one of two people who wrote the game back then in their University days. The other was Ian Bell.
So, a little history out of the way, Why would you buy this today? As they say, NEVER try and catch a falling knife!
This is the second profits warning and how often is a third warning given. PE is still high 20's and the company is still very highly priced to the rest of the market. The amount of shares in issue is low, being just 40m, which can cause big movements of the share price.
On the plus side, todays drop hit support level, but still I see this dropping in time further, and I wouldn't be surprised to see the SP hit somewhere between 950 and 850.
Like many other companies, Frontier Developments (LON:FDEV) has benefited from Covid but this, like many others seems to have been a one off and the share price reverts back to the March 2020 level.
I do like this company, but I try not to be emotional about it. Sales will always be lumpy, depending on release dates for the games. There is no dividend either, which imo means the SP will be more volatile and when a SP drops it is often hard for it to stop.
Anyway, just my 2p worth. Keep up the good work!
Re Frontier Developments (LON:FDEV) - it certainly looks like a falling knife and one I'm relieved to have sold out of on the first profit warning. But this could be a good investment one day in the not distant future. The company owns decent franchises and has a good record of new launches, recent execution problems aside. It's hard to value the shares on earnings right now but on an EV/Revenue basis the shares are very cheap relative to mature competitors like EA Sports at a near 40% discount for the NTM and are at a mere third of the price of more appropriate, if more profitable and currently better managed, comparison Team17.
Is a third warning likely? It's definitely possible because this TU did not have the feeling of a kitchen sinker - more a pray for better luck! I'll be watching with interest as I think there's a good business in there going through a hopefully temporary tough period.
I agree it could be a good buy for the future but catching a falling knife is dangerous. Inevitable shares continue to fall after profit warnings so better to wait generally, or just buy a small position and add ad it drops further.
With F1 Manager coming out this year, and the Jurassic World film coming out (which could re-boost sales of the Jurassic World game), do you think now could be a time to buy FDEV?
On the other hand, here is a company which has invested in increasing its staff by (~250) one third to harness their ingenuity in creating future products, at the expense of profit today. Seems quite ballsy to me. That’s a lot of interviewing!
Adding 250 in a tight market is a distraction to the people trying to build the games. The games aren't good at the moment - I think this is a long term slide. Costs rising, quality falling on the product side. There are better choices for new staff to go and the franchises are stale. It will take a lot to revitalise, if they can only recruit those available at an unsustainable rate, then the talent pool is diluted. With falling share option values for the older and higher skilled staff - they will be tempted into companies that are in the ascendancy rather than hope product improves with an inexperienced enlarged team - I think the share price will tickle the 2019 levels of 750 in the next year.
Very good today
Excellent
Hi Paul,
Excellent pre-amble this morning !
It has got me thinking along with reading other subscribers comments below, and I have come up with maybe holding a lump of
BAILLIE GIFFORD AMERICAN CLASS B - ACCUMULATION (GBP)
It has made 216% in five years and at one point it was up 340%.
I have resisted holding the American dream stocks as I thought they were unlikely to be able to carry on motoring, but I am thinking you may well be right in that this could be a good entry point.
best regards
Neville
Hi Neville,
Just my tuppence worth, but I'd be a bit cautious about getting into the BG US Growth fund at the moment.
Similar to Cathie Wood's ARK fund, they invest in US growth names, which normally carry speculative valuations. There seems to be an ongoing rotation of capital from growth to value, so BG and ARK have both taken a hiding.
I was invested in BG last year, also attracted by the sterling performance which was incredible - but looking at the chart now (weekly shown below), its in something of a no-man's land and may take some time to establish an uptrend again.
Of course, I could be wrong and it will start moving up again imminently, but IMO its a risk buying in here.
Hi Breakout,
Thank you for sharing your thoughts and opinions on if now is a good time to invest in BG American.
I think you are probably right on the downward trend due to the rotation of G to V.
But medium to longer term I do not think it would be wise for us UK small cap investors to bet against the US dream ending any time soon., I used to but Pauls thoughts this morning got me thinking, and I thought that building a lump of BG American over time by 'pound cost averaging' may be a sensible thing to do.
After all the community here are very impressed if any of us can average 17% to 18% per year over 5 years in UK small caps, which takes hours and hours of research, reading, knowledge, patience, controlling our emotions and risking our money. So maybe 15% or 20% of our portfolio in something like BG may just be a sensible helping hand?
regards
Neville
Im in UK and US but not Europe and Asia. Not sure how to get there outside of trusts and funds - maybe the safest option. How many hours in the day is the - biggest problem.
Honestly, the main reason I subscribe to Stockopedia is for for these daily updates. Excellent analysis, v. much enjpy the macro outlook too.
best,
C
How kind, thank you. Jack and I very much appreciate subscriber feedback! :-)
Best wishes, Paul.
Thanks for the focus on the US market today. I've been alluding to the silent bear market in the US in any of my end of year/performance posts recently. I hold a large proportion of growth stocks and a 60% weighting to the US, so, as a non-trader, I've suffered substantially, with indiscriminate drawdowns of 30%-50% for all but the most established tech giants. Even huge cash machines like Intuit and Adobe are down more than 20%.
However, the sell-off has been, as I say, indiscriminate, and some terrific growth companies look a lot more attractive now. The point about the US is it's the only market in which an investor can address mega-trends at scale. Software is eating the world and produces prodigiously cash-generating businesses with incredibly sticky moats - think Autodesk, Adobe and Intuit. A look at the share performance of these names over a decade ought to be serious food for thought for value investors. Yes, central bank support has juiced share prices but look at the astonishing fundamental performance of the underlying businesses.
Today we are experiencing powerful secular trends that can be played by participation in US growth companies with prodigious cashflows and powerful moats, acknowledging that valuations will still raise more than eyebrows amongst value-followers here, even after recent falls.
Artificial Intelligence (NVDIA, Alphabet, Facebook/Meta)
Cloud computing (Microsoft, Amazon, Alphabet, Cloudflare)
Digital Transformation (Application specific - Adobe, Salesforce, Intuit, or picks and shovels - Datadog, Dynatrace, Elastic)
Cybersecurity (Crowdstrike, Palo Alto Networks - balanced value share! Zscaler)
Metaverse (Unity, Roblox, Facebook/Meta, Adobe)
Big Data (Snowflake, Confluent, Palantir)
Hybrid working (Atlassian, Asana, Smartsheet, Monday)
Adtech - (Alphabet, Trade Desk, Ironsource, Digital Turbine)
And the glue that binds these themes together as highly investable is the move towards SAAS, where many years of revenues are contracted into the future, giving incredibly stable AND predictable revenues. Hidden in the quarterly accounts of a SAAS company is something called the RPO (remaining performance obligation) and its companion metric, the DBE (dollar-based expansion) rate. Together these measure the value of forward contracted orders and the rate at which existing customers increase spending year-on-year. They form the closest thing to a crystal ball that management and investors have ever had access to. If you are looking for winners, dig into these two ratios.
As a former business owner and someone who has twice carried out a full digital transformation of an enterprise, I cannot shout loudly enough about the benefits it has delivered nor the commitment to ever increasing operational spend as a trade-off for the welcome fall in capex that the cloud has wrought.
Sub-FAANG, every one of these is down 40% on average on a rotation to value. I'm not calling the bottom but some analysts, admittedly with skin in the game, are describing the sell-off as overdone.
As for big tech being expensive - hilarious!! Alphabet and Facebook/Meta are cheaper today than they have ever been. After 50- and 10-bagging respectively within a decade!! I actually think most UK investors just assume FAANG is pricey without bothering to look at the data. These firms own the world we live in and are amazing "money fountains" valued at the S&P 500 average!!
Hi BnB,
You said silent bull market. The context suggests you meant silent bear market?
Regards, Paul.
Corrected. Well spotted Paul. I’m obviously feeling positive today!
Well said BnB. You named 12 of my stocks there, so I hope you continue to be right!
Hi BnB
An excellent posting categorising some of the important growth and innovation US stocks.
I thank you for your helpful paragraph about two key metrics .......
And the glue that binds these themes together as highly investable is the move towards SAAS, where many years of revenues are contracted into the future, giving incredibly stable AND predictable revenues. Hidden in the quarterly accounts of a SAAS company is something called the RPO (remaining performance obligation) and its companion metric, the DBE (dollar-based expansion) rate. Together these measure the value of forward contracted orders and the rate at which existing customers increase spending year-on-year. They form the closest thing to a crystal ball that management and investors have ever had access to. If you are looking for winners, dig into these two ratios.
I will investigate these further.
Regards
Howard
Howard - if you want to explore SaaS valuations a bit more, I'd highly recommend Saul's Investing Discussion board on the Motley Fool boards - this link gives an overview of some of the key points but there are lots of other posts
https://boards.fool.com/my-tho...
Re: Inmode
This is a case of their technology being superior to the competition (patent protection) and the stickiness (switching costs) then begetting consumables sales - like Intuitive Surgical if slightly less life-critical.
The magic is in the fundamental ratios: ROCE 32%, gross margin 85%, EBIT margin 45%, FCF margin 45%. Throw in growth in excess of 20% (historically far higher) driven by a secular trend of people curating their online image in social media.
A comparable mature medtech (ISRG, MASI, ABMD) with sub 20% growth and strong but inferior operating numbers is on a 2022 p/e of 60x. InMode is on 26x.
Umpteenth upgrade in this morning's earnings report.
Hi BnB
I think that reply was intended for me.
I must admit to doing very little research on $INMD so I know very little about their patents or how strong they are. Nonetheless their top line growth is very good and as you point out their financial metrics are excellent, no doubt what attracted me to investigate it in the first place.
On many occasions I have a tendency to overthink company prospects, and perhaps this will prove to be one of those instances and I will miss out on something special.
Incidentally I was fortunate to buy into one of the shares you just mentioned, albeit towards the end of its rapid rise a few years ago - Abiomed. Perhaps if I'd see the opportunity earlier I would have done even better on this one.
Thanks again for the insight and best of luck with Inmode.
A
Hi Charlie
Many thanks for the SaaS valuations link. I will explore it.
Regards
Howard
two key metrics
Thanks Howard. They really are a gift, even if the extra visibility is often baked into the price. When the market values a stock based on conservative management guidance but the RPO and DBE suggest revenues will be much higher, it's analogous to a value investment - albeit at much higher multiples - at least until the name overshoots. Cloudflare in 2021 is a good example. Management and the market said 30%, the metrics said 50%, which is how the revenues turned out. The overshoot and subsequent fall is another matter!
Hi Paul. Many thanks for you thoughts on the US market. My returns have been excellent over the last 4 years with 40 % in US shares. I subscribe to the USA Stockopedia and HL are good when trading. I would love your views on the US market occasionally as, over the long term, the American markets have out performed ours. A US blog would be a great addition. Thank so much for your ongoing thoughts.
Does trading US stocks require a specialist platform that is open when the US markets are open? If so what is the cost?
I have tax efficient SIPP and ISA with AJBell but I don't believe I can trade after 4.30pm. I've been caught out previously when the US markets have made big moves after the UK market has closed so I am cautious when investing in US.
Revs8. I think IG index are pretty good with their trading hours
My provider is completely flexible and deals with Us stocks easily at similar costs of the uk - just an extra tab for us picks so practicably other than the "currency issue" it can be simpe if you have decent provider.
Practicably speaking i have found us stocks and isa dont mix very well as you cannot hold us dollars in an isa (is there a way around that? i think not).
As my us stocks mix has increased i have ended up having an abormal split of us holdings in my sipp - this avoids any currency translation costs as long as i am happy to retain dollars when i sell a share and keep those dolars till i buy my next us holding. Even Somero Enterprises Inc (LON:SOM) has ended up in the sipp due to the ability to receive dividends in full. with no tax leakage I am not convinced having such a lopsided approach ref splits is totally sensible but being within 5 yars of 55 and treating isa's and sipps as pots of cash for some funin the not too sistant future it works for me. What does put me off is the forced extra % paid if you do go down the route of buying via isa or any other platform where you need to convert currency just to trade and potentially they get the fee when you buy and when you sell.
Note ref timing issues most us companies tend to report before open or after close of us so there shouldnt "normally" be much time sensitive stuff reporting wise after the close of the uk market if you like to switch off at 4.30 pm.
Really AJ Bell, you can't trade after 4.30pm even US shares? Can't believe that.
I use Ig Group (LON:IGG) ISA, no fees if you do 3 trades in previous month and then 0.5% forex fee, which is good if doing smaller trades.
I have used HL in the past but they are expensive for US stocks.
AJB are supposedly becoming more trader orientated - still waiting.
You can trade through AJ Bell in USA though I believe it is online only from 7:00 -9:00pm according to their website. However, in addition to the £9.95 commission there is also an FX charge (sliding scale) which mitigates against significant trading. I suppose one benefit of using AJ Bell for USA trading is can reduce/eliminate dividend tax if held in SIPP (provided completed necessary form - available on their site). A better option though one that means you lose the tax shelter of ISA & SIPP is to set up a U.S. commission free trading account with the likes of Charles Schwab. There is a minimum funding level of $20,000 (could be $25,000) and you would still have FX charges when converting sterling to dollars and vice versa but these days there are plenty of options that offer much better rates than the high street banks.
That's weird re AJ Bell US trading hours. Halifax, ii, and HL all let me trade while the market is open. I would never have thought to even question it.
hi all.
I was wrong about buying US stocks on Youinvest. You can buy them after the UK market closes.
I just tried buying a apple at 19.20 and was given a price. I suspect my previous problem was buying UK based derivatives which close with the UK market.
Hi Revs8. You can trade the US market using iweb or AJBell with no issues. They will require you to complete a not very onerous tax form w-8ben.
It feels like there is some demand for more US market commentary and discussions, so to kickstart things, I've just started a new discussion encouraging the sharing of ideas of US market research resources. I've shared a list of the sites and services I use to research and generate investment ideas in the US. Hope it's useful!
Thanks Charlie, that's really helpful to flag up sources of info on US markets. You forgot a link to your own post! So here it is:
https://www.stockopedia.com/co...
A question from me. What is the US equivalent of investegate, or the RNS on the Stock Exchange website, for company live news, please?
I can get quarterly earnings reports on US companies from their own company websites, but what I need is a newsfeed, so I can see what companies are reporting, in real time. Any ideas what site people use?
Thanks, Paul.
Thanks for linking my post Paul!
Good question re: RNS's. I've set up alerts on Stocko and Seeking Alpha for the companies I'm interested in but I imagine there's a better way of doing it. Possibly directly from the SEC (https://www.sec.gov/edgar/sear...) or there are sites such as Koyfin (https://app.koyfin.com/home) which have a free and premium service that I imagine would be able to provide this.
There's also the Quatr app which provides all earnings calls and transcripts - mostly US companies but also some big international companies. If you put a watchlist in there, I think it flags all upcoming announcements.
Not sure if that's much help but let me know if you find anything more useful.
Thanks, Charlie
Paul,
I set up a portfolio on seekingalpha.com. That generates articles that I send to a dedicated folder in my e-mail. You get quarterly earnings call transcripts and links to presentations.
The SEC portal for company filings is called Edgar. https://www.sec.gov/edgar.shtm...
There is equal access to information for all shareholders under the US Fair Disclosure rules - very much lacking in the UK.
https://en.wikipedia.org/wiki/...
I can get quarterly earnings reports on US companies from their own company websites, but what I need is a newsfeed, so I can see what companies are reporting, in real time. Any ideas what site people use?
Seeking Alpha is pretty good site for news if you subscribe £25 a month. You can sign up for news alerts on your watchlist. What you can’t get is broker research, although the site is full of analysis from the investor community, many of whom claim to be CFAs.
I’ve looked long and hard for alternatives but the only other feed I subscribe to is from Refinitiv (via Metastock Xenith) for about £1500 pa - a sort of poor man’s Bloomberg terminal - which provides broker upgrades and global stock updates like earnings releases as well as comprehensive fundamentals on every listed firm in the world. Sadly, this extra expense has not made me noticeably richer - except in Japan - but it does fill in a lot of gaps.
Away from IT there is good value in US small caps right now. Try $INMD for very high quality growth at a reasonable price. Priced at half the medtech average for its fundamental profile. Earnings just out today.
Hi BnB
Thanks for your posts today, most insightful.
I decided to look at $INMD based on your "reasonable price" comment and chuckled when I saw that I had already looked at it about a month ago and had made the following note:
"Expensive! And I don't understand what's so great about it. Can a competitor come in and take their market?"
I did actually watch a youtube video on the procedure at the time of my research (posted below) and was assured by my partner that this product would appeal to many people (I personally didn't get it.)
Anyway, sadly not one for me despite the remarkable growth.
---
On a separate note, for those who don't want to sign up to seekingalpha, but want unlimited access to the quarterly call transcripts (why can't UK companies do the same thing?), Fool.com offers these without restrictions now, eg this one: https://www.fool.com/earnings/...
Cheers
A
I get the news alerts from Seeking Alpha on a free account.
Couldn't agree more about the quality and value of the large US tech stocks. I think Polar Capital Holdings (LON:POLR) offers a good and very cheap way to get exposure to this sector.
With asset managers you indirectly get exposure to the assets they hold. Just under half of Polar AUM is in tech, and they are very much focused on the quality larger caps (and avoiding the speculative, high priced stuff). It's on a PE of around 10 and seen consistently strong AUM growth so looks very good value to me.
Hey Bouden
Did you mean Polar Capital Technology Trust (LON:PCT)? I hold Polar Capital Holdings (LON:POLR) as I like the FM sector, though since hitting £9 this one has dropped considerably. Their Tech trust has been their star for years, and healthcare popular too but not such good performance.
I was actually referring to the fund management company Polar Capital Holdings (LON:POLR) as I think it's a great company at a very cheap valuation. Polar Capital Technology Trust (LON:PCT) is of course the one to go for if you want pure tech exposure, but as I say the fund management company has around half its assets in tech so this gives good indirect exposure.
Yes, would welcome more input on US stocks. An insightful short Economist podcast chronicles the decline of UK markets with emphasis on lack of decent IPOs https://www.economist.com/brie... Couple of extracts from the printed word (subscriber only I think):
''A shame, then, that those heady years in the run-up to the global financial crisis set a high-water mark for Britain’s equity market. A decade and a half later, any pretensions the City once had as the world’s stock exchange have been dashed. Its share of global ipos has dropped by a factor of five, to 4%, and the number of companies listed on it has fallen by 40% since the peak in 2007. As a share of the global equity market, and even of the sclerotic European one, the value of Britain’s has dropped steadily (see chart 1).,,,,,
Meanwhile, missing out on the biggest and most exciting ipos has left Britain’s equity market looking more like yesterday’s world than tomorrow’s. The ftse 100, an index of the largest companies listed on the lse, is stuffed with the shares of miners, energy firms and banks. It is much lighter on technology firms, which account for less than 2% of its value, compared with 39% for the s&p 500, its American equivalent.....
The result of all this is a vicious cycle. If London’s equity market puts a lower value on companies than its peers do, firms with bright prospects will choose to list where they can sell their shares for more cash. The absence of exciting flotations then begets a sagging stockmarket and continued low valuations. High-performing firms whose share prices are sullied by association with laggards then make for attractive targets to be picked off by private buyers. And so the cycle continues.....
London is also being outclassed by foreign tech clusters. Compared with its international rivals, the City’s regulatory environment is less friendly to tech founders seeking to float their company without relinquishing voting control or forcing their early backers to sell large chunks of their shares. It also lacks New York’s deep ranks of analysts who understand tech and fintech firms well enough to value them properly. Fairly or not, the drubbing handed to Deliveroo at its ipo earlier this year reinforced the impression held by many that London’s investors are simply too hostile to tech companies to bother with. “If I’m a fintech founder looking to ipo, why on earth would I run the risk of getting treated like Deliveroo when I could just go to the Nasdaq instead and be welcomed with open arms?” says one tech lobbyist.''
Meanwhile, we have today Mr Smith's widely reported Unilever-bashing in the Telegraph https://12ft.io/proxy?q=https%...
Investment star Terry Smith attacks Unilever for ‘ludicrous’ focus on social and environmental issues
Consumer goods giant should spend more time worrying about profits than purpose, according to the Fundsmith Equity fund manager
Agree, this was a gem from plain speaking Terry Smith. So I am repeating it below. Hope tick boxing companies and fund managers plying their sustainability credentials because they think that it’s what investors want to hear, will take note
Unilever seems to be labouring under the weight of a management which is obsessed with publicly displaying sustainability credentials at the expense of focusing on the fundamentals of the business. The most obvious manifestation of this is the public spat it has become embroiled in over the refusal to supply Ben & Jerry’s ice cream in the West Bank. However, we think there are far more ludicrous examples which illustrate the problem. A company which feels it has to define the purpose of Hellmann’s mayonnaise has in our view clearly lost the plot. The Hellmann’s brand has existed since 1913 so we would guess that by now consumers have figured out its purpose (spoiler alert — salads and sandwiches). Although Unilever had by far the worst performance of our consumer staples stocks during the pandemic we continue to hold the shares because we think that its strong brands and distribution will triumph in the end.
Hi Paul,
Thanks for your preamble. In my opinion predicting general market directions is orders of magnitude more complex than analysing individual shares, which is why you can ask 10 “experts” for an opinion and generally get 10 different responses.
Like you I am positive about the prospects for small cap stocks this year in particular those that are set to benefit from re-opening themes. However, I believe some of your statements are definitive when they could be more nuanced. In particular:
“We need to draw a distinction between inflation (which is high, and could be persistent), and interest rates. In the old days, these were closely linked. They're not any more.”
I personally read that inflation and interest rates are temporarily dislocated and the reason is explained when you said: “The markets seem addicted to low interest rates now…” I agree they are and our political leaders are terrified of derailing the recovery-gravy train.
You also said “and I can't see them returning to historic levels any time soon, or maybe ever.” I would ask if we need historic levels of interest rates for it to cause panic in the markets? Signs of interest rates failing to tame inflation will be enough.
For macro economic commentary I like to read the words of Mohamed El-Erian https://www.linkedin.com/in/mohamedelerian/ (for a global / US perspective) and Roger Bootle https://www.telegraph.co.uk/business/2022/01/02/surging-inflation-will-define-2022/ (for a more UK based view).
Both are well versed in macro-economics and are cautioning against central bank complacency and highlighting that labour and fuel prices are rising rapidly and unlikely to come down soon.
I’m not saying disaster is just around the corner (I’m fully invested, mostly in re-opening small caps). But I do caution that fuel and labour price rises are going to persist and lead to structural inflation and at some point governments will be forced to act. When this happens the markets are going to scream and we are likely to see significant turbulence.
Decent updates from Portmeirion (LON:PMP), Dfs Furniture (LON:DFS) and £DNLM.
Hopefully Sanderson Design (LON:SDG) follows suit!
Yet another great preamble from Paul today!
Guess most here know this but in case a few don’t CNBC Channel 210 on Freesat covers the US markets for many hours each trading day. A good time to watch it is just before the closing bell (2100 hours UK time) and then the first section after that. There is loads of comment too. Wilfred Frost (son of David) is key presenter most days, but nearly all the others on the programme and the commentators invited on are Americans.
It was while watching CNBC that I discovered how SO many NASDAQ shares especially have been falling heavily even on days when the index has held up or even gone up. One day recently 612 Nasdaq shares fell to 52 week lows. So it seems it really is the very big names on sometimes very racy ratings that are hiding a very different story underneath.
Hi ken,
I also like to have CNBC on in the background (not in the morning though, as I'm too busy here!), as it's very useful for background info, and I agree with everything you said.
It's such a pity that Jim Cramer trivialises the tone & peoples' perception, of what is otherwise a very good channel, with his fake eccentricity/unfunny humour. Such a plonker, which is a pity, as he's very knowledgeable.
CNBC does have some excellent interviewees, and commentators, although obviously a lot of it needs to be taken with a pinch of salt.
Did you see that bitcoin fool on yesterday? Absolutely hilarious - young, wearing a baseball cap, talking about how he was going to change the world with crypto, total certainty that prices were going up forever. Another marvellous reinforcer for my sceptical view of the value of blockchain tokens (which is nil, in my eyes).
Regards, Paul.
Good solid trading update from Mpac (LON:MPAC) which appears to be a really well run company in a good market niche that is thriving both in the US and Europe.
Numbers all in-line and closing order book of £77m means next year is already 75%+ covered. A PE of 14 doesn't feel expensive and 10% of market cap is now net cash so balance sheet is strong.
I think the contract win with FREYR Battery back in July 2021, should prove to be very positive medium term. They made good progress in the development and build of the clean energy casting and unit cell assembly line and remain on track to be completed in Q3 2022, so should see revenues starting to come through this year. This could end up being a big division of the group I think but nothing really priced in for it.
It amazed me that many speculative, wildly over-priced, trendy US shares (e.g. Peleton, Coinbase, Robinhood, Cazoo, Docusign, Gamestop, Beyond Meat, just to give a few examples) have absolutely crashed in price. Many are 50%+ down.
That's putting it mildly, I've posted before that there has been large falls in individual stocks in the U.S. One week into 2022 and a staggering 40% of all Nasdaq stocks have fallen at least 50% from their 52W high. That's usually bear market numbers.
This article has an interesting chart in it from Sundial Capital research (click on it to enlarge it).
https://www.bloomberg.com/news...
I too would like to see a US focused blog as most of my research is now using my USA subscription. Like Paul says the market is huge with great liquidity. $10bn companies over there can be as exciting in growth as £10m companies over here but with probably less risk.
Hi unwise2,
I've posted before that there has been large falls in individual stocks in the U.S.
I couldn't remember who flagged up this issue here, so many thanks for this. I was amazed at the situation when I did some work on it this week.
Regards, Paul.
In my view need to be careful buying the big stocks like Apple, Microsoft, Meta etc. now. US market is at a turning point with as you say many of the lower tier growth stocks already corrected. Question is do we need to see bigger falls in the mega stocks too before market stabilises? Time will tell but I am personally steering clear of growth stocks until picture becomes clearer.
I think there has been a stealth bear market in the US for a while, indices have been held up by the behemoths.
I for one would like to see more coverage of the US markets. It's where the biggest opportunities are - the biggest companies, the most liquidity, the bigger moves.
I pay for access to the US shares on my Stockopedia subsription, but apart from the stock data and screening, there is no real commentary or coverage - I think Stocko is missing a trick there. There's lots of interest this side of the pond in US equities.
An SCVR-type blog on US stocks would, I think, be very popular.
I also have US subscription and believe a US blog is certainly a gap in the service offered by Stockopedia
I would probably subscribe to the US section if there was such a thing.
Completely agree, a US version of the SCVR would be a great addition. I don't subscribe to the US shares access here but I would do if there was some regular blog commentary on US stocks.
I agree, a US equivalent to the UK SCVR would be great. The US is such a large and liquid market and is currently about 60% of the global stock market, so you can't really ignore it even if you want to. Also, I know FX charges etc. are a pain, but it has so many great companies listed that UK just don't have equivalents to, sad to say.
Plus, the long term return of US stocks is like 2-3 percentage points higher than UK (i.e. a lot over time!), and of course the pound has been declining against the dollar since 1775 or so... S&P500 did 27% in 21 vs 14% for FTSE100 - a large difference.
The FX charges are a pain, one way to avoid them is by spreadbetting, which I use to trade US stocks in my IG account.
The only caveat is that for spreadbetting it's really necessary, in my opinion, to use stop-losses and having tight risk management which isn't to everybody's liking.
Another way to avoid FX charges is to open an account with a US based online broker and deposit USD into that account and leave it there. If you are buying and selling US stocks, why incur FX charges and spreads each trade?
M Winkworth (LON:WINK) Another profit upgrade, special div, and commentary on the London property market.
Are there any suitable trackers / ETF's that people are aware of to provide exposure to FAANGs?
Maybe Vanguard Mega Cap Growth MGK , but someone might suggest a better one.
I went for Vanguards VUSA for my first ever toe dip into the US market S&P 500. Added to my portfolio for 2022.
I really love reading you preambles!
Loving the preambles. My favourite part of the blog by far.
Paul, if you believe that Facebook, Alphabet, Google valuations are sensible then you must surely agree that Alibaba stock represents even better value!?
On the numbers Alibaba is phenomenally cheap but regulatory risk is unlimited in my view.
darren23,
you must surely agree that Alibaba stock represents even better value!?
No, I don't touch any Chinese stocks, ever. Way too much risk for me.
Regards, Paul.
darren23
then you must surely agree that Alibaba stock represents even better value!?
Have you even looked at the stuff the chinse government have thrown and continue to throw alibaba's way - and are you fully aware that you probably dont actually own shares in main trading entity when you invest here?. Alibaba may be decent value on metrics if you ignore all the huge red flags -but surely the huge red flags are the reason why the shares appear "value".To me its reasonably evident the vast majority of the money making machine here thats "flows through to holders of promisary whatevers" can only exist while the chinse government want to allow that situation to continue. They could think of any excuse tomorrow to remove current holders from any of the china relate benefits - or reduce the cashflow proportionately at will to make life tough. It might come to pass that china has extracted their pound or pounds of flesh fully now and will leave them be - but i certainly wouldnt presume this is the case. I have no problems anyone saying they are worth the gamble - just dont moan if chian do what they do ref this company. I kind of think its easy for china to play shrewd here and let the current situation play on as it is for as long as they want al we know if they have the "nuts" when it comes to the impolrtant future decisions ref share ownership in that country.
One of the issues raised with the 'desperateness' or innovation (if you prefer) of US stock markets, advisers and all the other interested parties, was that they were prepared to help shape the Alibaba float, as this was a move away from a shareholder structure per se, to one where there were instead something like an entitlement to share in the profit income of Alibaba. Leaves the Company very much in the hands of the Chinese State, which limits foreign control, taking an indulgent view of such arrangements continuing.
Paul, its always great to read your preamble, and even more so when you talk about the US market. Half of my portfolio is with US stocks.
I look forward to hearing more of your thoughts from across the pond in the future.
Take care,
S.
Re Portmeirion (LON:PMP) - Super trading update this morning with sales at £104Mn (+12% vs 2019, +10% vs consensus) and profit of "at least £7Mn" (+10% vs consensus). All key mkts up (US, UK, S Kor) and shift into digital going well. In short, everything I wanted to hear on my second biggest position.
The only 2 notes of caution was that no fct will be given for 2022 until March full year results, with company citing Covid and continued container cost uncertainty. Plus some of the sales rise is simple cost pass through in the short term, hence no profit leverage. However, I think they were previously over discounting so I think the pricing can stay as the 'excess' supply chain costs on importing fade.
I really think the new-ish MD has got the business strategically and operationally right now, with costs under control (gas contract fixed through to '24 I think, automation reducing costs) but most importantly better products being sold better and increasingly from high-margin company-owned websites into better managed key markets.
I am an ex-Mkt Dir and used to be frustrated that is an inherently gift and collectibles business, perfectly suited to direct to consumer selling but was so old fashioned and poorly executed online. Recent hires have really upgraded the online operation and I am very optimistic the progress can continue.
They never publish a breakdown of sales by brand but I hope that recent acquisitions Wax Lyrical (4+ yrs ago and an under performer) and Nambe (bought just before Covid) might now be starting to deliver, having previously under-performed. Nambe + full control of the Canada JV + website upgrades + headwinds for dept store retail abating (as so few left to die and the remaininder have improved) mean the US will do really well this year with a much stronger, integrated operation.
Share is very thinly traded and was diluted during Covid but I think can go significantly higher, based on fundamental and will resume generous dividends from next year (this year still modest). I will be adding more up to the maximum % I will hold on any one share.
Portmeirion (LON:PMP)
Zipmaster
. Plus some of the sales rise is simple cost pass through in the short term, hence no profit leverage.
I think you have hit the nail on the head here Zipmaster - in some respects taking figures at face value its very dissapointing if the sales are that much ahead of expectations that less than 10% of the "cream" has flowed through to profits. I am not going to over criticise them here but perhaps flagging up higher expected sales and higher expected costs back in november would have been more transparent - it seems obvious to me they must have known the extra costs existed back in november. The alternative is that if they had not secured the extra 10 mill of sales they were "not expecting" then we would have had the mother of all profit warnings here - i kinda guess internally they probably knew they would be ok? - thats a big presumption on part though with high seasonal sales here at year end.
Overall though the end result is very acceptable i will give them a pass ref my personal minor quibbles above - they cant have had any easy job forecasting anything last year** and the lack of the extra "unexpected" (expected?) sales flowing through to the bottom line has reasonable logical excuses short term - they have beat forecasts after all so i will continue to hold here at current share price -!! (**i do prefer they try though ref forecasts rather then keep figures too close to their chests in year)
Rmillaree,
Re Portmeirion (LON:PMP) - "Plus some of the sales rise is simple cost pass through in the short term, hence no profit leverage". 2 thoughts:
i) if final sales surge was unexpected, are they a sign that next year sales were brought forward and sales will suffer in 2022? Or a sign of surprising strength? what drove the costs and for what absolute value - inbound freight, distribution, wages? I guess we will know more in March. My hope is that as at least freight costs drop away, they can hold prices and gross margin will rise.
ii) ) Whilst forecasting must be hard, I agree no reason not to try. I will write to them (again) and see if they will move towards the ever narrowing range approach for sales and profit forecast of someone like Next for '23.
Must say I take something of a different view regarding some of the "FAANG" names. One thing I question is the historical context of returns from this segment of the market, is it normal to expect the share prices of these to rise 15%+ per annum indefinitely? Because that seems to be many peoples expectation! I believe net margins at these companies are as high as the US markets have ever seen historically - I guess people need to decide for themselves if all this is sustainable. I also think it is clear that companies like this have been able to continue to grow after reaching such scale, as they monopolise their markets (for example by buying out disruptive competitors, before they've grown enough to truly challenge), something that historically might have drawn the ire of regulators. Do regulators really no longer have any power in across the pond? Couple this with the gargantuan power of indexing, which is essentially flooding in to purchase the biggest equity names every day, regardless of company performance or newsflow. Between indexing and the Powell backstop, sometimes I wonder how much of a true "market" really exists? Do discretionary buyers/sellers have the buying power to move prices in these biggest of big names any more? What has happened to the idea of price discovery?
As always I resign to acknowledging that I have no idea where prices end up going, maybe these names go on and perform over the next 10 years like they did the last 10. What I can say is if that happens, then somehow the game will have changed fundamentally, and that worries me.
Hi FederalReverse - I agree it's not normal to expect 15%+ returns indefinitely - all the disruptors get disrupted eventually, however these companies (I'm particularly talking about Amazon, Alphabet and Microsoft here) have shown their ability to have amazing optionality allowing them to keep expanding and dominating new areas meaning that even with trillion+ dollar valuations, they continue to rapidly grow revenues and income. They are at the forefront of mega-trends (whether it be digital advertising, social media, cyber security, gaming, e-commerce, cloud etc.) so I can't see this coming to a grinding halt any time soon. The regulatory piece is a genuine risk though there's a view that this isn't a huge risk to shareholders if these companies got broken up, as the value of the parts could be greater if broken out - I saw someone suggest that the value of AWS on it's own could be around $1.5 trillion meaning you're currently getting Amazon's e-commerce, advertising etc. for almost nothing - same could be said about Alphabet and YouTube - shareholder value would probably be created through this kind of regulation. Charlie
Well said FederalReverse
If a shareholder technically is the part owner of a company personally I cannot invest in the likes of Facebook with its questionable tax practicies .
Teachers, nurses etc need paying for and the Silicon Valley robber Barron’s enrich themselves at that expense .
Morning Paul - loved your preamble and great to hear you're getting involved in the US markets which now accounts for around 60% of my portfolio and growing. As you point out, the quality of companies in the US is quite extraordinary if you look in the right places - huge growth, amazing innovation and cash-generating machines. The savaging of growth tech shares has hit me hard which has been particularly difficult to deal with as the indices have powered ahead, but the frothiness did need to be dealt with - hopefully we've reached a bottom for growth shares but who knows. I remain very bullish on the long-term outlook for innovative, disruptive, tech-enabled businesses and the high growth, high margin world of SaaS companies - the world is changing at an extraordinary pace. I also agree that most of the mega-cap tech shares look great value - I own Amazon, Microsoft and Alphabet and expect them to keep on compounding for years. My jury is out on Meta's vision for the Metaverse but could be a game changer if they get it right.
Would welcome any US-focused discussion threads. Good luck!
Hi Charlie. I am sure it is well known to many UK investors who trade in the US, but I find the Seeking Alpha subscription to be very valuable. Some excellent analysis, and very useful for those who are new or learning that market.
I have been staggered at the seemingly unconstrained profit potential of the large US tech companies, but agree that their dominance and evolving business models will compound nicely for the next decade at least.
I am pleased that I avoided the really frothy 'ARKish' tech stuff which has been hammered. I am becoming quite interested as these pull back, in some cases by 80% v ATH's. I have an extensive US watchlist including SOFI, Acuity Ads (competitor to Tremor), Alibaba, Square and Discovery (will be the 3rd big streaming player). Risk-reward seems more balanced over there at current prices and there may be more to fall for those with a keen eye.
How much is the Seeking Alpha subscription? I only used the free version, I use Tipranks free which I find better.
Think I got an offer for the first year of Seeking Alpha at $15/month, and $19.99 thereafter. Not used Tipranks but will have a look.
Hi Expat - thanks - I've been weighing up the Seeking Alpha subscription recently and think I'll go for it. Have been trying out a few subscriptions recently to see what they're like - Motley Fool (Share Advisor and Rule Breakers) and 7investing are both great sources of ideas. Have also come across Saul's Investing Discussions on the Motley Fool boards which is quite extraordinary if you're interested in hyper-growth companies (Saul is up 1,351% over the last 5 years - no joke!). Admit I've been stung by some ARK stocks (not bought because of ARK I hasten to add) such as Teladoc, Roku and Square - they definitely got ahead of themselves but the likes of Teladoc have been overly punished I feel and currently look like a great buying opportunity.....but I've been wrong on that all the way down! Personally I'm fascinated by ARK / Kathy Wood's view on innovation and disruption though.
Thanks - some further interesting US research platforms for me to look at.
I am also fascinated by Kathy Wood - but I wouldn't invest in her funds. She is a mad futurist, and although some of her arguments are very cogent (and inspiring) her future valuation assumptions stretch credibility. If Tesla had not gone into the stratosphere she would be in deep trouble but credit to her for having faith in Elon when that business already seemed ridiculously expensive. She is either mad or brilliant - the jury will be out for another 3-5 years maybe.
mad AND brilliant perhaps?
A US focussed discussion thread would be great for the site as well in terms of expanding coverage and attracting new subscribers. There are plenty of companies (apart from the FAANG names) that are of good value that can contribute to any intelligent discussion on investing here
Hi Paul
A nice preamble pointing out the opportunities in the US market. I have invested quite a lot over there over past years. I would welcome the Stocko community covering some of those shares.
I assume you are already a follower of Cathie Wood and her monthly ARK Invest 'In the Know' market review. Which includes economics, politics (as they impact markets), monetary and fiscal policies, market movements and her focus on innovation stocks.
If not, and maybe of interest to you and also others this is her video 8th Jan (48 mins). I watch her vids each month and find her insights into US market context extremely valuable.
A point I would make is that many US stocks are very well covered by a whole host of US vloggers. A handful are outstanding in their in depth coverage and daily/weekly vlogs. Sadly, we in the UK have not yet created such a high quality and dedicated army yet. There are a few but not really close to matching the US people.
Maybe you and the Stocko team could catalyse a UK-based vlogging movement.
Regards
Howard
I am definitely not a follower of Cathie Wood! She strikes me as completely detached from reality, when it comes to valuation, and has chased up many stocks to absurd valuations, and continued talking her own book all the way down (her entire fund is down about 50% from the peak, even though Tesla the largest position has held up well).
In every bull market, there are always some "star" fund managers, who nearly always end up crapping out when their particular bubble bursts. Look at Woodford for example. It's when these people believe their own hype, that they're the most dangerous.
And before anyone responds that I get carried away with individual shares too (guilty as charged!) I'm managing my own money, not other peoples'. Plus I don't chase anything up to silly valuations, as that type of thing is an accident waiting to happen.
When Facebook, Alphabet, Google are on sensible, GARP (growth at reasonable price) valuations, I can't see the point in shooting for the stars with some speculative tech stuff that is already priced to perfection. So it's good to see the over-priced stuff with low (or nil) profit margins correcting. They're still expensive, even at halved (or worse) prices, a lot of the former growth darlings.
Hence why I think the mega cap US techs are so much more attractive. Also, elephants can gallop these days! As you say, everything is changing so fast.
P.
Paul
I am definitely not a follower of Cathie Wood! She strikes me as completely detached from reality, when it comes to valuation,
I would agree withn you here Paul although she can talk the talk for sure. I am guessing she and her funds though will live or die by the quality of the companies she picks long term. I think we will have to look back in 5 -10 years time and judge her on how her conviction picks have done long term. I wouldnt dismiss the possibility if she has done her research and found eough "winner winner chicken dinner" disruptive stocks that the end result could be very good - practicably speaking is anyone that good that they have enough edge over the rest of us to pick the next big winner rather than the next promising candidate - hmmmmm. , i am kind of siding for you that at prices she is happy to pay to buy what she wants she has a tough job on her hands.
One thing i have noticed is that she seems to to doing more flip flopping with regard to holdings than i would expect if you have high conviction plays and you know its going to take years for the value to out. That does seems a bit of a red flag IMHO. Perhaps i have misunderstood her approach and she is simply hoping that the sectors she is investing in would be enough to guarantee success - if she is taking the line that some of these must come good i would slightly worry she may miss out on the real winners due to te difficulty in finding real winners.
Anyway certainly good fun watching the journey and there are some interesting stocks being flagged up here that are starting to come down materially in value.
I agree, I think Cathie Wood is absolutely brilliant at what she does. She is so good in fact, that at times, I struggle to decide whether she truly believes all the absolute nonsense that comes out of her mouth, or if it is really just all part of her game to ramp as many people in to her funds as humanly possible.
Honestly I think Cathie Wood pretty much epitomises the culture of investing today. A market where participants (punters) are encouraged to take endless risks (because daddy Powell will always come in to save everyone if something goes awry), and where authorities/regulators have been completely hamstrung and/or no longer have any interest in preventing malpractice, misselling etc.
Does Cathie have a disclaimer in her vlogs declaring that this "should not be considered financial advice"? I can't bear to listen long enough to find out.
Hi FederalReverse
I do not disagree with much of your comment, but do believe that as a five year horizon investor (which I am) I do gain insights from ARK invest/Cathie Wood. Obviously I do my own research, which is far easier to do for US market than the UK.
Graphs below of a 5 year comparison of ARKK vs the US indices and UK FTSE All Share would suggest ARK do in fact have an edge which is differentiated from the indices, by quite some considerable margin.
That said investing in these innovation growth stocks can be a wild ride. They are not for the low risk investor at all.
Regards
Howard
I'm on the side of don't listen to Cathie, if we look at where the gains have come from, are they just purely riding on the wave of inflated options activity in Tesla?
This is a really refreshing read - the US market is full of overvalued growth stocks but they're currently getting battered and yet at the same time the US mega caps are wonderful companies that return enormous profits. I feel like the Google, Microsoft, Meta etc of this world are the best current bet to park money to combat inflation.
Portmeirion (LON:PMP) (I Hold)
Very pleased with the PMP trading update this morning. - just for once it turns out that this'optimistic bod' has been exonerated!
The consensus figures were too low - below the trailing 12m - but understandable caution from management under the circumstances.
£104m revenue and £7m profit before tax are bang on the nail for my forecasts based upon a 'good christmas' .
Can't claim all the credit though - the standard of shared analysis and discussion on the advfn board has been excellent .
More to come from this company based upon the value in its brands, its US brand and operations and the investment in UK production efficiency and on-line channels.
EDIT - to add some context - they have not only blown the 2021 forecasts out of the water - but also the current concensus for 2022 - the revenue is 12% above the pre-pandemic record. Profitability before tax at £7m remains below the peak of 2018 (9.7m) - primarily due to extraordinary shipping costs - and can be expected to improve in 2022 as shipping costs fall from their peaks and improved margins from their investments feed through,
cheers
Mark
Morning Paul
If you get a chance can you cast your eye over Frontier Developments (LON:FDEV) as there seems to be a good pipeline, but recent performance poor. I hold having purchased on recent dip.
Re USA share, I agree and have been buying the Google, Amazon, Apple, Meta but just missed out on Microsoft on dip. I like Zoetis in the US as a very long term hold, and will top up on weakness.
Greyster
Morning greyster,
Sorry but I don't think we'll get round to looking at £FDEV because there are so many updates out today, we're not going to get through everything, and are initially focusing on the out & under performing updates, as they're the most price sensitive.
Regards, Paul.
Paul, Frontier Developments (LON:FDEV) are down 22% so maybe worth a look.
Paul, Frontier Developments (LON:FDEV) are down 22% so maybe worth a look.
Thanks Rustbucket, I hadn't spotted that. I'll try to look at FDEV then, as it's a big mover.
Frontier Developments (LON:FDEV) It was a bit of a late advise, shares were not down initially, also Frontier Ip (LON:FIPP) updated today, it's a bit confusing having 2 Frontiers reporting, on the same day.
Ok, no problem Paul. The market has spoken and it has dropped 25%. My stop loss was triggered at 1480 and maybe will revisit when it has settled. I will need to recalculate my view on intrinsic value and chart support, which could be around £10 mark.
Good luck ploughing through updates.
best wishes.
Greyster
Ref. FAANGS and Jim Slater, so elephants can run.
I think if Jim Slater were here today he would accept that the likes of Apple are exceptional cases and whilst Apple does not run as fast as it did it nevertheless continues to move forward. Once an elephant gains momentum there is little to stop it.
Jim is still here but via his son Mark ( Slater growth) . A spiffingly good fund if you’re that way inclined.
The elephant graveyard is full of dead elephants though.
Probably with all this bullish FAANGS talk going on a good time to short it ?
BSV
Interesting pre-amble there Paul. A US based blog would certainly be a welcome addition to Stockopedia’s current offerings if you were able to fit it in, perhaps if the SCVR team was to continue to expand this could be something you and Ed would consider?
Some of my best gains have also come from US markets in recent times, trading names such as ACLS, AMTX & LEU.
Morning Paul. I’m pleased to see that you are taking an interest in US markets and that collectively we will benefit from informed discussions on opportunities that exist. Personally I have held Apple since 2011 and see it now as almost a hedge against inflation. For me this is a lifetime hold.
I have used the Jim Slater guru screen to pick up some US nuggets such as MYR Group that have delivered stellar returns riding off the back of the infrastructure spend.