Small Cap Value Report (Weds 12 July 2023) - RBGP, HSW, SHOE, MEGP, RNO

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Hostelworld (LON:HSW) - up 3% to 125p (£154m) - Trading Update - Graham - AMBER
Hostelworld reiterates guidance on the back of a strong H1 with adjusted EBITDA making a €10m swing into profitability. The company may be close to generating financial results similar to the pre-Covid years, and the debt load is no longer of significant concern.
RBG Holdings (LON:RBGP) - up 16% to 31p (£30m) - Disposal of LionFish - Paul - AMBER/RED
Good news that the litigation financing problem division has been sold (for less than book value). That brings an end to a costly distraction & cash consuming activity. As mentioned earlier this week, the bombed out legal services sector could be an interesting area for value investors to rummage around in, after DWF received a bid approach. We don't have enough information on RBGP to judge its value at this stage, and high bank debt worries me, so AMBER/RED is to reflect the uncertainty & higher risk.
Shoe Zone (LON:SHOE) - up 10% to 257p (£109p) - Trading Update (ahead exps) - Paul - AMBER
A superb trading update, and big (29%) increase in broker forecast profits. Reasonable valuation still. However, I am worried about emerging Chinese direct competition from rapidly-growing, predatory website TEMU.
ME International (LON:MEGP) - up 2% to 168p (£636m) - Interim Results - Graham - GREEN
Expectations are unchanged as this photo booth /laundry /vending machine company issues interim results. However, it raised its outlook only last month. The company seems to enjoy excellent pricing power and high consumer demand. I will stay positive on it at this valuation.
Renold (LON:RNO) (Paul holds) - Down 4% to 29p (£65m) - FY 3/2023 Results - Paul - GREEN
Forecast-beating results, and upgraded broker estimates for FY 3/2024 have fallen completely flat in the stock market today. Bizarre markets right now! The valuation looks way too low to me, even allowing for the large cash outflows into the pension scheme. Too cheap I think, so I'm happy to continue holding.
Paul’s Section:
RBG Holdings (LON:RBGP)
27p (pre-market) £26m - Disposal of LionFish - Paul - AMBER
This legal services group might see a bounce today, as it confirms disposal of its problem division, LionFish (which does litigation finance, seemingly not very well).
The sale is for £1.07m immediately (to reduce an intercompany loan), with potentially up to another £2.0m in deferred payments, dependent on the outcome of legal cases being financed by LionFish.
This seems to be below the NAV of the cases (i.e. sunk costs) of c.£4m, so there’s a loss on disposal of about £1m.
Also, RBG seems to be keeping 4 out of 8 cases, which it says are fully funded (so presumably no further cash required to finish them).
RBG will no longer be on the hook for a further £2.6m of expected costs in relation to the 4 cases it is disposing of.
Paul’s opinion - there could be a bounce in this share, which seems to have been in a relentless downtrend this year. There was also the recent excitement around takeover talks, which caused a big rise in DWF (LON:DWF) (another legal services group). So as mentioned at the time, I think this sector could be an interesting area for bargain hunters to sniff around.
RBG’s foray into litigation finance didn’t work, so it’s good the division has been disposed of, as planned. That should mean after the disposal write-off, then losses and liabilities of that division should be gone, clearly a positive thing.
I’ve had a look at the FY 12/2022 group accounts, and £3.8m losses from LionFish are separated out as discontinued operations. I’m not sure the £10.9m adj PBT is valid, because it includes a £3.8m gain on litigation assets at the top, under revenue.
Stockopedia is showing the forward PER as just 3.4, but the lack of trading updates means that I don’t know how the company is performing versus forecasts. Hence at this stage, it’s impossible to accurately value RBGP shares, it’s a leap into the unknown really.
Also, its balance sheet is weak, dependent on £22m of loans at Dec 2022, partly offset by £3m cash. It has a lot tied up in receivables, as is often the case for lawyers, which can often contain things that need to be written off.
Overall then, for traders & gamblers, this could be an interesting punt, for a rebound. But it’s not possible to judge whether it will make a good investment or not.
Hence I’ll stick at AMBER/RED, as I need more information. The risk of a profit warning seems high, but has the share price already baked that in maybe?
Oversold, or in serious trouble? We don't know at this stage -
Shoe Zone (LON:SHOE)
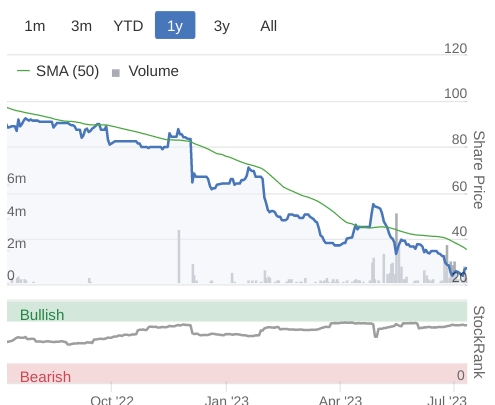
Up 10% to 257p (£109m) - Trading Update - Paul - AMBER
This value shoe retailer has issued one of the most upbeat-sounding trading updates I’ve heard for a while -
Shoe Zone is pleased to announce that since its last Trading Update on 9 June 2023, the Company has achieved an exceptional month of sales. Trading has significantly exceeded management expectations due to continued strong demand with volumes up double digit on last year, despite no price increases on our core ranges.
Alongside exceptional trading, the Company has also experienced margin improvements due to the lower container rates and favourable foreign exchange rates with management expecting these improved margins to continue for the rest of the financial year.
As a result, the Company now expects adjusted1 profit before tax for the financial year ending 2 October 2023 to be not less than £13.5m.
1 Adjusted to exclude the profit on the sale of freehold property and foreign exchange revaluations.
Broker update - many thanks to Zeus, who crunch the numbers for us. It’s another (big) upgrade to forecasts - EPS for FY 9/2023 goes up from 16.9p to 21.8p, which gives us a PER of 11.8x - hardly demanding for a company performing so well.
Divis forecast at 9.0p gives a growing yield of 3.5%, with a good history of paying special divis on top.
Paul’s opinion - SHOE was one of my favourite shares for 2023, being on my runners up list here in January. Although the previously forecast drop in earnings did seem strange. So it’s good to see forecasts significantly raised again. A reminder that broker forecasts are definitely not gospel, and can often be considerably above or below reality, due to the sensitivity of profit to trading conditions. Predicting this is difficult, but there are sometimes clues. Bulls on SHOE (eg. CockneyRebel) have been saying for a while that the forecasts were too low, and he's been proven correct - good work!
SHOE’s customers are clearly appreciating the selling prices that have not been raised, delivering increased sales volume, and with good gross margins (helped by cheaper freight, and the strong pound, now approaching $1.30 today).
One word of caution though. The Chinese are coming. I reviewed website TEMU in a recent podcast, and the extraordinarily cheap products they are now air-freighting direct to customers in the UK (the Lenovo earphones are a stunning bargain at £8). I’ve just checked, and TEMU is selling shoes, including childrens, at low prices. SHOE makes high gross margins on Chinese-made shoes, but TEMU now means customers can buy direct from China, at lower prices. I reckon that could potentially damage SHOE (and other retailers that buy product from China, and mark it up a lot).
So for that reason, I’m a bit wary about SHOE, facing what could be its most serious emerging competitor. Hence even though the figures are terrific, I’m shifting from GREEN to AMBER over this new, very aggressive Chinese competitor. Look at what SHEIN did to the likes of Boohoo (LON:BOO) and ASOS (LON:ASC) - it wiped out their profits completely. There’s a risk the same thing could happen to SHOE, so I think bulls need to seriously consider this emerging risk.
Renold (LON:RNO) (Paul holds)
Down 4% to 29p (£65m) - FY 3/2023 Results - Paul - GREEN
Renold (AIM: RNO), a leading international supplier of industrial chains and related power transmission products, is pleased to announce its audited results for the year ended 31 March 2023.
Record trading performance and order book….Significant revenue and earnings growth….Successful integration of significant strategic acquisition
Some excellent figures in the financial highlights -
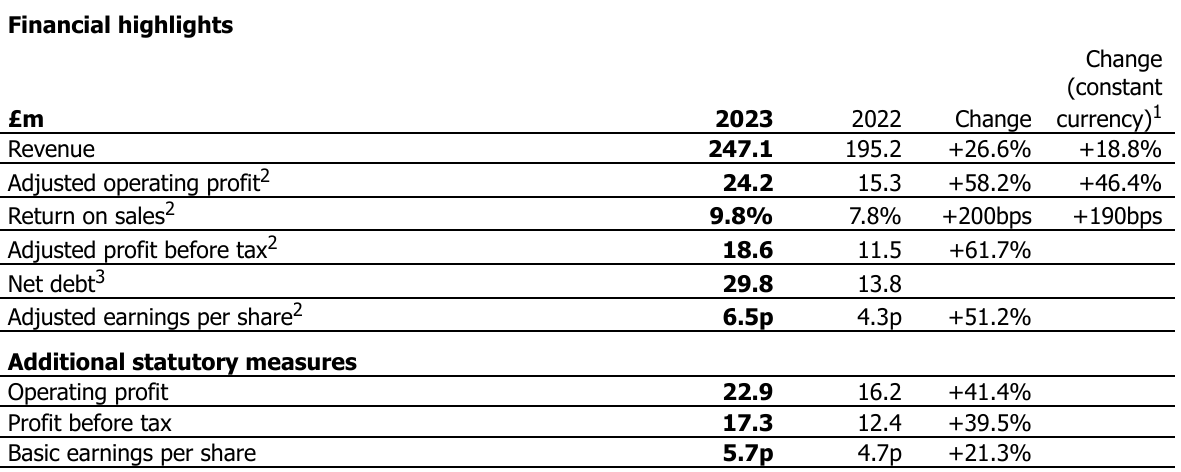
Note the boost from favourable currency.
Only a small difference between adjusted and statutory profit.
Super-low PER of only 4.5x (partly explained because of cash-hungry pension deficit).
Alternatively, a more cautious valuation would be based on the 5.6p EPS at constant currency, giving a PER of 5.2x
Net debt (above excludes leases) is up due to an acquisition.
Healthy order book -
Closing order book £99.5m, up 18.3% against 31 March 2022 |
Acquisition of YUK is performing ahead of expectations, which gives me increased confidence in the acquisition strategy - buying complementary businesses in a sector RNO management knows well - hence unlikely to make mistakes. The acquisition strategy also dilutes the pension deficit into a larger group.
Outlook comments sound confident -
… we have entered the new financial year with good momentum and confidence in the excellent fundamentals of the Renold business, although macroeconomic trends add a note of caution.
Throughout the reported period the business performance has been on an improving trend and finished particularly strongly as supply chains eased in the last quarter.
We expect the current financial year to be no less challenging, but we remain vigilant in the environment within which we operate; however, we started the new financial year from a positive position with good momentum and confidence in the capabilities and fundamentals of the Renold business and the markets we serve.
Given that Renold has demonstrated great resilience throughout covid, and the energy/inflation problems more recently, I’m not worried about the macro comment above. It’s a fairly standard thing that most companies are saying (sensibly) at the moment.
Dividend policy - Directors reckon they can generate better returns from internal investment, and acquisitions, rather than paying divis. The pension scheme sucked out £5.8m this year, and £4.8m LY, so that’s a considerable drain on cashflow, which would otherwise be available for divis.
The pension payments are rising by £1m pa, so this remains a big issue, which should be factored into valuing the shares on a much lower PER than would be the case for an equivalent company that doesn’t have a pension deficit problem.
Bank debt - looks fine to me now. In the past it has been over-geared, but that is no longer an issue in my view, eg -
The Group has operated well within agreed covenant levels throughout the year ended 31 March 2023 and expects to continue to operate comfortably within covenant limits going forward.
The net debt/adjusted EBITDA ratio as at 31 March 2023 was 0.9x (31 March 2022: 0.6x), calculated in accordance with the old banking agreement. The adjusted EBITDA/interest cover as at 31 March 2023 was 13.7x (2022: 19.6x), again calculated in accordance with the banking agreement.
Going concern statement looks fine, and has some useful extra information, but nothing that worries me at all.
Balance sheet - NTAV is around nil, once intangible assets are written off.
The pension deficit stands out, at £62m, but down by over a quarter on LY, on an accounting basis.
In other respects, I’m satisfied that the balance sheet looks OK.
Broker forecast - looks undemanding, at 5.2p adj EPS FY 3/2024, so I would hope to see ahead of expectations trading updates as the new financial year progresses.
Paul’s opinion - I’m very happy to continue holding for the foreseeable future.
Renold shares look significantly under-priced to me, I would say 50p+ would be a far more realistic valuation than the current 29p. So it’s great value, with a positive outlook too.
It sailed through covid and more recent macro problems, displaying strong pricing power, and repeating revenues (as a lot of chains are replaced on essential maintenance schedules, rather than being discretionary spend).
I’m half-expecting a takeover bid for RNO too, which would be a nice development, if a suitable premium were to be offered.
So far, the stock market really hasn’t given RNO any credit for an excellent turnaround, and the upside from its bolt on acquisitions strategy. A re-rating upward looks only a matter of time.
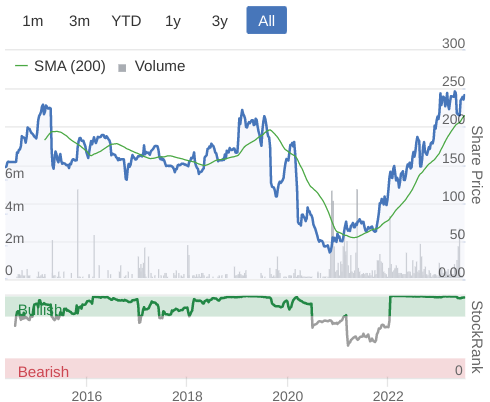
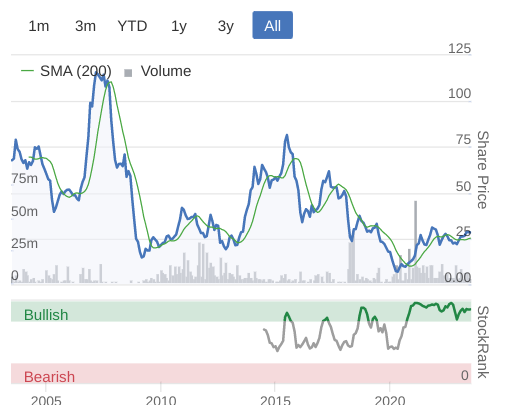
A lacklustre long-term chart, but Renold is a greatly improved business now, so a re-rating is long overdue I think.
Graham’s Section:
Hostelworld (LON:HSW)
Share price: 125p (+3%)
Market cap: £154m
This online travel agent gives a quick update on trading for H1.
H1 revenues are €51.5m (up 57% on last year). We already knew from the statement in May that revenues were running at a record level in the first quarter.
The number of bookings made on the platform is up 64% but the net average booking value is slightly down to €15.15, which the company says is due to a higher proportion of them being in Asia.
Direct marketing spend as a percentage of revenue falls from 60% to 51%.
H1 EBITDA is €5m, versus an EBITDA loss of €5m in H1 last year. The company leaves the full-year forecast unchanged for full-year EBITDA of €16.5 - 17.m, “absent any deterioration in the macro-economic environment, the reintroduction of Covid restrictions or air travel disruptions”. The company included a similar disclaimer in their May statement.
Debt: as I discussed in May, Hostelworld has taken great steps towards solving its debt issue, replacing a large and very expensive facility with smaller and cheaper facilities (coming in the form of a term loan, an RCF and an overdraft).
The company announces today that the interest rate charged on its RCF has fallen further, thanks to an agreement with the bank that sees the rate fall if the company deleverages. Hostelworld is now paying a margin of 3.25% over EURIBOR (previously 3.75%).
Net debt now stands at €16m.
CEO Comment:
…I am delighted that we have delivered record generated revenues and improving EBITDA margins driven by our differentiated Social growth strategy and a continuing focus on operational excellence and cost discipline.
Looking further ahead, I remain very confident that our innovative, asset-light business model is well-positioned, well-financed and firmly on track to deliver against our long-term growth goals
Graham’s view
I remain interested in Hostelworld. Prior to Covid and what that did to the travel sector, it did generate material profits for shareholders. It even paid dividends from 2016 to 2019!
Recent trading updates suggest to me that it is on track to return to its former glory. The revenue and booking numbers certainly attest to that. All the indications are that this will be a record revenue year; perhaps it won’t be in real, inflation-adjusted terms, but it should be in nominal terms.
I’m close to turning green on this one, but I’ll hold out and wait for proof of convincing profitability down at the bottom of the income statement. Adjusted EBITDA is likely to be excellent; if the company converts this to real profits then there’s a strong chance I’ll turn positive on the stock.
ME International (LON:MEGP)
Share price: 168p (+2%)
Market cap: £636m
ME Group International plc (LSE: MEGP), the instant-service equipment group, announces its results for the six months ended 30 April 2023 (the "Period").
It’s difficult not to be impressed by the table that opens these results:

The company notes that pandemic restrictions eased in Asia compared to the prior year, and this did help to boost results.
The net cash balance has fallen but an amazing £43.5m has been returned to shareholders over the past 12 months - the company had more cash than it needed.
Performance at each major division:
Photo revenue +25% to £84m (the number of units fell slightly, so the revenue growth is entirely reflective of higher activity and higher prices).
Laundry revenue +37% to £38m (the number of laundry units continues to grow at a rapid pace)
Printing revenue +11.5% to £6m (these machines have been removed from the UK and Ireland after a trial; they are “far more profitable” in France.
Food vending +106.5% to £6m
Outlook
Key elements of the outlook include the M&A strategy (see Paul’s recent coverage of a small acquisition in Japan), the installation of 10,000 next-generation photobooths, continued expansion of the laundry estate, and development of food vending operations.
They are now back in the FTSE-250 index, a highly attractive place to be.
Forecasts are unchanged for today, but they were upgraded as recently as 1st June. These expectations are for revenues of £300-320m, EBITDA of £100-110m, and PBT of £64-67m.
Chairman comment
Sir John Lewis states that the company has a “resilient business model where we benefit from a dominant market position, with limited or no competition, in many of the countries in which we operate”. I suppose he is right - there can’t be many other companies operating these machines on anything like the scale that MEGP does.
CEO comment outlines performance by geographic segment, with 23.5% revenue growth in the key segment of Continental Europe.
On a personal note, I thought my eyes were deceiving me when I saw Revolution laundry machines on a trip to Portugal last month - they are everywhere now!
Graham’s view
Last November, I included MEGP on a list of “four contrarian stocks to buy for a rebound” (the others being TTR, IGR and JUP). MEGP has performed the best out of that selection, up over 60%, and although I don’t own these shares personally, I’m inclined to “let my winner run” and maintain my positive view on them.
They are not nearly as cheap as they were then, obviously, but earnings upgrades have kept a lid on the earnings multiple (c. 12x according to Stockopedia).
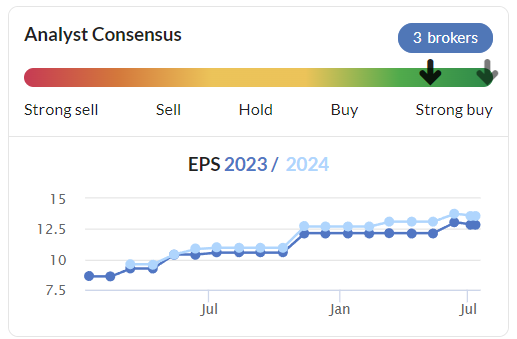
Now a member of the respectable FTSE-250 index, it will be even easier for stock market investors, domestic or international, private or institutional, to justify owning them.
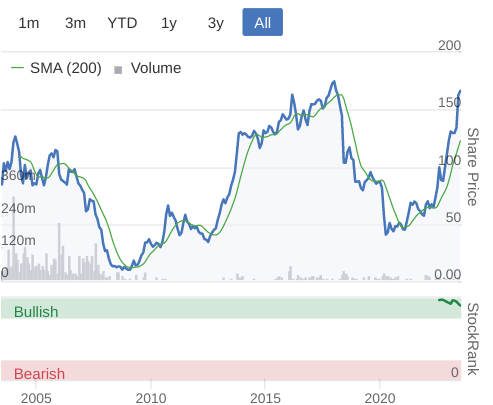
Everything I liked about this company last year remains true today, except they now have significant momentum in both the share price (MomentumRank 90) and in their financial results. The valuation isn’t setting off any alarm bells for me at this point so I’m staying GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
Renold (LON:RNO) - is there a possibility that Renold could offload its pension liabilities to a company like Legal & General?
Hi Robert,
Renold (LON:RNO) - is there a possibility that Renold could offload its pension liabilities to a company like Legal & General?
It could, but that would come at a cost, so it probably makes more sense to keep the pension scheme, and gradually fund it from annual deficit contributions.
Where companies have offloaded pension schemes in the way you suggest, it's been where there's a surplus I think.
Regards, Paul.
Unbound (LON:UBG) now down to a £651k mkt cap after the RNS today. What a fall.
Bit confused as to what's going on today, anyone else seeing this unusual green colour all over their portfolio?
I was wondering Paul, if you noticed the FY trading update of Knights group (LON:KGH) on Monday 10th. It’s dropped massively over the last couple of years is on an extremely low PE. Could be some big upside coming in the not too distant future. It’s ridiculously cheap so could be of intert to readers , despite your aversion to these types of companies.
I note the comment from Paul regarding SHOE and the competition from the likes of Temu and Shein. At some point Western regulators are going to need to get a grip of these companies and hold them to the same standard as UK ones. The media need to get stuck in here too, but their mates can trade stock in those Chinese names so there's no incentive for them to do so.
Decent inflation numbers from US.
Wish we were down to 2.97%
We probably would be if they could just wait 5 minutes!!!
Paul, great Small Cap Podcast/Macro on the weekend as always.
Interesting about Temu - had a look at work with some collegues after you spoke on it.. the garbage we can get shipped over for a few pence is outrageous !
They seem to have the advertising down to a T, getting plenty of AD spam from them on all social media platforms!
But the quality is terrible.
BBC News - Mortgage payments set to jump by £500 for one million households
https://www.bbc.co.uk/news/business-66172954
Why does the BBC or news outlets report on the positive news that millions of households will see extra income from interest on their savings?
Surely now being able to get 4-5% more interest than 2 years ago, means that many households will have more money to spend?
BBC talks about the have-nots Boon, while yourself talks about the haves. Not many with stressing mortgages are on Stocko.
Quite correct about mortgages. Most owners own outright or have a fixed deal. There are far less repossessions happening these days than there were in the 90’s. I do know one person on a variable mortgage because he can’t remortgage due to having gone through a bankruptcy a few years ago. But he will be in a very small minority. The banks are trying very hard not to repossess.
Because it is not negative, most news is negative, especially on the BBC. No wonder a lot of people don't watch it anymore.
Why does the BBC or news outlets (not) report on the positive news that millions of households will see extra income from interest on their savings?
The economic reason is that, in theory, savers tend to be older and consume less, so are less likely to spend the extra interest. Borrowers tend to be younger and extra debt repayments eat into their dicretionary income. The net effect is to take money out of circulation.
The business reason is that bad news sells.
timarr
But if they have more money then they may spend more? Plenty of older people around here, spending loads of money on their houses. Expensive restaurants tend to have older people eating in them. Some economists are suggesting raising taxes to reduce inflation. Not sure about that.
Chancellor Hunt has already done this, raising corporation Tax, lowering your Capital Gains and Dividend Tax allowances. But then , the latter only affects the smaller investor in equities so I am not sure how this will make any difference to inflation. Perhaps it will do the opposite to the intended.
Whilst that us true, it was income tax on the wealthy: "Kate Barker, a former member of the BOE rate-setting committee, said income taxes should increase for the better-off to help the central bank curtail inflationary pressures."
"Why does the BBC or news outlets report on the positive news that millions of households will see extra income from interest on their savings?"
Because you don't get made homeless for not receiving enough interest on savings. Also, the £500 per month is a hit to the "real" economy. Whereas more interest just goes into bank accounts where it just sits there, unspent, gaining more interest.
This is a tongue in cheek answer so please don't take this the wrong way but you yourself are guilty of not reporting the FULL story, the time line on the 'one million' was 2026 !!!
and it was 'nearly' one million !!
By Tom EspinerBusiness reporter, BBC News
Mortgage payments will rise by at least £500 a month for nearly one million households by the end of 2026, the Bank of England has said.
There must be 30m households in the UK, so on that basis 29m aren't going to be too badly affected ( or not at all for the third who own outright).
1. There will be far more housholds seeing their mortgages rise by under £500, and for many lower income families a rise of less than £500 can still be a massive problem.
2. A lot of private renters rent from buy to let landords. They won't be absorbing the extra mortgage costs. Either rents will go up, or some landlords will sell, leaving tentants potentially homeless.
I was being simplistic and clearly there will also be some who could be quite badly affected by even a £200-300 increase each month.
That said, mortgage affordability rules are quite strict now so wouldn't expect too many low income families to have been given mortgages in the first place. The rules also should factor in the ability to absorb higher rates (whether this works in practice is another thing)
I think rising rents could potentially be more of a problem, although there can be quite a lag before landlord put rents up, and I can't see too many wanting to sell up in the current market, at least not imminently.
Mortgage affordability rules used to be much tighter. When I took out a mortgage in the 80s the rule was 2-2.5 x salary, with little allowance for a 2nd one. Now 4.5x is common, and it can be higher. We've had a decade of extreme low interest rates, and we are still below the 50 year average. I'm not saying we will see 6%+ as the norm soon, but people many been sold mortgages that are unsustainable in a high (normal?) interest rate environment. The transition is going to hurt for many.
True rules were tighter if you go way back. I was thinking of the pre-financial crisis era when practically anyone could get a mortgage, with no deposit required.
Four sectors are at the bargain prices : Housebuilders, Private equities, Real estates and packagings .
The first three have been discussed in details here but the packaging sector less so: Smurfit, Mondi and DH Smith offer good value.
all four sectors are down because of high interest rate and fear of recession. In my mind the depressed share prices reflect this scenario well.
I think packaging sector also hit by concerns of oversupply, which I believe is weighing on paper prices. Some more exposed than others.
Must admit I like Mondi (LON:MNDI) looks good value and a structural winner
Retailers are in demand today. Has there been a sector upgrade? Marks and Spencer (LON:MKS) ASOS (LON:ASC) Card Factory (LON:CARD) Boohoo (LON:BOO) THG (LON:THG)
Maybe the trading update from Shoe Zone (LON:SHOE) has lifted the sector?
Retailers always benefit from a strong sterling.
Probably this?
https://brc.org.uk/news/corpor...
https://home.barclays/news/pre...Covering the five weeks 28 May – 1 July 2023
But does that take into account inflation? Inflation on food is around 18%. On food I buy I suspect it is higher, as some items have almost doubled in price.
Begbies Traynor (LON:BEG) Full year 2023 results yesterday. Here's their analyst presentation video & podcast.
Always interesting what they say about the broader market.
Tpximpact Holdings (LON:TPX) FY23 results presentation by new management from last week. Video & podcast.
You've obviously read the actual FY23 results but some of the key highlights of their aspirations going forward:
Tamzin. will yesterdays Sosander call be released as a podcast. I missed the zoom live
Yes, here it is Sosandar (LON:SOS) full year 2023 results presentation podcast and video.
The (non) tagging issue is getting worse. Only one of the five companies covered yesterday was tagged and none of today's three companies covered has so far been tagged.
Do Stockopedia really care about this? It appears not given the number of times this has been commented on on here without any apparent solution being offered.
It is making subsequent searching for historic commentary more and more of a lottery.
Subscribers will walk before long - do something now please.
Agreed.
just logged in and today currently I have no tags and yesterday only has Eagle Eye Solutions (LON:EYE tagged for me.
Hovered over cancel subscription but in the meantime come on Stocko sort this bug out, and in the meantime of the meantime have your human QA correct this it and input manually if needs be.
Not only do we miss your writers excellent right ups just as important we miss other subscribers views.
Makes a mockery of DYOR!
I check all the tags and replace any missing ones as part of my weekend routine now. Yes it's annoying!
Why can't Stocko Management a) explain to subscribers exactly what the issue is and b) resolve the matter with an IT fix. Silence from them is simply very poor customer service and subscribers deserve better.
Paul, "Bulls on SHOE (eg. CockneyRebel) have been saying for a while that the forecasts were too low, and he's been proven correct - good work!"
He sold out of Shoe Zone (LON:SHOE), some time ago, it was covered in your interview with him. Card Factory (LON:CARD) he is very keen on now.
Shoe Zone (LON:SHOE) updates have been rather inconsistent recently. I sold my remaining shares today, so they will probably soar.
Shoe Zone (LON:SHOE) I hold, going ex-dividend tomorrow so could be one reason to sell today and see a drop in share price tomorrow? We'll see, but as long as the returns on capital remain strong I'll continue to hold.
Shoe Zone (LON:SHOE) Did not realise about ex-dividend tomorrow. Price to buy is now lower than I sold at. I'm quite happy with the price I got, nearly sold a while ago, I thought there would be some profit taking. I may buy them back if the price falls enough. So many shares fallen back in this market.
I wouldn't be worried about chinese online competition for Shoe Zone (LON:SHOE. From our experience, like sofas, foot wear is a very hard product to buy online and get the right fitment. 9 times out of 10 the shoes have to go back and without a high street presence all the harder. Love Next for that very reason.
I have found most chinese made shoes to be too narrow for my feet, stopped buying quite a few brands now. I look for wide fitting, not that easy to find these days. Clarks and New Balance are too brands that do them. Probably got enough shoes now to see me out.
Mizuno are also good for trainers, had to swap when Asics changed there design about 4 years ago after 25 years of custom!
I'm looking to replace my wet shaving brush. Temu are offering a 'hand-crafted' (sic) synthetic brush for £2.48. What a joke - surely contravenes advertising standards? Pure badger brushes are upwards of £30 - apologies to animal lovers.
Hi Paul, I was wondering if you were going to comment on the Sosandar (LON:SOS) webinar from yesterday.
I would be very interested in reading your analysis of Sosandar (LON:SOS) results at some point please Paul. I believe this was one of your largest holdings and hopefully still is :-) Thank you.
Yes. Sosandar (LON:SOS) please Paul. I hold too, and your analysis will be very helpful.
Regards
Martyn
Agreed on Sosandar, particularly as Singer’s note from yesterday has earnings of 1.2p to March 24 and 1.7p to March 25.
If the company hits those numbers it will be very cheap.
They have so much more scope in the uk. If international sales goes well, then I think it will do really well.
Sosandar is not cheap at all (remember that interest rates are not O% now)and will need another fundraise , as it is not generating any cash.
Yes, I'll cover Sosandar (LON:SOS) probably on Friday. I remain an enthusiastic long-term holder. I'm in Spain at the moment, and it's ridiculously hot so am struggling a bit. Flying back tomorrow afternoon, so should be able to focus on SOS on Friday.
Although the outlook comments were overall OK (in line exps), maybe the 10% current trading growth rate disappointed some investors, as it's slowed markedly from the very strong prior year comps.
Off topic looks like Wentworth Resources (LON:WEN) deal not going going ahead or delayed discount to nav plenty of cash earning bank interest
Wentworth Resources (LON:WEN) Not off topic, looks like another delay, the FCC playing hardball.
Does being a micro-cap make a company off-topic for the SCVR? Wentworth Resources (LON:WEN) certainly isn't for myself, having sold a quarter of my holding in April at 30 pence I'm now champing at the bit for a final resolution.
No, not unless they are below around £10m. But energy stocks are not cover by Paul/Graham. But members are free to discuss them.
Hmm, almost worth a forum of their own. How do we set up a resources forum? I know there are a bunch would contribute from time-to-time. I sold out of a fair holding at 30-32p in January. I tend not to wait around for a bid to close if the share price reponds quickly to get near to the bid price. Normally, I find the extra couple of % isn't worth waiting around for if I see other shares on which I have a target price of 25% or more higher. The bids do not always come through or can be farught,as in this case.
But you have made me look at Wentworth Resources (LON:WEN) again at this price. It's a solid business, with plenty of cash, But I took it off my watchlist, as there were too many RNSes coming through, and they seem to have taken down the website already. Can anyone link me to recent operational updates? It feels like Katherine Roe has essenmtially checked out, so it's become a bit of a black box, but at 24.5p, it must still be at a substantial discount to NAV.
It has been discussed before and I think there have been a posts but not a great deal of interest.
You just go into Discuss, start new post.
Why don't start one?
still and aim company so website stays until a delist from the market?
Totally (LON:TLY)
Monday's announcement of results highlights included:
• Substantial increase in profit before tax to £1.8 million (2022: £1.3 million).
• Increase in basic earnings per share to 0.94 pence (2022: 0.92 pence).
Sent to IMC by me on Monday for today's webinar (advance Qs are sent to the company the day before):
Result - RNS this morning: "Basic EPS for the comparative year was 0.59 pence, not 0.92 pence"
I'd like to think it was me but I now see that '1gw' at ADVFN and no doubt others spotted the same thing.
However, I now find the 0.92 figure in last year's final audited report in note 25 to the a/cs (and nowhere else):
https://www.totallyplc.com/app...
After the trading outlook in the prelims and now this I do not have a great deal of confidence in this company or their auditors.
Was there a share issue in the period so on a line for longer basis the EPS might change?
'Like for like' sorry I'm on a phone
Knights group (LON:KGH) there were interim results a couple of days ago which I commented on at the time as looking healthy. I wouldn't mind your view on that Paul given that we are talking about law firms and potential bargains. You previously gave it a thumbs up. As previously mentioned I work in legal services and I hold Knights group (LON:KGH) . As someone commented the other day, there is a poor sentiment of the firm across its lawyers. Roll On Friday is a good lighthearted source of information on this.
Knights group (LON:KGH) started doing a bit of research here as looks very cheap and appears to be performing well. As a people business one of the first things I do is check out the Glassdoor reviews - unfortunately these don't look great, with lots of solicitors complaining about the culture or various other gripes. I recall the main cause of the earlier share price collapse was the high staff churn and lack of people coming back to office, so something to keep an eye on.
Morning Paul, thanks for your comments on RBG Holdings (LON:RBGP) . Good news as far as it goes but the real test will be when they provide details of trading for the 1/2 year which hopefully will be towards the end of this month.
Ten Entertainment (LON:TEG)
Thought the half year results were excellent. Despite £2m PBT headwind from previous years VAT reduction they still managed to beat last years H1 results. LfL growth is good given they held prices and therefore had no benefit of increased prices in this number. Site expansion driving low-mid single digit growth.
Just looks too cheap on a PER of 7 and a net cash position doesn’t it? Particularly compared to Hollywood Bowl (LON:BOWL) which is fundamentally the same business only quite a bit richer rated. Can’t see anything in the metrics to really justify that.
I’d say I’m surprised to see no positive reaction to this but in this market I guess I’m not!
From memory Ten Entertainment (LON:TEG) has significantly more bank debt than Hollywood Bowl (LON:BOWL) therefore more risk from interest rate increases or a reduction in trading. I could be wrong as Stockopedia includes leases in the debt figure (from memory).
I find it odd these two businesses seem not to have passed on the inflation in their prices I think that will prove to be a mistake. Right now consumers are expecting price increases that won’t be the case when interest rates really start to bite.
No it doesn’t !! Ten Entertainment (LON:TEG) has zero debt and net cash so will be getting paid interest not the other way around. That’s also made clear in the half year results
The debt shown in stocko is leases (same for Hollywood Bowl (LON:BOWL) )
David
I stand corrected, I’ve wombled off and taken a look at the balance sheet and you are right I’m wrong. Thank you.
Neil
£TEN
From memory Ten Entertainment(LON:TEG) has significantly more bank debt than Hollywood Bowl
As davidjhill has confirmed your memory has failed here - per finals they had 10 mill cash and no real debt. I am ignoring lease obligations which are simply future rent payments !!!
In agreement David. Not sure why it trades at such a discount to Hollywood Bowl (LON:BOWL) despite the latter's Canadian expansion. I hold.
It’s an odd one. I understand Hollywood Bowl (LON:BOWL) is expanding internationally but I mean when has North American expansion ever gone wrong for a UK business………!!!!! So there is both risk and reward there but only the reward is priced in compared to Ten Entertainment (LON:TEG) where only the risk is priced in. Just seems odd given earnings quality metrics are basically very similar, but despite results there seems to be no investor willingness to close the gap. Hey Ho…..more patience required
Maybe worth taking a look at XLMedia (LON:XLM) this morning? I can't remember the last time the company released any positive news?!
Can the sale price (for 6% of the revenues) be extrapolated over the the total European casino portfolio to derive a rough valuation for that part of the business?
Sterling has claimed sharply against the $. Doesn't a strong currency suggest a strong economy? Or is the $ weakening due to their issues? Any views?
*climbed
You have an hour to make any corrections to your post which makes it easier for readers.
Simply click on the pencil symbol on the bottom R of your post (hover over it and it tells you how much time you have left):
Hi, no such option on a mobile device. I won't be near a desktop for a while so can't edit.
Implies that UK interest rates will go up and US ones down. Strong £ helps to reduce inflation - which is a good thing
No it doesn’t imply that at all, but strong sterling helps inflationary pressures.
No it doesn’t imply that at all
If Cable’s recent strength isn’t based on relative expectations for the direction of interest rates, then what is it Yiannos? A sudden realisation that the UK economy is far stronger than the US?* The Brexit dividend? James Bond is better than Ethan Hunt? The Lionesses are bringing home the World Cup from those pesky Yanks?
* Hint - if this were the case AIM would be at all time highs.
Turkish interest rates flew and their pound collapsed !! So , if you think that the direction of interest rates implies the weakness or strength of a currency then…….
Don’t know about the World Cup ; I do like the Lionesses manager though ; very capable indeed; probably they should give to her the men’s managerial job as well.
It is because interest rates have gone up in the UK and expected to go up again. The £ is up against most currencies.
If you look at the US Dollar basket (on IG Index) that is down, so that helps the pound, but the pound hasn't risen much against the Euro. The Euro is rising against the Dollar. So it could be weakness in the Dollar. Not an expert in this.
Strong currency, in Sterling case, means higher interest rate and higher fixed income for international investors.
Strong currency with low interest rate (Swiss Franc) is the sign of strong economy.
Shoe Zone (LON:SHOE) very brief trading update reports 'exceptional' sales, not inflation driven, over the last month since the June 9th update. I'm not complaining but would they have been quite so quick to update if he 'shoe' was on the other foot? [I hold]
Shoe Zone (LON:SHOE) Todays unexpected TU was a welcome sight this morning due to an exceptional month of sales
Profit pre tax raised again & now expected to be not less than £13.5m. I remain a happy holder
I was particularly interested in their comment re margin improvement due to lower container rates. As a read across other retailers should be experiencing the same
Interesting timing of TU as Shoe Zone (LON:SHOE) go ex dividend tomorrow 13th July
My morning smallcap tweet: Sliced returns
Argo Blockchain (LON:ARB) Fiinu (LON:BANK) RBG Holdings (LON:RBGP) Kelso group (LON:KLSO) XLMedia (LON:XLM) Shoe Zone (LON:SHOE), Itaconix (LON:ITX), Hostelworld (LON:HSW)
◄Argo Blockchain (ARB)► Bitcoins mined in June down 17% on May. Blames higher average network difficulty and increased curtailment of mining operations at the Helios facility". New kit in Quebec expected to increase hashrate capacity by 12%. [SP=12.5 Cap=73m]
◄Fiinu (BANK)► cost cuts and redundancies at subsidiaries, Fiinu 2 Limited and Fiinu Holdings as co fails to get exit funding to consider seeking re-application of banking license. Also "unable to utilise the funding options announced on 15 March 2023 with Dewscope Limited and GEM Global Yield and GEM Yield Bahamas". £4.3m at hand. Options include a change of strategy and/or a sale of the Group's technology assets. [SP=6.3 Cap=17m]
◄RBG Holdings (RBGP)► gets £1 for LionFish plus £1.1m loan repaid and an additional payment of up to £2m, subject to performance conditions, to repay additional intercompany debt. Book loss of £1m (assuming all £2m repaid?). [SP=28 Cap=27m]. I hold.
◄Kelso (KLSO)► has made £1.7m on THG shares purchases. [SP=2.65 Cap=8m]
◄XLMedia (XLM)► sells three European gaming domains and associated websites for $4m = 4.7x rev. Co will continue to operate igaming business in the Swedish and other European markets. [SP=10 Cap=26m]
◄Shoe Zone (SHOE)► guides FY-Oct adj pretax £13.5m+ after an exceptional month of sales. "Volumes up double digit on last year, despite no price increases on our core ranges." Surely no price rises helps volume! Margins better due to the lower container rates and favourable FX. [SP=238.55 Cap=110m]
In line: ITX, HSW
#shoe presumably they mean revenue up double digits despite no price increases
Shoe Zone (LON:SHOE)
ME International (LON:MEGP) Interims add welcome further detail on the fast growing nature of their laundry business. Continental Europe is growing well as they install 50-60 machines a month
Recently raised expectations for the year reiterated along with a 2.97p dividend. I wouldn’t be surprised if we see a Special Dividend too at some point (assuming no major acquisitions are made)
I remain a happy holder as they execute their 5 year strategy
Your thoughts would be very welcome as always Paul & Graham
Loungers (LON:LGRS) Loungers has reported record revenue of £283.5m, up 85% on pre-Covid FY19. 29 new sites opened during the year, taking the total to 222 at year end. Excluding the continued estate expansion, like-for-like revenue growth was up 7.4% on the last year, and an impressive industry-leading 17.6% over the last three years. Inflationary pressures have impacted margins, especially wage inflation, while the results also reflect the end of government Covid-support measures. The adjusted EBITDA margin (IFRS16) was 16.7%, down from 22.6% in FY22 and 18.7% in FY19. However, management reports that inflationary pressures are easing and they aim to restore margins to pre-Covid levels over the medium-term. Brief note here: https://www.equitydevelopment....
MEGP (LON:MEGP) Good morning Paul. Your thoughts on this morning's Interim Results from ME Group International Plc would be appreciated.
Trading update from Pagegroup (LON:PAGE) guiding in-line with expectations. Q2 gross profit down 6.5% which is not as bad as a I feared following the update Robert Walters (LON:RWA) last month.
Strong interim results from ME International (LON:MEGP) . Dividend increased but no special this time, which is understandable given the recent acquisition in Japan.
ME International (LON:MEGP) - nonetheless at 2.97p this is a 14% increase in the interim dividend. vs. last year at 2.6p. [I hold]
Hi Paul,
Hopefully you will "chain" yourself to your laptop to report on any company beating "market expectations" today.
Would that be Renold GloucesterBob? ;-)
I like what I read in their results this morning. It would be interesting to see if they give any update on their pension liabilities too. With high inflation, hopefully that will bring down their liability.
Would you please cover Renold Paul?
Many thanks,
DH2.