Small Cap Value Report (Weds 14 July 2021) - ZOO, AGY, FIF, SHI, NUM, PMP

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Timing - today's report is now finished.
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
I enjoyed watching this webinar from our friends at PIWorld last night, with stock picker Richard Lennard. He always comes up with some interesting stock ideas, and I'm following up on his positive mention of recent float Made.com (LON:MADE) . Entertaining delivery too, he's quite a character! A lot of us did very well on Redde Northgate (LON:REDD) (I hold) at least partly thanks to his prompting last year.
Zoo Digital (LON:ZOO) - results from yesterday strike me as unimpressive. Very poor 21 year track record, of never really making any genuine free cashflow. Yet another placing done in April 2021. Why is this valued at £100m?
Finsbury Food (LON:FIF) (I hold) - this trading update sounds positive, but fails to explain the key point, whether the company is trading in line with expectations or not. I think in this case it's safe to assume it's doing OK, and by my calculations could be 7% ahead of market expectations for FY 06/2021. Looks good value on a PER of about 10.
Portmeirion (LON:PMP) (I hold) - H1 (quiet half) trading update doesn't explicitly state performance vs expectations (how annoying) but does imply that everything is fine. Nice turnaround underway here, and the valuation still seems reasonable. All-important H2 trading yet to come, but the "strong global order book" augurs well. Thumbs up from me.
Jack's Section:
Allergy Therapeutics (LON:AGY) - Revenue ahead of expectations and costs lower than expectations, so a good result. The allergy products pipeline looks intriguing but a market cap of £160m on little to no profits means that getting these products approved and commercialised is key.
Sig (LON:SHI) - full year profit outlook raised as turnaround takes root and the trading environment becomes more supportive. The shares have rerated from a low base and, while there is still potential upside providing management continues to execute, increased shares in issue limits some of that upside.
Numis (LON:NUM) - Trading remains strong at Numis, which is investing in its headcount and has a strong pipeline well into FY22. Business is cyclical, but the shares continue to trade on a modest PE and the near term outlook remains robust.
.
Paul's Section
Zoo Digital (LON:ZOO)
122p (down 3% yesterday) - mkt cap £100m
Final Results - for FY 03/2021
Unimpressive figures, which I’ve skimmed through -
- Revenue up 33% to $39.5m
- EBITDA of $4.5m isn’t real profit in my view, and turns into only $962k operating profit.
- Loss before tax of $3.57m is mainly due to a $3.47m “fair value on embedded derivative” charge - no idea what that’s for, do any readers know?
- Weak balance sheet, with poor working capital position, and negative NTAV - however this was rectified post period end with a £7.4m placing in April 2021. Although this does reinforce that ZOO is not generating much, if any free cashflow.
- Accumulated losses of $59.3m stand out, in the reserves section of the balance sheet. Is that all down to ZOO itself, or did it reverse into a cash shell with previous losses perhaps?
- Development spending of $1.27m was capitalised in the year, plus $2.29m of physical capex.
My opinion - I’ve followed ZOO for years, and it went nowhere in near-insolvency from 2008 to 2017. Then it suddenly shot up, something like 15+ bagging in 2018, but fell back some of the way when the hype turned into little real-world commercial progress - i.e. it’s never really generated meaningful profits or cashflow.
More recently, the strong share price rise (in an uncritical bull market) looks like more of the same to me. Lots of positive commentary/hype with the latest results, but a failure to generate free cashflows again.
Why would I want to invest in something that listed 21 years ago, and is still having to raise equity to keep the business functioning? I cannot see any evidence of a strong business model here. Yet enough people believe in it, to attribute it a £100m market cap. Good luck with that, the story looks very stale to me.
.

.
Finsbury Food (LON:FIF)
(I hold)
91p (yday’s close) - mkt cap £119m
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for both the retail and foodservice channels, is today providing an update on trading for the full financial year, ending 26 June 2021, prior to entering its close period ahead of the preliminary announcement on 20 September 2021.
This is one of my core value shares - low forward PER, well managed, trading well, sound balance sheet, high StockRank.
On 26 May 2021 it told us that trading was strong, and ahead of market expectations, with at least £15m PBT expected for FY 06/2021.
This is what today’s update says -
- H2 trading continued to be strong
- H2 revenues up 9.1% vs LY H1
- FY revenues up 2.3% to £313.3m - almost back to pre-pandemic levels, despite continued disruption to some of its markets (e.g. foodservice - i.e. cafes)
- Overseas (small part of the business) doing very well, FY revenues up 13.4% on LY
- Net debt has fallen from £21.5m to £13.1m in the most recent 6 months - impressive
- Cost/efficiency improvements ongoing with Operating Brilliance Programme
Outlook comments - rather vague, but this suggests more upside to come once foodservice gets back to normal -
Our Retail business performed very well and while our foodservice business has continued to be impacted by Covid-related restrictions, the performance of the division has continued to improve on a quarter-by-quarter basis since the outset of the pandemic…
Looking ahead, while the current operating environment continues to experience near-term uncertainty amidst challenging economic conditions, assuming trading conditions continue to normalise, we are confident in our ability to make further progress in the current financial year and in being able to deliver on our longer-term growth ambitions."
My opinion - a positive-sounding update, but conspicuous by its absence is any profit guidance! The whole point of trading updates is that companies are supposed to tell us how profitability is versus market expectations. FIF did that in its 26 May update, but ignores it completely today.
Given the 26 May profit guidance of >£15m PBT was quite recent, and today’s update talks about strong continued trading since then, I’m guessing that expectations would probably be at that level, or slightly better. We shouldn’t have to guess though, the company should have specifically confirmed guidance today.
It doesn’t help that there’s no broker coverage available to PIs either.
Using the StockReport consensus estimates, actual revenue of £313.3m is 1.1% ahead of £310m forecast. Net profit (after tax) of £11.2m forecast looks too low, as the company has previously indicated at least £15m PBT, take off say 20% Corporation Tax, and we’re at >£12.0m PAT, or 7% ahead of analyst consensus.
Looking at forecast EPS of 8.55p, if I add 7% onto that, then it comes out at 9.15p EPS for FY 06/2021.That’s a PER of 9.9, in a year that was curtailed somewhat by the pandemic.
This looks a modest valuation, and I think a PER of say 13-15 could be justified. Plus we might allow for (say) another 1p on EPS when foodservice fully recovers. Put that together, and my price target is 132-152p, or 45-67% upside on the current share price. That mainly hinges on my assumption that the earnings multiple should rise from c.10, to 13-15. The market might disagree, and leave it on a low PER, since it looks a fairly boring, ex-growth company. If the rating remains this low, then FIF could be a bid target possibly?
Dividend resumption should be on the cards too, and with a low PER, and modest net debt, the dividend paying capacity is quite high - e.g. it could pay out 5%, twice covered, a very attractive option for income seekers.
Inflation doesn’t worry me at this type of company, because it should be able to pass cost increases on to customers. We already know that the customers (supermarkets, etc) would switch to other suppliers if they could get the same quality at a lower price, so it’s safe to assume that FIF should be able to stand its ground if/when inflation feeds in, because the same cost inflation would impact its competitors too.
Overall then, a thumbs up from me, this share looks a good one for value investors.
.

.

.
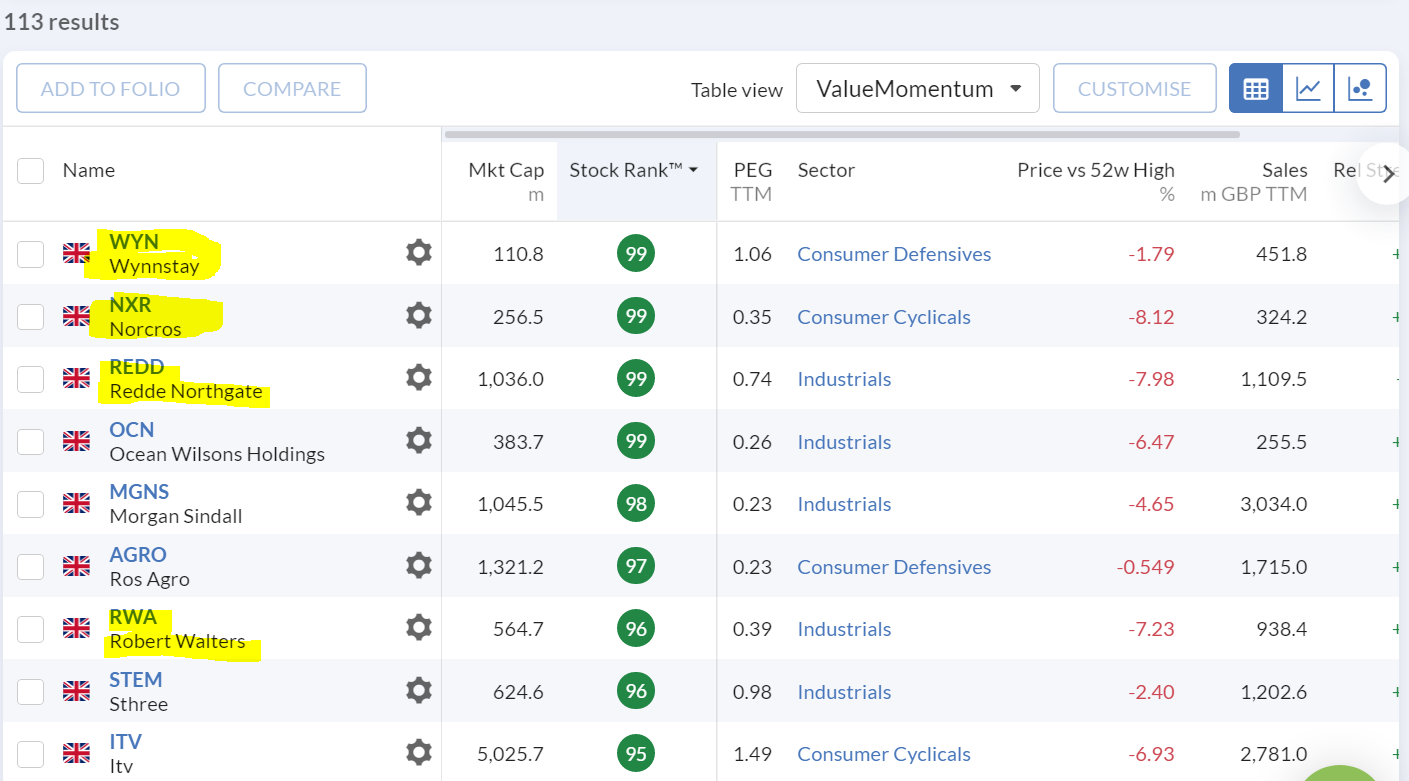
Incidentally, FIF qualifies for the Value Momentum Screen, so thought I'd take a look to find similar companies, and it comes up with some good stuff actually, see screenshots below, which I've sorted by StockRank (there are loads of other ways to display, and sort the qualifying shares using the "Table View" drop down menu, and clicking on column headings to sort by that variable). It's quite fun playing around with these screens, as they can throw up interesting shares.
.
I've highlighted below a few that I recognise from positive write-ups here in recent weeks -
.
Portmeirion (LON:PMP)
(I hold)
655p (unchanged, at 10:59) - mkt cap £92m
Before looking at this, I should point out that H1 for PMP is not very important, as it’s a heavily seasonal business that makes most of the profit in H2.
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands, updates on trading for the six months ended 30 June 2021.
Strong year-on-year sales growth
I would hope so, given that H1 LY caught the worst lockdown 1 period.
Sales here is the same as revenues (I checked the £32.0m H1 LY number to the previous accounts) -
Sales for the first half of the year will be approximately £43.0 million (2020: £32.0 million), representing an increase of 34% compared to the prior period. We were pleased to see sales growth across our three biggest geographical markets of the UK, USA and South Korea compared to H1 2020. We have also continued to see strong sales growth in online channels in our major markets.
Sales vs pre-pandemic level - this is much more meaningful, and is encouraging -
Against pre Covid-19 performance in H1 2019, our like-for-like sales at a constant currency are up by 6% (excluding the benefit of Nambé acquired in July 2019 and the remaining 50% of the issued share capital of Portmeirion Canada acquired in August 2020).
Divis/outlook - this bit is also encouraging I think -
Given the continued and sustained improvement in our trading, we re-confirm that we expect to resume dividend payments for FY21.
Current trading/outlook - I’m happy with this -
"We have continued to trade strongly in May and June and it is particularly pleasing to see that we are achieving like-for-like sales growth over pre Covid-19 trading levels, despite continuing disruption in our markets due to the UK's lockdown in Q1 2021 and ongoing Covid-19 related global shipping and supply chain delays. This performance demonstrates the strategic progress we are making as a business, including our online and digital transformation and rest of world sales growth.
We have a strong global order book going into our important second half trading period. Whilst we remain cognisant of the ongoing supply chain-related challenges, we remain confident of the trading outlook for the rest of FY21."
Diary date - 14 Sept 2021, for H1 results.
Dilution - unfortunately, the share count did rise in the pandemic from c.11m to 14m shares. Pity, as it probably wasn’t necessary as things turned out. Hence that means we need to take about 22% off previous EPS figures to lower them to the same level of profitability spread over the increased number of shares (assuming I worked that out correctly).
Peak previous earnings of about 75p would now be 58p for example. There could be upside on previous peak earnings, due to acquisitions, and efficiency improvements.
My opinion - unless I missed it, this update ducked the important point of specifying how PMP is trading versus market expectations. This should be explicitly stated in every trading update, from every company. With a footnote to give the figure for market expectations.
That said, there seems enough positive commentary in this to imply that it’s trading at least in line.
I like the turnaround here under the newish CEO, and the focus on online sales is important. Other problems seem to have been resolved too.
Overall, I think the valuation seems reasonable, possibly even cheap, if the full year numbers are hit - dependent on peak season in the run up to Christmas.
.

.
.
Jack’s section
Allergy Therapeutics (LON:AGY)
Share price: 25.59p (+2.36%)
Shares in issue: 641,772,718
Market cap: £164.2m
The Allergy Therapeutics CEO says it has grown revenue at a compound annual rate of 9% since its formation in 1999. This doesn’t quite come across in the revenue chart but clearly the trend since 2015 is encouraging.

Translating that revenue growth into profitability has not been so straightforward, although this too has started to tick up over the past couple of years.

This is a biotechnology company focussed on the treatment and diagnosis of allergic disorders, including aluminium free immunotherapy vaccines that have the potential to cure disease. It specialises in short course treatment technology platforms with promising potential in the US for its peanut, allergic rhinitis and immunotherapy treatments.
The group sells proprietary and third-party products in nine European countries and via distribution agreements in an additional ten countries. Its pipeline of products in clinical development includes vaccines for grass, tree and house dust mite, and peanut allergy vaccine.
- FY revenue to be up 7.8% to c£84.3m (+6% on a constant currency basis), ahead of expectations, but helped by a strong euro rate,
- Restrictions to travel and a reduction in scientific conferences have driven cost savings,
- Consequently expenses are expected to be ‘significantly lower than market expectations’,
- Cash balance at the end of June 2021 was £40.3m (30 June 2020: £37.0m)
Performance in Germany has been solid although the group has experienced weaker sales in southern Europe owing to more Covid-related disruption.
It says the regulatory environment continues to be ‘challenging’ and therefore investing in further market access and regulatory expertise.
Pipeline - the group expects results from the VLP Peanut ex-vivo biomarker study in Q3 2021. The results here will form an important part of its submission to the US Food and Drug Administration (FDA) for the opening of the Investigational New Drug (IND) application and pre-IND meeting, scheduled for autumn this year.
Manufacturing batch scale up has been successfully achieved to maintain product supply through the development programme and the first in-human Phase I trial is expected to commence in Q1 2022. It’s potentially a big opportunity for the group but commercialisation looks a little way off yet.
The exploratory field study in the Grass MATA MPL clinical development programme, G309, is underway with all patients treated and read out is expected in H2 2021.
Conclusion
There are two big pipeline milestones approaching in the form of the VLP Peanut ex-vivo study and the Grass MATA MPL exploratory field trial.
It sounds like there’s potential, but Allergy has also steadily diluted its shareholder base over time, which makes me slightly cooler on the stock.

The group does say that due to the higher revenue and reduced costs, it expects to be able to fully fund the Grass MATA MPL pivotal Phase III field studies and the Phase I Peanut programme with existing cash resources and a small amount of additional debt. So it’s possible that the days of steady equity dilution are coming to a close.
Still, looking at the long term share price chart, it’s hard to escape the feeling that this stock has in the past seriously disappointed the market.

Companies evolve and make progress though, and the investment case can change. The more recent trend in share price is encouraging. Allergy is growing revenue, costs have been (temporarily?) reduced, and the company is doing what it can to progress a pipeline that could have a lot of potential. Incidentally, it qualifies for the R&D Breakthroughs Screen.

And there’s been a swing in return on capital employed, up into positive territory. So it could well be that a lot of hard work and financial investment is beginning to pay off.

Meanwhile the balance sheet looks fine and the company is net cash. Tiny free float though - just 14.27% of shares in issue, with a spread of 400bps, and an EMS of 10k meaning only chunks of about £2,500 can be reliably bought or sold.
I can see things that make me wary here and also things of interest. FinnCap has a target price of 45p compared to today’s 25.6p. I tend not to attach too much weight to explicit price targets, but if they are materially above the current market price then that can indicate there’s something worth exploring in more detail.
At the current market cap of more than £160m and with little to no profits at present, the opportunity would have to be very compelling.
Sig (LON:SHI)
Share price: 49.04p (+2.34%)
Shares in issue: 1,181,556,977
Market cap: £579.4m
SIG might be classed as a Neutral stock but the truth is it’s firmly in ‘turnaround’ mode, with a sharp 2020 fall meaning the shares now trade on just 0.3x trailing twelve month sales.

It has been loss-making for four of the past five years and, even when this distributor of building products was profitable, margins were very thin.

But directors of the company have been buying stock recently, and the share price momentum since the start of the year has been positive. The finances are flagged as weak but it’s worth mentioning that nearly half of the group’s total debt is actually capital lease obligations.

Trading update - first half of the year
Strategy of re-connecting with Customers, Suppliers and Employees is positioning the Group well, enabling it to take advantage of both strong near-term demand and healthy long-term fundamentals… Full year profit outlook raised.
Highlights:
- Strong revenue growth with like-for-like (LFL) growth of 33% against Covid-affected prior year and up 1% against the same period in 2019, to £1.11bn
- UK distribution 2021 vs. 2019 LFL -19% to £244m,
- UK Exteriors +14% to £194m,
- UK total -7% to £439m,
- EU total +7% to £669m,
- Underlying operating profit of c£13.5m,
The group's ‘Return to Growth’ turnaround strategy is delivering improved organic sales performance, and has been supported by continuing robust demand in the repair, maintenance and improvement ("RMI") segments in most markets.
Group profitability improved throughout the period as a result of the normal seasonality in the business and the improving trading across the group. SIG finished the period with net debt of £58m (pre IFRS 16) and with gross cash balances of £174m. Reported net debt on an IFRS 16 basis is expected to be £284m.
The cash outflow was driven by the seasonal increase in working capital, which was more pronounced than usual due to the strong trading. SIG has also built up modest increases in inventories ‘in light of likely supply challenges in the coming months’. The group comments:
We are continuing to see shortages of materials in certain areas, as reported previously, and input price inflation remains significant in some categories. We have navigated these challenges with minimal impact to date, despite some longer delivery times.
UK - Good progress here and SIG expects to be just over break-even at the underlying operating profit level for H1, ahead of plan.
The UK Distribution turnaround is focused on delivering distinctive expertise and superior local service. It’s ahead of plan with continued momentum. The business's sales were on a declining trend throughout 2019 and most of 2020, and hence the 19% drop in UK distribution versus 2019 shown above. SIG expects positive growth figures in the second half.
The UK Exteriors business is trading well, benefiting from the strong demand environment.
EU - France is doing well, helped in particular by strong RMI demand in Exteriors, as well as the strong foundations built in the business in recent years. Germany also saw good growth throughout the half.
Benelux lags but the group has made changes in its commercial leadership and believes performance will pick up soon. Ireland was affected by the significant government restrictions and the group also expects to see improved growth in the second half here.
Conclusion
On the whole it looks like the return to profitability in H1 was faster and more significant than previously expected so there is momentum here. Material shortages and input price inflation are a concern - as they are right now with many other companies.
At the moment everybody is hoping this is a transient or at least containable trend, but there’s the possibility of it developing into something more sustained and problematic.
Regardless, SIG expects H2 to be both profitable and cash generative, with full year underlying operating profit expected to be ahead of previous forecasts. Worth keeping tabs on assuming societies continue to reopen - shares in issue have more or less doubled over the past couple of years but if it can recover to its old market cap, that would still be more than 80% upside.
That’s not a sure thing, of course. There’s always execution risk in turnarounds and SIG is low margin at the best of times, but currently the group is being helped by a more supportive trading environment.
Numis (LON:NUM)
Share price: 372.90p
Shares in issue: 107,767,448
Market cap: £401.9m
With all the placings and IPOs that have kept the market busy over the past year or so, it’s no surprise to hear from the horse’s mouth that brokers and investment bankers like Numis are doing well. These are cyclical businesses but everything’s going well at the moment - is this as good as it gets for the share price, or is there further to run?
The share price has not spent long in the high 300s in the past.

But these are exceptional times and there’s a chance pent up demand could drive a further rerating given the group’s modest valuation.

Following the very strong trading over the first nine months, we look forward to reporting a record performance for the full year.
An unsurprisingly strong Q3 performance with revenue in excess of £50m. This is slightly lower than the H1 run rate, but is still up on the same period a year ago which benefited from a lot of COVID related deal activity.
Investment Banking and Equities are doing well thanks to investment in clients, talent, and growth initiatives. Work is ongoing to diversify the business by product and geography. Overall, year to date deal volumes and average deal fees are materially ahead of the comparative period.
IPOs contributed in the quarter, but M&A advisory and Growth Capital Solutions for private companies also continue to deliver strong momentum. These areas are where Numis sees scope to expand and improve the quality of its deal flow. It also sees a clear opportunity to expand its Equity Capital Markets offering outside the UK.
The Equities business delivered another strong revenue performance, consistent with recent quarters. Market volumes and activity levels declined slightly but Numis continued to gain market share.
Conclusion
Numis is investing in investment banking talent and will continue to add further headcount over the next few months to support its ambitions. It looks like an operator very much in a position to take market share amid strong trading conditions.
I don’t see why the supportive backdrop would change any time soon. The group itself says that its pipeline for the remainder of the year, and into next, ‘remains very strong’. Assuming it can continue its trailing twelve month performance then the shares trade at 7.9x earnings, which looks cheap given the positive commentary.
Conditions will inevitably turn at some point but there’s nothing on the horizon just yet. So for now this is a high QV stock earning excellent returns on capital with a strong pipeline stretching well into FY22.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Zoo are forecasting that turnover will hit a 100m in less than five years having grown over a third in the last year. The share price is up some twenty percent since the last stockopedia comment
Hi Paul, Jack. Is it worth adding Saga (LON:SAGA) ticker in the title of today’s report so that we can track the good and detailed (and entertaining) discussion for future reference?
If it is not too much trouble, this could be a great addition for future reports? Thanks.
My comparator for Made.com (LON:MADE) (no position) is WestWing (WEW - I hold), a German-based company which essentially does the same thing, but on the European mainland.
I believe that WEW plan to expand into the UK shortly.
Looking at 2020:
Made.com had a negative Adjusted EBITDA for 2020, but it looks inevitable that this will be positive going forward given the company's growth.
On points 1. and 3. I think WEW offers more value in this space, but as a holder I would say that.
That's not to say that I don't see potential in Made.com. Quite the contrary. I think it's a well-known brand and growth is inevitable. But I also think the market is going to soften this year after so much confinement, so if I was going to buy in, I would probably do so towards the end of the year, or at least after a few results have been announced.
GrahamScott,
You mentioned container costs going through the roof.
A few months ago I actually asked WEW IR's about their logistics expectations for 2021. They didn't reveal much, but they seemed to imply that prices have indeed gone up, but they weren't worried about it. I got the same impression from management from the WEW Investor calls I have listened into.
Purely for reference, in 2020 shipping was 9.77% of WEW's revenue. So even an increase in container costs on the Far East ---> Europe segment shouldn't have too much impact on the bottom line.
Cheers
A
Abtan
A few months ago the expectation was that shipping prices were going to drop down to $4000 at the time they were around $10000. My company operated off the back of a major UK budget retailers shipping contract so we were on a 1000 container per year rate. According to our shipping agent he’s hoping to see rate drop by a couple of thousand over the next month but still nowhere near pre COVID rates. The issue is due to….
- Some ships still mothballed so lack of space
- Severe shortage of containers in China.
- Shipping lines not budging on rates. I’ve heard rumours that this last quarter they’ve made more money than they have for the last 5 years combined.
Maybe I should be looking at buying CMA CGM, EVERGREEN or MAERSK shares?
EVERGREEN MARINE share price a 10 bagger since container crisis started although a 10% drop today so maybe container prices are expected to drop
Saga (LON:SAGA)
I haven't looked into Saga (LON:SAGA) in any detail whatsoever, so apologies for my ignorance here (and my laziness in investigating myself), but my general perception was that that they have done quite a few fundraisings over the last 18 months.
I imagine there was a refinancing in there, presumably for a lower interest rates, which would make sense, but didn't they also do an equity raise about a year ago (well after lockdown 1) to keep the business afloat?
If they have been able to operate at breakeven since March 2020 and can do so for the foreseeable future, what was the point in doing any fundraising at all?
Or am I completely misunderstanding something?
A
Hi abtan,
All the information you need is here, my summaries of SAGA news releases, in readily digestible format, I hope :-)
Regards, Paul.l
Saga (LON:SAGA)
Thanks Paul
I honed in on your post in September 2020, shortly after the Saga (LON:SAGA) equity raise I was thinking about:
https://www.stockopedia.com/co...
It's insightful, but I still don't understand why the equity raise was required in the first place if cash generation was never going to be a problem.
I thought I had read an RNS about this raise, which didn't really give a convincing rationale for the decision, but I'm assuming there's a more detailed RNS out there that I haven't read.
Anyway I doubt I'll get time to look into this one in detail, and I was merely curious, so I will leave it there.
Cheers
A
Paul, Richard Lennard talking about Made.com (LON:MADE) on the PiWorld webinar definitely fired my interest in the company. Hope you are able to share your view once you've had a chance to look into it.
I'm stake building every day in Made.com. Most investors appear to not be understanding how they operate. Disruptor, D2C model (thereby able to offer better value to customers as many middle men are being cut out), capital light business. They raised 63m up until 2020, created a 315m revenue business with that and still had 40m cash left in the bank at the end of 2020 (which is nothing but amazing). Returns rates are low at 6%. They are already profitable (accounts here don't show that because income had to be deferred due to delayed lead times). Rather than a 3m loss, they have actually made a 5m profit (so they are already EBITDA positive). Further unwinding of deferred income is coming into affect which will boost revenue more. They are 63% (!) up on sales in Q1 2021. Highest margins in the sector. The last time i was so excited about a UK company is when i discovered Reach PLC in April 2020. I have a research piece that was released on 8th August and the figures are mind boggling.
What did anyone else think of the System1 (LON:SYS1) results today?
Light on current FY outlook, but it seemed impressive that they managed to limit revenue drop to -10%, and more interestingly, cut loads of cost (plus also some covid support) to drive an increase in adj PBT!
Suggests to me that management used the COVID period to really restructure the business, and that we might see a leaner, more profitable business emerge.
Then there is the big question on their key asset - ads database - and whether their SaaS product called Test Your Ad can be the growth driver. Should have huge operational leverage, as its subscription based and high gross margin, not needing warm bodies to deliver ongoing value to clients, unlike the rest of their agency-like business.
My calc is there even if we take historic earnings just passed (statutory EPS of 13p) and assign a modest PE of 17-25x (assuming revenue and EPS growth in the years to come) it should be trading at a 220p-325p range, with the current share price at only 220p, offering some good short to medium term potential.
(I Hold)
I must say I was astonished that they stated that in the future the business could be worth £1 billion. I would be delighted just to get back to the sp I bought at some years ago! Lol
Well.... always good to see management with big ambitions :)
In truth, there's a very small outside chance that Test Your Ad gains so much traction that it is the default ads measurement system used by all companies globally, to measure and benchmark performance. I buy the argument: so far, in marketing departments, only digital marketing has been thoroughly forced to have robust performance measurement. Most Above The Line (ATL) marketing departments has so far escaped the Performance scrutiny. But everywhere, CEOs and CFOs are demanding ways to measure marketing performance, whether ATL or BTL.
Kinda how like YouGov is now de-facto first (and possibly only) choice for measurement in many areas, and generates profits hand over fist.
Problem is - System1 has been a serial disappointer over the years. Is this time different?
Betaville has further details on the rumoured private equity approach to Redde:
"TDR Capital is said to be the private equity firm that has been circling Redde Northgate, the London-listed vehicle management company.
People following the situation said that TDR Capital is rumoured to have approached Redde Northgate about buying the business for 475p a share.
However, it's believed the approach may have been rebuffed because the company and some of the group's shareholders won't accept less than 500p a share..."
I certainly would not be at all happy to sell for 500p. Though my vote would be akin to a butterfly flapping it's wings.
Hi John,
Thanks for posting that about £REDD
It reinforces the awful system we have here, in that companies only report takeover approaches to the market (i.e. their smaller shareholders!) when forced to do so because the story has leaked to the press. Pathetic.
I did think it was odd that REDD shares spiked up to 450p intra-day yesterday, then came back down to c.410p again, so looks like there might have been some insider trading going on there? I just put it down to a fat-fingered trade at the time, but maybe it was worse than that?
In my view REDD is worth more than 500p, but I'd gladly accept 500p because it's 20% more than the current market price, and I could then recycle the money into something else that doesn't contain a bid premium in the price.
Will be interesting to see if REDD confirms the takeover approach or not. It should do, as that's price sensitive information.
Regards, Paul.
Hi Paul and Jack, I just noticed that all the ticker tags apart from Numis (LON:NUM) have dropped off the bottom of the report and I've raised it on the green button. Just thought I'd check if that was the right thing to do?
Hi Indie,
Yes there's a bug in the system that occasionally deletes all the tags flagging up the tickers, so thanks for pointing out that this seems to have happened today. They've reappeared, so maybe someone at HQ put them back in? Or they might reappear automatically, I'm not sure.
But yes, do flag missing tickers with the green blob, or with a comment here, as I might not spot it.
Thanks, Paul.
Hi Paul, yes, Chris of the Green Button reinstated (most of) them - you had Redde Northgate and Made.com as well.
Great to hear, thanks Chris at HQ! :-)
re: Allergy Therapeutics (LON:AGY) (I hold)
the net profit figures for this company are misleading as the company is spending it all on R&D for the peanut and grass allergy treatments. If the R&D efforts came to nothing there would still be a profitable operation left selling the existing treatment portfolio. The grass allergy treatment is about to enter phase III so is at an advanced stage of development. As biotechs go I think there is a greater margin of safety than most thanks to the existing portfolio along with a potential new product upside with a huge addressable market.
Accrol Group (LON:ACRL) FY21 results released today, there are CV19 adjustments, however, gross margin up 5.8% to 27.7%. Market share now 15.9%. Outlook in line with expectations. Management will give us the full story of how their strategy is coming together. We look forward to hearing more from management tomorrow, 15th July, 1.15pm. Register here.
Paul, many thanks for flagging the PIWORLD interview with Richard Leonard. Yes, he's very entertaining and has some great picks. This one has been very popular, which makes doing these worthwhile!
Open Orphan (LON:ORPH) spin-off Poolbeg Pharma priced at £50m for IPO. July 19 admission.
Open Orphan (LON:ORPH) (I hold) - Cathal Friel, exec chairman bought £300k of shares at 26.5 p, as he suggested he would, plus more by a non-exec. That won't do any harm.
Trading ahead of expectations and a positive note from Liberum on Science In Sport (LON:SIS) , including a comment on possible acquisition regarding their price target. Any observations here?
We'll have a look at Science In Sport (LON:SIS) if there's time. Thx for flagging, I hadn't spotted it's trading ahead of exps, we always like to focus on those, rather than boring in line stuff..
Many of us hold Sylvania Platinum (LON:SLP) which continues to fall on no Company News.
In the past this stock has been volatile but current fall is really strange when you look at the fundamentals. I would be interested in Jacks view as he has a very deep knowledge of the stock based on his excellent Reports.
I posted this yesterday:
Sylvania Platinum seems to be taking a beating over the last few months, again on no news. The price of Rhodium has dropped by nearly 50% from its highs earlier this year but still, the business remains significantly undervalued.
I know there is political instability in South Africa at the moment which will no doubt make some investors nervous. AA might be selling in the background too. Lots going on without any real news from the BoD at SLP.
Either way, business is ridiculously cheap considering EV stands at £260m with £60m cash in bank, generating £90m net profit this year potentially and even more cash.
I can only assume it is because the PGM prices are well off their highs.
Tharisa (LON:THS) is in the same boat, excellent results but despite numerous investor presentations price just remains a week
Rhodium price is well rising this week from 17.5k to 19.7k (matey), but if you are going to check the news, sad ones coming up about South Africa: https://www.bbc.com/news/world...
Sylvania Platinum (LON:SLP) Rhodium prices are back down to the levels at the end of Jan.
The third wave of Covid is severe there with about 350 deaths per day recorded. The daily figures are erratic but it may have peaked now.
Rio declared force majeure and halted operations at Richards Bay due to violence and civil unrest including the killing of their mine general manager.
There is massive civil unrest in many regions of South Africa. I'd regard that as a good reason to be worried. Oh, and of course covid.
It's unfortunate that the Sylvania Platinum (LON:SLP) share price has declined in recent days but this is likely to be temporary noise. Fundamentals are still very strong. Investors are probably concerned about the situation in South Africa and whether things could deteriorate further. If it does, PGM prices are likely to increase due to a lack of supply. Hence, considering the longer-term, I feel there's a reasonable margin of safety and I'm not too concerned for now.
Are you going to be covering MADE Paul?
Certainly peaked my interest. Not much on stockopedia as it’s a fresh IPO. RNS yesterday- Directors have set their bonus targets at achieving between 25-36% CAGR revenue growth and eps at 3.5-5 eps by 2023. Given its loss making currently this would suggest that it’s about to reach scale and turn positive.
Three months to March they have experienced circa 60% revenue growth compared to previous year and 70 million cash in the bank.
Made.com (LON:MADE) I saw the video and was intrigued by MADE. The customer feed back is truly appalling and has put me off completely. Paul
How does it compare to DFS for example? https://uk.trustpilot.com/revi...
made.com has over 4 stars on trustpilot which for an online furniture store is incredibly high. In my past life I ran an e-commerce business selling amongst other things mahogany furniture. Delivery is a nightmare and couriers do break things so bad reviews are expected. I think a better comparison for made.com would be IKEA.com or IKEA.co.uk both of which are in the low one stars…
https://uk.trustpilot.com/revi...
My main concern for made.com is there manufacturing base which is mainly the Far East from what I can deduce. Nothing wrong with quality but shipping costs have gone through the roof. When I sold our business and retired in September 2020 I was bringing in 100 x 40ft containers a year at a shipping cost of $1400 per container. Speaking to the new owners it’s now $16000 per container. If you’re importing 3 piece suites then you’re only going to get a maximum of 20 in a container, that’s a minimum of £600 added to your landed cost per suite. Hopefully they’ll look at moving more production to the Uk as the savings in China manufacturing is being lost at this present time.
Made.Com (LON:MADE)
Where are these reviews?
On Trustpilot they are pretty good.
Are you going to be covering MADE Paul?
Probably not here. But will mention it in passing if I do get round to looking at the IPO Prospectus at some stage. There are so many companies to look at, that it's all about focusing on the things where I see obvious upside.
Hi Paul and Jack, I’d be glad if you could take a look at the trading update from £NUM.
Moves from Neutral to Contrarian.
(I hold)
Indie, you need a space after your ticker as periods, commas etc kills the link. I hold Numis (LON:NUM) and have been waiting years for it to perform for me.
Cheers.
Thanks, Silver Moon
Numis (LON:NUM) pls
Also do any of the readers rate £A2M A2 Milk ? The stock price has come off a lot from highs but it has a unique product (a certain grade of milk and is a health trend) and is rerating in terms of value.
Seems £A2M is an Australian stock?
Yes, but I think it could be a winner!
But this is for U.K. small caps.
My morning smallcap tweet: 23 companies today
Open Orphan (LON:ORPH) Avon Rubber (LON:AVON) Symphony Environmental Technologies (LON:SYM) £7DIG Water Intelligence (LON:WATR) Avacta (LON:AVCT) Allergy Therapeutics (LON:AGY) Alpha FX (LON:AFX) SIG (LON:SHI) Kanabo (LON:KNB) Numis (LON:NUM) Kromek (LON:KMK) Fulcrum Utility Services (LON:FCRM) Good Energy (LON:GOOD) Mission (LON:TMG) Intelligent Ultrasound (LON:IUG) Portmeirion (LON:PMP) Finsbury Food (LON:FIF), Arecor Therapeutics (LON:AREC), Science in Sport (LON:SIS), DP Eurasia NV (LON:DPEU), McBride (LON:MCB), IQE (LON:IQE) M Winkworth (LON:WINK)
Open Orphan (ORPH) €900k contract win. [SP=25.25 Cap=169m]
Avon Rubber (AVON) becomes Avon Protection. [SP=2494 Cap=774m]
Symphony Environmental Technology (SYM) FDA approval for d2p antimicrobial food contact technology, for a much greater loading of the d2p technology, and also wider use. "We are confident of announcing the start of commercial sales during this year and in the medium term, generating significant revenues from d2p treated films." [SP=19.03 Cap=34m]
7digital (7DIG) wins contract extension to 2023 with its global technology company customer. [SP=0.93 Cap=25m]
Water Intelligence (WATR) $9.5m placing at 920p, a 2% discount, for working capital to fuel further momentum in growth. [SP=935 Cap=145m]
Avacta (AVCT) gets ISO 13485 certification so its CE mark for the AffiDX® SARS-CoV-2 antigen lateral flow test can be transferred to Avacta from its partner, Mologic, [SP=135.5 Cap=344m]. I'm short.
Allergy Therapeutics (AGY) guides FY(June) rev £84.3m, ahead of market expectations, up 8% (6% constant currency basis). Expenses significantly lower than expectations due to covid. [SP=25 Cap=160m]
Alpha FX (AFX) guides FY(Dec) above expectations as H1 rev rose 89%. [SP=1545 Cap=633m]
SIG (SHI) guides FY(Dec) op profit ahead of previous forecasts as H1 U/L op profit hits c. £13.5m, better than previous expectations. [SP=47.66 Cap=563m]
Kanabo (KNB) medicinal cannabis cartridges will be available shortly for UK patients. "This delivery will fulfill Kanabo's key milestone of the 'Sale of the Company's Medical Cannabis Products in a Primary Market'." [SP=16.01 Cap=59m]
Numis (NUM) Q3 rev over £50m, slightly lower than the H1 run rate, but up on 2020. "We look forward to reporting a record performance for the full year." [SP=371.5 Cap=400m]
Kromek (KMK) wins new contracts and repeat orders across all of its target segments: £173k nuclear detection, $84k repeat order in medical imaging, $250k insecurity and £349k in biological-threat detection. [SP=16.24 Cap=70m]
Fulcrum Utility Services (FCRM) £4.9m multi-utility infrastructure contract for a major new employment park. [SP=31 Cap=69m]
Good Energy (GOOD) defends rejection of 340p offer. [SP=321 Cap=53m]
Mission Group (TMG) guides H1(June) rev up 9% and op profit £2m (-£1.8m), ahead of the Board's expectations. [SP=74 Cap=67m]
Intelligent Ultrasound (IUG) guides H1(June) rev up over 40%, mainly due to the simulation division. Op loss £2.3m (£2m) due to planned increases in R&D, office and warehouse expansion. "2021 is therefore expected to be a year where we will continue to invest heavily in R&D, but also focus on generating the compelling key opinion leader study data..." [SP=14.66 Cap=39m]
Portmeirion (PMP) guides H1(June) rev up 34% and up 6% LFL at const FX on 2019. "We have a strong global order book going into our important second half trading period. Whilst we remain cognisant of the ongoing supply chain-related challenges, we remain confident of the trading outlook for the rest of FY21." [SP=668.9 Cap=94m]
Finsbury Food (FIF) guides H2(June) rev up 9% and FY up 2%, almost at pre-pandemic level. "Assuming trading conditions continue to normalise, we are confident in our ability to make further progress in the current financial year." [SP=91 Cap=119m]
In line: Arecor Therapeutics (LON:AREC) Science in Sport (LON:SIS) DP Eurasia NV (LON:DPEU) McBride (LON:MCB) IQE (LON:IQE)
[Edit] M Winkworth (LON:WINK) buried in dividend RNS it guides FY beat. 2.2p + 2.6p special divs for Q2.
I see that over the last 15 days Saga (LON:SAGA) has dropped from £4.50ish to around £3.50 with no obvious reason. Anyone have any idea why this is the case?
It is now very close to dropping below its 200 day MA which is often a trigger for many other people to sell which would only lead to a further drop.
Personally I still see this as a long-term hold and might take this as an opportunity to pick up a few more. My only suspicion is that with further uncertainty around Covid people are worried about the recovery, but I feel that whilst we may have further short-term trouble ahead, longer term we will be back to normal and hopefully full-steam-ahead.
Saga (LON:SAGA)
I think leisure stocks in general have not done well recently - looking at the rise in covid cases for the last month that really tells us everything we need to know - I think the trend here is bot as good as some (me included) may have hoped for. This tallies with the murmurings of discontent from some about normal life resuming next week. Also saga has had fantastic run up in shareprice last 12 months one has to expect some pullback at some stage most of the time after chomping gains.
I think many people think of Saga (LON:SAGA) as simply a travel business and so when COVID concerns surface it sells off with all the other travel businesses. Thing is, it’s not just a travel business, it’s a travel and insurance business (about 50:50 split). Admiral (LON:ADM) reported a few days ago with a big earnings beat in part because there are fewer car accidents with so many people no longer commuting. Saga’s insurance business will be similarly positively effected and unlike many parts of travel, cruises are now going ahead and very well booked. Recent sell-off therefore looks wrong to me and should correct when they next report their half-year results.
Saga (LON:SAGA)
Nebraska1977
"I think many people think of Saga (LON:SAGA) as simply a travel business and so when COVID concerns surface it sells off with all the other travel businesses"
I think the market knows the score here that its not all about the travel buisness- note you cant argue though that they have spent huge wad on cruise ships and that the cruise prospects are important if they want to return "chomping profits"
" Recent sell-off therefore looks wrong to me and should correct when they next report their half-year results. "
Have you actually looked at year earnings forecasts recently per stocky for this current year? ( yearend next january) they have halved in the last 3 months!! and these downgrades include downgrades in the last month - not exactly steaming ahead news really ? As other have said (Pauls great chart comparison with carnival illustrates this well) i do feel this is natural noise and the downgrade is no biggie IMHO with regard to long term prospects - great chance for one to add some more if one is confident of prospects.
If you want to read into the tealeaves somewhat i was watching this interetsing video recently that comments on statistical analysis that suggests that stocks that have performed super well in recent past well are prone to underperforming the market short term after that spurt - whereas poor recent performers tend to outperform - i like to run my winners much more now personally than i used to but there does seem some arguments here that one should not be averse to banking some profit aftyer a good run. I can't really comment on how solid the stats are being refernced in this video so could easily be hocus pocus - i would at least want to see how and when they poick the winners and losers - its easy to find results you wnat to see like this if you look hard enough unfortunately.
Hi KevinS1,
Saga (LON:SAGA) (I hold) is unusually volatile. However, if you plot it against another travel company (even though SAGA is a hybrid travel/insurance group), it's remarkable similar - see chart below of SAGA & Carnival (LON:CCL)
It's all just background noise anyway. SAGA's finances are bulletproof since the recent second bond fundraising, it can ride out any eventuality.
It doesn't matter to me if it's £3, £4, or £5, because as a long-term holding, my target is £12+
It amazes me how short-term the market is in its thinking. Every twist & turn of the covid situation seems to cause exaggerated movements up and down. Best to completely ignore it, in my view, and think long-term on stuff like this.
It amazes me how short-term the market is in its thinking. Every twist & turn of the covid situation seems to cause exaggerated movements up and down. Best to completely ignore it, in my view, and think long-term on stuff like this.
RE: Saga (LON:SAGA)
Well, that's the opportunity for private investors, isn't it? When a lot of the investment industry is short-term focused or driven by automated trading programs our edge is patience.
But you can see why investors are nervous about the cruise industry - it's just been reported that a cruise to nowhere in Singapore has had to be quarantined because a fully vaccinated passenger has tested positive.
https://www.straitstimes.com/s...
Normality, in some form, will resume at some point but international travel looks like being constrained for some time to come because it relies on cooperation between governments, none of whom have a clear plan for themselves, let alone other nations.
timarr
This highlights another problem. Towards the end of the article it mentions that the passenger's test turned out to be a false positive. Operators will find it difficult to handle this situation in the absence of a more accurate test that can be applied onboard.
RE: Saga (LON:SAGA)
This highlights another problem. Towards the end of the article it mentions that the passenger's test turned out to be a false positive. Operators will find it difficult to handle this situation in the absence of a more accurate test that can be applied onboard
The false positive was a previous cruise, the current case has been confirmed.
In fact the current case wasn't detected on board - they were identified as a close contact of a confirmed CV-19 case (presumably from prior to boarding), were isolated as a precaution and then turned out to be positive through a PCR test. They'd tested negative using a lateral flow test before the cruise.
All off this is going to be normal from now on - the question is to what extent we can live with CV-19 cases around us. If everyone on the cruise was vaccinated would it be reasonable to just carry on? Given that vaccinated people can still catch it and transmit it can they be allowed off the cruise and allowed to mingle with other people?
I don't know the answer to any of this and, as far as I can tell, neither does anyone else.
timarr
Saga (LON:SAGA) well said Tim,
Also, people can still die even if vaccinated or get long covid, so this is not risk-free. With an absent government possibly they will have to get everyone to sign a waiver to avoid liabilities.
BSV
Spot on. I've been on several cruises - it has been and will continue to be a breeding ground for covid. Even if the passengers themselves are meticulous (and they are not - hence sporadic bouts of norovirus!) and are all double vaccinated the crew live in cramped conditions and are far more likely to pick it up and spread it themselves and possibly try to hide it (they rely on tips) making it more prone to spread. Until it's able to be treated like a cold/flu by authorities (I.E. ignored) being on a cruise is off my agenda. Whilst a lot of companies cater for families or younger cruisers SAGA is firmly at the older more vulnerable end of the market - we know being double jabbed stops 90%+ of infections but an outbreak on one of their boats could easily put dozens of passengers in hospital or worse. Add in the costs of mothballing these new boats. Still a massive risk in my opinion.
"we know being double jabbed stops 90%+ of infections"
Sadly that's not true. It stops 90%+ of hospitalisations (for a period of time, as yet unknown), not infections . The most recent study by Israel's health ministry estimates that a full course of the Pfizer vaccine is 64% effective against infection by the delta variant (somewhat lower than previous estimates and may not fully account for asymptomatic infection). Which figure is more important depends on the question. While the hospitalisation figure is more important overall, in some cases the infection rate is more important.
Take the issue of herd immunity, which is now being discussed again. The Lancet says that R0 for delta is between 6 and 7. Let's say 6.5. If the vaccines were 100% effective, you could achieve herd immunity by vaccinating about 85% of the population. If the vaccines are about 70% effective, you would need to vaccinate about 120% of the population, i.e. you cant do it.
This means that on the typical Saga (LON:SAGA) cruise there is no such thing as herd immunity. Once onboard the disease will spread, even if everyone is double vaccinated. When that happens, current data says that about 5 to 10% of cases would require hospitalisation. Perhaps this figure would be significantly higher given the demographic of a SAGA cruise.
The vaccines are superb but they do not solve all our problems.
The most recent study by Israel's health ministry estimates that a full course of the Pfizer vaccine is 64% effective against infection by the delta variant (somewhat lower than previous estimates and may not fully account for asymptomatic infection).
RE: Saga (LON:SAGA)
There are quite a lot of questions over that Israeli study - largely because the data isn't in the public domain. However, it did show 93% effectiveness against serious illness so it's not all bad news.
But even so, in a closed environment like a cruise ship that suggests that a significant number of people could end up in hospital if allowed to run rife. In addition the limited data around hospitalisations of fully vaccinated people seems to suggest that they're older and often immunocompromised - which sounds like it could include a lot of regular cruisers (not that I'd know).
If we assume that CV-19 isn't going to go away and there will be new variants - virtually guaranteed while significant percentages of the world's population remain unprotected - then this looks like an ongoing problem for cruise ship operators. We have to learn to live with the disease but not all business models will survive intact.
timarr
I agree that the cruise operators are vulnerable, with Saga (LON:SAGA) perhaps being more vulnerable than most.
As mentioned in my previous comment, herd immunity is impossible by just relying on current vaccines, so once the virus is onboard, they either have to do some kind of lockdown, or, given time, everyone onboard will end up being exposed. If they do a lockdown, not many of the passengers will regard that as money well spent. But if they don't, and everyone is exposed, then possibly 5%+ of the passengers would require hospitalisation, perhaps even more in a Saga demographic. The average cruise ship (I read) has 3000 passengers, so on those figures, 150+ people would have to be evacuated from the ship for urgent hospital treatment in some already over-stretched foreign country. Given that, an onboard lockdown is the only viable option. Some holiday that would be.
The world's press would be all over a story like that and I think it would come as a shock to many people who want to believe that it's all over and that "freedom day" has now arrived. I can see an explosion of demand for cruises followed by a collapse after the first problems occur.
The average cruise ship (I read) has 3000 passengers, so on those figures, 150+ people would have to be evacuated from the ship for urgent hospital treatment in some already over-stretched foreign country.
When I read that I didn't believe it but it's correct, based on the latest numbers we have for the delta variant.
That led me to looking at who is still vulnerable in the UK population. There are about 2 million over 50's who aren't fully vaccinated so if there are another 5% of the vaccinated group for whom the vaccines haven't worked there are still 3 million people at risk here.
With CV-19 spreading like wildfire in the younger population it's inevitable it'll work its way up the age groups over the next few weeks. I suppose the most at risk group are older people who don't believe CV-19 is real and are no longer protected by others social distancing, so that'll make for some very odd ICU interactions.
On balance I think travel and hospitality companies are still quite risky propositions in the short term. As for the longer term, who knows?
timarr
CMP/ Timarr, excellent comments, however is the 5% hospitalisation ratio in vaccinated people actually correct?
This is one of the few sources that I could find which relates to hospitalisations after vaccination in symptomatic individuals. I believe a great proportion of those who contract covid-19 are asymptomatic- this data doesn't include them in the analysis (which much skew it). Also only 166 of the symptomatic 14019 were hospitalised i.e. c.1%
It refers to 96% effectiveness against hospitalisation with Pfizer and 92% effectiveness with Oxford/Astra. I'm no expert but surely this means that only 4-8% of hospitalisation will occur in a vaccinated cohort . e.g. if 10% (I've got no idea if this accurate) of unvaccinated people need hospital intervention then in the vaccinated cohort then 4-8% of 10% should end up in the hospital (.4-.8% on average) or 4 to 8 people per 1000.
6 (on avg) people at sea in need of hospital treatment clearly isn't ideal. So we're still left with the same conclusion which is widespread lockdowns onboard to prevent that outcome (or worse if everyone is over 65). Not ideal at all.
To put myself in the position of the cruise ship operators I would counter that everyone is tested pre-boarding, they wear masks when in circulation and on some cruiselines they are all double vaxxed so likelyhood of breakthrough covid in enough passenger saturation to yield hospitalisations is vanishingly slim.
On balance though given the international docking risk, I agree that international cruising will likely remain off the cards until the current peak crests and cases are low in the UK and welcoming destinations.
-----------------------------------------------------------------
I may have got the wrong end of the stick here so please send across any links you may that are relevant.
Mentioned link:
https://khub.net/web/phe-natio...
Anyone interested in cruise ships, whether as investor or traveller, should read the Green Eye column in th current Private Eye (p.23, cont p94). It highlights the environmental and non-COVID health damage done by cruise ships. They would be a deserving target for a global tax to cover the costs of the damage, if there were such a thing.
I cannot gine a link because the article seems available to subscribers only on line.
I have no position in Saga (LON:SAGA) or any other cruise company.
Richard
exactly my thoughts Paul. And of course with Boohoo (LON:BOO)
Thanks Paul. Hopefully you are 100% correct and we will look back on these small movements as "noise" in a few years time. I shall continue to be happily invested in Saga (LON:SAGA) and await the rewards.
Thanks for your continued work - its amazing what you get through and how you have such a brilliant ability to turn complex sets of numbers and commentary into such a superb and easy to understand summary - Jack as well. Thanks to you both.
SAGA's finances are bulletproof since the recent second bond fundraising, it can ride out any eventuality.
Net debt is 2.9x EBITDA, the bond issued came at an increased fixed cost 5.5% Vs 3.375% = +£5.3m interest. Pre this bond issue cash burn was at the lower of a range £7-9m. This compares to liquidity of £78m.
Willingness to rebook has helped cashflow, as long as this continues things are ok for now. At best they have twelve months to improve cash burn so the deterioration in the outlook for travel as a direct result of lack of vaccination in other countries and spread of Delta , understandably impacts the outlook. A further equity issue can not be ruled out... so not bullet proof IMO.
RDHOWARTH - Saga (LON:SAGA) isnt burning cash. The numbers you refer to - I think - are for the travel division only. In 20/21, the company as a whole was actually slightly cash generative.
Apologies should have said travel cash burn £7-9m .... compared to liquidity of £78m. A numbers of things combine to give the group outcome. Cashflow in Ins can be somewhat unpredictable.
Best news I can foresee for travel sector would be a Western Vaccine initiative to help those countries without their own programme.
Hi RDHOWARTH,
Sorry a lot of that post from you is incorrect!
Pre this bond issue cash burn was at the lower of a range £7-9m
No! that is the cash burn from the travel division only. The insurance division generates a similar amount of positive cashflow, so the business can operate around cashflow breakeven forever, even with the travel division mothballed.
... liquidity of £78m
It's way more than that now, and the bank debt has been fully repaid.
Willingness to rebook has helped cashflow
No it hasn't because all customer deposits are held in a trust account, and not used by the company. They only turn into company cash once the cruise or tour begins.
At best they have twelve months to improve cash burn so the deterioration in the outlook for travel as a direct result of lack of vaccination in other countries and spread of Delta , understandably impacts the outlook
Completely wrong, because it's not burning cash (see explanation above).
A further equity issue can not be ruled out... so not bullet proof IMO.
They wouldn't have refinanced with the bond, if another equity placing was on the cards.
Overall, I'm encouraged by your post, because it shows that some investors misunderstand the facts, you're certainly not the only one! Hence why the current valuation doesn't make sense.
The liquidity position really is bulletproof, if you crunch the most recent numbers post bond-raise no.2, so I stand by my earlier comment on that.
Regards, Paul.
From refi statement Jun 22.....
the Group remains subject to a minimum liquidity requirement of £40 million, which can be met either through cash or undrawn and committed facilities;
· the maximum amount of liquidity that can be used to fund the cruise business has been increased from £55m to £115m; and
Well I did say pre bond issue originally. The above two statements have been added since the bond issue that further clarify the situation. The funds available to fund the cruise business have been increased .... never the less are not unlimited. Should the business continue to burn cash at £7m a month this would give 16 months cash. I would suggest that in reality this number can't fall much below £50m.... since you need to be able to fund 6 months at any given time. This bond issue came at increased coupon of 5.5%.
Despite your comments I stand by mine that the balance sheet is far from bullet proof ...since they have finite capital and a cash burn to fund. I did not say an equity raise was on the cards - I said it can not be ruled out. I think this a fair enough.
IMO "bullet proof" means exactly that.... clearly a long drawn out restricted travel situation will test this balance sheet. It doesn't mean don't invest in Saga but you have to size your exposure appropriately and acknowledge the risks.
It's pointless arguing with you. Like many investors, you've clearly latched onto a visceral view of SAGA, and now refuse to change your mind even though the facts have changed (with the latest bond issue).
This is not the case and I haven't argued against investing in Saga, I simply said you can not argue the balance sheet is bullet proof. It gives others the wrong impression.
The liquidity position at SAGA is bulletproof.
You got nearly everything wrong in your previous post, so I'll rely on my analysis of the facts, not yours, if that's OK.
Yep, it can ride out any eventuality. Except the emergence of a new strain that postpones travel resumption beyond March 22 ... but that would never happen.
I guess we just agree to disagree. I meant no offence.
The insurance division generates a similar amount of positive cashflow, so the business can operate around cashflow breakeven forever, even with the travel division mothballed.
Apologies but this just isn't true.
Sorry but it is true. Insurance broking generated £81m of EBITDA (flows straight to cash as per company disclosures) and Insurance underwriting generated £59m of EBITDA last year. Figures will be similar this year, if not better due to lower claims. That is notably more than what company has disclosed as cash burn from Travel biz (which will be lower now that the 2 cruise ships are sailing around the UK with passengers on board).
Probably just lowered expectations for a resumption of holiday cruises based on
* the spread of the delta variant
* the number of countries blocking access to UK holiday makers
The Saga (LON:SAGA) travel operation is certainly not completely dead in the water. Spirit of Discovery is currently on a 14 day cruise around the UK.
I see that Avon Rubber (LON:AVON) has changed its name from Avon Rubber to Avon Protection. That should help their US operations where potential clients were probably a little confused by the name!
Not as confused as a visitor to Australia would be if he (or she) wanted some Durex - the brand name there for 'Sellotape'.
Not sure the new name makes things much clearer. A US customer going into a chemist and asking for 'protection' would probably be offered a 'rubber'.
“Not as confused as a visitor to Australia would be if he (or she) wanted some Durex - the brand name there for 'Sellotape'.”
Good to know, or you could get yourself into a very sticky situation.
I've always found Sellotape a workable alternative in emergency circumstances.
Avon Rubber (LON:AVON) has come a long way from Freshford, Wiltshire and like to pass into American hands as did it subsidiary Avon Tyres. I hold.
Portmeirion (LON:PMP)
Company seem reasonably happy with progress with mention of strong trading in may and June.
They seem proud that lfl sales are up 6% compared with 2019 - lets be frank h1 2019 was a poor Trading period so its a vey undemanding stat comparing to that poor trading period.
It not all about lfl’s though as sales are materially up compared to 2019.
I have to presume that this is an inline update at worst , all I really care about is clear comparisons to what expectations are for year previously and now and the company doesn’t really give us any useful info - any useful info will come via the backdoor of broker notes.
Note expectations are for ramp up in profits 2022 anyway so this company Needs to keep delivering well just to make that goal imho at present - so some pressure on management to deliver here.
Certainly not the most confident of my holdings albeit things seem to be ticking over for now.
Re Portmeirion (LON:PMP) - I am much more positive (albeit recognising the impulse to be optimistic about a large personal holding).
In recent years, PMP has underperformed having acquired 2 sizeable businesses (Wax Lyrical in 2016 with £12Mn sales and Nambe (£13Mn) in Sept 2019 but not seen even this T/o gain come through. Arguably, +6% LFL vs 2019 base business is not exactly stellar but….
Equity raise in 2020, diluted cheaply but did strengthen balance sheet and enable what I think have been good uses of cash for the long term
In short, reasons to be cheerful on profit as BOTH topline and % margin should be improving (evidenced by resumption of dividends is confirmed although this was expected).
Crucially, this is occurring when the share price is 640p vs 925-1200p range in 2017-19. A 22% dilution in 2020 occurred so perhaps 780p vs 925-1200p is better comparison).
The business is much better now than 2019 but I was prepared wait for end of ’22 for good news to come through.
Now I think the FY2021 results will be very good and a catalyst for a significant re-rating. I would now be disappointed if we don’t see 1000p again by Feb ‘22 (ie +50% vs today excluding dividends). I've bought more this morning.
Portmeirion (LON:PMP) - Zipmanpeter - good note. Well put. I'd not seen yours when I posted. It seems we are on the same page. This is one of my strongest conviction holdings at the moment.
cheers
Mark
Portmeirion (LON:PMP)
Zipmanpeter
Thanks for that - excellent rational thinking unlike my ramblings of a madman.
The fact that i still hold shows that i do still have faith/hope but they do have hard work to do and prior history has been patchy.
I think my gripe today is at the lack of specific clear guidance ref profits and expectations for year more than anything else. I should probably though take confidence though that the following sentance should mean they are at least on track with broker forecasts even if they didn't exactly say that.
we remain confident of the trading outlook for the rest of FY21."
Increasing profit over 50% next year seems a big ask in one year but hopefully some of that is simply covid related headwinds this year that should not be present as much next year or them being slow to assimilate all the moving new parts into profit making machine. As you say 15*next years current expected EPS is 850p without any upgrades flowing - i do think though that somewhat rightly so the market is unlikely to give the company the benefit up an uprating until they are slapped in the face with next years numbers - bring on those wet fishies
Portmeirion (LON:PMP) Trading update
My glass is perhaps a little more half-full. I am impressed by the rebound in sales. Up 34% at 43m is well ahead of my forecast for H1. Of course it says nothing about margins and profitability, but after recent events and investment I don't think we should assume the worst there?
Admittedly (excluding Nambe and 50% of PMP canada) it's 6% ahead of a poor H1 in FY19 but if my calcuations are correct its also a few pennies ahead of the 36.9m of H1 in FY18.
Looks like Nambe has also done well increasing turnover significantly . Nambe plus PMP Canada looks like £6m by my calculations.
H1 is too quiet and too early to read too much into H2. But Christmas sales are not made in a day and the visibility of export orders and increasing digital sales provides some indication of improving expectations for H2 as well.
Shame about the dilution from the capital raise - but the investment in production scale and efficiency, warehouse efficiency , brands and digital channels has the ability to more than compensate if executed well and leave some cash on the side.
Ok, so my glass is quite full this morning.
I must have got something wrong though - as the market seems to think differently. I've bought a few more anyway.
FWIW my forecast for H1 was 4p eps. That now looks a little conservative? and 48p eps for the FY. The current broker forecast is 37p for the FY reduced from 67p in May. That seems too conservative to me - and 67p is not out of the question in my opinion but DYOR,
cheers
Mark
Some good discussion regarding PMP; a few thoughts from me:
I have gone through the TU today from PMP and going back through recent years to 2018, accounting/deducting turnover from acquisitions it would appear that H1 for PMP is the highest or equal highest (we wait for the H1 results) since the incorporation of Wax Lyrical.
For the sake of brevity; my estimates are:
Usual H2/H1 for PMP is around x2.5 so, using the data in the TU and the H1 2019 turnover; it seems that the H1 for Pre-Nombe/100% Canada was £37m with an additional £6m from Nombe + extra 50% (full ownership of Canada). If we assume the usual 2.5 H2/H1 then “old PMP” alone gives a turnover of £92.5m.
Then we need to add in Nombe & the extra 50% Canada which I estimate as £6.0m in H1. Being cautious let's assume that this stays the same in H2 ie full-year = £12m
So, being cautious, I estimate a turnover for 2021, based on what we know at the moment, of say £104m against a brokers forecast turnover of only £90m for 2021, If all goes well that’s a significant beat in terms of turnover. As for PTP, we will have to wait until the H1s are announced.
Overall and including the return to dividend payments, I feel very confident about prospects for PMP.
Trading update from Mission (LON:TMG) I quote 'creator of work that counts'. More Director Speak.
https://www.londonstockexchang...