Small Cap Value Report (Weds 14 June 2023) - RWA, SPSY, MOTR, CGS, MRK, SAA, SFR, FDEV

Good morning from Paul & Roland!
Today's report is now finished.
Terrific reader comments today, thank you! Keep them coming, we need more discussion!!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Lots of interesting companies for us to look at today! We've run out of time now.
Summaries
Robert Walters (LON:RWA)
Down 14% to 402p (pre market) (£301m) - Trading Update - Paul - AMBER/GREEN (edited from GREEN originally)
It's a profit warning I'm afraid, bad luck to holders. I run through the numbers below, hampered by a lack of broker forecasts. Short-term the shares are likely to plunge today, but it's a fundamentally sound business, so they should recover in time. Annoying for traders, but not a big deal for medium-long-term shareholders. Very strong balance sheet with plenty of net cash, and generous divis, so no concerns over solvency/dilution. I'm staying green on this, as I see profit warnings from quality companies as potential buying opportunities, for longer term investors. EDIT: after reader comments below, I think editing this to AMBER/GREEN makes more sense. Thanks for your input!
Motorpoint (LON:MOTR)
Down 4% to 120p (£109m) - FY 03/2023 results - Roland - AMBER
Profits collapsed last year, due to a mix of one-off and persistent factors. But the balance sheet looks okay and I think the business could be well-positioned for a recovery. While risks remain, I’m cautiously optimistic about the outlook for this car supermarket group.
Castings (LON:CGS)
+5% to 428p (£178m) - FY03/2023 results - Roland - GREEN
This engineering group delivered a sharp rise in volumes last year as its customers opened the floodgates to clear production backlogs caused by semiconductor shortages. Demand is said to remain strong and I rate the quality and management of this business highly.
Marks Electrical (LON:MRK)
Up 4% to 95p (£99m) - Preliminary Results - Paul - AMBER
Decent revenue growth for FY 3/2023 results, but profit is slightly down. Good balance sheet & cashflow. I like the business, but online electrical retailing is so competitive, with no pricing power, so everything is all about being the most efficient operator, which MRK does seem to be. Founders 74% stake is too high. Valuation is too high for me, hence why I remain AMBER. Sub-70p would tip me into green!
Quick Comments
(no additional detail below)
Spectra Systems (LON:SPSY)
166p (pre market) (£74m) - Update on development contracts - Paul - GREEN
I’m following this share, and it’s been a previous podcast “mystery share”. In recent years it has displayed good growth, high profitability, and has plenty of cash, and pays generous divis. Plus some excitement from potential new contracts. So it’s well worth a closer look I think. The StockRank is high, at 92.
Today’s update says it has won a new contract, and achieved milestone payments on another. These were as planned, so it’s not changed the outlook -
"We are pleased to make this announcement today. These developments and payments were included in our financial projections for the 2023 fiscal year and solidify our expectations for the full year results."
Paul’s opinion - a reassuring update. This is an interesting, niche company, I like it.
M&C Saatchi (LON:SAA)
Down 9% to 158p (£193m) - AGM Trading Update - Paul - AMBER
It’s quite short, so here it is in full - I’ve bolded the most important bits -
The more challenging trading environment, as widely reported across the sector and previously referenced in the Company's 2022 full year results announcement, has continued, and has impacted the pace of business into the second quarter, particularly in the Advertising and Media specialisms.
However, the Company is benefiting from its diverse range of businesses, with the Passions, Consultancy and Issues specialisms continuing to perform strongly.
Whilst we expect a small decline in like-for-like net revenue for the full year, we remain confident in delivering year-on-year Headline PBT growth and Headline operating margin improvement. This will be achieved through a combination of the high operational gearing inherent in the business model, targeted cost savings and the global cost efficiency programme.
As a result, Headline PBT is expected to be significantly weighted towards the second half, although net revenue is expected to be more evenly spread.
The Board remains confident in its strategy and the medium-term growth targets set out at the Capital Markets Day held in February 2023, driven by the quality of its diverse set of businesses.
Paul’s opinion - this doesn’t look too bad actually. It's recovered a lot of the initial drop this morning to 140p, being 158p now at 12:39. We know macro conditions are tightening, so it’s to be expected that cyclical sectors like marketing might see a slowdown, which has been reflected in a falling share price since it peaked in Feb 2023, when conditions were looking more benign.
The most important bit is that SAA seems to be coping alright, through improving margins, and cost cutting.
I haven’t yet seen any broker updates, so can’t comment on valuation until we have more information.
Overall, I’m quite intrigued by SAA shares. There are some interesting reader comments below, talking about the takeover approaches. There were some big historical problems, but I seem to recall those have now been resolved.
Quite interesting, and definitely one to add to the watchlist for a cyclical recovery in due course, I think.
Severfield (LON:SFR)
Up 9% to 67p (£207m) - FY 4/2023 Results - Paul - AMBER
Excellent results today from this structural steel group.
Revenue up 22% to £492m, and adj PBT up 20% to £32.5m, underlying EPS 8.5p = PER of 7.9x. Cheap, if profits are sustainable? Divis 3.4p for the year, up 10% = yield of 5.1%.
Big order book of £510m at 1 June 2023. Outlook sounds upbeat about its chosen markets, including India. In line with expectations for FY 4/2023.
Balance sheet solid, with NTAV £129m, net debt eliminated in the year, now holding £2.7m net cash. So should be able to weather a recession, if we have one, and a lot of revenues are overseas.
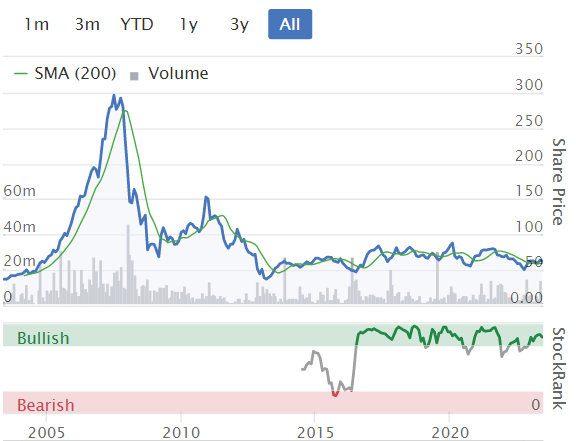
Paul’s opinion - this intrigued me when last looking at it in March. So far, it doesn’t seem to have any macro problems, and the big order book seems to provide about a year’s worth of forward orders. What happens after that? I’ve no idea, but personally I wouldn’t want to invest in a very cyclical business like this, at this stage in the cycle. Look back to what happened to the share price in 2007-8, and it’s never really recovered. Even post-crisis, the last 10 years have only seen a sideways share price. So yes the shares look attractive value, with a low PER, and good yield, plus the reassurance of a nice balance sheet. It looks a much better business now, than 10 years ago too. So some merit, but not for me at this stage.
.
Frontier Developments (LON:FDEV)
Down 8% to 537p (£212m) - FY 5/2023 Trading Update - Paul - AMBER
Graham covered the big profit warning from this computer games publisher in Jan 2023. Today it says performance has been in line with guidance provided in Jan. It selectively picks some profit measures, but I’d need to see the full accounts for clarity. Cash of £28m. Foundry games label launched in 2019 hasn’t worked, so it’s not seeking any new third-party business, being wound-down it sounds.
Guidance doesn’t sound very good, but it is in line with expectations, let’s hope there’s upside on this -
The Board is therefore comfortable with current analyst forecasts for FY24, with consensus revenue at around £108 million and the majority of analysts projecting an Adjusted EBITDA loss in the range of £5-10 million.
Paul’s opinion - I don’t generally invest in the computer games sector, where the smaller ones in particular are so dependent on individual game releases doing well. That said, the repeating “franchises” can be very valuable to acquirers, look at the previous takeover activity in the sector. So not for me, but might be worth readers doing some more research on it. Graham reckoned it was interesting value in January, and today’s update reiterates that profit guidance.
Note that FDEV is due to launch a Warhammer game, which is Games Workshop (LON:GAW) ‘s brand. That share has been a stunning performer, pity I sold mine at 1200p, as it’s 8-bagged since then! So it will be interesting to see how the customer passion for GAW’s products will (or won’t) translate into computer games. Incidentally, I see GAW itself has risen to a new YTD high today on a positive update.
Paul’s Section:
Robert Walters (LON:RWA)
466p (pre market) (£348m) - Trading Update - Paul - AMBER/GREEN
Robert Walters plc (LSE: RWA), the leading international recruitment group, today provides an update on current trading.
The current year is FY 12/2023.
April & May 2023 saw net fee income down by 10% at constant currency, 9% reported.
That’s triggered a full year profit warning -
It is now considered likely that profit for the full year ending 31 December 2023 will be significantly lower than current market expectations.
I don’t know if you can make sense of this next bit, but it seems contradictory to me - the market’s weak, but also strong is how this reads to me! -
Reduced levels of candidate confidence and lengthening time to hire were signalled in the second half of 2022 and, contrary to the Board's prior expectations, are not yet showing sustained improvement. Conversely, recruitment market fundamentals such as job flow, candidate shortages and wage inflation remain solid, suggesting that when market confidence recovers there will likely be a return to meaningful growth.
Costs - looks like it might have ramped up overheads at the wrong point in the cycle, perhaps? (easy to say with hindsight) -
The Group has invested significantly in both headcount and its global infrastructure over the last two years, and whilst appropriate cost reduction is central to the management of the current short-term pressure, we will protect our strategic core to ensure we can fully benefit from future growth opportunities as they arise.
Next trading update will be on 6 July, for the whole of Q2.
Broker updates - there’s nothing on Research Tree since 2019, so unfortunately private investors will now be at an informational disadvantage compared with the preferred clients of the brokers who will be sent a broker note detailing how much the profit miss is likely to be. We’re kept in the dark. This is highly unsatisfactory and unfair. Information is supposed to be released to all investors at the same time, that’s a core requirement of company law. So giving some investors privileged information (because the brokers have privileged access to the company, and broker forecasts are basically the company’s forecasts) seems to break that principle.
Current forecast consensus is 49.8p, so at 466p/share the PER is 9.4x.
If revised EPS drops 20% to 40p, then the PER would be 11.7x
If revised EPS drops 40% to 30p, then the PER would be 15.5x
The share price found support around 400p at recent lows, but depending on how bad the forecast reductions are, then it seems likely to me that the share price is more likely to be starting with a 3, than a 4, later today. We’ll soon find out.
An interesting long-term chart, showing that buying after previous disappointments is a good strategy -
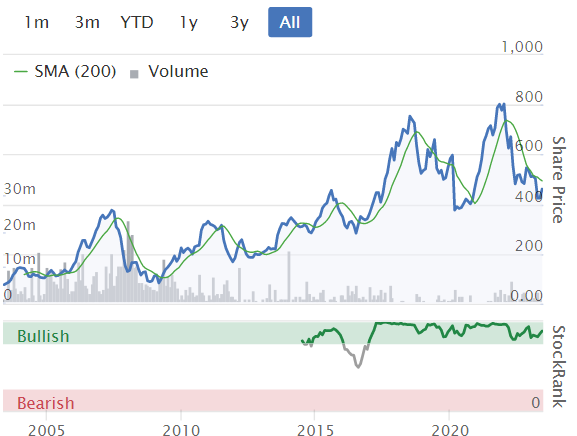
Paul’s opinion - shareholders don't like profit warnings, but for medium to long-term holders, this shouldn’t be too much of a worry, as earnings & hence the share price are likely to recover once economies are back on track. Plus it gives long-term watchers (like me) a potential buying opportunity.
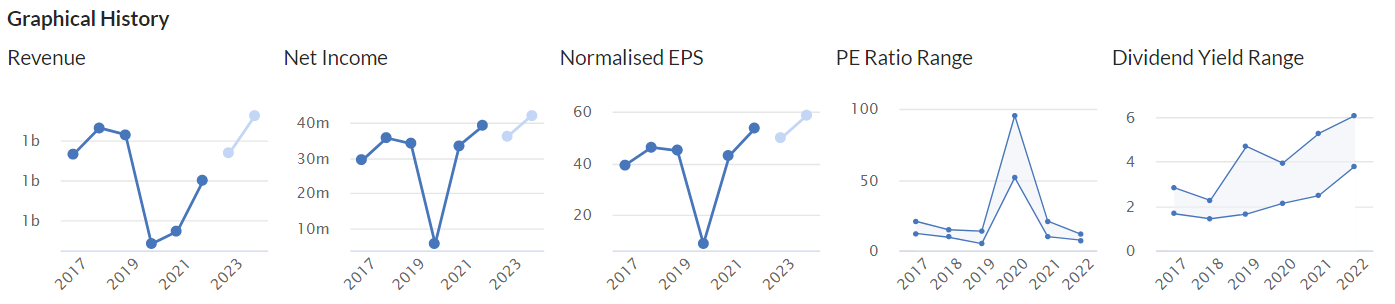
The medium-term track record is good, with an obvious spike down for covid, but either side of that, earnings look quite reliable. This is a high quality business in my opinion -
Balance sheet - I’ve checked the last set of accounts, and it’s important to note a very healthy balance sheet, with NTAV of £155m, including net cash of £97m. So there’s no issue at all with dilution or insolvency risk, despite a profit warning shareholders can still sleep soundly at night (well, once this heatwave has passed anyway!).
Dividends are well-covered too - it looks like the policy is to pay out about half earnings as divis. So it’s possible divis for this year might be cut, but given its balance sheet strength, the dividend paying capacity is still intact.
My opinion - clearly a disappointing update, and shareholders are likely to take a bath today. However, I don’t mind profit warnings from fundamentally strong businesses, as they recover in time. For that reason, I’m leaning towards seeing today’s news as more of a potential buying opportunity, than a cause for alarm. There doesn’t seem to be anything fundamentally wrong with RWA, it’s just entered a period of softer trading probably due to macro factors. Most of its operations are overseas (Europe & Asia), with UK relatively small.
Is this a precursor to a recession? Who knows. It does make me a little more wary about the macro picture though, as labour markets were supposedly strong.
Anyway, for long-term holders I don’t think there’s anything to panic over. Yes the shares are likely to fall, but in time they’ll recover. Probable read-across to other staffing companies too, so it might be an idea to review any other holdings you have in this sector, and consider selling a few perhaps?
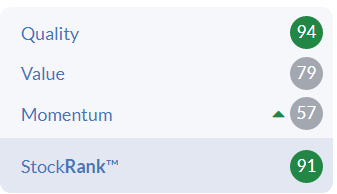
Note that the StockRank is high, confirming the quality of the business. Although I imagine the Momentum score is likely to drop after today's profit warning -
Marks Electrical (LON:MRK)
Up 4% to 95p (£99m) - Preliminary Results - Paul - AMBER
Marks Electrical Group plc ("Marks Electrical", "the Company" or "the Group"), a fast-growing online electrical retailer, today announces its unaudited preliminary results for the year ended 31 March 2023 ("the year" or "FY23").
We previously reported (here on 13 April 2023) MRK’s FY 3/2023 year end trading update, with the key points being: revenues £97.8m (up 21.5%), net cash £10.0m, aEBITDA >£7.5m, positive start to April, Canaccord forecast 4.7p EPS.
Let’s see how the actual results compare…
Actual results for FY 3/2023 -
Revenues £97.8m (exactly in line), up 21.5%
Adj EBITDA £7.5m (again, exactly in line), up 4%
Adj EPS 4.82p (ahead of 4.7p forecast)
The more meaningful profit measures are actually down a little, eg. adj EBIT £6.24m, down 2% vs LY.
Net cash £10.0m (exactly in line)
So no surprises in the above, it’s as expected.
What about outlook & current trading - this sounds encouraging for FY 3/2024, and sounds in line (without directly saying so) -
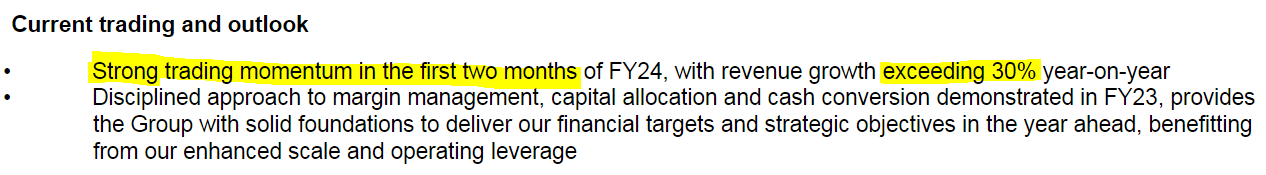
Webinar - tomorrow at 14:30, organised by Equity Development, sign up link is here. Mgt came across very well on previous webinars, in my opinion. Definitely backable people - hands-on entrepreneurs (from any background, I don’t care about that), which is the main thing I look for in small caps.
Other sundry things I spotted in the accounts -
Finance income has gone up from nil, to £71k, suggesting that net cash is now earning some interest, and is not just a window-dressed year end balance, good to see.
“Fair value gains” of £481k (£195k LY) helps boost profits. Does anyone know what this relates to? I can’t find an explanation in the commentary.
Balance sheet - looks good to me, and is building nicely year-on-year, with NAV at £13.8m (LY: £9.4m). Inventories look well controlled, and has fallen slightly to £14.2m, despite strong revenue growth. That’s an important indicator, that MRK is operating efficiently, getting stock in, then turning it around quite fast, essential in this sector.
Lease liabilities are very small, again suggesting an efficient operation.
Receivables are small, likely to be payments in transit from card processors I imagine, and maybe some commissions from selling warranties?
Overall, the balance sheet is good, so there’s nothing to worry about re dilution or insolvency.
Cashflow statement - looks healthy, nice clean numbers. Helped by favourable working capital movements (keeping tight control of inventories, whilst trade payables rose £3.5m).
Modest capex of £1.0m in the year, and nothing capitalised into intangibles.
Dividends paid only modest at £1.0m, so I’d say MRK has considerably higher future dividend paying capacity. Hence the modest 1.2% dividend yield should improve as the years go by, potentially quite a lot - I think this share could end up paying a yield of 3-4% without stretching itself.
Ownership structure - the founder owns 73.6%, which is uncomfortably high for an AIM stock. We like the owner’s eye here at the SCVRs, but are not so keen on the owner having complete control. iEnergiser spooked many of us.
Paul’s opinion - an interesting challenger in the electrical retail sector (online only), which I think is a much better business than AO World (LON:AO.) - MRK makes a superior operating margin, has much more % growth potential (as it’s starting off small), a better, simpler balance sheet, and importantly does not have extended warranty liabilities on its balance sheet (unlike AO, which has big potential exposure there).
So it’s a thumbs up from me for the business itself.
However, as mentioned before here on 16 Jan, and 13 April, I’ll only go AMBER on the shares, because they’re over-priced for my purposes. Canaccord reckons 5.1p EPS for FY 3/2024, which will mean no overall profit growth in 3 years. At 95p per share, we’re being asked to pay 18.6x, which is just too high, considering this is such a competitive sector, with absolutely no pricing power - quite the opposite, it’s a race to the bottom to win orders by offering the lowest price, which people compare online.
There are some economies of scale as it grows (more buying power, and more efficient deliveries with shorter routes serving more drop-offs. However, I think there are also dis-economies of scale, as warehouses could become too large & unwieldy.
So what it boils down to is probably this -
- Do you want to invest in a low margin, highly competitive sector?
- Are you prepared to pay a full price for future growth?
I’m leaning towards no, on both questions.
That said, MRK has really impressed me, and I would pick this share ahead of AO and Currys, which both have significant issues in my view.
Could MRK end up beating forecasts? That looks quite possible, given the strong trading in Q1 to date. So the bull points are quite good, and if the shares were 70p or less, I'd go green. Also I'd like to see the free float increased, with the founder reducing to under 50%, ideally. AIM rules need to change, so that nothing can float unless there's a 50%+ free float. The current rules are ludicrous.
Roland’s Section:
Motorpoint (LON:MOTR)
Share price: Down 4% to 120p
Market cap: £108m
Final results - Roland - AMBER
The Group expects to emerge in a normalised market as a leaner and more valuable business ready to seize a significant opportunity.
Motorpoint’s high operational gearing is a consistent theme of commentary on the stock – for good reason. The company’s low margins and fixed cost base mean that profits can swing wildly given small variations in margin and revenue.
Today’s results highlight why it’s important to understand this. Motorpoint’s revenue rose by nearly 10% last year, but operating profit fell by almost 75%.
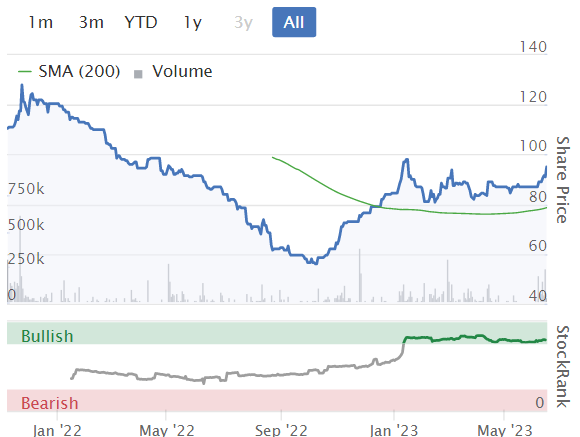
The firm’s shares have now also fallen by 75% from the record highs seen in 2021:

Let’s take a look at the numbers to understand more. Does this business offer a turnaround opportunity, or is it now at risk of failure?
Results summary: today’s results cover the year ended 31 March 2023. They show record revenue but a significant fall in profits, due to higher finance costs and a reduction in gross margin on used cars due to stock shortages.
Revenue up 8.9% to £1,440.2m
Gross profit down 19.4% to £85.7m
Gross margin: 6.0% (FY22: 8.0%)
Operating profit down 72.8% to £6.8m
Operating margin: 0.5% (FY22: 1.9%)
Finance expense up 103% to £7.1m (FY22: £3.5m)
Pre-tax profit (loss): £(0.3m) (FY22: £21.5m)
That’s the bad news. There was also some good news.
Motorpoint has strengthened its balance sheet somewhat by reducing stock levels to 51 days (FY22: 54 days) and carrying out sale and leaseback deals on two properties. The group ended the year with net cash of £5.6m (excluding stocking facilities), versus a FY22 net debt of £21.2m.
Market share also continued to improve:
Market share (0-4 years old): 3.5% (FY22: 3.1%)
Avg mkt share within 30 min drive of store: 8.9% (FY22: 7.7%)
These metrics suggest to me that Motorpoint is maintaining its record with customers for competitive pricing and good stock availability. This reflects management’s deliberate strategy to give up some margin last year, in particular on finance commissions.
As a result of this, retail gross profit per unit fell to £1,300 (FY22: £1,466).
The number of vehicles sold last year fell despite market share gains. This implies a significant reduction in used-car sales across the UK:
Retail vehicles sold down 8.9% to 57.3k (FY22: 62.9k)
Wholesale vehicles sold down 6.9% to 32.4k (FY22: 34.8k) - wholesale sales are customer part-ex vehicles sold through Motorpoint’s B2B auction service
Motorpoint opened two new locations last year, taking its total to 19, but the company has now paused its expansion programme. However, online sales have continued to grow, even as the pandemic effect passed:
Ecommerce revenue up 5.7% to £660.5m
Electric vehicle: today’s results mention the “widely-documented fall in value of Electric Vehicles” as one reason for the drop in margin. The company says that in the latter part of FY23 (i.e. Sept ‘22 - Mar ‘23) stock values fell by as much as 30% over a four month period.
We aren’t told what the profit/loss impact of this was, but it highlights the risk the company faces if it’s caught out by market moves in used car pricing and valuations.
However, when I look at Motorpoint’s website today, the company only lists 128 electric cars for sale out of a total stock list of 4,965. I don’t expect any further impact from EV pricing falls.
Finance costs: the impact of rising interest rates was also significant and will be longer-lasting, in my view. Borrowing costs affected Motorpoint’s results in two ways last year:
interest rates on the group’s stock financing facility rose, so it cost more to hold vehicles in stock. This may have been one reason why the number of days’ stock held was reduced.
Rates on car purchase finance also rose. Motorpoint says it sacrificed some of its finance commission to reduce the impact of higher finance charges on customers.
Higher borrowing costs are here to stay, in my view. But once rates level out, then I’d imagine the impact of this will be much less significant – prices will simply have to adjust.
Outlook: trading in FY24 will continue to be impacted by higher interest rates and inflation. But CEO Mark Carpenter says that recent growth in new car registrations should mean that used vehicle supply improves over time.
Meanwhile, Carpenter is confident that last year’s market share gains should also help to drive future growth and improved profitability.
There isn’t any specific financial guidance for FY24, perhaps unsurprisingly.
Consensus forecasts on Stockopedia prior to today suggest that adjusted earnings are expected to recover to 8.4p per share this year. That would price Motorpoint at 15x forecast earnings – not expensive if you believe that earnings can eventually recover to pre-pandemic levels of c.15p per share.
Roland’s view: it’s probably worth remembering that this business is 25 years old and has weathered previous slowdowns.
Another positive, for me, is that CEO Mark Carpenter has a 9.9% shareholding, so his interests should be aligned with those of shareholders. Founder Mark Morris has retired from the board, but also retained a 4.7% shareholding.
I’ve admired this business in the past. I think it’s well-run, with good scale and an attractive customer offer. However, I have to admit that I started this review thinking that I might have to go red on this stock.
However, after looking at today’s results I feel more positive. I think Motorpoint remains in reasonable financial health and could recover strongly over the next couple of years. Risks remain, but I’m happy to go amber on this stock.
Castings (LON:CGS)
Share price: 427p (+5% at 09.50)
Market cap: £177m
Final results y/e 31 March 2023 - GREEN
Our customers continue to increase schedules with the demand for heavy trucks in particular remaining very strong.
Today’s results provide straightforward commentary and clear, unadjusted accounts. Reading these makes a refreshing change from the opaque jargon and adjustments used by many firms.
Castings’ main business is producing cast iron and machined parts for truck manufacturers. The group is also expanding into areas such as wind energy.
This business had a frustrating time in 2021 and 2022, when it was forced to hold back production because its customers could not get the computer chips they needed to build new vehicles.
Automotive supply chain issues now seem to have been largely resolved and Casting has had a strong year. Shareholders are now set to receive a special dividend in addition to the ordinary payout, which has not been cut for over 30 years.
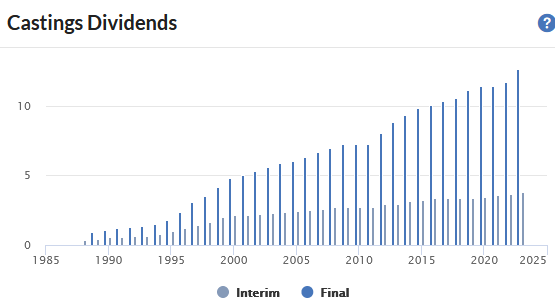
Results summary: turnover rose by 35% last year, lifting operating profit by 36%. The company says its despatch weight – an indicator of volume – was at the highest level since 2014 (although I note that operating profit was 24% below 2014 levels):
Revenue up by 35% to £201m
Operating margin: 8.2% (FY22: 8.1%)
Pre-tax profit up 38% to £16.4m
Basic earnings up 61.5% to 31.66p per share
Ordinary dividend up 6.9% to 17.35p per share
Special dividend of 15p per share declared
Net cash: £35.6m (FY22: £35.8m)
Return on capital employed: 11.9%
Castings’ financial performance was strong last year and the balance sheet looks bulletproof to me. Net cash of £35.6m is equivalent to nearly 18 months’ operating expenses.
The total dividend of 32.4p gives a trailing yield of 7.6% at current levels – nice to have.
Trading commentary: last year’s rapid increase in customers’ build schedules supported higher profits, but the company says this was skewed towards “certain production lines”. Rebalancing activity in the firm’s foundries “caused some inefficiencies” but this is now said to be “behind us”.
My reading of this is that experienced operational management handled the challenges well. Margins were unchanged last year despite this sudden increase in volumes. In my experience, some less accomplished manufacturers would have taken a hit to margins in order to fulfil the surge in orders.
Castings reports its results under two segments, foundry operations and machining.
Foundry: output increased by 6.6% to 53,100 tonnes last year. External sales revenue rose by 36.7% to £199m, mirroring the growth in group revenue. Segmental profit was £16.3m (FY22: £13.1m).
Higher costs have been passed through, but with some disruption due to production rebalancing.
Machining: this is the CNC Speedwell business. Revenue rose to £27.7m last year, (FY22: £22.5m) but only 7% of revenue came from external customers.
Segmental profit for the year was £0.2m (FY22: a loss of £0.9m).
Management say that £1.4m has been invested in this business during the year, including £0.4m on automation and £0.5m in a more power-efficient cooling plant.
These productivity and engineering improvements are said to have driven an improved profit performance in the final quarter.
It would be easy to look at the segmental results and suggest the disposal of the machining business. But the small proportion of external revenue implies that the majority of machining activity serves the needs of the foundry business.
Keeping CNC Speedwell in house seems prudent and in keeping with the company’s focus on providing a quality service to its (much larger) clients. I think it’s a sensible strategy.
Outlook: Castings says its customers “continue to increase schedules” and that demand for heavy trucks is particularly strong. Demand from other sectors such as the US market, trailer braking and coupling systems and wind energy is also said to be growing.
Broker forecasts suggest earnings will remain at a similar level this year, putting the shares on c.14x forecast earnings.
Roland’s view: one risk often mentioned in connection with this business is that the adoption of electric vehicles could render the core foundry business redundant.
I think this is unlikely for the foreseeable future. It seems likely that heavy trucks will be among the last to make a wholesale switch to electric power, if indeed they do. I suspect that alternative solutions such as hydrogen may be more successful in this market, due to the power and range required.
In my view, Castings is a well-run and high quality business. However, the capital-intensive nature of the business means that returns on capital will probably always be relatively modest – last year’s figure of 11.9% was the highest since 2017, according to Stockopedia data.

Given this, this isn’t a business I’d pay too much of a premium for. However, Castings shares still remain below historic highs, despite recent gains.

Given the positive momentum in the business, I’m going to go green on this stock. I think there’s scope for profit margins to improve further this year as recent price rises fall through to profits.
Assuming demand remains stable, I think Castings continues to look fairly priced at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
Does anyone else have concerns about the macro factors reported in the Motorpoint (LON:MOTR) results impacting the broader car dealership sector e.g. Lookers (LON:LOOK) and Vertu Motors (LON:VTU? Both shares held up well today so broader market thinks not perhaps but interested to hear opinions of others that may be better educated on this sector in general.
Dalata Hotel (LON:DAL) (I hold)
Dalata Hotels put out a H1 trading update today, which looked good to me.
EBITDA is expected to be higher than €100m (vs €84m last year) - which I believe will result in free cash generation = c.€50m.
I would hope for a slightly better performance in H2.
Net assets at year end = €1.2b.
The Market Cap today = €1b.
There's also a decent pipeline of new openings over the next couple of years.
Before taking a position a few weeks ago I did look at a handful of other listed hotel groups, but found nothing as "cheap", though I was impressed with the quality of Hilton Worldwide Holdings (NYQ:HLT)
It's probably a too late in the day, but I'd be interested in hearing thoughts on listed hotel groups, particular opinions on valuations in this post-covid, reduced work travel environment.
Thanks
A
Saga
https://www.stockopedia.com/sh...
It appears On Beach Group (LON: OTB) is turning around once again! does anyone know any reasons behind it or the recent seismic fall was an overreaction? I always believed competitive beach getaways won't suffer due to money being tight , however I benefited little so far for over a year now, I hope this time it will be different (I Hold).
Talking about holidays, there's also been a staggering recovery in the share price of Carnival (LON:CCL) recently, despite its heavy debt load. Maybe pensioners are spending more freely now that they're getting good savings rates?
Paul.
Carnival have just been given a push by Morgan Stanley and Bank of America. The $35 billion debt doesn’t seem to be stopping the share price gains. Carnival are issuing their results on the 26th. I hold but wouldn’t but for the shareholder $150 to $250 on board spend perk.
But not back yet to the share price before the Interim Results in On Beach group (LON:OTB) . Which I had thought was decent enough and positive in terms of forward outlook, but the markets marked down the price after the results. Probably because H1 profitability was poor; but that is not a surprise, given the seasonality (Oct-Mar) and also the huge forward investment they did in headcount and brand marketing to position themselves for H2 high season (Apr-Sep) and onwards.
I've had conviction that summer volumes is going to be fantastic back since the start of the year. But now, all the major players and news outlets have more or less confirmed that booking volumes are excellent. And I wouldn't be surprised if OTB releases a profit upgrade trading statement in July or August, when those forward bookings get actualised into real revenues.
(I hold in the Boon Fund)
UP Global Sourcing Holdings (LON:UPGS) - UPGS hosted a capital markets presentation at the Exclusively Homewares exhibition in London’s Business Design Centre yesterday to discuss the upcoming re-brand of Salter as part of its overall brand rejuvenation programme. Having confirmed its expectations for FY2023 financial performance in a statement the previous week, prospects for a strong second half to the year remain in place. UPGS’s belief that it will match market expectations in FY2023 is important. With an end-July year-end the company has significant visibility regarding the FY2023 H2 trading period. A £163m full year revenue figure would require double-digit growth in the second half, which would be impressive and something that the business is clearly confident of achieving. Accelerated sales momentum in FY2023 H2, prospects of major benefits from a holistic approach to brand management and sustained commitment to serving the mass market with affordable “feel good” products for every home reinforce our view that fair value for UPGS’s shares is 250p. We base this view on 1.5x EV/sales and 12.2x EV/EBITDA. Link to note here (Innovating for growth): https://www.equitydevelopment....
R&Q Insurance (LON:RQIH) for those interested in their equity issue and update on restructuring the group, there is a new research note and audio summary out today. Access it here: https://www.equitydevelopment....
May I say what excellent posts there have been in here today
Great to see so many different companies discussed with varying points of view
*of those discussed I only have Games Workshop (LON:GAW) & remain a happy long term holder after todays TU
I haven't got anything specific to say other than that I'm really struggling in these markets. I have been investing for a long time and through various market conditions - 2000, 2008, 2020 etc. however I'm finding that the length of this bear market in small caps difficult to manage mentally. I have tried to be pragmatic and pick up shares and investment trusts, that I perceive to be fundamentally undervalued - especially if they offer a decent yield and turnaround strategy. The large cap markets are disconnected (perhaps only a few constituents of these markets) to the small cap markets and this makes me nervous because if the large cap indices have a wobble, then that will also impact small cap shares negatively. It always amuses me when talking heads use the phrase "period of volatility." which really means period where markets will fall! Today was just another in a long line of profit warnings from companies I have bought recently Robert Walters (LON:RWA) and CMC Markets (LON:CMCX) yesterday - I realise that market conditions will change at some point but because of the length and breadth of the bear market, I'm feeling depressed and despondent. I realise that markets and the economy are not in sync, and I have heard that once a technical recession is announced the market has usually bottomed. I'm going to sit on the sidelines for a while and perhaps put my remaining funds into investment trusts to avoid company specific issues and profit warnings. I've also just been made redundant, which doesn't help with the feelings of financial and general anxiety. How is everyone else coping in these markets? Any insights as to when things may start to become more positive? Thanks.
The best I can say is that these cycles come and go, at some point small caps will be on fire again. I have Eneraqua which was down 40% in a day, TekCapital smashed down, Volex down, Saietta was down 90% at one stage, DGI9 beaten up, CML Microsystems £6 down to £4. Luckily this year my biggest positions Google & Tesla are doing well but they were also beaten up massively in 2022. In the meantime I'm concentrating on buying the very best companies at depressed prices, picking up the dividends and waiting. All the best, Paul
Sorry to be hearing of your being made redundant, hopefully you have seen warning signs and have planned for this possibility. Cash could well be king at this stage.
That sounds tough at the moment bsharman, I hope that things turn around for you. I dont think that it is a bad idea to take advantage of the increasing interest rates at the moment, I am about 70% in cash at the moment.
Hi Ben,
Really sorry to hear about your woes, but I'm glad you've shared them here, because a problem shared is a problem halved, I find.
It's very difficult at the moment, for sure, especially in small caps. I have quite frequent (mental) down days too, when I think about all the money I've lost in the last 18 months, it's horrendous. So I just blot it out, and try not to look backwards, other than to adapt my approach so that it can't happen again.
Also, it's actually OK to feel miserable sometimes! We don't have to pretend to be happy all the time. What I find helps, is to get the anger/sadness out of your system, do some exercise & get some sun, and then sit down with pen & paper and work out a plan of action to gradually improve things. Once you can see, and have planned a recovery strategy, you can focus your energies on implementing that, instead of dwelling on things you can't change (i.e. the past).
Also, I've been through some monstrously bad times and recovered, so if it helps, remind yourself that your problems are probably only a fraction of what Paul survived!!! (obviously I'm guessing there, so forgive me if that's intrusive or flippant).
Have a free hug too! :-)
I'm really pleased you posted your thoughts, as normally people only post about periods of great success, then go quiet when things are more difficult, suffering in silence. So it takes guts to post about things that have been difficult for you, so I admire you sharing that with the community here.
Best wishes, Paul.
Thanks Paul. I appreciate your reply and the virtual hug.
It definitely feels better to share and understand that I'm not alone. This is a great community of investors, and it certainly helps to bounce ideas around and vent our collective investment frustrations as well as looking for positive tangible solutions.
I think the redundancy which was announced last week in combination with my savings in the market reducing day-by-day has had a big impact on my (mental) health and wellbeing. I'm fairly resilient however having come through a lot of merde in the past and will try and look at this as a recovery/turnaround situation!
Enjoy the podcasts each weekend and the daily SCVR, so thanks to you and the team.
Hi bsharman,
I can certainly emphasise with your feelings - I have been actively investing since the late 80's and I struggle to remember a more difficult time to make consistent profits. However, in my experience to use a cliche it's often darkest before the dawn and although we cannot accurately predict when the markets will recover we can say that each day that passes is a day nearer to the recovery beginning. Today, many small caps (in particular) are trading at hugely attractive multiples and it seems Armageddon has been priced into their share prices, there is also the pressure of Fund Manager redemptions further hitting shares (which ultimately is not based on the value of the underlying businesses themselves). Because of this I see today's valuations in quality small caps as one of the best investment opportunities of my lifetime.
For me patience is the key.
Like you I have taken a few hits recently - none bigger than Hostmore - but fortunately it's an outlier and I am trying to learn from these mistakes - for Hostmore I never particularly liked the business but I thought it was undervalued - in future I will not be investing in businesses where I don't respect the product or offering. I think Buffet had something say about not buying poor businesses at a good price - lesson learned.
On the plus side I can remember buying M&G PLC for 97p & Aviva for 225p during the pandemic and they doubled in less than a year - it seems obvious now but at the time it felt like the market must know something I didn't and I was taking a big risk. Similarly today, it's hard to imagine businesses doubling in value over the next 12 months but for some this will happen - for me this means having a robust approach in trying to find these undervalued businesses (stockopedia is a big help in keeping the analysis objective) and holding onto them long enough to get these returns.
How all this relates to today is that I have positioned about 70% of my portfolio where I will hold if necessary for 5 years + so short term fluctuations although annoying don't hurt too much - fyi my biggest holding is in Legal & General (LON:LGEN) and it has been a little volatile of late but with a decent yield and strong business I cannot see any reason to sell in the future.
Apologies to all for the ramble, but my basic message is to find good businesses that are undervalued and do nothing (regardless of ST share price) until the share price hits your target or becomes overvalued (through price appreciation or new facts about the business's LT prospects).
Wish you all the best for the future.
Paul
bsharman
Like others I’m sorry to read of you going through such a difficult time investing and then getting that kick in the teeth of being made redundant.
It’s a strange market in that the indexes don’t reflect the reality of what’s often been going on, which is relentless falls for some sectors, including small company shares which have taken a big hit.
My solution is one you mentioned. I.e seriously consider Investment Trusts. Many of those too have performed badly for a couple of years, and have now gone to much larger discounts than usual. That’s a buy opportunity for good quality Trusts. Also I use Investment Trusts to invest all round the World and to cash in on Countries and Regions and sectors doing much better than UK small company shares. A lot of those look stunningly cheap, but a portfolio holding mostly small company shares is too narrow in that it magnifies the underperformance in difficult times like now. Obviously the opposite applies in the good times, but then a lot of other shares and sectors will be doing well too, so it still pays to diversify.
There is one exceptional buy opportunity right now. That’s quality shares paying unusually large dividends that are even seeing dividend increases year on year, and in some cases even several times in a single year. There are also a lot of Investment Trusts paying exceptionally big dividends too. My portfolio is stuffed full of these, and though capital gains have been small over the last couple of years, the dividends have been flowing in every week almost and funding new big dividend paying investments too. It’s a virtuous circle.
I could post more detail on these shares and Trusts but the Small Company thread is perhaps the wrong place, and I’ve found if posting or replying on other threads there’s little or no useful follow up. The same applies if posting here the following day and beyond. The result is that there are a lot of superb articles on Stockopedia that don’t get the recognition they deserve because it’s this bb that’s the one that’s by far the most alive.
Hi Ken. Thanks for your reply. I have been buying through the winter and spring a number of investment trusts, which are on big discounts and those that have high yields - infrastructure for example. Perhaps I should spread my small cap risk by investing in some of the best performing small cap investment trusts such as Rights and Issues Investment Trust (LON:RIII) and Blackrock Throgmorton Trust (LON:THRG) and trust the managers. However I'm trying not to get sucked into what seem to be very high yielding companies such as Vodafone (LON:VOD) only for their dividends to be cut or cancelled. Where do you see the most value at the moment? Perhaps Stockopedia should start an Investment Trust section or more articles on these and mid-caps?
bsharman
I’ll try and reply sometime tomorrow.
Hi Ben
My commiserations too on being made redundant. Just possibly an opportunity to sit back and see if you're happy, or fancy a change of direction?
You mentioned Rights and Issues Investment Trust (LON:RIII) - are you aware that the Manager changed recently? Previously run very much as a 1 man band by Simon Knott and his father before him. Now run by Jupiter. I've no idea about Jupiter - but Knott seemed to be a class act. I don't know why he retired - my reading between the lines (which might be 100% wrong) was that he was being coralled into being more conventional and decided he'd prefer to bow out. He was very successful. I sold at this point.
All the best
Andy
Hi bsharman
I hold about 30 big dividend paying shares and Investment Trusts with current dividend yields from 7% to 16% and most of them hopefully without risk of dividend cuts, and in some cases with policy of further dividend increases. These exceptionally high yields reflect the current bargain prices, rather than a warning sign of dividend cuts or cancellation ahead. I won’t list the 30 now but will another time if of interest.
For now your suggestion of going for Investment Trusts makes sense as these pooled investments are less risky than single shares, and as with a lot of shares, some are very cheap and on big discounts.
The following are Investment Trust sectors you might think are worth considering. And this link is for the aic page for Global Trusts where there are several very good long term performers. Aic is much better than Stockopedia for Investment Trusts as Stocko include a lot of info not needed or relevant and exclude must knows like discounts to NAV. So I haven’t provided the link for each share for access to the Stocko stock page for each one.
https://www.theaic.co.uk/aic/f...
Perhaps:-
BIOTECH AND HEALTH.
e.g IBT. 7% discount and 4% dividend
COMMODITIES.
e.g BRWM 6% dividend and the best of the Trusts if wanting to invest in the biggest Mining Companies in the World.
COUNTRY SPECIALIST.
e.g VOF. 14% discount and 3% dividend. VIETNAM is little understood by UK investors bit is described as the new China. Make sure you read the monthly updates from the Managers of the 3 Vietnam Trusts.
GLOBAL.
Several very good ones.
JAPAN AND JAPAN SMALLER COMPANIES.
e.g BGFD. Discount 8% but tiny dividend. The BG Trusts traded at a premium and were top performers until the last year or so.
OR AJG 15% discount and 5.5% dividend or JSGI.
USA.
e.g NAIT. Discount 10% and dividend 4%.
PROPERTY UK COMMERCIAL
e.g AEWU 105p 3% discount 8% dividend or SREI at a big 31% discount and 7.6% dividend.
PROPERTY EUROPE COMMERCIAL
e.g SERE 26% discount and 7% dividend or EBOX 40% discount and 7% dividend.
UK EQUITY INCOME and UK SMALLER COMPANIES.
There’s such a wide choice. As with all potential Trust buys check out their top 10 holdings and try and find one that includes small company shares covered in SCVR reports. Also I prefer conviction portfolios and look for Trusts with as much as 50% of their portfolio in their top 10.
OR for UK Smaller Companies don’t go for Investment Trusts if tempted by single company UK shares covered by Paul, Graham and Roland.
Hope that helps a bit and that your quality of life can somehow improve soon.
Keep smiling. Things always get better in the end. Money worries are stressful for sure but in time it works out. I personally understand you situation. I’ve lost my house, twice, going from being comfortable to desolate. I wrote my car off just over a year ago, putting me out of work for a month. But I’m still here, I could easily of died with the accident. Last month my engine died in my car which put me out of work again for a month and cost me £9k. So I do understand money worries.
I was married for 16 years and when I got divorced it felt like my world was torn apart. I changed jobs immediately as I felt I didn’t need to be in a job I detested any more. Im still doing my new job 16 years on and while it has it moments it was the best thing I did.
It pales in comparison though to loosing a loved one. Four years ago my 24 yo son died. This by far has been the hardest thing to cope with in my life. Divorce, job and money issues pale in comparison. What has worked for me is to keep busy. Hobbies and diy projects help massively. Taking pleasure in the small things in life. I found hill walking helps to put some prospective in live.
My point is, what ever life throws at you, you get through it. Humans tend to think and worry too much about money. It doesn’t make you happy. So keep smiling and one day, hopefully soon, the market will change in your favour and you will look back and wonder what you were worried about. In the mean time, keep learning, avoid those risky shares and priorities what makes you happy.
Great post.
keep looking keep alert and above all keep the faith
Sorry to hear of your circumstances. Keep struggling on . You cannot lose until you give in
I share your pain I am down also and it is difficult and very lonely sometimes .Cant offer any solutions however sometimes switching the screen off going for a walk and reading a book can be a welcome distraction . As for you job hope you find something soon .
For anyone who has an interest in Somero Enterprises (LON:SOM) this is an interesting read across into the warehouse sector.
https://www.ft.com/content/802...
Somero Enterprises (LON:SOM)
Thanks for the link smatthews1 but it is behind a paywall. What's the gist of the article?
Can read it here https://archive.ph/cMPIC
Thanks for that Wolf of Wall Street and an interesting read. I believe the article refers to manufacturing rather than warehousing which is where Somero has a niche product in laying "high quality" concrete floors. It is difficult to know if this will create an opportunity for Somero.
In the near term this in-shoring will definitely increase prices so I dont see prices coming down any time soon.
Nearshoring is happening. My redundancy is related to one of our trading business sourcing from China and Taiwan and customers moving away from this Asian supply chain. There is therefore a real risk to other listed businesses, which supply goods and products manufactured in China.
Something is fishy with Motorpoint (LON:MOTR) persistent trading weakness. The used car industry right now is doing pretty decently; used prices continue to rise (albeit with some pain in segments like EV). Time to sell is still very healthy.
All of this should be resulting in robust earnings for used car dealerships. As rising prices generate more margin between when they buy and when they sell. And low days to sell means fast turnover of their working capital, which should result in higher RoCE.
It would be a different story if Motorpoint profits were depressed because they are chasing growth. But their growth ambitions over the past year were modest; just 2 new locations I believe?
They talk about digital investment, but their site looks like from the 2000s, and similar to any of the other used car websites (eg Cargiant).
Puzzling. Maybe they just have very weak management and a flawed business model.
Super cryptic FY Dec23 outlook statement from Spectra Systems (LON:SPSY)
"....solidify our expectations for the full year results."
Do they mean that there is still some more contracts / work to be committed for the rest of the FY, and therefore there is currently a visible gap to rev and earnings expectations?
Or that this contract has more or less guaranteed they will now hit their FY expectations?
This is a helpful trading update, the first after the CFO abruptly left.
Nice dividend yield and what is likely to be steadily growing earnings for the next few years, backed by some sizeable contracts signed with their central bank customer in the past 1-2 years. Also some modest growth engines, that have an opportunity to be bigger potentially. 16x PE is steep on the surface, but probably justified given the high gross margins, operational gearing potential if they grow the top-line, and long-term central bank contracts underpinning a lot of the revenues.
Multi-bagger this won't be, but its one of the shares that lets me sleep soundly at night (except for the abrupt CFO departure recently!)
(I hold in the Boon Fund)
Problem with SPSY is the enormous bid-offer spread. Not sure why this is with a 75% free float? I hold.
Interested in the Castings (LON:CGS) investment case then Listen to Adam Vicary, CEO, and Steve Mant, CFO present the FY 23 results at a webinar at 12.30pm on 19th June. Register
https://us02web.zoom.us/webinar/register/5216831860820/WN_wTIuqR1kTEafab6HLiuxNg.
I see that both house brokers have upped their forecasts today
Zeus has raised profit before tax forecasts (PBT) for 2024 and 2025 by 15.6% and 13% respectively. Zeus valuation estimate is 596.9p
Canaccord has raised PBT forecasts for 2024 and 2025 by 10% and set a target price of 550p.
Great discussion on Robert Walters (LON:RWA) . From ny personal experience of looking for a new role. Things are really really slow. Employers are sitting on CVs sent to them, then the role either goes on hold or filled internally (as its cheaper given inflation). I can't see this changing unless macro picture improves. But we all know it will improve, so it is a matter of timeframe when investing. I would wait for a few more profit warnings/downgrades before jumping in
It's fascinating that buy and hold investors views are completely different to traders (weeks/months hold rather than years) Not saying one is better than the other, just a different mindset.
Personally, being more of a trader, I wouldnt even look at Robert Walters (LON:RWA) It's in a down trend and earnings momentum is going in the wrong direction. It's a quality company and id like to hold it at some point but I'd rather wait for trading to improve/ earnings increasing...if that means I miss the bottom then that's fine because I've no idea where the bottom is.
The buy point in Nov 2020 was when the price made a higher high and broke above all moving averages, price doubled from there. Its well under water today so plenty of work for moving averages to flip into a bullish looking trend anytime soon
Vs 2008/09
2015 sell off
M&C Saatchi (LON:SAA) downbeat AGM update with second half weighting, which off course Mr Market doesn't like. My reading is that the company anticipates making current forecasts, but we will have to wait and see.
"Whilst we expect a small decline in like-for-like net revenue for the full year, we remain confident in delivering year-on-year Headline PBT growth and Headline operating margin improvement. This will be achieved through a combination of the high operational gearing inherent in the business model, targeted cost savings and the global cost efficiency programme.
As a result, Headline PBT is expected to be significantly weighted towards the second half, although net revenue is expected to be more evenly spread."
The company is perhaps one of the most globally recognised 'advertising brands', but does a great deal more. The capital markets day presentation available on its website is worth a watch. I think that it is worth significantly more than the current share price, although this is unlikely to be reflected until the macro economic climate improves. Clearly others think so too. Saatchi received two bid approaches recently. From memory Vin Murria was prepared to pay 207p or thereabouts and Next 15 (LON:NFG) 247P in a cash and shares offer.
Richard Staveley at Rockwood Strategic (LON:RKW) has a significant holding and thinks that the bids were opportunistic. He thinks that the shares are worth 300p in a decent market. We shall see.
I hold and happen to agree with Mr Staveley as one might expect.
Over to you Paul?
Thanks jonno, very interesting. I'm just finishing off a section on Marks Electrical (LON:MRK) then I'll look at M&C Saatchi (LON:SAA) next. Thanks for your points re the bids for SAA, etc, that's a useful refresher, as I'd forgotten the details. I do recall being surprised at how well SAA performed during the pandemic.
Best wishes, Paul.
Staffing companies unsurprisingly under pressure this morning after the profit warning from Robert Walters (LON:RWA) although SThree (LON:STEM) holding up ok, at least so far.
Reduced levels of candidate confidence and lengthening time to hire were signalled in the second half of 2022 and, contrary to the Board's prior expectations, are not yet showing sustained improvement. Conversely, recruitment market fundamentals such as job flow, candidate shortages and wage inflation remain solid, suggesting that when market confidence recovers there will likely be a return to meaningful growth. - I read this as "Employers are in desperate need of high quality staff but we don't have high enough high calibre people on the books to fill the postings, therefore it is taking ages". This would be a concern to me if I held!
Employers are in desperate need of high quality staff but we don't have high enough high calibre people on the books to fill the postings, therefore it is taking ages". This would be a concern to me if I held
No. It doesn’t mean that. Might have the chance to elaborate later.
Employers are in desperate need of high quality staff but we don't have high enough high calibre people on the books to fill the postings, therefore it is taking ages". This would be a concern to me if I held
No. It doesn’t mean that. Might have the chance to elaborate later.
Quick reply to clarify this comment. The company’s statement means that skills gaps exist right across client organisations but the employeers are constrained from taking advantage by the following:
a) line managers might want/need to hire, but budget/headcount freezes mean they aren’t able to
b) jobseekers are more cautious because of talk of job cuts, be that in the press or the jungle telegraph. Ironically, candidates feel safer sticking at a company with a hiring freeze than moving to one that is still hiring, ie with better prospects. This further limits candidate supply and means that those which proceed with an interview are more likely to back out.
As for “candidates on the books” that isn’t really how sourcing works today, in a world of CV clearing houses like LinkedIn, Monster, Jobserve etc
Thanks BnB, you clearly have a lot of knowledge so thanks for clarifying. I just applied my perception of how recruitment in education (my field) is looking right now, where we have plenty of candidates but very few with the skillset to be successful in challenging schools.
I'm in education and where I am we have zero candidates coming through , especially in Physics and Maths.
Hey Paul have to take issue with the green on Robert Walters (LON:RWA) afraid.... apologies
Hey Paul have to take issue with the green on Robert Walters(LON:RWA) afraid.... apologies
I have some useful insights to share on this TU but I’m heading out for the day and my wife is waving the car keys at me. All depends on macro in the end - doesn’t it always for cyclicals?
Given Robert Walters (LON:RWA) is my largest position - I would have told your wife "she can wave the keys all she likes, but your busy typing" - however Ill look forward to these insights later!
I'm in staffing too - and know RWA employees - their KPIs were raised 1 month ago, leading to many complaints of staff to me as they are already high.
In hindsight I should have seen that as a sign that all wasnt well - as raising high KPIs leads to an exit of lower performers and raising the game of higher ones.
Anyway, Ill sit tight - rather than buying or selling as there is high demand globally for employees, its just that there are large layoffs happening at big names, which is leading other companies to be more hesitant.
Interesting, thanks Jef. Maybe a cost saving exit of lower performers is what Robert Walters (LON:RWA) is aiming for?
Are you able to say why you take issue? I'd be interested to read your and any other subscribers counter viewpoint. [I hold]
Hi Paul,
According to your traffic light system:
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Robert Walters (LON:RWA) Has issued a profit warning and so in the short term Is not trading well. It's a mid-long term hold and so I wonder if an AMBER rating would have been a more appropriate rating at the present time notwithstanding the mid to long term prospects and strength of balance sheet?
Many thanks
Bristolian
Yes, fair comment Bristolian. I'll amend Robert Walters (LON:RWA) to AMBER/GREEN I think. A useful prompt, thank you!
Thanks, Paul.
Morning RDHOWARTH!
Hey Paul have to take issue with the green on Robert Walters (LON:RWA) afraid.... apologies
Fine, but are you going to explain why?!
Also, do remember that our traffic light system is not a comment on short-term outlook. It's more how we see the fundamentals of each business, in the medium/long term. So I would say I'm AMBER short term on RWA, and GREEN longer term, which hopefully doesn't muddy the water!
I see SThree (LON:STEM) is slipping a little today too, which makes sense, as people do the read-across.
Will be interesting to see what other recruiters say about current trading. And cyclical companies generally, it's feeling increasingly premature to be expecting a recovery. More profit warnings likely in the short term. Although interesting that (so far anyway) RWA has only slipped about 15% today, whereas I was expecting a typical c.30% markdown on a profit warning. In a way that could be seen as encouraging, in that the market had already priced in lower profits to some extent. Although it's difficult to draw such conclusions, when it's subject to the vagaries of what individual shareholders decide to do (the vast majority of course don't do anything!)
Regards, Paul.
EDIT: on reflection, I think you've got a point, so I'll amend it to AMBER/GREEN, bit of a fudge, but that better reflects shorter term uncertainty, but solid longer term fundamentals & low valuation, strong bal sht, nice divis.
I note the circa 15% fall thus far today but Robert Walters (LON:RWA) has risen recently and at the time of writing is more like' just' 8 or 9% below where it was on 1st June. Nonetheless at less than £4 the SP is only just above the Covid low point. Cyclicality!
Yep apologies I just thought green was inconsistent with current trading and outlook. Great co though it is.
Hey Paul have to take issue with the green on Robert Walters(LON:RWA) afraid.... apologies
I have some useful insights to share on this TU but I’m heading out for the day and my wife is waving the car keys at me. All depends on macro in the end - doesn’t it always for cyclicals?
This call sits on the horns of the global market’s own dilemma: are we headed to recession or not? If your view is yes, then Amber is the right call - it’s a quality company that will likely rebound well - but not before a couple more tricky quarters. If you believe in the immaculate disinflation (stateside) - and the broader market seems to - then today might be your buy point. The market’s own, less severe reaction today perfectly embodies that conflict. SP should be down 25% to 30%, especially after a recent strong bid, BUT structural demand is still high across the globe and weak revenues are sentiment (nervous candidate and cautious budgets) driven.
Other observations:
I think Paul is correct - over-investment in new consultants at the top of the cycle is proving painful - they’ve increased costs and diluted the productive cohort just as conditions became tougher, leading to negative operating leverage.
Japan is the key market and there are significant structural changes in that employment jurisdiction that should be long term supportive, as might rumoured Chinese stimulus nearer term.
Share is at levels last seen only a week after the (it’s the end of the world) Covid low, from which it trebled in just months. Traders will wait for the turnaround in momentum. Long term investors have started accumulating already.
Who is smarter? Ultimately, the macro will decide.
Superb, thanks BnB!
Is James Fisher And Sons (LON:FSJ) starting to look like a convincing turnaround? £22 to £4 with no dilution, peak EPS 88p, new CEO, recently completed refinancing and what looks like improved trading in their AGM statement this morning?
Still a heavy debt load and a lack of insider buying but it looks like there is some potential? Can't say I have a grasp of the moving parts re each division- does anyone have any insight? Can they recapture those peak earnings? (the $64,000 question!)
James Fisher And Sons (LON:FSJ) AGM Statement (I hold)
Looks like the turnaround is now well underway - more advanced in some divisions than others, but a distinct lack of banana skins in evidence.
I've held shares for a long time - it's been a disappointing couple of yearsto say the least. With the benefit of hindsight the company bought and build successfully but without integrating its acquisitions and prior to the pandemic the wheels came off its capital allocation discipline. Badly. Its avoided selling the family silver and owns several market leading businesses. I like the market opportunity - in off-shore renewables installation and maintenance, O&G life extension and decommissioning, defence, coastal tankers and increasingly LNG ship-to-ship transfers. Having been concentrated for many years in the North Sea Fisher is now putting in place infratruture to support renewables growth internationally particularly across Asia and the US and O&G/renewables in the middle east as well as long term growth in LNG transfers.
Without having raised fresh capital the debt burden remains uncomfortably high. Especially at the half-year when the working capital to support the offshore season is spent - but the revenue to unwind that, and to pay down the debt has yet to appear. This year the working capital swing is higher to support growth in the subsea business in the North Sea and with debt from the capex to support the new generator fleet now working in the US.
The lack of fresh capital also constrains the ability to invest in growth whilst making interest payments and paying down the debt.
An interesting decision not to raise capital. Most companies would have raised - which would have made it easier for management, but probably not improved longterm returns to shareholders. I suspect that the decision not to raise would have been in some way facilitated by the existance of the family stake ( 23% ) which is now held via the Sir John Fisher Foundation a charitable trust. Harder work by management in the short term - and constrains the rate at which growth can be supported from a very limited pool of capital. In the long term it has the potential to significantly increase returns to all stakeholders?
I bought more - but started buying too early. I managed to buy more when it was most distressed at 250p. But those were difficult times and I will likely regret not having bought more.
Can it return to 88p earnings? Yes. Definitely. Revenue (480m) is now growing again and I expect ahead of management expectations. Margins will improve as revenue improves, debt falls and as the 2 years spend upon productivity, integration and capex begin to pay off. In the longer term I expect them to significantly exceed 100p earnings.
Will it return to 2000p a share? That will take longer. Multiples have been slashed and companies that have blotted their copy book will take longer to earn back the trust of the market. But I think that the new board is making all the right moves to restart a consistent record of under-promising and over-delivering.
Perhaps the most positive thing about today's trading update is the change in management tone - having changed 180 degrees from putting the problems and challenges at the top and downplaying the recovery - to putting the turnaround across the divisions at the top with the usual comments on challenging markets now back at the bottom. Leads me to think that the turnaround in Energy and Marine Transport is more advanced than management would have us believe. The full year forecasts dont seem too demanding and there is the potential for them to beat the figures on revenue and slightly on earnings alongside winning new contracts in the current halfyear.
cheers
Mark
I agree illiswilg, starting tentatively to look much better. Watching the trades in the last month theres been a buyer happily mopping up any sells so will see how it goes. No dilution is key I think.
Coming up to a crucial long term breakout point. Loads of accumulation in last 18 months( green bars on the left)
Similar to Gooch & Housego (LON:GHH) Green shoots of a turnaround, accumulation and a breakout (tho would prefer volume surge) I find turnarounds much more difficult to trade but the upside can be really good
Thanks mark- very interesting !
Severfield (LON:SFR)
Results for the year ended 25 March 2023
Profits ahead of expectations, high-quality order books, post period-end acquisition of Voortman to accelerate European growth strategy
Severfield plc, the market leading structural steel group, announces its results for the year ended 25 March 2023.
£m
Year ended3
25 March 2023
Year ended3
26 March 2022
Change
Revenue
491.8
403.6
+22%
Underlying1 operating profit
(before JVs and associates)
33.1
26.9
+23%
Underlying1 operating margin
(before JVs and associates)
6.7%
6.7%
-
Operating profit
30.2
22.8
+32%
Operating margin
6.1%
5.7%
+40 bps
Underlying1 profit before tax
32.5
27.1
+20%
Profit before tax
27.1
21.0
+29%
Underlying1 basic earnings per share
8.5p
7.2p
+18%
Basic earnings per share
7.0p
5.1p
+37%
Return on capital employed ('ROCE')
15.8%
13.5%
+230 bps
Headlines
§ Revenue up 22% to £491.8m (2022: £403.6m)
§ Underlying1 profit before tax up 20% to £32.5m (2022: £27.1m), ahead of expectations due to strong operational delivery
§ Underlying1 basic earnings per share up 18% at 8.5p (2022: 7.2p)
§ Total dividend increased by 10% to 3.4p per share (2022: 3.1p per share), includes proposed final dividend of 2.1p per share (2022: 1.9p per share)
§ Year-end net funds (on a pre-IFRS-16 basis2) of £2.7m (2022: net debt of £18.4m), reflects improvement in working capital
§ High-quality, diversified UK and Europe order book of £510m at 1 June 2023 (1 November 2022: £464m), includes new industrial and distribution, film studio, commercial offices and nuclear orders
§ Value is building in JSSL - share of profit of £1.3m (2022: £0.8m), reflects record EBITDA of £11m and output of 108,000 tonnes
§ India order book of £139m at 1 June 2023 (1 November 2022: £143m)
§ Post period-end €24m acquisition of Voortman, an innovative, market-leading Dutch steel fabrication company, to accelerate our growth strategy and strengthen our market position in Europe
Outlook
§ UK and Europe - significant pipeline opportunities in the UK and continental Europe - many of our chosen markets continue to have a favourable outlook
§ Voortman acquisition is on track to be earnings enhancing in 2024
§ India - well-positioned to take advantage of significant post-pandemic growth opportunities, very encouraging outlook for Indian economy and strong underlying demand for structural steel
§ Inflation falling in certain areas but we remain mindful of the macro-economic backdrop
Did Severfield mention the industrial action? I sold for this reason last month, my only red flag as I was keen on the company and its SP recovery. If the action is across the UK business losing this many days of work will cause serious delays in completing orders. Plus maybe more overtime, and higher future wages.
www.darlingtonandstocktontimes.co.uk/news/23569079.workers-severfield-strike-demand-fair-pay-rise
"Following four days of industrial action, hundreds of workers at Severfield, the headquarters of which is based in Thirsk, will take to the streets on Monday (June 5) urging the company management make a serious offer to resolve the dispute.
Workers are extending their industrial action to include a further nine strike days.
Ben Kirkham, GMB Organiser said: “Hundreds of highly skilled workers are taking their call for a decent pay offer directly to the company."
I guess they can afford to pay their workers a bit more now, considering these results!!
Yesterday CPI data was released and to all intents was in line....at the margin Id say the soft side of inline...so many numbers get quoted that it's hard to know which one we should be watching. The vanilla CPI would appear to have fallen from 4.95% to 4%. This was fairly predictable because it's all down to losing a large number at the back....not a front month thing. The number we lose next month is even larger ...1.37% falls out....so yes CPI will fall again to most likely below 3%. Jay can claim victory.
From June onwards the issue will be do we stumble along at a MoM rate 0.10-0.3% ....which will have the effect of increasing CPI in Q4....or drift lower indicating falling prices and recession. At the moment bad news, slowing data, has been taken well. We are in a goldilocks period for now, since rate increases thus far do not appear to have seriously impacted the economy.
In H2 ...the easy wins on inflation are behind us...so strong data means more rate rises...and weak data whilst meaning cuts ....will now confirm recession expectations. Since we still have 1 more month of positive data and not much happens over the summer the crunch is likely to come in Q4.
The MoM numbers after June will tell the story since we move from back month to front month driving the picture. 0.2% is par... and the best outcome for markets I would suggest. Thus far being patient and invested has been rewarded....I remain fully invested....but the risks into H2 begin to rise...
The bonds I have ran have experienced small losses as UK rate expectations have risen.....it looks like it makes sense to me to term out some exposure from very short < 1 year ..... for 2-4 year where yields have risen from 3.75% to 4.75%.. For example the 4.25% 2027 Gilt now trades below par at 98.
I haven't changed any equity positioning. Sherborne Investors (Guernsey) C (LON:SIGC) has started to tick up reflecting a rising Navient (NSQ:NAVI) share price. It still trades at a huge discount....but Navient (NSQ:NAVI) have announced a new CEO which I believe paves the way for a shift in strategy towards better value...loosely based on cutting cost and returning excess capital. The upside still looks attractive to me....potentially agnostic of the wider backdrop although the shares are volatile.
Best of luck closing out the half year and for the remainder of 2023.
Thanks for this RDHowarth. I found this very helpful.
Hi RD, the only issue I have with Sherborne Investors is their close connections with Electra Private Equity. I have looked at the Company several times and agree it looks really interesting but my first investment rule is I have to trust management. Certainly they have the experience.
Hi Camtab I completely understand.... the two companies in question were actually the final 5% or so of Electra ....the other 95% had realised significant value ...c100%. Never the less the experience at Hostmore (LON:MORE) has been particularly poor. I think they are very keen to sort that one out.... we will see. It's still touch and go with the balance sheet until a years cashflow comes in. It also means they are under real pressure to deliver with Navient (NSQ:NAVI) and have board representation without a fight so far. The omens look good but as usual it's not risk free. The change in CEO should be helpful. Anyway - this is sort of a regain your trust situation that I hope works out. Time will tell.
I assume this is relating to inflation in the USA, not UK?
Yep US cpi data
It's basically fascinating how this is playing out given these US numbers are being driven significantly by the back months falling away. October is a good month inflation wise but in November and December we will actually be losing negative numbers ....so potentially really unhelpful to those desperate for cuts to interest rates.
The UK situation is rather different from the US, out inflation is around 8.7% and interest are set to rise again soon. Energy prices for households will fall in July. Food prices still going up on some items such as vegetables, potatoes are said to be doubling in price due to shortages.
My morning smallcap tweet: The portfolio rodeo
Robert Walters (LON:RWA) Motorpoint (LON:MOTR) Plant Health Care (LON:PHC) Frontier Developments (LON:FDEV) James Fisher And Sons (LON:FSJ) Iofina (LON:IOF) M&C Saatchi (LON:SAA) IXICO (LON:IXI), Brave Bison (LON:BBSN)
◄Robert Walters (RWA)► guides FY-Dec23 profit significantly lower than market expectations. Recent 2 months' net fee income down 10%. "Reduced levels of candidate confidence and lengthening time to hire were signalled in the second half of 2022 and, contrary to the Board's prior expectations, are not yet showing sustained improvement." [SP=466 Cap=348m]
◄Motorpoint (MOTR)► FY-Mar. Outlook - expects conditions to remain challenging, tempered growth expectations and will limit investments to those that offer the best near term returns. [SP=NA Cap=NA]
◄Plant Health Care (PHC)► distribution agreement with Wilbur-Ellis Agribusiness, one of the largest US retailers of agricultural products. Will bring OBRONA to the US. [SP=9.2 Cap=29m]
◄Frontier Developments (FDEV)► guides FY-May in line. Guides FY24 in line. The review of Foundry (third party) games label concludes - will stop adding titles. [SP=578.98 Cap=229m]
◄James Fisher and Sons (FSJ)► Jan-May trading slightly ahead of mgmt expectations but guides FY unchanged. [SP=401.03 Cap=202m]
◄Iofina (IOF)► IO#9 IOsorb plant is operational. [SP=34 Cap=65m]
◄M&C Saatchi (SAA)► AGM stmt - the challenging trading environment has continued. Guides small decline in like-for-like net revenue but still confident of pretax growth. Pretax significantly H2 weighted. [SP=169.75 Cap=212m]
◄IXICO (IXI)► £2m 4 yr contract for the extension study of a Huntington's disease study. [SP=18.01 Cap=9m]
In line: BBSN
As Always, thank you MR C.
Marks Electrical (LON:MRK) - a reminder we're hosting an investor presentation with management tomorrow at 2.30pm - the registration link is here: https://www.equitydevelopment....
Marks Electrical (LON:MRK) - Built-in installations enhance growth outlook (detailed new research report here: https://www.equitydevelopment....)
Marks Electrical's preliminary FY2023 results confirmed the 21.5% sales growth and £7.5m EBITDA announced in the April trading update. The company generated £7.1m of free cash flow in FY2023, compared with £5.7m a year earlier, to end the year with a £10.0m positive net cash balance. Moreover, sales gains were 30% in the first two months of the current financial year.
An upgraded built-in installations programme represents an important addition to MRK's service offering, and raised awareness levels were notable in London, where they increased from 12% to 22% between October 2022 and May 2023 - a reinforced presence in the nation’s capital should be seen as a clear route to growth.
MRK’s ability to combine a consistent growth strategy with constant improvements in its offering and expanding awareness should, in our view, be rewarded with a higher share price. We maintain our 150p fair value, which implies FY2024 EV/sales of 1.3x and 16.2x FY2024 EV/EBITDA based on our current forecasts.
16.2 multiple based on future “bullshit earnings” / EBITDA seems a bit toppy in what is a competitive sector in a tough economy .
I would hardly call that “fair value”
Then again if they were paying me to say it. I guess I might (actually I would not)
Paid research notes citing a fair value based on a future EBITDA with a multiple of 16.2 well honestly not really what Stockopedia is all about is it ?
Think I would have wished for better operating leverage on 20% sales growth. EBITDA margins down. Long list of reasons given, some very plausible (e.g. end of business rates relief), but still feels like the jam is for tomorrow.
Castings CGS
I don’t hold but wish I did .
Absolute belting set of results and looks a rock solid company
Can’t even remember why but it’s on my watch list .
Pricing power looks great has passed on all its cost increase .
Has cash , makes even more cash , great balance sheet and pays out extra cash to shareholders .
No nonsense reporting straight forward .
Wow maybe recession risk but doesn’t look like they are struggling .
Might have missed the boat here but what a great easy to understand company producing great results .
Exactly how I feel. Only issue is will demand for trucks continue
Castings (LON:CGS)
Really pleasing results. "The turnover of the group increased to £201 million (£149 million last year) with a rise in profit before tax to £16.7 million compared to £12.1 million last year."
Dividend over 4% and close to 8% including the special which I suspect (but can't be sure) will continue in the future.
Note out from Canaccord on Research Tree raising forecasts for 2024 and 2025 by 10%.
Happy holder
Rather belatedly I've started to add notes on the chart for each folio stock (draw>call-out). It really helps me to understand why it's in my watchlist at all. Putting dates on the notes is a good idea too.
Hi planetx!
Yes, we really like Castings (LON:CGS) here at the SCVRs. I haven't looked at today's results yet.
My nagging fear with CGS (and probably the reason it always looks cheap) is that electrification means inevitably that demand for its main products (turbocharger housings for trucks) is likely to disappear completely, in say 10+ years?
So surely the key question is, how are they going to replace the loss of currently its main products? Hence I would want to see lots of emphasis on growth in new products/markets.
Regards, Paul.
EDIT: Roland's review of CGS is now up. He makes an interesting point that heavy trucks may not electrify, but maybe switch to hydrogen? That would be a very positive development for CGS, as presumably hydrogen vehicles would continue to require turbochargers.
Hi Paul
Castings (LON:CGS) - not sure you're correct re turbocharger housings - think that is Chamberlin (LON:CMH) ? Think Castings (LON:CGS) produce a wide range of truck components spread across engines & chassis?
Hi garbetklb,
I'm pretty sure I wasn't muddling up Castings (LON:CGS) and tiny nanocap £CMH.
I've been trying to find out the product mix that CGS makes, but am struggling to find it. Although this bit below from the 2022 Annual Report is helpful. If it's too small to read, it says that c.30% of revenue comes from powertrain components. It sees the move away from internal combustion engined vehicles as both a threat, and an opportunity.
A decent beat today from Games Workshop (LON:GAW) - it just keeps performing...
"Games Workshop is pleased to announce that for the 52 weeks ended 28 May 2023, we estimate the Group's core revenue to be not less than £440 million (2021/22: £387 million) and licensing income of £25 million (2021/22: £28 million). The Group's profit before tax is estimated to be not less than £170 million (2021/22: £157 million).
As in the prior year, in recognition of our staff's contribution to these results, we have paid during the year profit share cash payments, amounting in total to £11 million (2020/21: £10 million). These are paid in cash on an equal basis to each member of staff. Dividends declared and paid in the year were £136 million, 415 pence per share (2021/22: declared £77 million, 235 pence per share; paid £93 million, 285 pence per share)."
I'm a very happy holder here and looking forward to hopefully getting a concrete announcement on the deal with Amazon further to the "agreement in
principle" back in December.
Once again these are quite extraordinary numbers given that we are well and truly out of any Covid tailwinds (it makes me think that the boost from lockdowns has bedded in to leave Games Workshop (LON:GAW) with a much larger cohort of long term Wargamers).
Worth noting here that the overall revenue figure (core + licensing) is a stonking £465m versus a forecast, according to Stocko numbers, of £436m.
With growth like this and a potentially game changing (apologies, I hate this term but it could actually be applicable in this instance) deal with Amazon, I don't think it's looking overpriced at current levels.