Small Cap Value Report (Weds 16 August 2023) - RST, GATC, ESNT, CLX, MSLH

Good morning from Paul & Graham!
Today's report is now finished.
Inflation data
Has come out today from the ONS (Office for National Statistics). Here's the link to the report. Key points seem to me -
CPI inflation rate is 6.8% in July, down from 7.9% in July - good news.
Not so good news -
"Core CPI (excluding energy, food, alcohol and tobacco) rose by 6.9% in the 12 months to July 2023, unchanged from June."
Commentators seem to think that stubborn core inflation, combined with accelerating wages growth reported by the ONS yesterday, could mean the Bank of England keeps going with even more interest rate rises. It seems crazy to me that they're doing this, when we don't even know what economic impact the large increases already implemented will have. Anyway, everyone's got their own view.
It seems to me that hurting people in their 30-40s who mainly have mortgages, is likely to increase demands for higher pay from key staff. And push up rents. Thus fuelling more wage growth, and higher inflation. Do the people making these decisions really know what they're doing? Judging by central banks' long-term track records, I'd say vehemently no! Accusations of "groupthink" have come from some eminent sources, eg Mervyn King, and Andy Haldane.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Gattaca (LON:GATC) - up 6% to 102p (£32.5m) - Trading Update (profit warning) - Graham - GREEN
An unusual situation with this STEM recruitment firm as the shares edge higher on a profit warning. Perhaps like others, I’m enthused by the company’s willingness to pay dividends, having already bought back some shares. The cheapness on offer here is hard to ignore.
Restore (LON:RST) - 126p (pre market) £173m - Interim Results - Paul - AMBER/GREEN
The share price of this group has really crashed this year, on a profit warning. I was expecting more bad news, given the precipitous fall of late, but today's update generally reassures me that things haven't got any worse. Forecasts reiterated. Crucially, the debt situation looks under control I think. Could be a trade for a bounce, I reckon. Possibly!
Essentra (LON:ESNT) - down 0.3% to 154.8p (£453m) - Interim Results (in line) - Graham - AMBER
This former mid-cap has dropped into small-cap territory following some disposals that cleaned up its balance sheet and have enabled special dividends and a buyback. It’s an international component manufacturer and distributor and looks fairly valued to me.
Calnex Solutions (LON:CLX) - Unch 137p (£119m) - AGM Statement - Paul - AMBER
It's in line with expectations, but remember these were halved only a few months ago. Rating looks very expensive now, I can't see why shares are so expensive, given that a poor year is expected. Nice balance sheet though, and historically it's made fat margins. Price looks way too high to me, so bulls need to be very sure that profits recover strongly from the weak level expected this year.
Marshalls (LON:MSLH) - Down 4% to 247p (£625m) - Interim Results - Paul - AMBER/RED
We've had 2 profit warnings from this building supplies group previously this year. Today it says markets remain challenging, and no recovery expected until 2024. It dodges the question of performance vs market expectations. Together with considerable debt from an ill-timed acquisition, I'm giving this one the miss for now.
Paul’s Section;
Restore (LON:RST)
126p (pre market) £173m - Interim Results - Paul - AMBER/GREEN
Appoints an Interim CFO today (previously notified that the existing CFO was bowing out). The RNS is signed off by the Interim CEO, the previous one having fallen on his sword after a profit warning, and what looks like a failure of the whole strategy to diversify by acquisition.
Now we make it a hat-trick, with Interim results!
I’m keen to look at this one before 8am if I can, to see if there’s a trading opportunity here (for a possible bounce). It has been on my watchlist for a few weeks, given the calamitous share price performance this year, on what was previously a quite highly-rated growth stock -
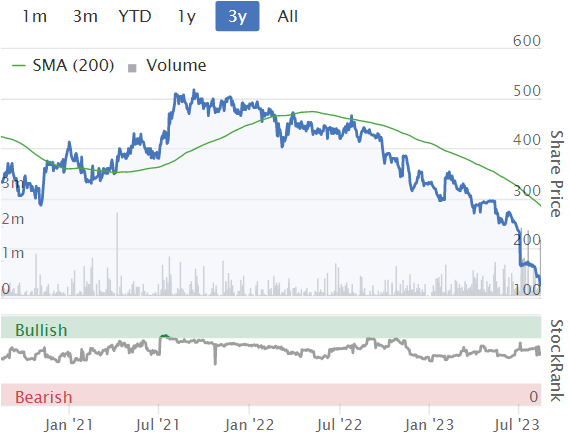
Restore plc (AIM: RST), the UK's leading provider of digital and information management and secure lifecycle services, today announces its unaudited results for the six months ended 30 June 2023 ("H1", or "the period").
Not a great start, with an unclear self-description above of what it actually does (the core business is document storage).
However, going through the rest of the statement, I’m quite encouraged by it. Crucially there’s no more bad news. Maybe the last profit warning could be the last one for this year ? -
Current trading remains in line with the Board's revised expectations to achieve an adjusted profit before tax of £31m for the full year.
Balance sheet - is weak, with NAV of £238m being dominated by goodwill on acquisitions of £294m. Erase that, and the £30m deferred tax liabilities (which is usually connected with goodwill), and I get NTAV negative £(26)m - not a disaster, but not ideal.
The other stand-out item is non-current bank debt of £123m, which is too high for comfort, partly offset by £25m cash, so net bank debt is £98m, which has come down slightly by nearly £6m compared with 6, and 12 months earlier. Banks and investors often focus on the direction of travel, as well as the actual amount of net debt, and are more tolerant when they can see it coming down.
As RST mentions in the commentary today, the business is still nicely cash generative (which I can confirm from the cashflow statement), so if it stops making more acquisitions, and limits divis & capex, then I could see it being able to reduce bank debt. Also, the key covenant measure of 1.8x EBITDA disclosed today is not into danger territory, and “well within” covenant levels.
So maybe the market shouldn’t be seeing this as a distressed debt situation, which was what I was beginning to worry about (and judging by the share price, so were investors in this).
Note that bank debt has been reduced by £35m (RCF), mostly funded by a fresh drawdown on US private placement notes (bonds) of £25m - note 10 doesn’t split these out, just calling the total “bank loans”. I’d like to know what the terms of the debt are, as it’s getting more costly each month as the Bank of England raises interest rates relentlessly, and the latest wage growth data suggests they might keep going with more increases, until they’ve succeeded in trashing the economy and impoverishing households with mortgages. Plus of course, the higher rates go, the riskier highly leveraged companies become, as just the interest cost alone is becoming onerous for many.
Overall, I’m still a bit worried about how much debt RST has, but it’s not at a level where I’d be ringing the alarm bells - particularly given that trading seems to have stabilised at a level where the business probably could reduce debt steadily in future.
Valuation - thanks to Canaccord for an update note today. They’ve pencilled in adj/dil EPS of 17.1p for FY 12/2023, down from 24.1p in 2022. If the business is now ex-growth, then I would only apply a PER of about 10 to that (also taking into account the heavy debt), so I get a valuation of c.171p/share. That compares with the market price of 126p currently, so possibility of a trade here for a bounce? I think maybe so.
Although that depends on who is selling in the market, and why? If institutions have lost faith in it, and want it off the books, the selling could continue. Or if they’re facing redemptions, and are forced sellers? Who knows.
My opinion - this is just a quick initial review. I think there are some positive signs here -
- Reiterating reduced guidance for 2023, so no more bad news.
- Maintaining a (29% reduced) divi suggests that it’s not panic stations.
- Sensible measures being taken to cut costs.
- Profit drop in 2023 is disappointing, but it’s not horrendous.
- Bank debt reducing, and whilst too high, doesn’t look dangerous.
Given the scale of the share price crash, maybe we’re due a bounce? It’s not a business I would want to hold long-term, but as a shorter term trade, this might be a buying opportunity? So it’s going on my watchlist as a possible trade.
EDIT: I'm tempted to go AMBER/GREEN for valuation reasons (could be a bargain trade), but think it's probably safest to stick to AMBER for now, as this is supposed to be a value report! Or maybe that means I should be more bullish, as I think it might be cheap now? I see it dipped in early trade this morning, but now seems to be edging up on a flurry of retail buyers. Actually, yes let's go with AMBER/GREEN, as I do think this looks a potentially interesting trade. I've just re-read the results, and it mentions that a lot of revenue is recurring, which helps.
Calnex Solutions (LON:CLX)
Unch 137p (£119m) - AGM Statement - Paul - AMBER
Calnex Solutions plc (AIM: CLX), a leading provider of test and measurement solutions for the global telecommunications sector, provides an update on trading ahead of its Annual General Meeting ("AGM") taking place at 9am today.
The current year is FY 3/2024.
It’s rare for the SCVR writers to completely disagree on any share, but that’s case with our recent comments on Calnex, as follows -
8/3/2023 - Paul viewed it RED at 117p, mainly on valuation grounds, as it looked much too expensive after a profit warning. On reflection, maybe that was a bit too harsh?
23/5/2023 - at 109p Roland viewed it GREEN after seeing excellent cash generation and a strong balance sheet in the historic FY 3/2023 results.
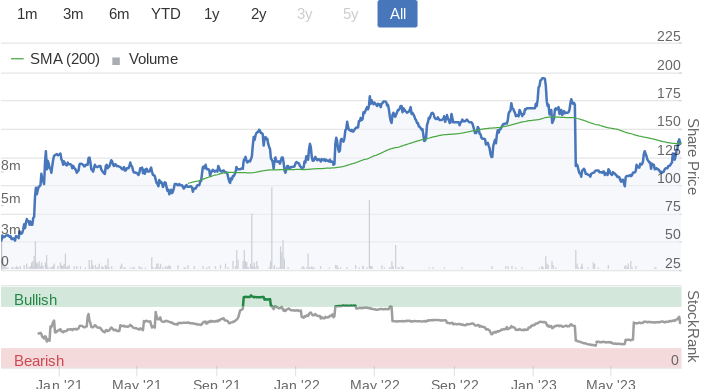
Much more important than our views, is that the market as a whole has been positive, taking the shares up to 137p in a nice rebound lately.
I wonder if this rise will stick, and puncture the moving average, or whether traders will bank their profits and move on (which is happening a lot right now with rebounds - sell the rally behaviour, typical of a bear market).
Today’s update at the AGM - this sounds a bit mixed, but reassures me that things haven’t worsened, and there might be some signs of a recovery possibly? This needs to be seen in the context of a sharp reduction in forecasts previously -
While customers continue to adopt a cautious approach to investment decisions, engagement levels remain high and there are signs of optimism with regard to the pipeline for H2 FY24, although the precise timing of orders remains unclear. Indicators across the wider industry also point to a cautiously improving outlook. The Board remains confident in the delivery of results for the year in line with current market expectations.
Cenkos (many thanks) was forecasting a drop in adEPS (adjusted, diluted earnings per share) from 6.8p FY 3/2023 actual, to only 3.6p this year - that’s from a note dated 23/5/2023. Assuming that’s still valid, since today confirms in line with expectations, gives us a PER of 38x the 137p current share price. That’s pause for thought. The way I look at it, shareholders holding this must be assuming that profits can roughly double in future, to get it onto a (still expensive) PER of 19x.
Supply chain - it says procurement issues are easing, which is what we’re hearing generally from many companies right now, which is helpful.
Balance sheet - I’ve just checked the last one, and it’s good, with plenty of net cash. No issues here.
Paul’s opinion - on reflection, I was indeed too harsh viewing this as red when it warned on profit in May 2023. Although as stated at the time, the main reasons were excessive valuation, and a nasty profit warning. It was being priced like a growth company, which is justified by the historic numbers, but not any more given that it halved guidance back in May, for FY 3/2024.
If you think profits are likely to double or more, then the valuation makes sense. If not, then it’s too expensive. An in line update isn’t good enough for me.
I think AMBER is a sensible view - nice company with good margins, but very expensive given that FY 3/2024 forecasts show a serious drop in profitability. Holders need to be very sure that this year is just a glitch!
Marshalls (LON:MSLH)
Down 4% to 247p (£625m) - Interim Results - Paul - AMBER/RED
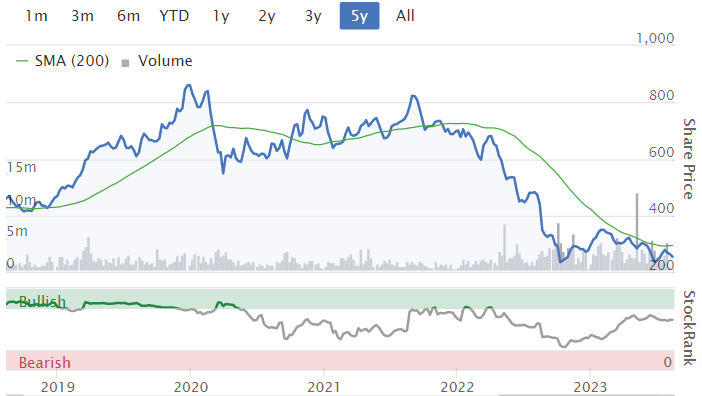
We’ve mentioned this building supplies company twice recently, with profit warnings on both 9 May 2023, and 31 July 2023. It strikes me that the share price seemed to shrug off the bad news surprisingly well. I've only done a quick review of the figures today.
Interim results today aren’t great: adj PBT is down 26% to £33.2m, but the underlying picture is worse, due to the figures being boosted by a full H1 contribution from a big acquisition. You can see the bigger picture from the reported segmental analysis.
There are some fairly big adjustments too, including restructuring costs.
Net debt is a bit of a worry, at £185m (pre-IFRS 16). This is also costly now, consuming over 20% of operating profit with finance costs.
Balance sheet isn’t great, but just about tolerable, providing trading doesn’t significantly worsen again, in which case things could get a bit tight.
Interim divi cut 54% to 2.6p.
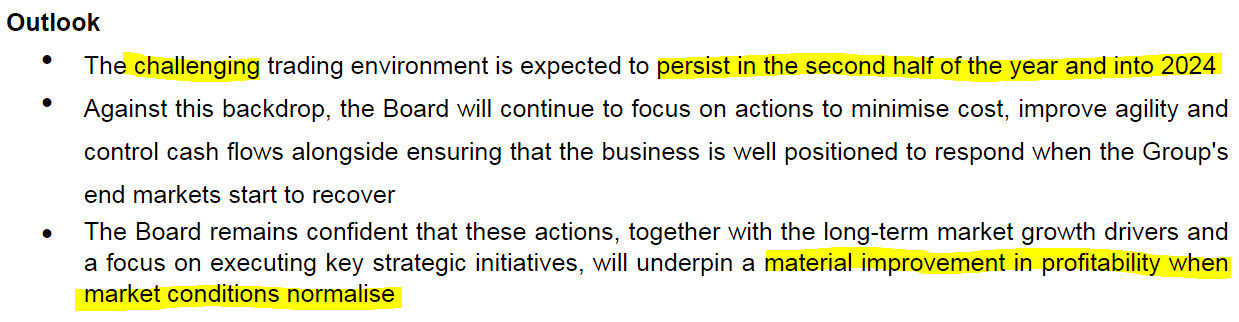
Outlook - this sums it up well - but dodges saying anything about performance vs market expectations, and I don't have access to any updated broker notes either. This makes me speculate that we could see broker forecasts quietly dropped further this year maybe?
Paul’s opinion - this is only brief, as I can’t see much point in digging deeper into the shares of a company that I wouldn’t be interested in investing in at this stage.
Bull case - profits should improve when current tough market conditions improve. Shares peaked at about 800p not long ago.
Bear case - consensus broker forecasts seem to be in a declining trend still, and the outlook today suggests recovery isn’t likely an time soon. Not cheap, on fwd PER of 12.7x, and there’s all that bank debt to consider too. Is it wise to be paying divis at all, given the uncertainty?
The share price is now back down to where it was 20 years ago. Is that an opportunity (for a big rebound in future?), or evidence of a not very good business? I don’t have a strong view either way.
It’s a pity the group geared up with a big acquisition at the wrong point in the cycle.
I think there could be better risk:reward situations in the sector, so this one’s not of interest to me.
Hence I think AMBER/RED, to reflect the wobbly outlook, and the bank debt.
It wouldn't surprise me for this share to have another leg down, to a new low, given that talk of recovery now seems some way off. This is a similar reason as to why I've cooled on the housebuilders too, as discussed here last week after an update from Bellway (LON:BWY) showing the order book massively down.
Graham’s Section:
Gattaca (LON:GATC)
Share price: 102p (+6%)
Market cap: £32.5m
Gattaca plc, the specialist staffing business, today provides the following unaudited trading update for the financial year ended 31 July 2023 ("FY23").
This isn’t one I usually cover but it should make for a nice company to compare with SThree (LON:STEM) (a share I usually write positively about!)
Here are the full-year highlights:
Net fee income down 1% to £43.6m. This is below estimates (not stated in the RNS).
Slightly heavier weighting in contract vs. permanent recruitment than last year. Contract 72%, permanent 28%.
“Continuing underlying PBT of £2.5m” is ahead of expectations due to “cost rebalancing programme and exit from low margin contracts”.
Contract recruitment: net fee income is broadly flat due to “exiting some low margin contracts”.
Permanent recruitment: net fee income fell 4% due to “industry-wide client and candidate challenges”.
Net cash is flat over the past six months at £21m, but is up compared to last year.
Outlook:
In light of the ongoing macroeconomic headwinds, particularly the uncertainty over the timing of any recovery in the wider economy and the Group's focus on sustainable contract growth, the Board currently expects profit before tax for FY24 to show marginal growth on FY23.
Estimates: Liberum have cut their adjusted PBT estimate by 25% to £3.0m.
Return of capital: the company plans to pay out a 2.5p full-year dividend, and a 2.5p special dividend. The EPS estimate for FY July 2023 is 5.6p, so this should be covered by earnings.
The company recently completed a £0.5m share buyback. With so much of its earnings flowing back to its investors, this seems like a very shareholder-oriented company!
CEO comment excerpt:
"The continued improvements in culture, staff retention and productivity are good signs that we are becoming a stronger business. Our progress has been impacted by the decline in the wider market, and although that is frustrating, I am pleased that we were able to continue to simplify and improve the business throughout the year and manage our cost base so as to report an improvement in profitability in the second half of the year."
Graham’s view
I wrote very harshly about this company in February, on the day of a profit warning. The company’s failure to generate statutory profits since 2018 was a red flag for me:
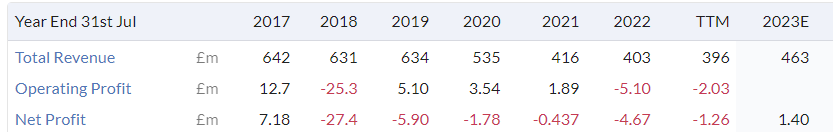
Despite my misgivings, I gave the stock a neutral rating, as it was only trading at a small premium to the company’s cash balance.
That remains the case today.
Despite the profit warning, the shares seem to actually be up this morning. That could be classic market inefficiency but I don’t think so. I think it’s because people understand that when a company is trading at an enterprise value of only around £10m-£12m, the real expectations for the business are already extremely low.
Much will depend on management’s intentions with the cash balance. Are they going to use it wisely? I don’t know.
As I write this, Gattaca’s enterprise value is c. £12m. At a 25% corporate tax rate, the expected £3m of adjusted PBT in the current financial year (FY24) translates to £2.25m of adjusted net income.
So I think the cash-adjusted PER here is about 5x (£12m divided by £2.25m).
Maybe this is good value? I think it could be. If management can do something reasonable with their cash pile, then it should be. I’ll tentatively give this stock the thumbs up today, on valuation grounds.
Management have shown shareholder orientation by returning cash to shareholders this year, so I want to give them the benefit of the doubt.
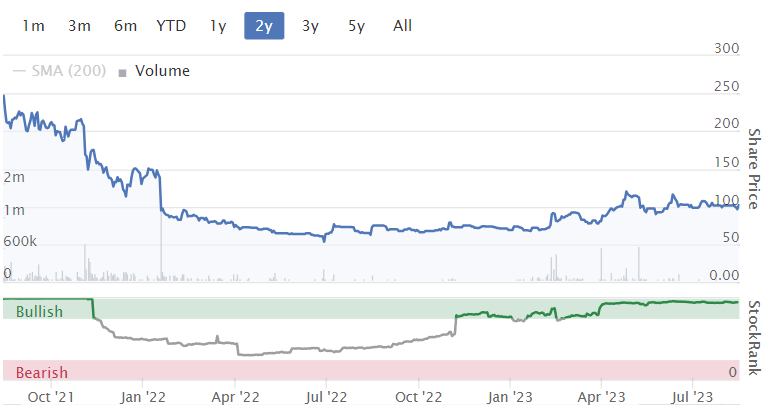
Essentra (LON:ESNT)
Share price: 154.8p (-0.3%)
Market cap: £453m
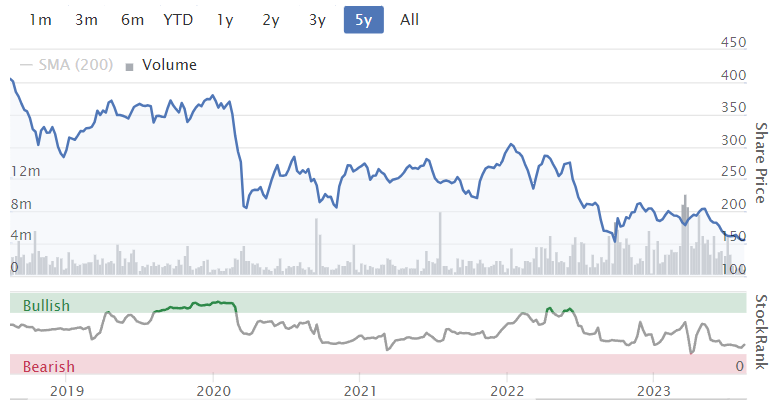
Paul covered this stock for the first time in January. It was previously too big to be in a small-cap report:
The great and the good are on the shareholder register: Soros, MFS, Fidelity, Invesco, etc.
Company description: “We are global manufacturers and distributors of vital component parts for hundreds of markets and thousands of products”.
They are focused on “injection moulded, vinyl dip moulded and metal items”.
H1 results: in line with expectations, and full-year expectations are unchanged.
There is a revenue decline, but a nice improvement in profitability:
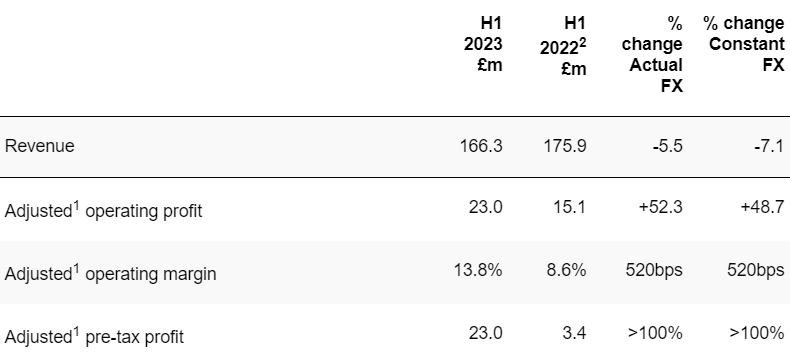
Note that the above numbers are not like-for-like, as there was an acquisition in December 2022. The like-for-like revenue decline is 10.4%.
Net debt improves from £310m (!) to only £8m, following two disposals.
The company is now looking to expand again, as a “bolt-on acquisition pipeline is actively being managed”.
A special dividend of £90m has already been paid.
There is also a £60m share buyback programme, with only 27% completed in H1. So I guess the company will have to increase its net debt by another c. £44m in order to complete this?
Outlook excerpt:
The business remains resilient and has the ability to manage volume impacts, through implementation of pricing actions, and careful cost management.
CEO comment excerpt:
"Essentra has shown financial and operational resilience in its first half year as a pure-play Components business, making further progress towards our medium-term targets, despite the macro-economic backdrop.
We continue to demonstrate the strength of our business model, which is underpinned by our global footprint, the breadth of our offer across a wide range of end-markets and our focus on our hassle-free customer proposition.
Geographic breakdown: revenues from APAC were very weak, down 18.3% at constant FX. The large “Americas” segment was also down 12.6% at constant FX.
Medium-term targets:
Organic revenue >5% CAGR
Total revenue >10% CAGR
Adjusted operating margin c.18%
Operating cash conversion >85%
Net debt to EBITDA <1.5x
These aren’t bad targets to have but I note that there is no reference to return on capital. Manufacturers should have a ROCE target, in my view.
Also, the 5% organic revenue growth target makes sense if inflation is 2%, but what if inflation is 10%?
Graham’s view
This is another special situation, where disposals have created a very different investment proposition: it’s now a “pure-play” business rather than a diversified group, and its balance sheet is far less leveraged.
These situations can sometimes throw out interesting investment opportunities. For example, if the large fund managers who own most of this company were to lose interest in it after the disposals, its shares might get sold down to an irrationally low price.
There is little evidence of that happening, however, based on the movements shown on Stockopedia’s shareholder page.
As for the company itself, I’m only mildly enthused by its medium-term plans and targets. 5% organic revenue growth wouldn’t really be anything to write home about, although an adjusted operating margin of 18% would be a good achievement.
I’ve not seen enough here to get me excited about these shares, which on face value appear to be fairly valued. Let me know if I’ve missed anything important!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Kitwave (LON:KITW)
This is a company I have been looking at and I quite like it. However, I notice that there has been considerable Director selling in June of this year. A total of over £4m by 5 different directors. I also notice that a similar thing happened in 2021, when 9 directors sold over £7M of stock. They don't appear to be the usual sell roughly half to cover tax liabilities from share options.
Does anyone out there have any insight? Is anyone else following this company, which other than this looks pretty good I reckon.
hi Norfolk'n'Good
re Kitwave (LON:KITW) Director share sales 7/23:
David Brind (CFO) sold 500k shares (retaining 1.5m shares) and Ben Maxted (COO) sold 150k shares (retaining 100k shares) so neither had a declarable level of holdings (i.e. less than 3%).
The other sales showing on Stocko were by Managers but not Board members. I believe that Chris Young is one of the sons of the founder and CEO Paul Young.
I note on Sharepad that Paul Young also apparently sold 200k shares but this is not shown on Stocko. However he still retains 10.8m shares representing 15.4% of the company. Personally I think it is only Paul Young's dealings that would be of any real significance for investors but in this case he only sold a tiny fraction of his holding.
I have been a holder since 4/22 and have a high regard for the company and management.
Kitwave (LON:KITW) are one of the few success stories of the 2021 crop of IPO's. Long established company since 1987, founder led with plenty of remaining skin in the game and growing both organically and by successfully integrated acquisitions in a fragmented market.
Lots to like imho.
Snazzy
Thank you, Snazzy!
I really appreciate you taking the time and trouble to reply. I thought someone may have the answer, and therein lies the beauty of the Stockopedia site and the SCVR readership. The accumulated knowledge is significant and has been a very useful source of information, ideas and learning for me. As have Roland, Graham and of course Paul Scott - now a legend in certain parts of Norfolk!
Roland did a good piece on Kitwave a few months back as well.
That was where my interest started.
Hi Norfolk,
Yes I also really like Kitwave (LON:KITW) and have mentioned it positively here 3 times so far in 2023.
However, the heavy Director selling has completely put me off for now. I don't care what the reasons are, whenever I've ignored big Director selling in the past, it's usually been a mistake, as something untoward often surfaces typically about 6-12 months later. A good recent example of that was when SDI (LON:SDI) 's CEO dumped most of his personal shareholding last autumn, and the performance this year has since disappointed. They know the company far better than we do, so Directors ditching a big chunk of their shares in any company, makes me a lot more wary that I would otherwise be. KITW falls into that category for me - a great pity, as in all other respects, it's a good company, and good investment story.
Regards, Paul.
Investegate seems excellent now under the new Ownership. An RNS which the LSE are showing as mid afternoon re a PMDR Marks and Spencer (LON:MKS) purchase has appeared simultaneously on their directors dealings section. Also, they reply promptly to any queries you might have and have now upped the max number of Companies you can list to 100 - I believe, Hat tip to them, it's now a very useful site.
I listened to a webinar from Capital (LON:CAPD) today covering their Interims announced today. I had never lsited/watched a webinar via the LSE before. Cheaper for companies than IMC etc? Registered via an email link I received as an interested party in Capital (LON:CAPD), with a registration number and a pin number. The presentation was 0900 for an hour. All the key senior execs were involved.
The numbers were not inspiring although the increasing diversification both beyond gold and beyond Africa are encouraging. The Labs section of the business is the fastest growing. The investments section of the business hold back the resultsbusiness/r. A third factor coming into the equation more and more is the political instability in Africa. The company is still not back into their Sudan business and some damage has been done as well as loss of business/profitability. This has an immediate effect on results eg Sudan where they hope to be back in in Q4 and I suggest negative investor psychology. The political instability now stretches across the whole of sub-Saharan Africa (not all countries of course and Capital (LON:CAPD) is only affected at the moment in in Sudan.
I was particularly interested in questions, and I thank our own Mark Simpson - via Mello and here too - for his insightful questions, and the ones I wanted to ask but didn't have time to put forward. They concerned some of the less satisfactory financials, the timings of the end of the contract with Centamin at Sukari in Egypt (with a chunk of capital assets which are quire specialised) and the political instability in Africa.
Not a share that is gong anywhere upwards fast. All IMHO of course.
It does seem crazy with higher interest to come. I do wonder though how many people with mortgages are actually affected. Most will be on fixed rates and it’s possible for those with a mortgage due for renewal to fix up to 6 months in advance and still change the deal in the 6 months. Despite all the horror stories of people’s interest payments shooting up by the press I believe it is in reality a very small percentage of those with a mortgage. It is mainly those that are first time buyers that will be hit hardest and many will likely hold off. Then on the flip side, those with money are now actually earning a lot of interest and so may have more disposable income.
I think around 100k households a month roll off their fixed rate deals in the coming year.
Which is about 2% of all those in the uk with a mortgage.
After lecturing everyone else on the evils of wage growth the BofE wasn't shy in spraying the cash around last month. They clearly dont need to accept they are poorer.
bailey's entire career has been one of being rewarded for failure while falling upwards
IMO ofc
Hi Graham, very useful write up on LON:ESNT which I hold. Or more accurately I bought back into recently having sold out at a loss @ £3 in 2020. One thing I might add is the current cash pile, which according to my calculations is still north of £250m even after the dividends and buy back. This makes it, IMO, better value than it first appears. Have I got my sums about right?
Your cash pile calculation is totally wrong. The company has a very small net debt.
Thanks
Re: £ESNT
Hi Berksbee - they report having net debt, not net cash! Best of luck with it. G
Paul, what would be your strategy for dealing with core inflation, if not raising interest rates?
Energy and food inflation is stabilising as expected.
Core inflation would seem to be a hangover of the excessive money printing during covid, and conventional economic practice would be to raise interest rates to tackle that. What alternatives are there?
If the Govt thinks there's too much money, chasing too few goods, then they could just raise taxes to remove purchasing power from the economy. They've done a bit of that (stealth taxes by freezing PAYE personal allowances, dragging more people into the 40% band, plus of course a big hike in corporation tax from 19% to 25%). Yet the Govt is still pursuing highly expansionary policy overall, with a deficit of something like 7% of GDP forecast this year roughly? So doesn't it seem that the BoE slamming on the brakes very hard, very quickly, through interest rates, is pulling in the opposite direction to tax & spending policy, which is still very loose?
We've probably not yet even seen the beginning of the next credit crunch either. I've heard some horror stories of banks pulling in facilities for SMEs. All of this has delayed effects, and whilst I'm no expert, the interest rate rises seem incredibly reckless, and with damaging effects that have barely yet begun. Surely a slower, more measured pace would have been more sensible?
What's caused inflation in the first place? The most credible explanation I've heard was Mervyn King, saying that excessive QE was done at the worst possible time - when supply was constrained by lockdowns. So too much money, chasing too few goods. But as we're hearing every day from companies, the supply constraints are now correcting. China factory gate prices are now falling, and with apparently 21% youth unemployment, they're seeing deflation, which comes through to us with a lag, at least for physical goods.
Meanwhile UK households are seeing a crunch on our disposable incomes, so we're already cutting back. Higher interest rates just takes money away from people with mortgages, and hands it on a plate to people who don't need it - savers. It's such a clumsy tool, it's really a miracle the UK economy is still functioning anywhere near as well as it seems to be.
And as always, the decent companies seem to manage, and still perform well.
Perhaps the best piece you have ever written.
Perhaps your nicest post yiannos ;-)
I think the UK's issue is that electorally there is no party willing to do what is necessary to increase productivity. That would be higher investment. A figure I've seen is 4% of GDP into R&D.
If you coupled that with higher spending on technical and vocational education, we'd have a chance of growing beyond our pitiful rate over the last 20 years.
I don't really have a solution. As we (the electorate) want continued high spending on welfare, especially the NHS, yet simultaneously seem unwilling to pay enough in taxes, governments will fill the gap by (1) cutting other areas of public spend eg investment and (2) borrowing.
So regarding interest rates and inflation, high inflation benefits borrowers and costs savers. Who is the biggest borrower in the UK? The government!
Therefore I think it has been inevitable that we have had an extended period of QE and negative real interest rates. It's there to shrink the government's debt! In a roundabout way, a more restrained and genteel form of money printing to part finance public spending. (Go overboard and you end up as Turkey etc with mega inflation.)
That said, I agree that the MPC should be pausing interest rate rises. They just cannot know whether successive increases have hit done the job. (But they do know that several years' inflation has shrunk borrowers' debt burden).
There must surely be greater risk now of triggering a deep recession by further immediate rises, compared to watchful waiting for several months. It will always be possible to contue increasing interest rates late 2023, if necessary.
Probably a UK general election within the next 12 months. So hard to see the goverment increasing taxes. My guess is whoever wins, they will increase taxes at that point, and this could be a remove any remaining upward pressure on interest rates.
Alas, the I can't any solution to our productivity problem post the G.E. We just are not willing to accept the deferred consumption which is the very definition of investment.
Need to sort out the jobless shirker and the perennial student, we need to get the able back to work. Now there's a challenge!
No thanks
But we have never been taxed so highly, we spend too much on welfare and free handouts. Companies should for many years 30 PLUS of been paying better wages rather than the Gov propping up the welfare state. Companies have failed to invest anything like the sums required in the modern world on staff and equipment. On top of this we have simply encouraged to many to go to Uni, only to be disappointed they are stacking shelves, far better companies employ the right people and develop the talent they require part in house and part technical colleges or similar.
And then we wasted a fortune on covid
At the moment we (the government) are wasting a fortune paying universal basic income to the wealthiest.
How so ?
net interests payment for the government I think are at around 120B at the moment up from around 40B (that won't be absolutely accurate) and that is likely to continue rising. That money is held in risk free assets and paid out in proportion to the amount of assets the holder has and is net spend by the government into the economy. As far as I'm concerned that is universal basic income to whoever holds them, and its not welfare recipients that typically do.
In a nutshell, the policy to reduce inflation is by pouring risk free returns to wealthy (or wealthier) people.
"But we have never been taxed so highly"
Are we taxed highly compared to other countries though ?
- surely with more pensioners than ever and us "paying as we go" with regard to these pensions and care home costs paid by the gov massively up we should be expecting higher taxes than the good old days when there were less old foggies collecting dosh. In some resects if we are closer to retirement than not then its the youth of today that will have a tougher job paying back for money we spent that we didnt have rather than us simply trying to get back to not accruinmg more debt.
Personally i dont think we are a million miles off being fair without making hard choices - being blunt allowing someone to give away 300k to kids then giving them 300k in care homes fees without paying a penny (as its all gone) - clearly suggests your average taxpayer is heavily subsidising those peeps having their cake and eating it to a ridiculous degree.
As Paul said earlier we simply dont live within out means - from 2010 -2020 we were going ok and we never tackled the deficit. The deficit should have ben paid off and we should have been saving for a rainy day. Lies lies and more lies from all policital parties in this regard - although i feel perhaps Rishi was probably the once chancellor who may have turned the tide - i wont blame him for covid coming along though so he was robbed of a chance of proving he want like the others. I would quite happily vote in a random bunch of experienced school dinner ladies/peeps to run the company in sensible fashion if that were a tick box option on the card.
If the conclusion is that there is too much purchasing power in the economy to match available supply (and I believe it is largely a supply issue) then the government has the tool to drain that.... ie fiscal policy. It's just a political decision. Meanwhile they insist its the BoE job.
Monetary policy doesn't appear to work at these levels of debt to gdp, or at least it causes a massive stimulative bias that is offsetting a slowdown. That and pay increases, indexation, etc are just throwing petrol on fire.
The BoE is relying on the theories of interest rates expectations and propensity of savers to spend, yet despite the lack of results thinks the answer is to continue juicing the economy (we'll find out soon) until the credit structure can't be maintained. Argentina was at 100% inflation and 80% interest rates last time I glanced.... yes there are differences when borrowing in dollars, but you would think someone would question the policy.
I believe inflation will go away due to changes in supply and I am more convinced of longer term deflation, but the government, BoE seem unwittingly determined for inflation to last as long as possible.
the government should be forced to balance the books on a monthly/yearly basis my vote is not a blank cheque for my government to borrow every month. cut something or spend less make a decision they get paid enough have a system similar to USA
If you prefer they balance the books every year they can raise taxes to achieve that.
The US system means the opposition can hold a gun to the head of the government (voted in by the people) and potentially cause a financial crisis in order to invoke their own policy choices. Th debt ceiling always gets raised regardless once they get what they want.
Anyone any thoughts on today's announcement from Concurrent Technologies (LON:CNC) ? The announcement is of an acquisition of a US company in a similar line of business, for 3 million, and a placing of 6 million. Concurrent Technologies (LON:CNC) has been around a long time, its past record is not particularly impressive, but is now on a growth spurt on the back of increased defence and energy sector spending. It is reasonably debt free, but under-capitalised for its growth rate. On the face of it, the rating is cheap for a growth stock (PER 14.8, PEG 0.5 according to Stockopedia.) There is a weak F-score, reflecting imho poor cash flow and the under-capitalisation. I don't hold, but it is high on my watch list.
I'm still trying to work it out, but here's my thoughts so far.
'Stryker' seem to be a customer of Concurrent Technologies (LON:CNC) who build the racks, buy the cards and assemble the systems which seem to be mainly defence & aerospace related. Their website is a bit low tech but there product lines do seem to include a fair smattering of military components. (Perhaps they think they don't need to advertise). What it seems to be is Concurrent trying to make themselves a more rounded supplier rather than simply a component supplier. Of course it means a placing at only 65p and dilution.
I've held Concurrent Technologies (LON:CNC) since 2019 and it is in the first batch of investments I made based on Stockopedia when I first became a sub. It was a bit staid then but had a safe cash pile. In retrospect a bit too staid as it seems much of the revenue was coming from older designs. Share price has not done well since early 2022 but I held because I thought their products would be in increased demand.
The old guard have left and the CEO is new, ex-Qinteiq I believe. He certainly seems to be investing to bring them up to date and pursue growth, at the expense of the cash pile.
They were badly affected by the semi-conductor shortage that arose from the lockdowns, so they tied up a lot of cash too in almost completed cards and they've only recently started to catch up on a backlog of orders. The new CEO did warn of this last year, and what he said has come to pass, so he gets a few brownie points for being open and honest. It indicates either a decent moat or exceptional diplomacy skills to be able to tell the customers their orders were going to be 18 months late and still retain the order.
Thank you for your appreciation of Stryker, As I understand the announcement, the value of Stryker comes more from its position in the supply chain, rather than its technology. The strategy makes sense, I had the feeling that in the past Concurrent Technologies (LON:CNC) has been pricing too low, set against its true design costs.
I'd say more likely that it is to make Concurrent Technologies (LON:CNC) a more rounded supplier with a US footprint. The accreditation they mention will have taken some effort to get, so the technology isn't negligible.
Interesting to note that Stryker were loss making last year and the consideration is approx half in Concurrent shares. So more dilution than I first thought. And the fund raise is for a lot more than just the cash consideration, so a bit of re-capitilisation on the quite.
Thanks for your comment on the pricing. I believe until recently they were living off older designs, so less scope for price increases than when a new design is introduced.
Gattaca plc (LON:GATC) A more positive FY update today than others in sector: continuing NFI seen just 1% lower at £43.6m and expected FY23 PBT above expectations at £2.5m; outlook is realistic but confident.
Net cash of £21m at 31 July y/e allows plans for 2.5p final div, 2.5p special div, and new £0.5m share buy-back
All in all , very encouraging progress
Gattaca
What do you “maintain your fair value at ?
Quite like seeing this in your summation always good for a chuckle .
Sometimes getting the Sectors right pays more than trying to pick up an individual stock unless both are the same!
When all energy intermediaries were going bankrupt the sectors surviving few were the place to be but we only had one choice here: Centrica (CNA) and that has done well.
Now with the NHS in crisis, the Private healthcare is the place to be but again I can only think of one company SPIRE (SPI).
Aviva and Legal and General do have some exposure to private healthcare but I believe that is limited.
Lucky dip, Aviva say this morning "We continue to
see very strong demand for private health insurance, with sales increasing by
58% as we expanded our services to corporate and individual customers." I hold and IMO a very robust business generating cash and returning it to shareholders. Undervalued and i continue to pick up their stock as they buy back in big numbers.
Good company report for Aviva (LON:AV.) this morning Toad, though private health insurance peanuts in the company's overall picture.
The story of 2023: the value of my small cap portfolio continues to rise but at a rate only slightly higher than I continue to deposit fresh money into my account,
A 6% return for 1H can’t be that bad in this market?
With all UK indices across the board flat to down now - anything positive is good and welcome. It feels complicated, it has for what seems like an age. I don’t know how many podcasts I listened to at the start of the year but I feel like only one was vaguely right…. 80% of the time, 12 months later the market goes up. We are muddling along.
I personally feel like we are sat in field of rich pickings … but we are also trying to swim against the tide… for now.
That's a decent return when compared to the FTSE indexes. But depends on how you benchmark your portfolio, based on your universe of shares you consider and hold.
If you replicate that for H2 I'm sure you'll be pleased be a double digit return for the full year! :)
Well done, that is not a bad return at all. I am positive to around a similar figure, but that literally happened in the last week due to one holding. I feel the tide is slowly turning, but have I just been lucky for once?
It was total return, including dividends received, and included a few clangers.
Yeah I agree not bad at all.... saying that if there are hundreds of us on here, then a tiny minority should be expected to have impressive results (Even if they choose stocks by dart throwing). Also, absolute gains are great, but it depends on what risk is being taken to get them.
I guess it's just a complex adaptive system and we are all trying to outsmart it.
I’m - 8% YTD and finding it hard just to sit on my hands. But I know that’s the right thing to do! For me this year is proving tougher than last year when alternative energy & commodities bailed me out - well sort of, I finished the year at -6%. I keep reminding myself that in the 2 preceding years I was up 45%, so I just need to sit tight. Maybe I just shouldn’t look at my PF for 6 months?
Lets face it we have endured two years of misery just look at the FTSE250 the past two years 24000 down to near 18000 again. I profited very well out of covid but my portfolio repositioning this year has failed me.