Small Cap Value Report (Weds 16 Dec 2020) - CPI, DRV, SDRY, CNC, EPWN, FRP

Good morning, it’s Paul here with the SCVR for Wednesday. It's a quiet news day (Edit: actually it's not, a load more came through after my initial trawl! End of edit) , so I've messaged Jack to say that I should be able to handle things solo today, and make some inroads into the backlog list.
.
Timing - Today's report is now finished.
Agenda -
Capita (LON:CPI) - Agreement to sell Education Software Solutions for up to £400m - helps very strained balance sheet
Driver (LON:DRV) - I review the results for FY 09/2020, published yesterday
Superdry (LON:SDRY) - Directorate changes, and waffle about the (not very convincing so far) "brand reset"
Concurrent Technologies (LON:CNC) - Trading update - ahead of expectations. Looks a nice little company.
Epwin (LON:EPWN) - Positive trading update
Frp Advisory (LON:FRP) - Half year results are in line, and the outlook sounds encouraging
.
Capita (LON:CPI)
43p - mkt cap £720m
This complex, low margin outsourcing group briefly dipped into small cap territory in October, but along with many other bombed out shares, bounced strongly in November on positive vaccine news, in what fund manager Keith Ashworth-Lord recently described as a “dash for trash”!
I want to follow up on it, because I covered Capita’s Q3 trading update here on 10 Nov 2020, and was quite shocked at how weak its balance sheet is - one of the worst I’ve seen, with NTAV negative at £(1.6)bn. Therefore a large equity fundraising will be needed at some point - hence shareholders are hostages to that being done on reasonable terms. If it’s bungled, and results in large dilution, then that could damage existing shareholders. Why take that risk?
There were going concern and bank covenant problems. So despite its size, I saw this share as very high risk.
A lot hinged on the pending disposal of its Education Software Solutions business. The good news (announced Mon 14 Dec 2020) is that an agreement has been signed with a credible buyer, Montagu Private Equity, to sell ESS for an enterprise value of up to £400m, with £298m payable on completion, expected in early 2021.
This certainly reduces risk at Capita, once it completes, which looks likely & imminent. However, Capita is far from out of the woods, because even with this cash injection, it will still have a painfully weak balance sheet. Also bear in mind that it’s selling off the family silver to raise cash. So whilst the balance sheet will improve from this disposal, the loss of the substantial profits made by the education division, £52.7m for FY 12/2019, means the remaining business is a lot less profitable & hence less valuable.
This deal reduces financial risk. Personally, I think this share looks awful, in a lousy sector, but good look to holders.
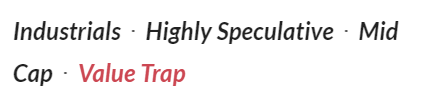
Note that the Stockopedia styles system doesn't look keen either -
.
.
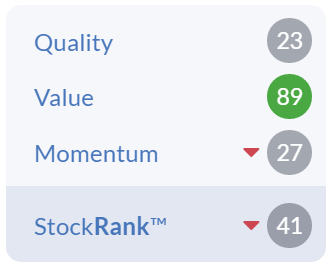
Lowish StockRank too (see below), with the low forward PER triggering a high value score by the looks of it - but this doesn't of course take into account that the share count could rise considerably, when an equity fundraising is done. Hence why I personally wouldn't hang my hat on the low PER being sustained. Remember, if a PER is in low to mid single digits, it usually means there's something wrong! The forward PER is shown as 5.4 on the StockReport here. Does that take into account the disposal of the profitable education division? That's something to check. Therefore that high value score could be vulnerable to downward revision when fresh broker forecasts feed through to the data, maybe?
.
.
Driver (LON:DRV)
Share price: 53p
No. shares: 52.2m
Market cap: £27.7m
Driver Group PLC (AIM: DRV), the global professional services consultancy to construction and engineering industries, is pleased to announce the dividend for the full year and its results for the financial year ended 30 September 2020.
Here are my notes from the recent trading update, on 26 Oct 2020. I always re-read my previous notes to quickly get up to speed, before delving into the latest update. Driver guided us to expect FY 09/2020 to deliver underlying PBT c.£2.5m, net cash strong at £8.2m, and I last concluded that the share looked good value at 51p.
Actual results are in line with that guidance.
- Revenue £53.1m (down 9%) - seems reasonable in the circumstances of covid/lockdown
- Underlying PBT is indeed £2.5m as expected, which is down 17% - again not bad, considering
- Strategy is to focus on higher margin work, which sounds sensible
- One-off severance costs of £0.76m takes takes a big chunk out of the £2.5m underlying PBT, to make actual PBT £1.74m (down 46%)
- Basic EPS halved to 2.6p - a PER of 20.4, but that does include the one-off costs, so adjusted EPS would be about 3.7p by my calculations, or an adjusted PER of 14.3 - which looks about right. Ah, I’ve just found the company’s adjusted EPS, which they say is 4.0p (down 15%), for a PER of 13.3
- Dividend of 0.75p to be paid in March 2021 - useful, but not exciting. Good to see divis reinstated (the interim was passed, which made sense at the time)
Balance sheet - is capital light, which is good - very little in fixed assets, which means more cashflow available to pay divis, in theory. Receivables have come down 12% on prior year, but still look too high, at £17.8m - that’s 34% of the entire year’s revenues, or 4 months sales, which I’m not comfortable with. That’s about double what I would expect to see (2 months sales), so an amber flag here - requires further investigation. The risk with large receivables, is that there could be disputed amounts in there, requiring a future write-off.
Current ratio (working capital) is very good, at 2.15 (for this type of business, I regard anything over about 1.5 as being strong)
Overall - this is a strong balance sheet, providing receivables turn into cash in due course.
Cash generation - has improved vs last year, due to favourable working capital movements. Bear in mind that when revenues shrink, this throws off cash. As the business (hopefully) expands in future, it could suck cash back into working capital, but that’s fine because the cash pile is healthy enough. Hardly any capex, which I like. Nothing untoward I can see in the cashflow statement overall, it looks fine.
Outlook & current trading - sounds alright overall. Not exactly brimming with confidence, but who is at the moment?
In view of the continuing global uncertainty as a result of the ongoing pandemic we are not in a position to reinstate forward guidance at this point. We will review the position at the time of our half year results.… Driver is conditioned to operating with relatively low forward revenue visibility and that has been made even more difficult because the pandemic has resulted in so much global uncertainty.
However, activity levels in the early weeks of the new financial year are encouraging and with a strong net cash position and the availability of increased debt facilities, the Directors believe that the Group is well placed to trade through this current uncertain market environment, and to take advantage of the opportunities afforded as a consequence of the disruption of COVID-19 in the Group's target markets.
I’m not sure what those opportunities might be? Is it suggesting competitors might be retrenching or going bust, or acquisitions perhaps? A bit more clarity on that would be helpful.
My opinion - it looks soundly financed, and has traded well in very difficult circumstances. If earnings rise in future, then that would drop the PER into attractive territory. Personally, I can’t get excited about this share, and think there might be better growth opportunities elsewhere. As a value share, it looks OK though.
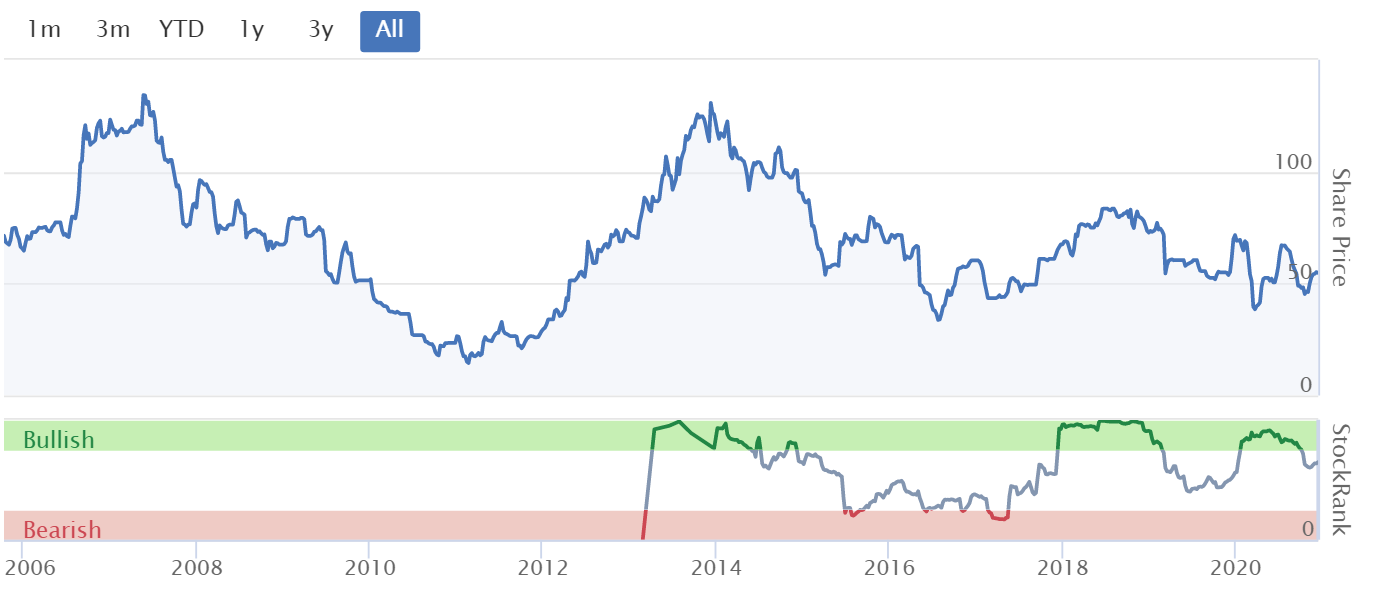
The trouble is, there's an opportunity cost to holding a share that goes sideways for years. 2011-2014 would have been a lovely trade, but it's very difficult to predict that kind of move. Imagine the profits that could have been made by holding say one of the big US tech stocks over the period below - contrary to the popular saying, elephants can gallop, very fast, some of them! Which does make me question what the point is, in buying unremarkable small caps?
.
.
Superdry (LON:SDRY)
Share price: 250p (up 4%, at 08:47)
No. shares: 82.0m
Market cap: £205m
- Founder & 20.3% shareholder, Julian Dunkerton, has been appointed CEO on a permanent basis - replacing his interim contract (to April 2021).
- Silvana Bonello (18 years at NIKE) is appointed Chief Operating Officer, effective March 2021.
- The Chairman, Peter Williams, is stepping down in 2021, when a successor is found. Dunkerton is in charge, I’ve heard secondhand from an insider that he’s very dominant internally - not necessarily a bad thing - I like founder-managed businesses. So Chairman is likely to be a fairly toothless role, in my opinion!
- CFO - they’re searching for a new one.
There’s additional commentary, which is mainly waffle about “resetting the Superdry brand”. Reading between the lines, it sounds like there’s no tangible evidence of progress yet - if there had been, then we’d have been given some hard numbers by now, e.g. this doesn't exactly fill me with confidence -
...There remains much to do - particularly against this current backdrop...
My opinion - this is a really tough turnaround, in my view. Much like Ted Baker (LON:TED) there is all the baggage of expensive, city centre shop leases, which are a millstone. Negotiations with landlords can only go so far, and in my view a CVA should be done, to clear the decks of loss-making stores & onerous leases, once and for all. I'd be much more interested in getting involved then.
I don’t think the broker forecasts are anywhere near realistic (i.e. too optimistic), and we have to remember that business rates relief, and furlough funding, have softened the blow this year. Once those schemes end, then retailers are likely to be facing really serious headwinds in future, requiring large sales increases to get anywhere near profitability again. How likely is that?
Remember that SDRY wasn’t making any money before covid struck. Therefore turning it around is a herculean, multi-year task. I just can’t see why people are so keen to gamble on that, when the odds look stacked against it.
If SDRY can really crack online sales, and shrink the store estate down to just a few prominent showrooms, then it could work. Joules (LON:JOUL) is a good example of a company apparently succeeding at that, and of course Next (LON:NXT) is the best in class for that winning strategy.
I’ll monitor SDRY closely, but for the moment, I think the stock market could be over-estimating the likelihood of a successful turnaround. If the turnaround gains traction, and looks like it's going to work, then of course I would turn bullish. But it needs to be based on realistic facts & figures, not wishful thinking.
My notes here from reviewing the interim results on 5 Nov 2020 give a lot more detail. A fundraising in late 2021 looks highly likely, in my view. In the meantime it has enough headroom, so no immediate cash crunch.
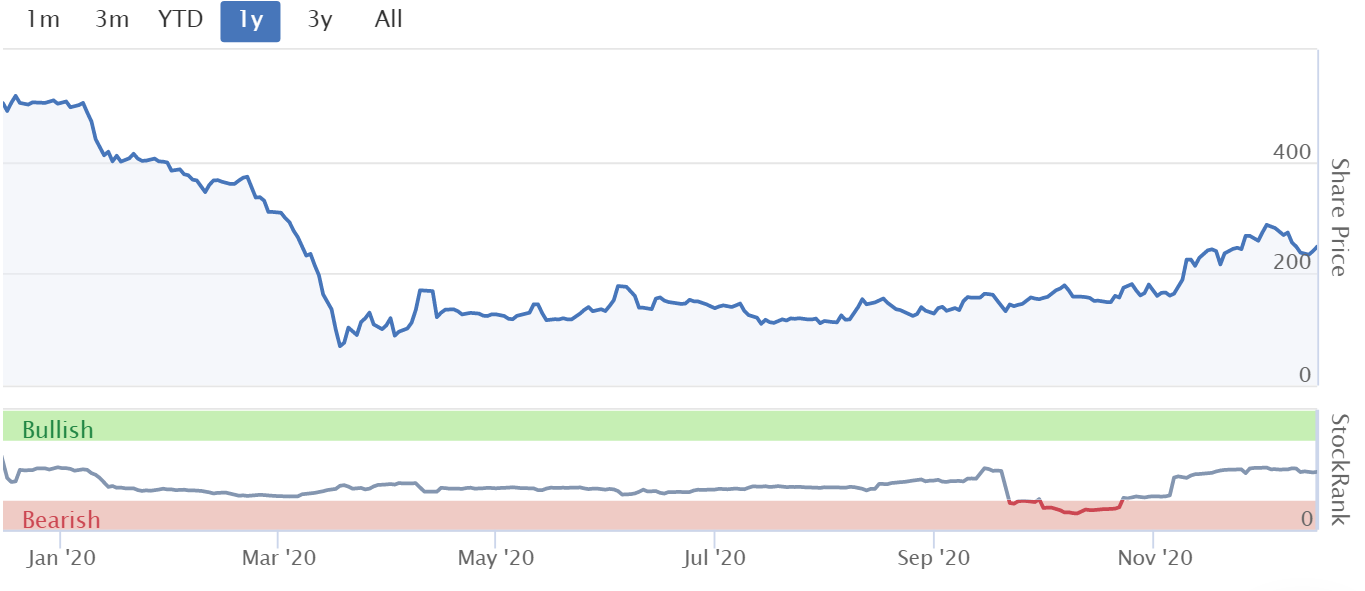
The chart looks good for now, but almost everything has rebounded lately. Will these increases stick? Some will, some won't, we just don't know which ones yet!
.
.
Concurrent Technologies (LON:CNC)
Share price: 108.5p (up 12%, at 10:11)
No. shares: 73.4m
Market cap: £79.6m
Concurrent Technologies Plc (AIM: CNC), a world leading specialist in the design and manufacture of high-end embedded computer products for critical applications in the defence, aerospace, telecommunications, transportation, scientific and industrial markets, announces a trading update for the year ending 31 December 2020.
Short & sweet, here is today’s update in full -
Based on its unaudited management accounts for 2020, the Company confirms that it expects to report revenues and profitability ahead of market expectations with cash generation remaining strong.
The Company also expects to continue the practice of paying a further interim dividend to shareholders and to pay this on or before 6th April 2021.
Clearly it’s a positive update, but doesn’t give any actual numbers. It would have been better to say: profit is expected to be in the range £x-y, subject to audit adjustments.
I suppose in this case, the code is generally that “ahead of market expectations” probably means something like 2-10% ahead of expectations (I’ve made that up), on the basis that you wouldn’t report if it was less than 2% ahead, and you would probably say materially ahead if more than 10%.
Isn’t it daft the way these things are done! Numbers are always better than coded wording.
Also, we're not given a footnote telling us what market expectations are, so I give this update a score of D - could try harder.
Thankfully, good old Cenkos come to our rescue, with an update note available on Research Tree, many thanks to them for this, it’s incredibly helpful.
Updated forecast for FY 12/2020 -
- Revenue raised to £20.2m (second upgrade in recent months) - note that about half revenues come from N.America
- Statutory PBT raised 19% to £2.5m
- Adj EPS raised from 5.7p to 6.1p (up 7%) - which at 108.5p share price, is a PER of 17.8 - which seems reasonable for a decently profitable company that is trading resiliently in a tough year
- Dividends - there’s a good track record of rising divis, and 2.55p is expected this year - yielding 2.4% - not bad in a low interest rate environment, and it’s well covered, and looks dependable
- Note that last year’s profit was boosted by a £1m keyman insurance payout, hence is not directly comparable to this year
Fabulous balance sheet (I’ve checked the last interims), with plenty of net cash. This suggests to me it’s a tight ship, with conservative management, which is very much what I look for, and what we need more of, in an uncertain world.
My opinion - this looks good to me. A decently profitable small cap, with a bulletproof balance sheet, and clearly operating in a niche with good margins, and seemingly dependable revenues.
My main reservation is that growth in profits has been pedestrian in recent years. So where’s the upside going to come from?
What I can say is that the financials get a thumbs up from me, so this would be a good share for readers to research further, to see if there might be anything exciting in the pipeline, from new products, etc. That’s outside my scope, so over to you.
.
Epwin (LON:EPWN)
Share price: 93p (up 5%, at 12:35)
No. shares: 143.0m
Market cap: £133.0m
Epwin Group Plc (AIM: EPWN) ("Epwin" or the "Group"), the leading manufacturer of low maintenance building products, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors, announces a trading update in respect of the year ended 31 December 2020 ("FY 2020") and notice of its full year results.
This sounds rather good -
Trading ahead of expectations for FY 2020
The Group has experienced better than expected trading conditions since reporting its half year results to the end of June 2020 on 10 September 2020. Demand from the RMI market, which represents around 70% of Group revenues, has been particularly strong during the fourth quarter of the year, while demand from the new build and social housing sectors has also been increasing.
This is more evidence, which we’re seeing across multiple sectors (apart from the obvious problem ones of travel, leisure, hospitality & retail), that the economy is recovering. I’m seeing this every day, from numerous companies. Hence why I’m bullish about the stock market - earnings are clearly now recovering, and massive Govt support measures are working, in preventing a prolonged or deeper recession.
LFL revenues were up 2% in July, and 3% in August (previously reported)
This improved to 5% ahead for July-November, implying (my workings below) assuming no seasonality, that Sept-Nov inclusive was up c.6.7% vs LY.
My workings below - as you can see, I just put in the numbers we're given, then the 320 figure is the balancing figure.
.

.
Year to date for FY 12/2020, revenues have improved from -33.4% in H1, to -15% for the 11 months to 30 Nov 2020 (versus last year). Clear progress in getting the business back to normal there.
Overall -
As a result, the Group's revenues and adjusted profit before tax for the year ended 31 December 2020 are anticipated to be ahead of current market expectations. Net debt at 31 December 2020 is also expected to be lower than current market expectations.
Other points -
- Pressure on supply chain, due to strong demand for extruded products
- This has impacted delivery times (hence some deferral of sales likely)
- Efficiency also impacted
- New warehouse in Telford should sort problems out in H2 of next year
- Dividends - will reinstate final divi (no amount given)
Outlook -
We look forward to a more positive 2021, with the medium and long-term drivers of our markets remaining strong."
My opinion - it sounds as if things are gradually getting back to normal, with another c.6 months needed to get there.
I think it makes sense to value the business on say 10p EPS future earnings. That would put it on a PER of about 9 - which seems good value.
Worth a closer look, I’d say, as a value/recovery idea, with a decent dividend yield likely in future.
.
Frp Advisory (LON:FRP)
Share price: 106.5p (up c.1.5% at 16:28)
No. shares: 239.6m
Market cap: £255.2m
FRP Advisory Group plc, a leading UK professional services firm specialising in restructuring advisory, is pleased to announce its unaudited interim results for the six-month period ended 31 October 2020 ('H1 2021' or 'first half').
Increasing size and profitability despite a subdued market
Highlights - to save me re-typing it all, I've copied the bullet points below, and added my own comments in square brackets -
Revenue increased 14% in the first half to £35.9m, 9% on an organic basis [Paul: in line with the H1 trading update previously]
· Adjusted underlying EBITDA up 7% to £9.7m [Paul: also in line with previous guidance]
· Adjusted PBT of £8.8m in line with Board expectations
· Strong balance sheet with cash at 31 October 2020 of £15.4m and an undrawn committed revolving credit facility (RCF) of £5m
· For the first half basic and diluted EPS is 2.48p. Adjusted EPS is 2.96p
· The Board declares an interim dividend for the first half of 1.6p per eligible3 share. This dividend will be based on shareholders per record date of 19 February 2021 and will be paid on Thursday 18 March 2021.The board intends to adopt a quarterly dividend payment schedule commencing in 2021
· The Board believes current trading is on track to comfortably achieve full year expectations
That all sounds quite good.
The half year trading update was published on 13 Nov 2020, I covered it here. FRP has an unusual structure, in that 25% of profits are paid out in additional remuneration to the partners. So it’s really a hybrid structure of a conventional partnership and a listed company.
I wasn’t sure whether the Cenkos forecasts included the 25% partners profit share or not, so I raised a query with the analyst, James, who kindly confirmed that his forecasts do indeed include this cost. So we don’t need to make any adjustments to forecast EPS.
Valuation - the latest Cenkos note out today (thanks again for that!) suggests:
5.8p adj EPS this year FY04/2021, a PER of 18.4, and
6.7p next year, a PER of 15.9
There’s likely to be upside on those forecasts, given that it’s already done 3.0p in H1, and the outlook says “on track to comfortably achieve” FY 04/2021 forecast.
Govt support schemes are keeping lots of zombie companies afloat, but clear signs are already appearing of struggling retailing/hospitality companies reaching the end of the line - e.g. Arcadia, Debenhams, and many smaller ones too. Also note that there are tons of CVAs being done in those sectors, to reset rents to affordable levels, which is lucrative work - I seem to recall that the relatively small & simple CVA done by Revolution Bars (LON:RBG) (I hold) cost about £1m. Both those sectors in their entirety need to reset rents lower, so CVA work could be a goldmine in the next few years for insolvency firms.
For that reason, I think even if Govt support schemes are extended again, as seems likely, it won’t be enough to save the many companies that are teetering on the edge already, and a few more months' lockdowns of some kind seeming likely.
Hence, sad though it is for the victims, FRP is likely to have plenty of work in the coming year or more.
Balance sheet - looks fine. As is usual for an insolvency practitioner, the receivables book is large - because these jobs are often paid after months, or even years’ work has been done.
My opinion - I think FRP looks good, and seems priced sensibly. If you’re bearish about the economy, then it’s a nice counter-cyclical thing to hold, and pays good divis too.
Even in a recovery, lots of companies are likely to need some form of restructuring. So either way, I reckon FRP should have maybe several years of work ahead.
It’s a respected firm, with a good name, and seems to be winning some high profile larger, complex jobs. Therefore it’s not really a direct competitor with Begbies, which seems to get the crumbs from the giants table! FRP is somewhere in the middle it seems. There could be upside from it moving up the value chain, which seems to be happening.
The problem is possibly stock market sentiment. With a vaccine now at the start of a rollout, we can see how the market is only really interested in cyclical recovery, and growth companies now. So will insolvency practitioner shares attract any buying interest? I’ve no idea, but it’s an important question. After all, for shares to go up, there have to be more buyers than sellers.
Fundamentals are good - FRP looks a decent company, and reasonably-priced. It could be a nice one for value/income investors to tuck away. I'm more interested in cyclical recovery/growth stocks at the moment, with probably larger & quicker upside potential, so it's not for me at this particular time, but i wouldn't rule out adding it to my portfolio if it languishes.
Having had more time to think about it, I'm more comfortable with the structure of shareholdings, partner profit share, etc.
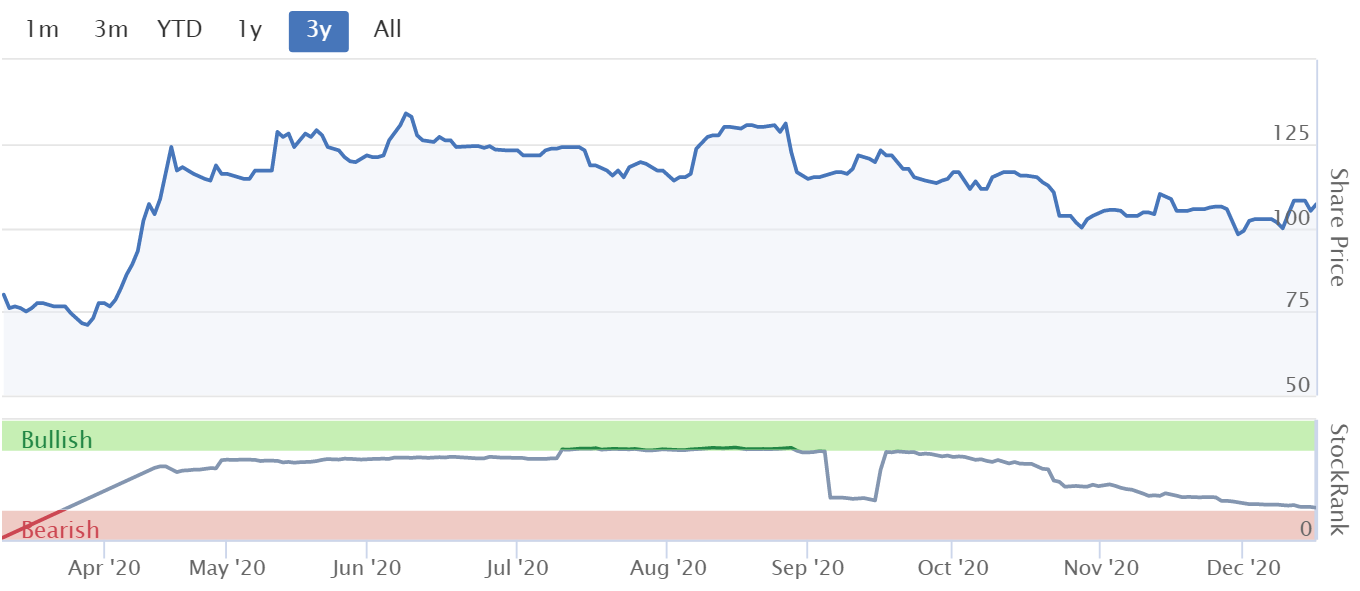
I'm not sure why the StockRank has declined so much recently, when the company is actually trading quite well?
.
.
That's me all done for the day! See you in the morning.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Bit of light entertainment here the dominion ceo has come out of hiding to explain why his fancy election counting machines couldn’t add up on election night - I can see clearly now (not).
https://youtube.com/watch?v=rqb5IHC96TA&feature=share
I know I really should be able to find this out for myself but I'm struggling.
Is there any connection between Frp Advisory (LON:FRP) , which listed on AIM in March 2020, and Fairpoint Group, which had the same ticker and whose AIM listing was cancelled in September 2017? They seem to operate in similar sectors but I can't find any other connection.
Many thanks,
Gostevie
No connection between FRP Advisory, and Fairpoint. Completely different companies.
Re £Boo - Thanks for the tip. I completely agree, it seems the Chairman has really got his head around these issues. Frankly it was the MPs who sometimes seemed out of their depth, to put it mildly! Must say, I’m really looking forward to the next performance update.
Oh dear - one of the more confusing EPIC codes - Paul - you need to put RBGP in for RBG Holdings (LON:RBGP) because Stocko is saying that you have written about Revolution Bars (LON:RBG) !
Someone is confused, but he did talk about Revolution Bars (LON:RBG) and not £RBGP
Boohoo (LON:BOO) On parliament TV now
https://www.parliamentlive.tv/Event/Index/2425b417-ad43-4885-8a8e-9c47c48d2698
Chairman standing his ground, quite well
I agree wholeheartedly. As expected, the highly competent senior management of a fantastically successful and ethical company like Boohoo (LON:BOO) responded to some quite hostile and biased questioning and questioner’s agendas, with straightforward clarity and remarkable restraint. I think I had better leave it there and put the kettle on LOL.
Thanks for the link to BooHoo (I hold) testimony to the Parliamentary inquisitors.
I've listened to the whole BOO section, and taken detailed notes. They dodged some of the earlier questions, but there was tons of detail given about all the exhaustive actions BOO is taking to fix the supply chain problems. It's 100% clear the Chairman is totally committed to pushing through this agenda of transparency & sustainability.
The Leicester East MP did not come across at all well, in my view. Caroline Lucas is nice, but very naive.
From BOO's side, Andrew Reaney came across very well, once he was allowed to get into the detail. Poor chap, they kept shutting him down every time he tried to chime in, prior to that!
The overall message is very clear - yes we got things wrong in the past, but we're absolutely determined to fix this, and are throwing real resources at improving supply chain problems, and ESG generally.
I liked Mahmud's answer about trade unions - "Anyone who wants to join, is free to do so. Simple as that. I personally don't want to join the union, so I don't want a meeting with them!"
Kelly Byrne said, "We pay National Living Wage, we don't discriminate by age, staff have healthcare & free shares".
Most points successfully rebutted I thought, especially from about half way through, when the BOO team seemed to get into their stride. At first they seemed a bit scripted & awkward, but that's natural I suppose.
Key point - BOO asked to come along to this session, as they wanted to set the record straight & demonstrate their commitment to improve. Mahmud's closing comment;
"It's not one thing we want to improve, it's everything. We will make things correct, that I promise you".
I'm happy, I think that was a credible session, with lots of specific details of what BOO has already done, and clear plans for what they're doing next. It's a lot more than PR, or box ticking, what they're doing, that's obvious.
Regards, Paul.
"Sellers Remorse" for selling my Boohoo (LON:BOO) @290p now 314p.
I in RMI means Improvement -see the second line in the announcement: "Repair, Maintenance and Improvement ("RMI")"
I know the frustration and often scanning text because of the amount one has to read I can miss the small details. ...
Ooops, my bad! Thanks for pointing out that EPWN did explain what RMI meant! My apologies, I'll amend the article now.
Regards, Paul.
Just dipped my toes into Rbg Holdings (LON:RBGP) today. It's completely out of favour in the current market. However, when stocks are shunned, for the contrarians out there, this could be an excellent play. Trade Update is expected in late Jan or early Feb 21. Current spread circa < 2%.
SUPPORT LEVEL - I have been scrutinising the trades over the past weeks. Whilst it has not gone up, it has remained at a support level of 58p (asking price). From the SP chart, you can see that this price has provided support in the past.
Currently, this is nearing the trough, the ciggie butt and it has been there for weeks.
During the Brexit negotiations last week, £RBGP's SP stayed relatively unmoved.
OCT 20 TU - From https://www.investegate.co.uk/...
Rbg Holdings (LON:RBGP) had a positive update which showed
a/ Lionfish getting back on track
b/ Convex Capital - the company specialising in selling companies - contributing to Rbg Holdings (LON:RBGP)
c/ Law firm side - remains robust.
From similar starting levels, the SP shot up to circa 10% after the TU.
SIMON THOMPSON (ST) - Given the positive TU, ST wrote an article on £RGBP, which lead to the SP to rise to its Oct 20, from 65p (after the initial release of the positive TU) to a high of 69p. Given that this has been one of his picks, it is likely that ST may recommend £RGBP come early next year again.
INDIVIDUAL COMPANIES PERFORMANCE
a/ Lionfish - is involved with litigation financing. In 2020, £RGBP have been strengthening this team with the appointment of a new head. Given the current climate, I would believe litigation financing is attractive for potential plaintiff companies and able to perform well in H2 and beyond.
b/ Convex Capital - with the possible changes in capital gains tax for entrepreneurs, this has spurred on entrepreneurs seeking to flog their businesses ASAP. See https://www.ft.com/content/012...
Whilst Convex may not be on a same playing field in terms of size and diversity as K3 Capital (LON:K3C), flogging companies is what Convex specialises in. In H1, they were pretty messed up with the lockdown. In H2, given the Chancellor's possible raid on CGT, I believe, Convex would be pretty busy despite Nov lockdown. Also Oct 20 TU, mentions that Convex aleady have sales in their kitty.
c/ Rosenblatt operation (law firm) - We know from the Oct 20 TU, Rosenblatt was doing pretty good in first part of H2.
"Following the publication of the Group's interim results for six months to 30 June 2020 on 16 September 2020, the Group's law firm, Rosenblatt Limited ("RBL") has continued to trade well with case value and volumes remaining significantly ahead year-on-year."
The question is how has / will Rosenblatt perform from 17th Sept to 31st Dec?
I believe that Rosenblatt have gone from strength to strength because a Cross read from Gateley Holdings (LON:GTLY) and Keystone Law (LON:KEYS) (particularly Keystone Law (LON:KEYS) who issued a recent TU on 30th Nov 20 stating that their performance was "comfortably ahead") - it seems that quite a few departments in law firms are doing very well given the planning of Brexit etc. So I believe the Nov lockdown had little to no negative impact on Rosenblatt.
FORGOTTEN STOCK
Like Creightons (LON:CRL) , £RGBP -
- got sold off big time and did not recover from the sell-off in mad October (the doom and gloom month)
- the vaccine jump, had no positive effect on it (and why should it given that more money was to be made from more visible covid-battered value stocks (plus fried chips on the side!) )
All this meant that SP has remained at a battered price of 59p (mid price).
Overall, I reckon Rbg Holdings (LON:RBGP) is an excellent opp for a contrarian play with minimal downside with short term possible upside of 15-20% (or medium term wise- 50%+ if £RGBP can get back to pre-covid SP (with Convex (who was acquired I believe late 2019) giving additional helping hand (however, you may need to balance this off with the potential dilution if Convex hits their targets and fulfils the earn-out clause)).
Yes it is not like £RR / or Iq-ai (LON:IQAI), ie rollercoaster ride. However, if you are like me and like your ciggie butt plays, this could be a good'un! Usual caveats, dyor.
Agree with all the above. Would also note that they have a few litigation cases that could see very big payouts, but very little of this is reflected in the balance sheet or market cap. In other words a nice free option.
Going for a nap Paul ? My you are fortunate to be able to do this. Have never managed a nap in my life and I am now in my 7th decade . No wonder you are so productive:)
Actually clears the brain. 20 mins not an hour. Drink coffee and takes 20 mins to work through. No noise - put earplugs. Have the dog touch the mouse on the works computer now and again so looks active - job done - except the dog thing. Automatic mouse mover - one of those big nap ideas :)
Hi Caper4,
I've always had a very unreliable sleep cycle, which constantly changes. Usually I'm a night owl, and struggle to get anything done before lunchtime, which is a nightmare for an investor. I get this from my mother, we both just perk up at about 10pm, and are full of beans until 2-3am. Strange isn't it? I read a theory that in ancient times, tribes which had a good mixture of night owls & early risers, stood a better chance of survival, because they always had people awake/alert around the clock, who could raise the alarm & fight off attackers. Whereas a tribe of entirely one or the other, could be easily slaughtered when they were all asleep. Interesting theory!
At the moment I'm on the early shift, starting work about 05:30 each morning. So by lunchtime, I'm tired, especially my eyes, from staring at computer screens for a long time.
I was diagnosed with type 2 diabetes this year (entirely my own fault, from poor diet, sweet tooth, sedentary lifestyle & far too much booze, so no sympathy expected or due!) which started during/after I had covid. It's not properly under control yet, hence I get very tired & have blurred vision by lunchtime, despite taking medication. So I'm focusing on healthy eating, exercise, and no boozing, and that seems to be starting to help. Hence why I do need to take a nap of about an hour at lunchtime, mainly to give my eyes a proper rest. It's really refreshing actually, giving your body & mind a proper rest half way through the day. My grandmother was always very busy, but had a sleep for about an hour after lunch, so it might be something genetic?
Everyone's different aren't they! Whatever works best, as we all know our own bodies/minds better than anyone else!
Best wishes, Paul.
Try running a snoring / sleep apnoea app while you sleep. You may not be getting enough restful sleep.
With respect to Driver (LON:DRV), the opportunities arising out of Covid relate to the quantum of projects that have been delayed as a consequence:
https://www.rics.org/uk/news-insight/latest-news/news-opinion/how-has-global-construction-activity-fared-in-the-face-of-covid-19/
Delays means claims and disputes (between Consultant, Contractors, Sub-Contractors, Employers etc) and that is Driver (LON:DRV) bread and butter although it’s the higher margin expert witness and arbitration work that comes a little later down the line that they will really benefit from.
Likely that we will have to wait until Q2/21 to have any real clarity on the volume of work that may arise out of Covid but I expect it to be fairly substantial.
I know an ex Director of Driver. I can't see the investment case for this company - its a bog standard consultancy selling hours by its consultants with a high risk of underutilisation. Another thing that puts me off is the high executive remuneration - £1m to the CEO? (page 28 of the annual report).
Regarding the "high executive remuneration" at Driver (LON:DRV) the £1m you refer to is pay for 8 months as CEO to end May plus £660k severance stipulated in his contract.
Alright do £600k plus shares of course. For a company that makes £2.5m?
Must admit excessive remuneration, free stock etc is one of the things that puts me off a company.
"something like 2-10% ahead of expectations (I’ve made that up)" LOL. I love your writing and insights Paul, especially when you casually throw in nuggets like this. Merry Xmas and keep up the good work
:-) Glad you enjoyed my little quip! It's a dry subject, so I like to lob in something a bit quirky from time to time!
Here are my heat maps for today (prices as at ~10:15am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volatility - volume / ATR up; moving more than a 20d EMA of the ATR):
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments. I define Small Cap using the Stockopedia Small Cap Size Group definition: Market Capitalisation between GBP 50 million and GBP 350 million.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap tile, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR related ones here in the hope that others may also find them interesting or useful. I aim to post sometime in the morning when I can, but sometimes work / family and other priorities get in the way.
greensiax
any thoughts on plus 500 post the ig group numbers yesterday.? Plus 500 looks very cheap v ig group and plus 500 mgt guidance for q4 looks ridiculously low in light of retail trading activity pickup on us elections and brexit. any thoughts ?
M Madar re Plus500 (LON:PLUS)
I've taken a small position in Plus500 (LON:PLUS) @1411p... (the gambler in me needs wins)... it does seem to be lagging CMC Markets (LON:CMCX) and IG Group (LON:IGG) .
Just going by the Yahoo volume indicators: It has 7 out of 8 days decline and a minor hold of price today on marginally below average volume.
I'd be pleased with myself to see 1450p to 1500p.
I'd top up if it falls in further chunks.
The metrics are reasonably good (SR 99) so a reasonable chance of some upside.
I figure, Plus500 (LON:PLUS) is going to move sooner than the other shares of interest on my list.
The UK govt is looking to go after the gambling industry in 2021.It may affect the spreadbetting firms who are trying to take precautions.IG are banning retail investors from betting on cryptocurrencies from january for instance.
"IG are banning retail investors from betting on cryptocurrencies from january for instance."
That is not at IG's initiative - the FCA has banned the sale of derivatives based on cryptocurrencies to retail investors by firms operating in or from the UK.
https://www.fca.org.uk/news/pr...
Personally I think that this is straying a bit far into nanny-state behaviour, but hey-ho. I don't want to speculate on cryto personally, but I don't see why others shouldn't. From my point of view as a holder of IG Group (LON:IGG) the most important thing to check was their likely exposure - not much fortunately, 2.8% of revenue from crypto last year.
Sensible move by the FSA to protect the foolish from the sharks.
Not an RNS (but probably should be) but Hornby (LON:HRN) has announced it's stopping fulfilling non-UK orders until after the New Year due to port congestion issues and Brexit uncertainty:
https://www.bbc.co.uk/news/bus...
"Due to the uncertainty surrounding Brexit & what it'll mean for our International customers, as of the 15th Dec, we will pause all non-UK orders until 4th Jan 2021.
We hope you can understand the difficult position we are in & remain patient with us until we can find a solution."
timarr
Hornby (LON:HRN) I hold and confess I'm undecided how to play this. RoW amounted to 37% of sales in H1 so not immaterial. I guess there are two questions: 1) value of likely international sales between now and 4th Jan. My guess is probably small. You're leaving it pretty late to be making international orders for Christmas now. 2) impact of final deal on prices. I think, taking worst case, WTO tariff on toys is low. No idea if there is a distinction for 'models'. In any event, these are not cheap items, they're uniquely available from HRN and so I don't think tariffs will have a big impact on sales.
On balance, I'll probably hold. Would love to hear alternative views, though!
Hornby (LON:HRN) I hold and confess I'm undecided how to play this.
Well there's no RNS which probably means it's not earnings sensitive - the RoW actually lost money in the last half year, although less than in the previous half. Obviously post Jan 1st it's hard to say, but doesn't look like a major impact.
Looking at the timing I can help thinking, rather unkindly perhaps, that the timing of this announcement is fortitous. It must be too late to make international orders now so the actual sales impact will be negligible. If this had come out a couple of weeks ago it might have been a bigger problem.
More generally though it's a flag about the kind of unexpected issues that can occur as we move to a new trading relationship, especially if we have a roadblock at ports for a few months. For most well capitalised businesses that should be short-term pain, but if you're struggling with cashflow it could be terminal.
As ever, avoid companies with weak balance sheets.
timarr
Not one you normally cover Paul but may be worth a look Simec Atlantis. Developing tidal energy and burning plastic and bio pellets in old coal stations. So good story. Bal Sheet poor as ever with these stocks but today share issue with US Institutional investor. Shares down because clearly dilution but I wonder if this won't bring the company to US attention. Anyway if you have time it would interest me.
Ra International (LON:RAI) Tomorrow's (17 Dec), 1pm, investor webinar with RAI is the opportunity to ask questions, following this week's trading update. Management: Soraya Narfeldt, CEO, Lar Narfeldt, COO & Andrew Bolter, CFO will deliver a brief overview, but you can get more detail of RAI, who they are and what they do in this excellent(!) short video.
To attend the Q&A webinar with management, register here. Hats off to them, to give all investors this opportunity.
Separately, over the next couple of weeks we have some cracking end of year round up interviews with some of our piworld guests this year. The wonderful Paul Scott will be updating us on how his year has gone, what went well, what he learned and which stock he's most bullish about for 2021, alongside others including Leon Boros, Richard Leonard, John Rosier, Cockney Rebel, Stephen English and a few others. All concise sound bites for Christmas/New Year. We'll post here, and of course on piworld.co.uk!
excellent. I much prefer people such as Paul or Richard to individual companies presentations. Thanks though Tamsin for the quality of the webinars and your always professional stewardship
Hi Caper4, I totally echo what you say. I also prefer interviews with people instead of interviews with companies.
Many thanks Tamzin for some excellent interviews throughout this year.
Please could somebody ask the Narfeldts whether they intend to reduce their c. 75% stake in Ra International (LON:RAI) .At present they are effectively unaccountable to all other shareholders. I think it is a really interesting company with great potential but the current dominant ownership by the founders is a red flag for me.
I really enjoy your interviews Tamzin. Great questions which often reveal very useful insights.
Tremor International (LON:TRMR) I know a few people are interested in this and I noted a piece of research this morning that shows a peer of Tremor International (LON:TRMR) has just IPO'd in US called SSP PubMatic. They are priced on 50* EV/EBITDA rising 25% on day 1 I think! Interesting to note that Tremor International (LON:TRMR) is on 9* EV/EBITDA and are also trading at significant discounts to other US related peers.
The differential is quite startling....looking at both I can't fathom where there should be a 5* market cap discount/uplift. I wouldn't want to try and argue which is a justifiable valuation but it does seem to highlight the massive difference in investor views either side of the Atlantic. Does make me wonder if I should probably have spent less time focused on the UK and more in the US though.
Back to Tremor International (LON:TRMR) and such valuation differences cause me to consider that it must now be a takeover target from a US entity. Even if someone pays double for the business they would create a lot of additional shareholder value (in the short term at least) so must be tempting. Reminds me somewhat of Codemaster as an example of richly rated US businesses buying less valued UK ones. It seems that you'd be crazy listing anything tech/healthcare/digital on the UK market these days as it puts you at a significant disadvantage.
Management have to be considering listing in the US and getting rid of UK listing. In fact as a shareholder I would actively encourage them to do so and that's a terrible indictment of the UK market. GAN was another recent example of a business moving to the US and quickly re-rating. There are quite a few others. Even if US tech is in a rather large bubble (and I personally suspect it is) a pooping of that bubble would probably still leave a UK company changing listings better off!
Bit of a musing on a quiet day
"that's a terrible indictment of the UK market"
Is it? Or is it a terrible indictment of the US market? Or the IPO market?
This narrative that the UK is a terrible market is really a narrative that the market is terrible for sellers of stock (IPOs, placings etc). Paul has often made this claim (I remember in relation to BigDish among others). But if true, then it's the same as a claim that the UK market is fantastic for buyers of stock (you and me), in which case you should waste no time in leveraging yourself to the hilt and buying everything in the UK that you can. (For the avoidance of doubt, I am not recommending this course of action).
In relation to Tremor International (LON:TRMR) I hold, but I think that the stocko designation of "highly speculative" is apt and there should be a sizeable reward on offer to those prepared to take the risk.
When you allow the creation of an arbitrage effect whereby any UK listed company in the tech/digital/healthcare space (or macro future trends) is massively vulnerable to takeovers by US companies that is a bad indictment of the listed market in question in my view. In this case it is the UK I am afraid.
That doesn't gloss over what we obviously both believe - ie that the US may be in something of a bubble hence I make no judgement as to what is the more sensible valuation. But it does create a massively dislocated playing field that is very unfavourable to those companies listing in the UK. Longer term if it persists it leads to a drain of intellectual property out of the UK into the higher valued market - in this case the US. That further degrades the quality of the UK listed market. So we can sit here and scoff at the high valuations that the US are willing to pay for these businesses at a theoretical and intellectual level but the practicality is that this polarised investor behaviour is acting as a drain of IP away from the UK and it has already started.
When you allow the creation of an arbitrage effect whereby any UK listed company in the tech/digital/healthcare space (or macro future trends) is massively vulnerable to takeovers by US companies that is a bad indictment of the listed market in question in my view
While not disagreeing with this the underlying problem is about the size of the addressable market. The US (and China and, theoretically, the EU) is large enough for a domestic company to obtain breakout scale without needing to go beyond its borders. The advantages of dealing with homogenous rules, culture and customers is enormous. A lot of share prices are based on extrapolation to the potential market (and I agree that many of the current valuations are ridiculous).
The UK lacks that scale and without it the potential for companies to grow at the same speed. If that were not the case the solution for UK companies would be obvious - they should list in the US. Sadly it's not that simple. That's not to say that you don't get secondary effects. Because the UK doesn't produce technology companies at scale the infrastructure to support that growth hasn't developed in the same way that it has in the US, which exacerbates the effect and the advantage of the US.
I don't think this is going to change. We will continue to create great ideas but for the most part we will never see them attain global scale before they get bought or outcompeted.
timarr
yes and no. It's not so much a domestic scale issue in my view, though the point about UK companies struggling scale up outside of domestic take-up is certainly valid. It is that for those that do achieve any scale in the right industry (ie following future macro trends) now offers an easy takeover opportunity of good UK companies straight into US ownership. eg William Hill recently, will GVC be next (I wouldn't bet against it - possibly MGM). Codemasters succumbed, will others follow? Several Healthcare companies moving assets into SPACs. GAN delisted and moved to US with great success are just a few examples.
I raised the Tremor International (LON:TRMR) example because it is a company I follow and is one of the more extreme examples of that valuation dislocation that I have currently seen. They are a global business - can't see them in the UK list for long. I can only hope as a shareholder that they re-list in the US rather than get bought out as that will yield me much better value but I'm braced for the latter. At a more macro level it disturbs me though as I don't want to see the UK stock market littered with low growth and commodity stocks any more than it already is.
It is that for those that do achieve any scale in the right industry (ie following future macro trends) now offers an easy takeover opportunity of good UK companies straight into US ownership
It's never been any different. Apart from ARM and, arguably, Autonomy name a single UK tech giant in the last 30 years?
Scaling a business requires the right ideas, access to markets and access to capital. The UK only really ticks the first of those boxes. Government support could help a bit with the second, although the coming changes to the takeover rules will provide some shelter for growth companies, but probably only at the cost of misallocation of capital.
Back when I started investing - over 30 years ago - this was a continual source of frustration to me. Now I can just invest in the best companies wherever they are.
Tremor International (LON:TRMR) has looked cheap because of its chequered history, not because the UK market systematically undervalues high growth stocks. All those online advertising companies have had deeply suspect and opaque business models - that's why Taptica's share price fell off a cliff when Google changed their ranking algorithm and why they've just settled the fake click lawsuit with Uber.
If those issues are truly behind it then the stock will rerate very nicely here in the UK. But the market has a memory, it often takes it a while to catch on when a change is occuring.
timarr
I believe it was XL Media which was hit by the change of Google algorithm, not Tremor.
I believe it was XL Media which was hit by the change of Google algorithm, not Tremor.
Yes, my bad.
All those video marketing companies look the same to me :-)
timarr
I've posted before (in detail which wont do here) re the resignation of the old CEO of Tremor International (LON:TRMR) around a US civil (ie non criminal and lower burden of proof) fraud case he was found guilty of in his prior payments related company that he sold to PE. IMO the PE buyer was a muppet, invested with credulity and didn't do his work well. I have no doubt that the PE guy got managed or sugarcoated information on the company....but this is the norm. I believe the nub of the case win was that company didn't tell him about paypal(?) threatening to withdraw services due to chargebacks (?). It was pretty obvious I felt that the PE biz were suckers that didn't know what they were doing but in a rush get a then sexy global payments business.
I developed a business some years ago that overlapped into much of the payment area...real cowboy zone that regulation struggles to get on top of and the big payments cos and banks etc were always messing with the small sexy fintech upstarts (keeping them in their place!)....we got loads of this. Related tangent...
Side note: holders of the very popular Bango (LON:BGO) -> I believe the sexy payment data monetisation they do is potentially/probably exploitation of regulatory loophole around online payments....people would pay a fortune to Facebook, Visa, etc for direct info on what their customers are buying and Bango provides a current loophole. I also note that the management of Bango are very promotional and like to move quick with acquisitions and disposals. I expect they'll be in with a new game changing acquisition which credulous investors will fund/swallow ;) Boku Inc (LON:BOKU) is probably overvalued but it is the more real play in this area and I expect that to prove out. The pop at Bango one day could be nasty.
So, I felt the stink re Tremor was smoke without fire aided by the vibe that Israeli = fraud. The person I was least comfortable with at Tremor /Taptica was the previous British chairman!
Anyway, in last couple of years I bought on the deep spikes down it had. I've been lucky though as I in no way foresaw the transformation they have undergone....that said the transformation is good! Tremor are in a fast moving space with behemoth competitors (Google!). Bruce Packard wrote a good critique in last week or so. But the positioning and operational momentum is strong and likely to persist for now...and the shares undervalued despite the recent pop up. It is highly unlikely that they don't surprise for the FY given the recent TU...it would be madness to have overplayed the recent TU and unlikely that short operating momentum dissipates as we head into year end and Christmas etc
That's correct it was XL Media.
The issue for Tremor, or Taptica as it was known at the time was that in 2018 the CEO Hagai Tal was accused of fraud. The accusations were related to the sale of a former company for which he was CEO and principal shareholder. Great Hill , a PE fund and the buyer sued for $122 million in damages. So Hagai Tal resigned from Tapitica and the stock tanked. The courts found in favour of Hagai Tal at the start of 2020.
Like or not that seems to have a lingering effect on the company's reputation. It wasn't help by the general feeling that overseas companies that listed on AIM were viewed with suspicion due to the rash of Chinese frauds. There were also some Israeli based company that had less than stellar reputations listed on Aim and well Tremor got lumped in with them.
I have held Tremor for a long time now and despite it's growth it still trades a discount to peers listed in other exchanges. Even companies showing no growth such Acuity Holding listed in Canada trade at a premium to Tremor.
I can certainly see them being a take over target for a US listed competitor which frankly I am hoping doesn't happen. It would be value accretive the buyer form the get go given the differential in valuation.
It would make sense for Tremor to list in the US. A higher valuation gives the company better options if they need to raise funds and would probably raise their profile in one of their significant markets.
Tremor has done a great job skating to where the puck is going. Management had the foresight to acquire companies in segments in the adtech space that subsequently grew massively and more so than the industry in general.
Timarr
If we need to quote Autonomy as a tech giant, maybe it shows how low we have come. At least it showed that UK tech companies too can sometimes have eye watering valuations but not much substance - as HP execs found out to their cost.
But the UK does have quite a number of foodtech and fintech stars - many started relatively recently: Ocado (LON:OCDO) Just Eat Takeaway.com Nv (LON:JET) (I think OK to still think as British) and Deliveroo are all tech companies in my mind. London Stock Exchange (LON:LSE) Revolut, Monzo are surely also principally tech companies.
And reportedly UK cybersecurity firm, Darktrace is being lined up for a >£3bn IPO on the LSE in early 2021. Being UK HQed and listing in London does not seem to be a problem for them - although the Mike Lynch and Sushovan Hussain links (to come full circle back to Autonomy) might prevent any US listing.
You have cause and effect the wrong way around.
The UK tech market is the second biggest outside the US. Companies from all over the world base large parts of their IT departments in the UK. This creates the issue, if it works and sells well in the UK, it instantly becomes a viable purchase for a US company before it gets too big and expensive to buy out.
So yes, UK companies get taken out early, not because they can't scale, it's because they scale easily and quickly.
"When you allow the creation of an arbitrage effect whereby any UK listed company ... is massively vulnerable to takeovers by US companies that is a bad indictment of the listed market in question in my view."
We'll have to agree to disagree then. In my view that is not an indictment of the market at all. It is just part of the way that markets work (and markets do work). I don't disagree that it happens, but I think the bigger problem would be if it didn't happen.
It's not just a function of the US v UK, we see it within both markets as well. There are several successful UK companies whose whole strategy is to use their size and highly rated shares to acquire smaller companies. I say good luck to them. Lots of people (including me) have benefitted on both sides of those deals. What results (on average, provided regulators are effective) is a more efficient use of capital and a more productive economy.
Can think of more than a few instances where sellers (often private equity) have managed unload some highly priced turkeys onto the UK IPO scene and gotten away with the spoils. So maybe not so terrible.
any chance you would be able to review todays Restaurant (LON:RTN) trading update?
Concurrent Technologies (LON:CNC) gave a trading update this morning. can you guys cover it? I bought some at the open and looks good to me.Thanks
If Paul doesn't get time Christian: Oct 27, 2020 by STOCKWATCH UK is a very good summary of recent events, if you haven't yet read it on discussions page. Todays announcement is a welcome turnaround from interims, although quite why this is rated a falling star seems a bit premature. A long way up yet I feel, although at their own pace
REDDE NORTHGATE...decent and detailed (27 pages of text) note from Mike Allen at Zeus today. Undeniably cheap. On his estimates, PE seen as 9.6x for e21 then 7.8x followed by 6.1x for the following years. Corresponding yield estimates...5.1%, 6.3%, and then 8.1%. Redde Northgate (LON:REDD)
Redde Northgate (LON:REDD)
Thanks for that Jeremy - seems very reassuring ref those quoted numbers albeit as ever we should expect future brokers estimates to be waaaay more than half full under "normal circumstances".
Hopefully the reduced 2023 PE is simply due to expected increases in EPS and net profit for that year?
The 7.8 pe 2022 figure seems to match exactly what is showing on stockopedia this morning.
We probably should disregard 2023 numbers as being something more suitable for the upcoming new "Foundation Series" that will hopefully be premiering on Apple TV before my free years subscription runs out.
Certainly these numbers are more than sufficient for this to remain a strong hold for me depsite the the nice rise in shareprice in the very short short time have owned. Often quick risers in my porttfolio get chucked out quicker than the bathwater.
When Martin Ward (current CEO of Redde Northgate) was CEO of Redde he tended to be conservative with a small 'c' on the numbers then over deliver.
Interesting. Guess I am more an investor than a trader but it rarely bothers me when a company such as Boohoo, Polar Capital, Redde etc rise or fall quickly. Indeed,if the share falls I tend to fill my boots. But then I only own about a dozen stocks and all are long term holds.
Trading is no doubt good fun but I don’t have the time or expertise to do this profitability. Good though to read posts from you and others on here who seem to know what they are doing :)
Trading is no doubt good fun but I don’t have the time or expertise to do this profitability. Good though to read posts from you and others on here who seem to know what they are doing :)
Despite what i posted i don't try to overtrade - i would guess my average holding length is easily 2 years plus per share. So this is more a rare quick success for me than any cunning method that regulalry books lots of quick 40-50% gains unfortunately for me.
Is there a link to where we can get our hand on this Jeremy?
Morning Paul, Frp Advisory (LON:FRP) interim results out this morning look interesting. Profit in line despite market being down on last year in terms of insolvencies. Also declared interim divi.
Thanks, Frp Advisory (LON:FRP) didn't come up on my first sweep of the TU/results statements, but I see it now. Will add that one to the list, as I had an update on it pending, after I queried something with the house broker. So I'll write up something on that one later this morning.
Regards, Paul.
My morning smallcap tweet:
SIMEC Atlantis Energy (LON:SAE) AFC Energy (LON:AFC) Cyanconnode Holdings (LON:CYAN) Concurrent Technologies (LON:CNC) NAHL (LON:NAH) Goodwin (LON:GDWN) MS International (LON:MSI)
SIMEC Atlantis Energy (SAE) to raise up to £12m in six tranches from New Technology Capital Group. Sounds somewhat like a death spiral. [SP=16.74 Cap=82m]
AFC Energy (AFC) strategic partnership with ABB, a world leader in electrification and digitalisation technologies. ABB and AFC will develop and launch a bespoke high power EV charging product. Both will "invest into a Commercialisation and Marketing Agreement, and Joint Product Development Agreement to showcase the supply of secure, reliable and flexible on-site power generation in ultra-rapid EV charging." [SP=37.5 Cap=254m]
CyanConnode (CYAN) headline 'Director Share Purchases'. Ooh, that sounds positive. But it's about paying directors shares in lieu of remuneration, so far from enthusiastically putting their hands in their pockets they are having the paper rammed down their throats. [SP=4.5 Cap=8m]
Concurrent Technologies (CNC) guides FY(Dec) rev and profit ahead of market expectations. Will pay a further interim dividend. [SP=95.03 Cap=70m]
NAHL Group (NAH) volumes in all businesses had a steady recovery throughout Q3, ahead of management's planning assumptions. "On entering Q4, the impact of the second national lockdown and localised restrictions have impacted volumes, but to a lesser extent than compared to the first national lockdown." Last 5 months rev down 15%. Frenkel Topping offer PUSU deadline extended to 13 Jan. [SP=44.15 Cap=20m]
Goodwin (GDWN) H1(Oct) rev down 11%, pretax down 22%. Guides H2 pretax at least level with H1. [SP=3380 Cap=254m]
MS International (MSI) H1(Oct) rev down 21%, pretax -£1.08m (-£0.49m). Order book up since Apr. [SP=130 Cap=22m]
CNC. An old favourite of mine. Fortunately have got quite used to them under selling themselves. A bit like Air Partner. I guess its sensible to be cautious in these times
Capita’s fall is well deserved. Their education software division (largely consisting of a ‘past it’s sell by’ MIS system which they supply to schools at outrageous profit margins) demonstrated for years one of the least useful characteristics of capitalism as it used its monopoly power to strangle innovation and competition to the detriment of society’s need for effectively managed educational institutions. Hopefully, though doubtfully, government ( the DfE) will learn from the example that by allowing too few to gain too much it makes innovation too difficult. A good lesson for investors too.