Small Cap Value Report (Weds 16 Nov 2022) - CARD, RNO, DOTD, MCB, CGS

Good morning! It's just Paul here today, because Graham is tied up, preparing for his Mello Chiswick talk at 13:00. Today's report is now finished.
I'll be arriving at Mello Chiswick probably mid-afternoon today, and am participating in the "Stock Slam" (starts at 17:15), where about 12 of us will get 3 minutes to each pitch a stock idea. I've decided to focus on housebuilders, which I think are excellent value, and my favourite small cap builder, mentioned here positively before, MJ GLEESON (LON:GLE)
I'm hoping to meet lots of Stockopedia subscribers at Mello Chiswick, do say hello - I'll be carrying a fluorescent yellow rucksack - as you know, I like to fade into the background! ;-)
Agenda
Paul's Section only today:
MADE.com - John Pye Auctions is to sell off the inventories, expected to begin soon. Click here for details, where you can pre-register, and maybe pick up a bargain?
Card Factory (LON:CARD) - a positive update came out mid-afternoon yesterday. It's raising profit guidance, as strong sales in H1 have continued into H2. This makes me much more comfortable about this share (which still has excessive net debt, remember). The coast now looks clear to gradually reduce debt from cashflows, without shareholders needing to worry about dilution or the bank getting cold feet. Risk:reward has significantly improved I think, so for that reason, I'll give it a thumbs up.
Renold (LON:RNO) - a quick review of its interim results has impressed me. Strong H1 trading, a record order book, upbeat mgt commentary, and a balance sheet that's OK, although net debt has risen a lot due to a big recent acquisition (that's already performing ahead of expectations). I explain why the risk of a profit warning looks low, and the valuation seems modest, with decent upside. So a thumbs up from me.
dotDigital (LON:DOTD) - I review the results for FY 6/2022 (seems very late). I'm pleasantly surprised by the numbers, and valuation looks quite reasonable once you adjust out the excess cash pile. I'm not sure about the longer term prospects, but as things stand now, this share looks quite attractive, having de-rated a lot in the last year. So it gets a thumbs up from me.
McBride (LON:MCB) [quick comment] - AGM trading update says its trading in line with expectations for FY 6/2023. That means loss-making, as forecasts have plunged in the last year. H1 revs to date up 29%, due to price rises, but of course costs have soared. “Funding situation has stabilised” after recent refinancing (which I covered here), with liquidity averaging £61m so far each month end in H1. Costs continue to rise, so seeking further mitigation with customers. My view - this is a risky special situation, but the remarkable leniency from banks recently (suspending key covenant until 2024) gives it time to dig itself out of the hole. Could recover, but too risky for me personally, due to the size of the bank debt. [no section below]
£CGS [quick comment] - very quick actually, as I'm almost out of time. Good interim results, well up on last year's H1. Passing on cost increases. Strong underlying demand. Fantastic balance sheet, even after paying out special divi. Shares have shot up a lot recently, so I hope some readers bought them when they were on special offer! Still reasonably priced, and with a good divi yield. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Card Factory (LON:CARD)
59p (up 15% yesterday)
Market cap £201m
Trading Update (ahead)
Card Factory, the UK's leading specialist retailer of greeting cards, gifts, wrap and gift bags, announces an update to its trading expectations for the current financial year to 31 January 2023 (FY23).
This positive surprise was issued at 14:45 yesterday, an awkward time, that disadvantages private investors, who may be at work and hence not able to react immediately. Still, nobody minds good news!
Summarising it -
H2 trading to date (Aug, Sept, Oct, Nov so far) "stronger than expected"
Largely driven by stores, which have seen revenues +6.2% (LFL) vs LY, year-to-date. That's impressive! Although note from the interim statement on 27 Sept 2022 that stores LFL was previously +6.1% LFL in H1 - so only a slight improvement in H2.
Online & commercial partnerships "performing in line with expectations" - but no figures given. Note these were negative in H1 (since stores LFL growth was +6.1%, but total LFL growth was +4.1%).
Encouraging start to peak Christmas trading period, with "sales marginally ahead of expectations".
All peak season stock sourced overseas has arrived in the UK, with a "significant proportion already delivered to store" - that's reassuring, but as supply chains are easing generally, then this is as expected, and is a nice tailwind for all non-food retailers, who import nearly everything from the Far East, especially with freight rates having plummeted too.
EBITDA guidance for FY 1/2023 raised from £88.8m to £96.0m. EBITDA is meaningless since IFRS 16, but CARD helpfully translates this into PBT guidance of £37.5m.
Next update will be on 17 January 2023.
My opinion - this is excellent news. CARD is still burdened by too much bank debt, so that makes the share price more geared to performance than for many other companies with stronger balance sheets. Hence out-performance is highly significant here.
I can't find any broker notes unfortunately, but looking at Stockopedia's consensus of £22.5m after tax, and assuming a 19% tax rate, that becomes PBT of £27.8m. Guidance is now £37.5m PBT, so a significant increase of about 35%. Apply that 35% to EPS forecast (consensus is shown on the StockReport at 6.22p), then I get 8.4p revised EPS estimate for FY 1/2023.
At 59p per share, I make this year's PER 7.0 - that looks attractive for a business that is performing well. Although if we take into account that net bank debt was almost £100m when last reported, which is about half the current market cap, then I would adjust the PER to a cash/debt neutral position of about 10. That's still good value, I reckon.
This is the first Christmas/New Year that hasn't had at least some pandemic/lockdown disruption since 2019, so maybe consumers are going to push the boat out, regardless of the cost of living squeeze? We've got full employment too (indeed labour shortages in some sectors). Wages in the private sector are rising below inflation, 2.7% below according to data on the news yesterday, but people can mitigate that - e.g. by reducing spending on electric/gas, helped by exceptionally mild weather. Same with food shopping - it's easy enough to eliminate inflation by product substitution. This raises the tantalising prospect that maybe Xmas/NY could be better than the doomsters have been predicting?
Or, it could be that as a value retailer, CARD is attracting business from elsewhere? We have seen other value for money retailers report that things are good, e.g. Shoe Zone (LON:SHOE) and B&M European Value Retail SA (LON:BME) recently. So it will be fascinating to see how things pan out.
As for CARD, I think this announcement is clearly good news, and despite debt still being too high, I think risk:reward has significantly improved. With positive trading, and guidance rising, the company should be able to gradually reduce its debt from cashflows, and I doubt the bank is likely to be breathing down its neck any more. Hence on balance, I'm happy to switch my previous caution over risk:reward to a thumbs up, because the facts have moved favourably, improving risk:reward. Well done to holders here, things seem to be moving in your direction.
Note from the chart below, that CARD has managed to get through the last 3 years without issuing fresh equity. Amazingly, considering how financially precarious it has looked at times during that period, so shareholders were more lucky than clever, I think! However, this means that in theory, the share price could recover back to pre-pandemic highs, if performance continues improving. It looks as if the guidance for FY 1/2023 is for profits of about half the pre-pandemic level, so there's some way to go still to return to where it was - e.g. EPS in the high teens in 2017 & 2018. If that happened, then the upside on the share price could be really good - maybe 100-200p possible in the medium term, who knows? The downside risk now looks contained, so risk:reward is quite nice here now, I reckon.

.
CARD also has a high StockRank -

Renold (LON:RNO)
23p (pre market open)
Market cap £52m
Renold (AIM: RNO), a leading international supplier of industrial chains and related power transmission products, announces its interim results for the six month period ended 30 September 2022.
Strong performance, strategic chain acquisition and significant increase in earnings
We like Renold here at the SCVR. It’s been a steady turnaround over several years, and it performed well during the pandemic - because its products are typically in demand irrespective of economic conditions, being replaced on planned maintenance schedules. As the market leader, and with a reputation for high quality, it is able to increase pricing & margins.
For more background, I interviewed the CEO here in Aug 2022.
A relatively large acquisition was made recently, which I reported on here in Aug 2022.
The large pension scheme is the only big negative I can see at Renold, and the company has successfully continued funding it (a cash drag of about £5m p.a.) without diluting shareholders.
Moving on to today’s announcement -
Interim Results
Headline numbers look impressive - although note the big jump in net debt, following a E20m acquisition - the amusingly named Industrias YUK, S.A. in Spain - performing ahead of expectations, and integrating well.

.
Adjustments - boost profit by £0.8m, which looks fine to me, as they’re all related to acquisitions, so are not underlying trading costs - it’s customary to adjust these out.
Pricing power/inflation - this bit is key, and clearly positive -
Price increases offset input cost and supply chain challenges
Order book at end Sept 2022 was healthy at £99m, a record high (LY: £72m)
Acquisitions - “Active pipeline of acquisition opportunities…”
Director comments - the CEO sounds upbeat -
Robert Purcell, Chief Executive of Renold plc, said:
"The strong trading momentum experienced in the second half of the last financial year has continued in the first half, with the Group continuing to successfully manage significant inflation and supply chain disruption, resulting in growing sales and record orders.
Whilst we are mindful that global markets continue to be uncertain, with ongoing labour and energy cost inflation and supply chain challenges, the Group's trading momentum continues to be positive. The Group has record order books and the acquisition of YUK provides opportunities for synergies and further growth."
Investor Presentation with Q&A - open to all - click here to register - starts at 17:30 today.
Pension deficit - the accounting deficit has dropped from £100.0m a year earlier, to £61.3m at end Sept 2022.
I think the best way to view this pension deficit is that it’s approximately £5m p.a. cash outflow. So the valuation of the shares needs to take this into account. Remember that pension scheme deficit recovery cashflows do not go through the P&L. Hence we need to reduce the PER, by an appropriate amount, when valuing the shares.
Dividends - none at the moment, although this is a policy decision, to focus on growth (e.g. acquisitions), rather than being strapped for cash. Sounds like divis should return at some point -
The dividend policy will remain under review as margin and cash flow performance continues to develop.
Going concern note - fine, no issues.
Balance sheet - NAV is £37.0m. This has risen strongly, due to a big reduction in the pension accounting deficit.
Intangibles have risen, due to the big acquisition. So taking off £40.3m intangible assets, gives NTAV of slightly negative £(3.3)m.
Inventories rose a lot, to £70.8m, now looking a bit too high, but that could be for reasonable reasons - lots of companies have increased inventories to ensure continuity of supply to customers. Higher inflation also means that working capital rises - 2 debits increase (inventories & receivables), whilst only 1 credit increases (trade payables), hence why periods of higher inflation will tend to suck in cashflow at many companies. That’s fine, the cash hasn’t disappeared, it’s just tied up temporarily in assets that turn into cash within a few months.
Broker update - many thanks to Finncap for an update note this morning.
Its forecast for FY 3/2023 is 4.5p adj EPS, which looks modest considering H1 has produced 2.7p, leaving only 1.8p to achieve in H2. I’ve checked back to pre-pandemic, and can’t see any obvious seasonal pattern, with H1:H2 revenues looking similar.
Therefore, it seems to me that current forecasts for FY 3/2023 look prudently set, hence the risk of a profit warning seems low. This is backed up by a record order book, and the repeating nature of a lot of Renold’s sales, so it has good visibility. Plus the proven ability to pass through increased costs.
My opinion - how to value Renold, is the tricky bit! Finncap has a target price of 50p, just over double the current price. This is based on a target PER of 10.9x, and EV/EBITDA of 6.4x, they add that this may require an improvement in market sentiment to achieve.
I’ll have a stab at valuation myself. I think 5.0p EPS is looking a more realistic target for this year. Given the increased net debt, and the £5m p.a. cash outflows into the pension scheme, then I’d be comfortable with a PER of about 8. Hence my personal price target would be 40p as things stand now, and maybe 50p (per Finncap) in an improved stock market/macro environment.
Hence the current price of c.24p seems to me an attractive entry point for patient investors. Hence a thumbs up from me.
The very high StockRank, for the last 2 years, encourages me too.

.
dotDigital (LON:DOTD)
85p (up 3%, at 10:11)
Market cap £254m
Dotdigital Group plc (AIM: DOTD), the leading 'SaaS' provider of an omnichannel marketing automation and customer engagement platform, announces its final audited results for the year ended 30 June 2022 ("FY22").
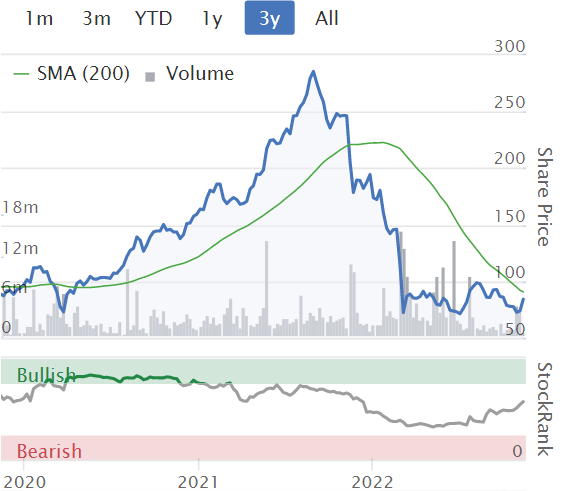
As you can see below, this share soared in the pandemic, and has since come all the way back down again. The same can be said of many other tech shares, which reached giddy over-valuations, and have since started to be valued like normal companies again.
.
Revenue growth - not bad at 8%, but as we’ve been flagging here for a long time, more than all the revenue growth is coming from charging existing customers more per month. Which surely means the underlying sales volumes must be dropping (i.e. more churn, than newly acquired customers)?

Is that a problem though? I’m not sure. You could argue that sticky customers have improving economics over time, more than offsetting churn, which could be seen as a positive.
Profit before tax (PBT) is £13.6m, up 6.2% on LY. This is on a statutory basis. The adjusted figures are a little higher (adj items are [modest] share based payments, and acquisition costs).
Adj diluted EPS is 4.18p (up 3% vs LY)
Valuation - at 85p, the PER is 20.3 - doesn’t seem excessive to me.
Acquisitions - seems to be an area of focus, let’s hope they spend the cash pile wisely. I worry that this might be an indication of limited organic growth prospects?
Current trading - sounds fine -
The positive trading momentum at the end of the period has continued into the new financial year. With the challenges from the first half of the year addressed together with favourable market drivers, the Group is tracking in line with expectations for revenue growth and profitability marginally ahead.
Balance sheet - NAV is £69.8m, which reduces to NTAV £42.4m if we deduct goodwill & intangibles. Software companies need very little capital, so I see the £43.9m cash pile being almost all surplus to requirements.
Cashflow statement - post-tax operating cashflow is £23.4m, but note that £7.6m of internal developments costs (i.e. payroll!) are capitalised onto the balance sheet. That’s fine, it’s allowed, but it’s big, at 12% of revenues. For this reason, EBITDA is a meaningless number, and should be ignored.
Note 14 also shows that the development costs capitalised of £7.6m, exceeds amortisation charge of £5.9m, flattering profit by £1.7m. It’s not a deal-breaker for me, but it’s worth being aware.
My opinion - the cash pile is 17% of the market cap (14.7p per share), and if we adjust out the cash, the share price would be just over 70p, and the PER would drop to about 16.7 - which sounds quite attractive to me, if growth can continue.
I’m only analysing the figures, I’m not making a more in-depth judgement on the company’s future prospects - that’s your job!
On the basis of these pretty solid numbers, and a valuation that looks reasonable to me, I’m going to give this a thumbs up. Risk:reward looks quite good, based on the information we currently have. Sticky customers spending more, tells me they must find the product useful. The challenge is now to accelerate acquisition of new customers, and make them sticky. That’s the bit that seems lacking currently.
Competitive challenges need to also be considered, which is beyond my pay grade. There must be loads of competing software products, and the main risk I see is if DOTD is overtaken by competitors, and withers away over time. I don’t have view on that side of things. The numbers though, look quite decent, and valuation seems reasonable.
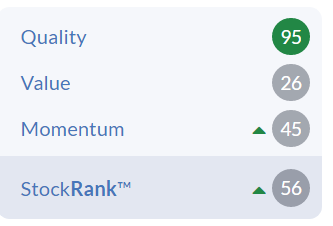
Stockopedia's algorithms are less enthusiastic, with a middling StockRank -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
I see Renold (LON:RNO) are issuing a Preference share dividend of 3p.
Who are these lucky people and is it normal for them to get a dividend when ordinary shareholders miss out.
RE: Renold (LON:RNO)
Who are these lucky people and is it normal for them to get a dividend when ordinary shareholders miss out.
Yes, that's why they're called preference shares. To be precise:
Preference shares, more commonly referred to as preferred stock, are shares of a company’s stock with dividends that are paid out to shareholders before common stock dividends are issued.
https://www.investopedia.com/t...
timarr
Just to add to what Tim has said, the prefs pay a set 6% pa. The company would be in default if it didn't pay.
I don't expect DotDig share price will go up until they issue an RNS which gives us reason to believe that Eps will start improving.
Helpful chart courtesy of Ed Conway at Sky on second hand car price inflation. Not good news for the likes of Vertu Motors (LON:VTU) and other car dealers so wonder if we might start to see profit warnings there?
This is old news as Vertu Motors have updated the market about 6-9 months ago that their profits will be about half of the year before.
Interesting interim results from Renold (LON:RNO) today. From a cash flow perspective they seem to follow some themes consistent with others:
Based on these cash flows alone, I’m not sure what the attraction is to prospective shareholders, unless you’re convinced that working capital investment has peaked and will unwind or that successful M&A will make it all better tomorrow.
Supply chain (Covid, geopolitics), energy costs and inflation have brought a covalency of unexpected challenges. But I also think these stresses highlight fragility in both the business and financial models of many companies.
Renold is not alone. Recent results e.g. Volex (LON:VLX), UP Global Sourcing Holdings (LON:UPGS) and Sigmaroc (LON:SRC), have shown otherwise “solid, well managed businesses”, in my view, to be in a similar category i.e. negative or only slightly positive free cash flow with debt levels rising, albeit partly to fund essential M&A to bring much needed growth.
This gives me two new concerns when trying to calculate the value of these businesses:
Is there more downside to come and, if so, is it worth holding your nose and sticking it out through a recession?
Enjoyed your weekly podcast AGAIN Paul. I have also enjoyed revisiting your interview with Robert Purcell this morning back in August. It will be interesting this evening to hear his comments on the fall in freight rates and whether they have become more predictable. Equally I am increasingly becoming concerned about the China situation and your recent comment on how reliant we are on them only increased my concerns. I am based in Cambridge which the Chinese have clearly identified as a place they want to be. But some of the Academics have in my opinion been naive about how they interact with well let's be honest not the Chinese but the Chinese Communist Party. The idea they would invest into sustainable cities along with our academics is all very nice but perhaps they are focussed on control and security which is at odds with our interests. China is also involved in building science parks etc here. Anyway I am rambling now so can only recommend people read Ian Williams "Every Breath you take". He is a respected knowledge on China, very interesting.
Anyone use services provided by Eenergy (LON:EAAS)? I would have thought their offering would be in good demand in the current climate, but SP says otherwise! Stockopedia doesn't rate them much on any metric.
Hi Paul
Excellent choice for your talk.
I , too , think the housebuilders are good value.
Let’s see what others think.
MJ GLEESON (LON:GLE)
I just had a look at the News tab for MJ GLEESON (LON:GLE) and yesterday’s item suggests that management are perhaps rewarding themselves over-generously …?
BRIEF-Proxy Advisory Firm PIRC Advises MJ Gleeson's Shareholders To Vote Against Resolution To Approve Remuneration Report At AGM
(Sorry - can’t reduce the font size on pasting in)
Hopefully Paul and others can consider this.
Ricardow
As a long-time holder, long suffering loser in MJ GLEESON (LON:GLE) I will carry on for longer but am aware that my vote will make no impression on the Board of Directors as anyone can see from the proportion of shares owned by the PI. Unfortunately for PI's this is a scenario shared by most listed companies.
Mmm interesting choice, Paul.
Until the mini budget and its consequences, I have been fully behind the MJ GLEESON (LON:GLE) story.....but the picture has changed considerably.
Mortgage rates shot up and wont come back down fast;
cost of living rising very fast (although varies according to every person/family situation, hitting the poorest most);
building costs rising and likely to continue after the support package on energy comes to an end in the spring;
wages rising faster in the private sector, but surely many prospective first time buyers will be workers in the public sector and they will be getting significantly less, even when they aren't on strike in the coming months!
So heart says get back into MJ GLEESON (LON:GLE), head says wait for a while. In the meantime, get rid of some anger and morally support the vote against the remuneration package of the bosses just for the hell of it!
ridavies, I listened, I have placed my vote.
Silver
£KMK £5m biological threat-detection contract award (new research note by Equity Development with audio summary: https://www.equitydevelopment.co.uk/research/5m-biological-threat-detection-contract-award)
Kromek Group has announced the award of a three-year UK Government department biological threat-detection programme contract worth £4.9m. Work on the contract is scheduled to commence in December 2022; the three-year term includes an option for extended maintenance-related services.
This is a significant contract and a clear ratification of the development work undertaken by Kromek, focused on the detection of biohazards which include the recent COVID-19 pandemic, but also extend to the development of systems capable of identifying and geo-locating other biological threats. In an environment currently absorbed by a variety of economic and geopolitical risks, the threat represented by natural or man-made biological agents has not diminished.
On the 10th November, Kromek added that it expects revenue growth of “approximately 45% for the six months to 31 October 2022. The latest, £5m, biohazard detection contract, adds to this momentum. Our FY23 outlook remains unchanged at £18.0m revenue, +49%YoY (E), EBITDA (adj.) of £0.3m, and a reduced EBIT loss of (£4.3m) vs FY22: (£5.5m). We also retain our Fair Value at 26p/share.
Re Kromek (LON:KMK) I understand all the wonderful new contracts that seemingly come up form time to time, and the great products they generate to deliver to an untold number of customers in a huge number of countries. How is it that they continue to make a loss over such a prolonged period of time.
They came on the Stocko scene around 9 years ago at an SP in the 60's. Since then it has been continuous decline; the average number of shares have increased between 2 and 3 times; the revenue has barely doubled, yet they appear to be in the forefront of significant elements of technological surveillance and protection.
Despite this new contract, deliveries starting in December so revenue for 3-4 months before the year end, the year end forecast from Equity Development is UNCHANGED. 'Running fast to stand still come to mind?'
The target price on Stocko, presumably from Equity Development is 233% vs current. Yes, 233%. For a company that has never made a profit, never paid a dividend from what I see over 9 years in the Stocko data.
What are they doing here on the market? Surely, they are uninvestible except for those who get enjoyment from self-flagellation on a huge scale?
Or am I missing something? Are they on the brink of something outstanding? Please help, especially the 9 people who have given the thumbs up to the preceding contribution/announcement.
re Kromek (LON:KMK), I have the impression this is a company run by a founder/scientist, who directs development spend more on the basis of what is interesting, than on the basis of the ROC that can be achieved. As a result, cash flow always runs behind capex. I have seen a few others like this in the past, the share price usually goes down until the institutional investors force someone with more commercial attitudes to be put in the driving seat. I don't think Kromek (LON:KMK) will be going anywhere until this happens here. I hold, which probably doesn't say much for my judgement.
Kromek (LON:KMK)
Fundamentally this business is far more valuable in someone else's hands than on the public market. We know this as its only competitors got taken out on significant premiums. The problem is that this type of IPR "value" obviously rarely gets recognised by investors unless there is a bid, and you don't invest for that potential alone. However, staying independent is actually good for business as most customers don't want to see Kromek (LON:KMK) in the hands of a competitor (particularly now they are the only independent).
The business should be cash profitable this year which is a step in the right direction but they need to make similar revenue growth next year to get meaningfully re-rated I think.
I do hold some but it's a tricky one.
Kromek is not going to be cash generative this financial year as it will need an extra £6m on capex. Also the company’s net debt will shoot to around £4m and it will certainly need another fundraise at some point. There are much much better investment opportunities around these days.
Great updates from Castings (LON:CGS) and Renold (LON:RNO) today, with Renold (LON:RNO) looking as though they will beat expectations H2 IMHO.
Castings (LON:CGS) claim to be passing all input costs on to the clients which is pleasing, along with an interim divi, X - 25/11.
I see them both having a solid lift, both on pretty low SP's but lets see what Mr Market thinks.
(I Hold Both)
Yes, an impressive update from Renold, considering the inflationary issues. A big reduction in pension liabilities too. I'd be grateful for Paul's thoughts on Renold. I was very impressed with how Robert Purcell came across in Paul's interview with him. He comes across as a safe pair of hands. I'm not surprised that the dividend has been put on hold, that seems sensible, also bearing in mind RNO received some 'forgiveness' in the USA. I am a happy holder.....
Finncap has upgraded FY23 forecasts for Renold (LON:RNO) to 4.5p meaning this trades around a p/e of 5 this morning. I don't expect a high p/e here because of the debt and pension but that seems far too pessimistic for a business that is trading well - am I missing something?
Renold (LON:RNO) Pleased to see a business I hold doing well, although you are far ahead of me Paul, I won't get chance to go over their figs until the weekend. In my opinion they've been quite a volatile share bouncing up and down between 20 and 30p this year (Five for a £, I love a share that's cheaper than buying carrots!) but this volatility works in your favour if you are a regular investor. The price only needs to go slightly over 40p and Renold will be a double bagger for me due to pound cost averaging; the share price will have less than doubled from today's price but the value of my holding will have.
I wanted also to offer some educated guesses in response to Patrick L about why the market looks to be discounting Renold's value. I think businesses that make "Actual things" as opposed to a service or better yet something that can be done via an app are terminally unfashionable. Renold has also evolved from a household name (There was a time when they were OEM chains for virtually all British bicycles and motorcycles and were the replacement chain of choice, stocked by places like Halfords), into an industry component who's continued existence generates a "Howard Hughes" reaction, friends are surprised that Renold lives and trades on the AIM and that I invested. Additionally very few people now work on assembly lines or in maintenance and so there is little comprehension of how much unseen work is done by chains, couplings and industrial clutches and by implication how important that market is.
#DOTD FY22 results overview video with CEO & new CFO. Strong results:
Video and podcast.
Separately, PIWORLD have a few events:
DSW Capital (LON:DSW) interim results webinar on Thursday 1st December, 1pm, when James Dow, CEO and Nicole Burstow, CFO will present results and take questions. Register here.
IG Design (LON:IGR) interim results webinar on Wednesday 30th November, 12 noon, when Stewart Gilliland, Interim Exec Chair, Paul Bal, CFO (to be CEO from 1 April 23) and Lance Burn, Interim COO will present results and take questions. Register here.
VSA Capital Aquis Stock Exchange showcase event. This is happening at the Royal College of Surgeons WC2. A full day event 9-7pm with free booze and food during the day and drinks in the evening. Lots to entertain. The main show is Britains got Aquis where 20 companies present and Fund Managers Andy Brough and Judith MacKenzie will judge their investment cases alongside Rich Ricci, Panmure Gordon and Jim Armitage, The Sunday Times. In addition, presentations by Sir Robin Saxby, founder of ARM, will discuss the future of tech, James Wood, Winterfloods on the dark art of Market Making and David Buik presenting the macro picture. Register here.
The VSA event is on Tuesday 29th November according to the link