Small Cap Value Report (Weds 17 April 2024) - ATG, SFR, ASC, LIO. Brief - TIDE, TST, SCE, AGFX, JET, IDS

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Wednesday 17 April 2024 - SCVR
Companies Reporting -
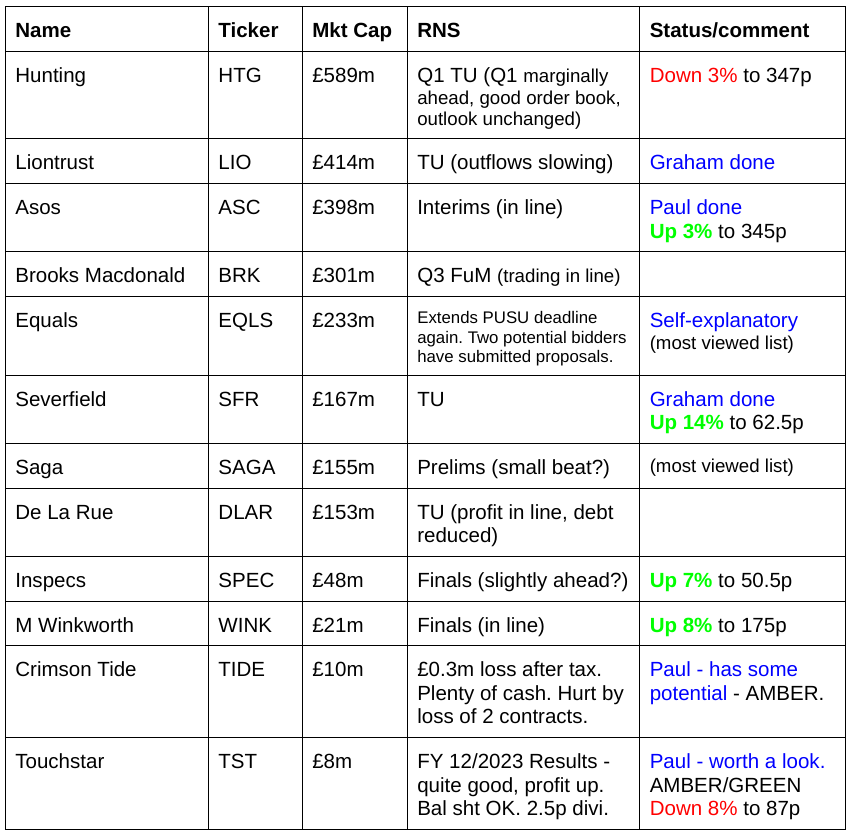
Other mid-morning movers (with news) -
Surface Transforms (LON:SCE) - down 17% to 3.25p - Reduced sales forecast - Paul - RED
Only a few days after reiterating its revenue target, a new (lower) range of possibilities is announced. It says this is in response to shareholders requesting worst case scenarios. I think giving a range rather than a precise figure makes a lot of sense, given the very considerable problems SCE is encountering in its struggle to scale up production to meet strong demand.
I’ll remain RED until it’s concluded the next fundraise, which is looking increasing and highly likely, unless it can pull a rabbit out of the hat, eg with some up-front cash from customers.
…projected FY 2024 range of £17.5m to £22m sales.
With the majority of the year still to come, 2024 sales outlook is dependent on the amount of progress made on reducing scrap, building capacity and delivering to customers.
Sales were constrained in Q1 due primarily to scrap and constrained manufacturing capacity. Significant progress has been made on reducing scrap and this is expected to continue through 2024. Similarly progress on expanding our capacity during 2024 is advancing.
Argentex (LON:AGFX) - down 7% to 49.3p
The only news today is influential & widely followed Harwood Capital reducing its stake from 5.06% to 4.42%. This might be perceived as meaning there’s a potential selling overhang for the rest of the Harwood stake, and that a key investor seems to be losing interest in the upside case. See our archive for the various problems that have beset AGFX.
Just Eat Takeaway.com NV (LON:JET) - down 6% to 1,120p (£2.3bn) - Q1 Update - Paul - AMBER/RED
Update seems to be in line, and it reiterates guidance for 2024. So I’m not sure why the price is down 6%, clearly the market wanted something better -
We reiterate our guidance including adjusted EBITDA of approximately €450 million and positive free cash flow1 before changes in working capital in 2024
Substantial share buybacks have been done -
Under the share buyback programmes announced in April and October 2023, 8.9% of the issued shares were repurchased as per 12 April 2024.
Weird balance sheet with huge cash pile, offset by huge debt pile. Heavily negative NTAV.
Free cashflow was still negative in 2023, despite improving from 2022.
Paul’s view - looks a can of worms to me, I won’t be touching JET.
International Distributions Services (LON:IDS) - shot up c.25% at 11:00, but is drifting down now, up c.15% at 12:12.
I can’t find any news, other than on Sky, “Post Office boss exonerated” - not sure if this is related to IDS or not? Please post a comment if you find anything to explain this!
EDIT: thanks to clanger, who has updated us with a reader comment below, saying the FT has reported a Czech billionaire is apparently considering a takeover bid for Royal Mail.
Summaries of main sections
Auction Technology (LON:ATG) - down 16% to 526p y’day (£640m) - H1 Trading Update - Paul - AMBER
We've previously quite liked this share, but it now looks largely ex-growth, and I dislike the weak & heavily indebted balance sheet. So I'm now lukewarm.
Severfield (LON:SFR) - up 14% to 61.6p (£191m) - Trading Statement - Graham - GREEN
Changing my stance on SFR to “GREEN” today after it “slightly” beats expectations, with a positive outlook for the new year, and simultaneously announces a £10m share buyback. I said previously I’d turn positive on the stock if that happened, so that’s what I’m doing.
ASOS (LON:ASC) - up 9% to 363p (£434m) - H1 Results (to 2/2024) - Paul - AMBER/RED
I do a demolition job on these lousy H1 numbers, and demonstrate why the turnaround plan, even if it succeeds, will result in a business making zero real world cashflow. Poor, overly indebted balance sheet too. It's a mess. However, with Frasers (LON:FRAS) controlling 27%, there could be some strategic value or deals here possibly? That's the only reason I'm not fully red.
Liontrust Asset Management (LON:LIO) - up 5% to 671p (£436m) - Trading Statement - Graham - GREEN
Retaining my positive stance on this one as the company reports more net outflows in Q4, albeit at a slower pace than previous quarters. While it’s not my favourite share in the sector, it does offer a generous yield and a cheap valuation against both earnings and AuM.
Paul’s Section:
Auction Technology (LON:ATG)
Down 16% to 526p y’day (£640m) - H1 Trading Update - Paul - AMBER
London, United Kingdom, 16 April 2024 - Auction Technology Group plc ("ATG", "the Company", "the Group") (LON: ATG), operator of world-leading marketplaces for curated online auctions, provides an update on its trading for the first half of FY24 (six-month period ending 31 March 2024).
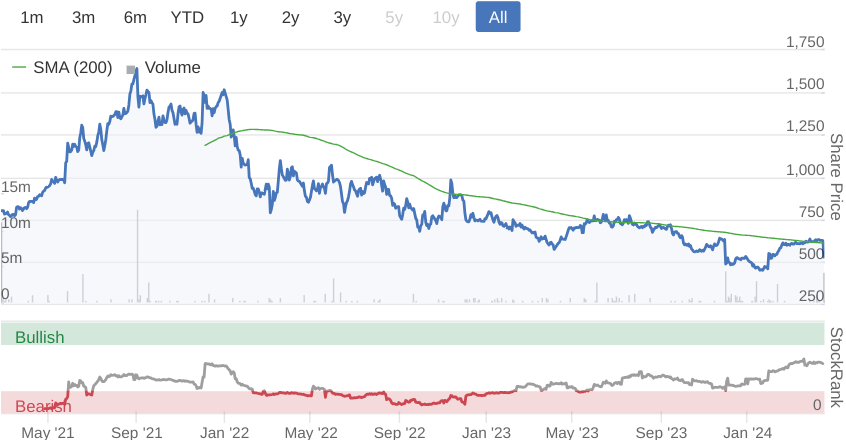
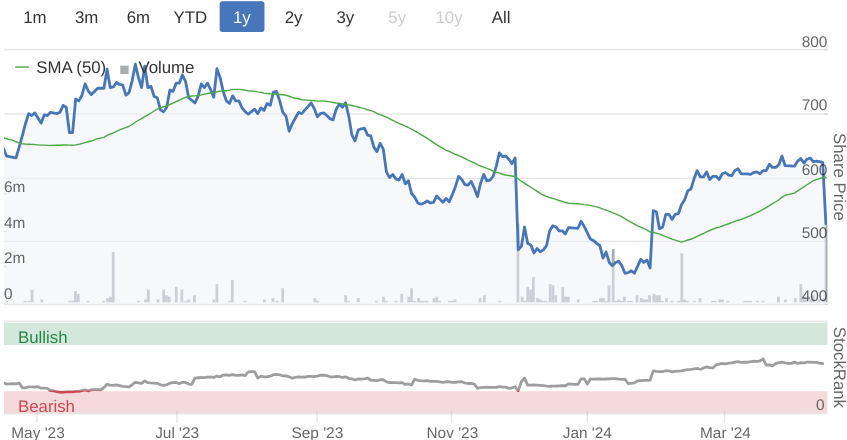
An interesting share, which dropped sharply yesterday. It floated in 2021 (yes, I know) and was initially well received, peaking at c.1,640p in Sept 2021, then sliding all the way down to c.450p by Jan 2024. A recent rally has been mostly snuffed out by yesterday’s fresh plunge. Is it a load of codswallop, or are we being offered a more attractive entry price?
Looking through our archive here, Roland saw it as amber on its 1/12/2023 profit warning, concluding that there might be some attractive qualities emerging after a drop to about 490p. Graham looked at it again on 31/1/2024, and boldly went green, after a 18% rise to 542p/share, after an encouraging trading update, although he concluded it was ”certainly not without risk”.
Here’s the chart since ATG listed on the LSE main market -
Zooming in, this is the last 12-months -
Latest news - this is an annoying update which gives piecemeal bits of information, but fails to pull it all together to tell us how the company is performing versus expectations. Who writes these things? The outlook below might help analysts, who can plug the numbers into their spreadsheet models, but to everyone else this is close to useless -
FY24 Outlook
We expect our full year Group revenue to be in the range of $175m-$180m implying a mid-point growth rate of 7%, including organic revenue growth of 2% - 5% and a strong contribution from ESN. Revenue growth in the second half of FY24 will be driven by the continued growth in value-added services, less challenging comparatives for the upcoming period, and encouraging trends seen from the roll out of cross-listing and ATG white label across the Group. The Group now expects its FY24 adjusted EBITDA margin to be 46% due to the mix of revenue with a higher contribution of lower margin value-added services relative to higher margin I&C commission revenue.
Broker update - good old Cavendish come to our rescue. It issues reduced forecasts, but they’re only trimmed really - FY 9/2024 adj diluted EPS is lowered 6.5% from 40.1 US cents, to 37.5c - hardly a disaster. Divide that by 1.25, and it’s 30 pence per share. So a PER of 17.5x - doesn’t sound expensive for a niche software company.
ATG did 32.6p adj EPS in 2023, and 29.5p in 2022, so this is looking ex-growth. Hence it possibly should be on a low PER?
Balance sheet - nothing said in this update, but looking back to 9/2023, I’m afraid it’s very poor. NAV of £530m includes intangible assets of £695m, so NTAV is heavily negative at £(165)m. Even if I eliminate the £41m deferred tax creditor, I still only get to £(124)m NTAV.
There was net debt of £116m at Sept 2023. I think that’s too high. Finance costs swallowed up most of the operating profit in H1 results.
Paul’s opinion - just on a quick review, I’m not enamoured with these figures. Growth seems to be stalling, and I’m worried that its big acquisitions spree might have resulted in it taking on too much debt. Maybe it overpaid for acquisitions, I don’t know?
So I can’t back up Graham’s previously bullish view, hence I’m shifting it down a gear to a neutral view of AMBER. We can always go back up a gear if the figures & outlook improve as time goes on.
Mind you, software companies often tend to attract big premiums from takeover approaches, and are more highly valued by private buyers than the UK stock market, so there could be upside here maybe?
EDIT: many thanks to one of our regulars here, grumpy5, who has left a comment below, saying that a competitor is gaining ground by undercutting ATG on price. Many thanks for this interesting industry info.
Also thanks to JamesKerr1 who below posts experiences of using ATG software, and the competitive landscape, which sounds challenging. More excellent insights, great stuff!
ASOS (LON:ASC)
Up 9% to 363p (£434m) - H1 Results (to 2/2024) - Paul - AMBER/RED
Interim results for the 26 weeks to 3 March 2024
The market cap of this eCommerce fashion giant rises by £36m this morning.
The numbers look pretty awful to me, eg -
H1 revenue down 18% to £1,498m
Adj (?) gross margin is also down, and very low at only 40.3%
EBITDA is a nonsense number, due to omitting large capitalised IT spend, hefty finance charges, and depreciation on its expensive warehouses.
Adj loss before tax is £(120)m vs LY H1 comparative of £(87)m.
Statutory loss before tax is even worse at £(270)m.
Note that this period includes the busiest season, autumn & Christmas, so it should be profitable, but is nowhere near profitable.
Its commentary follows the usual pattern of glossing over dismal results with talking up positives & turnaround potential.
Outlook -
AEBITDA for FY25 expected to be significantly higher than FY23 and FY24 driven by:
(1) materially higher gross margin following removal of old stock and higher full-price sales mix of flexible stock models; and
(2) ongoing transformation of the business following cost action already taken in FY23 and H1 FY24…
Our guidance for FY24 and FY25 remain unchanged and we are committed to accelerating towards an 8% EBITDA margin in the mid-term, enabling ASOS to be sustainably cash generative on an ongoing basis.
That sounds impressive, an aspiration to get EBITDA up to 8%. However, I’ve run a simple calculation to see what that 8% margin would turn into, in cash terms (assuming no working capital movements). I’ve replaced depreciation with actual H1 capex (most of which is internal capitalised IT development costs), and actual H1 finance charges. It looks like this -
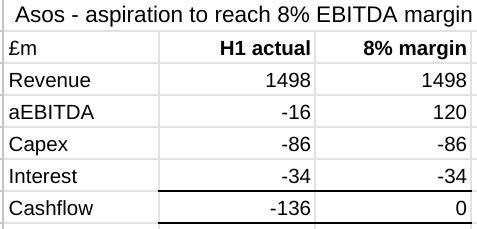
I’ve not fiddled the figures, the 8% EBITDA aspiration results in a big fat zero in cash profit the way I’ve defined it here (reflecting reality).
So the idea that Asos is going to become (or is) highly cash generative is complete hogwash!
Balance sheet - is weak. It has NAV of £620m, but that includes probably worthless intangible assets of £692m. So NTAV is negative £(72)m.
See note 15 for details on debt. It has large gross borrowings (excl leases) -
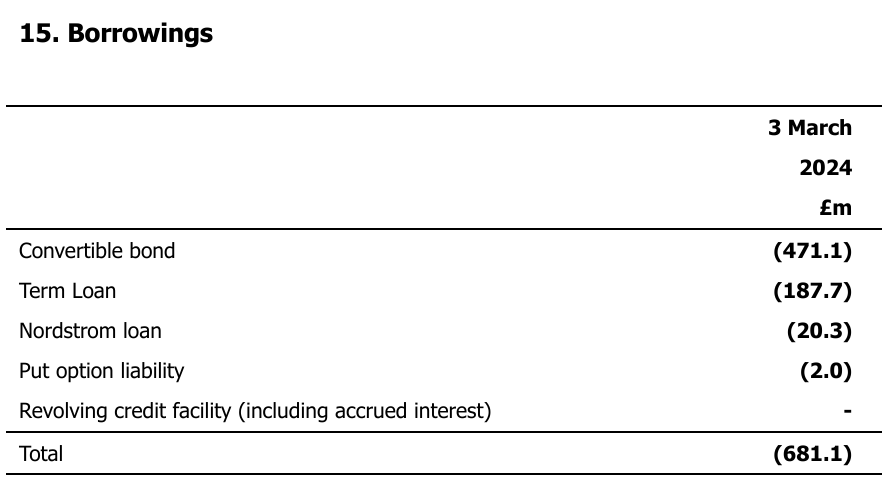
Given that Asos is not generating any sustainable cashflow (it relied on a one-off £176m reduction in inventories to report positive cashflow in H1, which obviously won’t repeat to that extent), then how is this debt above going to be repaid when it matures?
To be fair, there is £332m in cash, so almost half the debt, although year end snapshots usually present the most favourable view possible.
Paul’s opinion - on fundamentals, Asos looks in real trouble, and I could see it going bust in the medium term.
However, it also has turnaround potential, since the low 40% gross margin has lots of scope for improvement, and on £3bn revenues, that could be transformative. I think it would need new management first though, this has been a very badly run business for many years. This is possibly what Mike Ashley sees in Asos, and why he’s accumulated a 27.1% position (20% shares + 7% derivative). His approach (learned from Philip Green) seems to be buying struggling businesses (often out of administration), then applying brutal tactics to strip out cost, often involving hammering suppliers & landlords for discounts. But that didn’t work at Matches, and this approach can sow the seeds for future business failure, as relationships with important suppliers, brands, and key staff are trashed (eg. BHS, TopShop).
I wouldn’t touch Asos shares as a standalone business, because the numbers (and outlook) are so poor. However, there might be a trade in here for some kind of takeover deal perhaps?
We haven’t even touched on the Chinese (Shein, Temu, etc) battering this sector by deeply undercutting on price. Sure Asos sells third party brands, but that’s low margin business, and with handling costs, returns, etc, leaves no scope to make any profit.
On balance I’ll stick with my previous 2 reviews with AMBER/RED - lousy business, but might have strategic value to an acquirer.
Dave Murray is appointed new CFO. He’s got his work cut out, that’s for sure.
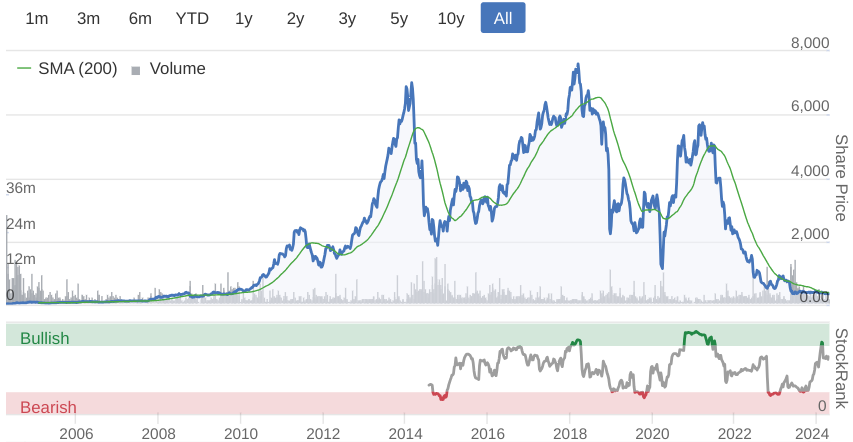
Almost a round-trip now! So I'm not feeling quite so bad about selling my 0.5m Asos shares at 9p many years ago, because they looked over-valued (I'd bought them at 5p) -
Graham’s Section:
Severfield (LON:SFR)
Up 14% to 61.6p (£191m) - Trading Statement - Graham - GREEN
This is a good news update:
Severfield plc, the market leading structural steel group, today issues the following trading update for the year ended 30 March 2024…
The FY 2024 result is “slightly” ahead of previous expectations.
Net debt, excluding leases, finished the year at £10m, also ahead of expectations.
Checking the recently published note from Progressive, their net debt estimate for FY 2024 was nearly £29m. So the company has beaten that by a very wide margin.
Reasons for the excellent net debt result include “an improvement in underlying working capital and an increase in advance payments” - I would cautiously assume that these factors could reverse, i.e. that the net debt improvement isn’t likely to be permanent. Working capital ebbs and flows!
Operational update
Some key bullet points:
Good growth in UK order book in H2 (to £511m), of which nearly £400m is due for delivery in the next 12 months. (GN note: this gives visibility over most of SFR’s forecast revenues for FY March 2025; £561m according to Progressive.)
Indian JV: order book has reduced but company still very positive on outlook and pipeline of opportunities. Profitability expected to improve.
Share buyback
Severfield already pays a decent yield (and the dividend is forecast to continue to grow).
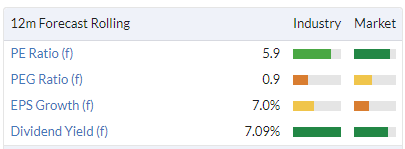
But it can afford to do even more for shareholders, as it announces a £10m buyback.
At the current market cap, that would give a meaningful reduction in the share count of c. 5% of total shares.
The company is keen to emphasise that its growth strategy is unchanged and that the buyback is possible thanks to “the highly cash generative nature of the business”.
Outlook
The Group is performing well, the outlook is positive and our businesses are well-positioned in markets with excellent long-term growth opportunities. Whilst there remains some uncertainty in the wider economy, we are seeing an improvement in market conditions which, together with our high-quality order books, diversified activities and operational delivery capabilities, provides us with confidence for the year ahead.
Graham’s view
Paul and I both expressed our views on this one in November. We each thought that the shares were cheap for good reasons, i.e. that a low-margin, highly cyclical structural steel group should trade at a cheap earnings multiple.
Quoting myself is usually a bad idea, but this is what I said at the time:
I think I would have to accept that this share was offering deep value if:
PER was 5x or less, or:
Dividend yield was higher than the PER (ideally >10%) and was covered by earnings, or:
The company was materially reducing its share count with a buyback.
Have any of these conditions been met?
PER: based on the latest Progressive forecast for FY March 2025 adj. EPS (9.3p), the adjusted PE Ratio is 6.6x.
The forecast dividend yield is currently about 6%, which is not higher than the PER. But it’s close, if you’re willing to use the adjusted PER of 6.6x!
Buybacks: Yes, the company is materially reducing its share count. A c. 5% reduction in the share count isn’t huge but it is meaningful and material in my book. And who knows, perhaps it can pave the way for further buybacks in due course?
Therefore, I’m going to stick to what I said previously and turn positive on this share now. It’s unlikely to ever be a high-quality compounder (the long-term share price chart backs me up on this), but it might simply be too cheap at this level, especially since the number of shares is about to start reducing.
Liontrust Asset Management (LON:LIO)
Up 5% to 671p (£436m) - Trading Statement - Graham - GREEN
Liontrust Asset Management Plc… the specialist independent fund management group, today issues its trading update for both the financial year ended 31 March 2024… and the three months ended 31 March 2024.
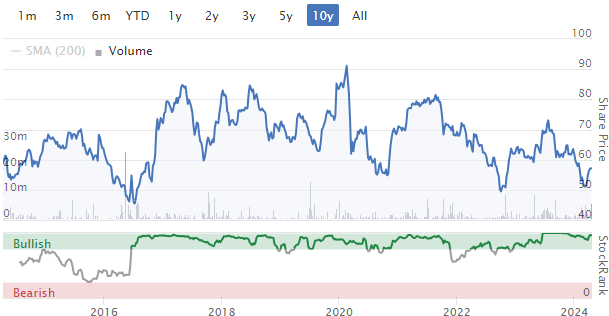
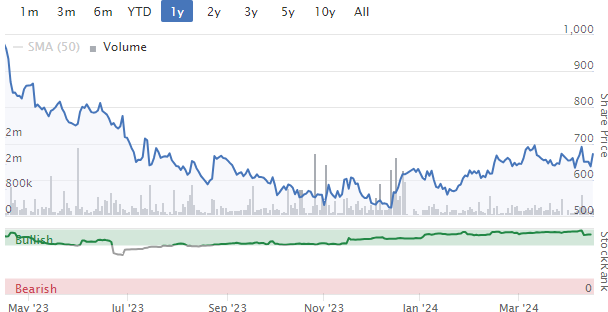
LIO’s share price has fallen and recovered since we covered last in August:
Today’s trading statement confirms that, unfortunately, the company has seen a decline in AuM (or what the company calls “assets under management and advice”) by 11.5% during the financial year to March 2024.
AuM finished the financial year at £27.8 billion.
Net outflows have been enormous, and far too big for investment returns to offset:
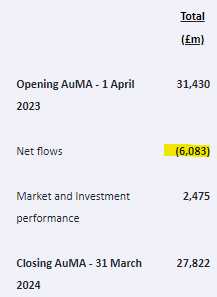
In my experience, it’s highly unusual to see c. 20% of starting AuM get withdrawn in a single year.
The main category of funds, “UK Retail Funds and MPS” performed less badly than the group as a whole, with about 15.5% of starting AuM withdrawn.
With £27.6 billion of AuM (or to be more precise, “AuMA”) as of mid-April, investors get £63 of AuM for every £1 invested in LIO stock at the current share price.
CEO comment
"We start the new financial year with confidence to drive the business forward after the challenges of the last 18 months.
Liontrust has improving investment performance in the short term as well as excellent performance over the long term and it appears the UK and other developed economies have reached peak interest rates. This follows a period in which many of our core investment strategies, notably quality growth, small/mid-caps and UK equities, have been out of favour, impacting both performance and flows. This led to outflows of £1.2 billion over the three months to 31 March 2024.
We have made continued progress against our strategic objectives, enabling us to seek to generate growth through an expanding product range, distribution and client base.
The outlook statement doesn’t give too much away; it reiterates that Liontrust wants to build its reputation abroad and broaden its investment capabilities.
Personnel changes: there are some NED changes on the Board. The executive team also sees new appointments including Chief Strategy Officer and COO.
Graham’s view
It has been a while since I updated my view on this one. While I agree with the CEO re: the outlook for interest rates, net flows continue to concern me.
The profile of outflows in FY 2024 was as follows:
H1: outflows of £3.2 billion
Q3: outflows of £1.7 billion
Q4: outflows of £1.2 billion
It can be argued that this is an improving trend, but it’s still deeply in the red and therefore it’s too early, in my view, to argue that the company has turned a corner. Others may be more optimistic, but I’d wait until flows were much closer to breakeven before getting out the champagne.
That said, I’m inclined to keep my positive stance on these shares as we have the classic “dividend yield higher than PE Ratio” situation:
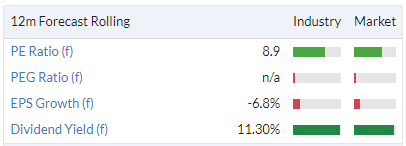
The dividend is barely covered by earnings and therefore should be considered vulnerable, but the cheapness is still readily apparent.
As before, I should reiterate that this is not my top pick in the fund management sector. Liontrust tried and failed to take over rival fund manager GAM, while other acquisitions it did get through have subsequently been impaired. I also believe that Liontrust is less differentiated than its peers when it comes to its investment specialisms.
This is arguably reflected in a cheap valuation and I do think that LIO shares are underpriced, but personally I’d invest in other fund management companies before investing in this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
edit: wrong thread
VLX ahead of expectations. VLX is usually covered on here.
Sorry, reading the wrong day.
It looks to me like it's best to be in cash until you're absolutely sure the next UK bull market has begun
Sadly ' no one rings the bell at the bottom ' , but the FTSE 250 appears to be forming a bowl on a 3 year basis and is above the 200 day m.a.
If you're really brave even AIM seems to be attempting a break out technically...
I'm starting to feel more confident on days like today ( inflation disappointment ), when we're not selling off....
Johhnycomelately
Surely we can never be sure that the next bull market has begun? There’s always the risk of new big shock bad news not already priced in by markets to send markets in to heavy falls.
Rather than stay in cash I much prefer buying when many shares are at bargain prices and top slicing or selling after big gains. Isn’t buying when a lot of bad news looks priced in, as is the case now, less risky because a highly rated share falls more heavily on bad news than a share bought when a lot of bad news looks priced in.
International Distributions Services (LON:IDS)
"The Board of IDS (the "Board") confirms that on 9 April 2024 it received a preliminary and conditional non-binding proposal from EP Group regarding a possible cash offer for the entire issued and to be issued share capital of IDS not already owned by EP Group and its affiliates, namely VESA Equity Investment S.à r.l ("VESA Equity") at 320 pence per share (the "Possible Offer"). VESA Equity is an approximately 27.5% shareholder in IDS.
The Board, together with its advisers, carefully considered the Possible Offer and concluded it significantly undervalues IDS and its future prospects. Accordingly, the Board unanimously rejected the proposal on 11 April 2024.
The Board believes the timing of the proposal is opportunistic. It does not reflect the growth potential and prospects of the Company under a new management team, a significant modernisation programme underway at Royal Mail, and the ongoing review by Ofcom in relation to the Future of the Universal Service Obligation."
Sky news are suggesting there’s another offering being considered, if they rejected £3.20 suspect the other offer they are considering is a step in from £3.20 suspect more news to come soon.
Interesting FT article on small caps performance although US focused. Also not sure if behind paywall for non subscribers but here is the link:
https://www.ft.com/content/abf...
Titon
Rockwood increase to 28%
Big spread at the moment .
The ex chairman / kingmaker Keith Ritchie and wife who Rockwood ousted is clearly selling down and Harwood increasing on back of this .
Pretty wide spread at the moment buy 77p sell 71p
This will take a long time to turnaround .
Key is to for me (and I m pretty certain Richard Staveley agrees) is jettison the Korean division ASAP.
It’s a 3 year turnaround at least but valuation is pretty low now at 8 million and real estate underpins most of that so hard to see too much downside .
Also noticed Rockwood sold a chunk of Argentex share price falls 10% transfer of funds? or more issues with Argentex
STV (LON:STVG)
Price 239
Market cap £109m
It’s always a strong buy when you come up with a growth stock trading as an income stock. Perhaps this is because of the liquidity issues facing the UK market in general.
Estimated revenues to climb to £240m in 2026 from the current £168m. Current dividend yield is over 5% and it goes ex dividend (7.4p) tomorrow
Studios and digital are showing a massive growth and they will be contributing about £30m inn2026. Current profits are £20m for the whole group.
Netflix , Apple TV+ , Sky , ITV and recently Warners Brothers Discovery are amongst their customers.
Very strong free cash flows expected over the next years averaging at least £15m pa.
All the best
STV (LON:STVG) Interesting Yiannos1 thanks. It still has a negative book value per share and significant debt. I wonder why they are paying a dividend rather than reducing the debt?
STV (LON:STVG)
The reason is that they have made an acquisition recently and current debt is easily being serviced. I wouldn’t say that the debt is significant though.
STV (LON:STVG)
It’s always a strong buy when you come up with a growth stock trading as an income stock.
I agree on the cashflows but do you realistically see this on a mid teens p/e? That said, I see 50% upside within 12 months conceivable, 24 months probable. What about you?
BnB
This is exactly what I see about 50% within 12 months , maybe if growth accelerates even more it can reach the £200m market cap. STV (LON:STVG) is a takeover target candidate as well.
Unfortunately the UK market and the continuing outflows is wrongly pricing these stocks. May be fortunately as opportunities emerge!
All the best
Paul and Graham thanks for your efforts covering so many stocks especially last few days which have been very busy
Hi Paul - Just to say, I've recently found your podcasts and find them very useful and also entertaining (much more so than many other market commentary podcasts!) Keep em coming!
That's kind, thank you Joe! Much appreciated.
Yes and appreciated you choose give up some of your weekend time to create these
Serabi Gold (LON:SRB) Hi Paul and Graham. Any chance of casting an eye over today’s update from Serabi, increased output by 12% compared with same period last year? I’m a little embarrassed to ask and add to your already exhausting workload but if you did have time at some stage that would be amazing. Thanks. Dave
Does Paul cover mining stocks?
They don't normally look at Resources stocks. Serabi Gold (LON:SRB) is on the mend after a chequered period of under delivery during a slow gold market backdrop. I used to own it because I thought they were fairly straight forward and have decent grade Gold although it's fairly hard to mine. They also appeared to have a growth story and at the time had a production target of 100,000 ounces of annual gold production. They acquired an ore sorter that should push short term production north of 50,000.
They are very geared to Gold prices ....so now these are rising, the shares are gaining favour. I travelled through a torturous process of renewing the Corrringa licence and at one point, lots of rumours they would lose it..... and I eventually had enough and sold. In January this year they actually won the license ... so that is a tick in the box and helped push the shares better.
They have net cash which is good and decent mine prospects. The production targets they were continually missing for a few years but they are sufficiently low to hit now ... at 38 - 40,000..... however, despite all the investment they have really struggled to get beyond this. This is a common story in the sector.... but if it's Gold exposure you want then Id argue that the big players like Newmont are also out of favour .... but don't tend to have all this gossip surrounding them. This is the main problem with small mining stocks whose operation is in South America.
I looked at the statement today and all is on track now ... so tick in the box... and gold price means cashflow will be good .... but I am out of touch with their Capex needs and whether they need to raise soon or not. I suspect not since net cash looks quite high.
Its not the managements fault that all the bulletin boards are full of chat on stocks like this but it is fairly exhausting as an investor... so im hiding in Fresnillo (LON:FRES) for now ....which probably has less upside in a hot market ...
Serabi Gold (LON:SRB) Really helpful thanks so much RDHowarth! I was also contemplating Fresnillo (LON:FRES) as it has been down on its knees, and silver is rising, but even so it seems relatively expensive with modest expected EPS relative to the 600p price. I don’t really see the attraction of it, other than its size?
tbh I am far from the most successful resources investor but in my humble experience valuation in a traditional sense makes little sense since often after very strong runs in underlying commodities these stocks end up being very cheap when you should sell them....so it goes without saying you need a healthy underlying commodity price backdrop. Asset life, Capex and future extensions/acquisitions all play a role in the production profile but virtually every company misses production targets. So it then boils down to the quality of the assets which of course favours the lager cos who tend to have lower production cost and more diverse assets ...normally. The silver to gold ratio ebbs and flows....with leads and lags... I would say copper is important to silver in way not gold...and I like the industrial angle. Silver lagged gold for some time but is now catching up as copper runs. There isn't a decent gold play at the moment since Endeavour Mining (LON:EDV) became embroiled in a CEO scandal. Silver is about middle in its range relative to gold but the operational gearing if price strength continues is huge.... and copper strength looks good. My timing in these things has been dreadful but ive averaged down and they are now coming back into fashion....all the miners have lagged the commodities so far. SPDR Gold Shares (PCQ:GLD) looks bit toppy to me on a short term view.....
I can't add a great insight on Fresnillo (LON:FRES) other than try and time it right or be willing to be patient. And don't over commit if you are unsure.
Best of luck.
International Distributions Services (LON:IDS) just reported in the FT. Stock up 18 percent currently.
Czech billionaire Daniel Křetínský is preparing a takeover bid for Royal Mail owner International Distributions Services, according to people familiar with the matter.
Equals .
Have to say the management would make great parents as they are so patient.
Very interesting strategy actually and maybe they have some fiduciary duty to shareholders not to be more vocal to a potential buyer.
I had quite a few bid approaches not at this level and after the first couple where we spent inordinate management time jumping through hoops of potential private equity / trade buyers I suddenly realised that devoting management time to potential buyers was a fools errand as they inevitably employed “advisors” who knew nothing about the business and you ended up running a business based on what you thought a buyer wanted to see .
This happened twice then after that I didn’t let that happen and we stuck to our plan and delivered our numbers to budget and refused to engage in lengthy due dilligence with a window shopper .
The good news with Equals is they are on plan and hitting their numbers so looks like they have no distraction factor .
I once had a very well known VC send up his right hand man for a factory tour , I was there with my Grant Thornton advisor and this had been dragging on so my wafer thin attention span was already breached .
He then proceeded to ask me a reallly silly question at which point I cracked with “Where do you do your due dilligence the f,,,in dog and duck can you please just F off and if your boss wants to buy part of my company tell him to come up himself”. I then kicked him out of the building much to my grant Thornton advisors disgust
“I wish you hadn’t done that “
Of course there is only one true negotiating tactic that is “the ability. Willingness (and stupidity” to walk away “
Anyway - of course the funny thing was I had an offer by the end of the week .
I didn’t accept it because having that type of investor would have driven me nuts and I would have driven them nuts.
Equals (LON:EQLS) - nice anecdote Planetx. I’ve been involved in a not dissimilar situation and you’re right that the trick for management is not to allow bid approaches to absorb so much time you take your eye off the ball of running the actual business. The willingness to walk away always grabs attention and accelerates the process. You do have to use it carefully though so as not to be seen as crying wolf.
I’m pleased to see that Equals (LON:EQLS) management don’t appear to be doing this and are growing as planned. I was also interested that not only are they talking to the two potential bidders but both have made indicative offers. That means we are now in a competitive bidding situation so hopefully that will drive the best offer price. If not then no problem for me - I’m happy for them to be independent but I’m happy to take a good offer too. I would be unhappy to see a low ball bid accepted that isn’t a significant premium over the current price.
Auction Technology (LON:ATG) Citywire press review for today quotes the Times
"An attempt to simplify its business model has forced ATG to cut forecasts for its full year profit margin and to temper its expectations for organic revenue growth"
Science (LON:SAG)
Lets be frank this is a quite horrendous update here - they are trumpeting increased profits compared to low prior year level and at the same time wiping out those profits and soem with real "exceptional costs".
Note execptional costs also too them into loss last year too.
Note i am completing ignoring goodwil w/off here thats an item i am happy to agree can be ignored.
So the reality is after what they themselves say is excellent 12 months for cruising they have managed to lose money for shareholders for yet another year.
One can take the positive that ignoring these exceptional costs theya re making decent progress IF you ignore the insurance woes too - so on some people may be happy with this update though - in the real world they have clearly lost money this year.
Then onto the elephant in the room and debt levels - some here particualrly our esteemed landlord have wrongly said the debt and solvency is not and will not be an issue - hopefully anyone who has previously said that can now concede that their viewpoint was probably over optimistic as the company themselves have now realised themselves they dont have a plan here to cope with solvency as things stand - strewth they must be a bit slow on the uptake here imho. Remember the company is already existing on then largesse of generous support from one of their main shareholders.
Under all scenarios modelled, the Directors have identified a need for additional mitigating action beyond the scope of normal trading to manage the solvency of the Group at key pressure points over the five-year period. These points include the maturity of the £85.0m loan facility with Roger De Haan in April 2026, and the maturity of the Group's £250.0m unsecured bond in July 2026. A range of options are currently being explored, including potential partnership arrangements, which would release capital and enable the Group to restructure its debt; new liquidity facilities; and an evaluation of corporate refinancing.
Its pretty obvious that their wanting to explore partnerships is not coming from position of strength and they and other commentators cannot hide that fact now they are admitting thne issue.
Note i thought they might scrape solvency wise - so i can see why Paul had taken viewpoint that it probably wouldnt be a problem before - but if you "operating profits" are continually wiped out by exceptional costs its pretty clear where the trend will lie.
I dont mind Paul havinga differing opinion on the debt issue here but he tried to call me out numerous times here saying i was wrong when i wasnt - i always conceded they may be fine but imho to suggest there was no issue was giving false impression to less experienced investors that there may be some downside protection on shareprice when the reality is there is nil.
They may come back strong here if they can turn insurance and underwriting around - cruising is plainly doing ok and they may be able to find partnership that is capital light so i am not saying this is a dead duck - just extremley risky investment for those whose priority is not to lose capital.
SAGA not SAG ??
Had me worried there for a while although I do hold both.
I think you meant Saga (LON:SAGA) not Science (LON:SAG)
I think you meant Saga (LON:SAGA) not Science (LON:SAG)
yes apologies for confusion all !!
Hi rmillaree,
I think you meant Saga (LON:SAGA) not Science (LON:SAG)
yes apologies for confusion all !!
Never mind, these things happen! Just a quick reminder that all reader comments can be edited in the first hour after posting using the fat pencil symbol. So I always double-check all my comments for typos, then edit immediately if I spot anything untoward.
yes thanks Paul normally i do just been a bit busy this morning so missed that one to edit
SAGA ( LON:SAGA)
Someone recently on here referenced the 2026 bonds trading circa 90
Where can one track how they are priced please ?
Saga (LON:SAGA) Frankfurt Bourse - 21/26 Bonds trade at 88/92 (bid/offer) suggest no bond market distress. Yield suggests cost of debt circa 10% p/a
Saga (LON:SAGA)
Saga (LON:SAGA) Frankfurt Bourse - 21/26 Bonds trade at 88/92 (bid/offer) suggest no bond market distress. Yield suggests cost of debt circa 10% p/a
The whole point here is that shareholders are normally screwed over to ensure bond holders do not lose out (if someone is going to lose out) . The danger here is that is exactly what may happen - shareholders may be forced into huge dilution so that bondholders and bailed out. So the lack of distress on bonds imho doesnt mean that shareholders should be thinking they are in the clear - i cannot fathom how anyone cannot see the obvious risk now here based on the text today - remember they are already in receipt of generous loan from Roger - seems reasonably clear cut we should presume this support may not last past april 2026. Note the issue here was always imho the 2026 bond - the fact they have good funds to pay earlier bond back doesnt alter the fact 2026 was always more sketchy.
Under all scenarios modelled, the Directors have identified a need for additional mitigating action beyond the scope of normal trading to manage the solvency of the Group at key pressure points over the five-year period. These points include the maturity of the £85.0m loan facility with Roger De Haan in April 2026, and the maturity of the Group's £250.0m unsecured bond in July 2026.
You seem quite angry about this rmillaree
I’m just pointing out that the bond market appears to be relaxed and where you can find the bond prices as requested by someone. Remember the scenarios they talk about are 2 years out - they are saying that they don’t expect enough operating cash generation over 2 years to redeem the bonds and Roger loan in full without some refinancing. They are obligated to put this in but that was always completely obvious. It’s no different to any company that has a fixed term bond. If the bond market is open then I’d imagine they will most likely try and refinance the bond before it matures through the issuance of a new bond. Bond issuance will look at the annualised net cash flow position to price that and the company may or may not be prepared to accept it. Saga (LON:SAGA) are also highlighting the option to sell and leaseback the ships as a potential way of not having to do this. Frankly that’s probably their preference as it would make them capital light but with some reduction to profitability on the ocean cruise. The window for this refinancing discussion is the next 12 months and they are flagging that they are looking at a variety of options.
That said I was unimpressed with the trading update as I was hoping insurance would be starting to turnaround and be less of a drag, but that appears to be at least a year away so I’m glad I didn’t add ahead of it and waited personally.
Saga (LON:SAGA)
You seem quite angry about this rmillaree
Not in the slightest - i am just pointing out to people that the lack of distress on the bonds does not mean that there could be or should be lack of distress danger for shareholders. This is a vital point here - imho and i am happy to be slightly over zealous in my reiteration of this fact if it avoids the impression that everything is hunky dory with regard to this particular ship ! Hopefully the board can navigate to safer waters without undue dilution - but the unecrtainty here is clearly out in then open now - its pretty obvious what normally hapens in such situations where their is uncertainty over funding - serious money tends to come in and target the shareprice often - or there can be material mismatch betwen people wanting to add and sell - the more the price goes down the more current holders are likely to be screwed if rights issue is needed.
Frankly that’s probably their preference as it would make them capital light but with some reduction to profitability on the ocean cruise. The window for this refinancing discussion is the next 12 months and they are flagging that they are looking at a variety of options.
imho its very late in the day to be flagging up issues with regard to £250 million bond due in 27 months - should they not have had plan in place prior to now ? clearly the best time to have got this sorted was before you needed to go to the market to tell them that you have an issue that will affecrt solvency - clearly they are not in good negotiating position with other parties if the other parties know Saga must geta deal done or go cap in hand to shareholders.
My opinion is just that if they can quickly turn insurance around (other companies seem to be doing ok) perhaps the current negative vibes might leave the scene.
So Insurance continues to be a drag for Saga (LON:SAGA.
Their 3 year fixed price policies are great for customers so we’ve got them for House and Contents and also for car insurance.
Another reason I go for Saga Insurance is their excellent claims payout record. They pay between 80% and 90% of claims. So again that’s good for customers but not for shareholders!
Their 3 year fixed policies started before inflation and insurance premiums went up a lot. So customers are locked in to bargain priced deals. No doubt they will price future 3 year deals more realistically and anyway it was Putin’s invasion of Ukraine that sent inflation soaring; something Saga Management couldn’t have foreseen. Nor could they have foreseen the big increase in car repair costs.
Partly thanks to Paul’s updates then, I got a 100% profit from Saga a while ago, but have not been tempted to buy since, and there’s nothing in their Results today (unless I’ve missed it!) to change that.
Saga (LON:SAGA)
its probably not the worst thing in the world clients being locked into those 3 year deals - lets hope expectations are grounded in reality when they lexit that deal - sometimes keeping happy customer with less admin hassles of many peeps swapping can semi compensate for short term pain - they should have some have some nice tailwinds here in that regard in next 18 months ? - even with tailwinds here they still seem to mange to be stuck in reverse gear though.
Another reason I go for Saga Insurance is their excellent claims payout record. They pay between 80% and 90% of claims. So again that’s good for customers but not for shareholders!
I have a friend in the insurance industry that tells me I should ignore those types of payout ratios that are advertised. Apparently most insurers do actually try to settle something so they can claim the high pay out ratio (often as high as 98% of customers paid out). What is more important to customers is how often they are loss adjusting the claims, and using complex and lengthy terms and conditions to avoid full payouts. Not an area I know a lot about but if correct then these numbers have little relevance as an investor or customer. The important questions would be around how much they loss adjust and how transparent they are around their terms and conditions.
For some reason every time Saga (LON:SAGA) is mentioned or makes an announcement it attracts an extraordinary amount of comment and analysis on this board.
I don’t get it. I see that it is supposed to be a turnaround, but the complexities of its various interests, the torment of its accounts and the regular and repeated failure (for one reason or another) to find a path to stable profitability, should suggest that after years of worse than average performance there is, somewhere, a huge pot of jam tomorrow (or some time). To me this seems unlikely, making the whole exercise futile. Am I wrong to to take the view that “there must be more manageable and profitable risks than this”.
Saga (LON:SAGA)
the thing is there has been some great upside potential here - look at the upside returns of McBride which shows what can happen when the ship is righted and newsflow turns positive. My comments are not necessarily saying Saga is the worst kind of investment - i have for the last couple of years though thought they had very little wriggle room for things not to go as planned and that if that was the case the downside protection was next to zilch. Fine for experienced investors used to binary type bets or for peeps who can closely monitor and exit if needs be - i have been continually posting here more as warning to the less experiened and pushback agains those that were saying saga had no debt financing issues though imho that was too glass full approach dismissing the 2026 bond elephant - hopefully in that regard at least its all out in the open now. For those that are not interested easy enough to move onto the next one - as an aside i do find it quite interesting how these deep debt/possible value ones pan out as its useful info for other similar investements too see how often they bounce back - i think all people positive previously on this share would probably agree its not really panned out as well as we would have hoped as the insurance profits have vanished at the same time the travel has come back as expected so the logical expectation of bumper profits has not been delivered - dont think many saw that coming. Either way no one can get them all right all of the time. Shares that could just as easily be 400p or 25p in 2 years i think will naturally generate suitably robust discussions.
I agree about there being “more manageable and profitable risks than Saga (LON:SAGA) Aislabie. Also with so many stonking bargains available at present among small and big Companies and Investment Trusts, why go for riskier choices like SAGA. Those bargains include shares where the dividend yield is higher than the PE ratio (e.g Phoenix group (LON:PHNX) PE 8.7 and 11.32% dividend Liontrust Asset Management (LON:LIO) PE8.9 and 11.5% dividend (if held) and M&G (LON:MNG) PE8 and 10.37% dividend.
For small companies is there a case for only checking out those with a “green” rating from Paul or Graham?
I sold Saga (LON:SAGA) a good while ago but can’t resist keeping an eye on shares I used to hold, both winners and losers, instead of just moving on.
One of the best performing small caps, over the last 2 years, was rated amber/red by Paul. It has gone up over 8x. Ed likes it, Stockopedia likes it but Paul does not. Hardly any coverage on the SCVR.
So no, don't just go by the green ratings.
Rusty2
I didn’t explain it well. Of course green rated shares can flop just as red (and also sucker shares on the stock pages) can do well. I didn’t say don’t buy them. It’s just that with so many quality shares available at bargain prices there is perhaps a case for the lower risk choices among them.
You can just select the green rated ones, however some shares have no or patchy coverage. The stock I mentioned in my previous post is Yu (LON:YU.) it is not some sucker stock, it has been highly rated on Stockopedia for 18 months, Ed regrets leaving it out of his 2023 NAPs because of a last minute swap.
I think there should be more coverage of companies, that are performing well, rather than covering lots of profit warnings.
Why focus so much on companies that are performing badly?
Once I've sold (e.g. Saga (LON:SAGA) I try not to look back and see how the share is doing....or at least only once every six months or so. Otherwise it's too easy to wallow in seller's remorse, to no avail.
I was hoping insurance business to do relatively well like other's but alas! it was not be, I sold mine with 11% loss today
Below is what I posted on 4th April re the insurance side of SAGA and 3 year policies, in response to a post by davidhill.
It would seem the 3 year policies are indeed a problem to them. SAGA blaming market conditions - rubbish! As we all know from our motor and household insurance renewals, prices have leapt ahead; +25%, 100% (or even more) in some cases, SAGA are either mismanaging (still!) their insurance business or cannot properly manage it due to the 3-year issue.
<<Apr 4, 2024
Saga (LON:SAGA). You too Davidjhill are not quite right, I think.
Let's assume these 3-year policies are evenly spread and simply take 50% then on average it'll be 18 month before they can beging the process of higher prices. That means they lag the wider insurance industry- as did DirectLine, but that was down to poor management - there the divi had to be cut, the sp sank, the CEO got sacked. It may come out ok but it's worth pointing out this IS a risk in SAGA's insurance business.
Second point you say that it'll be 'probably 1 year policies from now'. Not so, I've just checked their website and they still offer 3 year policies, both on household and motor. Again, this may not be a problem for them, particularly as the 3-year guaranteed price is based on no claims by the customer, those that do make a claim they can hit them (hard?) mid-way through the 3 years.
What we can say more categorically is that, all in all, it makes their insurance business less predictable than other general insurers who can act more swiftly (in as much as anything is predictable)>>
Auction Technology (LON:ATG) As a relatively novice investor, I am aware that Director Buys have some influence on general buying sentiment, but by how much?
Stocko shows 6 ATG directors selling £15.2M shares over the past 2ish years, and 2 directors buying a paltry £46K shares in the past 18 months.
Surely an enormous red flag for any potential private investor, or am I being too simplistic?
Auction Technology (LON:ATG) A lot of the selling seems to be share options, where the directors get the shares free. Which is another negative point, how many shares are they getting for nothing? Seems a bit excessive to me.
If getting shares free then why buy any? Yes I agree some red flags here.
Research shows that director buys are not a strong indicator of future price direction. However, director sells are a bearish indicator. Obviously the size of the buys and sells are highly relevant. A board of directors with very few shares is also a red flag.
Hi Epitychia. I don't suppose you could post a link to that research .... I would be incredibly grateful. The reason is I have for many years thought Directors sell for many reasons (including bad ones but sometimes to pay school fees; pay a divorce settlement; or, buy a new yacht ....), but they only ever buy in scale for one reason.
The reason is I have for many years thought Directors sell for many reasons (including bad ones but sometimes to pay school fees; pay a divorce settlement; or, buy a new yacht ....), but they only ever buy in scale for one reason.
This is very much the protocol I adhere to, with the addition that BIG director sales soon after a hot set of results with earnings well above trend are a red flag IF accompanied by a correspondingly hot multiple.
Or they are trying to stop the share price falling or to make it rise.
CEO and CFO trades are more impotent than other directors.
I think you might mean IMPORTANT rather than impotent .
Haha, there's a place in Hull reserved for the inventor of predictive text.
They do say Hull, Hell and Halifax oop North
They do say Hull, Hell and Halifax oop North
Yes, but we really don't talk like this
Try Google scholar. Directors are well paid so it is unlikely they are selling to pay day to day bills. A divorce would be an exception to that.
Potential short term trade ideas,
Whitbread (LON:WTB) :
FY24 Results on April 30.
Fantastic H124 and Q3 24 updates. Should beat PBT consensus numbers.
Germany break-even reiteration.
70 million share buy back pending out of 300 million. Another buyback possiblity in FY24 results as per Morgan Stanley.
Forward order book - Better than any year in history (guess due to Taylor swift Eras Europe tour)
Share price close to 1-yr low (around 20% less since the raise after Q3 update )
April 2024 minimum living wage increase accounted in guidance (along with reduced food inflation and energy price) (Q3 Analyst call)
Stong balance sheet NTAV to support share price from further fall.
Travellodge reported good numbers recently and should have a read accross for WTB.
I hold Whitbread (LON:WTB) (opened a large position yesterday) along with couple other short term trade purschases yesterday (IG Design (LON:IGR) , Keywords Studios (LON:KWS) ). Another one i'm watching is Rightmove (LON:RMV). Please DYOR and i welcome any comments on the negatives of these shares. Thanks
Good luck all.
Hi AD09 ... I also hold small positions in IG Design (LON:IGR) and Keywords Studios (LON:KWS) ... would love to increase both, but am concerned by lack of moat and AI effect respectively... both appear very cheap at these levels, but currently uncertain whether to increase....
Keyword seems v cheap so much so that I can’t help wondering what I’m missing.
Whitbread I struggle to get excited about given the high indebtedness
Having just stayed in a Premier Inn, it seems to be a very well run company. However the return on capital is low and perhaps they are not growing as much as the past.
Keywords Studios (LON:KWS) short interest is 3.72% - https://shorttracker.co.uk/com...
Last director buy of £55k in Feb, well above current price. Liontrust went over 5% in March.
Current trading and outlook
· We expect to deliver strong revenue and profit growth and further extend our market leadership position in 2024.
· Driven by improving organic growth, recent M&A, and the maintenance of adjusted operating profit margins above 15% as we continue to manage our cost base and drive efficiencies across the Group.
· Our organic growth expectations are unchanged, progressively improving from H2 23 levels as we move through the year and as the industry's appetite for new content returns, as well as allowing time for the output from Hollywood to increase post the 2023 strikes.
· Extensive M&A pipeline of opportunities in 2024 and confident of continuing our long track record of adding significant value to our business and our clients through our highly value accretive acquisition strategy.
Fcsts look ok too - p/e 10.6, peg 0.2
Chris Mcvey quite positive in this VOX chate (21:55 ins)
https://www.stockopedia.com/co...
Paul's review of results here - https://www.stockopedia.com/co...
Worth investigating more.
Re Auction Technology (LON:ATG) I am a (reluctant) regular user of its services. Relcutant because I begrudge its commission rates. But the good news, if not for ATG shareholders is that a competitor, EasyAuction, is gaining in presence - it has lower rates. So ATG's oligopolistical position is being eroded.
Hi grumpy5,
Re competition for Auction Technology (LON:ATG) .
That is very, very good information, thanks grumpy5. I'll add that to the main report, with a hat tip to you. Thanks very much indeed, industry information like this is crucial, as companies themselves won't tell us about competitive threats of course.
Best wishes, Paul.
As another regular and reluctant user of Auction Technology (LON:ATG) I entirely agree. There are two major players - ATG and Invaluable who have most of the antique/household auctions between them in the USA and Europe. So saturation is high and they have maxxed out the fees - it is usually 6 percent including VAT on top of the premium - so you end up paying a premium of 35 percent on top of the hammer. Easylive offers a cheaper alternative to smaller auction houses in the UK and has gained traction of late. Not completely ex growth yet, but where is the runway of significant medium term organic growth? I'm not sure that I see enough to make me want to pay up for the shares.
ATG commission
You can always arrange phone bidding direct with auctioneer and dodge the ATG fees completely .
Yes....until they forget to ring you! Happens all the time.
Hunting (LON:HTG) - Hunting plc reports that it is on track for FY24 targets, with a very healthy order book too. Our estimates don’t change but support our raised Fair Value of 436p/share. See and hear our new research here: https://www.equitydevelopment....
Severfield (LON:SFR) TU
Results slightly ahead of expectations, record UK and Europe order book, outlook is positive
Inflation in the U.K. eased to 3.2% in March, the Office for National Statistics said on Wednesday.
That was slightly higher than the forecast of economists polled by Reuters of 3.1%, but was down from 3.4% in February.
It should be published to two decimals, rounding to a single decimal is not good enough when the impact is so huge. Many will think it’s a clear 0.5pp miss which it may not be.
The falls are due to base effects, the back number falling away being 0.7% but the current month at 0.6% is too high. April base of 1.2% offers potential for more falls in the annual rate, and also May at 0.6%.... but it's hard to look at these numbers and say we have inflation licked.
£saga have an update
Aye, Saga (LON:SAGA)
Liontrust Asset Management (LON:LIO) issues its trading statement for quarter to 31/3. Net outflows of £1.2 B. Graham has covered LIO in the past and hopefully will review today.
Hope so too. Currently showing second most viewed in the Stocko community so lots of eyes on this one.
LIONTRUST
First of the blame game portfolio .
Thanks Graham for covering this. The asset managers represent a good barometer of U.K. investor sentiment.
You're very welcome! Cheers.
Equals (LON:EQLS) - Yet another PUSU extension! Yawn
Equals (LON:EQLS) I am not sure it is a yawn as on a quick first scan it would appear there is some movement, as this PUSU tells us that Equals have now had received an 'indicative non-binding proposal ' from MDP as well.
Yes but mkt not convinced anything will come off at Equals (LON:EQLS) . I'll continue to hold as this is a terrific business on its own. Board have to spend resources on this ridiculous situation. Time they get tough with a put up or shut up ultimatum!
I hold but don’t forget this is self inflicted by the board…
Equals (LON:EQLS)
Agreed Helvellyn.
2 indicative bids now announced.
My experience as a holder in Equals (LON:EQLS) since 2020 including many direct interactions with management is that they are experienced, highly, capable and would not enter into this situation or let it run on without very good reason.