Small Cap Value Report (Weds 18 Aug 2021) - ANG, TCN

Morning all, it's just Paul here today, with the SCVR for Wednesday, on an exceptionally quiet day for news.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Angling Direct (LON:ANG) - decent revenue growth in H1 of +19.5%, although online sales in the EU have plunged due to supply difficulties re Brexit. Guides to >£4.0m EBITDA for this financial year ending 31 Jan 2022. Tons of cash in the bank, so expansion self-funding. Looks quite good to me, worthy of deeper research I think.
Tricorn (LON:TCN) - announcement today indicates that business likely to be put into administration & sold to the highest bidder. Hence a 100% wipeout for shareholders is likely.
Angling Direct (LON:ANG)
72p (pre market open) - mkt cap £56m
ANG produced a record profit, in its results for FY 01/2021. Jack reviewed the numbers here.
No doubt fishing will have been stimulated by lockdowns, and receipt of Govt support measures, so it will be interesting to see if stronger performance is sustainable in more normal conditions in future?
Today’s update -
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides an update on trading for the six months ended 31 July 2021 (H1 2022).
The table (below) for H1 revenue growth raises a few questions. Online growth shot up 47.6% in H1 LY, as I would expect from the impact of lockdown 1 closing the stores & pushing business online (which was already a key focus pre-pandemic). That has slowed right down to only +3.2% in H1 this year, up against that tough comparative. However, in the line below that, it shows that UK online sales grew +15.8% to make up all but £1.2m of the total. That suggests rest of word online sales dropped heavily, from £3.1m to £1.2m - probably due to Brexit difficulties supplying small orders into the EU?

Retail store sales did well, +40.1%, but this is not like-for-like (“LFL”), so presumably has benefited from new store openings.
Net cash is strikingly high for a company worth £56m, at £19.6m (as at 31 July 2021)
Company commentary - all stores were closed for Feb, Mar, and through to 12 April 2021, due to lockdown 3.
Total sales growth in H1 of +19.5% was concentrated in Q1, against the softest comparatives.
European sales - as I suspected from the figures above, there has been significant disruption from Brexit -
German, French and Dutch native language websites sales in Europe (which comprise less than 5% of Group revenue) were down by 34.2%, impacted by post-Brexit restrictions on bait sales and significant customs border disruption, impacting lead times and customer confidence. The latter has started to improve in recent months, and it remains a strategic priority for the Group to establish a more efficient trading model in Europe.
Judging from what other companies have said, the only solution at the moment seems to be using a distribution network within the EU, rather than trying to supply lots of small orders from the UK, and running into customs administration problems & delays. That also means having to set up a customer returns operation in the EU. Asos (LON:ASC) (I hold) has apparently done this, via a facility in Poland, operated by Clipper Logistics (LON:CLG) . This does seem to be an area where smaller online retailers are having difficulties. Some are either raising prices, or just withdrawing from EU sales altogether.
It works the other way of course - in the UK market there’s now less competition from EU eCommerce vendors, who are having trouble supplying the UK (I’ve heard that Gear4music Holdings (LON:G4M) (I hold) main European competitor is having problems supplying the UK market, so G4M is gaining market share in the UK as a result).
Stores - 1 new site opened, and one relocated. Total is now 39 UK stores. Stores operated a call and collect service during enforced closure, in addition to web sales.
Strategy - continuing to develop gross margin, and improve logistics. “Good progress” with expansion plans, especially in Europe (no specifics provided).
Outlook - useful to have specific EBITDA guidance. The key numbers is pre-IFRS 16 of course, with the post IFRS 16 EBITDA figures generally being meaningless (as they omit some property rental costs).
The Company is only three weeks into the H2 period and the Board remains alert to evolving trading patterns as we emerge from the pandemic. Given the successful trading performance over the first half and notwithstanding the imposition of any further restrictions, the Board is confident that FY 2022 EBITDA will be not less than FY2021 of £4.0m (pre-IFRS 16) and £5.7m (post-IFRS 16), even taking into account the considerably reduced government support.
The Company's strong balance sheet means it is well positioned to further invest in its strategy to become Europe's first choice omni-channel fishing tackle destination.
My opinion - this looks quite good. It looks as if the company might have reached sustainable profits, and also has plenty of cash in the bank to fund expansion.
Seems reasonably priced. Looks worthy of deeper research.
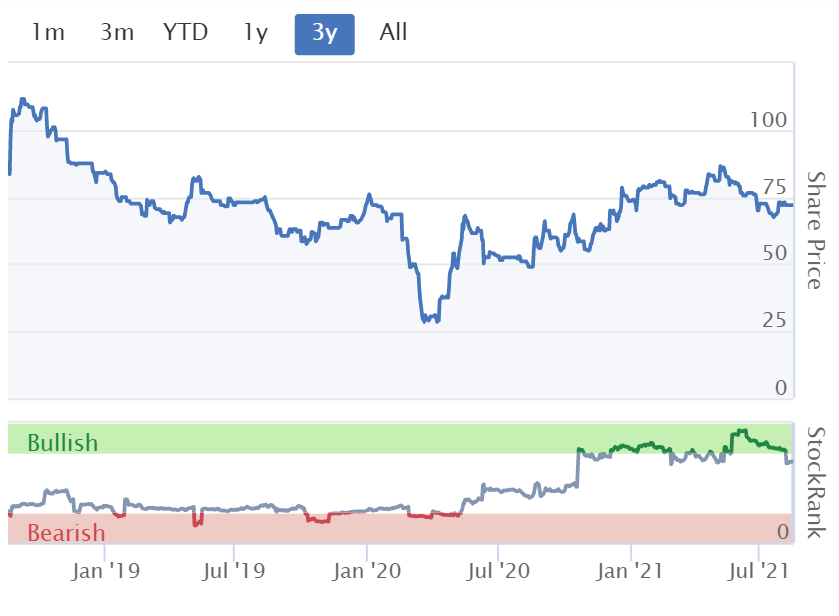
Note how the StockRank has steadily improved. Ecommerce businesses seem out of favour at present, so this could be a decent time to look at the sector maybe? Although ANG is a hybrid, with physical stores as well as online.
.
.
EDIT: an updated note has come through from Singers, via Research Tree, many thanks for that.
Earnings forecast has been raised by 8% today, with an indication there could be further upgrades.
Forecasts are a reminder that £4.0m EBITDA translates into a considerably lower profit before tax (PBT) of £2.7m, which is only 2.8p adj EPS - with the same EPS forecast for next year (FY 01/2023). That's not madly exciting, so bulls will have to hope actual results come in well above current forecasts.
At 72p per share, the forecast PER is currently 25.7 - not exactly a bargain. Although that doesn't adjust for the big cash pile, which would lower the PER considerably if stripped out, which I think is a reasonable thing to do, now the company is trading profitably.
If it beats forecasts, and expands meaningfully using its big cash pile, and cracks the problems in trading with the EU, then this could look a lot better in the not-too-distant future. So I still like it, even though the forecasts are not madly exciting.
End of edit.
Tricorn (LON:TCN)
Shares suspended - mkt cap £2.2m
Not a share we've been covering here recently, because it's well below our usual £10m cut-off, and has been in financial distress, looking for a buyer.
Bad news for shareholders today I'm afraid - your shares are probably worth nothing -
It is expected that, in the event such transaction(s) conclude, these would be likely to be conducted out of administration, in order to safeguard the continuity of the operation and employment, and consequently the consideration receivable by the Company is unlikely to result in any value for equity shareholders.
Suspension of trading on AIM
At the request of the Company, trading on AIM in the Company's ordinary shares have been suspended from 7.45 a.m. today, pending clarification of its financial position.
Due to all the taxpayer support measures for companies during the pandemic, insolvencies have been incredibly rare. So this is a reminder that, if nobody is prepared to refinance a struggling company, then administration (which almost always wipes out existing shareholders) is the only alternative. Company law dictates that companies cannot continue trading whilst insolvent, otherwise Directors become personally liable for the company's debts. Also remember that shareholders rank behind creditors. So when the money runs out, creditors take priority over shareholders.
Tricorn did warn shareholders that it needed more funding on 21 July 2021 -
The Group is currently operating within its existing financing facilities but increasing pressure on margins and cashflow means that additional resources will be required in the short to medium term (see also Going Concern note 2)
The key part of the going concern note said this on the same date -
As disclosed in the statutory accounts for the period ended 30 September 2020, the Group requires substantial investment within the next 12 months in order to return the Group to cash generative activity levels. The Directors have considered the going concern basis and in line with that disclosed in the statutory accounts for the period ended 30 September 2020, as at the date of approval of these interim financial statements the requirement for further funding over and above the existing facilities and the requirement for ongoing support from the Group's their bankers not to recall facilities repayable on demand present material uncertainties which cast significant doubt over the Group's ability to continue as a going concern.
So to be fair, the risks were spelt out very clearly.
I hope none of our subscribers got caught on Tricorn.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
I just hate the new site... They can take the old site from my cold dead hands...
Reality check: the old site is going and if we want the useful data, we are going to have to get used to it. The new site may become better once they've moved to their Cloud hosting and they can concentrate their spend on it.
I will re-evaluate my options when my subscription expires.
Something I already knew... I'm in the 3%.
From Stocko's point of view, if only 3% of users are using an entire (old) platform... its logical for them to pull the plug and concentrate their resources on the (new) cash cow.
I'll go down with the ship and on 13th September then I will try to live with the new site.
It needs to be put into context that The Stockopedia and StockRank TM based strategies appear to be increasing my personal wealth by 25 to 35% year on year, with records broken again this month.
One would be an idiot not to focus on the data not the delivery.
I'm surprised by the 3% figure, judging by comments on the forum it is far higher than 3%, maybe the old site users post far more comments than the new site users.
You have to remember that newer members don't have any choice and are forced to use the new site.
My biggest issue with the new site is it is sooo slow on both my PC and ipad, on the ipad it unusable at times. Looking at my folios last week on my pc, switching to the chart view on the new site still could not work even after 6 minutes, switching back to the old site it worked within 5 seconds. I have tried this several times and the new site is always much slower, often around 1-2 minutes, the old site is 4-10 seconds.
Hope things improve when the old site is switched off.
I agree Herbie. I don’t have quite such a performance issue with the new site on the iPad as you but it seems worse not better.
I was surprised by how low the percentage of users on the old site is. Perhaps that’s a reflection of the subscriber churn (users of the old site who leave are replaced by new users who have no choice) and general expansion in subscribers.
I remember being highly annoyed by an iPhone update one time where they had tinkered around with fonts, colours, layout etc and made it significantly poorer. But got used to it in time. So, I guess that we will get used to the new Stocko site in time and our memories of how much we loved the beautifully clear appearance of the old site will fade away.
Hi Graham,
It is still much slower on my PC as well. The Folio chart view was on the PC. I use my ipad for travelling and the wifi is often much slower than my home wifi, so it is a concern the site will not work on my ipad.
I don't understand why the new site is so slow on my systems.
I see over at Fulcrum Utility Services (LON:FCRM) the last remaining board member from the old guard has now been pushed out, Stephen Gutteridge. All the board members now are new, appointed in either 2020 or 2021.
The catalyst was Harwood Capital and Bayford Group, owning 25%-ish combined, taking two board seats last year.
There's also a new CEO, and CFO too (from Harwood Group).
I'm intrigued as it looks like Harwood and Bayford are being activist investors and successfully changed management and board.
Anyone have a view on Harwood Capital? Are they predators and PIs likely to end in tears here? Or do they normally do a good job turning around companies?
I note that a business contract worth quite a bit was announced a few months ago... with no other than Bayford Group.... talk about arms length...
My thoughts are that Harwood are very good at making money for themselves and their investors. I am looking at buying in to their trusts Oryx International Growth Fund (LON:OIG) and Odyssean Investment Trust (LON:OIT), both of which have performed very strongly indeed over the past year. They also run North Atlantic Smaller Companies Investment Trust (LON:NAS) which is doing very well. I think I would do that over following them into one investment.
Can anyone account for the big fall in Renalytix (LON:RENX) at 14:30 today? Clearly a case of the Americans pulling out - seems to be the fashion this week.
I've been tracking this one since a respected US analyst described this as the "the new Exact Sciences". Whether he meant a company with potentially 15 years of shareholder pocket-dipping and no profit to show for it, or a future massive multibagger - he wasn't clear.
No RNS or news story on my Refinitiv so I assume a rumour regarding product trials or similar.
Thanks
Nothing I can see on the news channels about Renalytix (LON:RENX) . Comments on another chat board suggest a sale of 80,000 at NY opening (against daily average volume of 40k) indicating the possibility of a big short seller (maybe with a shock horror „Research“ report to follow) or, someone with some inside scoop (insider dealing, heaven forbid, on AIM, surely not!) ….. or something else - discounted fundraise? 22% down at one point, sort of recovering now to 15/16%.
Gus.
In the words of EJ Thribb
So, Farewell then
Old Stocko format
You were loved by all
Who used you
Apart from a few
Weirdos who were happy
To be forced to adopt
The NEW!!!, IMPROVED!!! format
Now we all have to
Put up with the
Bits that don't work
From 13th September
In the name of Progress
EJ Thribb
(17 1/2 tickets still outstanding)
Perhaps its a way of flagging up the over 50's - must admit i will use the old format till the day it dies then mourn its loss till i realise the new format actually may not be so bad after all. One thing i miss on the old format is that next year broker forecasts don't show up - so perhaps there are other gems to experience when we do get pushed off the diving board.
Yawn, tired of hearing all the bleating and moaning about this tbh, if you don't like the new Stocko format then you can vote with your feet
#ANG - well summarised , Paul, and I agree with the conclusions too.
Cheers, Andy
Please! Why all the discussion of Novacyt Sa (LON:NCYT) here when someone set up a dedicated thread just a few threads below? Why bother when people degenerate to the bad old ways.?
Personally, I see it still as too uncertain, especially without any clear statement as to the nature of the dispute with DHSC (apologies if I've missed something). Other negatives I see are the downward pressure/publicity on travel pcr tests and the pressure from some newspapers to allow cheap lft tests for returning UK travellers. Also read recently that only a small % of UK lft positives are suitable for pcr testing as the viral loads are too low.
With hindsight of course a sensible hedging strategy would have been to pile into BNTX and MRNA at the start of the year - both being up almost 4x before recent correction.
There are very few comments on what appears to be a quiet day, nominally I am not interested in Novacyt SA (LON:NCYT), however, I have found the above comments very useful - comments I would not have read ordinarily.
usually we focus on small cap news and Novacyt Sa (LON:NCYT) had half year trading statement out today hence the discussion on here.
The dedicated threads are designed so that people can discuss specific stocks during periods where there may not be any immediate news.
The big benefit of this approach is that we can spot stocks we may not have considered before on SCVR and if they pique our interest have more detailed follow ups on dedicated discussions.
Wilbraham
I don't hold Novacyt Sa (LON:NCYT) and would not have found the dedicated thread. I thought the different and well-reasoned opposing viewpoints quite interesting.
Wilbraham
Novacyt SA (LON:NCYT)
Please! Why all the discussion of Novacyt Sa (LON:NCYT) here when someone set up a dedicated thread just a few threads below? Why bother when people degenerate to the bad old ways.?
Errrr Wilbraham you seem to be missing the point that this company has updated the market today and is in the market cap limits to be discussed here - i wouldnt expect the discussion to veer anywhere as its all on point today.
If you like Angling Direct (LON:ANG) and the niche, then $JOUT (Johnson Outdoors) may also be of interest. Its US based, and in the fishing niche (as well as many other outdoor activities), seems to be on a reasonable valuation imo, and still has good levels of ownership from the Johnson family. I hold.
Re Angling Direct (LON:ANG) - worth looking at how well Pets At Home (LON:PETS) have done with a similar niche focus, anchored on engaged customers who (almost) have to interact with stores for some things (eg live bait).
I expect this to build loyalty and the opportunity for cross-sell/re-sell ......and the HR strategy of recruiting older, knowledgeable, enthusiastic fishermen as sales staff is a good one. This gives a bit of a moat vs Amazon and the chain retailer for the higher spending customers and the wide inventory/high number of slow selling niche items gives it scale advantages vs single operation lifestyle stores. As long as fishing remains popular, I think it is increasingly well placed to do well and steadily roll out/takeover new stores and expand online.
I even like it being forced to be more pro-active in Europe since it seems to have a headstart vs local Euro-competitors. Now it will either be forced to get serious or quit and I can live with either!
If it can really drive its own label sales then another Gear4music Holdings (LON:G4M) is definitely possible.
(I thought about planning to wait for the price to drop a bit then bottom fishing but thought the pun too obvious at this stage of the week).
Any views from anyone re: the ongoing hostile bid of Good Energy (LON:GOOD) by Ecotricity?
I hold Good Energy (LON:GOOD) purely in speculation but reading the rebuttal see Ecotricity's balance-sheet being rubbished. As ever, I live in hope.
I have a small position in Novacyt Sa (LON:NCYT) and believe it is oversold.
The Company is doing a Presentation via Investor Meet at 1pm today which I intend to listen to in the hope of further understanding the current situation.
I do not expect any meaningful update on the dispute with DHSC as it is early days but I think a lot of holders who bought at very low prices are continuing to sell contributing to weakness in the SP.
don't think we will get anything on the DHSC side - lawyers unlikely to allow any meaningful comment on this whilst the dispute continues. At best we might get a timeline.
I'm looking for a couple of things (1) How long are their key clients expecting testing to persist and (2) forward strategy (ie how they will leverage the core diagnostics business and distribution capability and utilise cash post covid).
Novacyt Sa (LON:NCYT) look interesting as a contrarian play. Deeply unpopular with investors following the DHSC dispute but revenues reiterated at £100m for the full year and feels like they are likely to outperform that by maybe 5-10%. Extrapolating through I can see £40m profit and an EPS of 60p. However, that should be seen in the context of what I think should be around £140m of net cash. So we are paying maybe 2* EV/EBITDA at this level.
Assuming there will continue to be testing over the next 2 or 3 years feels like you are getting a diagnostics testing business and any favourable resolution of DHSC for free.
Anyone think I'm missing anything?
The bear case on NCYT includes:
It boils down to one simple point: the stock market looks to the future, and the future for NCYT is impossible to predict.
I have no position.
Cheers
Chris
But that's the whole point right....your comments echo what everyone else is doing without actually looking through the situation, which is where the contrarian value lies. It is classic investor behaviour where hype has led to dismay and as a result investors can't see much further than their nose.
to take your points
1) Private testing and foreign work has absolutely grown very strongly and will deliver in excess of £100m revenues this year. So that's the baseline. Any DHSC settlement or new business is just a bonus. It is already discounted to zero in the price so it doesn't form any bear case at all, there is only upside on that element.
2) If you assume testing is here for 2 more years (and I do) then the entire market cap of the business will be net cash. ie the business itself (or any DHSC settlement) is completely free.
What they have courtesy of covid is a strong diagnostics business capability with the distribution network to go along with it. That can be used for all sorts of things. The usual problems of procurement/preferred supplier etc are already sorted.
So buying here now what's my downside? Appears to be quite small. The main risk appears to be that they overpay or misuse the cash to buy things that don't have a good IRR. But at least those deals will be announced and I can take a view as and when they happen.
For me Novacyt Sa (LON:NCYT) has moved to a deep value play : I am trying to work out if I've missed something fundamental (rather than the DHSC noise) but so far I'm not seeing much.
I don't think you're missing any smoking gun. Most investors, especially institutional investors, want some security/pretence of revenues continuing and growing beyond 2/3 years. Full year rev of GBP100m, with the cash on top (not reported today), is a whopping 50-60% drop from last year but it does look cheap for a GBP250m market cap with high profit margins. The cash was GBP91m+ in the full year results, so decent firepower.
If those revenues continue for 5-10 years, I would whole heartedly agree that you're getting a bargain. But we don't really have a clue, just belief. You believe the testing and revenues will continue and grow, fair enough, but clearly others don't.
Alternatively, the market wants a concrete strategy about what to do next if/when these revenues die off, and there isn't one yet. Assuming we get one, and it's good, this might be a catalyst for a re-rating.
So you're putting your money in with eyes wide open, but it's a gamble as to what happens next. That's not to say you won't be successful, but that's why the price is what it is.
Good luck with it.
Chris
I don't quite agree and I'm not saying testing and revenues will continue to grow. In fact I am basing any investment decisions on the opposite hypothesis.
Cash was £91m and should be closer to £140m by the end of this year based on the £100m+ revenue estimates.
So EV at full year is basically £100m
I think 2 years worth of testing at existing revenue levels is conservative (ie no growth but no major drop off in next 2 years - average flat). At which point the cash thrown off means the EV of the business would be £0
So it is not a gamble as to what happens next. Testing will probably go on quite a bit longer but I assume it is zero. I expect some sort of DHSC settlement but I also assume it is zero.
My key point is that the existing business should be worth more than £0 hence the contrarian play.
Risk to my capital over the next 2 years therefore appears to be pretty low - downside of maybe 20% if testing falls off a cliff, but the returns could be quite material. So risk/reward appears to be heavily favourably skewed at current levels.
You make a really good case David, I'm going to look at this a fresh.
Good old community this.
Cheers.
Chris
No probs. I have found a number of good risk/reward trades on plays where investors are distracted by a particular issue when the real value proposition is actually elsewhere. I am hoping this is another one, though of course time will tell.
check out the presentation and Q&A that has just finished on investor meet company (it should be up as a recording shortly) as that's probably a great starting point if you want to look at it with a fresh eyes.
Cheers, will do.
Novacyt SA (LON:NCYT)
davidjhill
" I think 2 years worth of testing at existing revenue levels is conservative (ie no growth but no major drop off in next 2 years - average flat)."
Why is at that current market expectations* are that turnover will drop to £70 mill next year. How come your "conservative figures" are 50% higher than the company is guiding us towards at present?
*I have taken forecasts from stocky.
I wouldn't rely on stocky for this one. Their estimates for this year are way too high as well.
Company guidance on the call today was very comfortable with £100m for this year (ie likely to beat was my read across) and too early to put numbers on 2022. Lots going on, so there is no company guidance. New LTF product for foreign markets launched and US testing launch strategy coming soon.
My take is that I'd expect there is another year of some revenue consistency and maybe growth in the private sector (sport, films, events etc) and foreign markets (where covid levels and vaccination rates are much lower) coupled with the new products. Then I can see a big drop offset by some new business the following year.
Novacyt SA (LON:NCYT)
Company guidance on the call today was very comfortable with £100m for this year (ie likely to beat was my read across) and too early to put numbers on 2022. Lots going on, so there is no company guidance. New LTF product for foreign markets launched and US testing launch strategy coming soon.
Ok i guess the forecasts are outdated that makes sense as the they have flatlined which is often the best sign that they have beeen removed . I guess though if they aren't happy to give any numbers for next year i would take that as a really bad sign rather than a good sign or neutral sign. If they won't tell us anything - to me that suggests they don't have enough in the bag to provide a reasonable guess. However unreliable figures are i would rather know their best guess rather than they simply keep that info close to their chest and the chests of their best buddies. Just look at LoopUp (LON:LOOP) for an example of how quickly the wheels can come of the wagon when sales dry up - and to be fair to loop management they told us 8 months ago plus they weren't gonna make any profit this year. I guess you can see i am not impressed with any management that will say nowt about next year when they have company valuation is over £200 mill.
They didn't say they wouldn't, just that it was a bit early. If they had strong levels of visibility it wouldn't be on 2* earnings, so we can't have it all!!
I'm not advocating that I think this is a high quality stock (it might be but I'd say the jury is still out on that, at least for me).
What I am saying is that the special situation throws up an interesting trade where the risk to my capital from the low 300p mark looks to be relatively small given the net cash position and todays confirmation of trading being £100m+ for the full year (and seems like it will be closer to £110m). ie if revenues dropped through the floor immediately after the y/e I reckon I'd still have 75-80% capital value left and I view that scenario as being highly unlikely. It's all about risk / reward of the trade and this appears to be one of those unusual situations where I consider the trade mis-priced and I like those as they've tended to serve me well in the past.
I entered Novacyt SA (LON:NCYT) at 418p on the downward trend so took a hit of 25% odd as it dropped to its lows but thought there was still value in the company so kept holding.
Based on the presesntation I noticed two points that I thought worth mentioning:
1) The new contract they have announced for £4.5kk is for agents that are used in the equipment sold in Contract 2 which is being disputed. - I thought this was a strong indication that this dispute would be resolved in favor of NCYT considering the DHSC are actually using the test equipment they purchased but apparently have not paid for.
2)I felt NCYT dodged the question on what diseases they were focusing on for the future. (what will maintain momentum after covid) instead they largely focused on what Covid developments they were working on, which will take the company over the next 2/3 years. New platforms were also mentioned although I did not understand this element of the answer.
- IMHO NCYT still has everything to play for and more upside than downside so I am inclined to agree with davidjhill.
- The fact they have won a new contract with DHSC should help their public relations ( as well as revenue) and a strong indication of resolving thier initial dispute.
- They have loads of cash and if they spend it wisely should grow and expand the business (CFO spoke about M&A as part of a strategy - although they dont seem to have an M&A strategy yet)
- Covid going to be a round for quite a while yet even if the need for testing is diminishing (decreasing by 50% annually according to presentation)
Big questions is what they can do to maintain growth and momentum over the longer term.
I suspect you are right about Novacyt SA (LON:NCYT) but in answer to your question of whether you are missing something, I would point to the DHSC dispute. You seem to be assuming that this is as far as it goes. How do you know that? If the client that accounts for 50% of revenues is this unhappy with Novacyt, it seems quite possible that other clients may have similar concerns and be watching closely. What about further claims and reputational damage? What would it mean if there was evidence released in the dispute to show that performance is not as claimed?
You will know more about this than I do and I am not suggesting that these things will go against Novacyt, but perhaps there are more unknowns and so a higher level of risk than you are accounting for. Good luck.
cmpeckham wrote:
"I suspect you are right about Novacyt SA (LON:NCYT) but in answer to your question of whether you are missing something, I would point to the DHSC dispute. You seem to be assuming that this is as far as it goes. How do you know that? If the client that accounts for 50% of revenues is this unhappy with Novacyt, it seems quite possible that other clients may have similar concerns and be watching closely. What about further claims and reputational damage? What would it mean if there was evidence released in the dispute to show that performance is not as claimed?"
I do not know this for certain, but I suspect, from following Novacyt (which I hold) closely for the last year, that the DHSC dispute arose because the original PCR testing product which had been ordered in the DHSC contract was not easy to use by inexperienced or busy staff at NHS hospitals, because it required a number of different processing steps to be followed to get correct results. Novacyt responded to criticisms by developing a new PCR testing product called Promate that required just one processing step. I suspect that the DHSC refused to pay for the unused original product in the contract and asked for it to be replaced by Promate, which Novacyt delivered. I suspect that Novacyt is asking the DHSC to pay for both the unused original product and the Promate.
The fact that there has been an announcement today that the DHSC has entered into a new, but smaller, contract for Promate suggests to me that the DHSC is happy to continue using Novacyt's products, and so are the NHS hospitals which have the right to buy from Novacyt independently of the DHSC.
Kenmare Resources (LON:KMR) announced a very strong set of HY numbers this morning. Revenues +51%, EBITDA +121%m PAT +278%. Interim dividend 7.9c +217%. FY production guidance reiterated, Pricing outlook improved for H2. Scope for FY numbers to be upgraded.
Following the capital investment in 2020 the company is performing really well and management are delivering on their strategy.
There is a webinar for private investors tomorrow at 5.30. Register here
My morning smallcap tweet: Spitting out the indegestible
Falanx (LON:FLX) LoopUp (LON:LOOP) Angling Direct (LON:ANG) Quantum Blockchain Technologies (LON:QBT) Novacyt SA (LON:NCYT) Tricorn (LON:TCN)
Falanx (FLX) tardy trading update: guides FY(Mar) rev down 14%, reduced adj EBITDA loss. Trading since March in line with mgmt exp. [SP=1.02 Cap=6m]
LoopUp (LOOP) awarded 'Calling for Microsoft Teams Advanced Specialization'. Great but show me the money. [SP=37.88 Cap=21m]
Angling Direct (ANG) guides H1(July) rev up 20% and up 45% on 2 years ago. Expects FY EBITDA at least £4m (pre-IFRS 16) and £5.7m (post-IFRS 16), "The Company's strong balance sheet means it is well positioned to further invest in its strategy to become Europe's first choice omni-channel fishing tackle destination." [SP=73.32 Cap=57m]
Quantum Blockchain Technologies (QBT) rampy update on its cryptocurrency mining efficiency project which uses Quantum Computing, Machine Learning and other cutting-edge bandwagon leveraging techniques. The team of 13 sector experts is now fully operational! They have to be fair made GPU mining 10% faster giving "invaluable quantitative feedback on the optimisation techniques discovered by the in-house expert." [SP=1.24 Cap=12m]
Novacyt (NCYT) guides H1(June) rev up 50% though £41m is in dispute with Gov't. Nevertheless it wins contract for PROmate COVID-19 tests to the NHS for near patient PCR instrument platforms. Worth up to £4.7m. Also contract from WHO. Reiterates FY revenue guidance of £100m, excluding DHSC revenues. H1 was £54m. [SP=302 Cap=249m]
Also at 7:57 Tricorn(TCN) suspended pending clarification of the company's financial position
Tricorn (LON:TCN) update - will go into administration, unlikely to result in any value for equity shareholders.