Small Cap Value Report (Weds 18 Oct 2023) - SOS, KCT, HSW, RBG, 888

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Sosandar (LON:SOS) (Paul holds) - 17.75p (pre market) £44m - Trading & Strategic Update - Paul - AMBER
A big profit warning, dressed up to sound like a deliberate change of strategy. I'm not impressed. More detail below. Brace for a likely sharp fall in share price.
Kin and Carta (LON:KCT) - Recommended cash takeover bid (from Apax) at 110p, a 41% premium. Great news for shareholders, congratulations! [no section below]
Hostelworld (LON:HSW) - up 1.5% to 120p (£148m) - Trading update (ahead) - Graham - AMBER
More good news from this online travel agent. Gross transaction values and revenues continue to surge higher, and full-year adjusted EBITDA expectations are upgraded. The debt problem has been solved and my only remaining question concerns the valuation here.
Revolution Bars (LON:RBG) (Paul holds) - 3.2p (£7m) - Preliminary Results - Paul - AMBER/RED
I review the FY 6/2023 results published yesterday. The core chain looks in real trouble, and I think is heavily loss-making now. High risk, especially after a "material uncertainty" going concern warning. There are some positives though - good performance from Peach Pubs, and bank looks supportive, having relaxed terms. This could go either way, for risk-takers only. Best avoided for most investors I think.
888 Holdings (LON:888) - down 3% to 83.3p (£374m) - Trading Update (in line) - Graham - AMBER
After a profit warning last month, 888 has published its Q3 update without further changes in expectations. Revenues are under pressure due to variety of challenges in the Mid East and closer to home. Synergies and other cost savings hopefully keeping things under control.
Paul’s Section:
Sosandar (LON:SOS) (Paul holds)
17.75p (pre market) £44m - Trading & Strategic Update (profit warning) - Paul - AMBER (BLACK for spreadsheet - PW)
Lots of detail in this update, but for me it’s a profit warning, and I think the market is likely to take a similarly dim view.
Previous forecast (Singers) for FY 3/2024 was £58m revenues and adj PBT of £3.1m.
Today that’s been slashed to £46.8m revenues, and only £0.1m adj PBT! That’s a massive miss.
The commentary today tries to persuade us that this is a deliberate strategy to re-educate customers to pay full price, with long-term benefits. I don’t buy that, sorry. Why would you collapse your own profitability and sales growth? Also, what happens to the unsold stock, that still has to be discounted at the end of season?
Net cash of £7.0m looks fine, given that it’s probably near a seasonal low due to stocking up for the busy autumn season.
Poor results for H1 are indicated -
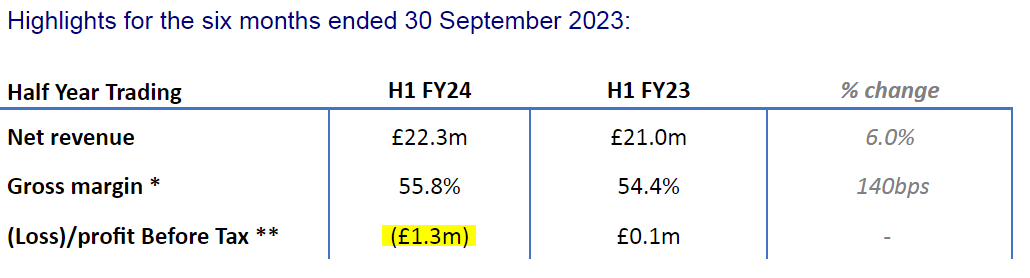
There’s lots more information, and if I’ve understood correctly, it sounds as if SOS is planning to open some of its own physical stores, is that right? Take it from me, running a network of physical stores will be a massive distraction from operating the online business. So I’m not sure that’s a good idea, although they will get amazing deals from landlords on empty shops. Could be a can of worms though, going down this route.
Paul’s opinion - this is clearly very disappointing. The share price has slipped a fair bit in recent weeks, maybe due to sellers who’ve tracked declining online traffic, which I know some investors do?
Unfortunately, we’ll need to adopt the brace position today, as I suspect another 20-30% fall is on the cards (writing this at 07:53).
Quite a few of us thought that the growth plans for this year looked too ambitious, given the relatively slow Q1, and that’s turned out to be correct, but I certainly wasn’t expecting anything like as bad as the revised guidance today. Oh dear.
Still, at least we don’t have to worry about the balance sheet. Slower growth means less pressure on cash, and there’s already plenty of cash, and they’re talking about breakeven in the FY (H2 is busier than H1 remember), so this is a setback, not a disaster.
Revolution Bars (LON:RBG) (Paul holds)
3.2p (£7m) - Preliminary Results - Paul - AMBER/RED
Peach acquisition delivering against a challenging trading environment
Overall result in line with expectations
Revolution Bars Group plc ("the Group"), a leading UK operator of 67 premium bars and 22 gastro pubs, trading predominantly under the Revolution, Revolución de Cuba and Peach Pubs brands, today announces its preliminary results for the 52 weeks ended 1 July 2023.
Sorry for the delay in typing up my notes on these results out yesterday.
I know people think I’ve been a perma-bull on this share share, but that’s not actually true. We’ve been highly critical here of the management, especially their decision to max out the overdraft to buy a chain of gastro pubs, Peach.
Also there’s been the small matter of the pandemic, lockdowns, energy crisis, and cost of living, in a sector which has been battered & bruised for years now. Hence any pre-2020 views are of course from literally a different world.
As the facts have changed so much, and just to clarify, I see RBG as a special (high risk) situation to trade, not an investment. Hence I’ve dipped in & out a few times in recent years, including a tiny current position (which is under 0.5% of my portfolio).
Here are my notes on the FY 6/2023 results -
Revenue up 8% to £152.6m
Adj PBT is a £(2.1)m loss, statutory loss (after big asset writedowns) is £(22.2)m, a deterioration from a small profit LY.
Very poor LFL sales of -8.7%. Bear in mind this is boosted by impressive +14.1% LFL sales at newly acquired Peach Pubs from Oct 22 to Jun 23. So I dread to think what the LFL performance of the core business is - probably well into negative % double digits - which is disastrous for a high gross margin, high fixed cost business. Is the core business actually worth anything now, is my main question? The market cap of £7m is saying not really, no.
Current trading - at least the sales fall is moderating, to -5.5% new year to date (from July to now), and -3.5% in the last 3 weeks. Given that average wages have recently overtaken inflation, then the squeeze on gross incomes has at least begun to reverse. Although of course higher stealth taxes from freezing personal allowances have eaten into net pay - I’d like to see some data on that.
Christmas bookings are good, up 18%, so we might see something of an upturn maybe? RBG needs it, very much so.
Outlook - confident of achieving FY 6/2024 expectations, which is another small loss, little changed from FY 6/2023.
Reasons for weak performance - obvious sector and macro factors, but I don’t buy management’s claim that younger people have been disproportionately impacted by the cost of living crisis. With minimum and low wages up the most (c.10%), I’d actually say the opposite. I think RBG has suffered because newer, fresher formats (eg Stonegate’s “PopWorld”) and the rapid growth in experiential leisure (e.g. XP Factory (LON:XPF) - I hold) is taking a chunk out of their market.
** Going Concern ** a major red flag, with a “material uncertainty” over whether it can keep within bank facility terms in a downside stress test. Normally I don’t risk any significant money on companies with going concern issues, because sometimes it ends up with a deeply discounted placing (RBG did 2 of them in the pandemic), or even insolvency. To be fair, plenty of companies successfully trade through going concern problems. But why take the risk?
Supply chain - it mentions 5 months of “severe disruption” to deliveries, I don’t recall this being mentioned before, so took me by surprise.
Playhouse format - hasn’t worked.
Bank debt - we’ve mentioned this prominently since the acquisition of Peach with debt a year ago. It was a crazy decision, just as the balance sheet had been sorted through 2 placings, to gear it back up again with this acquisition. Although some people have described it as a “life raft” for management, given how badly the core business has performed. It’s looking as if that was an accurate description.
The situation actually looks a lot better than I expected. The bank seem fully co-operative. Evidenced by the facilities being recently relaxed, with £30m available to Dec 2024, and covenants greatly relaxed (nothing related to profitability now, just a minimum liquidity requirement). I think that’s very good news actually, as the risk of an emergency placing looks to have receded, although we don’t know what discussions have gone on in private between the company and its bank.
Net debt of £23.2m at 15/10/2023 is clearly way too high, but remember it owns Peach Pubs, so in an emergency that could be sold off and get the bank back maybe half its money? Sell off a few key performing sites (eg Manchester), and the bank would probably get all its money back. But in that scenario, shareholders would probably end up with nothing. So a shareholder wipe-out here is a possibility in a downside scenario. Hence nobody should be risking money they cannot afford to lose on this share. If it pulls through and begins to flourish as the consumer squeeze ends, then there could be exciting geared upside to the shares. So make no mistake, at £7m market cap this share is now high risk: high potential reward. It could go either way, I don’t know which.
Balance sheet - huge deficit on the lease entries, which tells me they’ve got lots of heavily loss-making sites. Remember the leases were restructured during the pandemic, so things seems to be back to square 1. Maybe a CVA is needed to ditch the problem sites? However, as long as the bank facility remains available, which it seems to be, then I don't see any short term solvency or liquidity problems, it should be able to trade normally, paying suppliers & rents on time, etc.
Cashflow statement - it’s not cash generative. Borrowings were increased to fund the Peach acquisition.
Paul’s opinion - RBG is clearly high risk, possible high reward. As solvency risk is high, I have to mark it AMBER/RED, and that’s probably being kind. The only reason I didn’t go RED is because the bank situation seems a lot better than I expected, with greatly relaxed terms. That buys management time to trade their way out of the current problems with the core Revolution sites. Meanwhile the Peach Pubs are trading well, so maybe that acquisition might turn out to be the saviour of the group, who knows?
What happens next? No idea. Downside scenario - 1p emergency placing and heavy dilution, or insolvency. Upside scenario - trading begins to improve and we get a 3-bagger or more. Your money, your choice, although I imagine almost everyone reading this will be steering well clear, and I don’t blame you! This is for risk-takers only.
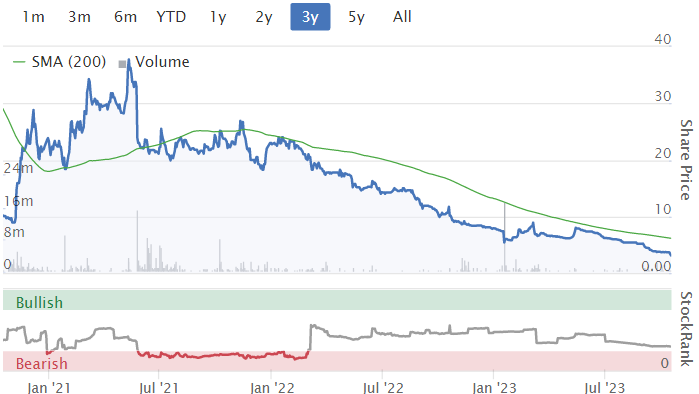
Years of misery for shareholders, and huge dilution from 50m to 230m shares too -
Graham’s Section:
Hostelworld (LON:HSW)
Share price: 120p (+1.5%)
Market cap: £148m (€171m)
This is an online travel agent which has seen a number of positive developments over the past year - surging revenues, debt reduction, and a lower interest rate on its debt facilities.
Today it upgrades guidance:
Based on our record revenue performance YTD, we now expect adjusted EBITDA to be in the range of €17.5m to €18.0m for FY23 (up from €16.5m to €17.0m communicated at our AGM in May 2023). This guidance is provided subject to any deterioration in the macro-economic environment, air travel disruptions, or any other material external factors in the balance of year.
Since the travel disruptions associated with Covid, Hostelworld has added a disclaimer to its forward-looking statements in this way. You can’t blame them for a little paranoia, after the disruption experienced in the travel sector!
An extra €1 million in adjusted EBITDA is a very nice indicator of positive momentum - although of course it is not the same thing as real bottom line profitability.
One of the reasons I’ve been hesitant to take an outright positive stance on these shares is an insistence on seeing real profits, rather than adjusted EBITDA. Consensus estimates suggest that Hostelworld will earn only a small net income in the current year.
Let’s get back to the trading update and see the other highlights. These numbers are year-to-date for the first nine months of the year:
GMV (gross transaction value of customer bookings) €496m (+38% year-on-year).
Revenue €75m (also +38% year-on-year).
5 million bookings (+43%).
As you can see, there is tremendous momentum currently. While this is still a function of the post-Covid recovery, it’s also true that results are trending significantly ahead of 2019 (the last pre-Covid year).
Total revenues in 2019 were €80.7m, while the consensus forecast (before today’s upgrade) suggested revenues of €91.3m in the current year.
Let’s round out our summary of today’s news:
Average booking value down slightly year-on-year (4%) due to a higher proportion of Asian bookings.
Net debt €13.4m (it was €22m at the start of the year, and €16m at the end of H1).
Interest rate on the debt reduces further to 2.65% over EURIBOR (it was initially 3.75% over EURIBOR, and then fell to 3.25% over EURIBOR). Net debt to adjusted EBITDA less than 1x.
Graham’s view
Once again, I’m tempted to turn green on these shares (see my comments in June and in August).
In June, the share price was 125p. In August, it was 134p. I’m surprised the share price hasn’t moved higher given the positive momentum and good news that Hostelworld keeps publishing:
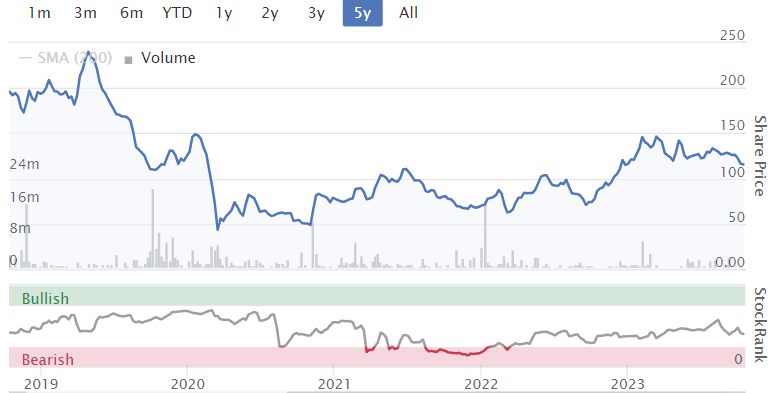
However, perhaps the valuation is perhaps still a little punchy? Converted to Euros, the market cap is €171m, for an enterprise value of €184m.
With adjusted EBITDA running at €18m, the company is trading at ten times that. And we can reasonably expect a large gulf between EBITDA and net income.
So I think I need to maintain pricing discipline and stay neutral on these shares for the time being. An interesting company with lots of good news, but perhaps it’s still priced about right for its current stage of progress.
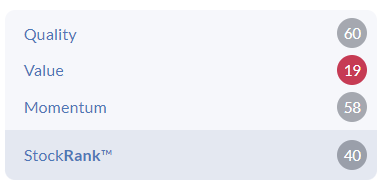
The StockRank still considers it to be overvalued:
888 Holdings (LON:888)
Share price: 83.3p (-3%)
Market cap: £374m
At the time of writing, Graham has a long position in 888.
888 (LSE: 888), one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green, today announces an update confirming its trading during the three months ended 30 September 2023
I covered this company’s profit warning last month in some detail.
With only a few weeks having passed since that warning, it would be strange if this Q3 update included any more nasty surprises.
Key points:
Revenue in the quarter of £405m, down 10% year-on-year.
UK & Ireland online: revenues down 10% “driven by ongoing impact of safer gambling changes and refined marketing approach, coupled with lower-than-expected betting net win margin from customer friendly sports results in September, particularly UK football”.
Retail (i.e. physical locations): revenue +1% year-on-year.
International: revenue down 19% year-on-year “with an ongoing significant impact from compliance changes in dotcom markets, particularly the Middle East”.
Problems in the Middle East with 888 failing to do its money laundering checks properly were responsible for a profit warning at the start of the year (and the former CEO left the company at the same time). The impact of this compliance issue appears to be dragging on.
The main positive takeaway that I am bringing from this update are:
Synergy delivery on track and significant cost savings being delivered - £100m of synergies were targeted from the William Hill merger, and if they are delivered then we have a good chance of seeing positive financial results before too long.
No change to Q4 revenue expectations (down mid-single digit) and FY 23 Adjusted EBITDA margin 18-19%.
Remember that the big-picture goals here are for £2 billion of revenue by 2025 and an adjusted EBITDA margin of 20%.
Assuming reasonable cash flow conversion, that would enable the company to pay its interest bill comfortably, reinvest in the business, and hopefully start to reduce its overbearing debt load.
I have no reason today to change my view on this company: it’s very high risk, but I am neutral as I do see significant upside if it pulls through. If trading continues to deteriorate, then it could well end up being a zero for shareholders.
The 2028 bond is trading at 93 euro cents, according to the Frankfurt stock exchange:
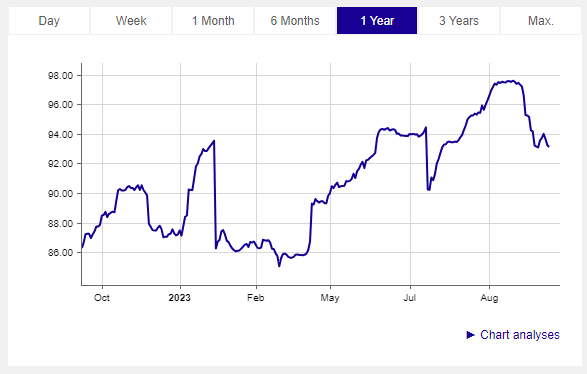
The September profit warning has hit confidence, but it’s far from panic in the bond market.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Revolution Bars (LON:RBG)
Lets have a look at what you could have won:
RBG 2.76p currently. (Normally they go up after I sell.)
Paul is probably right about 1p in 9 months.
Re Sosandar (LON:SOS)
I don't really follow closely but I had a small early investment in the biz. A variety of things put me off (partly too much early enthusiasm from PIs, me being a bit contrary!). For example, early on the FD (who seemed to do the work for a background CFO in name only!) was shaky and didn't seem to know what he was doing well enough. But most off-putting were the joint CEOs. Loads of enthusiasm and dazzle but neither are CEOs. They are integral to the business and its prospects but a good board or wise founders would have brought in an experienced CEO and then let two founders get on with making the product work as best as they can. I guess the move on to the high street partly comes from CEOs who get blown about by circumstances and ideas too much. The RNSs are evidence of 'on the hoof' approach too. They need a calmer more strategic hand on the tiller of the company to let them get on with making the biz hum.
Totally wild guess...but I see a brand that will be taken out (very) cheap ...and going all conspiratorial I wonder if some of the background board characters know this and are waiting for some rich pickings...
TBC I may well be well off beam...my imagination is running away with me
Hostelworld (LON:HSW) I'd be interested to know what the average age for a Hostelworld traveller is as i was recommended a very popular group on facebook called interrailing for the older crowd (Currently 25,000 members but it's only one group and a very active one).
It's all ages from what seems 50 upwards and a lot of people enjoy posting their itineraries and fun adventures aroud Europe, with a lot of interaction on postings, and most seem to travel for a month or more more budget conciously, so no hotels really.Perhaps it's a smaller but growing hostelling segment of people reliving their youth or just making a grand old time go a little further.
Could be a nice day for me tomorrow - Sky News is reporting that OnTheMarket (LON:OTMP) (I hold) is about to announce an agreed takeover bid from the US for £100m, which I've worked out implies a bid of c.125p. Sky says it's a "substantial premium", from the current 70p. Annoyingly, I was going to buy some more today, as it's been mysteriously creeping up in price 1-2p every day of late, when everything else was falling. Even more annoyingly, I sold about half a few weeks ago to free up some cash to buy more Plexus Holdings (LON:POS) (I hold), but never mind, a win's a win, even if only half a win!
Anyone else holding OTMP? If so, we should dust down our bunting I think! :-) That's my third takeover bid this year. I cannot remember a time before when small caps have been so bombed out in valuation/sentiment, yet there are loads of takeover bids happening. It seems completely mismatched. Another reason to be bullish I think, when private buyers are swooping on so many listed companies, that's pretty obviously telling us the public markets are too cheap.
Good for you Paul, you must have been feeling a little hacked off after Revolution Bars (LON:RBG) and Sosandar (LON:SOS) updates this morning - a good way to end the day.
Assuming there's only one CoStar (the company mentioned by Sky), they're already a big deal in commercial property including within the UK, I'm sure it's small change buying OnTheMarket (LON:OTMP). I'd be concerned in the longer term if I held Rightmove (LON:RMV), they're vulnerable to attack from a deep pocketed competitor in my view, being very expensive for estate and letting agents, nearly impenetrable for independent property companies not wanting to go through an agent, and then offering a consumer experience (in my opinion) that's not what it could be. [I hold none of the above]
Great news if true I speculated about 3 weeks ago because it had cash and looked so cheap .and was wondering why the price was going up on no news. I’ve used the website and it’s good.
on another angle I listened to the the Sosandar (LON:SOS) webinar and as usual am taken in by their enthusiasm for the product. This may be a good opportunity to invest as a reinvention of the operation . I can understand their logic as remaining online only has limitations they could see from the figures this wasn’t going to achieve their objectives.
i think that the possible clue was in the previous trading update when sales only grew by 10% which I believe to be for growth.
still have cash so we shall see if it works out but it looks cheap
1Spatial (LON:SPA) interim results presentation given by management last week video & podcast.
ARR growing at 10%.
Term license ARR growing fastest at 27%.
Gross margin up to 52% from 22: 50%.
High levels of renewals due in H2.
Final stages of agreeing first 1Streetworks annual licence for major utility.
In line for FY24.
Loss making for now.
In line for the full year.
After updates from #Bellway & #Barratts, the UK homebuilders are getting a real 'shoeing' today.
It is often said that 'stock prices lead earnings, which in turn lead the economy'.
Assuming this is still the case, then AIM must be pricing in a near nuclear winter wrt GDP, jobs & growth.
Sure this is part of the story. Yet equally the index just looks way over-sold to me.
Hi Paul, cant help but agree. Enjoy your podcasts on VOX btw - I was a customer of your precision guided investments a ten years back - it was a similar market and for the brave there were big gains - still think the same will happen this time but its not much fun waiting!
AIM All-Share Index is down 18% since the start of the year. Wowzers.
But is this surprising? The theme of "zombie companies" may be a good explanation. Over the years, AIM has collected all these zombies, and now the day of reckoning is here, they're all dropping like a stone in Share Price and dragging down the index.
Although I note that the AIM100 is also down 18% (and you could argue the top 100 companies are less likely to be Zombies).
Anyone have any stats handy on how many AIM shares go "bust" every year? Would be interesting to see if we have an uptick in 2023 YTD.
I am not sure on that. However, on a brief look I had was that over the years and on a sample of about 3000 listings :
1. 30% of these companies would have lost almost all your money ( so that’s about the same as going bust).
2. About 75% of all these companies would have lost you a considerable amount of money.
3. The annualised total return is a negative 1%-2%.
Revolution Bars (LON:RBG) Its a sorry tale. Walk away. You'd lose less money putting your cash in a Building Society. I can't see any upside for a retail private investor.
Its funny how a bar that plays on The Communists Fidel Castro and Che Guevara really is quite good at taking away money from those bad old Capitalists.
NGHT by far the better option (I hold neither). Taking all of the oversubscription back in May 2021 looks a stellar move now.
Hi Michael,
I'm curious why you think Nightcap (LON:NGHT) looks attractive? It doesn't make any profits either, so not much different to Revolution Bars (LON:RBG) (I hold)! I see little to no attraction in either share (my position in RBG was only a tiny punt, bought recently).
It's such a tough sector at the moment, smaller operators are not going anywhere, unless they've got some key point of difference, such as XP Factory (LON:XPF) (I hold).
With today's news that wages growth has now gone above price inflation again, that should mean that downward pressure on consumer disposable incomes should begin to reverse. Hence the bombed out hospitality sector could be an interesting sector to look at with fresh eyes. The unexpected takeover of Restaurant (LON:RTN) is further evidence that the big money might be anticipating a consumer discretionary recovery, maybe? The companies that have survived, have greater market share too. Although it always amazes me how quickly defunct bars & restaurants seem to be replaced with a new operator.
Regards, Paul.
I'd say Loungers (LON:LGRS) is the right place to be for hospitality, they keep opening glorious sites and I expect them to do very well. the founders' X account is a great place to see what is coming up. https://twitter.com/AlexReille...
Morning Paul - the chart on NGHT looks equally as terrible - so not one I'd be rushing in to buy either!
But if I had to pick I would say NGHT has fresher brands that are growing (and have more potential) whereas RBG currently is paying debt over expanding.
Also think the risk of a placing is higher at RBG than NGHT (though I could be wrong!). Management hold 20% of NGHT too, so entrepreneurial management.
Yes, agree that those who survive may be able to prosper. I'll wait for the trend to turn on any first though.
Nightcap has too much debt and another profit warning is expected (by me!). On top , it has to spend millions on Capex yearly in order to keep its estate.
Another big 0 in the making.
I have owned Revolution Bars (LON:RBG) 7 times, and it is my only speculative "trading" share. Overall I am up 15%, so many thanks to Paul for highlighting along with the risk it brings.
My last purchase is the smallest punt and is now down 50%, I have been trying to walk away for around 3 weeks, including another go today, but my paltry amount of shares could find no buyers at least via AJ BELL. So though it's easier for private investors to "walk away" its not always possible
Think the management have big questions to answer. Borrowing a lot when interest rates were going up to buy a pub business (even though the pub bits doing ok) is bonkers. In the statement it suggests weathering the storm they didn’t weather the storm 6 months ago when buying the pubs.
Liontrust Asset Management (LON:LIO) larger outflows than Jupiter Fund Management (LON:JUP) on smaller AUM. Share price barely moved. CEO review is verbose without being specific. Hmm. My view is that there is a reasonable prospect of making a good return on asset managers over the medium term but the market continues downwards so perhaps keep your hands in your pockets for now.
Yes the fund managers will be a good recovery play at some point. Foresight group (LON:FSG) also looking interesting - down around 20% in a month, but flows are broadly flat (mainly institutional clients who tend to be steadier than retail investors).
Sosandar (LON:SOS) Trading and Stragety update presentation with Q&A from this morning, video & podcast.
A few 'take aways' from watching the above Sosandar (LON:SOS) presentation.
Their own website orders were down 20% in H1 !! I assume that this is the effect of now supplying third party retailers ? I cannot believe that no-one quizzed them on this. To me that shows that they have reached saturation point already. They were all too quick to say that opening their own stores would not effect third party sales, well I would argue that it plainly will. Their mantra, in the past, has been that their market is desperately under served and in todays presentation they give 3 examples of competitors doing exactly the same taking £100 million pa each and one of the founders jumps in near the end to point out that 'there are a lot more than 3 out there' doing the same thing we just chose these 3. I wish them and any holders the best of luck with the plan but i wouldn't be confident myself.
Thanks Tamzin. Another high quality webinar from PIWorld, as I would expect, you're really very good at these!
Must admit, I'm really perplexed by the dramatic change in strategy from Sosandar (LON:SOS) and of course the collapse in forecast profits for FY 3/2024. Makes it almost impossible to value the shares right now.
Although I remain hugely impressed with what the women there have done - creating a completely new brand from scratch, and taking it to profitability, is a phenomenal achievement. But it seems to me the explanations today have a gaping hole in them, in terms of credibility, for profits to have completely disappeared this financial year. That isn't planned, for sure!
So for me, the jury is out currently, although the share price halving in recent weeks is making me more interested in topping up possibly, as it's recovered from setbacks before, and there are no solvency concerns with a healthy balance sheet and net cash.
£150k fit-out for new 1,500-2,000 sq ft shops sounds very light, I think they'll need to pay a lot more than that to get a quality finish. Maybe they're netting off landlord capital contributions to arrive at £150k?
My main worry is that SOS management don't have any experience in physical retailing. They're fast learners, as they've proven before, but take it from me, it's not easy running a chain of shops, let alone making any money from them!
On the plus side, I like that SOS has so much data on its existing customers, it can select physical stores to be located in areas where they have loads of customers. Thus knowing demand exists in that area, and providing a base for click & collect, returns, etc.
A massive distraction for management time though, a chain of physical stores.
Regards, Paul.
Sosandar (LON:SOS) The trading update states that "The Company carefully monitors consumer shopping habits and trends on an ongoing basis. With clear evidence of consumers increasingly shopping on the high street...."
If true, this statement has implications for other retailers.
Edited to add:
I have now found some data from the ONS. The first chart shows all internet based retail sales as a proportion of total retail sales since 2008. Whilst there has been a reduction from the pandemic peak, I think the chart strongly suggests that the long term trajectory has now been resumed. The second chart shows textiles, clothing and footware.
Unless they have compelling evidence to the contrary, I suspect that a move into high street stores is ill judged.
Does anyone know why Focusrite (LON:TUNE) has dropped 9% today on no news?
Does anyone know why Focusrite (LON:TUNE) has dropped 9% today on no news?
It hasn't. That's just what the data feed says, but it was selling at these prices yesterday afternoon.
Supreme (LON:SUP)
There is an interview between CEO Sandy Chadha and Paul Hill this morning with an interesting bit on the full year being in line. With the normally stronger half yet to come it sounds as if Supreme is very much in the under-promise over-deliver camp. Start from 5m 27s in:
https://videos.voxmarkets.co.u...
It occurs to me in the wake of the surprising deal for Restaurant (LON:RTN) that we need to think a little about the difference between bank debt and lease debt. Of course in the lovely IFRS16 all debt is equal and as trading turns down ... the operational gearing destroys a lot of equity, irrespective of the debt. For a long time I have felt this risk is often ignored....and so I haven't really thought too hard about the benefit of using lease finance as opposed to bank finance and ownership.
Obviously leases can be renegotiated. A CVA offers the chance for a wholesale exit in some cases. Both banks and lessors will expect their pound of flesh from equity in a downturn. On the other side though leases offer an avenue for growth that may be richer and thus there are plenty of very successful lease financed franchise businesses like say Intercontinental Hotels (LON:IHG) that have done well. They can trade at high multiples, if growth is consistent. A well run brand is often an attractive badge that guarantees certain performance.... In cashflow terms, a well run brand and a lease finance is a capital lite business model. It's a virtual business with a lot of risk in downturns.....but it iS not without attractions in an environment of rapidly rising interest rates. Esp if it's not really the consumer feeling all the pain. Esp if traditional property finance is hard to get.
So without passing any judgement of the merits of the Wagamama brand etc it is perhaps not so outrageous that Apollo believe they can reinvigorate the brand back to growth and justify paying 9xEBITDA. Whilst it seems odd heading into recession, we don't know how long or severe this recession is likely to be. So far.... the consumer is holding up pretty well. I can imagine that there are a decent number of leases up for grabs and so an avenue for growth for careful management exists and maybe this is the Apollo thinking.
It also strikes me that small would also be an advantage for obvious reasons....having a clean book for one. If you have bought a pub, paid the wrong price, and now stuck with a loan that's costing more, that decision will continue to hold back return on equity for years. Contrast that with a new lease entered today...back book, front book idea. So thinking beyond the impending recession certain businesses will find themselves in a strong position...if their back book is small and they can grow. So yes, actually leases aren't all bad after all. A willingness to enter leases could be rather critical if other finance becomes constrained.
Revolution Bars (LON:RBG) We know how this one ends.
Just bailed on RBG. Turned a £15.1K investment into £2.2K.
Its in its death throws for which the little people come off worse.
Moving on with one's life. No Revenge Trading.
Commiserations to all who invested here. Bad Karma The Management.
Gama Aviation (LON:GMAA) - $131m disposal and return of at least 55p per share for company with EV of 88m per Stockopedia. Any thoughts on this? I picked up a few this morning
Did anyone here attend the Sosandar (LON:SOS) webinar this morning? Was it recorded?
Yes it was recorded, we'll be distributing the recording in due course.
The Sosandar (LON:SOS) webinar is now freely available on Research Tree: https://www.research-tree.com/...
I was heavily invested in Sosandar (LON:SOS) last year, and sold out entirely because I was fed up with their RNS announcements always trying to bury poor figures. I'd had enough of the continual obfuscation in their RNS updates. Unfortunately, I bought back in big on the Sainsbury's deal - thinking risk reward was much more favourable.
Today I sold everything on the opening bell - I didn't analyse the numbers, I didn't look at the whopping loss I had to swallow, I didn't think about the bricks and mortar strategy... I just realised I couldn't trust management at all.
This company repeatedly attempts to obscure less flattering financial numbers, often by burying them within optimistic narratives or focusing on more positive aspects of the business performance.
Being an investor requires trust in the outfit and accurate information to make the most informed decisions. The ongoing lack of transparency, coupled with the noticeable attempts to veil less desirable performance figures, has totally eroded the faith I once had for Sosandar. For me, it's now a bargepole stock - even if the numbers are great, could I ever trust them?
OBFUSCATION - gets my vote for word of the year Favourite ploy of all politicians, and now increasingly all publicly quoted companies
I completely agree moolahcoast. I have a smaller position which I have not yet sold. I wanted to read what Paul had to say. You have summed it up well also I think. I think the move into bricks and mortar makes no sense and will prove to be a huge distraction; I worry about Chinese competition and wonder just how strong is the brand (although my wife loves it); and I dislike intensely the attempt to obfuscate what is clearly a big slow down. This certainly looks like no growth share to me now
I think I will take the pain and sell.
Paul. Thank you for your excellent work. Should Sosandar (LON:SOS) not be rated as black because you have judged it to be a profit warning? (Despite the companies best efforts to mislead its shareholders)
WS, I think Sosandar (LON:SOS) would be a black on Paul's spreadsheet as today's RNS includes a negative profit warning. But it would also be another colour (on the RED/AMBER/GREEN scale) in terms of its prospects at the current SP. Since Sosandar (LON:SOS) have today discarded their strategy since inception, which is presumably because they can see its not working, and are now embarking IMHO on a wild punt to try and achieve success, I see it as a RED even at 13p. But it does have quite a lot of cash and perhaps there is some merit to the change of tack; so AMBER can perhaps be justified albeit I not for me currently.
Hi WarrantStar - yes good point, as it's a profit warning, I'll be recording Sosandar as BLACK on my spreadsheet. I should amend the article to include that, I'll do that now, thanks for the nudge.
Regards, Paul.
Interesting chart action on Ab Dynamics (LON:ABDP. Latest TU was pretty upbeat yet SP down a third from highs. Looks like a trader’s stock nowadays.
Sosandar (LON:SOS) as a dandy myself ;-), I was quick to comment to my wife that the latest TV adverts did not feature middle-aged-woman-friendly long sleeves. A sign maybe of efforts to break out of its traditional segment. Perhaps saturation has led to a pivot into more aggressively competed segments. I won’t be buying the dip.
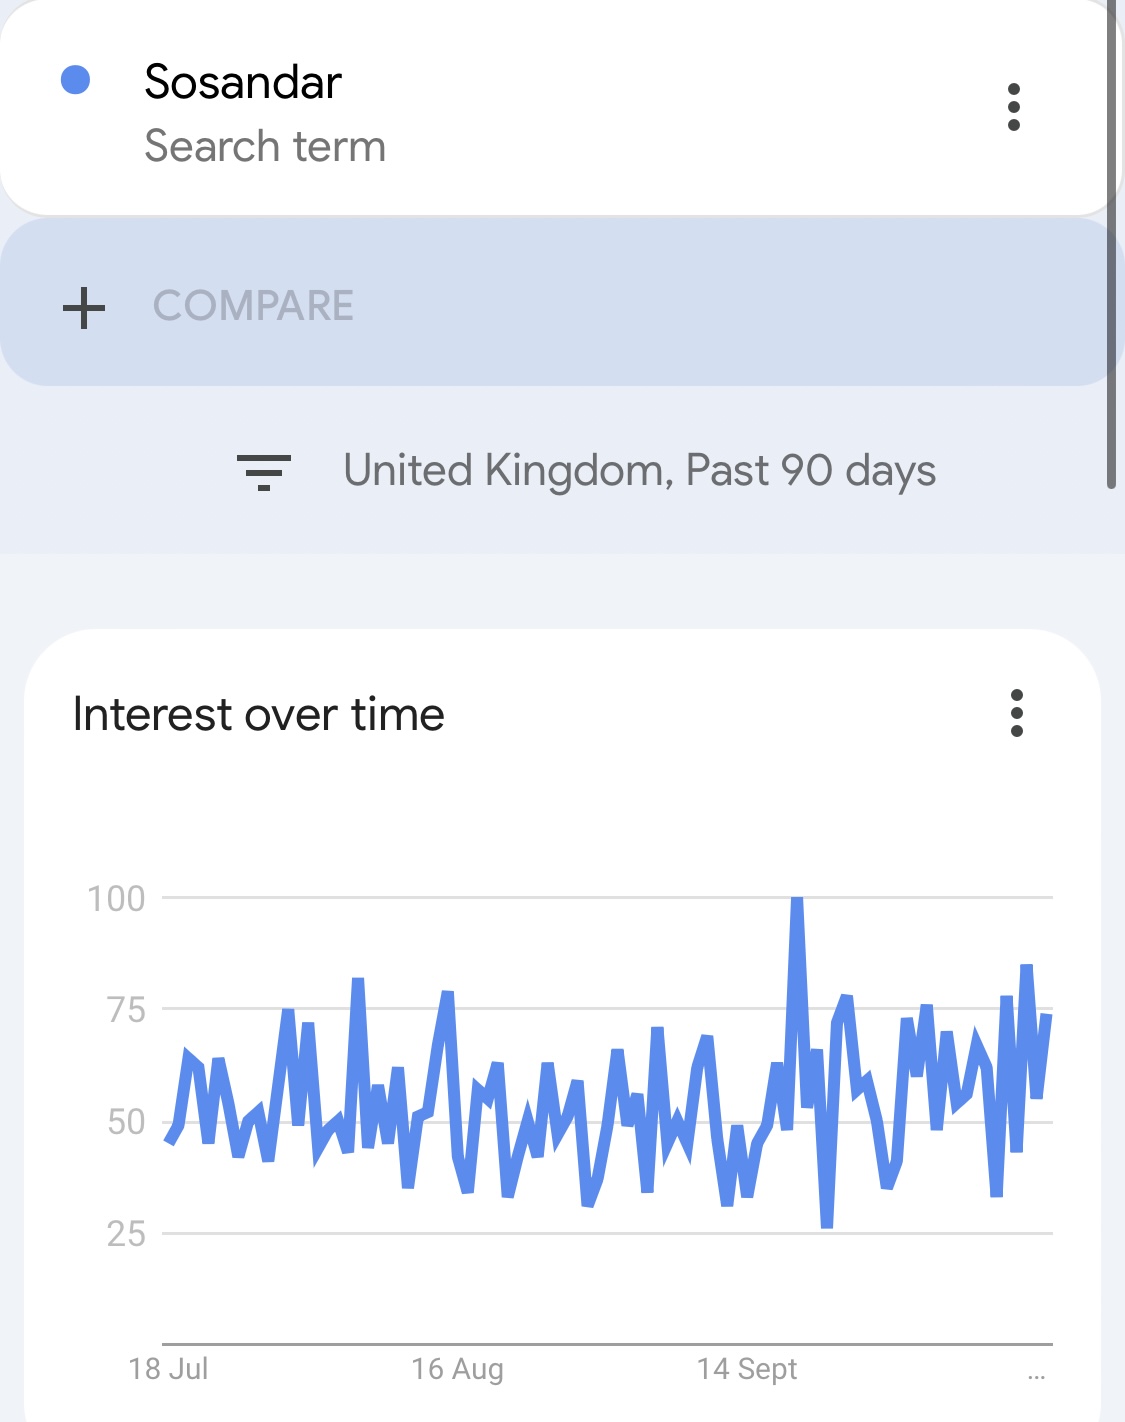
Sosandar (LON:SOS)note on Paul’s comment re tracking website usage. I (infrequently) have a check on google trends, but doesn’t really give the ‘granularity’ for being much use. For example, attached image for Sosandar, uk searches, 90 days. Looks consistent to me, over 12 months and beyond similar too.. does anybody have another reliable, free service which they use for usage tracking? Thanks!!
Ali
Hi, you can gleam a bit more info from SimilarWeb (for Sosandar (LON:SOS or any web based company), but it doesn't go back very far for free: https://www.similarweb.com/web... It does have more comparisons though, which could be useful. Thanks
Start with SimilarWeb for website traffic, and Data.ai for app installs and usage. The two big companies in the market (but by no means the only ones). You get very little through a free subscription though.
Google Trends is actually quite powerful, play around with the different settings.
Then there are other online intel, like customer satisfaction via Trustpilot reviews.
Sosandar (LON:SOS)
Wowsers i thought the communication from theiscompany over the last 18 months or so had massively improved up to troday. On a very quick read i am struggling to make any connection between what they have said and what the brokers are saying will happen based on Pauls post. Perhaps i have missed it but seems like a ludicrously poorly worded update warning i have only had brief read through info so i may have it completely wrong here.
they do offer a medium term cherry to shareholders but if they are throwing away decent real profit short term to acheive the end result it all seems sketchy without explanation. Any plan to deliver 10% to bottom line sounds fantastic.
The aim is tobegin delivering significantly higher gross margins, putting the Company on a
trajectory to deliver pre-tax profit margins of at least 10% in the medium-term.
If this is not a profit warning and the reduction in sales has not affected the bottom line figures and the difference in lost profits is extra expenses due to pivot to their new plan they have communicated this poorly. If this is a profit warning is it in tehir update today as i seem to have missed any bad news here !!
Does not compute - i dont understand why with their chequered history of delivery they would end up going to the bad old ways of not telling us whats up clearly and over promising whilst not delivering on the promise. Perhaps its me being over harsh here - but surely all shareholders simply wanted them to tickover and deliver the £3 mill of real cash profits they promised** the market?
** probably harsh wording here
That’s portmeirion, PCI Pal and now Sos all painting beautiful rosey pictures in the RNS but reducing or missing forcasts via brokers. None have the decency to update their shareholders. All are an instant sell. These small caps can’t be trusted.
Indeed. When things are going well, its easy to appear to be talented/ethical/<insert other good quality here>
Its when the going gets tough that we really see who is genuine. Applies to relationships, work, and also it seems company executives.
Now that Sosandar (LON:SOS) is going to go through a purple patch, would you trust management that shies away from telling the cold hard truth to their ultimate bosses: shareholders?
Or does this illustrate that the founders think that they are superior to other shareholders, and really this is the start of exhibiting behaviour that they only care about and work for themselves and their own interests.
That (small caps can’t be trusted) is my view. I read here because I find it interesting, informative and educational but my days of small cap investing are over (with the right to change my mind of course).
With my investment (all be them small 8.7% of the portfolio on total) in NVIDIA (NSQ:NVDA) Microsoft (NSQ:MSFT) Meta Platforms (NSQ:META) Tesla (NSQ:TSLA) Netflix (NSQ:NFLX) Amazon.com (NSQ:AMZN) (plus reasonable about 20% of portfolio) in Games Workshop (LON:GAW) Berkshire Hathaway (NYQ:BRK.B) up between 10% and 200% I really don’t need the “excitement” of AIM.
Regards
Michael
Well Im in NVDA and AMZN fairly recently = not interesting - yet? Sold TSLA on good gain yonks ago, GAW had since 1916, done very nicely but not much in last year and down most days currently - just my humble take...
GAW obviously 2016!
Its lucky I don’t work in Wilmslow anymore (where SOS has their office) as I’d be banging on their door demanding an explanation for this car-crash RNS and crazy change in strategy!
Sosandar (LON:SOS)
I always thought that Sosandar was a great business, very well run by two people who were in touch with their end consumer. However that was always the problem, their target market was far too small for them to grow to any meaningful size. In the UK the number of potential customers would have been around 3 million.
Yes but a very underserved market. What I find interesting is if they want folk to pay a higher margin why go into Sainsbury’s a cheap clothing outlet?
Sainsburys has not got a good history with guest fashion sellers - the Gok Wan deal did not go well AFAIK
For followers of Oxford Biodynamics (LON:OBD) the latest RNS release this morning continues the recent trend of encouraging updates and looks like very good news for patients in the UK. The company have signed an agreement with Bupa to offer the Checkpoint Inhibitor Response Test for customers with cancer. The announcement is available here.
This is further validation of the Episwitch technology and is unlikely to be the only tie up with an insurance company in the UK or the US or the only test that gets covered.
Interestingly, Oxford Biodynamics (LON:OBD) were very quick to publish frequent sales stats on CiRT earlier this year. Which showed a very good hockey-stick growth in tests ordered.
However, that has been notably absent in the last few months, despite doing quite a lot of announcements. The cynic in me says this might be because CiRT sales have hit a ceiling? That the early hockey stick growth hasn't continued?
This Bupa announcement would have been a great opportunity to mention something like "with over X tests now ordered by Y doctors for CiRT, it is clearly a test in demand".
But they elected not to provide that, even though they have provided this regularly in the past.
(I hold in the Boon Fund)
Oxford Biodynamics (LON:OBD) being set for another placing to fund growth...there will be a chance to get more position at a lower price (likely to pull below whatever placing price they have as market can't stand believing in growth). Could be interesting with aging
Sosandar (LON:SOS) the best but in the update for me, is their tip-off that high st retailers and in particular Marks and Spencer (LON:MKS) are having a good season ‘Sales through third party partners have also been very strong with Next and M&S in particular having a great start to the autumn season.’
Because so many of their competitors have disappeared? And just possibly M&S are finally stocking some clothes that people want to buy?
Kin and Carta (LON:KCT) Offer incoming at a 41% premium. Actual valuation is very low for the sector, reflecting the fantasy nature of the company’s adjustment-heavy profits, and also the current weakness in demand for DX services. I don't hold - it’s a relatively low quality business, but I do hold some competitors.
Positive trading update and vaping safety measures - new note & audio summary here: REPORT
In a Trading Update for the six months to 30 September 2023, Supreme reports strong performance in line with a consensus market (adj.) FY24 EBITDA outlook of £29.0m; matching our estimates. The Group expects H1 24 revenue of above £100.0m (+55%YoY) and (adj.) EBITDA of at least £15.0m (H1 23: £8.1m). Previously, to accompany the 26th September AGM, the Group indicated FY24 revenue of £195m-£205m, and (adj.) EBITDA of £28m-£30m, leading to an increase in our (adj.) EBITDA outlook of 13%. Supreme reports that the Elf distribution agreement has exceeded initial expectations, contributing c.50% of H1 revenue and gross profit growth, whilst all of the other four Business Categories have reported both revenue and profits growth. The Group has guided to FY24 revenue from the Elf opportunity of c.£40.0m and a contribution to (adj.) EBITDA of c.£4.0m.
At the AGM, Supreme had reiterated its awareness of concerns surrounding youth vaping in the UK. The Group has now announced an eight-point series of measures and recommendations designed to “ensure its owned brands do not create any interest from underage vapers” (full details in the body of the note).
Following our recent AGM upgrade, our estimates remain unchanged and Fair Value remains at 200p/share, indicative of a FY24 EV/EBITDA of 8.2x.
Supreme (LON:SUP) Update
The Group expects to report a record performance for the Period, with revenues in excess of £100 million (H1 2023: £67.6 million) and Adjusted EBITDA2 of no less than £15 million (H1 2023: £8.1 million).
Also they are going to adjust the packaging and naming of their vapes to reduce the appeal to underage vaping.
Good morning Paul
Any chance of a very quick brief comment/view onRevolution Bars (LON:RBG) update from yesterday?
If you can it would be appreciated.
Morning oliver,
Yes I've been through the results for Revolution Bars (LON:RBG) (I hold - very small amount, as a trade which hasn't worked) but haven't typed them up yet. I'll get on to that asap, once we've got the urgent news today out of the way. I've got a company call at 11am too, so quite busy today (as always!)
Regards, Paul.
Thank you always appreciated
Revolution Bars (LON:RBG)
debt up from prior update in July and the following text (should be bold red font 48!) says everything you need to know with regard to chances of losing your shirt (or being left with cocktail stained collar only) here. Anyone investing should be prepared to be wiped out
Going concern statement
The continued cost-of-living narrative and economic effects including the impact on consumer confidence means that a material uncertainty exists that may cast significant doubt on the Group's and Company's ability to continue as a going concern.
It is definitely another wipe out-always was anyway.
Yup. there seems to be only one shot through the eye of the needle to survive till 2024: stabilised Revolution trading over the next few months, and a rail-strike-free December and a boom in corporate Christmas party bookings.
None of the three things above seem very certain... but maybe they can pull it off at Revolution Bars (LON:RBG).
It is laughable that when it is sunny, they blame it on poor Revolution performance. When it is rainy, they then complain that Peach Pubs is performing badly. Why would one want to buy a company where, every and any day of the year, the company is struggling?
A good company makes amazing hay most days of the year, and then is able to withstand a few days/weeks of (external, unavoidable) shocks. Revolution doesn't seem to be able to do that consistently.
I wish the Revolution Bars (LON:RBG) RBG shareholders had agreed to the takeover back in the day - 2018 was it? would have saved me a bundle!
I thought something was off. The StockRank didn't show it to be a winner.
Revolution Bars (LON:RBG)
its very fine line this investing mlarky - i was lucky enough to be holder back then and lucky enough to look at what was being offered and made the judegment call that the downside risk if it didnt complete was greater than the upside potential if the sale price was upped. The reality is its all guesswork - i have had other companies i have sold out in similar circumstances where i have missed out on decent extra % so the fact i was lucky here doesnt mean without knowing the future that selling was correct - practicably spekaing though all holders were offered a sensible/decent exit price . What was easier to see was that as trading thereafter was weak and they had material debt practicably speaking there was zero downside protection if things continued to worsen (or stay the same when they started reporting losses) - so it was reasonably clear that as their "margin for safety eroded" and had ever increasing chances of vanishing then ultimately it was no surprise that the shareprice declined to the extent it did . Note that was all pre covid - alebit covid coming thereafter took away any chance of recovery without massive dilution.
Commenting on Paul's analysis... is there really an upside to Revolution Bars (LON:RBG) for small private investors?
Lets say trading recovers, they get back to break-even / profitability. They will still have this big slug of bank debt. Right now, the banks are lenient because they don't want to take control and have to messily restructure / sell it off.
But the moment the trading stabilizes, you bet the bank will be pressuring management to do an equity raise. And with the track record it has had, and the sector being unloved, I think investors would force a discounted placing.
There are a couple of 5-10% shareholders, they'll probably get read-in to accelerated bookbuild at a good discount price. There may be a token open offer to other shareholders.
Alternatively, management and some top shareholders will make a low-ball buyout offer, when green shoots of recovery / upside scenario starts to materialise. Snatching away most of the upside in a full recovery.
So why buy now (and take the risk of a zero in downside scenario) when one could wait for the upside scenario to materialise, and buy after the equity fundraising?
(of course this is all a hypothesis, but one I've seen played out many times with other shares in the past)
Revolution Bars (LON:RBG)
Lets say trading recovers, they get back to break-even / profitability. They will still have this big slug of bank debt. Right now, the banks are lenient because they don't want to take control and have to messily restructure / sell it off.
revolution has in the past had the ability to repay debt quite quickly - if pub chains go into tickover money they can even lose money and still have decent cashflow. Not trying to say they will do anything here but i wouldnt say making material inroads into debt is immpossible if they could get near breakeven
What is clear to me is that pub estates need ongoing "tickover" refurbs to keep the estate at something like max potential for each site - there is the danger if they allocate funds elsewhere or dont have funds to alocate then whole thing could go downhill rapidly if that hasnt already happened. As experienced bar/pub goer over the years its reasonably clear to see where owners have lost then plot and the customers go elsewhere en masse !
if the buisness model is broke even if they get debt down via rights issue it could still go belly up - either way there is so many shares in issue already the upsides are looking less and less appealing the longer they arent turning things around. Thats not to say they have zero chance though of making hay.
My morning smallcap tweet: Sosander pivot, makes divot with sales club.
Supreme (LON:SUP) Let's Explore (LON:LETS) Redx Pharma (LON:REDX) Sosandar (LON:SOS) Oxford Biodynamics (LON:OBD) Pipehawk (LON:PIP) Manolete Partners (LON:MANO) Hostelworld (LON:HSW) Hardide (LON:HDD), Activeops (LON:AOM), Cake Box Holdings (LON:CBOX), Cirata (LON:CRTA), Sigmaroc (LON:SRC), Capital (LON:CAPD)
◄Supreme (SUP)► H1-Sept trading in line. Will make changes to reduce appeal of its vapes to children eg plain packaging, name changes and selling only to retailers with age robust verification. [SP=107.5 Cap=126m]
◄Let's Explore (LETS)► becomes Huddled (HUD) today. [SP=2.05 Cap=4m]
◄Redx Pharma (REDX)► c.£14.1m subscription at 26p, a nil discount, to continue to progress its pipeline. [SP=25.2 Cap=84m]
◄Sosandar (SOS)► to reduce discounting and open shops. That sounds risky. To operate "reduced promotional proposition across all sales channels by the time the stores launch in spring 2024". Will hit rev but boost margins. [edit] So why had Singers slashed FY24 pretax f/c to £0.1m? Targets pre-tax profit margins of at least 10% in the medium-term. Guides FY24 rev up 10% and to remain in profit. Guides FY25 rev up 17%. Signed agreements with The Iconic in Australia and The Bay in Canada to begin selling online in Q4 (Jan-Mar 24). [SP=17.9 Cap=44m]
◄Oxford BioDynamics (OBD)► Bupa UK to cover EpiSwitch CiRT smart blood test for customers with cancer. [SP=34.6 Cap=70m]
◄PipeHawk (PIP)► wins £0.8m order for delivery this FY. [SP=10.58 Cap=4m]
◄Manolete Partners (MANO)► guides H1-Sept profit marginally down due to the reduction in average case sizes and investment in new staff and business development. A warning? Barclays will extend the Bounce Back Loan Recovery Pilot due to Manolete's exceptional results on the initial cases. Another bank to start similar programme with Manolete. [SP=134 Cap=59m]. I hold.
◄Hostelworld (HSW)► hikes FY23 adj EBITDA guidance to €17.5-18m from €16.5-17.0m. Year to Sept rev up 38% and bookings up 43%. [SP=118 Cap=146m]
◄Hardide (HDD)► guides FY-Sep rev £5.5m up 10% and EBITDA close to break even (-£0.9m). In line? [SP=14.81 Cap=9m]
In line: AOM, CBOX, CRTA, SRC, CAPD
Sigmaroc
Trading in line. A good outcome given the economic backdrop from a well managed company. I hold
I particularly like this line:
Cash generation for the Period has been positive with the focus
on de-gearing through to 31 December 2023
For me I’d like to see them not continue to tap up the markets when they have acquisition/investment opportunities, appreciate that the iron needs striking when it’s hot but I’d like to see them focus on debt being significantly lower and utilising cash flows / debt to acquire (but still keep debt lower than current).
outside of that I think the business is well run, with some expertise in place to take them to the next level.
The inflation rate in the United Kingdom remained steady at 6.7% in September 2023, defying market expectations of a slight decrease to 6.6%, as softer increases in prices for food and furniture were offset by a smaller decline in energy costs. Additionally, the core rate, which excludes volatile items such as energy and food, dropped to 6.1%, the lowest rate since January but slightly above forecasts of 6%. On a monthly basis, CPI rose by 0.5% in September, the most since May
Have you ever thought of writing a small caps investing book Paul. I think your wisdom, humour and style would assure best seller status. Perhaps a discount for stocko subscribers !
Yep.
.
That's very kind Fool Hardy, but there just isn't time to take on any other projects, we're so busy doing what we already do!
Although I did once work out that these reports, over the last 11 years, are the word count equivalent of me having written something like 50+ books! Maybe we could get AI to write a summary of all that lot!!
Best wishes, Paul.
I think the life story would be even better half auto biography half stocks, such as when Paul nailed what used to be known as the old daily mirror and got his confidence back and was back on an up. Paul has a fascinating story to tell hopefully one day he will indulge us.
His rambles a few years book about how he flipped books on the market as a young scamp was great as well.
C'mon Paul get the typewriter out as you head to semi retirement could even lead onto a film who would play you though ?
Regards Andy
I remember the days of Paulypilot on Motley Fool .He stood out as a rising star back then
Those were the days! And the Motley Fool socials in that pub on Warren St.
I believe Paul was one of the bios that didn’t make it to the final version of Free Capital (an excellent book BTW) so perhaps Guy Thomas could be persuaded to publish a second volume of those left out in the first book?
I have no way of contacting him though.
Regards
Michael