Small Cap Value Report (Weds 18 Sept 2024) - GLE, KETL, XAR, EYE. Briefs: VEL, CTG, MORE

Good morning from Paul & Graham!
USA interest rate cut is expected later today.
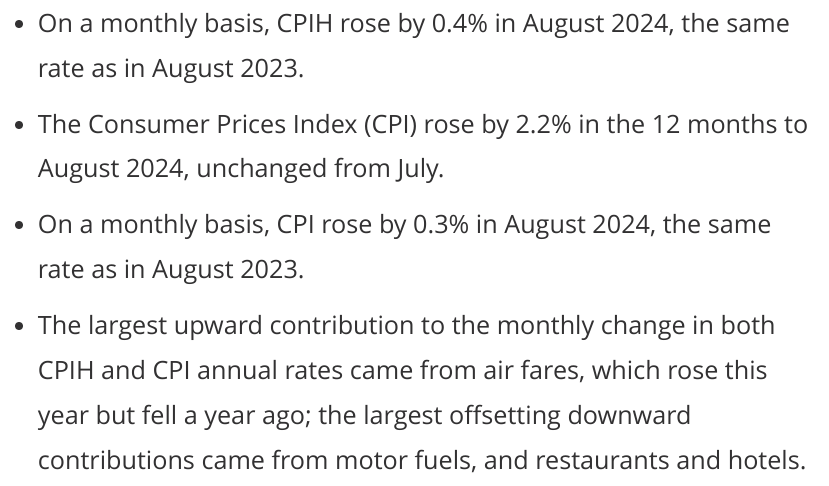
Aug 2024 UK inflation report - snippets of interest -
It's getting very busy now, with a deluge of June half year results coming through. So we'll keep flagging (almost) everything, with in-depth reviews for some of the more interesting items, eg. overs & unders (trading vs expectations), and the companies that you're collectively looking at (as disclosed by the home page "most viewed" widget). To keep expectations grounded, please remember that we can't cover everything in detail.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
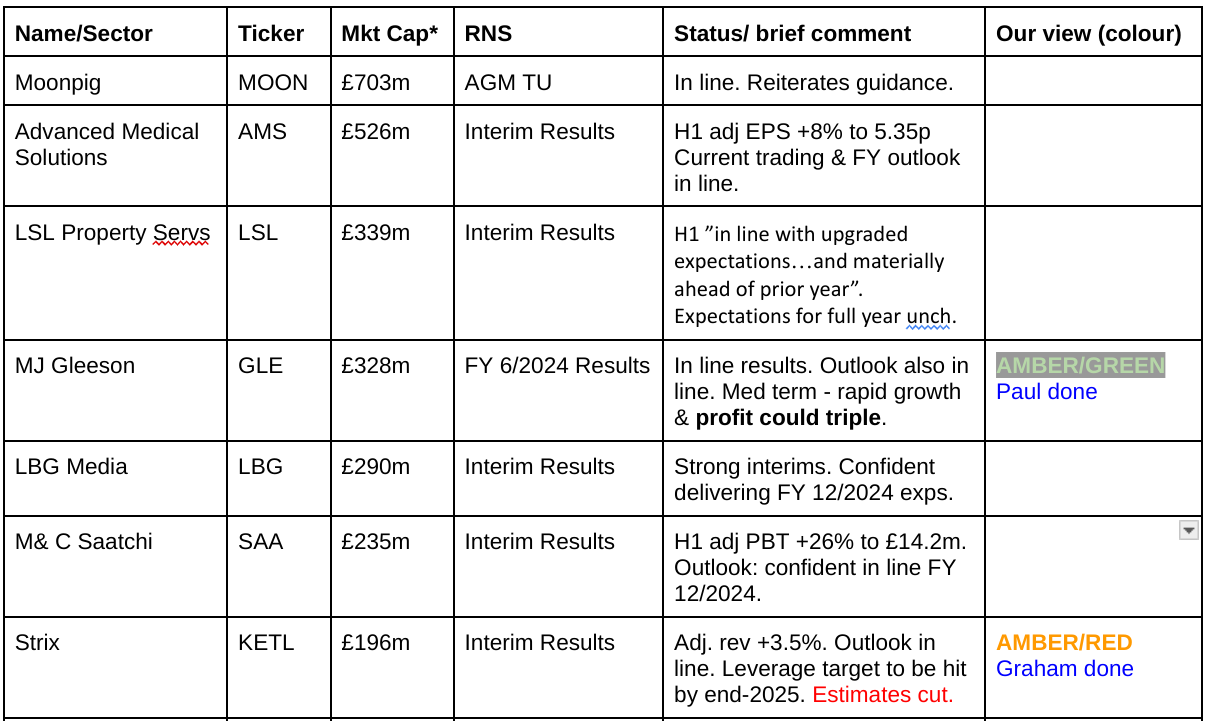
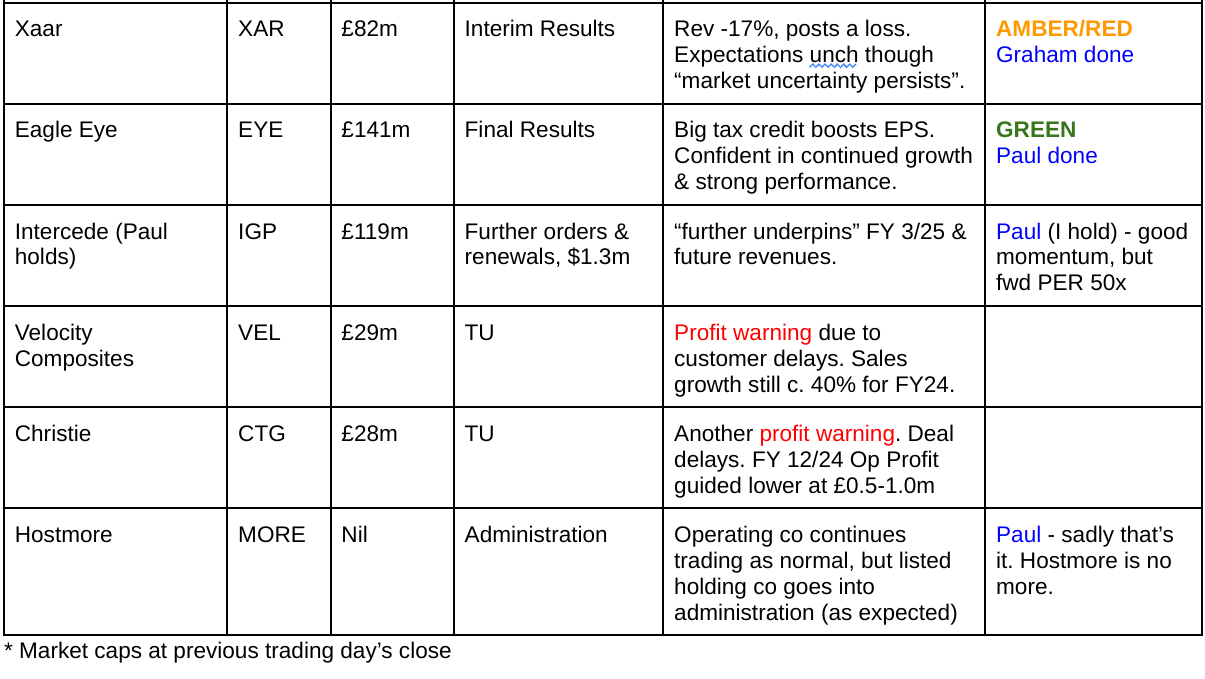
Summaries
MJ GLEESON (LON:GLE) - unch 573p (£328m) - Audited Results FY 6/2024 - Paul - AMBER/GREEN
In line results for FY 6/2024. Outlook sounds upbeat for FY 6/2025, with some signs of customer demand improving. More interesting is the longer term growth planned, with it claiming to be able to triple profits (sounds intriguing). Superb balance sheet too. Political risk:reward not currently clear. I like it overall.
Strix (LON:KETL) - down 3.5% to 80.7p (£186m) - Interim Results - Graham - AMBER/RED
Today’s outlook statement says that the company is on track to report results for FY24 in line with expectations, but if you dig a little deeper you find that forecasts have been cut due to currency and commodity price movements. That’s just one layer of the confusion faced by investors as they try to make sense of KETL’s numbers. I’ll give this one a miss now.
Xaar (LON:XAR) - down 1% to 98.5p (£78m) - Interim Results - Graham - AMBER/RED
Forecasts are unchanged at this printhead manufacturer and the cash balance has slightly improved. But there’s little else tangible good news to be found in today’s release. Profitability is currently very weak and maybe it can improve, but the company itself doesn’t know when this might happen. I’ve been disappointed by this stock too many times and for too long, so I think a mildly negative stance is reasonable.
Eagle Eye Solutions (LON:EYE) - down 4% to 455p (£135m) - Results FY 6/2024 - Paul - GREEN
A wide variety of profit measures for us to choose from! I remain of the view that this seems one of the best growth companies on AIM. As always valuation is tricky, but it seems to have a successful niche service, with an impressive client list. Continuing good organic growth. I like it. Notes also below from a chat with management today.
Paul’s Section:
Eagle Eye Solutions (LON:EYE)
Down 4% to 455p (£135m) - Results FY 6/2024 - Paul - GREEN
One of my favourite UK growth companies, EYE is a global SaaS company, primarily serving retailers (especially large grocery chains) with complicated customer personalised reward schemes. So think in terms of the loyalty apps for ASDA, Morrisons, Waitrose in the UK, and Leclerc in France, Woolworths in the US, etc. Offers and rewards are targeted to individual customers, using machine learning - eg it won’t offer you promotions on cat food or alcohol, if your previous spending shows that you’re a teetotal dog owner.
Very impressive clients, and sticky too - with almost no churn, and recurring revenues (which tend to grow as customers expand their use of the EYE platform). I had another catchup today with the CEO & CFO, and think I understand the business model a bit better now. Clients that use the EYE service are able to increase customer basket sizes, and frequency of shops, using personalised promotions. This gives a payback of about 7x for grocery retailers, and 4x for brands. Hence it’s clear why customers like the service, and keep using it. EYE has demonstrated impressive growth in recent years (mostly organic), as it wins new clients all over the world. Hence why I like this share. The difficult bit is how to value it, as mentioned before.
Earlier this year our SCVR reviews have been -
19/3/2024 - GREEN (Paul) at 570p - good H1 results, but valuation tricky. Cashflow not great.
29/4/2024 - GREEN (Paul) at 470p - Tesco has signed up for 1-2 year contract (Clubcard challenges) - impressive win. Shares are expensive, but could be worth it.
23/7/2024 - AMBER/GREEN (Roland) at 482p - FY TU - adj EBITDA ahead, buy revenue behind. Strong recent contract wins.
FY 6/2024 Results
Eagle Eye, (LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing, is pleased to announce its audited results for the financial year ended 30 June 2024 (the "Year").
“Strong growth in ARR and EBITDA, exiting the year with increasing win momentum”
Revenue up 11% to £47.7m
79% of revenues are recurring (very good)
Annualised recurring revenue at year end is £39.7m (up an impressive 19%, as recent contract wins start contributing)
Adj EBITDA up 28% to £11.3m, but this is not a real number, as a large element of the payroll is capitalised.
Adj PBT is much lower at £4.5m, and this is only up 4%
Note that a large £2.8m (£2.4m last year) shares based payment is adjusted out.
Statutory PBT is much lower again at only £0.7m
A big tax credit of £5.0m (recognising previous tax losses as usable) boosts PAT to £5.7m, and heavily skews EPS to a meaningless 19.5p, so we need to ignore EPS at this stage, or recalculate it to normalise the tax charge.
Quite a mixed bag there, with a very wide variation of profit measures, depending on which measure you prefer. I tend to favour adj PBT, whilst bearing in mind the management share schemes are very generous.
Outlook - more of the same, good growth in the pipeline -
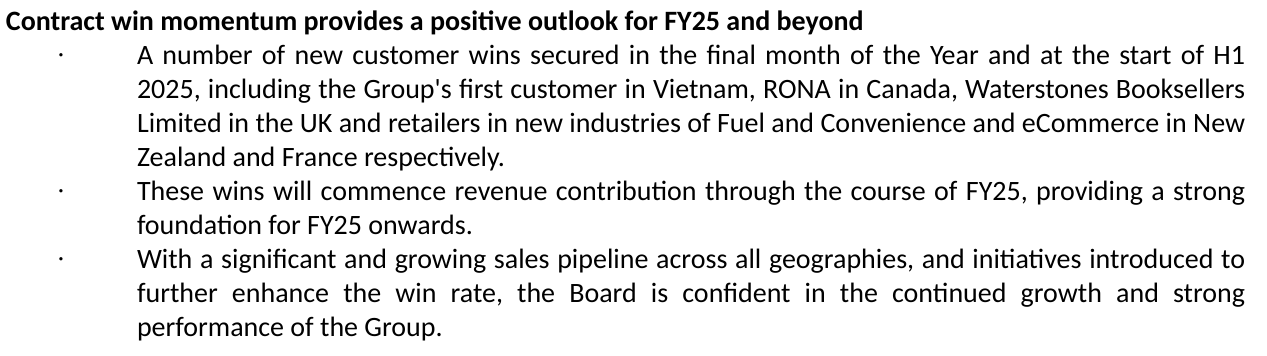
“The Wins achieved at the end of FY24 and into FY25 mean we anticipate significant ARR growth in the year ahead. While this will naturally take time to flow through to revenue, the inherent operational leverage in the business means that over time the overall financial performance of the business should be very powerful.”
“Our ambition is to grow the business significantly, with our medium-term goal to achieve the next milestone of a £100m revenue and 25% adjusted EBITDA margin business and the timing couldn't be better - our exceptional offerings position us at the forefront of a global personalised marketing revolution."
Balance sheet - looks fine. It’s about £14m NTAV, including £10.6m net cash, improved by c.£1m from last year end. This looks financially stable to me, and I think EYE should not need to do any more equity raises.
Cashflow statement - isn’t great, as mentioned before, but it’s somewhat hampered by negative working capital movements vs last year. Most of its cash generation is absorbed into development spend & contract costs, so there’s not really much in the way of proper free cashflow at this stage, but I think that should come in future years as growth should see the benefit of operational gearing.
There are no divis, and it did repay about £1m of debt in the year, so work in progress I would say, not yet a big cash generator.
Q&A with management - very interesting, many thanks to the CEO/CFO for their time today. A few points I touched on (this is just my recollection of the gist of what was said, so don’t take this literally please!) -
Outlook comments - a bit unclear, I emphasised that I much prefer a crystal clear “in line with market expectations” statement, rather than waffling around the topic. Partly because it’s quick for us to CTRL+F search for “expectations” in the busy 7-8am hour, but also because more vague wording introduces doubt. They took my point on board I think.
Customer churn - have any customers left? No. Nectar was expected, and previously mentioned, which I recall. So is “land and expand” how things work? Yes, very much so.
Competition - who else is doing this? Plenty of competition from eg CRM companies, but nobody is doing loyalty schemes as a pure play, and nobody doing it as well as EYE.
Contracts take time to set up. Are those costs expensed? No, all new contract costs (and revenues) are deferred, capitalised onto balance sheet, then amortisation starts once the contract goes live (see £2.6m “contract fulfilment costs” in fixed assets).
SMS revenues are small and seem to be fizzling out. Yes, this is mainly JD Sports, and they are switching from SMS messages to other means of talking to customers, which are cheaper.
The slide deck talks about opportunities outside of grocery, in other retail chains. Yes, grocery is best as there’s so much more data, with customers shopping so frequently. Fashion, DIY stores, etc, is less frequent customer visits, but there’s lots of potential.
Given AIM shares are so much cheaper valuations than US & private equity, have you had any takeover approaches? You know we can’t answer that! But we wouldn’t sell out on the cheap.
Any further acquisitions? Always on the lookout, but nothing imminent.
AI is such a buzzword at present - but some people are saying it can be great, but also produce garbage. How do you avoid producing garbage? That’s true for generative AI (language models, although they're getting better), where it’s trying to answer questions. However, our AI is machine learning algorithms, which is very different. Our system builds a ring of products around each customer, based on what you buy. Then it looks for gaps where we can suggest products you might like, thus it allows grocers to increase basket size, and build loyalty. Great, proven payback for customers and brands.
Sales through partner channels is an interesting growth area.
UK small caps stock market still in the doldrums, is it dead in the water? We think it will recover, but don’t know when! Institutions are very supportive, and sometimes can’t buy in the size they want due to market illiquidity. Some private investors tend to drift away in subdued markets.
My overall impression - management seem straight-talking, giving direct answers to my questions. So all good I think!
Paul’s opinion - I remain of the view that EYE seems one of the best organic growth companies on AIM.
Shares have drifted sideways to slightly down in the last 3 years, despite very considerable growth having been delivered, so I think shareholders are now getting a lot more for your money than in 2021.
I would like to add some EYE to my personal portfolio when funds permit.
As mentioned before, it’s a tricky share to value at this stage. £140m market cap doesn’t seem excessive given its impressive growth, big name clients, sticky recurring revenues, and (modest) profitability. Could it become a bid target I wonder? Possibly, who knows. The Americans tend to value this type of business a lot higher than we do, it seems.
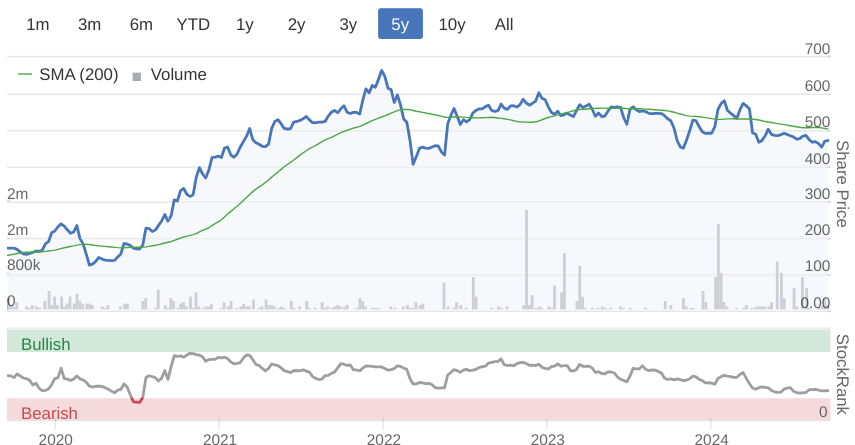
MJ GLEESON (LON:GLE)
Unch 573p (£328m) - Audited Results FY 6/2024 - Paul - AMBER/GREEN
We like Gleeson here at the SCVR. It builds low priced starter homes mostly in the Midlands & North.
Results for FY 6/2024 are as expected -
“Results in line with expectations as Gleeson Homes delivers a strong performance”
Of the two divisions, Gleeson Homes is by far the more significant, with Gleeson Land providing rather erratic, smaller contributions to profit -
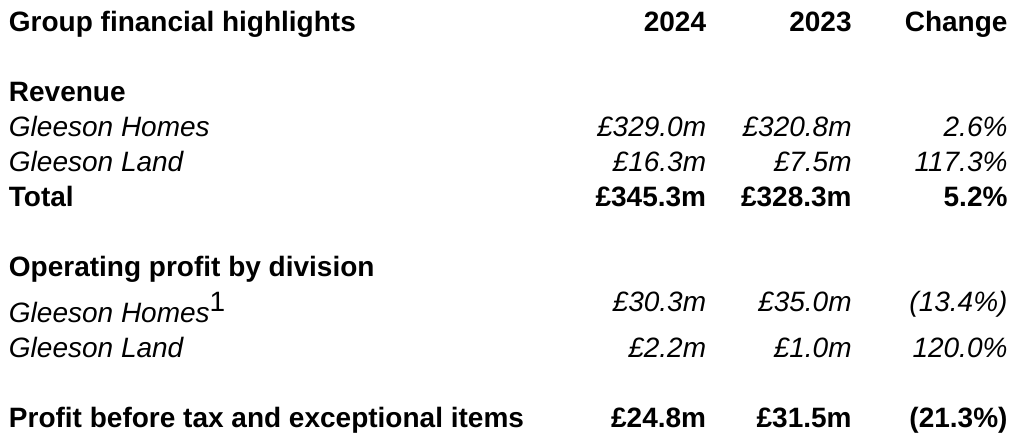
Market conditions have been more difficult for housebuilders, so it’s no surprise that profit is down 21% on the previous year.
As you can see below, forecasts were reduced multiple times as tough macro caused reduced demand, and higher costs -
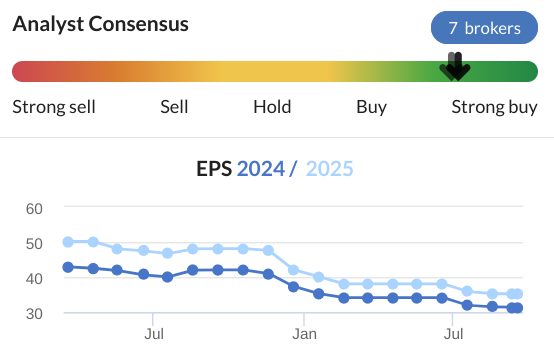
The hope is obviously now that we could be at or near the bottom of the earnings cycle, which is backed up by macro factors moving in the right direction, such as improving consumer confidence, falling mortgage rates, and the long-term structural shortage of decent quality housing.
There are risks with this sector though. The new Govt wants more houses built (good), but is also keen to raise more tax revenues, and had been vocal on the cladding remediation issue, so lucrative housebuilding could come under the beady eye of the Chancellor, to see what additional taxes can be extracted maybe? The rights and wrongs of this are outside the scope of these reports, but personally I don’t want to hold any housebuilder shares until we have a clearer idea of what Govt policy overall will be, and what financial help or cost it all nets off to for this sector.
Outlook - no surprises for FY 6/2024 performance then, what about the future?
Things are starting to improve -
“Gleeson Homes' net reservation rates have been improving and in the 10 weeks to 6 September 2024 was 0.50 per site per week compared with 0.39 per site per week over the comparable period last year, an increase of 28%. Cancellation rates were 0.11 per site per week compared with 0.10 per site per week over the comparable period last year.
With a number of sites close to achieving planning and in sale processes, Gleeson Land is expected to deliver an improved performance in FY2025.”
Note that the last sentence specifically talks about the small Gleeson Land division.
This is the best bit -
“In an improving market environment, the Company is confident that Gleeson Homes will meet market expectations5 for the current year and, more importantly, fulfil an ambitious programme of site openings which, supplemented by a growing pipeline of partnership transactions, will drive the exciting growth planned for FY2026 and beyond.
In delivering our objective of 3,000 new homes per annum, the Company anticipates its profitability could broadly triple and the Company would resume its position as the fastest growing listed housebuilder in the UK.”
That is very interesting, the plan to almost double completions from 1,772 in FY 6/2024, to 3,000 pa in the medium term (presumably). By benefit of it being smaller, GLE has a bigger % growth opportunity vs the larger housebuilders, hence why this share could be a good pick maybe.
It already has a substantial and growing land bank too, so 3k plots pa looks feasible given that it already has over 6 years’ land at that higher sales run rate -
“Land pipeline up by 1,763 plots to 19,138 plots (2023: 17,375)”
Broker update - Singers helpfully updates us. It has FY 6/2024 as 33.0p, rising in subsequent years to: 36.0p, 43.4p, and 49.6p. Those seem modest forecasts, and I would hope to see GLE beat those numbers, given its ambitious growth plans (and talk of tripling profit, which suggests nearer 100p in future earnings - not clear on timing though).
At 573p/share the valuation stacks up on a PER basis, if we assume GLE might be heading towards 40-50p in the next year or two, which I think looks doable.
I also like to combine a PER valuation, with an NTAV valuation at property companies, so let’s look at assets -
Balance sheet - is fantastic, as always. £298m NAV, all tangible. Hardly any fixed assets, so it’s all just a big pile of land, and inventories, in the books at cost. So there’s upside on this number. Hence the price to tangible book is 328m (market cap) divided by £298m NTAV = P/TBV 1.10 - I prefer paying less than book value, but this is tolerable.
Paul’s opinion - GLE looks very interesting, due to its ambitious growth plans. If it does triple profit, then 100p EPS is possible, put that on a PER of say 10x and you’re at 1000p/share - nice upside from the current 573p share. Although that journey is likely to take several years, and things could go wrong along the way.
I want to wait until end October budget, to see if any punitive tax measures are taken by the new Govt. However, I do like the growth story here at GLE, plus the solid asset backing, and its focus on the more resilient low cost end of the market. So for now AMBER/GREEN feels about right, ucnhanged from our previous views on 16/2/2024 and 11/7/2024.
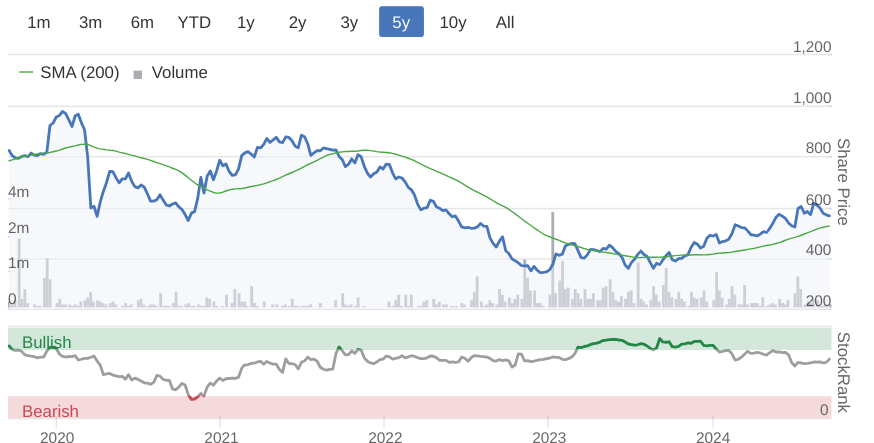
Graham’s Section:
Strix (LON:KETL)
Down 3.5% to 80.7p (£186m) - Interim Results - Graham - AMBER/RED
Impressive results this morning from Strix, if you’re happy to focus on the adjusted numbers.
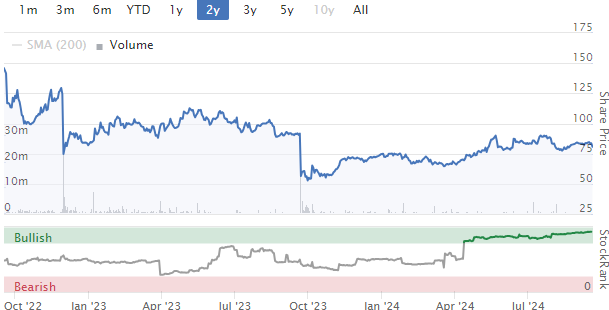
The stock has been on a recovery path:
Here are the highlights:
Adj. revenue +3.5%
Adj, operating profit +9.2% to £13m
PBT +15.9% to £8m
Unfortunately, the unadjusted figures paint a different picture.
At actual exchange rates, revenues increased by less than 2%, and all other growth rates are lower.
The “actual” (i.e. unadjusted) operating profit is a measly £1.1m (H1 last year: £10m) and the unadjusted pre-tax loss is £4m (H1 last year: £5m profit).
More positively, net debt has reduced and this number is not so easy to fudge. Net debt reduced to £69m (as of June 2024), down from £93m twelve months earlier.
The company did get a boost from a £9m placing, which was responsible for some of the debt reduction.
As a consequence, the leverage multiple has fallen to 1.76x, down from 2.66x twelve months earlier.
A leverage multiple of 2x is generally considered safe, although I have in recent years developed some doubts around the underlying quality of KETL. So I think we should probably apply stricter standards to this company than we would to others.
Bank facilities: an £80m RCF (corporate credit card) has been extended to October 2026.
Outlook
There’s a lengthy outlook statement; the punchline is that KETL is on track to report results in line with expectations, “notwithstanding the macro uncertainties”.
The target for the leverage multiple of 1.5x should be achieved “ahead of the end of FY25”.
Against that, there has been “relatively lower trading for parts of Q3”. The company says it is waiting for clarity on sales trends as it moves into peak season.
Estimates
I’m discouraged to see that forecasts have been revised lower by KETL’s brokers/commissioned researchers.
For example, the company’s Nomad has cut the revenue forecast for both this year and next year by c. £3m.
They have cut the adj. PBT forecast by 2.5% this year and by 5.6% next year (new estimates: £23.6m this year, £25.3m next year).
The cuts are blamed on currency and commodity price movements, not on the performance of Strix itself.
It’s another reminder that investors need to get their hands on these research notes if they want to be fully informed, as the RNS itself will not contain all the needed information.
Balance sheet - balance sheet equity is £43m but if you deduct intangibles (£68m) then this goes deep into the red.
Total bank loans add up to over £90m (down from £106m six months earlier). Headroom on the main lending facility is £9m which doesn’t seem particularly high to me.
Adjustments - a key adjustment in the results has been the classification of a subsidiary, “Halosource” as a discontinued operation. This means that losses associated with Halosource (nearly £3m) are removed from KETL’s headline numbers.
However, the decision to dispose of Halosource was only made privately by the Board of Directors in May and I have seen no indication that anyone is interested in buying it. So I don’t think that KETL could argue too loudly if investors wanted to include Halosource’s losses in the figures for H1.
More generally, there are nearly £12m of adjusting items to bridge the gap between actual PBT and adjusted PBT. This is a very large number, so here’s an example of what it includes:
Impairments amounting to £5.8m (HY23: £nil) including tooling/intangibles, inventories and licensing agreements associated with product lines in the Consumer Goods division where the group does not intend to place further commercial focus or allocate resources.
Graham’s view
I previously had a positive view on this stock, but was neutral on it when I covered it last year (in Sep 2023 I was AMBER with the share price at 54.5p).
Paul has been RED on it, primarily because of the poor balance sheet.
My main problem with KETL, apart from the debt load, has been the M&A strategy. If the kettle control business was so good, with long-lasting patents that laid the foundation for a quality business, why make it so much more complicated with acquisitions?
However, I was happy with a neutral stance on it last year, on the basis that management had agreed that debt reduction was the priority.
At this stage, with a market cap of nearly £200m and a share price of 80p, I am leaning more towards a negative view than a positive one, so I’m going AMBER/RED.
The company has been moving in the right direction in terms of deleveraging, and should be available to avoid financial distress, but it is reliant on the refinancing of its bank loans.
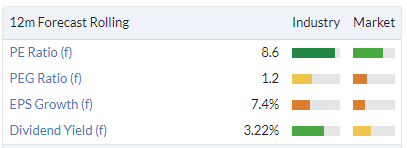
The more fundamental problem for me is that I no longer believe that it has a quality business. If it had kept things simple, then perhaps the kettle control business alone would have generated a fine return for investors. Instead we have an extremely complex situation where the level of adjustment to the numbers is beyond what I feel comfortable with. So I would be happy to avoid this one, even if it’s superficially cheap with a StockRank of 92.
Xaar (LON:XAR)
Down 1% to 98.5p (£78m) - Interim Results - Graham - AMBER/RED
Xaar, “the leading inkjet technology group”, announces H1 results to June.
The company remains loss-making and nearly everything is moving in the wrong direction, except for a small increase in the cash balance:
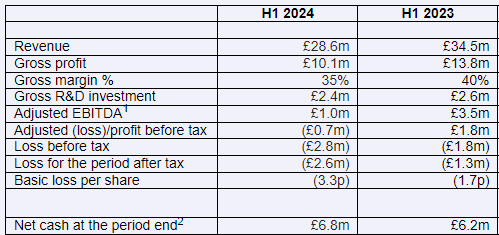
Xaar’s ceramics business is now described as “legacy” (this was previously this biggest contributor of revenues and profits).
Outlook: “Market uncertainty persists although expectations for the full year remain unchanged”.
CEO comment puts on a brave face:
We remain confident in our strategy which is increasingly demonstrating the unique capabilities of our printhead technology. Our pipeline of opportunities has increased in quality in both existing and new application areas and increasing numbers of OEM's are engaged in, or actively planning, new product launches incorporating Xaar printhead…
We continue to focus on the elements of the business that are within our control, enhancing our technology, supporting customer adoption of our printheads, managing our cost base and strengthening our cash position demonstrating the benefits that Xaar's unique capabilities can deliver to customers. We remain convinced of our ability to maximise the substantial opportunity we have.
Graham's view
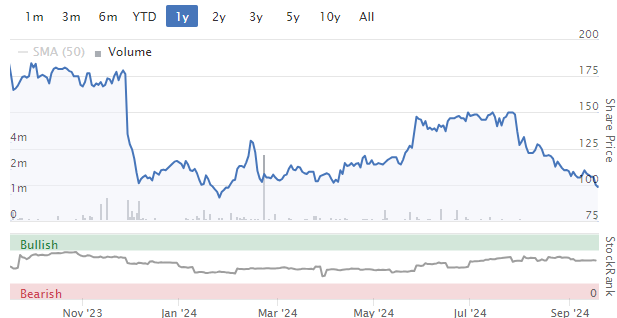
I was RED on this after its Nov 2023 profit warning (share price at the time: 132p).
Paul upgraded to AMBER in March 2024 with some signs of stabilisation.
1-year chart:
As with KETL, I’ll strike a balance today and go AMBER/RED.
It’s not all doom and gloom but Xaar has been around for a while and we’ve learned to expect volatile results due to uncertain demand, sensitivity to macro conditions and product cycles that come and go.
Here’s a classic example from today’s outlook statement:
As sales volumes improve and energy costs stabilise, we expect gross margins to improve in the medium term. We remain cautious on providing precise timing given the current market backdrop and uncertainty caused by economic and geopolitical effects.
In other words: the company itself cannot predict when profitability might improve. So it would be brave for anyone outside the company (such as myself) to make any predictions.
Estimates from Progressive suggest gently rising revenues this year with adj. PBT close to breakeven (£0.4m), improving to £1.6m next year.
But even those adjusted numbers would not be able to support the current market cap.
Perhaps this will work out well for investors, but to me these shares more closely resemble gambling tokens than sound investments.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Strix (LON:KETL) - Investor Presentation video recording
Mark Bartlett (CEO) and Clare Foster (CFO) of Strix Group plc hosted an Investor Presentation covering their Interim Results for the six months ended 30th June. Management discussed key highlights of the period, including an increase in adjusted revenue, gross margins and EBITDA metrics. The team provided a comprehensive Financial overview with the return to balance sheet strength and reduced net debt leverage, as well as details on the restructuring and rebasing of the business over the past few months, streamlining it for the future. Management gave more granular insights on each business category and answered a range of questions submitted by investors.
?si=G8CA-oVWgagbZ7YDGreat write-up on Eagle Eye Solutions (LON:EYE) FY24 results, Paul. Here is the presentation given to analysts yesterday morning video & podcast.
Paul had flagged up the dire straits of PZ Cussons (@PZC), the consumer goods business, at the time of its full year trading update in June. But today’s full year figures - a £83.7m operating loss and a 44% cut in the annual dividend – underscore the parlous state of its business caused by its continued over-exposure to the Nigeria economy whose currency has collapsed.
Back in April the company announced a major corporate shakeup to unlock shareholder value, including the proposed sale of St Tropez, its US beauty business said to be worth circa £100m, and a possible exit from Nigeria.
All it could say yesterday was that the sale of St Tropez was "progressing” and it had received a number of “expressions of interest” in the full or partial sale of its African business. No wonder the shares fell over 12% on the non-news to around 90p.
Progress in sorting out PZC’s balance sheet and Nigerian exposure has been far too slow. Whilst PZ’s relatively new top management team comes with lots of FMCG industry experience, it appears far less well equipped to navigate the political and economic cross currents of Nigeria’s volatile economy.
The only potentially good news was the announcement that Vivek Ahuja, who joined the board as a non exec in January, is taking over as PZ’s senior independent director. He has over 30 years experience in global finance having been deputy group CFO at Standard Chartered bank and currently chairs the risk committee of NatWest Markets.
Hopefully, he might be able to get to grips with the serious exchange rate challenges that have so damaged PZ’s long-overdue recovery plans.
After FY23, the company was talking positively about meeting the rule of 40+ (Rev growth + adj EBITDA margin >40%)
The “real” rule of 40 is for cashflow margin + revenue growth, not some easily manipulated metric like adjusted EBITDA margin. I’m sure it’s a good product with a fine future, but that’s all that is keeping the SP high IMO.
Hi BnB,
It's an interesting concept the real rule of 40, without back testing it feels like a very high bar, do you know of any UK listed companies that pass this test?
It’s a bar that a lot of US high growth stocks hit. But I’m not sure about the UK.
I am a holder in Eagle Eye Solutions (LON:EYE) and think that the long term future is good and the valuation is not expensive. But I think it has to be admitted that FY24 was a disappointing year.
After FY23, the company was talking positively about meeting the rule of 40+ (Rev growth + adj EBITDA margin >40%). This year Eagle Eye has fallen behind this.
Despite the management’s positive spin on the Untie Nots (now renamed Eagle AI) acquistion - there was little growth on the Untie Nota revenue in H2 Vs H1 or vs H2 FY23. As far as I understand, ilno contingent consideration will (now be expected) to be due to Untie Nots at end CY24. The statutory PBT was only positive because of the write down of this contingent consideration.
Despite this FY24 performance, I hope the Shore forecasts (on Research Tree) upto FY27 can be met (which shows Eagle Eye hovering around the 40% level). The recent contract wins gives me comfort that momentum can be reinvigorated in FY25.
Creo Medical (LON:CREO) announce “Transaction to establish Strategic Partnership with leading global endoscopy manufacturer”
Slightly strange timing (at 12 noon) but it does explain the rise in share price. Q2 results are due around now so they could be interesting (I hold).
https://www.stockopedia.com/sh...
LSL Property Services (LON:LSL)
I was wondering whether anyone has any thoughts, preferably negative ones, on LSL Property Services (LON:LSL) ?
I first came across it after watching one of the Paul Hill interviews (thank you Paul) but I rarely see it mentioned anywhere else.
There are 3 profitable divisions:
This division has a 40% market share.
There's a net cash position (£33m) and it is cash generative enough to comfortably invest in the business.
The current market cap is £330m and I am hoping for underlying cash generation for the year of c£25m (my calc,)
The underlying business seems excellent and I question what I'm missing. The SV division alone looks like is should justify the current valuation.
Any thoughts would be appreciated.
A
Hi Abtan - can I ask why you would prefer LSL Property Services (LON:LSL) to Mortgage Advice Bureau (Holdings) (LON:MAB1) ? Is it for the SV division which already seems to have a significant market share? Of for the spread of business compared to Mortgage Advice Bureau (Holdings) (LON:MAB1) ?
Looking at the price action since March 2010 the price seems in the middle of a range between 200p and 450p. Do you think that there are reasons for LSL Property Services (LON:LSL) to trade above this range?
The forecast P/E of 13.3 doesn't obviously strike me as lower than its typical multiple so, again, do you see earnings beating forecast or do you anticipate multiple expansion.
Finally, if you run a comparison (I know it's crude) in Stockopedia, Mortgage Advice Bureau (Holdings) (LON:MAB1) looks a better quality business that has previously been much more highly rated and which has slipped quite significantly in price recently (possibly because of the H2 weighting it needs to meet to meet FY expectations - however, it does have a typical H2 weighting and there are good reasons to believe mortgage lending has picked up in the last quarter).
You can presumably tell that I hold Mortgage Advice Bureau (Holdings) (LON:MAB1) having bought in recently at 620p and 610p. So I would be interested to hear your reasons for preferring LSL Property Services (LON:LSL) as I am probably a weak holder of Mortgage Advice Bureau (Holdings) (LON:MAB1)
LSL Property Services (LON:LSL)
Hi Mammyoko
can I ask why you would prefer LSL Property Services (LON:LSL) to Mortgage Advice Bureau (Holdings) (LON:MAB1) ?
It wasn't really a case of one or the other.
Most of my research was simply on LSL Property Services (LON:LSL) and I thought there was value here.
I did of course have a quick look at Mortgage Advice Bureau (Holdings) (LON:MAB1) , but it's quite clear that they operate differently, given that LSL states that its market share of the gross mortgage market is higher than MAB's (10.7% vs 8.3% FY23) and yet MAB's revenue is materially higher.
If it's of interest LSL have a JV called Pivotal (they own 47% of it) focussing on the B2C segment, so I imagine that they have seen MAB's success and want some of it. The ex-CEO of LSL (and 7% owner of LSL) recently left the board of LSL to focus fully on growing Pivotal.
---
I don't really look at share price ranges or P/Es so I can't really answer your next question I'm afraid.
As I mentioned before, however, if I look at each individual division and apply what I see as reasonable Operating Profit multiples, which I know is subjective, then the Sum of The Parts (SOTP) just seems too low.
For 2 of LSL's divisions - Financial Services and Estate Agency - I did work out the Operating Profit multiples of both Mortgage Advice Bureau (Holdings) (LON:MAB1) and Property Franchise (LON:TPFG) , and then reduce these both by 5 for my SOTP calculation - the LSL divisions are both comparatively smaller and therefore should not be trading at a premium.
For the Survey and Valuation division I assumed an Operating Profit multiple of x10.
With a 40% market share, and with it being so profitable, I would hope/assume that it is not lower than this.
---
On your point about comparisons, the LSL Property Services (LON:LSL) business model has changed so drastically over the last 2-3 years, it's hard to even compare it with itself before 2022 and I'm sure the Stockopedia ranks do not reflect the change properly yet.
However, it's very cash generative, has no debt, is growing through self-funded acquisitions and organic growth seems like it's coming - Quality (and Value?) do not seem to be an issue.
A
Hi Paul.
Don’t know if you managed to attend the Journeo (LON:JNEO) IMC but in case you didn’t my summary below.
At a high level super impressed with the ambition, strategy and understanding of their demographic. I’ve always been a fan of the management which is one of my reasons for holding.
First lets address the discussion points from yesterday
Then onto other topic highlights for me
Summary - I was a fan before but came away more so. Worth a watch if you haven’t done so. This looks like a potential future multi-bagger to me. Has all the hallmarks of it - growing market, first mover advantage, expanding margins, highly cash generative, attention to R&D, no balance sheet gremlins and expanding SaaS model. So I hope to see big increases in EPS over next couple of years plus a re-rating to a higher multiple reflecting the ARR and company growth prospects. Fingers crossed - I hold and may add if it doesn’t re-rate soon.
Best
David
That's great info, thanks for posting David!
Great to have clarity on the cash/deferred revenue question - we were both partly right, which is a nice outcome ;-)
Indeed Paul :-)
and a great example of why it’s so important to have a proper well reasoned debate. By finding areas of ambiguity we can ask management to clarify and therefore make better decisions.
One edit : they failed to answer my q on whether they genuinely only felt that would do 8p eps in H2 based on broker forecasts. So either they didn’t see it (but said they’d covered everything) or they didn’t want to!! I suspect I got my answer through the silence……….. ;)
Thanks David. Excellent post.
They did also highlight a need to come back to the market in order to fund "transformational acquisitions", which they suggested could be in 2025. Can they double their revenue without that? Probably not. Nonetheless, still a lot to like!
Hi Daniel
What Journeo (LON:JNEO) mgmt said was that they expect to do 50% growth over next 2 or 3 years on an organic basis. So whilst they won’t double revenues in that time if they don’t make any acquisitions they could quite happily double on an organic basis in say 5 years. The market size and opportunity is certainly there.
They also said they may do bolt on / infill acquisitions : I don’t expect them to come to market if they do these. Two or three of these could easily get them close to the extra £25m.
They said that for transformational acquisitions they would likely need to come back to market - but they also said that these transformational deals would possibly well exceed the inorganic £25m revenue target. What’s interesting here is they are signalling an unwillingness to use debt, which lowers the risk in my view. I suspect for a good transformational deal they will be heavily subscribed with little reason for any discount to whatever the price is at the time. I don’t mind them coming to market as long as it is earnings enhancing. That’s what capital markets are for after all.
"We are anticipating one or two acquisitions early in the new year, these will be bolt-on acquisitions. We do have some discussions about transformational level acquisitions, which we may be completing during 2025, but we will need to come back out to the market for those because they are beyond the cash and debt facility".
yep - exactly. Could be a really interesting year.
Hostmore (LON:MORE) mad how fast they have capitulated from floatation to zero very quickly.
I note Shoe Zone (LON:SHOE) are up over 20p in the last week or so. Is it a case of possibly results beating the beaten down forecasts ( as has happened before) or are there other forces in play here?
Also noteworthy is Babcock International (LON:BAB) whose SP has nosedived from 550 to 465p recently. Is this just a reflection of the Harland & Wolf situation?
Disclosure - I hold both
Hi Threepeat,
My suspicion is the following (Planetx might have more evidential input)
1) freight shipping costs have been falling and given this was one of the reasons Shoe Zone (LON:SHOE) highlighted as a reason for the shortfall that could be reversing
2) Chinese manufacturing is struggling a bit so I do wonder if there is a deflationary input cost element being factored in
3) Rumours that the Chancellor will shut the VAT loophole on overseas competitors benefitting from being able to sell ex-vat when the like of Shoe Zone (LON:SHOE) can’t.
The two former should lower costs and offset some of the increased minimum wage impacts. The latter should reduce the benefit of buying from online Chinese competitors - particularly for the likes of shoes, where there is a significant benefit in trying them on/taking them back, or at least it should reduce the risk of online competitors making any significant inroads into ShoeZones market share.
Anyway let’s see. I suspect it is more the forward looking view driving the price rather than anything we might expect in the numbers themselves
I hold a “starter” level of investment in Eagle Eye Solutions (LON:EYE) and given its chart that is just as well! But today’s results seem to confirm my original thesis. The company clearly has a software loyalty system that can impress big and respected retail brands, leading to growing revenue and increasingly sound earnings ( although flattered by tax credits) and cash flow. The outlook is positive and there are already recent wins to underpin the growth projection, the optimism supported by a positive review from Shore Capital. BUT the market hates it, with another 4% down this morning and there is one big question: if the prospects are so darn good why has there been no meaningful Director purchases in over five years?
I will be looking with interest for Paul’s notes on his zoom meeting
Interims out today for Argentex (LON:AGFX) where they have reaffirmed guidance and significantly reduced capex, whilst cash generation was stronger than expected. Strategic progress was positive too, with a licence for Dubai soon to be completed and operational efficiencies being pursued such as freeing up liquidity by renegotiating collateral requirements and licencing agreements. Business remains loss making and is expected to do so in FY25 but management are taking pragmatic, sensible steps and geographic expansion alongside moving into alternative banking is key to materially increasing revenue.
Any thoughts on Argentex (LON:AGFX) H1 results. Were actually quite a bit better than I expected. Think there could be an interesting turnaround here so mulling over timing of taking a position.
Whats hot whats not .
HOT - Transense good update showing fhat its sawsense technology is involved in an 11m project with some big hitters .
Long runway on sawsense but Ryan Maughn starting to look a very credible MD in getting both sawsense and translogic into commerciality .
HOT - Capital , easy to buy in the low 80s seems to be a constant seller and this looks a cracking entry point They are sitting on a few hidden gains that marlet isnt recognising ..
NOT - Vertu and SDG and Speedy , Ive moved to neutral / sell on all these as I think this down “cycle” is going to be cery long and hard and with the middle classes about fo get mullered in the budget hard to see an uplift in cars and fancy wall paper .
Also SDG havent announced a licenze deal for a long time .
Bit late though for new buyers on Transense hopefully a few bought in when it was around a quid .
National world also easy to buy this week at 15.4p .
Capital (LON:CAPD) could be due to David Abery's holding coming on the market, he had ~500k shares and died recently.
Frankly, I don't believe the inflation figures.
It cost me £5 for a coffee and a coke in a Sainsburys (not the cafe, just the regular shop) at the weekend. That would've been £3, maybe £3.50 pre-pandemic. Near 50% for reasonably basic stuff in 4 years, the official inflation figures are nowhere near that.
I think people are living much lighter, spending similar but buying less - I certainly am - remind myself of my Dad with how many times I say 'How Much??'
Meanwhile, across the pond, indoor exercise bike company Peloton charge $95 to "reactivate" the bike if you sell it second-hand. There's also some nonsense about needing to subscribe monthly in order to vary to bike's resistance, plus you get "exercise programs".
Crazy times.
I think you need to understand how the inflation figures are calculated. It uses a basket of goods and services with different weightings, so many products will increase more than CPI and some less. On a personal expenses level the inflation figure is meaningless because it does not reflect how we each spend our money.
Indeed, I spent £3.75 for a small block of cheese at the garage yesterday... Outrageous
Hi Simoan,
Over the last few decades they have changed the basket of goods and services used to calculate inflation. Also hedonics skew the data [If you are getting more utility/pleasure from new version of mobile phone, then they can adjust the price rise as quality improvements].
If you use the old basked of goods and services as done by John Williams at shadow stats, you can see that inflation figures are nonsense https://www.shadowstats.com/
GBP measured against a proper yardstick (Gold):
Yes, I’m aware the basket of goods and services used by the ONS is constantly changing, which on its own makes it measurement meaningless over time. On a personal level, I pay no attention to it, although I recognise that the government needs to use some kind of figure for economic reasons, including state pension increases etc.
Hi Simoan,
Milton Friedman famously claimed that inflation is always and everywhere a monetary phenomenon. Later he clarified that he was referring to episodes of persistent inflation. In the short run, supply shocks can impact the price level. Inflation / currency devaluation deflates debt of course...
To digress slightly: There are various parallels to be drawn with ancient Rome, if you are interested then read this short article. Also this book is excellent.
I read somewhere that a pre-condition for economic prosperity was that citizens trusted their currency.
Friedman, an economist I admire, said that inflation was a form of tax.
Gov'ts can either cut spending (ha!), increase income via raising the tax rates (which will stifle the economy), increase borrowing (which can be dangerous), or inflate the supply of money (which is effectively taxation by other means).
In the past people could store their labour (preserve purchasing power) via holding real money (gold), whereas now if you store your labour via fiat currency in a bank deposit account you will see the purchasing power of your labour diminish over time. That is to say you can't preserve your labour this way.
So a so-called "savings account" at a retail bank that pays some interest isn't really a savings account because the real rate of return (the post inflation return) is a negative figure i.e. inflation is eating away at the capital in a nonlinear fashion (i.e. it compounds over time)
I'm not sure what indebted countries can do at this point. This is all new in the sense that before 1971 we had currencies backed by something tangible (gold). If you look at M1 Supply (chart below) in the United States for example, you can see that about 80% of all dollars in circulation today were printed since Covid...
That should be very interesting and there ia another, Caesar by the two Goldsworthys. Here is a page that has relevance with current affairs. Soon to be assasinated, things went downhill thereon.
Haha thanks Silver moon
https://truflation.com/dashboa...
It cost me £5 for a coffee and a coke
Coffee prices have spiked for idiosyncratic reasons. Nothing to do with general inflation trends.
Price of virgin olive oil has also gone through the roof, not sure why.
It's an eye-watering rise! A litre of Waitrose own brand EVOO just a couple of years ago was £4. It's now £9.50 (insert startled face emoji). But this is less inflation and more climate change - the really hot, dry weather across the Mediterranean in recent years has had a devastating impact on the olive harvest - massively reduced yields - and therefore much less olive oil being produced - supply/demand does the rest. And as the EU produces something like 70% of the world's olive oil, there's not many alternatives. See this article from that must-read periodical, the Olive Oil Times.. https://www.oliveoiltimes.com/...
There is also some that consider seed oils, or the refining of such, is the cause of cancers and obesity which did not exist when we were all scawny little runts post wartime. Saw some 'no palm oil' bread which makes M P Evans (LON:MPE) (I got into when Ukraine was invaded) on the nasty list.
Trouble is when try to find 'non-processed' i.e. in their natural state foods we will end up living on about 10 products. Can't drive anymore, can't smoke and the 'pint' will soon be the 'beer shot' and now can't eat.
The only thing left is gambling on spread betting - hoping gold booms on a 50 points FED cut - well silver actually not so in the 'news'. Used in solar panels don't you know, our future energy supply apparently especially in the Midlands according to Ed. Interestingly Norway still exploring oil and gas fields, so their ability to keep the lights on for those fixated on doonboggles, and increase their sovereign funds is a good plan.
Is a slippery slope
harvest was poor
Agreed. A lot of the basics have doubled in price from what I see. Its much worse than the figures we are presented with.
Miserable Jack, coffee has been going up worldwide, a good part due to the wrong weather in Brazil and Vietnam! CPI would be massively higher if it was just based on coffee and not a v big shopping basket.
True, Arabica coffee futures have surged above $2.6 per pound, reaching new 13-year highs as weather conditions in Brazil, the world’s leading Arabica producer, continue to deteriorate. Brazil is currently experiencing its driest weather since 1981.
However, the coffee price has been quite stable since 2002 (see below chart) if measured in gold (real money). The volatility we see is from the fiat currencies we use to measure the price of coffee (e.g. GBP / USD etc).
Keep in mind that a pound of coffee is still a pound of coffee, and can be roasted and ground up to brew the same number of cups in 2010 as in 2002. A gram of gold is still a gram of gold, and can make the same fillings, or jewelry, or plate the same number of electrical contacts in 2010 as in 2002. In 2010 there is a slight shift in preference in favor of gold over coffee, but we're talking about 15%.
The US Dollar, on the other hand, has lost about 75% of it's purchasing power over the same time period, that is, it takes $4 today to buy what $1 bought in 2002.
Source - PricedInGold.Com
I've been rekoning on the Pound halving every ten years as a rule of thumb which is why all my savings are in shares.
Apparently Robusta coffee is used for instant and Arabica for the beans 'proper' coffee. The Robusta has been hit but don't have the facts. Supply and demand works it out eventually, but its the growers get hit in the 'beans'.
Depends on where you're spending your money. A pint of Carling is £7.25 up the road from me in London, the same pint in Suffolk is £4.80.
In the city of London opposite Leadenhall, I had a lunch of fish and chips with mushy peas that was ok and a pint of London pride for £13. Witherspoons is cheaper than my local which is 40 miles outside of London.
Doombar £3.12 a pint at the King of Wessex 'Spooners in Bath, £1.99 at the Bridge House 'Spooners in Chippenham just to keep the footfall in balance, nothing to do with inflation of course.
You should see the price of my car insurance. Up 20%. No claims. Last year's was up a lot, too.
About a year ago I had contemplated buying shares in Direct Line Insurance (LON:DLG) on the back of the hikes, although shares are down over 1 year. I'm thinking of revisiting that idea.
Hi Mark Not surprised with your insurance experience Re: Auto renew inflation - my car breakdown auto renewal arrived with a 24% increase (They didn't have a valid card so couldn't just allow my inertia to rob me!) I did an online "meerkat" search and it was cheaper that way than the previous year! - SO I phoned. Got told that they could only match quotes from their own website - so I checked while on line AND IT WAS CHEAPER STILL, they couldn't match their own website so the renewal was cancelled and I bought online from their own website. It is a Mad, Mad AI World we are being drawn into. Marketing Inflation
You're lucky, my car insurance trebled this year despite 13 years no claims
Did you compare???
Spent a long time comparing, yes. Managed to get it down to a 2.5x increase by increasing my excess quite a bit.
Strix (LON:KETL) - Deleveraging picks up steam - new research report here: https://www.equitydevelopment....
Today’s interim results to June demonstrated strong progress overall, particularly at the margin level. Double digit growth in the regulated and less regulated kettle control markets was encouraging. Furthermore, the restructuring of the Consumer Goods division and the exit from price sensitive kettle control markets also underpinned the rise in margins. Indebtedness declined markedly, reflecting a combination of firm controls in place, positive cash flow and the placing of 5% of the shares during Q2. However, Q3 has proven volatile within the kettle controls market.
Higher commodity pricing (copper/silver) and a less favourable translation rate (Australian dollar and the Euro versus sterling), are expected to have a wider impact to revenues and profitability from H2. As such we have revisited our financial expectations for FY24 and FY25, resulting in adj. EPS downgrades of c. 6% for both years. We have reduced our fair value/share to 145p (from 167p previously), which represents a premium of 74% to the current share price).
M&C Saatchi (LON:SAA)
Positive interims and confident outlook. Shares remain cheap in my opinion for what is one of the most globally recognised brands in advertising. I hold.
MPAC (LON:MPAC)
Nice looking acquisition. Moving upstream, filling gaps in complete automation line solution offering. Good diversification of client base - overlap is only about 15%. So should help continue smoothing revenues which in turn should hopefully Re-rate the shares to something closer to industry peers
Earnings accretive in first full year. Only slight negative is 4.9% dilution. Not a major issue though in my view - benefits should more than compensate.
Advanced Medical Solutions (LON:AMS) got a shout from Mark Kleinman last night on Twitter/X. Apparently Private equity (Inflexion) running the slide rule over it., no price mentioned or indeed decision whether to go ahead with a bid.
Advanced Medical Solutions (LON:AMS) a decent position for me as it’s a natural takeover target with its enlarged product and geographic footprint following its acquisitions earlier this year. Solventum (NYQ:SOLV) seem to me to offer the best fit and post 3M Co (NYQ:MMM) demerger are no longer constrained. We will see, but AMS will surely be snapped up before too long. .
My morning smallcap tweet: Opportunity knocks, comes in & eats your lunch
Velocity Composites (LON:VEL) Ingenta (LON:ING) Aukett Swanke (LON:AUK) AFC Energy (LON:AFC) Christie (LON:CTG) Intercede (LON:IGP) ValiRx (LON:VAL) Transense Technologies (LON:TRT) MPAC (LON:MPAC) 1Spatial (LON:SPA), Advanced Medical Solutions (LON:AMS), LSL Property Services (LON:LSL), MJ GLEESON (LON:GLE), M&C Saatchi (LON:SAA), LBG Media (LON:LBG), Strix (LON:KETL), Public Policy Holding (LON:PPHC), Xaar (LON:XAR), Argentex (LON:AGFX), Skillcast (LON:SKL)
◄Velocity Composites (VEL)► warns FY-Oct rev only £22.8m+. Blames "delays in both the US regarding the sale of kits to the end customer, and planned production increases in two OEMs in the UK". Wins contract renewal on the A350 programme. [SP=44.12 Cap=24m]
◄Ingenta (ING)► warns FY-Dec EBITDA only £1.8-2m after weak H1. [SP=115.13 Cap=17m]
◄Aukett Swanke (AUK)► warns FY-Sep loss as H2 was only brakeven. PLans extra £1m cost cuts. [SP=1.51 Cap=6m]
◄AFC Energy (AFC)► creates a subsidiary Hyamtec to "commercialise AFC's next-generation distributed ammonia cracking business". It means commercialise the technology surely? And if only AFC was a cracking business! [SP=12.52 Cap=107m]
◄Christie (CTG)► warns FY-Dec rev miss of 5% max and op profit £0.5-1m.. Blames "weak invoicing in its International brokerage operations as previously announced and insufficient growth in its visitor attraction software business". [SP=110 Cap=29m]
◄Intercede (IGP)► wins contract orders and renewals worth over $1.3m. These "further underpin the Group's revenue for FY25 and contracted revenue backlog for future years". [SP=202.13 Cap=119m]
◄ValiRx (VAL)► subsidiary Inaphaea BioLabs signs Evaluation and Commercial Use Agreement with Spain's Xenopat. Inaphaea will be entitled to an upfront fee and % of service royalties on commercialisation. [SP=1.81 Cap=2m]
◄Transense Technologies (TRT)► selected as a partner for Gov't £11m project to develop EV in-wheel motor power electronics. No indication of TRT's share of this. [SP=180 Cap=27m]
◄Mpac (MPAC)► buys Boston Conveyor & Automation for $17m in cash and paper. Expected to be EPS enhancing in the first full year. [SP=430.15 Cap=88m]
◄1Spatial (SPA)► wins €1.5m four year contract renewal with a National Public Authority in France. [SP=58.53 Cap=65m]
In line: AMS, LSL, GLE, SAA, LBG, KETL, PPHC, XAR, AGFX, SKL
MPAC (LON:MPAC) - Earnings enhancing acquisition broadens capabilities - new research report here: https://www.equitydevelopment....
Mpac is acquiring the entire issued share capital of Boston Conveyor & Automation, Inc., (“BCA”), a US-based supplier of robotic automation and conveyor equipment for the Food, Life Sciences and general industry sectors, for a total of US$17.0m (£12.9m).
The purchase comprises US$11.0m in cash, sourced from the Group Revolving Credit Facility, plus US$6.0m from the issue of Mpac shares. The Group’s lender has agreed to increase the RCF by £5 million to £25 million, ensuring that the Group will continue to have a strong balance sheet with significant undrawn borrowing facilities available to fund its ongoing development and working capital.
The acquisition of BCA adds a full range of primary and secondary packaging systems expertise, expands and augments Mpac's positioning in its core Food & Beverage, Healthcare and Clean Energy sectors, and offers opportunities to grow both Original Equipment sales and Service revenue. The acquisition provides a significant growth opportunity into EMEA through Mpac’s sales presence, a geography previously unaddressed by BCA.
The acquisition of BCA is immediately earnings-accretive to the Group, adding 2% to FY24 revenue (pro rata) and 8% and 10% respectively to our FY25 revenue and (adj.) EBITDA outlook.
We take the opportunity to introduce forecasts for FY26 and raise our fair value to 550p/share, indicative of a FY25 EV/EBITDA of 6.7x, which remains at a significant discount to the peer group average of 10.6x.