Small Cap Value Report (Weds 2 Sept 2020) - BOO, CAMB, CRL, ARC

Good morning, it's Paul here with the SCVR for Weds.
Estimated timings - I'm now listening to the Creightons webinar (from noon), and cooking myself a cheese & mushroom omelette. So I'll get on to Arcontech (LON:ARC) after that. Should be finished by 2:30pm.
Today's report is now finished (14:24)
Today's agenda is;
Boohoo (LON:BOO) - my notes from chat with company last night
Cambria Automobiles (LON:CAMB) - Trading Update
Creightons (LON:CRL) - Preliminary Results
Arcontech (LON:ARC) - Final Results
As a reminder, I haven't got time to look at everything each day, so I tend to just select 4 or 5 of the more interesting companies, taking into account where possible reader requests. It's helpful when people post a comment explaining why a company is a good investment proposition, rather than just can you have a look at this, because I happen to own some shares in it!
.
Boohoo (LON:BOO)
I had an interesting chat with Boohoo (LON:BOO) last night. My thoughts here had come to their attention (yesterday's SCVR I assume), so we discussed the current situation. The key points were;
BOO adamant that it has done nothing wrong
Directors/family are exasperated & upset by their reputations being besmirched, and false allegations being thrown around (latest one is they've been falsely accused of people trafficking!) in newspapers & social media
Don't see it as their role to police the entire third party supply chain. Govts bring in minimum wage rules, so Govt's job to ensure compliance across all industries, including fashion sector. Suppliers are third parties, not owned or controlled by BOO. What about Jalal Kamani then? He left BOO some time ago, set up his own business, and is completely separate. Not a supplier. His company just re-packaged some BOO gear made in Morocco - see correction in The Times
If any suppliers are proven to be abusing rules, then they will be dropped
BOO has always been completely open about using UK suppliers. If they had anything to hide, then they wouldn't have told anyone!
Why do you use UK suppliers, when labour is so much cheaper abroad? Convenience, and it's fast. But UK production is relatively expensive, as labour cost so much higher
Competitors are buying garments made in Bangladesh where labour costs 50p per hour - where is the outrage against that?!
Speed to market - is an advantage of UK production. My article was right, in that production in Turkey or N.Africa only takes 5 days overland. However, another option is air freight from the Far East - this is only £1/kilo, so about 50p per garment. This works out cheaper, and almost as quick, as UK production. Hence if more overseas sourcing is done, gross margins will go up, not down! I was right about this, and lots of analysts/commentators got this completely wrong. This blows apart the bear case, in my view.
Is it a family firm still? Very much so. Family & staff who've been with them for the long term work 20 hours per day, flat out, it's that passion & love for the business that has made it so successful. "We've created the best fashion business on the planet", and growth continuing - got 9 brands now, that could be 18 in a few years. No limit to the number of brands that could be added, providing it can all be managed
There you have it, a robust defence from the company. I remain firmly of the view that this supply chain publicity has presented us with a lovely buying opportunity, for one of (maybe the) best growth companies on the UK market.
.
Cambria Automobiles (LON:CAMB)
Share price: 51p (up 2%, at 09:25)
No. shares: 100.0m
Market cap: £51.0m
This is a car dealership chain.
The Board of Cambria provides the following update on its trading for the eleven months to 31 July 2020...
Significant disruption from closure of all showrooms between 24 March - 31 May 2020. Reduced level of aftersales (repair/servicing) remained open throughout. Had a material impact on trading in Mar, Apr, May, despite mitigating actions taken.
Creditors - good to see CAMB is not stretching tax creditors. Companies that are doing this, could be building up problems for the future;
... maintained timely tax payments so that it does not build up a deferred payment liability.
Current trading - June & July trading was positive - "well ahead" of LY & mgt expectations, although has not fully recouped negative impact of lockdown.
Year-to-date 11 months sales -
- New vehicle sales down 27.6% on LY. Margins up - profit per vehicle up 4% vs LY.
- Used vehicle sales down 21.6% on LY. Margins up 4.3%
- Aftersales down 13.6%
- Govt support - drew £3.7m from furlough scheme, and £1.1m in business rates reduction
- Cost-cutting - in the process of "significant reduction" in staffing levels
- Focusing more on luxury cars
Outlook - June, July and August were good.
Cautious outlook comments, mentioning worries about;
- Order book for Sept "building at a slower rate than the previous year"
- Concerned about economy & consumer confidence in Q4
- Furlough scheme ends in October, with expected rise in unemployment & reduced household incomes
- Brexit uncertainty & lack of clarity - a 10% tariff (under WTO rules) would have "a significant impact on sales volumes"
- Emissions regulations mentioned, but not clear how this could impact CAMB?
- No guidance given, due to uncertainty
... potentially challenging economic conditions from Q4 2020 onwards
My opinion - there's almost too much detail in this announcement, but no profit guidance. Therefore I don't know how to value this share, until we have sight of the preliminary results, due out on 25 Nov 2020.
I'm reluctant to rely on broker consensus figures, which look about flat against last year, at c.10p EPS. I've just had a look at flash notes from N+1 Singer and Zeus, which don't have forecasts. Although Zeus estimates that FY 08/2020 profit could come in about 20% below last year (since H1 was ahead, and H2 impacted by covid). That implies about 8p EPS this year. That's a PER of 6.4 times, which looks cheap considering what an unusually bad year this has been.
Maybe there's scope for this share to continue recovering? It's not yet clear where demand for cars is likely to settle, once the pent-up demand has worked through the system? Like others in the sector, CAMB is blessed with lots of freehold property on the balance sheet, hence why this sector is quite interesting - these companies are really hybrid shares - part car retail/servicing, and part property companies.
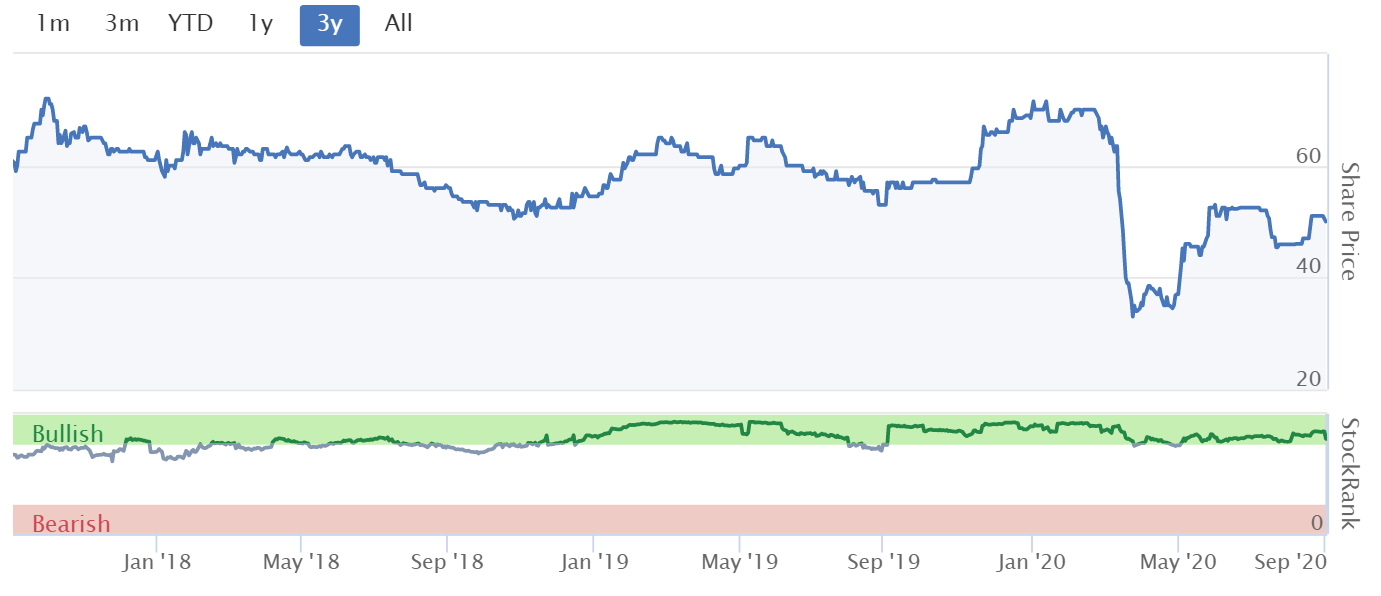
Overall, this looks quite good - asset-backed, and cheap on earnings multiple. One way or another, the issues mentioned as being of concern are likely to be sorted out longer term. Stockopedia likes it too, with a consistently high StockRank over the last 3 years, see below;
.
.
Creightons (LON:CRL)
Share price: 55.5p (up 2%, at 11:18)
No. shares: 64.75m
Market cap: £35.9m
Online presentation - at noon today, so I've just signed up for that. Hopefully there should be a recording afterwards for people who are reading this later today.
Preliminary Results - for the year ended 31 Mar 2020. Note that this will have pre-dated the worst impact of covid, which is likely to fall into FT 03/2021.
Revenues up 9% to £47.8m
Operating profit is highlighted, but I prefer to measure Profit before tax, because that includes the increased finance charges which are sometimes associated with property leases. PBT is up 24% to £3.55m, a good result, and a reasonably good profit margin of 7.4%
EPS - there's a large difference between basic EPS of 4.99p, and Diluted EPS of 4.34p. Note 5 gives the detail on this, and the total share options of 9.5m seems excessive, at 15% enlargement of the existing share capital. That would need looking into.
If we use diluted EPS of 4.34p to take into account potential dilution, then the PER is 12.8 - which seems a reasonable valuation.
Acquired Peterborough freehold site for £4m. Good, I like freehold properties on balance sheets. £3.0m long term loan funded this.
Balance sheet - fixed assets have gone up £3.6m to £5.96m, which I assume is related to the freehold acquired?
Working capital looks healthy, with a current ratio of 2.49 - very good indeed, and includes £2.96m of net cash. I'm happy to ignore the £2.8m long term debt, because this is related to the freehold purchase (it was nil last year).
Overall this is a very clean, and decently strong balance sheet. I don't see any insolvency risk here at all.
Favourable (low) tax rate - note that this boosts EPS somewhat.
Final dividend of 0.5p (up 25% vs LY) - yield quite low though, and note that divis only started again after a long absence in 2017. With the 0.15p interim divi, that's 0.65p for the full year (the narrative in the RNS today says 0.55p, but I think that might be a typo?), a yield of only 1.2%.
To put that in perspective, the quoted market bid/offer spread is 3.0p, so you would need to hold for at least 4 years probably, to recoup the spread through the divis! In practice, you could probably buy inside the spread, but I'm just pointing out that the divis are not a material factor in buying this share, more just nice to have.
Covid - £400k delayed sales for FY 03/2020, and small increased costs.
Post year-end: covid boosted sales from shift to supplying hygiene products, and higher costs to create safe working environment, and;
Trading to the 31 July 2020 is ahead of last year, which has enabled the Group to absorb the increased costs and risks associated with the pandemic.
My opinion - this looks a really nice share. Reasonably priced, with a decent balance sheet, and a good track record. So it gets a thumbs up from me.
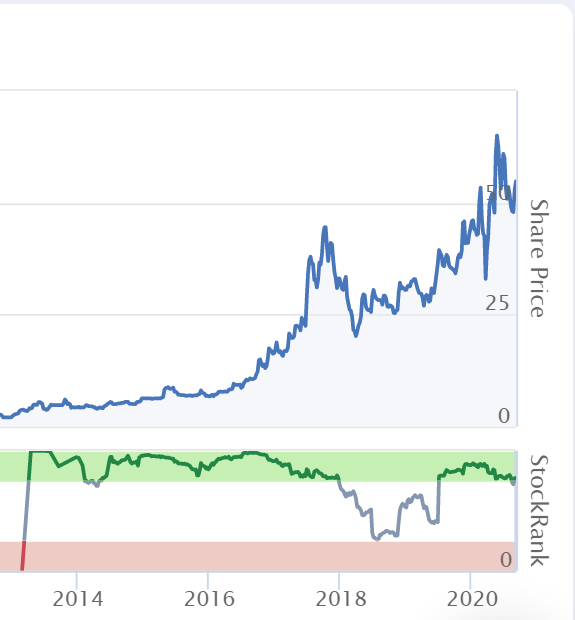
Long term holders have done amazingly well - it was only 2p back in 2013;
.
.
Post Script - the Creightons results webinar organised by our friends at PIWorld was really good. Tamzin hosts these things so well. I found it very informative indeed, and the 3 Directors (Chairman, CFO, Marketing) came across as open, and knowledgeable. Questions were excellent, and answered honestly, it seemed to me. So I feel these are people I could trust, and would be happy to invest in.
I also like the longer term aspirations for the business, to arrive at £100m revenues (doubling from now), and raising the margin from 7% to 10%. That looks do-able, from a mixture of acquisitions, and creating new products internally.
Creightons shares probably won't shoot the lights out, but as a tuck away & forget thing with a 5-year view, I could see investors doing quite well, if management continue to execute well.
Results webinars are absolutely brilliant, I am finding them so useful, and such an efficient use of time. Let's hope all companies engage with investors in this way.
.
Arcontech (LON:ARC)
Share price: 180p (down 7%, at 12:09)
No. shares: 13.2m
Market cap: £23.8m
Arcontech (AIM: ARC), the provider of products and services for real-time financial market data processing and trading, is pleased to announce its final audited results for the year ended 30 June 2020.
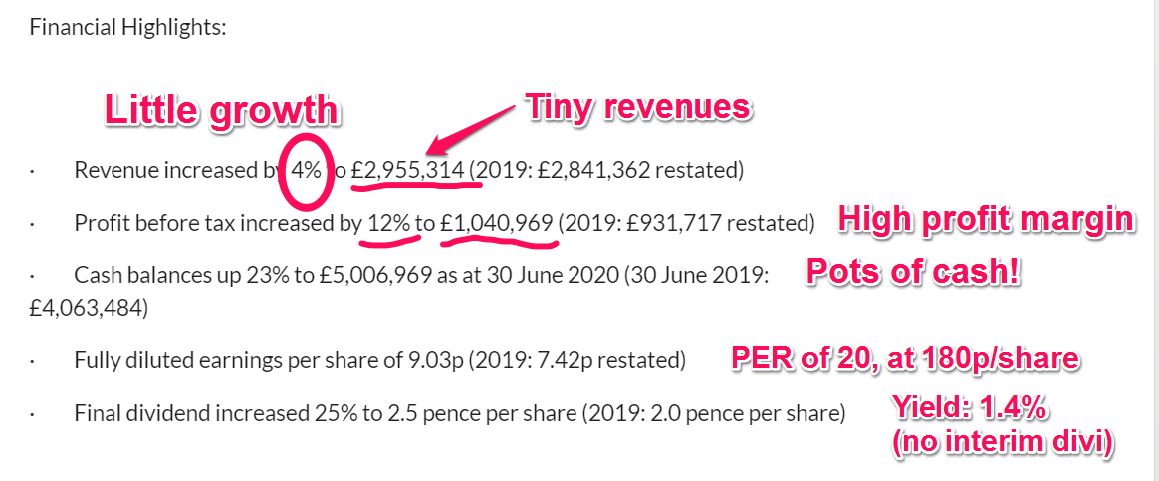
I've never really looked at this company properly, but checking the archive I had a quick look here on 15 July 2020, on the prompting of a subscriber here. At the time I thought it looked potentially interesting, with an unusually high profit margin on tiny revenues, and announcing in line with expectations trading, along with £5.0m cash pile, and the intention of pay a dividend.
Today we have;
Arcontech (AIM: ARC), the provider of products and services for real-time financial market data processing and trading, is pleased to announce its final audited results for the year ended 30 June 2020.
I've done one of these;
.
Revenue is highly concentrated, with the 4 largest customers being 63% of total revenues. Therefore profits could be clobbered if client(s) were lost.
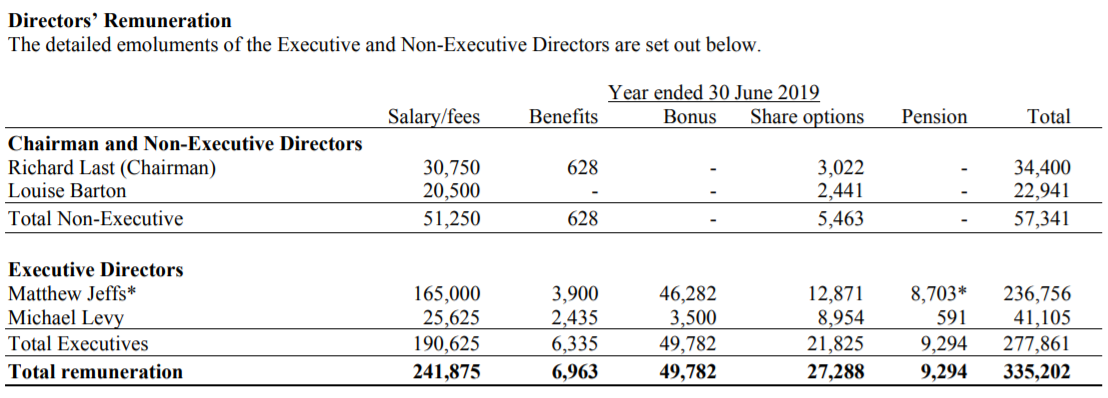
Directors remuneration is basically just the CEO, with scraps for everyone else, including the CFO Michael Levy who must be part-time, I imagine.
.
ARC only has 16 staff in total, including Directors.
It's not at all clear to me why this is a listed company?
Outlook comments - recurring revenues provide stability. Mentions negative macro factors. Long & complex sales cycles. So doesn't sound like there's much prospect of a step change upwards in sales & profits.
My opinion - too small to be listed. Probably over-valued at the moment, given that it's a tiny company relying on 4 main clients.
Mind you, it's decently profitable, and could shoot up if they were to land some big clients in future, who knows.
Overall, it's not for me.
I'll call it a day there, see you again in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
I would be careful not to attach too much importance to the HaloPure technology announcement by Strix (LON:KETL)
Firstly, it is an RCS not an RNS so I would take that to mean it’s not likely to make a material difference to their results at this time.
Secondly, they bought this in from HaloSource. That company basically failed. It was one of Neil Woodford’s disastrous investments.
Thirdly, speaking as someone with a background in use of bromine technology for disinfection, I am not convinced that the HaloSource technology offers sufficient and cost effective enough differentiation over other bromine delivery technologies and alternative disinfectants. I haven’t found information on the amount of AOX and bromates formed (environmentally undesirable byproducts). Nor have I found information on how they would control the level of residual free or total bromine in these applications. Nor have I found information on how, for these industrial applications, this compares with bromine created by reaction of what are basically commodity chemicals, which will be much cheaper, or chlorine dioxide, which will have a better environmental profile, e.g. no AOX formation, for those interested in the environmental performance.
That information may well exist but I couldn’t quickly spot it on their website.
It’s a long way from household water filters, their background, where HaloSource couldn’t make a go of it, to industrial type applications.
Hopefully, for those involved it will be successful. No position myself.
With respect to Boohoo, I wonder if I could provide my perspective as a long term investor as I sometimes think I am in a tiny minority in using this approach. Paul's comments about Boohoo on this site ages ago triggered my interest and after doing some additional research I bought the shares at 33.6p on 12.10.15 and a few more at 50.9p on 19.06.16. Over the years I have been grateful for all the comments from Paul and others on this company as it has made it much easier to assess events at the company. The funny thing is that I have never seen any reason to sell as I was unable to detect that anything had fundamentally changed to make the company unattractive in the longer term. I'm not suggesting that this approach is necessarily a good one but in some ways a buy and hold strategy certainly simplifies investing.
Hi Peter, as Jim slater said, ‘if the story changes for the worse, sell, otherwise dont’ a core tenant for me too
£BOO. Thanks for the call notes! I'm slightly surprised they are able to get airfreight from Asia quite that cheaply given the current capacity constraints...but otherwise pleased to see that my little analysis from yesterday was also fairly accurate!
Agree that this has given us a great chance to buy a great business at silly prices. Happy to have built a nice position at an average of 244p. The strategy of bolting on complementary brands makes much sense. They have retained the buying, design teams for Oasis and others rather than sacking everyone and moving it to the main Boohoo offices, which helps each brand keep its handwriting. Implies they are building for long term success while also leveraging economies of scale on the web platform, supply chain and other back office functions.
Paul/Ed, Is it possible to show any edits to the original scripts in a different colour (red?) This would immediately highlight additions to the text to anyone scrolling through. Rather than laboriously scrolling through finished reports looking for the edit a different colour would jump off the page. Keep up the great work Paul.
Hi cojode,
The interface for writing these articles is very simple (great for my purposes!), and it doesn't have any facility for me to change the colour of the fonts.
In practice, it's unusual for me to add anything extra to sections once they're written. Very occasionally I might do, but only if I'm correcting something that was factually wrong, or some other occasional reason.
Also, I do lightly edit each section shortly after writing it, when I read it back & spot typos or things that I've not expressed very well, but I wouldn't alter the meaning of what I said.
On a positive note, it's great to hear that you're such an avid reader that you notice edits! :-)
Best wishes, Paul.
Hello all, I noticed that Steppe Cement (LON:STCM) today announced that their largest shareholder has raised his interest to 30.8%. I thought this would trigger the "rule 9" mandatory offer but this isn't mentioned in the annoucement. Does anyone know how this works and if he is compelled to make an offer for the outstanding shares?
Steppe Cement (LON:STCM) is registered in Malaysia where the corresponding threshold is 33% .
Many thanks! I had incorrectly assumed the takeover panel rules applied to all companies listed on the UK markets.
Thank you Paul for contacting Boohoo (LON:BOO) founders/owners/managers and writing up the conversation. I wish it could be published to wider audience but at least subscribers here are getting the inside track. It is beyond my comprehension why the media seem to “have it in” for this one particular company. (In the scheme of things what about Imperial Brands or BP or BAE)
As Stock Whittler wrote on Twitter yesterday I am just grateful to The Guardian and The Sunday Times for giving me the opportunity to get back in to Boo at a reasonable price. Having sold (panic sell) in Feb/March at an average of 231p. I never expected to be able to get back in at a “reasonable” price, I have managed to build a 10% of portfolio position at an average price of 307p. Not as good of course as the price I sold at but stilL reasonable.
I was lucky enough to get a 44.2% CAGR (it was Paul who put me on to Boohoo in the first place in 2015) the first time I invested in Boo and while I don’t expect the same growth rate (that would give Boohoo a market cap of £24bil and make it 19th in todays FTSE) but a 20% CAGR to give it a market cap of £9bil in five years time is a reasonable possibility.
Kamani and Kane must have their eyes on the scale of H&M (revenues $22.7bil) and Inditex ($28.8bil).
It is beyond my comprehension why the media seem to “have it in” for this one particular company. (In the scheme of things what about Imperial Brands or BP or BAE).
Not sure BAE or BP would ever call themselves darlings of the media. Banks would happily exchange their media coverage for that of BooHoo. Wetherspoons and Sports Direct anyone? Let's not make BooHoo out to be some angelic exception. It's just their turn in the spotlight and much of the criticism is not without merit.
re Barratt Developments (LON:BDEV) results today.
Over the last week or so I looked at why Persimmon (LON:PSN) had done so much better than the other housebuilders. Pre today the expectation for Persimmon (LON:PSN) 2020 was to be down 17% in volume. Persimmon has a Dec year end whereas Barratts is June. Barratt Developments (LON:BDEV) jun 2021 were expected to be 30%+ lower than 2019 pre today. This looks harsh based on todays statement. Barratts have said today they expect volume to recover in 2021 to 14750 units, a rise of 17% from 12604 achieved in 2020. This budget is still 17% below 2019. However, when you read through Persimmon's outlook they expect the calendar H2 2020 to be in line with 2019, giving room for the guidance to be increased.
What does this mean? All the house builders had very conservative expectations for 2021 except £PSN. It looks to me as though the implications of the combination of updates from Persimmon (LON:PSN) and Barratt Developments (LON:BDEV) leave plenty of room for upgrades, this is why the stocks have risen today. Furthermore, recent quarantine action being taken by the UK government would appear to be positive for the sector. If the UK can avoid local lock downs due to this then build rates should be achievable and so far demand remains robust. Cancellation rates are low and clearly the stamp duty holiday is a positive for demand. If you are a young parent and expect to upgrade to a larger family home in the next 2-3 years you are heavily incentivised to move now.
In conclusion, there will be variances in cost performance and margins achieved between the different players but todays news is supportive of the volume outlook for the sector. I wouldn't worry too much about historic numbers to 30 June 2020. The sector offers decent upside if it catches up £PSN.
Really interesting thoughts RDHOWARTH. I'm a holder of both Persimmon (LON:PSN) & Barratt Developments (LON:BDEV) and have come to broadly similar conclusions.
The great cash position at Persimmon (LON:PSN) is a great source of comfort but I tend to think that Barratt Developments (LON:BDEV) with a current P/BV of 1.04x has potential to re-rate to at least 1.4x from here.
Regards
Paul
Excellent insight direct from Boohoo (LON:BOO) Paul (I hold). Worth every penny of the Stocko sub.
Paul just wanted to thanks for your continued insight into the world of Retail - I certainly have a lot to learn despite my wife working in Finance for CathKidston! This bit is particularly insightful "This works out cheaper, and almost as quick, as UK production. Hence if more overseas sourcing is done, gross margins will go up, not down!"
Not sure i will ever understand the stock market. Arcontech, great set of results, down c7%, Barratt, bad results but optimism up c7%. I also hold Creightons and Strix so a good day today.
All builders went up today, as Nationwide reported:
“UK house prices rose by 2.0% in August, after taking
account of seasonal effects, following a 1.8% rise in July. This
is the highest monthly rise since February 2004 (2.7%). As a
result, annual house price growth accelerated to 3.7%, from
1.5% last month. "
Countryside Properties (LON:CSP) up 5.5 per cent today. That is a big move for this stock (I hold). I wonder if it is time to look again at the property REITs? Buyer of Newriver Reit (LON:NRR) myself below 60p (I hold) as I see a big move as and when dividends restart. Possibly as a scrip dividend in the first year. I do not understand the move in HMSO today myself ; "the market capitalisation of Hammerson will be made up of the existing Ordinary Line, Nil Paid Rights Line and Dummy Call Line"......from todays rns. Hmmmm
cafcash49 I thought the same this morning when I saw the fall having been impressed by the results. There is obviously concentration risk in that they have only a few customers but with 1/5th of mkt cap (5 yrs of PBT) in cash I would have thought that risk is covered. Other salient figures:
Revenue increased by 4% to £2,955,314
PBT increased by 12% to £1,040,969
Cash balances up 23% to £5,006,969
That’s a 90% free cash flow conversion.
Net margin of 30%
That said looking at the trades (I don’t have level 2 or anything fancy, just on Sharepad) I think maybe it is a volume thing with nearly 6 times yesterday’s volume and there was one large trade at the open (assuming I have understood it right, which is not a given) which was more than all the shares traded yesterday.
Buying opportunity?
Regards
Michael
Arcontech (LON:ARC)
4% revenue growth fairly low so today's reaction makes sense.
I think they are ok in the long run. ARC operate in a small niche and sales with financial firms take a long time to bring to fruition. But once in, customers are somewhat locked in as ARC modules are embedded into their systems.
20% of market cap in cash is handy.
I hold a small number.
£arc i evaluated their main product as part of a replatforming for a bank of their market data suppliers, they have a good product but their sales cycle & then implementation, as they say is long and complex but the biggest issue is they are up against Reuters & Bloomberg & other specialists, highly competitive with with a market who dont like changing this piece of the infrastructure. I thought they were good but needed more traction as an investment, that was five years ago, leon boros likes them a lot but they have remained quite pedestrian for a long time.
Short and sweet update from Computacenter (LON:CCC)
it has become clear to the Board that the likely out turn for the year as a whole will be materially above the Board's previous expectations as set out in the Group's Trading Update Statement announced on 22 July 2020.
£BOO. Looking forward to its controlled growth hoping this will not become diworseification. I hold.
Thanks for your notes Paul.
'Diworsification.' Like it. Should be new entry in the translation of the dictionary of management speak!
Diworsification was coined by Peter Lynch in One Up on Wall Street (well worth reading if you haven't done so).
Interesting announcement from Strix (LON:KETL) this morning.
It bought Halo Pure technology from Halo Source for £1m in March 2019. It's now looking to launch a solution to clean water and keep it clean for Chinese automated farms - a market it reckons worth £50m. The "keeping it clean" function is described as unique.
Also, exploring healthcare and dentistry applications having recently appointed an exclusive Chinese distributor.
The market seems to like the news.
Could you look into Concurrent Technologies (LON:CNC) if you get a chance? Thanks
Sorry, I ran out of time, and didn't get round to looking at Concurrent Technologies (LON:CNC) .
Adding to the general £:BOOing that's still going on. I find it ironic that the Guardian et al are attacking a British Company for (horror) buying British goods. I for one applaud them. It gives real jobs to real people who may not have many alternatives. Disclosure I bought on the initial bad news and Paul's elegant commentary.
Hi Berksbee,
Yes, I agree. The end result of the Guardian's vendetta against BOO, is that UK jobs are likely to move abroad, creating unemployment in Leicester, because it's cheaper & now less hassle (not having to actively audit suppliers) to use overseas suppliers. What a counter-productive outcome.
Regards, Paul.
Yes but socialism does tend to lead to counter productive outcomes but people don’t seem to learn!!
The issue is largely about the minimum wage being paid (or not) to Leicester garment factory workers.
Though introduced by Labour in 1999, George Osbourne took the concept further in 2016 with the introduction of the National Living Wage, seeking to wrong foot Labour at the same time.
Personally, I don’t see this having anything to do with socialism, but about political parties of all colours expecting employers to follow the law.
I hold £boo
I hold Boohoo (LON:BOO) but see it as a good thing if the Guardian and Sunday Mirror articles have a positive impact on reducing exploitative working practices in Leicester, on the assumption that such practices exist.
Thanks Paul for sharing your conversation with £BOO. I'm a long term holder (since 2015) so haven't added any in the recent volatility but as you say has been a terrific opportunity for investors to invest in one of the best growth companies in the UK over the last few years. Given it's sizable discount to Asos (LON:ASC) and it's better margins, business model and brands, I would argue that Boohoo (LON:BOO) is still rather cheap.
The ESG angle to me is a very odd one. Why just the outrage if there are social issues on our shores? Why is it okay if Bangladesh, Morocco, Turkey or another third world country does the labour for a ridiculous cheaper price and then if you flying the product over, that's also not very ESG-friendly! If investors truly want to take into account social issues when investing, then a serious chunk of major global companies are uninvestable - Apple (chips/phones produced with poor working conditions), Facebook (poor controls that allow certain countries to rig marketing to influence people's political decisions i.e. Brexit, UK and US elections) etc
The issue with Boo and Leicester is not just about international standards, which clearly are lower elsewhere - though comparison with earnings need to be made with caution, the cost of living in Morocco, Bangladesh etc is about 1/3rd that of the UK. But the issue is that the suppliers of a UK company appear to have been breaking UK employment law. If that is proved true, and that Boo were complicit, then the damage may go beyond reputational. And quite clearly, though bad employment practices globally are a concern, and production being moved to such places is not welcome, it's not an acceptable argument to say we should not worry about it, and about apparent breaches of the law because production might move elsewhere. If we are not prepared to stand up for decent employment practices in our own country then we have next to no chance of bad influencing practices elsewhere.
"Facebook (poor controls that allow certain countries to rig marketing to influence people's political decisions i.e. Brexit, UK and US elections)"
LOL use of Marketing to influence peoples decisions and choices - whatever will they think of next...
I'd always dismissed Strix (LON:KETL) as a boring company, but the announcement today of their HaloTech developments, focussing on water purification and disinfection in the livestock chain in China, coupled with the chart, which looks like breaking out, has prompted me to make an initial buy. Would welcome any thoughts
Hi Donald
I bought into Strix (LON:KETL) earlier this year for my mum's ISA (aka Pension) after seeing it flagged within the SCVR initially, so a happy holder currently.
There were two main parts to the buying decision (aka DYOR). Firstly as an "old fashioned" investor, they make real stuff that I can kind of understand what it is, they have a genuine turnover and make a profit.
The second was the R&D investment into new products and expansion into wider areas which is what today's RNS has highlighted this was very much an opportunity for future growth, which they seem to be delivering on.
As always why did I not buy more? But at the same time good decision and happy to keep holding.
Thanks
Tommy
Donald -
I started buying Strix (LON:KETL) last year after it came to my attention through a PIWorld interview with Stephen English (thanks Tamzin). It is worth watching here https://www.piworld.co.uk/2019/04/17/navigating-the-markets-with-stephen-english-part-2-of-2/ - he describes the company just after 29 minutes in but start from the question at 28:27 in. He describes it better than I can - dull on the surface...strong patents...disruptive new products.
There are some ED reports here https://research.equitydevelopment.co.uk/research/tag/strix-group-plc
Up 10% on an RNS-R looks a bit heavy and takes it to a new high.
Hi Paul,
Any thoughts on £arc please?
Thanks
Morning, Additional request for Arcontech (LON:ARC) please - I hold but don't really understand what they actually do. The largest holder is Anthony Cross of Liontrust, but PA, and the new Chair is Ex-CEO of Group NBT which was enough for me to add a few!
My morning smallcap tweet:
ImmuPharma (LON:IMM) Zoetic International (LON:ZOE) Redcentric (LON:RCN) Oncimmune Holdings (LON:ONC) Pendragon (LON:PDG) Cambria Automobiles (LON:CAMB), Gooch & Housego (LON:GHH)
Immupharma (IMM) £6,5m placing at 11p, a 33% discount, to keep the lights on. [SP=16.5 Cap=30m]
Zoetic (ZOE) sells remaining interest in its oil and gas assets for $20k, net of debt. Also in final negotiations of a second CBD international distribution contract. [SP=17.6 Cap=34m]
Redcentric (RCN) confirms reports of bid talks but is also evaluating potential options in relation to organic growth and/or potential acquisitions that might be made. Expects formal sale process to end by Q4. [SP=142 Cap=220m]
Oncimmune (ONC) has signed an autoantibody profiling collaboration with a leading global biopharmaceutical co to complete in Q2 2021. No £££. [SP=146.5 Cap=93m]
Pendragon (PDG) conclusions of strategy review - cost cuts, efficiency improvements and to grow and diversify Pinewood, a SaaS dealer management system and CRM tool. Also it plans to 'Disrupt standalone used cars' utilising leverage and whatnot. [SP=8 Cap=112m]
Cambria Automobiles (CAMB) June and July trading well ahead of the previous year and management expectations. But "order bank for September is building at a slower rate than the previous year and the Board has concerns around the broader economy and customer confidence." [SP=52.49 Cap=52m]
In line: Gooch & Housego (LON:GHH)
Creightons if you get a chance Paul. Preliminary results out today.
If anyone gets a chance to listen to the Creightons (LON:CRL) Piworld webinar at noon I'd be interested to hear any key points while I'm slaving away at work! Creightons (LON:CRL) are usually quite open in those.
Based on the commentary about the post year end performance I am working on the basis that the higher operating costs (supplier issues combined with warehousing social distancing maybe?) have probably negated any improvement in profit for the current year. The net cash and dividend position is positive though.
from my side net profit, operating profit, revenue all increased. + dividend. All good in my book, this overrides the issues they have had this year. Still a very high ROCE to, and buying out their property albeit with a loan combined with enhanced sales of Pure Touch in the forward months, with COVID not going away.
HI Patrick
I am booked in to the Creightons (LON:CRL) presentation, so kids permitting I will listen in. Being made redundant last week gives me a little more time in life...all though a lot more worries.
I had sold out last week after the delay in results and was pleasantly surprised with the overall tone of today's results with some sections up and some down, when as you noted that the interim report in July could be read as a profit warning (aka down on 2019).
I am thinking about buying back in as a longer term holder, but might let the price drift (downwards slightly?) for a few weeks. So what felt like the traders buying in ahead of results take profits if they bought at £0.47 (or do not get the further upwards spike this morning) and so I can hopefully come back in lower than the exit point.
Thanks
Tommy
Sorry to hear that Tommy. Hope something you want comes up soon.
Thanks Camtab, fingers crossed I have an interview Friday morning it is a large step down from my last role but local, and I think more than one position too, with a lot less travel so has what appears like a lot of benefits right now...
Besides thankfully I went for the "sleep at night" school of investment, and though I only read "Rich Dad, Poor Dad" earlier this year we have thankfully actually followed a lot of its recommendations of making sure we are financially secure as we can be right now so it is worrying, but the house is made of bricks on rock so the wolves cannot get in for a long time :)