Small Cap Value Report (Weds 20 March 2024) - EQLS, XPF, TRST, FDM, WINE, PRSR, YU. . Brief: JMAT & ABDX, CCC

Good morning from Paul & Graham!
Inflation data
Is just out from the ONS at 07:00 - this looks encouraging, I see readers were discussing the forecasts of c.3.5% for CPI yesterday, it's come in slightly below -
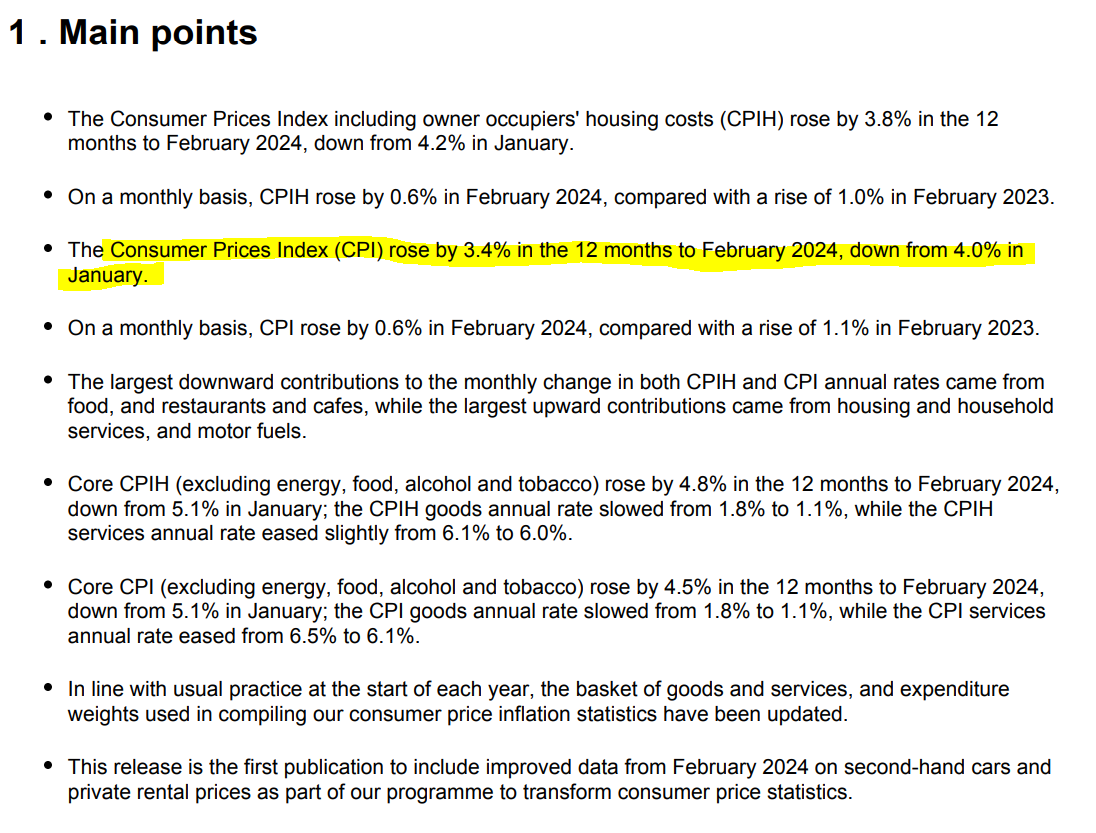
(excerpt above: with thanks to the ONS pdf release at 07:00 today)
Paul's comment - surely this now makes the case for interest rate cuts stronger? Although the Bank of England looks into a lot more data than just the headline inflation figures. Conventional wisdom is that central banks need to raise interest rates to curtail economic activity, when inflation rears its ugly head. However in this case, I think the inflation was mostly caused by supply chain problems during and in the aftermath of the pandemic, and the energy crisis, so inflation would have fallen by now anyway.
There's also a persuasive argument that interest rate hikes in the UK might actually be fuelling inflation. Why? Because the impact on borrowers is mostly deferred, due to mortgages being fixed for a year or two, sometimes more. Meanwhile savers are feasting on interest income for the first time in c.15 years. In the short term anyway, higher interest rates have surely pumped money into the economy, not removed it? Although I don't have any reliable figures on this.
Also higher interest rates are fuelling private rent increases. I'm in exactly that situation with a buy to let, and I've been relaxed about the rent, not increasing it for years in order to keep good tenants. However, now the mortgage is set to more than double, I've had to tell the tenants it has to go up to full market rent, and even that won't cover the increased mortgage. That must be happening throughout the economy, with private rents and mortgage payments gradually rising, creating a hotch-potch of different effects on different households.
The sooner they get interest rates down to something more sensible, say 3.5%, the better. After years of being too low, they've overshot the other way now. This always seems to happen in most economic cycles, nobody making the decisions ever seems to learn, do they? Mind you, economists seem to have little to no ability to predict or plan the economy, so why do we take any notice of them at all?! I think policy is little more than educated guesswork, and very prone to group-think (as Mervyn King has emphasised in his interesting comments on the current situation).
NB. I should add that I'm not an expert in economics, but do understand the basics. It's fun to discuss anyway. In my network I often find that people with basic common sense and business experience can be excellent readers of the economic tea leaves. This was confirmed in the book Superforecasting, which I haven't mentioned for a while, a fascinating read. So don't let supposed experts shout you down, your opinion could be more accurate than theirs!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
It seems like there might be a problem with the RNS this morning, with several people reporting that expected results for some companies have not yet come through.
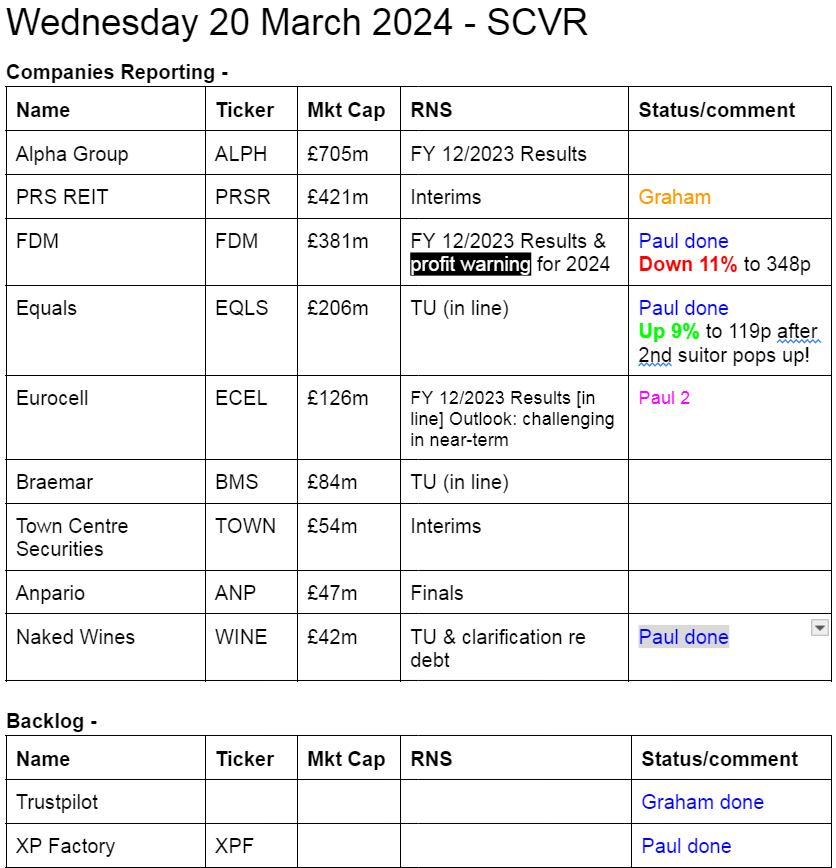
Other mid-morning movers (with news) -
Johnson Matthey (LON:JMAT) - up 8% to 1837p (£3.37bn) - positive market reaction to disposal news (medical device components business) for $700m cash to Montagu Private Equity. Doing a $318m share buyback with some of the proceeds (c.7.4% of its shares). Not a company I’m familiar with, but the value metrics on the StockReport look quite attractive, and it might be worth a closer look maybe?
Abingdon Health (LON:ABDX) - up 24% to 10.5p (£13m) - Launching self-testing products for iron & vit D deficiency, being launched in Boots. Provided by ABDX in partnership with Crest Medical. No financial details, so I can’t add anything here. ABDX has been a serial loss-maker historically, and looks like an opportunistic pandemic IPO in Dec 2020 that’s c.90% down since then. H1 to Dec 2023 showed doubling of revenues to £2.4m, and reduced losses. I suspect it will need another fundraise, as net cash reduced to £1.3m at Dec 2023. So the usual pattern of positive news, then a placing into the spike, looks likely here, a cynic might say. Interim results mentioned it had orders in place from retailers, but didn’t name Boots.
Computacenter (LON:CCC) - down 5% to 2,788p (£3.42bn) - FY 12/2023 Results - PAUL - AMBER.
Adj PBT up 5% to £278m. Adj dil EPS up 3% to 174.8p (PER 15.9x). Outlook - expects an H2 weighting to 2024, due to “challenging” last year comparatives in H1. Bal sht looks OK, NTAV £627m, including “adjusted net funds” of £459m.
Paul’s quick view - good long-term track record, soundly financed, looks like earnings growth is taking a breather. Valuation seems reasonable. StockRank 96. On a very quick review, I can’t see anything wrong with it, other than the update today introduces the risk of a profit warning, given it says expect an H2 weighting. I’ll go AMBER.
Summaries of main sections
Equals (LON:EQLS) - 110p (£205m) - Trading/Strategic Update, PUSU deadline [in line] - Paul - AMBER
A reassuring trading update showing continuing strong revenue growth. Overall it says trading is in line with expectations. PUSU deadline extended yet again! UPDATE: Sky News says EQLS has been approached by Railsr with a proposed merger. Equals rushed out a response, confirming it has received "an indicative non-binding proposal" from a consortium including Railsr and (more importantly) TowerBrook Capital, regarding a "possible offer" for EQLS - so a takeover rather than a merger. Things are getting more interesting!
XP Factory (LON:XPF) - 14.75p (£26m) - Interim Results - Paul - AMBER/GREEN
A previous favourite of mine, but the forecast profits have failed to turn up! Highly misleading presentation of these lacklustre results (a small loss before tax) has undermined my trust in the company. That said, these are good formats, and it could power into decent profits in a consumer recovery, possibly? So on balance I remain moderately positive, but I also flag the downside risks below.
EDIT: See company's response to my article, clarifying the position with lease entries on balance sheet, which I have added below.
Trustpilot (LON:TRST) - 190p (£787m) - Results for 2023 - Graham - GREEN
Great results from Trustpilot as the company moved into statutory profitability for the first time after expectations had been raised during 2023. Another dose of operating leverage should provide a strong tailwind to profit growth in 2024. A share buyback is ongoing.
FDM (Holdings) (LON:FDM) - down 11% to 348p (£381m) - Preliminary Results - Paul - BLACK (profit warning), AMBER on fundamentals.
I have a quick look below at FY 12/2023 results, and its latest profit warning (last one Nov 2023). Business is still slow, and it's maintaining staffing capacity in anticipation of a recovery at some point. Balance sheet is fine, generous divis maintained. I've not yet seen any revised broker forecasts, so we'll have to wait to see what the damage is when consensus forecasts update. UPDATE: Shore Capital (many thanks) has updated, and it's nasty. - FY 12/2024 forecast EPS down from 26.6p to 21.1p, down 21% on already soft forecasts. So the 2024 forecast PER is now 16.5x - not looking bargain unless you factor in a considerable improvement in future earnings. So shareholders have to hope 2024 is a one-off bad year, and not the new normal.
Naked Wines (LON:WINE) - up 10% to 56p (£41m) - Trading & Refinancing Updates - Paul - RED
A clarification update today has helped stem the panic caused by Sky's report on Monday. Delving into the detail below, I'm far from convinced that WINE is out of the woods. Although there is a wide range of possible outcomes I think, good and bad, discussed below. Too much guesswork for my liking.
PRS Reit (LON:PRSR) - up 3% to 78.7p (£432m) - Interim Results - Graham - GREEN
PRSR has the largest portfolio of single-family rented homes in the UK, which continues to grow. Interim results show strong growth in LfL rents (11%) and excellent performance in both occupancy and rent collection. At a big discount to its official NAV, I like this one.
Yu (LON:YU.). - 1480p (£248m) - Final Results (out y’day) - Paul - AMBER
Fantastic 2023 results and a positive outlook for another good year in 2024, so I can see why bulls like this share and keep chasing it higher. As mentioned before, it's whether bumper profits are sustainable in the long run that I doubt. But for now, it's been a terrific share, well done to holders.
Paul’s Section:
Equals (LON:EQLS)
110p (£205m) - Trading/Strategic Update, PUSU deadline [in line] - Paul - AMBER
This is one of the payment services/forex companies, which has moved into meaningful profitability in the last couple of years, after a patchy history previously.
What is the point in the PUSU deadlines that the takeover rules require, when they just get extended over & over again? They’re not really deadlines are they!
This potential bid situation has been ongoing since 1/11/2023. As far as we know, Madison Dearborn seems to be the only party involved, and today EQLS says -
Whilst the Board recognises the time elapsed since the commencement of the Strategic Review, it considers it to be in the best interests of shareholders that the Strategic Review remains ongoing to allow further time for it to reach its conclusion.
As part of the Strategic Review, discussions are ongoing between Equals and Madison Dearborn Partners LLC and, to allow further time for these discussions to take place, the Board of Equals has requested that the Panel on Takeovers and Mergers (the "Panel") extends the PUSU Deadline further.
It will be interesting to see what happens, but as mentioned last time, in my experience the longer things take, the increased likelihood of a deal falling through. However, given talks still seem ongoing, there must be something going on, so maybe a deal might be reached? We don’t know, without inside information, which would mean we couldn’t trade the shares.
More interestingly, we also get an update on trading - which is in line -
The Board is pleased to provide an update on the Company's current trading, which continues to be in line with the Board's expectations. Trading in the first quarter of FY-2024 up to 15 March 2024 (the "Period") has continued the strong growth trajectory of FY-2023 with Revenues in the Period reaching £22.2 million, up from £17.4 million in the same period in FY-2023, representing an increase of 28%. In keeping with recent trends, trading has been robust across the business with particularly strong growth from Solutions.
Paul’s opinion - this sounds reassuring that trading is in line with expectations.
Based on the StockReport, the valuation of 18.6x forward earnings looks fair to me.
It’s a good story, but I’d personally want to see a longer track record of profitability, to be sure that profits are sustainable. Hence why I’ve not invested in EQLS. The story sounds good though, and I’ve been impressed with several webinars done by management. This sector is really all about the crumbs falling from the table of the major banks, who don’t seem to want low margin business, creating an opening for challenger companies who do well out of it. EQLS says that it has created an impressive IT platform, and is used by some larger clients too. Mind you, they all say that.
Overall, I don’t have a strong view either way, and can see merit in the bull arguments. So I’m happy to stick at AMBER. It might make sense to keep some powder dry to buy any dip in case bid talks are called off. Although that would then mean missing out on any bid premium, so it’s a tricky one!
UPDATE at 10:10: Sky News says EQLS has been approached by Railsr with a proposed merger. Equals rushed out a response, confirming it has received "an indicative non-binding proposal" from a consortium including Railsr and (more importantly) TowerBrook Capital, regarding a "possible offer" for EQLS - so a takeover rather than a merger. Things are getting more interesting!
This one has been all about timing -
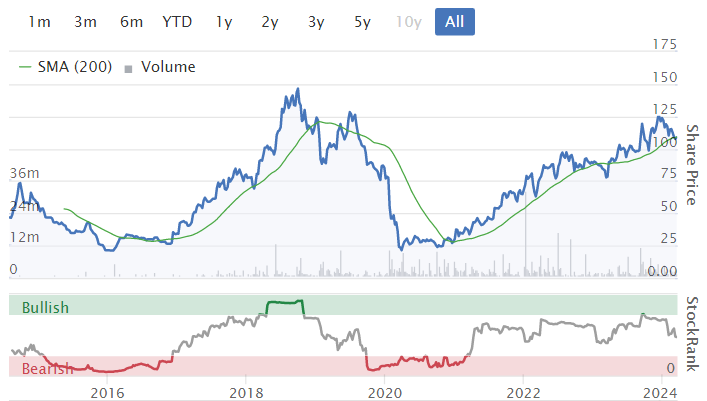
XP Factory (LON:XPF)
14.75p (£26m) - Interim Results - Paul - AMBER/GREEN
XP Factory plc (AIM: XPF), one of the UK's pre-eminent experiential leisure businesses operating the Escape Hunt® and Boom Battle Bar® brands, is pleased to announce its unaudited interim results for the twelve months ended 31 December 2023 ("2023").
(sorry this was meant to be a quick section, but it turned into a full review!)
Note this is a 12-month period, with the old year end of 31 Dec 2023. The current period is being extended to 15-months, in order to move the year end to a more convenient date, as previously reported.
Background - last night I listened to an extremely bullish-sounding interview from Vox, with the CEO (who’s a very nice guy, but that doesn’t matter for our purposes here) on my headphones whilst going for a walk. On returning, I felt highly motivated to look at the numbers. It turned out the figures were far from being a cause for celebration as the interviewer in this company-funded interview presented it. So this is a useful reminder that if the company has paid to be interviewed, it is not necessarily honest or accurate commentary, and in this case I felt it went as far as being highly misleading (more the host than the CEO, to be fair).
In contrast, remember nobody pays for our views here at the SCVR, they can’t be bought. Our duty is to you, the subscribers.
Disclosure on my own position - I was previously much more enthusiastic about the potential for XPF, but the forecasts were surreptitiously lowered, and it doesn’t actually make any real world profit currently. As the facts had changed, I changed my opinion. Although I’ve kept a tiny placeholder position, so it’s on my screen as a company that is potentially interesting, if the facts improve then I would buy back a proper position size. So technically I’m holding some shares personally, but it’s so small as to be insignificant.
Results for the year-ended 31 Dec 2023 -
Very rapid revenue growth +96% to £44.8m, due to annualising the large site opening programme in late 2022, new sites in 2023, LFL growth from maturing new sites, and buying back some previously franchised sites.
Adj EBITDA is complete nonsense, but it’s £8.0m (up 103%)
Operating profit of £1.8m is also nonsense, as it doesn’t include part of the site rental costs, with £1.8m “lease finance charges” being below this line.
Actual profits? It’s a loss of £(535)k. That is not a good performance, although in tough macro, and after a rapid site opening programme, it’s not a disaster.
Balance sheet - shows a large deficit on the lease entries, suggesting BOOM must have a significant number of loss-making sites, but the company has previously denied this. RoU assets is £20.3m. The lease liabilities total £29.3m. That’s a £9.0m deficit, and significant as RoU assets are only 69% of the rent liabilities. So I don’t care what management says, it clearly has some problem, loss-making sites, I’ll go by the numbers.
Cash of £4.4m looks adequate, as the site opening programme has now slowed right down. Maybe the cash figure might have been window-dressed for the year end, as current assets of £7.9m is a lot lower than £16.5m current liabilities.
NAV is £25.5m, but taking off intangibles of £23.7m, NTAV is modest at £1.8m.
However, I could also reverse out the lease entries, which would boost adj NTAV to £10.8m, which isn’t bad actually.
Overall, I think the balance sheet looks stretched, which explains why the new site opening programme has now slowed to a trickle. I think it needs another fundraise of c.£5-10m, to be able to accelerate site openings.
Cashflow statement - does actually look quite good, to be fair. Although working capital has been squeezed, boosting cashflow, and remember that a lot of the rents now appear in finance costs further down, rendering operating cashflow meaningless.
That said, it has funded £6.75m of capex without an equity fundraise. So if expansion capex was switched off (always an option with roll-out businesses) then XPF would generate positive cashflow.
Therefore the way I see it, management are not in an emergency, but are in a difficult position where they need to raise more equity if they want to more rapidly expand the business. Yet the share price is low, so there would be a fair bit of dilution from any meaningful fundraise.
Paul’s opinion - I really dislike the over-promotion of this share, where investors are only told the positives, yet have to look more closely ourselves to find the negatives - the most obvious one being that it doesn’t make any real world profit.
That said, conditions are incredibly tough for bar operators, and I imagine lots of competitors are likely to disappear after the big April 2024 increase in Living Wage, with in my view listed competition Revolution Bars (LON:RBG) and Nightcap (LON:NGHT) at significant risk of insolvency. Mind you, not many bars close forever, usually they’re taken on by a new operator, at a lower rent.
With many younger people now apparently teetotal, and the cost of drinking out being prohibitively expensive, we’ve just got far too many pubs and restaurants now - serious over-capacity.
The good thing is that XPF is offering something superior to conventional bars - the game-playing experience is excellent, and they’re also pulling in punters at other times with large sporting screens. The food & drink offerings are OK, nothing special.
Competition? There are other operators growing in the same experiential leisure space, although XPF has secured some very good sites in prime locations, on reasonable rents, due to the timing of its site opening programme mainly in 2022. First mover advantage maybe?
Could it benefit from a consumer recovery later in 2024? I would say so, yes. Also corporates are getting people back into their offices, and need to do team-building - XPF is ideal for that. If you mystery shop a Boom site, you can see that people are really enjoying the experience, it’s a very good format I think.
Overall, I’m torn between amber and amber/green. Last time I was amber/green, and nothing much has changed, so I’m happy to stick with AMBER/GREEN - moderately positive, but with some reservations (mainly the stretched balance sheet, limiting site roll-outs, and the over-promotion of the shares which I find misleading). If I had to pick a recovery share in the small cap hospitality sector, XPF would be it. Everything else just seems too risky to me (e.g. RBG, NGHT, MORE, TAST, VARE all spring to mind as things I'm avoiding).
Right to reply - XP Factory (LON:XPF) - we're always happy to talk to companies if they think we've got something wrong in the SCVRs. I had a call yesterday from a rather miffed CEO of this experiential leisure company. He said that the deficit on the lease entries on its balance sheet was due to netting off landlord contributions (creditors - for rent-free periods and reverse premiums) against the Right of Use Asset. That sounds plausible, so I've asked for more information, and will publish that here when it comes through. Just wanted to flag it straight away.
Here we are, XPF's CFO explains the lease entries - many thanks for this - it certainly puts a much better picture on the lease entries on XPF's balance sheet. So my apologies for jumping to an incorrect assumption about these entries in yesterday's report. I think we're all learning as we go along re IFRS 16, which almost everyone agrees is a terrible accounting standard, a big backward step!
Subject: Response to Paul Scott's comment
Whilst I will leave you to form you own opinions on the XP Factory performance, there is at least one factual inaccuracy in your comment which I believe is misleading. You state that the “balance sheet shows a large deficit on the lease entries, suggesting BOOM must have a significant number of loss-making sites”. The company has been the beneficiary of significant cash contributions from landlords on the majority of its Boom sites and on some Escape Hunt sites. Under IFRS 16, these landlord incentives are netted off against the Right of Use asset. Ordinarily, at the lease inception, the right of use asset would exactly set off the leasehold liability. However, when a landlord contribution is received, the Right of Use Asset is reduced by the contribution, meaning it will be smaller than the lease liability. Once the lease commences, the lease and the right of use asset will amortise down and slightly different rates, depending on the rental payment profile, which will lead to a further mismatch. However, the substantial majority of the difference in the case of XP Factory is due the cash benefit from landlord contributions – ie a benefit to the company. It has nothing to do with the performance of the individual sites, which within Boom generated an 18% EBITDA margin – 23% in H2 - after fully accounted rent charges as set out in the statement.
FDM (Holdings) (LON:FDM)
Down 11% to 348p (£381m) - Preliminary Results - Paul - BLACK (profit warning), AMBER on fundamentals.
We last reported on a profit warning here on 13/11/2023, which said its IT consultant numbers hired out were down 18%, so it reduced outlook for FY 12/2024.
FY 12/2023 figures are out today, with adj PBT down 3% to £50.2m (a v good margin on £334m revenues). Adj EPS is down 12% to 32.9p, so a PER of 10.6x. Dividend held at 36p, so not quite covered by EPS, but sending a strong message by maintaining it. Balance sheet is healthy, with ample cash of £47m and no debt.
Outlook - this is the problem bit. Market conditions “remain soft”. FY 12/2024 performance now “likely to be materially below its earlier expectations”. Difficult to predict recovery, and it’s maintaining staff capacity ready for a recovery.
Paul’s view - no strong view either way, but I could see this share being a decent recovery play, if/once it starts reporting a recovery in business. So I’ll stick at AMBER on fundamentals. UPDATE: Shore Capital (many thanks) has updated, and it's nasty. - FY 12/2024 forecast EPS down from 26.6p to 21.1p, down 21% on already soft forecasts. So the 2024 forecast PER is now 16.5x - not looking bargain unless you factor in a considerable improvement in future earnings. So shareholders have to hope 2024 is a one-off bad year, and not the new normal. Maybe the share price needs to sell off a bit more to get risk:reward into better balance?
Naked Wines (LON:WINE)
Up 10% to 56p (£41m) - Trading & Refinancing Updates - Paul - RED
Sky News upset the applecart on Monday with a piece saying that WINE had appointed debt advisers Interpath, which I commented on here.
Today WINE retorts that it had previously advised on 15 Dec 2023 (Interims) that it was working with an adviser to look at debt options. Whilst that is true, it was contained within a going concern statement that concluded with a “material uncertainty”, which specifically mentions the risk of breaching banking covenants. Anyone getting bullish after today’s update needs to re-read the going concern statements carefully, I suggest.
Today it says further -
The existing credit facility expires in April 2025 and as such the Company is running a typical replacement review well in advance of that date. The Company is targeting a facility of similar scale with additional financial and operational flexibility, providing more capacity to pursue the actions being undertaken to return the company to profitable growth. Constructive discussions are being held with a number of parties to secure this.
Again that’s true, but I’m more worried about possible covenant breaches, rather than the April 2025 expiry date. Remember facilities become technically repayable on demand if covenants are breached (although lenders usually agree a waiver for listed companies), raising the risk of an emergency equity fundraise and big dilution.
Trading update - Q4 (to Mar 2024) revenues have continued to be in line with expectations (nothing said about profitability though). Net cash has improved to £17m from £3m at end Q3 - that is good news. Anticipated net cash for Mar 2024 year end now at top end of previous range (£0-15m). Remember though that it should be sitting on a large cash pile belonging to customers, but it’s spent that on buying huge amounts of wine - which could be a big problem is customers close their accounts and ask for their cash back.
Paul’s view - I think this clarification today improves things somewhat. I can foresee a very wide range of possible outcomes here. If trading genuinely starts to improve strongly, then this share could be a multibagger. How likely is that though? It still seems to me that the company is in a downward spiral, struggling to afford the marketing spend it so badly needs to replenish the customer churn that all businesses of this type are bound to have. The issue of massive over-stocking with wine really worries me, as there could be anything in those numbers. Downside case a multi-million write-off of unsaleable wines? It’s already had to make some provisions against inventories, and you often later find out that such impairments are the tip of the iceberg. Hence I remain very wary, but good luck to people punting on it. I’m prepared to miss out on a big potential gainer when there’s this level of uncertainty, and a business model that has never made any reliable, repeating profits.
The other question is whether the brand is worth anything to an acquirer? That’s a possibility - look at what happened with Hotel Chocolat out of the blue. Bids can sometimes come for the most unlikely seeming companies, as acquirers sometimes see something that may not be obvious to us.
Anyway, there’s just too much guesswork involved for my tastes, so I’ll stick with RED to flag up the risk and uncertainty.
Yu (LON:YU.)
1480p (£248m) - Final Results (out y’day) - Paul - AMBER
Stunning 2023 results from this utilities supplier came out yesterday. I don’t think we can add anything in terms of analysis, other than to repeat that it all depends whether the huge rise in profits is sustainable or not? YU reckons it is, saying -
The Board expects to continue to deliver sustainable and profitable growth as the significant market opportunity available is seized by the Group's differentiated position and digital capabilities.
Revenues up 65% to £460m
PBT up 580% to £39.7m
Adj diluted EPS 182p (up 507%) - PER of 8.1x
Divis 40p
Net cash £32.1m
I liked the new collateral arrangement which we covered here on 23/2/2024, unlocking a lot of cash.
Outlook - sounds like 2024 is going to be another bonanza year -
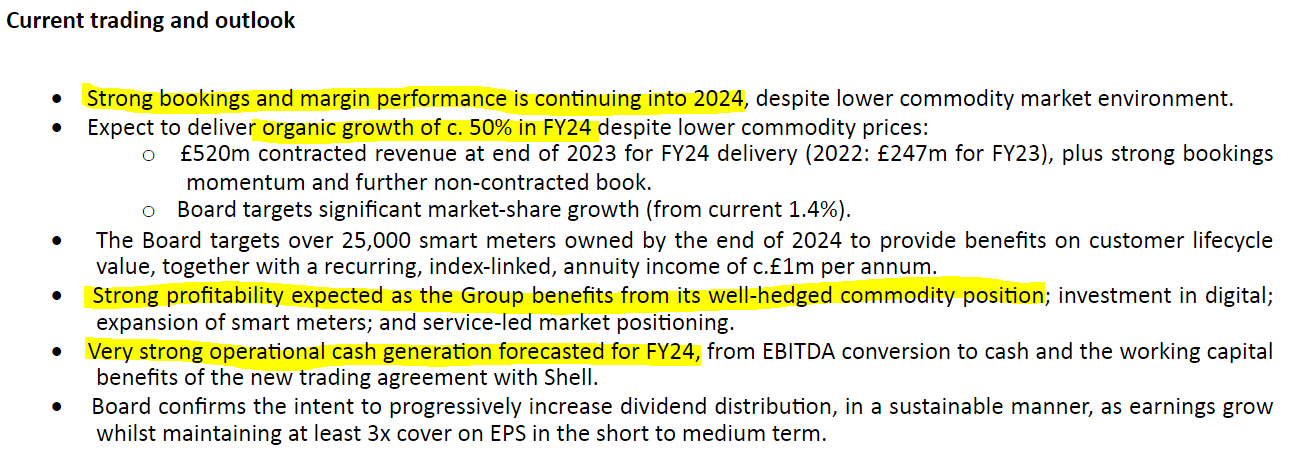
Paul’s opinion - fantastic figures, and outlook. It seems obvious to me that these are super-normal profits, caused by short-medium term opportunities provided by the energy crisis. YU management seem to have played a blinder with their hedging, and contracts with customers.
Once energy markets normalise, and people can shop around again for supplies, then it will be interesting to see if profits remain this high? Big Director selling would be a warning sign worth heeding I think, but there's not been anything of significance yet. Note founder/CEO Baljit Kalar owns 51.8% of the company.
Another bull case is that lots of smaller, badly managed energy suppliers went bust during the energy crisis. So as a survivor (which has prospered, not just survived), then maybe YU could have less competition to contend with in future?
There’s also the regulatory framework to consider, which might change if the Govt changes maybe?
I can see why people like these numbers/outlook though, they’re fantastic!
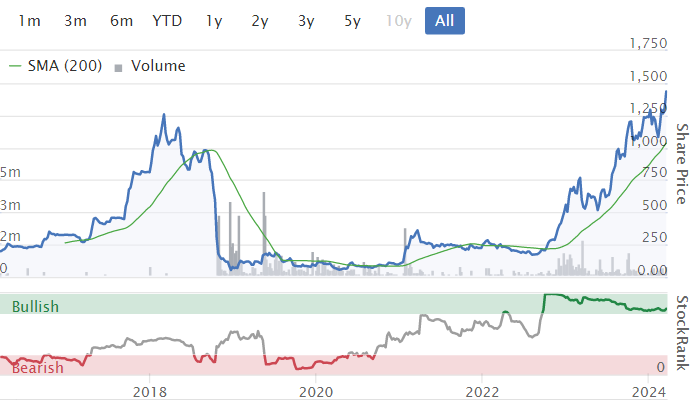
Note that the share price crash in 2018 was caused by accounting problems - overstated profit. Let's hope the accounting is more prudent now.
Graham’s Section:
Trustpilot (LON:TRST)
Share price: 190p (-9% today, results were out yday)
Market cap: £787m / $999m
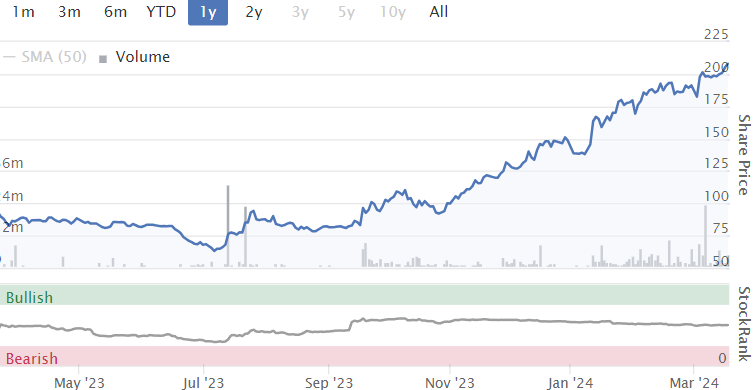
The market reacted very positively to these results from Trustpilot yesterday - the shares were up 9% at one point, before dropping back lower again.
Momentum has been remarkable here for some time:
Here are the full-year highlights:
Revenue +18% to $176m (+17% at constant currency)
Annual recurring revenue +22% to $197m
Adj. EBITDA $16m (previous year: $4m loss)
Net income $7m (previous year: $15m loss)
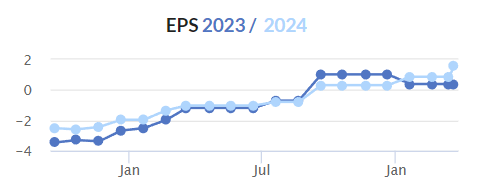
The bull thesis played out as intended, as the company moved from losses into profitability. Indeed, it did this earlier and more impressively than the City originally expected. See the trend in EPS estimates:
Net income was boosted by some accounting effects which investors might justifiably treat with caution, e.g. $4m of sales commissions could be capitalised in 2023 under the accounting rules, whereas previously they would have been expensed and dragged on the year’s profits.
On top of that, the company was able to recognise some deferred tax assets. This is normal when a loss-making company becomes profitable, and it has the benefit of reducing future taxes paid. But, in the case of Trustpilot, the benefit is extraordinary: they recognised over $12m of tax assets and if I’m reading the footnotes correctly, they have another $24m they might recognise in future, depending on the evolution of their profitability.
Just another reminder to treat net income with care - it can be highly volatile, and there are often some strange accounting effects involved.
Net cash is an objective number and finished the year at $91m (previous year: $73m). Greatly improved free cash flow, as the company made the transition from losses into profitability, enabled the commencement of a $25m share buyback in January 2024.
Strategic highlights show the continuation of strong growth metrics:
Monthly unique users +30% to 57 million
Total reviews +25% to 267m
Number of reviewed domains +22% to 1.1m
Outlook is for more of the same, but allowing a wide range of possibilities:
The bookings growth we achieved in 2023 and the ongoing momentum in the business underpins our confidence in continuing to deliver mid-teens constant currency revenue growth, and we also expect to achieve further operating leverage in the current financial year. The Board is confident in the Company's ability to deliver sustainable growth and long-term margin improvement, as we expand to capture the significant global opportunity ahead.
“Mid-teens” revenue growth combined with more operating leverage could lead to a wide range of outcomes but most of them are very positive as top-line growth should produce another very dramatic improvement in the bottom line.
This is why I haven’t been terribly concerned about Trustpilot’s PE Ratio; it’s not relevant in cases where earnings this year and next year are not representative of earnings a few years from now:
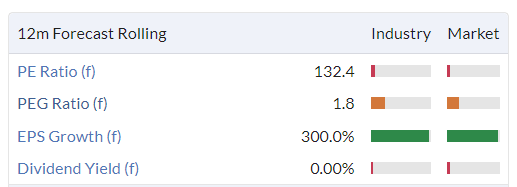
For what it’s worth, I see that Trustpilot’s PEG Ratio according to Stockopedia is quite normal at less than 2x: this ratio is much wiser than the PE Ratio, I think!
CEO comment:
“In my first six months at Trustpilot, I have witnessed first-hand just how powerful our platform is for consumers and businesses worldwide. We made strong strategic progress in 2023, building on robust foundations to grow our network of consumers and businesses and deliver profitability and positive cash flow ahead of expectations. By driving consumer adoption and delivering ever greater value to businesses through innovation, we are confident of delivering sustainable growth and long term margin improvement.”
Low customer growth?
One of the bear points I’ve seen raised (here and elsewhere) is a low increase in the number of active paying business customers at Trustpilot.
That argument remains intact in the sense that the company reports 26,000 paying customers at the end of 2023. At the end of 2022, the company reported 25,000 paying customers.
These numbers have been rounded but nevertheless the number of active paying customers is still only increasing by c. 4%.
When a company leaves out a percentage growth rate, it’s often because the percentage growth rate isn’t very impressive.
Last year, Trustpilot saw 9% growth in the number of active customers.
This year, it could not bring itself to mention the 4% growth rate. Instead, it makes an argument as to why the 4% growth rate isn’t relevant:
Importantly, our strategy is to increase the revenue opportunity within our installed base, principally by focusing our direct selling into the enterprise market, typified by larger deal sizes and lower churn, whilst addressing the smaller business market via self-service channels. Therefore, we do not see growth in the absolute number of paying customers as a critical data point per se; instead, we believe we should focus on increasing average contract values and increasing retention over time.
Graham’s view
Clearly, I’m a believer in this stock: I’ve left it on my best ideas list for two years in a row, despite a soaring share price in 2023. Yes, I did consider taking it off the 2024 list, but I still believe that there is a story worth backing here.
Let’s consider some possible risks:
Reduced growth - with growth in the absolute number of customers having slowed down to a crawl (c.4%), there is a risk that this starts to drag on revenue growth sooner or later, as existing customers may reach the limit of what they are willing to pay. Company guidance for “mid-teen” revenue growth could mean 13%-14% at the lower end of the range. It becomes harder to justify a racy valuation multiple at that sort of growth rate.
Increased competition - Trustpilot’s success is likely to attract competition. There are already alternatives such as Bazaarvoice, Feefo and Reviews.io. (Perhaps this is inevitable, but all three of these competitors have terrible ratings on Trustpilot! 1 2 3)
Valuation - At a price to sales multiple of about 7x and without a level of earnings that can justify the current market cap, perhaps the stock has entered overvalued territory? The ValueRank from Stockopedia is only 4.
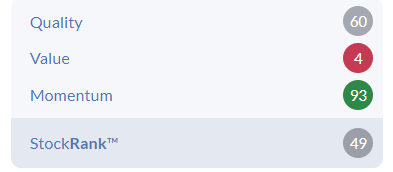
Personally, I remain bullish even though the stock has doubled compared to where I originally took a positive stance.
With regard to competition, I do not view the existing alternatives as offering serious competition. They don’t have the consumer brand recognition, and I don’t see any evidence that they are on track to anything comparable to Trustpilot’s brand recognition.
With regard to valuation, I’ll value it on a pre-buyback basis. So we have $91m of cash deducted from the USD market cap, giving a market cap of $908m.
ARR has reached $197m, so we have an EV/ARR multiple of 4.6x. I would say again that in my view, this is not particularly high for a company with good prospects and a strong competitive position (not to mention the fact that it is already profitable and cash flow positive). Maybe compare it to some US-listed software companies and then reconsider if it still seems expensive!
(Paul adds: I read with interest previous reader comments about concerns over TRST's business model, and have to say I found some of those views alarming. So for me personally, whilst I admire Graham's impressive performance on this share, I'm more sceptical - not just on valuation, but also the actual business model too).
PRS Reit (LON:PRSR)
Share price: 78.7p (+3%)
Market cap: £432m
This isn’t one we normally cover, but let’s check in and see how the property market is treating the private rented sector. PRS Reit has the largest portfolio of single-family rental homes in the UK, spread out across all major regions along with Scotland and Wales but excluding London.
These interim results show lots of movement in the right direction:
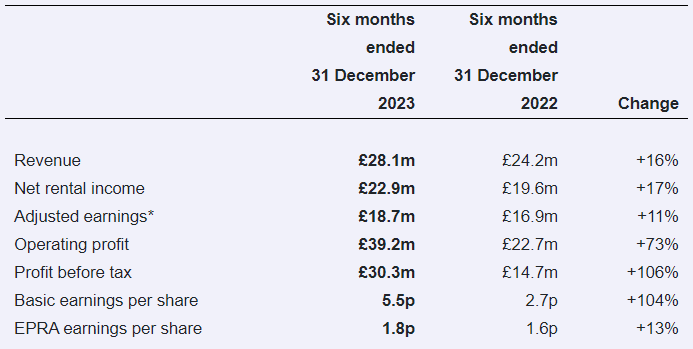
The improvement in profitability “mainly reflected the difference in gains from fair value adjustments on investment property”, i.e. £20.5m of property value gains were recognised in H1, versus only £6m in H1 last year.
Net assets are up 3% to £679m. The market clearly doesn’t trust this figure, given the latest market cap of only c. £430m. Net asset value per share is 123.6p.
The number of homes in the portfolio continues to grow and reached 5,264 at the end of December, having an estimated rental value of £60.3m (£11.5k p.a. for each home).
Operational metrics are immaculate:
Rent collection has improved from 98% to 99%. Average rent as a proportion of gross household income is only 23%.
Occupancy is unchanged at 97%, or even higher if you include tenants who have paid deposits and passed referencing checks.
Like-for-like rental growth of 11.1% (9% for renewals, 16% for new tenants).
Dividend target for the year is 4p. That means a yield of 5%+ on the current share price.
Recent dividends have not been fully covered by earnings in recent times, but the situation is improving, as the company explains:
Dividend cover has continued to increase as home completions and lettings have advanced, and as we exit March 2024, earnings have reached a level on an annualised run-rate basis that fully covers the target dividend.
Analysis of NAV: this very useful table shows how the latest NAV has been derived.
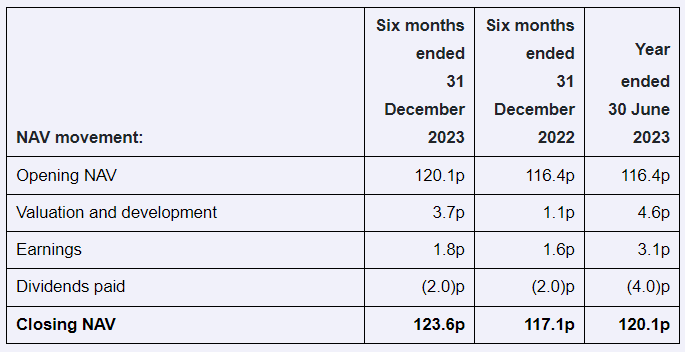
This table confirms that earnings (excluding valuation gains) have not quite been sufficient to pay the dividends (e.g. 1.8p vs. 2.0p in H1).
Outlook:
Between 1 January and 8 March 2024, 42 new homes were added to the portfolio… A further 270 homes with an ERV of £2.5m were under construction at 8 March 2024
Rental demand for high-quality family homes remains very strong nationally and is expected to grow against a background of structural under supply, higher interest rates and continued cost-of-living pressures.
Balance sheet and debt
PRSR has £460m of available facilities; it has drawn £415m of them and expects to use the remaining amount over the next 12 months “as we finish the current phase of construction, completion and letting activity”.
The lenders are all mainstream (Scottish Widows, L&G, RBS, Barclays) and most of the debt is classified as “long-term investment debt” with an attractive average cost of only 3.8%.
Graham’s view
I met the CEO/Co-founder of PRSR’s management company some years ago and was impressed by the story; all of this time later I’m pleased to see that the company continues to go from strength to strength.
Dividends per share have fluctuated but I think the prospects should be good from the current level, given the upward movement in rents:
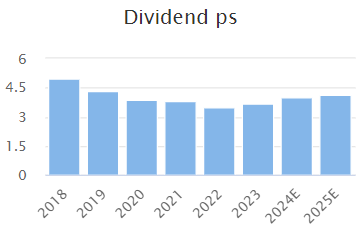
Investing in REITs isn’t for everyone; they tend to suit those who are happy with a moderate long-term return and are looking for less risk than you get with a typical equity investment. The PRSR share price illustrates this:
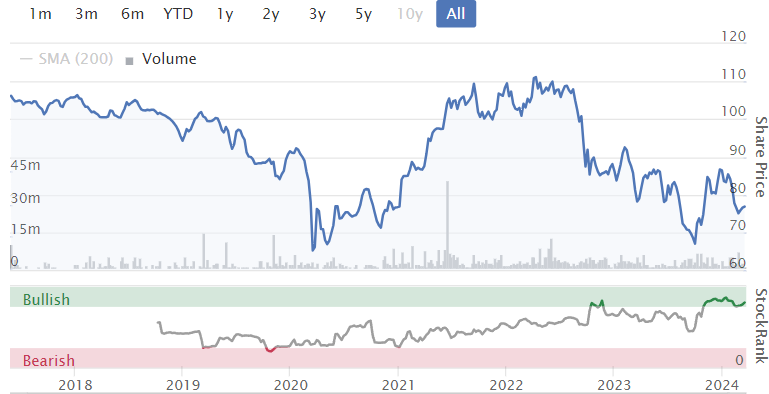
My personal view is that the rental sector will remain in high demand. Even if lower interest rates improve mortgage affordability next year, which in theory would cool the demand for rentals, there is still a widely acknowledged lack of housing supply. And perhaps one of the long-term effects of the cost of living crisis could be sustained high demand for affordable rentals, which PRSR is ideally positioned to provide.
This stock is unlikely to “multi-bag” but I like what it’s doing, how it’s positioned and the valuation at a hefty (36%) discount to NAV. There is some financial risk given £400m+ of net debt, but according to the footnotes of today’s report, most of this debt is locked in at fixed rates until 2033-2038.
Plenty to like here, in my view, and this stock should be of great interest to REIT investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

124 comments
Hi I'm beginning to wonder if its an algorithm doing part of the monitoring as it seems even any reply to a post flagged dubious initially is now getting moderated even if it says "the sun is shining"
ahhh the AI bots are taking over ?
Simon Thompson is a charlatan. That is my very considered opinion. His work is often very poor…but his tips move the market due to followers
Far too many comments are being removed by the moderator. Most of us on here are sensible adults that don't need to be protected like children. The process should be that the moderator should explain to the writer on what grounds the comment has been removed. Vague reasons like Does not comply with content guidelines would not be sufficient. The writer should be informed as to what guidelines have been broken. I don't expect that this will happen. And would not be surprised to if this comment was "disappeared" . Or maybe the moderator should send a private message to the writer with some guidance about the content of the post without actually removing it.
Naked Wines (LON:WINE) closed my account and had my money back about 18 months ago. Have to say during my stint as an "Angel" I did have some pretty decent wines from them. Glad to be out though and reducing my wine intake :) Sacrilege I know!
Bloody hell the moderation here is getting out of hand
I've no idea what difference of opinion has cropped up today but it feels like half the board has been moderated, the same as yesterday
I can understand if someone is coming out with racist/sexist etc comments then yes these should of course be removed as a matter of course
However we are all grown ups here, and I feel the moderation is getting trigger happy
If people are having a debate and difference of opinion then so what? We as subscribers can either read or scroll on
I personally as a inexperienced investor can sometimes gain an insight from these discussions and I'd say it gives us a glimpse into people and their make up which also helps with gaining an opinion on who's comments are worth listening too
It's going to start feeling like a echo chamber on this board shortly if this continues, which is the opposite of what we want and need
I do hope this recent excessive moderation can be nipped in the bud
Callum
Hi Callum,
Our deleted comments were expressing very similar thoughts to your own regarding excessive moderation. I'm assuming your comment and this one will be deleted shortly
Thanks for the reply and information kouremenous
I've not been able to log on during the day this week due to work commitments
I find it abhorrent that when I do get the chance to log on and hopefully gain a small piece of investing knowledge/advice/insight from more experienced investors and their thought processes that goes on, that stockopedia have decided to delete posts just because they dislike what's said
If there is no major red flag to the post then leave it be and let readers form their own opinion of the wording of the posters
The thought processes of the posters here are of enormous benefit to us all and I'm sure all subscribers realise there's a wealth of experience in these boards and people will naturally have different opinions, that afterall is what makes the market
Callum
perhaps the moderation is more a tool to cut out the follow up spats from happening rather than anything else - it it like watching a saturday night (hmmm is that even the right night) itv movise in the early 2000's when all the fun stuff was either cut out or overdubbed with ridiculous stuff deemed to be more suitable for kids - thankfully dont think we get as much of that as we used to.
A woman walked into a bar and said, "Give me a double entendre!”. So the bartender gave her one.
"It's going to start feeling like a echo chamber on this board shortly if this continues, which is the opposite of what we want and need"
I recall a post a couple of months ago where it was proposed that an ongoing thread should be started to discuss Stockopedia improvements and to identify the errors in the data.
Stockopedia declined and cited one reason as being that threads acted as an echo chamber and might not be representative.
It could be that Stockopedia wished for such discussion to be kept under wraps via the green button. That fair enough, but I thought it was not good judgement to describe their own board as an echo chamber.
Stockopedia have lost a lot of the original posters who were excellent contibutors and gave a broader view of investment ideas. If these subscribers are still active it would be good to get them posting again and try to revitalise the board. Any takers?
Wow!
Equals (LON:EQLS) I was assuming the ex-bank small forex players currentlly exist due to the ogliopoly that major highstreet banks currently have coupled with all their unwillingness to change the big fees they all make on them due to most peoples' inertia to change banks once they've probably banked with their parents' bank as a kid or young person (plus it's so complicated and drawn out doing it in reality).Not wanting to get too political but those same big highstreet names that have all sorts of extra fees (a social contract of sorts perhaps!) and are cutting back on what they offer the average customer in terms of retail branches, cash machines etc... in exchange for bad deposit rates and other extraneous fees their customers accept for an 'easy life'.Especially the ones that have invested in a digital platform like Equals (LON:EQLS), which naturally isn't easy to develop.. perhaps they do have more of a moat (?) currently at least.
And the digital only platforms that currently appeal to the younger a lot i'm assuming are hot on their heels!I heard the online bank Monzo raised again $340 million at a valuation of $5.07 billion with the recent round invested by an Alphabet (NSQ:GOOG) owned fund to expand and introduce new products.
Thought that Braemar (LON:BMS) might have bounced a bit today on an 'in line' trading update. Shares have been weak of late and the stock now yields over 5% with a p/e under 7x. Company obviously has work to do to convince after its delayed accounts last year but it is very cheap relative to Clarkson (LON:CKN) . Strange also that Braemar (LON:BMS) don't appear to have communicated this update to either Edison or Cavendish because neither has published a morning note on it today.
I hold Taylor Maritime Investments (LON:TMIP) worth a look big directors buys of late 8 cents/year paid quarterly and big discount to nav thay also own 80+% of Grindrod Shipping Holdings (NSQ:GRIN)
#EQLS
Super smart investor Simon Thompson at @IChronicle reckons a 'fair take-out' price for Equals would be 175p/share.
https://www.investorschronicle...
Investor?
He does not buy any of the shares he tips. I still remember his coverage of Globo and all those Chinese AIM stocks that went bust,
That rather a long time ago now tbf, no? Would you not credit someone with having learnt from those experiences?
Secondly, I think it IC policy that columnists are not allowed to buy shares in companies they cover. He therefore does not own shares in companies he tips as its policy, not because he is not prepared to eat his own cooking.
More recently Naked Wines (LON:WINE) is a Simon Thompson Bargain share tip for 2024. His recent hit rate does seem to approximate to the toss of a coin....
Paul, re Yu (LON:YU.)
“. As mentioned before, it's whether bumper profits are sustainable in the long run that I doubt.”
What are your reasons for doubt ?
Hi Paul - FYI, UK Money Supply has fallen gradually over the past 2 years, since the BoE began hiking interest rates (re your above liquidity comments).
"UPDATE at 10:10: Sky News says EQLS has been approached by Railsr with a proposed merger."
What is it with Sky news which constantly seems to break news before anyone else - and usually accurate news? Props to them for keeping their noses to the ground but how on earth does this keep happening without - apparently - anyone asking some pertinent "insider" type questions.?
Totally agree.Reporters can't tell who told them or are their contacts using wikileaks?I understand not revealing your sources re whistleblowers etc.. but this is\could be market abuse surely?Perhaps not.
They must pay better for gossip. As far as I know profiting from being made an insider is the illegal bit. Publishing it and making it public is different perhaps. The FCA are pretty hopeless at punishing insider trading if they ever get around to it at all imho. Too busy at the moment nosing about in brokers about whether cash earns interest rather than keeping charges low.
<yawn> awfully tedious Equals (LON:EQLS) hype and pump today. Anyone got a good handle on the biz and its growth engine?
A merger seems a bit of an implicit confession of weakness...as did putting the thing up for sale.
IMO Hammond is a plonker...very bad Chancellor and a man with more ego than his intellect and personality can carry.
But hey, I could be wrong ;)
Oooh. Haven't been in here for a long time. See there's been a lot of moderation going on (don't know for what).
Very curious to see if my rather innocuous post not liking a stock nor a past chancellor infringes decency.
Just a reminder that Good Energy (LON:GOOD) (99 overall on stock page) issue their Final Results on Tuesday. Share is rising ahead of them and up another 5% to 295p so far today.
I had sold but bought back last month.
LPA (LON:LPA) a late RNS, trading update, looks like a profit warning, shares are down 10%.
-18% now
So if LPA (LON:LPA) FY Sep24 is now break-even, and the £1m PAT brokers had for FY25 is probably less... say £0.5m instead...
What's holding up the £8.9m market cap? There is some good NTAV backing (71p worth) but its going to take at least two years now to get to meaningful profits... and that's if there is no further delays to those train contracts...
Order book at the last read-out with FY Sep23 results was also declining, so their cupboards are a little bare in terms of revenue growth momentum ex-train-contracts.
I'd say the drop today to 66p isn't the end - as more investors run through the trading update, this should drift lower to sub-60p. But will find a floor with the strong NTAV backing...
IQGeo were late getting their results RNS out this morning, but a really interesting growth stock (I hold), with a smallish double-beat on rapidly growing revenues and having just reached profitability / positive cash flow. Seems like Warpaint London, in that the broker is downplaying the forecasts, assuming growth evaporates when it is clear that repeat revenues are very strong and new customers continue to be onboarded. Opinions welcomed.
IQGeo (LON:IQG) +Rec rev £15.7M +67% rev growth to £44.5M +Exit ARR £21.3M +41% +£6.6M adj EBITDA +ve FCF +£11M net cash +New prod launches +Strong order book £57.2M +New cust wins. Potential negatives are not in the main narrative of the statement: Lower recurring rev %, £965k tax provision, higher opex for growth, no div.
I hold too Mike. It is the first stock I have ever bought almost solely on the recommendation of users because, at the time (2 years ago) I really could not see the attraction on the basis of the financials.. My two brother-in-laws, who are both mathematics graduates, and who have both used IQGeo's products rave about the company.
Two brother-in-laws that are mathematics graduates? What are the chances of that? - Might need a statistician graduate to work that out,
Netcall (LON:NET) , have announced a 5 year contract renewal with a leading transport company for 7.6mm which is an uplift of 36% and adding 400k to ACV. They're expanding their use of the low code platform to incorporate use of RPA (robotic process automation)
We had a good discussion the other day on the merits of Netcall (LON:NET) vs ServiceNow (NYQ:NOW) both of which are excellently positioned for digital transformation. This contract shows how once a company adopts a platform and creates applications using it, it's very unlikely for them to switch away as all would need to be rewritten. In fact they use it more and more leading to H1 Net Revenue Retention of 119% which combined with increasing new customer bookings, gives them a long runway.
The reason I like Netcall (LON:NET) is the widespread usage of their Customer Engagement software (e.g. 75% of NHS trusts). While there is renewed growth here with the move to the Cloud, more importantly it gives them a foot in the door to promote their Low Code and RPA platform as their customers look for Digital Transformation solutions.
Hi Graham,
Just a slight correction for Trustpilot (LON:TRST) - The ARR is now $197m not the $179m you mentioned.
Thanks for the write-up. It is my largest position since last year so it's good to be aware of the bear case although I do not see anything in them to raise red flags.
Re: Trustpilot
Thanks for the correction MGI - I've fixed that in the report! G
Totally agree with your comment above Paul. Inflation had nothing to do with people spending too much but was the result of money printing and the supply chain problems created by the lockdowns. And the high interest rates are adding to costs, hence fuelling inflation. However I dont hold my breath as at the last meeting two members wanted to increase rates even further, all the while telling people they should not ask for wage increases as they are inflationery. However, that does not apply to them.
Yes, good news on inflation today with CPI at 3.4% and even RPI down to 4.5%. There will be further sharp drops in April with the energy price cap moving down significantly.
Unfortunately, the BoEs hands are tied in my view. They have to follow the Fed not lead, otherwise they risk a run on the pound (i.e. speculators buying dollars and selling sterling) that would cause another jump in inflation. The 9.8% increase in the National Living Wage will also keep core inflation higher from April onwards and offset some of the negative inflationary elements working its way through.
All eyes are on the Fed decision this evening, but they won't be cutting for a few months yet based on the current market consensus.
CPI down is largely due to Feb 2023 inflation of 1.1% (nearly 14% annualised), dropping out of the calculation. I think Feb 2024 was 0.6 so annualise that to 7.2%. Puts things in perspective a bit.
Equals (LON:EQLS)
FOR IMMEDIATE RELEASE 20 March 2024
Equals Group plc
Response to Media Speculation
The Board of Equals Group plc ("Equals" or the "Company") (AIM: EQLS) notes recent press speculation and confirms that as part of its ongoing strategic review the Board has received an indicative non-binding proposal from a consortium (the "Consortium") comprising Embedded Finance Limited ("Railsr") and TowerBrook Capital Partners (U.K.) LLP ("TowerBrook") regarding a possible offer for the entire issued and to be issued share capital of Equals.
There can be no certainty that any firm offer for the Company will be made, nor as to the terms on which any firm offer, if made, might be made. Shareholders are advised to take no action at this time.
A further announcement will be made when appropriate.
In accordance with Rule 2.6(a) of the Code, by not later than 5.00 pm on 17 April 2024, the Consortium must either announce a firm intention to make an offer for Equals under Rule 2.7 of the Code or announce that it does not intend to make an offer for Equals, in which case the announcement will be treated as a statement to which Rule 2.8 of the Code applies. This deadline will only be extended with the consent of the Takeover Panel in accordance with Rule 2.6(c) of the Code.
The Yanks better hurry up! Equals (LON:EQLS)
Paul with reference to your comments about experts I will attempt to insert a little humour. What is an expert? X is the unknown factor because many experts don't know what they are talking about! And a spurt is just a drip under pressure!
I was always told that " an ex is a has been and a spurt is a drip under pressure"
It's a very British thing to disparage knowledge and expertise and instead revere 'common sense'. I don't think it's done us much good.
Hi NK104,
I want to come back to you on this point, where you said -
It's a very British thing to disparage knowledge and expertise and instead revere 'common sense'. I don't think it's done us much good.
That's absolutely not what I did in the main report. My point was very specifically that economics is an area where many people with knowledge and (supposed) expertise are very obviously and measurably poor at predicting the future, let alone making sensible policy decisions. Superforecasting is a fantastic book recommendation if you haven't already read it, which proved through data that people consistently good at forecasting in many areas tended not to be sector experts. They tended to be experienced, older people, good with maths, statistics, and probabilities, with logical thought processes. I think we've got quite a few people like that here as Stockopedia subscribers actually.
This was far from a throwaway remark of the more general kind that you wrongly believed it to be, I have great respect for people with expertise in almost every other area of knowledge apart from economics.
Just wanted to clarify that.
Regards, Paul.
NK104. You may well be correct. My little attempt at humour does not mean that I think that experts' opinions should be ignored. I remembered the joke because I thought that it was an amusing play on words.
https://news.sky.com/story/ex-....
Equals (LON:EQLS)
Equals holders may be interested in this. I am assuming this is not a hoax.
Equals (LON:EQLS)
We have at least 2 parties interested in Equals.
Ex-chancellor Hammond's fintech Railsr eyes merger of Equals | Business News | Sky News
I hold
Equals (LON:EQLS)
I suppose this prolonged set of negotiations does give a bidder the opportunity to track forecasts against performance, but that doesn't make the management look particularly strong or confident as a negotiator.
Quite why they have sought a bidder remains an issue, and the potential acquirer may be doubtful/suspicious on that account and want more proof of results, after all its not as if its an urgent issue that they were pressing on the company.
Usually these strategic reviews fail because of some of the above factors.
Equals (LON:EQLS) The performance up to 15th March has been pretty stonking - I make it revenue of £415/day v £301 in H2 2023. So performance hasn't been impacted by the talks.
Re sourcing a bidder - my guess fwiw - if they go private they get to share a bigger part of the profits. Plus they get a good profit on the shares held.
XP Factory (LON:XPF)
Excellent analysis from Paul.
Lease liabilities show the clear picture.
I can definitely see a fundraise and the usual blah blah blah ….. another acquisition or just to fund growth!
All the best
XP Factory (LON:XPF) I completely agree, not a fan of this business for all the reasons Paul states. I don't even rate the product, I went a few months back to the main one on Oxford Street and found their offering significantly inferior to other experiential night outs in London which makes me think these will not be not sticky dependable revenues.
The cash flow makes it look optically cheap but I don't believe shareholders will ever see that money, just my opinion but better places to invest.
I must admit I'm disappointed, not sure if it will ever reach its potential, Richard doesn't seem to want to make any tough decisions.
If Boom is such a good business model, why do they keep having to buy back franchises??
XP Factory (LON:XPF)
Given the substantial royalties payable to the central co, I suspect that some XP Factory (LON:XPF) franchisees quickly work out that they can't make much, or indeed any money from the business, and then lose their motivation.
The dash for rapid growth in 2022 always puzzled me. It was a helluvan achievement by mgt to open so many new sites so quickly, but it must have left all sorts of problems to clear up in its wake. Hence why I think a much smaller new site opening programme in 2023 was wise. In his promotional interview, the CEO indicated that they had done a lot of work to maximise returns from the existing estate. I can remember when I mystery shopped the highly successful London (Oxford Street) site, I saw customers had piles of coats next to their group. Where's the cloakroom, I asked management? We didn't put one in, it was an oversight, was the reply. So stuff like that can be fixed, and bar capacity at peak times, etc. To be fair I think that's all part of the growing pains for any small business growing really fast, and I remain impressed with what they've achieved so far during very tough macro. Hence why I'm still moderately positive for the future re XPF.
The gross margin is something like 80%+ as games revenue is almost 100% margin, so this thing is really geared to a consumer recovery, and achieving breakeven in the meantime actually isn't bad.
Regards, Paul.
I also went to the Oxford Street branch with my two brothers over the Christmas holidays and although the games are good fun the music was dreadful and blasted at such a ear drum bursting volume that you couldn't make conversation. My brother put his noise cancelling headphones to try and block it out in the end. We may have just been too old mind you.
Perhaps a fundraiser wouldn’t be a bad thing if used for expansion. Head office costs at £8m seem high and if reallocated over additional venues may be more in proportion to revenue. The boom sites are popular with the younger demographic who drink less and want cheapish entertainment . I do agree though that the ceo views are rose tinted.
What are views re: looking at XP Factory (LON:XPF) on a cash flow basis? If you strip out working capital changes (i.e. the £2.6m sitting in payables as window dressing), maintenance capex and lease costs I make it £3m left to do what they like with. That's not a lot, esp. given 4 new sites last year cost over £4m, but I think paints a better picture than the P&L which includes depreciation of the capex which was funded by equity raises.
In terms of lease liabilities, what's the real world outcome of that? Presumably this is why XPF has been snapping up franchises - they're making a loss and the franchisee wants out, and XPF thinks if they manage it themselves they can turn a profit?
Definitely an end of year window dressing on the cash figure as current liabilities are double the current assets figures. Paul has already correctly spotted and covered this.
The clear red flag is the change in their depreciation policy that does not make any sense at all. If you carefully study this announcement they shouldn’t be allowed to do that on the new five and ten year life basis (for this sector).
Can’t remember the exact year but it was before 2000. We were assessing the figures of a retailer (not in the UK) as they have changed their depreciation and life for their buildings to 200 years! They went bankrupt in two years as new auditors were not willing to accept this.
They will definitely need a fundraise and a company to avoid.
Always personal opinions.
All the best
Just read Paul's addition to XP Factory (LON:XPF) , with the response from the CFO about RoU and long term lease liabilities...
So I accept management explanation that for new sites, because of landlord cash contributions, then RoU is lower than LT Lease Liabilities out of the gates.
But then doesn't the balance sheet have to.... balance?
So that "cash incentive" difference between RoU and LTLL. Where does it go? Property/Plant/Equipment for fixtures and fittings? Cash in current assets? It has to go somewhere right?
What do you have against Yu (LON:YU.) ? (I am a long time holder). Another set of good results yesterday which don’t merit a mention. You have in the past mentioned risks associated with the stock but the metrics have always seemed solid to me. I would appreciate your thoughts.
What seems to get forgotten in all the news around inflation is that if you compare the CPIH index at Feb 2021 of 109.4 to todays Feb 2024 of 130.8, this is an increase over 3 years of 20%. So if you had £100 in Feb 2021 and did nothing with it, this now has a real value of £83.5. Big winners and losers with that kind of inflation.
Also very clear, that indexation around capital gains needs to return because otherwise they are just taxing inflation.
Alpha International (LON:ALPH) ALPHA GROUP DESCRIBES STRONG 2023 PERFORMANCE
(Sharecast News) - Alpha Group International reported a strong financial performance 2023 in a trading update on Thursday.
The AIM-traded firm's unaudited figures showed a 12% increase in revenue to £110m, with profit before tax soaring more than 140% to £115m.
Underlying profit before tax grew 10% to around £42 million, as the company maintained a consistent profit margin of 39%.
Its balance sheet strengthened, with adjusted net cash rising by over £60m to more than £177m.
Alpha Group highlighted its diversification strategy's success, yielding resilient revenue and robust profit growth.
It also emphasised a disciplined credit and risk approach, resulting in its lowest client default levels in five years.
Strategic investments led to operational efficiencies, and hiring focused primarily on the front office, the board explained.
Key initiatives in 2023 included the launch of a fund finance division in May, the establishment of new corporate FXRM offices in Madrid and Munich, and the acquisition of Cobase in December.
The company acknowledged challenges from the interest rate environment and macroeconomic uncertainties throughout the year.
While the third quarter presented difficulties, Alpha said it ended the year positively with record revenue in the fourth quarter.
Despite potential macroeconomic challenges in 2024, the firm said it was confident in its strategy.
In the FX risk management (FXRM) sector, conservative client hedging and credit appetite amid uncertain economic conditions posed challenges.
However, diversification efforts, including growth in institutional FXRM and overseas offices, mitigated issues in the UK corporate business.
Alpha Group said it expected growth prospects in FXRM for 2024, with investments positioning the division for success.
In alternative banking, reduced deal activity affected account growth, but revenue increased 18% to £34m.
The division generated over £73m in other operating income from interest on client balances, indicating optimism for future prospects.
Alpha Group's fund finance offering, launched in May, had a successful start, with plans to leverage cross-selling opportunities.
The acquisition of Cobase in December expanded the company's product portfolio and client base, particularly among medium to large corporates.
Alpha said it was aiming to maximise synergies between the two businesses in the long term.
"Despite a challenging trading environment in 2023, our team has continued to work hard to deliver profitable revenue growth, whilst also making excellent progress on our long-term growth strategy," said chief executive officer Morgan Tillbrook.
"At the same time, our previous diversification into alternative banking has enabled us to benefit from exceptional levels of interest income.
"Whilst we have opted to exclude these numbers from our underlying profit for transparency, the fact remains that this is very much a by-product of our diversified business model and is providing us with transformative levels of capital from which we can significantly enhance our long-term growth prospects."
Tillbrook said the company had already started to show that in 2023 with the acquisition of Cobase, the launch of its new fund finance division, and new offices in Spain and Germany.
"The higher interest rate environment has created economic headwinds which have impacted our underlying revenue momentum.
"However, the additional operating income of over £73m that we have generated as a result of this same environment has more than compensated for this, and highlights the resilience of our diversified business model.
"In simple terms, 2023 showed that in a higher interest rate environment, underlying growth becomes more challenging, but the cash and statutory profit from interest income becomes exceptional - a trade-off that, in reality, creates significant opportunities for Alpha's long-term growth prospects."
Yes and do you have an opinion on this? Those interested in Alpha International (LON:ALPH) will already have read the RNS. Also please tone down the huge capital letters headlines; felt as if I was being shouted at.
Hi Wol,
It did read very loudly didn't it.
I'll do my usual quarterly sell of what a great company I think Alpha International (LON:ALPH) is. No surprises today in the full year results today, just confirmation of the trading statement in Jan. The interesting point was the confirmation that the move to the main market from AIM should take place in May. Not sure whether this will provide any ooomph to the share price or not, but generally it should be a good thing for the perception of the business from clients.
One of our very clever and exceptionally attractive correspondents wrote in the comments section on the Week Ahead blog this week:
"Outlook I think depends a lot on rates, so they probably don't have much to tell us there. The line from management is that rates high equals lower growth, but then whilst rates are high they make a wedge of additional revenue / profit from the interest on large client funds they hold in the alternative banking division. Which can then be reinvested to really power growth when it returns. "
They mentioned this again today, and it really is a huge selling point. I also think it demonstrates some really positive qualities in management (hat tip to CEO Morgan Tillbrook), that you don't see often at all from exec. management teams, who want to take credit for everything all the time, and obfuscate anything which might be caused by luck or circumstance. They specifically exclude from the revenue figure, the interest income from the huge client cash balances they maintain. This is listed as a separate line item (called net treasury income), and I've not seen any other company set it out as clearly as this.
Anyway, check them out, you might even like them.
Cheers
Chris
Alpha International (LON:ALPH)
is there any danger of the FCA looking at them ref the cash cow that is interst income?
Certainly looking at the long term progress here of the numbers on stocky financial summary its a thing of beauty other than 2023. Is faster earnings growth expected to retur in 2025 or are they now past the stage of posting great numbers ?
£ALPHA
is there any danger of the FCA looking at them ref the cash cow that is interest income?
I've asked myself the same question. The key difference, it seems to me, is that customers are corporate, not consumer, and presumably both well-informed as to the implications of the policy and with big pockets to cope without. I'd add that forex hedging incorporates an element of interest rate hedging anyway - when you buy or sell against your home currency six or twelve months hence you pocket or stump up the interest differential inherent to the currency pair. It all gets reasonably complex so I imagine corporate treasury departments just look at the apparent value in the overall price they are offered and decide if they are happy in the round. At least, I hope so.
Yes, I think the consumer vs corporate / institution issue is the biggest point. Plus, the average interest rate Alpha International (LON:ALPH) got throughout the year was 3.6%, so comfortably below the BoE rate for 2023. So - pure speculation - they may be sharing interest with clients (or alternatively, getting lowish rates from whoever they park their money with). Who knows, but I don't feel it's the same size risk as HL, IGG and the rest.
On future growth, the consistent message from mgt. is that lower growth is expected whilst we have higher interest rates and tighter monetary policy. It suppresses their clients' activity, which also chimes with all the messages from the wider economy.
I can't recommend reading the CEO Statement in todays FY results enough. He is bullish on future growth, and gives specific reasons for doing so. In my opinion, the reporting is similarly transparent, open and honest as Next (LON:NXT), it's really thorough.
I also take it as a bull point that it's not often talked about here.
Cheers
Chris
I can't recommend reading the CEO Statement in todays FY results enough
Completely agree. It's on a par with another paragon of clarity and transparency in Games Workshop (LON:GAW)
Alpha International (LON:ALPH)
Cheers BnB - very useful info. as you say corpoirates (as long as not micro sized) shoudl be able to look after themselves. I dont know the detail but i do know some smaller companies are treated better ref deposit protection limits so not sure if that might be similar here if there was issues.
It's not interest income per say, as they explain in today's report;
"The Group is only able to obtain attractive interest rates on these overnight client cash balances because of our ability to aggregate numerous individual client balances, many of which are transitory in nature and typically only held for a short amount of time."
The clients in question operate in the alternative banking sector, so are VC funds, PE houses, hedge funds, infrastructure funds etc. They are moving money around the world and will therefore have zero expectation of receiving interest on the balances (i.e. it is a specific amount for an investment etc).
Well worth spending a few days researching the business in full, it's absolutely outstanding as others have already pointed out. Could easily grow into a solid mid cap in the medium term.
They have a buy back in place but there is consistant selling. I'm still losing moneyAlpha International (LON:ALPH)
I thought that the Eurocell (LON:ECEL) numbers were below my expectations. I'm also a little wary because of some rather poor reviews that I read from local builders using them, and I thought that some depots looked a tad scruffy (whereas I can't speak too highly of Screwfix). But you can't trust many reviews, and I may be maligning a good company. Certainly a cyclical recovery stock.
On a separate subject, I've bought back into TP Icap (LON:TCAP) pretty heavily, having had to sell out for a tax trade. It's a company that has got some baggage caused by multiple acquisitions, but I think that it is slowly but surely becoming a decent financial plumbing business of some size. Certainly undervalued, even if I don't like some of the activists that have been circling. A decent divi also.
Eurocell (LON:ECEL)
I thought that the Eurocell (LON:ECEL) numbers were below my expectations.
were your expectations different from those of teh company and their brokers ?
the company confirmed today and also in january that numbers had met prior expectations so not sure why you have different take here ?
today
Against this challenging backdrop, we are pleased to report profits for the year in line with expectations and strong cash flow generation.
january
Despite these challenges, we are pleased to confirm that we anticipate
underlying profit before tax for the year ended 31 December 2023 to be in line
with market expectations.
Perhaps the reason could be non underlying items although higher these items dont seem ridiculous and i suspect they are no shock based on todays comments above
Non-underlying items of £3.5 million in 2023 include restructuring costs of £2.7 million and £0.8 million of costs relating to strategic IT projects which are classified as an expense as they use cloud computing. Non-underlying items of £2.5 million in 2022 include restructuring costs of £2.2 million (redundancy payments of £1.6 million and tangible and right-of-use asset impairment charges of £0.6 million) and £0.3 million of costs relating to the refinancing of the Group's £75 million Revolving Credit Facility.
So confused as to how they could miss what you were hoping for when they clearly say they have hit what they told us they would do !
Yes, it is exceptionals that influence my view of profit, plus some concern that so much cost removal can affect customer service. This is a company that I want to like, but can’t quite bring myself to, yet.
FDM (Holdings) (LON:FDM) Another profit warning today..I think this is the second in 6 months so should we expect another one this year? Don't they often come in threes?
Eurocell (LON:ECEL) Probably still a couple of months too early to buy cyclicals but Eurocell are doing and saying all the right things and their model looks very operationally geared to benefit from top line increases.
I don't hold (yet) but I think at some point this will one of the better buys for when growth returns in the RMI market.
Interesting Eurocell (LON:ECEL) (I hold) FY23 results, eps is down to 11.0p (from 21.4p last year), in line with expectations. What I like to see is c.£27m of free cash generated, by controlling inventories, so net cash in the bank (excl leases) of £0.4m. This free cash flow compares to a market cap of £123m.
Probably another tough year ahead but I hope well positioned for lower interest rates. We will see......
Re Eurocell (LON:ECEL), I understand from an employee they are closing their Ilkeston factory and consolidating at South Normanton. Why and impact on the business, I know not.
Eurocell (LON:ECEL)
I suspect thats part of the normal process of doing business , i suspect alot of the tech nowadays has moved on from how things were done even 10 or 15 years ago - so companies like eurocell and epwin probably need to perhaps almost start from scratch every so often. Thats mere speculation on my part but i do suspect shelf life of shed type manufacturing stuff is nowt like it used to be back in the day when there were alot of places that look like they have been around longer than Cliff Richard?
Paul I think that is a fair assessment on EQLS.
Will you be covering Kenmare Resources (LON:KMR) today?
Hi Paul
I think Equals (LON:EQLS) expected adj EPS is expected around 9p so this is a PER of 12 not 18. Throw in net cash and it’s around 10*
that’s not expensive in my view for a company growing at circa 30%+ p/a.
Btw thanks for all your hard work every day on the research you put in to all of the different shares you cover. In reality this forum only really works because of it and the debate it provokes.
Best
David
Equals (LON:EQLS) - I can see from the table that Paul Hill has provided that the adjusted EPS excluding SBPs for 2025 is 8.82p. The adjusted normalised eps on Stockopedia for 2024 is 5.9p which must include SBPs.
For this company, excluding SBPs has a near 50% impact on the EPS.
whats an SBP ?
I think it is Share-Based Payment
Hi David, may I ask you a naively sounding question regarding Equals (LON:EQLS) as I am still familiarising myself with it. How do they actually win new business? Is it cold calling? word of mouth? do they have to spend big on marketing? how do they do it? And are these growth projections tempered as they become a larger business?
Mix of both from what I can make out. Planetx in one of his businesses gets called up regularly to sell their services. From what I can see the services they offer allow for land and expand approach : ie client uses them for basic FX, then moves to multiple IBANs and finally on to payroll for example. To win business they cold call SMEs and word of mouth / marketing.
So existing customers seem to be using more and more of their service, becoming both stickier in the process (better revenue visibility) and they are attracting new clients through their business dev team.
BRBY down today as Kering warns: “This performance primarily reflects a steeper sales drop at Gucci, notably in the Asia-Pacific region. Gucci comparable revenues in the first quarter are expected to be down by nearly 20% year-on-year”
This one is a serial gapper in a long term downtrend, best to avoid.
The BOE has said for a very long time, their target is 2% inflation. They have not deviated, so I expect interest rates to hold until the target is very close or reached. The reigning party in government would love to have interest rates go down so they could claim the credit of lowering inflation and lowering interest rates, so I expect them to pressure the BOE to lower - but personally I hope that the BOE stick to their remit and show the world that they can be relied on. Democratic interest rates have historically been a very bad thing. The same thing, in my opinion is also happening in the USA. I want interest rates to go down as that means asset prices go up - but I don't want a yo yo environment, a steady ship for the long journey is my preference.
#EQLS
Patience is a virtue. And fortunately the board of international payments & forex platform Equals Money has plenty of it.
Today they extended the “Put up or shut up” deadline again for another 4 weeks until 5pm Wednesday 17th April. Coincidentally one day after the FY23 finals are set to be released on the 16th.
Personally, I suspect this will be the last ‘drop dead’ date - given that Madison Dearborn Partners, LLC and/or any other interested buyers will then have reviewed the full 2023 audited results, from which to decide whether (or not) to make a binding/conditional offer.
The good news is that either way, trading continues to be strong with YTD’24 turnover reported to be up 28% YoY to £22.2m (vs £17.4m LY) thanks to improving revenues/day, 1st sales from Europe and “particularly strong growth from Solutions” which target larger corporates.
Indeed this increase is actually higher than my own FY24 projections (see below) of 19% top line expansion, which generates a valuation of 170p/share.
As such to me, despite the recent softness in the stock price, things are still looking positive.
Disclosure: I own shares in Equals Money (largest position) and the company is also a Vox Markets client.
Looks like things might be developing faster than I originally thought for Equals.
https://news.sky.com/story/ex-...
A wise person once said "if you spend 15mins on economics, you've wasted 9mins." It amazes me how there are economist teams in all large banks/ fund managers. I'm sure they are no better at predicting or providing anything more useful than say the bbc "economic expert"
Peter Lynch was that wise person.
Anpario (LON:ANP) results nothing to get excited about apart from 'Strong start to trading in the current year'. Broker has raised '24 EPS this morning by 18% tho + PBT 15% (there was also a tender offer here), so maybe worth a look as a potential recovery play. m/c £46m, £10m cash.
Anpario (LON:ANP)
Hi WOSS
Thanks for bringing this up.
I looked at Anpario for the first time this morning and, although it looks quite cheap, the company doesn't seem to have had much growth over the last decade.
It was on an expensive rating before and I presume there must have been something to justify this, so perhaps there's a recovery play here if the share price reverts to its previous high multiple.
Apologies for being lazy, but does anyone know if there is there something special about the company or its products? There appear to be quite a few competitors out there too, and the few I looked at seemed to have far greater resources.
Thanks
A
Hi abtan.
Been a holder for over 10 years. My take as a lay person. Anpario have range of natural products to promote growth, primarily but not exclusively in pigs and poultry. Historically antibiotics have been used by farmers for this purpose, but this process is gradually being legislated out and when first mooted led to high multiple for ANP shares. Farmers very slow to change and global agricultural markets difficult, so revenues have been disappointing last few years. They look to have a bit of pricing power. Very prudently run, with no historic debt that I can recall. What they have done during the difficult past three years is to make the manufacturing process much more efficient and the business has always been a solid cash generator. Operational gearing is high, so with the outlook comments suggesting higher volumes of product and also better margins I am hopeful of significant improvement in profitability this year and yield nearly 5% gives additional comfort. Always DYOR!
Anpario (LON:ANP)
Thank you for sharing your thoughts Stuart, they are much appreciated.
I must admit to being somewhat torn here.
The underlying cash generation (£4.5m - my calc) is excellent compared to the current EV of c.£35m.
However:
makes me wary that the share price does not deserve a premium and, whilst possibly too low, doesn't have much upside.
One to think about.
Thanks again.
The spread is nearly 9%.
Bank of England thought process -
When labour market is tight people ask for wage rises in order to pay their mortgage. Who would have thought it?
Higher interest rates simply don’t work when the causes of inflation are external. There is no excess demand in the economy that needs to be crushed. We have the most expensive energy in the world due to mad government policies. We have a crisis of lack of investment. I really don’t know what higher interest rates are trying to achieve.
I completely agree Donald. Would things have been different if they'd stopped at 2 or 3%? I doubt it.
Deliberate policy to have some of highest energy costs in the world is one of the dumbest things I've ever seen a government do.
Hi Wolfie,
I was thinking the same about high energy prices. Surely the last couple of years has shown that a better policy would be for central Govt to more heavily subsidise energy costs during a price spike, then it wouldn't cause such a large spike in inflation, and all the follow-on financial damage from that (eg. strikes, and huge increases in the public sector wages bill). Mind you, that would be a very risky policy, if energy prices remained high the subsidies would have to be stopped.
Incidentally, I'm listening to a fascinating podcast series, 4 hours about 1974 - if you think things are bad now, listen to this, to make you feel a bit happier about now! It's called The Rest is History, episodes 417 to 420. The delivery can be irritatingly chirpy, with the narrators trying to be funny, but failing most of the time. But the content is superb.
Regards, Paul.
I love that podcast series (both that particular run and in general), Paul. Another recommendation from me. Although I must confess, I do find them very funny!
Surely just a transfer of wealth from poor to rich?
Lower interest rates = lower pound = higher cost of imports (balance of payments deficit, anyone?) = higher inflation
High interest rates do decrease price inflation. Increase the price of borrowing results in less borrowing which reduces demand which reduces price.
Core CPI at 4.5% and with the minimum wage increase in April inflation could spike again. Can't see BOE lowering rates just yet.
Think there’s a problem with RNS this morning… expect a deluge of further updates soon!
My morning smallcap tweet: Iron filing
Abingdon Health (LON:ABDX) Equals (LON:EQLS) Hornby (LON:HRN) Poolbeg Pharma (LON:POLB) Oxford BioMedica (LON:OXB) Symphony International Holdings (LON:SIHL) PayPoint (LON:PAY) 600 (LON:SIXH), Braemar (LON:BMS)
◄Abingdon Health (ABDX)► to sell Iron and Vitamin D deficiency self-tests as Boots own brand. [SP=8.85 Cap=11m]
◄Equals (EQLS)► PUSU extended to 17 Apr. Trading in line. [SP=109.5 Cap=205m]. I hold.
◄Hornby (HRN)► contracts The Fat Controller (Mike Ashley) as consultant, for free. Frasers is a shareholder of Hornby. HT to @rhomboid1MF for the gag. [SP=34 Cap=58m]
◄Poolbeg Pharma (POLB)► Notice of Allowance from US Patent Office for Immunomodulator II patent application. Expects grant of a patent in due course. [SP=9.95 Cap=50m]
◄Oxford Biomedica (OXB)► wins contract from a US-based biotechnology company for the manufacture of lentiviral vectors. Also two new programmes with existing clinical-stage clients. No £££. "Payments will support the Company in achieving its medium-term financial guidance." [SP=186.6 Cap=187m]
◄Symphony International (SIHL)► Dec NAV $0.7427/sh cf $0.7058 in Sept. Market overview. [SP=0.4 Cap=205m]
◄PayPoint (PAY)► Lloyds Bank Cardnet becomes the main card acquiring partner across PayPoint network. This "will strengthen our market position, accelerate the growth of our merchant network and provide better tools and support for our SME and retailer partners". [SP=488.01 Cap=355m]
◄The 600 Group (SIXH)► [last night] rev for 11 months to Feb down 19%. Guides FY-Mar pretax loss over $5m. Won't prublish H1 before end Mar deadline, so shares will be suspended 2 Apr. [SP=2.76 Cap=3m]
In line: BMS
Equals (LON:EQLS) - PUSU deadline extended and strong trading update:
Trading Update
The Board is pleased to provide an update on the Company's current trading, which continues to be in line with the Board's expectations. Trading in the first quarter of FY-2024 up to 15 March 2024 (the "Period") has continued the strong growth trajectory of FY-2023 with Revenues in the Period reaching £22.2 million, up from £17.4 million in the same period in FY-2023, representing an increase of 28%. In keeping with recent trends, trading has been robust across the business with particularly strong growth from Solutions.
Further detail will be provided in the Company's final results which will be released on Tuesday 16 April 2024, along with a further trading update.