Small Cap Value Report (Weds 21 Dec 2022) - SDG, WAND, INSG, TRMR, XSG, PURP

Good morning from Paul & Graham! Firing on all cylinders again, so let's hope we have some interesting news to cover.
Today's report is now finished.
Agenda
Paul’s Section:
Sanderson Design (LON:SDG) [Quick comment] - 113p (£81m mkt cap) - this is a “reach” (non-regulatory) announcement, of a new licensing agreement with Ruggable (two-piece rugs, with the upper piece being washable - clever idea!) SDG’s William Morris fabric designs will be used. It says this is the “second major” licensing deal in the USA - a key market that SDG wants to aggressively grow into, seeing a big market opportunity there. I reviewed the in line interim results here. As I noted at the time, strong licensing performance is offsetting weaker trading in the main business, which if it continues, could help SDG get through this recession.
My view remains positive on SDG shares - it’s easy to imagine this share being double the current valuation once the economy has returned to normal. Between now and then, there’s obviously the risk of a profit warning, and the company has previously indicated a wide range of outcomes is possible, shorter term. Balance sheet is bulletproof, so no risk of dilution or insolvency, hence it's a good long-term hold I think, if a potential dip shorter term doesn't worry you. Maybe one to take a small position in, and keep some cash on the side to top up on a warning (which may or may not happen), I was thinking.
WANdisco (LON:WAND) [Quick comment] - 900p (£621m mkt cap) - here’s an interesting share, that has soared in the last 6 months. We flagged here on 28 June that a big contract win was starting to look interesting, although the results announced on 15 June were dreadful. The key “tell” that something interesting was afoot (with hindsight) was that it got away another fundraise in June, at a premium, despite reporting terrible numbers. Afterwards, a series of big contract wins were announced. That was the turning point, it's tripled in price since then. So we’ll have to take a closer look at any more companies that look basket cases, but successfully raise fresh equity without having to offer a discount, as that suggests instis are being privately told that there’s a very positive outlook, and believe it to be real. Yesterday saw another deal announced, $31m, with half paid up-front. This reinforces my view that something very interesting seems to be happening at WAND.
Tremor International (LON:TRMR) [Quick comment] - Up 9% to 300p - mkt cap £433m - Sky News says that TRMR has appointed Goldman Sachs, to try to sell the company. That could make sense, as it’s become obvious that stock market investors don’t trust the company and its figures - otherwise it wouldn’t be trading on a forward PER of 4. I’ve never understood the business model, so generally avoid trying to write anything about it. Graham reviewed it here in August, flagging up various issues. The Director dealings page doesn’t suggest they’re bullish about the company with their own money. Major shareholders look interesting, including a Saudi family office owning 24%, Toscafund on 15.5%, and News Corp at 5.9%. Interesting that its excessive share options scheme has been challenged by shareholders recently. My view - no idea, I can’t determine if it’s good or bad, so I’ll steer clear.
Xeros Technology (LON:XSG) [Quick comment] - one of many dismal, jam tomorrow companies on AIM. Mkt cap is now only £6m, but you can now buy at 3.8p, below the 5.0p price of a recent fundraising, which replenished the coffers (for now). An update today says its Indian partner is shortly to launch domestic washing machines using XSG’s technology. Trials of larger washing machines are also underway. “Financial guidance remains unchanged” - it’s previously said targeting breakeven by 2024. Cash burn this year has been high, and revenues so far negligible. So this is high risk, but could be a speculative multibagger if sales take off - chances of that happening? Slim, I would say! If it needs to raise cash again, we could be looking at a wipeout like at TWD. So it looks very high risk, but very occasionally something like this does pay off. Looks like Canaccord (very shrewd small cap investors) like it, with a 14.3% recently bought stake. Might be worth a flutter, with money we can afford to lose?
Purplebricks (LON:PURP) [Quick comment] - here’s an interesting development, on a slow news day. Shareholder Lecram Holdings requisitioned an EGM, to attempt removal of the Chairman, Paul Pindar. The result came out 2 days ago, and was 28.3% in favour of Pindar’s removal, and 71.7% against. So it failed, but a 28.3% yes vote is significant, which the company acknowledges in its comments. The new CEO says she recognises that “past performance has not been good enough”, and reckons that FY 4/2023 results “will be clear for all to see… substantially improved cash and profit performance”. Cost base has been reduced by £17m. My view - PURP still has cash in the bank, and the latest CEO’s comments today do suggest that it has made some progress. The £29m mkt cap is well supported by £31m net cash at Oct 2022. Positive cash generation guided in early FY 4/2024. Worth a speculative dabble possibly at 9.2p per share?
Graham's Section:
Insig Ai (LON:INSG) (£17m) - looking at this share for the first time, it has applied so-called “machine learning” techniques to improve and automate the ESG process for fund managers. They have enjoyed success with at least one asset management company agreeing to pay a long-term revenue stream to Insig AI. This deal, it is thought, combined with other sales opportunities, will lead to Insig AI being cash flow positive from next summer. However, the stock remains extremely high risk and is surviving now only thanks to convertible loans provided by two individuals (including the Chairman) and shares that have been gifted to it by a pair of directors. (More detail below)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham’s Section:
Insig Ai (LON:INSG)
Share price: 16.5p (unch.)
Market cap: £17m
This describes itself as “the data science and machine learning solutions company serving the asset management industry”.
It is yet to achieve much from a financial point of view:

Let’s quickly look over Monday’s interim results to September 2022, to see if there are any green shoots.
- Revenue: £950k (last year: £900k)
- Operating loss: £2.6m (last year: £500k)
Unfortunately, there are good reasons why this one is categorised as a Sucker Stock:
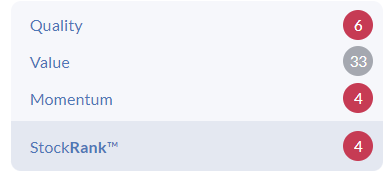
The Chairman’s statement is crammed with jargon and buzzwords. The main achievement of the company, it seems, has been to build:
…a repository of machine learning ESG company disclosures on more than 2,500 global businesses. Our database now encompasses all constituents of the S&P 500, the STOXX 600 and the FTSE 100/250/350 together with hundreds of non-listed corporates.”
These “ESG diagnostics”, it is thought, will enable fund managers to demonstrate objective compliance with their ESG mandates.
Funding - the company is expecting to be cash flow positive from Q2 2023, as it has a long-term revenue agreement with a customer that is tied to that customer’s AUM.
For now, it is surviving on convertible loans from the Chairman and another shareholder.
In addition, the company has today been gifted shares worth £1.1m by two of its founding Directors. This is a very rare event, in my experience! If you want to interpret it positively, you can see it as a reflection of the commitment of the Directors to see this company through to success.
Alternatively, you can see it as a sign that the convertible loans aren’t enough, and the company is living on fumes.
Outlook
Last month, we set out that we had prioritised and accelerated the timeline to expected profitability of the Group. This was underpinned by our expectations for the receipt of recurring revenues from sharing of management fees. Substantial investment over the last 18 months should result in payback with these revenues expected to commence next summer. Over subsequent quarters, these should grow substantially.
My view
I must admit I’m intrigued by the company’s claims that it will be cash flow positive from next summer. Watch this space, maybe?
If it’s true that they can automate the ESG process for fund managers, then in principle that is something I can see the value in.
Objectively speaking, however, this stock is clearly very high up on the risk spectrum and is not a “value” share. It will be a tremendous achievement if they can avoid diluting shareholders.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
£PURP (No holding) Paul, thanks for flagging it up, I had read recently (but forgotten) that they were proposing Harry Hill the co-founder of Rightmove to the position. Definitely one to keep on the radar IMO
WANdisco (LON:WAND) -> v interesting developments... but v high odds the exponential move is too hot too quick
THG (LON:THG) The Hut Group
On. Monday Paul mentioned the impact of withdrawal of trade credit insurance on Matalan. Today this article in the Guardian relates to THG. No holding, just hat tip to Paul for drawing attention to the risk.
https://www.theguardian.com/bu...
Hi rwh3ue,
Thanks for flagging that article about THG (LON:THG) seeing its trade credit insurance reduced. A couple of points -
THG says the trade insurer was reducing limits on unused accounts, which makes sense. However, my experience long ago was that when cover is reduced, it often becomes difficult or impossible for new suppliers to get cover.
There's an interesting footnote to the Guardian article, where obviously the company must have complained about the original article suggesting it's in financial trouble -
"This article was amended on 20 December 2022 to remove reference to THG cashflow being “under pressure”. While a reduction in insurance cover can affect a company’s cashflow, the article did not intend to suggest THG would be in serious financial difficulty because of it. As the article reports, sources close to THG say the insurance change has no bearing on THG’s financial position."
I found the CEO's comments about floating its shares in London being a mistake, and that the whole process has "sucked". Clearly self-reflection is not in his repertoire. Floating something at an insane over-valuation, promising the world, and then disappointing with poor performance, doesn't seem to register with him, in that the whole situation is his fault. He's too much of a self-publicist too, seemingly enjoying being photographed flexing his muscles. - are we supposed to be impressed or something?! It's a horrible look I think, especially on a middle-aged man, and makes me worry that the company might be led by a delusional narcissist.
I wouldn't touch THG, almost at any price.
Regards, Paul.
Lot of wailing and gnashing on Tremor International (LON:TRMR) as usual...
The directors are over compensated relative to moral heuristic of many....and I think most execs are generally rewarded too much and too easily.
Tremor execs are not over compensated relative to their US adtech peers (and they are a US company that due to history are listed here)
During the period of high share comp earnings they were significantly outperforming their peers in an operating sense
The CEO Ofer Drucker deserves to be considered to some degree as founding entrepreneur...yes the company existed already...but is re-orientation of it is massive and so far phenomenally successful. So in that regard he is more worthy of the comp than many
A significant portion of the share comp goes to staff
Tremor is very highly revenue and profit generative per head of staff...can't remember exactly but approx $650k per head
There is some element of anti-Israeli prejudice going down with the company too. A heuristic that all Israeli cos are crooked.
UK fund managers once again make an arse of themselves with how they handle their fiduciary duty. The comp structure was agreed 3+ years ago under old chairman with shares in the doldrums....they had their opp to disagree then. Rather they wait until the volume goes up and make a hugely showy but counterproductive intervention after the company has shown great operating success (got to separate from share price)...
...cynically I'd say UK fund managers are trying to push a transaction by peeing off the mgt...this is not value maximisation. If they had balls and a view to value creation/recognition they would wait for the value to be realised through this rough cycle point. Instead they want to try off load their shares due to short term emotional angst and investor pressure on them. Not good stewards of capital
Well said
Agree - I hope it is nothing more than exploratory.
I do think there is too much greed in the comp structures though. I take your point about being agreed 3 years ago but the 2 motions proposed for the AGM that were then withdrawn under pressure was an attempt to rebaseline in favour of the directors, which frankly feels like a pretty poor time to be trying it on given shareholders have seen a 60% fall.
Thanks mojomogoz for reminding us of the recent history of Tremor International (LON:TRMR)
This is fair "The CEO Ofer Drucker deserves to be considered to some degree as founding entrepreneur...yes the company existed already...but his re-orientation of it is massive" can't argue with that. Then it is all the more important for the BOD to ensure that the successful entrepreneur's interests are aligned with those of others in the company.
Your point that a high % of the compensation goes to staff is also well-made. Nonetheless I still feel that there is a mismatch between the rewards that have flowed to staff and those that have accrued to shareholders. And that the board should have been more active and skilful in managing this.
From the Simply Wallstreet analysis
'
Ofer's total compensation ($USD 18.31M) is above average for companies of similar size in the UK market ($USD 1.05M).
'
Compensation vs Earnings: Ofer's compensation has increased by more than 20% whilst company earnings have fallen more than 20% in the past year.
'
Name_________Position__________________Tenure____Compensation__Ownership
'
Ofer Druker CEO & Executive Director 3.67yrs US$18.31m_____2.54%__$ 10.8m
'
By my count Offer had made over $ 6.5 million in multiple share sales Dec 21 to Dec 22
Would anyone be able to cover Yourgene Health (LON:YGEN) (LON:YGEN) with their latest half year update & capital raising?
Yourgene Health (LON:YGEN)
Just a quick look reveals poor results with continued losses and includes a profit warning. Deep discounted placing to keep the light on. Approx 200% dilution for existing shareholders. Looks grim and desperate. Bargepole territory.
Snazzy
very very poor. They had opportunities to raise funds at much higher prices even up until recently so I am flabbergasted that they waited until they had a desperate need and had already cratered the share price 90% before raising at a further whopping 75% discount! Wow! Stewardship has been shockingly bad in my opinion. Say they will have enough funds until Q3 2023 on a baseline level of revenue post raise - that's bad and spells even greater dilution coming to my mind.
Great healthcare technology that is genuinely needed and CEO talks a good game in his videos, but the reality is an absolutely dire performance for shareholders - what have they achieved, something like a 98% capital loss in the last 2 or 3 years?! So they've basically wiped out shareholders yet are still in seat? hmmmm - draw your own conclusions to that
I have a little bit of value to add regarding £TRMR. I wrote to the company asking about the dormant shares and did the company have any plans to cancel them. This is the reply I got back from the company:
"Thank you for your email. Tremor has no intention to cancel the dormant shares. By retaining the shares in treasury, the company eliminates the need to issue new shares, including as part of its employee share incentive schemes."
When I last checked there was 42 million dormant shares that will possibly find there way back into directors pockets. No position.
ref INSG. I am NOT recommending anyone to buy this stock as, in my opinion, the BoD has failed to do what it has said it would do on more than one occassion. However, it may be worth noting that the (interim?) Chairman has purchased approx. £300k of shares in the open market since Nov 2021 and has a considerable share holding, as well as providing the emergency funding (my words)
Insig Ai (LON:INSG), no director deals, since August, showing on Stockopedia, I'm finding that on several stocks recently. I thought this had been sorted out by going to new supplier?
£25K 8th November
It is not under the directors dealings.
As Roger Bacon pointed out in yesterday's comments the LSE has suspended trading in Trackwise Designs (LON:TWD) under rule 1510 - disorderly markets. Too many trades remain unsettled. This is the first time I remember having seen a stock suspended under rule 1510 since the Russian sanctions were implemented in March, when the Stock Exchange suspended a number of Russian ETFs.
I have no specific knowledge of the Trackwise situation, but my suspicion would be that the most likely reason is that buyers of shares in the recent placement having been selling shares (as the stock has been trading at a significant premium to the placement price) but these placing shares will not be admitted to the market until 9 January (and are dependent on a vote at a General Meeting on 6 January.)
The LSE has stressed that sellers are still required to settle their outstanding sales of TWD (even though trading is suspended). It will be interesting to see if the LSE resumes trading in the shares before 9 January.
I don't think this suspension is due to any fault of Trackwise. But with the Open Offer still outstanding (where the company is hoping to raise a further £1.5m), it cannot be helping to have the shares suspended.
Thanks Wiimbledonsprinter. I'm not often mistaken for a philosopher.
John Springford - "My latest update estimates Brexit reduced Britain's GDP by 5.5 per cent by the second quarter of 2022. My model avoids the cherry-picking of data, and performs better than its critics’ methods."
https://www.cer.eu/insights/co...
AIM blue this morning! Shock ha ha
Hi Paul
A short but quite informative Edison conversation with the CEO of £WAND 14 mins from yesterday
Regards
Howard
This is really tech stuff - Any recommendations of other material to read up on would be appreciated - especially in order to understand the remark towards the end of the video - that high-speed trains create so much data...?
Hi bohenie
Go to YouTube and type in 'Wanddisco' and several vids will be there. Scan through to see which catch your attention. Additionally, WANdisco (LON:WAND) themselves have their YouTube channel where there are several vids covering their progress and technical explanations. This link should take you there
https://www.youtube.com/@WANdi...
If you are interested in this IoT large scale data capture space. Another company I follow which focuses on the IoT with regard to smart cities and also working with OEMs to capture all the data being generated by their fleets of cars, is the Manchester based company $WEJO
$WEJO is listed in the US but take a look at its website for many vids and presentations about this IoT space. Here is a link to their YouTube channel
https://www.youtube.com/@wejo_...
Here a link to their site
https://www.wejo.com/we-are-we...
Regards
Howard
Have an EV then you are a data set for where you go, how often etc. Suppose already there with the mobile but when they start charging you for the carbon you use there is no escape. 2024 fast becoming 1984.
Hi GarryC
Yes, clearly (1984) and with the insane 15 minute city regions across Oxford its beyond surveillance its pre-defined restrictions. I understand the same is proposed for Canterbury.
As an investor it can sometimes be a bit of a dilemma assessing investing opportunities versus personal value judgments. Clearly many of the new big data, AI, data capture at the edge etc ... businesses can easily have a dark side to them. Yesterday's innocuous tech becomes tomorrows dystopian power grab.
Regards
Howard
The problem I have with WANdisco (LON:WAND) is that its shares are so much more expensive than some data manipulation equivalents like Snowflake or than another meaningful comparison with very similar growth expectations, Sentinel1, an endpoint security provider. These are both market leaders with far better penetration and recognition - and comparable or superior prospects for growth and profitability - yet WANdisco is more expensive by a factor of 5x-10x. Yikes!
Hi BnB
High price might be in part due to 82% held by major share holders I suspect.
I watched WANdisco (LON:WAND) for quite a while and always was put off by wide spreads. These reduced recently in random periods in sessions.
No idea if recent rises will stimulate selling, or attract more buying. It's quite a techy play and might not keep ahead of competitors.
suspect (as others have mentioned) it might end up being bought up. The insiders have invested over 10 years building it up s they might be keen to cash in at some juncture. Also, competitors might want to incorporate the tech into their own offerings.
We shall see.
Regards
Howard
WANdisco (LON:WAND) - easy to get sucked into the story but in six or more years has not turned a profit. I'll wait.
A sky news story on £trmr last night about appointing Goldman Sachs to start a sale process. Up 16% in America yesterday. No announcement today. I seem to remember similar news stories before when the share price was low. Also 2 resolutions on share options were withdrawn prior to the recent AGM.
https://news.sky.com/story/lon...
Tremor International (LON:TRMR)
Interesting developments at £TRMR
I wonder whether the board being forced to pull their compensation resolutions, coupled with the high cost of capital they face in the public markets, has led them to conclude that Tremor is better off in private hands? The Toscafund analyst sounded less than impressed on the last earnings call, so could be pressure from them too.
Would this be their reason to buy back its own shares rather than pay a dividend I have to wonder? I hold Tremor International (LON:TRMR) in two accounts and am losing patience.
As a long-term holder in Tremor International (LON:TRMR) my perspective is that the Chairman and independent directors are not doing their jobs, i.e. representing the interests of shareholders. More accurately, "to promote the success of the company for the benefit of its members." That's in the Companies Act, it's the most basic of directors' duties.
You've got a position where the business has been successful yet the shares are cheap. The company is sensibly buying back shares in the market. At the same time it is issuing millions of new shares to its own executives, who are selling them in the market for cash. So it's a straight transfer of wealth to the management and the shareholders aren't benefiting from the share buy-backs as they normally would. The share count has barely gone down at all.
The current CEO turned the company around and deserves to be rewarded, by seeing his substantial shareholding go up in value. What cannot be right is for his rewards and those of other executives to be so large relative to the market cap and to continue regardless during the current period of underperformance. That's when the independent directors need to step in. It's not easy to get that balance right, but it's what they are well-paid to do.
Tosca have a habit of dropping stories to Kleinman at Sky News, so I infer that they are unhappy with their holding (I would be!), and want to jolly the sale process along. The directors' sales speak volumes to me.
Ferrexpo (LON:FXPO) with a cautious yet positive update. Good to see them producing and meeting contracts.
I didn't realise, until I looked just now, that Ferrexpo's operations are primarily in Ukraine.
This has been the trouble all along, I never envisaged holding Ferrexpo (LON:FXPO) as I'm not a day trader.
I held Ferrexpo (LON:FXPO) in two accounts but sold on the invasion, whilst there are a lot of its operations in "safe" areas of the country and they have managed to reroute a lot of their exports for me it just became a share where it was not in my investable territory.
I concur with the thought that it is a trading share right now, just all over the place with no rhyme or reason.
Once things reach their conclusion I would be happy to put it back on my watch list, but for now just not a sleep at night candidate.
Tommy
I do not hold Ferrexpo (LON:FXPO)