Small Cap Value Report (Weds 21 July 2021) - VINO, PCIP, LGRS, TSTL, CRL

Good morning, it's Paul & Roland here with the SCVR for Weds. Many thanks to Roland for stepping in to help, so that Jack can have a few days off.
Timing - TBC. Very busy again for company reports, so we'll get through as many as we can by mid-afternoon.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker.
Agenda -
Paul's Section:
Virgin Wines Uk (LON:VINO) - trading update for FY 06/2021, with revenues & EBITDA "marginally higher" than previously expected, following a strong finish to the year. Demand is still good. I'm warming to this share, but still want to wait and see how demand and growth settle down post-pandemic.
Pci- Pal (LON:PCIP) (I hold) - another positive trading update, with guidance given in early June now exceeded, for FY 06/2021. Still loss-making, but very strong organic growth augurs well for the future. Plenty of cash following recent placing.
Creightons (LON:CRL) - Results for FY 03/2021 look very good - boosted somewhat by one-off sanitiser sales in lockdown 1, although there were also negative hits from covid. Weighing up those offsetting points is a key point for investors to consider. Very nice balance sheet. Looks a decent company, at a reasonable price, I like it!
Roland's Section:
Loungers (LON:LGRS) - full-year results for the year to 18 April. These numbers were always likely to be poor, but the company appears well positioned to move forwards from the pandemic.
Tristel (LON:TSTL) - a modest upgrade to profit guidance appears to have been overshadowed by disappointing news on US expansion hopes.
Virgin Wines Uk (LON:VINO)
205p (up 4% at yesterday’s close) - mkt cap £115m
This direct to consumer wine eCommerce business floated in March 2021. I’ve been keeping an eye on it, as it looks potentially interesting as an investment. As with most new floats, I tend to keep my distance at first, as mishaps often occur in the early days, since so many new issues are priced to perfection, and sometimes have some underlying problems that may be hidden from view. Or they’ve enjoyed a purple patch, facilitating a nice exit price that subsequently unravels. My suspicion is that, as with another recent float, Parsley Box (LON:MEAL) there’s likely to have been a big boost to trading from the pandemic lockdowns - which are certainly not over - plenty of people are still semi-isolating, which I’m doing at the moment actually, to avoid putting vulnerable loved ones at unnecessary risk whilst case numbers soar.
Trading update on 6 May 2021 - I reviewed it here, and it struck me as a little confusing in parts, although generally positive, and couldn’t make up my mind about the share, but leaning more towards positive, but still a bit sceptical.
Virgin Wines UK plc (AIM: VINO), one of the UK's largest direct-to-consumer online wine retailers, today provides an update on trading for the year ended 30 June 2021 ("FY21").
FY 06/2021 “finished positively”
Strong customer demand in May & June 2021
Revenue & EBITDA “marginally higher” than previous expectations
*The Board considers current market expectations for the year ended 30 June 2021 to be revenue of £73 million and EBITDA of £6.3 million.
New guidance -
Revenues £73.8m up 30% on last year, and +74% year before that
EBITDA £6.4m, +45% LY, and +183% year before that - I’m impressed.
Net cash - of £8.4m at 30 June 2021, and assessing opportunities to invest cash, including “organic investment initiatives” - a bit vague, they could have explained that better.
Diary date - FY 06/2021 results due out w/e 22 Oct 2021.
Current trading - “positive sales momentum” continued into July.
Also mentions: customer loyalty, subscription schemes robust, and new customers being acquired at competitive cost.
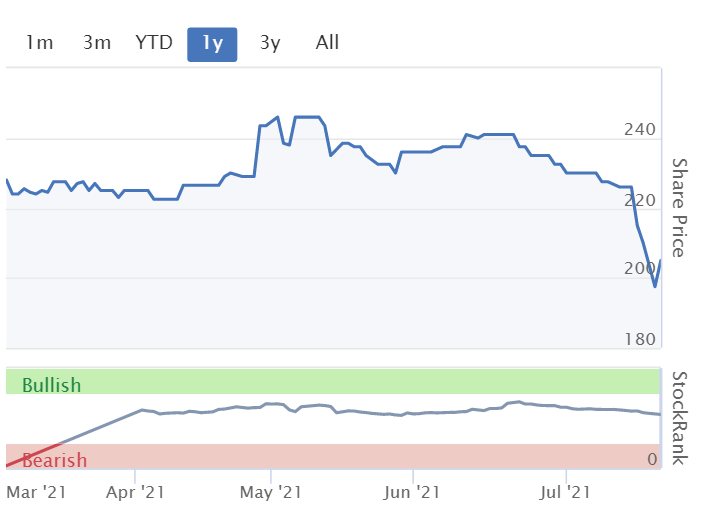
My opinion - I’m definitely warming to this share, and the recent c.20% fall in share price has gone some way to correct for my previous concern that the price was looking toppy back in May.
Overall pandemic conditions are still far from back to normal, so I think it’s too soon to be sure whether buoyant demand is likely to continue for the foreseeable future, or might still be receiving a boost from pandemic conditions?
The best way to assess any company, is to become a customer. I’ve had several orders from Virgin Wine, and the wine has generally been pretty good.
It’s subscription service is clever - I don’t actually recall signing up for it, but noticed £25 per month being deducted from my PayPal account. Then I got an email from Virgin Wines, saying you have £50 to spend on wine, and we’ll add £25 bonus to it, so that’s £75. Of course it worked a treat, and I ended up buying about 15 bottles for a couple of hundred quid. Twice. So clever marketing, and I think the Virgin name & branding definitely help too.
Management came across very well on a webinar a few weeks ago.
On balance therefore, I think this share looks quite interesting, but I’ll sit on the sidelines for the time being, to see if it continues to prosper once conditions become (hopefully) more normal, whenever that might be.
.
Pci- Pal (LON:PCIP)
(I hold)
86p (last night’s close) - mkt cap £56m
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, is pleased to announce a trading update for the year ended 30 June 2021.
The main attraction of this share is the very rapid organic growth, building sticky recurring revenues. The main downside is it’s still loss-making, and pushed back breakeven by deciding to accelerate international growth recently (which has up-front costs).
Growth is certainly impressive -
After a strong year of trading, PCI Pal expects to announce revenues of approximately £7.3 million1, a substantial increase of 66% on the prior year (2020: £4.4 million), and an adjusted pre tax loss marginally better than current expectations2.
1 The £7.3 million expected revenue is subject to audit confirmation.
2 Current market expectations for FY21 revenues is £7.0 million and an adjusted pre-tax loss of £3.6 million.
That’s a £0.3m revenue beat. Note that, as I reported here on 8 June, guidance had already been raised 3 weeks before the year end, so another increase today is a positive surprise.
An alternative KPI used by the company to demonstrate the run rate of future revenues is Total Annual Contract Revenue (TACV), running at £9.5m (up 41% in the year). This is a useful measure at rapid growth recurring revenue companies.
195 new customer contracts in FY 06/2021, almost double the prior year. It must be quite a job to handle all those implementations, but as pointed out, the software (which helps process secure payments) is cloud-based, and sold by resellers, hence the business looks nicely scaleable & can cope with rapid growth.
Customer retention - high, said to be over 100% - which muddles two factors in my view, it would be better to split out customer attrition, and customer upsells, not offset them. But nobody can quibble at a negative net attrition rate!
Net cash looks healthy at £7.5m, mainly sourced from a £5.5m placing in April 2021.
Visibility is high, since TACV of £9.5m covers most of the forecast £10.4m revenues for FY 06/2022. I think this is signalling that a beat against forecast is likely for the new financial year just started.
My opinion - I see the recent pullback as being healthy, as like many shares, the price probably got a bit ahead of itself.
Today’s update tells us that the very rapid growth is ongoing - this company clearly has a niche product that is in strong demand, with very large potential markets. It can do rapid roll-outs, to lots of clients, because it’s cloud-based & sold via resellers. Then a long stream of recurring revenues should roll in for many years. That’s such a good business model.
This latest update has renewed my enthusiasm for this share, it looks a clear long-term winner to me, for people prepared to tuck it away for a few years.
I’ve got mixed feelings on the strategy to continue incurring losses through increased overheads, to expand into new markets. Surely the main, USA market was big enough? I probably would have preferred a tighter geographic focus, and a swifter move into profitability.
That said, today’s news should mean there’s little downside risk from 86p, in my opinion (other than unpredictable short term volatility), given the very strong upward trajectory of recurring revenues.
Stockopedia drenches me in cold water, with a dismal StockRank of 22 - it doesn’t like companies that make repeated losses, a very good sense check!
Note that PCIP qualifies for a shorting screen, based on its poor Z-score. However, this has been superseded by the recent placing, so is no longer relevant.
.

.
Creightons (LON:CRL)
79p (up 10%, at 10:10) - mkt cap £51m
Creightons Plc (the "Group" or "Creightons") is pleased to announce its preliminary results for the year ended 31 March 2021.
The company forgot to include a description of its business at the top of the results statement. Looking at Creightons website, it seems to produce & sell hair, skin, beauty & hygiene products, under lots of different brand names.
The 10% rise today needs to be seen in a context of recent days “flash crash” that we saw in many shares, not just small caps either, some mid caps too. It’s bounced back to where it was last week essentially.
So many share price charts look similar, don’t they? We could have bought practically anything in Oct 2020, and made a similar gain.

.
The highlights look really good -

.
Brexit - no significant impact, which is what practically all companies I cover are saying.
Covid impact - a mixed bag - the last point strikes me as a very heavy expense of £1.6m, given the relatively small size of the company, I’d be interested to know what is within that figure -

.
Cost increases are mentioned, similar to what many companies are saying - raw materials scarce & rising in price, freight from Far East expensive. Sales prices were raised accordingly, but not enough to fully offset cost increases.
Demand for hygiene products “reduced rapidly” when lockdown 1 ended, so this looks like a bit of a one-off boost.
Dividends are being paid, total only 0.65p for the year, a yield of only 0.8%
Balance sheet - is excellent. NAV of £20.1m, less £1.1m intangible assets, gives NTAV of £19.0m, which is really strong for the relatively small size of the business. Working capital looks particularly healthy. Hence no solvency, or dilution risk here, in my view. Also I think it has scope to make further acquisitions from existing resources.
Cashflow statement - it’s a genuinely cash generative business (£6.2m operating cashflow this year, £6.6m last year).
Capex was only £869k this year (£4.6m last year).
In both years, much of the cash generation fell through to increased cash balances, so it all looks pretty healthy to me, and the numbers look straightforward, no funnies in there that I can see.
Investor presentation - it’s great to see so many companies producing results webinars for the wider investing community, a spin-off benefit from the pandemic. Companies I talk to say that it’s so much easier to do back-to-back Zooms with investors, and a public one too, at results time, so I think this will persist beyond covid.
The Company will host an online presentation for analysts and investors at 2.30pm on 28 July. To register for the presentation please follow the link: https://bit.ly/CRL_FY21_results_webinar28721
My opinion - I can’t find any broker notes unfortunately. Since the company has a big private investor following, it would be helpful if they could make sure some broker research gets out there, either through a commissioned research company, or by switching to a house broker that publishes its research on Research Tree. To borrow a phrase from Jeremy Corbyn, broker research should be for the many, not the few!
Overall, these results are very good I think, and the company also gets ticks in the boxes of its shares still being reasonably valued, and having very sound finances, and producing a pretty solid operating profit margin.
I like this, it’s a decent company at a reasonable price.
The main issue to research, is to estimate how much future profits will be affected by the fall away in one-off sanitiser revenues, but offsetting that should be reduced costs, and improved trading in the areas where demand reduced. It might be safest to assume profits might slip back a bit from the level reported today?
.
Roland’s section
Loungers (LON:LGRS)
274p (pre-open)
Market cap £282m
“Material market out-performance post re-opening”
Loungers runs two branded chains of cafe/bar/restaurants across England and Wales -- Lounge and Cosy Club. The group has 175 outlets in total and now intends to resume opening sites at its pre-Covid rate of 25 sites per year. Seven new branches have already opened since May.
The focus of both brands is very much on all-day opening, casual dining, etc. There aren’t any outlets in my area, but I have heard good things about them from friends and family.
Loungers’ financial year ended on 18 April, so this included numerous periods of closure and restrictions. Against this backdrop, I don’t think today’s full-year numbers look too bad. I’ll start with a look at these and then move on to look at the company’s trading since reopening in May.
Financial highlights
Last year’s performance was obviously affected by periods of closure.But furlough, business rates relief and some rent waivers meant that Loungers’ costs were contained during lockdown.
I’m encouraged by the results that the company did achieve during the periods it was open.
- % of weeks able to trade: 34%
- Revenue: -52.9% to £78.4m (FY20: £166m)
- Gross profit margin: 41.8% (FY20: 40.8%)
- Adjusted EBITDA: £13.9m (FY20: £28.8m)
- Adjusted EBITDA margin: 17.8% (FY20: 17.3%)
I’m impressed to see that revenue only fell by 53%, even though the company’s sites were closed for 66% of the year. Similarly, both gross margin and adjusted EBITDA profit margins were stable when compared to the previous year.
My reading of these numbers is that when Loungers’ locations were open, they were operating profitably and with strong capacity utilisation. Given the year we’ve just had, I think that’s the best that can be expected from an operator in this sector.
Exceptional costs: Loungers’ accounts for the past two years show plenty of moving parts and exceptional costs. In FY20, the company reported £15.3m, mainly relating to its IPO and to impairment charges (presumably triggered by the first lockdown).
Exceptionals fell to £1.3m last year, relating to Covid costs.
Although I’m not generally a fan of heavily-adjusted profits, I think these costs all look reasonable and are likely to be genuine one-off costs. So I’m not too concerned.
Balance sheet: More importantly, Loungers seems to be emerging from a difficult year with an undamaged balance sheet.
The group’s net debt is broadly unchanged at £144m (IFRS 16 - including lease liabilities) or £34.3m (IAS 17 - excluding lease liabilities).
That seems like a positive result to me. In both cases, I believe the group’s leverage looks manageable. I’m not concerned about the balance sheet, which was reinforced with an £8m placing last April.
Trading since reopening
Management are very bullish in today’s results on trading since reopening, claiming “significant” outperformance versus the wider sector. The numbers certainly seem encouraging:
- Underlying like-for-like sales +11.6% for 17 May - 18 July versus the same period in 2019. This excludes the impact of the reduction in VAT.
- Non-property net debt has fallen from £34.2m in April to £18.2m on 11 July, thanks to negative working capital. What this means, I think, is that the company saw a cash outflow when it initially restocked its outlets, but is now benefiting from customers paying for their food and drink before Loungers needs to pay its suppliers. This is how supermarkets work, too.
The company says that it’s invested heavily in slimming down its menus, reconfiguring its sites and improving outdoor space. Many of these changes are expected to deliver lasting benefits going forward.
Loungers’ locations are also thought to have helped - the company is mostly small towns and suburbs, not travel/tourism/office hubs.
My view
Today’s results and commentary confirm my view that Loungers is well run and financially sound. I don’t see any reason why this business can’t return to profitable growth from this year onwards.
Plans to open 25 new sites per year seem ambitious to me, but progress so far does seem encouraging. Management appears to have a sound strategy and good operational execution. I’d guess that property market conditions are favourable for new tenants, too. Securing new units at reduced rents could provide a tailwind to profitability over the next few years.
Are Loungers’ shares worth buying? The stock has recovered strongly and is now trading above pre-Covid levels, despite (modest) dilution from last year’s £8.3m placing:

Consensus forecasts for the current year put Loungers on 28 times forecast earnings. That seems a full price to me, given that this sector is competitive and relatively low margin.
However, Loungers does seem to have the potential to become a best-in-sector operator. Such businesses can sometimes continue expanding for a surprisingly long time. Wetherspoons is one such (past) example, in my view.
I’m not sure if I have the conviction to buy, but if I held Loungers’ stock today, I’d certainly be inclined to keep on holding.
.
Tristel (LON:TSTL)
594p (-10% at 08:50)
Market cap £283m
Infection control firm Tristel makes disinfectant wipes and foams that are used to clean medical devices after examinations. These are typically routine procedures such as endoscopies and ultrasounds.
The company also has a smaller but growing operation producing surface disinfectant wipes.
Both product ranges are built around the company’s proprietary cleaning chemicals. These appear to have some moat-like characteristics, including patent protection and regulatory barriers.
This highly-rated growth stock has been a 10-bagger since 2014:

However, Tristel’s share price is down by 10% as I write, following today’s full-year trading update. Something seems to have upset the market. What’s happened?
“Positive signs of recovery”
Despite today’s share price drop, today’s update actually appears to be a modest upgrade to previous guidance.
Updated guidance: For the year to 30 June 2021, Tristel now expects to report revenue of £31m, with adjusted pre-tax profit of £5.5m.
Previous guidance in April was for £31m/>£5m.
Last year’s results (2019/20) were £31.7m/£7.1m.
The background to this is that sales of medical device cleaning products have suffered over the last year due to the widespread cancellation of routine outpatient activities.
The company says that its seen demand for these products improve since April as outpatient departments have gradually returned to normal activities.
Although sales of surface disinfectant wipes have grown strongly over the last year, it’s important to remember that these are still a small proportion of total sales. Tristel’s half-year accounts show that although sales of surface wipes rose by 80%, they still only accounted for 12% of total revenue.
Investment update/US progress: Today’s modest upgrade to profit guidance doesn’t seem to explain the share price slump, unless the market was expecting a more substantial upgrade.
I’m not sure, but I wonder if today’s sell-off is linked to the second piece of news in today’s update, which relates to Tristel’s US expansion hopes.
Back in 2017, Tristel invested in “a medical device company focussed upon women’s health”. The investment is said to have led to a close collaboration that’s yielding some “exciting” product development initiatives.
Like Tristel, this unnamed company’s shareholders wanted to break into the US market. Their strategy was to try and sell the business to a larger medical device company which would have the resources needed to succeed in the US.
We learn today that - so far - this strategy has failed. No buyer has been found. This investment was previously valued at £0.8m on Tristel’s balance sheet, but will now be fully impaired - i.e. written off. Although the investee company is said to be trading as a going concern, it sounds to me like there’s a risk it could fail.
This isn’t a disaster for Tristel, which had net cash of £8m at the end of June and can afford small speculative investments. But it’s disappointing and suggests that hopes of an indirect entrance to the US market have been stymied.
My view
Tristel’s largest client is the NHS, but the group generates more than half its revenue abroad. However, the company has been trying for years to gain approval to sell its products in the US - by far the world’s largest healthcare market.
So far, progress has been slow. The company has promised an update on current US FDA submissions in October, so we may learn more then.
In today’s update, CEO Paul Swinney reflects on a difficult year for the company, commenting that this “ordinarily stable and predictable business has been disrupted by both Brexit and the pandemic”.
However, Mr Sweeney does say that the company is now seeing signs of a return to normal.
I don’t have too many concerns about Tristel’s financial performance. The company has a track record of consistent growth and strong profitability:

What concerns me is the company’s share price. Even after today’s fall, I estimate that Tristel shares are trading on 65 times FY22 forecast earnings. The dividend yield is less than 1%.
Although I expect Tristel to continue generating incremental growth in its main UK and EU markets, I don’t think the outlook justifies this valuation.
In my view, the stock’s high rating is only likely to be justified by a successful entry to the US market. As things stand, I don’t know how likely this is or how soon it might happen.
As a result, Tristel is too expensive for me to consider. However, I do think this is a good quality business that’s likely to continue performing well after the pandemic.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
thanks Paul, I'm glad it's not just me struggling to make sense of it. They are an interesting company with a strong moat but they seem to be stuck in low gear
Northern Bear (LON:NTBR)
Grrrrrrrrrrrrrrr - what on earth are Northern Bear doing releasing year end results at 8.21 am? unless its a deadline day surely thats a complete no no? its all very bizzare - i am guesing share price reaction today is more to do with the timing of the news release than the actual figures contained therein - not very clever.
Northern Bear (LON:NTBR)
On the face of it pre tax profit of £1.2 mill excluding intangible w/offs is a fairly decent outcome compared to £2.00 milion last year. They have managed very well with the covid related issue they have. Dividend scrapped so as not to offend others - at least this means all the profits and more have gone to improving the balance sheet - net cash position at year end of £3.1 mill is nice albeit their balanmce sheet is still not the strongest - having said that i hahe been saying that for years and they now have current assets exceeding current liabilities with no long term loans - so not bad as long as their big debtor book mostly pay up as expected.
at £10 mil market cap for a company that can probably earn £2 mill profit in a decent year still seems cheap as chips. Even cheaper with todays reaction to results not being good - numbers seem fine so i have to put that down to poor timing of release.
I will continue to tough this one out.
Hi Paul, I would love to know your thoughts on Revolution Beauty which was admitted to AIM on Monday 19 July 2021.
Past accounts for Revolution Beauty can be accessed here:-
https://find-and-update.compan...
find-and-update.company-information.service.gov.uk/company/09915831/filing-history
This needs the https:// put in front of the above address as it looks like it won't let me paste the full address on here.
Their full accounts only go back to 14 December 2015 and yet they’ve stated they’ve been trading since 2013.
They were called TAM Beauty (Distribution) Ltd before Revolution Beauty and before TAM they were called Freedom Beauty (London). I can’t find any actual full accounts for them under these two names.
Your thoughts would be appreciated if you have the time.
Many thanks.
Revolution Beauty is on my list of things to look at. Quite a few smart investors have told me that I will like it!
A coffee break thought
I appreciate that I skim read the SCVR when I get a chance, sometimes this is during the day like the last couple of days to clear my head of work and enjoy my coffee, and other times it it three days later after 10pm. But Paul, Jack and obviously today Rolland's your work, thoughts and points of observation are much appreciated!
Anyway after my posts the last couple of days regarding a "Sea of Red" and a "Stage 4 Portfolio" obviously today is the reverse, and almost but not quite a "Sea of Green" though the green is really only making up a bit though not all of the red. Or maybe just giving me a bit of positive reinforcement bias?
Another thank you for the thoughtful and honest replies. It is good to get a dose of think about what is really important and focus on that for a few days.
So tonight is look through the bookshelf and chose a few things, both read and unread to take on holiday, and start to get the kids to think about toys to take with them too.
Tommy.
ps. I still hold, though my mum (well me) sold Anglo Asian Mining (LON:AAZ)
just seen below you have already answered my question to another person, thanks
Hi Paul
on yesterdays report you said ref #SOS "I’ll do some more work on this later", did you have chance to take a further look at them, thanks
I'll type up my notes from the Sosandar (LON:SOS) webinar today, later this afternoon. As mentioned in another reply below, I don't see any point to going through the historic figures, because the very strong current trading is more important & has completely changed the outlook, very much for the better.
Regards, Paul.
Hi Paul - I also watched the webinar and share your thoughts. Until this update I viewed Sosandar (LON:SOS) positively but with some degree of scepticism, as indeed others were right to point out certain key areas as amber flags. A lack of consistency/transparency on growth metrics being the main concern. However, for me recent trading (and particularly how well the company is selling into selected 3rd party platforms like Next and John Lewis) the outlook has completely changed. It now strikes me that Sosandar (LON:SOS) could be a major player over the next few years and hopefully no longer need placings to achieve this. Risk/reward now looks heavily skewed to the upside.
Director buy at Sanderson Design (LON:SDG) (I hold). Christopher Rogers (NED) purchased 35,000 shares at 167.4p (£58,590 worth) - transaction date 20th July. This increases his total holding from 75,000 to 110,000 shares (representing 0.15% of company’s total issued share capital).
Skimming the annual report his current remuneration is £48,000 and In the small print it appears C. Rogers received a bonus of £76,563 during his time as Exec Chairman, 2018-2019 paid at the completion of that contract. Looks like a decent buy vs. previous holding and current remuneration.
A busy morning for me with 4 of my shareholdings Bloomsbury Publishing (LON:BMY), Loungers (LON:LGRS), Wickes (LON:WIX) and Royal Mail (LON:RMG) reporting!
I like Loungers (LON:LGRS) without really having to think about the figures good as they are. Why?
1. I like to eat there as they provide good quality food and drink for the price and it is good to invest in businesses that you actually visit and like.
2. Everyone else I know who has visited speak favourably of them.
3. They are open all day and do terrific business
4. They are ambitious with plans to expand and further improve the business. Subsequent to investing I have seen Paul mention a couple of times that his contacts believe the management to be of top quality.
I fully expect to see good share price moves in the future. Portillo's in the US has 68 restaurants and is expected to IPO on a valuation of between $2.5 and $3.0 billion! If only!!
Lots happening today. Impressive results from Creightons (LON:CRL) and great updates from Bloomsbury Publishing (LON:BMY) and Ekf Diagnostics Holdings (LON:EKF), plus a very interesting announcement from £SPSY. All of which I hold.
At some point Creightons (LON:CRL) will make an acquisition, but having met the very able management team lead by Bernard Johnson they will be patient and I trust them to get it right. It was also a nice touch in March, from a commercial and collegiate perspective to award all staff share options. On average staff have each been awarded 4000 share options at 74.5 pence, exercisable between 3 and 10 years from 16th March 2021.
All the best
Hi Paul, just wondering if you are planning on writing a bit more detail around the Sosandar (LON:SOS) results from yesterday? Thanks
Hi Andy,
Hi Paul, just wondering if you are planning on writing a bit more detail around the Sosandar (LON:SOS) results from yesterday? Thanks
Possibly. I'm attending the webinar today at 11:30 shortly, so will jot down key points from that, and might type them up here later, or tomorrow.
I don't think there's anything to be gained from ploughing through the results from Sosandar (LON:SOS) because the growth in Q1 FY 03/2022 is by far the most significant development, which I flagged up yesterday. Plus the cash has been filled up again with a recent placing, so no cash or balance sheet concerns. Hence I think it would be a poor use of time to pore over now historic & largely irrelevant results.
I did buy a few more this morning though personally, as mentioned yesterday here, I think the company has reached an inflection point, where it looks to be heading for revenues doubling to about £25m this year, which gets it to breakeven, or close to it anyway. Hence there should not be the need for any further fundraisings, and I could see the shares re-rate usefully from here. It's a big thing when a growth company jumps the hurdle from repeated losses, into profits, because people then model in the operational gearing from further sales & margin increases, and can come up with some exciting numbers.
I'm quietly hoping for £100m valuation here in say the next year, based on the above.
Risks? Mainly that sales growth suddenly slows down. Also fashion risk - if they get the product design or quality wrong, and customers desert them.
Regards, Paul.
Fantastic and much appreciated. Sosandar (LON:SOS) is in my top three and I have hung on in since Jan 2019. I am hoping this is going to be a multi bagger (and maybe even a 100 bagger, if I give it long enough). I really believe in the niche Sosandar (LON:SOS) is serving (quality to an older market) and with the big shift to online sales, they have a lot to play for (fingers crossed:) )
Nice to see Roland here again.
Nice to see Roland here again.
He's great isn't he! Delighted that he was available to cover, and Roland's articles are very much in tune with the value/GARP approach that Jack and I also follow, so all consistent. Glad you approve :-)
Regards, Paul.
All 3 of you are fantastic people, many thanks for the work and going the extra mile for this community.
Sthree (LON:STEM) H1 presentation to analysts. As you'd imagine STEM (Science, Tech, Engineering, Maths) recruitment is firing on all cylinders. Net fees up 10% yoy, ptp +114%, EPS +140%. Outlook ahead of expectations, although cautious. Video & podcast.
Sosandar (LON:SOS) FY21 results webinar today, 11.30. Register here. Paul commented yesterday, 'Today’s update tells me that the business model is now proven, which makes the shares much more attractive than before when it was highly speculative.' See full write up here.
Creightons (LON:CRL) FY results as others have already commented, management continue to deliver. Large boost from soap & hand sanitiser. See management present at a webinar next Wednesday 28.7.21, 2.30pm. Register here.
Also, Tekmar (LON:TGP) Capital Markets Day, tomorrow Thursday, 4.30pm. They service the offshore energy market, so an interesting space. Register here.
I don't mean this in any way as criticism against the managers but it seems to me if I was in hospitality everything I would say would be extremely positive. This is because the Covid issue remains present and balance sheets are fragile and another lock down will take a lot of investor support. My view is there probably won't be another lockdown but still seems far from certain.
There has been a number of comments over the last few days on the weakness in South African PGM stocks. Those interested should see Rio’s RNS today that it is closing one of its furnaces at Richards Bay because of feedstock shortages caused by the unrest. While Rio’s Richards Bay facility is far from the platinum fields, it is near South Africa’s key port.
Ref South Africa
Norcros had the following to say today about the situation.
"Whilst we have experienced some disruption from the recent period of social unrest the impact on our business to date has been limited and the current situation is stable. The safety and wellbeing of our employees remains our priority as we continue to monitor the position."
Bushveld Minerals (LON:BMN) reported today that there had been some limited issues with goods transport at the port, however that was easing now and no impact near the mines.
my read into this situation is that it is immaterial to real etc valuations of resource operators in SA and any SP weakness is a buying opportunity. The market doesn't like uncertainties and generally over reacts. Some great prices out there on Tharisa (LON:THS) Sylvania Platinum (LON:SLP) Bushveld Minerals (LON:BMN) etc currently. Sylvania Platinum (LON:SLP) is bouncing back today for example, up 8% on no news of its own.
So why are Sylvania Platinum (LON:SLP) shares up 10% today?
Some other UK shares are also leaping up on no news, what have a I missed?
Trading update from £BMY ( I hold) for 4 months looks good but the price has hardly moved. Looks like it is in line with market expectations
Bloomsbury Publishing (LON:BMY) (I hold)
This is my new favourite holding and whilst today's update didn't blow the lights out, I was nonetheless pleased with how things are progressing.
First, let's get the only negative out of the way.
The Academic year-on-year percentage published today is incorrect (it's +33%, not +35%.)
A silly error for such a small update.
And now for what I thought were the positives:
Looking at the stock report it would also the fastest growth rate since 2016 if momentum can be maintained.
The company has forecasted 25% revenue growth (from £12.5m ---> £15m this year) so there's a good chance this will be exceeded.
The BDR contribution margin is c 80%, with minimal capex and what appears to be relatively fixed costs, so most new revenue here falls straight to the bottom line.
The customer retention rate is >90%.
Average monthly revenue back in 2019 was £530k.
By my rough estimate, average monthly revenues for the first 4 months of this year is now c.£1.3m.
Combine this with the 81% contribution margin + £7.6m of fixed costs (both figures communicated by the company) would generate an operating profit of £5m.
In my opinion this profit deserves a premium rating.
Note the highlighted BDR figures below (if you can see them!) are my estimates.
---
H2 has generally been the larger period for the company, so if trends continue then I can imagine this year's forecasts being beaten.
Of course, these are not ordinary times, which probably explains the sensible "in line with expectations" announcement this morning.
Nonetheless, a good first 4 months to the year and I remain a very happy holder.
A
Very difficult to judge the future “normal” for Bloomsbury Publishing (LON:BMY) IMHO. If it’s anything like the last four months, they seem excellent value at the current SP, but I have no idea how to reach a sensible judgement on the growth or not future of the retail part of the business.
Bloomsbury Publishing (LON:BMY)
Hi Shanklin
Completely agree with you on the legacy publishing service, which is why I like the BDR product so much.
It's sticky, it's been growing very well for years and capex looks minimal (it was £1.1m last year.)
It would be good to have a view on Fonix Mobile which seemed to hit a positive note in its Trading Update but has continued its downward price path.
Many thanks Abtan,
Your analysis is really helpful to read - for those of us that do not have the time to go into this level of detail.
I was really impressed with the revenue growth y-o-y, but then disappointed to read it is only "in line" with forecasts for turnover and PAT.
Y/E 2021 = 185m revenue, of which 49.4m was delivered through P1 to P4 (26.7%).
Y/E 2022 = 193m forecast revenue, of which 63.1m has already been delivered in P1 to P4 (32.6%).
This suggests they will deliver lower revenues P5 - P12 in 2022 @ £130m, than the same period in Y/E 2021 @ £135m.
I'm wondering if this is credible or are they being cautious in today's update?
Why should Bloomsbury Publishing (LON:BMY) share move up, if it's only in line with market expectations, often stocks with in line results fall back.
Bloomsbury Publishing (LON:BMY) are always very cautious and then update as the year moves on. They are making acquisitions and I believe they will continue to grow to the extent that it is one of my larger half dozen holdings.
Good morning Paul, will you be looking a Fonix Mobile (LON:FNX) , I know you wrote positively about them back in Jan after they floated back in October 20? Just wondered if you views had changed. Time permitting of course. Thank you.
Hi Lefty99,
Not sure I'll get around to Fonix Mobile (LON:FNX) as there are so many other things reporting, and I'm not confident in my understanding of the niche it operates in. Someone said something about the end of 3G might hurt it?
I do remember having a Zoom with the CEO of Fonix, and he answered my questions very openly & well, and was amazed that I had read the whole of the Admission Document lol!
Regards, Paul.
No problem Paul, totally understand, busy reporting day today.
Lefty99 - It looks like a solid update to me for Fonix Mobile (LON:FNX) . Continued growth in profits and Total Payment Volume, as well as continued growth in customers (13%) (which can only be a good thing as one risk here is customer concentration, even though they’ve never lost a major customer – and today’s update confirms there has been no churn).
I believe today’s numbers are very slightly ahead of the Finncap forecast who maintain their price target of 200p. At the current price of 128p it feels good value to me for a company that continues to grow, with great ROCE and ROE metrics, “over 99% of income of a repeating nature”, and has a big potential to expand internationally (which they are about to begin in Austria, as well as another European territory in the coming months). They also pay a healthy dividend (though you probably could argue they would be better off building up their cash reserves, and / or reinvesting in the business).
Must admit I wasn’t aware of the potential issue Paul mentions with 3G – it’s not something that jumps out at me as being a problem for them but I’m quite possibly missing something – it’s been known.
I hold, and have added on the recent weakness.
I agree (and hold). I did a deeper delve into £FNX because of the share price tale off recently but I found much to like. Structurally sound, good profit generation, competent sounding and financially committed management. I ended up topping op at about 128.
I interpreted this update as cautiously positive and find the drop counter intuitive (but then I find much about short term share price movement counter intuitive). Unless there are operational issues in the pipeline which have passed me by, I can only think Fonix Mobile (LON:FNX) is currently misunderstood by the market.
any chance of a look at Paypoint (LON:PAY) after their quarterly trading update. I sold out earlier this year but looking to get back in possibly
Had a look at the update - very difficult to pull out what matters, but seems to be in line. Does much depend on how many of its 26000 store customers are 'convenience' which may thrive, and how many aren't and may quietly decline? Also seems to be coming late to ecommerce. But certainly a lot going on.
thanks for your thoughts. I agree they have a lot going on. Maybe they need to focus a bit more
Hi Kevin,
any chance of a look at Paypoint (LON:PAY) after their quarterly trading update.
I've spent about 20 minutes looking at this, and my head is spinning on its axis LOL! It's so complicated, that I would have to spend the rest of the day unpicking everything, so I've abandoned it, sorry.
Paypoint did come up on my radar recently, as being potentially interesting - the dividend yield looks very good. But the bills payment side of the business seems to be in decline, and it's buying other things to offset that decline. That's about as far as I got. Sorry about that.
Regards, Paul.
I agree, its a case study on how not to do a trading update.
On Paypoint (LON:PAY) I will persevere this weekend to read through. Its got a very unique moat - the Paypoint One terminal in 26,000 stores. It cannot be easily replicated. If they can find the right way to unlock value, they will effectively collect high margin rent from convenience stores up and down the country.
Morning all. VINO etc. The practise of surreptitiously obtainaining subs has been around for a while and seems to be employed by just about every online IT company and retailer from Amazon down. Its very convenient and obviously hits the mark particularly well in USA. To me it seems like borderline theft like the persistent professional football fouler who gets away with many fouls which pay off big time. Personally I think no frills or silly deals Aldi and Lidl have some fantastic wines at very fair prices, as do Waitrose and MKS sometimes. There are also still some very good friendly and knowledgeable independent vintners often to be found at farmers markets these days. Of course we're here about shares and so the likes of VINO and WINE have been terrific investments. Speaking of which I hope this isn't old news to Saga holders, I meant to post yesterday
The start of the week was pivotal for us in the UK but also for SAGA:
Head of trade sales Iain Powell, speaking to TTG at Spirit of Adventure’s naming ceremony on Monday (19 July), said the line had retained 70% of existing guests since the start of the pandemic, putting Saga in a good position for forward business.
Powell added the line had seen “astounding” forward bookings through the trade, which had surpassed 2019 levels for three of the last six months. “It shows the demand that’s out there and coming through travel agents – we can’t thank them enough for what they’ve done,” he said.
Powell claimed Saga’s cruise capacity was 45% sold for next year, prompting it to bring forward the launch of its 2023 programmes to November and December instead of next spring. The line’s Saga Experts online training site is also being bolstered with new e-learning modules, plus additional content and ship imagery.
There are also plans to add online meetings with travel agencies, along with a ship visit programme starting in the autumn that will focusing on Spirit of Adventure in Dover and Southampton, with visits organised in line with Covid protocols.
Hi Paul,
Any thoughts on the deal £DIS announced yesterday? I hold
Large placing in order to fund an investment in a new whisky distillery west of Glasgow, which also gives them the ability to create a 'home' for their gin brand Blackwoods by producing it on the same site. Seems to be driven by the new non executive director they brought in, Roland Grain, who has funded half of the capital raise. In addition to the shares issued now, there are a large number of warrants maturing next year.. hard not to be a bit upset by the dilution.
Thanks!
Morning ar7268!
Distil (LON:DIS) is too small to interest me. I can't see why it's listed, and has been for about 20 years now. Imagine how much all the costs of listing would amount to over that time, and for what in return?
Good to see that a Non-Exec has funded half the placing, as you say. The 2p placing price looks more than fair to me, I can't see why the business as it stands is worth anywhere near the £10m market cap. Trouble is, as you also say, the warrants whip away a lot of the potential upside, from existing holders.
I'm perplexed as to why you would want to hold this share at all, when there are thousands of other, much better companies out there to invest in?
Regards, Paul.
Thanks Paul!
Attraction for me was their consistent record over the last 5 years of growing revenue, FCF (to a lesser degree) and net income and the fact that they were small meant that if one of their brands gained even moderate penetration into the market the sp could increase relatively easily. In addition, they have no debt and hadn't issued stock since 2016/17.
In essence, it looked like a well run company with significant upside potential; a bit of a speculative play (its a small part of my portfolio) but with downside protected somewhat by the underlying quality. As you say, with the upside potentially capped by the warrants i think i may need to re-evaluate.
My morning smallcap tweet:
Tricorn (LON:TCN) Fintel (LON:FNTL) Argo Blockchain (LON:ARB) Spectra Systems (LON:SPSY) Foxtons (LON:FOXT) Arena Events (LON:ARE) Tristel (LON:TSTL) MySale (LON:MYSL) PCI- PAL (LON:PCIP) Fonix Mobile (LON:FNX), Wickes (LON:WIX), EKF Diagnostics Holdings (LON:EKF), Bloomsbury Publishing (LON:BMY), Norcros (LON:NXR), Speedy Hire (LON:SDY)
Tricorn (TCN) Strategic Review and Formal Sale Process. Cost increases squeezing profit so co won't have necessary cash to make the required investment to deliver the turnaround strategy and return to profitable cash generation. [SP=5.5 Cap=3m]
Fintel (FNTL) sells non-core Zest Technology for initial £10m. Guides H1 in line. [SP=220 Cap=213m]
Argo Blockchain (ARB) planning to dual list in US. [SP=85.5 Cap=326m]
Spectra Systems (SPSY) Aeris banknote cleaning process shown to deactivate covid. "When Covid-19 was emerging as a pandemic, a multitude of central banks expressed interest in whether Aeris could both remove soiling as well as deactivate SARS-2." Will co ever make a sale of Aeris? [SP=148.66 Cap=68m]. I hold.
Foxtons (FOXT) confirms rumour that it may sell its mortgage broking business,. [SP=46.75 Cap=152m]
Arena Events (ARE) repays £2m loan from shareholder Lombard Odier Investment Management, saving £0.4m PA. What, a 20% int rate? [SP=15.02 Cap=49m]
Tristel (TSTL) guides FY(June) rev £31m and pretax at least £5m. In line? Co "confident that sales and profits growth will resume this year and the investments made in people, systems and new market registrations will lay the foundation for strong growth in the years ahead." [SP=660 Cap=311m]
MySale (MYSL) guides FY22 rev materially ahead of market expectations as FY21 rev in line, U/L EBITDA A$4.2m ahead of market expectations. [SP=7.1 Cap=62m]
PCI-PAL (PCIP) guides FY(June) rev up 66% to £7.3m and adj pretax loss marginally better than expectations which are £7m and -£3.6m resp. "We start the new financial year in a strong position. With our TACV accumulated to £9.5m, we already have high visibility towards the market forecast revenues for FY22 of £10.4m." [SP=88 Cap=57m]
Fonix Mobile (FNX) guides FY(June) rev and profit comfortably in line with mgmt expectations. Maintains 100% client retention. [SP=128 Cap=128m]. I hold.
In line: Wickes (LON:WIX) EKF Diagnostics Holdings (LON:EKF) Bloomsbury Publishing (LON:BMY) Norcros (LON:NXR) Speedy Hire (LON:SDY)
Norcros (LON:NXR)
Another day another norcross trading update we have been blessed with frequent updates lately here.
This is presumably scheduled update ref first 3 months of the year and company has quoted progress is in line with expectations for the year - nice simple summary of where they are at - zilch confusing corporate speak thankfully.
Note they are outperforming their markets and sales are up 19% compared to the same period in 2019(31/3/20 year end) - comparison with 2019 meaningless. The interesting thing here is that current broker forecasts per stocky are expecting only 2% revenue growth compared to ye 31/3/2020 so they really are well up for this 3 month period ref sales. It strikes me that in line quote today seems ultra conservative - perhaps some brokers will upgrade if they agree with my basic maths?
One word of warning is that costs for all companies at present are on the rise so it may be threat less may be dropping to the bottom line - don’t think this is their busy time of year either so I am happy with inline with at present.
Pe per stocky back down to under 9 again here And the ranking given by stocky is a comfortable 99 - they currently should be in a position to be able to afford to splash the cash (secured facilities mind) on new acquisitions if they can find owt of value - pretty sure they will actively be looking since they spiked bs k into net cash position.
Hi rmillaree, (LON:NXR)
I have held Norcros for a number of years now PER has also been low and traditional commentary is that share price has remained cheap in comparison due to the Pension deficit. Personally I have been amazed that the company has not been subject to a takeover bid particularly when the share price has not really correlated to the increase in profits over a number of years and in fact during Covid when it sunk to the depths of £1.25. Again recently the share price accelerated to £3.44 only to sink back again to £2.85 before latest update as with most stocks. It seem to me that the Market Makers manipulate certain stocks the movements up and down which I can't fathom and which I fund hugely frustrating this stock being one which on fundamentals imo still appears cheap. (LON:PFD) had a similar problem with a Pension Deficit which appears to have been restructured and share price now sits at 3 times its former levels, accepting that other conditions, trading have impacted also.
Science Group ( LON:SAG) has also released excellent updates upon which the share price has gone up but then sinks back again for no apparent reason.
On Norcros (LON:NXR) how much revenue do they get nowadays from South Africa?
I was looking at Norcros (LON:NXR) this weekend and asking that same question...
Revenue – UK 220.2 (68%)
Revenue – South Africa 104.0 (32%)
Revenue – Group 324.2 (100%)
Underlying operating profit – UK 26.9 (80%)
Underlying operating profit – South Africa 6.9 (20%)
Underlying operating profit – Group 33.8 (100%)
I do like the look of them but decided due to the SA situation to hold off, despite revs weighted more to UK and profits even more so as the margins appear to be better. I'm not a big news hound so it feels like another situation that would probably catch me off guard.
Morning All,
Paul would you be able to look into Creightons (LON:CRL) please
Thank you
elliot
What do you think of Creightons?
Fully diluted EPS of 5.8p seems like an awesome increase and makes the stock look cheap at 72p.
Bit of a fly in the ointment, group revenue increased to £61.6M, an increase of £13.8m. Of this £14.6m was in hygiene products that had £0 sales the previous year - do they expect this to reverse and therefore revenue will fall this year?
We have no way of knowing because Creightons (LON:CRL) don’t have any forecasts, either their own or broker that I can find. Even the SR doesn’t have any estimates.
The stock has fallen recently, this lack of clarity about the future is probably why.
Really decent results from Creightons (LON:CRL) (I hold) - look at the long-term chart! It is still looking like reasonable value on a p/e basis. Today is a slight beat on the revenue expectations the company set out in a presentation in November last year when they said they expected £60m revenue for the year.
Also worth noting that H2 saw decent sales growth of 21% - my worry was H2 might drop off given the benefit of hygiene products as we saw with e.g. Venture Life (LON:VLG) . So this gives me some encouragement that this momentum has continued into the current financial year.
The lack of an outlook statement is frustrating but note to newcomers to this stock that Creightons (LON:CRL) does not usually provide one. Somewhat annoyingly they tend to have a barebones RNS with no broker coverage, and then do a much more transparent presentation to investors which this year will not be until 2.30pm on 28 July! (https://bit.ly/CRL_FY21_results_webinar28721)
For me this is a buy and hold share given the long-term track record.
The one disappointment is its own direct to consumer sales are still small at £1m despite the pandemic .
Creightons (LON:CRL) I've up-date my evaluation at https://www.stockopedia.com/co...
Still feel the company needs re-rating as a growth stock.
BSV
Nice summary. I hold and am hopeful about the future of this company but that hygiene products success might come back to bite them this year. And I think they recognise that with their holding of the final dividend rather increasing it.
Morning Paul
Virgin Wines (LON; VINO)
I was speaking to a friend about wine recently. He wanted to know what I spent on a bottle of wine?
I thought for a moment and replied: "about 45 minutes"
Michael
Hi Paul
Will you be commenting on Next (LON:NXT) excellent (surprise brought forward two weeks) TU here or on on the Boohoo (LON:BOO) discussion in the context of possible read across to the latter, even though way above SCVR mkt cap.
Thx.
Regards
Michael
Sparkling results from Next (LON:NXT) in their usual clear delivery. Am very much hoping for read across into £BOO after my top up at 269.9 on Monday's dip (have owned since 22-25p days). Another request for Next (LON:NXT) pls Paul.
Hi Michael,
Since you asked, yes I've had a quick look at the impressive update from Next (LON:NXT) today. I think it definitely has read-across for Boohoo (LON:BOO) and Asos (LON:ASC) (I hold both) because it confirms that, despite strong pent-up demand for physical shopping, online is still the main area of growth. This confirms my view that a lot of the shift to online shopping in the pandemic has probably been structural, and is not likely to return to the High Street fully. Many people have got used to ordering online, which leaves High Street operators with a big dent in their business model. I wouldn't touch any fashion retailer unless they're doing half their sales online now.
Another interesting point, is that the online fashion retailers Boohoo (LON:BOO) and Asos (LON:ASC) have both de-rated recently, see chart below - they've ended up very closely correlated, so maybe the ESG worries at BOO weren't that important after all, since Asos has slipped by the same amount and hasn't had ESG issues.
Next (LON:NXT) says something very interesting about the weather. As everyone in the sector knows, weather being good or bad has a massive influence on clothing sales, especially at this time of year. Asos spooked the market by saying sales softened in the last 3 weeks of June - but I would have expected that, as it was tipping it down with rain at that time. So there was no reason for Asos shares to sell-off, nor BOO to follow it down. That's a potential buying opportunity in my view.
Also, I think the M.East licensing deal for DEB was terrific, and isn't in the forecasts. A friend googled the M.East DEB stores, and they're huge! Run by a giant conglomerate. So that deal is likely to be very decent additional profit for BOO. I think there could be serious broker upgrades late this year, into next year, because DEB has the potential to be seriously lucrative for BOO - my contact there told me they see DEB as "the jewel in the crown", once it's fully launched & fully stocked, with a big marketing budget to drive traffic to it. that's expected this autumn/winter. See the BOO mgt webinar a few weeks ago, they were all raving about the potential from DEB. Yet there's hardly anything in existing forecasts for it.
NEXT mention weather today, saying -
2. The onset of extremely warm weather at the end of May and start of June. Growth significantly slowed once the very warm weather passed.
That should have turned around in the last week or so of hot weather, so expect more positive current trading from fashion over the next month or two. Also, with people going out more, then going out clothes will be in greater demand.
I think BOO looks stunningly good value now - likely to smash forecasts, and only on 19 times next year's forecasts. That's the wrong price, unless something goes seriously wrong. I know some people are worried about the growth of Chinese competitor Shein, maybe that's holding things back?
Regards, Paul.
Thank you so much Paul for your comments on Next (LON:NXT) and £BOO. I concur with all you say but it has been a tough two months (portfolio under water YTD, having been +12%) and have taken a psychological battering so needed a bit of confirmation bias from you!
Boohoo (LON:BOO) is my 1st/2nd/3rd largest holding depending on price volatility of it and a couple of other stocks (Anglo Asian Mining (LON:AAZ) and Games Workshop (LON:GAW)) at an average price of 276p. Would top up if it wasn’t already 11.3% position but also wanting to keep some (a lot?) of cash on the side lines for now.
Regards
Michael
PS Will keep and eye on Shein but feel that Boohoo (LON:BOO) has a lot of momentum behind them as a brand and this from the Shein web site is just plain odd IMO. (And I can find nothing on the site about where the product is manufactured, ESG standards etc):
The Production Chain
Once the design has been prototyped, the product officially enters into the production chain. At this point, advanced equipment and professional handiwork come into play. When we visit the factories, we sometimes lament the production-related inefficiencies. However, we are very pleased that through effective communication and cooperation, we are able to see shortened production cycles to release new products. We pay special attention to details like fastening and ironing, so we can present to you a flawless design. [My emphasis]
Keep Up With The Latest Fashion Trends
Sheingals are stylish and elegant. We keep up with the latest fashion trends around the world and quickly bring these styles to the market. So whether you're looking for bohemian dresses, patterned shirts or chic swimwear, we've got what you want and we'll keep you at the leading edge of fashion at any time. [My emphasis; does this mean we rip off other designs?]
Regards
Michael
Glad it's not just me. Was thinking how smart I was to get +12% ytd a couple of weeks back. Now at 0%. Still, most of my portfolio has a high Q rank so hopefully H2 will see a rebound - pubs are open and party season will start early this year. We've already organised a big work night out for next week.
Suspect that we are not alone but people tend not post their downs.
Personally I am happy with my holdings and am riding out the volatility but it is unpleasant!!
Regards
Michael.
Its comforting to know that the last 3 weeks have not just been me suffering, where I have gone from 35% YTD down to 13% as of close yesterday.
When you read on Twitter that some people are down 3% on the week, I'm thinking I lost that most days, what am I doing wrong. I now think, I haven't lost 22% of the years profit, I'm still a healthy 13% up.
I would have found it soul destroying previously with the constant drip down every day, but my 3 years membership of Stocko has shown me (at last) that choose wisely, my own buying criteria is now so strict, there are only 3 shares on my list, actually 4 but cannot bring myself to buy a Kazakhstan cement company. Of my current 10 holding 6 are above a stock rank of 90, the rest are SCVR highlights and I do not want to sell any.
So thanks for Paul, Jack and Rolland and all the other contributors here on SCVR for sharing their experience. At times like this its comforting to know, we are not alone.
Shein is definitely a worry.
Amongst the Insta and Tiktok crowd, many more Shein haul videos in the last few months compared to Boohoo (LON:BOO) or PrettyLittleThing.
Problem with Shein is that the quality is super variable. However, its so cheap that the allure is there amongst the teens and 20s.
Really appreciate this extra comment on Next (LON:NXT) Paul, thanks!
As a Sosandar (LON:SOS) holder, an interesting data point.
£NXT LABEL third-party brands (full price) sales up +64% YoY. Sosandar (LON:SOS) didn't break this out into its own performance in its trading statement. Suffice to say this hints that Sosandar (LON:SOS) is seeing good sales growth through NEXT marketplace.
The other interesting thing was that Next (LON:NXT) say total full price sales +20% YoY, but they really struggled in Adult Clothing (-6%). This pales massively in comparison to Sosandar (LON:SOS), where orders tripled (+200%) YoY, revenues up +256% YoY, hence the inference is that revenue per order is up too, which would imply they did more full price sales.
Its looking like the Sosandar (LON:SOS) brand and range is really hitting a sweet spot in the market, where they are selling volume and at full price.
Wish Sosandar (LON:SOS) would do a detailed trading statement like NEXT! So much clarity.
(I hold Sosandar)