Small Cap Value Report (Weds 21 Oct 2020) - D4T4, ZYT

Good morning, it's Paul here with the SCVR for Weds.
It's a fairly quiet day for news today, here's what has caught my eye so far;
D4t4 Solutions (LON:D4T4) - Trading update & Capital Markets Day (CMD)
Zytronic (LON:ZYT) - Trading update
.
Timings - I'm hoping to get most of it done by the 1pm official finish time.
.
I'm having technical problems, and all my work just got erased. So am having to re-write it from scratch.
D4t4 Solutions (LON:D4T4)
Share price: 192p (down 12% at 09:49)
No. shares: 40.2m
Market cap: £77.2m
I follow this company regularly, having written about it 5 times in the last year. Here is our archive of comments, which you can find for any company under the “Discussions” tab on the StockReport of every company;
.
In August the company put out an in line with expectations update.
Today’s update - is for H1 from April- Sept 2020, in FY 03/2021. This also says trading has been in line with expectations, which doesn’t make sense to me, because the figures are poor.
H1 revenues are only £5.09m (down 42% on H1 LY) - this is blamed on delays to new contracts, which have now slipped into H2. This has happened before with D4T4. The good news is that once before, I recall the company had a very weak H1, but it recouped the shortfall with contract signings in H2. Therefore management assurances here do have credibility, because of the good track record of delivery on previous assurances.
Despite gradually moving towards a SaaS model, D4T4 does still seem to heavily rely on large, lumpy contract wins. Recurring revenues are now up to 55%, but that is likely to be flattered in a low revenues half year.
Strong interim net cash position of £12.08m
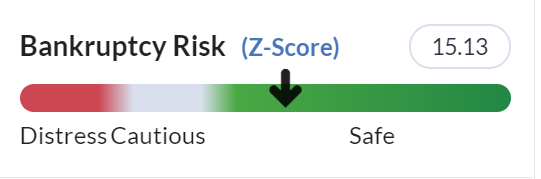
I’ve checked the last balance sheet, and it’s very good, with plenty of net cash. This business is securely funded, and there are no worries about solvency.
This is confirmed by a healthy Z-score;
Operational details, and contract wins, etc, are explained in the RNS, I won’t regurgitate all of that here.
Outlook
Ongoing focus on existing and new strategic partnerships continues to grow our increasing pipeline of opportunities across the business
The board remains confident in delivering a solid finish to FY21, in line with management expectations
· Prospects for H2 strongly underpinned by:
o High level of annual recurring revenue from new licences signed during the second half of last year and support and maintenance revenues
o Strong visibility on new contracts due to initiate during H2
o Significant pipeline of new business in negotiation with existing clients wishing either to increase the footprint of the Celebrus CDP software or to extend the use of the Celebrus hybrid Customer Data Management (CDM) platform solution
"Overall, we are in a good position with a number of contracts in final negotiation and a strong pipeline with an increase in new opportunities. Based on our organic business, H2 annual recurring revenues and the depth and quality of contracts in final negotiation coupled with a strong new business pipeline, we remain confident about our prospects for the full year."
My opinion - it’s clearly a poor H1, and we’re not given any figures on profitability, but with revenues this low, it must be a loss for H1. I’m not keen on the way this has been glossed over in the trading update.
That said, the outlook comments are upbeat, with plenty of justification provided for expecting a stronger H2, which has happened in the past.
I’ve just read a very helpful update note from Finncap, which reassures on the achievability of H2 revenues, which need to be over 3 times H1 revenues in order to hit full year forecast. That sounds a stretch, but Finncap reckons a lot of it is already in the bag.
So the company needs a very strong H2 to hit forecast, and that’s only 6.6p EPS for FY 03/2021. I’m not sure how a share price of 192p makes sense in that context, which would be a PER of 29 times, for a company which is now in a downward earnings trend (over the last 3 years).
Despite transitioning to SaaS, the company still seems heavily reliant on large contract wins. So it’s difficult to forecast earnings, and even more difficult to work out what this share is worth. Software companies with recurring revenues do tend to be highly valued though.
I can’t make my mind up on this one, so will sit on the fence.
CMD - the company says it is providing a virtual capital markets day, but I can't find the details for it. The RNS says a recording will be made available on its website afterwards.
A CMD is often a precursor to an equity fundraising, although I cannot see why D4T4 would need to raise fresh equity, given its strong balance sheet. Alternative reasons can be: to drum up buying interest, in order to allow an existing holder to exit. Or to raise funding for an acquisition. Or management just want the share price to go higher. I don't know what the reason is for D4T4's capital markets day.
.
Zytronic (LON:ZYT)
Share price: 110p (down 4% at 11:27)
No. shares: 16.0m
Market cap: £17.6m
The company has had a rather grim year in revenue terms for FY 09/2020, but I’m impressed that it seems to have avoided making heavy losses despite greatly reduced revenues.
At the time of our Interims in early May we explained that, due to the effects of the COVID-19 pandemic, anything except short term forecasts were challenging, and the prospects of a positive return during this financial year would be remote.
Sales for the year to 30 September 2020 have reduced to £12.7m (2019: £20.7m) and the business has remained profitable before exceptional items relating to restructuring and furlough costs. EBITDA for the year ended 30 September 2020 is positive.
The Group's cash position continues to be strong at £14.0m (2019: £13.1m) and has increased by £1.6m since 31 March 2020, benefitting from a reduction in working capital.
As mentioned before here, the cash pile is now equivalent to the bulk of the market cap, with the business thrown in almost for free.
Outlook - uncertain.
My opinion - this share is of interest mainly to value investors. With a whacking great cash pile sitting there doing nothing, it does at least underpin the company’s valuation.
I think shareholders should be pressing management to pay out the surplus cash. It could give shareholders £10m of surplus cash, which would be c.62p per share. There’s no justification for sitting on such a large cash pile, as a comfort blanket. Shareholders could put the cash to better use.
My main concern with this share is that management have previously mentioned some long-running projects are reaching end of life. Thus the company seems to be experiencing a gap where old projects are winding down or have ended, but not enough new projects are coming through to replace them. Obviously this is why the share price has been depressed.
Overall I think risk:reward looks quite good here. Investors are paying virtually nothing for the business itself, since the share price is mostly covered by the company’s own bank balance, most of which is surplus.
Despite poor revenue, it has remained profitable, before exceptionals. The cash pile is intact, indeed rising, as working capital unwinds.
Hence the share price is nicely underpinned, even if performance remains lacklustre. So the upside potential is in for free. A surge in new orders could see financial performance improve, and that could cause the share price to rise.
Hence little downside risk, but upside in for free. That seems quite decent to me, as a tuck away and forget type of share.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

126 comments
Time spent on bulletin boards during working hours must be v detrimental to productivity.
False positives and false negatives are all part of something call the table of confusion. That's a great name in itself, and there are many derived ratios as you can see.
There is a related plot called the ROC plot which can be used to tune the "cutoff" point of your test to get the best possible classification quality. (Yes - no test is born with a fixed false positive ratio. It's chosen by its designers.)
For stock pickers, it is worth pointing out that Bayesian classification is not just for diseases. You can apply it to stock picking, where the PPV (positive predictive value) is often the important ratio. You don't mind missing good stocks (false negatives) but for the set you do pick you don't want too many false positives.
(I'm rather amused that Wikipedia describe these concepts as part of "machine learning" (and hence AI) when they've been around since before computers were even a "thing". It's just bog-standard statistics really.)
Tullow Oil News very encouraging today - Could be the beginning of the long-awaited turnaround look at the 290M Market cap Vs the 575M they are about to receive...https://www.bloomberg.com/news...
Hi Paul, could you elaborate on the Finncap research note in general terms. Are these put out by the Brokers who follow each company and are in the public domain, or are they for their existing investment clients?
Finncap reports you get for free here - https://researchlibrary.finnca... - as you can for from some other brokers e.g. Edison, Hardman & Co. and Progressive Research. Paul uses Research Tree where a lot of non-free Broker research is also put. For that you have to pay £25 a month.
Be aware that someone has to pay for free research and often it is the company on which the report is done, so it is not entirely independent.
I was thinking of joining Research Tree. There are 2 options for the subscription; £8 per month for 3 companies and £25 per month for unlimited following. Does anyone know if you go with the £8 for 3 companies - can you change those companies which you wish to follow on a regular basis or have to stick to the original selection?
£8 per month seems reasonable if i can switch companies in and out.
Hi OldSchool05
I was notified of your comment/question by Mr Stredder of Mello so I thought I would answer.
Yes you absolutely can change your 3 companies. Each selection must be held for a minimum of 1 month, after which you are able to swap in other companies by visiting your profile page.
Obviously if you have any issues with it, you make an incorrect selection, or we don't have any research on any of your selections then let us know using the webchat feature and we will change the selection for you without needing to wait a month.
Hope that answers your question. Happy Thursday everyone!
Cheers
Rob
Thank you very much indeed Rob. Best wishes
Hi Paul, I have noticed that from time to time you lose all your work and you have to start from scratch again which can be extremely frustrating. This sometimes happens to me, even when typing emails. So what I do to overcome the problem is....
Everytime I get to the end of a paragraph I highlight all the text I have written and then CNTL C (ie, Copy) all my work. Should I then lose the document or email I have just written then all I do is... CNTL V (ie, Paste) and everything I have previously copied then magically reappears again. It saves me from having to use many choice words!
PS, thank you Paul for all the excellent reports you keep producing, I find them very informative.
If you have access to a product like onenote that autosaves, Ctl-A (select all), Ctl-C (copy), tab over to Onenote, Ctl-V paste :)
It's fully searchable too, so you can find specific text and companies if you have a page per day.
google docs would be another useful option to author the text in - every modification (eg each letter entered) is saved instantly.
I've not used Google Docs, but yeah, anything that saves each character as you type will save lots of heartache :)
I use Onenote too . It’s great for organising your thoughts .Among other things I have a page for each Company in my portfolio. It’s easy to put in links to extra website data on each page.
Bought in on Boohoo (LON:BOO) at 250p they are very cheap now compared to Asos (LON:ASC) and Next (LON:NXT) and they have double the margins of Asos (LON:ASC) and double the growth rate with US sales doubling since last year. The audit news is completely a non-event for the business and Khamani (who I think is very good along with Caroline) is putting his money on it.
with respect the audit news is not a “completely non event”. That is misleading. The audit news is poor and with it comes risk. Risk that a tender process will not materialise in time as those willing to tender wait for the parliamentary committee to see if there is any reputation risk to their brand. Risk that Boohoo (LON:BOO) need to step down to tier 2 firms.
That said I am largely long term bullish on Boohoo (LON:BOO) Myself but do not underestimate the impacts and effects the market and particularly institutions take to audit processes.
If they will have to appoint a Tier 2 auditor, then I will invest in them too as for them will be a good contract. Win-win situation (last famous words??? ahahah time will tell). I hold.
how does this stop them selling to 16 to 24 year old ladies?
Bullseye! Who cares about about how “institutions” (institutional investors) respond to changes in auditors. I am interested in the business.
Arent individual investors? It has often been a signal.
I beg to differ, they are likely to go with Ernst & Young and move production out of the UK and pay people even less so well done to those on their high horse for costing UK jobs but Boohoo will be fine.
I want to also point out that no institutional shareholders have sold shares since the news broke and their biggest even bought shares at 312p, above where it is now.
Couldn’t agree more David.
It is very easy to dismiss or start to filter out the noise that disagrees with your point of view in a situation like £BOO. I said before I think the question of S has now been answered (at least as far as it should be) - Boohoo (LON:BOO) employed businesses that were paying below the minimum wage - they are sorting it - it’s done. More importantly, their last set of results seemed to indicate that the negative publicity is not affecting their customers or sales in any meaningful way.
The PWC RNS is a fascinating new twist however. While in one way, it could be nothing - just PWC removing themselves from low margin reputation risk business, it also could be the first warning that there are actually serious issues below the surface with Boohoo (LON:BOO) - honestly as observers we just can’t know. We can’t afford to simply dismiss this though either. G is even for a fashion business like BOO, by far the most important of ESG for investors. We have to have confidence our money is being protected.
I’ve decided that I’m willing to roll the dice and have bought in 4 times this week at an average price of £2.52 (this is a big position for me). My guess is this is all just noise - amplified by the short sellers who really have it in for this company. My original valuation of £3.60 went up to £3.85 after the last RNS. However, I will probably start to unwind this position somewhat at £3.30+ - we’ll see at the time. I need confidence in both the company and the market and I’m finding both hard to find right now...
Boohoo (LON:BOO) Next (LON:NXT)
Thornabian
Bought in on Boohoo (LON:BOO) at 250p they are very cheap now compared to Asos (LON:ASC) and Next (LON:NXT)
Hmmmm interesting - i was slightly surprised that boohoo would be seen as cheap compared to Next at present. Not sure what metric you are using - but the comment has piqued my interest.
I have held both in the past and would hold both again if the price is right - so i am semi fanboy on both fronts - i do have slight red flags with boohoo though - but they have more scope for growth i think that compensates for that extra risk.
Anyway lets look at 2022 expected earnings and pe's
Next market cap £8.39 billion expected 2022 profits £484 mill - pe of 17
Boohoo market cap £3.1 billion expected 2022 profits £130 million - pe of 24
Looking at this the differential between the two is not as much as i would have expected factoring in the consistently higher growth at present that boohoo seems to be churning out. So compared to historical norms where boohoo has had consistently higher premium rating i would probably agree that at these shareprice levels (boo 250p next 6300p) boohoo looks somewhat "the better bargain" at present - albeit its more expnsive on basic pe measure i am using - that probably shouldnt be a shock factoring in the recent shareprice decline that boohoo has had.
I would say in deference of next - the next 2022 forecasts look very conservative to me they made £599 mill profit 2019 and £610 mill 2020 - so the £484 mill 2022 probably still has some covid element attached to it - once covid issues subside i suspect we could expect earnings to be back at the £600 mill level+.
With boohoo - i don't worry that it is necessarily the case but it has crossed my mind that they may currently have covid related tailwinds that are helping boost sales as presumably less people are visiting stores and buying more online which should benefit them - this may reverse somewhat when shopping is less of danger to ones health?
Growth rate and growth rate beyond one year. Then factor in segmental reporting: Boohoo (LON:BOO) US sales have doubled in one year and are still very small in a huge market but it shows they are hitting a significant infliction point there.
I didn't say Next or ASOS were bad, just that Boohoo (LON:BOO) has better margins and far better growth making their market cap vs the two, much better value. Static valuation measures don't necessarily mean something is value if it doesn't grow more than its competitors.
With boohoo - i don't worry that it is necessarily the case but it has crossed my mind that they may currently have covid related tailwinds that are helping boost sales as presumably less people are visiting stores and buying more online which should benefit them
But rmillararee, doesn't more or less the same apply to £NXT? After all, they appear to be attempting to transform much more towards an online business.
Yes, you could say that, once covid is behind us then the online Next sales will revert back to their physical stores but one could just as easily say that, whilst Boohoo (LON:BOO) 's sales have benefited from customers being unwilling to visit other suppliers' physical stores, maybe these "new" customers will like the Boohoo (LON:BOO) experience and stay.
One could also argue that Boohoo (LON:BOO) 's sales would have been even stronger had their customers wanted/needed even more clothes to go to places that have been prohibited/restricted (clubs, pubs, cinemas, Ibiza etc. etc.).
Disclosure:- I hold both Boohoo (LON:BOO) and Next (LON:NXT) and am happy to continue doing so.
I hold both too. But when Covid is gone I will be on airlines, cruise operators, restaurants and travel companies. The survivors.
Can you share your list with your picks in these fields? Thank you.
You do have to wonder why the likes of Next haven't spun up a "challenger" - advertise for recent graduates, get them to create a brand and a design philosophy but give them the seed capital and access to the larger corporate resources. Let them go wild with some experienced retailers acting as mentors.
Next (LON:NXT)
You do have to wonder why the likes of Next haven't spun up a "challenger"
I suspect that next simply can't compete against boohoo on price and make a decent roi - that's the one thing boohoo have always been able to do is make decent margins on pretty low average order values. If they did start up a competitor it could also end up affecting the margins from their normal fare.
Price is not the only thing to compete on :)
If you look at what SOS are doing, you have to wonder why the likes of M and S, Next etc aren't doing this. The banks have tried to set up their own versions of challenger banks to break out of the static groupthink ways of working :)
Creating a billion pound biz is easy isn’t it. Just need a few young graduates and some very sensible, suit-wearing mentors.
Who said it was easy?
Loads of IT Companies have "garages" where people are sent to explore ideas and create new products, services and revenue streams. Plenty of them generate significant amounts of revenue. I can relate to one idea that started life as a health check to generate billable revenue, then became a way to automate health checks, then expanded to multiple products, and is now baked into a major cloud provider's backend.
Boo and Sosandar both started in a similar way.
Every billion dollar business started with an idea. It's easy to do nothing, it's even easier to do nothing and sit behind a keyboard and moan at others about how hard things are.
Next is a business that is loved more by its shareholders (as Wolfson is good operator and articulate communicator) than its customers. Boohoo is a business that is loved more by its customers than its shareholders. I will take the latter every time.
You should also consider the beta of the two companies and what the risk is of achieving those returns. Boo has a rather higher beta than Next so you might get a greater distribution of return from it.
Since there is a lot of talk here on the fashion industry and like myself Paul has been known to hold Next (LON:NXT) (although I don't think he does anymore?) there is some negative comment today about an equal pay inquiry and potential tampering with evidence by destroying documents (allegedly). The article is published by Alliance News so I hope this link works: https://www.morningstar.co.uk/uk/news/AN_1603256614600102000/next-accused-of-destroying-documents-ahead-of-equal-pay-claim-case.aspx
I continue to hold.
Im just wondering if there is such an accusation on Next (LON:NXT), why the share price hasn't tumbled?! It is therefore not illogical to say that £BOO's recent moves downward is a panic selling and overreaction to the situation. After all, will buyers in US care who the auditor of Boohoo (LON:BOO) is?! Of course No. I believe people who have sold it (apart from traders) will not be very happy in near future. (I hold).
That was Boohoo (LON:BOO) response to the enquiry as the whole fashion industry pays people 50p per hour in Bangladesh but the media are upset about reports of people being paid £3.50 in Leicester.
People can argue that the cost of living is higher but they are not forced to work there and can find better, higher paying jobs. Having competitive salaries is all part of a competitive economy, the focus on minimum wage for the whole of the country has damaged that because the whole country doesn't have the same cost of living and people are in different circumstances.
This is just a long way of saying, this sort of news doesn't really impact the fashion industry from a business sense, just short term selling from 'reputational' news...although it is frankly hypocritical from them (media and others).
We either enforce the minimum wage or we don't. Many disagree with it but it's law. If it's not enforced then the honest and lawful employers face a disadvantage against the unlawful. That is corrosive to society.
I hold Boohoo (LON:BOO).
That wasn't my point, the point is people care about low pay in the UK but not in another country, hypocrites.
Is this an investment board or the Guardian comment section?
Some seem too quick to thumbs down posts just because someone expresses an opinion they disagree with. What’s the betting the thumbs downers (just like some of those who moan about BOO posts here) themselves contribute nothing useful investment wise?.
Thornabian is entitled to his opinion that some people care about low pay in the UK but not in another Country (e.g Bangladesh at 50p an hour sometimes). I agree with him but if I didn’t I wouldn’t thumbs down the post. Also his point applies to some of the media comment. They too seem obsessed with exposing BOO but disinterested in much worse going on in deprived Countries. Nor are they commenting on exploitation of workers in the factories supplying so many in the clothing sector. Anyone just relying on media comment could easily think it applied to BOO only with all others in the clothing sector, squeaky clean!
Is the boo lens that overpoweringly distorting that all economic history and fact should be bent to its narrative?....its a shoddy casual moralising you are inflicting upon us.
I gave you a thumbs down for the above Ken as the comment is pure nonsensical whataboutery with a bit of faux moralising thrown in. Thornabian should stop whinging too...wear his down thumbs with stoical pride ;)
It is economic nonsense to compare the wage of Bangladeshis to Brits. And it is economic suicide to seek the 'justice' of paying them like Brits. Nothing against the good people of Bangladesh (who I regularly enjoy the culinary delights of....well adapted for crude British taste of course).
Clothes makers in UK should obey minimum standards. All durable growth anywhere globally transforms to highly standards based if it to escape the well documented middle income trap. Japan and South Korea were abuse and pollution driven hell holes going back many decades for example as they did rapid catch-up...but they managed to adapt and institutionalise and so capture and spread their wealth at a societal level. Brazil is a superb example of repeated failure to make the leap despite seeming to have the necessary mojo.
Just think how much you pay your barber in UK (or other service providers). It can seem extortionate when compared to next to nothing cost for personal services elsewhere in the world. But that is how and why we have prosperity....there is no cutting wages to competitive prosperity, particularly of the least affluent in a society. This is not a politically driven view. Prosperity is not sustained through cheap labour.
Arguments that we should be pleased to have the industry here regardless of wages paid are entirely bogus. A society with decent level minimum standards in provision of essential goods (housing, education, health, etc) ends up paying in many much more expensive ways to compensate. There is nothing good or noble in the Leics garment nexus.
If well run productive UK garment manufacturers can't survive in the UK then that means competitors elsewhere have some form of explicit or implicit subsidy. Subsistence wages count as such. So do poor environmental standards, indentured labour, subsidised non market priced capital or subsidised power too (all found in China...and why we struggled to compete). It is very very rare that in a 'free market' productivity and proximity don't compensate adequately for cheap labour alone.
I knew it was only a matter of time before you appeared to give your really long responses, I haven't posted here for a few months and some things never change. :-)
But I will answer you because you are contradicting yourself, you are basically saying we should have free markets but control wages.
That is also the very definition of anti-competitive and your silo view just means all jobs will go to somewhere willing to allow the true free market in the sense of supply and demand across borders, rather than in one jurisdiction.
Demand in the sense, if people do not like the standards of a company then they can shop elsewhere - but they don't.
Hence, my point about hypocrisy of those criticising £Boo because £3,50 was in the news but their competitors are paying peanuts in another country....
You either force offshoring of jobs or you destroy supply, neither is a good solution.
This is what has happened for 20 years in Europe.
Dear Thornabian. Welcome back!
I'm sorry you don't like my posts as they are too long. At least my inanity tends to be concentrated in one spot and so very easy to ignore. But don't you think it is far better than be inflicted with rat-tat-tat of serial bitesize inanity polluting the stream?
Global 'free markets' don't exist which is why I had in quotes and concepts of Ricardian equivalence across variable jurisdictional governance standards are intellectualised nonsense. GATT was an attempt to make fairer markets and reduce unfair terms of trade so as we would jaw-jaw not war-war and then some countries went further with varying degrees of free trade agreements.
Since industrialisation no country has risen to 'first world' economic breadth and sophistication without gouging those already at that level to some degree (and I'm not claiming the 'first world' played fairly the other way in terms of exploitation). China is the example par excellence...so much so that it has risen to global dominance and displaced a huge amount of western capability. We've been very tardy in recognising the cost. Trump is awful...but he is creation foretold by (the equally as awful at times) Jimmy Goldsmith (look up some of his interviews (https://www.youtube.com/watch?...)on trade, politics, social conditions, etc on GATT. Super foresightful...probably as he was a businessman rather than economist, politician or policy wonk so saw things as they are rather than how he hoped. Farage, Trump, European reactionary right-wing all come from ignoring the obvious message he gave.
You are victim to hackneyed concepts of free markets and perfect competition in the argument you present that 'if people don't like the standards of a company they can shop elsewhere'. Companies/countries don't present their ugly underbellies and consumers don't go looking for them (nor do the press mostly as real journalism doesn't pay). And it remains nonsensical logic to compare a British wage for just about anything to an emerging market one where people really can live on much much less. You haven't even attempted to make faux free-market Ricardian equivalence type adjustments to your argument....extension of your logic means that a country like UK should give up seeking to provide high levels of education and healthcare as a public good and leave it to free market competition with, say, Bangladesh. A reversal of several hundred years of enlightenment progress and the 're-serfing' of the British work force. I assume you don't really mean that....even if that is less positive for Boohoo (LON:BOO) ;)
I put it to you Thornabian that you have an ultra siloed spreadsheet like view of global competition and pricing....
(I would explain more but I think I am over my permitted verbosity quota so I'll leave it there...)
PS In everything the USA is a special case....that may be becoming a more normal case in the coming decade and in that lies a lot of global change and disruption.
You have it the wrong way around. Barbers can charge high wages because there are high earners to pay for the good quality personal service that someone is prepared to pay for.
That requires a high skill, high productivity workforce.
You can't force high wages and expect prosperity. You just end up with a lack of productivity and the removal of work to somewhere cheaper. Eventually the world will run out of places that are cheaper and everyone across the planet will have moved up a level. There is no shortcutting that.
IGPJ -> entirely wrong
UK barbers earn better than Dhaka barbers as they have a broad population of ordinary people that have adequate disposable income. Its quite chicken and egg but it certainly isn't the trickle down of high pay uber productives.
Domestically focused activities particularly services in highly developed nations are notoriously unproductive. Japan is example par excellence as their aggregate economy is astoundingly persistently good in productivity and innovation gains. But that comes from their industrial capability open to international competition. Its true everywhere.
Unfortunately some people believe we are all made more competitive by cheapening services labour....the evidence is fairly unequivocal that we create domestic deflationary forces, increase indebtedness to maintain consumption, reduce security and mobility for non uber productives (PS I don't view most professional services as productive...just highly waged).
Of course high wages doesn't force prosperity but that is a ridiculous axis to judge a society on, and ridiculous basis of argument. And it obviously more clear that forcing lower wages on many viewed as less productive does not create prosperity either. There have been many errors made in US, UK, Europe since the 1930s but it is hard to argue that spreading the wealth has not had a role to play in creating massively advanced and prosperous societies with living standards of poor relative to rich unimaginable 150 years ago.
Well said, better than I put it and I don't owe it to any of them to explain it, nothing I said was not factual.
I stopped posting here for quite a while because it has become like a Twitter feed of self-importance rather than people properly discussing investments or companies.
BTW I don't disagree with what you said about enforcement but how can you justify the same minimum wage in the North of England vs the London surrounding areas where cost of living is completely different?
From an economic point of view, how is that good for business and competitiveness as a nation?
People here from their down votes are very smug about that fact but it doesn't escape me why Europe has been in constant demise for 20 years whilst Asia has grown at an incredible rate, we just aren't competitive in many areas.
I believe that there was collusion between some of those firms paying less than the minimum wage and the workers themselves.
The firms were aware that the affected workers were also claiming social benefits that they may not have been entitled to.
Systemic and ingrained abuse and a muddied situation.
"One factory’s managing director admitted workers were getting minimum wage. He explained that staff wanted to claim benefits so he was under pressure to pay less than minimum wage, and they would leave if he paid them more."
https://www.shropshirestar.com...
The suppliers were third party, not part of Boohoo anyway but I haven't heard about the collusion point though, is it just a rumour?
The independent enquiry found Boohoo did nothing wrong.
FTSE100 fell below 5800 this morning. Bp (LON:BP.) hit another 52 week low today. Smaller banks such as Metro did so yesterday. Construction stocks such as Galliford Try Holdings (LON:GFRD) (despite its cash pile) are hitting all time lows daily.
Many small cap stocks have not been hit yet; indeed a number of small cap resource and bio stocks have been bought recently to almost crazy market caps. Is this just punting? Novices chasing hyped rubbish pushed on twitter and message boards? Possibly; I would not want to be in some of these stocks when they start to fall. There seems to be plenty of appetite for discount placings though.
The amazing Novacyt Sa (LON:NCYT) shows no sign of stopping and hit a new high today. I hold and see it going much higher myself although a stock that is up 165 fold on the year.....the percentage gains of a further move up are almost insignificant by comparison.
Novacyt Sa (LON:NCYT) there it is! This is one management that have deserved every penny of their salary, options, rewards!
52 Week High1,000.00
52 Week High Date21-Oct-2020
52 Week Low 6.5052
Week Low Date29-Oct-2019
I think you’ll find BP hit a new 25 year low now just a 52 week one. I worked there for many years and feel the new CEO has rather lost the plot.
I think its about 35 years but I cannot find a 50 year chart for BP. Below 200p would be extraordinary and I am sure many personal pensions are heavily invested in this stock. They were talking about investing heavily in windfarm tech but its all a bit late now as prices have soared. I do worry about the UK economy if BP and Shell turn into dust. I agree with you; I don't think they have a clear strategy for the future.
this didn't appear in either of the news lists below (but thanks HollandSmith and MrContrarian) however it caught my eye;
Real Estate Investors (LON:RLE) - £2m share buyback announcement from yesterday and large director buys (£382,000) announced today.
https://www.stockopedia.com/sh...
this continues to be paying a decent dividend, plus their rent collection is improving from the initial covid crash. I think the share price has the possibility to recover very well in the longer term.
their recent trading update also clarifies that their exposure to much of the covid related property worries is limited: "No material exposure to indoor shopping centres, out of town retail, department stores or prime retail/fashion locations"
Anyone who has fallen in love with a share may relate to this weeks IC podcast interview with Tim Harford.
Edit - deleted the link because it didn't work for some reason.
Anyway search for Investors Chronicle podcast Tim Harford and you should find it. It's dated 10/19/2020 (US format I know).
Or this link may work https://play.acast.com/s/inves...
This link doesn't seem to work for me, anyone else?
It is probably the IC paywall. Just copy the following into Google to find the podcast - tim-harford-there-is-a-short-term-penalty-and-a-long-term-reward-to-contrarianism
Sorry about that. I did click when I posted to check it out and it worked. But now it doesn't.
Anyway search for Investors Chronicle podcast Tim Harford and you should find it. It's dated 10/19/2020 (US format I know).
if you use iPhone podcasts it is in there...search under Tim Harford, Investors Chronicle and it pops up.
IC Podcast - quite bizarre - if you go to https://www.investorschronicle.co.uk/search/?q=harford it will appear as the first item. Click on that and it will take you to the url that does not work directly!
Hi All,
We've seen a lot of press about the new 20 minute COVID test, using the LAMP test (Loop-mediated Isothermal Amplification) that the airports are selling for GBP80. Does anyone know if that is one of £NCYT's products????
As I understand Novacyt Sa (LON:NCYT) are using the 'gold standard' PCR testing system.
If anyone knows the answer pls let me know......
I see Novacyt Sa (LON:NCYT) is dropping today.....
Some of the commercial aspects of testing feels v. much like tulips but then again, this isn't going to drop off the radar tomorrow!!! V difficult to know whether Novacyt Sa (LON:NCYT) is over bought or not. BTW: Following the Stocko discussions re Novacyt Sa (LON:NCYT) to date on this.
Hi Snooker, it is not one of Novacyt's products.
Please read through the comments on the Stock Pitch thread (again?) or Novacyt Sa (LON:NCYT) by Keelan Cooper. The information you seek is all there...
https://www.stockopedia.com/co...
TKS Forbsy....
The thing I would say about Novacyt Sa (LON:NCYT) is that it is generating significant free cash flow (£10's of millions per month currently), is debt free and has stated it will use the cash for buying up other interesting Bio-Techs. It has started this diversification process this week with the acquisition of the company that produces its testing machines to improve vertical integration - purchase is earnings additive immediately.
The next trading / operational / financial update will make for very interesting to see if the growth in production seen in March/April/May, and cash flow, has continued.
Current price is starting to look high BUT the way this winter is going so far I can see their sales increasing significantly further.
The downside to the share is that the product it mainly produces (CV19 testing) SHOULD be limited in large scale production so probably these revenues will diminish in 12 - 24 months (we all hope so anyway).
I am a holder and have been lucky enough to hold since early 2020.
Hi Nick,
You wrote that you've been lucky enough to have held Novacyt shares since early 2020. Presumably the value of your holding must have increased many times since then and it now represent a much more significant percentage of your portfolio than when you first bought it. I would be interested to know whether you are setting yourself an upper limit on that percentage and top-slicing when it goes above that, or whether you are keeping your original number of shares regardless.
Novacyt Sa (LON:NCYT) (I hold) was one of my holding too, not from early days, but a punt around 260p. As people correctly mentioned there are key facts RE Novacyt Sa (LON:NCYT):
1- Strong balance sheet. No debt.
2- Extremely cash generative.
3- Phase 2 of contract with UK government (if it gets extended which I see it will) will be multiple times bigger that what Novacyt has so far. Reason is, their instruments are already all over UK hospitals and it's hard to assume NHS will just decide to throw them away and use something else right now.
4- It is now targeting biggest market by far, US. It is partnering with giant US healthcare providers (news due). It is also going to India by a larger scale and UAE and Germany.
5- Its antibody new product so far has not contributed at all to the share price. Assume if a contract gets underway RE that product too.
6- Recent broker research by Numis: short term target price of 1,360p and long term £34. If you put that on PER, you will see that even at say £15, PER is super low.
7- Don't think 1-2billion mcap for a leader in diagnosis is anything. Look at the mcap of US companies which are less attractive that Novacyt Sa (LON:NCYT) and their mcap is multiples of billions. Reason is simple: the market is huge.
8- Novacyt recently bought, outright, IT-IS manufacturing facility that was producing some of its products. This means the whole process can now be controlled by Novacyt Sa (LON:NCYT), hence, better marketing and better service is expected.
9- One of the biggest factors for me: So far, no major institution has yet started buying into shares. As soon as it starts, the Share Price will shoot. As Mark Minervini puts it: this is just the beginning.
I will personally hold till around £20 before top-slicing.
Hope the above helps.
The bit that worries me slightly is that even at this size no institutions are buying. You have to ask why. I can only think it is because people see material risk that revenues drop off a cliff quickly and that it therefore only deserves a PE of 4 or 5 since it is too much like a one off. Clearly a 15 min accurate test could decimate revenues almost overnight potentially, or is this wrong?
I am annoyed at myself for not buying at 400p when I think the risk in this regard was much lower. I have also seen the blue sky estimates of £30+ p/share and to be honest I wouldn’t rule it out, but equally I am now less keen to buy at these levels.
The build up of cash clearly de-risks the share price though so I find myself in a quandary over whether I need to put my own FOMO back in the box or whether this can still double or treble. It’s a funny one to value and I am struggling to apply my risk/reward ratio to it.
davidjhill,
The 15 min test is nowhere as accurate as the PCR tests. It is only good for huge places to open up the economy with some risk.
PE of 4 or 5 is way too low. Assume what portion of the mcap is already cash in account? even if the second phase of UK gov contract doesn't go through. Put that on top of the margin Novacyt Sa (LON:NCYT) has, which no AIM company has ever had! To be honest, £10 is still cheap imo.
Hi mort1980,
You wrote: "The 15 min test is nowhere as accurate as the PCR tests. It is only good for huge places to open up the economy with some risk."
The Oxford Nanopore rapid LOOP test seems to provide very good accuracy, according to this article:
https://www.research.ox.ac.uk/Article/2020-09-25-evaluation-of-lampore-rapid-tests-for-covid-19-show-high-levels-of-diagnostic-sensitivity
An extract from the article says:
"The positive clinical specimens came mostly from patients with symptomatic infection, and among these LamPORE had a diagnostic sensitivity of 99.1% (i.e. it was positive in 226 of 228 samples positive by RT-PCR). Among negative clinical specimens, including 153 with other respiratory pathogens detected, LamPORE had a diagnostic specificity of 99.6% (i.e. it was negative in 278 of 279 samples negative by RT-PCR). Overall, 1.4% of samples produced an indeterminate result on first testing, and repeat LamPORE testing on the same RNA extract had a reproducibility of 96.8%."
OxNan have a webinar on 29 Oct https://www.ipgroupplc.com/eve...
I've held off as the main vehicle in is through Ip (LON:IPO) which according to advfn posters just isn't successful at managing its successes, eg they incubate then seriously reduce just as the business hits an inflection point. Ceres Power and Avacta being two recent examples.
Yes, but the precision and accuracy of the LAMP-based methods are well below PCR-based ones. Remember that in this era a little bit of error is too much.
Hi mort1980,
I wrote "The Oxford Nanopore rapid LOOP test seems to provide very good accuracy, according to this article:"
and you replied "Yes, but the precision and accuracy of the LAMP-based methods are well below PCR-based ones. Remember that in this era a little bit of error is too much."
I must apologise. I should have written ""The Oxford Nanopore rapid LAMP test seems to provide very good accuracy, according to this article:"
The article suggests the Oxford Nanopore tests have 99.1% accuracy for positive specimens and 99.6% for negative specimens. Not quite as good as the 100% accuracy claimed by Novacyt for its PCR tests, but it's pretty close.
That is an interesting clarification pka.
Just to put it into terms perhaps more commonly bandied about recently.
0.4% false positives. IE of 1,000 positives reported 4 of them won't be. From the best guesstimate I can arrive at that is possibly about the same or a little higher than PCR, although as they used PCR to validate I'm not totally sure of the conclusion.
0.9% false negatives - IE of 1,000 negatives reported 9 might actually have the disease. This is probably the more pertinent one for any agency wanting to use the test result to grant access to someone proven to be Covid free. However the article indicates that the positive samples they used were all from symptomatic cases, the asymptomatic or pre-symtomatic ones are the harder to detect, so I would personally be cautious about the effectiveness of the test without further studies.
I have somewhat lost the context in which this was been discussed today, but I was thinking in the context of yesterday's discussion about whether the tests being rolled out at Heathrow bode well for cruises (eg Saga (LON:SAGA) ). In that context it will come down predominantly - Hong Kong and Italy do already and some other countries do not require a test at all at this stage, so perhaps the omens are good? Although probably it is too early to call!
From my understanding that's not how false positives work.
It's not for every 1000 positives 4 of them will be false, it's for every 1000 tests, 4 of them will be positive whether or not the person has CV.
If you're doing 100,000 tests per day, that's 400 people misdiagnosed. Given the infection rate is something like 250 per 100,0000 population in some parts of the country, the test is next to useless for mass sampling.
Please, I have this wrong, correct me, I'm not hear to spread disinformation, this is my understanding of the false positive rate.
Hi IGPJ,
Yes of course you are correct, I "mis-wrote" (if that is a thing?)
The rest of what I said still stands though (as I was thinking the correct thing even if I wrote the wrong one!)
On the subject though of whether the false positives render the results useless I have to disagree - when cases were very low in the summer it was potentially an issue (there were some wild claims from apparent experts.) Essentially though now with test positivity rates pushing 10% the fact that 0.4% of them might be false is not really a huge problem.
I would agree that as prevalence of illness goes up, the validity of the test increases, both on the false +ve and false -ve. If 10,000 people have it, missing 900 isn't likely to make much difference, especially as the tracing service only contacts about 70% of those who need to isolate if I remember that statistic properly.
Thank you for your considered and polite response, some of my posts come across a bit more antagonistic than I mean them to be at time of writing when I later read them back.
Hi Gromley,
The tests being rolled out at Heathrow are the LAMP-based tests from Oxford Nanopore, which the report I referred to say are over 99% accurate. I now have a big holding in Novacyt, so I wonder whether sales of their PCR-based tests, which are supposed to be 100% accurate, are likely to be adversely affected by competition from Oxford Nanopore. I suspect that they are selling to different types of customers and that there is room for both companies to be extremely successful.
I tried to hedge my bets on these testing technologies a few days ago by buying a holding in the IP Group investment trust, which has about 15% of its portfolio in Oxford Nanopore. However, I sold that holding the next day after reading comments on ADVFN that IP Group had a track record of selling some of its investments shortly before they became enormously successful.
Hello davidjhill. You are right that Novacyt is a funny one to value as its success currently depends on very few products and relatively few contracts and it will be impacted by the duration of the acute phase of the pandemic. It would be accurate to describe it as a speculative investment at its current valuation. I would suggest that the unpredictability of its future is one reason why institutions are not more interested, although I have a feeling that Woodford would have bought it if he was still around. I think Novacyt is very much one for private investors who are willing to accept (or enjoy!) investments with a high risk to reward ratio.
Novacyt SA (LON:NCYT) The AIM market listing may put some off, it is also very volatile. Some institutions already have holdings, Vatel Cap. has 3.7m and L&G has 2.5m shares, there are others with smaller amounts.
I bought in after the last results, I had held previously but sold out on the previous results. Don't think I will be buying anymore, in fact I sold some a while ago.
So, I sold some when it peaked around 400p to de risk - then I decided to invest that money back in when it had dropped to circa 280p.......since then I have sold some more at around 900p. It is something I watch and worry about a lot as I now have a number of shares that have grown so much they breach my normal holding limit.
Some like Plus500 (LON:PLUS) I will keep as the dividend is still around 10% (estimated) and I cannot see them reporting bad results at year end. Others like Novacyt Sa (LON:NCYT) and Open Orphan (LON:ORPH) cause more concern and I have been offloading small amounts when I think there is a peak.....
I have some of the investment in my SIPP which is (again) outside of my normal approach to risk. 2020 is leading to bad habits!
Hope this helps.
Hi Nick,
Thanks for your useful reply to my post.
Do you have an upper limit on the percentage of a single stock in your portfolio? If so, would you mind sharing the figure with us?
I am not that organised - In reality it works out to be around 4%. for shares generally BUT for AIM shares it is normally around 2%.
For funds I am happy to go to 8%
Hope this is useful
HI Nick,
Thanks for that useful info.
Snooker2020,
Further to my comment above which I hope you find useful, price corrections are absolutely normal as far as they are 'healthy' corrections. In case of Novacyt Sa (LON:NCYT) is super-healthy! Basically, weak-handed traders are being offloaded, some profit taking, etc. The trend is clear upward by all metrics.
Let's hope Novacyt Sa (LON:NCYT) also produce a 15 minute test!
A bit of calm is needed I might suggest! On closer reading of the most recent RNS, it is implied I think...
”The acquisition of IT-IS reinforces Novacyt's strategy, as announced on 17 September 2020, by strengthening the Company's IP portfolio to enhance and secure future value, as well as further expanding its core capabilities, whilst maintaining attractive margins. It also means the Company is well placed to expand its near-patient product offering through the existing IT-IS instruments and also through new product developments.”
“....With the acquisition of IT-IS, the Company is well positioned to address this drive towards rapid, decentralised testing and deliver additional growth opportunities.
Unexpected trading update from TRMR this morning showing considerable growth and profit. They have been going through an acquisition over the last year as well as buying back shares.
Robust full -year (Jun 2020) results from Croma Security Solutions (LON:CSSG), the security services provider, this morning.
It's a tiny business, with a market cap of £10.1m but, having traded profitably through COVID, holding cash equal to 40% of its capitalisation and with "trading post year end progressing well", I consider it well-placed to grow into a higher valuation.
(I hold).
Although too small for most, I am long and watching REACT (LON: REAT) They do deep cleans in public areas eg schools stadiums etc. And which has continued to make strong progress in the period, achieving 42% organic growth in revenue to approximately £4.4m* (12 months ended 30 September 2019: £3.1m). Profit ahead of forecasts.
As mentioned, too small for most here but acorns and oak trees and all that....
8 likes...seems that others may have an interest.
I have a small speculation in React (LON:REAT) too...given the size of the company its not possible to be anything other than small.
Net cash has increased by c.£350k since interim (factoring in £1.16m raise in June). Approx £150k of that was timing related on receivables around end of first half. So lets say its at least £200k for the second half....and given half on half as well as YoY growth then perhaps there's another £150k of receivables effectively hanging over the year end?
Earnings and cash translate quite well it seems for this business so H1 £50k earnings and then £200k plus for H2 -> £6.5m market cap on 26x current earnings after a 'turnaround' year of growth at 44%. If this is what they report then share price is probably fulsome for now. But if there's a net receivables carry over in the cash (half on half growth hints it) and earnings for the year approach £500k -> 13x current earnings on 44% growth -> share price will move a decent bit higher on results.
Some points:
Anyway, a lot to play out and very high uncertainty and risk...but execution to date is positive
ADDITION: I see that house broker Allenby forecasts PBT £182k....so lower than what I put above and they have a better idea/access than I.
Tremor International (LON:TRMR)
Interesting announcement about raised full year expectations and confirmation that although times are uncertain they expect to beat the consensus estimates that still remain in the market. Unfortunately they don’t tell us what those are.
I find this a somewhat difficult business to understand in terms of the details of what they do, so I tend to think of it as just being in video advertising services. That would seem to be a good area to be in now with more and more of our activities moving online and moving from still pictures to video as the telecommunications tech evolves to make the delivery of video across a wider range of devices pain free.
In the past, some people have confused this business with being like XL Media but it’s really a very different kettle of fish.
A few years ago they were tainted by association with someone who had some reputational baggage but I believe that is behind them. Some people have also fretted about the fact they are an Israel based company. I don’t think we should make sweeping generalisations that any foreign domiciled company is not to be trusted. Perhaps more vigilance is necessary but cases like Patisserie Valerie show that problems can occur anywhere.
They acquired Unruly earlier in the year and it sounds like that integration has gone very well.
So, my feelings are that they are going places and I am happy to hold.
Hi Paul, even though the market cap is very small, could you have a look at the trading update from React (LON:REAT) please?
A decent full year (Sep 2020) trading statement from React (LON:REAT) this morning.
Yes, with a market cap of £6m, it is tiny, but with that sort of cash generation and growth (albeit helped by COVID), there is surely a strong argument for value here.
(I hold).
Hi Paul - would you consider looking at Gamesys (LON:GYS)? Granted they're a touch big (£1.4bn market cap), £400m debt but update yesterday announced Q3 revenues up 31%. Importantly this company is global and has turned a profit starting in 2018 if I recall. What moat does online bingo and casino have (you ask)?..so do I, but this company has an impressive uptrending profit cycle. (I hold). Warning Net Margin is small (c.2%) combined with low divs & debt is maybe why the market voted with its feet yesterday (-7.8%). 4 years ago. Matylda asked in Aug'17 for SCVR to cover it then but no interest. Stockranks reasonable at 70 and big Stocko community following ...so I'm suggesting there are others interested..
I'd be interested.....
Good morning Paul
I'd be interested in your thoughts on Spectra Systems (LON:SPSY) . They just announced a new contract with a central bank for bank note authentication systems (systems to distinguish between genuine and forged banknotes). The contract, to run over several years looks as if it could be worth between $14m and $50m. That sounds like a very big contract for a business whose 2019 turnover was $13.2m.
Although one would think that Covid-19 is reducing our use of banknotes (for fear of virus transmission) a recent report (sorry, I can't trace the source) suggested that, worldwide, banknote use is rising. And Spectra Systems (LON:SPSY) are also extending their technology to the authentication of commercial products. They are e.g. being trialled for the use of their technology to distinguish between genuine and counterfeit cigarettes.
The red flags on this company are:
1. a US business listed in the UK
2. AGM's held in the US are always inquorate
3. I have never had the opportunity to see or hear the CEO / management
This has been a long term hold and has done very well for me so far.
I second the request for Spectra Systems (LON:SPSY) - which Paul will be familiar with from Virtual Mello a few weeks ago where it got a strong and bullish pitch from Alan Charlton in the "BASH" section, and was well received by the panel, which included Paul.
For me the questionmark was whether Spectra could go beyond the successful cost-cutting / margin expansion of recent years and actually deliver revenues beyond the level of 5-6 years ago - and today's announcement is a very positive answer to that. (I hold, and also topped up first thing).
I also second the request for Spectra Systems (LON:SPSY) (I hold).
I propose exempting US stocks from the "Avoid all foreign stocks on AIM" rule. It keeps coming up with Somero as well. They listed here because they are too small for the American markets. Apply the usual due diligence of course but for me the risks are less than with UK based Aim companies. We are hardly short of fraudsters ourselves.
In general US companies are better managed than UK ones . Fraud is much more effectively prosecuted there than it is in the UK and wrongdoers are more likely to end up in prison. It's the UK that is the poorly regulated den of dodgy companies.
I hold Spectra.
I have a long term interest and currently hold both Spectra and Somero (both listed on AIM but based in the USA)!!
I believe Spectra has developed (but is careful not to reveal) considerable IP in the field of security for both banking applications and product identification.
If you look at historical news releases they have a very good relationship with a major central bank with whom I assume the latest (and I think their largest ever) contract has been secured!
The Company said in a previous RNS that they would exceeed their profit forcasts for the year. They have a high profit margin and pay a good dividend! Quite how this has been achieved seems a well held secret!
Hello Julianh. Whilst I am wary of most small foreign businesses listed in the UK, I'm not sure I would regard smaller US companies listed in the UK as a red flag. I have found that, providing you are selective, smaller US businesses on AIM can actually produce some profitable opportunities as they often address global markets. This is only a tiny part of my portfolio, but I have had pevious success with Lifeline Scientific (now aquired) and Water Intelligence (I have now sold) and I currently hold Spectra Systems and Boku, both of which are growing satisfactorily and address quite large markets. In some ways I think these companies fly below the radar because they are not attractive to US investors because of their UK listing and they are not attractive to UK investors because they are foreign companies.
Spectra Systems (LON:SPSY) also has a small listing as Spectra Systems (LON:SPSC) which are shares that for some historic reason have transfer restrictions attached, though these restrictions seem not to inhibit trading. The quoted prices typically put SPSY significantly ahead of SPSC though the gap narrows markedly and erratically from time to time. I hold both, as a consequence of not noticing SPSY when I first bought SPSC. They pay the same dividend
I asked the CFO how to convert SPSC to SPSY, as the SPSY price is higher and conversions are sometimes reported in RNS. I had a quick and clear reply, conversion is free but it can only be done with physical certificates.
It must be inconvenient for them to run two listings. Maybe they's just buy back SPSC one day. Meanwhile I'm very happy with the yield and capital gains.
Zytronic (LON:ZYT) FY update - big drop in revenue, but profitable before restructuring and furlough costs.
- Market cap was £18.5m yesterday, but it has cash of £14m - giving an Enterprise Value of £4.5m;
- Last 5 years: profits totalled £19m with a good proportion of that paid in dividends.
Re Zytronic (LON:ZYT) why would furlough costs be excluded from EBITDA? Is that not just staff costs?
re Zytronic (LON:ZYT), I have been looking for a good time to jump in (no current position), but they've made a loss at the bottom line this year and after today's update, I'm wondering if they'll be profitable, even at the operating level, next year.
In the last 7 years , they've needed roughly £17m to break even at the operating level. Granted, there has been some restructuring, but I think that much of the cost saving has come from using the furlough scheme, which is obviously not sustainable. It's not (entirely) a software business, and they certainly can't dial down costs indefinitely.
Half year rev was £7.4m. That means rev in the most recent 6 months dropped to £5.3m, and that's after the (albeit limited) opening up we had after April. While COVID certainly can't have helped, it looks like the structural decline in demand that was already in place isn't going anywhere. Even assuming that revenue picks up a little next year, I struggle to see revenue above £13m and costs will increase to boot. £13m is obviously very finger in the air, though. If there are good reasons to believe there will be a jump back to previous revenue levels, and if they can hold onto their workforce until that happens (or rehire if they let them go), then maybe it's ok.
Could be an option on the turn-around, but it also sounds as if the cash balance is being flattered, so I think you're almost certainly paying more than £4.5m for the underlying business. If that's a business going to be losing money from here on out, then even if they wind it up, you're sitting on a loss.
Thank you - very useful insight in the business and prospects of Zytronic (LON:ZYT)
I very much agree and don't have a lot to add.
I rather suspect that Covid has accelerated the decline of some of their markets. Though there may be an element of increased sales and investment cycles.
There is considerable execution risk in yet another turnaround - not least technological obsolescence - but the company seems well managed, well financed and with well regarded niche products?
There may even be something of a Covid silver lining for 'contactless' touch screens in the near future . If they do succeed in selling into new applications then the current price will look cheap - but recent company history suggests this always takes longer, and is more expensive than anticipated?
Tough one to call. On balance I am backing a turnaround - but how much of a turnaround? The poor H2 sales certainly knocks confidence,
cheers
Mark (I hold)
I also hold - and have similar views to you. I am in no hurry to add above £1. I am unclear what management's strategy is - they are experts at giving little information to the market. While post-covid (whenever that is and whatever that means), I could see the gambling markets recover (particularly in Asia), I suspect that the ATM business for banks will never recover and that cash usage will continue its long-term decline.
Hi Paul,
Hope you're well!
Some interesting buys in Boohoo yesterday:
M Kamani (Group Exec Chairman) - 300,000; Catherine Catto (CFO's wife) - 5,825; B Small (Deputy Chairman & NED) - 10,000.
Albeit modest, I rather like buys linked to a CFO....
and I bought a load more yesterday :)
And Brian Small is an ex CFO - he's no mug.
I had a thought about BooHoo (which may have already been said, an awful lot has been written about them). Their target demographic is the hardest hit age group financially speaking in this pandemic. Its likely their customers are going to be a bit strapped for cash for a while.
The furlough scheme is unwinding this month, scary to think what that will do to unemployment figures and what age range is hardest hit.
Not sure what age you are but i have teenagers and they're typical in that they're influenced by fashion. When you don't have a lot of cash, you're going to go for the best you can get for your buck. Boohoo fits that. They would rather not eat that not look good in front of their mates and potential partners. Not exactly smart but few teenagers are. I remember the days...
My morning smallcap tweet: Room with a view.
Equatorial Palm Oil (LON:PAL) ECO Animal Health (LON:EAH) React (LON:REAT) Spectra Systems (LON:SPSY) Zytronic (LON:ZYT) Tremor International (LON:TRMR) Cohort (LON:CHRT) £C4XD Metro Bank (LON:MTRO) Petards (LON:PEG) LoopUp (LON:LOOP) Seeing Machines (LON:SEE) Mercantile Ports & Logistics (LON:MPL), £D4T4
Equatorial Palm Oil (PAL) proposes RTO of Capital Metals, a company developing a mineral sands project in Sri Lanka, . Shares suspended. [SP=0.77 Cap=4m]
Eco Animal Health (EAH) guides H1(Sep) rev significantly ahead of management expectations and the prior year. The figure is a secret. "Product pricing and manufacturing costs have remained broadly stable through the first half of the financial period although higher volumes have resulted in some additional customer discounts." R&D spent cut, remains under review. [SP=203.25 Cap=137m]
React (REAT) after 42% H1 rev rise, guides FY pretax ahead of market expectations driven by both COVID-19 related decontaminations and a number of non-COVID-19 related projects. [SP=1.24 Cap=6m]
Spectra Systems (SPSY) wins central bank for the development, manufacture and servicing of a sensor system. Worth $1.9m dev phase, $5.6m to 2023, up to $34m for the delivery of sensors, and a service component worth c. $7.5m. [SP=170 Cap=77m]. I hold.
Zytronic (ZYT) guides FY(Sep) rev £12.7m, down 39% and EBITDA positive. "Whilst we are still facing uncertainty regarding levels of future business, particularly from the Gaming and Financial sectors, Zytronic is in a strong financial position." [SP=111.55 Cap=18m]
Tremor (TRMR) guides FY(Dec) ahead of market expectations with rev $340-360m amd adj EBITDA $30-36m. [SP=175 Cap=233m]
Cohort (CHRT) wins 3 contracts worth c. £16m. Start this FY and deliveries in 2021 to 2028. [SP=562 Cap=230m]
C4X Discovery (C4XD) £15m placing at 14p, an 11% disc. Comes with warrants. Placing "expected to provide the Company with at least twelve months working capital" ie keep the lights on or as co puts it "advance the core investment portfolio to near-term inflexion points" blah blah blah. [SP=16.4 Cap=20m]
Metro Bank (MTRO) Q3(Sep) trading. Assets flat during Q. CET1 remains materially in excess of regulatory minima. "Activity levels continue to gradually recover post-lockdown, with new account openings tracking higher at around 90% of pre-pandemic levels." [SP=59.5 Cap=103m]
Petards (PEG) wins eyeTrain contract from Bombardier. No £££. "Bolsters the Group's present order book to £12.3 million of which £6.9 million is scheduled for delivery in 2021." [SP=7.5 Cap=4m]
LoopUp (LOOP) launches LoopUp Rooms which "combines the Group's premium remote meeting solution with off-the-shelf hardware to create competitively-priced, plug-and-play video conferencing suites". [SP=225.6 Cap=125m]
Seeing Machines (SEE) MoU with global aerospace and defence technology company, L3Harris Technologies to collaborate to enhance pilot training technology. [SP=4.27 Cap=144m]
Mercantile Ports & Logistics (MPL) H1(June) rev still a miserable £155k. Preatax -£2.6m (-£2m). Cash £7.8m and undrawn facilities £10.1m. CFO leaving in Nov and claims he enjoyed it. He is thanked. [SP=0.22 Cap=4m]
In line: £D4T4
£GPM although a microcap worthy of a look into....
Chairman: Substantial gains in both NAV and the funds sp.... appreciation of 54% in NAV and 64.4% in the six months to the end of june 2020.
They’ve only gone and done it again!
D4t4 Solutions (LON:D4T4) do the, now fairly regular, second half weighting statement. It should be noted that they’ve always come through in the past having done this dance at least twice before that I’m aware of, but I still expect a drop off in price this morning.
Hi IGotPoesJacket
The statement from Peter Kear regarding future prospects and outlook for the full year was positive and fairly emphatic, so I am not sure that the reaction will be overly negative. Still we shall see.
£D4t4 are one of my larger holdings.
All the best
Yeah, I’m just basing my musings on history of my experience with this share. I’ve been in for a few years now and expect this to do well in the mid term. I recently bought more when it went to 180 but sold at 205 thinking it would flatline but it went back to 220 - still, always leave 10% for the other guy :)
If it heads back to 180 today or over next couple of weeks, I’ll try and replay that trade :)
They’re on a forward PE of 28 according to Stocko which is quite strong and the revenue profit figures look bad for last year because of the transition to a recurring revenue model. However good history of contract wins and the pipeline narrative is good especially as the product is being integrated into other provider’s solutions. I’m long here and staying long, but trying to trade any price weakness.
hi IGPJ
And regarding D4t4 Solutions (LON:D4T4) ive lived through two of these H2 ratings, and hung on, and bought the dips, and thankfully the CEO was telling the truth, but i did think oh no, not again. However the two big positives here are
1 the recurring revenue, which is growing strongly from very little two years ago. Two years ago i asked the CEO by email why they were not going for SaaS, he basically said we are but slowly, so over delivering here i thinks.
2 the partnership progress which will really turbo charge sales if the product is good, so this is a super important KPI for me. The below statement & results i’ll watch carefully. If Teradata is doing what this statement says the thats a big endorsement. A bit of googling I think.
Has anyone out there experience of working with D4T4 & celebrus product?
J
and the statement i forgot to add for D4t4 Solutions (LON:D4T4) (Can we have edit on mobile please..)
Teradata, D4t4's business partner, launched the "Vantage Ignite program", a major product initiative into its global installed base enterprise accounts where D4t4's Celebrus Customer Data Platform (CDP) products are central to the initiative
Comment on D4T4 results from TechMarketView daily email:
"
The shift by D4t4 Solutions Plc to a recurring revenue model continues to take a significant top line toll. In its latest trading update, the Surrey-based AIM-listed data solutions provider states that revenue in H121 (the six months to 30th September) will be down a thumping 42% yoy to £5.09m. This level of sales and the anticipated associated adjusted profit are, however, said to be in line with management expectations.
There was continued progress by the company on its move away from a perpetual licence pricing approach during the reporting period. 12 monthly recurring revenue, as a percentage of total revenue, increased to over 55% (March 2020: 45.2%). Once the fall in overall first half turnover is factored in, however, the underlying growth in SaaS sales was more constrained. Nevertheless, there were significant recurring revenue-based contract wins secured in H1 including a large South American retailer and the Group's first customer in the US healthcare market.
Despite a COVID-19 driven elongation of first half sales cycles, D4t4 remains positive regarding the outlook for the rest of the year. A strong visibility on engagements due to initiate during H2 and a reportedly healthy pipeline of new business makes the company’s board confident in delivering a solid finish to FY21.
Market reaction to this latest update, however, appears less optimistic. In early trading, D4t4’s share price had dropped by c.11%."
I looked at D4T4 a few weeks ago and thought it looked interesting. But I got put off when I saw disclosed in the annual report that a single customer accounted for over half of sales in FY20 (it was even higher in FY19). There was no disclosure about what type of client this was. If this was an end-client, I would find this very worrying - but perhaps it is a sales partner , where this would be less worrying (e.g. Dotdigital (LON:DOTD) has significant exposure through Magento).
Do anyone here have insight into D4T4's customer concentration?
re £D4T4, I thought that a high proportion of sales was through sales partners - as you might expect for a "platform" product. But I hadn't spotted the level of customer concentration.
Wimbledonsprinter, it is not an end client - it is one of the three big partners. (Probably Teradata, possibly Pega or SAS - others might know for sure). Richard Beddard shared your concern and wrote about this on his blog (but still bought).
I hold - maxed out sizewise - and have confidence in H2 again being very strong. (The way they recognise revenue vs. renewal dates seems unnecessarily lumpy and H2-weighted to me - and I believe this management team is credible wrt statements about negotiations, pipeline etc). I plan to watch the recorded CMD later to see what I learn; interested to see if retail and/or healthcare are one-offs or "real" new sector opportunities - could be additional upside if they have a real advantage (if tagless real time data is important/valuable) and partners push it.
vprt - Thanks for highlighting the Richard Beddard blog on D4T4
Good morning! Below covers today's regulatory and potentially price-sensitive announcements.