Small Cap Value Report (Weds 22 Dec 2021) - D4T4, MEAL, CAM, CNS, KBT

Good morning! It's Paul here with the SCVR. As there's not much company news this week, I'm trying to handle the SCVRs solo, to give Jack more time for other duties.
Agenda -
Paul's Section:
D4t4 Solutions (LON:D4T4) (I hold) - 2 large contract wins are announced, but seem to be in the forecasts already. They company reassures that it should achieve its FY 3/2022 expectations. I'm struck by the size of these contracts, which will contribute 37% of the entire year's forecast revenues. Even after the recent c.30% correction in share price, it's still not cheap on a PER basis. However, I continue to be impressed by the potential for this company to scale up in future, possibly, which could transform its valuation if they succeed in winning more large contracts. No guarantees about that of course, so it requires a bit of a leap of faith.
Parsley Box (LON:MEAL) - a trading update that tries to sound upbeat, being in line with lowered market expectations. However, on doing a little digging, it's clear that this company is burning through cash at a prodigious rate, and has nearly run out. It says more funding is needed in early 2022. Very high risk, I think this share is probably heading to zero unfortunately. Bargepole I'm afraid, due to the high risk of insolvency, based on these numbers. I hope punters manage to salvage something from this bad investment. I think anyone holding this is crazy, because it looks highly likely to end up at zero, given the very high cash burn.
Camellia (LON:CAM) - my first ever look at this overseas agricultural group. I like the strong balance sheet, and good track record of dividends. Today's update is ambiguously worded/punctuated, and I can't find any broker notes, so can't take it any further. Developing country , and exposure to volatile agricultural prices, turns me off.
Corero Network Security (LON:CNS) - issues a positive trading update during market hours. Has this cyber-security company finally turned a corner, after years of heavy losses? I don't know, but there do seem to be some encouraging signs.
K3 Business Technology (LON:KBT) - issues an in line with expectations update for FY 11/2021. The balance sheet has been fixed now, with some non-core disposals businesses sold. My view: neutral.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
D4t4 Solutions (LON:D4T4) (I hold)
285p (pre market open) - mkt cap £115m
D4t4 Solutions Plc (AIM: D4t4, "the Group", "D4t4"), the AIM-listed data solutions provider…
This is effectively a trading update, with the key part saying -
These multi-year contract wins add over £3 million per annum to the Group's ARR as well as over £9 million to the current year's revenues.
Along with existing contracted H2 ARR and continued good visibility of the pipeline for the remainder of this financial year, the new wins underpin the Group's confidence in achieving board expectations for the full year.
I’m struck by the new contracts adding >£9m to this year’s (FY 3/2022) revenues - that’s 37% of the whole year’s revenues, a huge number. It’s very good news, but also reminds me that D4T4 still seems to be dependent on lumpy licence revenues (which are often almost 100% gross margin for software companies). Some of that £9m might be implementation fees, and support, it doesn't say.
Seasonality - D4T4 has a very heavy H2 bias to results historically, and often scares investors with a poor H1, but then seems to deliver the goods in H2.
EDIT: thanks to davidjhill who points out in the comments section below that D4T4 has large contract renewals that fall into H2 each year, which is what creates the H2 weighting to results. End of edit.
I wonder if the company is setting itself up for a beat against expectations nearer the year end? It feels like that might be the case, let’s see what brokers say in any update notes later today.
Note that H1 revenues this year were £7.6m, and the FY 3/2022 revenue target is £24.3m, hence £16.7m revenue is needed in H2 to hit Finncap’s revenue forecast. Today’s contract wins bank >£9m of that £16.7m H2 target, plus there will be recurring revenues already in the bag. So it’s looking promising.
My opinion - there’s more detail in the announcement, all of which sounds encouraging, including the first sale of its new Fraud Data Platform software.
Both Jack and I had concerns about valuation, with the price looking toppy at the peak of c.400p earlier this year. The price yesterday was 285p, so a fairly hefty c.30% fall from its recent highs - although that’s similar to many other small caps which have sold off heavily in the last 3 months in particular. So I don’t see the fall back in price as being anything company-specific, it seems more about nervous holders trimming back or selling out. Probably.
Generally, I think it needs a company to issue a reassuring trading update, confirming market expectations, to stop the selling, and trigger some fresh buying, in depressed market like we're experiencing now for UK small caps. That’s what has happened here, so I expect this share could recoup some of the recent losses.
The valuation still looks high, a forward PER of 32.4, but I continue to believe there’s something special going on at this company. If it can scale up, and as we see today these are big contracts with large organisations. So the figures could look a lot more interesting in the future.
In the meantime, it’s already nicely profitable, so investors need not worry about cash burn, or equity fundraisings, as it’s sitting on a decent cash pile already.
Overall then, I think with a lower share price, and a reassuring trading update today, risk:reward for investors seems a lot better than it was earlier this year.
.

.
Parsley Box (LON:MEAL)
38.5p (down 12% at 08:25) - mkt cap £16m
Trading Update & MD appointment
Parsley Box Group plc (AIM: MEAL), the direct to consumer provider of ready meals focused on the Baby Boomer+ demographic, today issues an update on trading.
Recent trading has been in line with the last update - a profit warning on 30 Sept 2021, which I reviewed here.
Revenue is “on track to deliver full year revenue marginally over the £25m forecast, representing modest year on year growth.”
H1 revenue was £14.0m, so H2 is lower at £11m.
Cash - £2.2m is expected to be left in the kitty at 31 Dec 2021 year end. That’s way down on the £6.5m reported at 30 June 2021, so an alarming rate of cash burn, despite marketing spending being reduced in H2.
Inventory levels improving, after (previously reported) problems with outsourced production
Marketing spending reduced by a third in H2 vs H1 - “whilst stock availability was significantly constrained, resulting in approximately 20% lower order numbers and therefore revenue in H2 compared to H1.”
Product ranges improved & extended - 50% relaunched with new recipes - good, as some of the previous ones were absolutely awful, and the product looks nothing like the photos in the brochure/website, which I found misleading and caused disappointment when my order arrived. Successful companies surprise & delight customers with their products, which is what drives repeat business.
A new MD (20 years at John Lewis) has been appointed, to free up the CEO’s time on business development, “and in particular strategic growth opportunities.” - what does that mean? Acquisitions, partnerships, who knows?
Funding - the biggest issue - it’s running out of cash, and needs to do a fundraise (from a position of weakness I would say, so there’s a risk of heavy dilution) -
In order to support its investment plan, Parsley Box intends to raise further funding during Q1. Certain members of the Board together with their associates have indicated their intention to invest, demonstrating their strong support for the Company.
My opinion - this looks really bad.
I’ve managed to successfully resist the urge to buy this share, thank goodness. The trouble is, it’s become clear that the float price was excessive, and unjustified given poor performance in 2021.
It’s still not clear if MEAL has a viable business model at all. Actually, it looks clear the business model is not viable. Just because something has dropped in price by c.75%, doesn’t mean it’s cheap, if the starting price was wrong.
If the product had wowed me, then I might have been prepared to have a punt. The trouble is, I tried a box of these meals, and thought they were pretty awful. Although it’s true I’m not the target market.
The company has burned through £4.3m in H2 (cash down from £6.5m in June 2021, to £2.2m just 6 months later) - that is really bad, and calls into question if the company is going to be able to survive. It’s certainly dependent on another fundraise, without which I believe the company could go bust in 2022.
With the high risk of a 100% loss here for investors, and no signs of MEAL being a viable business, so little potential upside, I think risk:reward looks awful. I hope they manage to turn things around, but if I held this share, I’d get out while I can, and salvage something from a bad investment.
.
Camellia (LON:CAM)
6875p (up 4% at 10:13) - mkt cap £190m
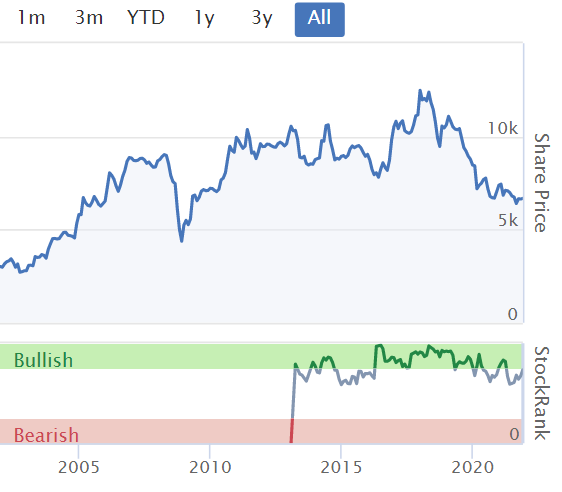
This share seemed to peak in 2018, and has been drifting down since.
Something seems to have gone badly wrong in March 2021, with broker forecasts being slashed in the following 5 months, as you can see -
.

.
We don’t seem to have ever covered this share before in the SCVRs, I don’t know why, there must have been something I didn’t like about it. I’m not keen on UK listed companies with mainly overseas operations, particularly if they operate in developing countries, because I've seen so many of those shares go (often very badly) wrong in the last 25 years or so that I've been in the market.
Many (particularly AIM-listed) overseas companies ended up being scams, or having something seriously wrong with them. For that reason, I almost always avoid AIM companies with overseas operations. Somero Enterprises Inc (LON:SOM) is an exception.
If I do consider an AIM company with overseas operations, then I look for 2 key things to reassure me -
- Stock market listed for a long time, and
- Paying decent dividends over 5+ years
Camellia passes these 2 tests, since it listed 20 years ago, and has a good track record of paying divis. So it looks OK, let’s have a closer look.
Here’s an investor presentation (only 6 slides) which explains what the company does. It claims to be the world’s largest private producer of tea. Also other crops being produced are avocado, and macadamia. Agriculture makes up 85% of group revenue. Smaller divisions are Engineering, and Food Service.
Running through previous results, some key points -
H2 seasonal weighting to profitability - when majority of harvesting of agricultural products occurs
Developing country risk
Cash pile & investment portfolio look significant to the valuation
Refocusing operations - diversification & non-core disposals
Volatility of prices for agricultural products - interim report mentions over-supply of tea (which makes up most of CAM’s revenues), and significantly lower avocado volumes from Kenya
Bought Bardsley England - the UK’s second largest apple grower (850 hectares in Kent)
2 aerospace interests sold
Net cash of £62.1m at 30 June 2021 (which is a third of the market cap)
Balance sheet looks complicated, but strong, including nice cash pile - it would be important to consider where the cash actually is though - as developing countries can have restrictions on sending cash abroad.
OK, that’s given me a rough idea of what the company does, so let’s look at today’s update.
This is rather ambiguous -
…These changes have resulted in improved margins for a number of our agriculture businesses which coupled with the rigorous cost-saving measures implemented across the Group, leads the Board to believe that the underlying profit before tax* for the year is likely to be substantially above market forecasts in the range of £7-9 million on revenue which is now expected to be 4-5% below market expectations.
* Underlying profit before tax seeks to present an indication of the underlying performance which is not impacted by exceptional items or items considered non-operational in nature and for example excludes impairment charges, gains/losses on disposal of assets and restructuring costs.
Are they saying market forecasts are £7-9m profit and they’re “substantially above” this figure? Or that they’re going to achieve £7-9m profit, which is substantially above (lower) market forecasts? I’m leaning towards thinking that £7-9m profit might be the outcome, and market forecasts are lower? How do readers interpret the above? Improved punctuation & wording would have made this clearer - I’m surprised the broker & PR didn’t pick up on that.
I can’t find any broker notes.
My opinion - this is an unclear update, and with no broker notes available, I can’t take this idea any further, due to lack of information.
On a first, superficial review, this looks quite an interesting, sprawling group.
Developing nation risk is not something I generally take on, so it’s not for me.
The share price is back to where it was 15 years ago. Although the total shareholder return would be better, including divis. Wouldn't it be great if we had a chart showing total shareholder returns, not just the share price?!
.
.
Corero Network Security (LON:CNS)
13.15p (up 16% at 12:02) - mkt cap £65m
Pre-close update regarding market expectations
Issued at 10:35 today - grrr, it’s so annoying when companies do this - issuing updates when the stock market is open, thus giving an advantage to professionals who are glued to a screen all day, and disadvantageous to everyone else who is busy doing something else.
Corero Network Security plc (AIM: CNS), a leading provider of real-time, high-performance, automatic Distributed Denial of Service (DDoS) cyber defense solutions, today issues a pre-close update for the year ended 31 December 2021 ("the year").
Here’s today’s update in full -
Subject to year-end close and external audit finalisation, the Board anticipates revenue to be broadly in line with market expectations and EBITDA to be significantly ahead of market expectations for the year and positive.
The increase in EBITDA is a result of a better than expected gross margins coupled with lower operating expenses.
The scale of the profitability is linked to the remaining sales opportunities to be closed before the end of the year.
A more comprehensive trading update will be provided as soon as available to the market in January 2022.
That sounds fairly good, although a profit rise from cost-cutting is not as positive as revenues beating target. Improved gross margins is good.
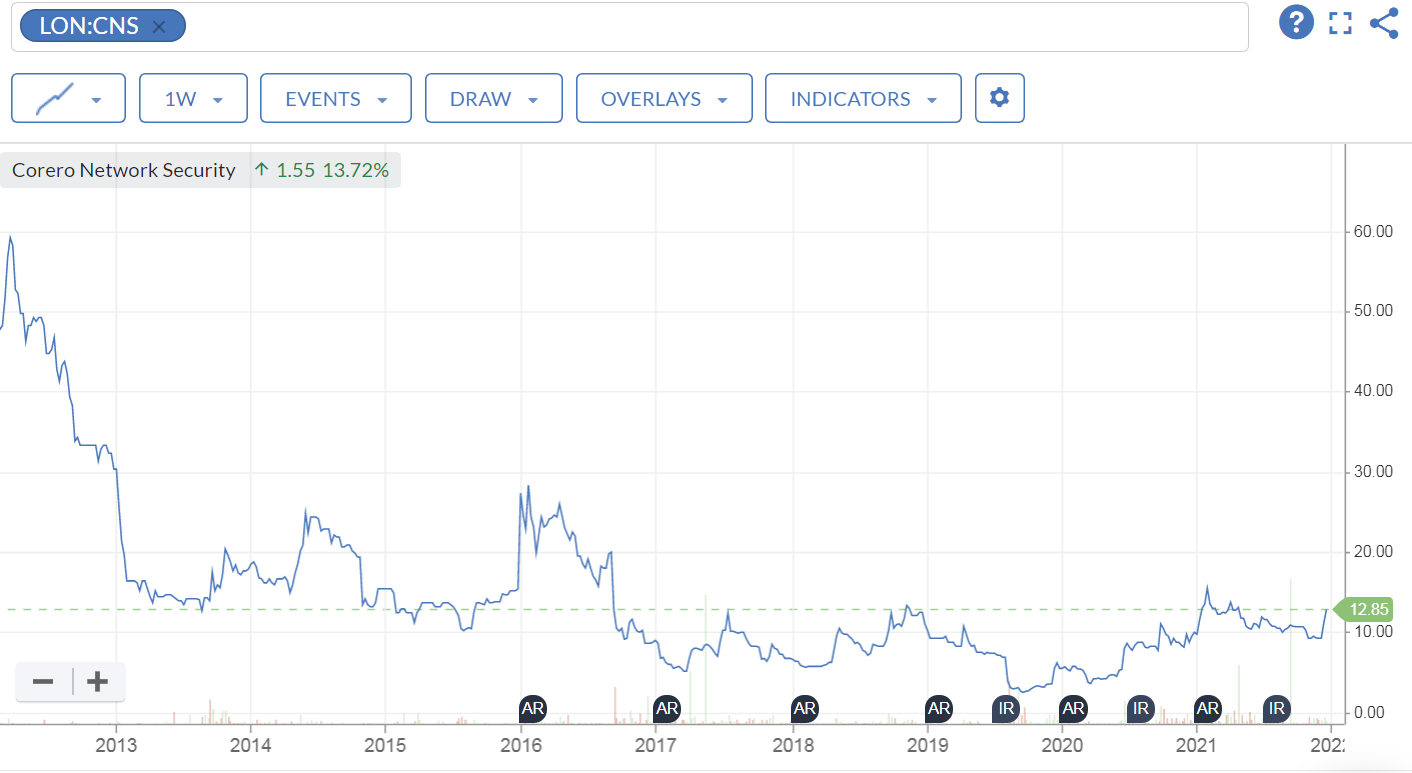
Corero has a poor track record, with many years of heavy losses, and dilution from fundraisings. The current share count is 495m, up from 133m in 2015. So I would need fairly heavy duty evidence that the business is improving, before wanting to buy.
Having a look at its website, Corero seems to operate in an interesting growth area, of preventing Denial of Service attacks on customers’ websites -
We are a global leader in real-time, high-performance, automatic DDoS defense solutions. Both Service and Hosting providers, alongside digital enterprises across the globe rely on Corero’s award winning cybersecurity technology to eliminate the threat of Distributed Denial of Service (DDoS) to their digital environment through automatic attack detection and mitigation, coupled with network visibility, analytics and reporting…
Quick review of H1 results (published 14 Sept 2021, for 6 months to 30 June 2021) -
Corero achieved a negligible $0.1m EBITDA profit in H1.
This was a loss before tax in H1 of $(1.2)m (which benefited from what looks like one-off “other income” of $637k - forgiveness of PPP loan)
Net cash was $5.1m at 30 June 2021
NTAV weakish at $(0.6)m, but as with most software companies, it benefits from favourable working capital (customers paying up-front), so this balance sheet is probably OK
Capitalised R&D of $938k in H1
My opinion - I can’t get madly excited about today’s update. It’s OK, but the company is still loss-making once you take into account capitalised development spending. EBITDA isn’t a real-world profit figure for this type of business.
So from a value/GARP investor point of view, the mkt cap of £65m can’t be justified.
However, from a growth investor point of view, in a bull market for tech companies, the valuation could be seen as quite reasonable. Cannacord points out in a previous research note that Corero’s peers are valued at 3x its rating (on an EV/Sales basis, which seems crazy to me, but that seems to be the current fashion for growth investors).
Corero has some big name US partners, including Juniper Networks. I wonder if there’s a possibility that it might become a bid target from the US? Juniper already owns 10% of Corero. There’s only a small free float, which can be great when really good news comes out, as there are hardly any shares to be bought, so people have to chase up the price to get any.
The Chairman, Jens Montanana owns a 38% stake, so he’s in the driving seat.
Overall, it’s not my usual type of share, and the long track record of poor performance and heavy losses does bother me. That said, I’d be inclined to have a small speculative punt on this, if I were swimming in cash (sadly not the case right now!)
As you can see below, this share has been a lousy performer, and the share count has risen a lot over this period too.
.
.
K3 Business Technology (LON:KBT)
179p (up 4% at 13:16) - mkt cap £80m
This is a software group. I’ve not looked at it for a while, and in the past its weak balance sheet ruled it out for me. Checking its H1 results though, the good news is that the balance sheet was fixed earlier this year, with some disposals. NTAV is now positive, at c.£3m, after writing off £25.7m goodwill and £8.4m other intangible assets. So it is now within my investable universe.
The company seems to now have a much tighter sector focus, on fashion & apparel brands, and sells both third party, and its own software.
Interim results to 31 May 2021 look ropey to me, with it still being loss-making.
Trading update today - FY 11/2021 has been in line with management expectations. We have to assume this is the same as market expectations - why couldn’t they just have said so?
Adj EBITDA expected to be higher than LY (continuing ops, i.e. ignoring disposals)
Stronger operational cash generation
No figures provided on either of the above
Net cash of £9.0m - which is a comfortable position I think
New clients mentioned (but no brand names provided)
2 non-core businesses sold for £16.4m in total during the year, which has transformed the balance sheet, so looks a good move to me
New CEO has reorganised the “go-to-market team”
My opinion - used to be negative, due to balance sheet weakness. Now that’s fixed, I’m neutral on this share. It seems to be undergoing a turnaround plan, but I can’t see any evidence yet that there’s an exciting investment opportunity here.
Software for the apparel sector doesn’t strike me as a particularly exciting niche, with so many participants under competitive & structural pressure, even the online companies now.
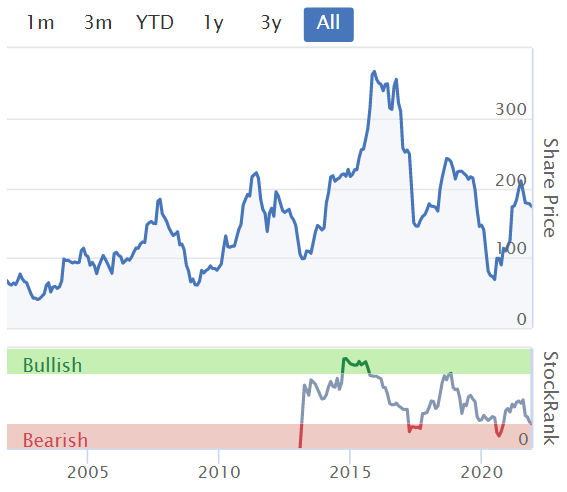
A long-term chart like the one below, suggests to me that this share might be better for traders, not long-term investors possibly?
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Parsley Box - I agree with the doom laden conclusion - but am surprised at the stockopedia QV values given this analysis.
Mcbride (LON:MCB) banking covenant Dec21 waiver just announced. So that removes covenant risk until Jun21, the next test, which they are also in the process of negotiating.
An interesting play if you believe that inflation has peaked, and they will be able to drive through double digit price rises successfully across all contracts.
Long term play is that many smaller private-label suppliers would have gone against the wall with inflation, so should lead to more market share. In addition, absolute profit should increase from 2023, given that their top-line revenues will increase c20%-30%, from both existing sales let alone organic growth from more market share. That is if they manage to hold onto their profit margins.
Would leave their debt and pension obligations more manageable.
Can really see this being a PE takeover once the risk and turnaround is done. Refi the bank debt at cheaper rates, and milk the low PE/cashflow multiple, and then re-IPO in a few years time.
(I don't hold but a share I have been in and out of over the decade!)
CAM
“The share price is back to where it was 15 years ago. Although the total shareholder return would be better, including divis. Wouldn't it be great if we had a chart showing total shareholder returns, not just the share price?!”
I do not know this share but Sharepad gives the total returns figures:
15 years -0.276% pa
20 years 5.49% pa
Regards
Michael
Anyone attend the Revolution Bars (LON:RBG) AGM today? Any new commentary or interesting sentiment from management?
I note their shares have recovered somewhat in the last few days, despite now more restrictions in Wales and Scotland announced, and a good chance for England ones to come.
I can’t understand the price recovery, given all the bad news re covid, only thing I can see why is that the share was tipped in the times last week. (I hold)
Further gains this afternoon for Revolution Bars (LON:RBG) off OK (not huge) volumes, but post AGM.
Probably just tracking the wider recovery in travel and hospitality shares. But I'm just a PI in the dark!
I think broadly speaking a few things have become quite a bit clearer that is now manifesting in a unwinding of some of the sell off.
1) Omicron appears far less severe
2) highly transmissible so lots of cases but peak wave comes quickly and then drops off rapidly
3) quarantine windows can thus be reduced - mitigating staff shortages
In other words all the real world data the South Africans kindly gave to us (and was completely ignored by our own science at the outset - instead focussing on doomsday panic) appears to be bearing a reasonable semblance of reality here as well. Assuming that continues to play out then peoples confidence should return quite quickly leading to a very short window of pain for hospitality and travel restriction windows. So for now I think investors are moving back to a slightly negative but more neutral position.
Pre Omicron Revolution Bars (LON:RBG) was 23p so has moved from 18p to 21p reflecting that mild negative sentiment. The group is net cash positive so also has wiggle room to cope with short term pain in my view.
The real world data was closely examined by scientists the world over, but at least initially it was not peer-reviewed so the rational approach was to play safe which, thankfully scientists and clinicians did. No-one ignored what was coming out of South Africa.
They did and they even said they did. They did not overlay any real world data over their own modelling, instead preferring to dismiss it completely and predict doomsday instead, with all the consequences that has. The one good thing that may come out of this mess is if the models prove to be woefully inaccurate again it will force a re-think.
It's still early days in S Africa, this morning's RNS Brief from £BRB makes for interesting if not disappointing reading. I hold.
BRB ?? Can't find that on RNS. Do you mean Biomax Rubber or Breaker Resources?
I confess I’ve never explored the business in detail but the thing that has kept me from investing in D4t4 Solutions (LON:D4T4) is that their revenue growth has been so slow for so many years at a time when =“data is the new oil”. It can’t all be down to a switch to SAAS billing, surely? So where’s the magic IP?
I have a small holding in Corero Network Security (LON:CNS) . My view is that it is essentially a potentially very useful service to on-line businesses which would incur little cost in producing additional sales; especially as the majority are now provided from a remote server, rather than the old black box approach. It's a bit like Pci- Pal (LON:PCIP) which was growing great guns until the recent IP lawsuit. Partners such as Juniper may prove a powerful driver for new sales.
It is undoubtedly a total punt but after a torrid ride it would not take much good news from here to produce a fairly dramatic turnaround.
I know next to nothing about cybersecurity but my first thought when I read Paul's comments about Corero Network Security (LON:CNS) was why would you use them for just one service (DDOS) when US companies like Cloudflare offer DDOS & so much more (load balancing, rate limiting, DDOS, edge compute, CDN, developer tools etc.) Just my 2p worth.
I might be the only person under 60 who enjoys the meals from Parsley Box (LON:MEAL) a lot but thank goodness I resisted the temptation to invest.
Hi Gostevie,
I remember you saying you like Parsley Box (LON:MEAL) food, and several other subscribers here have mentioned that they, or elderly relatives, enjoy them too. The TrustPilot reviews seem generally OK.
I think management need to take a much more focused, and lower cost approach. I remember the CEO saying they like to maintain a big call centre team, as many customers like placing orders by phone, and like to have a chat because they're lonely. So MEAL staff are happy to provide this service. Lovely though that is, it's expensive, and unless a much more profit-focused approach is taken soon, then I think it could pull the company down into insolvency.
It all depends whether they're able to raise fresh equity in 2022, and at what price. Very high risk, in my opinion.
Regards, Paul.
I looked at the company at IPO - I thought it could be a great business as there is a need - but the food looked like school dinners and it only comes in tones of brown. It is many decades since I was at school but at least we had something resembling green, even if it smelt of sulphur. Maybe as a nostalga play? but is this really better than going to a supermarket and going for a chilled dish and a few fresh prepared veg that can be microwaved easily?
I keep thinking that we'll see Jamie Oliver popping up on the screen trying to save our pensioners from the new "turkey twisler".
Santa Rally anyone? Article from Investing.com
According to Politico, the U.K. Health Security Agency will say later Wednesday that its data confirm that Omicron causes less severe illness than Delta, the variant that was dominant in the country until this month. However, it’s also expected to warn that high case numbers could still lead to a sharp rise in hospitalizations in due course – something that has failed to materialize yet, either in the U.K. or in South Africa, where it was first detected.
I just saw this report on the South African Omicron situation on Bloomberg.
South Africans contracting Covid-19 in the current fourth wave of infections are 80% less likely to be hospitalized if they catch the omicron variant, compared with other strains, according to a study released by the National Institute for Communicable Diseases.
Once admitted to the hospital, the risk of severe disease doesn’t differ from other variants, the authors led by scientists Nicole Walter and Cheryl Cohen said.
https://www.bloomberg.com/news...
South Africans contracting Covid-19 in the current fourth wave ofinfections are 80% less likely to be hospitalized if they catch the omicron variant, compared with other strains, according to a study released by the National Institute for Communicable Diseases.
Quick swag: if Omicron is twice as transmissable as Delta and 80% less likely to cause hospitalization then, all things being equal, the number of people hospitalized under Omicron would rapidly exceed those under Delta.
All other things aren't equal, of course, because we don't know the impact of the UK's far higher vaccination rate, or the role of natural immunity which is greater in South Africa, or the impact of the younger SA population or the effects of mandatory mask wearing there. Still, it makes you think.
Swag figures: Delta has an R of about 5 and a hospitalization rate of 2.3%, Omicron has an R of 10 and a hospitalization rate of 0.46%.
Feel free to correct my guesstimates.
timarr
I thought the R rate in London last week was estimated at 3-5 for Omicron. And Delta is surely no more than 1 given how long it has been around? Should we just put London under lockdown and leave the rest of the country alone? Cancel all trains in and out until the New Year and close off access to the M25!
Covid total infections have been stable for 5 days now and only increasing by 1/3 each week through December. Appreciate that may change but until it does let's stay open - please.
Numbers have been flat for 3 days. Too soon to hope we're coming through this through individual action and common sense plus massive booster numbers and even a good uptick in first vaccinations? Good to see some additional help for hospitality and arts as they have already been massively impacted by our choices over the last 2 weeks. Keep well.
I thought the R rate in London last week was estimated at 3-5 for Omicron. And Delta is surely no more than 1 given how long it has been around? Should we just put London under lockdown and leave the rest of the country alone? Cancel all trains in and out until the New Year and close off access to the M25!
No idea what you're on about, I didn't suggest any of that - and more than happy to take an alternative number for Omicron R if you have a source for it. All I've seen is that it's 2 to 4 times more transmissable than Delta, which itself had an unmitigated R of 5.
As I noted, those figures aren't accurate due to hoards of confounding factors. Plus, as marben noted below, if Omicron is less dangerous then hospital stays will be shorter, which will reduce the overal NHS load.
All I was doing was pointing out that just because Omicron is less dangerous than Delta it doesn't necessarily follow that it will have a reduced impact on the NHS. But given the potential for the NHS being overwhelmed, you can see why government advisors are anxious.
All of which, under the circumstances, I thought might be a useful observation for investors thinking about where to invest at the moment.
timarr
There is another complicating factor IMO. Not really discussed in media.
Everyone has been focused on whether hospital admissions will be too high and overwhelm the system.
However, there's been no focus on hospital capacity. The difference with omicron is that it is more contagious than Delta. Hence with the same level of protection (mask, gloves, etc) the risk of transmission between healthcare worker to healthcare worker is higher. Also risk of them catching it on public transport, at home, socialising, etc.
If hospital capacity falls because of a lack of staff, that still causes the system to be overwhelmed and hospitals maxed out, even if hospital admissions outlook isn't bad.
dahokolomoki
True but what also does not seem to be discussed in the MSM is whether the policies that have been adopted to “control” the virus will overwhelm the economy. Further SAGE (I know S stands for scientific) is made up entirely of scientists. No economists, businessmen, bankers, social scientists etc.
I believe that policies in reaction to the pandemic can not be separated from the supply chain issues and the inflation (possibly high inflation) that we are currently experiencing. If in “protecting” the NHS while perhaps not destroying the economy, we cause long term damage to it, is that a sensible course of action.
Regards
Michael
Hi MichaelFBS. I think we all know what death from COVD infection means but I would be grateful if you could clarify what "overwhelming the economy" means in terms of deaths?
True but what also does not seem to be discussed in the MSM is whether the policies that have been adopted to “control” the virus will overwhelm the economy.
The evidence suggests you do more harm to the economy by letting the infection run relatively uncontrolled than by tight controls. Countries that have kept infections and deaths to a minimum have suffered much less econimic slowdown than thos that haven't. The UK is amongst the highest in terms of both economic conraction and deaths. That is complicated by Brexit which has also hit the economy, but the trend is clear, and the UK is not the only country showing that.
Deaths, lots of expensive hopsital care, loss of work time, people avoiding crowded situations by their own choice to avoid infection all cause damage to the economy.
I take your point re hospital capacity and that this may vary with staff sickness.
However IMHO "hospital admissions" are the wrong number to be monitoring, as there are also Covid hospital exits, generally through patients getting better but also due to patient deaths.
And allegedly AIUI average hospital stays with Omicron are considerably lower than with Delta as its far less severe, certainly in terms of the South Africa experience.
So, its the number of people in hospital with Covid (and therefore on Covid wards) vs the associated hospital capacity which is key... ...IMHO.
Looks like more liquidity and buying in small caps past couple of days. Santa small cap rally!
Inflation seems to be the main culprit.However when I see around me I see deflation on non essential items.War between Ukraine and Russia could be in Feb when the ground is solid and the heavy vehicles can cross the borders.Hopefully little friction.What do you do when everything is overbought or overpriced.Energy prices when they come down can help with reducing inflation.Bank of England has increased the interest rate which is very minuscule.Equity seems overvalued so the increase in interest rate will not allow the money to flow from property to Equity.Gold has traditionally been used to hedge against inflation.Digital Currency has now partially taken its place as they are in Limited quantity and may replace the paper currency in the future.However it has to cross a lot of Hurdles to get there.
Is it possible to have five Companies in the new year ,that can go in the Bargain bucket .Dont forget the new mutated virus is weaker than the original strain for its survival.How do you stimulate the economy to increase growth?
Morning all,Thanks mr c for your morning's update.
CRS ,update to winding down where the management group feel they need to be incentivised & rewarded for failure,if it's a case where they feel they need to be motivated with monetary rewards even though their fees are over 2% & performance has been shocking then i can only say Richard Bernstein should be ashamed of himself.
Re Crystal Amber Fund (LON:CRS), I was tempted to buy in here given the discount to NAV but mainly to vote against that incentive scheme! But I thought better of it - given the background of an activist investor being disrupted by a more ruthless activist I think it's probably more entertaining to watch from the sidelines.
Hi everyone, I’m wondering, if Putin were to take Ukraine easily, then maybe spurring on China to act and they go for Taiwan - we’re all wrapped up in Covid… where is the safe money? Food? Fuel? Gold?
Weapons?
Do you think? I don’t think the appetite for boots on the ground is there.
Our own Government has incrementally disarmed us over the last century and few know how to pop a bullseye any more, the UK is now the ultimate woke (and target).
Investments are only as secure as the world that underpins them. Having some cash desposits at least allows the chance to pile in on the back of any stock market collapse. Gold always valued in times of uncertainty but it is very price volatile. The price of sterling deposits is an almost certain 5% loss from inflation this year.
The other thought would be going further afield from Eurasia to the USA, whether equities or US government bonds.
I like the line in the K3 Business Technology (LON:KBT) trading statement '...in line with management expectations'
Fundamentals aside the Parsley Box (LON:MEAL) website looks completely unappetising. I understand they're going for an older clientele but when you compare to Gusto or even Hello Fresh this feels like a non starter. Both of whom have substantial technology teams which are not cheap. Feels like Parsley Box has a long, long way to go.
Parsley Box (LON:MEAL) - just looked at their website. Completely agree that the presentation of food is v poor - some of the descriptions seem OK, but the pics are v unimaginative.
Looking through Trustpilot reviews - they look credible. But a recurring theme is that portion size is small - something that should be easily fixed.
Given who their target customer is (elderly, probably housebound), I thought the Parsley Box (LON:MEAL) website looks fine. Also it's very easy to place an order, and I found the whole ordering process worked really well, when I last tried it out.
The problem with the photography, is that it's not the actual product! Photos show large chunks of meat, whereas I found the actual product has the tiniest little specks of meat.
I'll place another order, to see what the product is now like, they do say it's been improved. The half bottles of red wine were gorgeous, one of the nicest wines I've ever tasted.
Regards, Paul.
also cost of energy bills will finish off energy intensive businesses
Discounts for those? Have to balance the books somehow to keep GDP afloat.
No need for gas storage according to Michael Fallon in 2013.
https://www.gov.uk/government/...
Bill payers will not be asked to subsidise increased investment in new gas storage facilities, Energy Minister, Michael Fallon confirmed today, saving bill payers subsidy costs which over 10 years could have amounted to £750 million.
Gas supplies seem to be holding up, despite the very low energy produced by renewables recently. I found this site interesting: https://grid.iamkate.com/?utm_...
As you can see wind/solar have been low this year only producing around 23.4% of our energy and that excludes imports. Last year wind produced far more energy. Replacing gas unless we go nuclear will not be easy.
But Gas and Electric domestic prices will be shooting up again in April, unless gas prices fall back, prices have gone again recently because of the Ukraine/Russia situation. Demand should start to fall off in March/April unless we get a cold spring again.
D4t4 Solutions (LON:D4T4) (I hold) Paul - my thoughts are very much the same.
It's been a while coming but this is now shaping up like last year. A disappointing H1, followed by contract wins update in December and a confident in meeting expectations statement. Then during or at the end of Q4 more contract wins and a 'beat' .
These two wins are very chunky. Last year they itemised more wins - but no contract sizes. I take that as a message. As well as being over a third of revenue in this year - it raises ARR by near 30% which means the FY23 forecast of £27m revenue needs to be raised even if FY22 isn't. Yet.
Looking at H2 very simply:
Forecast rev 24.3m - H1 of 7.6m is £16.7m in H2
H2 run rate 'arr' is 5.2m which gives them £11.5m to sell - and these contracts add £9m
leaving only £2.5m of further sales in Q4.
Which raises the probability of a beat in my view considerably -one more large contract win and they beat. But with such long pipelines nothing is certain til its certain. On the flip side - these are very sticky customers and this large win demonstrates their ability to both cross-sell and upsell.
The icing on the cake will be when their recently bought in sales team starts to make sales directly as well as through their partners. The product development has been evolving the ability to do this. But patience is needed.
cheers
Mark
The other thing to mention here is that they don't announce all contract wins, only very material ones. So you are assuming in the above that no other sales have been made and I find that unlikely, so I expect they are probably very close to hitting this years expectations already. Then towards the end of the financial year a number of contracts are renewed - the company are obviously trying to move all contracts to ARR but there are quite a few legacy ones that haven't. It is actually this end of year renewal bias that causes the skew in H1/H2 rather than any specific seasonality.
The Fraud platform opens up a very large new market for them, so the first significant sales to global players is actually the key component to this announcement that should make people reawaken. I didn't really have any concerns over H2 expectations as they generally have quite high visibility over this despite the actual recognition coming at y/e.
Hi David,
Re D4t4 Solutions (LON:D4T4) (I hold) you said -
It is actually this end of year renewal bias that causes the skew in H1/H2 rather than any specific seasonality.
Yup, good point. As I was typing the article, I felt uneasy using the word "seasonality", which didn't feel quite right at conveying the contract renewals falling in H2.
I've edited the article slightly to reflect this point (with a hat tip to you!) Thanks for flagging.
Best wishes, Paul.
D4t4 Solutions (LON:D4T4) (I hold). I'm not sure that I'm suggesting they do....
But companies with seasonality often align their own financial year to avoid having the business peak right at the end of the financial year, to avoid this "will they, won't they" uncertainty - which seems pretty pronounced in D4t4 Solutions (LON:D4T4) case.
Hi garbetklb,
D4t4 Solutions (LON:D4T4) don't really have seasonality. They just happened to sign a number of large contracts towards the end of their financial year which renew at the same time every year and create an effect that looks like seasonality. In D4t4 Solutions (LON:D4T4) case they are trying to move away from this with high conversions to ARR. It would be odd for them to move financial year end in this case. An ARR model is much better.
best
David
D4t4 Solutions (LON:D4T4) -
'So you are assuming in the above that no other sales have been made'
Thank you David - but no, I am not assuming that. I said
'this is now shaping up like last year. A disappointing H1, followed by contract wins update in December and a confident in meeting expectations statement. Then during or at the end of Q4 more contract wins and a 'beat' .'
It looks to me as if we are in a agreement?
My figures were intended to show that exceeding expectations is very likely - though perhaps I was too understated in leaving people to draw their own conclusions. I would be very surprised if they don't make another £2.5m sales in Q4 - but then nothing is certain until its certain. Management is cautious and prudent. I like that. It's part of the attraction for me.
I agree with you that the FDP is a huge opportunity.
The one problem I have with D4T4 is being able to forecast what kind of sales trajectory is actually likely for the next few years. The management is cautious - and as a result the broker forecasts make the shares look expensive. The market opportunity is huge, and reality will be somewhere in between.
The historic CAGR revenue is 4%. Which I know covers the transition and increasing product development. Even the 2 year forecasts CAGR revenue is 9% - which would not justify the current share price. So where is realistic? I am sure that they have internal targets for their penetration of the market. I am finding it hard to pin down between the unhelpful forecasts and huge?
Do you have a view on what rates of sales growth you think likely?
cheers
Mark
Hi Mark,
Yes, no disagreement. I suspect in-line statement is a cautious view, which is fine if they beat.
What I am trying to articulate in general is that H1 wasn't "disappointing", nor was it the previous year. It was more or less exactly as expected. The illusion of disappointment is created each year at H1 stage when sceptics come out and say "oh my gosh, how are they going to make the numbers up in H2?". The answer, of course is in the heavy weighting of H2 renewals, where the probability of that renewal is very high but uncertain until pen is put to paper. Unfortunately too many investors don't bother to understand the company's results - a symptom of our time that everything must happen right now! The company is addressing that by moving to an ARR model which should help considerably once transitioned.
Whether the share is expensive or not on 35* earnings rather depends on your view of future growth. I don't think it is out of kilter for similar data driven software businesses here or in the US, so on a relative value basis it isn't. On a pure PE basis it may appear expensive but one of the problems with PE analysis is that it completely ignores the core value of IPR creation. So from my viewpoint it is only expensive if you think there is little in the IP. The reason I hold is that I consider the IPR valuable and best in breed and this is being demonstrated in top tier global financial institutional sales (and importantly cross -selling). The fact that these large corporates both renew and buy additional / up scaled products at the same time tells you the product adds value and that bodes well as a reference point.
I agree it would be helpful to understand sales growth expectations but I suspect the real growth in sales on FDP initially will be large and lumpy affairs that management don't want to predict the timing over. I doubt these are factored into the expectations. Thus I feel this stock will rise in steps as sales come through rather than a nice gradual rise but I'm ok with that for now.
D4t4 Solutions (LON:D4T4)
Thank you David.
Yes. I fell into the trap of using the label 'disappointing' - without being clear that whilst it was disappointing to some it was not to me. Uneventful would have been my description. Words can be so hard!
I pointed towards the 30% increase in ARR from these two contract awards.
An annual increase of 30-40% in ARR would do me very nicely over the next few years. I ragard this award as a very useful pointer towards what might be realistic as a baseline - with plenty of upside potential.
As you can probably tell I am not that happy without a spreadsheet - mainly so I can benchmark my own expectations. I'll be reading the tea-leaves carefully over the next 18 months to see if this is something I can build out towards a forecast.
thank you for being so helpful,
cheers
Mark
Thanks Mark
Nothing wrong with being comfortable with the spreadsheet. I expect that probably keeps you from making some horrible mistakes over time.
I think your tea-leaves description on D4t4 Solutions (LON:D4T4) isn't wildly off the mark. It certainly puts a number of investors off the stock and I can empathise with that. You need a certain amount of faith in the value of the IP to hold whilst the PE ratio appears high, something the Americans are probably better at than we are in general. I'm bullish over the company medium term and think this price will look very cheap but I understand why others don't see the same value. A few good sized FDP wins will help with that and probably the thing to be watching most closely.
Is there a 2022 stock picking challenge scheduled? I missed the 2021 challenge due to having never seen any notification until it was too late. Just making sure this doesn't happen again.
This is the original I believe, which we should support more than the glamorous Stockpedia one...
http://stockchallenge.co.uk/
The entry form is one of the tabs along the top.
Interesting report from Capital (LON:CAPD) this morning. Not the most newsworthy but significant for the company is a contract win in Tanzania with an existing customer which should add over $30m in revenue over the next 3 years. This is against the background of 2 upgrades to revenue this year (though this contract only starts this month and wont affect this year's financials.) The current forecast is for $220-$225, so an extra $10m a year for each of the next 3 years is not insubstantial.
The excellent Mark Simpson covered Capital (LON:CAPD) (along with Cmc Markets (LON:CMCX) ) at the November Mello meeting under the title 'hidden value'.
This 'picks & shovels' company is making significant value added progress. I only wish I had taken Mark's advice when he presented Bloomsbury Publishing (LON:BMY) a year earlier. In this case I have added to my Capital (LON:CAPD) holding this morning.
Given the relative shortage of news this morning, I wonder if I may indulge myself with a bit more commentary on Capital (LON:CAPD) which I find more impressive the more I look at it. Unfortunately the market doesn't share my enthusiasm and would be interested in other readers thoughts on why not. The PE is 7.4; the stocko rating is a Super Stock; stock rank is in the 90s; the momentum is high. I can see a few negatives, but I will leave that to other readers to come back on if you will please. You can also come back with some positives I have missed. A general invitation.
I have dug back a bit further this morning. I listened to the InvestorMeetCompany presentation on 25.8.21 and hadn't done before. Must have missed it. I was very impressed by the Exec Chair presentation, single handed who is also a large shareholder. Skin in the game. Perhaps he is a very good manager and presenter and I am a gullible investor, or perhaps the story is a very good one and about to get better.
The business is based on a rig operation in many parts of Africa, with long term contracts, but the most recent jump is big - for them - investment into earth movement contract in Egypt, on a long contract. So a lot of additional debt - but which as he put it 20% debt to equity with which he is comfortable. that is out of the way now, and the payback on the 2020-2021 investment of £135m is revenue of around £65m for a long, long time.
The rig operation is becoming more efficient, and the figures shown in the presentation (I recommend you watch it - are very attractive......but there is more.
As the Chairman says, he comes from a financial market background, and the business has for some time been investing in companies with whom they work - and very profitably. Listen to the presentation........ and this is not a short term thing either. It will continue, and is building in profitability. In answer to a question, he did say that one of the investments was in a company expected to come to market in H1, 2022.
Last but not least, Capital (LON:CAPD) is actively offering another service, using a technique developed in Australia (he is Australian) called Crysos. This is delivered through their operation called MSA Labs and may well turn out to be a successful company in its own right, with a medium term revenue target of $50-$80m. It also offers their clients a service they clearly value, with results in hours rather than weeks.
Finally, I was most impressed of all by his answers to 2 questions.
The first was about M&A intentions. He said basically he didn’t see the point. He said the possibility of new business comes up; if they get he can get the equipment and the people. Why bother with M&A when you pay a lot more for the extra business. Seemed quite simple really! Whether that answer will be affected by the more recent logistic and wage inflation issues, I don’t know. I wouldn’t think so.
The second was about broadening out into non-gold focus. He said that in the past, the company had been into nickel and copper, and he said that he could see an extension into copper and lithium for example.
In the meantime, he seemed comfortable that the industry Capital (LON:CAPD) focuses on was seeing more investment now after a period of under investment; and they were winning long term contracts with top grade companies. So he felt that although potentially cyclical, after a low in 2016, he felt the industry’s investment cycle was at quite an early stage.
What’s not to like, and will we see a re-rating sooner or later? 4 brokers are positive, and the broker forecast has a target price of nearly 60% above the current SP. Don’t know who the brokers are. Maybe someone else has access? We should see free cash flow EPS start to come back in 2022 which may have been holding back the SP.
Oh, and yes just a restatement form my previous offering today. A new contract expansion in Tanzania, and yet another revenue hike – the third of the year. If you see the chart in the presentation which shows the passage of % increase from revenue through to profitability, it is a very steep positive curve. With a forecast of around $225m now in 2021, the medium term target he is setting at $600m. Attractive, IMHO.
If you have got this far, thank you for your perseverance and I look forward to the wealth of comments that must be out there.
ridavies
Thanks for your thoughts, do you have a link for the investor meet presentation please.
Richard
No, you will have to join if you are not a member already - no cost - and then search for this presentation - Capital or CAPD on August 25th this year.
Hi Richard
Sorry my link is straight to the login page
https://www.investormeetcompan...
Cheers
Tommy
Nice summary, thanks. There's a lot to like here, I'm not sure what a reasonable PER is considering the operational and juristiction risks, say 9-10? As a capex heavy biz the investment case rests on whether you agree with the CEO's view that were are early in the investment cycle of Gold mining in Africa, and also bullish Gold generally.
I'd like to see them diversify into Cu/battery metals for sure. Also, although the CEO and founder have considerable skin in the game (12% and 6.4% respectively), I'm a bit wary due to the level of director sales from the Commercial Exec - over £0.5m this year, all around 80 - 85p level.
Capital (LON:CAPD)
Very nice new contract with AngloGold Ashanti for $33m over 3 years. Good to note it uses 5 rigs from the current fleet, increasing utilisation rates.
Growth looking good here at the moment and with capex tailing off now the investment in the Centamin contract is over, there now appears potential for increased dividends.
Phil
(I hold)
Good morning. Like you Paul, I hold D4t4 Solutions (LON:D4T4) and this is an impressive set of contract wins. It is particxularly interestng that the announcement includes the first 'conversion' of trial to purchase of the Group's FDP product.
If I remember correctly, the company announced that it was going to increase investment in sales and marketing especially in the new product FDP at the expense of current profitability. The market was not particularly impressed with that at the time, and in the general sell off in the last few months the SP has fallen significantly.
As you and Jack say, the valuation still looks high. However I would hope and expect it wont take too many more wins like this with top quality customers at what must really be a tough time to build sales out there to convince the market about the validity of the company's medium term strategy. I am looking to increase my holding at an appropriate time.
Good morning Paul,
I wonder whether you'd like to circle back and have a look at Innovaderma (LON:IDP) FY results from last Monday? Looks like the turnaround is beginning to work with margins improving and increasing proportion of sales direct to consumer. It's had a very difficult year but its new management team, fresh capital and new focus has promise. Finncap have a report on them and a price target of 90p. The SP today is below the recent raise.
I have been buying and hold a small position.
Cheers
Francis
Re Innovaderma (LON:IDP) - I also think that Mgt are doing all the right things (and that the previous mob were borderline crooks/incompetents given the adjustments made).
The clear focus on Skinny Tan and very much secondly Charles&Lee, with exit or JV to handle the other brands makes sense etc. So, post Covid, the future looks much brighter.
Gross Margins are sharply up to over 60% and a 'more nuanced' ie not exclusively Facebook digital strategy is in place, leveraging Amazon and influencers - a perfect mix IMHO for the the product and target audience.
I think we will see Marketing as a % of sales fall sharply (as at Sosandar (LON:SOS)) as they get this right ie selling more from less spend, a double gain. Since this is 39% of rev this could be worth several margin points on its own.
That said, do you not feel that a trade sale would realise the most real value as the acquirer could cut a lot of organizational cost, achieve bigger discounts on marketing buys. Creightons offered last year valuing the company at around 8Mn, about 10% less than today but today's business has cash on hand following placing and is better overall - but the price is not.
So I would not at all be surprised to see someone come back with a better offer this year - unfortunately, it will not be in the interest of the much better MD/Mgt team to be interested, otherwise this might have been my Christmas flutter.
Thanks for your input on Innovaderma (LON:IDP) Peter.
I think the (aptly named) Prolong JV (it's an Erectile dysfunction product) with their largest shareholder Mark Ward (also large shareholder in Revolution Bars (LON:RBG)) was a good move as frankly they had too many brands to manage for such a small business.
Cheers
Francis
Alot for £IDP rests on the Skinny Tan brand, as the biggest revenue driver for them.
Unfortunately, it disappointed in sales so far this year. Management said COVID impact, and that it is recovering. But my own research shows that the category has expanded massively in the last two years, with lots of new brands and new products. Skinny Tan has some legacy brand equity, but many of the new products have existing brands that have equity too.
On top of that, I'm not sure they have fully cracked the formula for ecommerce growth and influencer marketing - two key ingredients.
I watched your Stockslam presentation on this with interest Francis and Innovaderma (LON:IDP) has been on my watchlist since without me yet pulling the trigger.
i like how the story is panning out here just not sure about the product.
i like the invested management who seem to be doing what they said they would.
Not me at Stockslam I'm afraid Clint, must have been a different Francis. There's no doubt there's a market for their product but the previous management weren't up to the task. The news this week was very encouraging and I believe it might be about to turn the corner.
Cheers
Francis
Hoping so Francis.
Apologies for the mistaken identity!
Clint
Thanks for that ForAFewDollarsMore in fact the Innovaderma (LON:IDP) StockSlam wasn't fwyburd it was me - clearly people called Francis have an affinity for the company :-) You did well not to invest at the time, since my pitch was clearly too early. Your view "I like the invested management who seem to be doing what they said they would." is very much where I'm at. There's really good alignment of incentives. The products seem fundamentally OK but fighting for a share of a crowded market.
With hindsight, it seems clear that the turnaround is taking longer than I had hoped. I agree that management are doing broadly the right things, but the fall in sales is disappointing and increased margins have not fully compensated for it. I'm still holding and looking for improved sales next year. Fundamentally it's a sound product range with growth potential if the marketing is done right.
Best wishes,
Francis (the other one)
Thankyou Francis.
It seems 2 + 2 = 5 in my calcs here!
Sadly the rationale on my share picking seems to be working in a similar way!
I will have a serious look on another dip but need to offload something first. Hopefully though there won't be another dip...
Shout out at Xmas to MrC for his superbly useful summaries and instructive, concise daily wit: "Majority owned by chmn. Hmm." Hmm - 3 letters, not even a word but says a lot! Thx.