Small Cap Value Report (Weds 22 Feb 2023) - SDG, GHH, AVG, SIS, ANG, SNX, TRT

Good morning from Paul & Graham.
Today's report is now finished.
I (Paul) recorded an interview with Paul Hill of Vox Markets yesterday afternoon, which should be published later today. So I'll insert a link to it here, when available. We run through the main shares that I've bought using my windfall from the takeover bid at Seraphine (BUMP), all previously mentioned here. It was a good back & forth discussion, with lots of interesting topics, although we ran over time at about 1hr 10m, so people might want to watch it in two sections instead of all the way through!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Sanderson Design (LON:SDG)
119p (pre market open)
Market cap £85m
Major licensing agreement with NEXT
There has already been licensing of designs from SDG to NEXT, but the relationship is now deepened to include SDG’s Clarke & Clarke brand -
… NEXT will hold a master agreement giving exclusive rights to produce a very broad range of Clarke & Clarke homeware products including bedding, towelling, tableware, furniture and lighting.
An initial £2.6m accelerated licensing income will be recognised this year, FY 1/2024. As licensing income is almost pure profit (but can be lumpy), this looks a material deal in the context of existing forecast from Singers being £12.0m PBT for FY 1/2024. Hence I imagine forecasts are likely to be raised at some stage.
The relationship with NEXT sounds as if it might make sense for NEXT to bid for SDG at some stage?
The new agreement marks the latest in a series of licensing agreements between NEXT and the Group's brands. These include a Morris & Co. womenswear agreement signed in May 2021, which has since been extended and will see the launch of a new range of NEXT Morris & Co. womenswear for autumn/winter this year.
My opinion - I imagine this could be worth a share price rise of c.10% today, maybe more, who knows? (I'm writing this pre-8:00 market open). As regulars might know here, SDG is one of my favourite value/GARP shares, and I was tremendously impressed with the strategy & ambition from CEO Lisa Montague - one of the most interesting & fun CEO interviews I did last year here (audio) and here (written version).
EDIT: an update note from Singers has just come through (many thanks), saying it's difficult to forecast the income from this deal, but estimating a value of 11-20p for the discounted cashflows. That's consistent with my guess of a 10% share price rise from this deal. Existing forecast for FY 1/2024 is unchanged from Singers, but with more solid underpinnings from this deal. End of edit.
Shares are good value still, maybe partly due to uncertainty over the short term macro uncertainty, and how this might impact the mid to high end furnishings market that SDG supplies.
If you’re prepared to take that macro risk, and think longer-term, I think the signs are that this share should do well - I imagine 200p+ looks a realistic target share price for patient investors. Also it has a lovely strong balance sheet, so there’s not any dilution/solvency risk to worry about, even if short term trading disappoints (which can always happen with any share).
Hence overall, a continuing thumbs up from me for SDG shares. Today’s announcement should give a decent boost to, and hence reduce risk, for FY 1/2024 performance. Also there should be ongoing licensing revenues (unknown size) for a 5-year period from product launch in spring/summer 2024 onwards.
I like the business model, of SDG specialising in designs, and its huge back catalogue as well, then licensing these to retailers & wholesalers, who can look after the product sourcing, and selling of the product.
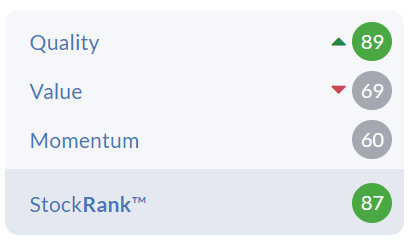
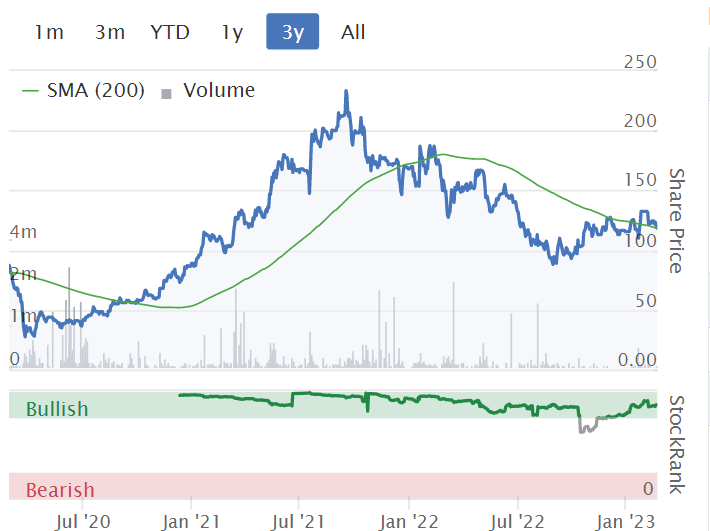
Stockopedia also likes SDG shares, with a high StockRank -
Avingtrans (LON:AVG)
375p (down 3% at 09:09)
Market cap £121m
Avingtrans PLC (AIM: AVG), the international engineering group which designs, manufactures and supplies original equipment, systems and associated aftermarket services to the energy, medical and industrial sectors, today announces its interim results for the six months ended 30 November 2022.
H1 revenues of £50.0m are as expected.
Adj PBT was £4.0m (slightly up on H1 LY of £3.8m)
Good order book with over 90% of revenues secured for FY 5/2023.
Outlook - “cautiously confident” of achieving market expectations, which is 22.8p adj EPS, giving a PER of 16.4 - probably priced about right.
Balance sheet - is strong, with net cash of £17.3m. Although receivables stands out as very high, at £49.2m, which is at least double what I would expect to see for a business with £50m revenues in 6 months. Checking back to the 2022 Annual Report, note 18 reveals that trade receivables were only £17.8m (which is around the level I would expect), but that another £25.7m “contract assets” was included within receivables - as I understand it, this is where work has been carried out on contracts, booked as revenues, but not yet been invoiced. This seems an unusually large number, so I’m raising an amber flag here, that it needs more explanation, and investors need to be comfortable that this large asset is actually going to turn into cash. When? And why is there a considerable delay in invoicing for this work (which would move it into trade receivables, and then cash, once the customer pays). Large contracts with delayed cash receipts can introduce risk that something might go wrong.
My opinion - the numbers look OK (apart from high receivables on the balance sheet). It’s a difficult share to value, as the strategy is to buy businesses, turn them around, then sell them. Management seem pretty good at that, as evidenced by a strong long-term share price performance.
This creates a problem for investors, as to how to value AVG shares? Logically, it seems to me that a sum-of-the-parts basis might be best, which would involve having to analyse all the different companies within the group, and try to guess what each might be worth to an acquirer?
Or we can just treat it as one group, and apply a reasonable PER, which seems to be what the market is currently doing.
Overall, it looks priced about right for now, so I view it in a neutral way.
It would need a lot more research to find the upside, from the individual business units, what contracts they’re winning, etc.
The only thing I don’t like is excessive receivables, apart from that, everything looks OK. So it could be worth readers spending more time doing the more detailed work to properly assess it as an investment. I’ve heard that management is highly regarded, so together with decent long-term shareholder value creation that’s a good starting point for more digging.
Angling Direct (LON:ANG)
31p (up 5% at 10:50)
Market cap £24m
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides the following unaudited trading update in relation to the financial year ended 31 January 2023 ("FY23"), ahead of announcing its Final Results on 16 May 2023.
This looks an OK update, in line with expectations.
FY 1/2023 is expected to show revenues of £74.1m (up only 2.2% on the previous year, but up a much more impressive 58% on pre-pandemic). New store openings have helped growth.
European operation is small, but growing.
EBITDA of £2.2m, but this only translates into PBT of £0.6m, so this is effectively a business running lots of shops & an online business, at just above breakeven. Not very exciting at all, unless there’s a credible plan to increase margins, which doesn’t seem to be the case - the strategy seems to be chasing revenues (by offering low prices) & gain market share. Something might come of that long-term, if ANG ends up being a consolidator and competition withers away?
Net cash of £14.1m is a key investment positive for this share. The overall balance sheet position is better still, as it’s carrying a lot of inventories too.
My opinion - I very much like the balance sheet strength, but what is the point of this business existing? It’s trading a whisker above breakeven, and continuing to expand store numbers, and its European presence, but not generating any return from the deployment of a considerable amount of net assets.
I can’t see what’s going to change, to suddenly make this a great business, because it’s up against plenty of competition, and consumers are likely to shop around on price.
Shareholders have the downside protection of a lovely balance sheet, but what’s the upside excitement? I don’t see any particular upside. So I can only be neutral on ANG shares. The risk is that it could attract a revolving door of value investors, who could park their money in these shares, and then get bored after a year or two of nothing happening.
The top 7 shareholders own 82% of the shares, so it might cross their minds that the AIM listing brings little to no benefits (ANG is fully financed already, so doesn’t need to raise more cash from the market), and will cost several hundred £k in unnecessary costs. So I’d say de-listing risk here is probably too high for me.
It might be a decent trade though, betting on market sentiment improving, possibly?
Graham’s Section
Gooch & Housego (LON:GHH)
Share price: 550p (pre-market)
Market cap: £138m
Trading is in line with expectations at this manufacturer of laser components and systems, according to today’s AGM update.
It has a year-end in September, so we are now in the fifth month of the new financial year.
In August 2022, it issued a serious profit warning, which I covered here. Let’s see if the various issues at the company are being resolved.

Recruitment - UK production facilities are now “fully resourced” and “whilst we still have further roles to fill in some of our US facilities, the situation continues to improve”.
Supply chain - there are “persistent” supply chain constraints, but increased inventory continues to protect the company from this issue.
Order backlog - GHH is “making steady progress in lowering its lead-time for new orders received and reducing its overdue order book”.
The order book rises from £110m to £129m year-on-year, but it is down from the record level seen in September 2022.
Increased production has helped to reduce the backlog, and there has also been “a moderation of order intake” in some categories, “with evidence of overstocking by some of our customers”.
Inflation - because of the large order book, it’s going to take some time for GHH to pass input cost inflation onto its customers and for this to show up in revenues. It first needs to fulfil the historic orders!
My view
This strikes me as a comforting update for shareholders who have had to put up with a long list of problems and issues at this company.
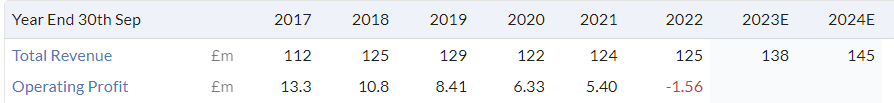
However, I also note that the company’s adjusted PBT estimate for FY 2023, while unchanged today, is now just £9.3m (from finnCap). After what has been done to the FY 2023 estimates, I don’t think I can have any faith in the FY 2024 estimates. GHH’s profits are just too volatile.
The operating margin was weak even before the company turned unprofitable:
I’d like to be more positive on this stock. It is tackling its various issues and does, I believe, have some growth prospects. However, margins and returns have been disappointing in recent years and I think it’s reasonable to have doubts about the underlying quality at this point.
Science in Sport (LON:SIS)
Share price: 13.5p (+8%)
Market cap: £23m
Science in Sport, the premium performance nutrition company serving elite athletes, sports enthusiasts, and the active lifestyle community, is pleased to announce a pre-close trading update for the financial year ended 31 December 2022.
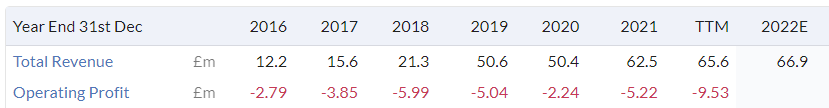
I’ve tracked this company for several years and unfortunately witnessed a stock that has been a money pit for shareholders:
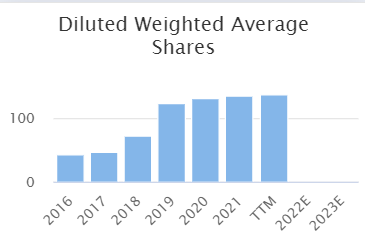
The share count has jumped again, to 172 million, after the company printed another 33 million shares at 15p each in September 2022.
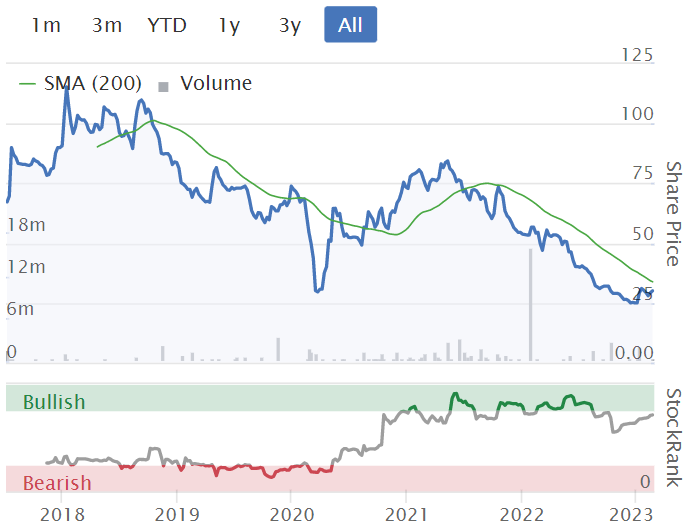
The market lost confidence in it last year, after temporarily allowing the market cap to exceed £100m during the 2021 post-Covid rally:
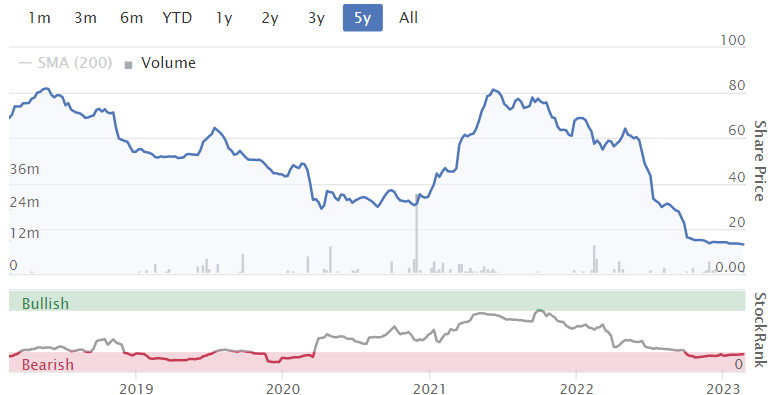
At the time of the September 2022 placing, it announced a “strategic review”, arguing that “the current market capitalisation of the Company fundamentally undervalues the Group and does not recognise the inherent value of its premium brands and market positioning”.
The review “may or may not result in a sale of the Company or of certain Group assets”, and has caused the stock to technically be in an “offer period” since then. This is why Stockopedia publishes the warning that “this security is involved in a takeover situation”. However, I am not aware of any evidence of any offers having been made up to this point.
All of which brings us back to today’s update. Let’s see what’s new.
Full-year performance was “broadly in line with expectations”.
Revenue growth 1.5% to £63.5m, and margins in line with expectations.
Operational developments - the company has a new Manufacturing and Logistics hub in Blackburn which, it is claimed, can grow SIS to £200m of revenue. Today’s update informs us that a new protein bar line has been commissioned this month at this site, and is now fully operational. This should lead to “a transformation in margin”.
Outlook - “optimistic” for 2023:
Macro factors including COVID-19 in China and Amazon global inventory reduction are alleviating. Retail in all regions is in line with our expectations for growth, and the UK had a strong start to the year. Margins are strongly improved due to initiatives including the above items, and a second wave of price increases beginning to contribute.
My view
I’ve always hoped that this company would succeed. When you review the company’s products (also here), it seems like the company should be able to enjoy some pricing power and should be able to generate profits. But it just never happens. At least not yet. The marketing budget and other costs always seem to make it impossible.
Could the new Blackburn facility be a gamechanger? I guess so. I also agree with the company that its current market cap is quite low. The price to sales multiple is now only around 0.33x, which would be far too low if it was performing reasonably well.
There is also the possibility that the company could receive a generous takeover bid during this offer period, and that shareholders could get out at a handsome premium to the current share price.
However, despite these factors, I can’t bring myself to take a positive view on these shares yet.
The company has had the same CEO for the past 12 years and he owns less than 1%. Perhaps if he had better alignment with other shareholders, they might not have been diluted so much during his tenure?
On the June 2022 balance sheet, the company reported net debt of £7m. It then raised £5m (gross) which will help to cover at least a portion of 2022’s losses, but I’d be surprised if the company didn’t have the begging bowl out again sooner or later.
In summary: the shares do have some speculative merit at this low valuation, but the balance sheet is probably still very light on cash. I would need to see proof of an improvement in performance before having any confidence in this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Nice update from Angling Direct (ANG) Expansion and nice cash balance buttressing the balance sheet makes it a defensive stock.
Hi Paul - will you take a look at Transense Technologies (LON:TRT) as I know you are a holder, albeit a small position? Their interims today seem to leave them a quite a bit to do in H2 but, on the other hand, they also seem to have a good pipeline of opportunities and management speak states that there has been 'accelerated growth in revenue and profitability since period end'. Harwood have a 5% holding - as they do in many similar companies. They have £23m of tax losses brought forward (the flip side of previous, consistently poor performance!)
I hold
Hi mammyoko,
I wasn't planning on looking at Transense Technologies (LON:TRT) (and it's not one I hold, not sure where you got that idea from!)
I recall doing some digging on it a couple of years ago, and came away with the view that it might make a bit of money from a licensing agreement with a finite life, but that the upside looked too limited to make the shares worth bothering with.
So unless something has changed for the better to give more upside, it's probably not worth us spending any time on it.
Sorry about that.
Regards, Paul.
Hi Paul - you held on 23 July 2021 but assume you must have sold since then. You conclusion then when the price was around 60p was as follows:
Is it a good investment? No idea! The market cap is about £15m at the moment, and that doesn’t strike me as excessive. It could do well, if royalty incomes rise (there seems to be a decent opportunity there, in large mining trucks, so still a bit niche). Plus a few other projects. The downside seems to be that new tech in the automotive sector seems to take forever to actually start selling. Look at Seeing Machines (LON:SEE) for example. Although TRT is not interested in mass market products.
Overall, I enjoyed talking to management, and can see there’s some speculative upside here, probably with quite limited downside (in a bull market) due to the reduced overheads, and flow of royalties - although note the Bridgestone deal ends in 2030.
I get the feeling they want to extract some shareholder value here in one way or another, so I think it’s worth holding onto my small, speculative personal holding. But don’t feel motivated to buy any more at this stage, let’s see what happens. There’s interesting potential here though, so I wouldn’t write it off.
The change for the better is possibly the number of SA projects that are in the pipeline - 40 compares to 24 at September 2022. Also the comment in the Financial Highlights
Accelerated growth in revenue and profitability since period end
The thing that has also changed since you held previously is that Transense Technologies (LON:TRT) is now profitable and that sales and PBT are forecast to increase significantly in FY23 and FY24. Plus, of course, that £23m of brought forward tax losses means that PAT = PBT for some time into the future.
The question is whether those forecasts are accurate. Evidence from these interims suggests that they have quite a lot to do to make this year's forecast but they have re-affirmed that they are in line to meet full-year expectations putting them on a prospective p/e of 11.6 according to Stockopedia, falling to just under 8 in 2024 if they maintain current momentum. This seems to be too low to me. January has started well with both Translogik and SAW delivering 'strong revenues' The slowdown in the growth of iTrack royalties from 46% in FY22 to 11% in H1 FY23 is anticipated to return to higher growth in H2 FY23. There is a large - but speculative - pipeline of SAW opportunities which remains loss-making but which Neil Rogers believes it is worth continuing to invest in. They seem to have enough cash - £1.28m at 17th Feb - to not need to raise fresh funds and they are re-iterating their intention to start paying a dividend. There are interesting talks on SAW going on with Parker Meggitt which they expect to conclude in H1 FY24.
To me, this looks as though it has turned a corner into sustainable profitability and that there are sufficient signs of interesting new business - including torque-measurement in electrical vehicles to improve range - to be positive about both FY23 and FY24. I suppose there's always the possibility of Bridgestone or Parker Meggitt acquiring them. To me that's enough to be of sufficient interest and I've bought more today at the lows
Thanks for the additional info on Transense Technologies (LON:TRT) - which made me look a bit closer, so I've added a quick comment into the summary section above.
Bottom line - if it achieves the challenging forecast from Allenby, then this share could have nice speculative upside. Trouble is, it's difficult to know if those numbers can be achieved or not, so a bit too much guesswork for my liking.
Also the main revenue stream has a finite life to 2030.
Generally it takes so long to commercialise technology like this. Transense has been around for almost the whole 25 years I've been investing, always promising jam tomorrow, but never getting anywhere. Although now it's stopped burning cash, and there are signs of life with the very small new projects, you could get lucky. Look at what happened with Surface Transforms (LON:SCE) - that's another one with ground-breaking tech, that soldiered on for years, and then seemed to hit the jackpot more recently.
Thanks, Paul. I agree that there is some risk around the forecast here from Allenby. However, at a market cap of £15m and profitable compared to Surface Transforms (LON:SCE) with a market cap of £95m, I think this is a much higher quality proposition and one with much less risk given the value of the brought forward tax losses per share.
I don't have the benefit/baggage of having seen this be a serial disappointer over an extended period so would be interested to hear if it has had similar false dawns. The presence of £23m of tax losses suggests that it probably hasn't and that that deal with Bridgestone was genuinely transformational (in relation to the profitability of an admittedly miniscule company). I agree that there is some risk around the deal expiring in 2030 but that is some way off and, if the product is still used then by Bridgestone's customers, then a new deal would have to be negotiated. Alternatively, Bridgestone might just buy the company before the expiry of the deal if they continue to gain new customers. I don't know the strength of the IP or the competition but assume there must be plenty.
I'm not getting carried away with this one. I've got a decent chunk bought back in September and added to this morning. Mark Watson-Mitchell is a fan and, as I mentioned Harwood are there. But the other holders look quite a rum bunch, including someone who could be a World Poker Series player!
Forgot to mention to anyone interested, Nigel Rogers who is Executive Chairman at Transense Technologies (LON:TRT) is also Chairman at Solid State (LON:SOLI) and Surgical Innovations (LON:SUN) - the former somewhat more profitable for investors than the latter
More (possibly irrelevant) information about Nigel Rogers - he was CEO of Stadium Group for ten years some years before it was taken over by TT electronics (LON:TTG) at a 44% premium. His Linkedin bio references his turnaround skills at both Stadium and 600 (LON:SIXH) where he was also CEO for three years. He looks to have been less successful there but that, in Buffet's famous words, may well have been a case of 'When a management with a reputation for brilliance tackles a business with a reputation for bad economics, it is the reputation of the business that remains intact.'
hi Paul
re Sanderson Design (LON:SDG)
I like the business model, of SDG specialising in designs, and its huge
back catalogue as well, then licensing these to retailers &
wholesalers, who can look after the product sourcing, and selling of the
product.
Forgive my ignorance but could you please clarify how the licensing deal works in practice. Do Next source the product from Sanderson? If not, and they have the freedom to source product from elsewhere, then where are the quality checks to ensure there is no brand damage to Sanderson in the event of poor product quality?
Snazzy
I spoke to the CEO at a Mello about whether Next could produce their own fabric and clothes and she said yes they could. (in context of not being constrained by Sanderson capacity)She did talk about either working on designs with them or giving feedback on designs to them but I cant remember if it was voluntary.
Thanks Fegger.
Sounds like Sanderson Design (LON:SDG) will also earn some profit from collaborating / sourcing Next in addition to the licensing income. Would be handy to know the anticipated breakdown.
Snazzy
Pebble (LON:PEBB) announced they'll publish their FY22 results on 21.3.23 with a FY22 results presentation & Q&A on 23.3.23, 1.30pm. Similar to 4imprint (LON:FOUR) & Altitude (LON:ALT) providing products to the promotional products industry. Facilisgroup with recurring revenues is particularly interesting. Register here where you'll also find details of webinars for:
Made Tech (LON:MTEC) H1 Friday 24.2.23, 12.30pm and
Somero Enterprises (LON:SOM) FY22 Wednesday 15.3.23, 4.30pm (SOM is so unloved PE8.7, Dividend 7.3%!)
Reassuring interims from Avingtrans (LON:AVG) Both energy divisions performing to plan with the exciting potential for the medical division (Magnetica and holding in Adaptix) in the development of portable MRI and 3D X-ray scanners respectively, on track.
Over 90% of current year order cover secured and net cash at year end of £17.3m, in excess of 50p per share, post further investments in Magnetica, Adaptix and working capital. The latter to mitigate supply chain issues, which have started to show signs of easing.
Patience will be rewarded, or at least that is my view
Paul/Graham, thoughts?
Sanderson Design (LON:SDG)
Hence I imagine forecasts are likely to be raised at some stage.
If they dont say it i aint believing it unfortunately - the company had the chance today to confirm if they expect this to affect bottom line numbers and they said nowt. Note this deal will have been in the making from well before the most recent update so i will stick my neck out and say imho its most likely these numbers will already have been mostly/fully factored into the forecasts for this year. Note they had "strong" licence income last year too - so simply to match last year they probably need 1 or 2 deals along these line. So whilst great news this deal exists and £2.6 mill may in itself ensure "a year that matches last" - unless they tell us they expect to make more that they did previously i will simply presume these numbers will support current expectation and no more. Note you could be correct here i may very well be cautious in my assumptions here - i just expect companies i hold shares in to tell us when expectations materially change and they have not said that is the case.
The relationship with NEXT sounds as if it might make sense for NEXT to bid for SDG at some stage?
Does next need the hassle ?, brands come and go ref popularity are they not simply better off letting others doing the hard work and driving great deal from flavour of the month based on the fact they are the elephant in the room. If i was a next buyer (i know didly squat about brands or buying) - i would surely want the flexibility to buy what will sell best - i would not want to be forced to /buy sell tat just because my boss had splashed ou £100 milion on their pet project. I dont dispute that having some core own brands for next may make financial sense - just seems like unnenecessary distration from core duties as a general rule(we do know next focus well on what they do best).
Hi rmillaree,
I like Sanderson Design (LON:SDG) as a company and am an admirer of Lisa Montague. I recently sold my holding in the company for a handsome return being fortunate to have added significantly during the pandemic. This was to fund what I think are more promising opportunities. I may well buy back at some point, should the share price and available funds align.
However I cannot fault the logic of your narrative. As you say the agreement with Next (LON:NXT) would have been sometime in the making, so it is logical to conclude that the outcome will have been included in the recent trading update.
All the best
Hi rmillaree,
Yes you could be right actually. A note has just come through from Progressive, which implies that a deal like this one with Next was already expected. That would also tie in with Singers not raising forecasts either. But getting the deal signed is clearly a positive, and helps underpin existing forecasts, which I think is the phrase Singers used.
Regards, Paul.
Sanderson Design (LON:SDG)
Thanks for that update paul - either way the news today has to be taken positively even if already fcatored in.
Re Sanderson Design (LON:SDG) - I agree with Rmillaree that the licencing news probably just secures the current forecast....but I think a bit of time for the CEO's focus on the US market to mature and world/western economy to improve is all that is needed. She seems to be doing a lot of things right.
On £NEXT being an outright buyer, I also think it unlikely ....but perhaps more possible than you might imagine since NEXT have moved to clever strategy of buying stakes in brands they see working for their customer base whilst leaving the Mgt to run the day to day. But speculation about a takeover is not my investing cup of tea (actually hemlock recently?)
I do, however, like the SDG business and see it as better than a few years ago when the share price was much higher on the same share count - I loved the core sku simplification strategy in businesses like Sanderson Design (LON:SDG) ! I hold and am tempted to add more.
Also - I note that only with NEXT, are their licensing deals including accelerated licensing fees.
If Sanderson Design (LON:SDG) was already on firm financial footing (as it looks like based on net cash position), why are Next happy to throw in accelerated licensing payments?
Wouldn't this be only used if Sanderson was stressed for cashflow and pressed Next to give them upfront payments (in exchange for say, a discount on the licensing fees)?
I note that they did this accelerated licensing fee thing too in their original/first contract with Morris & Co back in 2021. So maybe this is BAU and I'm worrying too much that this is a red flag?
Assuming the accounting treatment is identical to that at £GAW...
...At Sanderson Design (LON:SDG), presumably the £2.6m is the minimum guaranteed licence income over the 5 years of the deal. So a minimum £520k per year, the question being by how much can the income to the company can be expected to exceed that?
Obviously the £2.6m will be an asset on the B/S, but the arrival of the associated cash will probably be phased over the duration of the agreement
SDG
I’m a huge fan largely due to license agreement which I see as growing not lumpy , in fact it’s a golden nugget for SDG .
Historically lumpy maybe but the way retailers like Next recognise brands now is very different to 10 years ago .
That’s why they are signing 5 year deals because they know the value .
A good friend of mine represents the Conan Doyle estate and the landscape has changed .
I really think the “royalty income is lumpy” comments are not understanding the evolution of how the historic brands are recognised by the major commercial players - they want and need a piece of the action for long term , on long contracts .
I did previously say that once SDG royalty income exceeds annual 10 million it becomes a very clear buyout target , getting close now .
Hi planetx,
The only reason I mentioned that licensing income at SDG has been lumpy, is because that is a fact! There have been a number of licensing deals previously where fashion retailers have run just a season's products based on SDG designs, which were one-off product ranges, not continuity ranges (from memory, I think one of those was H&M?)
Although as you say, a 5-year deal with NEXT is a lot more interesting going forwards, and for an extensive product range by the sounds of it. And homewares are more likely to contain continuity ranges for best-sellers, rather than being one-offs, compared with clothing.
After the initial period, I assume that future royalties will be based on production/sales volumes, so it depends how the new products from NEXT resonate with their customers.
Regards, Paul.
Paul
Wasn’t actually referring to your comments but a previous discussion on here where it kept getting mr ruined
William Morris archive I believe is a much better long term proposition than it was a few years ago and I think the big players such as next know this too.
If I owned a company that owned an archive like that I’d be pretty happy to the point I would consider it a Buffet “most”
. And I guess shareholders actually do own that so it’s a very strong hold / buy with limited downside and a long term asset that I think is not fully appreciated .
I can remember times in the not distant past when patterned wallpaper wasn't popular at all. Classic though the Morris designs undoubtedly are, and of enduring quality and appeal, they do not have the same moat as say Hermes or Louis Vuitton, because the latter can evolve its designs over the years, while the Morris archive is frozen in time and subject to the whim of fashion trends.
Sanderson Design (LON:SDG) shareholders are one successful episode of "Changing Rooms" from ruin!
Okay, that's overstating it, but would you accept my note of caution?
My morning smallcap tweet: Applied Graphene Materials has slipped away
Powerhouse Energy (LON:PHE) Applied Graphene Materials (LON:AGM) Science in Sport (LON:SIS) Sanderson Design (LON:SDG) C4X Discovery Holdings (LON:C4XD) Kinovo (LON:KINO), Angling Direct (LON:ANG), Seeing Machines (LON:SEE), Transense Technologies (LON:TRT), Avingtrans (LON:AVG), Gooch & Housego (LON:GHH), Synectics (LON:SNX)
◄Powerhouse Energy (PHE)► Framework Services agreement by which Petrofac will provide engineering design and supply chain development services on PHE's pipeline of projects. [SP=1.1 Cap=44m]
◄Applied Graphene Materials (AGM)► proposes to sell biz for $1.3m and de-list. Strategic review showed business can no longer continue as an independent entity. Nowt left for shareholders. [SP=5.5 Cap=3m]
◄Science in Sport (SIS)► guides FY-Dec broadly in-line with expectations. Margins in line. Outlook in line. [SP=12.5 Cap=22m]
◄Sanderson Design (SDG)► 5 year licensing agreement for its Clarke & Clarke brand with Next. Licensed products will be sold from 2024. £2.6m will be booked this FY. [SP=122 Cap=87m]
◄C4X Discovery (C4XD)► Garvan Institute of Medical Research reports successful Parkinson's patient stratification approach using C4XD's new precision medicine platform PatientSeek. [SP=17 Cap=43m]
◄Kinovo (KINO)► £12m five year contract from Hyde for electrical testing and associated works. Also awarded first position on the Hyde Framework Agreement. [SP=37 Cap=23m]
In line: ANG, SEE, TRT, AVG, GHH, SNX