Small Cap Value Report (Weds 22 May 2024) - ZTF, NGHT, ZED, MAB, MAB1, VLE, POLX

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
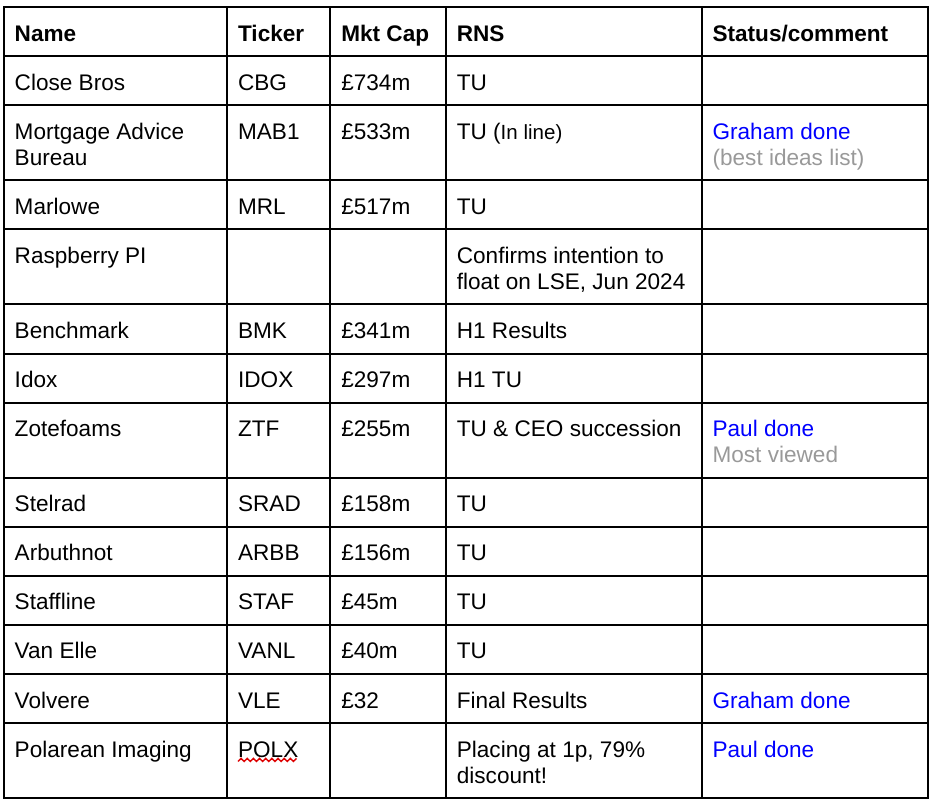
Companies Reporting Today
Other mid-morning movers (with news) -
Nightcap (LON:NGHT) - up 10% to 4.25p (£10m) - Fundraise for £3.5m at 5p/share - Paul - RED
Another fundraise (it raised £1m at 6p in Feb 2024) - presented as if it’s for expansion, but I think it’s more likely to keep the lights on. It admits there could be further fundraises. Highly ambitious management (who greedily draw excessive remuneration for themselves), talk as if they’re a sector consolidator, but a quick glance at their last accounts (Dec 2023) shows a loss-making ragtag of bars, with a weak balance sheet, negative NTAV of £(6)m, and net bank debt of £5.6m. So this latest £3.5m raise (if successful, only £750k is firm) would still leave it with net debt. There was a bad profit warning in Feb 2024 too.
Paul’s view - management strike me as greedy, and delusional. Rather than being a consolidator, I think this fundraise prevents them from joining the list of unremarkable bars groups going bust. It’s just a horrible sector, where very few operators make any money. Maybe they’ll pick up some of Revolution’s old loss-making sites at cheap rents and with long rent-frees?
Zenova (LON:ZED) (I hold) - up 22% to 2.2p (£3m) - Sells fire extinguishers to 2 hospitals - Paul - speculative nanocap
I can’t really give this a colour code, as it’s so small & speculative. Interesting products & newsflow, but as I mentioned here on 29/4/2024, I think it will need another fundraise. It’s one of an alarming number of low quality nanocaps that seem to have found their way into my personal portfolio. I’ve renamed the RNS title above to make it more accurate. The fire extinguishers have been extensively tested by the NHS it says, and Zenova is now an official supplier, and expects “significant sales to follow in the coming months”.
I see that the auditor was recently changed, suggesting they fell out with the old one I imagine, as it was well after the year-end, when companies don't usually change auditors. FY 11/2023 results don’t seem to have been published yet. Hence I imagine ZED shares are likely to be suspended by 31 May 2024 (next week!) since AIM companies have 6 months to publish accounts. So personally I’ve already assumed the brace position for a bumpy ride in the coming weeks. The RNS is full of exciting-sounding product news, but nothing of any substance in terms of the financial performance. H1 figures were lamentable, showing negligible revenues. What possessed me to buy some of these?!
Mitchells & Butlers (LON:MAB) - up 13% to 300p (£1.81bn) - Half Year Results - Paul - no colour.
Another mid-cap producing a superb recent rise in share price. Strong H1 results, and positive outlook - “Full year outturn expected to be at the top end of consensus, with momentum into FY 2025”. Large balance sheet, with £2.2bn NTAV (above market cap), with lots of property, plant & equipment at over £4bn, about 4x net borrowings (excl leases) of £1,037m. So needs a very careful look in particular at property valuations, and debt terms. I don’t have time to do that today, so won’t give a colour code. Looks potentially interesting though - although it’s almost tripled in share price from the Oct 2022 low, so I wonder if the gains have now been made?
PCI- PAL (LON:PCIP) - up 13% to 66.5p (£48m) - Victory for PCI-Pal in Court of Appeal - Paul - AMBER/GREEN
Good news today -
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, is pleased to announce that the Court of Appeal for England & Wales has ruled in its favour in the unfounded patent litigation case brought by its competitor Sycurio Limited. The Court of Appeal dismissed the appeal after just one day of the two day hearing, upholding the original ruling of the High Court announced by the Company on 25 September 2023.
Further good news, in that £1.1m held in escrow will be released to PCIP, as an interim award of costs. Could there be more to follow, I wonder? Ah yes, PCIP mentions that further on, saying more details about further costs it is seeking from the other side will be released shortly.
Paul’s view - clearly this is good news. I think there’s still a patent dispute in the USA yet to be decided though? I imagine a resounding success in the UK court might improve the odds of a similar victory in the USA, but who knows? Looking at the fundamentals for PCIP, it’s been a long and frustrating road for shareholders, with long periods of drift in between spikes up. Organic revenue growth has been superb in recent years, and multi-year losses are now finally set to turn into profits. However, the latest Cavendish forecasts only suggest barely above breakeven at adj PBT level for both FY 6/2024 and FY 6/2025, which does raise the question, what’s the point? All that hard slog, and multiple fundraises, just to get to breakeven. Hence I think the bull case only makes sense if investors think these forecasts can be significantly beaten, which might well be the case, I have no idea.
Just to emphasise, we only look at the facts, figures, and forecasts on the day here in the SCVR. It’s your job to do the fortune-telling about what the future holds! Also different investors buy/hold/sell with a whole range of strategies - a popular method is following the chart, which seems to be turning up at PCIP. Momentum can be very powerful in an early stage bull market, which I think we’re in. Also tech investors often value things differently, on sometimes aggressive multiples of revenue and EBITDA. Each to their own. Anyway, for me, I think the positives of patent risk receding, and strong organic growth, just about offset my scepticism about modest profitability. Let's hope we see upgrades in future. So I’ll stick with AMBER/GREEN for now.
Polarean Imaging (LON:POLX) - down 62% to 1.4p (£3m before, £17m after dilution) - Deeply discounted fundraise at 1p (£3m before dilution) - Paul - AMBER
We’ve been resolutely RED on this interesting, but under-funded company, all the way down, most recently on 7/9/2023, 7/12/2023, 29/2/204 and 10/5/2024, warning that dilution was obviously coming and that it could be on potentially ruinous terms for existing shareholders. That’s exactly what has happened, with a 1p raise today increasing the share count from 216m to 1,207m if full uptake of the £2m open offer (9 new shares for every 10 existing) . It reminds me a bit of Surface Transforms (LON:SCE) - promising sounding tech, but constantly running out of cash. It just isn’t worth the risk holding shares in anything speculative, unless the cash runway is c.2 years+ in my opinion. Although no two situations are exactly the same. Key question now, is it worth backing now at just over 1p? Maybe, but I would remind you that previously POLX said it needed to raise $10m, which is has done today. But that a further $20-25m would be required in due course.
Paul’s view - now that the cash runway is extended, I’ll temporarily go up to AMBER for a few months probably, and we’ll see what if any commercial progress it makes, before probably going back down to red when it’s close to running out of cash again next time. We are coming into a new bull market though, hence why there might be speculative upside here for a punt? Personally I wouldn’t pay 1.4p though, as I decline to hand a 40% profit on a plate to holders of about 83% of the new total number of shares bought at only 1.0p.
Summaries of Main Sections
Zotefoams (LON:ZTF) (I hold) - up 1% to 524p (£256m) - Trading Update & CEO Succession - Paul - GREEN
Revenue growth in Jan-Apr 2024 is up 14%, ahead of +11% in the forecast. It reiterates trading in line with full year expectations, so I suspect they might be in a comfortable position, maybe a bit ahead of expectations? The tone about its ReZorce development project has been noticeable more positive lately, including a recent press launch, so I suspect the odds are moving in our favour for a good outcome there, but that's just guesswork mainly. Not cheap, and it is capital-intensive, but I remain positive on Zotefoams shares, and hold personally. EDIT: my notes from InvestorMeetCompany webinar added below.
Mortgage Advice Bureau (Holdings) (LON:MAB1) - down 4% to 893p (£510m) - AGM Statement - Graham - AMBER/GREEN
A good update from MAB; the market may have gotten ahead of itself. SP is still 15% higher vs. when I covered the full-year results. Some growth is expected later this year, then normal growth from next year. I moderate my view to AMBER/GREEN to reflect the high valuation now attached to these shares.
Volvere (LON:VLE) - up 5% to £14.11 (£32m) - Final Results - Graham - GREEN
Good results showing continued progress at Shire Foods. The Chairman includes in his remarks an acknowledgement that the Volvere share price is not matching up with the company’s asset values; the directors are considering how to “unlock” this value. I am happy to hold and look forward to their ideas.
Paul’s Section:
Zotefoams (LON:ZTF) (I hold)
Up 1% to 524p (£256m) - Trading Update & CEO Succession - Paul - GREEN
22 May 2024 - Zotefoams, a world leader in cellular materials technology, provides a positive trading update for the four months ended 30 April 2024 (the "period"), ahead of its Annual General Meeting to be held today.
Revenue growth looks good so far in FY 12/2024 -
“Trading in the period has been strong, with the Group sustaining the positive momentum seen in FY23 to deliver overall sales growth of 14% and record revenue…”
That’s ahead of the +11% revenue growth in Singers 2024 forecast.
Overall trading is in line with expectations -
“Performance in the first four months of the year has been strong and provides a solid platform from which to deliver further financial and strategic progress in 2024. While being mindful of remaining macroeconomic volatility, the Board's full year expectations remain unchanged, and it is confident about the long-term prospects of the business.”
Helpful footnote, all companies need to include this in trading updates please -
“Note. The Board understands that current market expectations for the year ended 31 December 2024, prior to release of this trading statement, are revenue of £138.5m and adjusted profit before tax of £14.9m.”
ReZorce - there was an upbeat update on this fully recyclable drinks carton development project recently, here on 15 May 2024. There was also a very helpful note from Singers (many thanks) on 16 May 2024, available on Research Tree, which gives more colour on the opportunity with ReZorce. I don’t know any more than anyone else, but it seems to me subjectively that the messaging on ReZorce has become noticeably more enthusiastic, and by doing a press launch on it, I’m taking from that ZTF must be confident the product works, and can be launched. Although that’s still subject to quality & performance testing in bigger trial batches. Note that ZTF is talking about getting external investment in to scale up ReZorce, so my main worry is they don’t give away too much of the upside to partners. Let’s have a placing here, and fund it ourselves, would be my preference. Investors are usually happy to put up fresh cash in a placing if it’s for a viable expansion, not to prop up a failing business model (where valuations are brutal, as seen again today with the disaster Polarean Imaging (LON:POLX) )
Shincell - a partnership was announced previously, but I don’t understand the implications of this, so welcome receiving a more detailed update on what this entails with the August publication of H1 results. Sounds like ZTF might be licensing some new technology or products?
CEO succession - all planned, so nothing to worry about, as very long-serving CEO David Stirling retires. New CEO Designate is Ronan Cox.
Outlook - with the first 4 months ahead of forecast (for revenue) and a fairly upbeat commentary below, it feels to me as if the risk of a profit warning should be quite low here -
Performance in the first four months of the year has been strong and provides a solid platform from which to deliver further financial and strategic progress in 2024. While being mindful of remaining macroeconomic volatility, the Board's full year expectations remain unchanged, and it is confident about the long-term prospects of the business.
Paul’s opinion - as regulars will know, I’ve been keen on this share for some time. My rationale has been that the core business is decent, riding out both the pandemic and energy crisis with aplomb. The various products & divisions seem to balance each other nicely, with any downturn in one area being offset by growth elsewhere, which is again demonstrated in the detail of today’s update.
Critics point out that the business is quite capital-intensive, which is true. However it generates a decent enough ROCE of 12.2%, and note it owns the freeholds on properties which I like, even though it might suppress ROCE a bit compared with leasing properties (depending on the lease terms).
Singers has 22.3p pencilled in for FY 12/2024, so a far from cheap PER of 23.5x. However, FY 12/2025 sees a big forecast rise to 30.8p, which if achieved would make anything under 600p/share look a fair price, in my view. I’m not sure if Singers have factored in an income for ReZorce in future, or not. If anyone knows, please could you post a comment below.
ReZorce sounds as if it’s increasingly credible, and the potential could be enormous longer-term. Although I imagine ZTF would become a bid target if it takes off, and there are not any blocking founder/management stakes unfortunately, just a bunch of fund managers who would probably grab the money if someone offers a big enough premium in a takeover bid.
Overall then, despite the big recent rise, I still find the opportunity here fairly compelling - a good core business, and potentially big upside from a late-stage development project. So I’ll remain at GREEN. For full disclosure, I am required to disclose that I hold personally. ZTF is also on my top 20 share ideas for 2024, (now up 25.7% YTD, with Graham remaining stubbornly ahead of me at +28.6% YTD!) so it’s good to see ZTF developing nicely.
Hopefully we might get some guidance about the potential financial benefits from ReZorce with the next set of results? We’re in the dark so far, just guessing - so a rising share price needs more certainty of at least the range of possible outcomes. I hate relying on the “this could be huge!” type of comments, as that can allow expectations to get well ahead of likely reality, but we don’t know at this stage.
EDIT: I listened in to the IMC webinar today from ZTF, and enjoyed it. The new CEO Ronan Cox led it. LinkedIn says he spent most of his career at Coats (LON:COA rising to President of Performance Materials, which sounds like relevant experience for ZTF. Also present on the call was the CFO, and the outgoing CEO David Stirling. There was a pleasing dynamic between them all I thought, and Stirling is staying on until Oct 2024 to gradually handover the reins on key growth areas of Shincell, and ReZorce.
Shincell - paying this Chinese company £9m over 5 years, in order to use (licence?) its tech for use in new products & markets. Some exclusivityin "strategic markets". "Greatly accelerates innovation" in mixed gas technology that ZTF has been working on.
ReZorce - "very exciting project" for 100% recyclable drinks cartons. "Large response" from the industry, despite no marketing done yet. "Huge market", "massive opportunity" (CFO). Tailwinds coming from legislation for drinks companies to improve recyclability of packagaing. Strong IP. Seeking investment partners, as ZTF is not a packaging company, and needs "considerable funding" and expertise from a large industry partner. ReZorce is "World's first, and only fully recyclable drinks carton". Can be scaled up "pretty quickly". Going through testing for sterility. Don't anticipate any problems with testing.
End of Edit.
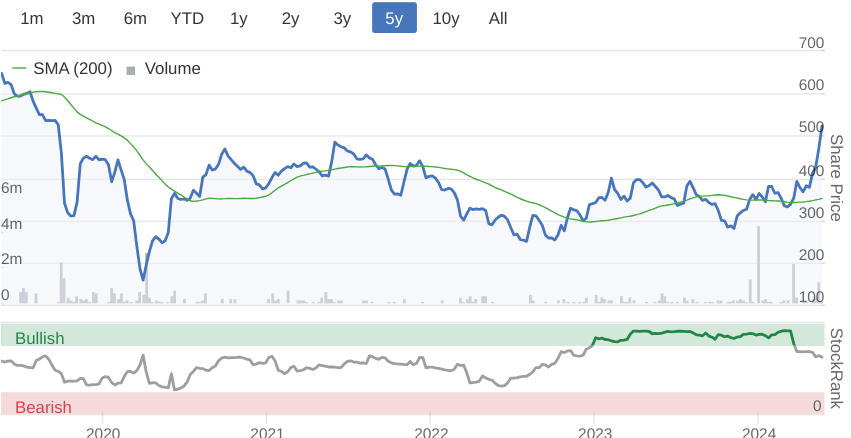
Very strong recent move might attract some profit-takers perhaps?
Graham’s Section:
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Down 4% to 893p (£510m) - AGM Statement - Graham - GREEN
This AGM statement is in line with expectations.
Key points in relation to the wider market:
Completions: there has been a 13% reduction in new mortgage lending for Q1 2024, due to a low pipeline being carried into the year.
All purchase-related activity has picked up
Remortgaging is slightly down
As for MAB itself, they have “performed well in these conditions”, growing market share. Their own mortgage completions in Q1 were £5.7 billion, only slightly down on Q1 last year (£5.8 billion) (this figure includes both new mortgages and product transfers).
Adviser numbers: a slight fall in the number of advisers to 2,110. I was hoping to see a slight increase here, but on checking my notes from the recent full-year results, the company did warn that “we do not see normal growth in organic adviser numbers resuming until 2025”.
Here is the latest update on the growth outlook:
The momentum in our new Appointed Representative ("AR") recruitment activity continues to be strong, and consequently we expect a high number of new firms and advisers to join MAB over the next few months. Our pipeline of incoming new ARs has also continued to grow strongly over the last few months…
"We expect our existing AR firms to start growing their adviser numbers again later in the year, most likely as consumer confidence improves when there is more certainty around the outlook for mortgage interest rates and our firms can plan with a greater degree of certainty.
(GN Note: “Appointed Representatives” are the mortgage intermediary firms in the MAB network.)
So a little more patience is needed before adviser numbers start to grow again.
CEO comment:
Our performance once again demonstrates MAB's ability to continue winning market share in all market conditions.
Boardroom changes: the company has a new Chair and new CFO. But importantly the founder-CEO (who is also a major shareholder) remains in place.
Graham’s view
I don’t see any reason to change my view on this: a high-quality franchise-based business that performed well even in the very difficult housing market conditions seen in 2023.
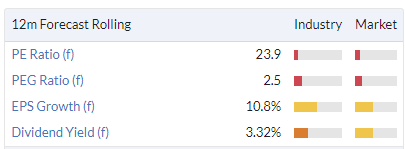
Admittedly, the shares have had a great run up and they do price in an improvement in the company’s performance in the years ahead:
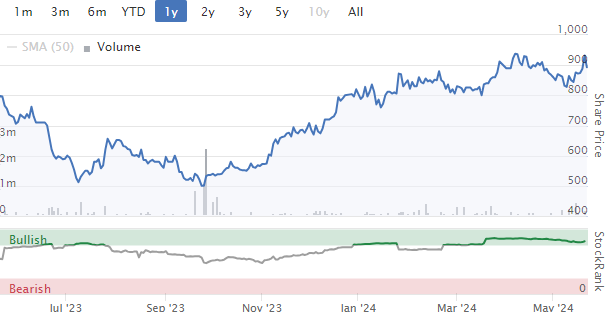
Compared to when I covered MAB in March, the shares are up by a further 15% since then.
That’s the context for today’s slight drop in the share price:
Having checked the best ideas spreadsheet that is shared by myself and Paul, I see that MAB shares are up 9% year-to-date, after having gained a mighty 60% last year.
With “normal” organic growth still not expected until next year, I’m therefore going to moderate my view on MAB to AMBER/GREEN. To be clear: I still rate it very, very highly as a high-quality long-term investment. And I’m glad I put it on my best ideas list for this year. But perhaps the company does need to grow into this valuation now, before any further share price gains will be justified.
Personally, I am optimistic when it comes to the potential for a strong recovery in the mortgage market, but of course nobody can be sure about these things.
Volvere (LON:VLE)
Up 5% to £14.11 (£32m) - Final Results - Graham - GREEN
(At the time of writing, Graham has a long position in this share.)
Even though this is a big holding for me personally, I tend not to cover it too often in the SCVR, as it’s rather illiquid and something of a niche interest.
It’s a turnaround investment vehicle founded by the late Jonathan Lander and his brother Nick Lander.
It came as a great shock when Jonathan Lander passed away in August 2023.
Nick Lander is now running things.
Today we have results to December 2023. I’ll break it down into the key points of interest.
Shire Foods: this is Volvere’s only operating subsidiary. It manufactures pies and pastries for a variety of customers but the headline customers would be supermarkets such as Iceland.
Up until the death of the former CEO, a key talking point was the lack of M&A activity which left Volvere only holding a single business. But more on that later.
Shire Foods has been a successful investment for Volvere. They initially invested £500k back in 2011, to buy 54% of the equity. They also provided working capital.
Today they own 80% of the business. Shire’s 2023 results are as follows:
Revenues £43m (2022: £38m)
Profit before Volvere’s charges (interest and management fees): £3.9m (2022: £2.8m)
PBT: £3.5m (2022: £2.4m).
The way I look at it, Volvere’s stake in Shire Foods should be valued based on 80% (reflecting Volvere’s ownership stake) of the profit before Volvere’s charges.
So for 2023, I would use an earnings multiple of £3.9m * 80% = £3.1m.
Let’s apply 25% corporate tax on that for after-tax net income of £2.3m.
A buyer of Shire might also need to inject some cash into the business but I don’t think the amounts involved would be very large. It should also be pointed out that Shire owns a freehold property (valued at £3.75m in 2021) along with substantial plant and machinery assets.
If a small but successful food manufacturing business, that owned its own properties, could fetch an earnings multiple of ten times trailing after-tax net income, Shire might be worth c. £23m.
Of course I’d be delighted if it could achieve a higher value than that - its growth over the past five years has been superb and perhaps a buyer might give credit for that. Although there has been no indication from Volvere up to this point that they have any interest in selling Shire.
I should add a risk warning that Shire’s revenues are highly concentrated in its top customers. One customer is responsible for nearly half of revenues, and the top four customers generate over 90% of its revenues.
Some commentary on the performance and the outlook at Shire:
In recent months we have found the recruitment market easing somewhat and have been able to recruit for additional shift requirements that are needed to support growth, particularly for the second half of the year when our volumes are traditionally higher. Labour and energy costs are expected to increase this year and, whilst we will endeavour to recover these through increased gross margins, there is no certainty that these will be mitigated in full. Increases in raw materials' costs have, however, largely stabilised and this is expected to remain the norm in 2024.
Overall not a bad outlook - I would hope for another solid performance from Shire this year.
Indulgence Patisserie: no point dwelling on this for too long. It was an acquisition that didn’t work out, and it has been shut down. However, I note that Volvere sold Indulgence’s properties for £2.25m (purchased in 2020 for £0.95m).
Investments and central costs: Shire’s central functions generate investment returns on the group’s liquid financial assets, but also have to pay the Directors.
This year, investment returns improved from £0.7m to £0.8m.
The amount paid by Volvere to the company owned by the Lander brothers reduced from £650k to £549k, and I expect this number to reduce further.
The balance sheet now has cash and available-for-sale (liquid) investments of £23.7m (2022: £20.8m).
Total balance sheet equity for Volvere shareholders is £34.5m.
Future plans?
The big question since last year has been the direction that Nick and the other directors wish to take the company in now. Will they carry on the mission of investing in turnaround companies, and start investing Volvere’s cash, or is now a good time to think about winding up?
Here are most of the top shareholders who might want to have some influence on the decision:
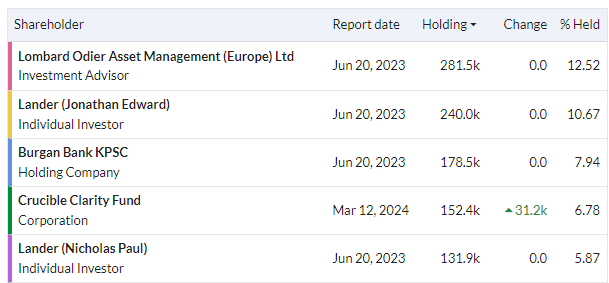
The Chairman has this to say today:
The Board is conscious of the Group's share price, which it does not believe reflects the underlying value of the Group's assets. These are principally cash, liquid investments and the investment in Shire Foods. We are considering a number of ways through which to unlock this value for shareholders and will update investors on these developments at the appropriate time.
Graham’s view
Firstly, in terms of current value, I believe that Volvere is likely to be worth in the region of £47m (80% of Shire valued at ten times trailing earnings, plus cash and liquid investments). Let’s call it £46m, as there are borrowings of £1m associated with Shire. This equates to a share price of about £20.50.
How to achieve this? My own vote would be that Volvere should now look for ways to wind up in an orderly manner. I would return most of the cash currently on the balance sheet to shareholders and I would sell Shire: not in a hurry, but I would start to look for a suitable buyer who is willing to pay a fair price for it.
If none of this happens, then I am not in any huge rush to sell my Volvere shares, but I’m also unlikely to hold them forever.
At the end of the day, the company does need to make a decision - to either put its cash to productive use and invest it, or to return it to shareholders.
Investing will be the more demanding option, and will necessitate a fresh appraisal of their investment strategy.
If they do choose to call it a day, they can do so with their heads held high, having achieved terrific returns for their shareholders over many years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

105 comments
Volvere (LON:VLE)
Hi Graham, would there be any material capital gains tax implications if they decided to wind up the business by liquidating the land and operational assets?
Volvere (LON:VLE)
i would guess capital gains is what it is - if sub trading business is sold thats likely to generate tax similar to corporation tax on the profit they have made on this investment - that being then case its just like most years - if company reports profit then we should expect corp tax on that profit as normal. One might be able to work out base cost here so not all proceeds may be profit.
similar with property copmpany would pay tax on gain made - they may have soem indexation alowance if that property has ben held for many years
Other than that its likely that shareholders would pay tax they owe on their gain - it is sometimes done as choice of capital or income. so if they closed and did return of capiatl to shareholders it might be does as capital item or dividend payout or mix of both or choice of one or the other
my comments are billy basic and may be missing something
Not smallcap but maybe interesting.Hargreaves Lansdown (LON:HL.) Telegraph article.
Hargreaves Lansdown has rejected a shock £4.6bn takeover raid from a consortium led by Abu Dhabi’s wealth fund and the private equity giant CVC Capital.Hargreaves’ board rejected a 985p per share bid on April 26, according to the consortium. The group said it was considering another approach for the company and has until June 19 to make a firm bid or walk away.
Statement regarding Hargreaves Lansdown - 18:06:13 22 May 2024 - News article | London Stock Exchange
Hargreaves Lansdown (LON:HL.) is still the 6th most short UK equity too according to shorttracker.co.uk.They're not just coming for our companies, but for our investors too!
is there a page which highlights those stocks which pass the most long screens?
This should give you that: https://www.stockopedia.com/sc...
You need to add 1 on as it does not count itself.
thanks rusty
Larry The Cat:
Lots of people asking me where I was when Sunak announced the election. I was inside, because it was raining. Only an idiot would have gone out in that...
Been a while since I posted a chart. There is that old adage saying "Sell in May and go away".
Make of this what you will, This is the FTSE weekly chart. The trend lines I plotted I did months ago.
Hello gmtrader. Since you have gone to all the trouble of putting this together, I'm confident a lot of us would be interested to know what your conclusions are, and then we can add our 'make of it what we will' on top of that to give a nice rounded discussion and some useful, well thought out comclusions! Thanks.
Well I’ll have to keep it brief as I’m now at work.
May is traditional time for a weaker market as many in the industry go on holiday. The ftse is clearly in an uptrend longer term, but it never goes straight up. So following the chart trend channel it is likely to reverse lower. Whether this is the start or not who really knows. It could quite easily follower the top trend line for weeks.
personally most of my stocks are longer term holds and so I’m happy to hold through any down turns but if I was holder shorter term stocks I would be hesitant to hold with the ftse so high. Also US charts having being hitting all time highs. It’s going to be very turmoil imo with elections here and the US.
For the record I do hold a couple of small ftse shorts.
Haven't tested the ol Bollinger Bands for some time. Into Ichimoku and as give more information and MACD as sense check, but like most of these indicators by the time it flags buy its too late. So you have to take fundamentals and sentiment as well as the chart and take a punt.
Not looked at the FTSE but on the weekly stocko FTSE 100 Index (FTSE:UKX) 8000 is clear resistance now broken, but is it support. Certainly a stop position +5%.
With a new election in play then risk is high and this market is overbought (sorry its tea leaves not facts).
The FTSE is perhaps not so relevant as holds lots of internationals so tend not to bother looking at it.
Have put Mr Bollanger into the mix for fun
We are in high momentum territory for sure. And sorry but "spidey senses" says we are going closer to 8000 than 8500 (the next resistance ceiling).
The problem is it's all USofA we are a minnow in the big fishpool. Forget the macro and focus on our stuff that does good stuff and then gets captured by the bigger fish. Sorry wine kicking in. Time to stop typing at 19:48.
A caveat to my post is that if you followed me you would be poorer. But I'm getting better.
Hi, I mentioned Close Brothers (LON:CBG) when it tumbled below £4/sh (putting it into small cap territory!), having lost half its mkt cap mostly on the back of the FCA investigation into Motor Finance. Since then there has been a moderate rebound, with the stock over £5 recently. Today's Trading Update seemed to frame the reparations to single figure millions, with more initiatives to take care of Process in future. Given the FCA has stood back to allow CBG to deal with customers, before concluding the review (and determining any fine/penalties), and given the apparent limited extent of the problem, it does appear the £42m loss in market cap today, on top of £600m loss previously, might be an over reaction? Did I miss something, the rest of the update looks innocuous (apart from little colour on outlook)?
Close Brothers (LON:CBG) (I hold). Actually the 'single figure millions' only refers only to The Borrowers in Financial Difficulty (BiFD) review that the FCA is conducting. This is in addition to the separate review of historical motor finance commission arrangement by the FCA.
So the total in compensation to be paid by Close Brothers (LON:CBG) is likely to be more, probably a lot more, than single figure millions.
I do agree though that the previous £600m fall in CBG's market cap was overdone.
Close Brothers (LON:CBG)
i briefly read todays update and came to the conclusion they said didly squat about the fca review of review of "historical motor finance commission arrangements."
they did mention the fca looking into "Borrowers in Financial Difficulty ("BiFD")," and mentioned single digit million hit only ref that issue.
i presumed that these were two completely different items ?
can you advise if my presumption is wrong ?
i think one of us has completely miss-intepreted what teh company is saying today ref review of "historical motor finance commission arrangements."
note they did have some comment ref "historical motor finance commission arrangements."
which was
The group expects to incur a higher level of group (central functions) net expenses for the remainder of the 2024 financial year, primarily reflecting an increase in professional fees and expenses associated with the FCA's review of historical motor finance commission arrangements.
The Board remains confident that the identified actions will position the group well to withstand a range of scenarios and potential outcomes of the FCA's review of historical motor finance commission arrangements.
this last two parahraphs made my presume these are completely different items and that the elephant sized one is very much unresolved with zero useful comment today !
i could easily have gotten this wrong i must admit !
Quilter (LON:QLT ) is a UK wealth management company offering investment and financial advisory services. It operates in two segments: Affluent, which includes Quilter Investment Platform, Quilter Investors, and Quilter Financial Planning; and High Net Worth, which includes Quilter Cheviot for discretionary investment management, and Quilter Private Client Advisers for financial advice. Trading at 114p today.
Paul did a cursory review on 6 Mar 2024 and classified it as AMBER: “A quick review of its results below, showing a nice rise in profits, an OK outlook for 2024. However, it also mentions a review of historical advice, which is the issue that clobbered STJ shares recently. That uncertainty puts me off wanting to delve any deeper here. Nice 4.9% yield though, and AuM are rising.”
Quilter also qualifies for Value Momentum Screen (Momentum Investing). A recent chart signal suggests an uptrend with a short term target of 130-135p
I have bought some today!
For some years now Volvere (LON:VLE) has been treated with remarkable respect for the Landers supposed quality management and turnaround expertise. I have never understood where this came from, obviously if you have £20mm of cash in a £30mm market cap the company is safe and should be able to expand. But after more than five years they only have a marginally profitable bakery and despite £20mm in cash apparently no ability to spot a business with potential but lower than realistic price and a need for funding (ie almost any number of AIM companies). They may have not just missed the bus but a whole fleet of buses. Graham now seems to have at least partially converted to the view that Volvere’s inability to make a worthwhile return on either the cash or the bakery, demands a major review of where they are going.
I imagine it is because - prior to Indulgence - they had never done a losing deal and have a remarkable underlying track record.
e.g.
Vectra was bought in 2003 for £2m and sold in 2007 for £8m (inc retained cash)
Sira was bought for £1.4m in 2005 and sold for ~£10m in 2009
Impetus was bought for £1.3m in 2015 and sold for £28.3m in 2018
and the 'marginally profitable bakery' Shire Foods was bought in 2011 for £0.5m and is now worth north of £20m, making 8x their original investment every year in profits
They used those proceeds to consistently distribute to shareholders. 14% CAGR since IPO ain't bad considering they have basically always had net cash - and it'd be better than that if the business traded at less of a miserly valuation today.
So - returns in the top decile of listed companies, by a management team with skin the game using an exceptionally conservative balance sheet.
... and all of that is despite the entirely fair point you make around their lack of deployment in the last 5 years. There is a continuum in life between aggressiveness and conservatism and I think there is a healthy debate to be had around whether they have erred too far on the conservative side. Personally I prefer having this debate rather than the far more common debate about listed directors who have splurged money up the wall on deals which have destroyed a huge amount of value.
(for the avoidance of doubt I own lots so am biased)
Thanks Aislabie,
I always enjoy a well-argued contrarian view, and must admit you've said things that were also vaguely in the back of my mind, although Graham knows way more than me about Volvere (LON:VLE) .
Regards, Paul.
Mpac Group (LON:MPAC) good to see many followers posting here already - very encouraging news that first production trial of 24M Technologies SemiSolidTM unit cells has been completed in Norway. Supports optimism in our recent detailed research note: https://www.equitydevelopment....
Zotefoams (LON:ZTF) investor meet today. As always really impressed by management, the new CEO spoke with conviction and clearly has high aspirations for the Rezorce project. I asked about the potential for a shareholder placing to fund the Rezorce project as they have stated they need investment partners. Response was essentially that the potential market is so large in comparison to the size of Zotefoams (LON:ZTF) that wouldn't be a viable option. Significant financial contribution from an investment partner will be required to meet the potential high demand if the product goes to market. A lot of companies interested in the product should it be successful. They also reiterated the importance of protecting the IP and repeatedly clarified that the recent Shincell agreement was one way. Another interesting feature was the added potential of the packaging being microwaveable. Adds potential use for soups for example. Certainly recommend anyone interested in investing in Zotefoams (LON:ZTF) gives it a watch.
Missing Paul Scott
Paul, we are so not to see you at the Mello today.
Hope life is too good at Cozo!
I'm sorry about that Yadi. I've had a lingering chest infection for a fortnight, and the warm weather in Gozo is helping me gradually shake it off, but still have a newly acquired "smoker's cough" hack. So I decided to stay put until I'm better. Send my love to everyone at Mello, with apologies for my no-show this year.
P.S. Dave reminded me that my BASH pick last year was Zotefoams (LON:ZTF) so nice to see that's done well!
Zotefoams (LON:ZTF) I would be interested to hear anyone else's takeaways from this morning Zotefoams presentation.
Mine are that the Rezorce carton packaging opportunity is extremely interesting but somewhat unquantifiable at present. I am also sorry to see David Stirling is departing, I liked his no nonsense approach, but at least he is staying until the end of October and I was pleased to sense a good chemistry beteween him and new CEO Ronan Cox, who comes with a decent CV.
Group CEO succession - Zotefoams
MPAC (LON:MPAC)
Oh wow - they’ve only gone and done it !!!
First trial battery unit rolling off the production line with Freyr - that’s a major milestone
Check out recent video presentations from CEO Adam Holland on this - their technology is actually building the battery (not just packing it once complete like most packaging type lines). That opens up a whole additional world of opportunities for complex engineering for automated production and packaging.
It’s only been out as an RNS reach but in my opinion this is much more than that suggests.
MPAC (LON:MPAC) This is my biggest position and I don't know how to quantify this announcement in money terms but none of this is factored into the forecasts, the TAM is enormous and the mkt cap is only £100m which is completely covered by the existing revenues. I think I just talked myself into buying a few more.....
MPAC (LON:MPAC) is becoming one of my largest positions too and I have always discounted the battery assembly business potential to zero. It makes up none of my valuation estimate and from what I can see makes up none of the brokers estimates of 550-600p valuation.
I see this announcement in a similar light to the Zotefoams (LON:ZTF) announcements on their new packaging. There is a real propensity for MPAC (LON:MPAC) to be THE global leader in this space now. As Adam Holland says it is really really hard to do this so assuming MPAC (LON:MPAC) have the patents I would expect on their tech engineering they should be able to build a moat.
I can’t measure the potential but am very happy at a PER of 12 with year end net cash for an engineering business in a growth market with such upside. Zotefoams (LON:ZTF) trades on 23* PER. So I see loads of scope for a re-rating anyway even before the battery assembly potential.
Hello davidjhill, re MPAC (LON:MPAC) you make a comment 'assuming MPAC (LON:MPAC) (LON:MPAC) have the patents' do you have any foundation for suggesting they do? I don't know, and don't know anything at all about the share of the relationship between the 4 component companies involved in today's announcement. Any further information would be gratefully received. It clearly matters as far as the future valuation of MPAC (LON:MPAC) is concerned Thanks a lot.
Thanks for the swift post David! I had been planning on getting some MPAC (LON:MPAC) shares for a while and was hoping we might hear more on Freyr. I wasn't subscribed to RNS for MPAC but on reading your post I got my rapid speed fingers out and managed get on the IG app and jump in before the bump. These additional in the moment contributions to the SCVR are so beneficial to individual investors. I can't monitor every RNS but I can keep an eye on the SCVR regularly throughout most days. Cheers.
Nexxen International (LON:NEXN)
Maybe I am becoming desperate and can't find anything to buy given the recent jump in prices but I've been looking at Nexxen and can't escape how compelling these forecasts are for 2025:
Mkt cap £340m
Net cash £150m
Free cash flow £51m
Now I know the old Tremor business has had a chequered past but an EV/FCF ratio of 3.7x combined with an aggressive share buy back programme and a decent looking chart that's tempting isn't it?
I don't know, if there are any holders out there who know the back story and understand the business (I don't but I think advertising is past the trough point of the cycle) then please feel free to throw some colour on this but I think this looks like a good risk/reward trade at first glance.
Thanks
I hold Nexxen International (LON:NEXN) - probably shouldn’t have held through the cycle but there you go. I see plenty of upside from here.
Paul says too many red flags for him to look at but I’m not really sure what these are. Mgmt originally had $100m of debt whilst holding a lot of net cash and this was questioned. It was for acquisitions but clearly no more have materialised so they have paid this off and retain $150m of net cash. That seems sensible.
Then people questioned whether the cash was real - it clearly is. They have bought back a lot of shares and paid the debt off so clearly no problem there. If the cash generation is real then this share should trade at a multiple of todays price imo.
The business has remained cash flow positive throughout what has been a nasty downturn. That gives me confidence that they can survive the natural cyclical effect of the advertising industry and are now large enough to survive. The fact that this has now turned and mgmt are sending positive signals and more importantly meeting quarterly forecasts (as they were guilty of consistently missing them over the last couple of years) means it could be a good time - almost Bowly as cockney rebel would say.
BUT - management pay has been excessive in the past and the share buy backs have not resulted in cancelled shares but treasury shares. I don’t like that - it suggests management are greedy. Yes, there are less shares but it doesn’t mean those couldn’t be reissued.
Anyway - my suspicion is that this has a good way to run if economic conditions remain robust so I remain long but let’s see.
Nexxen International (LON:NEXN) it suggests management are greedy
Understatement of the week and it’s only Wednesday, David. I can see the opportunity for an easy buck here for myself. But I’m simply too stubborn to get into bed with Drucker.
Nexxen International (LON:NEXN)
I did warn about this many times.
Defined not a holder and I will advise all holders to have an extensive research into the management of this company and their past track record.
All the best
Couldn't agree more!
Seen an interesting article which mentions overall in the uk net bank deposits exceed mortgage liabilities . Increasing interest rates has actually increased disposable cash rather than the opposite effect which you would expect stimulating the economy
worth notice only about a third of the 29m households currently have a mortgage
Pretty sure it was this Woodford article
https://www.woodfordviews.com/...
correct wasnt sure if we were allowed to post a link to it
"correct wasnt sure if we were allowed to post a link to it"
Hi investwise, of course you can post a link to anything that is interesting to other investors as far as I'm concerned (but I don't control the moderation - which went haywire briefly, but now seems fine).
The preconditions for interest rate cuts have been met. The prevarication may continue. Whether it's June 20 or August 1 for the first cut, or even dragged out to September, the direction of travel seems clear. I'd expect 2 or 3 cuts by end of year possibly with ECB leading the way. US might hold off as their economy is flying.
Time to position accordingly?
Is that why Marston's (LON:MARS) is finally flying with all their debt?The share is still on a tear even today after yonks drifting at all time lows.
No idea Strawbs. Not following the pub sector other than for the entertainment of reading Tim Martin's pronouncements in his half and full year reports. Presumably someone sees it as good value. Good luck if you hold.
Marston's (LON:MARS)
Is that why Marston's (LON:MARS) is finally flying with all their debt?
Its a pretty logical conclusion here that this would help - debt is the elephant in the room - imho however "fixed" most of their borrowing may be clearly lower interest rates will aid the company as and when refinancing is needed.
perhaps the results last week satisfied the market (they werent great but perhaps good en ough)
imho marstons is so loaded with debt its almost bordering on a binary bet - the main potential issue if that as the price goes lower the higher the potential dilution if they need to raise funds - if the share goes too low then practicably speaking shareholders could be close to being wiped out if dilution would be silly high %
note the share is very bombed out so perhaps the truth is it undershot on the low side and is on its way back. Anyway investing here should be prepared to lose the lot imho.
Note as alot of their debt is on fixed rates they may not benefit as much as one might presume short term with rate reductions.
final one of note - could someone be sniffing around this company as takeover prospect?
with this share one should expect large swings as its possible to probably argue shares may be next worth to nowt or may be worth £1 a pop if they can pay down debt and or realise value by selling some excess proporety at book value .
This mornings disruption to the readability of the comments section was down to a post which included a very long line of text copied and pasted . The quickest way to sort the problem if it happens again is to use the green button to send a message to Admin and flag the message as "disruptive" even though it was accidental. Be aware that some places where you might copy a post use automatic wrap around rather than fixed length lines using "return" so a copied text will appear as one line that you should edit to fit.
Benchmark Holdings (LON:BMK), the aquaculture biotechnology business, will be hosting an investor presentation TODAY at 12.30pm following publication this morning of their Q2 and Interim results for the three and six month periods ended 31 March 2024.
The online event will be hosted by Trond Williksen, CEO, and Septima Maguire, CFO - the webinar is open to all existing and potential shareholders. Questions can be submitted during the presentation to be addressed at the end. Sign up here: https://www.equitydevelopment....
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Update should provide a good read across to Property Franchise (LON:TPFG) that has a significant position in mortgage finance since the merger with Belvoir. I hold and have recently added.
Hi Paul Zotefoams (LON:ZTF) I hold. According to the Singer note from 16th May they are only allocating 25p for the vale of ReZource for their target price of 500p. Today they have upgraded their target price to 605p. With a blue sky fair value of over 900p. There is a presentation on IMC at 11.30 today
Hi Verbier93,
That's great thanks for the additional info on Zotefoams (LON:ZTF) [I hold].
I might down tools at 11:30 then, to watch the IMC webinar.
Regards, Paul.
Warpaint London (LON:W7L) Manchester United FC (MANU), which initially listed on the London Stock Exchange, then traded on the OTCQX, and eventually did a US listing on the NYSE in 2012. Other companies which are listed on the OTCQX are: Roche Holdings Ltd, Tencent Holdings Ltd, Nestlé S.A., LVMH Moët Hennessy Louis Vuitton SE, Adidas AG, Softbank Group Corp.
I'm a keen fan of Raspberry Pi, and its founder Eben Upton. It's an example of great British innovation, and proof that Britain can do good things if it tries. I suspect its valuation will be lofty. I'm glad they decided to float on the UK market. It must have been tempting to list on the US, where tech is all the rage.
The big worry is that tech is soon to be coming off the boil, of course. There is more credible competition these days in the market-place for their products. Despite all logic, I'm tempted to have a daft wee laddie punt on it. The trick is to keep the punt small. You don't want to be betting the farm on it. I view it as an option on Upton continually being able to innovate.
Can retail participate in the Raspberry Pi float?
Did you know that RPi are manufactured by Sony in Wales? Jeff Geerling a Youtuber was given a tour https://www.youtube.com/watch?... of the factory.
Thanks. I'll check it out. I was aware that they were manufactured in Wales, but not by Sony. I seem to recall that this turned out to be a strategic advantage at some time, although I think it was more to do with Upton wanting to keep everything as British as possible.
Upton has come in for some criticism, for example throttling back on hobbyist supplies during inventory shortage in order to serve small businesses, allowing them to stay afloat. For my part, I consider his actions reasonable.
Although he hasn't come out and said it explicitly, I do get the feeling that Upton wants to make it a great British success story, and "do the right thing". And heaven knows, we could use one.
Large-cap electrical components retailer RS (LON:RS1) reported their finals today, sending the shares down 11% in early trading. Revenues fell 1.3%, gross profit by 6.6%, operating profit by 26.9%, and Net profit by 35.6%. So, it's not surprising that the market reacted badly to the news.
The RNS provides some commentary:
"2023/24 was a challenging
year. Markets were difficult with weak global industrial demand, change
from peak to trough electronics cycle and geopolitical tension impacting
confidence just as supply constraints began to ease. In addition, a
deeper analysis of our performance in 2021/22 and 2022/23 identified
that RS was a major beneficiary of unusual post-pandemic trading
tailwinds, particularly in electronics."
I do admire RS as a retailer, though. Although it mainly sells to professionals, there's some hobbyist interest in their wares. I found them to be a professional outfit offering good service. It's a pity I didn't buy the shares years ago, when I first admired them.
It is interesting to look at the analyst estimates chart, which clearly showed a downtrend in their expectations over time. So maybe we shouldn't be too surprised by the disappointing results. They were well-signalled.
According to my calcs, RS still has a healthy ROE of 17.3%, and a more-than-adequate interest coverage (8.9).I don't own shares, but I'm still interested in them, and I'm going to stick my neck out and say that it's an opportunity to buy the glitch.
I share your view of RS. I have dealt with them as a mail-order electronics company since the 1960's when they started as RadioSpares with a small product range in a tiny catalogue. I've always regarded them as an economic "bellweather". Is this a buying opportunity?
Solid inline update from Coats (LON:COA) this morning. (I hold)
Apparel, revenue 14% higher - customer inventories and buying patterns returned to more normalised levels. As previously highlighted, destocking commenced later in Footwear, creating a lag effect in the recovery relative to Apparel; Footwear returned to growth in the period, with revenue 6% higher year-on-year, as demand from several major brand customers picked up as their inventories also normalised.
Sporting summer seeing pick up in demand, albeit from a low base year in 2023?
Our strategic projects continue to deliver significant operational and financial benefits and we remain on track to achieve overall savings of $70 million by the end of 2024.
Growth also seen in sustainable threads, market leader; also a reminder that Pension fund top ups ceased late 2023 adding 2m p/m FCF.
Group adjusted EBIT margin being at least in line with our 2024 goal of c.17%.
Chance of a beat at interims?
Todays CPI number marks the passing of the base effects ... for the remainder of 2023 there was a slightly volatile mix of monthly numbers ...but the v large energy numbers have exited the data. (Last April was +1.2%) I would look much more to the current monthly numbers now and to be perfectly honest, if we can hold a range below 0.5% with an average nearer 0.2% then all is ok. Today's may be slightly high and thus the bond market behaves accordingly but let's face it, the economy is doing ok, so I don't expect much change in rates for now.
Markets are doing a great job of shrugging everything off, this won't last. Our conviction will be tested soon, so it's good time to let go of your least favourite ideas, that may have already disappointed.
Marks and Spencer (LON:MKS) I should have put my whole portfolio in M&S, safe as knicker elastic, nearly 2 bagged my original buy.
Marks and Spencer (LON:MKS) Still only on a PE of 12 after this morning's rise, so think scope for further upside.
same here, wish I had been braver and bought more ( i bought @ 132 and 118)
it went below £1, but I wasnt brave enough to pull the trigger
It does make you wonder Slops I did a back test and looked at 60/40, S&P 500 & 10 year US treasury and other than a dire 2022 it chucks out decent figures most years.
So this does make me wonder why I bother with all my research, other than I enjoy it but I reckon for 8-10 of hours of research per week I probably still slightly under perform 60/40 structure over the long term which would require about 1 hour per week research and maybe quarterly rebalance.
I think even Fundsmith has started to under perform its benchmark I do wonder if its the case that once these funds get oversized they end up turning into trackers just because they have to buy mega caps for liquidity issues.
Apparently Fundsmith has underperformed it's benchmark, for the last 3 years running. I don't think size is the issue, just some badly timed investments, such as PayPal Holdings (NSQ:PYPL), Adobe (NSQ:ADBE) and Intuit (NSQ:INTU, also missing out on the big technology winners.
Knicker elastic sags over time......
Any thoughts on Marlowe (LON:MRL)
Yes, that LTIP introduced in 2021 is scandalous and makes it an absolute barge pole for me. ;-) Other opinions are available and equally valid.
Marlowe (LON:MRL) My thoughts are that Normalised EPS is always massively higher than reported EPS due extremely large adjustments. Some of these adjustments might be fair enough, but very likely some of them are designed to flatter the results. To my mind this means that forecasts are meaningless because it is likely that they too have been subjected to massive adjustments. It is theoretically possible to analyse all these adjustments to try and figure out whether or not they are valid, but I think it very likely that it would be a waste of time. It's probably better to move on to another company whose results are more transparent.
All fair comments, but then along comes the sale of a small part of the total business for a thumping great chunk of cash. This has given them a rock solid balance sheet and a valuation anomaly. Hence the improved sentiment towards Marlowe (LON:MRL) and why I now hold. Also attracted to the long-term term growth profile of the market they are in.
Expected news from PCIP a day early as the trial lasted one day instead of two. Sycurio (the company suing PCIP) offered 90p which is in available court documents (current price 60p) and so real value likely higher. I am long so biased. Cash generative and this year should be profitable.
Edit: This is only the first leg though, US leg to come! If no agreement before then..
Soon after listing on the same US index OTCQX Team Internet (LON:TIG) has risen by 30%
Ooops -the comments section screen's gone all wonky on my pc - it's since moohlacoast's comment below - the copy and paste comment from Zotefoams (LON:ZTF)
Zotefoams (LON:ZTF) Well done to Zotefoams’ on their RNS which finished with:
"Note. The Board understands that current market expectations for the year ended 31 December 2024, prior to release of this trading statement, are revenue of £138.5m and adjusted profit before tax of £14.9m."
If only every company would do this!
Hi - can you somehow change the copy and paste bit re ZTF please?
Moolahcoast ... could you replace your RNS quote with plain text, please? It's somehow conflicting with the way the comments section is displaying and making it unreadable.
ZTF Here we go:
Note. The Board understands that current market expectations for the year ended 31 December 2024, prior to release of this trading statement, are revenue of £138.5m and adjusted profit before tax of £14.9m.
Volvere (LON:VLE) ( I hold) is a nice read this am although nothing much to add to the prior trading update that contained all the useful numbers. The NAV is £14.83 and priority one would appear to get the share price back to this ...no doubt buying back as much stock as possible ....which helpfully improves the NAV.
Group cash is £23.74m Vs a market cap of £30.36m at 1350 share price. So the market is valuing an 80% stake in shire Foods at under £7m. The Net assets does a slightly better job of capturing value .... doubling it to £14m. Arguably Shire would fit nicely into a larger company that could extract synergies and may command a value up towards £30m ... 80% of which would be £24m ... this would be a huge result, every £2m net to Volvere (LON:VLE) above £14m ... is £1 of additional NAV. So £20m for Shire which would be less than 7x ... would increase NAV to £15.83. Yet quoted food companies would appear to have scope to trade substantially higher than this.
Clearly decent value on the table...with communication ruling nothing out. Great custodians of businesses. Deal flow has been quiet for several years but also further back in their past.... I believe Nick will manage a good outcome for all shareholders.
Volvere (LON:VLE) , would be great if Graham or Paul can say a few words about this undervalued little company today. Could be valued as follows:
£23.7m of cash & short-term investments
£3.8m of Shire Foods profit before tax (and intra group charges). 6x multiple, of which they own 80%. Circa another £18.3m.
£42m of value, or £19 per share (with 2.25m shares in issue), vast majority of which is cash? Less a little bit of debt.
Calnex Solutions (LON:CLX) I watched the investor presentation this morning and was reminded how much I like the management there for their straight talking approach and detailed answers to questions. I had a to-and-fro with another investor on here when the share price was up near 80p from half that level, arguing that the downturn in orders would persist and that shares had rebounded too fast. Now that the market has woken up to this reality, I’m much more interested in the prospects and have reopened a half position. I think there’s a couple more frustrating TUs in the offing, but shares could start to move if/when US interest rates finally begin to turn down.
Thanks for the update, saves watching it.Although I liked the ceo Tommy when i last watched an investors' presentation.I remember the concern when Spirent Communications (LON:SPT) got taken over as Calnex Solutions (LON:CLX) was a supplier.Seems like they have the history of sales of the products their end teleco market needs when it recovers and cloud/data centre looks promising.
I knew there would be a Doubting Thomas.
I see myself more as a Macro Malcolm
Warpaint London shares given the green light to list on American market as well as aim market in London
wonder if this will boost the price?
I'm struggling to think of any UK company that has successfully listed on the US over the counter market. Perhaps my memory is failing me, anybody help?
Team internet group? Team Internet (LON:TIG)
Soon after listing on the same US index OTCQX Team Internet (LON:TIG) has risen by 30%
Thank you both. TIG certainly did well.
Hello commentators on Warpaint London (LON:W7L) and the US listing. I cannot comment on the success or otherwise of other UK companies doing the same though Indivior (LON:INDV) I believe did add a listing in the US market in 2021 if my memory serves me correctly. It stays with because I remember reading the RNS at 7.30 on the fateful morning of the announcement, and I almost bought at the mid 880s....but didn't. It moved pretty quickly up to the2000 mark. That hurt...hence the memory.
Of course, the difference in product offering and scale between the two companies is stark. Indivior (LON:INDV) is a major player in the fight against the spread of the drug ketamin (again from memory) and it has also had some legal issues in the meantime which have hit profits, and it has moved its primary listing to the US recently..........but back to Warpaint London (LON:W7L) and what the future may hold.
I listened intently to the CEO of the company at his recent presentation to a Mello Monday evening recently. I had previously examined the company's performance in detail and especially following the major sale by two directors of a large number of shares at a discount - SP down to 450. Why if the demand was so high, was the sale at a discount - they increased the volume sold because the brokers said demand exceeded supply and persuaded Sam and co to up the volume. (I should add that they still remain major shareholders and I added to my holding at the lower SP which ensued)......but I digress a little.
The final figures for the year showed that the major share of sales and sales growth was into the EU which was a surprise, a pleasant surprise, given the deep distribution in the UK. It had passed me by. However, in answer to the question as to where the company's future focus will be, it was very clearly - in the US. He even had a chart which showed the potential and similarities - market 10 x the size vs UK, but also similar characteristics in terms of consumer attitudes to value etc. In other words, do in the US what we have done in the UK and the sky is the limit was my interpretation.
Three other things that struck me from this and previous 'meetings' with the CEO and his team.
In the US, the company acquired the distributor some little time ago. As a small player, at the bargain end of a very fragmented market, owning your distributor must be worth its weight in gold. Gives .your products pride of place in any discussions with trade buyers instead of a maybe mention.
Additionally, some time ago they really took a knife to the items in the ranges, I guess what marketeers call the 80:20 principle. It has clearly worked, increasing focus on what sells, and reducing overhead costs.
Finally, the message from last week's Mello Monday was that the US was the No 1 target, and this was before the announcement today about additional listing in the US. No mention was made of this at that presentation. I don't know what the additional costs of this listing will be - others may, and it would be good to know. However, if this gives more power to the distributor's arm, then all well and good.
I look forward to any comments from followers and fellow holders /admirers. If the company succeeds in the US as in the UK and EU, then the SP could go forward in leaps and bounds from here.......and then there is Asia. New listings have been achieved recently in the Philippines, and in answer to my question about potential in Japan and South Korea, the CEO said they already have a distributor in Japan. Exciting times!
The only thing that concerns me a little as someone who has spent his whole career in FMCG companies with brand leaders and significant reputational moats supporting significant price premia, Warpaint London (LON:W7L) is at the other end of the spectrum. Another chart at the presentation showed the price comparisons versus premium brands of I forget what he called the items - I would call them special occasion items e.g. for the Xmas trade. For the same quality said Sam - and the products were clearly very good look-alikes - the price 'discount' for the Warpaint p;product vs the premium brand ranged from something like 60% to 80%!! The CEO said this always impressed the potential trade buyers. Given my years of experience, this level of discount says this product can't be very good in quality terms........but what do I know about the cosmetics market and the target audience. Sam and his team do, the SP trend and key performance figures are living proof, and this is good enough for me.
A quick update on some RNS's for some of my holdings;
Niox (LON:NIOX) - in line AGM statement update
Marks and Spencer (LON:MKS) - some barnstorming full-year numbers. Should be well received with nearly all key measures showing significant growth
ME International (LON:MEGP) - sells its orange juice business (very small business only acquired in 2019) for approx £4m and reiterates its focus on its core business of photo-booths & washing machines - no loss/write-downs from the sale as all costs covered by profits from the 5 yrs held.
Looking forward to seeing the Marks and Spencer (LON:MKS) share-price reaction. Just need to be careful that these have not already been reflected in its recent price rises.
Marks and Spencer (LON:MKS)
Revenue (that matters) seems to be in line but debt (including leases) lower than expected. Dividends restored (3p) expected.
All the best
Marks and Spencer (LON:MKS) results lauded as ahead of expectations - I can see revenue is ahead - but whichever way I look at profit I see a slight miss (when compared to Stocko forecasts). Maybe I'm missing something. (Impressive debt reduction - maybe we should get the board to run the country for a while).
forecast: forecast 2024 earnings: 23.21p
achieved : Adjusted basic earnings per share 24.6p
Fair.
Adjustments may be the problem. Looking at last year's earnings: RNS from Marks and Spencer (LON:MKS) last year adjusted eps was 18.1p. The results just published for this year state last years comparative adjusted eps (last year) was 16.9p. Stocko says last year's normalised EPS was 15.9p.
So not certain the 24.6p will end up as the final stocko eps for this year. But basically you're right! 24.6 is higher than 23.21.
Pads away with tail between legs.
UK CPI inflation drops to 2.3% from 3.2% in March
UK CPI inflation drops to 2.3% from 3.2% in March
You do realise this is a lot worse than expected and is likely to delay the onset of interest rate cuts?
I knew there would be a Doubting Thomas.
It’s true though. Interest rates now unlikely to be cut until August
I would have been amazed if the UK went first before the USA.
The US economy is absolutely booming, with investment at record highs as reshoring accelerates. The whole point of having your own currency is so you can choose the rates appropriate for your circumstances.
Expected was 2.1% and it came in at 2.3%. Markets will open in the red. FTSE futures are -0.6%. It reads nice as a headline but it was all in the price. Long term the picture is good, but short term this could delay rate cuts. Let's be honest, Bailey is terrified of making a move before Powell and will do anything to justify waiting just as long as him.
This is the headline, not that its hit 2.3%! Like others have said this is a a fairly big miss. They will only drop rates when solidly around 2% for 2-3 months, maybe 6 months. Ive though for a while that earliest US/UK go is August for a drop in rates.
.... Just in time for elections.
….,Just in time for elections.
Maybe he's right to wait Ben given if we go first the pound could weaken making imports more expensive and inflation starts going back up, I get the impression UK, US and Euro need to come down in tandem.
Worse than expected and this is the reason the Futures are showing an opening of about -0.5% at the moment.
Hi BnB,
The Guardian says that City analysts expected a drop to 2.1%, so the fall to 2.3% is less than expected. Although to be fair, it's still a substantial drop, and leaves us only slightly above the arbitrary 2% target. Driven mainly by food & energy inflation falling apparently.
Thanks to slopsjon for flagging this news release.
Regards, Paul.
When you look at the forecasts for the last 12 months only one actual has hit the forecast. Some missing high some missing low. This just goes to show that these experts aren't as expert as they and everyone else thinks.
Inflation measurement is fuzzy and imprecise, though, isn't it? Today's figure of 2.3 might reflect inflation that is actually 2.1 or 2.5 or ... etc. I thought that's why the target is 2 - because if the target was 0 and inflation was measured as 0, the fuzziness means we might actually be in deflation. Setting the target at 2 avoids that.
Yes there are revisions a few months later.
So it might actually be lower but the 2.3% gives BoE the excuse not to reduce the rates, which they dont want to do atm.