Small Cap Value Report (Weds 22 Nov 2023) - SAG, DUKE, VCP, PEBB, TTG, VIC

Good morning from Paul & Graham!
Today's report is now finished, I'll switch to Autumn Statement work next.
Autumn Statement
Today from 12:30. Rather than my usual summary here, we're doing a Stockopedia team effort today, with a separate article here for discussion on this topic. Megan and I have jointly contributed to this article.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Very colourful today!
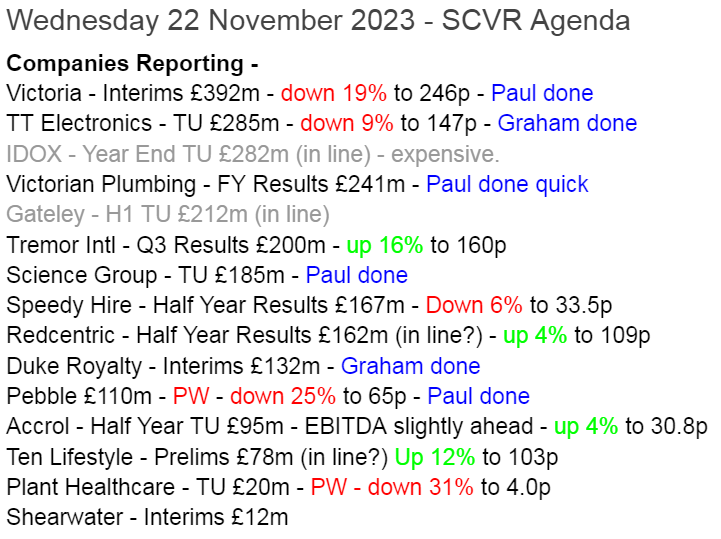
Summaries
Science (LON:SAG) - 405p (pre-market) £185m - Trading Update - Paul - GREEN
A reassuring update says that this diversified group is trading in line with expectations overall, despite some softer markets. Nice balance sheet with plenty of cash & liquidity, so expect more acquisitions, which management seems to adopt a sensible approach towards. Valuation remains quite modest, for a decent quality group. So I remain positive on this share.
Duke Royalty (LON:DUKE) - unchanged at 31.2p (£132m) - 2024 Interim Results - Graham - GREEN
Quarterly recurring revenues are now over £6m at Duke, although today’s interim results show profits being held back by losses on equity investments and by higher interest costs. For those willing to bear some risk, I think the NAV discount and 9% yield could be tempting.
Victoria (LON:VCP) - down 16% to 256p (at 09:32) £292m - Interim Results - Paul - RED
A sharp fall in H1 revenues, and wobbly sounding outlook worries me, as it's combined with a horribly weak balance sheet with massive debt - exactly the type of thing we need to be avoiding at present. This is looking high risk now, so needs to be seen as a dangerous. Or, if things work out, it could be a lucrative special situation. Could go either way, but I'm not interested in taking the risk here.
Pebble (LON:PEBB) - down 33% to 59p (£98m) - Trading Update - Paul - AMBER
Profit warning for FY 12/2023 wipes out a third of the share price. Seems a rather harsh reaction, to what seems a setback rather than a disaster, due to slowdown in order intake at one division. Balance sheet is sound. Reasonable track record. EBITDA is nonsense, due to heavy capitalisation of dev spend. Overall, nothing madly exciting here.
TT electronics (LON:TTG) - down 7% at 150.5p (£266m) - Trading Update (profit warning) - Graham - BLACK for spreadsheet - GREEN on fundamentals
TTG’s value has fallen by £20m today as adj. PBT is now expected at the lower end of the forecast range. The reason for this according to the company is £2m of costs associated with a breakdown of machinery. I continue to see good value on offer as TTG deleverages.
Victorian Plumbing (LON:VIC) - up 5% to 78p (£253m) - FY 9/2023 Results - Paul - AMBER/GREEN
Victorian Plumbing Group plc ("Victorian Plumbing", the "Group"), the UK's leading bathroom retailer1, announces its audited full year results for the year ended 30 September 2023 ("2023"), highlighting the significant progress made against its strategic priorities.
These numbers look good! Adj PBT is up 29% to £20.3m, on £285m revenues (up 6%).
Adj diluted EPS 4.7p, up 24%, for a PER of 16.6x
Huge marketing spend, at 28% of revenue.
Dividend payer, 1.4p (up 27%), plus 0.45p interim = 1.85p total, yield of 2.4%
Outlook - confident, and FY 9/2024 has started well, with revenue and margin growth vs LY. New warehouse to open in 2024, removing capacity constraints & inefficiencies.
Share based payments are hefty at £3.9m in both years, that’s 20% of operating profit!
Lovely balance sheet - capital-light, with £45m NTAV all in cash basically!
Cashflow - note it’s capitalising intangibles of c.£3m pa. Biggest outflow is payment of divis.
Paul’s view - this looks a good business. Probably priced about right, but given that it’s trading strongly in tough macro, I’ll go with AMBER/GREEN, as they’re clearly doing something right! [no section below]
Paul’s Section:
Science (LON:SAG)
405p (pre-market) £185m - Trading Update - Paul - GREEN
This is how SAG described itself in its last interim results -
Science Group is a science & technology business providing consultancy and systems to an international client base. The Group comprises five operating divisions, supported by a strong balance sheet including significant cash resources and freehold property assets.
I confirm the balance sheet is indeed good.
We’ve reported positively on SAG the last 3 times here -
24/3/2023 - GREEN 387p - Good FY 12/2022 results. Modest valuation. Cautious outlook. Good bal sht. Strong long-term track record.
18/5/2023 - GREEN 400p - in line AGM TU. Good value at 12x PER. Roland & Paul both like it.
24/7/2023 - GREEN 415p - complicated interims. Sound finances, good value. Owner-managed.
Today’s update - is reassuring -
The Board of Science Group anticipates that Adjusted Operating Profit for the year ending 31 December 2023 will be in line with expectations. Benefitting from the Group's sector portfolio and disciplined cost management, Science Group remains on track for another record year in 2023.
Track record shows no impact from the pandemic,decent growth, but paltry divis - so this is a growth stock, not an income investment -
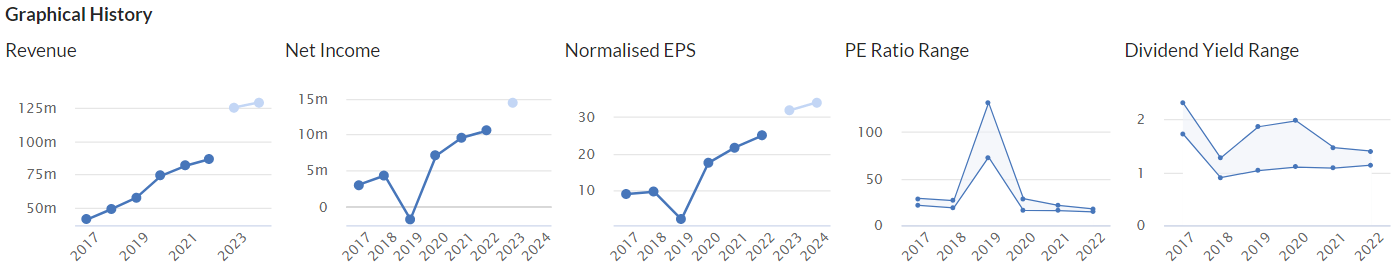
Acquisition of TP Group seems to be going well.
Cautious outlook -
The Board remains cautious on the outlook for 2024 with geopolitical instability exacerbating the impact on our clients from high interest rates, a weak consumer economic environment and uncertainty associated with political elections (USA and UK). While the reduction in inflation in the Group's key geographies provides some optimism, confidence in end-user markets is unlikely to improve in the near term. However, as consistently demonstrated, the Board considers that Science Group's sector diversity, disciplined management culture and strong financial position will continue to provide resilience.
It made similarly cautious outlook comments earlier this year, but seems to have navigated this year fine, so I'm not reading too much into the caution above.
Share buybacks - surely these reduce liquidity over time (although provide an exit route for sellers)? Share buybacks do enhance EPS and DPS, and with the shares looking good value, buybacks are a good thing in my view -
In this challenging period for small cap investors, the Board recognises the importance of share trading liquidity. As a result, when permissible and if in the Board's opinion to be in the best interests of all shareholders, the Board has continued the buy-back programme. During 2023, the Company has (to 17 November 2023) bought back 828,885 shares, equivalent to approximately 1.8% of the issued share capital, at a total cost of £3.3 million.
Cash & liquidity look ample, giving it options for further acquisitions -
Science Group maintains a very strong balance sheet with gross cash at 31 October 2023 of £32.4 million and net funds of £19.2 million. This robust capital foundation, further enhanced by the undrawn bank facility of £25 million, enables the Board to continue to evaluate corporate opportunities in line with the Group's strategy.
Paul’s opinion - this update strikes me as neutral for the share price.
Broker consensus is 31.6p FY 12/2023 and 33.8p for FY 12/2024. So at 405p, the PER is 12.8x, dropping to 12.0x in 2024 which remains good value I think, for what seems to be a well-managed, decent quality group of companies.
Shareholders have done well over the last 5 years, SAG shrugging off all the pandemic, macro chaos, and a savage small caps bear market over this period - and note the green StockRank -
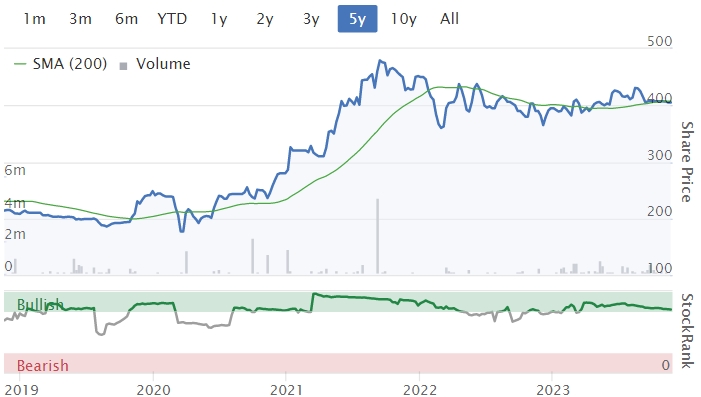
I can see why there’s little volume traded in SAG shares most days - it strikes me as the type of company that investors would tuck away and hold for the long-term, and would be of little interest to short-term traders.
I remain positive on SAG shares - a quality outfit, at a modest valuation, and it seems to be coping alright, despite softer markets in some parts of the business.
Victoria (LON:VCP)
Down 16% to 256p (at 09:32) £292m - Interim Results - Paul - BLACK (PW) for spreadsheet - RED on fundamentals
Victoria PLC (LSE: VCP), the international designers, manufacturers and distributors of innovative flooring, announces its half year-report for the six months ended 30 September 2023, delivering a H1 FY24 performance in line with management expectations.
EBITDA margin improvement despite softer market demand
Key numbers -
H1 revenue £643m (down 17%, which seems a large fall)
Underlying operating profit £54.3m (down 11%)
Profit before tax £31.7m (adjusted), and £(19.2)m statutory - adjustments are just too large for me.
Net debt (excl. leases) £671m - this is the big issue, VCP has got way too much debt.
Net debt/EBITDA 3.8x (LY: 3.4x) based on bank reporting basis.
Diluted adj EPS 13.48p (LY H1: 17.87p)
Finance costs are now huge, at £52.2m in H1 alone, with £22.6m of that called underlying, and £29.6m non-underlying.
Outlook -
"The remainder of the year continues to look more challenging with ongoing lower demand maintaining pressure on top line sales, alongside inflation edging up raw material input costs. Accordingly, the Board now expects the resulting impact of these headwinds to slightly more than offset the c. £20m EBITDA benefit from the previously announced reorganisation programme. Nevertheless, thanks to the extensive reorganisation Victoria has undertaken over the last 24 months, the business is far better prepared to meet these challenges."
We cannot predict precisely when the rebound will occur although we are (clearly) continually closer to that point. Nevertheless, we view the second half of FY2024 with caution, with increased geopolitical uncertainty and continuing high mortgage rates impacting consumer confidence and discretionary spending. Consequently, we are managing the business to optimise results, market share, and cash flow until the inevitable recovery in demand.
Balance sheet - is a complete mess. NAV of £82.8m is down from £294.7m a year earlier.
Intangible assets (acquisition-related) total £453.9m, so NTAV is negative £(371)m. In a bull market when interest rates were zero, nobody would have worried too much about that. In a bear market, with much higher interest rates, it’s a big problem.
The middle, working capital section of VCP’s balance sheet is fine.
It’s the long-term liabilities that scare me witless, at £1.26bn.
Paul’s opinion - clearly demand is much softer now, but partially mitigated with margin improvements.
I’ve previously expressed my concern over the excessive debt and weak balance sheet here, which combined with deteriorating profitability is now looking precarious.
Remember also the kerfuffle over the qualified audit report in Sept, which the company rebutted strongly, but it’s still a negative for some investors.
Again as previously mentioned, I don’t like all the adjustments in the figures, which seem excessive, and make it very difficult for me to determine if VCP makes any genuine profit at all? Combined with a mountain of debt, I’m repelled by these numbers I’m afraid.
So it has to be a shift from amber/red to just RED - due to the elevated risk.
As with lots of companies, it could all turn out fine, and people who take big risks can sometimes achieve out-sized returns due to the gearing effect (upside all flows to equity if things work out well, as the discount for downside risk disappears - as we saw with Videndum (LON:VID) yesterday on its refinancing). With VCP though, I just don’t want to take on this elevated level of risk. One for traders maybe? The share price is very volatile here because investor perceptions can change so much, and so rapidly, having a geared effect due to the massive debt pile.
I could be wrong, but I have a feeling VCP has been on the receiving end of a shorting attack? Let me know if you have any info on that, in the comments.
Note 2 shows that the company gives itself a clean going concern assessment. Although note 1 says that interims are unaudited (normal), but also says they have not been reviewed by the auditor - that’s not normal in my experience. Usually, I would expect the auditor to sign off the going concern note, even in interim results. Otherwise companies could put anything they like in interim statements. I’ve raised a query with some experts on auditing, and wonder if any readers have relevant experience & knowledge and could comment on this?
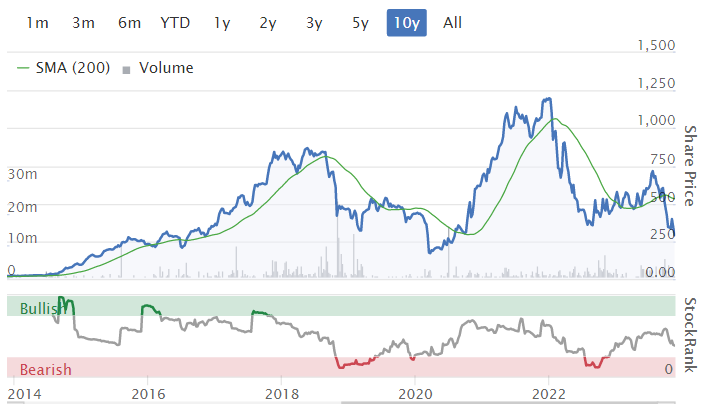
Looking at the 10-year chart, it’s had 2 distinct cycles of multibagger then major correction now. Look how much money was made in 2020-21 though, on that rebound! So this can be quite an exciting share to trade. On fundamentals though, I’m steering well clear. As I emphasise every week in my podcasts, the key shares to avoid right now are highly geared, weak balance sheet companies that are also showing signs of trading deteriorating. We’ve seen how these can very quickly turn ugly, and are then forced to raise fresh equity at multi-year low share prices - recent examples being XP Power (LON:XPP) and Videndum (LON:VID) . It wouldn’t surprise me if VCP ends up in a similar position, but that depends on how the debt is structured, which I think contains covenant-light bonds, so it might be able to survive without dilution. That’s the key area to research, for anyone considering a punt here.
Pebble (LON:PEBB)
Down 33% to 59p (£98m) - Trading Update (profit warning)- Paul - BLACK for spreadsheet (PW) - AMBER on fundamentals
The Pebble Group (AIM: PEBB, OTCQX: PEBBF), a leading provider of digital commerce, products and related services to the global promotional products industry, is today updating the market on its expected performance in the year to 31 December 2023 ("FY 23").
It’s a profit warning, but only seems mild, so I’m a bit surprised the price has been clobbered by 33% this morning. Mind you, profit warnings often sound mild if the PR has smoothed them over in the RNS, then you see broker forecasts slashed! I can’t find any broker updates here yet.
Slower order intake at one division is blamed for revenues now expected at £124m for FY 12/2023, down 7% on 2022. The StockReport shows consensus expectations at £140m revenue for 2023. So a £16m shortfall, which is quite big to happen this late in the year.
Margins are better than last year though, so the impact on EBITDA is modest -
Group EBITDA of approximately £16m (FY 22: £18.0m), maintaining Group EBITDA margins close to FY 22.
Net cash expected to be at least flat with last year’s £15.1m.
Paul’s view - this doesn’t sound a disaster by any means. I haven’t looked at PEBB this year, as the company never really interested me. It seems an OK company, I’ve just had a quick look at the last interims. Forget EBITDA though, as it’s capitalising loads of costs into intangible assets, so actual profit is much lower than the fantasy EBITDA numbers. Hence why it can only afford to pay tiny divis, there’s not much real cash generation here.
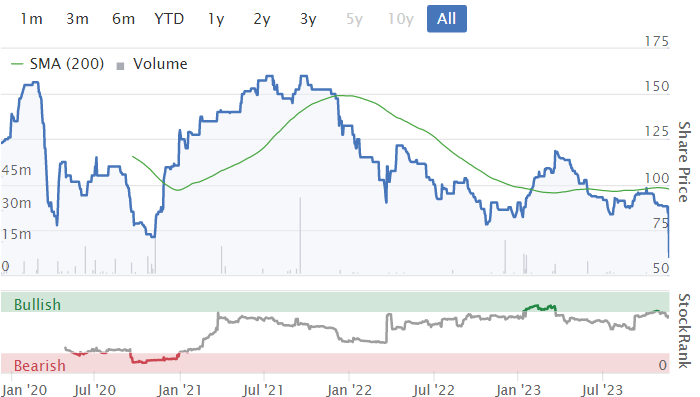
So overall I’d say it doesn’t really interest me. Although it’s a half-decent company, which is profitable most years, so it might be worth taking a fresh look, now it’s hit a new low since floating in Dec 2019. Let’s go with AMBER.
New low today at 60p -
Graham’s Section:
Duke Royalty (LON:DUKE)
Share price: 31.2p (unch.)
Market cap: £132m
Duke Royalty Limited (AIM: DUKE), a provider of alternative capital solutions to a diversified range of profitable and long-established businesses in Europe and abroad, is pleased to announce its interim results for the six-months ended 30 September 2023 ("Interim 2024").
Let’s catch up on the latest developments at Duke.
Total cash revenue is up 35% in H1 to £14.1m (H1 last year: £10.4m).
More meaningfully, recurring cash revenue is up 17% to £12.2m (H1 last year: £10.4m).
The recurring revenue figure excludes various one-off deals such as when Duke sells its equity stakes in businesses, so it’s a more useful measure of underlying revenue.
In Q1 (see our coverage in September), Duke’s quarterly recurring revenue crossed over the £6m mark for the first time. So it is no surprise to see H1 recurring revenue just over £12m.
Free cash flow comes in at £7.9m (H1 last year: £6.5m).
Dividends in H1 have been 1.4p so far (H1 last year: 1.4p).
The 0.7p quarterly dividend has been flat for two years - Duke was explicitly designed to be an income play and some investors might be wondering when they will get an increase in the quarterly payout.
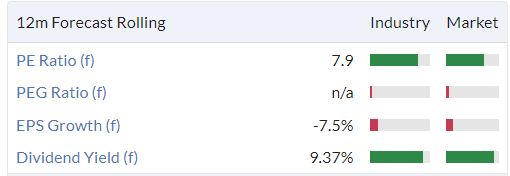
However, for what it’s worth, the yield is perfectly reasonable based on the current share price:
More importantly, the flat payout has given Duke a chance to consolidate its asset base. Based on the current share count of 421.5m, the dividends in the first half of the year cost the company slightly less than £6m, which were covered by nearly £8m of free cash flow.
Operationally, the H1 highlights were:
Over £18m deployed into new and existing investments.
Number of royalty partners grew by one to 15. Note that the number of underlying operating companies is far larger (c. 60), as some of the royalty partners are themselves owners of groups of businesses.
Duke made a successful exit from one investment (this was previously announced).
£40m available liquidity for future investments.
Chairman comment excerpt:
"During the interim period Duke was able to post its twelfth consecutive quarter of increasing recurring cash revenue which was a fantastic achievement for the Company. In line with this strong financial performance, the Company also maintained its quarterly dividend of 0.70p per share. Investors can be reassured that the dividend payout remains well covered by operating cashflow with the attractive yield representing a pillar of Duke's ongoing business model and its overall financial discipline.
The outlook statement is quite long, I think these are main points:
“Cautiously optimistic” for the rest of the year.
Duke’s product is still thought to be unique in the financing industry..
They are currently reviewing how they articulate their message to business owners - they think that some changes to the message will open up more opportunities and broaden their appeal.
Balance sheet shows equity of £162m as of September 2023, down from £164m in March 2023.
Income statement shows a statutory profit of £3.4m, down from £10.3m in H1 last year.
Among other things, the latest period’s profit result was impacted by unrealised losses on equity investments and by higher finance costs (the interest bill grew by over £1m).
Graham’s view
I’m a former shareholder here, who bought and sold my shares in the company before its Covid-related slump:
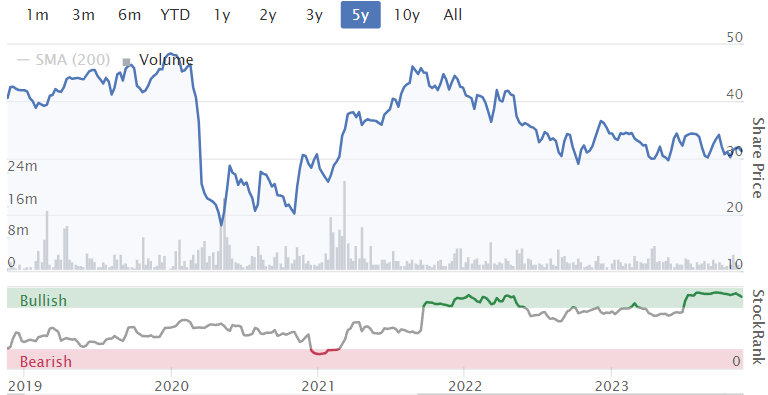
Perhaps I’m overly anchored to the prior valuation, but I continue to think - see our prior SCVR comments in the archives for more - that Duke is likely to be undervalued here.
The shares currently trade at a 19% discount to balance sheet equity and at a yield of about 9%. I expect to see the quarterly dividend increase before too long.
It’s not a perfect investment by any means - there are plenty of risks and uncertainties associated with the portfolio. I would prefer if the company stuck to its core product and did not take equity stakes in its royalty partners. However, I think the sturdy performance through Covid does give Duke and its management team quite a lot of credibility at this point.
One reasonable question mark is around future fundraising plans. The company did raise funds at 35p in 2022, and it might be tempted to do that again. So don’t be too surprised if you see another placing before too long.
At the cost of some more dilution, investors would get further diversification of the portfolio. Long-term, I think much more diversification might be needed to get these shares onto a more premium rating.
TT electronics (LON:TTG)
Share price: 150.5p (-7%)
Market cap: £266m
TT Electronics plc ("TT", "the Group"), a global provider of engineered electronics for performance critical applications, publishes the following trading update on the Group's performance in the four-month period ended 28 October 2023 ("the Period").
This is another stock I’ve been positive on for the past year, but the share price hasn’t been cooperating very well:
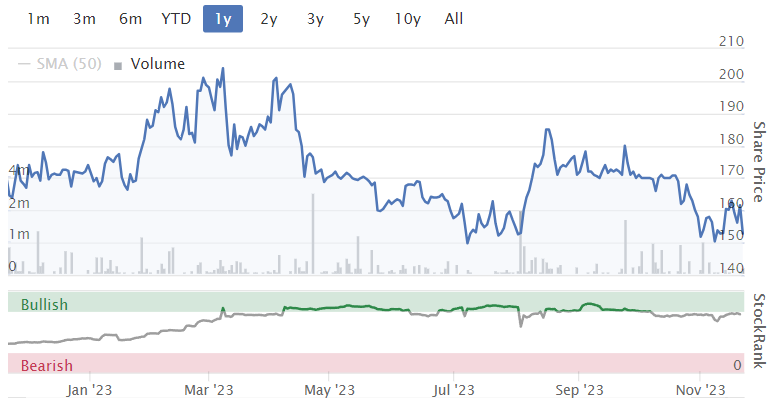
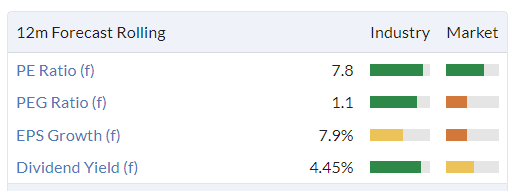
Valuation has been appealing:
Let’s find out what the issues are with today’s trading update.
Organic revenue growth: 4%. As we noted in August, there were signs that revenues might be about to plateau as orders appeared to be slowing down. Consensus forecasts suggested only a marginal increase in revenues in 2024.
There is also a seasonality issue: last year saw a very strong H2 compared with H1, but that is not going to repeat.
Each division appears to be doing ok:
The performance of our Power & Connectivity division continues to show good year over year improvement, and GMS (Global Manufacturing Solutions) is sustaining its strong margin performance. Trading in Sensors and Specialist Components has been in line with our expectations other than the one-off impact of the previously highlighted machinery breakdown experienced in one of our facilities, which continued for longer than anticipated, impacting profit in Q3 by circa £2m.
Balance sheet: The investment thesis I set out here included a forecast reduction in net debt, which I hoped would lead to a better valuation for the equity. TTG confirm today that they are on track to show “much improved cash generation over last year and a further reduction in leverage”.
Outlook is at the lower end of expectations:
While the Board still expects good year on year improvement in revenue and profit, as a result of the machinery breakdown in S&SC we now expect to report Group adjusted profit before tax towards the lower end of current market expectations for 2023.
The company helpfully discloses that the range of forecast adjusted PBT is £43.1m to £46m.
The breakdown in machinery has cost them c. £2m as mentioned above, and is not being adjusted out, so we have a very simple explanation for adj. PBT hitting the lower end of the range.
TTG has a new CEO, who says:
I am excited about the potential for TT and can already see opportunities to unlock further value across the business, driving growth, efficiencies and performance through capitalising on our positions in the structural growth markets in which we operate. I look forward to sharing more detailed thoughts shortly after our FY23 results, as we plan the next phase of our disciplined growth strategy.
Graham’s view
I don’t think I should change my view on this on the basis of a one-off mishap. The market cap might be down by £20m today, but the cause is only £2m of exceptional costs.
A more serious concern might be the slowdown in revenue growth, although that has been baked into expectations for a while.
Up until today, EPS expectations had been pretty stable:
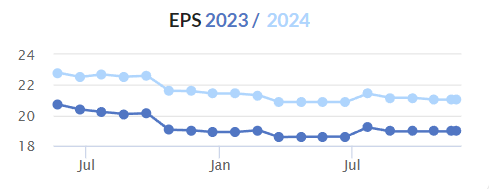
Net debt was last seen at £139m, about half the market cap, but the leverage multiple was only 1.8x as of the most recent interim results. I’m looking forward to seeing this fall even deeper into territory that most investors would consider to be safe.
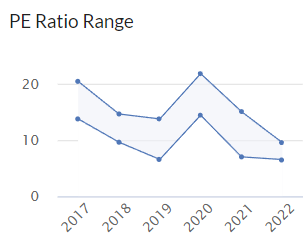
As that multiple keeps falling, I can’t avoid the view that the market will have to re-rate TTG’s equity higher at some point. In short, it still strikes me as a higher-quality company than the 8x P/E multiple suggests. In bull markets, it has traded at much higher valuations:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Off topic and definitely not small cap but I've been buying easyJet (LON:EZJ) over the last few weeks. I think that is the best travel opportunity out there. The are really building out their Holidays team to compete with TUI, Jet2 and BA holidays. They have a very good new holidays team in place with a clear plan, on top of a very successful airline I think it presents a good opportunity.
results next week which should be interesting
Probably On the Beach group plc is the best one in that sector (leisure)-no debt , cash generative , operating margin over 15% and still plenty of room for growth.
Maybe but OTB don't own anything. easyJet (LON:EZJ) have the competitive advantage of owning the airline they give the holidays business preferential air fares. Then they get 15-20% on the accom, transfers and other auxiliaries happy days
Did you mean to say : they don’t OWE anything?!
No, own. They are reliant on 3rd party supply
They do own a website that generates about £200m revenue (currently!) and they do not owe anything , whereas Easyjet do not actually generate any meaningful cash flows (at the moment) and their debt will double in 2 years.
Agree NewInvestor1972. I have held easyJet (LON:EZJ) for a while- so well down. As a user I can see how they are increasing the margins without putting off customers- not been on an empty flight for a while now. Yes it is annoying when you book and see all the add-ons, but it is increasing profit per seat. I bought originally because I feel they will be taken over one day and there is huge value in the brand-in my opinion. Maybe I was a bit early!
The race is on:
easyJet (LON:EZJ) V On Beach group (LON:OTB)
:)
Not Jet2 (LON:JET2) ?
The last three times I have tried to travel with EZJ they've cancelled every time. The last time, they had the aircraft sitting at an airport 30 minutes flight time away for 10 hours before they finally sent us home. I no longer even check their prices where before I didn't check anyone else's. Just one experience obviously, but I think they've lost the plot on customer service.
QueasyJet. I had so much hassle over a damaged suitcase claim for £30, about 30 years ago, I vowed never to use them again, which I have not. Why do they do it, paid out in the end.
I like easyJet, better than Ryan air and wizz air for a low cost airline, BA is pretty crap nowadays.
Jet2 are probably the best in that group.
Not a small cap but looks like interesting activist investor engagement going on at Entain (LON:ENT)
FT was reporting that 3 activist U.S. hedge funds have built up meaningful stakes and are seemingly in the process of trying to remove the CEO given significant underperformance of the shares.
Interesting to see this play out.
There is a lot more inherent value in Entain (LON:ENT) than the market is attributing to it - largely, the rumour goes, due to investor scepticism as to the CEOs ability to unlock it. The right changes could make a material difference in my view. When I looked through the strategy there is a clear opportunity but I am also less than convinced with the CEO and her ability to execute to that plan unfortunately.
Hi Paul, were you going to do a quick review of SDY's interims? Warning this morning, but retrace not as pronounced as it might have been and dividend retained. Chart still suggests recovery, but I would be interested to know the house view. I hold.
Hi Brucie5,
I noticed that Speedy Hire (LON:SDY) only fell a little yesterday, so given the large number of companies reporting, it didn't make it onto the final list. Sorry about that.
Regards, Paul.
Just had a quick look through Calnex Solutions (LON:CLX) interim results from yesterday. I didn't read through word for word so may not have caught everything.
Couldn't really see much new information over their trading update last month. I like the stock and used to hold, though sold before the recent big fall (a rare well timed sell) when other companies in the sector were putting out profit warnings. Good to see that they are moving to a more diversified customer base.
Thanks for the excellent company analysis that you do. The colour coding system is really good but can I ask what does black refer to, e.g. black for spreadsheet?
Paul's spreadsheet recording the companies analysed:
https://docs.google.com/spread...
Row 2 explains the colour coding, black is Profit Warning
Could do with a permanent link to the spreadsheet somewhere.
Thankyou.
Good luck to anyone dealing with Victoria (LON:VCP)
A nuts and bolts business such as floor coverings effectively run by an investment banker never appealed to me.
I always think the love of complication and 'too clever by half' strategies can end up masking a bit of a dog's breakfast.
A decent director buy of 130k at 10.4p in Made Tech (LON:MTEC) last Friday. Management have skin in the game and own 42% of the company. EV of £7.9m against a MC of £16m as there is £8.3m cash on the BS. PSR of 0.4. Could there be a management buy out here?
Check how much he pocketed during the IPO!
Still burning cash this company.
Read this interesting snippet today: “The amount of leverage in Berkshire’s capital structure amounted to 37.5% of total capital on average,”
The leverage came from the insurance float. If the premiums exceed the claims, then he is effectively borrowing at a negative interest rate.
That's one of the original 'tricks' he used to get his start i think, after the awful takover of Berkshire Hathaway, the textile business in decline, due to being aggravated by the founder who was going to buy the lot, offering him a slightly lower price for his equity than previously agreed.I think he said that was one of Buffett's worst investments at the time, but i'm not sure he was too keen on the shoe business, Dexter Shoe as he bought it with Berkshire equity too, which he bought and loved at first.
What is happening at MTI Wireless Edge (LON:MWE) ? The company has been making numerous share buy backs last few months art prices significantly higher than the present price. Fair enough - there's plenty happening to have pushed the price down.
Today's announcement states that all the shares in Treasury have now been sold at the current price of 31.5p.
"MTI announces that it was informed on 21 November 2023 that ......." - Does that mean the company didn't know who they were selling the shares to at a price lower than what they bought them for, to the 2 largest shareholders in the company?
"The funds raised by the sale of the treasury shares will remain within the Share Repurchase Programme for future transactions."
Fishy or fishy?
Tremor International (LON:TRMR) feels like the share price has bottomed. Market was clearly expecting bad news yesterday and despite them beating Q3 guidance by 4% whilst lowering full year guidance by about 4% the shares are up strongly this morning.
Given current market cap they plan on using the cash pile to buy back more shares. $20m gets you almost 10% of the shares bought back now!!
Trading at 1* EV/Ebitda versus other US competitors (where the lowest is 4*) this feels like the low point to me with considerable value on offer. As advertising demand starts growing again earnings should start moving ahead nicely. This business is inherently cyclical - so if they can generate this type of profit in a very weak macro environment then stronger macro should lead to good earnings and much stronger share price.
Regarding Tremor International (LON:TRMR) be wary of the buy backs. The last time I checked they had loads of shares in the treasury but were not planning on cancelling them. In my humble opinion it is all designed for director remuneration. Could be wrong but either way no position.
Some of this was planned to be used for employee/director share awards but that was voted down by shareholders. Unlikely to get any traction from shareholders until the share price moves materially up.
Not quite sure what to make of the announcement by NextEnergy Solar Fund (LON:NESF) that it has sold a solar farm to a private fund also run by Next Energy!? This is part of their asset recycling programme.
http://newsfile.refinitiv.com/...
“o The purchaser, NextPower UK ESG Fund, is a 10-year closed-ended private
fund managed by NextEnergy Capital. It is a private unlevered Fund investing
in new-build solar projects in the UK. NextPower UK HoldCo Limited is under
the common control of the wider NextEnergy Group along with NextEnergy Capital
Limited (Investment Adviser to NESF) and NextEnergy Capital IM Limited
(Investment Manager to NESF) and as such is a related party of the Company.”
They say it is 100% premium to the asset’s holding value but how does anyone really know?
Agreed. I hope to attend their IMC presentation on Friday and will be interested if it comes up in the questions or will ask it myself.
Yes please raggedtp. Selling something from your right hand into your left hand is hardly what I would call capital recycling. Either the investment is so good that they can't bare to part with it (in which case, why is NESF selling out) or there just aren't any buyers out there (quite possible). If you could find out, I would be obliged.
TT electronics (LON:TTG)
I hold.
A slightly disappointing update this morning, but not a disaster.
'While the Board still expects good year on year improvement in revenue and profit, as a result of the machinery breakdown in S&SC we now expect to report Group adjusted profit before tax towards the lower end of current market expectations for 20233.'
Helpfully the footnote states
'Analyst consensus expectations for 2023 adjusted profit before tax are in a range of £43.1m to £46.0m.'
Given that the company attributes an impact on profits of £2m from machinery breakdown, this implies adjusted profit before tax of £44m. Importantly the update also cites a continued reduction in leverage
'Trading in Sensors and Specialist Components has been in line with our expectations other than the one-off impact of the previously highlighted machinery breakdown experienced in one of our facilities, which continued for longer than anticipated, impacting profit in Q3 by circa £2m.'
Like many UK small caps the shares remain cheap and will be cheaper today. However it strikes me given the continuing reduction in leverage and the company's expertise in electrification that it is an obvious bid target, but then again so are a number of UK stocks. Having said that who foresaw the bids for Hotel Chocolat (LON:HOTC) or that perennial basket case Fireangel Safety Technology (LON:FA.)
Why is the Autumn Statement made while the market is open? Is it sponsored by hedge funds with their high speed trading ?
Decent results from Sage (LON:SGE). Revenue and Profit both up ~10%. Shares up 7% as I write. Fully valued IMO until you look at International Rivals. SaaS revenues growing nicely. I hold.
Yes, very impressive results - not exactly a small cap so not one for this thread, so started a discussion here: https://www.stockopedia.com/co...
One thought on Sage (LON:SGE) results, relevant to both small and large caps is the revenue growth of 11%. The markets clearly love this, with shares up 13% today - a huge rise for aa FTSE 100 stock.
Well inflation was around 10% p.a. in the UK and roughly 5%-10% during the reporting period. So beating inflatiom, even by a little, is a sign of the pricing power of a quality business.
So when we look at results being reported now, if there is lowish revenue growth (or none), this is an amber flag. Either the business is cyclical or (worse) if it is a non-cyclical business then failure to keep up with inflation shows a lack of pricing power.
One recent example would be HALEON (LON:HLN, which recently reported pedestrian revenue increases in a trading update, well below inflation.
In the smaller cap world Treatt (LON:TET) recently said they expected 5% FY23 revenue growth or 3% constant currency. All things being equal it suggests a business that is OKish but hardly deserving of a premium rating. Stockopedia gives it a forward PER of 18.2 right now, but that's after a share price decline from over 66%.
Sage (LON:SGE)
Sage definately have been playing the long game with the business cloud product which is mostly replacing the old sage desktop - its been a pretty crappy albeit improving product that is taking time to hit critical masse - i would say they will probably hit a purple patch about now but that may run dry at some stage when saturation point is reached . One danger here for sage is that there is massive scope for someone to come in and do a better product and charge half the price and still make money - whether that happens or not i know not but for what they charge all the similar comapnies sage/xero/quickbooks are remarkably annoying in what they dont do easily that they should do easily - for example on sage cloud you cant even flip vat schemes without going to extreme levels - to even switch off vat it involves call to support for them to work out that they need to do something with their magic tokens behind the scenes before i can then do fake vat return if i have the right combo of secret settings and then switch off vat - on xero you change vat at flip of a switch - but then xero doesnt even deal with payments on account siuply like sage does,
Hey ho my original assessment that sage would get to £10 back in 2001 (it dropped masively from dotcom boom time) was proven right - just took 20 years of waiting for that one to pan out as planned.
Sigmaroc (LON:SRC)
I hold.
Taken aback by this morning's announcements as I thought the days of share issuance were behind us.
I do rate the management team. They are very entrepreneurial, e.g. tie up with Arecelormittal, use of Aqualung technology for CO2 capture from lime kilns and intended sale of the gas, development of Greenbloc, low carbon concrete blocks etc. Also they have done a good job with the integration of Nordalk, the previous large acquisition.
Regarding this morning's announced acquisition I see that the vendor, CRH intends to subscribe for placing shares as do directors and senior management. The latter close to £1m.
'As part of the Placing, a CRH Group company intends to conditionally subscribe for Placing Shares
Certain Directors of SigmaRoc intend to participate in the Fundraising for c.£395,000 in aggregate, respectively, of Placing Shares in the Placing at the Placing Price. Other senior management intend to participate for c.£555,000 in aggregate, respectively, of new Ordinary Shares in the Placing at the Placing Price.'
Sigmaroc (LON:SRC) has to date performed creditably in what are challenging economic conditions. As for the share price I remain sanguine as it has suffered like the vast majority of UK listed small caps/AIM stocks. Whether the proposed acquisition, if it completes turns out to be a game changer either way, we will have to wait and see.
In conclusion I wish that the company would stop issuing equity, but if I had the option to sell, which clearly I don't given the suspension, I would continue to hold and once I have fully digested the details of the proposed acquisitions may add, subject of course to the share price. For the time being I will have to trust the management team under Max Vermoken and hope that it has avoided the dreaded hubris and not bitten of more than it can chew.
Sigmaroc (LON:SRC) I picked up the above table from the RNS this morning. There appears to be an error in the aggregate profit of the Enlarged Group, which i find highly unprofessional.
It appears they are paying Euro £645m for Net Assets of Euro 417m (as at 31/12/22) for the Deal 1 targets (German, Czech, Irish), including 10% deferred consideration. So this is 8.7x 2022 EBITDA or 17.9x profit after tax (2022). It feels like a high price.
Later in the admission document they mention a belief of finding £30m EBITDA in addition per annum through synergies. To be fair, they have a decent record of doing this.
The New Option Plan for the directors is based on an exercise price of 60 pps, with a 3 year vesting period.
It's a complicated deal and i need to read more later.
Jonno and OldSchool05, thanks for your posts on this.
I hold and share Jonno's views on management and progress so far. I held off buying the recent dip, waiting for more positive news for the construction industry to support structural growth.
Corporate action not showing on II so assume accelerated bookbuild successfully completed.
I hold Sigmaroc too. They will have increased the share count circa 10x since 2017. They are buying a strategic asset at 7.1x EV/Ebitda( Liberum and includes deferred) whilst issuing at circa 5.1x. The benefits are in the future and will be eaten by banks initially.
Back in the day I owned CRH sub €2! These are very strong businesses with high barriers to entry and extremely long life assets. I’m a bit peeved this morning…”not another placing”. Liberum are suggesting 100m + fcf by 2025-6.
I will see how it settles post suspension, there has clearly been pushback from institutions re the price as the Liberum note refers to a 50p price but it’s actually placing at 47.5p. I suspect it could still be a great investment but long duration and with a constant flow of sellers post all the placings.
I think I have seen some margin numbers which I will try and question. They look high vs CRH and Breedon. Btw CRH is on 11x pe next year, most exposed to the faster growing US and moving its listing to the US. I looked up Martin Marietta and see it’s on 22x. Just saying :)
Cambridge Cognition Holdings (LON:COG) (I hold) change of auditor announced, is this a concern? Share price has declined significantly this year, held throughout this difficult time but might look to draw a line under this. Anyone else in a similar predicament?
Never held this but they need fresh capital so you know what’s coming!
Change of auditor usually a bad sign. Disagreement over aggressive / dodgy accounting.
Possible, but also possibly a perfectly reasonable procedure of putting audit work out to tender periodically, to keep control of costs and ensure they are not letting themselves be overcharged as a captive client. You have to take your pick failing any other information.
I do not think the change of auditor by Cambridge Cognition Holdings (LON:COG) should be viewed as a precursor to a raise. This can be the case with a change of broker but unlikely to be the reason behind a change of auditor. CEO Stork got rid of his unimpressive and short lived CFO about a year ago. The new encumbant seems a really good personality fit to me. Also Grant Thornton have not enjoyed the best reputation recently. I think these reasons are likely to lie behind the change.
Redcentric (LON:RCN) interims this morning. There is much detail on the integration of acquisitions now coming to a close. That, coupled with action on the cost of electricity for running data centres (annualised savings of £2.3m realised) means that a leap in profits and cash flow is expected in the next financial year.
In their note Cavendish expect adj. eps 3.6p this year and 9.3p next and conclude "At 11.6x FY25E P/E, and on an FCF yield of 10.5%, this successful company is stupidly cheap"!
My morning smallcap tweet: Cruising for a losing
TT electronics (LON:TTG) Speedy Hire (LON:SDY) Pebble (LON:PEBB) Plant Health Care (LON:PHC) Science (LON:SAG) Accrol group (LON:ACRL) Sigmaroc (LON:SRC) Quadrise (LON:QED), Idox (LON:IDOX), Gateley (Holdings) (LON:GTLY)
◄TT Electronics (TTG)► warns FY23 adj pretax towards the lower end of market expectations. Blames previously noted machinery breakdown at Sensors and Specialist Components. [SP=161.6 Cap=285m]
◄Speedy Hire (SDY)► warns FY towards the lower end of mgmt expectations. H1-Sep rev down 3%, adj pretax down 56%. [SP=36.95 Cap=171m]
◄Pebble (PEBB)► warns FY-Dec rev expected to be c. £124m (£134m) due to poor order intake at Brand Addition. [SP=85 Cap=142m]
◄Plant Health Care (PHC)► warns FY-Dec rev flat to modest growth and FY24 rev c.28% lower than market expectations of $23m. Blames "lower levels of inventory being maintained by the Company's distributors and regulatory delays in some territories". USA weak. [SP=5.9 Cap=20m]
◄Science (SAG)► guides FY-Dec rev miss but adj op profit in line. Blames "global economic and geopolitical climate with investment by clients in consumer and industrial sectors". That's just about everything then. Cautious on the outlook for FY24. [SP=400 Cap=182m]
◄Accrol (ACRL)► guides FY-Apr adj EBITDA £21m+ cf F/C £20.5m. CItes strong margin recovery. Expects adj net debt close to 1x EBITDA by FY end. Certainly better than a poke with a shitty stick. I hold (ACRL, not the stick). [SP=29.6 Cap=94m]
◄SIgmaRoc (SRC)► monster €745m acquisition and placing. £200m placing at 47.5p, a 5% discount, to part finance buying lime biz from CRH. Classed at RTO. Suspension. [SP=50.2 Cap=348m]. I hold.
◄Quadrise (QED)► successful industrial demonstration test of MSAR and bioMSAR fuels at client's site in Morocco. Discussions for long-term commercial supply. [SP=1.17 Cap=18m]
In line: IDOX, GTLY
Good results and ahead exps outlook yesterday from Intercede (LON:IGP) is followed up today by a meaningful buy from the Chairman, 100k shares at 69.7p.
This is now a nice flurry of Director buying in 2023 and 2022.
Also note that the CEO seems to have exercised 620k options at 27p back in Sept 2022, but not sold any to pay the tax, which is a good sign I think. Nice to see management building up a meaningful stake with options (what they're designed for, not as a bonus to cash in immediately!) and market purchases.
Good morning Paul, I see that CEO and CFO are very well renumerated for such a small company and the more shares they buy the better-off they will become, the company is a desert for dividend-seekers like me so I do not and will hold.
ACRL putting out its market expectations at the bottom of the RNS so you don't have to go elsewhere to check. Would be great if this could catch on.
Interesting update from Sigmaroc (LON:SRC) - reverse takeover of significant lime companies from CRH (LON:CRH) - leading to 400m additional shares to raise £200m+. Earnings enhancing in first year and shares suspended today until the arrangement is approved at an EGM in mid-Dec
I have held Sigmaroc (LON:SRC) in the past and they are an aggressively acquisitive european wide buildings material company - and this will mean its share count rises to 1bn+ - up from a little over 100m in the last five or so years.
Very complex and no view, but interesting.
Interesting update from Sigmaroc (LON:SRC) - reverse takeover of significant lime companies from CRH (LON:CRH) - leading to 400m additional shares to raise £200m+
Always fun to watch the goings on here. But we’ve seen shares in issue increase tenfold while the price remains stuck at the same level. That’s why I like my buy and builds to fund from cash flows. I won’t be buying this company but will be interesting to see how the deal transforms operations.
"The Company is also seeking Shareholder approval to adopt a New Option Plan in order to incentivise the executives and senior management and align their interests with those of the Shareholders."
Because their salaries are not enough incentive to do their jobs. If they really want to allign their interests with shareholders they should be stumping up for their own shares and watching as the investment goes nowhere for years while the share count goes through the roof. It is us long suffering holders who need the incentive.
I thought yesterday's interview of Richard Staveley by Paul Hill was particularly excellent. Some great ideas discussed in a very clear and matter of fact manner. I especially liked the arguments for owning Pressure Technologies (LON:PRES) , M&C Saatchi (LON:SAA) James Fisher And Sons (LON:FSJ) and Restore (LON:RST). Thank you Mr Paul Hill for these fund manager interviews, they're great.
Many thanks Burnt Onions for the very kind words. Richard is front row box office
He is but you deserve a solid pat on the back for cutting to the chase and asking great direct questions, the questions that us fellow investors would like to ask but often don't have the opportunity to. Talking of which, next time you speak to him can you ask him about Pennant International (LON:PEN) ? He's bought 7.5% of the company but has so far kept in under wraps in interviews. Thanks again.
Burnt onions
Thanks for that I had missed the pennant investment
Looks a decent opportunity on first glance I’ll have a much closer look in next day or so .
Not a huge fan of sone of Rockwood current holdings so I always have a good look at what they are into and cherry pick accordingly .
Pennant looks very illiquid but good sector and seems close to the no brainer category provided you can cope with the illiquidity . Also going to be hard to build a good position unless one of the main funds holding is selling down (they were and that’s how Rockwood got their 7%)
Yes they are very helpful but all fund managers should be invited to provide an insight into their holdings.
The Interactive Investor channel over on Youtube regularly features fund managers to discuss their holdings, for those interested.
Seen them , but it’s different when they are interviewed by people that they actually know a couple of things about stocks and do invest themselves in the stock market!