Small Cap Value Report (Weds 23 August 2023) - CHRT, TRCS, ANX, COST, ANG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Cohort (LON:CHRT) (Paul holds) - 484p (pre market) £200m - Contract Win - Paul - GREEN
A contract win announcement doesn't move forecasts, but does provide an opportunity for me to review the numbers below, reiterating my positive view (that's why I bought some recently). High quality scores, a low valuation (fwd PER 13x), large order book giving high visibility, reasonable & well-covered divis, a strong balance sheet, and experienced management - what more could I ask for?!
Tracsis (LON:TRCS) - down 1.5% to 778p (£229m) - Trading Update (in line) - Graham - AMBER
This diversified group serving the rail and wider transport industries reports that FY July 2023 has finished in line with expectations. Growth in cash was held back by acquisition payments but those are now in the rear-view mirror. Seems to be fairly valued.
Anexo (LON:ANX) - Up 12%y’day to 67p (£79m) - Interim Results - Paul - RED
These numbers look uncannily similar to the disastrous Accident Exchange and Quindell - big profits, but little to no cash generation, due to gigantic receivables swallowing up arguably fictitious profits that don't turn into cash. Although to be fair, H1 2023 cashflow was better than in 2022. I'm very wary of this business model, explaining why in detail below, having seen it all before. Although it could be a trading punt for the brave!
Costain (LON:COST) - up 5% to 51p (£141m) - Results for six months to June 2023 (in line) - Graham - GREEN
I am obliged to go Green on this stock despite my distaste for low-margin contractor stocks. The company raised £100m in 2020 and currently has around £130m of net cash. It’s an accident-prone, risky business but at a PER of 4x I believe that it’s in value territory.
Angling Direct (LON:ANG) - up 3% to 39.5p (£31m) - H1 Trading Update (in line) - Paul - AMBER
An in line update, for negligible £0.9m aPBT expected for the full year. The £17m cash pile is the main attraction here. I think management needs to do something good with it - eg buy another complementary business, and scale things up. The current business model seems rather pointless, unless they can meaningfully improve profitability from a whisker above breakeven at present.
It's another quiet day for news, so hopefully we might cover one or two backlog items in addition to those below -
Paul’s Section:
Cohort (LON:CHRT) (Paul holds)
484p (pre market) £200m - Contract Win - Paul - GREEN
Cohort, the AIM-listed independent technology group, announces that its subsidiary Systems Engineering & Assessment Limited ("SEA") has been awarded a 32-month contract to the value of £17.5 million with a UK customer to provide an External Communications System (ECS) for a major defence programme. The ECS will provide enhanced real-time data exchange, critical information dissemination, and seamless co-ordination, significantly enhancing overall mission effectiveness.
Is it additional to forecasts? I’d guess probably not, judging from this bit -
"This contract is another significant win for SEA and will deliver essential communications capability to our customer's programme. It builds upon SEA's long-standing reputation and record of successful performance in this technology area. Together with other recent wins across the Group, this contract further underpins our order book and enhances the visibility of future revenues."
Paul’s opinion - I recently bought some Cohort shares after being impressed with its FY 4/2023 results (reviewed here on 19 July), and I interviewed its CEO here on 28 July, which I thought went very well, and gave me a better understanding of this collection of 6 defence-related businesses.
What I particularly like is - high quality measures, low PER (fwd: 13.3x), well covered divis yielding 3.1% (capable of paying more), sound balance sheet, and a large & growing order book giving great visibility. That’s pretty much exactly what I look for in any share! Add in experienced management with a long track record of sensible acquisitive growth.
Today’s contract win doesn’t sound as if it’s moved the forecasts, so must have been expected. This is now the 7th big contract win this year, the previous 6 are listed in a note available from Equity Development.
CHRT shares have dipped in the recent market sell-off, for no company-specific reason, so it’s now about 10% cheaper than the price I happily paid, so any further falls might induce me to top-up my position. We like bargains here! I think the risk of a profit warning should be quite low, since it has such good visibility from a large order book.
As you can see below, the track record is good, and this share is usually valued on a much higher PER than 13x currently. So I see this one as an opportunity. Today’s contract win was a good chance to review my position, and I’m happy to stay GREEN on it.

Anexo (LON:ANX)
Up 12%y’day to 67p (£79m) - Interim Results - Paul - RED
Anexo Group plc (AIM: ANX), the specialist integrated credit hire and legal services provider, is pleased to report its Interim Results for the six months ended 30 June 2023 ('H1 2023' or the 'period').
I normally avoid this share, as I’m not a fan of the ambulance-chasing legal services sector. There’s too much regulatory risk, spivvy operators, and often cripplingly large receivables books, which can hide a multitude of sins, as we saw with Quindell and Accident Exchange - both still marked on my memory. There have been other smaller operators in this sector that have also crashed and burned.
Although Redde Northgate (LON:REDD) is an exception, which broke the mould by working cooperatively with insurance companies, and has been a reliable, generous dividend payer since. Redde then lowered its sector risk by merging with van hire business Northgate. Actually, reviewing REDD’s StockReport, it looks cracking value currently on a forward PER of only 6.4x, and a lovely divi yield of 7.3%. That seems to me as if it might be coming into buying range again (lots of us did well on it here from buying the pandemic lows).
However, if the sector leader only commands a PER of 6.4x, then why go further down the food chain with Anexo?
Anyway, the 12% rise in Anexo shares yesterday compels me to take a fresh look.
Directorate change - a long-serving former CFO Mark Bringloe (cue: predictable jokes about his surname, and the share price), is returning as interim CFO.
Anexo Group plc (AIM: ANX), the specialist integrated credit hire and legal services provider, is pleased to report its Interim Results for the six months ended 30 June 2023 ('H1 2023' or the 'period').
"Significant revenue and profit growth with unchanged outlook for the year"
H1 revenue up 13% to £77.8m
H1 PBT up 12% to £15.2m
This is probably the worst sector imaginable for profit figures, which are sometimes meaningless. It’s cash collection & receivables that give us the true picture.
Outlook - in line -
The focus in the first half of 2023 has been firmly on the conversion of profits to operating cash flows. The Group has shown robust growth during the period and plans to continue to optimise cash generation in the second half, whilst increasing activity levels within the Credit Hire division to levels previously seen in the first half of 2022.
Growth in cash collections allows the Group to increase activity, including continued investment in HDR [Paul: housing disrepair] and additional emissions claims, without the need for increases in net debt. The focus for the second half is to ensure this investment is self-funded. Management has confidence in meeting market expectations for the year.
Balance sheet - the most important bit for me.
Oh my giddy aunt! It has receivables of £233.5m! That’s equivalent to 18-months revenues that haven’t turned into cash.
This is mainly funded by equity, with NTAV of £155m. Clearly the market doesn’t have confidence in these figures, with a market cap of only £79m, and nor do I.
Look at the huge impairments already booked against receivables. How do we know if these are adequate? Some of these claims could be worthless.
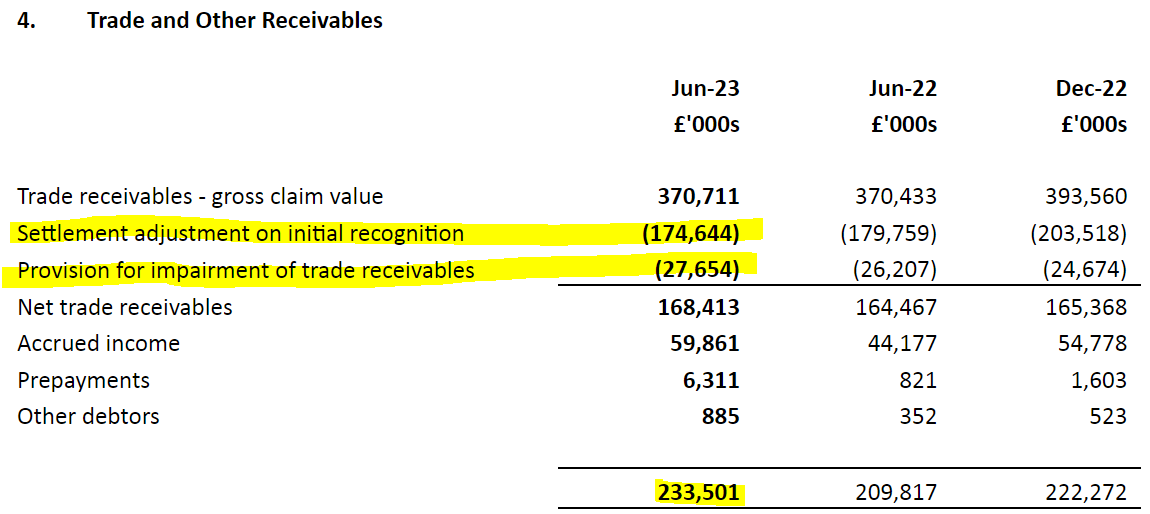
There’s £7.4m in cash, and £58m in interest-bearing debt (excl. lease liabilities). See note 5 for details on the various loan facilities (RCF £10m, invoice discounting £25m, and others, some of which are expensive). I can see why they want to generate cash to pay down debt, as it looks a little stretched.
Cashflow statement - the numbers at the top for cash generation look large (£23.9m in H1 this year, and £40.8m for FY 12/2022), but follow the figures down, and it almost all disappears - e.g. £34.1m consumed in 2022 by increased receivables. That’s a classic warning sign in this sector, and these numbers remind me very much of Accident Exchange, which was a disaster for shareholders. It kept reporting big profits, none of which turned into cash, and in the end it ran out of money & got taken out for peanuts by a big US financial firm. It looked dirt cheap all the way down to close to zero, as problem companies often do.
Note also that in H1 2023 the trade payables increased by £7.1m, helping cash generation, and to be fair, the increase in receivables in H1 2023 was less than in 2022, at £11.2m.
So we get to £19.8m cash generated from operations in H1 2023.
After that, there’s a hefty £4.1m in interest paid, £5.3m in lease payments, £1.8m in divis paid, negligible capex, and a net £10m of loans repaid.
Simplifying it then, it generated cash of about £10m in H1 after finance/lease costs, which was used to reduce borrowings. Not too bad I’d say, but the real test will come in future, whether the horrendously high receivables can turn into cash, or whether in reality the figures would have to be massively discounted to persuade insurers to pay up.
This is reminding me so much of Accident Exchange and Quindell, it’s uncanny.
Paul’s opinion - I’ve seen enough to know that this is a bargepole job for me. Credit hire only works well if it’s done the way Redde does it, with modest receivables, by agreeing reasonable terms with insurers that they’re happy to pay.
Anexo seems to be jumping on other compensation bandwagons, like the emissions compensation, and now defective housing.
The fundamental (and big) problem with this business model, is that it’s incurring costs up-front, and over an extended period whilst cases are developed, then eventually (18 months later it seems) insurers might pay up, which often requires a negotiation and discount offered by the claims company to settle. Insurers have deeper pockets than the claims company, and they can (and have) driven some out of business by doing nothing, and waiting for the claims company to run out of cash.
The figures are very much deja vue for me, re Accident Exchange and Quindell, both of which ended really badly. Although Quindell managed to stuff some gullible Australian legal firm (Slater & Gordon) into a wildly overpriced takeover bid, which later destroyed almost all of S+G’s shareholder value, with it eventually delisting from the Australian market.
Who knows what is going to happen with Anexo’s share price?
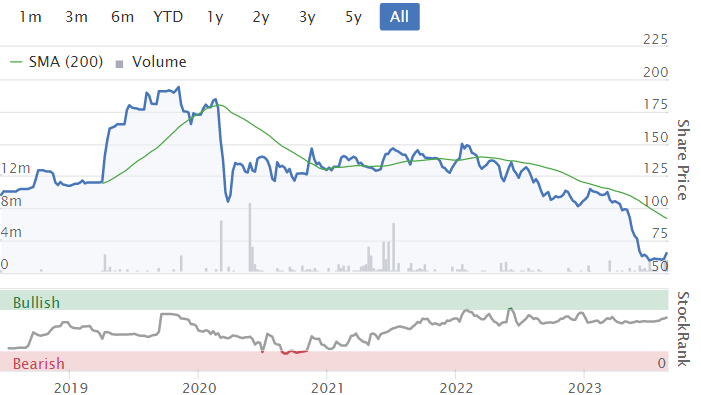
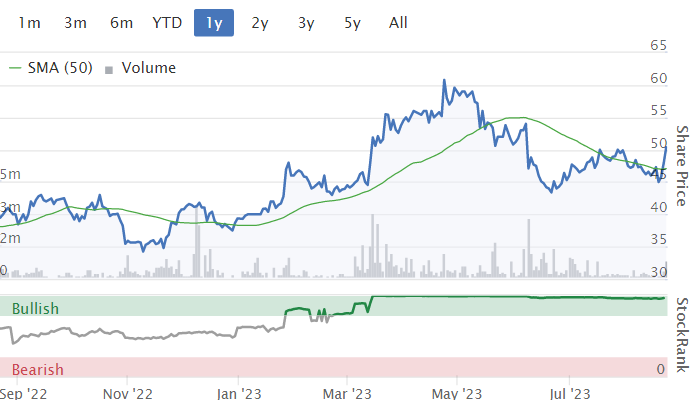
The chart below is looking tempting as a trading punt, for a rebound. But the fundamentals of the business look terrible to me, and I’d be pretty confident that the end game for Anexo is not likely to be positive, mainly because the profits aren’t real, if they don’t turn into cash.
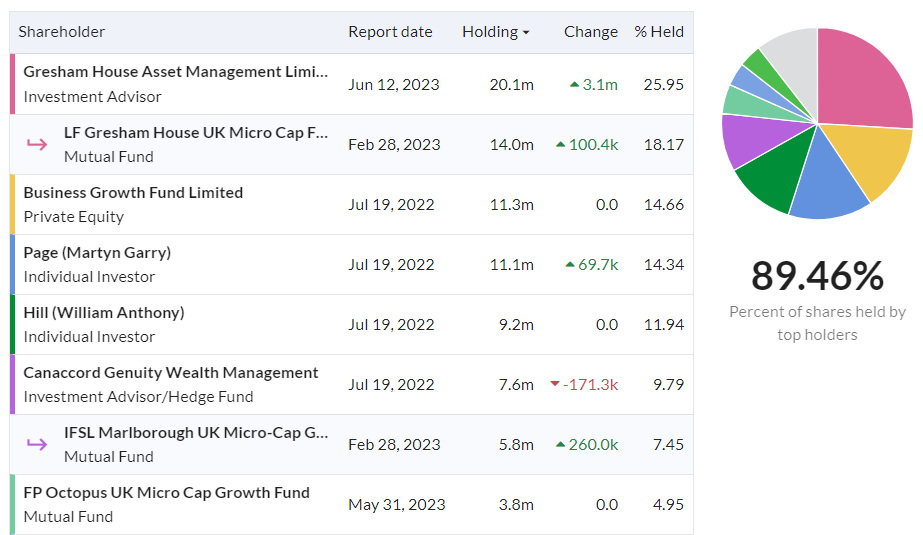
The shareholding structure is highly concentrated, with 3 big holders.
For me, this is a definite avoid, so it’s RED. But good luck to any traders who have a punt on it, the share prices of these things can go all over the place, and many investors don’t even look at the balance sheet, just relying on (artificial) profit numbers. That can work well for a while. I remember Quindell became almost a personality cult of the CEO Rob Terry. I could see it for what it was, and wrote dozens of negative pieces about it here, pointing out all the holes in the accounts, and got a lot of abuse over it, but I was proven correct in the end. Accident Exchange I’m afraid was a less happy tale, where I bought into the CEO’s bullishness, even visiting its HQ - never again! That was an expensive lesson, but it’s seared on my memory, which is a good thing, as I’ll never go near any similar business again. Anexo looks very similar.

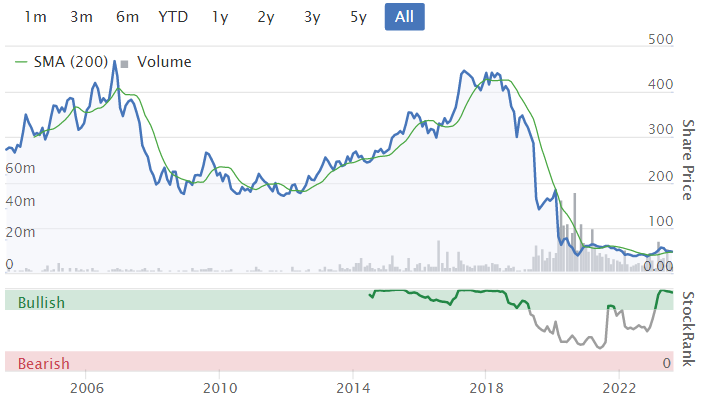
Here's the chart since it listed. It seems to have only paid 6p in total divis since listing - that's because it doesn't generate any cash!
Angling Direct (LON:ANG)
Up 3% to 39.5p (£31m) - H1 Trading Update (in line) - Paul - AMBER
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides an update on trading for the six months ended 31 July 2023 ('H1 24').
H1 revenues up 11%
LFL (like-for-like) store sales up 4.9% - not bad, but that’s below both inflation and likely pay rises for staff, I imagine.
2 new stores, now operating 47 in the UK.
European online sales still very small, but growing well, especially in Germany.
Net cash of £17.6m, up slightly, which is equivalent to 57% of the market cap - the main reason to own this share, I suggest!
Outlook/guidance -
Overall the Board is confident that a combination of continuing UK sales momentum with balancing European growth and profitability means that the Group is well placed to deliver revenue and Pre IFRS 16 EBITDA in line with full year market expectations."*
*Angling Direct believes that market expectations for the year ending 31 January 2024 prior to this announcement were revenue of £83.0 million and pre-IFRS 16 EBITDA of £2.7 million.
Paul’s opinion - as I’ve pointed out before, the EBITDA figures are not a good measure.
Many thanks to Singers, whose update note today shows £2.7m EBITDA turns into £0.9m adj PBT - just above breakeven really, on revenues of £83m. So not a very good business model really. Why keep opening more stores, when they don’t generate any meaningful profit?
I imagine maybe half that modest profit might come from interest receivable on the cash pile?
The main attraction of this share is the net cash pile. What mgt eventually do with it, is key to whether there’s going to be any shareholder value created here.
I was bullish on this share, when it was 25p, as the cash pile supported pretty much the entire market cap. Now it’s risen a fair bit, I don’t see it as such good value, so it’s quite tempting to bank the profits. Upside would need to come from a meaningful improvement in profitability I think.
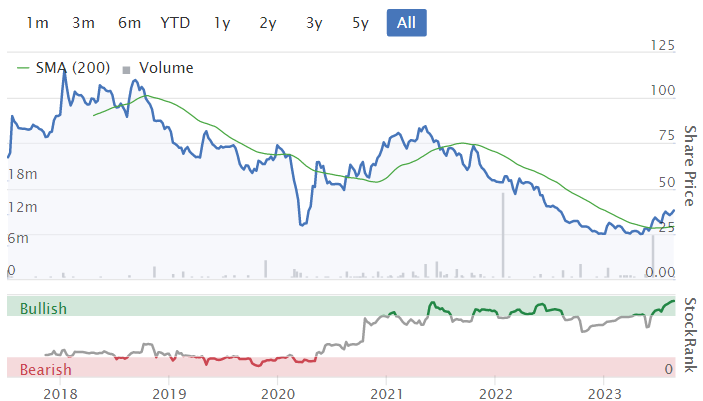
Checking out the major shareholders, I imagine the big holders might be pushing for something to be done - a sale, or merger of some kind maybe, to crystallise shareholder value? So something could happen here, in terms of corporate actions. Hopefully not a de-listing though - it seems pointless being listed when this small, and with such a small free float. So maybe an opportunity, or a risk here?
Graham’s Section:
Tracsis (LON:TRCS)
Share price: 778p (-1.5%)
Market cap: £229m
This is an “in line with expectations” trading update for FY July 2023.
Description: Tracsis is “a leading provider of software, hardware, data analytics/GIS (geographic information systems) and services for the rail, traffic data and wider transport industries”.

Highlights:
Revenue +19% to £81.5m
Adjusted EBITDA c. £16m (last year: £14.2m)
Cash c. £15.3m (last year: £17.2m) after paying £9.5m of contingent/deferred acquisition payments during the year. “All material earn-outs have now been paid.”
The company signals an intention to get back on the acquisition trail, now that the payments for historic acquisitions are largely complete.
Rail Technology and Services Division: strong UK growth with large multi-year SaaS contracts for train operators and Network Rail, and strong North American growth “driven by the US Government’s infrastructure spending bill”.
Data, Analytics, Consultancy and Events Division: revenue growth ahead of expectations. There has been a “very strong post Covid lockdown recovery in the Events and Traffic Data businesses”.
Outlook - there is no specific “outlook” section, but the final paragraph says the following:
In order to continue providing a solid platform for ongoing scalable growth, the Group has continued to integrate its activities, technologies and operating model. Alongside this, technology investment has increased to accelerate future growth which will continue through the forthcoming financial year. As a Group we expect the weighting of growth to be in the second half of the next financial year as we continue to grow our pipeline and deliver a large orderbook of work.
Graham’s view
When Roland covered this one in detail in April, it was trading at 24x earnings.
Similarly, when Paul looked at it in February, it was trading at 25.5x.
With the marching of time, we can now use the (higher) FY 2024 earnings forecast as the basis for this multiple.
Also, the share price has drifted lower, like so many other stocks in our universe.
So it’s now back at a cooler valuation:

Profit growth has been uneven but the overall record here is decent and I think I can see why investors might want to give it a punchy rating. The company’s acquisition process seems to be working well. At this valuation I’m neutral.
Costain (LON:COST)
Share price: 49.86p (+4%)
Market cap: £138m
This contractor publishes H1 results:
Revenues down slightly to £664m
Adjusted operating profit £15m (last year: £14m)
Reported operating profit £7.6m (last year: £11.9m), “reflecting costs of repositioning digital services towards growth and our Transformation programme”.
The “Transformation programme” is both credited with increasing the company’s adjusted profits and blamed for reducing its actual profits!
Note the extremely low margins (c. 1% operating margin for Costain this year) - this is why I avoid this sector.
However, Costain is special because of its balance sheet: it has net cash of £132m.
Almost any business can be a value investment if it can be bought at a discount to net cash, and that is almost the case here.
The company raised £100m in early 2020, after suffering problems with a range of contracts.
Let’s scroll straight down to Costain’s balance sheet and see how it’s holding up currently.
Total equity: £210m
Tangible equity: £163m
Working capital: £72m
There is a pension scheme to be aware of - and there was good news about reduced deficit recovery payments last month, discussed by Paul here.
And the wealth isn’t locked up inside the company: Costain has a history of making dividend payments, and is planning to pay them again soon.

The risk, of course, is that the company gets into serious contract difficulties again.
The order book currently stands at £2.5 billion, down from £2.7 billion year-on-year. The company expects awards to be made later this year on “the very high level of bids undertaken in H1 2022”.
Outlook: trading is in line, with a strong pipeline.
We remain mindful of the macro-economic and geopolitical backdrop, recognising the challenges it has created for inflation and energy costs, and its impact on the rephasing and rescoping of some major contracts, in particular in Transportation…
…we remain on track to deliver an adjusted operating margin run-rate of 3.5% during the course of FY 24 and 4.5% during the course of FY 25; in line with our ambition to deliver margins in excess of 5%.
Graham’s view
It’s not a sector that I like to go fishing in but I can see the argument that this one is simply too cheap at this level. We have a very cheap earnings multiple and a rich balance sheet. It’s not often that you get both.

I think I’ll have to go Green on this for the simple reason that a market cap any lower than this would strike me as just plain unreasonable. It’s already trading at 4x earnings (and the “target P/E” on forward earnings, according to the broker, is only 2.3x!). It’s already trading around the value of its net cash balance. It’s almost certainly a poor-quality and risky enterprise but those features seem to be priced in at these levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Note to self ... esp. wrt to Anexo (LON:ANX) ... always check SCVR to see if there are red flags that Paul highlights. And check on freecashflow yield. Despite booking £19.5m as net profit for 2022, the free cashflow has been negative for at least the last 6 years.
Perhaps another tip-off is that although revenues and profits have been rising steadily, the Stockopedia momentum score is red.
Mark,
I find that Paul's spreadsheet is a very quick and easy way to get to a summary of SCVR write ups.
Thanks WarrantStar - that's exactly why I spend a couple of hours every weekend doing the podcasts, and updating the fecking spreadsheet! LO ;-)
Anexo ANX I had a quick look at this yesterday as it looked so cheap. I decided I didn't understand what they actually did but I did wonder if they were a beneficiary of the closer scrutiny on housing conditions after deaths caused (apparently) by fungi in dilapidated properties. I also noticed that Gresham House and one or two other reasonably sensible (one hopes) institutions had decent positions. Paul has, however, been very good on identifying basket cases a number of which I have owned and occasionally lost a shirt or two on despite his warnings. One of the big investing lessons is cutting or avoiding losses. Sleeping at night is actually pretty important.
Anexo could go up, it could go down. But it's fundamentally shit. Same as Quindell, ACE, and all of them.
Is fundamentally shit a technical term? Lol
Graham - thanks for your report on Costain (LON:COST) . You say "The risk, of course, is that the company gets into serious contract difficulties again" and later describe the company as risky.
There is risk in any company but, as you say, COST got into very serious problems with the A465 Heads of the Valleys road in S. Wales and the Peterborough and Huntington compressor upgrades for National Grid. As a result the a/cs to 30/6/20 took an exceptional loss of £94.7m. Lesson learned - from that point on in the presentations I have watched there has been reference to the new risk management culture as in this slide on that half year:
For the half year reported today there is a presentation on IMC tomorrow at 10.00 or this morning to analysts recording here: https://stream.brrmedia.co.uk/... from which:
The snag is that lots of construction and financial firms in particular talk about their risk management controls, but as an outsider it's almost impossible to gauge :-(
Thanks for the chart - very useful and some fair points.
I think Sandy giving some of his salary away to his team is good leadership. I am sure the junior ranks at Supreme only earn £20-30k so its a sign of a good leader when he is prepared to help them out in tough times, in my humble opinion. You can bet his team think Sandy is a great boss and will put in even more effort!
Civil contractors like Costain (LON:COST) always operate on slender margins but they rely on their ability to turn cash over using stage payments. Contracts are normally paid on monthly valuations not when the job is finished (depending on the contract terms and subject to retentions) so ROCE becomes more relevant to these type of companies.
Cohort (LON:CHRT) (I Hold)
I added Cohort to my portfolio shortly after reading Richard Beddard’s analysis and addition to his Share Sleuth portfolio. Some of the bull and bear points in my personal opinion,
Bear points:
Bull points :
2016:
2023:
Paul - Thanks for sharing the interview with the CEO.
Cheers
Nesh
Also big orders need to repeat or be replaced, otherwise the business shrinks when they finish. It always amazes me how many businesses talk retrospectively about 'legacy' and 'one-off' orders or pieces of business but never flag them ahead of time. It can really screw up forecasts of future sales/profits. This isn't a reflection on cohort (I haven't looked at it) but is a general comment.
Paul - Thanks for sharing the interview with the CEO.
My pleasure. I was impressed after talking to the CEO at Cohort (LON:CHRT) - I've bought some, and will just wait to see what happens in the next few years. It looks pretty good to me, but time will tell.
Supreme (LON:SUP) annual report released today after prelims a few weeks back. Chart seems to be moving up nicely again. I hold.
All credit to Sandy Chadha as you don't see this at many plcs; maybe a lesson for some FTSE-100 bosses!
"Annual base salary for Sandy Chadha was £287,500 and Suzanne Smith was £175,000. Sandy Chadha agreed to formally waive his salary entitlement for the last 6 months of the year, by way of a legally binding agreement, in order to finance the accelerated and increased pay-rises to support the wider workforce in response to the cost of living crisis."
Cohort (LON:CHRT) announcement looked really good as Paul mentions. Quality company. Still haven't got round to buying shares in it, but should have done!
“Sandy Chadha agreed to formally waive his salary entitlement for the last 6 months of the year, by way of a legally binding agreement, in order to finance the accelerated and increased pay-rises to support the wider workforce in response to the cost of living crisis."
Maybe he could give the other half to help charities and health services dealing with nicotine addiction in young children. Or to local authorities to help clean up discarded disposable vapes and recover the battery minerals so acutely required for the energy transition.
"Maybe he could give the other half to help charities and health services dealing with nicotine addiction in young children. Or to local authorities to help clean up discarded disposable vapes and recover the battery minerals so acutely required for the energy transition."
Supreme (LON:SUP) isnt for me but that's like expecting the CEO of a drinks company or Tesco to give half his salary to charity because of alcohol addiction. He's not doing anything illegal so why should he.
One of the better looking charts out there. Potentially start of stage 2. Just missing volume.
You can’t compare Chadha to a hired gun at a big drinks plc. Sandy is Supreme!
I agree with what Paul says about Cohort (LON:CHRT) but I recently opened a position in Qinetiq (LON:QQ.) . The valuation metrics look better there, although they do have to bed in a large US acquisition. Just thought you might be interested.
Good morning Paul and Graham,
Tracsis appears to be making consistent progress in spite of train strikes and National Rail's slow reincarnation, both here and in North America. Your thoughts would be appreciated, if you have time.
Hedgecutter, I agree Tracsis (LON:TRCS) does seem to be continuing on with its growth story.
The Trading Update looks like a beat against Stockopedia data for FY23, on the top line revenue at least:
The TRCS StockReport shows a forecast £77.3m in revenue and net profit of £9.8m for FY23, so a comfortable beat on the sales side. Now they only tell us the adjusted EBITDA figure and not net profit, and we saw last year that the £14.2m reduced to a profit after tax figure of £1.5m , and we may not see much improvement on that as they also tell us that £9.5m was paid out in the year relating to contingent and deferred consideration "that was consistent with expectations and aligned to strong performance from historic acquisitions". Presumably this relates to five earlier transactions, being RailComm, Compass, Bellvedi, iBlocks and The Icon Group (£9.3m noted as contingent consideration in last year's annual report).
It still leaves them with a year-end cash balance of £15.3m though, so enough to fund their activities, small dividend, and possibly further acquisitions.
Looking back I see I've now held my TRCS shares for just over 10 years, and I've no intention to reduce just yet. Hopefully the growth story will accelerate as they grow in North America, and also secure more contracts from the UK government's 'Great British Railways' restructure. Fingers-crossed!
Thanks for your thoughtful comments strollingmolby.
Tracsis is one of my losers so far, but railways still have huge untapped potential and the company is at the leading edge of making it more efficient and profitable and easier to use and operate in two of the major railway countries of the world.
Not quite a small cap, but NVIDIA (NSQ:NVDA) (I hold) announce q2 earnings today.
This could be consequential for general market sentiment, so worth keeping an eye on.
Value rank is 0, so the sp bakes in continued strong performance, but several brokers have upped their targets well beyond the current level.
Any kind of miss on q2 or less-than-bullish outlook could trigger a sell-off.
Good results from Costain (LON:COST) this morning. Net cash now £132.1m and MCap given by Stocko £132.5m so the business is almost in for free!
Margins have been a problem in this business and the current management have set out to improve this. In the outlook statement they say "...we remain on track to deliver an adjusted operating margin run-rate of 3.5% during the course of FY 24 and 4.5% during the course of FY 25; in line with our ambition to deliver margins in excess of 5%".
The pension review gives a significant drop in future contributions:
The new contribution plan from the Group to the Costain Pension Scheme runs from 1 July 2023 to 31 March 2027 and is for a payment of £3.3m per year, payable in pro rata monthly instalments, which will increase in line with inflation (CPI) each 1 April. This replaces the previous contribution plan to the Scheme, which from April 2023 had increased to an annual payment of £11.98m paid in monthly instalments.
Even before these results:
Agreed. NVIDIA (NSQ:NVDA) is the market leader, but I do think it might be the Cisco Systems (NSQ:CSCO) equivalent of this boom. There are going to be lots of companies using AI who end up doing much better. The valuation is ridiculous, but that doesn't mean it can't double from here.
Hi sharw,
I don't know Costain (LON:COST) 's position in particular, but pretty much like all construction companies, I'd bet that not all of that £132m belongs to Costain. Some of it (maybe a large amount of it) will be made up of money paid up-front by clients, and money withheld from suppliers.
So if Costain (LON:COST) was liquidated tomorrow, this £132m wouldn't be available for distribution to shareholders, and you can't knock it all off for valuation purposes. Notes to the accounts might make this clearer.
Cheers
Chris
Costain (LON:COST)
Chrisfarrell21
I don't know Costain (LON:COST) 's position in particular, but pretty much like all construction companies, I'd bet that not all of that £132m belongs to Costain.
Well said Chris ignoring payables really is pretty poor when it comes to trumpeting the fact that the cash is theirs - if there are payables (232 mill here !!) then the cash most certainly isnt theirs (shareholders) to do with what they want and that cash often need to be there so that their suppliers have confidence to give them credit!!
I have looked at the annual report in that regard - there is 232 million owed out in current trade and other payables (leases ignored !). So in some respects the company only has half the cash it owes out to suppliers and the like !!!!!.
In fairness to the company and sharw the company has approx £190 of receivables owed in - so practicably speaking a decent % of whats owed out is covered by whats owed in and the company has very decent % of its market cap as tangible net asset value - so useful highlight by sharw.
Note ref investing risks then higher these numbers are compared to profits (amounts owed out and owed in) - the more risk we are taking that in a crunch they might have to do a material w/off of receivables and also have extra liabilities appear at a whim not previously provided for on payables side (construction often works on application for payment basis which leaves room for dodgy stuff)- i would say a very high % of similar companies that have bene listed with such high amounts owed out have come a cropper at some stage or another particualrly if contruction and or long servicing contarcts are involved ! - would love to see analysis of how much 50 of thn best knoiw listed names doing stuff like that have managed over past 20 years - i would suspect returns are dreadful unless one is very astute at heading for the exit before times ever get bad !
Normal sub contract conditions are that the main contractor, ie Costain, pays the subbie one month after client payment is received, although there have been many main contractors who deliberately flout those terms. In Costain's results they owe £50m more than they are owed, so I would think most of that is payments due to subbies. This is fine if your turnover in construction contracts is at least stable or preferably growing, but if, for example, Costain's move into more of a consulting role from construction grew substantially that back log of subbie payment would come out of the company's cash balance. I don't see that as happening in short order and therefore am hanging on waiting for better times.
Well quite, but there's often a big time imbalance as well, which can a create a huge benefit in Costain's favour; i.e. the client pays after 28 / 30 days max., but then Costain doesn't pay the subbie for 45-90 days (depending on the type of supplier and relationship). Just before Carillion went bust, they wrote to subbies unilaterally extending payment periods to (I think) over 100 days to try and eke out some financial advantage.
The other factor from this now is that Carillion can make good money (at a considerably better margin than its actual main business of building stuff) from just holding on to other people's money for as long as it can. 3-5% on £130m is not a bad little side hustle, when your operating margin hovers around 1%.
Cheers
Chris
Hi Chris
love the way you casually call Costain (LON:COST) Carillon in your response…obviously a non Freudian slip…..or was it…
For any Costain lawyers who may review this site ... it was totally accidental :p
Costain (LON:COST)
Well quite, but there's often a big time imbalance as well, which can a create a huge benefit in Costain's favour; i.e. the client pays after 28 / 30 days max., but then Costain doesn't pay the subbie for 45-90 days
Being frank any company employing such tactics may be morally bankrupt (some caveats below) - for exactly the reasons laid out as to what happened with Carillon. I think there has been movement the last few years to guide companies like Costain to act ethically and reasonably with regard to small subcontractors - if they aren't it aint good clever or something that should exist (IMHO). Hopefully Costain are of the ethical variety and pay as agreed and to reasonable payment terms. Note things can be run ethically and the business can probably still run with more owed out than owed in (as the case is here) as they could be taking deposits - or have fair and reasonable reasons for witholding paymets. If there are any complaints from subbies about not being paid on time f that would be a red flag (if they mess supliers around they will no doubt happily shaft shareholders)- hopefully they are one of the good ones here . Poor treatment of subcontractors used to be be endemic at listed housebuilders - not sure if things are much better now , i still suspect its all still slightly spivvy type activities going on to hit targets for one reason or another. If costain is squeeky clean here that would make me much mote comfortable investing. IMHO things work much better in this kind of industry when end client middle man and subcontract workers are all colaborating and trying to not screw each other over.
Sorry Chris, I don't quite understand your post. Sub contract conditions are normally based on standard forms which can occasionally be amended by agreement before a sub contract is let, but then they are "enforceable". During my time representing a normally quite critical subbie, if I was about to sign up to a new project with a contractor I didn't know well, I often made the statement that failure to honour the sub contract payment timing provisions (and a couple of other terms) would be regarded as a fundamental breach of contract entitling us to stop work etc. Most of the main contractors expressed shock at that statement, real or unreal I don't know, but it served its purpose.
The timetable was normally that the subbie "measured" his work to a date agreed before contract placing, which would on big complicated jobs be up to a week before the main contractor's date for measurement with the client. The main contractor then completed his measurement and submitted his valuation incorporating the subbie's, and perhaps the bit not yet billed by the subbie, to the client asap, usually within a few days. The client then went through the valuation and certified whatever they believe to be a reasonable valuation again usually within a week, and payment was then due to the main contractor within 30 days, followed by the MC paying the subbie within a further 30 days. This means that from submission of his valuation the subbie waits for something like 75 days for payment, but the economic advantage to Costain is 30 days of subbie cash in the bank, and perhaps 100 days for the subbies work in that part of the month measured by Costain after submission of the Subbie' valuation. Most subbies who have a good relationship with the main contractor overcome that "early valuation" anomaly.
What you are suggesting as a source of better margin is the practise that the government is trying ineffectually to stamp out - not paying on time, whereas Costain are proudly saying that they adhere to contract payment terms, which very much enhances their relationship with subbies, without whom they would be in deep trouble.
Hi, no I'm not saying they don't pay by the contractually agreed timescale, just that they agree longer contractual timescales in the subcontracts / supply agreements, compared to their client contract.
Govt. are making an effort to force main contractors to pay within specific, shorter time periods, but some govt. contracts with main contractors have horribly long payment terms themselves, so there is no incentive in those situations to shorten them with your supply chain. It depends on the type of work and project and which part of government is tendering the work, but then govt. can by a bunch of hypocrites at times (no!).
If main contract project payments are milestone based, which a lot of big ones are, then the subbie payment terms can vary wildly, depending on the relationship between the parties.
Cheers
Chris
You have to wonder, in a world where when I pay for something with my card it appears on my bank account within seconds what the justification for creditors hanging onto cash for even 30 days. Very handy for the clients and main contractor etc, and I can understand why they would resist change, but no excuse I can see for not phasing it out.
Costain (LON:COST) do seem to be foreshadowing a cash outflow in H2 https://www.costain.com/media/...
The frightening thing is that, even with competitors like Carillion being taken out of the market, the main contractors' margin remains no better than 1 or 2%.
Good morning Paul
Is there any chance you could glance an eye over the Costain results please?
Morning oliver,
You've got 13 thumbs for your request for Costain, so we'll make sure we cover that one today.
Regards, Paul.
Thank you much appreciated.
Market sentiment and mood is relentless low, but there is plenty of value around.
Will things become cheaper? At some point doubtless some will, but who can predict?
I sense those investing now won't suffer buyers' remorse 3 years hence . . . . . . . . Now what to buy?
I'm having FOMO on a number of stocks but don't have the 500k I need to invest in every idea.... so I end up just doing nothing, which I will regret
Over time I've lost more money being out of the market than being invested in it
Today (and for a while now) I'm pretty fully invested. Lots of great opps IMO. It means I've had to cull or reduce some positions to build the ones I want most which always feels a bit rubbish. Full investment makes me very uncomfortable but its the right thing to do when doubt and fear has prevailed so strongly. Things may go down more obvs...or a negative surprise is possible. I can't see the future. I always look 3+ years and try not be overly reactive to current sentiment
You could probably size a bit below £500k per position to solve that problem ;)
I'm having a busy summer with travel and a venture so not looking at blow by blow market stuff...my semi-detached perspective is I think things have picked up in that the relentless liquidity drain is over. Speculative/spiv cos still being taken out and shot obvs...so if one has a penchant for the occasional financially flaky and/or moonshot company the going can get rough with them (I've got some that I think are the right side of speculation...but if I'm wrong I'll get my head beaten in on them!)
My morning smallcap tweet: Tiny issue
Bivictrix Therapeutics (LON:BVX) Cohort (LON:CHRT), Angling Direct (LON:ANG), Tracsis (LON:TRCS), Costain (LON:COST)
◄BiVictriX Therapeutics (BVX)► get US patent providing broad protection for BVX001. [SP=12.5 Cap=10m]
◄Cohort (CHRT)► wins 32-month UK contract worth £17.5m to provide an External Communications System for a major defence programme. [SP=484.5 Cap=201m]
In line: ANG, TRCS, COST
Thanks for this - I know you do it every day - but it's very much valued.
Yes enormously valued my many of us, and the occasional pithy remark enjoyed in particular