Small Cap Value Report (Weds 23 Nov 2022) - KGH, IGP, CML, FNX, BOTB, DPEU, DIA, ABDP, ACSO

Good morning from Paul & Graham. We're off to a flying start today, with some comments left over from yesterday's news. Today's report is now finished. I'm halfway through DLAR, so will finish that in tomorrow's report.
Agenda
Paul's Section:
Knights group (LON:KGH) [quick comment] - an honourable mention for TheFloatingInvestor who flagged up here in yesterday’s reader comments that the CEO of KGH just spent £1m buying shares at 83.9p. (Although context is that he banked £61m in Jan 2021 selling at 390p!). He’s already got 20.7% before this transaction, so seems well-aligned. Yesterday’s TU looks pretty good to me - H1 in line, and outlook sounds upbeat. I won’t have time to dig deeper, but want to flag this as something readers might want to assess more carefully. The forecast PER looks super-low, and the CEO splashing the cash in a meaningful way, makes me think this could be a buying opportunity perhaps? DYOR as usual though please. [no section below]
Intercede (LON:IGP) [quick comment] - Interim numbers look good to me. Note there’s a big benefit from the negative tax charge (R&D credits possibly?), so it made £1.2m PAT for H1- good profit growth. IGP should have benefited from the strong dollar, as its customers are mainly in the USA. £10m net cash is more than healthy. £32m mkt cap doesn’t strike me as excessive. H2 outlook is in line with expectations. I’d like to see faster organic growth, which is the main reason my interest has waned a little recently. It’s fundamentally a very sound company in my view. The jury’s out on whether it can accelerate growth into something more exciting. [no section below]
CML Microsystems (LON:CML) - more detail below. Good interim numbers, and a substantial increase in broker forecasts. Management tantalise us with vague outlook comments, but conclude that they see a "very positive outcome" for FY 3/2023. There's also the matter of a net cash pile about a third of the market cap, and surplus freehold property. All in all, this looks very interesting now I think, hence will include it as a mystery share (i.e. one of the best shares of the week) in this week's podcast.
Fonix Mobile (LON:FNX) [quick comment] - a rare thing this one - a fairly recent float (Oct 2020) that hasn’t collapsed in price! Yesterday’s AGM trading update said it has started FY 6/2023 positively, in line with expectations. It’s planning growth from new products, and internationally, and mentions a “growing pipeline of client prospects”, and is “confident in the growth potential”. This looks an impressive company, and has very sticky clients. Paying decent divis too. Thumbs up from me. [no section below].
Best Of The Best (LON:BOTB) [quick comment] - says today that H1 trading (May-Oct 2022) is in line with market expectations for FY 4/2023. Negotiations with Teddy Sagi’s investment company (Globe Invest Ltd) seem to be dragging on. Putting aside the disappointments of the past, I think the valuation is looking potentially attractive again. A fwd PER of only 7.2 could provide good upside, especially now that online advertising is probably getting cheaper again. There's also the potential for international growth via Globe Invest's involvement (29.9% shareholder). Worth revisiting perhaps? Disclosure - I have a tiny holding in this, but not of any significance. [no section below].
accesso Technology (LON:ACSO) [quick comment] - a positive trading update has just come through: strong trading ahead of expectations. Revenues now expected to be $138m+ for FY 12/2022 (the StockReport shows consensus at $135m, so a slight rev beat). Favourable margin mix, and cost savings. Cash EBITDA margin now 17%+. I'm not sure how that translates into actual profit, they don't say. Looks like this could be worth closer inspection, I don't have enough information to draw a firm conclusion, but this update is clearly good news.
Graham's Section:
DP Eurasia NV (LON:DPEU) (£58.5 million) - another mixed update for its investors from DPEU. Guidance is unchanged and the company did make an operating profit in H1 of this year, so things could be worse. But this ten-month update shows unimpressive like-for-like sales trends, and it’s impossible not to be nervous about this stock given the economic conditions in Turkey and the political conditions in Russia. It also needs to deleverage its balance sheet quickly, as a Russian bank recently needed to give it a covenant waiver. This stock remains extremely high-risk though it is still showing some signs of life.
Dialight (LON:DIA) (£96m) (-5%) [no section below] - the “global leader in LED lighting for heavy industrial applications” confirms that expectations for 2022 are unchanged. Revenues are up 23% at constant currency (up 30% in pounds). The Lighting division has outperformed Signals and Components, where Q4 orders reflect “the softer worldwide demand in the opto-electronic market”. Input cost inflation is mitigated by sales price increases and operating leverage.
The main trading currency (around 80% of revenues, I believe) is USD; this explains why the reported sales increase (30%) is so much higher than gains at constant currency (23%). Dialight has now converted its RCF from pounds to dollars. This appears to be a smart move - it means better alignment with their underlying business, and they are effectively cashing in their gains from borrowing in a weaker currency. Net debt remains around £20m and this should not be onerous if they hit targets. I’m neutral on this stock as I don’t know how to assess their competitive advantages, and profit margins (gross, operating) don’t stand out. The stock gets a QualityRank of 76 which feels generous.
Ab Dynamics (LON:ABDP) (£365m) (-0.5%) [no section below] - It was a record year at this transport testing and simulation company. FY August 2022 results show revenues of £80m (+23%, mostly organic growth), and there’s a small improvement in gross margin. Adjusted operating profit grows at a quieter pace (+18%) to £12.7m, due to investment spending at ABD Solutions, and the statutory operating profit is much lower at just £5.2m. The company acknowledges that 2021 was impacted by Covid, making the prior-year results much easier to beat.
I continue to maintain a positive view on this business while remaining unsure about how to justify the 32x earnings multiple it carries. Expectations for FY August 2023 are unchanged, the full-year dividend has increased, cash conversion is good, the balance sheet is strong, acquisitions are going well (with more to come), and 41% of revenues are now recurring in nature. Fans of this business are likely to remain involved and remain interested.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
CML Microsystems (LON:CML)
436p (up 6% at y’day’s close)
Market cap £69m
We last looked at CML here on 28 Sept 2022, when it issued an ahead of expectations update for H1 (to Sept 2022). It’s an unusual share, where a good part of the valuation rests on its surplus cash & property assets, which I covered here in Aug 2022.
Today we have -
CML Microsystems Plc which develops mixed-signal, RF and microwave semiconductors for global communications markets, today announces its unaudited results for the six months ended 30 September 2022.
Headline H1 numbers show a good improvement on last year -
Revenue up 22% to £10.1m
Strong gross margin of 76%
Overheads well contained, with dist & admin costs only up 3% to £5.77m
PBT up 81% to £1.8m (note that the LY comp benefited from other income of £437k, which disappeared in H1 this year - maybe pandemic Govt support, at a guess?)
Outlook - a bit waffly, but the last sentence sounds quite exciting, particularly because this is a conservatively run company, not some blue sky rampy thing. Also it’s clear that acquisitions are on the cards, to make use of the surplus cash -
The financial year commenced with the business positioned nicely to grow well, despite the various macroeconomic headwinds that have been a feature of the last two years. The results achieved for the opening six months have been strong in absolute terms, delivered through a clear strategy for growth and backed by a disciplined and determined workforce.
The effort being expended towards capturing the organic growth opportunities in front of us is delivering tangible results, both operationally and financially. Opportunities exist to accelerate delivery of our objectives via complementary acquisitions and management continue to devote an appropriate amount of time towards exploring them.
The good progress being made is built upon strong foundations laid during previous years. This, coupled with the energy and enthusiasm to succeed and a clear strategy for growth, enables the Board to have confidence that continuing progress will be made through the second half year period, delivering a very positive outcome for the year as a whole.
Broker upgrades - it’s often difficult to interpret updates, but brokers are given a closer steer (most of the time), so that’s why I look closely at what they say.
In this case, Shore Capital (many thanks) make a substantial increase to forecasts, moving up 43% to 22.2p for FY 3/2023, and 27.4p for next year.
That makes the 436p share price much more palatable on a PER basis, plus of course there’s also the surplus cash & freehold property assets to take into account.
Balance sheet - very healthy indeed, with plenty of surplus cash (equivalent to about a third of the market cap, so this is a key point).
There could be long-term upside on the property assets too, but planning permission has been a long-term wrangle, so I would treat that as a bonus if it ever happens.
And if not, at least the staff have a lovely spacious, leafy campus to work at, which would probably enhance employee satisfaction & retention, I am guessing.
My opinion - CML is looking a lot more interesting after this update. I don’t know anything about the products, or their potential, but the numbers are starting to look good, together with strong outlook comments. This suggests to me that readers might want to do some more detailed work on this yourselves. Plus of course there’s all that downside protection from a lovely strong balance sheet with surplus cash - which could turn into upside if acquisitions are made at the right price. Let us know what you think, I think there could be potential here. I think this might have to be a “mystery share” for this week’s end of week podcast - i.e. one of the most interesting shares I’ve seen during the week.
It's been a safe haven in recent years, whilst carnage has been going on around it with many other small caps.
Note the high StockRank, which could improve further as increased broker forecasts feed through (likely to improve the value score).
EDIT: thirty fifty twenty helpfully points out in the reader comments below that CML has been buying back its own shares, so shareholders benefit from increased EPS, due to there being fewer in issue.
Graham's Section:
DP Eurasia NV (LON:DPEU)
Share price: 40.15p
Market cap: £58.5m
This stock represents the one and only time I decided to try investing in a newly-listed company. It didn’t work out, and I lost most of the funds I invested in it.
DP Eurasia is the exclusive franchisee of Domino’s Pizza in Turkey, Russia Azerbaijan and Georgia.
The long-standing business in Turkey is its primary asset, and the stock also came to the market with an exciting growth proposition in Russia.
Unfortunately, Turkey has been a difficult place to do business. Russia also, as you might be aware, has a few issues currently.
Take Turkey for starters. Inflation there is currently running at 85.5%.
Even leaving the recent rise in inflation to one side, the currency markets have been predicting and responding to problems in Turkey for some time.
Here is the 5-year chart of the pound against the Turkish Lira::
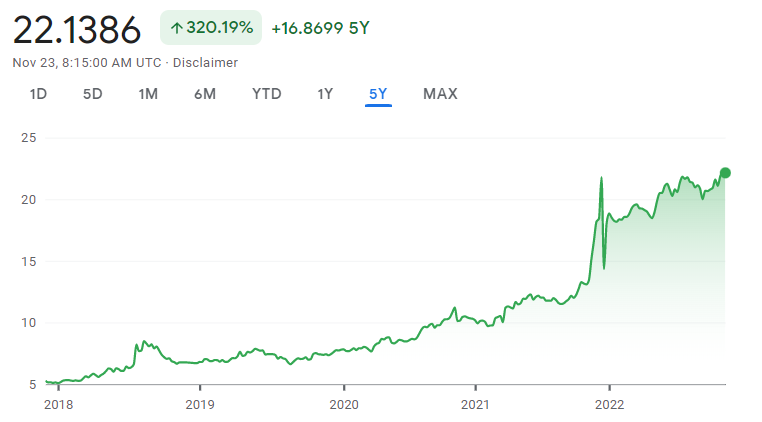
Therefore, while the recent surge in inflation has been painful for all concerned, the truth is that the Lira has been collapsing for years (as measured against other currencies).
The effects of this on the value of a consumer business operating in Turkey are Not Good.
DPEU share price:
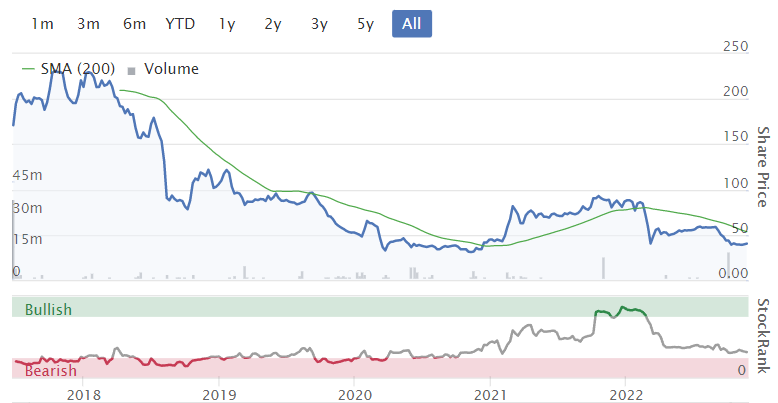
In the end, I decided that I could no longer hold these shares as the risks were clearly much bigger than I had initially realised, and it was no longer an investment but a speculation.
Let’s check out today’s trading update, and see if the situation might have improved for long-suffering DPEU shareholders:
- Number of stores 845 (last year: 806)
- System sales in Turkey for the first ten months of the financial year: TRY 2.3 billion.
This sales number represents a gain of 66.8% nominally, but is a reduction of 3.3% after applying the accounting rules as they relate to hyperinflation.
When looking at the sales figures for Russia and the other countries, it’s far more useful to see how they performed in their own currencies, not in Turkish Lira.
This table is key: like-for-like growth in each country’s own currency:
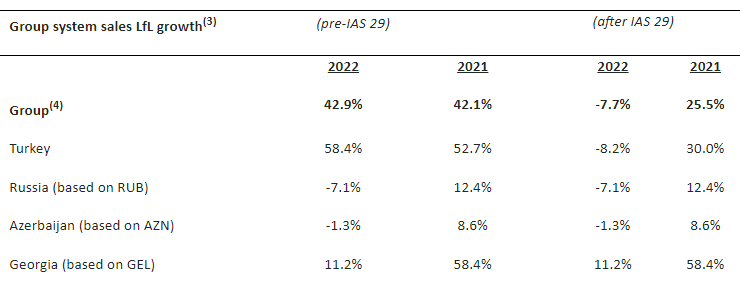
“IAS 29” is the accounting rule for hyperinflation. The key points therefore are:
- Turkey’s inflation-adjusted like-for-like sales are down 8.2%. There was a major change in VAT which I think is responsible for c. 7% of this.
- The other countries don’t currently require hyperinflation adjustments.
- Russian like-for-like sales are down 7.1%. The other countries are too small to move the needle.
The company considers this is a “good performance”, on the basis that there was “a very strong prior comparative” in 2021, and on the basis of the inflationary environment.
They are still making progress in converting customers to online ordering: delivery orders are now 82.3% online (up from 76.6% last year).
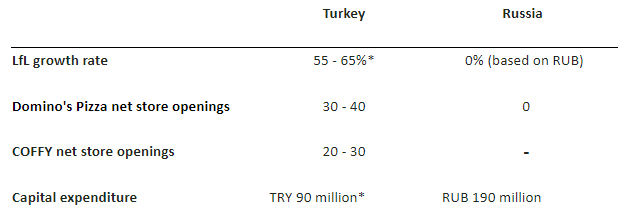
Outlook - no change to guidance for 2022:.
A snippet from the CEO comment:
"We retain a fundamental commitment to ensuring franchisees remain profitable. As a result, franchisee demand is very strong and our Domino's Pizza store count in Turkey has increased by 31 year-to-date. Given our strong pipeline and sustained franchisee interest, we remain confident that 2022 will be another solid year for Domino's Pizza network expansion.
Balance sheet
Today’s update informs us that the company has cash plus an undrawn facility that add up to total liquidity of TRY 289 million (£13 million).
The interim results disclosed that net debt was TRY 1085 million (£49 million).
It’s not overly comfortable. The company needed and obtained a covenant waiver from its Russian bank for 2022.
My view
As usual, I come away from a DPEU update thinking that the numbers still don’t conclusively prove that the investment thesis is wrong, but I remain unsure about how close we are to seeing the company make a meaningful profit.
In H1, the company made an operating profit of TRY 28 million (just over £1 million), on sales of TRY 1.3 billion (£57 million). So there are signs that it could be turning the corner.
Russia: after so many years waiting for the Russian operation to bear fruit, I’m glad to see that net store openings there have finally reduced to zero.
The company’s current strategy in Russia is to stop investing in its growth there and simply to optimise the existing store network. That sounds good to me: it doesn’t make sense to keep investing heavily in Russia until we have proof that DPEU can make meaningful profits, which it should be able to do with its existing stores. DPEU needs to deleverage, which means letting its existing stores mature and hopefully start generating some cash.
There are also the political risks in Russia of course, which are probably very significant and are beyond my ability to assess.
Turkey: my one comfort here is that DPEU is in the food sector, though it’s not cheap food. In a hyperinflation, I expect food producers to be able to pass on their cost increases to consumers more easily than almost any other sector.
And given the collapsing Turkish economy, I would say that (inflation-adjusted) like-for-like sales growth of minus 8% is not too bad!
Conclusion: I guess it goes without saying that this share remains extremely high risk.
We have a net debt pile that’s about the same as the market cap. We have poor like-for-like sales growth. We have geographic exposures to a hyperinflationary country on the one hand, and on the other hand a country that’s in a physical and economic conflict with the West.
But it is a Domino’s master franchisee, and there are only a few of them. As measured by price/sales, it is less than half the price of DP Poland (LON:DPP) and cheaper again compared to Domino's Pizza (LON:DOM) (but I suppose that is to be expected).
We also have a cornerstone shareholder (49%) in the form of Jubilant Foodworks, who own the Domino’s franchise for India, Sri Lanka, Nepal and Bangladesh. I think we can safely assume that they would not mind owning 100% of DPEU. But would they have to pay much to get the other 51% that they don’t own yet? If DPEU ends up in need of a bailout refinancing, then the answer is clearly no.
Unfortunately, I think this stock remains far too risky for almost all investors, for now. But I stubbornly still think it’s possible that this stock could eventually turn good.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Crestchic
Just punched through the 300p barrier which it’s been banging it’s head on in the past 4 months .
If it holds above 300p probably going to trade in the 300-350 range for the next period .
Think the Camacord selling has gone and there was a vacuum of stock today and it’s popped up a range .
I tried to buy some Crestchic yesterday and couldn't get any - none available. Bit frustrated to see the price rise today but I already have a few so pleased in that respect.
I concur, I tried to buy yesterday but no deals available.
I had an offer today but didn't accept the price being asked so just let it lapse, maybe tomorrow.
Tommy
I don't hold Crestchic (LON:LOAD)
Crestchic (LON:LOAD) (no position)
Hi Planetx
I'd also like to extend my thanks to you for sharing insights from your site visit.
It is most definitely appreciated, irrespective of whether or not I do, or eventually will, hold a position.
A quick question if it's okay. Did the company say anything about their receivables balance and whether it has come down since the last reporting period? I must admit that this was one of the things putting me off...no doubt another example of me overthinking things.
I completely understand that this is a very specific query and will not be surprised if it didn't come up in conversation.
All the best and thanks again.
A
Alliance Pharma (LON:APH) down nearly 40% today on lower guidance for the year, £30m instead of £33m I think and also the CEO Peter Butterfield “stepping away” until January. An over reaction or not?
£BOO The Times is not looking for Boohoo advertising. John Lewis massive warehouses run with 3rd party workers on the other hand....not a word. I live in a sea of these type of distribution warehouses and know people who have worked as pickers in them; they are all similar to a greater or lesser extent. It's client journalism, same as the SBF/FTX crypto scandal: Marc Cohodes who broke the story "also said that he went to Bloomberg in July to report on Sam & FTX and Bloomberg's crypto news team passed on it, said it was bad for business, they'd "lose access" and it'd be "too much work."
A technical glitch - the only share which has been tagged this morning is accesso Technology (LON:ACSO) (see screen print). This means that none of the other shares which Paul and Graham have written about will appear on Stocko searches. For example if you look at the page for Dialight (LON:DIA) and click the "Discussions" tab todays SCVR report does not appear, but if you do the same for accesso Technology (LON:ACSO) it does. Sadly the Stocko search engine is restricted to tags only - so any discussion in the comments section disappears into the ether if it isn't tagged by Paul or Graham.
Hi MichaelC,
Many thanks for flagging the disappearing tags, we have an ongoing battle with this, they vanish sometimes for no apparent reason. I put them all back in again manually before lunch, but they vanished again. So I've re-input the tags AGAIN!
It really helps when people point out any missing tags, so I'm glad you did. I normally check, but sometimes things just happen, and we don't know why.
Regards, Paul.
There is an old homily " don't fight the tape" and yet as an investor in the less traded areas of the market this is sometimes the whole point. Yesterday and today two of my holdings CentralNic (LON:CNIC) and Eckoh (LON:ECK) have produced good results with almost no comment here and a fall in each of their share prices.
So either I am completely mislead by their announcements or the market has completely misunderstood them. Usually the market is able to recognize the trend correctly. And yet..
Paul made a brief note that leaned heavily on Centralnic's lack of net tangible assets but I think that the accounting conventions have for some time now shown an inability to properly show intangible assets. For a company such as CNIC the growing revenue is both organic and acquisition derived, and it shows that those assets, intangible or not, are definitely assets! The cash is flowing well (which is sanity)and, quite rightly in my view, is being correctly allocated to more (intangible) assets which CNICis turning into more cash. The growth of dilution with additional shares is slowing as the company increases in size. I may be wrong but it is surprising that that there is not apparently much interest in commenting.
The lack of comment, positive or otherwise, on companies such Centralnic and Eckoh, growing international companies with substantial business and prospects is strange, while SCVR has quite a lot of cover and comment on companies which are striving not to get smaller and more irrelevant than they are already (AO World, Joules, Osirium, BOTB, Podpoint from just this week).
A quick look at the financials would suggest CentralNic (LON:CNIC) is a screaming buy. Personally I've never understood why what what they are selling isn't a commoditised product that should be subject to fierce competition, so I can't explain why revenues and margins are growing so rapidly. If anybody could enlighten me perhaps I could become a shareholder !
I got out of CentralNic (LON:CNIC) pretty early on this morning having been holding happily, but alas as much as you can sit and shake and scratch your head, you can't fight the Market which is clearly seeing something I am not....and for now I have to sit this one out. Painful but necessary, as preserving capital is my number one priority.
I do see a few cracks showing in the recent gains across the board with SP's under pressure. Sureserve (LON:SUR) down a huge amount, and now K3 Capital (LON:K3C) looks under pressure. I think we have a lack of buyers prepared to jump in and support these recent gains, which could well see them unwound.
Pressure on the FTSE 250 and below seems relentless ATM, but pretty unsurprising with the current outlook I suppose, With the FTSE 100 stuffed with global mining and commodities leading the way across Europe, and perhaps giving us all the miss guided feeling of confidence.
CentralNic (LON:CNIC) is one of my largest holdings and one of only two of my tech stocks showing a decent profit. It feels a lot like the other one, Equals (LON:EQLS) which was beaten up by the market following my initial purchase at about 116p all the way down to 25p. Each time I looked at the numbers the company seemed to be making good progress and I added (nervously) a few times; the last one at 29p. It recovered steadily to 96p now.
To me the reasons for the current market reaction to CNIC are similar. Everyone is nervous of the tech space at the moment and CNIC is not easy to understand, given its rapid acquisition programme, related amortisation and mix of currencies. This year the early bond redemption increased the amortisation charge but that is a one-off. The refinanced bond should help here and it is probably good to be re-based in USD following the currency's recent rapid rise - it it unlikely to get much stronger, and in any case now matches the majority of its income. There was also a shock in in the PI community when the 2021 audited pre-tax results was much less than the unaudited update due to recognition of a loss on hedging instruments - probably a one off, but the shock lingers longer!
I haven't added but remain a very optimistic holder.
I did comment on CentralNic (LON:CNIC) the other day, in the reader comments, and explained why I didn't find the numbers appealing, and I don't feel I can add much to the discussion, as it's not a business model that I particularly understand.
We've commented on Eckoh (LON:ECK) dozens of times, just check the archive.
It's so boring when people whinge about not liking the stocks we comment on. We've been over this ground numerous times - we can't cover everything, and we focus mainly on things we understand, that are newsworthy (e.g. ahead, or below expectations). I think Eckoh was just in line this time, so not a priority.
If you think something is good or bad, feel free to post a comment here explaining why.
My comments were not supposed to be aimed at you or Graham, your inputs being very welcome - and I recognise that, for the most part, staying on the right side of tangible net worth is a sound position! I am sorry if my comments came across as a whinge, absolutely not what was intended
My concern was more with the direction of community comments that do not seem as interested in debating these stocks as I would have expected.
Thanks Aislabie, I appreciate your reply. It is a bit dispiriting when we try our hardest to cover as much as we can, then people criticise because we haven't covered what they personally find most interesting. We cover about 500 companies here, which is at least half of the entire small caps market, so I think that's pretty extensive. Although obviously my personal sector specialism on retail/eCommerce has been awful in the last year. That's just the way it goes.
But going back to CNIC, there were several reader comments discussing this stock the other day, and I thought as a community we actually had a good bull-bear discussion on it. But I think several of us don't like the accounts, the gearing, the lack of cashflow, how big EBITDA turns into almost nothing in post-tax profit, etc. There was a good discussion about it, maybe you didn't see all the reader comments?
Anyway, we managed 9 companies today, despite being on a super-tight schedule, not being defensive (OK, well a bit!!)
You've got to remember also, if a company reports in line with expectations, it goes to the bottom of the list for us, because that's not newsworthy.
We'll keep doing our best, but we can't cover everything.
Best wishes, Paul.
Home Reit (LON:HOME) - short attack! c29% fall today as we speak. Here is the report - https://viceroyresearch.org/20...
Cerillion (LON:CER) RNS today saying they will announce FY22 results this Monday, 28.11.22.
The CEO. Louis Hall, (who did an excellent interview with Paul recently here) & CFO will give a webinar with Q&A on Friday 2 Dec, 12 noon, register here.
The last trading update said the Adj PTP to be materially ahead due to fx, better resource allocation, lower financial costs & less amortisation and depreciation. It always looks a tad expensive but management continuously delivers!
Morning Paul, maybe not the place to put this but I just wanted to say I've listened to your podcast for the first time and I really enjoyed it. I only started investing a year ago and its only to small amounts so I have much to learn! You come across really well and in terms that for a complete novice like me are easy to understand!
As an old RSM of mine used to like saying 'listen in troops, you might learn something' Keep up the good work!!
With thanks to KC and Sicilian Kan on other boards, my attention has been drawn to an impending IPO. Conviction Life Sciences Company are hoping to raise up to £100m in the first issue to invest in 20 – 40 biotech companies outside the US which they consider to be undervalued..
https://clsc.uk/
https://clsc-docs.s3-eu-west-2.amazonaws.com/CLSC-Investor-Presentation-NOV-2022.pdf
They intend to be long term shareholders. This will be of particular interest to Angle (LON:AGL) investors as it appears to be one of the companies in which they intend to invest.
Thanks for that Jim. Anything of interest re Angle (LON:AGL) at the moment would be good! Though I would still be saying to the company, for heavens sake, focus on the US. The UK NHS seems to be disinterested in Angle (LON:AGL) and not a lot of progress in Europe with one (small?) distributor added in the Czech Republic.
Presumably Company B is Angle (LON:AGL), Jim?
£CML - Operating profit is £1750k after Amortising Development Costs of £831k but £2,291k of development costs have been capitalised ( per cash flow statement). If all development costs for the period were written off to the P and L then the company would be just above break even.
Therefore to a large extent any judgement of the true profitability of the company relies on whether/how much the capitalisation and amortisation of development costs reflect reality
Calnex Solutions- interims yesterday-is a really high quality little business which deserves more coverage
Just FYI, Calnex Solutions (LON:CLX) is presenting their interim results on InvestorMeetCompany today at 12h15.
De La Rue (LON:DLAR), profit warning, looks like demand is down.
Morning Rusty2,
I've started looking at De La Rue (LON:DLAR) - down 24% as we speak - seems a harsh reaction given the already bombed out share price.
I've got to catch a train shortly, but have just had my mobile phone data allowance increased 25x at no cost (result!), which means I should be able to tether my phone and work on laptop to finish this section before lunch. Expect typos though, as typing on a moving train does tend to produce erratic results LOL!
Regards, Paul.
I don't think you can. Worth flagging up to the Stocko team I think.
A big "expose" article on warehouse working conditions at Boohoo (LON:BOO) warehouse in Burnley. By the Times. It is a shocking read.
SP dipped this morning. But I think the blood are not on the streets yet with this one... Wait for the politicians to all pile on to vilify Boohoo and threaten some action. Then we'll see some further pressure on the SP.
Is it shocking? Warehouse work is hard - physically demanding, and challenging targets have to be met. So only suitable for fit/active people. There's a video version of the Times latest attack on Boohoo (LON:BOO) below. Have a look at the comments left by people - many are saying that conditions are tough in numerous other (named) retailers' warehouses.
BOO is automating its warehouses, which is probably a good thing, as these type of jobs are not pleasant - I've worked in warehouses myself, and it's not much fun. Or actually it can be, if the managers are upbeat, pleasant people, and get a good team spirit going, but that's probably quite rare.
I have read a similar report about working at an Amazon warehouse. I don't remember anything about excessive temperatures, but the targets were relentless.
Its the same with supermarket online shopping target iph targets need to be hit but working conditions a little better, staff doing all the work that customers used to do.
I've seen Glassdoor comments about working in the Next (LON:NXT) warehouses. Dire.
I remember working in warehousing 20yrs ago was the worst job i ever had its never been pleasant! Always had targets but that warehouse looks pretty modern, i worked in old converted mill during winter was freezing ! Remember being timed going to the toilet!
Well that was interesting reading - The Times article I mean. Boohoo (LON:BOO) will suffer further for this. Interesting as ever that The Times has chosen now to publish the article. The key thrust of the article is related to a period in the summer, several months ago, when the temperature was 32 degs. However, there are many other negative comments which are designed - rightly - to make anyone uncomfortable and 'modern slavery' drips from every paragraph.
Whatever, it makes uncomfortable reading - not that the buyers of Boohoo (LON:BOO) products will be Times subscribers/readers! It will be picked up elsewhere and on social media I guess.
This will run and run as will the Boohoo (LON:BOO) SP and no doubt focus on other similar retailers too. SP down already 15% in 3 days I estimate. Had recovered recently, in the last month. Now lost all of that.
Well I think sending a bloke in who pushes pens, asking provocative questions, and then read by people who have never done a days manual work will give this reaction, although I'm not a fan of Boohoos share, and I dare say this will have a negative effect on the price.
Try working in construction which has killed more people since the year 2000 than all of our armed forces put together over the same period. I used to dream of a job in a warehouse when I was piss wet through on a building site, but always felt better treated and paid than I was when I worked on a farm knee deep in cow shit, and liked the fresh air of the farm compared to working in a plastics factory.
Discrimination of any kind as pointed out in the film is not acceptable, we work as a team and should all be prepared to work where ever we are put, so if true is not acceptable.
I know now days as a country we make very little, so these jobs seem like slavery, but perhaps the Times should have gone a little further back up the chain and visited the sweat shop where all those clothes were made, but out of sight out of mind I guess.
You have to crack a few eggs to make an omelette, and for some time to come, someone somewhere will have to do the cracking.
my grandson works in an Amazon warehouse loves it . Decent money, good laugh and he says no pressure. He is only 25 and fit as a butchers dog, don't think it would suit me.!
Boohoo (LON:BOO) (I have a tiny mainly remnant holding, from my original buy at 26p)
Might be a buying opportunity if theres enough blood on the streets - I'd be looking for 26p or below?
I seem to remember that Channel 4 Dispatches did pretty much the same thing a few years ago with a 'whistleblower' and undercover reporter as an agency temp. I have no doubt that being an agency temp in any warehouse in the UK is not a fun job. Nor is fruit picking. Courier driving. To name a few. There are regular complaints and exposes. Roll on warehouse automation. Better for all stakeholders? The Jethro Tull of the warehouse industry?
I've just found a link to that report still on channel 4
I've not read the Times report - from what I've heard so far it seems conditions are better this time around? Aside for the temperature of course. Though - assuming this was back during the summer then I was struggling with temperatures at least as high working (or not) outside. I remember apologising to our postie that he had to deliver our post. I didn't think to ask how far he'd walked pushing his trolley :-)
Boohoo made some improvements to conditions after the first expose - though most likely mainly for permanent staff - less so for agency workers.
Heres a 'glowingly superficial' report from the Manchester Evening News on the improvements and expansion from 2018. Back in the days when Boohoo seemed a global phenomenon - and nobody had heard of Shein. Five years ago - seems a world away now? I don't suppose the Times report referred to free lunchtime Yoga sessions for Boohoo staff much?
Burnley was Boohoo's first warehouse I think - and I was wondering why they have chosen to put all of the recent funding £125m ? into automation of the Sheffield warehouse. I guess that they will get around to Burnley as they can afford it - but most of the cash is likely now flowing towards the new US warehouse? Might be a while.
Without having read the expose - I'm suspecting that it's bigging up the story for the 'scoop', and behind it all - despite all the negative coverage - Boohoo will be no worse than most large users of agency warehouse workers. Most likely Burnley as the oldest, is the worst problem. Maybe something a bit more than extra yoga sessions this time around. More training for supervisors perhaps. But I don't see legislation changing on agency works much.
I'm not convinced that this expose will impact Boohoo's sales or competitiveness much if at all except in the very short term. And what impact it does have will likely drive some of the sales towards Shein - which I find highly ironic!
As I said - might be interested in adding to my existing tiny holding in Boo if the price drops substantially enough - though I don't have a lot of funds available to deploy and the risk/reward does not look irrestible at the moment,
cheers
Mark
Boohoo has already shaken off the investors who bothered about this sort of thing after the report 1, or was it 2 years ago? It is not an ESG holding.
I don't think that having targets is unreasonable - but they have to be fair and sustainable. I have no idea if the reporter really gave it a go, but the story loses value if he met the targets he was given, so he isn't incentivised for it.
I don't think it is unreasonable for boohoo to expect reasonably fit people to do that sort of work.
I do think it is completely UNREASONABLE to have high temperatures like those stated. If they can't sort it out then they should shut it down.
Manager fail again!
Leadership ethics failure highlighted again! (while sitting in their aircon offices?)
I don't hold.
Just finished reading “Outsiders” by William thorndike, “eight unconventional CEO and their radically rational blueprint for success”
One of the books on Warren Buffets top 20 books to read, best one so far (I’m trying to read all 20)
Now onto John Maynard Keynes “essays in persuasion” which is needing some resolve.
Outsiders very much worth reading.
Agreed on Outsiders. Does anyone know any managers of UK listed companies who might qualify? It seemed to be applicable to Admiral for a while, with the effective CEO an COO partnership, but am less close to it since DS has taken over and Munich Re. divested.
There is a summary of the book as a book on Amazon and I bought it for my Kindle after reading this, so much cheaper but if it piques me I'll buy the real thing.
Will Thorndike has also appeared as a guest on Invest Like The Best with the always effervescent Patrick O’Shaughnessy https://podcasts.apple.com/gb/... and is also now running a podcast called 50x
Belvoir
Good update from Winkworth yesterday reads across into Belvoir .
Belvoir dropped to bottom of its trading range yesterday at 184p so looks good entry point .
Just a note both look good long term buys with good dividends .
Hi planetx,
I agree, Belvoir (LON:BLV) looks very good for a long-term purchase at the current price.
I met management (CEO, CFO, and Chairman) at Mello, and had a good chat. They're straightforward people, hands-on managers/entrepreneurs, which is exactly what I look for at small caps.
BLV has an excellent track record I think, and being mainly a lettings business, it sails through downturns, as demonstrated in the pandemic. Rents are rising strongly, so that feeds through (with a lag) into higher revenues.
Nice little business, priced attractively low, in my view. (no position)
RegardS, pAUL.
The only problem is landlords (including myself here 10yrs) are leaving the private rental sector in droves because of BTL tax changes, ever increasing regulation, almost certain demise of section 21 and of course the main driver the massive impact of interest rates on properties that are heavily leveraged. For 2023 the finance side related to new sales will be well down. It's unlikely for the foreseeable future that values will increase, they are already falling, how far who knows. The mortgage companies are ratcheting up lending criteria, this will of course boost rents if people can't buy.
I'm selling at least half my portfolio. The party for now is over, owned outright yes landlords will weather the storm but somebody needs to tell the Politicians on all sides that continual landlord bashing only makes things worse for tenants. A falling supply of properties to rent and a demand side that simply will not fall = Increasing rents
I bought a big chunk of BLV in March/April 2020 very nice, I knew it would do well. For now I have retained a very small interest. Totally agree it seems a well run business and one that I will surely own again.
Concerning Belvoir (LON:BLV) and the PRS (private rented sector) the White Paper A Fairer Private Rented Sector includes 4 references to tenants being able to challenge "unjustified rent increases". Section 4.1 says 'Any attempts to evict tenants through unjustifiable rent increases are unacceptable. Most landlords do not increase rents by an unreasonable amount but in cases where increases are disproportionate, we will make sure that tenants have the confidence to challenge unjustified rent increases through the First-tier Tribunal.' "Unjustified" is not defined. The current Housing Minister, the ninth in five years, said recently that the government does not propose rent controls but after reading a report of other things she has said I'm not convinced she has read the White Paper thoroughly. At their conference in September the Labour Party said they would abolish automatic evictions for rent arrears. I think the PRS (private rented sector) will shrink by a considerable amount but it will take some years before it affects businesses like Belvoir (LON:BLV), and for some time rising rents will offset the loss of clients - until the effect of rent controls becomes severe and horror stories of un-evicted non-payers of rent become widespread. My family has been involved in the PRS for over 60 years, off and on. In my opinion we are heading back to what it was like before the 1988 Housing Act.
EDIT - we have sold one of our properties and I am filling in the paperwork to sell another this afternoon.
Would private landlords not just be replaced by businesses running a portfolio of properties? It feels like economies of scale are needed to make BTL viable. The question is whether these business would use the services of Belvoir - presumably they would unless they are able to do it in-house.
The key question here is risk, if you cannot identify whether you can increase prices or not on rent, or that you can use due legal process to remove a tenant who has not paid rent, then would you as a business want to enter into this?
I have one rental property left, and holding for a number of reasons (owned outright), but have put on hold reentering the market for more currently due to the changing rules.
I would also add in for private landlords there is a pending tax reporting change which is likely to force quarterly reporting to HRMC and mandate a proprietary software programme, not just Excel which does the job very well for me.
Tommy.
I think you're right to get out of this market - seems an incredible amount of hassle for very modest returns. Over the long term I would expect far higher returns from some of the companies featured on these reports, and with much less hassle!
A near example?
https://www.propertypartner.co/blog/october-2022-portfolio-update/
Commendable performance from two retailers given the economic gloom, both of which I hold. Pets at Home (LON:PETS) and £HFD No comment expected on the former as not a small cap, but perhaps some commentary on Halfords (LON:HFD) The transition to motoring services is progressing, increasing the percentage of non-discretionary spend across the group. Both trading within consensus, albeit Halfords (LON:HFD) towards the lower end and both continuing to pay dividends.
I hold both.
ECO Animal Health (LON:EAH) ECO Animal Health had interim results out this morning - we are hosting an investor presentation with them on Monday (28th Nov @ 10am) - you can register here: https://www.equitydevelopment....
ECO Animal Health (LON:EAH) is a share that is going nowhere without China (and Japan) recovery. It must be very dispiriting but the Chinese hierarchy's attitude towards the economy versus Covid offers little encouragement for the future.
Regardless, pork prices in Chinaare now back on the up significantly. H2 should be a good one. https://www.globaltimes.cn/pag...
CML Microsystems (LON:CML) - thank you Paul for the thorough analysis. i would only add that they have bought back and continue to buy back their own shares.
disc. i hold
Thanks, good point re buybacks at CML . I'll add that to the main report, with a hat tip to you!