Small Cap Value Report (Weds 26 April 2023) - PSN, NICL, BRCK, ELM, LTG, TST, POLX, EYE, W7L

Good morning from Paul & Graham.
Today's report is now finished, at 13:44
(for any new subscribers, we first post a blank "placeholder" article at 07:00 every weekday, so that readers can add your initial comments on the day's announcements, which we encourage, especially if you add your own insights to any news. The main article then gradually builds throughout the morning, until usual finish time of 13:00, when the SCVR email goes out)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Summaries
(more detail in sections below)
Persimmon (LON:PSN) - 1289p (up 4% at 08:42) - mkt cap £4.1bn - Paul - GREEN
This Q1 trading update caught my eye, and has read-across for lots of smaller caps that are dependent on a healthy housing market. Q1 traded as expected, but the outlook comments sound rather encouraging for a housing market recovery. Hence I think the whole sector is worth a fresh look.
Nichols (LON:NICL) - £10.90 (pre-market) (£398m) - Graham - GREEN
Q1 update for AGM is in line. Out of Home business struggles, blamed on cost of living issues. CFO leaves. Adj. PBT of £25m is forecast for 2023. I like this company and hope for improvement in subsequent years.
Brickability (LON:BRCK) - up 4% to 68p (at 10:08) (£205m) - Paul - GREEN
Given uncertain macro conditions, I find this ahead of expectations update a positive surprise. The forward PER of only 5.9x is clearly factoring in a significant cyclical downturn in profit - but there's no sign of it happening so far. Although outlook comments imply some softening may happen short term maybe? Very good value in my view, so it has to be green.
Elementis (LON:ELM) - down 1% to 117.8p (£689m) - Graham - AMBER
Another Q1 AGM update. Trading and outlook are in line with expectations. Market conditions are said to be affecting demand but the company is also showing signs of pricing power. Could be worth a closer look.
Learning Technologies (LON:LTG) - down 16% to 109p (£861m) - Graham - AMBER
Final results in line but the outlook is a profit warning due to a forecast EBIT growth rate for 2023 of only “high single digits”. It would be nice if profit warnings were delivered in a more straightforward manner.
Warpaint London (LON:W7L) - up 7% to 210p (£161m) - Paul - GREEN
Slightly ahead of expectations FY 12/2022 results. Together with an even better Q1 performance than was indicated about a month ago. Lovely balance sheet, and decent cash generation (funding organic growth and reasonable divis). It's not often I find strong organic growth, at a still-reasonable valuation. Thumbs up from me.
Quick Comments (from Paul)
(no additional detail below)
Touchstar (LON:TST) - this minnow software company confirms it has reduced the share premium account by £1.2m, which enables it to legalls pay divis or do share buybacks. Recent results showed it had 41p/share in net cash. There might be some potential with this share, I've been following it for years, but progress has been quite slow so far. Only £422k PBT (although that doubled from LY) recently reported.
Polarean Imaging (LON:POLX) - a very strange one, where investors were excited about FDA approval for its imaging technique/product, which happened and the shares subsequently collapsed in price. With hindsight, a good example of too many people chasing up the price on the rumour, but then seeing the price crash on the actual fact. At only about a quarter of the hyped-up previous price, maybe it's worth a fresh look now? Today's news is I think the first commercial sale of its specialist gas blend for MRI scanners.
Eagle Eye Solutions (LON:EYE) (Paul holds) - good newsflow continues, with yesterday's announcement of a new 5-year contract with John Lewis & Waitrose. It seems to be an existing client, but has signed up for a new product with EYE, if I'm reading the RNS correctly. I should add that I bought a starter position in EYE (we clearly disclose all personal holdings here) earlier in April, after listening to webinars on PIWorld. This share is more expensive on traditional metrics than I would normally tolerate, but it does seem to have genuine expertise in a niche, serving big clients internationally. Hence it strikes me as something with genuinely exciting growth potential. It's moved into profit now. Concerns are over valuation, and management greed that other investors have flagged.
Paul's Section -
Persimmon (LON:PSN)
1236p pre-market (£4.0bn) - Q1 Trading Statement - Paul - GREEN
A mid-cap housebuilder, which is relevant here for read-across to lots of small caps - as so much hinges on a healthy property market. There’s lots of info in this update - Q1 trading was as expected (weak, due to the macro chaos last autumn) - Q1 completions down 42% on LY, build rate 30% lower, but this is reflected in forecasts that have already been slashed across the sector.
So this issue really is, are there signs of life in the outlook comments? Yes, is the short version. This reads well I think - e.g.
- Selling prices holding firm (+10% Y-on-Y, surprisingly), so no signs of having to discount heavily to get sales agreed.
- Recent weeks have seen “some encouraging signs” re customer activity.
- Current trend suggests FY 12/2023 volumes will be at top end of previous guidance of 8-9k properties sold.
Building cost inflation stabilised at 8-9%, with “limited signs” of that easing. - Customer confidence improving, but less so with first-time buyers, who are finding affordability stretched, and harder to secure mortgages.
FY 12/2024 outlook sound positive - expecting a recovery in both volumes and margins (this is currently not reflected in forecasts, so there could be upside here).
Paul’s opinion - I think this is very encouraging, and am flagging up the whole housebuilder sector to SCVR readers as possibly being worth a fresh look. PSN’s share price is back down to barely above the chaotic time last autumn. Whereas some other housebuilders have seen a good recent bounce, so maybe this one could be an interesting one to look at? Or maybe there are specific factors affecting PSN that investors are wary of?
Strong balance sheets across the sector mean that there’s not really any solvency or dilution risk, even if the macro picture were to worsen due to unforeseen events.
You do have to also take into account remediation costs re cladding, and the additional rate of Corporation Tax that housebuilders will be subjected to in future.
Brickability (LON:BRCK)
68p (up 4% at 08:50)
Market cap £205m
Following on nicely from a housebuilder, is this distributor of bricks.
I last reviewed its positive update here in Feb 2023, which was ahead of expectations - surprising plenty of us I think, given that housebuilders have slowed down their pace of construction, as mentioned above in my review of PSN.
It’s obvious from the low share price that investors must be expecting a slowdown from BRCK, given that its forward PER is only 6.3. There’s also an attractive dividend yield of c.5.2%, but no asset backing (unlike the housebuilders).
On to -
Brickability Group plc (AIM: BRCK), the leading construction materials distributor, is pleased to provide the following update on trading for the year ended 31 March 2023.
Continued robust performance, record Adjusted EBITDA of >£50m and strong acquisition pipeline
Q4 “remained resilient”, despite macro uncertainty.
FY 3/2023 is ahead of expectations again (following an upward revision in Feb 2023).
Revised guidance now is £50m+ adj EBITDA (consensus previously £47.1m)
Revenue of £681m is up an impressive 31%, but most of the increase has come from acquisitions, since only +4% is like-for-like (LFL).
Note that the exceptional performance last year from timber has been a headwind this year. This is important, because the other divisions achieved +15% LFL revenue growth, much more impressive than the +4% overall growth including timber.
Net bank debt is insignificant now at only £8m.
Acquisition pipeline strong, and I think it can probably make more acquisitions without dilution, given modest debt.
Outlook comments sound a little cautious, with mention of challenging conditions in some sectors, and robust long-term demand (which I always think is softening us up for shorter term weakness!)
Broker update - many thanks to Cenkos for publishing an update on Research Tree. £50m EBITDA becomes £43.1m adj PBT, and 11.6p EPS - so at 68p/share, I make the PER only 5.9 - which leaves plenty of scope for a downturn in demand (that hasn’t actually happened as yet, but might do).
Forecast for FY 3/2024 assumes a small slowdown in EPS to 10.2p.
Paul’s opinion - this update strikes me as remarkably good in the circumstances. Maybe price rises are obscuring volume shrinking, possibly? Ultimately, I don’t care where growth comes from (price, volume, or a combination), all that matters is what’s happening to profit - and it’s going up here.
It’s getting very tempting to throw caution to the wind and buy BRCK, given that the 68p share price already effectively prices in a halving of future earnings. Maybe that’s too cautious, providing possible upside on the share price?
Warpaint London (LON:W7L)
210p (up 7% at 12:09)
Market cap £161m
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce its audited results for the year ended 31 December 2022.
Record sales and significant profitability reflect strong full year performance; positive start to 2023
This is one of my favourite GARP (growth at reasonable price) shares, so let’s see if its FY 12/2022 results stand up to scrutiny.
Key numbers, with my comments -
Revenue £64.1m, with over half now being international (+48% growth).
Gross margin up to 36.4% (LY: 33.8%) - I’m impressed, given that input cost inflation would have been a headwind.
Adj operating profit £10.3m (LY: £7.0m)
Adj EPS up 44% to 11.2p (giving a PER of 18.75) - this is a slight beat against a forecast of 11.2p from Shore Capital (many thanks).
Current trading - I last reported on Warpaint here on 24 March 2023 when it gave a positive view of FY 12/2022, after a strong Q4, and indicated that strong trading had continued into Q1 2023.
Q1 has turned out better than imagined, with £18.5m sales (I deduced c.£17m in my last report here), giving Q1 growth of 40% (and note that the Q1 2022 comparator was strong, so beating it by 40% really is impressive). This is all organic growth remember, there have not been acquisitions of other businesses.
Gross margin is also said to be up in Q1.
Outlook - sounds confident, and I think we can clearly expect more organic growth, from W7L’s simple but effective strategy - increasing its presence, and range sizes, in large retailers, globally.
Inflation & gross margins - this is interesting, and I think could apply to many more companies providing consumer products -
The currency options we have for the current year, the falling container rates, new product development, sourcing, and growing sales in the USA, will all help to protect our margin in 2023…
In addition, the increased scale of the business has given the Group increased buying power.
Ownership structure -
Share options charge is modest, at only £0.2m in both 2022 and 2021, bravo for that.
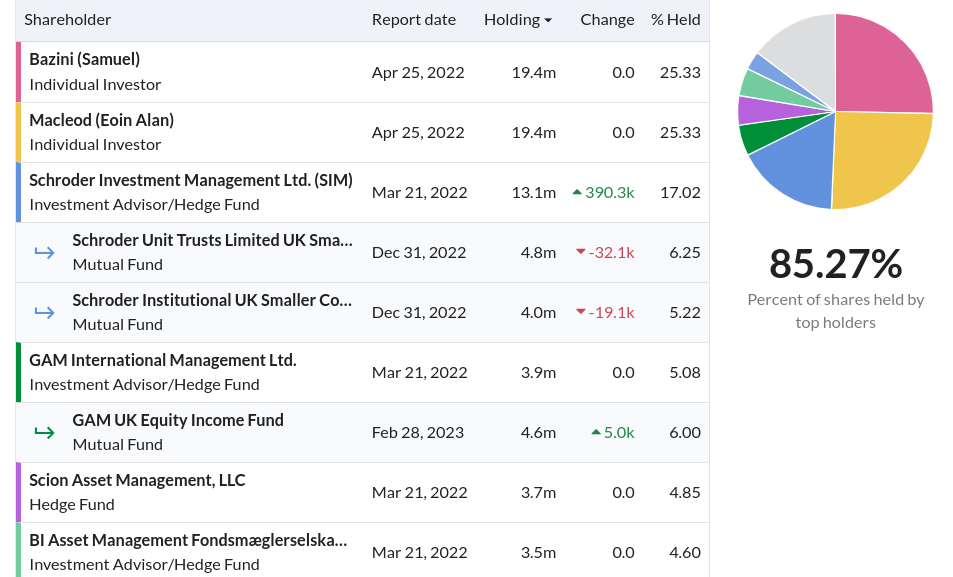
The owners’ eye here - founder management own 50%, so we have to decide if we trust them. Personally, I do trust management here. There has been no dilution in the last 5 years.
Balance sheet - is excellent. NAV is £37.8m, which becomes NTAV of £30.3m once I write off intangibles. Note that of the intangibles, £7.3m is goodwill that is not amortised, and the other intangibles assets (brands and customer lists which is goodwill in all but name) have now been practically eliminated in 2022. So the amortisation charge will almost completely disappear in 2023, which means the statutory and adjusted numbers should become almost the same in future - a plus point for people who like clean accounts, with no adjustments. Interesting only to accounting geeks!
This is a capital-light business, with hardly any fixed assets - only £1.4m PPE.
Inventories of £18.7m have hardly increased, despite much larger revenues, which is good to see. Receivables look fine. Note that trade payables is hardly anything, which suggests to me that W7L must be paying cash on delivery for purchases, probably to get the keenest prices & get the best service from suppliers (who generally focus on making sure customers who pay promptly are at the front of the queue for production slots).
Cash of £5.9m is healthy. There are no bank borrowings. I suggest the company splits this out on the balance sheet, instead of lumping together lease liabilities under the same heading as bank borrowings.
Cash generation is good, and as with the balance sheet, these look clean numbers with nothing unusual in them. The cashflows are real, and have enabled the company to self-fund its growth (which is just a little extra working capital), and pay decent divis too. So shareholders benefit from the company growing, with a reasonable income stream from divis on top. Very pleasing.
All 122 staff given a £1k cost of living bonus, on top of usual salaries, is a nice touch.
Forex is hedged, with details given. This means 2023 gross margins should be safe, even if currencies move a lot.
Paul’s opinion - regulars here will already know that I view Warpaint very positively. It was meant to be on my 2023 top 20 watchlist, for unfortunately I forgot to include it, and can’t change it retrospectively.
These numbers, and confident commentary reinforce my positive view of the company. Brokers have upgraded 2023 expectations today, and I'm expecting more out perform trading updates later this year.
It’s one of the simplest investing concepts I’ve ever seen - the company sells products that customers like and repeat purchase, at good margins, and is growing strongly by signing contracts with more retailers to stock its products. That’s it!
I suspect we’ll probably see an undulating but continuing upward trend in share price. I suspect the share price is likely to be up to about 300p by this time next year, if the strong organic growth continues. That’s an attractive proposition I think, assuming nothing goes wrong of course, as always.
Graham’s Section:
Nichols (LON:NICL)
Share price: £10.90 (pre-market)
Market cap: £398m
This is an old name in beverages where I’ve been positive, thinking that margins can normalise with the passing of time.
Today we get a short Q1 trading update on the day of the company’s AGM. Key points:
Revenues +4.2% year-on-year to £41.2m. It needs to do a little better, to keep up with inflation!
“Packaged” business +7.7% to £32m led by growth in Africa. UK revenue was only “marginally” ahead of prior year.
“Out of Home” business continues to struggle:
As expected, the Group's Out of Home ("OoH") business has seen a slower start to 2023 than in the prior year, with revenues down 7.8% to £9.2m, as continued significant cost of living pressures are being experienced.
Between Covid lockdowns and the cost-of-living crisis, it has been a difficult few years in which to sell drinks for consumption out of home. These beverage businesses were once considered to be almost bulletproof, but it turns out that they have vulnerabilities after all!
I see that Roland has been rooting around for value in the sector, and has found a few candidates (including Nichols).
Turning back to today’s Q1 update:
Cash remains strong at £57m
The outlook is unchanged (thanks to the company for confirming that market expectations are for adjusted PBT of £25.3m in FY 2023)
We also get some management-related news. John Nichols, the grandson of the founder of the company, will remain on the Board as a NED after stepping down as Chair. The great-grandson of the founder is also a NED. It’s nice to see this continuation of family influence.
Less positively, the CFO has resigned after three years with the company. No reasons are given. It doesn’t look particularly well-planned as the search for a new CFO seems to have only just begun.
Graham's view
We all have our biases and in my case, I like this sector (soft drinks) and I like this stock. I like the heritage at Nichols and its long-term financial results, even if recent years have been more difficult.
That’s why I’m going to continue to give this stock the thumbs up, thinking that it can only be a matter of time before margins are restored as inflation feeds through the economy, and before out-of-home consumption returns to its previous popularity.
I could be wrong, of course. Or I could be too early, which is the same thing!
Turning to the chart, I am reminded that it has been a “lost decade” for Nichols shareholders, as the shares have made no progress since mid-2013:
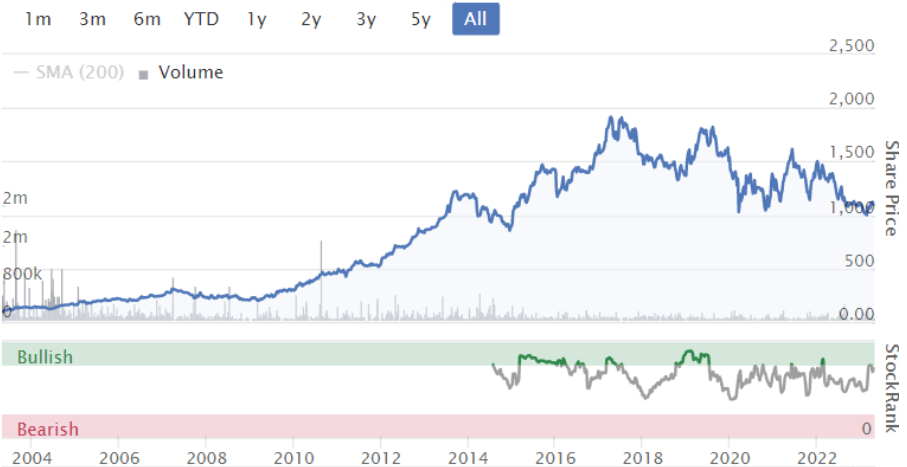
Revenues in 2013 were £105m, versus £167m forecast in 2023. So progress has certainly been made since then! Profit growth simply hasn’t lived up to expectations yet - but I still think there is a good chance of improvement in the years ahead.
Elementis (LON:ELM)
Share price: 117.8p (-1%)
Market cap: £689m
This is a specialty chemicals company that rarely (if ever?) gets mentioned in these reports. Perhaps we should give it a chance?
It’s an international company with leadership in New Jersey, Amsterdam and London. According to his LinkedIn, the CEO seems to be based in New York.
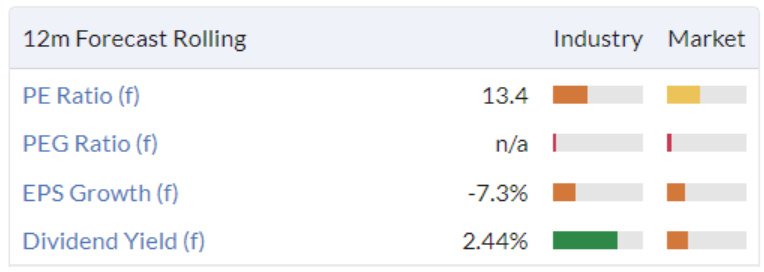
Earnings have been very volatile over the years, but it’s currently offering some value on a PER basis:
Today we have a Q1 update:
Trading is “resilient against continued subdued market demand conditions”, in line with expectations.
Revenue is “flat on an underlying basis against a strong prior year period”
Performance Specialties: performance is weaker due to “continued challenging demand conditions”.
Personal Care: performance has improved, thanks to higher margins on stable volumes. Comments suggest good pricing power here.
Outlook:
The year has started as expected with the benefits from self-help and pricing actions offsetting market related volume softness in Coatings. For the full year, we are confident that further strategic progress will drive improved financial performance and a further reduction in leverage, in line with expectations.
Let’s check how leveraged they are. According to the full-year results for December 2022, they had net debt of $367m (plus some lease liabilities). But they also sold a subsidiary for $119m in January 2023, with “pro forma” net debt to EBITDA falling to 1.9x. So their leverage appears to be under control, so long as earnings remain solid.
My view
Chemistry was my least favourite subject in school, and perhaps it’s no surprise that I can find the chemicals sector to be a little dull!
I’ve been dimly aware of this stock for a long time, without ever examining it in too much detail. But it’s been a respectable FTSE-350 member for many years and if you’ve got any interest in the chemicals sector, it could be worth a closer look.
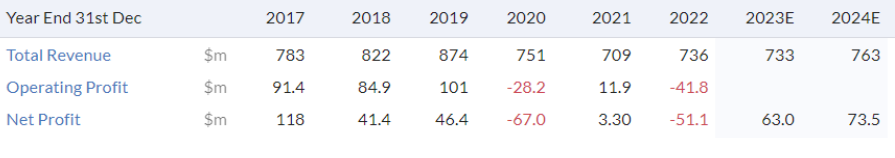
Last year’s $51m loss involved a $103 goodwill impairment. Hopefully better days ahead.
Learning Technologies (LON:LTG)
Share price: 109p (-16%)
Market cap: £861m
Learning Technologies Group plc, a global market leader in digital learning and talent management, announces results for the year ended 31 December 2022.
I thought I would add a few words on this one, as it has suffered a significant fall in its share price despite reporting “revenues and profit ahead of expectations, as previously announced” for 2022.
Revenues have more than doubled to nearly £600m, and adjusted EBIT is over £100m (actual PBT is £40.5m).
The problem is with the outlook statement:
Despite a more challenging macro environment, we have seen moderate revenue growth in Q1 and continue to expect to deliver high single-digit adjusted EBIT growth in 2023, supported by a strong pipeline
They reiterate that they are on track to meet 2025 goals, but the market can’t look past a disappointing outlook for the year ahead.
According to prior broker forecasts, adjusted EBIT was supposed to grow by c. 16% in the current year.
Instead, investors can only look forward to a “high single-digit” rate of growth, i.e. 7%-9%.
So when the company says that they “continue to expect to deliver high single-digit adjusted EBIT growth”, they are actually delivering a profit warning, because this is worse than prior expectations.
Graham’s view - I haven’t got a strong opinion on the merits of LTG. It appears to be a varied mix of businesses, some of which might be decent quality, I’m not sure. I just wanted to clarify that today’s announcement is a fully-fledged profit warning, in case anyone was wondering.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Hi Paul/Graham,
Polarean Imaging (LON:POLX) is an interesting one, I’m keeping a close eye on conversions and first unit sales. Main aim initially I believe is selling to the top of the pyramid with theory that the rest follow suit.
Important quarter for news so one to follow i agree.
Hello Paul/Graham, the tags have missing apart from Warpaint London (LON:W7L) on today's report.
I bought into Persimmon recently at around the current price. It was a very basic thesis that the stock is back to 2014 levels after a 2/3rds decline from its peak. It hasn't bounced at all since October despite the stock market and economic outlook moderating substantially since then.
I'm looking to move house currently so have a very active interest in my local property market. Things seem quite strong at the moment, after grinding to a halt for a few months late last year.
Mortgage rates are only 4.5% which is very 'normal' if we look at the pre-GFC period. People have had very large wage rises and I think the economy is just fine, right now. It's been the most eagerly awaited and most 'certain' recession in living memory. But not everything is a 2007-09 or 2000-02 type event, and I'll react to a 'proper recession' if/when it happens.
I could easily envisage a quick pop back to 2,000p on Persimmon. That's what I'm hoping for, at least!
I see Card Factory (LON:CARD) released a later (than 7am) RNS stating an acquisition.
I have followed this for a few years now and tbh it’s starting to look interesting for a long hold. Previously I’ve shorted this share as it looked like it wouldn’t survive but now I’m rather impressed.
Hold Card Factory as well. Local ones always seem quite busy and debt looks very manageble considering the high margins against running costs with the small outlets, very cash generative. Seem to have bumped prices up a bit recently but sending a card is a pleasure for many.
Interesting point Graham makes on Learning Technologies (LON:LTG) trying to sneak out a profit warning.
Couple of points Id make. Why would any private investor buy a company who use a broker refusing to publish on researchtree unless they're very good at reading balance sheets. Straight away you're at a disadvantage.
Learning Technologies (LON:LTG) says EBIT growth will be high single digits, the additional language used in the outlook statement is positive. Asked Bard, it gave 8 out of 10 and outlook positive.
Reality is EPS lower than forecasts, margins under pressure, EBIT forecast growth roughly halved. Peel Hunt cuts EPS by 13%.
Is it really worth the effort having to run around playing the game of find the forecasts, when the company (which we're supposed to be part owners in) can just include it in the RNS or use a decent broker.
re Sherborne Investors (Guernsey) C (LON:SIGC) (I own)... Navient results for Q1 are out. The call is at 1400. They look pretty positive to me without being blockbuster. Maybe something comes out of the call.... Nothing yet has been announced re a significant restructuring or strategic review... although Sherborne normally push for this. The discount remains huge at nearly 30%... staying patient is never easy but im still hopeful of north of 100 which is plenty from current levels.
re Persimmon (LON:PSN) and house builders, I have to say I find them somewhat curious. If you believe rates return to very low levels increasing mortgage availability and affordability then they will rebuild value from current levels and all are a buy. I lean the other way if pushed but also think the cycle has peaked....so does a softer rate outlook open the path for better share price perf.
On the face of it, and keeping it simple Id say yes. Leave it at that. BUT if you had to push me what could go wrong rather than just argue rates stay higher...inflation sticky etc.... maybe it's more subtle... and rate uncertainty and a more volatile cost outlook means its a more difficult business. Last ten years pretty much everything went their way... costs well behaved, land buying ditto, interest rates lower and lower and lower. If looking forward it's a bit more tricky, returns and margins will be lower. So ratings will be lower. So price to book has fallen .... for Persimmon (LON:PSN) its above 1.1x... which seams fair enough to me. PE may well reflect overly cautious guidance although the divi guidance remains somewhat lacklustre. If they can grow the current 5% ish yield at 10% per year then I think they are a little cheap but not screaming cheap. I can of course get a not growing nearly zero risk 4% off the government.
Traditionally the period Nov - May is the time to own these stocks... and has played out gain this year. Persimmon (LON:PSN) was the most expensive, had the highest margins, returns and price to book. It was the default long versus short the others which has reversed over the last 6 months.... maybe other factors but I guess mainly that.
On balance they look fair value to me ... with the stretch in spread between Persimmon (LON:PSN) now much much lower there is probably some catch up.... Im not massively excited either way though and have no positions.
I take a very different view.
The persimmon share price is at around a 5 year low, falling by around 57% in 2022. And a further 10% at the end of March, on slowing sales and a short term poor outlook. Despite the obvious headwinds for housebuilders in the short term, I do think as inflation eases and if we do enter a recession, demand will collapse significantly and so too in due course will interest rates subside and mortgage become easier to obtain and be available at lower interest rates. We may not need to wait too long for nascent buds of improvement but with the stockmarket being a forward locking mechanism, share prices will rise long before the upturn and in some cases substantially so.
Currently, Persimmon, trades at a PE of around 7x, has £800 million of cash on the balance sheet, no debt, they have a massive land bank and unending demand for new homes. A five year average return on capital of 23%, a return on equity of 25% and an operating margin of 26%.
On a quality and valuation basis, I think this share looks a very good prospect and in the meantime, while we wait for a share price recovery we are compensated with a yield of over 5%. I bought a position after fall in March and will buy more on any further short term share price weakness.
Yellow Cake (LON:YCA) estimated NAV at 25 April based on spot U3O8 @ 53 and assuming delivery of the recent Kazatamprom order = 446. At 375 that's a 15% discount....attractive if you like the idea of Nuclear driven Uranium demand. The long term cost curve points to levels between $75 and $100 ....shortages could results in higher prices. Ive held this for some time now, plenty of interesting commentary in the statement for background if you are interested. If momentum picks up the discount normally narrows.
If you want to get the vibe on uranium market short term then the Cameco (TSE:CCO) Q1 update this Friday is the significant newsflow as they will give info on underlying dynamics in this small opaque market. The market in both physical proxies like Yellow Cake (LON:YCA) or Sprott Physical Uranium Trust (TSE:U.UN) can move off it (discounts widening/narrowing) and uranium equities (Sprott Uranium Miners UCITS ETF Acc (LON:URNM) good proxy). Depending what Cameco say Friday the market can move a lot. I've got no forecast for you, just pointing out a near term event!
Not really proxies as both own physical Uranium.
Most U near producers are valued as if U is already US$60/llb .... we ain't even there yet. The last time we had a screaming bull in Uranium, the equities were cents; this time around they are dollars.
I don't understand the point you are making as it seems to be different from issue discussed...so as stated they are proxies to physical uranium which is what Yellow Cake (LON:YCA) holds which was the company first discussed by someone.
'Spot' uranium is a slippery fish as there is no immediate exchanged based market and then the forward market which is where most transactions occur is super opaque and loads of agreements (a utility with a producer typically) don't get reported at all. The 'market price' is really a reported price by two consultants. There are many issues and gripes with how they report. I'd say take the reported spot price (currently $52) as the minimum price that is transacted on...then I think transactions (forward agreements) are taking place at probably up to $70.
At the moment its assumed that contracting takes place near and above $60 at least. As that is the 'real' but opaque market that means we are already around $60,
'Downstream' uranium prices have spiked hugely since the Russian invasion (as near half of that capacity is russian)...that enrichment and conversion prices. As the processing takes c.12-24 mths depending on bunch of factors there is a lag on hitting the uranium price. So at the moment raw preprocessed uranium not moved so much....but tick tock and need to feed the fuel fab cycle.
Valuing the equity is very tricky. I'm happy to discuss that more but the cents v $$$ point is a nonsense...so if you want to make an actual substantial value statement/comparison then please do.
The biggest non producer (so development stage) company is Nexgen Energy (TSE:NXE) . Its US$1.75bn market cap and burning cash. A high risk investment. But with a very high grade proven asset with upside development potential its easy to make an argument that its super value despite a C$5 sp, with potential for meaningful multiples upside depending where place one's flag on assumptions (ie, annual FCF could be at or exceed current market cap...depending on assumptions). I'm not tipping it....just using the biggest development asset.
UAE opened its third nuclear power station in OCT22 with a standardised design from KEPCO Engineering & Construction Co (KRX:052690) based on a US approved Westinghouse (Cameco (NYQ:CCJ have the IP I think) system. Cleaner, cheaper, provides base-load and energy security for 60 years.
Meanwhile in the UK we pray for inclement weather.
I see the Central Intelligence Agency getting a slap on the wrist for poor etiquette by UK standards and will need to sit in the corner for a few weeks until they behave better -> Narf Industries (LON:NARF)
I was reassured by the TU from Trifast this morning (we hold) and a bit surprised by the early bounce. You gave it an Amber on Feb21st Paul, is the bounce worthy of a quick look at the TU?
Sureserve cwindfall
Sold all my Sureserve yesterday that puts me back into a high cash position from fully invested .
Think we’ve had a decent rally last month so might just park it .
Wynnstay I might top up on, it’s looking pretty bombed out and out of favour has come off a long way. Despite last year being “a one of” it’s almost down to levels of feb 2021 which is illogical
Since then it’s got retained earnings from the one off , several acquisitions for cash , plus a fund raise at 580 if I remember .
Below NAV , with cash , making money . Looks oversold and it’s a great long term one .
Glad to hear your thoughts on Wynnstay (LON:WYN) , planetx. I hold, and your analysis is v helpful.
Re Wynnstay , thanks for that planetx, just bought a few, the spread was big but Barclays smartinvestor (they hadn't got me in mind when they named it) got well inside at 336. Will monitor and add.
Barclays have never been that efficient for me !! I think you meant 436 8-)
I did mean 436 JimMcLad, I got over excited while typing!
436 or 336? That’s a steal if it’s the latter!!
Restaurant (LON:RTN) looks like more news from activist shareholder yesterday having upped shareholding significantly, does anyone have any views on what will happen next? Share price looks cheap but sector massively impacted by cost of living / inflation squeeze.
Persimmon and other housebuilders: current trading might be better than expected, but how high do mortgage rates end up going, given failure of the Bank of England to raise interest rates in time versus inflation; it now becoming ingrained?
Like Persimmon (LON:PSN), I'm 'contrarian' on this subject of interest rates. The hugh hike in rates has led to far higher mortgage costs, the effect of which is still to come as fixed rate deals come to their end; rents also higher. Power companies have been allowed to increase their prices exponentially despite a large proportion coming from renewables the cost of which has not increased. And where is all this money ending up - the major banks have been steadfast in keeping their savings rates down - now the BoE asks people not to seek higher wages....!
The government is always talking of achieving a growing economy - but quite the reverse is on the cards as we all have so much less to spend.
I am encouraged by the results fromRBG Holdings (LON:RBGP) which I hold.Buried in the Statement is the news that they had 4 offers for Lion Fish and due diligence is underway. This seems like a potentially good outcome as the disposal will help to reduce debt and give the Company a share in any successful outcomes from the Litigation Finance cases.
It will be interesting to see how the market reacts to these full year results.
RBG
Watch those freebies they like putting in their pockets and taking out of yours .
Self serving management with a proven history of rewarding themselves with literally millions of free charge shares for achieving the simple hurdle of turning up for work .
I’d avoid this company like the plague .
RBG Holdings (LON:RBGP) has changed. The previous CEO was given the boot and the previous CFO decided against staying even with the share options. It's a completely refreshed board with the exception of the Chairman. They are disposing of their litigation finance venture LionFish which, apart from having a very odd name, incurred significant losses. 4 offers have been received and one is at the due diligence stage. They will be focussing on their core profitable businesses. Given the very low share price, I think the future is actually quite promising. The main problem point is the ex-CEO Nicola Foulston still holds 12% of the shares. I would second a request for this to be looked at today, though appreciate there are so many results out this week.
Thanks for reply .
Probably worth asking the chairman to clarify what is the policy going forward regarding issuing
- zero cost options to management without any performance criteria
- zero cost options with performance criteria
If they dodge the question or answer yes I would not waste your time holding .
I raised this at an AGM last year with chairman of Holders who owns 40% and I’m on around 12%, and said if they ever did that would be simpler for me just to give them cash out of my pockets there and then and we could get it over and done with .
He did say they thought that would never happen and they would not be stealing ftom fellow shareholders .
"zero-cost options" are shares by any other name, normally needing to be held for several years. The quantum matters but if a reasonable alternative to an upfront cash payment, that's ok.
The cost depends on how their financed (something often overlooked) - if they come from newly-created shares at the time of vesting, that's a dilution for shareholders; but if they're bought in the market and held in a trust (or transferred from Treasury) at the time of grant, that's effectively a cash cost - any subsequent gain its paid by the market and not the company itself.
There is an investormeetscompany presentation at 10:30 so perhaps we can find out then!
My morning smallcap tweet: Supply of credibility?
Supply@Me Capital (LON:SYME) Narf Industries (LON:NARF) Brickability (LON:BRCK) Trifast (LON:TRI) Arecor Therapeutics (LON:AREC) Polarean Imaging (LON:POLX) Physiomics (LON:PYC) Warpaint London (LON:W7L) RBG Holdings (LON:RBGP), Sanderson Design (LON:SDG), Dar Global (LON:DAR), Nichols (LON:NICL), Image Scan Holdings (LON:IGE), Biome Technologies (LON:BIOM)
◄Supply@ Me Capital (SYME)► commitment for first Inventory Monetisation transaction from traditional funding sources. WIll monetise up to €1.2m of warehoused goods. Zomboni trills "we are breaking down remaining barriers to Supply@ Me Capital being recognised by potential funders, globally, as the unique access point to a novel and untapped real asset class...". Whatever. [SP=0.05 Cap=29m]
◄Narf Industries (NARF)► audited FY-Dec will miss end Apr deadline because auditor asks for "additional evidence regarding invoices and the timing of revenue recognition that involve very sensitive and confidential United States Government contracts and their associated milestones". Shares wil be suspended .Trading in line. [SP=0.92 Cap=16m]
◄Brickability (BRCK)► guides FY-Mar rev up 31% and 4% LFL. Adj EBITDA £50+, ahead of market expectations of £47.1m. [SP=65.68 Cap=197m]
◄Trifast (TRI)► guides FY23 adj pretax marginally ahead of the Feb guidance. confident of a marked improvement in FY24. [SP=62.6 Cap=85m]
◄Arecor Therapeutics (AREC)► get US patent for "a novel formulation platform that enables the development of enhanced monoclonal antibodies". [SP=267 Cap=82m]
◄Polarean Imaging (POLX)► first order for XENOVIEW gas blend One cylinder. [SP=24 Cap=51m]. I hold.
◄Physiomics (PYC)► signs Collaborative Services Agreement with ValiRx's subsidiary Inaphaea BioLabs. "Service users of Inaphaea will be able to benefit from Physiomics capabilities in a single service contract with Inaphaea." [SP=2.82 Cap=3m]
◄Warpaint London (W7L)► FY-Dec. Current trading sounds in line plus "significant further expansion in the US with H-E-B stores, CVS BIRL stores, where initial sales have been ahead of expectations". [SP=195 Cap=150m]
◄RBG Holdings (RBGP)► FY-Dec. Current trading sounds in line. [SP=44.24 Cap=42m]. I hold.
In line: SDG, DAR, NICL, IGE, BIOM
RBG Holdings (LON:RBGP) - any thoughts would be very welcome
We could do with knowing what Nicole foulston is doing with her holding. I hold
RBG Holdings (LON:RBGP)
Investor Meet Company at 1030 this morning.
Surprised and happy with the trading update from Brickability (LON:BRCK) . Trading ahead of expectations, revenue forecast at £645m, but coming in at £681. Net debt down to £8m. They give the dreaded 'adjusted EBITDA' figure but still, this figure of £50m compares to £40m last year so can we expect a similar rise in EPS as well ? They have a forward p/e of 6x and the sp has been battered this last year so I think we can expect a nice rise from here.
Sanderson Design (LON:SDG) final results for the year to 31/1/23 look just about in line with the last forecast I saw (Progressive note end of March) and a slight beat compared to Stocko concensus.
Progress with licensing, US sales and Morris & Co but sales down at the other brands.
Sounds like a reasonable outturn considering the state of consumer confidence through last year although volumes are likely down even though revenues are flat. Interested in your thoughts Paul & Graham.
Thanks Sutters, not sure why by SDG results didn't come up on my trawl of the RNS.
I'll definitely take a look later this week, thanks for flagging.
Regards, Paul.
Warpaint London (LON:W7L) as a shareholder I am pleased with todays results
Cash balance growing nicely from £5.9m at year end to £8.6m on 31/03
US looks to be well and good to see direct online showing growth (off a small base)
I hope you might find time to comment today Paul or Graham please?
RE: Warpaint London (LON:W7L)
Sales up 28%, international sales up 48%, profit margin up to 36.4% (from 33.8%), adjusted eps up 44%, final dividend up to 4.5p (from 3.5p), record cash in bank, launches into Asda and New Look in the UK and Sallys and Nordstrom in US.
https://www.londonstockexchang...
The lipstick effect is a mighty powerful thing.
timarr
Warpaint London (LON:W7L) I don't understand why this is (8.19 am) drifting in the market. Were the expectations that high? So the UK is in real terms treading water (or worse) but the growth in the rest of the world is impressive. If they can work in the US, then they have a fantastic future. The US trial was going into a limited (22???) number of stores in a group which has 9000, so if that trial is a success (which the sales increases suggest) then that would be transformational. The market does not agree with me though as we are now down to to £2.04 to buy from £2.13. Is this going to be one of those stocks that it will take a few days for the penny to drop? At the moment I'm being told I'm clearly wrong.
W7L Great results today followed by upgrades from Shore Capital. I believe priced about right in current market and expect SP to increase as earnings come through in 23 & 24.-Current pe =16 falling to 14 in 24. -I am holder
I am a holder and very pleased with all I've read today, plus what I believe will come about going forward
Re £WZL I have been holding back on this to see how the Us is playing out. It seems to be going well beyond the Xmas present type distribution it was achieving. PS I ma impressed they have their own distributor over there, not attached to a long list of product being touted by another distributor. So great promise there.
Continental Europe seems ot be going very well indeed too, growing into the biggest section of the business.
They have people on the ground in Hong Kong, helping their penetration of the Chinese market and their production sourcing. The launch into Japan will be intriguing.
The distribution gains in the UK going forward are exciting, given that the real base for take off was the Tesco model which has grown well. There seem to be promise of future Tesco distribution gains there still, even now.
A very down to earth company, having made a clear out of the also ran product elements that can slow down every element of future growth. Focus, focus, focus on the 80:20 rule - focusing on the 80% from the 20% of the lines and they wont go far wrong.
Virtually doubling in price this last year, naturally the PE is high, but I believe we can expect high growth across a wide range of significant territories going forward, especially with value for money being the name of the game in our high inflation world.
What a gem...and I could listen to the management presentations all night -like a feature film, music to my ears. They make so much sense - but sense is simplicity carried supremely well.
PS Not doing very well with getting the £WZL company up there in blue. Using my normal route. Failing. Help!
Warpaint London (LON:W7L)
That's because it is W7L notWZL
PS Not doing very well with getting the £WZL company up there in blue. Using my normal route. Failing. Help!
Cos it's a seven in the middle not a zed - W7L = Warpaint London (LON:W7L) :-)
timarr
Q1 of the new year looks very strong and whilst the company statement today did not specifically upgrade expectations, I see Shore Capital have done so, lifting FY23 EPS by 10% and also lifting medium-term forecasts. Looks like the earning upgrade momentum continues here!
Warpaint London (LON:W7L)
Another request for Paul or Graham to take a look at Warpaint's results.
Please.
Hi Aston Girl,
Took me a while to get round to it, but I've just finished my review of W7L results. Looks excellent! As regulars know, I very much like this organic GARP share. Will try to interview the CEO again on my return to the UK.
Regards, Paul.
Hi Paul,
Thanks for your work on Warpaint London (LON:W7L) today.
I had done a lot of research on the company just before your interview of their CEO Sam Bazini in January, which was the catalyst for me to take a position, another thank you.
The investment case here looks fairly compelling.