Small Cap Value Report (Weds 26 June 2024) - CMCX, MEX, VLX, MSI, W7L

Good morning from Paul!
All done for today, sorry for some sections being slow to gestate.
Starting off with my delayed review of CMC Markets (LON:CMCX) below, mine and Graham's star performer from our 2024 shares ideas lists, up 200% YTD - is it time to take profits, or has it got further to run? Who knows, that's for the market to decide.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
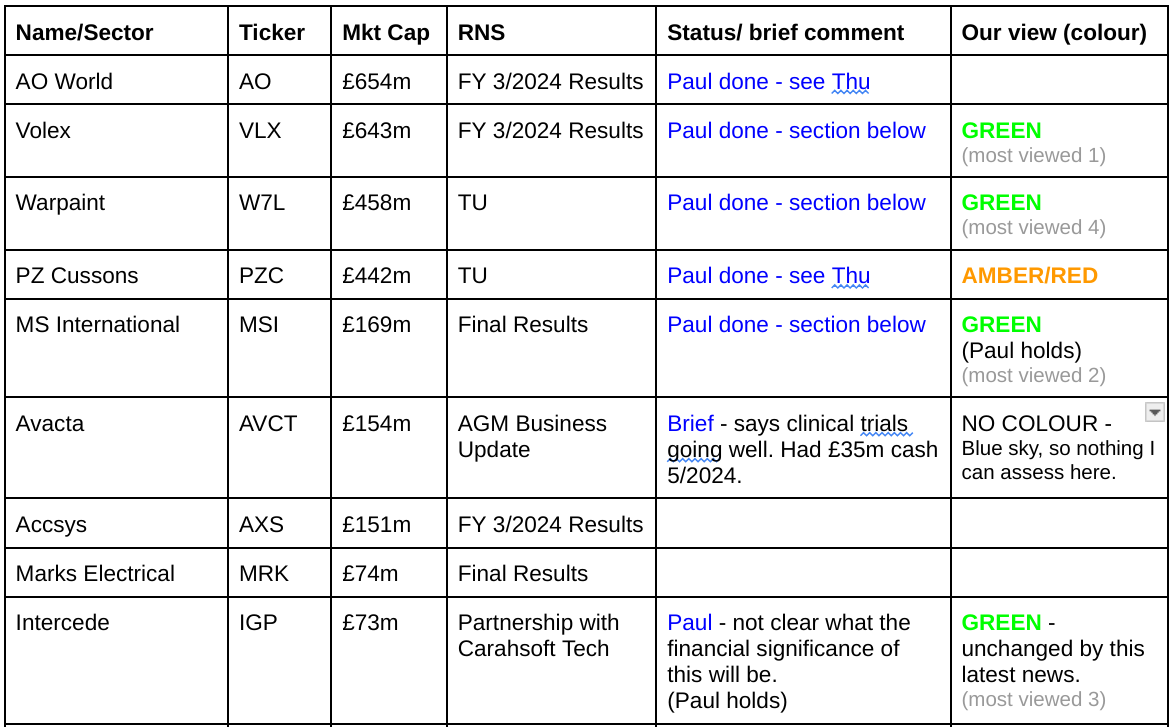
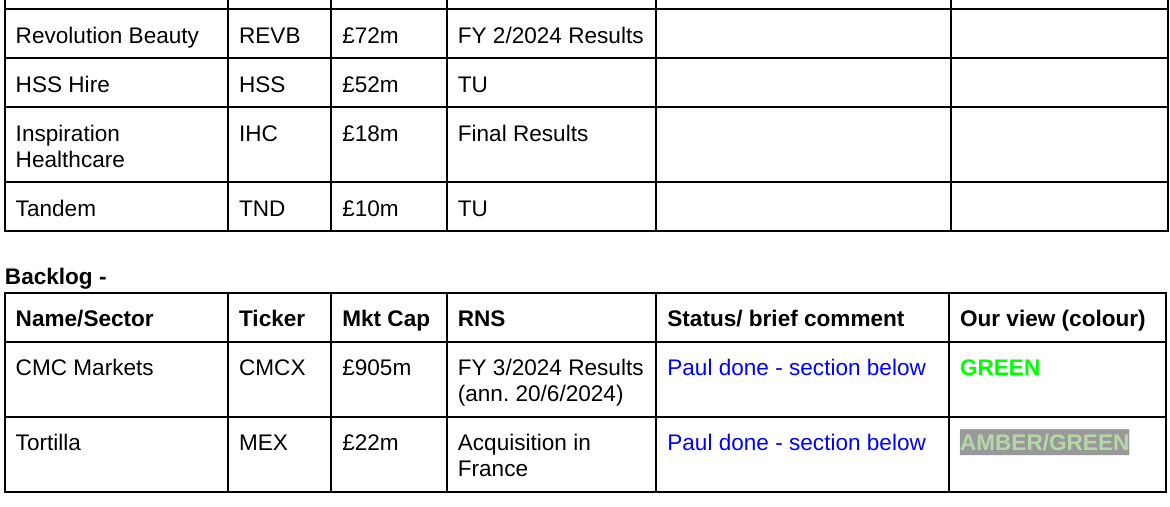
Companies Reporting
Summaries
CMC Markets (LON:CMCX) - 314p (£878m) - FY 3/2024 Results (ann. 20 Jun 2024) - Paul - GREEN
Our star pick here at the SCVR, coincidentally chosen independently by both Graham and I for our top 2024 share ideas lists. Now up more than 200%. Has it peaked now? I have no idea, shares can do anything, as we know. Although crunching the numbers, I feel the 3x higher valuation does indeed stack up, so I'm sticking with GREEN.
Tortilla Mexican Grill(LON:MEX) - up 10% y'day to 57p (£22m) - Acquisition - Paul - AMBER/GREEN
Announces an interesting deal to acquire an established French burrito chain. It dents short-term profitability, but management reckon they can turn it around in 2 years, and use this as a springboard for European expansion. I discuss the bull & bear points, concluding moderately positively - the valuation seems too cheap, but I'd prefer a more robust balance sheet.
Volex (LON:VLX) - down 6% to 334p (£604m) - FY 3/2024 Results - Paul - GREEN
Good results for FY 3/2024, slightly ahead of broker consensus. I run through the detail below, and come away happy. This share strikes me as good value, so I'm very happy with GREEN.
MS International (LON:MSI) - up 7% to 1,100p (£180m) - FY 4/2024 Results - Paul (I hold personally) - GREEN
Fabulous results, with profit tripling. Defence division generates almost all the profit. Order book up again. Balance sheet strong. Ageing owner-managers likely to sell the business at some stage I suspect. With such good figures, and "excellent prospects" for the defence division FY 4/2025, I'm inclined to let my winner run.
Warpaint London (LON:W7L) - unch 588p (£458m) - Trading Update (AGM) - Paul - GREEN
Strong growth continues at this makeup company. It doesn't refer to performance vs market expectations, but does say H1 revenue is rising faster than forecast. H2 weighting as usual, due to Xmas. Share price looks up with events, but with a positive outlook and tendency to beat forecasts, I'm inclined to remain positive on W7L, although top-slicing after a 6-bag rise also looks prudent, but that's up to you!
Paul’s Section:
CMC Markets (LON:CMCX)
314p (£878m) - FY 3/2024 Results (ann. 20 Jun 2024) - Paul - GREEN
This financial trading platform has put in a remarkable turnaround.
“Net operating income at a post-COVID high. Adjusted profit before tax up 52%.
Cost efficiency programme in place to drive profit margin expansion.”
Adj PBT rose an impressive 52% to £80m.
“...consistently strong performance throughout H2”
...in both institutional and retail divisions.
“several major client wins during the year and a strong pipeline of potential clients.”
Higher interest rates boosted profit by £22m.
Dividends total 8.3p for the year (up 12%), a yield of 2.6%
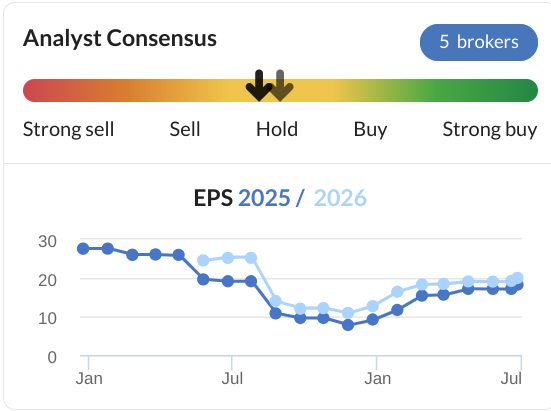
No broker notes available to us. But broker consensus forecast has been on a strongly positive trend, more than doubling from peak gloom in Nov 2023 -
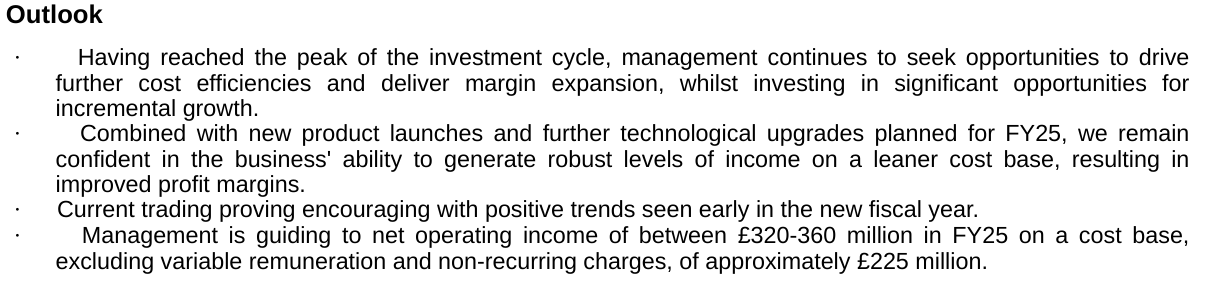
I wish they would give simpler guidance just saying what they think the range of PBT outcomes is likely to be, rather than providing some elements and then leaving it up to us to put them together.
Net operating income was £333m in FY 3/2024. So the forecast range of £320-360m is quite wide, from a bit below, to almost 10% above.
The cost base (excl variable remuneration) seems to have been £250m in FY 3/2024. So the guidance of £225m above looks to be a £25m cost saving. That ties in with an announcement on 5/2/2024 that it was slashing costs, including 17% of its staff.
Variable remuneration was c.£17m in both of the last two years.
So if I’ve got this right, then they seem to be saying PBT could be between £78m and £118m.
Assuming corporation tax of 25%, gives PAT of £59m to £89m, divided by 280m shares = 21p to 32p forecast EPS.
At 314p the forecast PER for FY 3/2025 is between 9.8x to 15x.
So assuming my figures are roughly correct, then the current share price seems to stack up, and looks about right. Hence my conclusion is that the big bull run from c.100p to over 3 times that price now, this year alone, seems fully justified by the fundamentals.
Balance sheet - was very strong, and this was a key reason both Graham and I picked CMCX for our top 10 & top 20 share ideas for 2024. The rationale being that the share price of 105p at end 2023 was more than fully backed by CMCX’s own liquid assets. So the business was literally in for free. Looking back it was a bizarrely positive value opportunity. Although we didn’t predict it would recover profitability so quickly.
NTAV is now £375m, and it’s a remarkably good balance sheet, groaning with liquid assets. Fixed assets are small, which will just be some office fit-outs and equipment. There are no significant long-term liabilities, other than £12m lease liabilities (future operating rents). So the main assets and liabilities are within working capital, which was £648m receivables and cash combined, less £298m current liabilities. Hence £350m net current assets, and a current ratio of a very healthy 2.18. Remember there are no inventories either, being a service business. The narrative says it’s way over the regulatory minimums for balance sheet strength.
Altogether this is a superb balance sheet. Although NTAV is now only 43% of the market cap, whereas at the start of 2024 the market cap was actually below the NTAV of £326m, which was just a crazy, and obvious valuation anomaly.
Paul’s opinion- something remarkable seems to be happening at CMC. This snippet reinforces that -
“"This strategy, based on continuous product launches and multiple application connectivity through the CMC Markets Connect brand, means we are making great strides in a huge market segment of B2B and institutional business, with limited competition from our peers.”
As demonstrated above, I think the tripling of share price this year stacks up on fundamentals. It’s not even expensive based on the latest guidance.
It’s always tempting to bank some profits after a spectacular run, but I can’t help feeling that something very interesting and exciting seems to be happening here, and the price is far from stretched (providing nothing goes wrong).
I was intending to reduce from my GREEN view, but after going through the numbers and outlook, I’m more inclined to run with it. Sadly I didn’t buy any personally, because I didn’t anticipate that the trading turnaround would be so rapid or sizeable. Never mind.
"Institutional, B2B and multi-asset, multi-currency platforms, across all brands is the future, and ours. We have built the infrastructure which will allow us to significantly increase our growth potential whilst improving profit margins through scale.
"It is going to be an exciting couple of years."
This looks & feels like a winner, so I’m sticking with GREEN.
Tortilla Mexican Grill (LON:MEX)
Up 10% to 57p y'day (£22m) - Acquisition - Paul - AMBER/GREEN
Interesting news yesterday from the UK’s largest Mexican-style burritos chain, Tortilla - it’s bought a small French chain called “Fresh Burritos” for 4m Euros - a mixture of cash (2.7m euros) , and assuming debt (1.2m euros). The target has 13 company sites, and 19 franchises.
Fresh Burritos seems to be operating at a small loss, but MEX sees ways to improve performance -
“expected to contribute £2.5m of additional annual adjusted EBITDA (pre-IFRS 16) at 24 months maturation.”
We’re reassured about bank covenants - important, as MEX is not well capitalised. I’d like to see it raise more equity once the share price has recovered to a more sensible price (say 100p+) -
“The cash payment has been funded from Tortilla's existing committed financial facilities with net debt remaining well within the Group's covenant headroom ensuring flexibility to continue to fund its plans.”
For full disclosure, I’m not currently holding, as I sold mine a little while ago to raise funds to buy more Zotefoams (LON:ZTF) and Intercede (LON:IGP) . I still like this share though, and it’s on my top 20 share ideas for 2024, because I think it’s a good brand, and there should be upside on future profits once energy and food costs recede, and consumer demand recovers after the disposable income squeeze of the last two years.
This acquisition is likely to weigh on short term profitability a bit.
UK trading update - useful, and sounds OK -
“The core UK business is trading in line with the Board's full year expectations. The Company will provide a market update on its H1 2024 performance in July.”
Paul’s opinion - it strikes me that buying an established operator for a modest price is more sensible (and cheaper) than trying to start from scratch.
Former CFO turned CEO, Andy Naylor seems to be fizzing with ideas, and is getting things done. There was an IMC webinar yesterday to explain the deal in more detail, which I've just watched. There sound credible reasons for the deal (eg well invested sites in good locations), and fairly simple improvements to raise margins (eg central kitchen planned for a fitted out 15k sq.f.t site in Lille), springboard for further European expansion & franchising. My main question is whether the acquired sites have workable rents, or could be too expensive? Also, there will be additional overheads from managing a new French division, and extra costs, whilst it's sub-scale.
Many thanks to Liberum for revised forecasts, which does clobber profits down to breakeven in FY 12/2024, and a 35% drop in 2025 forecast PBT. Although the longer term upside kicks in from 2026. I think this reinforces the reality that MEX shares will probably require patience to see a meaningful re-rating. It depends though, in bull markets, investors are happy to pay up for future upside. Not so much in bear markets. Imagine if this share was a new IPO. I reckon it would get people excited about the growth, and upside potential, and probably list at 100p. So buying now at c.56p includes a discount for disappointment mainly due to tough macro in recent years. That could be an opportunity, time will tell.
Overall I’m probably neutral on this French deal. It might have been better to focus on developing scale and profitability in the UK market, before venturing into Europe? That said, I continue to see this share as under-priced on the recovery potential, so am happy to stick at AMBER/GREEN - positive overall.
Four Directors combined have just spent over £100k buying shares, including the founder, interestingly.
There's not been any dilution since it listed, 39m shares in issue. Some interesting names joined the shareholder list recently, in a clear out of a stale bull holding. I'm anticipating more dilution, but not ruinous - say a £5m placing at 100p in 2025, would be my optimistic guess? Although MEX has confounded the critics by operating fine without any additional equity so far - so I see dilution as being something the company can control, rather than an emergency. That changes the outlook for the shares considerably. As we move from bear market into bull market, it's important to change our thinking, otherwise we'll miss some good opportunities from unfounded fears.
Volex (LON:VLX)
Down 6% to 334p (£604m) - FY 3/2024 Results - Paul - GREEN
Volex plc (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, announces its preliminary results for the 52 weeks ended 31 March 2024 ("FY2024").
Record profits delivered; accelerating strategic investments in growth opportunities
The highlights table shows impressive profit growth, helped by acquisitions (with a corresponding increase in net debt) -
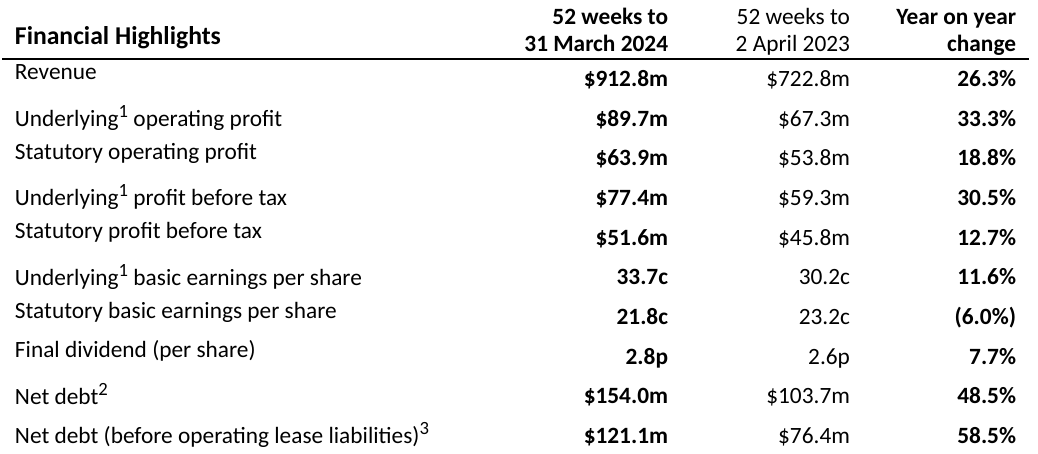
Valuation? EPS of 33.7c (slightly ahead of the StockReport’s broker consensus number of 32.6c) converts into sterling of 26.6p = PER 12.6x which strikes me as a modest valuation for a growing group that is executing a successful acquisitions strategy.
Broker consensus is a further increase in EPS to 36.1c this year FY 3/2025.
Adj PBT growth of 30.5% becomes only 11.6% growth in adj EPS, which seems to be due to an increased share count (179.9m average shares in issue, vs 158.7m last year, a 13.3% increase) and a higher taxation charge.
End markets have once again been mixed, with data centres being the best performer, offsetting some weakness in EVs and consumer electricals. Macro conditions have been tough, and VLX seems to have coped well with supply chain, and customer destocking issues, plus issues re hyperinflation in Turkey, where VLX has made some large acquisitions.
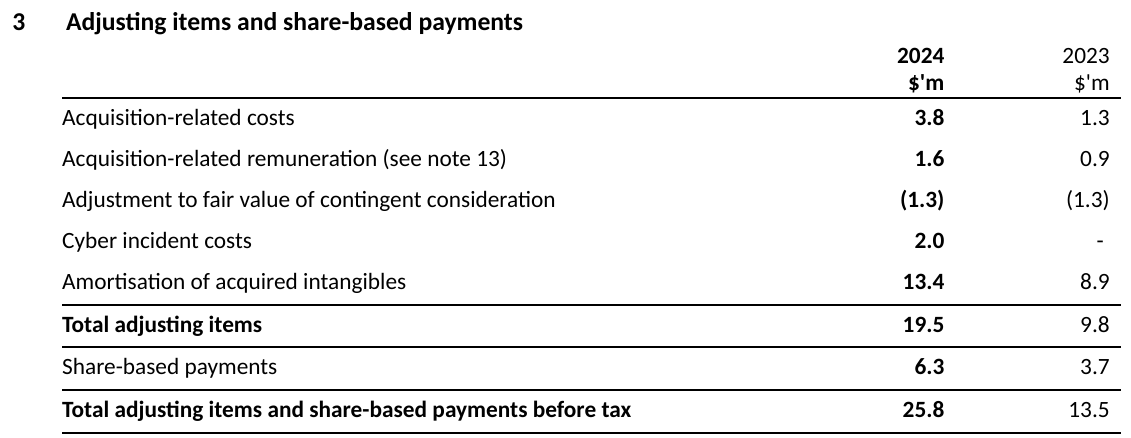
Are adjustments reasonable? I can live with these (table below) although note the share options charge is a fair chunk of the year's profit -
Outlook - some interesting bits below. Overall I think it reads a bit mixed. I would have preferred a shorter, more precise outlook statement, just telling us if they’re trading in line with expectations or not.
“The improvement in demand from our Electric Vehicles and Consumer Electricals customers towards the end of FY2024 and the beginning of FY2025 is encouraging, indicating a reduction in the impact of destocking in these areas. The significant growth in Medical and Complex Industrial Technology included some one-off catch-up due to better component availability, which is not expected to repeat in FY2025. However, we continue to secure new projects in these sectors, demonstrating how our global capabilities and manufacturing footprint support our growth objectives.
There is a significant opportunity to accelerate our growth in the Off-Highway sector outside of existing geographies served by the Group. Based on customer feedback and requests, we are therefore expediting our plans to launch an Off-Highway business in North America. This initiative will underpin our growth strategy in this sector.
With a clear strategy and execution plan for each of our markets, we are accelerating our investment programme to achieve long-term growth. This includes broadly doubling operational investments and raising capital expenditure to around 5% of revenue for the next year. We enter FY2025 with the business in excellent shape, positioning us to meet our five-year plan targets and deliver sustained growth and value for shareholders.”
Exec Chairman Nat Rothschild’s comments seem upbeat -
“Our strategic investments in FY2024 and those planned for FY2025 will expand capacity at key locations to meet anticipated future customer demand, positioning Volex for further growth by leveraging our dominant positions in attractive sectors. With leading positions in our end markets, strong cash flow and robust financial position, we are ideally positioned to capitalise on the significant growth opportunities available to us.
"Our acquisition pipeline remains promising, alongside incremental organic initiatives, underscoring our commitment to achieving our strategic goals. Having started the new fiscal year with strong customer demand, we are confident of making further progress in FY2025 and we are firmly on track to achieve our five-year revenue target of $1.2 billion by the end of FY2027."
Balance sheet - looks OK to me. As it makes more acquisitions, intangible assets (goodwill) are increasing, to a substantial $253m. However, NTAV is still positive if we eliminate intangible assets, at $83m, or £65m. That’s only 11% of the market cap supported by NTAV, so investors need to be aware that there’s little asset backing here.
Bank facilities have grown, but it’s leverage multiple at year end is reasonable at 1.0x.
A new facility of a whopping $600m, unsecured and on improved terms, for 4 years, was agreed in June 2024, so clearly the banks are very relaxed about Volex as a borrower, which is encouraging. Although I hope management don’t over-gear, as we’ve seen with say Victoria (LON:VCP) and the corresponding damage to its share price, and possibly even its solvency.
It probably wouldn’t be appropriate for a humble small caps commentator like me, to lecture someone called Nat Rothschild about banking!
Cashflow statement - looks healthy, with growing operating cashflows. The big item is $134m spent on acquisitions. This was financed through $72m raised from new equity issued, and a $51m increase in bank borrowings drawn down.
Going concern statement is clean, no issues there.
Results webinar details -
A live presentation will be held online at 10.00 a.m. BST on Friday 28 June 2024 on the Investor Meet Company ("IMC") platform.
Broker forecasts - nothing available unfortunately.
Paul’s opinion - this all looks fine to me. I’m surprised shares fell c.6% today on these sturdy results & reasonable outlook. Maybe the talk of short term costs being incurred to increase capacity might have led some investors to trim their short term profit expectations? It will be interesting to see if the broker forecasts dip slightly over the coming days?
I look at things the other way - to my mind, VLX spending money in the short-term to expand capacity and go into new markets where it sees opportunities, is a positive thing, and should result in a larger & more profitable group in the medium term.
Overall, I remain enthusiastic about this share as a long-term holding, being a successful GARP share. So it’s another GREEN from me. I see good upside on this share, for patient investors, and it should attract a more generous PER once we’re more established in a bull market. Could it be a bid target? Anything is possible, but I suspect Nat Rothschild (26%) wouldn’t sell the company unless the price paid was generous. He’s mentioned before in webinars that he sees the share price as under-priced.
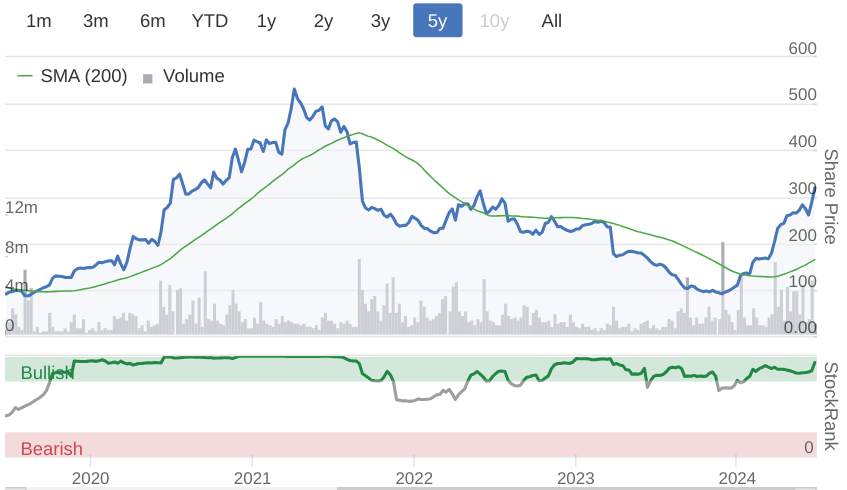
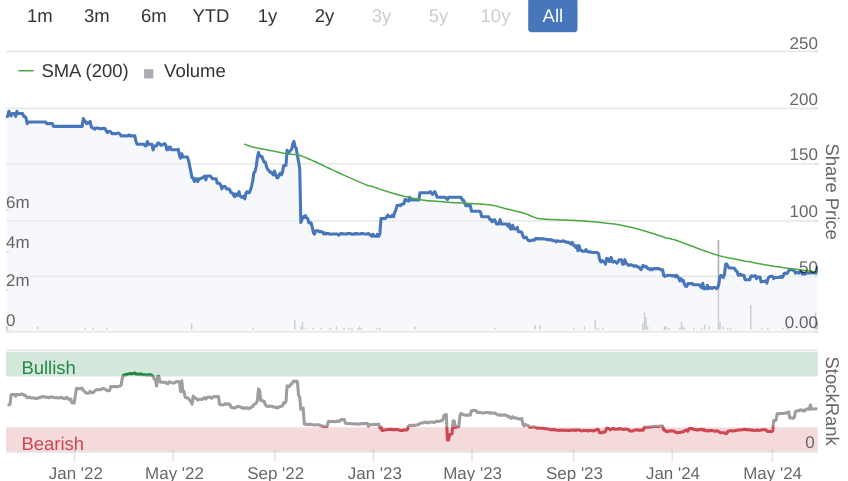
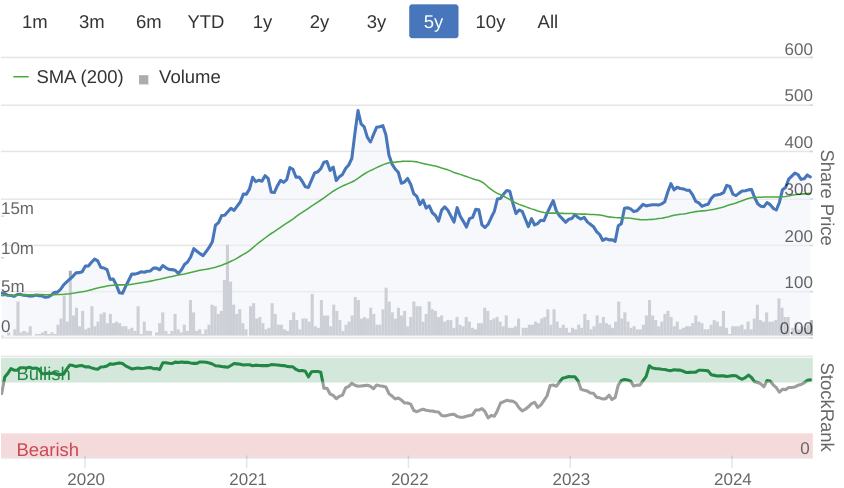
Volex is one my top 20 share ideas for 2024. It's only up 1% YTD, but I cannot see anything wrong with the original share idea, quite the opposite actually, it's performed well on fundamentals, but for unknown reasons demand and supply for the shares seem to be in balance. Maybe there's an institutional overhang, who knows?
Buying the dips looks a good strategy on this share -
MS International (LON:MSI)
Up 7% to 1,100p (£180m) - FY 4/2024 Results - Paul (I hold personally) - GREEN
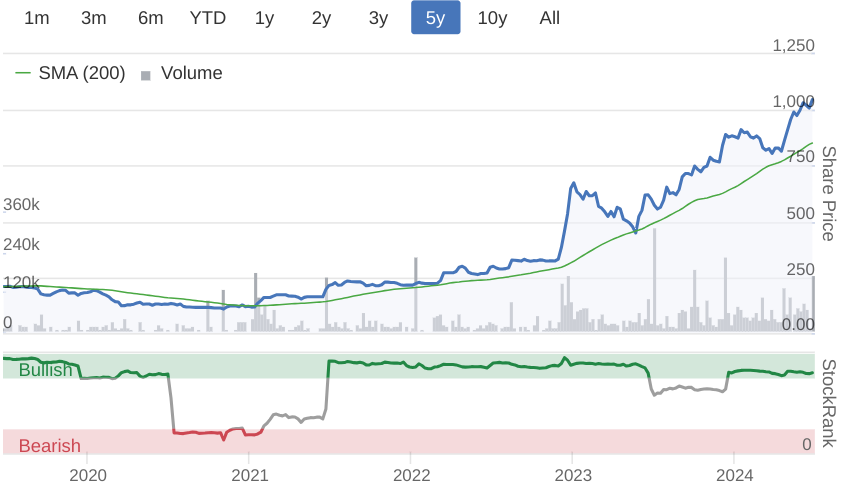
One of our favourite value/GARP shares, MSI was another share that I put on my 2024 top 20 shares ideas list. It’s up about 27% YTD.
Graham likes it too, and in the last year we’ve favourably covered it 3 times -
10/7/2023 - Paul - GREEN - 540p - FY 4/2023 results subdued, due to large order slipping past year end. But large order book suggests FY 4/2024 should be excellent.
3/10/2023 - Paul - GREEN - 780p - Flurry of large military contracts won. Mgt say “significant upwards step change” in performance underway. Exciting.
12/12/2023 - Graham - GREEN - 882p - Strong H1 results. Not overvalued despite big price rise.
So this was a good company, with strong prospects, hiding in plain sight! One reason it could have been overlooked is because owner-managers don’t seem very shareholder friendly, and there are no broker forecasts, so it wouldn’t come up on any screens for broker upgrades. Investors who did their own research, or just read our reports, have done nicely on this one so far.
The company has several seemingly unconnected niche divisions -
Defence - the most exciting bit with large US, Royal Navy & German navy orders (>£100m intake in the year). This division generated nearly all of the group profit, at £13.0m operating profit (vs only £2.0m LY). Group total operating profit was £14.8m.
“...will make MSI the current primary supplier of small calibre naval weapon systems to three of the major 'NATO' navies.”
“All told, we perceive that the excellent prospects for the division bode well for the current year.”
Forgings - has had a softer year.
Petrol Station Superstructures - difficult year, impacted by Ukraine war, but achieved breakeven.
“Looking forward, the outlook for the petrol station forecourt industry in the UK looks promising. In eastern Europe much depends on what happens in reaction to the ongoing war in Ukraine.”
Corporate Branding - has restructured, after disappointing performance.
“We are confident that the UK based operation will continue to flourish as we invest further to grow its capability. The restructuring programme, to re-align the Netherlands and Germany based businesses to a more sustainable level, is progressing to plan.”
Some numbers for FY 4/2024 -
Revenue up 31% to £110m
PBT up 209% to £15.7m, an outstanding result.
Diluted EPS is up 179% to 67.5p = PER of 16.3x
Balance sheet is healthy. NAV £50.8m, less £2.4m intangible assets = NTAV £48.4m
Cash has shot up from £12.3m to £35.5m, but I would treat this as partly a red herring, since contract liabilities have also shot up, so it looks as if some of the cash is up-front payments by customers, confirmed in the cashflow statement.
Overall the balance sheet is comfortable, and low risk.
Dividends are fairly insignificant at total 19.5p for the year, yield of 1.8%. I think the business has the capacity to pay more in divis in future, providing performance continues to be strong.
Paul’s opinion - beware of my unconscious bias, as I own shares in MSI.
These results are obviously superb, but reinforce to me that it’s now a bit of a one-trick pony. Almost all profits come from the defence division, so that’s the area to focus on in your further research. If this was just a one-off good year, then the shares could be overvalued now. If however, this bumper year is the start of a new era of high performance, then shares could continue rising. The naval guns have been ordered by 3 NATO navies, which tells me MSI has something special on offer. Also its anti-drone guns seem to be very topical, and attracting interest.
What we really need is more detailed information from the company, via broker notes.
The order book growth is of key importance, and this gives me confidence -
“The Group's order book has, once again, risen substantially to a record value of £162m (2023 - £115m) at the year-end”
The other divisions are a sideshow. Maybe MSI should sell-off these, and become a defence pure play share, probably achieving a higher rating, and possible takeover bid activity (since owner-managers are getting on a bit, that’s the likely exit route I imagine).
I’ll stick with GREEN, although I don’t have enough detailed information about the company to make me totally confident about the outlook, there is an element of guesswork in my view.
Warpaint London (LON:W7L)
Unch 588p (£458m) - Trading Update (AGM) - Paul - GREEN
Warpaint London plc (AIM: W7L; OTCQX: WPNTF), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands…
This is another of our long-term favourite GARP shares here at the SCVR.
Good growth in revenues again, up 25%, and margins improved -
"The Group continues to trade strongly with sales for the six months to 30 June 2024 expected to be approximately £46 million (six months to 30 June 2023: £36.7 million), with margins continuing to be robust and ahead of those achieved in 2023. Consistent with previous years, due to Christmas gifting orders and the Group's momentum, sales are expected to again be second half weighted.”
Outlook - its growth strategy of focusing on larger retailers globally, seems likely to continue delivering more growth -
"Further progress continues to be made with expanding the Group's presence in larger retailers globally and the Group has significant further opportunities to grow sales, both with new and existing customers. The Group has a number of planned product roll outs to additional stores in the second half of the year and remains in active discussions with a number of UK and overseas retailers about stocking the Group's products.
Valuation - shares have been a remarkable gainer, and congratulations to the many subscribers here who hold W7L shares -
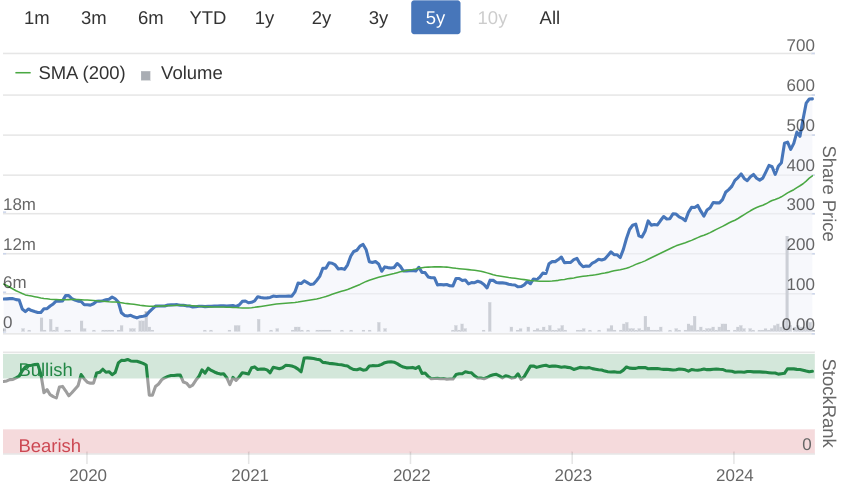
I think the valuation looks fully justified, because EPS forecasts have tended to be much too low previously, so the forward PER of 24.3x will probably turn out to be a good bit lower than that, since earnings tend to beat forecast.
Paul’s opinion - it would obviously be tempting to bank some profits with a top-slice after any share has 6-bagged, which I think would be sensible.
That said, the fundamentals continue to power ahead, and I’m happy to run with it, at GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Project 2025 has significant implications for capitalism and hence our investments and yet
Project 2025.jpg
Cantab, for a moment I thought this was more Horse manure for us mushrooms, typo and all. But....
Wikipedia: Project 2025 - Wikipedia
Economist: https://econ.st/3L71fKB - I searched for Project 2025 and this was on top. Quite a few other articles.
Silver
Agreed offer for PlantHealth Care today at 9p. Another interesting little company bites the dust!
Plant Health Care (LON:PHC) I remember this from, I believe, the 1990s. Other than as a trade it has been a dog with fleas as far as actually being a good business is concerned. They promised industrial quantities of jam tomorrow.
Well my average price is just short of 4p so I am a happy guy.
Thanks Paul for taking a look at CMC especially with so many companies reporting today
Alliance Trust (LON:ATST) and Witan Investment Trust (LON:WTAN) to merge, two of the oldest Investment trusts. https://www.stockopedia.com/co...
Good write up on CMCX Paul. I'd add at the results presentation Cruddas mentioned they are near to doing another big asian tie up with a large financial institution.
Also they have declared they will pay out 50% of pbt in divi's, so if they did top end of your eps forecasts there's a 5% divi coming too, going forward or more perhaps
Cockney Rebel
Volex (LON:VLX) down 7% after announcing increased FY25 investment levels to keep up with client supply chain localisation requirements.
Capex to increase from around 3% to 5% of revenue (ie $50m) plus an expected doubling of ‘operational investments’ (i.e. from $8m to $16m).
In aggregate, this guides FY25 investment to $66m. Per Sharepad forecasts, FY25 capex was expected to be $30.2m
However, no improvement to the end of FY27 Revenue target of $1,200m or the underlying operating margin target of 9% to 10%.
Share price down despite references to leveraging competitive advantages, cross selling into and out of the new (mostly) acquired off highway division, 2 year payback periods and 20% return on investments.
This on the back of a mixed bag of FY24 results across Volex (LON:VLX) various markets, where some ‘one offs’ catch up orders in medical and complex products seem to have offset weakness in EV cables and consumer electronics.
A business that looks like it’s been asked to run harder for mediocre growth.
Thanks Cuddlesticks. Pretty much what I had calculated and concluded too for Volex (LON:VLX. Whilst I'm sure the investments are sound would have been good to state their expected return ie upgraded FY25 and FY26 forecasts. Questions to be asked on the upcoming IMC meeting. Would be good to get Paul's full analysis on the Volex (LON:VLX) results.
Seeing Machines (LON:SEE) appears to have made an announcement earlier that has been strangely received. When announcing the $16.5mn contract renewal with Caterpillar there is a hidden pre-close statement in which the CEO says : "As the end of the current Financial Year approaches, the Board of Seeing Machines anticipates that the Company will close the FY2024 period at or ahead of market expectations for Revenue and Cash". Yet shares down.
This company has very interesting prospects and contrary to some concerns about a cash raise and claims that it will be: " Despite Cash EBITDA being lower in FY2024, the Board confirms that the business is funded to deliver on the Seeing Machines business plan and reiterates its expectation to achieve a cash flow break-even run rate in FY2025". I hold.
Singers has some forecasts out today for Argentex (LON:AGFX)
2024>2025 PBT loss 4.9m > loss 4m
Net cash 18.8m > 14.4m
Given they had 18.3m net cash Dec 2023 which is all needed for day to day trading -headroom dropped to only 2m in March which forced a placing- and cash is forecast to drop to 14.4m next year does anyone really think they can develop an alternative banking solution without another placing. Their track record at messing things up is fantastic tho.
Argentex (LON:AGFX)
Woss, are you thinking of these as a contrarian play? Not like you to comment on such a low quality stock unless you’ve done some work on this and think there is potential for a turnaround ?
Sorry not my field of expertise so haven’t got anything to offer in fact not quite sure why I am writing this post!
Maybe too much sun on my bald head……
Hi Mr B, no just trying to figure out what Harwood saw in them when they were buying at 50-57p. Even on Singers forecasts if everything goes fine and they don't raise its still valued at 20x PE on 2026 numbers
Can see lots of potential for this to possibly go badly wrong quite quickly.
There was a Rockwood presentation on IMC this morning by Richard Staveley. He talks about Argentex (LON:AGFX) - the one that went wrong! - 39 mins 20 secs in here:
Wynnstay
Catching up from yesterday
Looks a business if you owned you’d be happy to own
Below NAV
With cash
Making 10 million a year .
Can’t see any downside
Can’t see too much upside
Can see a nice dividend
Can see IHT cover
Can sleep at night .
Can’t get too excited .
it’s the Dennis Irwin of my portfolio , solid in defence and Keeps a clean sheet but doesn’t get many goals .
Volex (LON:VLX)
Downing Strategic Micro-Cap Investment Trust (LON:DSM) are a fan and I believe that Volex (LON:VLX) is their largest holding. Unfortunately the former is in wind down and they are likely to sell into the market opportunistically so putting pressure on the share price. Whether this has happened this morning I don't know.
Not dissimilar to the situation with Telios and Card Factory (LON:CARD).
Just looked up their May factsheet - where it shows Volex holding at 5th position - approx £1.5m so frankly no big deal. No - I'm afraid the drop in SP today is symptomatic of the current market - good report - price down! Only plus - good opportunity to top-up.
Any reason Future (LON:FUTR) is up 10% today?
The big jump up today was due to an upgrade to 'buy' from 'underperform'. - Future PLC Target Raised to 1,280p from 635p by Jefferies. Also worth noting that a few of the short positions, namely Qube are selling out and buybacks are still going on.
Upgrade from Jefferies to buy from sell.
Future (LON:FUTR)
Learning Technologies (LON:LTG) has sold its non core Vector VMS business for $50m on cash / debt free basis with closing due in July.
LTG leveraged itself up in July 21 to buy GP Strategies for an EV of £247m (also raising net £82m of new equity at 192p), but it’s been paying down the debt from operations and non-core disposals. The net debt on 31.12.23 was £78.6m. It received $21.4m / £16.9m debt/free cash free consideration on 2 Jan 24 from the Lorien disposal and has a further $50m / £39.5m to come in July from the VMS disposal. Adjusting the year end figure for the two disposals gives £22.4m net debt, but the actual figure is presumably now much lower as LTG generates lots of cash from operations.
The business that has been sold, VMS, had calendar 2023 revenue $11.4m and EBIT of $7.1m. Using the cash free / debt free consideration of $50m and a tax rate of 25%, we get PAT of $5.3m and a P/E multiple of 9.4. This is about the multiple as the market is giving to LTG’s core business (10.1 for 2024 and 9.3 for 2025 per Stocko). (The disposal will of course reduce PAT by c. $5.3m on an annualised basis, less the savings in debt interest on the consideration.)
Tandem
Looks ok though they mention freight rates up 300% in the past month so that’s going to be a big drag on their profits and on their FOB orders many customers won’t bother shipping .
Kids bikes are doing well but Isla bikes have closed and Frog bikes don’t seem to be leaping off the shelves so much so good progress here .
People keep hanging children who all get a new bike whereas adults aren’t buying bikes at the moment .
There may well be an opportunity for tandem in the next 24 months depending on Mike Ashley / Evans / wiggle / sports direct mafia .
There’s a bit of industry buzz that they haven’t got a clue what they are doing, it’s all wel and good buying distressed assets cheap but then building them into a world class operation delivering great products on time and backing it up with good CS and tech support is a very specific skillset .
So my prediction is Evans / wiggle / sports direct will find it very very hard and leave the door slightly open for the likes of tandem .
But I’d say tandem aren’t good enough to step through the door so will remain a confused business who blew all their cash on a lovely too big warehouse and are now filling it by offering 3PL to others .
But honestly who on earth would risk 3PL to tandem when there are real experts out there .
There’s opportunity coming in bikes in 12-24 months when the current over supply is depleted and there are less players in the market all with smaller gonads especially of Mike Ashley cannot deliver and take the open goal .
I’m pottering around with bike parts and big upswing in parts / accessories as the demise of wiggle / PBK / ribble (not selling p/a) , Planet X (not me) has left the first open goal so may as well kick it in .
Hi planetx,
Do you have any updates from your forwarder w.r.t to the sharp rise in freight costs? There's likely to be quite a few importers from China impacted. Eg Luceco (LON:LUCE) which has already started drifting. tia
I’ll give him a call after 9 see what is happening .
Surprised tandem said tripled
I can confirm this also. Any importers we should be looking at who will be impacted, or will anyone benefit?
DFS Furniture (LON:DFS) is definitely one of the former to consider IMO
Got chatting to a guy working in freight yesterday during the England game as it was so drab. He of course mentioned the red sea but also said that more and more freight ships are being used between China and South America, the added competition leaving less availability for China to Europe which is keeping costs higher. No idea how accurate his comments are as I'd never met him before in my life, and know very little about the sector and its workings. He was confident however that freight costs would not be coming down any time soon...
Taylor Maritime Investments (LON:TMIP) said in there last tu that south america trade was very strong
Have sold my holding in LUCE. Something off and feel bad news around the corner. Might be wrong but a little depressing seeing the constant stop in sp.
Have sold my holding in LUCE. Something off and feel bad news around the corner.
By contrast, I have bought back in today at the level I prematurely exited a month or two back. That’s what makes a market and I’ve time to allow disruptions to sort themselves out. Short term however, this is a gold plated guarantee that you have made the right move!
Loads of stocks doing the same thing. Bodycote (LON:BOY) is another, there are plenty more, see Renold (LON:RNO, Zotefoams (LON:ZTF) Ashtead Technology Holdings (LON:AT.) etc.
It does seem to be the stocks that have been heavily publicised and talked up in recent months, those popular with retail investors, are the ones that have seen the recent pull backs of 10-20%. I own a couple myself and the one link is they all seem to be regulars on the top 10 list on Stocko, even when there is no news. Rusty is right, if you were to plot all of these shares on the same chart they look almost identical, a big run up followed by a pull back. As a lot of these have seen strong gains the pull backs are probably justified.
Someone spoke recently about looking specifically for stocks where the "community" score was lower. I am sure there is some merit in that strategy if the data is actually reliable. All of these mentioned stocks have a buy of over 20%, with Zotefoams (LON:ZTF) up at close to 35%. Avoiding buying stocks which already have very high ratings could be a smart play. Or on the flip side, buying when the number drops, I note Journeo (LON:JNEO) has dropped to 24%, it was up at over 45% during the hype if I remember correctly.
Did Stocko HQ ever confirm how these numbers are calculated?
No, never got an answer about how Stocko, calculates the community ownership. All l got was this "
Community Activity
This bar shows the percentage of our community that are buying, holding or selling the share. As more community members increase (/decrease) their shareholding, the buy (sell) percentage will increase. If the community is mostly passively holding , with no new transactions in the share then the bar will be mostly grey. Watchlists portfolios are not included in the calculation.
This data is completely anonymised. No data will be shown where we do not have a large enough sample such that an individual would have a significant impact on the percentages shown."
My follow questions were never answered.
If watchlist portfolios are not used where does it get the information from?
The Community Activity can't be accurate unless we are all asked to nominate our "active" folio(s).
Only one of my folios is real!
Luceco (LON:LUCE) Hi Gaz you have sold and I have bought your cast-offs! Yes there is a temporary headwind perhaps in costs but the longer-term trends look favourable for this potential multibagger.
Hi planetx,
Woom is the new Islabike - Austrian brand, big in Germany and getting more popular in the UK.
Woom is better than Frog and Squish for quality and weight. In fact, as a seller of premium-brand lightweight kids bikes, I would rank these top 3 kids-only brands as follows:
1st=Woom. Austria's answer to Islabike. Superlight and excellent quality.
2nd=Frog. Very popular in the UK. Light and very good quality.
3rd=Squish. Cheaper than Woom & Frog. Light and good quality.
Squish (Tandem (LON:TND) doesn't have the superior paint finish quality of the other two brands and I see them more as a follower, rather than an innovator. Woom has the best engineering of the three.
I still don't understand why Islabike threw in the towel. They didn't go bust, they just decided to shut up shop. I always thought Isla were better than Frog and miles ahead of Squish and seemed to have no problem selling their more popular bikes. I contacted Islabikes on several occasions to enquire about becoming a dealer but they weren't interested - said they wanted to remain D2C only. I wonder if they would have been still around if they had decided to go B2B and D2C, like Frog?
I think Isla had just run its course for her personally .
She did very well over the years .
They caught a bit of a cold in the USA
She’s not particularly materialistic and I think simply rode off into the sunset to enjoy life .
Can’t fault her . She was the first to do great kids bikes and set a standard for others to follow .
Just bought my 4 year old a Bobbin which feels a bit bobbins. I should have checked out Woom.
Not sure hanging children is great for kids bike sales,
On the shipping/freight bit... wanted to chip in what I heard on the PROCOOK (LON:PROC) investor call just now.
Their results today, didn't give any commentary at all to recent spike in shipping rates. But Procook do source ALOT of products from China and the Far East.
On the IMC presentation today, I asked in the Q&A, but got a very vague answer. It does seem like they are impacted, they mention "weekly" discussions/monitoring within the org. They reassured that they have ordered and planned ahead to not have any disruption to stock for later this year. But they didn't address the cost part of the question, whether it is elevated for them or not currently. Nor did they reassure that they have fixed-price contracts, or hedging, etc.
Reading between the lines, I think it is likely Procook will be impacted with higher shipping costs. BUT this is just my reading the tea leaves, rather than the company explicitly stating anything...
Volex (LON:VLX) down 9% with AJ Bell live prices, didn't see that coming, hopefully MM shenanigans
Opportunity knocks?
Interesting RNS from Intercede (LON:IGP) this morning announcing the appointment of Carahsoft Technology Corp as a reseller partner. IGP has 18 integration & reseller partnerships (see www.intercede.com/partners/integration-and-reseller/) and it usually just adds them to the list on its website without a stock market announcement.
Why RNS this one then?
The partnership is to resell to the US public sector MyID Multi-Factor Authentication (MFA) including FIDO and MyID Password Security Management (PSM) solutions. So not the “top of the pyramid” PKI contracts that are currently the main revenue generator and where IGP has recently been very successful through its partnership with Guidehouse. MFA and PSM are the products developed following the Authlogics acquisition. IGP has no (or at least very low) sales of MFA and PSM into the US public sector at present, so the partnership opens up a large new market.
Carahsoft is privately held and had turnover in 2021 of over $9bn (see www.carahsoft.com/awards/crn-fast-growth-150/2022-88). It describes itself as “The Trusted Public Sector IT Solutions Provider™, supporting Federal, State and Local Government agencies and Education and Healthcare markets. As the Master Government Aggregator® for our vendor partners, we deliver solutions for Cybersecurity, MultiCloud, DevSecOps, Big Data, Artificial Intelligence, Open Source, Customer Experience and more” (see www.carahsoft.com/about).
The partnership seems to put quite a lot of heft behind MFA and PSM in the US public sector. I imagine Carahsoft's sales pitch will lever IGP's stellar reputation at the very top of the pyramid (with PKI to federal agencies).
Yes. The advantage of MyID MFA is that it includes FIDO which is more secure than pure MFA and will be a big selling point when combined with their government reputation. They were smart in getting feedback from their potential customers (who asked for FIDO) and delaying the launch of MFA until they could include it from the CMS product.
Carahsoft is a big company but they sell a hell of a lot of products - see this slide : https://www.carahsoft.com/solv... and that's just for security solutions.
My morning smallcap tweet: Shelling out for nuts
Inspiration Healthcare (LON:IHC) Tribe Technology (LON:TRYB) Learning Technologies (LON:LTG) Seeing Machines (LON:SEE) Intercede (LON:IGP) Warpaint London (LON:W7L) Spiritus Mundi (LON:SPMU) Triad (LON:TRD) Crimson Tide (LON:TIDE) Checkit (LON:CKT), Avacta (LON:AVCT), HSS Hire (LON:HSS), PZ Cussons (LON:PZC), Tandem (LON:TND), PROCOOK (LON:PROC)
◄Inspiration Healthcare (IHC)► £2.4m placing and £0.5m retail offer at 14p, a punch in the gob 43% discount, to keep the lights on. Also FY-Jan. Outlook in line. [SP=24.33 Cap=17m]
◄Tribe Technology (TRYB)► undercapitalised tinpot startup makes £0.8m placing and sub at 4.5p, a 22% discount, to keep the lights on. Buyers get 2/1 warrants at 5.4p. Also £0.6m convert issue . [SP=5.1 Cap=13m]
◄Learning Technologies (LTG)► sells VectorVMS for $50m. In FY23 Vector generated revenue and Adjusted EBIT of $11.4m and $7.1m resp. [SP=82.5 Cap=653m]. I hold.
◄Seeing Machines (SEE)► gets $16.5m payment as part of five year license renewal with Caterpillar. Trading: guides FY24 rev at least at market expectations but a 'cash EBITDA' miss. Blames "aftermarket margin mix due to the slower than expected transition from Guardian Generation 2 to Generation 3 and the previously reported adverse Automotive royalty volumes and mix". Co still has funds to meet biz plan. [SP=4.72 Cap=196m]
◄Intercede (IGP)► partnership with Carahsoft Technology Corp to Make Digital Identity Cybersecurity Solutions available to the Public Sector in the US. [SP=125.2 Cap=73m]
◄Warpaint London (W7L)► AGM stmt - guides H1-June rev c.£46m (up 25%) and margins up. In line? [SP=580 Cap=450m]
◄Spiritus Mundi (SPMU)► H1-Mar. Material uncertainty going concern stmt. [SP=4 Cap=2m]
◄Triad (TRD)► FY-Mar. Outlook very bullish. [SP=292.8 Cap=49m]
◄Crimson Tide (TIDE)► Checkit pulls out of bidding war. [SP=252.56 Cap=17m]
◄Checkit (CKT)► won't make an offer for Crimson Tide. [SP=23.96 Cap=26m]
In line: AVCT, HSS, PZC, TND, PROC
Volex (LON:VLX)
Prelims look to be ahead of concensus, with both revenue and underlying earnings an improvement on the recent trading update. Leverage is reducing and operating margins have increase to 9.8% versus the previous 9.3%
The outlook statement is positive with an anticipated recovery in the lower margin EV and consumer electrical. A lot happening but a lot to like. Nat Rothschild and his team have done a terrific job in turning around a tired and venerable British brand. Never say never but much more to come once Murat Ticaret is fully integrated and it launches in America.
Paul/Graham your thoughts would be welcome.
Data centre and AI big driver now for Volex (LON:VLX) :
Data Centre customers are reported within Complex Industrial Technology and represented 41.7% (FY2023: 21.2%) of revenue in this sector. The revenue in this sub-sector increased by 131% year-on-year, partly due to prior year shortages of up-to-date network equipment essential to support the adoption of 400 Gigabit-per-second architecture in data centres. As these shortages abated towards the end of FY2023 and throughout FY2024, demand levels accelerated as customers addressed their backlogs. In addition, the expansion of data-intensive artificial intelligence applications increased demand from Data Centre customers.
Looks good but why share price down 7%
Intercede (LON:IGP) is todays RNS a game changer ?
AO World (LON:AO.) - just a reminder we are hosting an Investor Presentation and Q&A with the management team at 2pm this afternoon - you can sign up here: https://www.equitydevelopment....
A big announcement in the in the investment trust world this morning with Alliance Trust (LON:ATST) merging with Witan Investment Trust (LON:WTAN). I hold both. It probably makes sense as both had a similar strategy and Witan needed a reset following the planned retirement of its CEO. I thought this might happen given Alliance Trust have been a lot more successful than Witan in recent times, but both use a multi-manager approach. I'm not sure about the Alliance Trust name change though and its a pity to be losing the golden oldie and dividend hero Witan Investment Trust for ever. It does create a super global investment trust though which is an excellent core low-cost global equity holding!
I am only on my phone but the Volex (LON:VLX) update seems positive band quite detailed in terms of financial performance. On track for the big plan but light on detail in terms of year ahead.
With Eps down and debt up c.50%, I think we may get a fairly neutral response, despite the impressive revenues and op. Profit increases.
We'll see.
Leverage reduced despite net debt up
Liontrust Asset Management (LON:LIO) Final results out today. Graham has previously commented on LIO where the share price is heavily discounted to reflect outflows. Better prospects ahead I believe.
Liontrust Asset Management (LON:LIO) - asset managers typically trade on 13* PER plus a bit for their large net cash positions (much of which is held for regulatory purposes and is not just free for shareholder distribution). This normalised market rating would nudge them up towards the 1000p level. Then you have operational gearing linked to an increase in both investor sentiment but also performance fees. Good long term track record - some point at short term rankings but long term performance is what actually matters - the rest is just short term noise. Not unlike us investors.
I personally can't see Liontrust Asset Management (LON:LIO) trading on a 13x multiple - that sounds right for a specialist asset manager such with good growth prospects such as Polar Capital Holdings (LON:POLR) Intermediate Capital (LON:ICG) but for me LIO lack any sort of differentiation in a very crowded market and could struggle to compete with cheaper passives. The £6bn net outflows over the year was around 20% of their starting AUM - I know sentiment to UK equities has been poor, but that does look worse than others.
Record profits form Volex (LON:VLX) vs reduced AUM from Liontrust Asset Management (LON:LIO) another rollercoaster days beckons.
Liontrust Asset Management (LON:LIO)
Results as anticipated for me - dividend now at 10% and doesn’t look under threat. Operationally geared to a recovery in investor flows too.
MS International (LON:MSI)
Excellent results at 71p eps. Given the net cash pile has swollen to 250p worth of the share price this is now a high class defence conglomerate trading on 10* cash adjusted PER. That just looks wrong compared to peers?
Order book now in excess of 1 years worth of revenue so that tells me that next years earnings upgrades should effectively be almost in the bag and given the positive tone of the board (who are notoriously curt and deadpan) feels very encouraging.
Feel this should be much higher rated - I mean look at Avon Protection (LON:AVON) for example which trades at more than double the PER rating whilst operating with net debt rather than a rock solid balance sheet.
I agree, David - it looks like they have 'smashed it out of the park' today. Sadly, I dont hold MS International (LON:MSI) as yet but it appears worth another look. If they could ditch the petrol station superstructures and forgings businesses prospects might look even better?
MS International (LON:MSI)
Agreed. Good results. Will take me a while to go through the details. But there is always a disappointment with MSI buried in there somewhere.
Defence revenue pretty much as I expected but profitability a little lower than I'd thought (Edit - always too optimistic - actually revenue and profit are lower than I expected but profitability/ operating margin is in line) I suspect, given the level of contract liabilities to be delivered in FY25 0 £42m - that one or more delivery didn't quite make the FY deadline. The silver lining is that any deliveries that did slip over the year will boost the H1 FY25 results.
The other three divisions turned in quite poor H2 figures, which softened the FY results a bit. Recovery here and turnaround in branding (always takes longer than I expect) will provide further tailwinds to FY25.
Cash generation quite enormous. Very impressive given that the defence business is also spending to expand capacity and capability.
The defence business is highly reliant on overseas clients- so good to see the RN finally got around to ordering 6 of the latest systems for the fleet support vessels now being built. I'm rarely one to praise the MoD - but here I think that they finally got it right. It's a very versatile and highly effective system for its price - particularly well suited to vessels that need an all round capability and don't have missiles. I expect to see a lot more sales in this space in future as countries react to not just Ukraine - but also the Houthi/Red sea situation. Also good to see the orders from the German Navy recognised - that really is an away win, as the German arms industry is not short of systems, and probably also reflects the versatility, ease of integration and lifecycle cost of the MSI system.
I've yet to go through in detail, but my gut feeling is that these results put the business in position for even better figures in FY25.
cheers
Mark
Hi Mark,
Thanks for your thoughts on this. If I remember correctly MS International (LON:MSI) makes up a significant portion of your portfolio and you are very knowledgeable on the share. Would be interested to hear any additional thoughts once you have been through in more depth.
Cheers,
BenHazz
Hi Mark,
Agreed - feels to me like next year is positioned to get closer to 100p. Of course with no broker coverage at all we have to make our own assumptions rather than any guidance.
Given the size of MS International (LON:MSI) now I’d really like to see a bit of coverage / forward expectations particularly given the order book coverage.
Be interested to see what you come up with (and then I will knock a few % off for your positive bias ;-) )
MS International (LON:MSI)
Hi David,
If I remember rightly you were pretty much on the button with 70p? Well done. Good call. 70p remained the bottom of my range - but I was closer to expecting 80p - another £1.62m profit. I can see where that has gone.
I shall have to 'fess up whether I've nobbled my own figures this time? Though if I come up with below 100p I think you can be fairly certain I've restrained my optimism.
cheers
Mark
Haha !! A double bluff…….. that’s ruined my strategy!!
In all seriousness though if we take a basic fag packet and draw up the order book change - then we might assume a 40% increase in revenues across this year. Even if there is no operational gearing and margins stay constant that gives us 98p EPS.
If we assume some operational gearing but a lower revenue % increase than the order book implies (possibly more reasonable if some of that order book flows into the following year) I come up with more or less the same number.
Net cash goes to 350p+ and EPS of 100p with a slightly better PER rating - say 13-15* then I get to 1650 - 1850p target. Currently I’ve set mine around 1500p, so basically I’m in no hurry to sell unless anything changes that story.
As I say be helpful to see if anyone else comes up with similar numbers given lack of coverage.
MS International (LON:MSI)
Well I think it would be fair to reveal that I'm still struggling to get my FY25 forecast eps - down - to 100p :-)
Currently stuck at 110p despite setting forgings and superstructures very close to the FY24 results with branding still loss making by a little.
Partly caused by some slippage of deliveries (the US FMC referred to in the commentary as an example) and lack of clarity on delivery of the remaining - Paladin - land systems and any additional orders currently in negotiation. Recently seeing some interesting variants of the Paladin system being exhibited - and system changes/upgrades tend to go hand in hand with customer requests?cheers
Mark
MS International (LON:MSI)
David, I meant to add that under the circumstances (lack of clarity, lumpy contracts, no forecasts) your top down approach to estimates is at least as valid, probably more so, than my bottom up approach which has more holes than a swiss cheese,
I would prefer to have 100p come out of my estimate - but I'm not there yet.
cheers
Mark
Mark
Irrespective - with expectations for me at 100p and you at 110p with the information from mgmt to hand but differing EPS estimate approaches that suggests we will hopefully not be miles off.
Assuming that is done a price of 1100p for this stock just looks far too low particularly given 350-400p of it will be in net cash by end of current year all things being equal.
fingers crossed this gets a bit more of a fair rating.
MS International (LON:MSI)
David,
Yes I agree. Very difficult to assess likely outturn because of the lumpy nature of the contracts, and the continued poor performance of forgings and branding divisions.
As it happens I've been through my assumptions for the defence division again and found some double counting.
Now reduced my estimates to FY25 group revenue of £124m and profit of £16.2m approx 98p. Which I am happy with as a 'base' case - though there is considerable upside to 110p and beyond, depending upon what gets delivered.
I'm stuck for time at the moment, so looking forward to doing more work when the AR comes out in a few weeks time,
cheers
Mark
MS International (LON:MSI) results look very strong as expected. Another god SCVR covered stock in the past. Feel the valuation must have at least 50% to run given the growth rate and EPS (and that's being pessimistic)
Great cash generation at MS International (LON:MSI) despite big increase in debtors, but that must be down to defence div where customers are in effect national govts, so no risk of bad debts. Stonking defence div performance. Aged owners/directors, but on the basis of this perf they would have no prob selling the co to the likes of Thales or BAe. I hold.
MS
Good South Yorkshire honest report writing . They don’t say much to the market but they say it straight .
No me too of EBIT
No mention of AI
No stupidly named initiatives
It would have been nice if they had used proper intro
“by heck lad s what a cracking year “
An even I can understand the year end report and financial layout .
AO World (LON:AO.) - Back to profitable growth; let’s go!
AO has completed its turnaround back into profitable growth and announced FY24 Adjusted PBT of £34.3m, nearly triple FY23. This was 2%-3% ahead of our, and consensus, forecasts and equates to a 3.3% Adj. PBT margin. Having gained over 600k new customers in FY24, and with an improved mobile offer, management is confidently guiding to at least 10% revenue growth in FY25E. This is an upgrade for consensus revenue growth of c.+8% (ED +13%), though company guidance for £36m-£41m Adj. PBT is in-line with consensus (ED FY25E £38.7m).
We recently initiated on AO detailing why its excellent customer service and AO Five Star membership club offer can drive repeat customer purchases and revenues, leading to improved profit margins (see “AO: Ready to grow; let’s go!”). AO has confirmed again its 5% medium-term Adj. PBT margin ambition and though we conservatively forecast 3.9% in FY26E, our blue-sky scenario analysis shows the potential for AO to triple Adj. PBT to over £100m by FY27E. We reiterate our 140p Fair Value, equating to a cal 2025 FCF yield of 5%.
Link to research: https://www.equitydevelopment....
Thanks for reviewing Tortilla Mexican Grill (LON:MEX). It's companies like this that I would never come across until much later in their journey without SCVR.
The Fresh Burritos deal creates a growing group of 132 fitted out restaurants, quotes itself as then being x6 bigger than nearest competitor on a European basis on an on trend niche, with a well established operating model including an established franchise model. With the additional French turnover picked up from what is hinted as a distress sale , it will have sales greater than £100Mn in a couple of years - the level at which fresh institutional or trade interest is likely. All for only£20Mn.
All restaurant groups are a fashion and timing risk on top of their operational challenges but the ones that get it right at the right time do very well.
The people who bought at 200p at IPO in 2021 weren't entirely stupid, just over optimistic and unaware we had (another) economic dip coming. We get to buy an (arguably) more developed, better and much bigger business at 57p at a potentially better point in the cycle.
There may be safer bets but I like the feel of this one.
Thanks for the write up Paul. I wonder if you are giving full credit for the cash positive business model and strong cash generation today, which seems to provide some margin of safety against a fairly flat balance sheet? I may be over egging this but it seems very undervalued to me given the market leading position, underlying profitability, strong growth in fast Mexican food as a relatively ‘healthy’ option and the large runway here in the U.K. and now in France.
I also note the Australian IPO of Guzman y Gomez which has a very similar offering and operating model and unlike MEX looks very overpriced at 4x sales! They did raise substantial new funds in the IPO and their growth rate has actually accelerated in recent years.
https://www.guzmanygomez.com.a...
There’s an interesting and helpful analysis of G&G here.
https://sbo.financial/blog/featured-blog/financial-teardown-gyg/
I do agree that a fair market should (!) see these drift nicely to 100p, and in an excitable market possible substantially higher.
Thanks Jon for that link, that's incredible isn't it? Valued at over £1.1 Billion and they only have 210 stores....
You may well be right and clearly you are buying into a Group that is now larger and more established than it was at flotation, for a price that has much less optimism priced in. The problem is that Tortilla Mexican Grill (LON:MEX) has failed to make it to being a profitable business (yet) and the question is will it ever? Perhaps it might with the tailwind of reducing fuel costs and lower food price inflation?
Personally I am sceptical of the new 'dual delivery' model as the uber takeaway sales might be both low margin and potentially damaging to the brand if food quality isn't maintained. I also think that the last thing a predominantly loss-making UK chain needs is the headache of integrating further loss-making French restaurants to the mix - I hope they have done their due diligence! Good luck and I hope the SCVR hasn't drawn you to a 'sucker stock' this time.
Tortilla Mexican Grill (LON:MEX) I agree Zipman, we are at a much better point, both in the economic cycle and the stage of business development for Tortilla to expand.
Just to add to yours and Paul's comments I went to see the company and came away very impressed at their level of ambition. They are set up operationally to be a much bigger company then they currently are and they acknowledge this will only work if they scale up.
The deal announced yesterday creates the platform to do this and the plan is to expand aggressively via the franchising route, just like Dominos did, rather than corporately owned. They take a percentage of revenues from each franchisee, I think approximately 8% of sales maybe? a successful franchisee will add about £45-50k straight to the bottom line and is very easy and inexpensive for them to set up.
The expense and execution risk is all in the next 24 months, I would have preferred it if they had £5m in the bank to fund this as oppose to borrowing it all but if they manage it then it could be a real multi-bagger, like the ones you read about in '100 Baggers', i mean you're buying it now with an EV of just £20m, that's peanuts!
A great risk/reward trade in my opinion, and it was good to see the Directors make a series of purchases yesterday as well.
Good luck to holders
Many thanks for going the extra mile to review £CMCX It really is commendable that you have put in the extra hours to thoroughly review especially when having listed in in your 2024 Top 20 Garp shares, that you have no position yourself.
This is a company that I resisted buying into until April this year, when its price momentum and turnaround potential was to good to ignore. Fully agree with your feeling that ,“something interesting and exciting is happening” so I will continue to hold. Prehaps it’s not too late for you take a modest position and to personally gain from this one?
Concur with your comments. I've top sliced CMC Markets (LON:CMCX) but will run the rest. Will Labour tax CFDs and spread-betting I wonder?
Has this been talked about? or just the permanent rumour ?