Small Cap Value Report (Weds 27 Jan 2021) - QUIZ, HEIQ, SBIZ, FLO, SCPA, SCS, WYN, KETL

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Timing - today's report is now finished.
Agenda - let's start with some sections I prepared earlier (last night):
Quiz (LON:QUIZ) - review of its Interim results
Heiq (LON:HEIQ) - 2020 trading update
Simplybiz (LON:SBIZ) - 2020 trading update
Flowtech Fluidpower (LON:FLO) - 2020 trading update
Today's news:
Scapa (LON:SCPA) - recommended cash takeover bid at 210p
Scs (LON:SCS) - trading update at end H1
Strix (LON:KETL) - 2020 trading update - you may not like my view on this one!
.
Jack's contribution:
Wynnstay (LON:WYN) - Final results FY 10/2020
.
Quiz (LON:QUIZ)
(I hold)
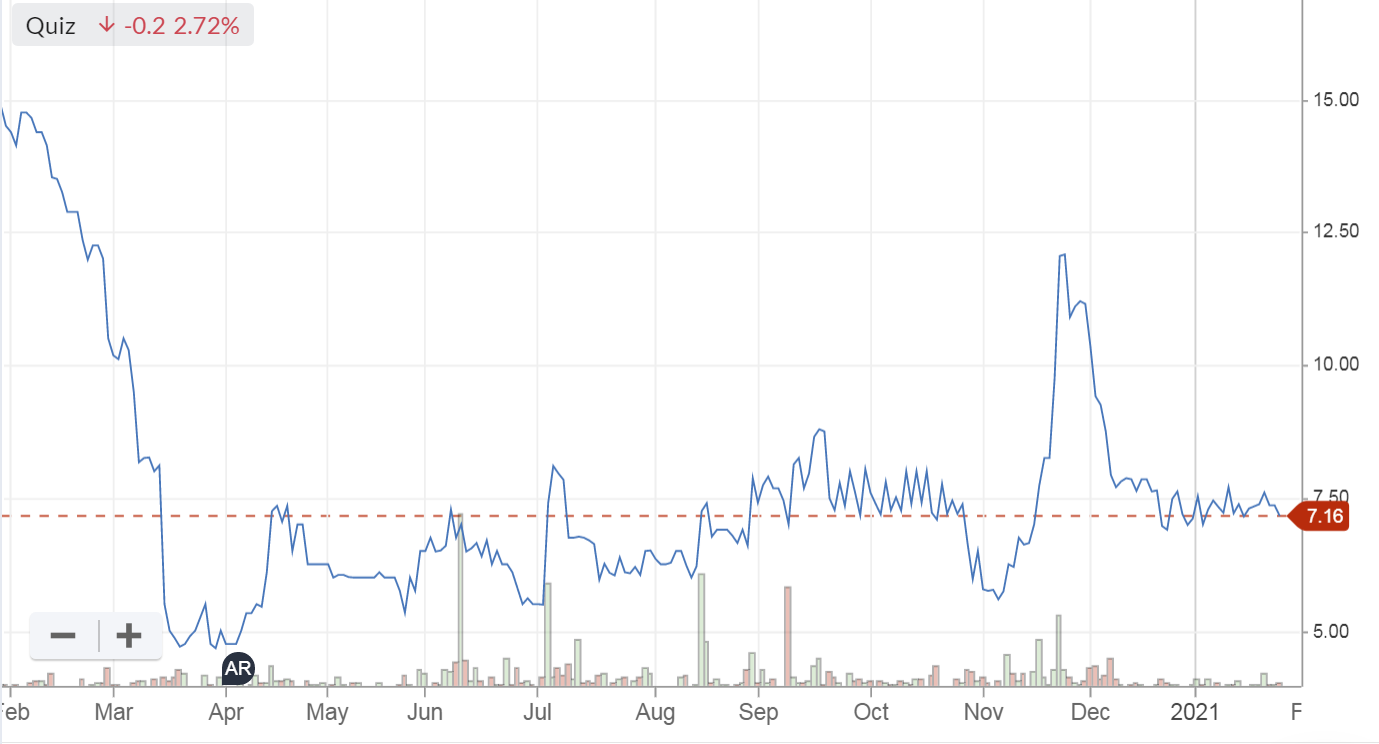
Mkt cap £9m at 7.2p
Interim results - NB this is a special situation, which did a pre-pack administration in June, to ditch all loss-making shops, and put the remainder on turnover rents. Hence the figures will look awful for now, because the shops were shut for a lot of the time. What matters is whether the business can survive, and rebuild once shops can open normally again, plus the progress of its online offering.
In a special situation, it's all about survival, so cash is king. This looks OK - £5.5m at 30 Sept 2020. Latest cash is £3.0m net cash as at 25 Jan 2021, with additional £3.5m undrawn banking facilities. Hence the liquidity position remains OK, and is better than I anticipated. Bulletin board experts who confidently predicted (with no evidence of course) that Quiz would run out of cash, have been wrong so far.
Concessions - I was worried that QUIZ might have bad debt exposure to Debenhams and Arcadia. It says that of its 142 concessions, 85 are in Debenhams, and 29 in Arcadia, all are expected to close. That would only leave 28 concessions remaining, so this side of the business is more-or-less over. Sad for the people involved of course, but new jobs are being created elsewhere by online & logistics companies. We can't stand in the way of progress, and there's really no longer much demand for many existing physical retailers, especially department stores, a concept that's arguably had its day. Pleasingly, re Debenhams & Arcadia, Quiz says -
There is no financial exposure to outstanding balances due from these businesses and the redundancy costs that would arise from these store closures would not be significant.
Online sales - down 50%. I’m disappointed with that, as I’d hoped Quiz online could take up the slack from closed stores. Of course its point of difference is special occasionwear, the worst possible category in a pandemic when special occasions can't happen. Pivoting to casualwear has only partially helped plug the gap.
Gross margin down sharply, from a previously very good 61.7% to 51.7%, again a bit disappointing, but I’ve seen worse.
Outlook & current trading - still poor, as you would expect when the shops are shut!
Balance sheet - this looks much stronger than I was expecting. It looks remarkably good actually. The pre-pack admin has got rid of most of the lease liabilities. NAV is £22.6m, less intangibles + deferred tax asset of £5.2m, gives NTAV of £17.4m - I don't’ understand how these figures are so good, so need to do some more work on this.
My opinion - pending, I need to do more work. I'm happy that my original reason for investing is intact - that the business would survive, and eventually prosper because it has restructured with a pre-pack administration, thereby getting all remaining shops onto turnover rents. That's absolutely key. Whether the product/brand are good enough? The jury is still out on that.
The finances are sound (see the good latest balance sheet), and with the founding family still owning about 50%, then I reckon this could recover. They've recovered before remember, from administration in 2008, to relieving the city of about £90m in a partial sale in 2017.
I'll do some more work on this, and report back in due course. Obviously not for widows & orphans, like any other struggling retailer.
.
.
Heiq (LON:HEIQ)
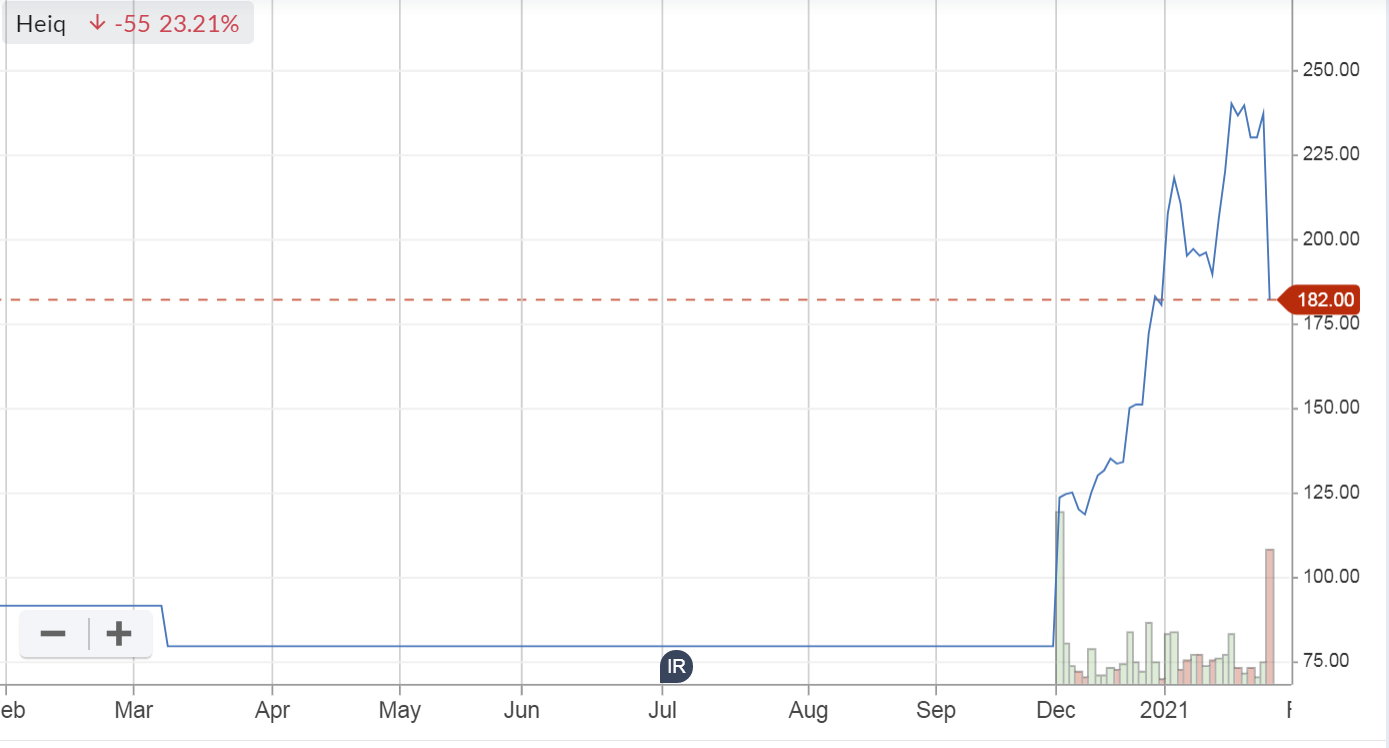
Mkt cap £229m (down 23% yesterday at 182p)
This innovative, technical fabrics company did a presentation at Mello Monday this week, then plunged in price 23% the next day. Did everyone at Mello open short positions then?! Possibly, but it seems the damage was done by this:
HeiQ Plc (LSE:HEIQ), an established global brand in materials and textile innovation which operates in high-growth markets, is pleased to provide a trading update for the financial year ended 31 December 2020 ("FY 2020" or "the Period").
Revenue for the year exceeded expectations
Operating profit for 2020 in line with expectations, despite record “investment”
FY 12/2021 so far has started in line with market expectations, confident about prospects
Liquidity said to be strong
Management speak all sounds upbeat
My opinion - why has the share price plunged 23% then? I don’t know, as nothing in the above strikes me as negative. People must have been expecting more.
The Mello presentation was enough to convince me I wouldn’t touch this share at anything like the current price. It’s had one decently profitable year, which could have been a one-off from covid-related products. There’s no track record of profitability anywhere near enough to justify a £229m market cap.
Hence I think it’s still wildly expensive, given we don’t really know what long-term profitability would look like. Hence not of any interest to me, but I’ve only done superficial due diligence, so I'm braced for angry shareholders telling me what an idiot I am!
It's a recent float, Dec 2020, having reversed into a cash shell by the looks of it. Speculative frenzy-looking chart:
.
.
Simplybiz (LON:SBIZ)
Mkt cap £175m, at 184p per share (up c.1% yesterday)
SimplyBiz (AIM: SBIZ), a leading independent provider of Fintech and Support Services to financial advisers and financial institutions in the UK, today issues a pre-close trading update for the twelve months ended 31st December 2020.
I last reported on its FY 12/2020 trading update here on 10 Dec 2020. That indicated “not less than 11.0p” adj EPS.
Yesterday’s update looks in line with that, and a decent reduction in net debt too -

.
Outlook - confident, nothing specific said.
My opinion - as mentioned last time, I think this share looks potentially interesting.
It’s certainly proven that its business model is resilient in an incredibly difficult year, so that increases the appeal, if you’re worried about the future. 2020 was the ultimate stress test for many companies, and we now know a lot more about how all companies perform in a crisis - valuable information.
I’d prefer to see a stronger balance sheet, and think the valuation currently looks about right.
Maybe it will need to do more acquisitions to more convincingly grow earnings? That wouldn’t sit well with an already negative NTAV balance sheet.
.
Flowtech Fluidpower (LON:FLO)
Mkt cap £61m at 100p
Specialist full-service supplier of technical fluid power products and services
FY 12/2020 revenues down 15%, with an improving trend in H2
“Small underlying profit”
Net debt down to £11.7m (£12.6m if delayed payment to HMRC is adjusted for)
Liquidity - sounds alright - bank facilities of £25m renewed in Nov 2020 for 3 years, and covenants adjusted
Cost-savings - some have been implemented, others are deferred into 2021 due to covid
Outlook - uncertainty means difficult to forecast, hence no guidance. Dividend policy under review. Cautiously optimistic.
My opinion - a bit uninspiring.
.
Xlmedia (LON:XLM)
Mkt cap £64m at 33p
XLMedia (AIM: XLM), a leading global digital performance publisher, today provides an update for the year ended 31 December 2020.
It did $27.7m revenues, and $5.1m adj EBITDA in H1.
Today it says the full year figures are $54.5m revenues, and $11.5m adj EBITDA.
That seems to show a sequential improvement in H2 over H1, from $5.1m in H1, to $6.4m in H2 adj EBITDA.
The company is trying to recover earnings from the lucrative casino sector, which it lost when Google penalised its sites in early 2020.
My opinion - it seems to be making progress. However, it doesn’t interest me at all, because earnings cannot be relied upon. Earnings have to be sustainable, as the first step for me wanting to invest in anything. Profit here largely evaporated when Google spotted that it was gaming their advertising system. That's a very flimsy business model.
.
Scapa (LON:SCPA)
Party time here! Recommended takeover bid at 210p cash.
18.6% premium to last night's close - not amazing, but this is double the lows of 6 months ago.
Kicking myself here, as I spotted the value and wrote about it here, at around 100p, bought some, but got shaken out of them, probably on a margin call as usual.
I remember speculating whether Scapa would be a bid target, as it has substantial operations in the USA. The acquirer is: Schweitzer-Mauduit International, Inc.
Inc. usually means it's American, which would make sense.
Shareholder support - is only at 16.65% so far, not enough to get it through. So I'd say there's no certainty this bid will proceed. Is the premium enough to convince shareholders to sell out? Will a higher competing bid crop up? Who knows.
My opinion - Scapa has had problems in the past, especially losing a lucrative customer contract, and legal action which is not yet resolved. There's a lot to be said for banking a nice profit in the last 6 months, and moving on. There again, an 18.6% premium is not madly exciting, so even if the bid fails, the share price wouldn't drop that much. A higher competing bid is possible. Tricky one, what to do? Sell in the market now to lock in the gains, or hope for a higher bid? That's your call. I sometimes sell half in this type of situation, then you win either way.
It feels like the Americans are cherry-picking good UK listed companies, and leaving us with what they don't want! Lots more possible takeover bids are in the pipeline, one of my city contacts tells me. He reckons many big investors (e.g. private equity) feel they missed out by being too cautious after 2008, so are much more gung-ho now.
.
.
Scs (LON:SCS)
(I hold)
Market cap £80m at 210p
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update ahead of announcing its interim results for the 26 weeks ended 23 January 2021 on 16 March 2021.
I don’t think there’s anything to be gained by trawling back through previous updates, and scrutinising how sales statistics have changed. The reason being that on/off/variable lockdowns render comparisons meaningless, and we see pent-up demand kicking in after lockdown periods.
So let’s look at the whole 26 week period, which contains a mixture of trading conditions -
Gross sales in the 26 weeks to 23 January 2021 increased 13.9% to £182.3m (2020: £160.1m). This increase is due to the significant order intake growth seen in June and July 2020 following the first lockdown, together with the strong trading in the first quarter of the current financial year. Unlike the first national lockdown, and in line with government guidelines, our distribution centres have remained operational throughout the period and continue to deliver goods to our customers.
As at 23 January 2021, the Group's order book is £90.5m (including VAT), £16.8m larger than at the same point in the prior year.
I’m happy with that. H1 revenues up 13.8%, and a closing order book up 23% on LY. Very good.
Online sales - are up 98% vs LY in H1, but that’s not much use as they don’t tell us the actual figures. After all a minuscule amount +98% is still minuscule! I’m not saying online sales are minuscule, but we really do need to be told the actual numbers, as well as the growth rate.
That’s a general point, applicable to all companies. Far too many of them try to hide the poor level of online activity by just talking about online growth, but don't give absolute numbers.
Why does it feel like a constant battle, trying to find out what’s actually going on, when reading trading updates? Far too many advisers trying to be clever, muddying the water, if you ask me. Transparency is best, all companies should aim to emulate Next (LON:NXT) and its disclosures.
Balance sheet - a standout feature with ScS, as mentioned here before, is the wonderful balance sheet. Customers pay up-front, so it has pots of cash. Reported at £91.8m as at 23 Jan 2021. That’s more than the market cap (of £80m!).
The contrast with larger competitor Dfs Furniture (LON:DFS) couldn’t be starker - DFS plunders the customer cash to finance the business, with debt on top. ScS doesn’t touch it, leaving the customer cash piled up on the balance sheet. Maybe there’s a middle ground, where ScS could be a little more aggressive?
I’d like to see ScS buy up some struggling competitors on the cheap, once the target has gone into administration for example, and do deals with the landlords to operate more profitably on turnover rents. Or buy some freeholds, if they're cheap?
This is a time of opportunity, especially for a cash-rich company like ScS, to do some careful but lucrative deals, laying the foundations for future growth. It needs to grow, which would also help move the market cap up into a territory where more institutions would become interested, and hence the rating would probably rise. At the moment, ScS shares seem to be permanently stuck in value territory.
Divis - nothing said about this today. Given the huge cash pile, there’s no reason at all why the company couldn’t restore the previously generous divis. If the company restores the last 16.7p divi, in due course, then that would be a yield of 8.0%! That’s extremely attractive. Therefore, I reckon income seekers (e.g. SIPPs in drawdown) would do very well to consider this share as a future generous yielder.
A policy decision has been made to hold back divis (maybe the company doesn’t want negative publicity possible from rewarding shareholders at a time like this?), but that doesn’t matter. It’s the company’s capacity to pay divis in the future which counts, and on that front this share looks very good to me. Once generous divis are restored, that could trigger a re-rating, so the possibility of maybe a 50% capital appreciation too, for investors who are happy to wait.
This is what the company last said about divis, last year -
Despite the strength of our balance sheet, the Board did not feel it was right to pay an interim dividend at a time when the economy was facing such uncertainty and that the Group was receiving government support. It seemed inappropriate to use the cash for anything other than protecting the financial strength and resilience of the business at such a crucial time. The Board recognises the importance of income to the Group's shareholders and will continue to assess when it is sensible to recommence dividend payments.
[source, RNS 29 Sept 2020]
My opinion - very positive. It’s a boring, overlooked company that is trading well, with a bulletproof balance sheet, and high future dividend paying capacity.
The only thing missing today is any mention of profitability! It sounds like we're probably in line, but mgt is coy about saying anything, as the outlook re covid/re-opening is still so uncertain.
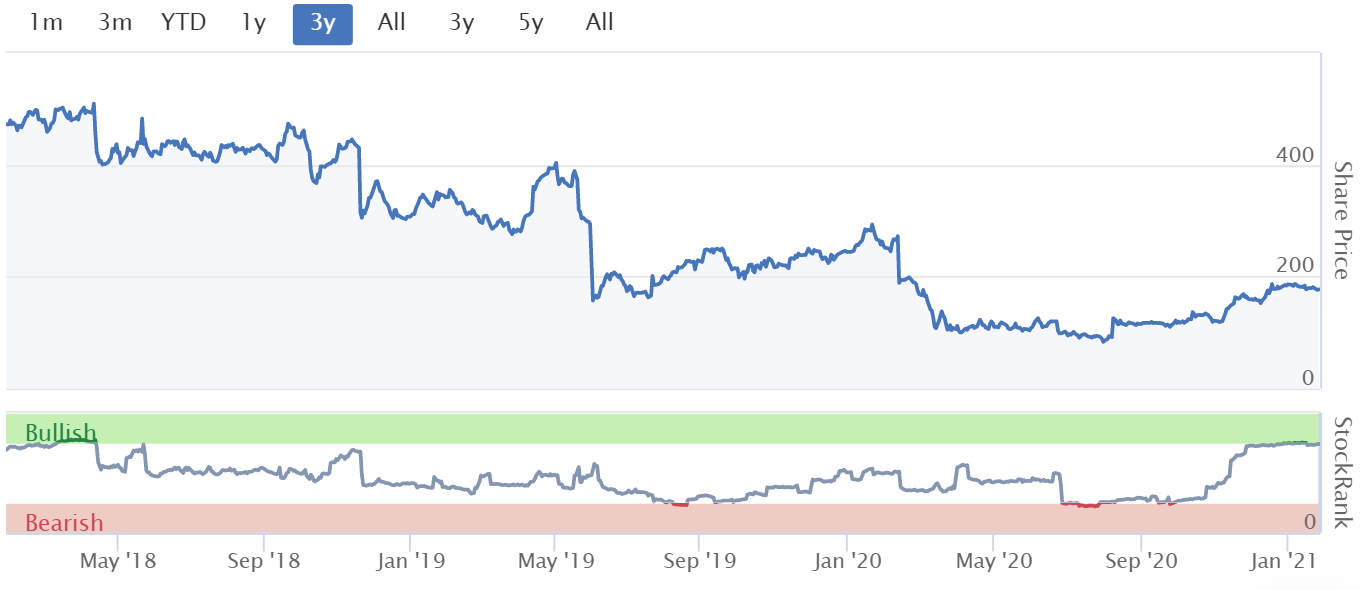
That fits very comfortably in the value section of my portfolio. I’m happy to sit tight, and probably might add more to my existing holding on any dips. It’s proven very resilient throughout covid. Don't expect any fireworks with the share price, as sellers always seem to overpower any attempt to rise. But who cares? That's only temporary - eventually strong fundamentals drive things up where they should be, it's just a question of being patient. Plus an advantage of sellers, is that we can buy as many shares as we want. That's not always possible once the sellers have finished. So a depressed share price, combined with strong fundamentals, strikes me as more of an opportunity than anything else.
The chart looks lacklustre, but if you add divis on, the total shareholder return has been better than it looks, and there's plenty of upside to come I reckon, if strong performance of the business continues.
.
.
Strix (LON:KETL)
Market cap £503m at 244p
Strix Group Plc (AIM: KETL), the global leader in the design, manufacture and supply of kettle safety controls and other complementary water temperature management components, is pleased to announce the following trading update for the year ended 31 December 2020.
Key points -
- “Marked recovery in H2 as anticipated”
- Adjusted profit after tax of c.£29.5m, up 2% on LY
- Strong order book visibility for Q1 2021
Positive commentary on both the core kettle controls division, and water filtration (LAICA acquisition). New products, and geographic expansion planned for 2021.
HaloPure - I’m not so sure about this acquisition. Looking back at its time as a standalone listed company, its performance was dismal - tiny revenues, and loss-making. So why would it suddenly become good?
Admin costs - looking at the 2020 H1 results, the P&L looks unusual, in that most of the gross profit flows through to the bottom line. There seems to be very low administration costs, only £1.4m in H1. Although considerably more (£2.5m) are classed as exceptional in H1 2020, and £4.0m exceptional admin costs in H1 2019.
The company says that it’s highly cash generative, and has a robust balance sheet (which it actually doesn’t, as if often the case when companies make such a claim).
Balance sheet - as at 30 June 2020, KETL had NAV slightly negative, at £(1.2)m
If we deduct £9.4m intangible assets, then NTAV was negative £(10.6)m
There was £49.0m borrowings in long-term creditors, a hefty chunk of debt.
This is quite obviously not a strong balance sheet. Whether that matters though? Probably not, if it can keep generating strong cashflows.
Cashflows are they really that good? The big divi last time seems to have been paid for through increased borrowings, not from profits. I see from the interims that in H1 2020 and H1 2019, more than half of the cashflows ended up going into capex, capitalised R&D, and purchase of intangibles. An amber flag here, it needs more work to get comfort on cashflows.
.

.
My opinion - I don’t like this one. Some accounting questions above, too much debt, a weak balance sheet, and a dubious acquisition of HaloSource.
In addition to that, the basic concept doesn’t make sense to me. Kettles are cheap, almost disposable, very simple items. There’s nothing high tech in a kettle. How come KETL can make so much profit, selling parts for kettles then? They seem to be made in China, so no respect for IP there. Hence surely the product would be ripped off & undercut by competitors? That’s what happens with everything else, so why would kettle controls be any different? It doesn’t make sense to me.
I’m sure the same question was asked by all the big name institutions who bought into the IPO, so there must be a persuasive answer to my question, which they will all have asked too, I’m sure.
Overall then, it doesn’t work for me, so I won’t be investing.
.
Jack’s section
Wynnstay (LON:WYN)
Share price: 340p (-4% at 09:30am)
Shares in issue: 20,051,043
Market cap: £68.2m
(Jack - I hold)
Wynnstay (LON:WYN) is a manufacturer and supplier of agricultural products that operates through two segments: Agriculture and the higher margin Specialist Agricultural Merchanting segment.
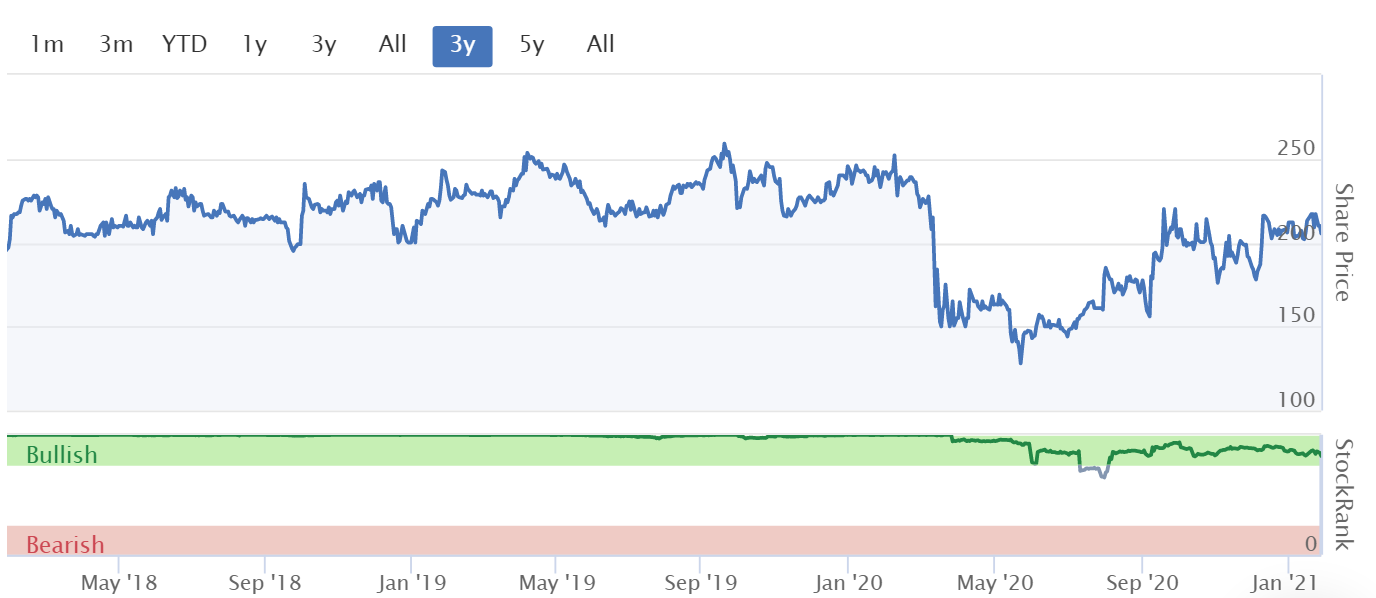
It’s one of those ‘boring’ stocks that often flies under the radar, but it has been flagged by the StockRanks for a long time now as offering great value across the board. The most recent stretch (highlighted) has seen its StockRank hit 100 several times:

With a market cap of around £70m, Wynnstay is unlikely to be turning the heads of any institutional investors quite yet, but what I see here is a very prudent and sensible company quietly executing on a proven strategy of organic growth and bolt on acquisitions. UK agriculture is actually quite a good space to be - this is a great land for farming - and Wynnstay has earned a valuable place in this ecosystem, built up over many decades.
While it might look like this share, and the profits it generates, never seem to go anywhere, there are signs of progress.
Breaking Wynnstay down into segments, Agriculture is resilient but undeniably low margin and at the mercy of commodity prices. Specialist Merchanting is higher margin and growing though, with improving returns on assets.

Although it only made up 27% of revenue in FY19, Specialist Merchandising contributed around 64% of group profit.
I think it’s an interesting company - modestly valued - with a history of cash generation, dividend payments, and a proven growth strategy, all underpinned by a hefty discount to net asset value. Probably one for patient, long term value investors. In fact, it provides a Scrip dividend programme for income seekers out there.
There are negatives of course. Low margins, commodity prices and the weather impact short term trading and it does look as though meaningful growth has been an issue over the past decade.

The winning word today is ‘resilient’, used five times. There are worse words, given the year that was.
Financial:
- Historically poor 2019 autumn planting season and 2020 UK harvest at 20 year low
- subdued farmer confidence and investment, reflecting weaker farmgate prices in H1 and Brexit uncertainty
- Revenue -13.7% to £431.4m (2019: £490.6m), affected by commodity deflation and reduced volumes in certain traded commodities,
- Increase in underlying PBT +4% to £8.37m but reported PBT down 8.2% to £6.98m,
- Basic EPS -11.6% to 27.73p,
- Net cash at year end increased to £8.42m; £14.71m before IFRS 16 implementation (31 October 2019: £3.84m before IFRS 16 implementation )
- Net assets increased to £98.18m/£4.92 per share at year end (31 October 2019: £94.95m/£4.79 per share)
- Proposed final dividend of 10p, meaning the total dividend of 14.6p marks a 4.3% increase.
Note 14 shows the bridge between reported and underlying PBT. Here it is:

Flicking over to Note 4 breaks out these non-recurring items.

That’s not the whole list of items, but it does make up the bulk of the charge. Store closures are understandable. The Goodwill and Investment impairment relates to GrainLink, Wynnstay’s specialist combinable crop marketing business.
This was largely due to trading volumes being impacted by the lowest UK wheat harvest since 1981, but the business still made a profitable contribution and Wynnstay expects ‘a significantly improved performance from GrainLink in 2021.’
Anybody familiar with Wynnstay reports will understand that this group is the opposite of the typical c-suite overenthusiasm. The top spots in companies often attract a certain type; students of the ‘Always look on the bright side of life’ school. It has its place. But it does also seep out into the tone of trading statements.
There’s none of that to be found in a company that originated as a co-operative of Welsh farmers, of course.
In fact you’re often left wondering if everything’s gone wrong until you look at the figures again a day later and realise they’re actually quite robust.
Conclusion
While the group notes poor conditions in the previous year, the numbers also show increased cash production, a rising net cash balance, increasing net assets per share, and a growth in full year dividend payment.
All this in a year where other companies have embarked on emergency placings at reduced share prices, and might be counting themselves lucky to be classified as a going concern.
These results bear the scars of the pandemic, but they also mean WYN trades on an historic PE of 12.6x falling to 10.7x, with an historic dividend yield of 4.17% rising to 4.25%. The net asset value of £4.92 a share is also worth bearing in mind.
I don’t think this company is going to rocket, but I do think it could rerate another 30% in the short term, and even double over a year or two if it can pleasantly surprise the market.
The shares are down today but Wynnstay continues to generate cash, invest for growth, and pay dividends to shareholders. The outlook section sees a notable change in tone from management, as well.
Now that a non-tariff trade agreement has been concluded with the EU, the picture for UK agriculture is significantly clearer and a major uncertainty has been removed. Wynnstay says the UK Agriculture Bill will change the way that farmers are supported by the Government and that it should benefit from opportunities to provide support here.
Agricultural commodity prices have generally improved over the past 12 months and the short-term outlook ‘remains strong’. Winter cereal plantings are significantly greater than a year ago, in line with a more normal sowing season. This will drive demand for arable inputs and yield a larger crop to trade post-harvest.
It says the new year has started well and it is assessing acquisition opportunities. This stock requires patience, but it also justifies a high Rank in my view.
.
All done for today! See you tomorrow.
Best wishes, Paul & Jack
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

128 comments
Very interesting what has happened since this article was written.
I can only presume the share price has increased so dramatically
Due to acquisitions.
You can speculate on what happened though.
"Brussels we need a billion CV19 vaccinations."
First month spent going through 20 million pages of EU Directives for guidance - finding none. Two months doing an EU compliant tendering process to ensure plumbers had the chance to tender as well.
I voted to stay in the EU - makes you wonder.
May I suggest that AstraZeneca supply vaccine to the EU from British plants but that before the doses are given each recipient pays over 20% VAT to the British government - cards accepted but not euro's.
Oh and each vial is subject to separate export documentation. to be completed in triplicate.
LoL
That's very naughty EJC. ;-)
The EU team today made it crystal clear that they do not have the first clue about contract law, so I would be inclined to let them get on with whatever legal path they want to follow,
Although AZN have said they are offering the vaccine on a not for profit basis, I suspect that any future deals they sign with the EU might include a substantial false claim indemnity.
I stand admonished!
Thanks Paul and Jack - an excellent report
neat summary for today
https://twitter.com/cnbcclosin...
Scs (LON:SCS) (no position)
FYI the company's true cash position was likely closer to £12m-£13m back in July (see my previous comment here).
They will definitely have unrestricted cash on the balance sheet right now and I imagine that they will be keen to keep it there.
Note the TTM revenues of £290m (Feb 2020 - Jan 2021) vs £334m at the same time last year (Feb 2019 - Jan 2020); quite a fall. I was surprised by this and was under the impression that they would be flying right now.
A
Appreciate the contrarian view and great spot in accounts, once lockdown eases people will lose interest in homes/furnishings.
Hi Paul
We’ve not been in agreement on several stocks recently but I have to say I am totally in agreement with you over the Halopure operation of Strix (LON:KETL)
HaloSource was a failed Woodford investment. I have personal technical knowledge and marketing experience (from a previous career) of the water disinfection market in industry and I am pretty confident that this Halopure technology would have been hawked around the industry players when the owners of HaloSource were trying to find a buyer. The fact that no one in the industry wanted it and it ended up with a kettle controls company (within a side line in domestic water filters) tells you all you need to know.
No position!
£heiq Thanks Paul for another excellent SC Report. I listened to the presentation on Monday & initially ; having had a quick view by Leon B. thought i would start a small stake; however came away with feeling it was over hyped, great enthusiasm and fast research into every possibility that appeared on their screen and also got the impression the Boss , who is the driver, did not work at it full time. Will wait to see land through the Blue sky clouds.
Strix (LON:KETL)
Regarding the weak balance sheet, just looking at the retained deficit on the balance sheet. This appeared first in the 2017 financial statements at £36.4m. This must have come about as part of separating out from other group companies as part of preparing to float on AIM. In the 2019 financial statements this stood at £14m. The ability of the business to generate high levels of net profits of around £20m will mean that the figure will soon becomes a positive retained earnings figure. As such, I am not worried by the perceived weakness in the balance sheet. However, the business should be a bit more articulate in conveying this message rather than just saying that the balance sheet is strong.
Strix (LON:KETL) - Debt needs repaying no matter how the company incurred it. But I do think companies with debt arising from its operations or acquisitions are less attractive than those carrying debt for reasons unrelated to the company's business. Circumstances giving rise to the former are likely to recur, whereas the latter tend to be one-offs.
Strix (LON:KETL) was loaded with debt by the PE house just prior to listing on the stock market and is lower now than it was then.
I've never got around to looking at Strix despite it being quite popular around here.
However that comment has put me right off. It is so formulaic and you could replace "Strix" with a long list of company names - most of which no longer exist or at least are no longer owned by their shareholders.
Moving on ....
Paul, I believe that the Strix (LON:KETL) net debt for FY20 is forecast to be slightly better than expected at £45.5m (1.2x EBITDA).
I take on board your comments about the not "robust" balance sheet, but I think there are mitigating factors and this is short term and the free cashflow is better than it looks at first glance.
This is because for 2019/20 they have incurred c.£16m developing a new factory in China, which is forecast to be up and running (and within budget) later this year.
Coupled with this, they also purchased Laica in 2020 (for c.£20m or £30 with earn outs) the majority of which was financed with £10m cash plus shares.
This is all reflected in the FY20 £45m debt position I believe, but will enhance earnings and cashflow going forward (and also accounts for a lot of the Capex).
Prior to the acquisition of Laica and the construction of the new factory the debt was reducing and free cashflow seemed good.
In terms of kettles being disposable, I agree, but thats what helps Strix (LON:KETL) make money. Kettles are changed on average every 3 years and they have a 54% global share of kettle controls - they seem to have lots of IP / patents which they vigorously defend. This also seems to be a growing market, with China and the US "under-kettled" compared to Europe.
They are forecasting doubling revenues over the next 5 years - most of this being done organically. If they can manage anywhere near this level of growth, then their high ROCE and margins should IMO lead to a much higher share price.
I am long, so obviously biased, so DYOR, and would appreciate any comments / contradictions.
To add to my post earlier this week on additional UK/EU import fees/duties, I have now also sold out of Games Workshop (LON:GAW) in addition to Boohoo (LON:BOO) , the only companies I hold with no EU distribution hub.
GAW Customer Services
For any interested I received the following email from Games Workshop customer services:
"When it comes to any duties fees or customs charges from sending an item from the UK to the EU Games Workshop will be shouldering these costs if any are applied to your order."
They couldn't quite explain how they would reimburse me and condescendingly replied "I think the best thing to do is not over think it too much" .
GAW Delivery Fees
I think they have significantly increased their EU shipping costs since January 1st to protect margins, but I can't be 100% sure of this.
Given the customers they sell to and the prices they charge, they might be able to get away with this.
----
A final point - I investigated a number of Benelux-based Warehousing REITs this week and nearly all of them were 100% occupied already.
Cheers
A
Just on Brexit efects it's worth noting that we've yet to see the real impact of the lack of financial equivalence due to the absence of a deal on financial services. This is hidden from most people and isn't exciting media content but it matters more in the longer term than a bunch of small businesses being unable to export to the EU.
For example, there's been a massive jump in euro interest swaps executed in the US and an equivalent fall in the UK - because EU companies are prohibited from using UK companies until there's a financial service deal
https://www.fintechfutures.com...
In any sane world the UK and the EU ought to come to an agreement on this, because it's in the interests of both to do so. But in a sane world we wouldn't be in this position.
At the same time most trading in European shares in the UK has moved to platforms in Amsterdam and Paris, again because of a lack of equivalence.
Quite what this means for any of the shares I hold, I don't know, although I note that most have set up subsidiaries in the EU so probably not very much, it's just business moving offshore from the UK. The earliest an agreement is expected is March, although there's no timetable and not much enthusiasm from the ECB who don't see it as a financial stability issue and therefore not a priority.
How we could get to Brexit without a deal on financial services is, frankly, mystifying. I can only assume the idea is that by avoiding tying the City to European regulation we can create new business. Be nice if they got on with it, though.
timarr
I don’t think there is a better example of Europe’s “punishment” strategy than this, Timarr and it frankly stinks. They are literally costing their own citizens and business on every transaction , massively reducing the liquidity of their markets, their businesses access to capital and outside of the share trading (which is regulated to EU firms) the business is migrating to the US and Asia anyway. It will always move to the most liquid and cheapest cost of capital. London, with a looser regulatory touch has long been the gateway for most of the world to invest in the EU - now that is much harder or at least more expensive.
The UK is losing now and possibly in the future, of course. But while money flows around the globe (and can’t be stopped), capital and wealth tends to accumulate and right now London is a major financial centre. My guess this is one area that in 2 or 3 years, it will be clear the EU made a major mistake not simply reciprocating the UKs offer of clearing.
I don’t think there is a better example of Europe’s “punishment” strategy than this, Timarr and it frankly stinks.
Hi Phuntt
I think it's a better example of "punishment" rather than the import / export chaos which is more a combination of an inevitable increase in border friction and the worst ever communications strategy ever (our government essentially pretending it's not happening). The EU were very particular about not forcing a date on the UK so that the lack of preparation couldn't be blamed on them.
In terms of financial services though, it looks bloody stupid. The EU could give temporary approval to EU firms to use UK clearing services while a deal is sorted out but have chosen not to, thus increasing the cost of capital all round.
Theories? Well, it certainly puts pressure on the UK to do a deal on financial services and reduces the UK appetite for doing competitive deals with other countries which would interfere with that. Otherwise it doesn't make much sense, as you've pointed out.
Of course, it could just the normal sclerotic decision making in the ECB which will get reversed as soon as the politicians stop squabbling over vaccine availability and notice that the cost of capital has increased dramatically ....
timarr
With regard to Wynnstay (LON:WYN), I have a founder investment in an agricultural data scraping software company supplying the product to major food retailers and manufacturers. It was the fact that Wynnstay was a client that led me to investigate them and invest in WYN. My view was that even if it did originate as a Welsh farmer's co-operative, there must be some senior management with their finger very much on the pulse. Having dug it out, what joy to find the stocko rating supporting the hunch. I'm accumulating.
Just got a quote on Microsoft from HL. No problem. It is also marked as up 21/2%
It's up ~3% according to Stocko. 20% it would be like $280 dollars, but it's ~$238
Looks like the US markets are crashing and so are some platforms, can't get into IG and HL is struggling and can't get any US quotes.
I'm in IG spreadbetting account and it flashed a message that some people are having problems.
Can't get into my IG account at all, just error messages. HL there are no live quotes on US shares and no trades, UK shares seem to be ok to trade.
Robinhood I tried also but could not get into it.
Prices in US seem to be bouncing up now, not that I can trade anyway. I wonder what that was all about?
$GME is up 85% today.
About GME
https://www.bbc.co.uk/news/bus...
Yeah, it's the WallStreetBet guys. Trading was temporarily suspended on IG for GameStop, Blackberry and AMC.
If you'd had an overnight £10 a point on GameStop you'd be looking at a £200,000 profit on the opening bel. AMC currently up 250 per cent.
Etoro also crashed on US open.
It's crazy
Yeah IG is down. Reported across Twitter, most of the major platforms are down in the US.
The conspiracy theorists are saying this is how the GME thing ends, with Wall St taking care of its own and shafting retail. Could get ugly if true.
IG back but wont calculate a margin for long or short FTSE.
Still can't get a margin on FTSE - you'd think days like today would be were they make a killing with so much volatility
I buy items from Aliexpress and they have started charging VAT at source since January, so its not just an EU thing.
Strix (LON:KETL)
I hold.....ironically physically as well in about 2 minutes time when it comes up to temperature
Hello Paul
In addition to that, the basic concept doesn’t make sense to me. Kettles are cheap, almost disposable, very simple items. There’s nothing high tech in a kettle.
Don't know whether you have bought a kettle recently. So my fancy kettle, and I lift this straight from the manufacturers website, has the following features
There will always be a market for cheap disposable kettles just like there is for cheap no frills cars/cookers/bicycles. Some of them are so cheap that it is barely worth getting them PAT tested but there is clearly a market for 'high tech' too. Raising the temperature to 85 rather than 100 requires some fancy stuff but it does make a better cup of instant when I haven't got time to do a real coffee.
I see this as a rapidly growing market tbh although I can see it falls into the what do you get the man who has everything territory and each to their own and all that.
;)
Re: Cheap disposable Kettles. Please tell my wife that ours managed to cost £100- it came with a four piece toaster though.
I hold Strix (LON:KETL) too, following Jack Brumby's tip here in May. Showing a healthy profit. The price is certain to rocket if I now pay attention to Paul's comments and sell my holding!
Apologies for this being non share related everyone but I made the mistake of describing your super kettle to my wife millbank71, and we would love to know the make and model - sounds really hot - well it would wouldn't it?
bosch twk7203
On Quiz (LON:QUIZ) they've managed to get to their good net cash position by unwinding working capital. But there's probably not much more to squeeze there. Key would be to estimate their monthly cash burn currently in lockdown, and assume 3-6 months of depressed trading before party wear rebounds to historic levels.
Then there is the debt facility. While no covenants, it does expire Sep 2021 from memory? Fairly sure there is a risk that HSBC would ask for a equity raise to bolster the balance sheet before renewing.
The they'll need cash for building up inventories again. Can't see their suppliers happy to extend stock on long credit terms, so there will be some cash demand there.
Furthermore it is uncertain how much rent deferrals, VAT, stretched creditors they have that needs unwinding in next 3-6 months. The snapshot from 30 Sep 2020is a bit old.
Hi dahoko,
Your comments don't seem to tie in at all with the numbers that I'm looking at for £QUIZ (I hold). Are you sure you're looking at the right numbers?
Inventories are not squeezed at all, they look high to me at £10.0m (at lower of cost or net realisable value remember). That's up from 6 months earlier, despite them having closed loads of shops. So there's nothing to support your points there.
Current assets are £21.0m (including £5.5m cash), but current liabilities are £11.2m. So a very good current ratio of 1.88 - that's not financially distressed, it's very good indeed for a retailer (which doesn't have much of a receivables book, remember as they sell mainly for cash).
Long-term liaibilities? Just £3.6m lease liabilities, and that's it.
Trade payables are down, not up. To £9.6m, from £11.4m 6 months earlier.
Sorry to be blunt, but none of your comments make any sense at all, when I check the numbers! Maybe you could have a closer look?
I'll go through the figures in more detail when there's more time available. Nice problem to have - why does the balance sheet look so much better than I expected?!
Please don't take any offence, Paul.
Paul, you're absolutely right - I had pulled the wrong numbers on Quiz (LON:QUIZ) into my spreadsheet - pitfall of having too many tabs open at the same time at different companies!
Stock has gone up, and digging through the interims, it looks like it has been provisioned against / written down in the period already so it represents fair value now going forwards and (hopefully) not an inflated value on the balance sheet.
You are right the balance sheet looks still decent for a company that's had a horrendous 6 months. Positive net current assets. Positive net tangible assets.
Still worried about the HSBC facility though expiring Oct21. There's no "family silver" in terms of property they can put up or sell to renew the facility. And I still think there's another £2m-£2.5m of cash burn in the months ahead before they return to cashflow break-even.
And business rates holiday ending March, and no word from Sunak whether its going to be extended.
Still, a compelling investment at the current market cap of under £9m!
Hi dahoko,
Ah mystery solved, thanks for double-checking your figures, I thought something looked awry, as your posts are usually very sensible!!
I've spent a bit more time on QUIZ's figures, and worked out where the balance sheet strength has come from - the previously heavy lease liabilities have now largely disappeared, because of the pre-pack administration getting rid of the previous lease commitments. That's repaired the balance sheet very nicely.
I'd like to see QUIZ (I hold) reduce inventories, which are too high. Plus of course they'll have surplus inventories coming back from the closed concessions. Hence lots of gear to shift, I imagine plenty of that probably would need discounting to not much above cost price. Hence we might see a further hit to gross margins, but turning stock into cash should mean cash burn could be little to nothing in my view.
Remember they're not paying business rates, and probably little to nothing in rents on the new leases.
Hence everything still to play for, I don't see any financial distress in QUIZ's figures, which is a pleasant upside surprise. Roll things forward say a year, and it should be trading profitably again, and I've pencilled in a share price 3-5 times the present level, if things play out decently longer term. Probably not much risk of it going bust either, hence I reckon risk:reward is a lot better than the current share price implies, but only time will tell.
Regards, Paul.
Hi
They managed to get a net cash position by taking government money, not paying their rent, and then having it written off. It would be like someone on benefits not paying rent and having the debt written off. It just a poor business and I hope your not invested here.
All the best.
BSV
Talking Macro - for those of us long in companies on very high PEs.... Note this is all speculation, it might be scaremongering, I am not an expert.
I just read an interesting tweet series about what is going on with Gamestop and possible ramifications.
Basically the tweets author was saying, sure this looks funny and who can't agree with "stick it to the shorts". However Billions of dollars are currently being thrown about in a market that is heavily based on leverage. If the funds currently massively underwater start having to sell down their long positions to meet their margin calls, we *could* see a tsunami of leverage unwinding that shocks the market.
Trade carefully! :)
Original tweet series:
https://twitter.com/hkuppy/sta...
Kuppy is the best spiv ever.
What he's talking about though is relatively narrow part of US market. Its much less systemic than the quant quake he references. The quant quake was by comparison the positioning of huge part of market being the same way through effectively QVM models (implementation differences cause drift between people over time in benign markets but when something shocks everyone suddenly moves in sync in buying and selling - note this happened before the famed 2007 event, for example during 9/11 and even before than in the late 90s to more muted degree through combo of emergent QVM and risk tracking models being used for first time).
I think in these tweets Kuppy is seeking to manipulate events. He has massive following amongst the stonks crowd...he is their messiah.
I might be very wrong but I think GME is a blip and that the brokers are well aware and able to manage the risk
Thanks for adding context.
There's a lot big names throwing tweets about. More evidence to me the regulator has lost control.
Some strange old moves in the US alright. AMC is up from $2 to $17 in last 3 trading sessions. GameStop has gone mad. iRobot trebled pre market. A social media driven frenzy of retail investors crowded in a small number of trades. Not healthy for a market this.
IG flashed a message an hour ago saying they had stopped taking options on GME and holders had to contact them directly.
Cineworld (LON:CINE) up 10% today, supposedly for the same reason as GME - it's heavily shorted. Crazy times!
I got stopped out of a Cineworld (LON:CINE) short at open this morning.
Will FOMC discuss raising Reg T requirements for first time since 1974?
Or would that be anti-democratic as the narrative is that the little guys are beating the big guys? And the Fed is probably very sensitive to being seen to be against the little guy at this time.
On balance I think its just another mad moment in a string of many. I suspect they will do nothing as its the big guys losing short GameStop and they will learn and adapt.
High valuation is probably okay-ish until late Feb, March. We are caught in a war between two unrealities...the unreality of tech super dominance over all and the unreality of value/old econ recovery. The former unreality has the upper hand as we are in a hiatus between anticipated recovery (Q4 last year) and real messy recovery (c.Q2 2021)
Hi Igotpoesjacket,
John Authers Bloomberg column touches on this very point this morning as does todays daily investors chronicle update from IC Trader.
Here is the Investors chronicle link: http://ftmail.ft.com/interface...
I think you need to sign up for John Authers free daily email at Bloomberg.com but it is well worth it as his columns are very thought provoking and I know Paul and others have recommended them here before.
Richard
I can shed some light on HEIQ.
The reason for the SP fall is that H1 est rev was $30M H2 $19.1M This was due to large sales of masks in H1. P23 of the Cenkos note dated 040120 explains this and the Viroblock revenue estimates.
But H2 margin was impacted by investment including the listing costs of $3.7M. So take out the one-off listing costs and you get this. 35% EBITDA margin.
So my conclusion is HEIQ is a high growth business making good margins and likely to grow quickly – certainly faster than the conservative Cenkos estimates. Ahead of itself at 240p but oversold at 160p. IMHO.
re Scapa (LON:SCPA), personally I think 210p is too low by quite a long chalk, even allowing for the legal shenanigans. I don't hold, and serve me right for not backing my judgement earlier.
Boohoo (LON:BOO) (I hold)
I think someone mentioned the possible impact on BOO of current issues being experienced re Brexit, and import/exports from/to the EU.
My sister-in-law runs a small online business that sells niche products globally, and she said that dispatching just 12 items to EU countries took her a whole morning in admin. Apparently it's very difficult at the moment.
I've seen press articles about this problem too - that large brands are incurring import tariffs, requiring customs declarations, etc, when sending goods into the EU now. Forget the politics, we're just interested in the business side of things here.
I also saw another article, saying that customer returns from online goods shipped to the EU are piling up at the ports, as nobody wants them! Also that customers receiving items ordered online from a UK website, are being hit with a bill on arrival from the courier, which some customers are refusing to pay. I experienced this when I bought some items from a US website a year or two ago, for about $200, and was stung for over £50 on arrival by the UPS driver, due to tariffs, etc. So I'll never order from an overseas website again.
How might this impact UK online retailers? From the ones I've looked at;
Gear4music Holdings (LON:G4M) (I hold) - seems to have pulled off a blinder, by setting up EU distribution centres in Germany & Sweden several years ago. So fully operational for a while, and it should be fine. It can directly import goods from the Far East into the EU, pay any tariffs on arrival in Germany/Sweden, then dispatch all over the EU without a problem, from within.
Boohoo (LON:BOO) (I hold) - mentioned this issue without going into specifics, in its update recently, on 14 Jan 2021:
Brexit
The Group has implemented operational systems designed to minimise the impact of Brexit on its customer proposition in Europe. The Group does however expect a small cost headwind, predominantly from higher distribution and administrative costs, which the Group will seek to mitigate where possible.
Other than that, I'm not sure what other companies are experiencing.
A newspaper article today says that UK companies are setting up warehousing in Holland, to get round the issue of problems at the border, which makes complete sense to me. Import UK-destined product from the F.East into the UK. Then import goods destined for EU customers direct into the EU. Probably more efficient to do it that way anyway.
BOO is an extremely fast, adaptable business, so in my view they'll find a solution (probably already have done) to this issue, so no concern there. Any impact would only be temporary.
For smaller companies selling online into the EU, this could be a thornier problem. Any thoughts?
Regards, Paul.
My wife sells items on Ebay and one item to Holland was a complete morning's work to fill in three customs declarations, including having to contact the buyer for information from him that she need to populate the form (he made the point that no one else had ever asked him for the information before).
It's not the tariffs that are killing exports and imports. It's the paperwork. I think it was a French minister who made the point that the EU is asking the UK for more paperwork than any other country EU member states do business with.
It's an outright punishment beating and effectively economic warfare. French hauliers are already refusing to deliver to the UK as they can't get backloads, tons and tons of EU produce are piling up and rotting.
We just need the media to highlight what is going on, retaliate in kind with massive paperwork checks of our own and encourage the population to buy from anywhere except the EU and China, who both run massive trade surpluses against us whilst being actively hostile towards us.
Good for the European warehousing industry though. Companies like Clipper should do well out of hosting UK companies products. We really need these Freeports, we were promised by the government, setting up quickly.
Lastly, this pettiness and difficulty to trade with is exactly why the EU is slowest growth area in the world and why several of its major economies are going backwards.
It's an outright punishment beating and effectively economic warfare.
I'm afraid this is complete non sense. It's Brexit. The UK wanted to be treated as a 3rd country by the EU, and it now is. These issues are exactly the sorts of reasons why the SM and CU were set up, and why there are a success. We wanted out, and we are. Undoubdetly, there will be a period of teething issues, not helped by the zero period of time between the agreement and its implementation, so systems were not fully functiona, and false promises of no problems. People now spending a morning filling paperwork will learn how to do it quicker. But the fundamental issues will not change, unless we renegotiate, which seems unlikely for now at least. It's hard to see how small exporters will be able to adapt. It was being in the EU that made that business model possible for small companies, and allowed that sector to develop.
off topic for investments, sorry.
peterg is exactly right here.
do other non EEC countries moan that there is paperwork to do when sending goods into EU states? (possibly, but I suspect not - they have other trade deals as they may need and are used to working with the setups they have)
what were we expecting when we voted to leave the EU - some form of golden parachute for being especially good over the last 30 years, or being treated like a traitor who should be provided the least possible benefits to avoid further breakouts from other member states?
expecting anything other than short term customs paperwork mess and short to mid term economic stagnation by leaving the EU would have been being a little naïve I think and I suspect any sensible small companies planning to trade with the EU post-brexit would have heeded the advice over the last couple of years to get ready for this.
expecting anything other than short term customs paperwork mess and short to mid term economic stagnation by leaving the EU would have been being a little naïve I think and I suspect any sensible small companies planning to trade with the EU post-brexit would have heeded the advice over the last couple of years to get ready for this.
That's a bit unfair on smaller companies - they couldn't get ready because they didn't know what to get ready for. Even many of those that thought they were ready have been blindsided by some of the issues. They simply don't have the capital to make expensive preparations they need to then change as the political winds alter.
In general small companies outside the EU don't trade direct with the bloc, they either use intermediaries (who take a cut) or don't bother (because it's too expensive). UK small companies who have been able to trade without friction as part of the EU have been left stranded by the tide going out - any of them whose business cases depend on friction free trade with the EU are in deep trouble.
Overall I don't think the EU are deliberately making things difficult for the UK - the reality is that it is difficult for any third-country to import into the EU, let alone one that doesn't know how to do it. The EU was never going to make things easier for the UK, regardless of the economic consequences, because, effectively, that would be signing its own death warrant.
Dragging this back to investing, I'm wondering what the impact on inflation will be? Rising costs and diminishing supply are fertile inflationary grounds, and any significant rise could significantly affect the government's ability to reflate the economy as well as raising interest rates. A run on sterling would be a real problem, and not just for investors.
timarr
I don't think inflation will be an issue. There's little to nothing the EU provides us that can't be sourced elsewhere and we may see prices of some goods fall. For example the EU can't produce foodstuffs as cheaply as Africa. The shops used to be full of South African fruit when I was a teenager, I suspect they will be again.
There's little to nothing the EU provides us that can't be sourced elsewhere and we may see prices of some goods fall
Longer term, I'd agree, but I'd still be concerned about the trajectory over the next eighteen months.
It'll take time to do proper trade deals and reorient trade channels, a lot of stuff is channeled through the EU (I still can't get my head around cabotage) and current shipping costs are through the roof. And, as we've seen in the past, companies are very smart at pushing through inflationary price increases under cover of political or economic upheaval.
Anyway, we will see. Boohoo apart, I'm very happy to avoid companies exporting or importing goods at the moment.timarr
"I think it was a French minister who made the point that the EU is asking the UK for more paperwork than any other country EU member states do business with"
To be honest, the vaccine rollout is not helping the economic problems. Die Zeit, one of Germany's most respected broadsheet newspapers, said that EU has managed to play into every criticism brought up during the Brexit saga - that "it is acting slowly, bureaucratically and [is] protectionist. And if something goes wrong, it's everyone else's fault". France has only managed one million vaccinations so far compared to over 7 million in the UK and some other European countries have only managed a tiny amount.
European leaders and the European Commission are getting roundly criticised daily in the media with the UK being held up as a shining example of what could and should have been achieved. Having known politicians all my professional life I can imagine exactly what impact that is having (can you imagine what Opposition parties would be saying in the UK?)....so I cannot see there will be any rush to improve anything at the moment in terms of trade and red tape etc. I suspect communication is very limited at the moment at ministerial level and these problems will continue for the rest of the year.
Afternoon barnetpeter, re the EU trade position and your quote (I voted remain, but NOT being political on the issue here)
EU has managed to play into every criticism brought up during the Brexit saga - that "it is acting slowly, bureaucratically and [is] protectionist. And if something goes wrong, it's everyone else's fault".
Exactly it's root problem - Maybe my vote was wrong, UK leaving (maybe followed by others) will get them to resolve their underlying dysfunctions.
Hi ezlifeme. I think we can be fairly sure that nothing much is getting done and the ONLY things Europe and European politicians are really interested in at the moment is the vaccine, who is going to get forced out of office and their likely replacements. Unfortunately, this means that the economy will rather get forgotten.
My company imports goods made in China and then distributes all over the EU. We generally use UPS on a next day service, as of this year most shipments are taking two days and the customer is being charged 10-25 euro admin fee, there has not been a lot of extra paperwork for us so far as UPS systems take care of the declarations . Typical order value is 5-25K euro to VAT registered companies. I think BOO will have to setup an EU fulfilment centre to remove the fees private individuals are paying on low value orders.
Re Boohoo (LON:BOO) and European sales, I am somewhat taken aback by Boo's solution to the extra costs incurred by the customer (basically tell us and we will refund you). This is not a real world solution and makes me question my belief in their commercial acumen. Maybe I am being overly harsh on them (and they source the US from Lancashire) but it was clear for some time that the agreement we would get would be pretty flimsy and entail a lot of admin and just these sort of problems.
Maybe Boohoo (LON:BOO) is, as I write, organising its Polish european fulfilment centre to be up and running shortly (a project of which we knew nothing)
Long BOO
Hi Housemartin2,
it was clear for some time that the agreement we would get would be pretty flimsy and entail a lot of admin and just these sort of problems.
Was it? I thought the consensus view seemed to be that the negotiations between EU & UK would go to the wire, and then both sides would compromise and avoid no deal.
I don't think people foresaw problems for eCommerce companies in this way.
For a business of BOO's size this is a fairly trivial issue. They can outsource distribution in the EU quite easily. Or rent a warehouse in Holland or somewhere, & do it themselves. Probably just weeks or a few months to set up something like that.
On the recent conference call re Debenhams, an analyst asked them how they intended dealing with returns from DEB customers, and BOO management indicated they're going to outsource the logistics. So it stands to reason that they'd do something similar with EU distribution for the main brands.
Some temporary disruption, might have a small profit impact, but it's not something that fundamentally changes anything, nor how to value the shares. Businesses of all sizes encounter operational glitches all the time. They can also dial marketing spend up or down at will, and that's a huge variable cost. I've been tremendously impressed with how online businesses did just that in 2020 over covid. Look at Sosandar (LON:SOS) (I hold) for example. It was burning through cash like nobody's business, but then they slashed spending once covid hit, and brought cash burn down to almost zero, despite sales growth slowing a lot. These online companies are tremendously flexible, it's a massive advantage.
Regards, Paul.
Paul Thanks very much for taking the time to respond.
I am not sure that the process of setting up a full scale fulfilment operation to serve EU countries is quite as straight forward as you imply, though I appreciate that you will know much more than me about this sort of thing.
Rgds
HM2
I sell on Ebay and I've simply been going to the post office, filling out and sticking a customs label on the parcel (as I would do if I was sending to e.g. USA) and off it goes, am I missing something??
Lets hope they are aware of the charges and don't refuse delivery. Here is an article about some of the issues: https://www.bbc.co.uk/news/business-55757931
I'm reading quite a few EU companies have stopped sending goods to the UK or are charging ridiculous delivery fees. Also apparently the £15 allowance has been scrapped, so even on a low price item you maybe charged VAT, duty and custom handling fees, which would often be more than the cost of the item, this even applies to used items. The Post Office charge £8, DHL I think is £30 minimum.
My understanding is VAT is payable on all items imported into the UK unless exempt.
Under £135, the VAT will be collected at the point of sale. Over £135 the VAT (plus any duty payable, plus a customs handling fee) will be applied by UK customs and charged to you separately by the customs agent.
Scott - interested to know if you've heard back from any of your EU customers. Have any of them been faced with having to pay duties/VAT/extra admin costs etc on receipt?
If not then maybe it's to do with the value of the goods being sent. Is that a possibility?
I know nothing about the new rules but is there a lower value of goods limit below which VAT/duties are not payable?
I haven’t heard back from any of them, but I generally sell low cost goods, max £20 I would say so either they are below the customers threshold or the buyers are just soaking up any costs (and probably swearing as they do so). It’s only hobby trading so I’m not shifting massive volume, I would say on average 1 - 2 items a day to EU.
Scott Porter
I haven’t heard back from any of them, but I generally sell low cost goods, max £20 I would say so either they are below the customers threshold or the buyers are just soaking up any costs.
It just so happens the vat free limit is generally 22 euros for imports - so you are probably pretty much on the bubble in that regard.
Note the current rule ends 1/7/2021 - so from that point on import vat will aply - however a system similar to the vat moss system called the import one stop shop - you will have to pay vat on a country by country basis and submit returns as approrpiate. Bit of apain but ultimately manageable .
https://www.avalara.com/vatliv...
something like that anyway
When my wife turned up at Hermes with the parcel (on which she'd also stuck the PO customs label on) she was specifically asked whether she'd included the customs invoice in triplicate. The form required an inventory of contents, the tariff number of the goods, the country of manufacture, her tax number and the receiver's national ID number.
Who knows what's right - and that's the problem. In the meantime, she's stopped sending to the EU.
Boohoo (LON:BOO) is an extremely fast, adaptable business, so in my view they'll find a solution (probably already have done) to this issue, so no concern there. Any impact would only be temporary.
Agreed. It would be disappointing if they hadn't already done so, but they have the finances to overcome this. As noted by abtan on a thread earlier this week Boohoo are offering to reimburse customers being charged duties and fees, so it does rather suggest that they haven't prepared fully for this.
As also mentioned by another poster they might benefit from UK customers switching from EU suppliers. I'd be a bit surprised if that was true, Boohoo caters for a specific type of customer, it's not obvious they'd be a substitute for EU suppliers.
For smaller companies selling online into the EU, this could be a thornier problem. Any thoughts?
Larger companies, in the main, can overcome a lot of the problems by shipping from outside the EU directly to the EU - the main issue occurs when shipping from abroad to the UK (duties apply) and then to the EU (duties apply). However, where materials are shipped to the UK (duties apply) and then finished in the UK the actual goods may or may not be subject to duties depending on the percentage of UK content.
Broadly, smaller companies didn't have the resources to prepare for any eventuality and were left exposed by the last minute nature of the deal. Many of them only supply to the UK and the EU and have no experience of cross-border customs and shipping. Large companies with cross-border shipping have software that manages the interface with the allegedly terrible government systems but smaller companies are trying to navigate them with minimal HMRC support.
It's hard to know how this will play out - clearly some of this is short-term, but many smaller companies won't survive to see better days. Some of it is longer term - the duties and fees aren't imaginary and even if companies can utilise European warehouses to minimise the pain they will still have to pay the overhead associated with that.
But in the end Brexit was about erecting trade barriers in return for other, non-economic, benefits. We shouldn't be surprised if it increases costs and reduces profits. Overall larger companies should be fine, eventually, but smaller ones will suffer disproportionately.
timarr
Letter in today's Times saying that shipping a pallet of paint to Ireland used to take 5 minutes and cost £95. Now taking an afternoon and costing £400.
I was looking on Amazon for toys for my grandson at lunchtime and there's a lot of stuff out of stock - more than I have ever seen.
The global shipping chains are in a Covid related mess with empty containers not getting back to the Far East. Add Brexit issues that have caused Felixstowe to be such a bottleneck that shipping companies are refusing to send ships there, and if anything I see this getting worse before it gets better
Hi herbie47,
My understanding is VAT is payable on all items imported into the UK unless exempt.
Under £135, the VAT will be collected at the point of sale. Over £135 the VAT (plus any duty payable, plus a customs handling fee) will be applied by UK customs and charged to you separately by the customs agent.
If you watch the programme 'Watchdog on The One Show' on BBC at 7pm tonight it perfectly explains the rules regarding VAT on goods from Europe. It confirms what you have stated is totally correct about who collects the VAT.
The net asset value of £4.79 a share is also worth bearing in mind.
Jack,
That is the FY19 NAV. The figure for year ending October 2020 is £4.92.
All the best, Si
Thanks for flagging Si, I've updated it to the 2020 NAV figure.
My take on the Wynnstay (LON:WYN) chart for anybody interested.
This chart is clearer on the weekly, and looks like its just now breaking out of a clean ascending triangle, or Minervini-speak VCP (Volatility Contraction Pattern).
Volume is decent, and I would consider it to be the 'buy zone', which is the blue box (breakout point +5%). However, the spread is fairly high at around 4%.
Note: This is not a 'buy' recommendation, but just my analysis of the chart.
Good summary there - but pretty sure it's trading well above the 200dma at the moment.
You're right! my bad. I'll edit the post.
Hi Jack, Excellent analysis of LON:WYN (I hold). One thing to add about the Agriculture side of the business is that it, if my memory serves me well, runs on a cost plus basis - low margin but essentially guaranteed - this provides a strong foundation for the growth side of the business. Now wondering if I should top up.
Anyone know what happened to HollandSmith - can't even find him in the forum?
also the HeatMap person?
I don't know what happened but last post was 1/12 and the last time he had a race with Mr. C to see who was first with the morning news was here:
https://www.stockopedia.com/content/small-cap-value-report-thu-12-nov-2020-snws-vlx-nwf-nxr-idea-ttg-clg-699743/?comment=1#1
Hi Paul, thanks for the great write up and your attention to detail on Saga (LON:SAGA) (I hold) yesterday. I read a motley fool article last night on Saga saying that the company had a cash burn of over £6m per month which had contributed to the net debt rising 139m since 31st July 2020. Obviously this paints a very negative outlook for the company!
However as you pointed out it is the travel division losing the £6m per month which is covered by the insurance division and the additional £139m debt was the drew down on the second ship (spirit of adventure) loan. A lesson to not believe everything you read and do your research.
Yes, well I'm afraid there are other, less diligent small cap commentators out there, but if you want quality, this is the best place to come! :-D
(my cheque's in the post)
Please forgive me for being up an off-topic subject.
I was watching YouTube (an investment program) and I was interrupted by an ad. It was a guy going on about Blockchain, His name was Mr. Teeka TIWARI, He describes himself as (multi-faceted financial market pioneer). After over an hour he was selling a tip sheet for USD 50.00 a year, He was very convincing, But as they say, if it's too good to be true etc.
So I thought I would ask the Oracle ....... Yes, that's you guys. does anyone know about this American gentleman? Is he legit?
I have tried Googling him but I am still not sure,
Again my apologies
He's just giving away tips for $50 per year out of the goodness of his heart right? These tips are so amazing and he's made so many billions in the market that he thinks its time to generate some returns for the little guy.
Caveat emptor.
That's what he said.
I think his brother is a colonel in the Nigerian army who is willing to give friendly Brits money if they can help him get his cash into the UK. All you have to do is give him your bank details and he will make you rich.
Of course, you are right, thanks
It could be worse - YouTube keeps showing me ads for Nigel Farage pushing his latest venture.
There was a comment / question in the comments yesterday about whether the £6-8m cash burn at Saga (LON:SAGA) was for the company as a whole, or just the travel division. Investor relations have just confirmed to me, as suspected, it relates to the travel division only.
Scs (LON:SCS) gave a decent update this morning. You may not feel the need to comment, Paul, as it basically confirms what you have said about ScS in the past. Rock solid balance sheet, pent-up demand, they can afford to wait until stores re-open.
In the meantime (my bold) "Gross sales in the 26 weeks to 23 January 2021 increased 13.9% to £182.3m (2020: £160.1m). This increase is due to the significant order intake growth seen in June and July 2020 following the first lockdown, together with the strong trading in the first quarter of the current financial year. " So they are catching up with orders, which is good.
"As at 23 January 2021, the Group's order book is £90.5m (including VAT), £16.8m larger than at the same point in the prior year."
"The Group's online sales channel continues to make good progress, with the half year seeing an increase in order intake of 98% when compared to the same period in the prior year." I can't see the actual figures, it might be a 98% increase on quite a small number.
"The Group has maintained a robust balance sheet, with cash at 23 January 2021 of £91.8m and no debt."
I am a happy long-term holder.
Scs (LON:SCS) continues to be a share that gives some confidence in holding. Now that the government allows distribution centres to remain open they can continue to deliver product. Sales increased 13.9% in the 26 weeks to 23 January 2021. They give breakdowns of order intake during the variety of circumstances including part closure and eventual full closure of stores but progress is still good overall there with the half year intake being 98% up on same period last year. Cash balance at January 2021 is 91.8 million (no debt and Stocko shows market cap to be £79 million) Is the Stocko enterprise value at £133 million correct?
The CEO is leaving but the handover is very orderly and retiring CEO stays available until July.
The dividend is not mentioned!
The outlook is cautious but positive: Whilst it is too early to provide clarity on the outlook for the weeks and months ahead, we remain cautiously optimistic given the strong trading experienced by the Group following the first and second lockdowns. Given the tactile nature of our products, the majority of customers chose to wait until stores re-opened to try our products in person before making their purchasing decision. This resulted in the business benefiting from pent-up demand, coupled with an increased level of investment by UK consumers in their homes. The Group has built a robust balance sheet and continues to focus on cost and cash management to ensure we maintain this resilience in these challenging times.
Also why does Stocko show the bankruptcy risk as high for a share with no debt and robust cash balances?
S&U (LON:SUS)
Also why does Stocko show the bankruptcy risk as high for a share with no debt and robust cash balances.
Not so coincidentally this exact same business in a prior incarnation i think had no debt one minute and went pop not so long after.
You should always drill down into the balance sheet to see what the payables are - it was the trade payables that brought hmv down and brought game to its knees - so debt is only half the picture with regard to bankruptcy risk - if your suppliers will stop giving you stuff on "tick" that will equally put you out of business IF you cant find sufficient liquid cash to make that problem go away.
Looking as sus they have £81 mill of trade payables - so this accounts for all the cash - obviously if they started making losses and the cash pile dwindled materially creditors may start to get twitchy. So i would say sound as pound here but the £81 mill liability is real in te same was as debt - albeit at least no interestbeing charged.
Note you may choose to ignore it but another material factor is the lease liabilities they are another £130 mill - so thats probably what pushes the stocky computer over the edge - it probably is a slight risk that if some stores stop generting profits they could end up with hefty future liabilities not covered by income - practicably speaking without having done the specific research i would be minded to say this is only a problem if the entite buisness model doesnt work at which time it woudlnt be good investment anyway - but if they have long leases and some units may never be the same post covid that would be an issue.
I would applaud the company for having the cash pile - it may not be making the most bang for your buck - but is does give everyone confidence (mostly supplier that matter IMHO) that the company won't go pop and should be enough to see it through the toughest of reccessions (if leases are ok) - i would say the stocky computer system here is doing an excellent job pointing out the £210 mill of liabilities shouild at least be considered before making an investment decision here.
I would have no qualms about holding here whilst the balance sheet is as good as it is - and i lost 2 of my shirts in a previoous incarnation of this very same business.
Hi, rmillarie, Are you actually writing about Scs (LON:SCS) rather than S&U (LON:SUS)?
Hi, rmillarie, Are you actually writing about Scs (LON:SCS) rather than S&U (LON:SUS)?
Yes well worked out SCS it was - apologies for any confusion
Also why does Stocko show the bankruptcy risk as high for a share with no debt and robust cash balances?
[ SCS (LON:SCS) ]
IFRS16 lease liabilities mainly.
I also saw the Heiq (LON:HEIQ) presentation at Mello on Monday. I came away with a really positive impression. However, a few days on and I am starting to cool. I am worried about the high climb in price over a month or so. I think this is down to its development of Graphene membranes which it has added to a mask product.
Graphene was meant to transform a lot of products, but companies in the market over the last 10 - 15 years have done poorly and never seem to get past R&D in to a profitable product (I might have missed a successful company?).
I also had a quick look at the IPO summary prospectus: https://heiq.com/wp-content/up... Ok, so a reverse takeover is a new concept to me. In the prospectus, it shows historical key financial info. In the 1st half of June 2020, it shows an operating loss of £65m. Would love to know what's happened to now show a profit?
Would also like to know the breakdowns of profit for its product lines, to see if less risky returns are from its other areas, rather than from Graphene and masks.
The risk taker in me wants to invest, but it will have to be at a lower price
I think you are looking at the losses of the company it reversed into, which was £65k not £65m?
Oh dear! I need my eyes tested :) Thank you
HeiQ. Very interesting evening at MELO. I think Paul hit the nail on the head again. A pe of 170! I guess the figures are still to follow to be fair. Very enthusiastic presentation and looks like a very interesting textile company making fabric with anti bacterial and virus blocker built into fabric. I notice Miton Group amongst others have a holding and management hold about 25%. Need some updating on info at Stokopedia!
Thanks to all contributors at Melo. I joined specifically to hear what the CFO of KMK had to say about their current financial situation. Another hard one to value at the moment, but potentially an exciting and important future.
Enjoyed 'the bash', a very democratic way to get a consensus of expert opinions on stock. Kape another one I have traded, and a little suspicious of its management and figures as pointed out by some wise owls.
I was impressed with their (Heiq (LON:HEIQ)) presentation at Mello especially around their products and Viroblock product in particular. This is an antimicrobial technology that HeiQ has developed and has been used in facemasks. It is something that may also gain traction under the COVID-19 environment and consider it a market opportunity.
However, as noted, the share price reaction to the trading update was severe. The share price has ran away in the past month since listing. And a further -15% fall to 155p this morning.
Andy Sav: in relation to the historic trading, HeiQ has achieved revenue of $21.1m in 2017, $26.2m in 2018 and $28.0m in 2019. Profit after tax has been around breakeven historically.
The numbers you are referring to relate to the listed company into which HeiQ reversed.
Cenkos has produced forecasts:
Revenue growth in 2020 of 54% looks good but then I wonder whether 2021 revenues expectations have scope to be increased.
They have forecast EPS of $0.05 for 2020 and $0.07 for 2021. This still puts HEIQ on a forward PE of 31 which is still quite rich. However, it is going on my watchlist and I will read the 2020 financials when released.
much appreciated :)
Continued director buying at U And I (LON:UAI) following the recent interims. This looks as if it may have the makings of a positive turnaround, given the radical action proposed and new CEO, Richard Upton. Further to my previous post I added to my existing holding, following the example of directors. Fingers crossed!
Also decent interims from Hargreaves Services (LON:HSP). Much more to come I think. It is now fully divested of its historical interests in coal and eliminated bank debt in the process. Reported NAV of 400p versus a share price of around 250p, plus the promise of a special (additional) 12p dividend at the prelims. Boring...maybe, but I am happy to be bored if that is the case.
Best wishes to All
Yes please Paul I would also be pleased if you had a look at Strix ,Strix (LON:KETL) but I wouldn't describe the share or the company as boring because they have a bit of technology that may be transformational in the pig farming sector in China . The TS has the following paragraph in it which I believe will be significant for the future growth of the company with the first installation at the end of this month
"For professional water, Strix recently announced that the HaloPure technology was selected by Chia Tai Group, one of the most specialised, well-known livestock companies operating in China, and Strix will install its full system by the end of January 2021. HaloPure's technology has become increasingly well recognised by the market and the evolution to offer farming solutions for clean drinking water is likely to result in significant further business opportunities for the Group in the future."
They have a whole stable of patent protected products and systems so the moat is quite a big one .Very cash generative and they pay good divis as well !!!!
By boring, that’s a compliment!
Water for pig farmers is not going to set the world alight like a Tesla or Netflix, but I see it steadily growing and being worth a lot more in 5-10 years time
Yeah, because the Chinese have a great record of protecting patents....
Great opener there Paul, with 5 companies before the bell - Much appreciated as always
Well, in lockdown there's nothing much else for me to do! So I was burning the midnight oil for you last night :-)
Do hope you save some of it - Thanks again
Paul
Can you have a look at Strix, £KETL please
Nice tuck-away share with good dividend and seems to have a decent moat with its products
Boring share but aspirations to double revenue in 5 years (which seems doable) and a nice yield on the way....
Thanks
My morning smallcap tweet:
CIP Merchant Capital (LON:CIP) Catenae Innovation (LON:CTEA) Seeing Machines (LON:SEE) Mobile Tornado (LON:MBT) Quartix Holdings (LON:QTX) Uniphar (LON:UPR) EQTEC (LON:EQT) Strix (LON:KETL) SCS (LON:SCS) Motif Bio (LON:MTFB) Wynnstay (LON:WYN) Applied Graphene Materials (LON:AGM), Renew Holdings (LON:RNWH), Hargreaves Services (LON:HSP)
CIP Merchant Capital (CIP) notes possible offer of 50p, below the SP of 56p. Co will consider it. [SP=53.63 Cap=29m]
Catenae Innovation (CTEA) £1m placing at 2p, a 23% discount, to "enhance its proprietary technology capabilities, build upon its business development strategy and for general working capital purposes." Also unimpressive trading stmt. [SP=2.53 Cap=6m]
Seeing Machines (SEE) [edit] update on work with US giant Qualcomm to to design a driver monitoring system solution. It read as if it was a new collaboration. "We expect this engagement to deliver significant incremental volume on top of our existing business plan." [SP=11.6 Cap=434m]
Mobile Tornado (MBT) guides FY(Dec) rev c. £2.52m .EBITDA c. -£0.40m. Recurring rev flat but non-recurring only £0.49m (£1.39m). Also 1 year renewal of long standing contract with its Mobile Network Operators customer in North America. [SP=4.8 Cap=19m]
Quixant (QTX) guides FY(Dec) rev $63.8m and adj pretax over $1m. No comparatives or in line stmt. "We have healthy order coverage for the first half of 2021, although delivery of the order book will clearly be impacted by a tightening of restrictions due to COVID-19." [SP=429 Cap=206m]
Uniphar (UPR) gudes FY(Dec) gross profit & EBITDA ahead of mgmt exp. The only figure they deign to reveal is organic gross profit up over 6%. "We are confident and remain on track to achieve our strategic objective of doubling EBITDA within 5 years of IPO." [SP=2.42 Cap=621m]
EQTEC (EQT) gets planning for for sustainable waste gasification and power plant at Billingham. [SP=2.42 Cap=170m]
Strix (KETL) sounds in line with FY(Dec) adj pretax up 2%. [SP=233.5 Cap=481m]
ScS (SCS) guides H1(Jan) gross sales up 14% and order book £90.5m up £16.8m. [SP=210 Cap=80m]. I hold.
Motif Bio (MTFB) reveals RTO target is a UK-based Antibody-Drug Conjugate discovery and development company. Shares remain suspended. [SP=0.5 Cap=3m]
Wynnstay Group (WYN) FY(Oct) rev down 12%, U/L pretax up 4%. In line? Current trading in line. [SP=354.79 Cap=71m]
Applied Graphene Materials (AGM) [last night] £5.5m placing at 41p, a 39% discount, to keep the lights on. [SP=NA Cap=NA]
In line: Renew Holdings (LON:RNWH) Hargreaves Services (LON:HSP)
Another takeover announced this morning: Scapa (LON:SCPA) receives a recommended bid from Schweitzer-Mauduit International, Inc. at 210p in cash. This is 18% more than the 177p closing price yesterday.
As a holder of Scapa (LON:SCPA) I am slightly disappointed by this offer - I see it as a smart opportunistic move by the bidder. I bought in last August and my initial price target was 240p, hoping for a longer recovery on a 2-3 year view.
The price was as high as 400p in 2019, with only c.20% added to the share count in the placing last summer (c.330p equivalent). I note it's trading at 220p this morning, 10p higher than the offer price, so some are expecting a competing bid. If that premium goes a touch higher I may sell out, but like Paul says, it's a dilemma, and 50:50 is probably a good approach.
It is a very opportunistic bid. And as you say, I wonder whether it flushes out any other bidders?
Interestingly £SCAPA did an equity raise last year and the share price dropped below to c.84p at the end of July 2020 before recovering after results were released in early-August. From memory, management were very cautious about the recovery initially and had factored this into their Covid-19 scenario. By August saw a substantial increase in demand and said there were trading ahead of these plans.
It sounds like a sensible management team of under-promise and over-deliver.
Morning Paul,
Would the Wynnstay (LON:WYN) results be something you might be able to take a look at?
Kind regards,
Paul
Wynnstay (LON:WYN) looks in line, according to MrContrarian, so probably not of much interest. But seeing as 12 people have up-ticked you, I'll give it the once over later this morning.
Thank you, Paul. Very much appreciated!
Outsourced to Jack in the end! WYN section is now up.
Thank you, Jack. Very informative write-up on Wynnstay (LON:WYN)
It has made for a nice swing trade on two occasions for me in the last year. I have been looking to add it to my longer-term holdings, but see it as a bit of an opportunity cost investment, when it comes to my far less than unlimited funds.