Small Cap Value Report (Weds 28 Dec 2022) - POLX, ROL, ARB, DPEU

Good morning from Paul and Graham.
We will cover whatever small caps news there is this week, and if it's too quiet for news, then I'll look back at one or two interesting companies I've been meaning to report on over the previous weeks/months. So I'm sure we'll come up with something interesting each day. Plus we might get some bombshell profit warnings of course this week, for companies that fail to close those year-end deals, or otherwise don't manage to catch up with their shortfalls against budget.
Your ideas - there's hardly any news today, so Graham came up with the idea that we could invite suggestions from you (in the reader comments) for interesting companies for us to write about this week. We'll do say 4 of them (2 each), based on which get the most reader votes (hit the thumbs up button for the one you like the most), and also please give a (at least) one line pitch for why you think the share looks interesting.
Agenda
Paul's Section:
Polarean Imaging (LON:POLX) - FDA approval is announced, after a disappointment & delay in Oct 2021. I'm told this is very significant news, so the share price could be in for a big increase possibly. EDIT at 08:12 - share price up 43% to 71p, well done to holders!
Rotala (LON:ROL) - a detailed update. The key thing is a major property disposal, which wipes out most of the debt. Remaining debt is asset-backed, HP on buses. So there's now ample liquidity for more acquisitions, or maybe divis/buybacks? Looks an interesting, and undervalued special situation. Worth a look, thumbs up from me. Very small and illiquid though.
Graham's Section:
Argo Blockchain (LON:ARB) (£38m) - the Argo share price has more than doubled this morning thanks to the announcement of a new financing agreement that secures the company’s future in the short-term. It should now have plenty of liquidity to work with and will have a reduced debt load moving forwards. The downside of the agreement is that it’s no longer going to own its major facility in Texas, and will have to pay hosting fees to the new owner from now on. Furthermore, the agreement achieves only a partial deleveraging. Given that prior to this agreement the company repeatedly warned it was going to become cash flow negative in the short-term, and that the bitcoin price has not improved, I expect that the company’s financial performance will remain disappointing in the short-term. However, it does at least now enjoy the possibility that the bitcoin price might bail it out, before it starts to run out of cash again. (more detail below)
DP Eurasia NV (LON:DPEU) (£79m) (unchanged) [no section below] - this Domino’s master franchisee has released a short update in response to what it calls “market speculation”:
DP Eurasia is evaluating its presence in Russia, the impact of sanctions and its continuing ability to serve its customers in Russia… Consequently, the Company is considering various options which may include a divestment of its Russian operations. Whilst work on a potential transaction is ongoing, there can be no certainty as to the outcome.
Trading in these shares has completely dried up, so it’s hard to know what investors will make of this news, but I imagine that most of them will reluctantly accept it. As I wrote recently, this company’s debt load has looked overbearing for some time. Depending on the sale price achieved, this problem could be addressed. Furthermore, the political situation is uncomfortable with a Commons MP naming DP Eurasia in parliament this month as a UK company that continues to do business in Russia (he appears to have missed the fact that DP Eurasia is not a UK company - it is registered and has an address in the Netherlands). For me, it’s all about the price achieved for the 170-odd Russian stores. I guess it’s possible that, given the political situation, they may be worth very little at this stage. But without more info I can’t form a strong view on the investment merits of DPEU shares at their current level. But it’s good to know that the company is considering all of its options in a situation that is about as bad as investors could have reasonably envisaged a few years ago. (no section below)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Polarean Imaging (LON:POLX)
50p (pre market open) EDIT: up 43% to 71p at 08:12, on heavy volume of 2.5m shares printed so far.
Market cap £107m
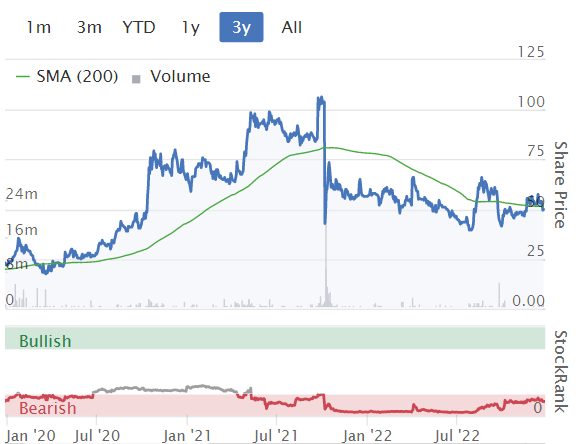
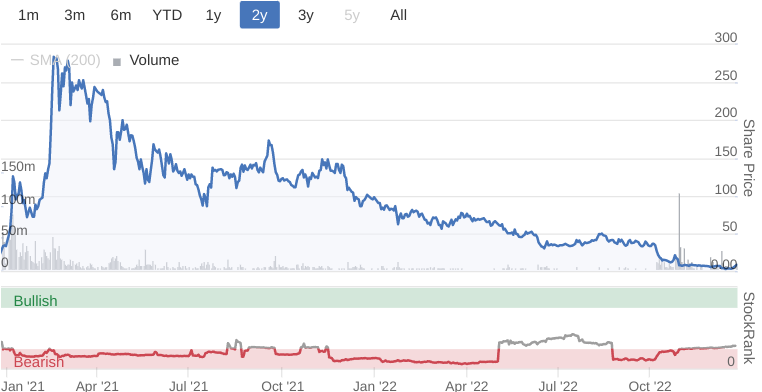
I’ve covered this share here several times before, even though it’s a blue sky project, because several shrewd investors told me it’s the real deal, and FDA approval would see the shares soar. It also has backing from credible shareholders who refinanced it a while back. Then the unexpected happened in Oct 2021 - the FDA denied approval, causing the share price to plunge 60% - as you can see on the 3-year chart below.
Although it seems investors have kept the faith that approval would eventually follow, as the share price has held up well, given that this brutal bear market for speculative small caps has almost wiped out many similar jam tomorrow type companies.
.
Today’s announcement is headed up -
FDA Approves Polarean's XENOVIEW™ (xenon Xe 129 hyperpolarized) for use with MRI for the evaluation of lung ventilation
I don’t understand the detail, so have asked my network of shrewd investors, and am told that this is very significant positive news today.
So we could see a decent-sized, positive, share price reaction today, if anyone is at their computers!
Rotala (LON:ROL)
34.5p
Market cap £17m
This bus operator listed on AIM in 2005, and its shares haven’t really gone anywhere. So I’ve not reported on it here since a brief look in 2016.
However, an interesting announcement was issued at 12:30 on 23 December, which caught my eye as seeming significant. Subscribers davidallen77, and jimrog64, have posted interesting comments below, thanks for those.
Here’s the latest announcement -
Business Developments, Trading Update & Prospects
Rotala (AIM: ROL.L), an operator of bus routes in the UK for businesses, local authorities, and the general public…
Contracts - details are provided for contracts tendering in Manchester & West Midlands. It’s won some smaller contracts, but not 2 larger contracts. The net effect is to reduce future revenues by £3.5m - not a big deal, in the context of £96.5m revenues for FY 11/2021.
ROL has “agreed in principle” to sell its Bolton depot to Manchester council (GMCA), and most of its buses there will be sold to the successful contract bidder.
Trading for FY 11/2022 is said to be “in line with its budget”. The wording is vague on this, but seems to be saying that FY 11/2022 resulted in a loss of £(1.3)m or better, similar to last year.
One-off gains from fuel hedging, and a leasehold disposal, will produce a hefty boost of £3.2m additional profit, to be reported as exceptional items.
Net debt - below £40m (meeting its target) at year end (but much lower if anticipated disposals complete post year end, more detail below)
CEO comments are upbeat, saying the company is “in a much better place for the year ahead”.
Outlook - expecting to return to pre-covid profitability.
Fuel cost has been 38% hedged for FY 11/2023 at below current market price.
“despite the increased cost of living, fluctuating fuel prices and general rise of inflation, the Board remains very confident about the future prospects of the Company.”
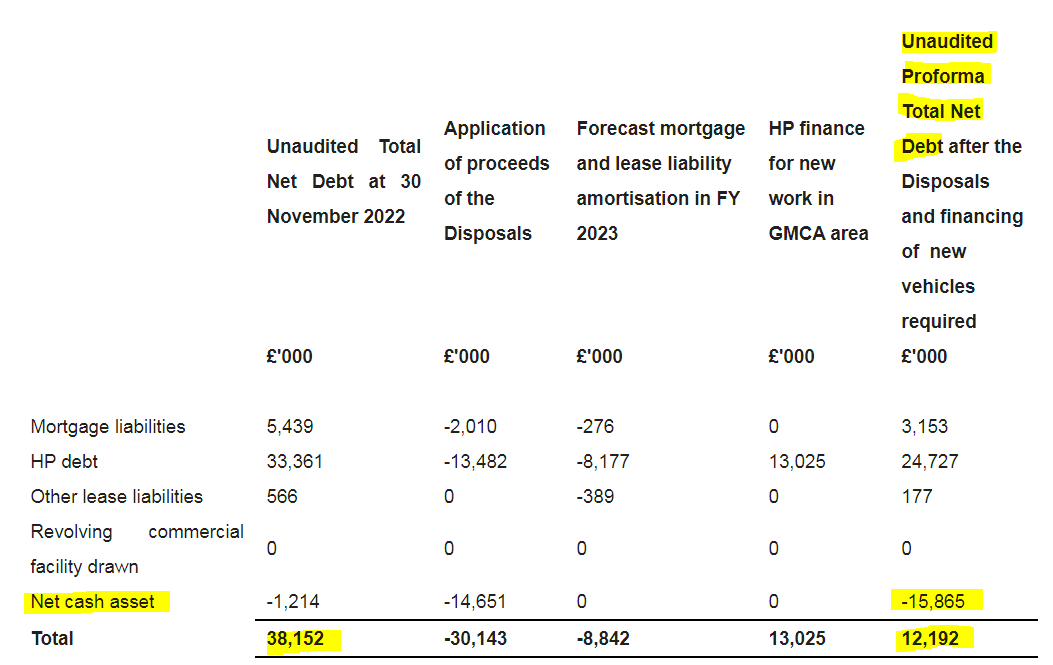
Disposals - subsequent to the 11/2022 year end, disposal of the Bolton depot & buses, will raise cash of £30.1m (very large, for a £17m mkt cap company). Of this, £8.8m will be used to pay down other debt. Then new HP finance of £13.0m will be drawn down for the purchase of new buses. Complicated, but this table below explains it well. Note that there will be a new gross cash pile of £15.9m, which looks like it will give the company flexibility - special divis/buybacks maybe? Or more acquisitions?
.
Gain on disposals - the assets being sold for £30.1m have a net book value of £22.7m, so that’s a £7.4m profit on disposal, which will strengthen the balance sheet (but presumably might also be taxable maybe?)
Passenger volumes - on buses are nationally at 85% of pre-covid. ROL’s operations are doing better, at 95%. Pensioners are reluctant to go back to pre-covid bus use, it says.
Government initiatives for the bus industry are said to be positive, but there is “continued turbulence” in the sector - seen as providing opportunities for ROL.
Takeovers - of the 2 largest companies in the sector are noted. Could ROL become a bid target too?
Bank facilities are described as “ample”, including an undrawn HSBC facility.
Main bull points -
- V high StockRank of 96
- Discount to NTAV
- Major property disposal at a substantial profit.
- Director buying - lots of smallish Director buys over several years. No big sales.
- Greatly de-geared now, and ample borrowing facilities (plus £15m gross cash)
- Strong finances now, creates opportunities.
- Sector consolidation - could be a bid target?
Possible bear points -
- Competitive contract tendering, so margins not great.
- Tightly held by top shareholders, limited liquidity - delisting risk? (note Nigel Wray holds 15.5%)
- Govt regulated sector = uncertainty of future policy?
My opinion - there’s lots of information in this update, and more detailed research & analysis of the numbers is needed.
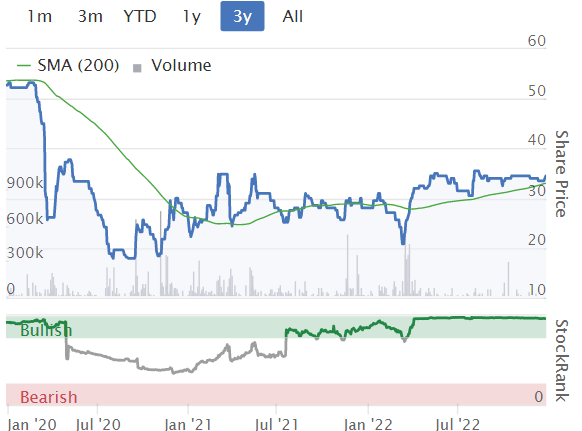
However, on a quick review from me, I think this share seems potentially interesting, and is well worth micro cap investors taking a closer look. It seems excellent value to me, especially as the share price has barely budged, despite a key announcement on 23 Dec, which should result in a much improved financial position. I think this share looks undervalued now.
Graham’s Section:
Argo Blockchain (LON:ARB)
Share price: 8p (+123%)
Market cap: £38m
The troubled bitcoin miner Argo Blockchain has released a major refinancing announcement this morning, that appears to stave off any immediate bankruptcy concerns.
Key points:
Argo sells its Texas-based facility for $65m (£54m) to an organisation called “Galaxy Digital Holdings”.
Argo maintains ownership of the mining machines at this facility, and will pay a hosting fee to Galaxy to continue to operate them.
Galaxy will also provide a new $35m (£29m) asset-backed loan to Argo, collateralised by the mining machines at the facility.
This is indeed a transformational deal. It replaces existing lenders with a new one, partially deleverages the balance sheet, and changes the fundamental position of Argo in Texas from a facility owner to a renter.
Out of the $100m received, $84m will go to pay off existing lenders (for context, total borrowings on the most recent interim balance sheet were GBP £118m, with net debt of £109m).
New mining strategy - the new owner of the facility is perhaps more sophisticated than Argo, who allowed themselves to trade at the mercy of a floating electricity price. The new owner will enter into a fixed-price power purchase agreement, and Argo will have access to electricity at the fixed price.
They will also need to have a “curtailment strategy”, which I presume means shutting down operations temporarily when there is too much demand on the power grid:
Argo will pay Galaxy a hosting fee and will collaborate on designing a curtailment strategy in order to participate in certain demand response programs offered by the Electric Reliability Council of Texas, which manages the Texas power grid.
Canadian operations
An interesting side note in today’s RNS:
Initially, Argo plans to refocus its efforts on growing and optimizing operations at its two data centers in Quebec, which are powered fully by low-cost hydroelectricity.
Argo’s CEO is, I understand, based in Canada, so perhaps he’d like the company to do something more local to him. But Argo’s existing Canadian operations have very low capacity compared to what the company is doing in Texas. Heavy investment in new machines would be needed to enable the Canadian operations to move the needle.
CEO comment
This transaction with Galaxy is a transformational one for Argo and benefits the Company in several ways. It reduces our debt by $41 million (£34 million) and provides us with a stronger balance sheet and enhanced liquidity to help ensure continued operations through the ongoing bear market. It also allows us to focus on optimizing our operations with significantly lower capex and opex requirements."
My view
The reduction in debt clearly gives the company more breathing room, and today’s share price movement reflects this relief.
The company now has enough liquidity to continue trading, and will enjoy some protection from rising electricity prices in future,
However, I’m not sure I would conclude that the company is completely safe, from a solvency perspective. Based on the comment by Peter Wall above, the debt reduction achieved is only roughly a third of the total that was outstanding as of last summer.
The new asset-backed loan has an initial term of 36 months and it will be up to Argo and Galaxy to decide what happens at the end of that period.
Also, I don’t see any mention of interest rates in today’s announcement but we can presume that Galaxy are charging healthy rates for taking on this exposure. And Argo will have to pay rent (the “hosting fee”) in Texas from now on - a fresh hurdle to short-term profitability.
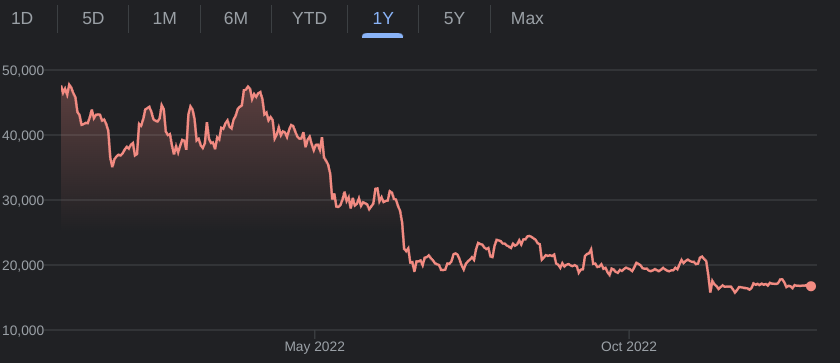
Bitcoin currently trades at $16,600, down 65% year-to-date. I suspect that the company’s financial performance will remain poor at this price:
As usual, this share, thanks to the strategy pursued by management, continues to look like a highly risky punt on bitcoin, with little equity value available for shareholders unless that price rises very significantly from its current level.
The new deal with Galaxy will see a stream of fees and interest going in the direction of their new financing partner, while Argo shareholders and management wait for the bitcoin price to bail them out one last time.
CEO Peter Wall continues to believe that what we are seeing is just a temporary “bear market” in crypto, not the permanent popping of a bubble. He may be right. Argo might get bailed out again. But at current crypto prices, I suspect that it’s only a matter of time before Argo gets into trouble again. At least they now have a chance of survival - and some time to come up with a more sustainable strategy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Hi Paul - have Equals £EQLS given you a date for the interview yet? V much looking forward !
Morning joshwood976,
No, what with Christmas and everything, I've not pursued EQLS. Will look at it fresh in January.
Regards, Paul.
Hi Josh & Scotty - FYI, I'm hoping to interview both Equals and Argentex again in January at the time of their y/e trading updates. As you may know, I own shares in both stocks
Thanks Paul! I'm not sure whether to do an audio interview with mgt, or just do a private Q&A and write up my notes from it. Will give it some thought, and obviously I don't want to duplicate what you're doing.
Rotala (LON:ROL) has long twitched my trigger finger without me committing; I've always had a pathological attraction to shares that are cheap enough that I could have brought them with my childhood pocket money! The main reason I haven't invested has been the continued uncertainty about the government prolonging Corona support arrangements for public transport providers. To the best of my limited knowledge this has still not been resolved.
It's interesting that pensioners have not returned. Our late lamented local operator Pennine Motors gave up in 2014 after years of NYCC's inadequate reimbursements for free pensioner travel, bringing to an end 75 years of distinctive (And clean) orange buses in the Dales. Reduced 'Ridership' by pensioners obviously helps sidestep this issue, although similar problems could be baked into the £2 flat fare policy for all; already in use in West Yorkshire and being rolled out elsewhere.
2023 could be good year for AIM takeovers.... Anyone suggest likely candidates? https://www.standard.co.uk/bus...
I'm not sure about AIM takeovers as most of my AIM holdings are underwater and here the Past provides lessons for the Future. So for myself especially a takeover is likely to result in a loss. Therefore Colin I can't be of help in that direction other than that you should keep an eye on the Insiders trading, you'll be playing in a casino.
Silver
Yes a takeover doesn't guarantee a profit unless paired with immaculate timing
I hold Somero Enterprises (LON:SOM) and 4imprint (LON:FOUR). Both are nice companies to own anyway but could well IMHO become takeover candidates from US money. They are AIM listed but do most of their business in the US.
Other candidates much appreciated
I don't like Somero duev to hassle with foreign dividend but a good company nevertheless
Somero Enterprises (LON:SOM) No hassle if held in a SIPP, you get all the dividend.
Somero Enterprises (LON:SOM)
Its a quick way of levelling wet concrete screed - fantastic and does a great job in tight timescales over large areas for clients that want billiard table floors as why would you not want one . Good buckets and shovels but no mission to mars. Apologies in advance.
Hello Colin,
iEnergizer (LON:IBPO)
ME International (LON:MEGP)
MS International (LON:MSI)
Just a few there!
Thank you! I have Greencore (LON:GNC) and Speedy Hire (LON:SDY)
I note a few interested in RM (LON:RM.). I owned this company for few years buying at c.150p and selling at the same approx price as it arced up and then down (I made a slither of positive return - whoop!). Fortunate to sell before its market denouement but I'd picked up a few changes that signalled problems coming.
Anyway, its in my mind to look again and was tempted when down in 20s. I held off as IMO the key risk is that both RM Education and RM Assessment businesses (high margin, latter had been high growth and 'digital' part of the business) may not be durable or good. I've become suspicious that both rely on the IT support and coding heft that has been provided by Indian staff and that product and sales have been generated more from brute force bidding and promising than real durable tangible product configuration that they have packaged and re-sellable. I liked the old CEO...but I have come to realise he was a tinkerer and control freak who had worked his way up the ranks at the company. He could deal with the complexity iteratively...but he didn't really have a vision. My perspective might be unfair...I'm an outsider so always guessing etc.
At the current price the company is cheap for its RM Resources business which is basically a school supplies business. But is currently has an over budget and time warehouse and systems consolidation project which has caused the debt build up and the need to raise cash thro sales of other bits of the business. So when I say its cheap I mean once the consolidation project is complete and assuming the biz isn't left with burdensome debt (...what they're tinkering away at right now to chip down...probably successfully assuming they haven't run into more probs on the project!)
Is there signal in the sale of pieces of RM Education and Assessment to fund dull old RM Resources transition? I'm suspicious that Education and Assessment are not durable business units and that we will see a downsizing, sell off and closing of more of this area. I fear that the opportunity to sell the businesses will be limited due to the nature of their Indian brute force requirements. And with Indian software labour relatively less cheap for a variety of reasons it makes less sense to have these units.
I took a position in RM at a time when I would say I was more biased to value and special sits sort of investments (partly personal bias and partly as everyone was obsessed with 'forever growth' or 'blue sky growth' stocks and willing to pay whatever for them) and it was pre the acquisition of Consortium and ill-fated integration into their Resources biz. I'm still keen on a bit of special sits if I can see it but less inclined to value as a reason and want more durable revenue/profit over long time than a price-asset-value garbitrage. IMO RM may be a good special sits again. I can't work it out without doing some work. There's a danger that the wind down of Education and Assessment divisions is not terribly cash fruitful as costs of close down and serving out or selling existing contracts proves onerous.
NOTE: The above has a lot of speculation in it that may prove very erroneous!
Today's RM (LON:RM.) announcement is pretty interesting - it goes to show that "intangible assets" do have value!
Edit: just realised that they haven't even registered it as an intangible asset! It's been off balance sheet this whole time...
I estimate that their remaining IP addresses are worth about the same, $10m, as the tranche they sold today. However, they might not be able to sell this, as those IP addresses look like they are needed for that division as part of the services offered to customers.
This sale definitely does alleviate some of the huge debt pile. But they still have quite a bit left, even with the $10m sale. And at the moment, I predict that they're still burning cash, as they need to finish their IT transformation, which will keep cash burning for another half year or two at the minimum.
With school budgets also being squeezed in real terms, I can't quite see how they will find growth opportunities. But am also watching with interest, given the eclectic mix of new shareholders here.
This is £RM’s second asset sale, the first being “RM Integris and RM Finance Business and related assets of its principal trading subsidiary, RM Education Limited” for $19.3m in late November
The 2 combined are worth $26.2m, which will chip away at the £61.6m debt but certainly not remove it
It’s a high risk recovery play imo so let’s see
Good afternoon everyone. Hope the holidays were enjoyed. I assume the Alka Seltzer stock price may take a slight positive point or two rise from all the sales! I have a question if I may... I find myself wondering if one of you fine folk may be able to assist me in deciphering this RNS from all the RNS speaky terms within. Basically... can someone layman-ise it for me please, I dont understand any of it LOL! (Evraz (LON:EVR)) https://www.stockopedia.com/sh...
It seems to be cobcerning a bond. They have to go through hoops to pay the coupons, and I imdgine this annoucement is about how thwy have achieved this. Suggest you look at or join the Evraz group on Telegram if you you want further comment.
Thank you.
@ Rotala: I notice that it has a presence in all 3 bubble charts and have bought a little. Love the hedging on fuel. Price of fuel, hopefully will come down in the near future and certainly over 18months. I wonder what the effect of £2 bus fares will have over the next 3/4 months and also, as higher wages are coming in, how this will impact on maintenance and parts costs.
A suggestion for topics to cover . Do we have anyone on the list here that was a professional trader in the seventies and can share strategy/ tactics from a period of managing high inflation. I'm in my early sixties and so was a teenager in the mid seventies so not much relevant memory from me I'm afraid.
Bet you saw some great bands though…!
International Options (which I hold):
- Like Tracsis (LON:TRCS) in that they provide products for use within the public transportation sector, but they have a much greater international presence.
- Have grown revenues every year since 2007, high gross margins (c80%) and increasing SAAS billing revenues.
- Their Investor Relations page is in English.
- An Electronic Manufacturing Service company based in Norway.
- I usually avoid investing in manufacturing companies, but this one has done well for me and I hope/believe it will continue to do so.
- Debt is high after a recent acquisition, but the company is working at full occupancy, so forecasts for 2023 are probably too conservative - the CEO indicated as much at their recent Capital Markets Day.
- They operate in key sectors - some growing (electrification, connectivity), some defensive (defence/aerospace, medical devices.)
- Cash generation looks excellent vs the current EV....even for a manufacturing company.
- Their Investor Relations page is in English.
"MarineMax, Inc. is a recreational boat and yacht retailer in the United States.
The Company is engaged in the retail sale, brokerage, and service of new and used boats, motors, trailers, marine parts, and accessories and offers slip and storage accommodations in certain locations.
It also arranges related boat financing, insurance, and extended service contracts. It also offers the charter of power yachts in the British Virgin Islands."
- Material asset-backing, including a large land holding.
The company has implied that this is materially undervalued.
I have estimated that at least half the current market cap ($649m) is asset-backed.
- Average selling price of their boats is $265k. One would assume that there would therefore be a limited impact on their customer base in any downturn.
For context the average boat selling price from a listed competitor OneWater Marine (NMQ:ONEW) is $160k.
- They are increasingly diversifying. Their recent major purchase (IGY Marinas) own Katherine Docks (in central London). Their marina business brings a highly recurring (and hopefully recession proof) income stream.
- One of 2 dominant players that I know of for music streaming services (the other being Apple).
- I don't use any Apple devices.
- I can't imagine ever cancelling my own subscription as I use the service daily for both music and podcasts.
- Revenues have grown from 1b EUR in 2014 to an estimated 12b EUR this year.
- Monthly Average Premium (paying) Users have grown from 52m at the start of FY17 to 195m users now.
- Non-paying user numbers have also continued to grow (currently 273m.)
- The +21% revenue growth in the latest reporting period was +1% price driven and 20% volume driven, i.e. not all growth is coming from price increases.
- Recent expansion of services into Audiobooks, with long term plans to diversify further.
- The current Average Revenue Per User (ARPU) is 4.63EUR per month.
At the Capital Markets Day the company outlined plans to get this to 18EUR by 2030.
I am personally doubtful of this target, and instead pencil in something closer to 7EUR by 2030.
In both scenarios the company looks highly undervalued at today's price.
- Cash generative, with growth funded from own resources
Spotify Technology SA (NYQ:SPOT) , has quite a bit of competition from Amazon, Tidal and Deezer, all of which have cut their subscription prices in the last year or so. I don't use Spotify because I can get better sound quality for less price or similar to Spotify. Im using Deezer at the moment, only £5.99 pm for cd quality streaming. Qobuz is another I have used, that is around £11pm but has High Res. files. Tidal also is only £10 for cd and HR.
Spotify said they would do cd streaming last year but it has never happened probably because they have been undercut by Amazon.
Spotify Technology SA (NYQ:SPOT)
Hi Rusty2
Thanks for the response.
Interesting thoughts on sound quality. Honestly, I'm not sure I would be able to tell the difference between Deezer/Qobuz vs what I currently have (Spotify).
I imagine that most are satisfied with the current quality they receive, whichever platform they use.
On the competition (other than Apple):
This is far below the 465m Spotify subscribers (of which c200m are paid customers.)
I have an old note saying that the Amazon Music userbase was half the size of Spotify's a couple of years ago, so these numbers still tie up.
I know that Amazon bundle Music with their Prime service, but this of course is only available in a handful of countries.
There is a music-only paid service in many countries, but a free streaming service is not offered everywhere.
I wonder why they don't offer this? Surely it restricts their growth?
https://en.wikipedia.org/wiki/...
For context it seems like Spotify offer their platform in nearly every country: https://en.wikipedia.org/wiki/...
I have put my entire Spotify (NYQ:SPOT) on the free prime music app. (It was greatly improved last month).
I never paid for Spotify and the ads never bothered me. But getting my music, and favourite podcasts on the same place makes my life easier.
Something to consider.
Hi Trevor
Sorry, I don't think I understand your point.
Spotify has a lot of music and a lot of podcasts, so why not stay?
A
I have put my entire Spotify (NYQ:SPOT) on the free prime music app. (It was greatly improved last month).
I never paid for Spotify and the ads never bothered me. But getting my music, and favourite podcasts on the same place makes my life easier.
Something to consider.
Well, the service may be free to the user, but Spotify and Amazon still have to pay the rights holder of the song. I always found the Amazon Music service poor and haven't looked at it for 4 or 5 years, so thanks for the heads up. I'll take a look.
All the best, Si
Yes Deezer are quite small about 9m paying subscribers. I've got a Spotify account but I don't use it, there must be millions like me. Other streamers are expanding as well, if Spotify is in most countries already then they may struggle to grow?
Amazon free is a waste of time, you get it with Prime, but it's only a small catalogue at low mp3. Amazon is mostly in the US, about 2/3 of revenue, many countries don't know Amazon.
The biggest music markets are USA, Japan, UK and Germany. Deezer have free but has adverts although you can block them on some devices. Tidal had a major revamp, introduced free and lower cost cd level, used to be £20, now is £10 for cd. Deezer and Tidal free, has the same music almost as the paid service but lower quality. Tidal is ok I have used it.
It is true many users are not bothered about sound quality.
One concern is if they do start making decent money there will be pressure from the record companies and maybe authorities to pay more to the artists, who generally get very little.
It is an interesting company but not one I invest in.
- One of 2 dominant players that I know of for music streaming services (the other being Apple).
- I don't use any Apple devices.
- I can't imagine ever cancelling my own subscription as I use the service daily for both music and podcasts.
- Revenues have grown from 1b EUR in 2014 to an estimated 12b EUR this year.
- Monthly Average Premium (paying) Users have grown from 52m at the start of FY17 to 195m users now.
- Non-paying user numbers have also continued to grow (currently 273m.)
- The +21% revenue growth in the latest reporting period was +1% price driven and 20% volume driven, i.e. not all growth is coming from price increases.
- Recent expansion of services into Audiobooks, with long term plans to diversify further.
- The current Average Revenue Per User (ARPU) is 4.63EUR per month.
At the Capital Markets Day the company outlined plans to get this to 18EUR by 2030.
I am personally doubtful of this target, and instead pencil in something closer to 7EUR by 2030.
In both scenarios the company looks highly undervalued at today's price.
- Cash generative, with growth funded from own resources
I don't understand on what basis Spotify is undervalued? Analyst forecasts show no profits until FY25 at the earliest. The Gross Margin is a crappy 25% and it is needing to diversify to distract people from the fact the current business model is barely viable. Looking at it as a business, all I see is a company that got grossly overvalued and has now, rightly, come down to earth. If you want to invest in the growth of music streaming revenues, then Hipgnosis Songs Fund (LON:SONG) seems a far better bet IMHO, especially now it has refinanced its debt.
All the best, Si
Spotify Technology SA (NYQ:SPOT)
Hi Si
Sorry, perhaps I should have used different wording. It's very expensive and I fully acknowledge that.
But I also believe in the long term story (for now).
On your other points:
a) the Premium (paying) service (which has risen from 14.3% 5 years ago to 28.0% today), and;
b) the free service, which bares all the costs of podcast content creation. The gross margin % has fluctuated between 0% and 10% in recent years, but the company has long communicated that this would be weak in 2022 (which it was) and expect there to be uptick from 2023.
I would hope that the gross margin therefore increases over the next few years, but in any case, when the revenue is so highly recurring in nature, I'm okay with it generally being stable, which it has been for the last few years.
I don't know why this would change given that majority of the Costs of Sale are royalty fees and where Spotify are the biggest player (outside of China.)
This seems a reasonable assumption as growth continues and is only slightly lower than what they spend at the moment.
There should be upside from reducing G&A %, but other than that, I'm not holding my breath for any serious operating leverage.
It took a little work, but the underlying figures show that whilst there's still user growth everywhere, it's really picking up in the ROW segment, for both paying and free users.
The company has implied several times, across different calls, that things were going well in LATAM and India. Especially with the latter, I can see this more clearly now.
So for me, there's still plenty of user growth to go for. I don't really see Apple as a key competitor in a country like India and Amazon don't offer a free service there (see my earlier post.) First mover advantage seems key.
Audiobooks seem like a natural vertical to target next.
The company has also started developing events and merchandise directly on their app. I'm particularly a fan of the former as I 'follow' new artists as I discover them and would be interested to know if they were in my area.
As mentioned before I think their 2030 ARPU ambitions are...bonkers, but even assuming they get to 7EUR, then I don't really understand why they wouldn't be significantly more profitable given my GM/R&D/S&M assumptions above.
There's more detail here if you're interested (and my apologies, their ARPU target is apparently 100EUR, not the 18EUR I thought it was!)
shorturl.at/djS05
-----
I've looked at Hipgnosis Songs Fund (LON:SONG) briefly in the past, but honestly came away confused by the never-ending share/debt issuance. Perhaps I need to take a look again.
Cheers
A
Finally, they're growing and not burning cash. This is a big plus for me.
Yes, I agree it's not going bust anytime soon and is just about generating FCF, but right now there are so many strong profitable companies going cheap on a longer term view that I don't see any reason to buy into a company predicted to make no post tax profit for 3 years.
I've looked at Hipgnosis Songs Fund (LON:SONG) briefly in the past, but honestly came away confused by the never-ending share/debt issuance. Perhaps I need to take a look again.
Well, it's a bit of an oddity; essentially an income investment that uses debt and equity financing to buy assets (in this case song catalogues). I like the total ambivalence as to the platform on which the songs are streamed i.e. Amazon, YouTube, TikTok, Apple, Spotify or Deezer; all generate revenue so you're really only playing the growth in music streaming, wherever that comes from.
Even if you disregard the last calculated NAV of 150p (06/12/22) the current price of 86.6p leaves a decent margin of safety. And while you wait you receive a 6% dividend yield. They have a tie up with Blackstone who hold ~4% and I'd be surprised if they or one of the larger song management companies didn't buy the company next year if the large discount to NAV persists.
All the best, Si
I am also a bull on music publishing and apart from Hipgnosis there is One Media but my preferred way of playing the theme is Warner Bros.Universal are another alternative.
Spotify Technology SA (NYQ:SPOT)
Hello again Si
"there are so many strong profitable companies going cheap on a longer term view"
I sort of agree and I sort of don't.
For example, I look at the 2022 decline of semiconductor and cybersecurity companies (eg ASML Holding NV (AMS:ASML) and Crowdstrike Holdings (NSQ:CRWD) respectively) and whilst many say that growth will return, I'm frazzled by the complexities of these industries.
I have no idea which companies have the greatest competitive strengths, or which future technologies might displace them. It's hard for me to evaluate if they are indeed "cheap" right now.
Something more basic, like the audio market, is a far simpler industry for me to understand. And I'm a regular customer too.
I don't usually like looking more than 2-3 years out as there are always too many unknowns.
But I don't mind making exceptions. And when I put the numbers together I see a relatively safe, understandable, cash-generative, long-term hold.
If my (hopefully conservative) estimates are correct then the share price CAGR from here could be >20% to 2030.
Let's see.
Hipgnosis Songs Fund (LON:SONG)
Thank you for sending this my way.
It's certainly an interesting company.
I've had a flick through the interims (Sept 2022) and noted the following:
Presumably this will go up, especially following the CRB ruling this year.
Interest costs per annum will therefore = $35m
Cash generation (post-interest costs) looks to be c$25m pa
- Cash generation (pre-interest costs) looks to be c$66m pa
- Cash generation (post-interest costs) looks to be c$31m pa
----
I think the company will struggle to reduce debt and pay a dividend without doing a fundraise in the near future.
---
I must admit to being confused by the valuation.
The EV is currently $1.8b & annual (unlevered) cash generation is $66m...so a yield of 3.7%.
If cash generation increased to say $100m (which I think would be some way in the future, even with the CRB ruling) then that gives me a yield of 5.5%.
---
I'd certainly be interested to have more granular detail of revenue generation from older songs to understand the risks of an ageing catalogue. I'm sure people still listen to 50 cent, but presumably he'll earn much less for the fund in 10 years time?
---
I was just wondering whether there might be other avenues for growth and then saw the outlook statement, which stated that "the Company expects to benefit from increasing revenues from social media, gaming and lifestyle channels."
---
I'm still hesitant here and it will be interesting to see how the story develops.
RE: Hipgnosis Songs Fund (LON:SONG)
There was an interesting article on Hipgnosis in the FT back in September: https://www.ft.com/content/66b...
That's probably behind a paywall for most.
The gist of the article is that they've run out of money to buy new songs and are annoying artists who were expecting to sell but can't. There's also now a complicated holding structure involving Blackstone (see below). Mark Mecuriadis, the CEO of HSF, sold HSM to Blackstone while retaining a stake, and Blackstone's money has now funded the purchase of a portfolio of songs (Leonard Cohen, Nile Rodgers, etc) held by HSC outside of the quoted fund.
The dividend is discussed in the article - to be honest I'm not sure I fully understand what the article is saying but it's something like:
The article ends by discussing whether the NAV calculation is valid - the discount rate used to calculate the portfolio value has not changed in the last year, despite the rise in interest rates.
In summary - the dividend seems to be at some risk and if it is cut then the share price will suffer. Blackstone are the most likely beneficiaries.
I think it's fair to say: it's complicated.
timarr
Welcome back Chaps.
A small cap suggestion. LON:BYOT. They recently published their results which did not overwhelm, but I listened to the investor update which sounded promising. Rationalised their product line, competitors exiting the market due to increased regulation and some positive noises about licensing deals.
2 suggestions, though both out of the small cap range:
The current market cap is £5.5b, so expensive.
I like it for many reasons, including:
- Currency transfer volumes continue to rise fast (+50% YOY at the interim reporting period vs 44% at the same time last year)
- Customer numbers are still growing fast (+41% YOY at the interim reporting period vs +22% at the same time last year.)
- Customer cash balance should come in at c£12b-£13b at year end (March 2023) vs just £830m in FY19 - this highlights their growing customer base (and that customer base using their services.)
- There are a lot of small players out there. I've only done work on some of the big ones, namely
- Western Union (terrible system),
- Skrill (much more expensive than Wise),
- Remitly Global (NSQ:RELY) (material cash burn due to marketing spend),
- Atlantic Money (cheaper than Wise, but I can't see how the business would ever be profitable, even if they matched Wise's current # of transfers.)
- Wise have a small marketing budget as growth has primarily come from word of mouth.
- Increasing gross margins as they become more efficient at transferring money around the world.
- I personally use Wise several times/year and am a big fan.
- I believe there will be a step change in profitability from the next FY driven by much higher interest income.
For context the company has actually been losing money in recent years on cash balances in the Eurozone due to negative interest rates.
- Current market cap = £1.4b
- Pet food sales continue to support the underlying business, with YOY revenues up 15% at the interim period.
- Subscription Plans continue to rise, now at 1.6m plans, up from 0.7m at the end of FY19. Annual Recurring revenue from these plans is now £135m vs FY21 total revenue of £1.1b.
- Highly profitable and expanding vet business.
- Material capex spend this year on a distribution centre - all funded through cash generation. Next year I would hope Free Cash Flow of at least £100m and for this to keep rising as the Vet business grows.
Really good suggestions!
Ecora Resources (LON:ECOR)
Royalty company transitioning to 'green' metals using the final tail-off of its metallurgical coal investment which is producing record revenue. The royalty model is quite interesting in these inflationary times.
Two years ago it bought a cobalt stream and recently bought a basket of development royalties from South32 (LON:S32) who became a significant shareholder.
Phil
Smiths News (LON:SNWS) - up 2.95%. Deutsche Wertpapieirtreuhand and some subsidiary bought 48m stake.
Where did you source the information regarding the acquisition of 48m (£ or shares) in Smiths News (LON:SNWS)
Sorry it was last December. Apologies. Saw it breaking up so was looking for a reason.
Interesting, thanks GarryC,
I like Smiths News (LON:SNWS) and have been writing positive things about it here for quite a long time, since the turnaround gained traction. It's played out exactly as management said it would - not something you can say about many attempted turnarounds!
Shares in SNWS have bounced strongly since the 20 Sep 2022 low of 27.5p, up to 47.8p yesterday, but it still looks cheap on fundamentals: fwd PER of 4.7, fwd divi yield of 8.7%, and balance sheet is OK-ish - with debt greatly reduced, and pension scheme jettisoned completely.
Downside risks surround the slowly shrinking business - mgt have said before that they can't keep shutting depots, and are close to the minimum number needed for the necessary geographic coverage. So it could prove more difficult to maintain margins in the future.
Upside potential is if they can come up with some new, and sustainable utilisation for their rapid overnight distribution network, other than just newspapers/magazines, which are in gradual decline.
So the share remains interesting, I would definitely hold them for the divis, if I owned any.
Regards, Paul.
INL-Inland Homes. Been a dog. Construction and debt problems but quality land trading business. New CEO earlier this month. Construction background. Looking cheap.
Looks very undervalued. Way below its net asset value and a good takeover prospect
Why not have a look at Tesla (NSQ:TSLA)? About as off piste as possible for this board, but recent price collapse has p/e of 20 whilst revenue growing at 50%. Would love to see how a UK small cap investor looks at a situation like this!
I missed Tesla (NSQ:TSLA) when it was $25 billion mc as I thought it was overvalued and didn't really understand all the different parts of the business. I have been gradually buying it over the last Month. The problem at the moment is Musk thinks it's a great idea to take on main stream media via twitter, not good for short tem Tesla news flow. These are shares I intent to hold into retirement in 15 years.
Everyone has always said Musk with fail and they have never been correct. MSM is generally looking for any bearish news they can throw out there at the moment
I too missed the Tesla (NSQ:TSLA) boat for the same reasons but started to buy in 7 weeks ago.
I now cost pound average and buy in once a month over a 10 month period, unless the price drops 10% from my last purchase price, I've hit the button 5 times in 7 weeks and expect to buy again before the year is out.
With
Is it still a bubble or now good value? How much is the drop due to twitter storm Elon loves to create, as he is not going to sell for the next 2 years, has Tesla (NSQ:TSLA) been over punished?
I would be interested in views of Integrated Diagnostics Holdings (LON:IDHC). Some substantial changes to figures in the last 12 months as a result of Covid bonus unwinding, but still a growing company, with a 28% operating margin, decent dividend yield and continual Director buys from the CEx who owns nearly 27% of the business.
Would be interested on comments on Somero Enterprises (LON:SOM). It has been commented on favourably in the past, so maybe there is not too much to add. It is a large part of my portfolio and I am still planning to hold it long term. However, it is proving a very frustrating share to hold, as despite consistent solid numbers, it seems to generate limited support. I imagine it is a fear of US recession, especially in the building sector which is holding it back. The lack of director purchases at these lower prices has been a concern. A trading update is due late in Jan, so hopefully it that is positive it will get a lift. Also, wonder why a US based cash generative business, who do not seem to need to raise capital, would stay listed on AIM.
Also, would be interested on any thoughts on Games Workshop (LON:GAW. Not a small cap, but I think a number of people here may be interested. An interesting deal recently with Amazon with regards to Warhammer.
Thanks
Games Workshop (LON:GAW) - £2.8bn mkt cap lol. Expansion into Asia via Nexon huge growth potential (manga/samurai look to the things) as well as Amazon, Marvel and Frontier Developments. Amazon already sell the gaming sets and models etc. Not been able to interest grandkids in models, airfix, lego or painting small objects - it's all online for them unfortunately. Watching Roblox (NYQ:RBLX) in that regard.
Nice the link works with US shares, well done Stocko.
A chat on the video gamers etc would be of interest. Favourite is Keywords Studios (LON:KWS) more nuts and bolts so not reliant on content. The space is tied up now with F1, Star Wars, LOTR, football etc all pretty much taken, so perhaps GAW has a niche.
Somero Enterprises (LON:SOM)
Hi OzzieTom
I sold out of Somero a few months ago on fears of the cement shortage dampening revenues - it was the main negative I picked up from the last earnings call.
Here's a sample article on the situation from a few months ago.
https://www.constructionequipm...
If volumes had held up I would have been more likely to keep holding, but sadly these started to slow down and I remain wary of the company's ability, or perhaps desire, to keep raising their prices.
I would love it if you could look again at Surface Transforms (LON:SCE. Their order book is piling up and they have only one other competitor with a comparable product in the US. SCE are taking orders away from the competitor. If production facilities come online in Q2 2023, then this could become a long term compounder in my view.
Brakes get very hot when over worked. Less an issue with 'normal' driving i.e. not racing conditions. EV's don't have engine braking or maybe with electronic gizmo control. So brakes work hard. The brakes in EV's also charge the battery so the bit of kit is doing lots of critical stuff. Carbon specialist materials probably essential for other than race cars.
Have no idea about moat or competitors. Open for more tech discussion other than youtube lol.
Sorry GarryC, you are wrong about EV braking. The motor will act as a generator when going faster than desired ie down hill or normal slowing down and this returns energy to the battery. Ask a wheelchair user. If driven properly no extra braking performance should be required. Mind you a lot of EV drivers drive like wallys.
Fonix Mobile (LON:FNX)
Would appreciate Paul or Graham's thoughts on this company. Floated in October 2020, they provide a platform for payments by text, phone etc. Interestingly they claim to never have lost a customer and never had a platform outage and have some well known names as customers, BBC Children in Need etc. Looks like they are net cash but this may be because they are holding customer payments ?
There seems to be a lot of competition in the sector although Fonix Mobile (LON:FNX) do seem to have found a niche within it.
They pay a dividend of around 3.25% and the share price has been very strong lately on no firm news although a recent AGM trading statement was positive without any specifics.
I really like Polarean Imaging (LON:POLX) and have been in for a while. The words 'game changer' get thrown around a lot but their technology is game changing for lung scanning. It's like going from black and white TV to colour. Great management team who know what they are doing. It's worth more research for sure.
Jubilee Metals interest me. One should never buy "on a goid story" but the plan to recover metals looks good and has some serious institutional investment.
Journeo (LON:JNEO) . You threatened a glance at this before Xmas . Big recent deal at a good price builds scale and sorts the balance sheet . Good space low valuation
Hi How about BT (LON:BT.A) bt . Not a small cap but it's reaching it's low at 100p a share where it's climbed to 200p a share twice in the last year . Its as a big moat with openreach . Its only going to grow sales with more using it's infrastructure. Virgin media biggest rivals . Just to get your views on one of uks leading companys maybe ?
And similarly Vodafone (LON:VOD) I have never held but wondering I I should - div yield 9%!
I was, until earlier this year, working at Vodafone. I do keep track of the Vodafone (LON:VOD) share price, and it is at almost record lows at the moment, but I still am not remotely considering buying the shares.
If you haven't yet, I would have a look at their debt pile, structure, interest rates, and refinancing profile required over the next few years.
And then have a look, in their core markets (Germany, UK, Spain, Italy) - have a look at the trends in mobile and broadband pricing, whether they're increasing or decreasing in this inflationary environment.
It has taken BT/Openreach just over a month to fix my phone and internet connection. They are institutionally incompetent. Four engineer visits plus two no shows. Inumerable telephone calls and many hours wasted. And they have form: almost exactly the same story seven or eight years ago. They must waste huge sums being so incompetent.
Yes had similar experience, at first a job to convince them there was a problem, then they were telling a few weeks later there was a problem with my internet. Sent some bloke, not BT, who tested my router and cables, nothing wrong. Then had a load of trouble getting them to do anything. Then they said there was a problem and sent an engineer, did not find anything, still no better, sent another one. Thought it maybe the router, order another one, no difference. Then they tried to send 2 engineers, one was just leaving when another phoned to say he was on his way. Anyway after about 5 engineers, it did improve a bit but still not as good it used to be. It like a nationalised industry still despite reducing the staff numbers considerably.
The problem is the old wiring but they don't want dig the road up to replace it all. At least the router is not going off all the time now. No fibre around here.
BT (LON:BT.A) I'm interested for the exact opposite reason having sold out last month. BT has an awful lot of legacy customers; like my Mum, who've been subscribers since the days of Trimphones and cottage loaf shaped Commer "Telecom" vans. These people pay a lot for service that isn't any better than any other provider and are typically unwilling to change provider unless something big happens. BT have a 2025 timetable for moving to a telephone over broadband service which will mean an awful lot of customers will find themselves on new tariffs and may start asking what they are really getting for their money. I see this as a step change.
Openreach's decision to provide infrastructure for any operator that wants it might maintain their share of the poles n'wires sector at the expense of BTs domestic customer base, as rivals will be able to advertise as being supported by Openreach but cheaper than BT...
On our bedtime dog walks I've recently noticed the encroachment of mysterious brown wall boxes onto many houses nearby, these have Virgin moulded into them. Virgin has their own dedicated network and they are clearly making headway, which bodes I'll for the Openreach moat.
They own the international cricket broadcasting rights for matches down under which really annoys me! "Sky sports cricket" doesn't give me all the cricket I want!
Contrarian investment manager Kernow Asset Management have taken a 3.02% holding in £SAGA.
Share price is up over 50% since the lows.
https://www.investegate.co.uk/...
Good morning could you look Rotala (LON:ROL) put out big update at 1230 before Xmas trading in line for this year, selling Bolton station for more than nav, winning smaller contacts but revenue forecast to be lower. A long read lots in statement no mention of dividend but debt below 40million thanks
Good morning davidallen77,
Good idea - I also spotted what looked like a very significant announcement from Rotala (LON:ROL) just before Christmas, so I'll look at that next.
Regards, Paul.
Thanks. This has been on my radar for a while. Persistently high stock rank, director buys and smart acquisitions during the year. They have got back to 95 per cent of pre pandemic business, and are reducing debt significantly. Look forward to your much more informed analysis.
Cheers Paul Rotala (LON:ROL) so illiquid owners getting senior now they must have a sell out plan?
Staffline recruitment? Been featured a few times before, but interesting year ahead for recruitment in general, and good to hear your views??
RM (LON:RM.) RNS today re $10 million sale of IP addresses. Potential turnaround stock. Major supplier to the UK educational establishment. Harwood Capital in the process of building a stake.
That looks a cracking deal, 10 million usd cash for assets not even on the asset register .
And only a fraction of their IP adresses
Now I understand why Rockwood are building .
Looks like selling off sone of the jewellery to pay down doubt looks a very good strategy .
My main concern is that they have recently taken on a joint broker which often seems to be a precursor to a placing and equity dilution.
RM (LON:RM.)
I don't understand why an IP address has any value. Would appreciate being enlightened by someone more knowledgeable.
Snazzy
A website is basically an IP address, the owner have to pay someone for the lease of the IP address, therefore I assume that's where the revenue is,. and IP4 addresses are in short supply, this the move to IP6 which has yet to take off
Not a small cap but a quality company which seems to be neglected at the moment - Gamma Communications (LON:GAMA) . You last looked at it briefly in Sept 2019 when the price was where it is now. Since then the company has nearly doubled PAT and added £200m of revenues. Obviously, a lot has happened since then in the markets! You concluded that it was expensive then and, obviously, multiples have contracted since 2019. The balance sheet is string with increasing net cash and over £100m of net tangible assets. It also doesn't have any pension liabilities.
It feels like a quality hold to me but would be very interested to hear your views. I guess that its prospects depend to a large extent on the future for the telecoms market on which I have no string views but it does seem to have sailed through recent turbulence without sustaining any damage and all of the price action seems to have come from the wider market.
I’d be keen on this one too. Been buying recently back in after selling towards £20 now the valuation multiples have contracted, good quality score and net cash. Great to hear your thoughts on Gamma Communications (LON:GAMA)
OK, I appreciate its a long shot request, but on the chance
How about Sylvania Platinum (LON:SLP) for the following reasons
However, if it fails to make the break, hope you both has a good Christmas and have a cracking New Year.
Now lets get voting.
Cooling on South Africa - you need to mine stuff, keep it (i.e. not stolen), pay the extortion (tax) and transport it to market through a nationalised (dysfunctional) railway and get it onto ships through a strike ridden port of Durban.
I'm heading to North America, copper and the big miners.
re Sylvania Platinum (LON:SLP)
True enough ... South Africa is a difficult operating environment ... but that's already priced-in, surely. I think SLP is an excellent holding within a well-diversified mining/resource stock portfolio.
My morning smallcap tweet: They've made them an offer they can't refuse
Argo Blockchain (LON:ARB) RM (LON:RM.) Polarean Imaging (LON:POLX) GSTechnologies (LON:GST) £FSI DP Eurasia NV (LON:DPEU) Applied Graphene Materials (LON:AGM) Mirada (LON:MIRA)
◄Argo Blockchain (ARB)► avoids imminent cash crunch by selling Helios mining facility to Galaxy for $65m and taking $35m loan with Galaxy. Cuts debt by $41m. Argo will maintain ownership of all mining machines, and Galaxy will host Argo's fleet of Bitmain S19J Pros at Helios. [SP=3.6 Cap=23m]
◄RM (RM.)► agrees sale of some IP address for $10.2m. [SP=51.5 Cap=43m]
◄Polarean Imaging (POLX)► FDA Approves Polarean's XENOVIEW (xenon Xe 129 hyperpolarized) for use with MRI for the evaluation of lung ventilation. XENOVIEW has not been evaluated for use with lung perfusion imaging. [SP=49 Cap=107m]
◄GSTechnologies (GST)► takes $1.6m convertible loan. Looks like a death spiral loan. [SP=0.95 Cap=14m]
◄James Fisher (FSI)► sells its Subtech Swordfish Dive Support Vessel for $24m. [SP=NA Cap=NA]
◄DP Eurasia (DPEU)► re speculation regarding an exit by the Group from its Russian operations. Co considering various options which may include divestment of its Russian operations. [SP=52.2 Cap=79m]
◄Applied Graphene Materials (AGM)► re formal sale process: non-binding indicative proposals have now been received for the its trade and assets or the shares in the main operating subsidiary. Cash crunch at end Jan as stated. [SP=5 Cap=3m]
[edit] ◄Mirada (MIRA)► H1-Sept rev down 12% "due to the investment in product to be deployed during H2, which will have a higher level of professional services and associated turnover". Don't understand how investment reduces rev.! Pretax loss $1m ($1.2m). Outlook " increased level of activity among new potential customers...confident that this level of activity will result in new announcements over the next few months".