Small Cap Value Report (Weds 28 Sept 2022) - CARD, REDD, FIF, PRES, BOO, GLAN, CML, K3C

Good morning from Paul & Graham! Today's report is now finished.
It was great to hear all your feedback, in yesterday's unusually busy comments section. We read, and take on board, all points of view, and it's good to see there are still plenty of investors out there still interested in small caps.
I've been through a few bear markets over the last 25 years, so I know that things can get a little fraught in the bad times. I bet the vast majority of us wished we'd done a lot of things differently over the past year. That's life isn't it, we just have to learn from our mistakes, and then gradually forget those learnings in the next bull market, which is my speciality!
We cover about 500 companies here, from numerous sectors, so there's something for everyone, and you can hopefully use our reviews to do more thorough research of your own. That's the idea! In normal markets, we spot loads of good stock ideas, and we warn people away from lots of dodgy things too. But ultimately, the buy & sell decisions are entirely yours.
In a bear market like now, most small caps have done badly. That's often when the best buying opportunities emerge for the next bull market, in my experience (e.g. I had multibaggers galore in 2003). So we'll try to sharpen our focus, but essentially the show goes on, and we'll do our best. You'll continue to be able to pick ideas, and details from our reports, to add to your own research process. Agree or disagree with us, when it comes to opinions. Sometimes we're right, sometimes we're wrong - same as everyone.
Agenda -
Paul's Section:
Firstly a few catch-up items -
Card Factory (LON:CARD) - I review its interim results, and can see both bull and bear arguments. Overall though, the weak balance sheet, and total reliance on hefty bank facilities, doesn't give me enough confidence to want to invest as we enter a recession.
Redde Northgate (LON:REDD) - a positive update, and a strikingly cheap valuation, with the dividend yield now above the PER - not something we see very often for businesses that are not in terminal decline. The valuation is now fully asset backed too, on a NTAV basis. Looks a smashing value buying opportunity to me, providing nothing goes wrong.
Finsbury Food (LON:FIF) - I enjoyed an excellent webinar from management yesterday, via InvestorMeetCompany. This is another company that is trading well, taking current macro problems in its stride so far, and has an attractive valuation too. Thumbs up from me. Although it tends not to attract a high valuation multiple, even in the good times.
Pressure Technologies (LON:PRES) - almost halved in price yesterday, on a profit warning. Bad luck to holders. Says it's likely to breach banking covenants imminently, not a good look obviously. However, it only owes the bank £2.4m, so that should be fixable with a waiver, or a small placing, but on what terms? Positive outlook comments on order book & pipeline. I do question though why it is listed? Too small, and with poor performance. Overall, it's difficult to see any compelling reason to hold, or buy this share, based on the information currently available.
On to today's news:
Boohoo (LON:BOO) (I hold) - interim results are poor, with profits largely disappearing. Reduced outlook for the full year also. However, it's not a disaster, and the balance sheet looks robust with plenty of freehold property, and net debt of only £10m. Although the structure of £325m borrowings, and £315m cash, raises some questions. I've been disastrously wrong on this share to date, but with extensive short positions needing to buy back at some point, I reckon we could now be at or close to a low in the share price.
Glantus Holdings (LON:GLAN) [no section below] - this is another disastrous 2021 float. It’s down 61% today to 13.5p compared with a May 2021 IPO at 102p per share. Today it warns that revenue & EBITDA will be significantly below market expectations. Worse than that, it’s almost run out of cash, and is negotiating with high cost lender Beach Point Capital for a $1.5m working capital facility. Looking at its previous accounts, it’s very obvious that this Irish software company was floated with inadequate financial strength (a negative NTAV balance sheet). So it needs to do a placing, but who would be interested, and at what price? Looks very high risk to me, just purely for traders/gamblers now. No section below.
CML Microsystems (LON:CML) - a rare (at the moment!) ahead of expectations trading update for H1 (to Sept 2022). It's also getting a forex tailwind from the strong dollar, as 80% of revenues are priced in dollars. Immensely strong balance sheet, with surplus cash and property, see our archive here for more detail. This share looks very interesting, I like the asset backing, and strong trading (with optimistic sounding outlook comments too).
Graham's Section:
K3 Capital (LON:K3C) (£173m) - yesterday’s final results were very encouraging as K3 Capital continues its mission to be “the leading mid-market specialist advisory business to SMEs” within its areas of expertise. I’ve not looked at this one before but I’m impressed by the company’s organic growth, its marketing strategy, and its financials with solid operating profits regardless of your view on the adjustments applied to it. The valuation is reasonable, too: I get nervous if I ever see a professional services stock at a very high earnings multiple, but K3 Capital doesn’t have that problem! More detail below.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Card Factory (LON:CARD)
45p
Market cap £154m
Card Factory, the UK's leading specialist retailer of greeting cards, gifts, wrap and bags, announces its interim results for the six months ended 31 July 2022 ('HY23').
Here are my notes from a quick skim of the H1 results -
Revenues up strongly to £198m, reflecting post pandemic re-opening of stores.
Note there is an H2 bias to trading historically.
Moved back into H1 profit, of £14.3m, or £10.8m if we strip out one-off items.
Net bank debt of £96.6m still strikes me as a bit too high, but it says this tends to be higher at the half year than the full year. Although intra-year spikes can be higher still.
Cost of debt worries me, if interest rates soar in the current environment, this could become expensive in future.
Products are a value proposition - a positive in these price-conscious consumer times.
Energy costs hedged to Sept 2024 - very good.
Conscious of wage inflation, but plans to raise prices to mitigate this.
Outlook - unchanged full year expectations (pity they don’t say what those expectations are!)
Current trading - sounds OK, with positive LFLs since the half year end.
Online - remains a huge gap, with still negligible online trading. I remain concerned that Moonpig & Funky Pigeon have snapped up this (lucrative) business from under CARD’s nose.
No divis, as focused on debt reduction.
Balance sheet is still weak, with NAV of £237m, less intangibles of £322m, gives NTAV of negative £(85)m. That probably rules it out for me.
Going Concern statement - all sounds OK. But bear in mind this business is entirely reliant on its bank facilities, which the bank clearly wants to gradually reduce, not a comfortable position to be in.
Cashflow - negative, as stretched creditors (e.g. rent & VAT arrears) normalise.
Business rates relief ended in April 2022, so will have been a partial benefit in Feb & Mar 2022 that won’t repeat in future.
Valuation - I can’t find any broker notes. But working on the Stockopedia broker consensus forecasts, see that they have reduced a lot in the last year -

.
Taking this in combination with a weak, negative NTAV balance sheet, with a lot of debt (especially at seasonal peaks), then the PER really should be low, in single digits, which it is -

.
What happens next, given consumers tightening our belts this coming Christmas? Who knows! In my experience, retailers are always nervous about Christmas, every year, but the big, late surge in spending always happens, every year without fail. Even when the economy is struggling.
CARD has a decent value for money product offering, with very cheap multi-buys to lure you in, just inside the shop doors. That is perfect for the belt-tightening times we live in, and recent trading updates seem to show that retail/hospitality offering value for money are still doing well, whereas other weaker offerings are struggling.
CARD’s vertically integrated business model, making the cards itself, maximises profit margins. Trading is recovering, and it’s profitable again now. So there’s a pretty decent bull case for this share.
On the negative side, I’m just not comfortable with the balance sheet & excessive debt. That’s not a good position to be in, when the economy is going into recession. Although to be fair, CARD has managed the situation very well, and its bank has been highly accommodative, but is charging a big lending margin for their patience, which could see lending costs hit c.10% if interest rates shoot up, as expected in the coming months. There might be some interest rate hedging, but I couldn’t find any detail on that, other than a small amount in note 14 of £1.0m in derivatives relating to interest rates. We need more detail on that.
Overall, I’d say the current share price probably looks about right, once you balance the bull & bear points.
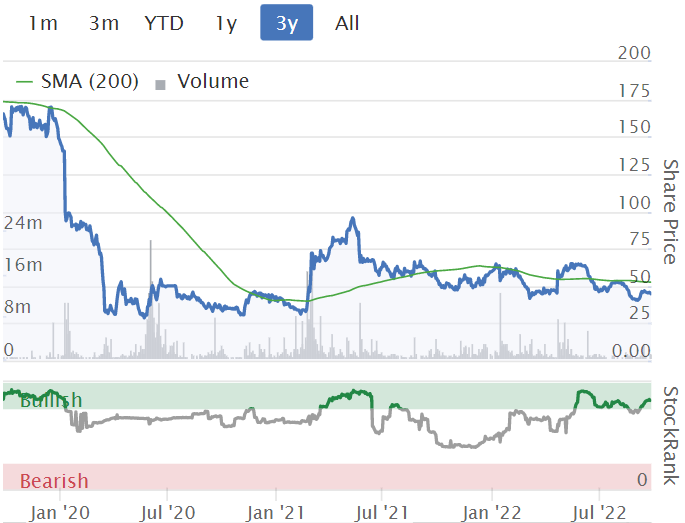
Note that the StockRank is high, at 82 -
.
Redde Northgate (LON:REDD)
295p
Market cap £699m
Redde Northgate plc (LSE:REDD), the leading integrated mobility solutions platform providing services across the vehicle lifecycle…
Encouraging start to FY2023
This relates to FY 4/2023.
Continuing to trade well.
UK&I supply of new vans, “remains tight”.
UK&I supply of new cars, “showing early signs of improvement”.
Spain supply of new vans, “better than expected”, and fuelling growth.
Residual vehicle values are still high, but “softening gradually” as expected.
Profit margins “remain strong”.
Inflationary pressures “actively managed”.
Redde division (accident hire cars) has seen a “strong rebound” post-Covid.
“Little impact” on traffic activity so far from higher fuel costs or recessionary fears.
Car fleet continuing to grow.
Previously announced new contracts being implemented.
Completed acquisition of Blakedale (specialist vehicles).
Share buyback increased to £60m in Aug 2022, c. two thirds now done.
Leverage “well within” policy of 1-2x (EBITDA, presumably?)
Refinanced in Oct 2021, with borrowing maturities extended (up to 10 years).
Divis - 15p final divi proposed (on top of 6p interim divi). Total 21p = 7.1% yield
Diary date - 7 Dec 2022 for interims (to end Oct 2022).
Outlook - a bit vague, but seems upbeat -
Whilst mindful of economic uncertainty, the Board remains confident that it has the right strategy to deliver long term sustainable value. The Group is supported by its enhanced mobility solutions platform, the structural growth in outsourcing, a diverse revenue stream and a broad spread of customers providing the business with quality, repeatable long-term contract-backed earnings.
My opinion - this all sounds most encouraging, and makes me wonder if this is a buying opportunity? The divi yield is now above the forward PER, not something we see often for companies in rude health. Plus the share price is fully asset backed with net tangible assets.
REDD looks like a highly attractive value opportunity to me.
The only downside risk I can think of, is of losing a major contract, which did smash the share price a few years ago, but it later recovered.
Also there was talk of profits being boosted by high residual values of secondhand vehicles, which is likely to be a factor that gradually unwinds over the next year or two, as new vehicle supply (constrained by semiconductor shortages) gradually normalises.
The more I think about this, REDD should probably be on my watch/buy list.
.

.
The Stockopedia computers like REDD too -

.
Finsbury Food (LON:FIF)
79p
Market cap £103m
Finsbury Food Group Plc (AIM: FIF) is a leading UK and European manufacturer of cake and bread bakery goods, supplying a broad range of blue-chip customers within both the grocery retail and 'out of home eating' foodservice sectors including major multiples and leading foodservice providers.
These results relate to the 53 weeks to 2 July 2022, so I’ll call that FY 6/2022.
Management delivered an excellent webinar yesterday, on InvestorMeetCompany. Here are my notes from the webinar -
Interesting slide deck is here
Revenues +14% to £357m (volumes up 8.7%, balance is price rises)
Profit before tax £17.0m (up 12.1% on LY)
EPS diluted 10.1p, up 17%
Divis total 2.5p (yield of 3.2%)
10 different macro-economic challenges mentioned in slide 5 - e.g. energy, raw materials costs, labour, supply issues shortages of drivers, etc.
“Not in a bad position”. Food is defensive in a downturn. Our products are affordable treats.
Kids celebration cakes are quite a big part of the business.
Strong balance sheet.
Well invested, efficient business.
Recovered from pandemic.
Split of revenues: 48% cakes, 38% bread, 14% overseas.
80% is sold to retailers (mainly supermarkets), 20% is foodservice (e.g. coffee shops).
Customers - mainly supermarkets (c. 50% of business is to Tesco, Co-Op, and ASDA)
H2 saw improved operating profit margin, as prices increases fed through.
Gross margin was slightly down for FY 6/2022 at 32.4% (LY: 32.9%)
Operating profit margin 5.0% (LY: 5.1%) - but note it was only 3.9% in H1, so stronger H2.
Net bank debt £20.6m, up from £13.1m LY. Only 0.7x EBITDA.
Overseas business: have increased from 50% ownership, to 85%. Planning on acquiring final 15% from the founders.
Capex accelerated, and took advantage of 130% capital allowances. Was £12.5m this year, up from £6.2m LY. Maintenance capex is about £4m p.a.
Free cashflow was £8.8m (down from £16.4m LY)
Major acquisition (similar size business to FIF) was progressed, but put on hold when FIF share price fell back (hence valuation metrics no longer worked). Not gone away, hoping to revive the deal at a lower price. This cost £1.8m in non-recurring costs, adjusted out.
New bank facility of £120m gives lots of M&A firepower. Very strong banking support.
Penson deficit at one subsidiary only, of £6.6m. Annual contributions are £763k, won’t drop as committed to this, agreed with trustees.
Lots of organic growth opportunities, e.g. artisan bread, and “free from” products, being pursued.
Price rises - challenging to implement, but most customers agreed, as the case for price rises is so clear, due to higher costs.
Working with customers to make things more efficient & strip out costs, e.g. optimising pallet sizes.
Question re broker research - yes take your point, MiFiD has made it more difficult for brokers to make research available to private shareholders. There is commissioned research available.
My overall impression of management is that they seem calm, knowledgeable, and competent.
Looking next at the figures in the RNS -
Balance sheet actually isn’t that strong, but it’s OK. NAV is £118.9m, less intangibles of £87.4m, gives NTAV of £31.5m. That’s OK, but there’s a fair bit of bank debt: £37.0m gross, and £29.6m net of £7.4m cash. That doesn’t tie in with the company’s figure of £20.6m net debt. The difference of £9m is explained in note 9 - they’ve included leases within interest-bearing debt, which is a poor way to present the information. I much prefer lease “debt” to be shown on the balance sheet in a separate line, to avoid this confusion. It’s very different to bank debt, so why combine them into one line?
Going Concern note is fine - no concerns here.
My opinion - we’ve reported positively on FIF here before, it’s a decent company I think.
I’m impressed at how resilient FIF has proven itself, in dealing with numerous challenges, especially inflation & supply chain problems. It has proven an ability to pass on higher costs to customers, a key strength right now, that gives me increased confidence in the shares, because I was previously worried it might get overtaken by supply chain costs & problems. Today’s results show that worry was misplaced, FIF is navigating choppy waters with considerable skill, it seems.
I’m not keen on management funding M&A with more debt, which of course is likely to be a lot more costly in future (there are swaps on existing debt to fix the rates). Since FIF’s own shares are on such a low PER, then this really hampers their acquisition ambitions - leaving management with two unpleasant options - either run up dangerous levels of bank debt, or excessive dilution for issuing new shares on a low PER, which would run the risk of acquisitions actually being negative for shareholders.
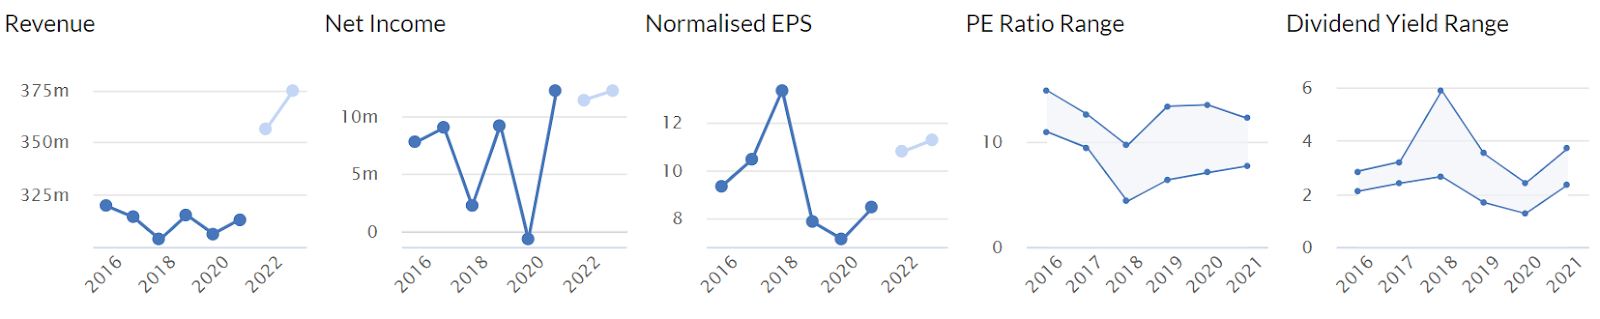
The other issue, is that even in the good times, FIF shares don’t tend to trade on a PER much over 10. So although the PER of 6.9 currently looks cheap, the upside on a re-rating is probably quite limited, if the past valuations are any guide (see graph 4 below) -
.
Overall though, the valuation metrics below are clearly attractive, for a business that is growing, and more than keeping pace with inflation. So as a long-term hold, I see this as a good share that should do fine over the long-term.
.

.
Pressure Technologies (LON:PRES)
33.5p (down 47% yesterday)
Market cap £10m
Bad luck to shareholders in this small, specialist engineering group, with a profit warning issued yesterday.
It says that H2 has improved from H1, but not enough to recoup the losses from H1, and below previous expectations. A variety of problems have emerged to cause this disappointing performance.
Outlook comments sound reasonably upbeat, with a good order book & pipeline.
Banking arrangements - this will have spooked a lot of investors - bank covenants are expected to be breached at end Oct 2022. Discussions with the bank are taking place. In more normal times, I would expect the bank to give a covenant waiver (for a hefty fee, to reflect the higher risk) and then ask the company to do a placing, to get the bank off the hook maybe?
It looks like bank facilities have already been halved, from £4.8m to £2.4m, and is currently fully drawn. Surely a placing could be done to sort out such a small level of bank borrowings?
My opinion - this doesn’t look a terminal situation, so it should be fixable. Although a placing could come at a deep discount, given miserable macro and market conditions. Or there’s always a risk that a predator could pounce, and force the company into administration, thus wiping out existing equity.
Hence I think we have to see PRES as now high risk.
Also, given a lamentable performance in recent years, I have to question why PRES is listed on the stock market? It doesn’t make any sense to me. They’re probably better off de-listing, and stripping out all the costs & hassle of a listing. Which I’m afraid is another reason to avoid the shares.
Years ago, I recall, PRES had a patch of good profits, and there was a massive spike in the share price in 2014. Since then, it’s just ground downwards. So maybe something needs to happen here - change of management, de-listing, takeover, etc.?
I see from the shareholder list that the top 2 holders are Schroders & Harwood Capital, which can both be activist when needed - not always to the benefit of small shareholders though.
It’s difficult to see much of a reason to continue holding this share, I’d be tempted to ditch it & move on.
.

Boohoo (LON:BOO) (I hold)
33p (down 11% at 08:19)
Market cap £415m
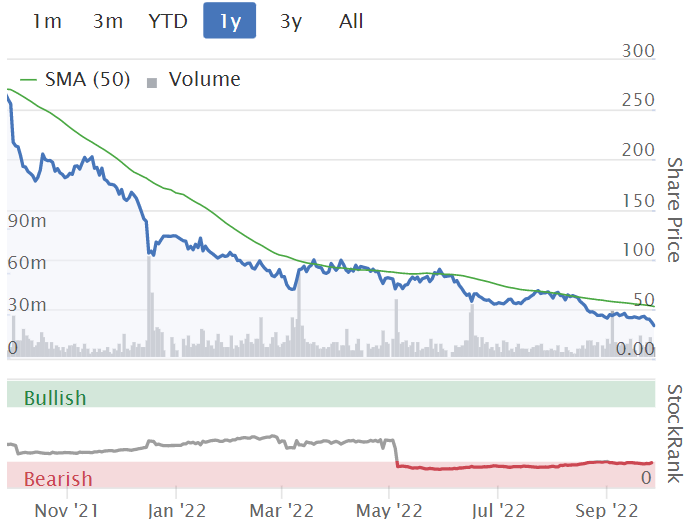
Poor results, but that’s already in the share price, which has fallen over 90% from the highs, along with peer ASOS (LON:ASC) and many other eCommerce companies. It’s incredible how this sector has gone from so highly rated, to completely bombed out. There could now be some nice buying opportunities amongst the wreckage.
So these numbers need to be seen in the context of a share price that’s collapsed - are things really that bad?
Some key numbers for the 6 months to 31 August 2022 -
H1 revenue £882m (down 10% on pandemic-boosted last year H1)
Gross margin also down, at 52.5% (LY H1: 54.6%)
Adj EBITDA £35.5m (LY H1: £85.1m)
Adj profit before tax (PBT) £6.2m (LY H1: £63.8m) - clearly a very poor result, but at least it’s still profitable at a time when competitors have been going bust (e.g. Missguided).
Statutory profit is loss-making, at £(15.2)m before tax.
Guidance - is a profit warning, with previous 4-7% EBITDA range now reduced to 3-5%. In the glory days, it used to be 10%+, which is now looking a distant memory, unlikely to be recouped any time soon, if at all.
Geographic breakdown - a big drop in USA sales of -29% is the main culprit for the drop in revenues, with other regions (UK, Europe, RoW) being around flat, combined.
Ongoing high air freight costs.
Individual brands - are not split out, so it’s a fair assumption to make that the core brands are going backwards, and partially masked by growth in the newly acquired brands.
Balance sheet - includes freehold land & buildings in the books at £131m. The commentary mentions that £96m has recently been spent on freeholds, which includes a new Soho office, which I visited recently when laying some flowers for her Maj - will try to dig out my short video of this. So if things were to get tight, the freeholds are a substantial asset to fall back on, that could be sold or leased back (edit: without much operational impact for the Soho office, as people can be easily relocated to say serviced offices).
Cash & debt is unusual, in that BOO has fully drawn down a newly enlarged £325m borrowing facility (which will incur much larger interest costs than in the past), whilst simultaneously sitting on a cash pile of 315m. So net debt is only £10.4m, not a concern at all. It says this arrangement gives flexibility for investment, and for intra-month cashflow moves, but it seems a rather extreme setup. My main worry is that, if trading deteriorates further, then could any covenants on the borrowings become a problem? Nothing is said about covenants, and the going concern statement doesn’t cover this issue either. So that’s my main query - what are the bank covenants, and what is the risk of a breach? I would work on the basis that the large bank facility might need to be reduced somewhat.
My opinion - when a share price drops by 90%, you already know the numbers are going to be weak, as indeed they are. But these numbers are not a complete disaster by any means. Solvency doesn’t look an issue (although I would like to know more about the bank facility terms). Costs can be scaled up and down, remember that BOO spends a huge amount on marketing for example, and paying influencers. That can be tweaked as required, giving a lot of flexibility compared with traditional retailers and their often ruinous fixed cost bases.
BOO is becoming more efficient gradually, with automated warehouses going live, which should reduce handling & dispatch costs.
As air freight improves, and supply chains generally loosen up again, then margins could improve again in future.
Set against that, this sector is fiercely competitive, but others are falling by the wayside (e.g. Missguided, and ISawItFirst [set up by Jalal Kamani, Mahmud’s brother] - both have ended up in fire sales to Mike Ashley). So there are likely to be fewer, but larger players in this sector, with BOO being one of the last ones standing probably.
Chinese behemoth Shein must be having some impact too, although its slow delivery & returns times are a key competitive disadvantage for customers who want “fast fashion” - i.e. something to wear tomorrow for a night out, not in 2-3 weeks. Speed to market remains a key strength for BOO, but it had to clean up its supply chain (at a considerable cost) whilst Shein and others seem free to do whatever they want, with little to no scrutiny - obviously unfair.
It’s now all about two things - (1) valuation - now down to little more than £400m market cap, for a big group, with close to £2bn revenues, the shares could now be too cheap, and (2) to what extent can it rebuild profits from effectively around breakeven right now?
My opinion doesn’t really matter, because I got it completely wrong over the last year. But for what little it’s worth, I do think BOO should be able to rebuild margins somewhat, over time, and there are good reasons to expect that (e.g. supply chains normalising, freight costs coming down, warehouse automation).
We should also consider the bear side - what if trading continues to deteriorate? Costs would then have to be cut (especially marketing), which would further slow growth. High returns rates are a continuing bugbear (although the introduction of admin charges for returns could alleviate this issue). Bank covenants could become a problem, which might affect future liquidity.
On balance though, I think we could be at or near a bottom for this share price. Remember too, that BOO is being extensively shorted, who will all need to buy back at some point. Hence ironically lots of buyers are already lined up, so if there’s a short squeeze, it could rebound strongly. There’s also the issue of whether the founding family will want to continue as a listed company, with the market cap now in small cap territory? Hence another risk for shorts is if the family decide to buy it back from the market (although they’re not known for over-paying for anything).
With this type of investment, I think it's so important to separate out the emotions of a disastrous share price performance to date, from a realistic assessment of what the future holds. There could be a nice recovery in share price here, at some stage, if fundamentals begin improving. Or there might not, if trading conditions continue to be difficult.
It feels too early to be factoring in an improvement in consumer sentiment. Much too early. But it will happen eventually.
.
.
CML Microsystems (LON:CML)
400p (up 15% today, at 11:10)
Market cap £64m
CML Microsystems Plc (the "Group" or the "Company"), which develops mixed-signal, RF and microwave semiconductors for global communications markets, is pleased to today issue a trading update for the first half of the current financial year (six-month period to 30 September 2022).
Positive momentum, trading ahead of market expectations
Strong trading in H1.
Revenues “well ahead” of last year on constant currency basis.
Further boost from the strong dollar (80% of revenues are in dollars)
Gross margin “robust”.
Costs as expected.
Forward order book is “healthy”.
Overall -
As a result, profitability is expected to be significantly ahead of management's earlier expectations.
At the current rate of trading and based on current exchange rates, the Board expects that for the full year ending 31 March 2023 both revenues and profitability will be ahead of market expectations.
Outlook - this bit sounds interesting -
The Board remains confident in the Group's strategy and its ability to deliver significant, sustainable growth over the coming years.
Valuation - many thanks to Shore Capital for an updated note today. It’s forecasting 15.5p EPS for FY 3/2023, but it sounds like CML is trading ahead of those figures.
Also a key point is that CML is cash rich, and has surplus land (with long-standing plans to develop a small business park on its existing HQ site). When you take all that into account, the apparently high PER looks a lot more reasonable. These are known factors, so already baked into the share price.
Also, this share is a nice place to be hiding in the current market chaos, because the stronger the dollar gets, the more CML’s profit is boosted. So expect sparkling numbers when it next reports.
Graham’s Section:
K3 Capital (LON:K3C)
Share price: 235p (-2%)
Market cap: £173m
In response to popular demand, I’m taking a look at K3 Capital Group.
Disclosure: I don’t recall ever having written about this stock before. Being unable to rely on prior analysis is a disadvantage, but at least I am bringing fresh eyes without any preconceived notions!
From their homepage:
K3 Capital is a multi-disciplinary and complementary group of professional services businesses advising SMEs.
The subsidiaries are involved in services relating to corporate finance (business sales), tax advice and business recovery (i.e. restructuring).
Final results for FY May 2022 were published yesterday. Here are the highlights:
- Group revenue +50% to £70.7m. Organic revenue +24%.
- The two largest divisions by revenue - Restructuring and Business Sales - both saw organic growth of 21%.
- The smaller division - Tax - saw organic growth of 35%.
- Profits are highest in Business Sales (EBITDA £10.8m), despite this division having lower revenues than Restructuring (EBITDA £6.7m)
And in terms of overall profits and cash:
.
- Group adjusted EBITDA +30% to £20.4m.
- Cash £13.7m
- EPS +11% to 20.64p
- Full-year dividends of 12.1p (last year: 9.1p)
All divisions “performed ahead of forecast, demonstrating strength and resilience of the business model”.
In business sales, the market is resilient and there are “more transactions completed than ever before”. This division is “the number 1 advisor by deal volume” in the UK.
In tax, there have been a “record number of claims submitted to HMRC”. This division benefits from “a high degree of contracted and therefore recurring revenue”.
In restructuring, as we have discussed before (e.g. in relation to Begbies Traynor (LON:BEG) ) the loss of Covid supports and other headwinds are increasing demand for insolvency services.
Outlook - complementary acquisitions are being explored, consistent with the strategy to have both organic and acquisition-led growth. There is a confident outlook for FY May 23, with a “robust pipeline” for the year ahead:
FY23 Q1 has seen continued momentum across the Group, delivering turnover in excess of £20m and Adjusted EBITDA of c.£6.5m* in the three months to 31 August 2022
A simple annualisation of the above figures would see revenues of £80m and adjusted EBITDA of £26m for the year, i.e. continued strong growth. The “mid-term ambition” is to reach £50m EBITDA.
The Chairman says:
"FY22 has been transformational for K3 as it continues to develop. The business has the foundations in place to be recognised as the leading mid-market specialist advisory business to SMEs.”
Acquisition and growth strategy
Six acquisitions were completed since the start of FY 2021. Management appear to be delighted with how they have performed.
The idea is to create synergies and boost each acquired company using K3C’s “unique distribution platforms, incorporating direct marketing, cross-selling opportunities and an ever-expanding professional introducers' network through our K3 Hub platform”.
I suspect that the K3 Hub is an important part of the secret sauce that has helped to accelerate K3C’s growth.
When launched, it was described as being aimed at UK accountants. Read more about it here. It now has over 2,000 people signed up.
For accountants, they get a fresh income stream (referral fees) and a range of helpful benefits designed by K3C. They also get an easy answer to the question of where to send clients who need more specialist advice.
For K3C, they get introduced to new potential customers by people these customers trust.
It’s smart business, and is based on the same flawless logic that sees Boohoo (LON:BOO) paying large fees to its social media influencers. To find new customers, sometimes you first have to find (and pay) the people that these customers trust.
But new businesses acquired by K3C don’t just get plugged into the K3 Hub. They also get onto K3C’s “data-driven marketing platform”. The company has a “leading SME data set and proprietary marketing platform”.
And they get access to the mutual cross-selling opportunities that arise between all of K3C’s subsidiaries. After all, the same companies often need help with M&A, restructuring and tax advice around the same time or within the space of a few short years!
Income statement
There has been a lot of talk about EBITDA.
Here is the translation of EBITDA to operating profit:
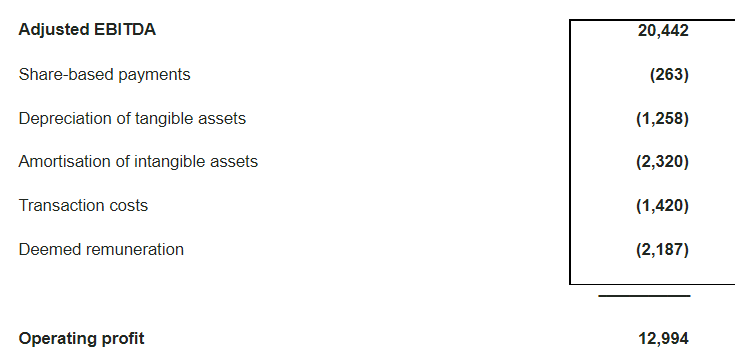
Let’s not get into the debate again around adjustments: I will leave it to the reader to decide if they wish to give K3C the benefit of the doubt around the amortisation of intangible assets.
From my point of view, I would only be completely satisfied to allow the following adjustments:
- Transaction costs
- Deemed remuneration
So for me, underlying operating profit is around £17m. But at least this is not a million miles away from the company’s adjusted EBITDA figure. The discrepancy between my view and a company’s view is often enormous!
Balance sheet
I’m not expecting to find much tangible equity. Indeed, net assets are £66m, including £57m of intangibles (tangible equity is the difference between these numbers).
At least this is positive, and the company still has net cash even if you deduct borrowings (£2.2m) and contingent consideration (£6.5m) from the gross cash balance (£13.7m).
My view
As far as the professional services sector goes, this might be one of the best stories I’ve come across in recent years. It looks like K3C has nailed the marketing side of the business, perhaps by putting in far more effort and placing more emphasis on it than their competition.
When customers find it difficult to differentiate between products, it’s the marketing that makes the difference: I think K3C has taken this principle and applied it to mid-market SME advice.
Are the shares a bargain? I’m somewhat biased against the professional services sector, having seen too many horror shows in this sector over the years (remember Fairpoint?), so I’d still be nervous if I saw a high PE ratio here.
But that’s not the case: K3C has a fairly average earnings multiple.
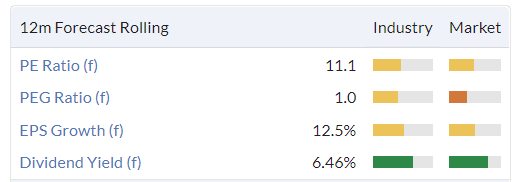
So I’ll take a positive view on this stock, given the average valuation against earnings and some positive features:
- Real organic earnings growth.
- An acquisition process that appears to be working.
- Huge success in marketing and customer referrals.
- Net cash, positive tangible equity, and arguably reasonable earnings adjustments.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
Life is never dull these days.
'Life is never dull these days'
Quite. What an inspiring orator Liz Truss is.
In the last month or so having read the Ray Dalio book
https://www.google.co.uk/searc..
I have gone long the $ against the £ ¥ € and recently the NZ$ and Thai Thb on the simple premise that in the current troubled times people would flee most currencies to the worlds reserve currency which has happened with most see below
https://www.nytimes.com/intera...
https://tradingeconomics.com/c...
seems to me people have lost all perspective when it comes to the fall in value against the $ it’s not really hard to see why the $ is so strong it’s the worlds reserve currency in times of war and turmoil people flee to a safe haven
Everything is priced in $ on the world market
Blaming everything on the latest mini budget is naive
Well worth reading the above mentioned book for a view on how to approach the coming years
Biggest concern for me is Labour getting in next election and moving us back to a time of state control of industry
https://www.reuters.com/world/...
Starting with power but it won’t end there
Would be interested in your take on this counter-argument, Bullhead.
https://kingworldnews.com/russ...
Radical, but I have known of Russian/Chinese discussions to try to end $ dominance for years.
Thanks for link in my opinion the $ will stay the reserve currency for the foreseeable future 10 years or more even after China becomes the largest economy by any measure
The west will slowly carry on losing its dominance and Europes long term fall in power and importance will only hasten because of Ukraine v Russia but the US will stay for a while yet the only thing that will stop that will be internal strife
Presumably the 'mini budget' won't get voted through unless it's considerably watered down ?
Expensive sticking plaster to the tune of £65 Billion & putting pension funds at risk. I do not think anybody has any confidence in the Government right now. This is not good news for the markets at all. They do not like uncertainty.
Some "mini budget", is not mini anymore. It needs people that know how the markets work & know what they are doing to sort this chaos out.......... To be continued.
Enjoyed the podcast but spent the next 30 minutes trying to work out the jingle, eventually got it down to the Twilight Zone, which seems quite apt at the moment.
Does anyone know why RBG Holdings (LON:RBGP) is down so much today? Reasonable results and forecast have recently been announced so I can't see a reason for todays 8% fall. Many thanks.
If you take your blinkers off, you will notice a lot of shares are down. Very few buyers around regardless of results.
Bank of England buying long bonds today to help get us out of this mess we are in right now.
Sticking plaster though as BOE only going to buy for a couple of weeks. Guess the Government better come up with a plausible plan before then that persuades the market that they know what they are doing !! Don’t have a lot of confidence in that . Do you ?
Just to be clear, I have always voted Tory so don’t want to be accused of a biased opinion .
Amongst all the red there seem to be some opportunities
... amongst short dated secured bonds.
I just wish I was quicker off the mark.
so the BoE has decided to intervene to end the gilt selloff by restarting QE, buying as many long dated Government gilts as necessary. Printing money to finance tax cuts seems an odd way to control inflation.
Printing money to finance tax cuts seems an odd way to control inflation.
They're printing money to keep the pension funds in business. A lot of the falls today are due to forced redemptions from pensions who have to match liabilities. Basically this falls under the BoE's remit to stabilise the UK economy.
If you're brave enough, it's an opportunity, especially among larger cap stocks. No reason things can't get worse before they get better, though.
timarr
Well a bit nervy for me today - spent 50% of my available cash.. No small caps although I find them more interesting after following them here ! The spread is just too large to justify (even though the long term returns might be higher). I just dont think that the lows have been reached over the next year or so. Anyway Auto Trader (LON:AUTO), Coats (LON:COA), Morgan Advanced Materials (LON:MGAM), Pan African Resources (LON:PAF), Vesuvius (LON:VSVS), Vistry (LON:VTY) added today in equal proportions.
Well a bit nervy for me today - spent 50% of my available cash
Brave, and possibly loss-making in the short-term but, hey, we're in this for the long game aren't we? :-)
I've topped up Aviva (LON:AV.), M&G (LON:MNG), Legal & General (LON:LGEN) and Rightmove (LON:RMV) today. UK focused shares have been badly hit due to the economic concerns, and then you have forced redemptions on top. Anything liquid must go when there's a liquidity crisis.
Blood on the streets and all that. Could get a lot worse before it gets better, the government seems determined to reprise the 1970's - high inflation, stupid budget, oil price shock, exchange rate crisis, stock market crash, eventual U-turn and cap-in-hand IMF bailout.
timarr
Thought we were supposed to avoid discussions about politics
Thought we were supposed to avoid discussions about politics?
I'd say it's historical rather than political. The point being that poor government policies in the 1970's, reminiscent of those today, saw the UK market crash by 70% - so just because we think things are bad now it doesn't mean they can't get a whole lot worse.
But feel free to report it if you like, I wasn't intending to give offence.
timarr
Well, I put in a reply to Paul the other day that it's hard to avoid politics when economics and politics are closely aligned. I guess the problems come when we use pejoratives like "stupid" and move away from objective discussion.
Nice divis on all of those, apart from RMV where the margin is amazing. I will have to learn about the financial sector, I tend to steer clear, but mostly from a lack of understanding ! Agree with all you have said :o)
Hi timarr,
It's important to remember that the UK's 1970s bail out by the IMF was because of pegged exchange rates at the time, which had to be defended. A bit like the ERM debacle in the early 1990s.
That's not the case now, we have fully floating exchange rates. So there's no exchange rate to target for policymakers, the markets will simply find whatever level where (mostly speculative) buying & selling in currencies match up.
I've never believed that QE would be unwound, ever. More recently, it was very obviously a fantasy for the Bank of England to think that they could start unwinding QE at a time like this, slap bang in the middle of an energy crisis when debt issuance by the Govt is soaring.
I understand the rationale for central bank independence, but maybe in emergencies it might need to be temporarily suspended, as it doesn't feel as if Govt & BoE are working together at the moment.
When markets become dysfunctional, and you have any kind of liquidity crisis, which seems to have happened today, then it needs swift, decisive action by the authorities. We saw with the Euro sovereign debt crisis, for about 4 years after the 2008 financial crash, that dithering & half-measures just encourage speculators to attack with more firepower. Then Draghi's "anything it takes" speech, amazingly, did the trick!
FWIW, I reckon the Eurozone has got far worse problems than us, e.g. Italy where debt:GDP is about 150%, and the only buyer of its bonds has been the ECB, which now holds about E500bn of them apparently, with the Germans worrying is money they'll never get back, unless the plates are somehow kept spinning.
I wonder, if the forex speculators might move on to attacking the Euro in earnest, once the pound stabilises?
Fascinating times, for sure!
Regards, Paul.
It's important to remember that the UK's 1970s bail out by the IMF was because of pegged exchange rates at the time, which had to be defended. A bit like the ERM debacle in the early 1990s.
Hi Paul
It wasn't really. The UK was briefly a member of the ill fated EEC snake, but was forced out in 1972, the IMF bailout was in 1976. Coming out of the snake saw the pound drop dramatically, which further fueled the inflation that Barber's budget had fanned the flames of.
The whole mess was then compounded by the next (Labour) government imposing rent controls which then triggered the secondary banking crisis and the blow out collapse of the stockmarket in 1973 - all against the background of soaring oil prices and mass industrial action.
My point really is that history doesn't repeat, but it does rhyme - and what looked like capitulation in the markets yesterday may well not be. The markets crashed by 70% in 72/73, doubled in 1974 but didn't recover their highs until the early 80's.
Not always easy being an equity investor!
timarr
If you have a chance could you explain this in more detail Timarr I'm guessing its due to db pension schemes having to purchase higher yielding bonds because their inflation rising commitments at annual reviews have increased , but who's buying what they are dumping (no one hence bank of England have to step in ?) presumably lower yielding bonds that they are sitting on a capital loss ?
Thats my stab at it but would appreciate your input if your happy to wax lyrical.
Regards
Andy
Try this:
https://www.ft.com/content/038...
My understanding is those DB funds are selling gilts to meet margin calls.....not simple.
Hi behind a paywall but I have found a couple of links to similar. Still interested in your input Tim if you can add explains why L&G and Aviva were spanked today.
try Google. Enter ft ldi
I can access this: https://www.ft.com/content/756...
Hi The Phoenix
It's fairly complicated, but when there are rapid movments in financial markets it usually turns out that someone has been assuming that those rapid movments wil never occur, based on historical data.
We have an example here today, where leveraged pension funds have suddenly found themselves temporarily embarrassed as they don't have the funds to cover the redemptions that their lenders are demanding, You have about £1.5 trillion in UK pension funds in these "low-risk" strategies, which can't possibly go wrong because the historical models show that they've never gone wrong in the past.
So we've been seeing selling of unrelated assets - in our case equities - to fund the collateral calls. The BoE intervention was to normalise gilt prices to give these funds a chance to sort themselves out. But it's not a long term solution, which can only come from the government.
timarr
Thank you Timarr - Even for you that was a classic exposition. I think there must be a severe risk that No10 Drowning Street will soon be asking for your uncanny explanatory abilities.
cheers
Mark
I think what has happened is that the collateral is really long term gilts; not equities. The regulator and the the pension consultants have pushed all schemes into a very similar strategy - liability driven investment, whereby the assets should match the liabilities in terms of future cash flows. This has led to extensive use of derivatives, whereby they buy long dated gilts funded by selling short dated gilts; collateralised with long term gilts. The events of the last couple of days has caused distortions in the gilt markets, requiring margin calls and hence the crisis earlier today.
I suspect that there are other problems elsewhere yet to surface - usually are when there are very sudden very large moves in markets where change is typically a lot more gradual.
I think what has happened is that the collateral is really long term gilts; not equities.
Hi shopoffrogs
Yes, you're correct I believe. We often forget that the bond and FX markets are far larger than equity markets and moves in those can have disproportionate and often unexpected impacts on shares. So while the main issue is in gilts, collateral is collateral, and it seems some funds have been selling equities and credit funds to fund their margin calls.
The LDI models are built on movements of tenths of percent moves in gilts, not the blow out we've seen in recent days, so it's no surprise that we're seeing stress. As you note, there will no doubt be other issues in the coming days.
timarr
Be very careful speculating on this. Its not about curve trades nor is it about redemptions. It's related to the mtm on the swap element of the liability trade. The velocity of any move always impacts on the margin call.
Thanks for the reply Tim, could I pick your brains on another topic I'm looking at Tritax Big Box REIT (LON:BBOX): reits have fell off a cliff the last week but looking at the Stocko report its showing a TTM book value per share of £2.39 against a price of £1,29 and a 5%+ yield which is covered.
Allowing for the current heightened volatility this would appear to be a good entry point on a medium term basis.
Or am I missing something other than rising interest rates won't be good news for property/any asset classes other than cash in the short term ?
Directed to Tim but if anyone else has a view happy to listen.
Regards Andy
Hi Andy
I don't know anything specific about Tritax Big Box REIT (LON:BBOX) but I think the news that Amazon had cut back its warehousing program had knocked the sector generally before the latest selloff?
Inflation is actually good for most property and REITs because its value tends to rise in line, despite interest rate issues. More broadly, though, the warehousing REITs are exposed to any wider economic downturn - basically they're logistic plays. While it seems inevitable that companies will need to hold more stock from now on due to supply chain issues the race to build more warehouses will presumably lead to oversupply at some point - and that point will be sooner in a proper recession.
So ying and yang. At a near 50% discount to NAV there's a big margin of safety. One thing to look at is the maturity of debt - if it's coming up for renewal soon then there could be a big hit to the bottom line. Tritax EuroBox (LON:EBOX) - which I do hold - has fixed rates and nothing repayable for four years, so despite its apparently high gearing is pretty damn safe.
I sold most of my warehouse REITs back at the begiining of the summer but held onto Tritax EuroBox (LON:EBOX) and Urban Logistics Reit (LON:SHED) - quite why I don't know, but having done so I'm in no hurry to sell them at a discount in the middle of a market frenzy.
timarr
Thanks Tim for the reply I have emailed Foresight who hold Tritax Big Box REIT (LON:BBOX): in their infra-structure fund the debt question. Out of interest are you ex/current wealth management industry as you seem to have a very good understanding of the macro/individual stocks ?
RDHowarth on the money a lot recently also so hat tip to him as well.
Regards Andy
The 45p rate cut is likely to net more revenue as high earners stop taking avoiding actions like retiring. If they got rid of the 60p marginal rate and the pension lifetime limit the tax take rise would be significant.
Many thanks Graham for looking at K3 Capital (LON:K3C), it is much appreciated. And apart from the question posed by a reader yesterday about their acquisitions last year, I'm reassured that you like what you see.
Cheers
Francis
PS: Hopefully we'll also get your views on Volvere (LON:VLE) when they finally decide to update the market! (I hold both).
Thanks Francis. Good luck to us both!! G
On Friday we had a very brief discussion on REITs in the comments section. They've continued falling sharply since the mini budget. Even "safer" REITs like Impact Healthcare REIT (LON:IHR) (with healthcare assets regarded as more stable) are being hard hit. I still don't fully understand why although given the BoE actions today it does sound like pension funds are having to sell off assets quite fast.
Is there an opportunity here or should I be getting out? Some of them are now at very heavy discounts to NAV per share. E.g. Tritax EuroBox (LON:EBOX) which I own is now 50% below NAV per share which seems nuts.
Some amusing thoughts from the chairman of Shepherd Neame (OFEX:SHEP) in today's results.
Forecasting at all times is hazardous. The Nobel
Prize-winning economist Kenneth Arrow, employed by the US Air Force
during the Second World War as a meteorologist, quickly realised that
his medium-term weather forecasts were no better than randomly right and
asked to be relieved of this responsibility. The response came back:
"the commanding general is well aware that your forecasts are no good.
However, they are essential for planning purposes." Inflation
complicates forecasting because it is unstable and hard to predict, and
especially when some of the present inflationary pressures result from
supply shortages arising from lockdown and from the conflict in Ukraine.
These may be ephemeral.
Results are worth a gander for anyone with hospitality sector exposure. Vastly different fortunes in their estate within and without the M25. I hold a rival Adnams (OFEX:ADB) (also an Aquis listed stock).
I'm struggling in this market.
I have made (too many to count) mistakes in my investing life <edit: and in life in general!> - started investing at the age of 18 in 1998 and have been through the crashes in 2000, 2008, 2020 and now. It feels horrible and I'd like to say it gets easier with experience, but it doesn't. I know that buying now will work out okay in the mid to long term and there are many sectors and companies that are almost priced to go bust. I remember thinking after the previous crashes that I wished I had put in more money at the nadir because the small investments I did make went on to do really well and multibag. However it is easier said than done and at the moment it feels incredibly scary buying anything. This should be a contrarian indicator along with mainstream news reporting on stock market falls and the economy and people who don't normally comment on the economy talking about it.
SO, although I'm feeling quite miserable and depressed that my life savings are being decimated each day (mainly income from my hard work - not speculating!) I realise that this could be a fantastic opportunity.
I have decided to move away from the more risky end of the investing universe and looking at bombed out sectors/individual companies with strong balance sheets and the ability to gain market share in a downturn - pricing power, moat etc. I'm also putting more money into Investment Trusts and ETF's to avoid individual company risk because this is a major issue with my stock selection and mental health!
I don't write much here these days, but enjoy reading the reports and comments each day as a subscriber for many years and sometimes it's good to know that you are not alone!
If anyone has any ideas for quality businesses at big discounts or Investment Trusts which have fallen well below their intrinsic value and look like ultimate bargains on a 2-4 year view, then please let me know and I'll do some research.
Best of Luck everyone.
Ben
P.S Paul I'd love to hear you talk (on your podcast, which I enjoy) or write about some of the things on your current watchlist.
P.P.S I'm running the London marathon for Save the Children on Sunday, so if anyone would like to donate - please contact me directly on twitter @BenSharman or on here. Thanks
Well, in terms of things at big discounts and ITs, sign up free to www.theaic.co.uk , Association of Investment Trusts, and see the ever-increasing discounts to NAV of classy smaller PE businesses like CT Private Equity Trust (LON:CTPE), NB Private Equity Partners (LON:NBPE), ICG Enterprise Trust (LON:ICGT) and Oakley Capital Investments (LON:OCI), which have been delivering well. Their investments are not subject to the knee-jerk reactions of public markets, so their NAVs are more stable, and usually only at carrying-cost, but their share prices have widened to 30%+ discounts. That's a huge buffer, when their declared NAVs are themselves theoretically discounted. And the first two, at these prices, are paying 5-6% divs.
On the subject of divs, £HEFL has not lowered its div. for years, has no intention of doing so, and now stands at 8% plus, with its investments all well away from the UK.
I have a lot away from the UK, even if listed here (like the popular Somero Enterprises (LON:SOM)). A UK, very well managed business, whose price has gone down, in my view unreasonably, in the last couple of weeks is £LGEN. The one thing Truss/Kwarteng will do right is widen the acceptable investment gates on pension liability buffers, and CEO Nigel Wilson is itching to put money to work in low-cost housing, usefulinfrastructure and the like. Div. rising 5% this year. At today's price that's a forecast yield of 8.5%! Also far higher than forecast P/E. (If you read this, Paul, I do hold £REDDE and agree with your similar point on them. I am a happy holder there today and even thinking about more at this price. Nothing has changed about the business performance/trajectory in the past 3 months, during which the price has been squeezed down 20%, while doing buybacks. This is an indicator of a 'crash' market, in which selling is indiscriminate.)
My advice is to seek stable and large divs to help you sleep nights. On which topic, can anyone tell me why NOT to buy more Diversified Energy (LON:DEC), an entirely US business, priced in $, divs converted from $, which has just decided to buy back 10% of the business, given the state of the £, while completing on a transaction to increase its gas assets in the central US at the same time, with hedges rolling onto higher gas prices (which are way lower there than Europe)? 15% withholding tax on the rising div still puts it on a forward yield of 11.2%, doing a stable thing, in a stable country in a currency that's powerful against the £. Oh, and it's easily tradeable, with a low spread. The only thing is that, given my standard diversification rules, I already have a 'full' allocation. (I am constantly pulled between diversification for risk management and having too many (currently 46) stocks for actual capital outperformance.)
It's not going to shoot the lights out on capital growth, but if you can live using less than your dividend income, crashes don't cause sleepless nights. Anyone got a bear case for me?
Hi Raggedtp.
Thanks for the write up - some similar thinking to myself. Lost a lot recently, but looking confidently to the future. I actually sold out of some of my more "defensive" positions today in order to be prepared to invest in some of the more "racy" stocks over the next few months. Having money on hand will be extremely useful once we hit the bottom.
Could I ask what HEFL is - I cannot find a ticker with this name, but am intrigued by its offering.
Best wishes
K
I assume HEFL should actualy beHenderson Far East Income (LON:HFEL)
Oops; sorry! Yes, £HFEL!
And Legal & General (LON:LGEN) and £REDD!
By the way, to keep it SCVR, Real Estate Investors (LON:RLE) has reported interim this morning. It's a small REIT. I know it's not very popular, but these were perfectly respectable results, and at 45% discount to EPRA NTA now, I'm sure Paul Bassi is getting fed up with the undervaluation. Meanwhile on track for c. 10% yield this year... Might be worth checking out. (I hold this too.)
Hi Ben
I am currently holding about 50-60% cash, kind of depends on what the remainder is worth at this minute, mostly the cash has been through selling on a manual stop loss (20% down from purchase or peak) to protect capital. Rule introduced in 2020 when I messed up with Covid, my low was July not March! Not that there is much satisfaction but Reach (LON:RCH) is now below what I sold it for at the lowest low then!
I am responsible for several portfolios.
The kids JISAs are with Fundsmith, drip feed every month.
Mum's is ISA (Pension) this is mostly like RaggedTP below, add in some holdings like City of London Investment (LON:CLIG) Impact Healthcare REIT (LON:IHR) BP (LON:BP.) Aviva (LON:AV.) Natwest (LON:NWG) so a hard last few days, but it is about an annual income and the cash from selling will go back in again, some of this is just getting too tempting to buy in. It is looking at companies I understand, make a profit and pay a dividend out of that (e.g. covered). I also hold things like Henderson Far East Income (LON:HFEL) and Real Estate Credit Investments (LON:RECI) too.
My watch list is a mixture of companies and ITs, so looking at a stable dividend that is covered right now and what the level of discount is.
I don't know who said it, but I still hold the memory, what is the difference between a 90% loss and a 95% loss? The first has gone down 90% from purchase, the second has lost another 50% again! I know semantics but realising why sometimes cash is not a bad place to be.
I am slowly buying things, still have the manual stop loss in place. I have no holdings above the 2-3% range, sold the last 5-6% down yesterday, Impact Healthcare REIT (LON:IHR) still 2% but we are not perfect.
Yes it hurts to see £10 turn into £7, but you still have £7 and you are not needing to spend it this evening I hope?
Good Luck!
Tommy
.
Open an IKBR account and trade with peanut spreads in dollars. Sorry but UK market too difficult this time - but will watch with interest of course.
The FTSE 250 is at 16,850… it touched a similar level in February 2014. Stockopedia states a forward P/E ratio of 11.65 for the index.
The S&P 500 is at 3,625… the same level as November 2020. With a forward P/E of 15.61 and a much smaller yield.
My hope is that UK mid- and small-caps are already a longer way along the corrective phase than most other equity markets. I do tend to think of bear markets in terms of the number of years of growth scrubbed off the index (8 years for the FTSE 250), and when I think ‘wow!’ then hopefully that’s a good time to begin putting money to work. Not that I have the guts to, yet!
And the FTSE100 is at a similar level to where it was in Dec 1999!
Judges Scientific (LON:JDG) webinar on Friday (30th) at 1pm. Register here.
EMIS (LON:EMIS) interim results presentation & acquisition summary.
Video and podcast
Paul
Firstly thank you for your wonderful opening comments. This past year has been hell though I did learn from my meltdown in March 2021 and have not sold at the lows as I did then and yes I should have raised more cash back at the beginning of this/middle of last year but then we are all super investors with hindsight. But..
My portfolio is about half the value it was last year (not all loss I have drawn some to buy a small overseas property) but still horribly down compared to say my son’s JISA say, which is mainly invested in BRK.B and US large caps (JPM, DIS etc) which is only off 9% this year and that was before the sterling crisis so probably flat in Sterling terms. But…..
give or take I think this calendar year the dividends paid to me in 2022 are going to be roughly the same as in 2021 and I don’t even buy looking at dividend yield. This gives me some comfort that all is not lost at many of my companies and that they will recover from the current share price rout.
On Boohoo (LON:BOO) it is now back below the price I first bought them at back in November 2015! Is that a fair valuation basis on discounting back all future cash flows of the company to get the intrinsic value of the company? I doubt it. In that first period of holding I made a 391.1% return. My current holding (with a much larger investment) is showing a 85.5% loss. I certainly didn’t see it coming and it certainly seems to be priced as though it is going to never make a profit again. The holding is so small that it is not worth selling but I also think that it is over done. That said congratulations to those here, and there have been a few vocal ones, that saw Boohoo (LON:BOO) as an accident waiting to happen. I should have at least listen rather than being closed to their views.
Regards
Michael
Boohoo (LON:BOO) - bad news normally means more bad news. For me too it's in the coffee can as a write off.
K3 Capital (LON:K3C) review please Paul and Graham. Interesting results yesterday, and could do well in a downturn. I added a few to my holding yesterday.
Thanks for all the rest this morning so far.
Good morning ridavies,
Yes, we spotted that there was a lot of interest in K3 Capital (LON:K3C) in yesterday's comments, so it's on our list of priorities for today. Graham's taking a look at it now, I think. I recall reviewing it before, and thinking it looked interesting. Although with deals drying up generally now, I wonder if profits will prove sustainable? Let's see what Graham thinks!
Regards, Paul.
K3 Capital (LON:K3C) worth noting while a fair chunk of their revenues come from the insolvency side, it only accounts for a small portion of their profits (sorry don't have figures in front of me). The majority of profits come from corporate broking which is obviously cyclical. Therefore I would not view this as a pure insolvency play such as Frp Advisory (LON:FRP)
Ahhh finally some completely irrational across the board sell offs....light at the end of the tunnel perhaps.
Yes, hopefully this is the capitulation phase
My buy triggers have been pinging left, right, centre over the last few days. If I were to religiously buy new stakes in all the triggered alerts, I'd be looking to add 8 new positions to my portfolio. Of course, I'm not going to do that; but definitely looking at one or two potentially before the week ends.
Since the start of Sep, I've been slowly taking some new positions for the Boon Fund, as well as topping up. Also have started to unwind my S&P500 short ETF; there's probably still a bit more pain to come, but the majority of the fall (both S&P and GBPUSD) I think is now realised.
My next monthly update for Sep, will likely be quite a long article, with lots of trading activity to share.
Re the market, positioning and activity. For me the opportunity to do much with my mistakes has now passed. IF something like Hostmore (LON:MORE) did go bust ... it costs me very little. (I have already outlined why I think this won't happen). The victims of this cycle have been been hit very hard already... who knows how and how long recovery takes but I will just wait it out.
It seems to me the parallels with both 98 in terms of currencies and 01 in terms of valuations of tech are playing out rather quickly now. I think we are sowing the seeds for a quick lunge down - response - and bounce back. Where I differ from others is I suspect we don't see a rush into risk like 2020 and see something more akin to 01-03. Its dangerous to over simplify the market... but broad defensive themes should play out.... as the economy will like remain troubled by global events. The good news is plenty of these are getting caught up in the wider sell off and a great buying opportunity is in the making... not for a quick buck... but to lock in solid long term returns.
A few weeks back I Mentioned Index linked Gilts...of which I still understand too little but #INXG is trading down at 11....either rates fall or you capture inflation not recognised in current index linked pricing... either way this should rise again from here. But I read today of LDI pension funds having liquidity issues and having to make cash calls.... so you are seeing liquidity driven selling (not investment) in assets and this provides the opportunity. The exact same thing is happening in equity.
Although comments from the boe were met with a shrug... I figure what the Ch was saying was this is your mess to the government. If you force us to raise rates further your budget has lost all impact. So now the govt needs to convince the currency market to back their plan... one way or another this will happen.... its popular to think people in central banks and governments are stupid but we all know that isn't true... the markets is in a brutal mood and mis-steps are crucified. Anyway Im not advocating some great hero trade ... not yet anyway... but I would try and stay calm ... and see the riot in sterling as the catalyst to sort out the right mix of policy and narrative. Riots and storms do die out. This will pass.... and as J Authers pointed at yesterday the last time the £ was caught in such a storm ... 12 months later it was 40% higher. This augurs well for share prices likely to follow the £. The UK market PE is attractive.
Anyway, markets are markets and are only an average after all. Now we have seen such falls...and more likely some more...but we can just focus on the stocks. From here looking forward returns will be so much better. We will lock in v attractive prices. You could by a large cap stocks like BT (LON:BT.A) and likely make 50% ! It still won't be expensive.... and will still yield 5%. Its definitely a time to read open minded and just accept our historical mistakes for what they are.
Happy hunting everyone... hoping you all find some nice bargains out there.
Good prelims from Avingtrans (LON:AVG), more or less on the money. The company is operating in vogue sectors, providing sophisticated 'picks and shovels' to the energy sector, oil, gas and nuclear. There is also the exciting prospect for its medical imaging division that is progressing development of a portable orthopaedic MRI/X-ray scanner.
Avingtrans (LON:AVG) is a well managed and securely funded company with good prospects, that is not exorbitantly priced. I am confident that the market will be completely disinterested!
I hold
Firstly thank you to Paul and Graham for soldiering on and swimming through treacle as the bad news continues to come. No point whatsoever crying over spilt milk ....
I just wanted to follow up on Hostmore (LON:MORE) where there have been announcements of decent buying from directors and those connected to Sherbourne. To me this confirms what I suggested the other day that a solution will be found for the quoted equity. I may be wrong and it may disappear in some stitch up private deal... but I suspect there is support for this one to come good. Hmmmm that doesn't mean it won't need to inject extra cash and dilution to come...which we "may" not directly participate in. However given the state of the current market a 2020 style recovery seems a faint hope.....more likely its all going to take longer, 2024? On the face of it we all might get upset if its get refinanced with an injection and we get diluted but I guess we will get plenty of opportunities to add at similar levels as it plays out...... Never the less.... energy will normalise...and footfall will return...wages and staff availability will likely normalise ....and any fears of a return of covid will fade. After all this plays out the platform operating numbers will also return to previous levels. For me, I don't mind increasing and following the recent buyers.... but mindful of all comments made re the risk.... and set in the context of other portfolio holdings.
Boohoo (LON:BOO) interims this morning don’t make for pretty reading but no different from others in the sector, with revenue declines expected to persist in H2 and EBITDA margin range lowered from 4-7% to 3-5% and a warning on inflation driving up costs. How I long for the days of the continuous groan on the Boohoo (LON:BOO) chat and the multi-billion market cap :-)
Haha yes, at least nobody will be complaining today that Boohoo (LON:BOO) shouldn't be in a small cap report! I'm working on the numbers now, should be a section up fairly soon. Quick view - poor results, and negative outlook, but it's still a substantial business, still profitable & balance sheet looks OK to me - although drawing down a large loan of £325m, whilst simultaneously holding £315m in cash, strikes me as odd. Also nothing said about covenants on the big loan, which is a potential worry.
Overall - the share price is down 90% from the highs, same as Asos, so of course these businesses are not trading well - the shares wouldn't be bombed out like this, if they were. Large short positions will need to buy back.
Obviously BOO and Asos, and eCommerce generally, have been disastrous shares to own in the last year, but it seems to me that BOO is probably close to the bottom now. So from this point, probably more upside than downside.
More detail to follow later.
Regards, Paul.
Morning Paul,
Boohoo is not a profitable business , the balance sheet does not look OK , it is definitely not even close to the bottom and there is definitely more downside than upside in the long term.
Boohoo will need at least £175m in 2023 just to keep trading.
Another one that will need a fundraise in the next 12 months.
Enjoy your day.
As usual, that's just a series of strident assertions, with no supporting facts or figures. Where do you get that £175m figure from please?
yiannos1 on Boohoo (LON:BOO) please can you explain your assertions?
Thank you.
Kind regards
Michael
Hi Michael
Have a look at the cash flow statement and especially the new loan and you will get there (believe me it’s not rocket science).
Boohoo it’s just not generating any cash for its shareholders.
Thanks
Yiannos1
£BOO I am traveling at the moment but will do.
I think the reason people ignored comments like yours was that they come across as 1. combative 2. Based on emotion because even though you have or may have gone through the cash flow statement etc the comments come across as though you haven’t and are just commenting because you hate the company. Whereas people want to see your workings, in the same way that Paul and others shows his even if you disagree with his/their conclusions.
Regards
Michael
Boohoo (LON:BOO) - I just had a quick look at the cashflow statement myself. Based on my very rough calculations, I think that if operating conditions do not change, they are good for c. 3 years without additional financing.
In FY22 there was a net outflow of cash before financing of £262m. Comparing where FY23 should/might land - cash from ops £45m worse (assume 50% v FY22, as per H1 23), capex £110m better, inventories/payables say £90m better (assuming gradual run down of stock as shipping improves) gives net outflow of roughly £107m (262 + 45 - 110 - 90). Given that they currently have £315m in cash -> roughly 3 years.
All very high level, of course.
Paul, is it right to say you still have a BOO position
Yes, I am still holding BOO, but a much smaller position size, as I was forced to reduce exposure in my Spreadex account. Ah, just realised I forgot to put the usual disclosure in, apologies, I'll edit the article now...
Thanks, Paul.
I think everyone here already knows you hold Boo Paul!
drawing down a large loan of £325m, whilst simultaneously holding £315m in cash, strikes me as odd.
Flexibility for investment, and for intra-month cashflow moves seems plausible but as you say, an extreme position. Are you able to speculate on any other possible reasons?
Well, I try not to speculate!
I've checked the RNS, and BOO's last Annual Report, and I can't find any meaningful detail on the £325m borrowing facility. It's not stated anywhere who the lender is, nor if there are any covenants, nor what interest charges are - just that it's linked to SONIA.
So there's a clear informational gap there about the substantial borrowings at Boohoo (LON:BOO)
Not an immediate worry, as almost all of it is sitting in the bank, in cash.
Not an immediate worry, as almost all of it is sitting in the bank, in cash.
That is really my question. I would expect a large amount of cash to attract some interest but I can't identify it in the accounts.
Boohoo (LON:BOO)
I thought the interim results presentation was worth watching The us warehouse will go live before next summer. working capital now neutral after being a drag last year and expected to remain neutral even if sales decline. Fully drawn down revolving credit facility to give max flexibility but with neutral working cap will look to repay chunks of the facility if appropriate. Flexible on which cap ex projects to pursue now and which to delay.
Do we talk about £BOO. Posts a loss, and net debt with declining revenue and margins with expected further decline in revenue and margins. Lots of talk in the RNS about gross cash which seems misleading when it has fully drawn down the revolving credit facility. What happens from here? Lots of initiatives sound promising but now, in hindsight, seem very badly timed (Building a £4 billion turnover capability). Spending £6.5m on revolution beauty shares (small fry)
Boohoo (LON:BOO) is now back in small cap territory
Morning Paul, excellent summary as usual. Just a quick note to say in your summary section for Redde Northgate (LON:REDD) you have "and a strikingly cheap valuation, with the dividend yield now below the PER ", which I believe should read "above".
Thanks for all your and your co-writers work over the years, it's a daily staple for me, even now after I've moved to Australia which affords me an easier time to read these at approx 5pm in the afternoon with a beer in hand (note: need to be careful with that buy button!).
Morning gregatrOn,
in your summary section for Redde Northgate (LON:REDD) you have "and a strikingly cheap valuation, with the dividend yield now below the PER ", which I believe should read "above".
Ah, well done, yes I was wondering who would spot that deliberate mistake first! ;-)
Best wishes, Paul.
(I'll fix it now. Thanks!!)
Some dedication Paul writing updates at 12:55am! Thumbs up from me.
Thanks! I'm finding it so difficult to focus on writing about shares during the day, with so many chaotic things going on at the macro level. So catching up in the evening can be a good time to focus on individual companies.
Thanks for all your hard work Paul.
Also, I find your podcast excellent. It is a very useful summary of the chaotic weeks we are experiencing. I like to listen to it on a Sunday morning with a coffee, while I prepare for another week on the rollercoaster.