Small Cap Value Report (Weds 29 March 2023) - MAB1, TM17, CARR, MBH, SUS, UPGS, AEO, KETL, RM., CDGP, SUN, TBLD

Good morning from Paul & Graham.
Today's report is now finished.
My CEO interviews are resuming after a break. Today I'll be chatting to the CEO of Belvoir (LON:BLV) - that should be up on my website & podcast channels by about 14:30. EDIT: Belvoir interview is now live. Also on my podcast channel (Small Caps Podcast with Paul Scott)
Then tomorrow I'll be talking to the CEO of Portmeirion (LON:PMP) (I hold personally).
I'll put the links in here when the first one is live.
NB I only tend to interview companies that I think are good, and am considering buying some myself (or already hold). Other requirements are a sound balance sheet, decent recent trading update, and a reasonable or cheap valuation. I don't charge for these interviews, so you know I'm only selecting the things I think are best, from a value/GARP perspective. Never recommendations remember, and some will go wrong, that's inevitable.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Main Sections -
(summaries here, main sections further down)
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Finals - up 1% to 628.5p (market cap £360m) - Graham - GREEN
Adviser numbers are expected to stabilise in Q2, with the mortgage market relying heavily on refinancing deals for sustenance. I still rate this one highly but it’s less cheap now.
Team17 (LON:TM17)
Finals & CEO change - down 9% to 405p yday (market cap £590m) - Graham - AMBER
Organic growth of only 3% but excellent growth through acquisition. Bigger news is the long-standing CEO stepping down. A good company; valuation looks fair.
Michelmersh Brick Holdings (LON:MBH)
Preliminary Results FY 12/2022 - up 5% to 95p (at 08:25) - mkt cap £91m - Paul - GREEN
Smashing results for 2022, ahead of expectations. Low PER. Nice dividend yield (well covered too by earnings). Superb ungeared balance sheet, strong cash generation. 2023 energy costs hedged. Selling price raised, maintaining margins. Even the outlook comments sound quite good. This looks really good to me, so I'd be inclined to ignore macro guesswork, and just have this as a core long-term holding. Thumbs up from me.
S&U (LON:SUS)
Finals - down 2% to £23.50 yday (market cap £285m) - Graham - GREEN
Strong results; persistently high collections in motor finance and highest ever “normalised” profits. Some risk from increased gearing and rising rates. Valuation appears reasonable.
Strix (LON:KETL)
Results - up 6% to 93.8p (market cap £205m) - Graham - AMBER
Adjusted profits in line with guidance; company is seeing green shoots of recovery. I’m nervous about its debt load but management have promised to stop the M&A spree and to reduce capex.
Quick Comments -
Carr's (LON:CARR)
Trading in its shares is being restored this morning from suspension, caused by a technical problem with the audit.
Aeorema Communications (LON:AEO)
Interims -up 10% to 75p (£7m) - Paul - AMBER
- Record H1 revenue of £7.1m (up 45%)
- H1 PBT £326k.
- “Very confident” about FY 6/2023.
- Balance sheet - NTAV £2.0m. Cash pile of £3.7m, but partly offset by creditors.
My opinion - Impressive rev growth. Too small to be listed really. I recognise several shrewd PIs on the >3% shareholder list. Might be worth a closer look for nanocap investors, but beware wide spread & lack of liquidity for anything this size. Small, but interesting company.
UP Global Sourcing Holdings (LON:UPGS)
Interims (in line) - down 4% to 135p (£121m) - Paul - GREEN
- Good online growth. “Continued normalisation of global supply chains”. Revenue from retailers down 11%, as over-stocking unwinds.
- H1 adj PBT down 5% to £9.4m.
- H1 8.6p adj EPS.
- Historical seasonality is heavily weighted to H1.
- Outlook - trading in line with FY 7/2023 expectations.
- Valuation - modest fwd PER 9.2x, and lovely dividend yield of 5.5%.
- Net bank debt down 36% to £19.4m, more palatable than before. Overall balance sheet is adequate, but only c.£6m NTAV - probably OK as it has few fixed assets.
Overall, thumbs up from me. The slight dip in H1 profit isn’t a concern to me.
RM (LON:RM.)
Prelims 11/2022 - up 8% to 70p at 10:05 (£59m) - Paul - AMBER
- Previously reported problems, led to divis being suspended.
- Bank facilities renewed to July 2025 sounds positive.
- Adj PBT down 65% to £5.3m. Statutory loss £(14.5)m.
- Outlook - vague, but says they will rebuild shareholder value, but tough macro conditions.
- Detailed going concern note is an important read - things sound tight, if trading were to deteriorate further, but otherwise OK. Disposals need to complete.
- Balance sheet looks precarious, with negative NTAV of £(15)m, and the pension surplus asset of c.£23m may not really be a surplus, so needs checking out.
My opinion - this is quite complicated, so best seen as a special situation. Difficult to value. Could be a nice turnaround if things go well, but be aware that it’s still quite risky.
Chapel Down (OFEX:CDGP)
Final Results FY 12/2022 - 37.4p (unch) (£66m) - Paul - AMBER
Good results flagged by grumpy5 in reader comments -
- PBT has risen from £1.1m in 2021, to £1.6m in 2022.
- Very good balance sheet, with £32m NTAV, and the company reckons open market value of its assets is higher.
- Not cash generative yet, due to increasing working capital and capex.
My opinion - could be interesting long-term. Valuation doesn’t stack up on conventional value metrics (other than maybe asset value). Could be an interesting punt if you like the wine & the shareholder discount. Personally I’m not keen on very slow, and capital intensive business model.
Surgical Innovations (LON:SUN)
Final Results FY 12/2022 - up 5% to 2.0p (£18m) - Paul - AMBER
Gosh, this company has been around for most of my investing career, it floated in 1998! Today it reports FY 12/2022 numbers -
- Good revenue growth up 24% to £11.3m.
- Only breakeven profits.
- Says the order book is strong.
- Balance sheet seems OK, so it may not need to raise any more equity (932m shares in issue is probably enough!).
My view - something good might eventually happen here, but as things currently stand, it’s difficult to see why anyone would want to buy or hold this share.
tinyBuild (LON:TBLD)
FY 12/2022 Prelims - up 14% to 52p (£106m) - Paul - AMBER
A reader request. Computer games company.
- Strikingly good headline figures - profit up 27% to $15.9m. Although of this, $11.1m appears to be “Other operating income”, which seems to be a one-off relating to eliminating a contingent consideration creditor - so caution needed.
- Outlook positive, says has good visibility due to portfolio approach to games (not a one-hit wonder), and at least in line with expectations for FY 12/2023.
- Interesting style & content of management commentary.
- Balance sheet is good, includes $26.5m cash and no interest-bearing debt, but down from $48.8m a year earlier, due to huge development spend of $35.8.
My opinion - looks potentially interesting. Note it’s owner managed, by what sounds a dominant CEO who owns 38%. Not a sector that I tend to invest in, as valuations get too stretched in bull markets, and earnings are often very difficult to predict. But this share has fallen a huge amount, and could be worth further investigation now.
To Do List
We'll cover the most interesting companies (eg. above/below expectations), and please remember there isn't usually time to cover everything -
Paul’s Section:
Michelmersh Brick Holdings (LON:MBH)
93.5p (up 3% at 08:47)
Market cap £90m
Michelmersh Brick Holdings Plc (AIM: MBH), the specialist brick manufacturer and brick-fabricator, reports its preliminary results for the year ended 31 December 2022.
Good numbers here, which the company says are ahead of expectations.
Crucially, it demonstrated pricing power, by raising prices thus mitigating cost increases - a key attribute that we’re all looking for right now.
Some numbers -
Revenue £68.4m (up 15%) - so quite a small business really. Larger listed competitors Forterra (LON:FORT) and Ibstock (LON:IBST) are multiples of its size. There’s also distributor Brickability (LON:BRCK) to consider in this sector.
Adj PBT is up a similar % to revenue, at +14.7% to £12.5m - note the strong profit margin here, at 18.3% of revenue - suggesting it has products with pricing power that are in demand.
Adj EPS 10.61p (2021: 9.33p) - up 13.7% - this is a PER of only 8.8x
Adjustments - look fine to me, being the generally accepted practice of eliminating amortisation of goodwill.
Taxation - as we’re seeing with many companies reporting now, the tax charge has dropped a lot from an inflated 2021 charge (due to deferred tax adjs re the 19% to 25% rate change forthcoming). This is why the basic EPS figure rose a lot from 2021’s depressed EPS (caused by tax). It looks as if they've normalised the prior year tax charge in the adjusted numbers, to give a realistic underlying % increase in EPS, so that's all fine. The adjusted numbers are reliable in my view.
Dividend of 4.25p is up 16.4%, and more than twice covered by earnings. Yield of 4.7% is attractive. The interim/final divis split looks to be about 1:2 historically.
So that all looks pretty good. Can it be sustained though, given that we know the housebuilders are seeing reduced demand, and in some cases delaying construction projects? MBH looks more niche though, so might not be affected so much.
Outlook - key points are - lots in here, all interesting -
… we enter 2023 with a high-quality forward order book, deliberately covering a breadth of end market channels from RMI, housing to commercial, social and specification projects, now further expanded by FabSpeed
Despite the ongoing challenging market conditions, we remain well placed at the premium end of the brick market in the UK and Benelux markets. The long-term fundamentals of these markets are positive, with brick continuing to be the façade material of choice due to its longevity, sustainability and energy efficient qualities in use, low cost and broad aesthetic appeal, whilst equally, available brick stocks remain at historic lows.
Importantly, the strength of our balance sheet provides us with financial resilience and also flexibility to pursue further acquisition opportunities…
As we enter 2023, the ongoing higher inflation environment continues to provide an uncertain backdrop as we look to manage our supply chain and input costs. Given the high energy requirements for brick manufacturing, our energy price hedging policy remains incredibly important to ensure that we are well placed to manage the impact of utility price volatility over the medium term, with our requirements again materially hedged at over 90% for 2023 with further contracts into 2024 and 2025. We remain focused on mitigating these risks through maintaining appropriate portfolio pricing, and in collaboration with our customers we introduced our standard timetabled price increase at the start of January 2023…
With elevated inflation and higher interest rates potentially impacting demand for our products, we believe the quality fundamentals in our business will provide resilience and we are well placed to continue our strategic progress through 2023 and beyond.
What to make of that? It sounds pretty robust to me, but it’s probably safest to assume that demand and earnings in 2023 might dip somewhat from 2022, maybe?
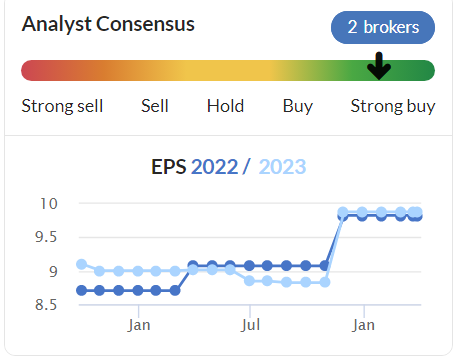
At the moment brokers are forecasting flat earnings in 2023, which might be a little ambitious maybe? (we obviously don’t know at this stage, it’s guesswork).
Balance sheet - is very strong. NAV is £89m, less intangibles and deferred tax, becomes NTAV of £80m. So what this means is that the £87m market cap is almost entirely supported by NTAV - that’s really pleasing to see.
Another way of looking at it, is that in a capital-intensive business, the £66m fixed assets are owned outright by the company, with no debt financing.
Working capital is also healthy, with a current ratio of 1.8
There’s a cash pile of £10.6m, with no interest-bearing debt.
Overall then, this is a cracking balance sheet, which gets an enthusiastic round of applause from me. Shareholders here don’t have to worry about solvency at all. Also it gives scope to make more acquisitions.
The commentary mentions potential sale of surplus land, which would be a nice bonus.
Cashflow statement - again, really strong. These are such nice, clean numbers, it’s a pleasure to review them. MBH generated £18m post-tax operating cashflow (2021: £13.6m), which comfortably funded £3.0m capex, a £6.0m acquisition, £1.5m share buyback, and £3.3m in dividends, with it still ending the year with a £2.4m increase in the cash pile. That’s very impressive I think.
You can see from those numbers that the dividend paying capacity is a lot larger than the 4.7% yield, which it can easily afford.
My opinion - as you’ve probably already guessed, I really like this share! It ticks all my boxes - a modest forward PER of only 9.2. A well-covered, easily afforded 4.7% dividend yield. A fabulous ungeared balance sheet. It’s demonstrated pricing power in a tough year for costs. And the outlook statement overall sounds quite positive. We don’t even have to worry about energy costs, with 2023 being hedged, and wholesale prices coming down so much that any future surprise might even be positive, who knows?
Downside risks are mainly macro - that demand could plunge if the housing sector really hits the buffers.
Overall, this gets an enthusiastic thumbs up from me. I think there’s a strong argument here to just ignore macro guesswork, and hold this high quality share for the long-term.
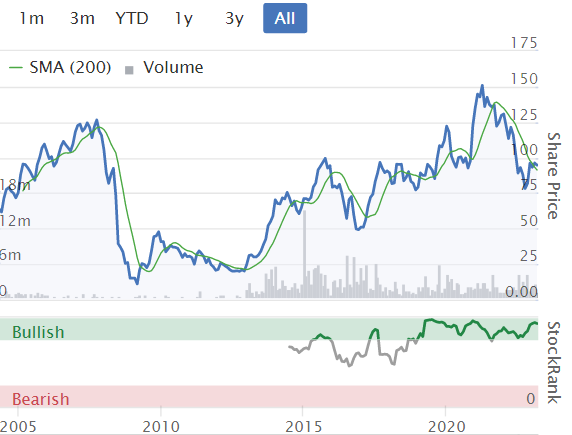
Stockopedia likes it too, with a 93 StockRank - I always like it when the unemotional algorithms confirm my analysis is on the right tracks!
The long-term chart does sound a warning though - it was absolutely crushed in the 2008 financial crisis -
Graham's Section:
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 628.5p (+1%)
Market cap: £360m
After a turbulent year for the mortgage industry, let’s see how the mortgage advice bureau did:
Revenues +22% to £231m (organic growth 11%)
Adjusted PBT +13% to £27m
PBT down 25% to £17m
Current trading is in line with expectations.
Adviser numbers dropped due to the mortgage market shock, but “we expect adviser numbers will stabilise in Q2 2023 and then build gradually as business volumes improve”.
Mortgage transactions are down 35% year to date (vs. 2022), but MAB says it is outperforming the wider market and growing market share. And it is thought that refinancing transactions will grow in 2023 despite the collapse in new mortgages.
Rates have reduced from their peak but are obviously still higher than they were a year ago (impacting affordability/consumer confidence).
Faster advice - using technology, they are looking to reduce the time to take a mortgage from enquiry to completion, from ten hours all the way down to five hours.
My view
Please see my previous comments on this stock - I view it as a quality business, and I mentioned it as one of my top ten ideas for 2023. As trading is in line with expectations, there is little reason to change my fundamental view.
One thing that has changed is the valuation. MAB’s share price has made good progress since I first became interested in it, and it now has a below-average ValueRank:
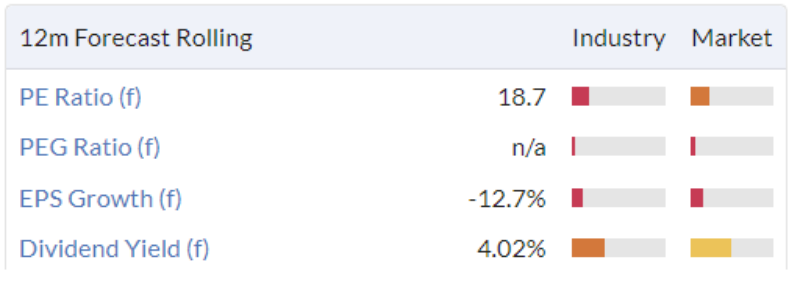
So is it “cheap”? Not really. But I will continue to rate it positively - this is the analyst’s equivalent of “letting my winners run”!
Team17 (LON:TM17)
Share price: 405p (-9%)
Market cap: £590m
It was a double RNS from Team17 yesterday, with both results and a statement on the CEO position:
…Debbie Bestwick MBE has indicated her intention to step down from her position as Chief Executive Officer of the Company once a suitable successor can be found.
The company is planning to do things the right way, with an orderly handover, and with Bestwick helping to choose her successor. To me, that seems appropriate as she has been so crucial to the long-term evolution of Team17.
The company offers reassurances that the business can survive without Bestwick as CEO:
Debbie will remain equally focussed on maintaining a "business-as-normal" mentality across the Group, with the senior team committed to delivering the Group's strategic ambitions.
Over the last eighteen months, a highly experienced and effective divisional senior leadership team has been established, that work closely together with the Executive team and are closely aligned to the Group's core values. This team now runs the day-to-day divisions within the Group and boasts extensive and unequalled gaming industry knowledge and operational experience.
My view - it is definitely a negative news story for the stock, but the reassurances around the search for a successor and the handover plans do take some of the sting out of it. With the right successor, I would say that the business can continue to thrive.
Now let’s take a quick look at the full-year results for 2022:
Revenue +52% to £137m (organic growth 3%)
Adjusted PBT +35% to £47m
PBT down 1% to £29m
Cash £51m
Adjustments - the £18m of adjustments include £9m of amortisation and £9m of “acquisition related adjustments and fees”.
In other highlights, Team17’s own IP was responsible for an impressive 41% of total revenues (up from 22% in 2021).
Headcount rose strongly from 265 to 392, including 53 who joined from acquisitions.
Outlook - lots of detail provided on new titles, and a reminder that acquisition opportunities continue to be studied.
My view - there’s no change to my view on this one. Last time (January), I was neutral, saying that I liked the company but that it was fairly valued.
The market cap now is around the same level, and it is going through a CEO change. So I probably like it a little less than I did in January. That said, if you are willing to allow those £18m of adjustments to the profit figures, then the shares do not look so expensive.
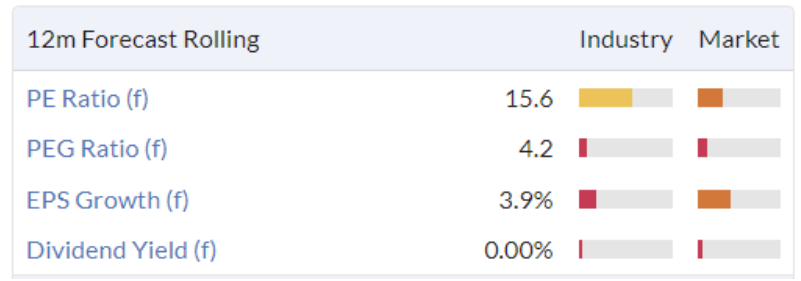
The StockReport does not take a strong view on it, either:
S&U (LON:SUS)
Share price: £23.50 (-2%)
Market cap: £285m
We covered the full-year trading statement from this lender last month. Yesterday saw the release of its full-year results.
Financial highlights for FY January 2023:
Revenue +17% to £103m
PBT down 12% to £41.4m
Net receivables +30% to £421m
Net borrowings £192m (last year: £114m).
These numbers alone tell you that a lot is happening at S&U: huge growth in the loan book, a significant increase in borrowings to help fund this, but profits reversing year-on-year.
The company explains that the prior year’s profits were abnormally high, and that it considers these latest results to represent the highest “normalised” profits in S&U’s history:
The profit for [FY January 2022] was enhanced by a lower than normal loan loss provision charge which reflected the lower use of impairment provisions made in the previous Covid-affected financial year. The average annual profit before tax in the two pandemic years to 31 January 2022 was £32.6m.
The property bridging division saw a small increase in PBT, with only one tiny impairment suffered despite receivables almost doubling to £114m.
The motor finance division saw a decrease in PBT (from £44m to £37m).
Within this division, the impairment charge ticked up to £13m. Arguably, that’s still an excellent result given a year-end receivables book of over £300m. Indeed, collections remain strong at 93.6%, marginally higher than they were a year ago.
Industry comments - there are mixed trends in the car market, although they mostly sound positive for S&U:
Overall used cars sales have not yet recovered to pre-Covid levels
Inflation has cooled as supply has increased; used car prices now only up by c. 3% year-on-year
Long-term trend is for used car prices to increase and for more people to finance their used car purchase
“Near prime customers are being rationed and restricted” by the mainstream - this gives S&U its opportunity.
Interest rates/gearing
S&U is now more leveraged than usual, but they say they are ready for higher rates:
A rapidly increased Bank Rate has been budgeted for, not only in our usual budgets but in our longer-term projections. Current signs hint that such a view might happily prove conservative.
Gearing is now 85.5% (calculated as net borrowings over equity). This is up from 54.9%.
Checking the balance sheet myself, I see that almost half of the company’s assets are now financed by liabilities. This is up from 37% a year ago.
It’s a more aggressive stance than usual, but I would argue that it’s a safer model than what we usually see in this industry.
Trading update/outlook: “Current trading is good”.
My view
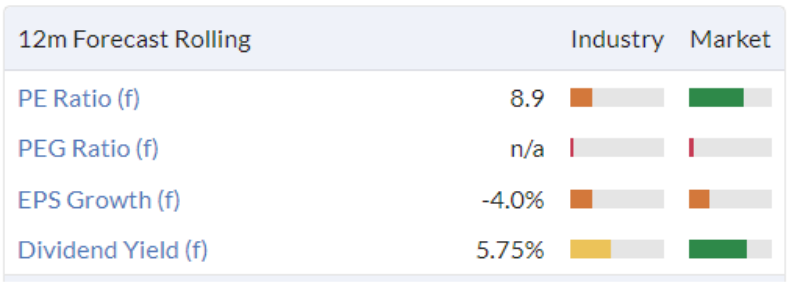
The valuation has ticked higher since last time we looked at this. However, based on the latest figures, the price to book value is still only c. 1.3x. I continue to view this as an attractive valuation for a lender that’s as good as this one is.
Strix (LON:KETL)
Share price: 93.8p (+6%)
Market cap: £205m
The market likes these results, although the headline numbers are poor as expected:
Revenues down 10% to £107m
Operating profit down 23% to £26m
PBT down 31% to £22m
The fall in revenue was “driven predominantly by a reduction in Kettle Controls due to market environment”. Global market share for kettle controls is maintained at 56% if you exclude Russia and nearby territories (if you include Russia, the company has seen a reduction in global market share).
Overall strategic highlights sound positive - the company appears to be happy with the integration and opportunities provided by Billi.
CEO comment:
"Following a period of uncertainty across a number of Strix's key export markets in Q4, recent sales data in 2023 indicates some green shoots are appearing and the path to a return of growth is opening across all segments.
The successful integration of Billi will propel Strix into a new growth phase, further diversifying away from the core Kettle Controls business with strong potential for greater top line growth and improved margins going forward.”
Net debt (excluding leases) rises from £51m to £87m. The company reduces its dividend in order to prioritise debt reduction instead.
Net debt/EBITDA is 2.2x based on the company’s calculation of trailing EBITDA. The plan is to get net debt/EBITDA below 2.0x during 2023 and below 1.5x during 2024.
I’m relieved to read an unusual promise from management, suggesting they are serious about paying down this debt: “there will be no further M&A activity or investment into new factory builds, with significantly reduced capex and working capital over the medium term”.
Outlook - kettle sales through an online retailer (Amazon?) grew 17% in January vs. the same period last year. There are “signs of a pipeline refill”.
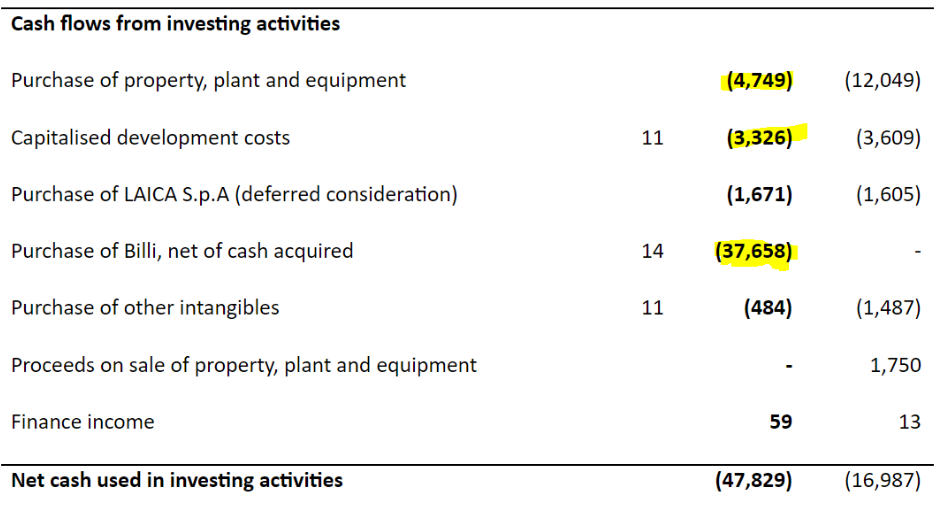
Cash flow statement is skewed by the Billi acquisition (£38m cost). The company also capitalises a few million pounds of development costs each year. At least the capex bill declined:
My view
I’m tempted to give this one a red mark, but I’ll stay neutral on the basis that management have promised to get cash flow under control with some clear promises: no more M&A, and no more new factory builds.
If they do that, then the promising cash flow from operations (c. £23m this year) can potentially start to take a bite out of the debt pile.
Remember that this company is registered in the Isle of Man, so it is not the typical domestic stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
This post has Forterra (LON:FORT) tagged. Am I repeatedly missing the article location is or is it not included?
It is mentioned under the Michelmersh Brick Holdings (LON:MBH) report.
Ah yeah seen. Cheers rusty
Paul
Belvoir (LON:BLV)
Many thanks for the time you took to do the podcast. Impressed that you deliberately avoided repeating the IMC content and asked some more detailed and probing questions. Loved the one about Trustpilot reviews and was impressed by his reasoned reply.
Have to admit the CEO came across very well - down to earth and not in the least rampy - very knowledgeable about the business - had a lot of facts at his fingertips.
I'm going to do some further research.
Thanks again.
Phil
Thanks Phil, I really appreciate the feedback re my Belvoir (LON:BLV) CEO interview. It does take a lot of background work to set them up, and not just repeat other presentations, so I'm really happy that you recognised that. There's always got to be one tough question, delivered directly!!
Hostmore
Rockwood strategic building a stake
Always worth keeping an eye on Richard Staveley and Christopher MIlls .
Must think it’s a bargain basement turnaround opportunity.
I think a lot of readers caught such a cold probably everyone wants to run a mile .
Re Christopher Mills & Hostmore. My main worry would be that he tries to do a deal with the banks, and dilute ordinary shareholders down to a negligible amount. So not necessarily a saviour for small shareholders. Look what happened at Fulcrum Utility Services (LON:FCRM)
Paul
Good point on Hostmore / Mills .
I looked at fulcrum in great detail a while ago even talking to Jonathon Bayford one of the main investors and the CEO.
Dodged a bullet there for sure and there was a tangible lack of asset backing and it was clear Bayford and Mills were very much looking after themselves only .
I guess your right that Hostmore is also loaded with debt and at risk .
I think going forward I need to apply “risk of dilution” sense check with the likes of Mills on board .
I’m in Titon too after Rockwood took there stake but that’s a 16 or 17 million asset value with cash for a 7 ish million valuation so safe from a smash and grab by those boots filling major shareholders who ultimately don’t care about us minorities .
Strix (LON:KETL)
Graham - thanks for your report. Regarding the M&A 'spree' I think it is worth remembering that the most recent addition, Billi, which has not helped net debt, was opportunistic - seen as a bargain when competition authorities required it to be divested before a much bigger takeover could go through.
A reminder that if anyone wants to ask a question about that net debt or whatever the company is doing a presentation on Friday. Details and registration link here: https://www.londonstockexchang...
Interactive Investor are saying that I cannot trade in tinyBuild (LON:TBLD) OR Somero Enterprises (LON:SOM) without completing a W8BEN form because they are US securities. Surely this is wrong because they are traded in London pounds sterling. Do subscribers get the same treatment from other UK brokers? Can anyone name a UK broker that does not require this?
Not sure, but why not complete one? Normally straightforward to complete online or is with other providers. I do for other reasons and not difficult.
You need a W8BEN for Somero Enterprises (LON:SOM), the dividend is subject US tax, without the W8BEN you will lose 30% of the dividend due ti US tax. With the form you will lose 15% or nothing if within a SIPP and the SIPP provider reclaims it. Probably same for tinyBuild (LON:TBLD).
I think it will be the same for all uk brokers. Does not take long to do and it lasts 3 years.
I bought Somero this morning on AJ Bell. I was asked to complete a W8-BEN form which took about a minute to complete. I was surprised needing to do this but figured it is because it is a US stock being traded in London? I would think it will be the same for all brokers?
Thank you for all your replies. I will complete the form and then I can hold these shares in my ISA.
If you have a SIPP you should consider putting Somero Enterprises (LON:SOM) or any US stock in there, saves 15% of dividend tax.
I have just bought tinyBuild (LON:TBLD) at 50.8p. Investor's Chronicle made a buy recommendation on them on 30th Dec 2022 at 112p. I analysed them and found that the share price kept going down due to a big seller in the market. So I put them on my watchlist. I am hoping that today's results will mark the turning point at which the share price starts increasing again.
IG markets
Paul Scott - I'm not sure you are correct re Tinybuild - but happy to be corrected. Sure the reversal (reduction) of the deferred earnout creditor would increase operating profit - as this payment is no longer required, but this is supposedly offset by a write off of the intangible asset which would have the opposite impact on operating profit - so should be broadly neutral as per the description in the operating profit note - bit misleading to suggest $11.1m to the negative (looks broadly neutral based on description)? Not questioning your ability - rather my understanding - could you clarify? Would be appreciated.
Hi drkelly1975,
Paul Scott - I'm not sure you are correct re Tinybuild - but happy to be corrected. Sure the reversal (reduction) of the deferred earnout creditor would increase operating profit - as this payment is no longer required, but this is supposedly offset by a write off of the intangible asset which would have the opposite impact on operating profit - so should be broadly neutral as per the description in the operating profit note - bit misleading to suggest $11.1m to the negative (looks broadly neutral based on description)? Not questioning your ability - rather my understanding - could you clarify? Would be appreciated.
That's a good question, I also noted that what it said in the commentary doesn't seem to tie in with the P&L itself. So this is what I'm basing my view on, where it is very clear that most of the profit came from other income -
So the way I read that, it without the benefit of other operating income, then operating profit would have been much lower, at $4.8m.
It is confusing, I agree, as the commentary contradicts what the numbers say.
Maybe the offsetting write-off is within the $34.4m general admin costs, that might be what they're saying?
Has anyone else looked into this?
Regards, Paul.
Agree it is very confusing - and I am also a qualified accountant! It would have to be through the general admin costs - can't really be anywhere else, if indeed they are correct with their narrative. Difficult to say with certainty though.
They don't provide an analysis of general admin costs but it seems pretty clear that that does contain a corresponding impairment of $11m, since that $11m has been shown as an impairment in the intangibles note, and so must have gone thorough P&L/Income statement and general admin is the only expense figure big enough.
This is perhaps mostly clearly seen in the reconciliation of profit to adjusted EBITDA.
Year ended
31 December 2022
Year ended
31 December 2021
Unaudited
Audited
$'000
$'000
Profit for the year
11,513
8,243
Income tax expense
4,417
4,281
Finance costs
73
8
Finance income
(80)
-
Share-based payment expenses
1,726
2,452
Amortisation of purchased intellectual property, brands and customer relationships
3,999
1,662
Depreciation of property, plant and equipment
747
117
Impairment of intangible assets
11,075
IPO related costs
-
4,588
Ukraine related costs
1,678
Acquisition costs
329
888
Other operating income
(11,122)
-
Adjusted EBITDA
24,355
22,239
Worth noting that they have capitalised a lot of development expenditure this year. Should mean a lot of growth to come - unless they have to write it all off!
The CEO's statement is worth a read, both to explain their decentralised approach, which is unconventional, and for bits like this:
"And I'm happy we said no to most "hyped" opportunities, such as going into social games a decade ago, all the crypto-esque scams, selling JPGs, and always stayed course."
A tech CEO who is sceptical of the crypto market gets my money!
I have a small position, as it is definitely speculative.
Seeing Machines (LON:SEE) crikey - more buys from directors. CEO has started to add to his position in last few days. CFO (new) has bought a chunk more. He has now gone from nothing to over 6m shares. NED has been buying a load. Not insignificant amounts either - I count something like 6.5m shares in the last week so around £400k worth.
Seems the market and the directors have completely different opinions. Hopefully the directors know more.
I see it too and yet the SP still down. What is going on?
Hi Raleigh4343 - yeah, I don't think retail investors understand Seeing Machines (LON:SEE) or actually how much of a moat it has built itself over the last few years. They only see a loss making, jam tomorrow share and as a long duration asset is under pressure. I get that - I felt much the same way until I listened much more carefully to what is going on.
The directors obviously understand it much better and they see where they are in the process and how much value will be created in the future. The broker thinks it is worth 21p which is about 4* current prices not that I pay much attention to broker targets.
They are debt free with lots of net cash and business plan is fully funded, so no real risk to the balance sheet or shareholder dilution. There is also an under appreciation by retail investors of the product which is heavily IP protected, will be mandated in most vehicles (cars, lorries, mining equipment, planes, trains) either now or in the coming few years and there are few credible competitors. Their main rival in the automobile space is winning about 30% of new RFPs by volume whereas Seeing Machines (LON:SEE) is winning 70%. I think that tells you which is better. Nonetheless even at a 50% market share the annual volumes will be enormous. The moat comes about because as we all know, to embed the tech into a new model of car is 7-10 years. Seeing Machines (LON:SEE) have been in this process for the last decade so whilst cars are now rolling off the production line with Seeing Machines (LON:SEE) technology embedded in the hundreds of thousands no-one is going to suddenly steal this business away. It's yours for the life of the model. In Europe to get a 4 or 5* NCAP rating you now have to have this driver tech included as standard so it is becoming regulatory mandated. They have years worth of data from their Guardian product (in mining machinery) to show it works, so from a car manufacturer perspective you will always buy this ahead of something newer or inferior for the simple reason of avoiding recalls or fines if it fails. The same will be true for the aviation industry where regulation will be even tighter. These are the reasons you will never have a cheap iPhone camera replacement as someone suggested.
Anyway - investors don't care at the moment, which is why the directors are loading up. They expect to make a lot of money over the next 5 years whereas retail is all about the next 5 minutes.
It is what it is....as Paul Hill says....."Patience equals profits"
Regarding tinyBuild (LON:TBLD) results, I'm interested to know how some of our more knowledgable and financially literate subscribers interpret some of the CFO's comments today:
"The $11.1m writedown relating to Versus Evil and Red Cerberus is offset by the decrease in contingent consideration ($11.1m other operating profit), resulting in no material impact on operating profit."
Is that an accounting sleight of hand or nothing to be concerned about?
Other things I noted are that net cash decreased to $26.5m from $48.8m whilst Capitalised software development costs, increased from $15.1m to $35.8m in 2022.
I'm not an accountant and struggle to understand if these are significant - my instinct is that the figures are being massaged to suit the required narrative. I'd be grateful for any informed insight.
Was wondering why Argentex (LON:AGFX) had been left behind after Equals (LON:EQLS) and Alpha results as would have imagined a good read across maybe heading into April. But interesting to see that someone bought 53,000 of them this morning at 124.5p in what appears to be a clearly worked order. Interesting
Medica has produced some reports today. I wonder if they are worth a discussion? The headline results seem good, and it seems an interesting niche; but I have not delved further. I hold.
Can't help but like them. Results were good. Net cash expected to rise dramatically to £25m over next 12-24 months which is 15% of market cap. Business is growing nicely with decent diversification now given that Ireland and US is growing strongly, so not just tied to NHS.
Cash generative and sitting on a PE of 11.5 dropping to sub 10 in FY25 (strip out cash and that drops to 8*) in what should be a steadily growing and stable market feels like the wrong price. Divi is only 2% but is still something.
Hi Paul, have I missed your review/thoughts on Synthomer (LON:SYNT) final results? Many thanks
No sorry, we both conked out yesterday, and didn't cover lots of stuff. If there's anything exceptional (e.g. not just in line with exps) then do flag it, and I'll revisit tomorrow or Friday.
Thanks Paul for the write up of Michelmersh Brick Holdings (LON:MBH). I'm a fan of MBH, but not a fan of the brick industry as a whole right now.
I've been tracking the government's brick deliveries statistics and the data from that last few months has been bad (see chart below). Presumably from big developers suspending activity in the wake of economic outlook / interest rate rises. Should get Feb-23 data in early April.
MBH management seems quite bullish regarding their outlook, but if the current trend persists I can't see how they won't be affected.
nice piece of research!
Thanks ar7268, very interesting. I hold Forterra (LON:FORT) and one of their investment theses is that with their additional UK capacity, then UK bricks will be substituted for European bricks. Do you know whether there are any stats on imported bricks?
Also given your comment on the brick industry, could you share your insights as why you prefer Michelmersh Brick Holdings (LON:MBH) to Forterra (LON:FORT)
In answer to my own question, I followed the source in ar7268's note, which is https://assets.publishing.serv.... I also downloaded the underlying data https://www.data.gov.uk/datase... and imports from EU are just annual, so not much use and in value, rather than bricks. Unfortunately information on the price of bricks is also confidential, so no use there either, but what is interesting is that stocks of bricks has increased substantially to 341 million bricks at the end of January 2023, highest since 2019. So I would guess that the manufacturers have been producing more than they have been delivered and building their overheads into stockholding. At the current rate of deliveries, they have about 3-4 months of stock, compared to the more usual 1-2 months
So it could be a rocky 12 months, which is in line with the p/e's in this sector.
Michelmersh Brick Holdings (LON:MBH)
First, many thanks to both ar7268 and martinck1 for taking the time to share that information on Bricks.
It was very much appreciated.
---
The below is from the Forterra (LON:FORT) results a few weeks ago:
"Total UK brick consumption in 2022 is estimated at 2.5bn bricks of which a record 570m (representing 23% of total market demand) were satisfied by imports due to a continuing shortfall in domestic production capacity...
...in the near term, the ability to displace imported bricks will insulate ourselves and other UK brick manufacturers from some of the fall in demand as our customers switch from imports to domestically manufactured products which are expected to become more freely available.
...We increased the majority of our brick prices by a cumulative 50% during the year"
And this from Michelmersh Brick Holdings (LON:MBH) today:
"Despite the more cautious outlook in the UK and European economies, it is important to note that the production capacity of the UK and European brick manufacturing industry remains well balanced when set against wider demand and as an industry we still have record low inventory volumes of bricks. "
Martin, thank you for pointing out the 341m January-2022 brick inventory figure.
Because the last few years have been a bit crazy I went back and checked Brick volumes in January 2020 (it can be found in the January 2020 file: https://www.data.gov.uk/datase...) when volumes were 443m.
So maybe that 341m figure isn't that much of a worry, historically speaking? This assumption would certainly tie in the comment above from Michelmersh Brick Holdings (LON:MBH) highlighting low brick inventory levels.
---
I should add that I hold Michelmersh Brick Holdings (LON:MBH) and thought the results today were excellent.
Happy holder
A
Loving the quality of the discussion here. I should have said "I'm a fan of MBH, but not the macro situation for brick demand.." because as pointed out above Forterras recent results have been excellent, my only preference for MBH vs Forterra / Ibstock is MBH (current) small size and larger room for growth imo.
MBH is on my watch list for all the reasons mentioned above, however (as you can see) I'm tracking the macro situation before buying. I'm uncertain how that declining trend translates into pricing power, so I'm waiting to hear a few more company updates/interims befores buying.
Re £KETL
I have taken a small position in this co, Strix, that probably has a little too much debt but once this is under control looks a good long term prospect. Especially with the recent Billi aquisition. Today announces EBITDA down c 20%
https://www.stockopedia.com/sh...
and PBT slightly below forecasts, PAT slightly above. At 7.59am I therefore adopted the brace position only to find that when I opened my eyes the sp was up 6.5p c 7%. What was that old Chinese proverb? Expect the unexpected.......?
I held Strix (LON:KETL) a while back post the profit warning and sold with a small profit before the last trading update (annoyingly as it went up and hit my target!!). I like the business but taking on that level of debt in todays environment doesn't give them much room for manoeuvre and was my main cause for twitching over the sell button.
That said todays announcement I thought was good. they have reduced the dividend and are focussing on debt reduction to 1.5* ebitda so capital allocation policy is at least now correct in my opinion. However, there is still a long way to go to achieve that and I'm a bit unclear on how much of cash generated can go to paying off debt, even after having gone through the cashflow statement. We also don't know what Billi generates. It feels to me as though £20m+ p/a should be achievable and that would bring debt down to maybe £40-45m after 2 years. That would be much better but still not great. I'd like to see signs of this happening before committing to the stock again but on my watchlist.
Thanks for that David and I'm inclined to agree that debt levels are currently too high so the cut in divi and management undertaking to reduce net debt is welcome.
As far as Billi is concerned most recent report states that;
In the 12 months ending 31 December 2022, Billi is expected to
generate revenue of c.£43.7m and adjusted EBITDA of c.£10.2m
remember aquisition only completed in Nov '22 and
Billi has a successful history of growth, with double digit revenue
CAGR over the past 5 years and is highly cash generative, delivering cash
conversion of c.88%
Add in the new factory that Strix has now completed all Capex on and I guess you have, hopefully, the classic Contrarian stock. As debt reduces from generated cash flows then everything else starts to look a lot more rosy and the sp should respond accordingly. Although I only hold a small position I still think this is achievable especially given the higher margins and room for growth within Billi.
Ps How does the ticker thing work again? Anyone? Please....
Press '@' then enter stock ticker / name and select the stock in the pop up box.
Thanks for that.
Thanks - thats helpful. so we can assume operating cashflow is circa £30m for the combined business. After some tax (IoM based so tax isn't a lot across the group), divi's and presumably some necessary maintenance capex I guess my £20m number for debt reduction annually isn't far off. As long as they have no more mishaps / further drop offs in demand then that feels like it is borderline ok and net debt would be in the £40m region a couple of years out which would be more comfortable.
our numbers on Strix (LON:KETL) are here if helpful https://www.equitydevelopment....
Strix (LON:KETL) Interestingly looking at both Equity Dev's and Zeus' forecasts there appears to be a possible revenue underestimate - unless I am missing something? Assuming the Strix' part of the business has a flat year and adding in Billi revenue you almost reach the projected revenue target for FY 2023 and yet these same forecasts talk of Strix in these terms
....evidence of pipelines starting to refill
....green shoots of recovery
We expect FY23 to represent an inflection point for the kettle control business
I'm also assuming the new factory is more productive and more efficient (reasonable?) thereby helping to balance out some of the increased finance charges. Let's wait and see but an earnings upgrade in the next 12 months is at least a possibility here?
TinyBuild prelim results look spot on to me! If that can be reviewed by Paul I'd be chuffed.
Outlook for UP Global Sourcing Holdings (LON:UPGS) is merely in line so Paul and Graham may want to focus on other names, but I like the shares at this morning’s level, so any thoughts would be appreciated, thanks.
UP Global Sourcing Holdings (LON:UPGS)
Company says its online sales have increased significantly, improving overall gross margins, whereas the retail business has had a bit of destocking post Covid, and is down circa 6%. Not chasing inflation with price increases to remain competitive
So, in trading terms, a bit of a see saw but keeping steady'ish in H1
It will be interesting to see what happens in the German market they are trying to expand in, given Germany's economy is starting to wobble a bit. Could be good for them as they are offering a lower cost product as I understand it?
Dividend is increased. Not sure if previously Paul took a slightly worried view about the idea of their dividend approach from memory.
I hold
UPGS have managed a challenging H1 very well in my view. Headwind of retailer de-stocking across the board which has been mitigated by an unconstrained internet sales operation. It looks set to get back to growth in the next financial year. Debt levels sensibly being managed down after the excellent Salter deal.
RM (LON:RM.) well we knew these results would be bad thanks to the illfated IT fiasco at Consortium & they are
Some positives, including extended banking facility to July 2025
Let’s see if the CEO, Mark Cook, can turn it around
I hold a small speculative position
Next (LON:NXT) results out today. I love the way this company presents its financial results. If you don't usually read them, I suggest you look, there are so many insights for other businesses.
I know its not a small cap, but as an example how to discuss a business this is top quality, including real coverage of the the problems.
Looks to me like they are are aiming to be tomorrow's landlords with an excellent route to the online market for creative retailers.
And this crazy market rewards them with a drop of about 6% !!
Well to be fair to the market, they are quite negative on next year's PBT and their eps won't be helped by the ridiculous increase in corporation tax. I don't think the market is used to honesty in forward prospects and Next usually under-promise and over deliver.
I should have that I hold Next (LON:NXT), in fact it's my largest holding.
But Next (LON:NXT) are "cautious on the outlook for its current year,
forecasting a profit decline".
I watched an interview with the CEO of Ecora on CNBC this morning . The company reported good results but the CEO scratched his head to explain why the share price has performed so badly over 1,2, 5 years.
I compared ECORA with BRWM and the latter has performed much better . Both paying good dividend.
Ecora Resources (LON:ECOR) on Investor Meet Company at 1100 this morning.
Despite their investments and name change they are still making most of their royalties from coal, which makes them uninvestable for me, maybe for others too? And their newer investments will not replace the coal money in the short term.
Yes, however it’s the high grade of coal that is essential to steel production not the low grade stuff they bung into power stations.
Despite the name change - something that I am always sceptical of - Ecora Resources (LON:ECOR) remains in transition - a work-in-progress if you will (I hold).
Even though FY22 was the last full year of coal revenues - which will step down by 50% this year and - I expect to be under 10% of NAV by the end of the year - I suspect that the market is focusing upon the current year fall in income, depressed commodity prices and the coal royalty doesn't help. Instead of looking towards FY24/25 as the Copper, Nickel, Cobalt mines on which Ecora Resources (LON:ECOR) has a royalty progress towards initial production.But that's what markets do. I don't think that there is a short cut to this, at least not one that the management team can control. Best that they stay focused upon investing in quality future royalties/streams at good value and as they approach initial production and NAV rises as the discount to revenue falls steeply - I expect the share price to follow suit in 1 to 2 years. Rising commodity prices and extension to mine life/reserves would be a bonus on top.
cheers
Mark
So...Ecora Resources (LON:ECOR) ...I'm out of the loop on this one. I looked some years ago when near 100p. I passed. I didn't like the old CEO. I also felt uncomfortable about their coal assets...not as its coal but as their rights attached in a slightly haphazard way from geographic perspective that I felt I could not forecast outcomes around and those outcomes could be very material. Obvs the coal bull hit and the returns were great. Then I'm not a fan of the shift to 'battery metals' focus. Nothing against battery metals...just don't think committing to fashion is the way for royalty company to play, and it looks possible they've overpaid for some of the fashion items.
The above is fly by banalysis based on old knowledge/prejudice...put me right
Mojo - re Ecora Resources (LON:ECOR) - No I don't think you've said anything that needs correcting - hence the currently disappointing share price.
I bought at around 100p - around 2019 was that? I should have sold quite a lot at 180p in 2022 but failed abysmally. Learning lesson. In opportunity cost.They bought some duds a few years ago. I think you're right. The jury is still out on the Voisey's Bay Cobalt stream, didn't look too clever to start with but its been better than baseline over the last 18months.
In amongst the duds they bought a 1.5% royalty on Brazil Nickel's Piaui mine together with the right to increase to 4.25% in exchange for $70m of construction funding - expected 2024. In view of forecast Nickel demand and current prices - that's quite a deal today.
New management (CEO) seems ok. Nothing special - but then I don't think management have to do anything special here. Just be competent and don't make mistakes.
Then its down to demand for Nickel and Copper? The nickel mine is the main reason I'm still holding. Though the deal with South32 on Copper looks like it will probably come good at around the same time. Whether I can hold on for that remains to be seen -I don't normally buy and sell much but a lot of other good deals around at the moment.........
cheers
Mark
Thanks
Ecora made a massive $107 million from Coal in 2022 on reduced volume. The Market knows their coal production is being phased out and this is a one off event otherwise we should have had a big pay out. they reduced the debt instead.
In the coming years the company will have no interest in Coal and instead has interest in copper, Nickel, Cobalt.
It pays good dividend and I am an investor.
Ecora pandering to the woke agenda and dumping coal is a mistake. I too am a share holder however.
My morning smallcap tweet: Pace setters and bed-wetters
Loopup (LON:LOOP) AFC Energy (LON:AFC) BSF Enterprise (LON:BSFA) Futura Medical (LON:FUM) Gulf Marine Services (LON:GMS) SIMEC Atlantis Energy (LON:SAE) Kromek (LON:KMK) Trakm8 Holdings (LON:TRAK) Mirriad Advertising (LON:MIRI) Versarien (LON:VRS) GSTechnologies (LON:GST) PayPoint (LON:PAY) Surgical Innovations (LON:SUN), One Media IP (LON:OMIP), UP Global Sourcing Holdings (LON:UPGS)
◄LoopUp (LOOP)► guides FY-Dec rev c.£16.5m, above market expectations. Adj EBITDA loss c.£1m, in line. Guides FY23 rev up c.25%, positive adj EBITDA. Marginal rev growth in FY24 as Cloud Telephony growth overtakes the decline in Meetings. [SP=2.95 Cap=6m]
◄AFC Energy (AFC)► delivered and validated its first cumulative 100kW Liquid Cooled Fuel Cell with partner ABB E-mobility. "ABB E-mobility has expressed an intention to invest a further £2m into AFC Energy by way of a subscription for shares in the Company replacing the subsequent payments due under the original contract." [SP=20 Cap=148m]
◄BSF Enterprise (BSFA)► £2.9m placing at 17p, a 16% discount, to continue development. Tons of warrants too. [SP=19.83 Cap=17m]
◄Futura Medical (FUM)► a full response to questions plus requested confirmatory data has been resubmitted to the FDA. Will it be enough? Ay, there's the rub. [SP=42.5 Cap=122m]
◄Gulf Marine Services (GMS)► contracts for one of its small class vessels spanning 272 days. [SP=4.69 Cap=48m]. I hold.
◄SIMEC Atlantis Energy (SAE)► holders have approved the amendment to the 2018 debenture deed in the nick of time. Will extend maturity from end Mar to 2024. Hiked int rate to 10%. Good progress is being made on the additional 120MW Uskmouth BESS project. [SP=1.25 Cap=9m]
◄Kromek (KMK)► repeat orders of $1.1m in medical imaging. [SP=6.54 Cap=28m]
◄Trakm8 (TRAK)► 1 yr contract extension from Sainsbury's. No £££. [SP=13.04 Cap=7m]
◄Mirriad Advertising (MIRI)► Strategic review: interested parties have been invited to put forward non-binding indicative proposals by early April. [SP=1.52 Cap=4m]
◄Versarien (VRS)► AGM stmt: engages experienced strategy and turnaround specialist. NEDs will waive any remuneration indefinitely. Execs may take pay cut. Amazing what can be done now Ricketts has 'resigned'. Desperate for funds eg disposals, potentially available grant income, possible interest from strategic investors or equity. [SP=3.07 Cap=7m]
◄GSTechnologies (GST)► cancels remainder ($800k) of convertible loan facility, having reviewed the capital requirements. [SP=0.36 Cap=6m]
◄PayPoint (PAY)► received ‘letter before action’ from a small number of market participants relating to the issues addressed by these commitments to address the concerns raised in Ofgem’s Statement of Objections (Sept 2020). Co intends to respond robustly whilst continuing to take appropriate legal advice. [SP=461.5 Cap=337m]
◄Surgical Innovations (SUN)► FY-Dec rev £11.34m slightly ahead of market expectations. I make that 0.35% ahead of co's guidance so slight indeed. "Order book is looking positive." [SP=1.83 Cap=17m]
In line: OMIP, UPGS
Sparkling (Ho Ho) results from Chapel Down (OFEX:CDGP) today, ebitda up 30%, and ambitious plans to double revenues 2021-2026 reconfirmed. Much extra acres going under vine, and gross margins edging up nicely. Sort of stock that tickles Paul's taste buds? Illiquid stock for a liquid product.
Seems a play on polarisation of wealth, affluent Brexiteers celebrating Englishness. The opportunity cost of a bottle of English sparkling wine nowadays being a really good quality still white wine, or why not pay a bit more for champagne? Unless they are biased, those high up the drinks trade tell me English sparkling wine just doesn't compare with champagne; so why would you buy ESW unless a proud Brit?
In the not too distant future, this could be one reason
https://metro.co.uk/2022/10/31...
Quite so. Whilst not wanting to get into an argument with Ed on a) Brexit or b) viticulture, it is a given that climate change is making the South Downs better able to grow chardonnay and pinot meunier, so able to compete directly with champagne (rather than using bacchus), and secondly that the big French houses are looking for English acreage or assets.
Agreed grumpy5
Unless political views are directly relevant to the investment case and/or macro factors they are best parked elsewhere.
Agreed Helvellyn.
Unless political views are directly relevant to the investment case and/or macro factors they are best parked elsewhere.
Disagree. As a wine collector and someone who enjoys drinking wine, many of the British brand sparkling wines are easily comparable to entry level Grand Marque champagne. I am not going to comment on individual brands, but as a general rule - easily comparable quality wise - taste is very individual. I enjoy chardonnay driven champagne (particularly Blanc de Blanc (100% Chardonnay) and the UK offerings are high quality. Now at the top end (deluxe Cuvees) such as Taittinger Comte, DP or Cristal - the UK doesn't produce much that is comparable currently. Those are however wines costing upwards of £150 a bottle and are essentially Halo products in those ranges, costing well above the NV and Vintage offerings that most purchase. Don't rely purely on what the drinks trade tells you - a lot are in the pockets of the large (profitable, cash rich) champagne houses. The French do an awful lot to protect the champagne designation and have concerns with respect to the British brands - the UK is one of the largest external markets for champagne globally, not that far behind the USA. Both Taittinger and Pommery have recently purchased estates in Southern England to produce their own English wine. I used to be a huge Taittinger fan (it was my wedding champagne) and still am, but I also find Nyetimber to be comparable in quality and I am about 50/50 in terms of what I purchase to drink. Investment is a different game and I stick to Deluxe Cuvees in only the best years - those are the only ones that really appreciate as such. That may well however change.
ps champagne is not more expensive than English sparkling wine - if so you're comparing the wrong wines!!
The calculation for Chapel Down (OFEX:CDGP) becomes completely different if you hold 2000 shares or more and get a 33% discount (I do). Also I believe the wine trade is overdoing its snooty attitude, having a huge investment in protecting its carefully nurtured champagne brands.
Although appalled by Brexit I don’t mind being a proud Brit and applauding a successful local business. I also very much enjoy drinking the product!
This seems like good value - 2000 shares is only c£800, so you get discounts (all listed on the chapel down (Chapel Down (OFEX:CDGP) ) website here - https://www.chapeldown.com/pag... - along with any rise in share price.
Not long until the new ISA allowance year starts (can you hold aquis shares in an ISA?)
On a similar (but more expensive) note, hold 100 or more shares in Next (LON:NXT) and you get a 25% voucher once a year.
Dave
Thanks for sharing the link to the CDGP shareholder perks! How did I not know this - going to take the offer of a free annual tour for 4 people, plus discounts on wines and dining there!
I had a quick skim of the Chapel Down (OFEX:CDGP) results, nothing much new not known from previous news, momentum still going strong.
The key interesting news is that Lord Spencer, near 30% shareholder, is personally joining the board himself. He is a billionaire that made his money with NEX Group. I note that Samantha Wren, the CEO of IPGL, is already on the board. So that gives him more control.
He is also invested in a few other wine businesses, such a Bordeaux Index. So clearly not an amateur when it comes to this area. He's had a stake in CDGP for many, many years. So the fact that he now thinks it is worth his time to be more hands on, is telling. Given that he has quite vast business and investment interests (look at his House of Parliament declaration of shareholdings!)
I somewhat regretted top-slicing my holdings at 39p (albeit short term the right call as it slid right back down to 32-33p and now still below), as I think once these results are digested it could continue upwards to nearer 45-50p. I am only planning to digest the results this weekend, and will make a call then whether to top-up some more.
(I hold in the Boon Fund)
FYI - the Stocko team are stumped on getting updated prices for Chapel Down (OFEX:CDGP) . Been stuck at the same price since Jan, despite raising a ticket a month or so ago. So check other sites for the updated price of this share.
The chart data is fine. Just the headline price, and the trading details (last trade = 27 Jan...!)
I'm surprised it hasn't been fixed yet. Anyone know the Product Manager internally to have a word? Surely pricing accuracy and updating is a core feature of a platform like Stockopedia? I would have thought it would be a P1 bug.
Strix (LON:KETL) prelims this morning. After the PW (30/11) about disruption from OEMs in China causing them to put stock into warehouse they say there were signs of recovery in Jan. and Feb. Equity Development forecast some recovery this year with greater increase in 2024 https://www.equitydevelopment....
The only positive figure in their summary is net debt +71% and I think they need to concentrate on getting that down.
Morning all,
Decent results from tinyBuild (LON:TBLD) drop looks way over done?
Re tinyBuild (LON:TBLD) (LON:TBLD), a key part of the investment decision is understanding the forthcoming dilution of shareholders from deferred consideration. The below article explains it far better than I can. All the best. Will
https://www.firmreturns.com/ti...
Probably too small a company to cover here, but Aeorema Communications (LON:AEO) decent interims today & a very bullish outlook statement. Big cash position in comparison to market cap too. Any holders or views on this one?
Aeorema Communications (LON:AEO) , the company has a good multi year growth record, is focused on sustainable, and yes talks confidently of the future. purifies this year could get close to £1m and to me the attraction is continuing growth and then profits get growing more aggressively as the fixed costs of a business and PLC are covered.
the chart looks to have excellent multi year momentum.
like any micro cap, maybe the low rating is justified until more people are convinced of its growth.
re CASH - the increase to >£3m. its slightly misusing, as trade creditors have also increased. i think a net CASH of c.£1.5m is more accurate for ongoing.
i hold
Revenue growth is very strong but gross margins are down and admin costs up, as they invest in the business.
The 27% growth in pre-tax profits looks very credible.
Profits after tax and EPS comparisons with the previous year are distorted by a tax charge this year vs. a tax credit in the previous year
The comment that '... We are very confident about the outlook for the remainder of the 2023 financial year.' made half way through H2 gives great confidence for the full year results and the strong cash position is comforting
Maybe if I get in early I might get these on your lists Paul and Graham. Michelmersch Brick, surely undervalued after strong results? Also good TU from UP Global Source Holdings, a dying dog still barking in Loop Up (another one I got badly wrong) and our only small gold play Shanta gold after a tip from our accountant who like us, is well retired!
Great results and good outlook too. Is there a read across to Brickability (LON:BRCK) which is even cheaper ? (p/e of 6x)