Small Cap Value Report (Weds 3 April 2024) - SDRY, REDX, TPT, PEEL, CLX, HFG

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
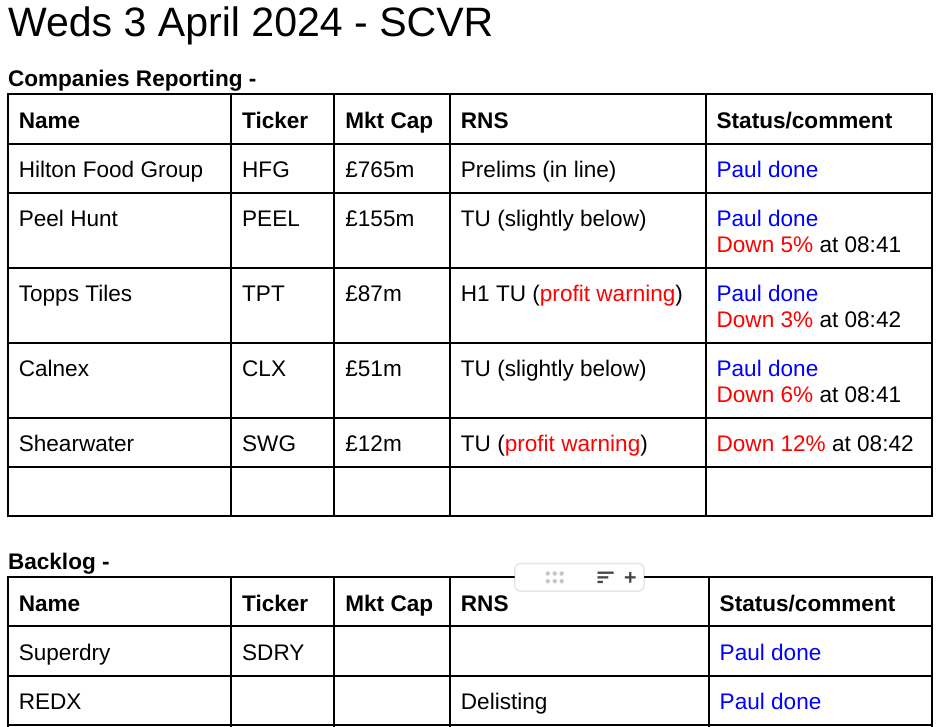
Summaries of main sections
Paul's section:
Superdry (LON:SDRY)
Down 53% y’day to 13p (£13m) - Dunkerton not bidding - Paul - RED
As regulars here will know, we’ve been very negative about SDRY’s chances of a turnaround or indeed survival, for a long time (I gave up counting after reading the last 9 reviews of it here, all negative).
As mentioned in Thursday’s SCVR, the bombshell announcement came from founder/CEO Julian Dunkerton, saying he did not intend bidding for the company. Far worse though, it also included this bit -
… is in discussions with the Company in respect of alternative structures, including a possible equity raise fully underwritten by Julian Dunkerton, which would provide additional liquidity headroom for the Company's turnaround plan. It is expected that any equity raise would be at a very material discount to the current share price, require shareholder approval of a Rule 9 waiver (as referred in Note 1 of the Notes on Dispensations from Rule 9 of the Code) and be conditional on a de-listing of the Company. A further announcement will be made as appropriate. There can be no certainty that a transaction with Julian Dunkerton will be agreed.
So there you have it - a deeply discounted fundraise, conditional on a delisting. That makes SDRY shares uninvestable for many investors, who can’t or don’t want to own shares in a private company.
It’s really now a question of how long SDRY can limp on for? Suppliers can see the share price, and read the news, so why would anyone now send any more deliveries into SDRY, knowing that as an unsecured creditor they’ll get nothing once it goes into administration? I can’t see trade credit insurers touching it now either. So I imagine insolvency could be quite rapid now, but it doesn’t really matter, as existing equity is likely to be wiped out in an emergency fundraise even if they manage to keep trading.
The key thing with situations like this, is not to throw good money after bad by averaging down on a situation that has gone disastrously wrong, in the forlorn hope of recovering previous losses. I hope nobody here got caught on this one, if so - why, when the risk was so obvious???!
Redx Pharma (LON:REDX)
Down 66% to 6.5p y’day (£25m) - Proposed Delisting - Paul - GREY (delisting flag)
We’ve not written about this share here since 2017, as the numbers were always so bad they didn’t justify any mentions.
The announcement yesterday from REDX saying it intends delisting, follows the usual format - telling us that the company has a great track record (despite making massive losses every year), and that AIM is of no use to them as they cant tap anyone for any more cash to burn.
The funding mugs are now employed in private finance markets -
The Board believes that as a private company we can access a broader universe of specialty investors and, accordingly, a larger quantum of future funding required to execute our strategy and maximise our value in the interests of all our Shareholders.
Paul’s view - AIM has never been the right place for speculative, cash burning jam tomorrow companies. If anything, the bombed out valuations are indeed a hindrance now, as they simply highlight what a low opinion public market investors have of this type of company. Many more similar companies need to de-list, I’m all in favour a mass clearout. Let’s have a smaller market, with better quality companies.
However, given that delisting announcements usually trigger a c.50-75% crash in share price, it’s essential not to hold anything in our portfolios which is loss-making, cash burning, and running out of cash.
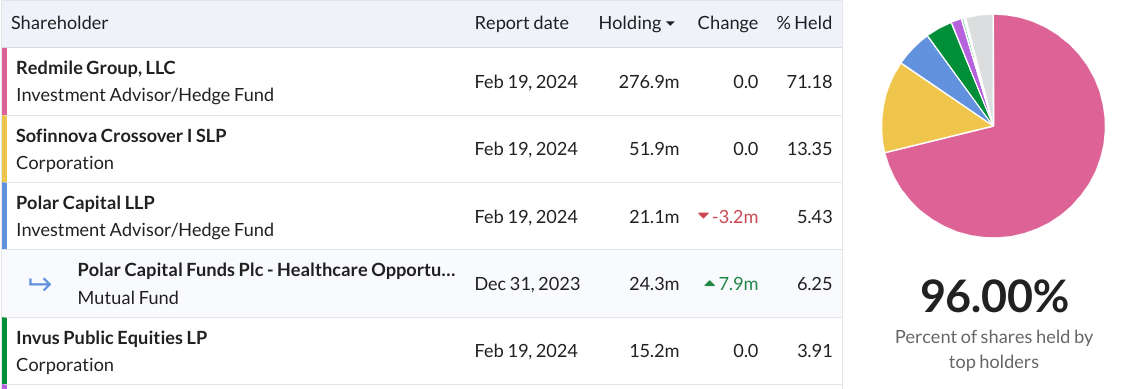
Another big red flag for potential delistings is a highly concentrated shareholder register, very much the case here at REDX -
Topps Tiles (LON:TPT)
44p (pre-market) £87m - H1 Trading Update - Paul - AMBER
Topps Tiles Plc ("Topps Group", or the "Group"), the UK's leading tile specialist, announces a trading update for the 26-week period ended 30 March 2024.
Graham looked at TPT on 4/1/2024, when it reported Q1 revenues were soft.
Brokers have been edging down forecasts in 2024 -
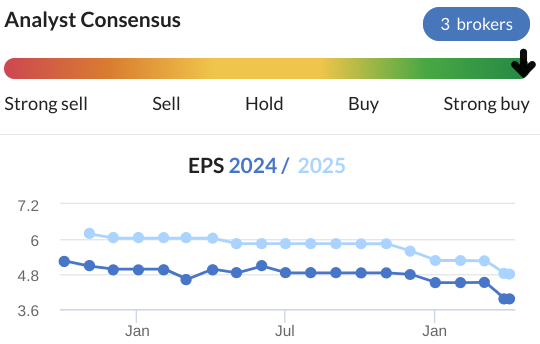
Today it says H1 revenues are down 5.9%, which is not good when so many costs (especially labour and energy) will be rising. It’s a deterioration from the -4% Q1 fall in revenues, previously reported on 4/1/2024.
Q2 was even worse, for the stores -
...like-for-like sales2 in Topps Tiles were 11.3% lower year-on-year3 in the second quarter, driven by lower footfall and volume
Gross margin was up, as expected it says.
Online growth was good.
Parkside (commercial business) improving, but only expected to trade at breakeven.
Profit warning -
…net profits were impacted by lower volumes, operating cost inflation and the impact of operational gearing, despite strong cost control throughout the period…
Group profitability in the first half of the year will be impacted by a number of factors including the weaker market, the timing of the holiday pay accrual and seasonally higher energy usage in the period. We continue to expect the Group's profits in 2024 to be weighted towards the second half as indicated in our Q1 trading update.
Key question - how much will profit be impacted by these issues? We’re not told. At present there’s nothing on Research Tree, so I’m in the dark.
Hopefully an update note might come through, so I can quantify the problem. Until then, city insiders have an advantage in that they’ve presumably already received broker updates, but we haven’t. It’s just not a level playing field is it?
TOPT did adj EPS of 4.49p in FY 9/2023. I’d be surprised if H1 this year is above breakeven. So it’s difficult to see it achieving more than 2.0p EPS this year as a whole.
Do we value the shares on a PER basis, or write off this year as an untypical bad year, and anticipate a future earnings recovery? That’s up to each investor to decide.
UPDATE: a note from Edison has just come through, with FY 9/2024 reduced by 40% to 2.7p. It's hoping for a rebound to 4.3p next year, so personally I wouldn't want to pay more than 10x next year, so that's 43p share price - which is exactly where the price is at the time of writing, c.43p. Edison reckons the shares are undervalued, but they're paid to say that, so I'd rather rely on my own independent view!
Is it financially strong? The last balance sheet showed £20m in NTAV, although it seems to have a favourable working capital position, with trade creditors more than fully funding the inventories. Receivables and fixed assets are not large either, so overall I would say the balance sheet looks adequate, and it had £23m in net cash at 30/9/2023. Assuming that’s typical, and not window-dressed for the year end, then I’d say the finances look OK.
Paul’s opinion - the share price has only dipped slightly in early trades (writing this at 08:10), so it doesn’t seem to have panicked anyone as yet. I’m not sure why anyone would be motivated to buy today though, other than to support the share price if they’re existing holders maybe?
I’m struggling to see obvious value here. So I’ll go with AMBER.
Peel Hunt (LON:PEEL)
Down 5% to 120p (£148m) - Year End Trading Update - Paul - GREEN
Peel Hunt, a leading UK investment bank, today announces a trading update for the financial year ended 31 March 2024 ("FY24").
Peel Hunt is probably best known for its outstanding company research. MiFiD saw to it that private investors are now denied access, because they have to charge separately for research, instead of bundling it as a package for institutions & high net worth (HNW) individuals.
Company headline -
Another resilient performance in challenging market conditions
Revenue for the full year is expected to be consistent with market expectations at approximately £85.5m (FY23: £82.3m), an increase of approximately 4% year-on-year despite equity capital markets remaining challenging throughout FY24. However, this was not quite sufficient to offset cost pressures and consequently we expect to report a loss for the full year broadly in line with market expectations.
RetailBook - set up by PEEL, this looks an excellent idea, aimed to provide retail investors with access to IPOs, follow-on placings, etc, on the same terms as institutions. It sounds similar to Primary Bid. Although for me, the key question is whether the city can get its act together, and actually promote some decent quality companies at reasonable prices. I fear the many disastrous floats in recent years (2021 in particular) may have killed the London IPO golden goose. Hence many of us are extremely wary of IPOs.
RetailBook received FCA approval on 2 April, so it will be interesting to see how this useful initiative pans out.
Outlook - this might be interesting for general market info purposes -
Market trading volumes remain low and ECM issuance continues to be subdued. We expect these trends to continue until there are meaningful signs of recovery in the UK economy and fund outflows reverse.
However, we continue to be active in public M&A, with financial advisory mandates on both the buy and sell side.
Whilst IPO activity in the UK remains muted, there has been more activity in Europe and sentiment towards IPOs is improving in the UK, with investors increasingly willing to engage in relation to high quality companies.
That last bit is good news. People generally are too gloomy about the UK, and down cycles always reverse eventually because shares become too cheap. As with many things, the solution for low prices is low prices - demand naturally returns. My main worry is how many decent companies will be left in the UK market, once the Americans have finished buying up our best businesses?!
I think we need some sensible reforms for new listings - eg AIM needs to reform the rule whereby companies with a completely dominant major shareholder can float, and then do whatever they like with the company. Surely it needs a rule that (at least) 50% of the shares must be freely floating? Otherwise there’s not much in listing, as there won’t be any liquidity in the shares once they start trading. All too often promoters have chased the lucrative fees, but not given a second thought to liquidity after a company floats, leaving many clients disappointed with their listing. Look at how many are now leaving AIM in disgust, with the low liquidity and low valuations usually cited as signs of market failure (but are all too often companies' own failings that they gloss over to save face!)
Paul’s opinion - both Graham and I think this is a good time to be looking for bargains in the financial sector. Although big regulatory risks have surfaced at several companies, smashing up their valuations, so I’m less keen than I was. Who knows what future regulatory risks might be lurking?
These companies are highly cyclical, so as long as they’re not losing money hand over fist in a downturn, then recovery should see profits surge again. They can make a ton of money in bull markets too, that is providing it’s not all paid out to staff - who often seem reluctant to own shares in their employers, causing a constant headwind of sellers cashing in share options at financial sector companies.
How to value PEEL shares? That’s the tricky bit, as ironically there aren’t any forecasts!
H1 showed only a very modest loss, and the guided revenues for FY 2/2024 above is about double the H1 level, so I’m guessing we’re looking at a modest loss, which isn’t a concern to me, given how awful markets are.
The last balance sheet at 30/9/2023 shows £91m NTAV, mostly liquid capital (there are large trade receivables and creditors), so it’s very healthy, and the £148m market cap is therefore more than half solidly backed by near-cash items on the balance sheet (mostly short term receivables).
We had an amazing opportunity a few months ago to buy CMC Markets (LON:CMCX) at par with its own working capital, which combined with a good recovery in trading has caused its shares to double in price this year. I don’t see PEEL being a bargain of that extent, but once the London market comes alive again, it could demonstrate a big, operationally geared recovery in profits. PEEL floated at 228p in Sept 2021. So being asked to pay 120p now is looking more appealing. I’ve just thumbed through the AIM Admission Document, and note that PEEL was staggeringly profitable in FY 3/2021, making £74m illustrative adj PBT, more than 10x the £7.1m more normal profit pre-pandemic in FY 3/2019. So there’s an astonishingly wide range of potential profit levels. No wonder they went for an over-priced float later in 2021! Canny selling shareholders pocketed £69m in the float.
Overall, it’s tempting. Graham usually reviews PEEL and has been green in the past due to its balance sheet strength, and the recovery potential. That seems a sensible view to me too, so I’m happy to leave it at GREEN.
Calnex Solutions (LON:CLX)
Down 3% to 57p (£50m) - Trading Update - Paul - AMBER
Calnex Solutions plc (AIM: CLX), a leading provider of test and measurement solutions for the global telecommunications and cloud computing markets, provides an update on trading for the year to 31 March 2024 ("FY24") and outlook for FY25.
Results slightly below expectations -
Calnex anticipates the results for FY24 will be broadly in line with market expectations, with revenues of approximately £16.3 million and margins maintained. The Company's cost base has been adjusted, maintaining and focusing R&D spend to capitalise on the opportunities available to Calnex whilst controlling other costs. The Group's balance sheet remains strong, with cash as at 31 March 2024 of £11.9 million after investment in working capital in H2.
Cavendish has trimmed its forecasts from a £(0.1)m PBT loss, to £(0.4)m. This isn’t some jam tomorrow story stock though. Calnex was previously an attractive-looking growth company, in particular note the decent growth, and high profit margins reported in previous years. Then it all crashed in the current financial year, FY 3/2024, blamed on industry-wide factors which also clobbered the performance of Spirent Communications (LON:SPT) - which has since attracted two takeover bids.
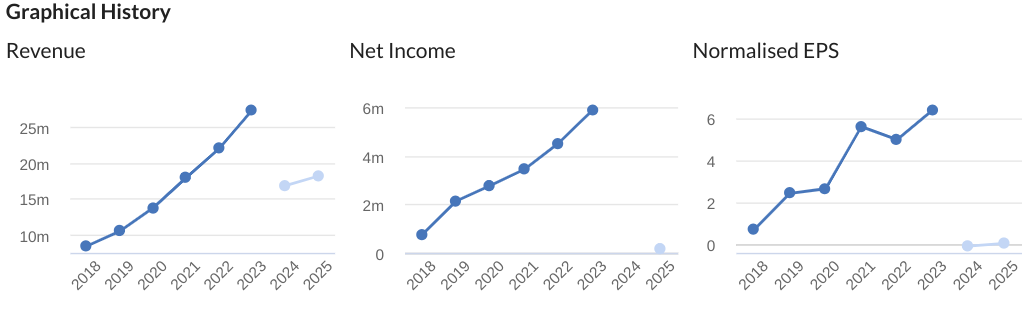
Outlook - nothing specific, other than that it feels well placed to return to growth. There’s also some technical stuff in today’s update about expanding into different markets, cloud computing, and opportunities for 5G.
Cavendish hopes for a small loss in FY 3/2024 to improve into a small profit in FY 3/2025, but nowhere near the previous levels of profitability achieved.
I don’t feel I can usefully assess what the future holds, as there isn’t really any firm information on it, and I don’t have any sector knowledge, so buying this share would just be a punt for me.
Balance sheet - is excellent. Last reported on 30 Sept 2023, it had NTAV of £13.6m, including net cash of £13.5m. Note that cash has come down to £11.9m as at 31/3/2024. Still ample, I’d say, so not a cause for concern.
Although looking at the H1 cashflow statement, it was negative at £(4.1)m, which seems a significant cash outflow considering the P&L was showing not much worse than breakeven. I see it capitalised £2.55m in R&D in H1, so it looks like the cash numbers are worse than the P&L figures. So maybe shareholders shouldn’t get too comfortable with the cash position, as it keeps dropping?
Paul’s opinion - it seems unlikely that the strong previous track record has just vanished, particularly given well-known telecoms sector problems. That said I have no way of knowing the extent, or timing, of any recovery. For that reason it would be total guesswork for me trying to value this share. It has to go into the "don’t know" tray. Given the excellent track record before this year, and the solid balance sheet, I think AMBER makes sense for me.
Hilton Food (LON:HFG)
Down 3% to 825p (£743m) - FY 12/2023 Results - Paul - AMBER
I’ve had a quick look at the 2023 results from this large food production group, but rapidly lost interest.
Revenues of £4.0bn only resulted in adj PBT of £66m (up 19% vs LY), a tiny profit margin.
I’d be looking for a transformative increase in profit margins to get me interested in this share, but the reporting broker is only expecting gradual improvement in profits in 2024 and 2025.
Adj EPS of 52.8p is above broker consensus of 50.4p.
Shore Capital (with thanks) expects 62.5p in FY 12/2024, which would be a PER of 13.2x
Divis are quite generous, and the yield is c.4%
Balance sheet is not great. Net debt has come down usefully to £140m, but the balance sheet is large, so I expect there would be considerable swings up & down for the net debt. Gross debt is much bigger than net debt too. Average daily net debt is the number we need, not year end snapshots.
Paul’s opinion - I can’t muster any enthusiasm at all for HFG shares. The reason I don’t like wafer thin margins, is because you only need some small unexpected changes in the many variables, to see profit disappear if something untoward happens. For that reason, I would only ever value this share on a single-digit PER, because the group clearly has no pricing power. Customers are always going to be shopping around and squeezing its margins. The debt is more expensive now too, with finance costs consuming about a third of the adjusted operating profit, and almost half of the statutory profit. Why on earth would anybody want to buy and hold this share, when there are so many other, better quality companies available to invest in?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Superdry (LON:SDRY) Maybe Next (LON:NXT) will buy Superdry (LON:SDRY) out of adminstration, as their kit is already on their website, and try lower the costs or do something more innovative?I don't know who is Superdry (LON:SDRY) 's target consumer is now, but i don't think they've been popular with younger people for a while.Next (LON:NXT) have done quite a good job like Mike Ashley of buying up a basket of distressed brands for very little.They already have all the rest of the infrastructure and do a lot of the backend even for GAP (NYQ:GPS) in the uk now.
Here's a nice little "today I learned" that seems applicable to management by metrics...
Godhart's law: When a measure becomes a target, it ceases to be a good measure.
Mark, So true. I’m having multiple flashbacks.
Goodhart - eminent economist and descendant of the founders of Lehman Brothers
I'm still contemplating a double-up on Wynnstay (LON:WYN) but haven't pulled the trigger yet. Their recent RNS concluded that they can still deliver this year, but the next few weeks weather will play a part. Interestingly, when I looked a few days ago at the flood map, their areas were not that heavily impacted - must be a first for Wales and the West! https://check-for-flooding.ser....I'm also interested in NWF (LON:NWF) which has better returns on capital. Less keen on Carr's (LON:CARR) despite Harwood being on the register.
Chart is trying to form a bottom. I might pull the trigger once 50dMA is cleared.
Wynnstay
Not sure the month to month / quarter to quarter makes much difference as it’s business model and pricing is on a cost up basis (so I understand )
The business model is to apply a % above cost and thus the low margin but consistent - it was originally a cooperative ?
It’s near enough the bottom of its range at least when it hits 350 then it will revalue on strength of market not so much company . Sure to be good inflows into a good company like this
I’m waiting for ISA allowance to top up as it’s a decent dividend and AIM so good ISA share .
Pretty flooded in West Carmarthenshire/Carmarthen town- and has been for months. They have a store in St Clears and Carmarthen.
I'm guessing the mission group has just vanished off the to do list as many seem to?????
Chri55,
Surely there's a much more polite way of asking that question? The team are covering a lot of reviews each way, they're going to get to them all.
You might be more successful at getting a company reviewed if you asked more politely.
If you're having a bad day, I'm sorry that's the case.
Corero Network Security (LON:CNS) quietly doing what they said they would. No debt, generating cash and as of today delivering their biggest contract win to date. New CEO already having an impact. Our results note is here if you missed it last week
https://www.equitydevelopment....
Thank you Equity Developments. I have just watched the update video for Corero Network Security (LON:CNS) (which I have held patiently for over 5 years first buying at 7.3 , topping up sub 4p and taking some profit at 14p 3 years ago - currently my largest holding). The update is both reassuring from an investment viewpoint, but also exceedingly frightening from a world cyber security view. Botnets and Brickerbots seem to be far more dangerous than cruise missiles nowadays! https://www.equitydevelopment....
Hanging this post on the dire (sad?) news that Superdry (LON:SDRY) is probably on the way out, I thought I would canvas thoughts on Shein.
I have never held Superdry but as somebody who has made and then lost, what was for me, a small fortune in Boohoo (LON:BOO), I am intrigued that we, in the UK, just don't seem to be able to get it right in retail/online retail. Additionally we are happy to throw ESG (which I think is a nonsense anyway) mud at home grown efforts, which seems to stick but Shein, whose clothes are all made in China and shipped, literally, half way around the world to its customers, announces a doubling in profits from $1 billion to $2 billion and this is reported almost breathlessly by the FT (Shein profits double to over $2bn ahead of planned listing https://on.ft.com/3IZPWmB), with no mention of the possibility that maybe these profits aren't real, the coincidence of the doubling being announced just as it is trying to IPO in the US or UK, questioning what conditions these clothes might made under etc etc. Ditto BYD.
Further it is interesting to note that the tariff on textiles and clothing imported in to the EU and the UK is just 12%. (In the US it is 25%). I am a believer in "Free Trade" and zero tariff barriers if there is a functioning market but where goods are produced under a state controlled markets system (China) then one has to question, in my opinion, whether the likes of Boohoo (LON:BOO), ASOS (LON:ASC), Superdry (LON:SDRY) are competing in a true market system?
Anyway that is my little rant over (the Boohoo lost really hurt) but as somebody who is poorer partly because of Shein I wanted to get it off my chest! :-)
Regards
Michael
It as if the previous AIM experience of Chinese companies being floated to exploit 'mug' investors has been entirely forgotten.
However, it is the case that in China people order enormous amounts through online services, and this means aligned with Chinese entrepreneurial spirit Corporations grow bigger, and then want to expand beyond their own borders, but carry with them some of the same issues of old about the way they go about their business dealings. This will include inevitably lack of transparency over certain matters. That lack of transparency and accountability mutes press interest because they know generally they can't garner 'facts' or criticise in the same way they do with UK/US Companies, and they are certainly not going to go to China and cause a fuss!
No - you are absolutely right Michael
Unfortunately the British media likes to bash British companies. They MUST be held to an ESG standard that far exceeds those of foreign competitors. But they must, whilst having their hands tied behind their back, compete in a wrestling match against said foreign competition and are expected to WIN. If they don’t then something is wrong with the British economy!!!!!
And so the answer is to entice foreign companies with little ESG credentials and even littler governance standards onto the UK stock markets as some sort of panacea to our eroding stock market. I mean this is so idiotic that frankly we probably deserve our demise!!
It recently took some eagle eyed public to spot that (I think was Temu) who were offering £40 to customers who signed away their data rights including voice and pictures and other sensitive metrics FOREVER!! Not even legal in the UK. When this was flagged up Temu complained about it not being a level playing field……….I nearly choked on my coffee. And there are concerns all over the internet about the amount of data and potential misuse of the data currently being collected. And yet our press mentions very little and British shoppers carry on giving away their lives to foreign companies and by definition their governments. All for some cheaper tat. So really the British public don’t care about ESG - they care about price, but because we “need” to care about ESG we put the burden onto the British companies we then don’t buy from because they are too expensive…..talk about contradiction. As long as we do that we can go on convincing ourselves we are better.
And as for the UK pension funds well dont get me started…….. we are the ONLY developed country where our pension industry invests less into UK stocks than our proportion of GDP. The US invests double as do most European countries. Japan is something like 10*
The UK? - HALF ! Wtf! Our UK pension funds cant even invest 5% of their assets into the UK itself. It is utterly ridiculous imo that government hasn’t dealt with that. It should be minimum in proportion. That additional capital grows GDP and the Economy and creates jobs and skills for the future. It is criminal this is being ignored. It costs nothing to do and adds a lot of economic home value. That is something the press should be all over but aren’t…….that is the bigger question.
ESG wasn't public driven, it's just another set of burdensome regulations. Unfortunately, Europe & the UK seem intent on increasing the regulatory burden companies have to operate under. It's like they are trying to make it as difficult as possible for companies to operate. It's no wonder Chinese companies thrive.
As an example, since I've been working in the city over the last 20 years or so, the size of compliance departments has increased about five fold, purely to deal with the increased regulatory reporting requirements.
I'm not too worried about the data Chinese companies are maybe collecting, as has been proven in the past the UK & US authorities do the same thing. In fact, most people do their job for them by declaring on social media their location, activities, likes, dislikes, lifestyle etc!
There is a big difference here af20001 - in this instance people were asked to sign away all of their data rights that could be used as the company felt fit. That includes your identity, pictures and voice. It means that they could feature your picture wherever they want for example and use your voice for AI purposes / deepfakes etc. etc. It isn’t about collecting data for marketing purposes - it controls that data in perpetuity for £40. If you are not scared by the potential future implications of that then you really should be……
The point I was perhaps poorly trying to make is any dodgy outfit can harvest whatever data they like from the heaps that people themselves make available. If I wanted to make a deepfake of someone I wouldn't first ask a user for their permission to use their data, I'd just harvest what I like from their public profile.
But you're right, anyone who signs their data away for £40 is a fool. But equally foolish is to broadcast everything about yourself on public platforms without seemingly thinking about about the consequences.
But I sense we're straying off topic here...
Boohoo (LON:BOO) employed/employs brown ladies in sweat shops in Leicester, according to a leading QC, (as well as China and other low wage/ low rights places). The UK listed fast fashion source from the same places as the Chinese.
I’m sorry snowdrop but that’s just not correct and a highly distorted interpretation.
Boohoo (LON:BOO) paid for the QC report! Go through their RNS history
I’ve been through them with a fine tooth comb snowdrop having previously owned. If you think that what is contained within their QC report is the same as the sourcing/conditions that make Chinese competitors so cheap then I am afraid you are deluded.
But let’s, for a second, believe that they are - why did the British press have a propaganda machine against Boohoo (LON:BOO) forcing such a QC report. Why was it on every news channel / feed whereas the competition eating their lunch are being lauded for making $2bn in profits and a potential UK listing?
The media went for a British company, forcing change making British companies less competitive as a result. But flag waving for a foreign company with less ESG.
100% right david, I lived for years in the East Midlands as a younger man. Worked in the knitware business for 3 years. Visited the home of an Indian colleague, met his wife who worked in a factory in Leicester. I saw no signs of exploitation or poverty, flexible working practices yes probably not unionised which was a bone of contention. Take a Streetview of Belgrave Road/Melton Road in Leicester on Googlemaps and see the high end shops. Compare with the Channel 4 Dispatch program which coverered working in Chinese factories, staffed by workers bussed in from the countryside with no right to settle, housed in hostel accomodation and working to meet quotas at minimum wages.
Precisely. My point entirely.
Michael
Snowdrop I’m afraid I don’t understand the point you are making.
Regards
Michael
Excellent comment and yes don’t get me started U.K. Government regulation of pensions.
If the textile import tariff is 12%, then Shein and Temu have a huge price advantage in taking advantage of the de minimis parcel tax loophole.
Not only are they getting away without VAT (20%) but also this 12% textile tariff!
How can the likes of any UK fashion retailer compete with this?
Not to mention the cost to the British taxpayer Boon as people switch!
The reality is you can’t compete with the Chinese on the online stage because the UK Govt makes it easy for them to circumvent the rules . Same with copyright infringement.
I know a number of designers who sell hand made designs in the UK and immediately they prove popular certain unnamed online competition just copies and sells them cheaper. There is no protection for our creatives starting out. It really is appalling. I want us to nurture and help the next generation but our policies are all designed to hinder that innovation/creativity.
David
It’s not only the Chinese that do the following - The biggest culprit if Jeff Bozo himself .
“know a number of designers who sell hand made designs in the UK and immediately they prove popular certain unnamed online competition just copies and sells them cheaper.”
The biggest culprit is of the course the main man and tax dodger extraordinaire mr Jeff bezos and his vampiristic drain on our economy and our retailers with his transfer of profits and great tax planning (or dodging ) .
List your products on Amazon at your peril as they are renowned for just copying successful products whilst they of course have full access to the sales on their Amazon channel
I am still mystified why 75% of the British population are more than happy to shop on Amazon let alone us investors hold shares in this criminal empire run by Doctor evil himself .
OK maybe I got carried away there but I feel better having got that off my chest and for the record I have never sold anything on Amazon nor will I ever do (unless it makes me stupidly rich and I end up with a big yacht and supermodel wife to go with my bald head )
:-) planetx
Oh dear.
I'm not up to date with the situation but I know that AliExpress.com did start to collect VAT at 20% on its sales to the UK about 2 years ago. (Earlier company doing similar to Temu selling direct from China) Dont know if it was voluntary. But means it is possible that Temu/ Shein might have to do the same.
Collecting VAT by foreign companies was brought in by EU rules, which the UK adopted before leaving. So an AliExpress price is before VAT is added at the checkout.
Come on Guardian make yourselves useful for once get after Shein, I'd say a fair percentage of the models have had the pics fiddled with, talk about exploiting the female form, whilst your at it come on BBC
Boohoo (LON:BOO) just rnsed fairly recently that they passed all the relevant ESG tests with 'flying colours'.I'm in for a punt around 40p with Boohoo (LON:BOO) as i think the management is savvy, they don't have the looming future savvier private equity debt that ASOS (LON:ASC) has.And i do believe Shein won't conquer the world and take over the whole world/UK market.Don't Shein exploit some loophole whereby there's virtually no duty on their imports because they are under a certain price and size...?I thought i read that somewhere.. perhaps the government can get rid of that.
Superdry (LON:SDRY) shirts online everywhere including Next (LON:NXT) are everywhere and very pricey relative.Next's own brand kit is so good value and quality similar to Marks and Spencer (LON:MKS) imo.I guess i'm betting small that Boohoo (LON:BOO) does have a few brands now, not reliant just on one, and still some brand power and not just cos it's the cheapest.And eventually the market will like a trading update and continue rallying for a while afterwards.
I would not buy any Boohoo (LON:BOO) until the directors start buying, have a look at the directors trades, makes interesting reading.
Deep Value Territory Picks
On the possibility that there will be some companies that in oversold / unloved space yet remain great businesses stuffed with cash, assets , and are actually still knocking out profit albeit reduced .
With following. Sort of criteria .
- have cash at least 20% of market cap
- have assets close to market cap (say 80%)
- are still profitable making at least 10% profit and likely to remain so even in tough market but will improvise in better market
Strikes me there are a few of these lying at the bottom of the ocean out of mind out of sight .
SDG is possibly one
Character group looks another
- 50 m cap
- 10m cash
- profit 5m (bad year )
- 40m assets
Any other spring to mind ?
Maybe a bit of a cigar butt strategy but these will also surely be prime takeover targets so I reckon a selection if the best ones albeit on a non conviction spread could be fun
Van Elle Holdings (LON:VANL)
- £38 million market cap
- £41 million net assets
- £9 million cash
- £3.5 million profit
- 3.4% div yield
- No debt
Morgan Sindall (LON:MGNS)
- £1.1 billion market cap
- £540 million cash (daily cash sligtly lower)
- £190 million assets
- £108 million profit
- 5% div yield
- No debt
Jet2 (LON:JET2)
- £3.1 billion market cap
- £3.2 billion cash (some customers, but i always leave them as credit use for next trip)
- £1.5 billion assets
- £400 million profit
- less div yield
- No debt
and then there are candidates like Ramsdens Holdings (LON:RFX) , Henry Boot (LON:BOOT) , Wynnstay (LON:WYN)
Good luck all.
AD09
Thanks, will work my way through those .
Already hold Jet 2 and Wynnstay - I keep adding a few to Wynnstay on the dips one of my favourites though its on its arse right now are price wise .
Van Elle Ive held before and is at the bottom of its trading range (seems to simply bounce between 36 and 44 ) . We had them quote for some piling work we add done and they were so expensive, we ended up using a contractor who sub contracts for them at half their price (but looks interesting at 36p level)
Dont like Ramsdens much due to their shops just look crap and I walk past it every day and just seems to feed off the bottom of society (irrational reason for not holding) .
Henry Boot I held but sold based 800m from my house and just wasn't impressed with their pathetic shareholder communication after I attempted to go to an AGM which no one seemed to know where it was . (childish toys out the cot reason for not holding)
I’ll second Wynnstay (LON:WYN) as one to watch. I currently don’t own as I sold out on past bad news (and saved myself some losses). However the SP is trying to form a bottom. With a little good news and chart confirmation then I will dip my toe back in.
Wynnstay (LON:WYN) quick look, margins very thin and spread quite wide.
Agree Rusty. And when things go wrong the SP is hit. Just like some of the construction companies. However there is excellent value and it is one of the most consistent dividend payers. “If” (a big IF), farming news improves and the bad news is in, then the SP will rise.
I think farmers will struggle this year, I know back in January, a lot of crops had been lost, even in my area which has been drier than most, due to the wet weather, since then it has been very wet in February. I think too risky but could work out.
Not exactly deep value but Castings (LON:CGS) looks good value to me, for such a quality stock. Think it meets your criteria.
These 2 might meet your criteria Ocean Wilsons Holdings (LON:OCN) and Tyman (LON:TYMN)
I don't hold but am considering.
Ocean Wilsons Holdings (LON:OCN) are interesting Greedo. I've held for a while along with Hansa Investment (LON:HAN) which owns c26% of the shares. They have not been great investments, but are now starting to perform. William Salomon effectively controls Hansa and Ocean Wilsons. It is well known that Brazilian ports group Wilson Sons is in play with a couple of possible bidders. If a successful bid happens this year, it would unlock material value to Ocean Wilsons Holdings (LON:OCN) and possibly then lead to a return of capital and/or Ocean Wilsons Holdings (LON:OCN) and Hansa Investment (LON:HAN) merging which would reduce cross holdings and discounts on discounts. Some of this is already in the price in my view. Whether or not it will happen is down to the price being right and what William Salomon prefers to do. He was behind the old merchant bank Rea Brothers amongst other things and is now the investment manager, Hansa Partners. He has always treated minority shareholders fairly in my view.
Got to get their stock from China? Via the cape and not red sea cost implications
I'm in the process of reading "What Works on Wall Street". Here's some snippets:
"Stocks with the worst price momentum are horrible long-term performers; the only time these stocks do well is in the first year after a severe (−40 percent or more) bear market when “junk” rallies have always occurred."
"Stocks with the best EBITDA/EV have earned the best absolute return over 1963–2009"
I haven't thought about specifics, but one could select stocks with an E/E (EV/EBITDA) of at most 6.5, and look for a high M (momentum ) score.
Here's a run-down on what AD09 suggested:
VANL E/E 3.1, M 59
MGNS E/E 4.6, M 87 (I hold)
JET2 1.8, 94
RFX 4.5, 55
BOOT 7.3, 27 (E/E looks a little high, and momentum a little low)
WYN 4.5, 50 (I hold)
JET2 looks cracking.
Edited out due to a typo.
Morning Paul
Any chance you could share thoughts on Gaming Realms (LON:GMR) post yesterday's Results if it's quiet enough today? Appreciate you commented on TU in Feb so maybe little has changed.
Market seemed to mark them down, though appear to be recovering this morning so far. Is this due to the continuing high levels of capitalisation of development spend? Would they even be profitable if they put this on the P&L?
No debt and cash at year end of £7.5m suggested to me that all is ok under the bonnet. Is that a fair read or would you or other members have a different view of their accounting practices?
EPS forecasts on the GMR page looks like they are slowly but steadily being reduced too. Maybe another contributory factor.
Gaming Realms (LON:GMR) I'm waiting for a bit of clarity from the investor presentation on the 9th. Interested to know what new markets they're working on. Would be good to see some director buying at these levels to show confidence moving forward, price is lower now than when the CEO last bought in August!
Hi KiwiCam - there's a brief interview today with the Gaming Realms (LON:GMR) CEO that covers potential new markets including a mention of Brazil although it looks to me that the required regulations are still to be worked out on that front. Perhaps there'll be more detail during the presentation..
Morning guys!
If you're not so busy (yeah, right!), might be worth a look at the finance provider Time Finance (LON:TIME) (I do hold).
Extended and improved their funding (lending) facility today after a decent Q3 update last week which headlined with...
"Eleventh consecutive quarter of loan book growth, 40% increase in 9 month Profit over corresponding period; already in excess of FY 2022/23 total"
PEG is 0.5 and the Stock Rank is 99 with the lowest value being 77 for Quality.
It's past (5 years) is rather choppy (impacted during the COVID period) - Appreciate any views either may have.
Cheers!
Yes, Time Finance (LON:TIME) is a Buy for me too (I don’t hold yet). Just as soon as I can dust down the piggy bank in the new tax year. Grounded and experienced management impress as do the figures. New BBB facility expands capacity nicely.
I have just bought some, Time Finance (LON:TIME) looks pretty good and it keeps appearing on my screens. Hopefully Graham can review it.
Time Finance (LON:TIME) I hold. If you haven't already done so, watch the ShareSoc presentation on https://www.youtube.com/watch?v=n-Lx8W2Hqo8 The management and the presentation is clear and informative. The Board members are mostly new since 2021 with bags of experience and appear shrewd and dynamic. The fundamentals all support the way forward too
My morning smallcap tweet: O ye of little FCF
Trakm8 Holdings (LON:TRAK) Shearwater (LON:SWG) Global Ports Holding (LON:GPH) Character (LON:CCT) Topps Tiles (LON:TPT) Corero Network Security (LON:CNS) Calnex Solutions (LON:CLX) Time Finance (LON:TIME) Peel Hunt (LON:PEEL) Genedrive (LON:GDR)
◄Trakm8 (TRAK)► guides FY-Mar op cash generation £5.4m (£4.3m). Cash at hand £1.4m, better than expected. Insurance capacity has been restored to co's largest insurance customer so shipments into the insurance market are expected to recover during April. Has bought IP from Action 365 (a Freedom Services Group) for £500k. Freedom Services places 4 year contract extension. £5.3m HSBC loan extended for 1 year. Also issues £990k convert at 18%. Strike 8.1p, a 10% discount. [SP=8.12 Cap=4m]
◄Shearwater (SWG)► sheer slaughter as it warns FY-Mar rev £22.5m down 16% and adj EBITDA £1m (-£0.2m), below market expectations of £32.5m and adj EBITDA £2.5m. Blames delays in concluding larger contracts. "The Board is reassured by a particularly strong renewal schedule for FY25 and a number of high value contracts in advanced negotiations with blue chip customers, providing confidence in returning to growth during FY25." [SP=49.44 Cap=12m]
◄Global Ports Holding (GPH)► signs 50 year agreement to operate cruise services at Liverpool Cruise Port. GPH will pay upfront charges, and (in certain circumstances) annual charges, amounts confidential. [SP=209 Cap=161m]
◄Character (CCT)► doubles buyback limit to £2m. [SP=262 Cap=50m]
◄Topps Tiles (TPT)► warns H1-Mar rev down 6% due to weak domestic sales. H1 profit will be hit by the weak sales, timing of the holiday pay accrual and seasonally higher energy usage. [SP=44.43 Cap=87m]
◄Corero Network Security (CNS)► $2m+ 3 year contract renewal and expansion with a leading US SaaS provider. [SP=8.8 Cap=45m]
◄Calnex Solutions (CLX)► guides FY-Mar broadly in line with market expectations with rev c.£16.3m and margins maintained. Blames "well documented ongoing challenges in the telecoms sector". "Customer engagement levels have remained high, providing confidence...in projects recommencing and customer spending resuming." [SP=58.2 Cap=51m]
◄Time Finance (TIME)► extends asset finance facility with the British Business Bank from £35m to £64m. [SP=38.8 Cap=37m]
◄Peel Hunt (PEEL)► guides FY-Mar rev in line at c.£85.5m but a loss broadly in line with market expectations. Outlook - "market trading volumes remain low and ECM issuance continues to be subdued...IPO activity in the UK remains muted, there has been more activity in Europe and sentiment towards IPOs is improving in the UK". [SP=127.55 Cap=157m]
◄genedrive (GDR)► NICE draft guidance recommends CYP2C19-ID Kit as the preferred platform for UK point-of-care genotype testing. [SP=3.75 Cap=5m]
O ye of little FCF
I can't stop chuckling!
And shear slaughter.