Small Cap Value Report (Weds 3 July 2024) - CML, EQLS, POLR, VARE, SYS1. Briefs: KWS, BCG, BMS, TPT, CRN, ETP

Good morning from Paul & Graham! Up early today, to catch up on a straggler from yesterday.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
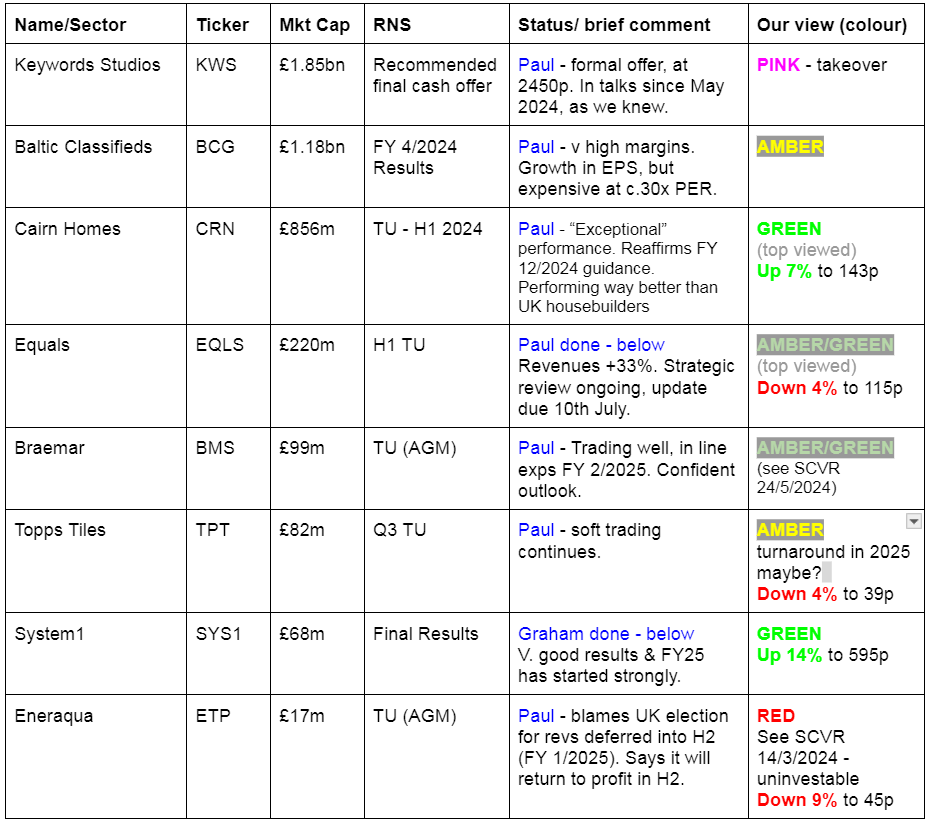
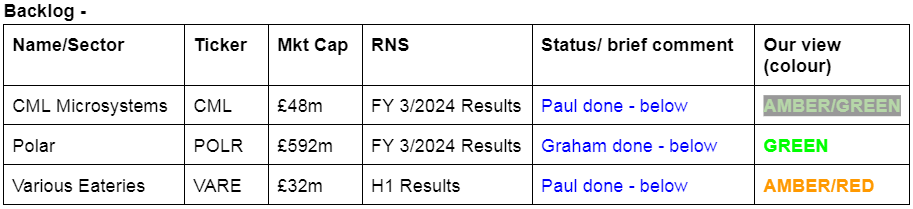
Summaries
CML Microsystems (LON:CML) - down 11% y’day to 300p (£48m) - FY 3/2024 Results - Paul - AMBER/GREEN
Profit is down, but in line with expectations. Valuation is supported by plenty of cash, and surplus property (now up for sale). I'm not sure what the future holds, as short-term outlook sounds quite weak. However with heavy R&D spend (20% of revenues), and upbeat medium-term comments, could this be the next Filtronic (LON:FTC) if it hits the jackpot with new products? I don't know, but it's an interesting potential upside case, and the cash/property protects against some of the downside risks.
Equals (LON:EQLS) - Down 4% to 115p (at 08:43) £215m - H1 Trading Update - Paul - AMBER/GREEN
Strong revenue growth has continued, although it doesn't say anything about profit vs market exps. This payments company is very popular with shrewd investors. A big rise in interest receipts on client cash, and "solutions" fee growth seem to be driving things. Graham and I have some reservations, so put it in the don't know tray, on amber previously. However, looking at it again with fresh eyes today, risk:reward does seem favourable, if you're prepared to take the risk of a sharp fall (est. to 80-90p I reckon?) if bid talks end (Madison Dearborn has already walked away).
Polar Capital Holdings (LON:POLR) - 583p (£592m) - Results for FY March 2024 - Graham - GREEN
As requested by readers, I catch up on the 2024 results from Polar, one of my top picks for the year. While “core” (adjusted) operating profit is down, other measures of profit are higher. I remain comfortable with my positive stance even if this is one of the more expensive fund manager stocks.
Various Eateries (LON:VARE) - 18p (£32m) - H1 Results - Paul - AMBER/RED
It seems almost impossible for smaller hospitality groups to make profits at all in current conditions, and these numbers reinforce that view. A decent fundraise, and debt for equity swap was done in Dec 2023 at 25p, doubling the share count, so we can now buy a third cheaper at 18p. Hence I've moderated from red to AMBER/RED, but still don't see a viable business here. It could become viable in a future consumer boom though, who knows?
System1 (LON:SYS1) - up 17% to 610p (£77m) - Final Results - Graham - GREEN
Barnstorming results from SYS1 and they enjoy yet another earnings upgrade, their sixth in a row! We’ve been positive on this one since 370p when Paul wrote on their upgrade in January. Momentum remains excellent with hundreds of new clients and big opportunities seen at existing advertising clients.
Paul’s Section:
CML Microsystems (LON:CML)
Down 11% y’day to 300p (£48m) - FY 3/2024 Results - Paul - AMBER/GREEN
CML Microsystems Plc, which develops mixed-signal, RF and microwave semiconductors for global communications markets, announces its Full Year Results for the year ended 31 March 2024.
Revenue up 11% to £22.9m - however more than all the growth came from the acquisition of MWT, which contributed £3.3m in revenues for about half the year. Without that acquisition, revenue would have been down c.5%.
High gross margin of 71%, so lots of operational gearing if it can scale up revenues - that’s the problem though, as historically CML has not demonstrated growth, and remained a small (but profitable) niche company -
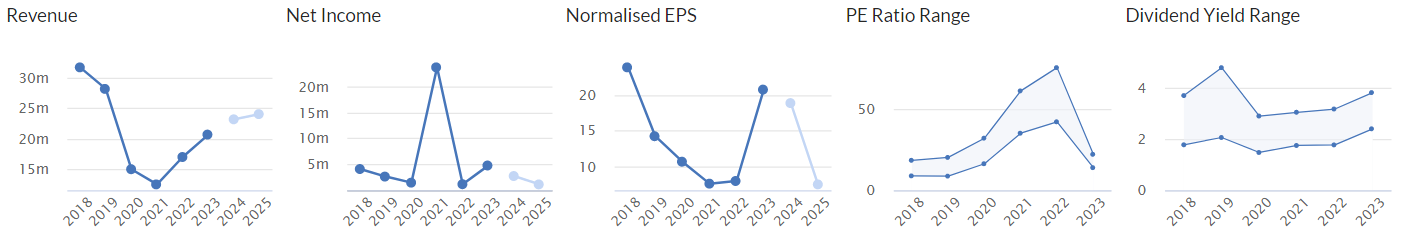
PBT was £2.52m (FY 3/2024), down x% from £3.16m last year (with a further £2.06m exceptional profit on top of that last year, from the sale of surplus land - and there’s more of that in the pipeline). Two brokers (Shore, and Progressive) adjust the PBT up by £0.6m to £3.1m.
EPS is reported by the company at 13.0p (down 33%, pre-exceptionals). However, Progressive adjusts it up to 14.5p. Personally I prefer it when companies report adjusted figures that are consistent with what the brokers report. Shore Capital adjusts the FY 3/2024 EPS up to 19.4p, so confusion reigns as to what EPS figure we should be using. To play it safe, maybe I should just value the shares using statutory EPS of 13.0p?
Earnings get a boost from the UK’s generous R&D tax credit scheme.
Outlook - not great in the short-term. There are two outlook sections, a short one from the Chairman, which claims revenue growth (but excluding the acquisition of MWT, revenue actually fell), going on to say -
“External factors, including current market conditions and the normalising of elevated customer inventory levels, make it difficult to achieve our profits growth objectives.
Despite the short-term outlook not being what I would like to see, I am confident that the Group is well placed against its more medium-term objectives. Exciting opportunities lay before us, we are addressing growing new markets which are supplementary to the more traditional sectors that have been a cornerstone of growth in recent years. The pipeline of opportunities has a strong upward trend, giving us confidence that we will achieve our strategy of sustainable long-term growth.”
Customer de-stocking has been mentioned before, so no surprises there. This is also mentioned by the CEO as an ongoing factor -
“the trading environment for the current year will continue to be influenced by the customer inventory overhang…”
Th Group MD’s more detailed outlook comments sound cautious, and uninspiring, at least in the short-term -
“The current full financial year is expected to show a further revenue advance, albeit not at the compounded rates seen across the prior four-year period. The full year inclusion of MwT's cost base along with necessary activities to unlock the full potential of the enlarged business will have an impact on operational profitability. However, these are essential and value-added strategic steps in the drive towards much higher medium-term gains.”
Broker forecasts - Shore seems to use a higher adj EPS calculation, and it sees 19.4p dropping to 10.7p from FY 3/2024 to FY 3/2025.
Progressive sees 12.8p in FY 3/2025, dropping from its different calculation of 14.5p in FY 3/2024.
We’ve then got a completely different, lower forecast of 7.4p in the Stockopedia broker consensus number, so I’ve no idea where that has come from.
What to do then? To keep things simple, I’m going to work on the 13.0p statutory EPS, which Progressive reckons will drop to 7.9p in FY 3/2025. Shore has a similar statutory EPS forecast of 7.4p for FY 3/2025, which ties in with the Stockopedia number.
Therefore at 300p share price, the PER is 40x which looks high.
However, remember part of the valuation at CML hinges on its strong balance sheet, with lots of cash and surplus property. Moving on to that -
Balance sheet - NAV is £51.1m, but that includes intangible assets (goodwill £14.4m, capitalised development spending £15.2m, and other of £3.4m), totalling £32.9m. Eliminating that gives us NTAV of £18.2m.
There could be upside on that number from further surplus property development & sales.
Cash looks very healthy at £18.2m, and no interest-bearing debt. However a key point is that the acquisition of MWT involved deferred consideration. I discovered this when I couldn’t find the £10.8m consideration paid on the cashflow statement. All is revealed in note 9, where it says net cash paid out was only £565k, with deferred payments in cash & shares as follows -
“ is payable over a three-year period, cash consideration £956,325 on 2 April 2024, cash consideration £2,171,783 and £475,807 (90,780 shares) on 2 October 2024, cash consideration of £1,557,331 and £475,807 (90,780 shares) on 2 October 2025 and £475,807 (90,779 shares) on 2 October 2026. “
I make that about £4.7m cash (or 10% of the market cap) outflows re MWT up to 2/10/2025 - which is about a quarter of CML’s current cash pile, plus a bit of dilution from the issue of new shares.
Hence it’s best to take a prudent view on cash, and adjust it down to £13.5m.
Although you could ignore this, and offset it against future land sales, which might be above book value, it’s not clear.
Cashflow statement - doesn’t impress me I’m afraid. All the £5m operating cashflow is used in capex (physical £1.5m [of which £1m is moving the car park, as part of the redevelopment of surplus land], and R&D development spend £3.5m). Shareholder returns were £1.75m buybacks, and £1.74m divis.
It warns -
“Cash flow will come under pressure for the year ahead for two main reasons; firstly, working capital to support the aforementioned strategic R&D initiative and secondly, as a result of further payments relating to the MwT acquisition, being $1.17m already paid on 2 April 2024 and a $2.65m payment due 2 October 2024.”
However, putting all that together, I think CML has ample cash & liquidity, so there’s not really anything to worry about. We just have to hope that its heavy product development (c.20% of revenues) delivers future benefits.
Dividends - total 11p for the year (unchanged), giving a decent enough yield of 3.7%.
Paul’s opinion - I hadn’t intended to go into this level of detail on the numbers, but CML has always intrigued me as a hybrid share with interesting growth potential (not showing in the numbers yet though), combined with strong asset backing to protect the downside and provide shareholder returns whilst you wait for something more exciting to happen with its future products. Plus it is still profitable, despite the lacklustre shorter term outlook.
Imagine if CML delivers a blockbuster product, as we saw this year from Filtronic (LON:FTC) ? For that reason I think CML might be an interesting share to add to our watchlists, so we get all the future RNSs, and keep our eyes peeled for anything that looks transformative in terms of order intake.
In the meantime, it’s very well financed, so no risk of seeing the upside snatched away with a horribly dilutive fundraise, as we all-too-often see elsewhere.
Offsetting that, the current trading sounds quite weak, and I do wonder if it might have another profit warning in it? De-stocking seems to have gone on for too long, that there might be more to it than just destocking, I’m wondering?
I’ve been green before, but think it’s probably sensible to moderate that to AMBER/GREEN for now, and await developments.
Equals (LON:EQLS)
Down 4% to 115p (at 08:43) £215m - H1 Trading Update - Paul - AMBER/GREEN
Consistent with prior years, Equals Group plc (AIM:EQLS), the fintech payments group focused on the Enterprise and SME marketplace, provides the following trading update for the six months ended 30 June 2024 ('H1-2024' or the 'Period').
Revenues have continued rising strongly -
“The Group is pleased to announce a strong period of trading in H1-2024 with revenues up £14.9 million compared with the same period last year to £60.0 million, an increase of 33% year-on-year (H1-2023: £45.0 million).”
I haven’t got access to any broker notes, but the StockReport shows forecast revenue growth of +20% in FY 12/2024. So H1 seems well ahead of that. Although I don’t know what the split of revenue growth between H1 and H2 was expected to be.
Graham’s notes are here on 16/4/2024, where he reviewed the impressive FY 12/2023 results, showing revenue up 37%, and an operationally geared increase in EBITDA of +70%
Previously we were told that YTD revenues up to 12 April 2024 were up 30%. So today’s news of H1 to 30 June 2024 seeing revenues up 33%, shows an improving trend from Q1 to Q2.
As the table below shows, most of the revenue growth is coming from “Solutions” -
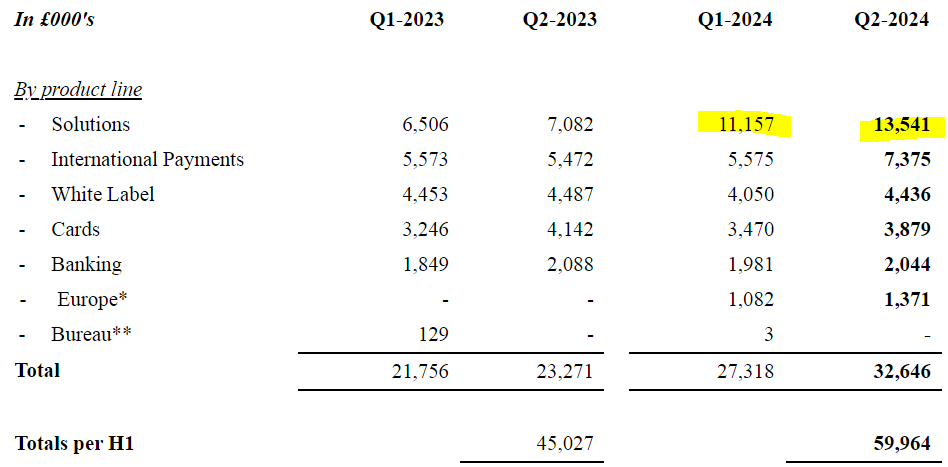
Another table categorises income differently, and this shows strikingly large increases in both fees, and interest income (maybe one-off growth from interest rates normalising?)
Interesting snippets here -
“In keeping with the strong growth in our Solutions platform, fee-based revenues have grown both in comparison to prior year and quarter-on-quarter during H1-2024. Within Solutions, fee-based revenues are more recurring in nature as customers typically enter into longer-term contracts with agreed monthly minimum fees.
The Group also earns interest income which is primarily earned on safeguarded customer balances held off balance sheet, over three currencies (GBP, EUR and USD) and across four Tier-1 banks.
Interest, particularly in Solutions, is a key component of the pricing discussion with clients and is therefore assigned to the segment generating the underlying balances. Not only have balances grown but the Group has renegotiated better rates and margins with its Tier-1 partner banks. “
Cash - EQLS had £20.5m of its own cash at 30 June 2024. The last balance sheet showed only c.£12m NTAV, so there's nothing much in terms of asset backing to support the share price if trading were to deteriorate.
Strategic review - seems to be going on forever, the next update will be 10/7/2024.
What’s missing? - we’re not directly told whether or not EQLS has traded (ie profits) above, in line, or below expectations. That’s the main point of a trading update, surely? Although it is only 3/7/2024, so this is more of a flash figures update to 30/6/2024, I suppose.
Paul’s opinion - quite a few shrewd & successful small caps investors that I know have all bought into this share in a big way. That’s a very good starting point for research, following shrewdies, although they get things wrong sometimes too, but it’s good to know that people who pore over the detail and get more right than wrong, like it a lot.
The numbers look very good to me. The only reasons Graham and I have previously stuck at AMBER with this share are because we’re not sure if the profit growth is necessarily sustainable (in such a competitive space), and we’re mystified as to why management seem so determined to sell the company. That could work out great, if a bidder is prepared to pay a whacking great premium, so upside here is potentially good. Also, the numbers stack up well even if a bid falls through - the StockReport shows the forward PER as 17.6x.
EQLS seems to have developed some successful offerings for B2B services. Interest rates rising has been a major boost to profit too.
Where does it go from here? I just don’t know.
However, given that the valuation seems reasonable on a PER basis, and revenue growth is continuing to be strong, plus the potential upside from a bid (even if that seems to be less likely after such a long gestation period), means I think we ought to recognise the positives and shift up a bit to AMBER/GREEN. Downside risk in the short term seems to be a drop to maybe 80-90p (my guess) if the bid talks end?
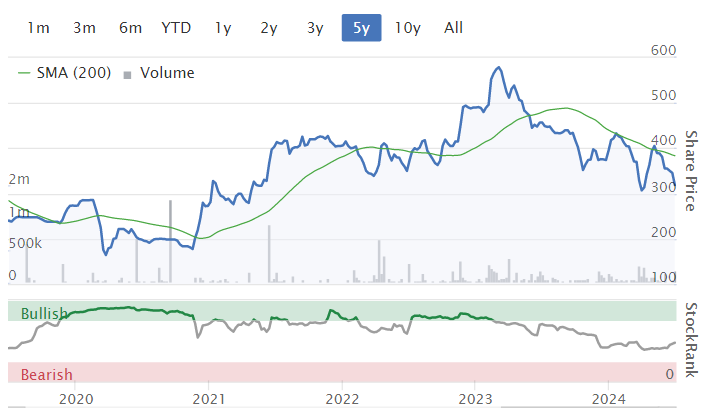
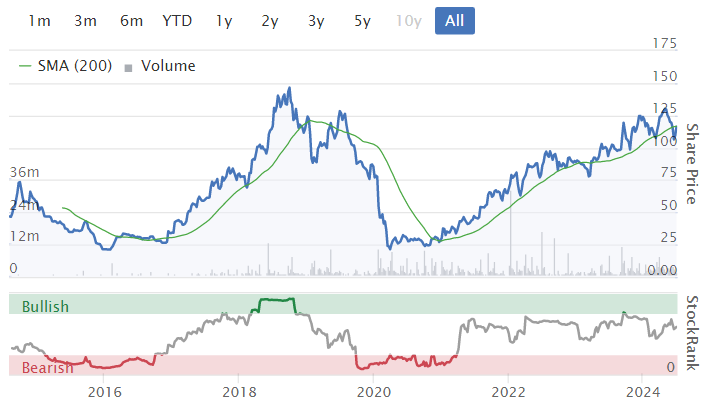
Since listing -
Various Eateries (LON:VARE)
18p (£32m) - H1 Results - Paul - AMBER/RED
Graham last looked at this upmarket bars and restaurants group majority owned (62%) by Hugh Osmond here on 1/11/2023, at 27.5p/share, concluding with RED due to poor performance, and being financially stretched. Graham also flagged de-listing risk.
VARE’s two brands are Coppa Club (trendy lounge/bar/eateries), and Noci (Italian style food with a twist).
Numbers for H1 (26 weeks to 31/3/2024) are poor -
Revenues £22.7m (up 10% due to new site openings. LFL revenues “slightly down”)
Adj EBITDA loss of £(1.2)m, improved a bit from £(1.9)m LY H1, but still terrible.
Loss before tax in H1 £(3.86)m, a bit improved from £(4.3)m H1 LY.
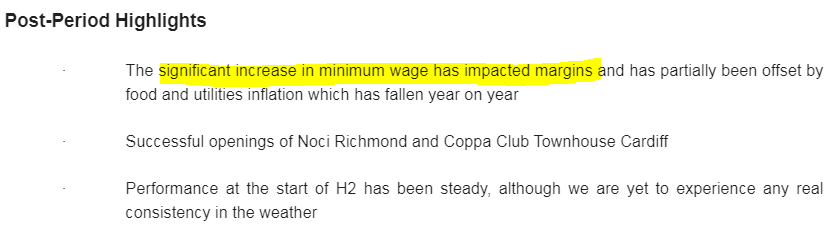
Outlook - vague, but sounds weak -
So far it has 20 sites, some of them quite swanky, looking through its website. However, central costs look far too high for a business of this small size, running at about £3.4m pa.
Balance sheet - this is the most significant change, and it’s positive. An equity fundraise in Dec 2023 raised £9.7m net of fees through 40.4m new shares being issued (24m to management) at 25p per share. Plus a debt-for-equity swap resulting in another c.45m shares also being issued to management. Overall, the share count has more than doubled from 82m to 175m. However, at least the finances now look on a sounder footing, and it’s very encouraging to see management (mostly Hugh Osmond) backing the company to the hilt. Although I still think de-listing risk remains high, because he might just decide the stock market isn’t attributing a proper valuation to the shares, and take it private on any terms he likes.
NAV is now £28.7m, of which £11.1m is intangible assets, so £17.6m NTAV.
Note it only has £2.1m in freehold property, the rest are leased. Also the NBV of fixtures, fittings & lease improvements are £21m, which is the sunk cost of fitting out all these swanky sites - the problem being they don’t generate an overall profit after all the central costs, so arguably these should be written down to nil.
Paul’s opinion - I’m increasingly coming round to the view that it’s almost impossible to make a profit from smaller groups of pub/restaurant/bars. Why? Because their costs are too high, after 2 years’ c.10% living wage increases, and wages are typically 30-40% of revenues. Combine that with a consumer spending squeeze, and people reluctant to pay ludicrous prices (everywhere apart from ‘spoons) for drinks.
Have any readers mystery shopped Coppa Club or Noci? I see there’s a Noci in Islington Green, where I often hang out (usually at Chilango, owned by Tortilla Mexican Grill (LON:MEX) after work, when I’m in London. I’ve literally never noticed Noci, despite walking past almost every day. Noci does a £15 lunch deal, so I’ll definitely mystery dine that next time I’m in London, and will report back here. Although the pictures on the website look like it’s one of those fancy places where you eat a meal, but need to stop off for a kebab on the way home, to properly satisfy your hunger.
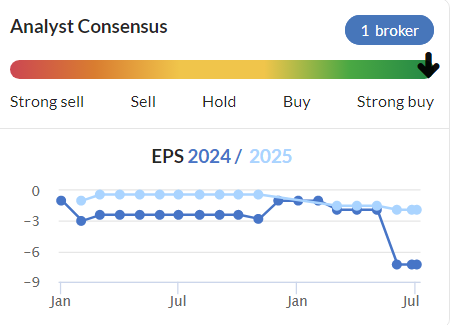
There’s no sign of a viable business here yet. Note broker forecasts were slashed deeper into the red a month ago. It’s fair that VARE says poor weather this year will have hampered performance, as it has some big outside areas that add a lot of extra trade when it’s nice weather. That’s true. As consumer confidence improves, and inflation recedes, then maybe performance could improve.
However, with more new sites planned, I can’t help feeling they’re rolling out a couple of formats that have not yet proven they’re viable. You have to decide whether it’s rich and stubborn founders ploughing more money into a failing business, or whether there’s an opportunity to achieve economies of scale here?
I would also add that VARE has spent a lot of money on its swanky site fit-outs. So these should be the boom times when those fancy new sites generate a good return on investment. That doesn’t seem to be the case. So imagine the millions that will be needed every few years to revamp the sites, to keep trendy crowds wanting to visit.
The main hope here is that we enter a consumer boom. The geared effect of c.75% gross margins in the hospitality sector could then prove lucrative for the survivors.
I suspect VARE could need another fundraise in future, which combined with de-listing risk, means I remain negative. Although the strengthened balance sheet means I’m happy to move up from red to AMBER/RED.
Graham’s Section:
Polar Capital Holdings (LON:POLR)
583p (£592m) - Results for FY March 2024 - Graham - GREEN
It’s time for a catch-up report on Polar Capital, another stock from my 2024 best ideas list.
Polar issued results for FY March 2024 while I was away.
Here are the key points:
Year-end AuM up 14% to £21.9 billion, despite net outflows of £1.6 billion.
Average AuM during the year flat at £19.6 billion.
Core operating profit down 6% to £44.8m, actual PBT up 21% to £54.7m (we’ll explain this in a few moments).
Full-year dividend: unchanged at 46p.
Snippets from the CEO comments:
"During the financial year, Polar Capital benefited from its differentiated funds range of thematic and sector focused strategies, particularly those with exposure to technology and its related sectors.
...AuM has risen further to £22.8bn as at 14 June 2024… "The positive net inflows of £56m as previously reported in the March 2024 quarter have continued in the current quarter with net inflows of £197m in the period 1 April to 14 June 2024…
The outlook is more constructive for risk assets such as equities with a continuing reduction in global inflation, interest rates peaking and central banks poised to ease monetary policy. Polar Capital has active, specialist and differentiated thematic, sector and regionally focused fund strategies with compelling long term performance track records and significant remaining capacity. While there remains geopolitical risk and a significant portion of the developed world population facing elections this year, our performance-led culture, strong balance sheet and improving sentiment for equities positions us well to continue performing for our clients and shareholders."
I’ve highlighted the standout pieces of information here: AuM has continued rising in the new financial year, there have been net inflows in Q1 so far, and Polar are positive on the macro outlook for reasons with which I’m sure many fund managers would agree.
AuM breakdown
Investment trusts are now 23% of AuM (last year: 20%), giving Polar marginally more protection against open-ended fund outflows.
In terms of fund strategy, Technology-focused funds have grown in size and are now 45% of AuM (last year: 38%).
Performance: strong numbers posted against peers and against benchmark (e.g. 72% of total AUM in the top two quartiles against peers over one year).
Explanation of the profit numbers: I think it’s worth understanding why “core” profit is down even though what I call the “actual” PBT was up strongly. Here’s the relevant table:
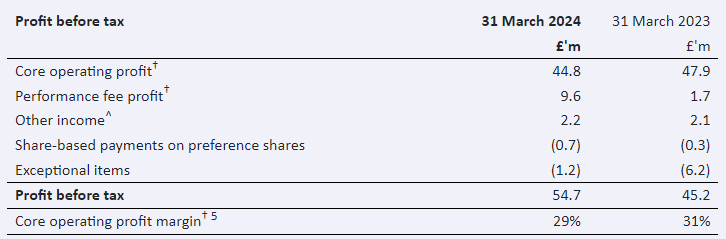
Core profit excludes the items listed here, with the main ones being performance fees and exceptional items.
We can see that in 2023, Polar had much lower performance fees and much higher (negative) exceptional items, both of which dragged on the relative performance of PBT.
So in 2024, actual PBT rose 21% despite falling “core” profits. As we often say here, “profits” are a matter of opinion!
Graham’s view
Regular readers will know that I’ve been bullish on most fund manager stocks for some time now, and Polar has been one of my top picks within the sector.
The Polar share price has shown some life this year, up 28%:
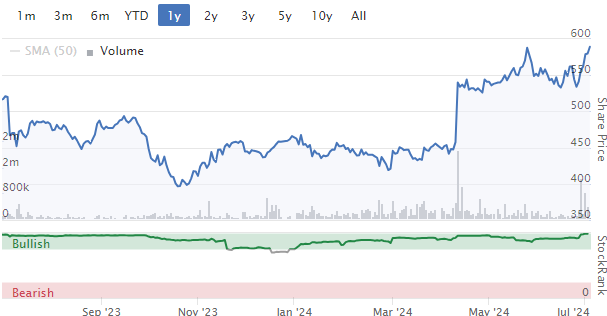
Today’s results show that even in a challenging year, with the company experiencing outflows, they remained highly profitable. They did need the help of higher performance fees and lower exceptional items to boost PBT, but that’s ok with me.
The fact that Polar is showing net inflows again in the new financial year is also highly relevant, although I must try not to get too excited about flows over one or two quarters.
The net flows number is the difference between two large numbers (gross inflows and gross outflows): it can be easy to forget this and how volatile the resulting “net” figure can be.
Polar had gross inflows of £4.4 billion in FY March 2024, implying that it had gross outflows of £6 billion.
That’s nearly a third of Polar’s total AuM that was churned by fund investors during the year. Fund investors do tend to churn their portfolios (in the same way that many stock investors do!) and the result is that fund management companies with open-ended funds are always vulnerable to short-term sentiment - whether that’s broad macro sentiment or sentiment relating to the fund management company itself.
Fortunately, I think Polar has maintained its high-quality reputation among fund investors in FY March 2024. Fund performance has been good and the company maintains its traditional strength in technology and healthcare.
The stock remains highly rated compared to its peers, e.g. the AuM multiplier is £38.50 (you get c. £38.50 of AuM for every £1 invested in POLR shares at the current share price).
Unlike its peers, it also has a double-digit PE ratio:
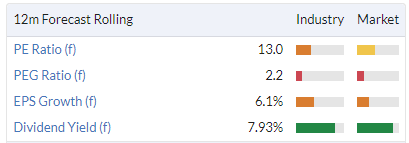
Even at this more expensive valuation, I’m comfortable maintaining my positive stance on POLR. It has an unblemished reputation in the sector, fund performance is good, and it’s experiencing net inflows again (although that could easily be reversed in any given quarter). I’m hoping for another good performance in FY March 2025.
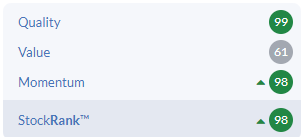
The StockRanks tend to agree with my assessment:
System1 (LON:SYS1)
Up 17% to 610p (£77m) - Final Results - Graham - GREEN
System1 Group the marketing decision-making platform www.system1group.com announces its results for the twelve months ended 31 March 2024 ("FY24").
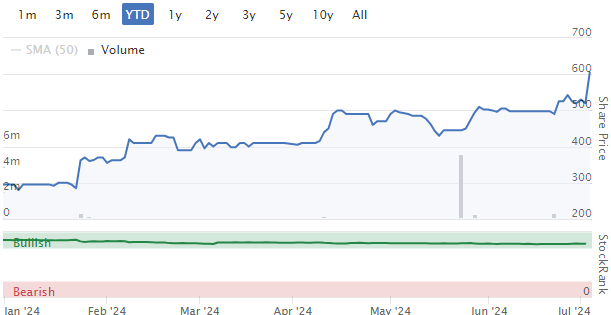
Paul switched us to GREEN on this one in January, following a second profit upgrade (share price at the time: 370p).
Fortunately, there was still plenty of upside from that point on. Here’s the year-to-date chart::
I was neutral on SYS1 in September (212p) and in December (218p).
It’s easy to say in hindsight after the share price has soared, but I agree that after the second upgrade, it made sense to change stance, as the business was clearly enjoying fabulous momentum.
Re-reading my December report today, I think my reasons to stay neutral were valid: the company had posted an excellent H1 adjusted PBT of £1.9m, but that number excluded over £1m of bonuses and commissions. Actual after-tax profits were only £0.6m. And while H1 revenue growth was excellent (27%), forecasts at that time suggested that growth in 2025 would only be 10%. Given the company’s many years of failure to generate material profits, I think I might still be able to justify my scepticism at that time!
Today, however, the company has turned up with truly excellent numbers for FY March 2024:
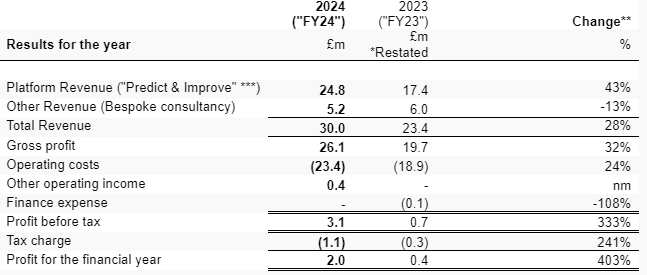
We finally have after-tax profits (of £2m) that I would consider material for a small-cap listed company - and it’s the best result for SYS1 in many years.
The company explains the profit growth as “owing to the flow through of far higher sales volumes and improved margins, more than offsetting a 24% increase in operating costs”.
Key performance indicators are no less exciting than the profit growth: the number of clients is up 44% to 428, free cash flow is £4m, and net cash has grown to nearly £10m (last year: £6m).
Dividend - 5p per share is proposed, a little less than a third of EPS (16p). The policy is to distribute 30-40% of average (“through the cycle”) earnings
CEO comment includes news relating to the new financial year:
"Our success last year was underpinned by 260 new client wins and our scalable growth model. In the coming year we will step up investment in attracting, winning and retaining customers in order to continue our growth trajectory. The new financial year has started strongly, particularly in the US, and we anticipate an increase of 50% in Q1 total revenue with platform revenue up 70% versus Q1 FY24. As a result we continue to expect strong double-digit revenue growth for the financial year as a whole."
The Outlook section provides more detail. I’ll put it in bullet points:
Bespoke consultancy revenue will fall as long-term contracts end. This “should not significantly affect overall group revenue or profit growth”.
1st big opportunity: US market. A new Chief Commercial Officer is US-based.
2nd opportunity: “Test Your Innovation” product suite relaunched.
3rd opportunity: growing revenues from large advertisers who are already customers of SYS1.
Graham’s view
I’m happy to maintain the positive stance on this one, as in general it’s wrong to stand in the way of momentum, whether that is business momentum or share price momentum - and SYS1 currently enjoys both.
The enterprise value is £67m once you deduct the cash balance from today’s market cap. Canaccord are estimating adj. PBT of £4.4m in the current year (FY March 2025) and £6m the following year, implying some reasonable cash-adjusted (pre-tax) PE multiples (15x this year, 11x next year).
I note also that it’s another upgrade from Canaccord this morning; they previously estimated adj. PBT of £4m for the current year. They say they have now made six consecutive upgrades!
Checking the cash flow statement briefly, I note that the results were not boosted in any significant way by capitalising software development costs.
For those considering an investment here, the management bonus schemes here should also be worth a look.
The company’s 2021 LTIP has granted options equivalent to 9% of the existing share count, but the conditions for them to “vest” aren’t being fulfilled. Therefore, the company has created an “STIP” (short-term incentive plan), something I’ve never come across before!
Overall, it seems that SYS1 is finally performing as well as it threatened to for so many years: its sales efforts are working, and its reformulated product set is working. It would be churlish of me not to be GREEN in these circumstances.
Value ratios will need to be updated soon, e.g. for the dividend:
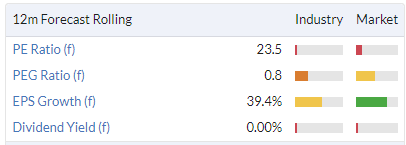
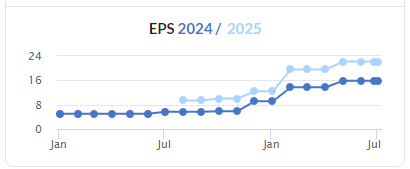
And yet another EPS upgrade will be on this chart:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Hi Paul and Graham,
I just want to say a huge thanks for the amount of reports you guys get through. It’s very much appreciated.
Very kind, thanks Daz! It's certainly a challenge, but we enjoy it most of the time! ;-)
System1 (LON:SYS1) - I've just watched the webinar on IMC at 15:00 today, and I think mgt came across very well - straightforward, and non-rampy explanations & answers. Good body language, no warning signs I detected anyway.
They seemed to want to rein in growth expectations, it sounds like the year just reported was exceptional, and growth might moderate in % terms as the numbers get bigger.
What I like about this is the scalability - huge markets (esp USA) and SYS1 seems to have a distinctive service that's in demand, with claimed very effective paybacks for clients. It would be good to hear some independent verification of this from anyone who has used SYS1 as a client. Are they as good as they claim to be?
Wish I'd bought some when we first spotted the growth accelerating! I've just had to pay over double that price to pick up a couple of scraps today!
Paul,
I watched the System1 (LON:SYS1) presention too and was impressed. My notes:
Some 80-90% of revenue is now the Test your Ad Platform. Ad Testing market size $2.5B ( SYS1 <1% market share). Focusing on US market (55% of total). Doubled sales team over last few years especially recently in US.
If sales Double from £30M to £60M Ebitda will Quadruple to £18M. Paying out 32% PAT as new dividend in October, although the %yield will be low.
System1 (LON:SYS1) is certainly an impressive turnaround and demonstrates how stock picking is such a difficult task! Ed Croft included it in his NAPs for 2022 and it was the worst performer in the NAPs, down 68% during that year. Since the nadir of end 2022 when the price hit 140p System1 (LON:SYS1) has nearly 5 bagged in a little more than 18 months. Looking at the stock report at 27 December 2022 any investor without strong knowledge about the business and its products/services would have steered well clear. Perhaps Ed was just a year too early! The recovery also demonstrates the point made in the 'multi bagger' analysis that even these type of shares have serious setbacks. The secret, which I definitely haven't mastered, is to know which stocks to stick with and which to jettison when tough times strike.
I work in the marketing effectiveness field so had already had some good knowledge of System1 (LON:SYS1) . Have not used them myself but have had numerous demos, and know others in the industry that do.
I first bought in Jun21 at 228p, sold in Jan22 for 420p, when the last "excitement" wave came and went.
I also steered clear in Dec22. It wasn't just the numbers that looked bad, but I wrote "the strategic review is a damp squib, wait for next update, more pain still to come, new CEO".
It was really only starting mid-23 that the signs of a turnaround were starting, and I could see that operationally they were getting their act together to sell the s*** out of a great product.
Bought in Nov23 at 190p. I do wonder if I wasn't so conservative and bought earlier at cheaper, the gains would have been so much more...
However, I did top-slice some at above 400p in Feb24, which I regret now but at the time it was the right decision. Portfolio weighting, risk/reward balance, etc.
I also watched the IMC today. Some interesting tidbits.
Headcount growth is what worries me; as that's what got the company into trouble the last time (when it went from 400p+ down to 140p). They bullishly scaled up ahead of revenues/profits too quickly (and management failed to deliver on the growth promised).
(I hold in the Boon Fund)
Spirent Communications (LON:SPT)
Are there any current holders of Spirent on here?
It would seem there is an arbitrage opportunity of 10% on offer if the Keysight bid goes through. Against today's buy price of 181.5p Keysight have offered 199p plus 2.5p special dividend. I have wasted time scrolling through a raft of RNS's to find the latest position, shareholders should have voted on the bid by May 22nd but after that the trail goes cold, I seem to remember reading that if successful the deal would go through in the second half of 2024 but i cannot verify that.
Has anyone got an up to date position or any thoughts please?
TIA
The market price is telling you that the deal could well be blocked. Remember that the underbidder has refused to raise their own offer in the belief that Keysight will run into Competition Authority issues. Buying Spirent Communications (LON:SPT) now is a punt on that not being correct.
I don't hold Topps Tiles (LON:TPT) and haven't in the past (although been on my watchlist since 2021!). My list of holdings, at the end of every month, is always fully published on my Substack.
I haven't had a chance to digest TPT today, been too busy... but it is a share that interests me, because it is still profitable, it has a decent enough balance sheet so won't go into trouble, it has a market leading position (£1 in £5 spent) AND they claim they keep increasing market share, signalising some competitive strength that will be profitable once the demand growth turns positive again.
Will this 2-bag or more? Probably not IMO. There's not enough here, unless they come up with a bold plan for Online + B2B to dominate those industries too...
But I can see an easily 50% gain, safe gain at a certain price once the cycle turns.
Topps Tiles (LON:TPT) A headwind will be increasing container costs.
I got lunch from Tortilla Mexican Grill (LON:MEX) in Southwark today and must say it was excellent. It was fast, fresh, the staff explained how it works very well, absolutely banging burrito which I ate walking across Waterloo bridge. Most impressively it was wrapped sensibly so that I didn’t spill any down my front. Full marks. I’ve been adding to my holding in recent weeks.
I would love to know how a MEX franchise stacks up Vs a Subway franchise if anyone has any idea.
Hi Paul, in terms of the updates I really value the detailed analysis, but would prefer to see it focussed more on Green and Green/Amber issues and less time spent on Amber and lower. Generally I skip through those as those stocks are less attractive for reasons you identify which I generally agree with.
Hi JonBeddell,
Thanks for the feedback. I understand your point, about us focusing more on the GREEN shares, which I think we tend to do that anyway - we usually start the day with any "ahead of expectations" updates - even if it's just to flag a good update early in our colourful list!
But we're mainly driven by the "most viewed" widget on the Stockopedia home page - that's telling us which shares the subscribers are in aggregate most interested in, so we prioritise those accordingly.
Also remember we're building & maintaining a literal stockopedia - so that subscribers can have an online reference book, to look back at our comments on something they might have read about, or has been tipped somewhere, and quickly be able to see our explanation of what's wrong with it!
So yes we'll flag good companies that are trading well, but a key thing is we also hopefully deter people from buying shares in total crocks by researching & writing about those too.
We're covering over 600 shares, which is not far off half the UK market, and I'm trying very hard not to miss anything good, within the mainstream sectors we cover. Any gaps in the list are usually things we've had a quick look at, and don't think are worth spending any time on.
Regards, Paul.
Hi Paul I never cease to be amazed at the effort you put in to providing considered commentary not only on nearly "half the UK market" but also on points raised in the SCVR comments. Thanks
Hi Paul, no complaints here, I find the mid morning updates very helpful and the detailed write ups excellent. I appreciate you also need to justify lower ratings with quality analysis so that makes sense too. All in all I’m a happy subscriber.
Great, thanks Jon, good to hear! :-)
In your latest podcast Paul you ask for feedback on whether we subscribers prefer a few very detailed reviews or a wider range with less individual analysis - my vote is for the latter. You also moan how some AIM companies that have announced they intend to delist don't mention this important fact in any subsequent RNS. One answer to this would be if Stockopedia flagged this up at the top of their report – as you do if a company is subject to a takeover bid.
Hi Globes, I agree that Stocko could flag this up, They do it for take over stocks so it shouldn't be too difficult to do it for companies delisting.
That's a good idea Globes, I like it! (a pending de-listing field on Stockopedia). Worth flagging that to HQ, as a suggestion for improvement, if such a field is available from the data providers.
Tissue Regenix (LON:TRX) (I hold) unusually high volume today: 761,991 vs Avg Volume of 50,349 (Stocko @ 14:10).
RNS today: Richard Sneller increasing his holding by 1.1% to 15.1% and Harwood Capital LLP holds 14.87%
Tissue Regenix Group plc is a medical device company in regenerative medicine. The principal activity of the Company is the exploitation of platform technologies in the field of bone graft substitutes and soft tissue.
Sales CAGR (3y) of 21.49% and Stocko forecasts becoming profitable in 2025 with EPS Normalised of 1.33p. Shares70m total.
Thank you for bringing AUTO to our attention. Is it a big rise that I smell? Hope so.
Ashtead Technology Holdings (LON:AT.) - A little reminder that following the crowd isn't always the smartest move. Panic selling on no news after a big pull back just because other people have chosen to do so isn't an investment decision, it's a self preservation reaction. Particularly over the longer term it is unlikely to benefit you, you might just giving others a chance to buy in at a better price.
Aside from a TR1 showing Abrdn reduced their holdings slightly on 30th May there has been no actual news in the last couple of months at Ashtead (maybe some mild worries about a labour governments taxation policies that don't seem overly relevant to the company). Despite this, the SP of Ashtead Technology Holdings (LON:AT.) fell back from a high of 880p to 688p, close to a 25% pull back, probably taking out some major stop losses on the way. There was a rush of volume as investors and traders sold (as was the case in a number of other stocks). In the following few weeks the SP has risen back up from 688p to 810p, it is now comfortably above the 50day MA again. Close to a 20% gain for anyone who bought the dip. I was fortunate to get in at 696p after it was raised by Rusty2, WOSS and Helvellyn on the Summer Stage 2's board, so thank you as always to those investors for sharing their knowledge.
Is it not a bit prudent to be wise on shares that drift on seemingly no news though? Could it be that there is news but that it just isn't available to PIs? YouGov (LON:YOU) rose from around £8 to just under £10 recently and then drifted down on seemingly no news before hitting with a profit warning.
Topps Tiles (LON:TPT) Broker eps forecasts down 10%, stock down 3%. I could be wrong but that says “bottom” to me, provided no further unexpected deterioration. It also happens to be the level of the Autumn 2022 low, so should be some support here. I know a couple of others are in this one, Boon perhaps? Add me to the list as I trim some extended winners and top-slice strongly performing building supplies stocks with regulatory backing (Alumasc (LON:ALU) , Epwin (LON:EPWN) etc)* and shift the proceeds into this recovery-dependent name.
* to be clear, I’m still holding my original investments, just capping the size of the stake.
Hi BnB,
You could be right, re building supplies sector at or near lows. Another point with Topps Tiles (LON:TPT) is that it's still (just about!) profitable, and cash generative, with an adequate balance sheet. So I don't see any concern over either solvency or dilution.
The operationally geared upside on some of these companies could surprise to the upside once economic recovery is more firmly established, and we start a broker upgrade cycle.
I like the other 2 you mention, and would add Eurocell (LON:ECEL) to that list.
Not sure about Headlam (LON:HEAD) though, that looks like it could be in trouble, but does have the cushion of large freehold property.
I seem to recall that Brickability (LON:BRCK) was another building products potential recovery trade too.
Regards, Paul.
You could add the brick producers to that list - my preferred pick is Michelmersh Brick Holdings (LON:MBH) but Forterra (LON:FORT) another possibility
Not a Small Cap but one of my stalwarts held since 2016, never added to, just kept in the background. Smurfit Kappa (LON:SKG) , interesting in the way it went from London to the Dublin Exchange, now returning to London and opening on the New York Exchange soon having joined with Westrock. Good luck to the Irish in succeeding in the US, I say.
A bit more volume than the usual 0 trades ex earnings reports a day for Northcoders (LON:CODE), especially since Dowgate RNS'd their 5% stake last month.Slowly moving up on little volume, although to be fair could equally mean they plunge on little volume.Nice, little company with good ceo/founder with a great idea and industry experience i thought and with decent secular winds potential..... coding bootcamps and government funding (part of the government's lifetime skills guarantee and plan for jobs - for what that's worth) to boot.'Its aim is to help passionate and capable people who live in Yorkshire and The Humber, the North East and East and West Midlands become the tech leaders of tomorrow.'
Fund managers stocks
Graham has reviewed POLR today but he is generally positive on most fund managers stocks. They are lowly rated in this cycle but not for long in my opinion. I also rate the platform player in this section, ABRDN (owns ii), IG are my favourite.
I expect a wave of M& A among these stocks in the next cycle. LIO and JUP are my candidate.
IPX is out of favour because of its ESG funds but a new government may bring some changes at the detriment of fossil fuel producers who are incidentally also good value at the current prices.
In addition to ESG, I would expect infrastructure funds to benefit from government contracts and a drop in interest rates.
These include the more traditional, such as BBGI Global Infrastructure SA (LON:BBGI) HICL Infrastructure (LON:HICL) and International Public Partnerships (LON:INPP), and their energy transition equivalents, including Downing Renewables & Infrastructure Trust (LON:DORE) , Octopus Renewables Infrastructure Trust (LON:ORIT) and Renewables Infrastructure (LON:TRIG) .
Most of them are showing signs of the sp recovering and all yield over 6% while you wait
American politics is so crazy I wouldn't be surprised if Rodney Dangerfield replaces Biden.
Was it ever clear why the Equals (LON:EQLS) management put the business up for sale? I can't recall anything being said that pointed to a strategic or even a personal reason.
My personal view is that they see themselves as vulnerable in the type of business they are in despite their growth, and have decided to sell whilst the metrics look good. But this has proved somewhat of a duff decision so far, for reasons that aren't clear when its been buying season for many other businesses.
Hanging on for a buyer is not a good look, but their tenacity in doing so for so long looks odd to an outsider.
I have sold out my positions but it must be nerve wracking for holders of bigger positions. Let's hope they get their rewards.
Equals (LON:EQLS) . I used them to buy some Euros recently, forced to, because of red tape at my brokers, was surprised by :a / The size of the turn ...they took (1.5 Eurocents ) and b/ The lack of paperwork required to set up the account.
I suppose if you were a shareholder a +b are good, but next time I would expect to get a better price and I would only go to them if I had to.
I would be grateful for your thoughts on Cairn Homes (LON:CRN)
See below.
"Berenberg cuts Keywords Studios to 'hold' (buy) - price target 2,450 (2,090) pence"
In other news, Berenberg think Labour has a reasonable chance of winning the election.
thank you Graham for looking at #POLR much appreciated
Intercede (LON:IGP) are on a great run since results and partnership with Carahsoft were RNS'd. Long may it continue. I know Paul said he's been buying. Very shrewd.
Thanks Peter T,
Yes I'm very pleased with progress at Intercede (LON:IGP) [I hold], one of my top 20 shares ideas for 2024.
It's has that look of a company where everything is coming together nicely, after years of turnaround work by a CEO I rate very highly.
My view is that looking too closely at results & broker forecasts is missing the point here. A small company that can win major contracts with huge organisations, especially US public sector, could have a value well beyond a multiple of the short term profits. Large, very sticky contracts too, so the upside case I'm hoping for, is an increasing flow of contract wins from the big systems integrators it now works with.
The catalyst for this amazing bull run seems to have been IGP's Capital Markets Day. I watched it on my laptop in Gozo, and the bit that really stood out as remarkable was that a partner of Guidehouse (US public sector consulting firm, formerly part of PWC) flew out to the UK to attend IGP's CMD, and gave a highly supportive talk, saying how impressed they are with IGP, and how well they work together. Sadly it couldn't be recorded for playback, so was a one-off, but it really impressed me, and I bought more shares during the CMD (often dangerous!) but it's worked out well so far.
How to value it though, and if/when to bank some profits? No idea! Personally I've just decided to run with it, and see where we end up, rather than trying to predict what the short term price does.
I hope some subscribers here are also on board, and enjoying the ride! Let me know what you think - how much do you think it's worth, and should we be thinking about banking, or running our profits?
Regards, Paul.
Agreed Paul re Intercede (LON:IGP) . I've held them off and on for 20 years as the product has always been market leading but the previous management less so. The new CEO (ok 5 years now) has corrected that. He took time to invest in the product, invest in the channel and leverage their reputation/knowledge to expand their TAM by moving into Multi-Factor Authentication and Password Security Management. They are the global market leader in high-end PKI credential management and are smart enough to use that to exploit niches in the more competitve MFA/PSM space rather than compete with the Microsofts of this world.
Their results will always be lumpy due to the large perpetual government contracts (although they are gradually increasing the SAAS element) but the recurring S&M revenues cover 95% of their cost base and they have a large cash buffer.
Their markets are growing at 20% a year and Ukraine/China means the EU will soon follow the US in stepping up their credential management regulations.
I started increasing my holding significantly after the October interims and now hold over 2% of the company. They are one of my top ideas for a 5 bagger over the next 5 years so am not selling a share even if the SP gets ahead of itself in the short-term as you never know when the next big contract will land.
The Brothers
Re Intercede (LON:IGP)
Wow! Thanks for the interesting and insightful information and as for 2% of the company - talk about conviction!!
Once the balance sheet was fixed, there was very little downside. As Paul (and the CEO) say, they have a client list to die for. Over 95% cyber breaches come from lax credential management. Intercede (LON:IGP) are market leader at the high end so it’s more a case of when rather than if for their business to take off.
I’ve also done very well with Intercede (LON:IGP) taking profits after a great run from 2021 and then buying again at 66p after their better than expected update and more contract wins last November. Both buys were largely the result of Paul’s quality analysis on the day of those Intercede updates.
e.g this one on November 23rd:-
https://www.stockopedia.com/co...
Intercede (LON:IGP) is the sort of share I probably wouldn’t have known about prior to subscribing to Stockopedia. I know Paul is not a tipster and I don’t treat him as one, but the consistent high quality of his and Graham’s analysis is extraordinary and at times must convince others too that a share they cover is well worth further checking as a potential buy.
Thanks ken, pleased to hear we helped you make a bob or two! :-)
Thanks Paul. ZANE benefits every month as a very modest pay back for your efforts.
Intercede (LON:IGP)
Paul - I agree with your thoughts on the CMD and I regard this as a strong hold and would look for any dip to add (while regretting not filling my boots at less than 50p last Sept/Oct but hindsight is always wonderful).
I came across this brilliant interview that I don't think has been mentioned here where the CEO talks about his approach, not just to the organisation but to the culture - worth watching:
Capita (LON:CPI) Interesting to see on https://www.voxmarkets.co.uk/a... that Rockwood have bought a stake in CPI. Surprised me.
Following on from Shoe Zone (LON:SHOE) profit warning yesterday I see that both Charles and Anthony Smith have transferred their entire holdings from their corporate vehicles to their (and their spouses) personal names. They hold 58% combined so not insubstantial.
Can anyone speculate why this would be? Apart from the obvious corporate CGT benefit on sale
Election reasons, corporate actions pending??
Re Shoe Zone (LON:SHOE) - a transfer is a realisation event if moved from one legal owner to another, so I'd guess they are taking advantage of the lower SP to minimise tax impact
Shoe Zone (LON:SHOE) Restructuring of their ownership are all government change related: Optimising for potential changes in inheritance tax rules. Enabling more efficient distribution of income between spouses. Establishing new base costs before potential capital gains tax rate increases. Streamlining structure to prepare for possible new regulations. Personal Allowances Utilisation: Better use of individual tax allowances and exemptions. Restructuring ownership to manage potential new wealth taxes. Increasing flexibility for dividend income distribution and taxation.
Shoe Zone (LON:SHOE)
Thanks both for your suggestions
Looks like Joe Biden is withdrawing from the presidential election giving way to Kamala Harris.
All the best
Where are you reading this Yiannos, can't see it on Sky or BBC yet.
US trusted source forwarded to me the latest odds-Kamala Harris odds to be the next president are shorted than Joe Biden’s-very strange !
He believes that with Gavin Newsom or Whitmer as running mate they will this and that there will probably be an announcement after the 4th of July celebrations.
We have to wait and see.
All the best
US trusted source forwarded to me the latest odds-Kamala Harris odds to be the next president are shorted than Joe Biden’s-very strange !
all you need to do is look on betfair exchange - that confirms this is correct.
No certanties here but as biden now only 1 in 8 chance according to bookies of winninmg election (trumps odds havent really changed much) it seems highly likely we are simply waiting for the official news that he will stand aside (perhaps he aint agreed and or been told yet) . Kamala i think was 40-1 not very long ago and is now slighly less odds than Biden - so it looks like that Kamala is most likely to get the nod when Biden agrees to go but no shoe in (Newsom then Obama next most likely)
Just taken a look at this. Interestingly, whilst Harris and Biden are similar odds to be President at around 6/1 on most sites, Biden (7/5) is still listed as more likely to be the Democratic Candidate over Harris (9/4). Suggesting, the bookies feel the Democrats have a better chance of winning with Harris at the helm than Biden. However, it is still more likely (only just at this moment according to bookies) that it will be Biden running for office.
Biden (7/5) is still listed as more likely to be the Democratic Candidate over Harris (9/4). Suggesting, the bookies feel the Democrats have a better chance of winning with Harris at the helm than Biden
i think you may have this logic wrong? - i think the decomcratic nominee is decided in august - not sure how plausible it is but i have heard talk of him not being replaced till after he is made the official candidate. based on current trends i would say its a long time for biden between august and November - so i would be doing anything other than preduming he wouldnt be ousted in that time period after he is made tehn official candidate. so in summary if the 9/4 shot pays out in august at that earler time you could lose that bet on harris but she might win the election by replacing him after that bet is settled.
pretty sure that i read the main reason Harris was such a long odds shot to become president was that she was polling much worse than biden if she was up against trump - that should be pretty easy to fact check. I guess if they had anyone clearly obviously expected to do better than Biden , Biden would have gone by now and thats the issue - its all lined up for Ombama to change her mind right now and give us a top weight matchup .
Hey ho all my speculation i could be talking gibberish as normal.
US politics- Not something I'm overly knowledgeable on to be honest rmillaree, I'm just regurgitating the odds and trying to make sense of them. Either way I can't see past a Trump win myself no matter who he's up against. I have certainly heard a few times what you mention about Harris being unpopular with voters.
If so they lurch from one poor choice to another. People have no faith in the competence of Harris.
Interested to read your opinion and the consequences on the financial markets on any candidate and how the bond market will react!
We had a taste on what the bond market thinks on Trump2 and the aftermaths of the debate.
All the best
John Authers of Bloomberg gives some views in his Points of Return article this morning. Anyone interested can sign up for free at https://www.bloomberg.com/acco...
That's a Trump win then
My post has more to do with the consequences in the financial markets , interest rates and inflation and not taking any sides.
A Trump win and the aftermaths on China’s tariffs will be terrible for the markets.
All the best
Hi Yiannos1,
I'm a little more hopeful regarding the markets if Trump gets elected. Can't stand the man but my hope stems from his laziness. During his first term as president he spent 1 in every 4 days playing golf and a considerable amount of the rest of the time spouting on Twitter.
Essentially showing little desire to change too many significant policies, building walls etc as that would require effort. In the mean time the economy and the markets ticked along nicely from 2016 until Covid. Potentially history could repeat itself.
Far more dangerous would be a loon with a work ethic as we witnessed with Truss...
Unfortunately the zealots that support Trump are going to do all the heavy lifting with what they are driving at in whole areas of destructive action, especially with regard to permanently skewing the civil service by changing career appointments to political ones. The long term damage to a civil and inclusive society are almost incalculable. We are seeing a taster with the political corrosion of the Supreme Court. For investors the main effect could be the extension of the US’s overreach into international trade by use of damaging tariffs and bans such as those currently bedevilling the sale of items that include any US content. For this I would particularly be concerned for UK companies in the defence businesses.
Unfortunately the zealots that support Trump are going to do all the heavy lifting with what they are driving at in whole areas of destructive action, especially with regard to permanently skewing the civil service by changing career appointments to political ones
it seems unfair to single out Trump when this seems to be par for the course ref everything us. Each country to their own but super happy we try and stay away from political people (mostly) when appointing judges/police chiefs and da's and the like (hmmmmm about police?) - i fail to see how they dont see the stupidity of their setup. If politically minded da's have a specific goal of taking trump down at time of election in some respects i dont even blame trump for fighting back dirty as its already a dirty system (imho) that is probably prejudiced against him. Note i dont have any sympathy for trump he has clealry made his own bed by his past actions.
unless Obama steps up to the plate - imho she would be the obvious choice if defetaing trump is most important thing - only issue being that up to now she seems to not have wanted the job.
be aware that us nationals are blocked from betfair exchange and anything like that (i know a few get round it by being in New Jersey - there are a lot of VPN endpoints there :). This means that the activity on betfair exchange reflects a fairly european view of US politics.
(Disclosure - I backed trump late 2023 - I dont like him but thought he would win - and from what I have read, on china, trump and biden do not seem to be much different)
Thanks Andrew spot on. You know your stuff.
That’s why I said in my original post a US source.
All the best
This means that the activity on betfair exchange reflects a fairly european view of US politics
Actually the betfair exchange price reflects a global price (a global view). The fact that it is restricted in certain locations is not relevant. The price differences get arbitraged away instantly (by multi account users, by value chasers, and by professional algorithms) - so books across the globe rarely get out of line for very long or by very much. The algorithms pick up on these small mis pricing anomalies and therefore they don't last long. There is no such thing as a European price vs a US price. The betting markets are extremely connected globally and you will find the that US prices will be a shorter price than the betfair exchange (how short depends on how greedy the operator is in terms of the spread between outcomes). This is the same as the UK prices which will also be shorter than the exchange - as soon as this moves out of line, there is an arb to be done and it gets gobbled up instantly.
I think Andrew was implying that the first move is made in the US and then everything adjusts accordingly and that’s the reason the US betting firms were the first to change their prices for the US presidential election.
Same here , I do not expect a US firm to be quicker than a UK equivalent one in the UK elections outcome. Simple to understand as almost all money come from UK bettors and prices adjust accordingly to exposure bookmakers have on these markets.
All the best
You said it better than I could :)
Results bang in-line with upgraded expectations at System1 (LON:SYS1) but sounds like Q1 has got off to a flyer and broker expectations for growth in the next year is modest - so expect some upgrades in the months/weeks ahead. Looks like CEO has managed to wangle a fair chunk of increased revenues into his back pocket... but whilst the business is booming and the share price rising I suppose we can't complain too much. Looking forward to Graham's analysis.
I'm also very pleased with System1 (LON:SYS1) results this morning, having taken a quick scan.
Maynard Paton also wrote a long blog post recently. Think he is bullish about a 1500p target share price (currently under 600p).
I'm impressed they managed to find more gas in the tank for growth;
Platform revenues - Q1 is +70% YoY. Q4 was +42%. Q3 was +46%. Clearly a step change?
However, they very prominently flag up massive recruitment this year... to keep up with growth... also that gross margins long-term will be lower than now...
Still, I think its hard to see profits not rising strongly over the next 1-2 years when growth is this strong. They also have net cash, so fully self-funding.
(I hold in the Boon Fund)
I see the SYS1 share price is up 15% this morning. I flagged the possibility of SYS1 good news on Monday, so it’s nice to be right occasionally.
…The System1 (LON:SYS1) YE announcement is 28 days earlier than last year (1st Aug 23)…. Could this be a case of SYS1 management being keen to announce further good news?
There is an Investor Meet Company at 3pm this afternoon for anyone interested.
IG Design (LON:IGR)
Further to post yesterday Joe Turner - see below, re shipping costs and general supply chain management, there is a very detailed and interesting note out this morning from Canaccord Genuity on Research Tree, entitled Price Weakness presents buying opportunity, describing the various actions management have taken to mitigate risk, control and even share shipping costs and protect/improve margins.
Joe TurnerJoined 201849 postsYesterday 10:24 am
Yes, freight cost is an issue for IG Design (LON:IGR) but I'm not so sure it's as big an issue as in the past (i.e. when it got walloped during covid). It made op profit savings of $8.7m in FY24 from normalising freight rates, but it also made op profit savings of $34.8m in FY24 just from better sourcing, so there are self help measures it can take to reduce impact imo. Can they repeat the improved sourcing next year ? Who knows. They are also closing down their factory in China & increasing near shoring, (esp in Mexico) so they're aware of need to minimise freight impact. They've also spoken to customers after covid near disaster and agreed to share more cost of possible increased freight rates in future as they took hit themselves during covid. Best way to reduce freight impact is to increase sales and that's next step of their recovery plan so we'll see. I'm a holder so I'm biased but I think mgt here are pretty switched on and I still think it's an interesting recovery play that's not fully played out yet.
This is a very good point Joe and one I picked up from listening to the recent Y/E results PI World presentation - it is specifically mentioned.
Profit taking and a market overreaction to 'bad' news has created a suitable buying opportunity for those that have missed out on the way up??
Would be interested in any thoughts on Activeops (LON:AOM) audited FY24 results. Before anyone asks, they offer, in simple terms, decision & productivity software to manage the workforce more efficiently (that took me some time!). Some highlights of interest:
• Profitable at PBT & EPS level now
• ARR at £25.1m valuing it at a ARR/EV of 2.2x
• Cash running better than expectations & currently at £17.6m
• "the business has started to see the benefits of the operational leverage inherent in the business model"
• CEO founder with 14% stake and runs a tight ship
Worth a look at least I think. I hold
I like Activeops (LON:AOM) MGinvestor.
The high PER is a bit of a red herring - this business could be doing much more profit but chooses not to as it wants to invest for long term success.
This is all genuine long term ARR now growing at double digits and that will drop through on an operationally geared basis now. We are starting to see that in last 12 months.
Typically businesses that support sticky long term financial institutions trade on a high multiple. Share price seems very stable in this range gradually creeping up. Think it could compound well as a longer term investment.
My morning smallcap tweet: Invest Side Story
Tekmar (LON:TGP) Shield Therapeutics (LON:STX) N4 Pharma (LON:N4P) Eneraqua Technologies (LON:ETP) Topps Tiles (LON:TPT) Physiomics (LON:PYC) Equals (LON:EQLS) Tribe Technology (LON:TRYB), Braemar (LON:BMS), Activeops (LON:AOM)
◄Tekmar (TGP)► wins €4m contract for delivery in Dec 25. [SP=9.25 Cap=13m]
◄Shield Therapeutics (STX)► $5.7m monetisation agreement with its largest shareholder for the right to receive the $11.4m China approval milestone payment from Jiangsu Aosaikang Pharmaceutical. [SP=1.69 Cap=13m]
◄N4 Pharma (N4P)► subsidiary Nanogenics has submitted an orphan drug application to the FDA for its product ECP105, for the prevention of scarring following glaucoma surgery. [SP=0.45 Cap=2m]
◄Eneraqua Technologies (ETP)► AGM stmt - election has slowed decisions by certain customers delaying some rev into H2 FY25. Still ecpects a return to profit in H2 and FY as planned. [SP=48.93 Cap=16m]
◄Topps Tiles (TPT)► trading broadly unchanged from that described in interims. Q3 rev down 7%. LFL down 9.7%. [SP=40.7 Cap=80m]
◄Physiomics (PYC)► £381k placing at 0.6p, a 50% discount, for various purposes. Also WRAP Retail Offer for up to £25k. Are you kidding? [SP=1.12 Cap=2m]
◄Equals (EQLS)► guides H1-June rev up 33%. Net cash £20.5m. Update on sales process on 10 July. [SP=119 Cap=223m]
◄Tribe Technology (TRYB)► joint development agreement with global mining technology company IMDEX "to develop future technology". No min revs for Tribe. [SP=4 Cap=10m]
In line: BMS, AOM
Cairn Homes (LON:CRN) in todays H1 2024 TU Irish home builder Cairn Homes report very strong revenue growth, 66%yoy, and another 45million E share buyback programme. I think Graham usual casts his eye over this one. It would be good to hear his opinion again.
This is one of my top 3 shares and. All the metrics are very positive. In my humble opinion, it compares very favourably on most metrics against it's UK based peers. With a very positive outlook, I will look to top up following recent pullback. Are there any negatives anyone can see as I may have my rose tinted glasses on?
Cairn Homes sits at number 9 in our portfolio philg2, I wish I'd bought more and I'm also looking to add. I often miss the potholes in balance sheets and appreciate the advice Paul Graham Roland and subscribers give.
Cairn Homes (LON:CRN) bought a while back for the divi and forward prospects. Cyclical buy and wait until the taps get turned on, all the while underpinned with share buybacks which I'm always attracted to. Still cheap, cheap, cheap IMO - I bought in at .94 and whilst there has been some weakness recently, today should see a decent uplift (double digit?) Still over 7% div.
Excellent growth and order book, with some Govt schemes boosting profit.
New opportunities in pipeline.
Now in a housebuilding boom.
Will benefit greatly when interest rates drop.
May add some more.
Morning Helvellyn, philg2, and JASVFS,
I had a very quick look at Cairn Homes (LON:CRN) a moment ago for our list, and the figures look great! Striking difference between its performance in Ireland, and the UK housebuilders.
Today seems in line exps, and the StockReport shows fwd PER 8.3x, divi yield of 7.2% (plus another E40m buyback announced today), and price to tang book is reasonable at 1.34.
Not sure if Graham will get round to it, as he's planning on doing some fund manager catchup items from y'day. But suffice it to say, no quibbles from me on CRN, it looks excellent. Thought I would post this in case we don't get time to cover it in more detail.
I suppose the question is whether we buy the UK housebuilders for a recovery in 2025 (arguably already priced-in), or just buy a barnstorming performer CRN in Ireland!?
Regards, Paul.
Morning Paul,and CRN investors. This is one of my top three holdings [AT from last year ,have top sliced but still an interesting hold - CRN,and TIME sieved from CDrefs reference points. CRN in the 90 p's and Time 27p ,so very pleasing .]
One of my interests after buying is upgrades [usually add more at such times] .
Time have recently done this with trading comment ,and I believe CRN are just about to have one too - because of this comment, all other metrics being sustained , of course, - 'We will grow our output by 30% this year and invest heavily in 10 new site commencements, including eight in the second half of 2024. , ' . This suggests , to me , we will have an upgrade before the year's out.
Otherwise well done CRN, and Irish govt, support too. I hold some VTY [I believe in the best position of UK builders due to the contracted builds ] . Using stoko 'comparison ' CRN still looks a buy. remembering I am a zulu fan ,for my selections. Tony