Small Cap Value Report (Weds 30 August 2023) - VTU, KBT, FLO, SDRY, OSI, INS, BELL, QRT

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
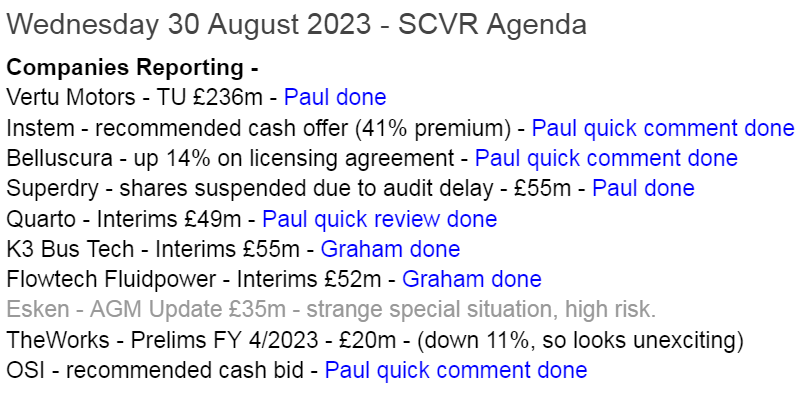
Summaries
Vertu Motors (LON:VTU) - down 1% to 68.6p (£234m) - H1 Trading Update - Paul - GREEN
H1 trading is in line with expectations, and it confirms FY expectations too. Surprisingly upbeat I think, considering tough macro. PER is only about 7x. Still lots to like here I think, so I remain positive.
K3 Business Technology (LON:KBT) - 116p (unch.) (£55m) - Interim Results (current trading in line) - Graham - AMBER
We haven’t covered KBT since 2021 and today’s interim results remind me why that might be. This provider of software products to the fashion industry reports an H1 loss; an H2 weighting should produce an “ok” full-year result, but there seems little to get excited about.
Flowtech Fluidpower (LON:FLO) - up 2% at 85.7p (£53m) - Half-Year Report (in line) - Graham - AMBER
This share remains materially lower than it was at the time of the profit warning it published in July. Revenues from high-margin distribution are lower due to the combination of a disrupted customer experience and external headwinds. Perhaps fairly valued now.
Superdry (LON:SDRY) - shares suspended at 56p (£55m) - Paul - RED
Shares are suspended today, due to late audited accounts not being ready for publication yet. It’s a full listing, so the deadline is 4 months after FY 4/2023, which is about now. It’s 6 months for AIM listed companies. It says this will only be a couple of days delay -
The Company is currently working with its auditor, RSM UK Audit LLP, to complete the final technical points of the audit of its FY23 results and expects to announce later this week. The Board confirms that the delay is a result of normal procedures taking longer than anticipated during the first year that RSM are auditing the Company.
The Company expects to request a restoration of the listing of Ordinary Shares on publication of its FY23 results before the end of this week.
Paul’s opinion - audit delays used to be extremely rare, and very much frowned upon. Since covid though, it’s a lot more common. With SDRY this has to be taken in the context of very poor financial controls, flagged up repeatedly in the audit reports in previous annual reports.
I think SDRY is having serious problems overall, evidenced by now having 2 expensive borrowing facilities, and the long silence over the supposed $50m IP sale.
After underestimating the warning signs at Joules, I’m not going to make the same mistake here, so I think it’s just safest to keep away from this one. RED. On the upside, if owner/manager Julian Dunkerton is able to deliver a turnaround (as opposed to just talking about it) then shares could do well.
Osirium Technologies (LON:OSI) - Up 79% to 2.15p (£3m) - Recommended takeover bid - Paul
Another one! This is an interesting nanocap which we’ve looked at here before, mainly in the reader comments I think. The problem was its precarious financing, and in the current environment, nobody much is interested in refinancing nanocaps. A US bidder, SailPoint Technologies, has stepped in with a rescue bid at 2.35p cash, a nice premium to yesterday’s close, but a diabolical result considering the previous highs of 150-200p in 2016-2019. With some big shareholders having agreed it, and convertible loan notes of £2.9m also having a big say in the matter, I think we’ll be waving a tearful goodbye to this share shortly. Pity, as OSI did look quite promising, if it had been properly capitalised.
Instem (LON:INS) - up 40% to 825p (£189m) - Recommended Cash Offer - Paul - GREEN
Well done to shareholders in this software company focused on the life sciences sector. A French private equity group has agreed with management to buy it for 833p cash, a healthy 41% premium to last night’s closing price.
I think the price looks fair, being about 10% below the all-time highs in a much happier market of 2021.
We only looked at Instem once this year, here on 1 Feb 2023, at 630p concluding that the share looked good, and worth a closer look.
Yet more evidence, growing by the day, that UK public markets are significantly under-valuing many companies, compared with private markets. I see that as a bullish sign for a market recovery in due course.
Belluscura (LON:BELL) - up 15% to 47p (£64m) - Exclusive Licence Agreement - Paul - AMBER
Not a company I’m familiar with, but it has cropped up as a top riser today, so I’ve had a quick look. Historic numbers are no good, with negligible revenues, and heavy losses, and prodigious cash burn to build inventories. So the valuation all rests on newsflow for promising-sounding deals, and hopes of future commercial success.
Today it says that a licensing deal has been done with a Chinese company, who will manufacture its portable oxygen concentrator. It’s a 10-year agreement, with minimum royalties of between $27.5m to $55m, depending on whether the deal remains exclusive for 5 or 10 years. Quite a hefty amount of money, if it turns into reality. It doesn’t sound like pure profit though, as BELL has to contribute towards sales & marketing.
It will be interesting to see how this pans out, but for the moment it’s too jam tomorrow for me to able to meaningfully comment here.
I see the Chairman is prolific company promoter, Adam Reynolds. Nigel Wray holds 10%. It has cropped up before as an investee company of Tekcapital, which still holds 11%.
Quarto (LON:QRT) - down 24% to 117.5p (£49m) - Interims - Paul - AMBER/GREEN
Thanks to Rusty2 for flagging interim results from this illustrated book publisher (main market is USA). I’ve had a very quick look, as almost out of time.
H1 numbers look poor, with adj PBT roughly halved to $3.1m. However, it has a heavy weighting to H2, so management don’t sound too concerned, even saying that H1 results are in line with their expectations. They don’t seem to have told the market that profits were expected to halve, as the share price is down 24% on the news.
Balance sheet - is pretty good. In particular, a sharp reduction in receivables has allowed Quarto to repay all its medium & long term bank debt, resulting in a net cash position of $9.1m. That’s very good, providing it can be maintained, and isn’t just a favourable timing difference at the year end.
Outlook - expecting challenging market conditions to continue in H2. Freight cost & delays have improved. I can’t find any broker research - an omission that the company needs to rectify.
Paul’s opinion - on the quickest of reviews, I think this share is worth you taking a closer look at, and properly researching. We used to follow it quite closely, but gave up right at the low point, and then it multibagged! (I think the vernacular is “Sod’s Law”). Looking at Quarto fresh today, after quite a long gap, I’m pleasantly surprised at the balance sheet strength. Disappointing results in H1, the quiet half, could be presenting a buying opportunity possibly, if you think it can bounce back in H2. Market cap of £49m doesn’t seem much to me, for what looks a well-financed business that has delivered a strong turnaround in recent years.
Paul’s Section:
Vertu Motors (LON:VTU)
Down 1% to 68.6p (£234m) - H1 Trading Update - Paul - GREEN
Ahead of the announcement of its results for the six-month period ended 31 August 2023, Vertu Motors, a leading UK automotive retailer with a network of 189 sales and aftersales outlets is pleased to provide an update on current trading...
Trading remains positive - in line with expectations for the full year
The Group has delivered a trading profit above prior year levels, aided by the Helston acquisition which was completed in December 2022. The Board anticipates that full year results for FY24 will be in line with current market expectations.
Helston was quite a big acquisition, so will have provided a material boost to the results.
That sounds OK. Here’s my summary of the other points in today’s trading update -
New car sales (incl. Motability) - volumes are up as supply constraints ease.
EVs (electric vehicles) - weak demand from consumers, so manufacturers are offering discounts. Fleet sector demand for EVs is “robust”.
Fleet & commercial vehicles - strong demand, improved supply, and gross margins “remain strong”.
Used vehicle sales - down 6.3% (to end July) - blames higher interest rates, and lack of supply. Prices are stable, apart from EVs (falling in price). Gross margins remain high.
Servicing - “strong demand” for this high margin activity. Shortage of technicians, so has raised pay again, to attract & retain - impact on profit margin %, but as expected.
Cost inflation - sounds under good control -
Group operating expenses as a percentage of revenues are slightly lower than last year despite higher energy costs, inflation, pay actions and investment in the Group's Information Technology platforms. A strong focus on driving efficiency and productivity is in place, with growing use of technological solutions to deliver efficiency and therefore cost reductions. The Group continues with its energy purchase strategy with 26 sites now having solar panels installed. 12% of the Group's July electricity requirement was self-generated, with installations at 14 further sites currently ongoing.
Interest costs - this is the main reason I’ve cooled on the sector a little - funding inventories with stocking loans is much more expensive now - I wonder is this a typo below “changes” looks it should be “charges” maybe? -
Interest expenses are higher than anticipated in the period due to increased manufacturer stocking changes as new car pipeline stock increased and interest rates rose.
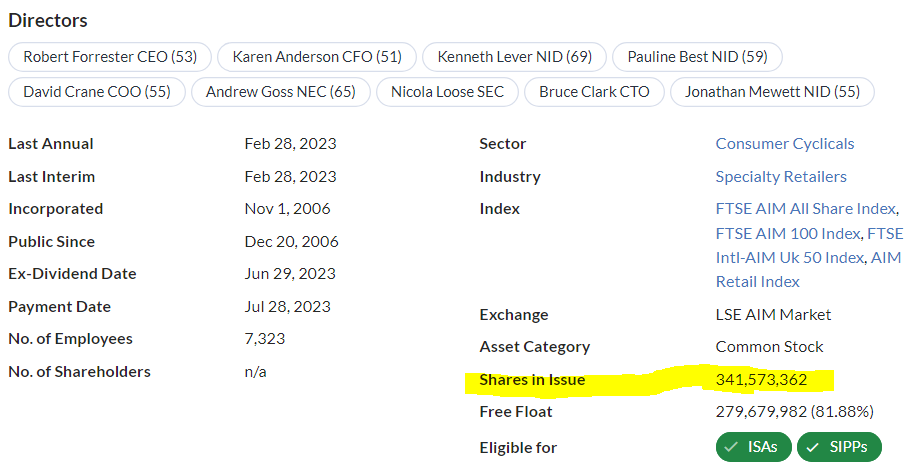
Share buybacks - are a notable feature of this share, note the StockReport shows a steadily declining share count, from 397m in 2018, to 342m currently (see further down the StockReport for the bang up-to-date figure).
This year so far, £4.8m has been spent on buybacks, reducing the share count by 7.4m shares, or 2% of the total. I like this strategy, of paying both divis and doing buybacks - makes sense when the valuation on the company is low.
Average annual shares in issue - coming down consistently, which is the opposite of what most companies do! -

Current shares in issue -
Outlook - sounds fine to me, no reason to panic, despite weak macro conditions I’d say -
The Board remains optimistic for the future. New vehicle supply is increasing whilst constraints in used vehicle supply in the UK persist, particularly in the sub-5-year-old parc, helping to underpin used vehicle values.
The roll out of agency distribution models is at an early stage and the Group will continue to monitor the impact on the business and financial returns. Whilst used vehicle purchases remain essential for many, the market outlook remains unclear due to the impact of inflationary pressures and higher interest rates for consumers.
Aftersales demand remains strong with actions taken to increase available resource.
The Helston acquisition made in FY23 continues to perform in line with expectations and remains on target to deliver on the planned improvements.
Management remains focused on operational excellence around cost, conversion and customer experience and the delivery of the Group's strategic objectives through enhanced performance coming from scale and technology.
The Board anticipates that full year results for FY24 will be in line with current market expectations.
Have market expectations been managed down? Actually no, they’ve increased (driven mainly by the Helston acquisition I think) -

With a share price just under 70p, and c.10p EPS expected this year FY 2/2024, and next year, then the PER is about 7x - still looking good value, despite the share price having been unusually robust this calendar year to date.
In valuation terms, VTU is unusual in the sector for having a share price that is only slightly above NTAV (most of which is freehold property, with working capital tending to net off).
Paul’s opinion - I was half-expecting a softening of trading, and a more cautious outlook, given current wobbly macro conditions. Hence I see today’s update as reassuring, and positive, despite being in line with expectations (which have increased, not reduced). Although at some point, used car margins seem likely to reduce, which could be why the stock market is only attributing a low PER to the sector?
The whole sector is in play re takeover bids, eg a protracted bid situation ongoing at Lookers (LON:LOOK) which is also trading well - I reviewed Lookers interim results last week here. So perhaps VTU could also attract a bidder? I’ve been saying that for a long time now, but nobody has come forward as yet.
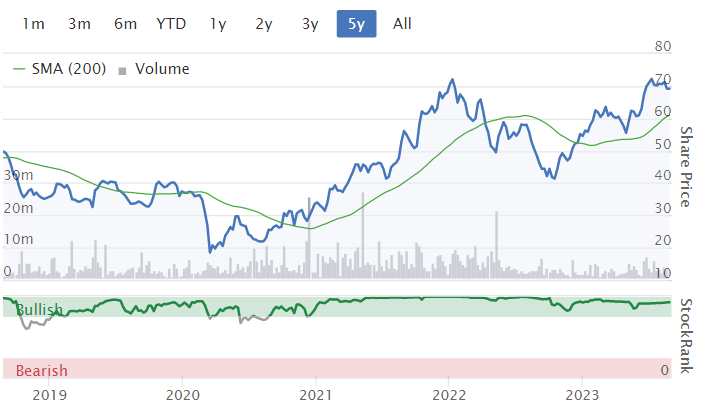
Vertu continues to fire on all cylinders, so I remain positive on this share’s fundamentals (I’m not currently holding, due to needing the money to buy other things). Hence am happy to remain at GREEN. Stockopedia is also green, with a very high StockRank -
Graham’s Section:
K3 Business Technology (LON:KBT)
Share price: 116p (unchanged)
Market cap: £55m
This is a “provider of business-critical software solutions focused on fashion and apparel brands”.
H1 performance is said to be ahead of management expectations, although they also say that current trading is “in line”.
There are losses in H1 on both an adjusted and reported basis.
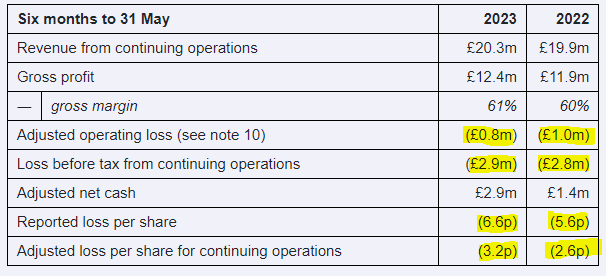
Depending on which metric you use, the losses in H1 this year seem a bit larger than last year’s. Management expectations must have been quite undemanding!
However, a change of accounting policy means that revenues of c. £1.1m were not recognised in H1, which otherwise would have been. So underlying performance is perhaps better than the table above would suggest.
The company says that there is a significant H2 weighting. However, the historical performance isn’t getting me too excited about what H2 might have in store:
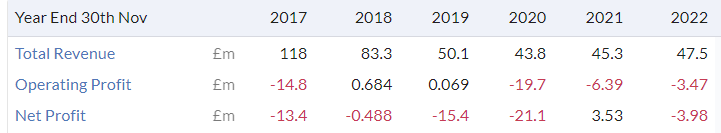
Broker finnCap forecasts a small adjusted PBT in the current year of £0.6m. I presume that this will translate into an unadjusted loss (after amortisation of intangibles and share-based payment expenses).
Operationally, the company provides a wide range of products and services:

K3’s Products division consists of K3 Fashion, K3 Pebblestone, K3 Imagine, K3 ViJi and various legacy products, which seem to be in run-off.
If you scroll down to the footnotes, you find that this division is currently loss-making. The company suggests that the legacy products are the issue.
The other division, “Third-Party Solutions”, is profitable. This division consists of a reseller of ERP software and a service provider to the Inter IKEA Group.
Outlook
Current trading and free cash flow; both in line with management expectations. Encouraging new business pipeline for H2.
Strategic fashion products - targeting growth of 30% p.a. in recurring revenue in FY23 and beyond
Board is focused on further simplifying operations, reducing central cost, adjusted net cash generation and continued transition to higher margin growth activities
CEO comment concludes:
Our healthy balance sheet underpins the improvements that we are making to the business. We remain focused on our high-margin growth opportunities, cost discipline and adjusted net cash as we continue to move to higher quality earnings.
Net cash as shown in the table earlier is £2.9m, with the option to draw down a little more from Barclays. This isn’t very reassuring but the company says its cash flow is weighted to H2, and renewals will be coming in.
Graham’s view
Unfortunately, I’m finding almost nothing to get excited about here. The company talks a good game about growth and recurring revenue, but the numbers are unconvincing to me. Even the broker estimates are uninspiring.
It’s a bit of a mystery to me as to how a mature software business - this has been around for decades - can produce so little profit. The company did simplify its operations a few years ago: did it sell some of its better parts?
I can only conclude that it’s a lower-quality business than its description would suggest. Remember that its profitable operating segment is the one which consists of a reseller and a services provider.
The unprofitable operating segment is the one which contains a wide range of software products. Why is it that legacy products are blamed for poor performance - shouldn’t they be the most profitable, since they don’t require any ongoing investment?
The balance sheet is thin with equity of over £30m that includes over £27m of goodwill, so there is almost nothing tangible that might support the valuation. And the rather small cash balance would concern me.
I’m tempted to give this one the thumbs down but I try to reserve that for extreme situations where the valuation makes no sense, where solvency is in doubt in the short-term, or where management is crooked.
I don’t think KBT deserves to go into that basket. The price to sales multiple is only around 1x, i.e. not high at all. It’s possible that they might get to breakeven or a small level of profitability over the next year or two. Maybe a takeover or more disposals could be engineered. So I’ll take a neutral stance.
Flowtech Fluidpower (LON:FLO)
Share price: 85.7p (+2%)
Market cap: £53m
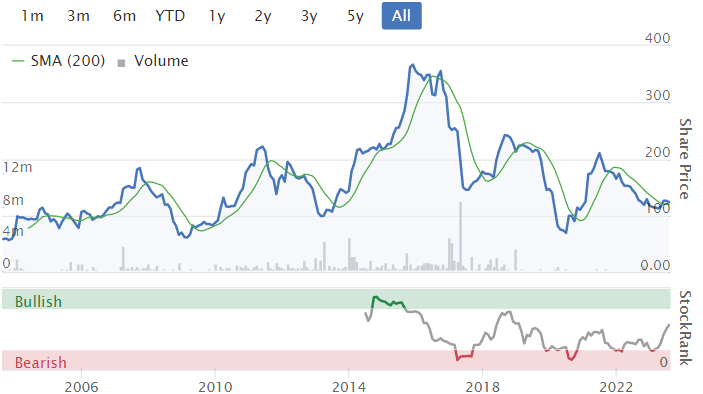
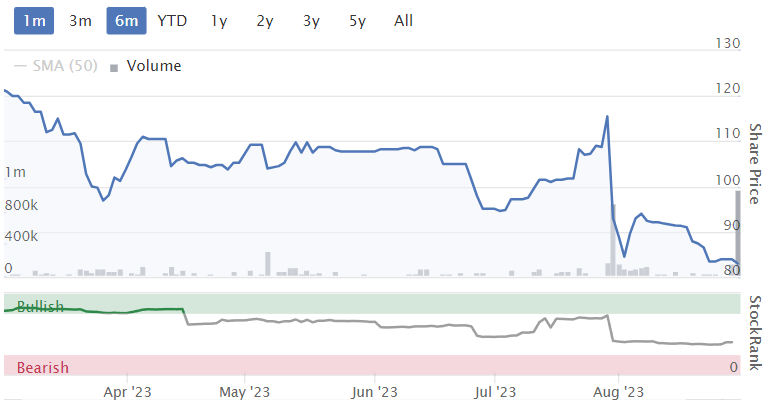
Despite a small bounce this morning, these shares are lower than when we last looked at them in July.
That July trading update was a profit warning which put a big dent in the share price:
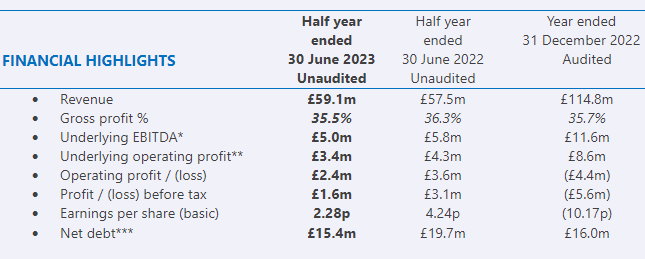
We now have the interim results which are in line with the new expectations after the profit warning:
And the new CEO Mike England offers the following comments:
"Despite increasingly challenging economic conditions, overall Group revenue increased by 2.8% in the period with a more positive performance in our solutions and services segments and a weaker performance in the product distribution segment, as previously reported. We have continued to make positive progress on working capital management, continuing to improve our debt position whilst maintaining tight cost controls.”
“We expect these market headwinds to continue through H2 23 and into 2024 but I am pleased to report good progress is being made in deploying an immediate performance improvement plan and the refreshed strategy, strengthening the leadership team and simplifying the operating model building the capabilities to deliver mid-term scalable growth in a highly fragmented market."
H1 gross margin is 35.5% (H1 last year: 36.3%), because the higher-margin “Product Distribution” segment has seen a reduction in sales.
This means that the group as a whole has produced below-inflation revenue growth and reduced profitability on those sales.
H1 PBT halves to £1.6m (H1 last year: £3.1m).
At least the net debt position, as previously reported, is stable/reducing, now at £15.4m.
Production Distribution: this segment is responsible for 45% of revenues. Here is the explanation for its underperformance:
“…in part due to the more volatile economic and industrial landscape but also due to internal challenges resulting from the consolidation of five businesses into one during 2021/2022 including the closure of the Leicester Distribution Centre, consolidating inventory into the main Skelmersdale Distribution Centre. Whilst this consolidation has enabled improved scale and efficiency, aspects of this integration have impacted some parts of the customer experience. Interventions are in flight to address this to ensure we have quickly returned to the levels of high service expected by our customers including further improvements to our website, catalogue, commercial discipline and our service.”
This is unfortunate; the customer has been impacted. Hopefully the new CEO (appointed in April) has a grip on this situation. The company has a “Performance Improvement Plan” for the near-term, and a “Refreshed Strategy” for more long-term goals. Included within this strategy is the target of a “mid-teens” underlying operating margin.
For context, it looks like the underlying operating margin in H1 was c. 6%.
Operating margin is often (not always) a very good metric for companies to focus on, so I can get on board with a strategy aiming to nearly treble this metric from its current level!
Outlook - expecting continued economic headwinds and a challenging H2, but optimistic about the company’s refreshed strategy.
Graham’s view - I don’t see any reason to change my view expressed at the time of the July profit warning. This company did perform reasonably well pre-Covid and may offer some recovery prospects. The new strategy, if it works to reboot margins, would almost certainly lead to a good result for shareholders. On the other hand, I still don’t think that there is much intellectual property here and I’m unimpressed by historic quality metrics. So at the end of the day, I’m far more excited about other opportunities in these cheap markets.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
(LON:QRT) Whilst the shares look good value, what about the ownership i.e. one man owns >50% and none of the other major holders are institutions.
Superdry clothing is overpriced and unfashionable. It had its moment at least a decade ago when I think David Beckham was photographed wearing one of their T-Shirts. The kids started wearing it for a while but when the middle-aged pot-bellied men started wearing the gear it became passé. Who is their target market? I would say that if you can afford Superdry (LON:SDRY) clothing, you would probably shop at Marks and Spencer (LON:MKS) Next (LON:NXT) or John Lewis and if you are young and looking for the latest affordable fashion, then it would be ASOS (LON:ASC) or Boohoo (LON:BOO) etc.
Indeed.
Those kids grew up and became middle-aged pot bellied men, but kept wearing superdry :)
Quarto (LON:QRT) HY results are out today, at 10am.. They were late and as usual not very good, shares are down 19%, maybe worth a look, Paul, if you have time?
Sure, I've had a quick look and posted a short section above. Looks quite interesting! Thanks for flagging :-)
The major shareholder holding over 50% has always put me off this after what happened with IBPO.
Just looking at the best performers so far in 2023 relative to AIM (+75% or more)
Traded a few of these, still hold 3. Rolls-Royce Holdings (LON:RR.) definitely the one I let get away, was an absolutely obvious buy on at least 3 occasions this year. Pretty even split between AIM and Full listing, just shows even in weak markets there's always opportunity.
Interesting table, Wolf, but what's the penulimate column (Rel to AXX 5td)? Five trading days?
yes, 5 trading days
Warpaint London (LON:W7L) was a nice trade for sure!
Marks and Spencer (LON:MKS) was also a screaming buy at <£1 a share last Oct yet as you say sometimes you just don't pull the trigger for some reason
double the irony here, given I read their reports and shop at them every weekend (m&s food is a snowball - this is the real secret sauce that's re-vitalising them)
m&s food is a snowball - this is the real secret sauce that's re-vitalising them
Couldn’t agree more. I was in the prime central Manchester store food hall last week. It was so good I wondered if I was still in the UK. Well, until I chatted to the cashier anyway! Beautifully presented quality food. Well done to the management.
First list is to weed out the junk. This is the whole of market performance. 48 more than 100%
Heres the top 20-
Paul will be happy.
Hi Wolf,
I'm not clear what the difference is between the 2 lists you published? Have you applied a different filter to them?
Very interesting anyway, and I recognise quite a few names on the lists from SCVR coverage. Paradoxically, it can be the really high risk stuff that sometimes delivers spectacular % gains! Although they don't always hang on to the gains longer term.
Thanks for all your very interesting comments here, you're really contributing some excellent perspectives :-)
Best wishes, Paul.
Thanks Paul. I try to add a mix of childish humour with some occasionally useful stuff :-)
Basically the top list filters out loss makers (one or 2 might slip through) Bottom list is everything. I used to trade penny shares for a few years, as you say every dog has their day , multibaggers can come from the most unlikely places.
"I'm not clear what the difference is between the 2 lists you published?"
One list of Good, one list of Bad, completely opposite poles. I hold only NAHL (LON:NAH) and Hummingbird Resources (LON:HUM) in the first and OptiBiotix Health (LON:OPTI) and RTC (LON:RTC) in the second. HUM I doubled down on, successfully and feel there is more to come, NAH is a hopeless case (self-serving directors) and OPTI too having bought on a high while the same goes for my RTC investment but which is showing strong signs of life. So all in all, Paul could well be right with his comment.
Interesting table. Kicking myself for not buying some Marks and Spencer (LON:MKS) - had held on and off just before the recent surge. Looks obvious in retrospect - it was trading really well and due a big rebound.
Results season is about to hit we have a number of webinars coming up from the PIWORLD stable all with live Q&A, register for them all here.
Next Tuesday 5 September, 11.30am: Headlam (LON:HEAD) H1. They have a new CFO who will be speaking here alongside the CEO Chris Payne.
Next Wednesday 6 September, 3pm: Somero Enterprises (LON:SOM) H1 their results are to be announced tomorrow. Low PE and high dividend.
Following Friday 8 September, 12.30 Pebble (LON:PEBB) promotional products similar to 4imprint. The last trading update was in line and they see Facilisgroup, the SaaS part of the business being a main contributor in FY24. They've been trying to build for a while and it sounds like it's coming to fruition.
Then, a way off Friday 17 November, 1pm Tracsis (LON:TRCS) FY23 results. They are always so organised! We'll get an update on how US rail is developing and the return of the data, analytics, consultancy and events business post COVID.
I agree with your comments re sp. Although not an exact comparison RFX price has suffered in same way. Both companies well managed and in growth mode--I assume bear market taking dim view of pawnbroking side of business.
Hi Paul, if you get time, maybe tomorrow even, could you take a look at RM (LON:RM.) which I have held since the giddy days just before Covid struck the stock market. I read of a large share option being awarded in today's RNS and looking at recent boardroom share purchases decided to double down. I've worked out how much the share price needs to rise by in order to be quits, I wonder if you think I could surpass myself?
Hi Silver Moon,
Yes I looked at RM (LON:RM.) recently here, and think it's awful - very high risk indeed, due to poor performance and excessive bank debt. Although I see there was news yesterday of a bank covenants waiver for Aug 2023. Although that in itself demonstrates that it's financially distressed. So the risk is clearly that a deeply discounted placing might be needed to prevent the bank pulling the rug out from under the company.
The third word, "currently" in this excerpt from yesterday's RNS worries me -
"The Banks currently remain supportive of management, recognising the
issues that the business has faced and also the steps taken through this
transformation period (cost savings and restructuring) to return to
previous levels of financial performance. In light of the continued
headwinds and the need for the annualisation of savings to mature, the
Company and the Banks entered into discussions to agree suitable waivers
and amendments to its existing facility."
Director buying has been only small in 2023 to date. Recent buys on 9 Aug 2023 look more for PR than anything meaningful (2 of them were only £5k apiece!). In a way I'd say that's a warning sign, not a positive, but each to their own. The biggest was £26k.
To me, this looks like the type of financially distressed situation, where averaging down is more likely to be a mistake than otherwise. Personally I'd only average down if a company is putting out good news, which is being ignored in a bear market, not where it's clinging on to solvency by negotiating bank covenant waivers every 3 months! There's a lot of risk with RM, why get involved at all, let alone average down? Your money, so your choice, and I hope it works out for you, but personally I wouldn't go near it until the finances have been stabilised on a firmer footing. insolvency/dilution risk looks very high to me.
I would be working out how much I could lose if it goes to zero, rather then working out what my breakeven price would be!
Regards, Paul.
Paul, many thanks for your valuable reply, I raided the current account to fund this which admittedly makes me a gambler. The gamble is on the newly added/changing Board who presumably need to hold some shares, accounting for the recent buys, perhaps I'm joining forces with chancers! Normally I would be putting dividend money into companies which pay nice dividends but there I go.
H & T (LON:HAT) is an interesting one. Superficially looks cheap on 7.5x 2023 and 6x '24 with good growth forecasts. EPS growth of 43% and 26%. You'd think they'd be doing well as many short term loan biz have gone bust or regulated away. CEO presents well.
Market doesn't seem to believe it tho. Maybe theres just a large seller around but the chart rolled over into a stage 4. Forecasts are being nudge down since March, didn't meet forecast eps 3 weeks ago and brokers are working overtime to prop up the price. I received another email today with a broker note link. There's been at least 8 since May which seems overkill for a company which is suppose to be trading well.
Any holders have thoughts?
Yes, I agree, not sure what's holding HAT back and agree on Ramsdens Holdings (LON:RFX) too, although they seem to have a little more spring in their step. Here's the H & T (LON:HAT) H1 presentation from August which gives a flavour of management and what they're up to. Both should have stronger H2 due to Christmas and fx travel money falling into the second half, further the regulation against loan sharks means the sources of small loans to tide people over a difficult time is very limited. I believe the average borrowing is c. £200.
Id say Ramsdens Holdings (LON:RFX) looks OK, still in an uptrend.
Seems more specific to H & T (LON:HAT)
H & T (LON:HAT) .
I was wondering the same thing myself, whilst reading one of the many research reports (Hardman I think). By one of their metrics the shares should be worth over £7 if I remember correctly.
Recent figs were affected by huge rises in some costs they said, eg Insurance doubled, staff costs etc.
That Ramsden's not affected suggests not a regulatory issue.
Could be selling from speculative holders from the placing recently throwing the towel in ?
I will continue to hold .
Director buying of shares in the market is sometimes just at a minimal level that they hope will offset some negative sentiment, but yesterday two Directors of Frenkel Topping (LON:FEN) (I hold) each bought over £70k of shares and I am inclined to put these in the “very encouraging “ category.
FEN has not had much love recently and I think they are performing at a level which deserves better, even allowing for concerns (such as Paul’s) that they might be considered as “ambulance chasers”. I think they are better than that but would be interested to know if anyone here has personal experience of using them.
Hi Aislabie,
No I don't think I said Frenkel Topping (LON:FEN) were ambulance chasers. That was Anexo (LON:ANX)
As you say Paul, Frenkel Topping (LON:FEN) looks delicious.
Looks like we have another potential buyout this morning as Rx3 Holdings Limited (Rx3) is considering making an offer to acquire Kinovo (LON:KINO).
Kinovo's largest shareholder, Tim Scott, who also owns Rx3, has experience in similar sectors. There is uncertainty about the financial situation of DCB Kent Limited (DCB), a company connected to Kinovo. Kinovo has made progress with some contracts related to DCB but significant risks remain, affecting Kinovo's financial forecast and liabilities. The auditors are concerned about Kinovo's ability to continue as a going concern due to uncertainties around DCB and funding ongoing projects. Rx3 acknowledges Kinovo's growth but notes the need for more investment in staff and infrastructure. Kinovo's top clients account for a significant portion of its turnover, and contract renewals in 2024 are uncertain. Tipacs2 Limited, a major shareholder, has acquired shares from another shareholder, Western Selection. Tipacs2's ability to buy more shares is now limited. Rx3 is considering various options for making an offer to Kinovo, including via a scheme of arrangement or contractual offer, and warns minority shareholders about the implications of being under majority control.
I don't know what's going on with XP Factory (LON:XPF) - there is always a seller there.
For anyone wavering about whether to buy Redde Northgate (LON:REDD) a reminder that it goes ex-divi tomorrow for a juicy 16.5p (about 4.8% at today's price). Sometimes ex-dividend dates accompanied by a large dividend payout are followed by a chunky fall in the share price where people bag the dividend and then move on, but the share price has been depressed here since June so I think there's less risk of that happening here. It looks very undervalued at a p/e of 6.5 despite rising broker estimates and, in my opinion, a decent chance of a beat against expectations this year. I'm talking up my own book here but I do think it looks like a very good value play.
Instem (LON:INS)
Recommended cash offer of 833p and 41% premium to the prevailing share price.
Went to a Progressive evening in 2019 and saw a presentation by Phil Reason CEO who I was lucky to talk to afterwards. I was highly impressed by his integrity and passion. After further research I started building a position and added many times.
Instem (LON:INS) always acquired best of breed companies and seemed to maintain the highest of standards.
The picks and shovels sector of pharma is one I like a lot and comprises a large amount of my highly concentrated portfolio. Instem occupies position 5.
I am sad to see it go. I am sure in time the share price would have climbed to a far higher point.
I have mentioned it on SVCR many times.
I suppose it is not the worst time to find a new home for the proceeds.
newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20230830:nRSd7281Ka&default-theme=true
Well said Michael…I remember reading your many contributions on Instem (LON:INS) over the years….& ignoring them…more fool me
Well said Michael…I remember reading your many contributions on Instem(LON:INS) over the years….& ignoring them…more fool me
Be gentle with yourself. I’m the bigger fool. In a back and forth with Paul Hill on the subject of undervalued UK tech stocks, I specifically highlighted Instem as my top pick. Then sold it a few months later in a purge of my more illiquid stocks.
Thanks John :)
I like humble but you are very far from a fool.
Like you I am not looking for the cheapest company on the market as they are often cheap for a reason.
Re (LON:INS) I’ve tried to post a link of an interview with Paul Hill and Josh Northrop where the latter actually raises the possibility of a bid for the co! That interview was only at the end of July…definitely someone to listen to going forward, a talented young fund manager obviously.
https://www.stockopedia.com/co...
Well done Michael!
We like Instem (LON:INS) here at the SCVR too, with a GREEN view on 1/2/2023: "this looks good, worth a closer look I think".
Thank you Paul! :)
Like others, you piqued my interest on this one. I particularly liked the way in which the market was absorbing sales. I was also interested in your assessment of Phil Reason and did my own research on his background which confirmed what you had said. I took a fairly large position in this as a consequence of your much longer term interest snd so owe you a huge thank you for bringing it to my attention here.
I’ve noted elsewhere a suggestion that Instem (LON:INS) may be of more value to a trade buyer and wonder if the price might be indicating a potential counter-offer from that direction? The discount to the offer price looks too small to be pure arbitrage. But perhaps it’s a done deal in current conditions. Like you, I thought it might have further to run than the take-out price so will probably continue to hold until it’s clear that there’s no other interest. I would have thought that there’s very little downside risk on this one.
Hi Mammyoko
It is very pleasing to me if my posts have been of benefit.
I think it is unlikely that a counter bid will be successful.
Phil and the board will want to ensure the company and employees continue to be looked after well. Archimed seem to be an excellent fit and have the funds to grow Instem (LON:INS) more quickly.
Flowtech Fluidpower (LON:FLO) . New CEO, Mike England starting to make his mark. New senior management team being assembled with five of the previous incumbents having left the business.
Performance improvement pan and refreshed strategy adopted. The former consists of simplifying the business, focussing on the customer and doing the basics well. A fair amount of management speak but he has certainly shaken things up, which was sorely needed. Will be interesting to see how it all pans out.
Debt reduction looks impressive. Gross margins have always been impressive but these have never translated into operating margin. We shall see if the aspiration do so comes to fruition.
Early days but at least things are starting to happen. I hold.
What the actual bollocks are Flowtech Fluidpower (LON:FLO) on about
"Our refreshed strategy (our journey to the future) sets out our ambition and has two key components"
a) A world of motion
b) The power of one
Chat GPT couldn't have put it better :-)
a) inspired by John Barnes' rapping skills
This is the reply from one of the AI bullshitbots. Sounds like the author at Flowtech has been on a course.
Question- "What the actual bollocks are Flowtech Fluidpower (LON:FLO) on about?
Our refreshed strategy (our journey to the future) sets out our ambition and has two key components
a) A world of motion
b) The power of one"
Answer- Flowtech Fluidpower (LON:FLO) is a company that operates in the fluid power industry, providing specialist technical fluid power products and services. The statement "Our refreshed strategy (our journey to the future) sets out our ambition and has two key components" suggests that Flowtech Fluidpower has outlined a new strategic direction for their future growth and success. The two key components of their strategy are:
a) A world of motion: This component indicates that Flowtech Fluidpower aims to operate in a dynamic and evolving industry. It suggests that they will focus on adapting to changes, embracing new technologies, and staying at the forefront of advancements in the fluid power sector. They may seek to expand their product range, improve efficiency, and cater to the evolving needs of their customers.
b) The power of one: This component emphasizes the significance of individual actions and contributions within the organization. It suggests that Flowtech Fluidpower recognizes the importance of each employee's role and encourages a sense of empowerment and accountability. They may focus on fostering a culture of collaboration, innovation, and individual responsibility to drive their business forward.
Overall, Flowtech Fluidpower's "journey to the future" represents their strategic vision and ambition for growth. It encompasses operating in a dynamic industry and recognizing the collective power of individual efforts within the organization.
Flowtech Fluidpower (LON:FLO)
Well, AI has got it wrong on the 'Power of One'. This was explained in detail in today's IMC presentation (recording now available ). It is all about making it one company. Nearly all the many acquisitions had carried on with their own brand name, own catalogue etc. but this is all being swept away as in this slide:
Thank you sharw. Human beats A.I again.
My morning smallcap tweet: Out of hours City colonoscopy
Instem (LON:INS) Belluscura (LON:BELL) Graft Polymer (UK) (LON:GPL) EnSilica (LON:ENSI) Esken (LON:ESKN) Marwyn Value Investors (LON:MVI) Flowtech Fluidpower (LON:FLO) K3 Business Technology (LON:KBT) Superdry (LON:SDRY), Vertu Motors (LON:VTU), Works co uk (LON:WRKS)
◄Instem (INS)► rec offer of 833p, a 41% premium. [SP=590 Cap=135m]
◄Belluscura (BELL)► Chinese co gets exclusive right to manufacture and distribute X-PLOR and DISCOV-R portable oxygen concentrators in China, Hong Kong, Macau and Singapore. Ten year deal has minimum royalty payments and share of profit. [SP=42 Cap=57m]
◄Graft Polymer (GPL)► R&D and supply agreement signed with Empresas Vilher, Mexico. "The technical teams are working on some exciting projects together which will hopefully lead to firm supply orders for our newly commissioned facility in Borovnica, Slovenia." [SP=2.3 Cap=2m]
◄EnSilica (ENSI)► €2.5m order for satellite broadband chip. [SP=66.85 Cap=52m]
◄Esken (ESKN)► AGM stmt. Sale of Renewables div "is significantly advanced". Biomass plant outages have continued "but there are now signs of an improvement in gate fees and plant performance is expected to improve". Co said same in June. [SP=3.5 Cap=36m]. I hold.
◄Marwyn Value Investors (MVI)► final amounts of VAT reclaim received. £4.94m after deductions and fees. [SP=85 Cap=52m]
◄Flowtech Fluidpower (FLO)► H1-June rev up 3% but pretax down 48%. Inflationary pressures partially offset by cost savings. Outlook: "We expect market headwinds to continue through H2 23 and into 2024 but I am pleased to report good progress is being made in deploying an immediate performance improvement plan..." [SP=83 Cap=51m]
◄K3 Business Technology (KBT)► H1-May ahead of management expectations. Rev up 2% but pretax-cont loss £2.9m ((£2.8m). Last trading update was June. Current trading in line. [SP=116 Cap=55m]
◄SuperDry (SDRY)► suspended due to late finals [SP=56.1 Cap=55m]
In line: VTU, WRKS
Robert Forrester, the experienced CEO of Vertu, tells it as it is in today's TU. He covers the main points affecting all motor traders, the TU shows the advantage of the Franchise or Agency model link with manufacturers at this time. We hold this growing company while it hits expectations. If you get time Paul or Graham, your observations would be appreciated. If any readers have had their cars serviced recently they'll know how important that is to franchised dealers, and grimaced at the costs.
Morning JASVFS. Yes, we always cover Vertu Motors (LON:VTU) here! Thanks for your synopsis, we like these, so encourage other readers to leave your comments too on companies that are reporting. It can often flag up the most interesting shares to us, that we might otherwise miss :-)
I see there's an update note out from Zeus, on Research Tree, so I'll take a look at that, and the RNS, and report back in about an hour.
Best wishes, Paul.
Vertu Motors (LON:VTU) I hold
Lack of demand for Ev's is no surprise to me. I own one, a BMW i3. It's a delight to drive, comfortable, effortless, quiet and very rapid. I can also charge at my home. Mine is the Range Extender version with a small petrol generator capable of adding about 60 miles to the range. Even so electric only range is 120 miles at best, in warm months. Winter is much lower, 90-100.
The big issue is our charging infrastructure. Firstly we have far too many providers, each with their own method of payment, multiple apps and so on. More are moving to pay by credit or debit card but it's slow progress. Some chargers are incompatible with the plug one's car uses so that cuts the number of available units. Then I find the majority of charging stations are on motorways. If you want or need to to be on A roads, charging stations are rare and usually, just one or two units at a supermarket or for hotel guests not you.
If you do find one, it is often out of service or occupied by someone who has gone off to do the weekly shop which takes far longer than required to charge the car.There are frequent complaints about bays being blocked by ICE vehicles who can't find a parking space elsewhere. Planning a long journey is a logistical nightmare.
Tesla cars have a much better range but according to Which? magazine, they are the least reliable of all EV's by a significant margin.
The Government in its ivory tower has decreed we should all be driving EV's. However they have left it to the free market to provide the necessary infrastructure with predictable results. Unless you only need a car for relatively short journeys and can charge at home, why buy an EV?
hi rwh3ue
Unless you only need a car for relatively short journeys and can charge at home, why buy an EV?
You are spot on.
I would also point out the amount of time wasted on re-charging versus filling up with petrol / diesel.
My diesel Mecedes C Class Estate does an average of 500 miles to a full tank (700+ on long journeys). It takes me 10 minutes to fill up.
Should I choose to buy an electric vehicle I would unable to charge it from home. Assuming a range of, say, 170 miles I would need to charge it up at least 3 times (probably more allowing for range anxiety) to obtain my current range of 500 miles. Given the problems of charging up away from home that you have identified that would be an awful lot of time and frustration expended every month just to effectively 'fill up' my electric vehicle. At least 2 hours versus 10 minutes. It makes no sense.
Until re-charging an electric vehicle is as simple and as time effective as filling up with diesel I wont be tempted or bullied into joining this crazy circus.
Snazzy
Don’t forget ev cars are a lot more expensive to buy.
And depreciate quicker
And the elephant in the room is when you will need to replace the battery, and how much that little exercise will cost. Maintenance of non-EVs is a much more known cost.
the other elephant in the room is the carbon footprint breakeven point is between 5 and 7 years! I wonder how many owners plan to keep a car that long...
Having just finished Ed Conway's excellent tome Material World, it makes one hesitate to rush into anything more electrical related than need be. EVs are massively more consumptive of copper and lithium, the mining and production of which is dire for our planet.
You have to assess the carbon footprint balance, vs ICE cars, over the lifetime of the car, not how long the original owners keep it for.
FWIW - I have a run around Gen 2 Prius hybrid had it 5 years. I have replaced the battery pack twice - costing me £350-£400 each time, it is a reconditioned unit (not from Toyota but a hybrid specialist). Toyota wanted over £1500 +vat & fitting for a new pack but only gave a 1 year warranty, if you want an extended warranty (max 10 years) you need to take it to them every year for a battery health check which costs about over £150+vat/year. As a hybrid I could at least drive it for a bit because of the petrol engine.
Here is an interview last year with the CEO of Group 1 Automotive (NYQ:GPI) (they have UK dealers) at about 3 mins in he talks about possibly most electric vehicles will be leased so as to over come the battery replacement issues ..https://www.cnbc.com/video/202...
Agree - it's bonkers that there's not a uniform nationwide charging network. Another failure of government. Tesla have it cracked - you charge from 20% to 80% in 40 minutes max at a favourable price; stay longer and it's a penal charge. Range of new EVs is 300+ miles on several models; 400 before too long. Batteries lose about 2% of their power each year. EVs have their disadvantages but they're a joy to drive.
Not sure where you get your figure of 2% battery power reduction each year. Tesla announced a general 12% reduction in capacity after 200,000 miles. It would take most drivers a very long time to get that mileage racked up!
For sure, older EVs that have no battery cooling (1st generation Nissan Leaf for example) will suffer more from that.
I think the main barrier to wider adoption of EVs is cost, rather than range. Not many people regularly drive 150+ miles at a time. The cheapest decent EV is way more expensive than a decent ICE car. Until such a time there are EVs with an on the road price of 15-20k then I would expect demand to remain limited. It might even be a generational thing - is old Doris over the road likely to upgrade from her old Micra to an EV and go through the bother of getting a charger installed at home?
I'm not sure how mining Lithium, Copper etc is any worse for the planet than extracting oil & gas. At least the materials can be recycled when the battery reaches end of life, rather than the extract once, burn once nature of oil & gas.
Don't worry about cost - the chinese are and will be seeing to that. Prices are falling sharply, just look at 2nd hand values.
I think the main barrier to wider adoption of EVs is cost, rather than range
I would agree - some peeps really are getting ahead of themselves with EV's though - the reality is they are still very "niche" (less than 5% of cars on the road?) - expecting full infrastructure and facilities for everyone/"me" to be in place now is just plain silly. I would agree it doesnt help if infrastructure and planning are poor but for now the fact they are so niche still probably leaves a decent pool of peeps who may get one as next vehicle even if it aint for you anytime soon. I dont really see an particular technical hurdles for infrastructure to come on tap at a later date - in some respects going biggie to soon would probably leave us with outdated bits of kit. I cant see any reason not to presume we will be in very decent place in 5 years time just due to natural evolution and the infrastructure will appear even if it somewhat lags what we should ideally have - that time is probably arriving pronto based on % of new vehicles being sold tnow hat are electric (there may be a spike here due to very attractive benefit rules currently for electric cars)
What amazes me is that anyone could buy a non tesla electric car and then be surprised that they cant charge it up en route to cornwall on bank holiday weekend !
from reasonable pool of peeps i know who have a tesla they are generally stunningly happy with their choice of vehicle. Other electric car users seem to be mostly happy although it aint been what they thought it would be for all.
Just like nearly all markets, EVs are going through a classic S curve.
The first people to buy are willing to pay over the odds for unreliable tech for the idea; over time the product improves, the price falls, more people buy in and competitors increase; eventually only the laggard consumers remain buying residual stocks.
The value equation becomes good for specific niches first (milkfloats!, golf buggies, virtue-signalling Hollywood A listers), then bigger ones (people with solar who can charge at home); and finally it goes mass market. Only Luddites and traditionalists still long for the horse and cart.
Long term EVs will beat ICE cars because they are intrinsically simpler and more efficient and thus will become cheaper.
So if you drive 500 rural miles everyday, enjoy the sound of an engine or like standing in a windy garage for 10mins filling your car, drive a diesel for another 10 years, no issue - but it will get ever harder to justify why you do.
I’d like the down thumb back…
An investment play on the slower uptake of EVs is certainly Sylvania Platinum (LON:SLP). I have held previously but sold out at 80p due to a swiftly declining Rhodium spot price. As an essential metal in the production of catalytic converters, if more ICE cars are required than projected, this could cause a spike in the Rhodium price, which would reflect very favourably on SLP. The Rhodium price seems to have stabilised at around $4000 per oz, if this starts to form an uptrend in the coming months SLP could be a nice mid-term play over the coming years. Current SP is 70p.
Another bid today. For Instem (LON:INS) at a 41% premium. Unfortunately I got bored and sold this one in the low 600s to fund new purchases. Congratulations to more patient holders.
Lucky timing for me as I only bought this in early August. However, the bid does seem quite opportunistic & in my opinion undervalues the company's prospects.