Small Cap Value Report (Weds 31 March 2021) - NXR, TPT, Deliveroo, CALL, GATC, AQX

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Timing - we're both on the case early, so should be done by 1pm.
Agenda -
Paul -
Norcros (LON:NXR) - a positive trading update, with clear guidance, profit up about 10% on previous guidance, which should trigger broker upgrades. Still looks good value, even after strong recent rise.
Topps Tiles (LON:TPT) - H1 trading update. Good Q1, weak Q2 (due to store closures from lockdown). Overall, looks priced about right to me, I can't get excited about this share because the company was struggling before covid.
Deliveroo - IPO has flopped. My comments on IPOs generally.
Cloudcall (LON:CALL) (I hold) - FY 12/2020 results. Costs are rising faster than gross profit, and that's set to continue in 2021. Not good.
Jack -
Gattaca (LON:GATC) - FY20 Covid hit for this engineering and technology recruiter, but improving leading indicators suggests rerate could continue. US Department of Justice risk remains a concern.
Aquis Exchange (LON:AQX) - maiden profit and successful integration of NEX exchange
.
Paul’s Section
Norcros (LON:NXR)
256p (pre market open) - mkt cap £207m
Norcros plc ("Norcros" or the "Group"), a market leading supplier of high quality and innovative bathroom and kitchen products, today issues an update on recent trading.
Further upgrade: strong momentum sustained…
a further improvement in profitability. Consequently, the Board now expects underlying operating profit for the year to 31 March 20211 to be no less than £31m on a post-IFRS 16 basis which compares to our previous underlying operating profit guidance for the year of no less than £28m.
Very good. Nice clear guidance.
Net debt - has disappeared!
The balance sheet remains very strong, and we expect to end the year at 31 March 2021 with no net debt (on a pre-IFRS16 basis) compared to net debt of £36.4m at 31 March 2020.
We’re not told if there’s any creditor stretch, or whether this is a sustainable position.
Valuation - Norcros’s interim results (6m to 30 Sept 2020) showed underlying operating profit of £12.8m. Full year guidance is now £31.0m+, which implies a strong H2 performance of c.£18.2m u/l operating profit.
My sums show that this approximates to 26p EPS for the full year.
Reasonableness check - existing broker consensus forecast shown on the StockReport is 23.5p, multiply that by 31/28 (being today’s upgrade in profit guidance, see above) also arrives at 26.0p EPS new forecast for FY 03/2021, so I’m happy with that figure.
Hopefully we might get some updated broker notes later, to confirm this.
The current share price is 256p, therefore the PER is 9.8 - sounds cheap, but bear in mind Norcros tends to trade on a single digit PER usually, due to its huge pension scheme, and its exposure to economic/political risk in South Africa.
My opinion - a strong update.
We’ve been saying for years here that Norcros shares look cheap.
9.8 times earnings for FY 03/2021 looks good value still, despite the recent strong rise in share price, because we can factor in further earnings growth in future years too. Plus probably more, sensible acquisitions, especially given that it has paid down debt, which gives it headroom to do more deals. So far management seems to have done well, with sensibly-priced acquisitions which fit well within the group.
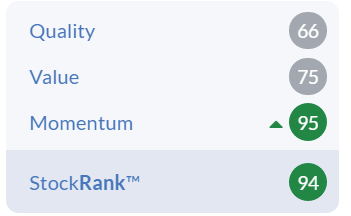
It has a very high StockRank too.
Overall - an impressive update, and I think the recent strong share price is justified by the improved fundamentals.
.

.
.
Topps Tiles (LON:TPT)
69p (roughly flat on the day, at 09:12) - mkt cap £135m
Topps Tiles Plc ("Topps" or the "Group"), the UK's leading tile specialist, announces a trading update for the 26 week period ended 27 March 2021.
Resilient performance against a challenging backdrop
H1 revenues are slightly down on LY, at £103.6m (H1 LY: £106.2m)
Q1 (Oct-Dec 2020) was strong, but Q2 weak (due to lockdown restrictions - closed stores)
Gross margins also worse in Q2 vs Q1.
Outlook - Expecting a “sharp increase in sales” imminently, when the current lockdown is released, with gross margins normalising, which is what happened last year when the first lockdown was eased.
Balance sheet - Topps claims to have a strong balance sheet, and is “debt-free”. I last reviewed the balance sheet here, and found it to be adequate, but not brilliant. It’s not a concern overall. Note that Topps has managed so far without the need to dilute shareholders with an equity fundraising, an important spin-off benefit from having a sound balance sheet. I imagine it can probably continue without needing to do a fundraising in future, which means that we should hopefully be able to rely on EPS returning to pre-covid levels in due course.
Valuation - tricky. I think the best way to value this share, is look at pre-covid trading, which was c.5-7p EPS, and assume it might return to that level in due course. A share price of 69p means a PER range of between about 10 and 14. That looks about right to me.
My opinion - the problem with Topps, is that its earnings were under pressure, and falling, before covid. Suggesting that it might have been struggling with competitor pressure.
The share price seems to have anticipated a recovery to pre-covid trading already, so I would need to see evidence that it can beat pre-covid trading in future - i.e. some developments which make it a better business than before. Maybe there will be less competition in future, as there must have been casualties from weaker, independent competitors going bust? What about the threat from online competition? It’s easy enough to look at pictures of tiles online, and be sent samples through the post. So is a large store network actually necessary?
Historically, Topps was a generous dividend payer, so that’s probably the main reason to hold this share, anticipating a return of generous divis. Although scarred by covid, I suspect a lot of companies might want to hold a larger cash buffer in future. They should do anyway, but people quickly forget crises in practice.
Overall, I’ve got nothing against Topps, but can’t see any compelling reason to want to buy or hold its shares at the current price, which looks about right.
As you can see below, it's not a growth company any more, hence should be on a lowish PER.
.

.
Deliveroo
Just a quick mention as this is topical.
Its IPO has gone ahead, priced at 390p, the bottom end of the 390-460p indicated price range. I was having a rummage through the Admission Document over the weekend, but gave up after seeing;
Two classes of shares: 1,704.5m Class A shares, for mere mortals, and 115.2m Class B shares for the founder Will Shu which have special rights for 3 years I think. To my mind, different classes of shares are just wrong, so it’s not something I would entertain buying into, unless there was a really compelling reason.
Secondly, the valuation looks utter insanity. It doesn’t even make a profit yet! In 2020 it made an underlying, adjusted EBITDA loss of £(9.6)m. So even the most favourable measure possible, didn’t even make it into the black. Remember this isn’t an early stage business, it’s been around for a while. After a load of charges, the underlying loss for 2020 was £(223.7)m!
We also have worries about regulatory/wages for the gig economy, workers rights, etc., which might prevent ESG funds (a big part of the market now) investing in Deliveroo.
Is it a ground-breaking, paradigm shifting platform for global domination? Or as Mark Brumby quipped, is it just an app, connected to a load of guys on bikes?!
Valuation - the IPO price of 390p seems to correspond to a valuation of £7.1bn! How can that possibly make sense?
Current trading - it’s opened way down on the float price, and at the time of writing is only just above 300p, that’s about a 23% opening fall. Very much a flop then. In my experience, when IPOs crash on opening, that often heralds a period of under-performance for that share. I remember when Hss Hire (LON:HSS) struggled to float, and was priced at the bottom of the range, it fell off a cliff a few months after floating, and has never recovered. Mind you, that was a mess from day 1, and was floated with an insolvent balance sheet.
On the other hand, Facebook flopped after its float in 2012, languishing below its IPO price for about a year. It’s since risen about 14-fold from the lows, over the last 9 years. So elephants can & do gallop in the modern world!
New listings generally - I’m told by friends in the city that there is a big pipeline of new IPOs, and loads of M&A activity, driven in particular by private equity (PE), awash with cash, and paying full prices. All boom time stuff, so it won’t last forever, but we could have a couple of good years out of this I reckon.
I’m all for more decent quality listings in London, we need to refresh the UK market, which has become stale. However, promoters must price them competitively. If investors are fleeced, with over-priced, opportunistic (e.g. beneficiaries of lockdown) floats, then the funding window could slam shut just as quickly as it’s opened up.
Primary Bid - it's great to see more floats including an offering for private investors, through primary bid. This is essential to create some liquidity. After all, what's the point in floating a share, if they're just placed in large blocks with institutions? There's not any post-IPO liquidity!
With Deliveroo going to a deep discount, it just shows that people punting on IPOs can’t just assume they will run to an immediate premium, you do have to be careful what you buy, and what you pay for it. I tend to avoid new issues, because the seller has chosen the timing & price, and they know the business much better than me. Hence I’m probably not being wise, being on the other side of that trade. But there are exceptions, some IPOs do brilliantly well - look at Fevertree Drinks (LON:FEVR) for example, where a private equity seller sold it cheaply, just as stellar growth was starting.
.
Mpac (LON:MPAC)
(I hold)
I mentioned this company yesterday.
I found its results webinar, with Q&A very informative, so here it is, the recording is now live. Video is a much more digestible format, than ploughing through a lengthy results statement, I find, and I often pick up on important points that I missed, when reading the relevant RNS -
.
.
Cloudcall (LON:CALL)
(I hold)
74p (down 4.5%, at 11:14) - mkt cap £36m
Checking the archive, I last commented here on CALL’s recent (2 March 2021) placing at 81.5p, raising £7.5m. Prior to that, I was not impressed with its trading update here on 22 Jan 2021, for FY 12/2020. As mentioned then, the problem with CALL is that it’s not growing fast enough, and overheads are constantly increasing. That has led to a prodigious cash burn ever since it floated, and repeated fundraisings. Always accompanied with super-bullish commentary! Forgive me for sounding jaundiced, but companies that keep missing targets deserve criticism. That said, covid wasn’t their fault, and it did knock the sector (recruitment) that CALL is mostly focused on.
Right, that’s the opening whinge out of the way, let’s look at the numbers!
Final Results - for FY 12/2020.
Revenue £11.8m (up 4% on 2019) - of which 95% is recurring/repeating
Gross margin high, at 81% (2019: 79%)
Loss after tax is the best measure I feel, because large tax credits are a genuine cash inflow, so should be included in the valuation. Overheads increased a lot, so the loss after tax was a hefty £(5.7)m, (2019: £(2.9)m)
It’s the costs which concern me. Sales & marketing rose 32% to £3.77m, and Administration expenses rose 24% to a heavy £8.55m. Remember there’s only £9.5m of gross profit generated. By my calculations, revenues would have to rise c.70% just to reach breakeven. Hence the company needs to greatly accelerate top line growth, or cut overheads.
Balance sheet at 31 Dec 2020 has since been augmented by the £7.0m (after costs) placing post year-end. Taking that into account, the cash position should be fine for now.
Note retained earnings of £(74.97)m in the reserves section - this company really has burned through a lot of cash. Actually, that figure looked too high, so I’ve checked back, and CloudCall (previously called Synety) was reversed into a shell, called Zenergy Power, which brought with it retained losses of c.£(49)m. So actually, Cloudcall has “only” generated retained losses of c.£(26)m in the last 9 years as a listed company.
It shouldn’t have to pay any tax then if it ever does make a profit.
Outlook -
Strong recovery in H2 2020 has continued into 2021 with performance since the end of the year in line with management expectations… as market conditions continue to improve, the Board fully expects the Group to return to its previous levels of growth…
Given the growth momentum generated in H2 2020, the Board is confident that the Group will be able to deliver revenue of £14m in 2021 representing growth of 18%.
In addition, the Company has provided guidance for 2021 operating expenditure which is expected to be approximately £16.9m compared to 2020 which was £13.9 million (including £1.3m of one-time COVID-19 related savings).
The Board also remains confident in its ambition to now reach monthly EBITDA breakeven by mid-2023 and achieve a £50 million revenue run-rate during 2026.
That sounds as if costs will once again be rising faster than gross profit in 2021 as well, so an even worse loss is on the cards.
My opinion - growth is nowhere near fast enough to justify the large, and rapidly rising cost base.
I’m not at all happy with things here. If we don’t see a serious acceleration in growth during 2021, then I think the time might have come to ditch this position. It’s less than 1% of my portfolio, and is really just a distraction now.
.

.
Jack’s section
Gattaca (LON:GATC)
Share price: 150.2p (-0.86%)
Shares in issue: 32,290,422
Market cap: £48.5m
Gattaca (LON:GATC) shares have done well over the past couple of weeks - in fact a few small cap cyclical value stocks appear to have outperformed over that timeframe.
Perhaps it signals a slightly more risk-on attitude with investors now anticipating a successful vaccine roll out and life beyond lockdown.

It was pitched to the Stockopedia Investment Club in early February when shares were below 100p but, although the Club voted in favour, a secondary vote for just one Buy in that meeting meant Ferrexpo got the nod. It looks like we missed out - you can read the pitch here.
This is a specialist Engineering and Technology staffing solutions business, with a core focus on in-demand STEM (science, technology, engineering, and mathematics) skills, so it makes sense that the share price would rerate given the increasingly likely prospect of an unlocked UK economy in the near future.
Highlights:
- Underlying revenue -30.6% to £206.5m,
- Underlying net fee income (NFI: revenue less contractor payroll costs) -33.7% to £21.1m,
- Underlying EBITDA -65.5% to £2m,
- Underlying profit before tax -86.5% to £0.3m,
- Underlying diluted EPS -84.9% to 1.1p, and
- Net cash balance of £22.7m.
Continuing underlying results exclude the NFI and trading losses of discontinued operations in China, the contract Telecoms Infrastructure markets in Africa, Asia and Latin America as well as operations in Dubai, Malaysia and Qatar (2021 H1: £(0.0)m, 2020 H1 restated: £(1.5)m). There is also £0.2m of restructuring costs, £0.2m of amortisation added back, and £0.3m in exchange losses.
In the UK, demand was most impacted within the Aerospace, Auto and Maritime business. Infrastructure NFI was down 33%, and Energy was least affected with NFI down 12%. UK Technology NFI fell 37% but has returned to quarter-on-quarter growth and Gattaca expects that trend to continue through the second half.
International operations, which make up 12% of underlying NFI, was down 33% to £2.4m.
The group restructured in October 2020, realising annualised savings of some £4m and paving the way for increased investment in headcount and consultants as conditions improve.
Gattaca has also nearly finished upgrading its global technology platform. The Primary Business Systems ("PBS") will replace legacy systems and provide a more integrated and flexible centralised system.
Conclusion
FY20 results don’t look pretty but, relatively speaking, emerging from the past year with a small underlying profit and equally small reported loss probably isn’t bad. The group enters 2021 in decent shape and many investors will no doubt be hoping for a quick improvement in trading conditions.
Whilst the pace of the recovery remains uncertain, Gattaca is seeing more encouraging signs in leading indicators like improving activity rates. Full year 2021 underlying PBT is expected to be in line with market expectations.
The recent rerating of shares does also have to be taken into account. But even with a more than 50% rise, those shares still look cheap on a forecast basis.

There are a couple of caveats. Trailing twelve month (TTM) free cash flow is flattered by some working capital movements, and price to sales should probably track Gattaca’s NFI rather than gross revenue. Still, adjusting for those, Gattaca trades on just over 3x FY19 free cash flow and 1.7x FY19 NFI, which is undemanding.
There is a hard-to-quantify risk in the form of the group’s ongoing legal action with the US Department of Justice. The outcome of any potential fines associated with this is unknown.
This might rule it out for some, but if you can tolerate that risk, then purely on valuation and outlook I could see this continuing to rerate as the economy unlocks.
Aquis Exchange (LON:AQX)
Share price: 600p (+5.26%)
Shares in issue: 27,169,696
Market cap: £163m
Aquis Exchange (LON:AQX) is trying to build a UK rival to the AIM market after acquiring the NEX exchange in early 2020 and rebranding it as the Aquis Stock Exchange. Since then it has attracted some activity, including the listing of China-focused ecommerce group Samarkand, which has a market cap of around £63m.
Aquis Exchange also operates a pan-European cash equities trading businesses and develops and licenses exchange software to third parties (Aquis Technologies).
It will be interesting to see if the stock exchange in particular can gain traction - it could take a while - but competition for small cap listings could be a good thing as it might drive down listing costs. Funny how Aquis itself chooses to list on AIM though!
We seem to be in a period of significantly heightened corporate activity, so I wonder if Aquis can capitalise on that.
- Revenue +67% to £11.5m,
- EBITDA up from breakeven to £1.5m,
- Maiden full-year pre-tax profit of £0.5m vs. FY19 pre-tax loss of £0.9m,
- Membership of Aquis Exchange grew by 10% to 33; market share of pan-European continuous trading increased to 4.7% during 4Q2020 (4Q2019: 4.2%),
- Post period, as of 31 March, As at 31 March 2021, membership had grown to 39 and market share to 5.0%
The group’s CEO, Alasdair Haynes, comments:
Momentum has carried into current trading, with strong performances across the Group and particularly notable progress in AQSE, which is now truly fit for purpose for modern-minded SMEs looking to float. We have a clear vision, excellent team and an exceptional drive to succeed. So, whilst the road ahead remains uncertain at a macro-economic level, we have confidence we have an exciting year in front of us.
As well as achieving profitability, Aquis hired its first Chief Technology Officer, built its first cloud native exchange, and acquired and integrated the NEX Exchange.
Aquis exchange
This is the cash equities trading business. It allowed clients to trade more than 1,500 stocks and ETFs across 14 European markets in FY20 and now offers Swiss stocks too.
Over the period, Aquis’ secondary market multilateral trading facility (‘MTF’) delivered growth despite challenging economic and regulatory conditions. The number of trading members grew from 30 to 33 and a number of members increased their activity levels, leading exchange revenue to increase 46% to £7.7m.
Market share of all pan-European has grown from 1.8% at the time of the IPO in June 2018 to 5.0% as of 31 March 2021.
Aquis Technologies
Aquis licenses its leading exchange related technology to international financial services clients. Revenue from technology licensing in 2020 grew to £2.3m, ‘reflecting the increasing interest in our high-calibre, in-house technology.’
The highlight of FY20 was a successful proof of concept project in collaboration with Singapore Exchange (SGX) and Amazon Web Services (AWS) to create a cloud native exchange.
Aquis Stock Exchange (AQSE)
The NEX Exchange was acquired in early 2020 and has been rebranded as Aquis Stock Exchange Limited (AQSE). As of 31st December 2020, 87 companies were quoted on its two markets, with a total market capitalisation of approximately £1.8bn. It works with 49 registered brokers and 8 market makers.
For the 9 ½ months ended 31st December 2020, AQSE delivered revenues of £1.2m and a loss before tax of £0.5m.
The group also generated data revenues of £0.9m, up 165% in 2020 and helped by the inclusion of AQSE.
Conclusion
The trading figures are still quite small here given the £155m market cap, but I think Aquis is worth highlighting as a company of interest going forward.
It’s the acquisition of AQSE that is intriguing. Can this rival AIM for small cap listings? And what further disruption and innovation can a hungry competitor bring to the table in the years to come? There is the risk that the incumbent exchanges are just too dominant and entrenched but so far it looks like Aquis has been able to grow market share in other parts of the company.
The valuation is expensive, with a lot of growth priced in, but if the company can execute then the opportunity is probably large and this could grow to become a high quality enterprise.
It’s too expensive for me given where it is at operationally, but listing is often costly for small and mid caps so I’m curious to see if Aquis can win meaningful business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Good Morning, would you be able to run through the LDG end of year results posted on Tuesday. Obviously not received well with the share price plummeting. Thanks
Best Of The Best (LON:BOTB) (I hold)
I welcome the secondary placing.
Aside from the fact that I think a payday is well deserved, the biggest risk I had with this holding was the founders themselves and their ability to do whatever they wanted with their extremely large holding.
It looks like their holding will be reduced to 47%, so just below that all important 50% mark. Personally I'd prefer if it was much lower. but this is a good start.
As for the announcement of new directors to replace the founder's family member (from memory I think it is his dad), I'm not holding my breath. I noticed that they recently appointed someone who seemed like a friend from their university days, though that could have been a coincidence that they all seemed to have gone to the same university at exactly the same time.
Suspicious director appointments aside, I'm still a happy holder (and I do appreciate the responses I have received from the company in the past), and for those who follow my workings on this company, it's looking like a decent finish to their financial year.
Cheers
A
Best Of The Best (LON:BOTB) I have applied too. It might mean the silly spread is reduced although the company has not raised any new money. In THIS case I can imagine institutions saying "look, we cannot buy any stock so it is pointless us talking to you". I can also understand the point that having a quote seems wasteful if no-one can buy or sell more than a handful of stock. Of course the shareholders want to cash in too. "A further 41,666 Ordinary Shares will be available for purchase at the Placing Price via the PrimaryBid platform" so I don't expect too many!
Primary Bid offering secondary placement for Best Of The Best (LON:BOTB) at a 16% discount of £24.00 only via their App. Time limited offer likely to sell out quite quickly. Looks like founder shareholders liquidating some equity. No position.
Gus.
I saw this as well, while liquidity is an issue for Best Of The Best (LON:BOTB), it never fails to amuse me when management dress up a very nice pay day - £60m in this case - as improving “liquidity”. Management will retain a huge percentage after the secondary placing but I do wonder if they are selling out at an optimal time (I’m probably alone at raising my eyebrows to some of the cited growth potential for BOTB). All the best to any holders. Will
See what comes of the LON:BOTB Primary Bid offer. It accepted my offer, but did say depends on allocation. Bit of a bargain I feel.
Nev
Best Of The Best (LON:BOTB)
Well after I put the kids to bed it was closed, after having to log into the web account as it had lost my iWeb account, had the account just not the iWeb bit, but figure it had done before then. So good look to those who were able to do things quicker than me
Tommy
Dear Paul
It is the first anniversary of my joining Stockopedia since retiring last March after forty seven years in the wealth management industry. It has been a steep learning curve in trying to replace institutional research now no longer available, as well as finding new systems enabling me to keep in touch with global markets.
Over my career, I have always been interested in smaller companies and have been fortunate enough both to own a number of highly successful businesses over the years and, latterly, backing several very good small company fund managers. I want, however, to offer my thanks to you and your colleagues for the excellent small company analysis you provide together with the Stockopedia screening process. Alongside astute comments from many of your subscribers, it has once again opened my eyes to the opportunities that exist in a largely under-researched area of the market. And I am still learning!
Kind regards
Phillip Arghebant
Thanks Phillip, what a kind message. Much appreciated by me, Jack & the rest of the Stockopedia team! :-)
Regards, Paul.
PrimaryBid have just announced a fundraising for Duke Royalty (LON:DUKE) who presented at Mello on March 7th. Priced at 35p, c.9% discount to today’s close. Part of a wider £30 /33 million offering.
https://www.stockopedia.com/sh...
Gus.
Gattaca - questions for Jack, and anyone else with an interest. 1) The ongoing expenses incurred in connection with the DoJ case are dramatically reduced compared with last year. Do you consider this a good or bad indicator, or of no significance? 2) Do you know if the company took advantage of HMRC VAT deferral in response to Covid. The company will pay VAT on its agent provision but will have no VAT on the majority of its costs (I imagine - I assume few of its personnel will be VAT registered). So deferred VAT is likely to be higher than may be anticipated on first impression. As a rough estimate based on UK turnover I estimate this could be up to around £8m. I can't see where this is taken account of in the liabilities, and could be a big drain on cash as this comes due. Any comment?
StudentUniverse, an online OTA focused on the student travel market says the following. Looks like the pickup in travel bookings hasn't started yet.
Read across for Hostelworld (LON:HSW) and Safestay (LON:SSTY) maybe even On The Beach (LON:OTB)
Source: Telegraph Live travel blog today
StudentUniverse, an online OTA focused on the student travel market says the following. Looks like the pickup in travel bookings hasn't started yet.
Well, you have rising cases across Europe and no signs that the UK will ease restrictions on leaving the country any time soon (August seems to be the best hope now). You'd also think when countries do accept travellers they'll want them to be vaccinated, which puts young people at the back of the queue.
It's a bit rich really - the kids are forced to spend a year in isolation to protect old people and then have to stay home and watch while the oldies go out to play ...
timarr
“ It's a bit rich really - the kids are forced to spend a year in isolation to protect old people and then have to stay home and watch while the oldies go out to play”
I’m guessing that was tongue in cheek, Tim.
In a similar vein, I think it is the duty of the government to send at least a couple of million unvaccinated people abroad to get infected by a third wave, bring that back home and pass it on to the 1 in 10 of the vaccinated for whom the vaccines offer only limited protection. What I don’t understand is that these kids are now back at school or uni and trashing a park in Nottingham so what more could they possibly want? Back in my day we had to keep ourselves amused for the whole summer holidays with just a cardboard box and a piece of string!
I’m guessing that was tongue in cheek, Tim.
Partially, at least, Graham.
The festivals this summer are sold out, but presumably a lot of twenty somethings aren't going to be able to go because they won't have been vaccinated. Hopefully we can pick up some cheap resold tickets and enjoy the bands without annoying young people getting in the way, sitting on each others shoulders and waving mobile phones in our eyelines.
They kids can go flake out in the park, as long as they maintain social distancing, wear masks and don't drink, of course.
Every pandemic has a silver lining :-/
timarr
"The festivals this summer are sold out, but presumably a lot of twenty somethings aren't going to be able to go because they won't have been vaccinated."
So, I'm guessing that was tongue in cheek, timarr.
I have sympathy with the young on this and agree with Tim. They are relatively unaffected health wise by Covid but have been forced to isolate for a year fundamentally to protect the over 70's. Consequential effects on mental health; and for Students one of the best years of their educational life has been ruined, not to mention the stress for those doing/not doing exams; a lack of social interaction at a time when they need it. None of that is good.
It is indeed a bit rich then that they see the Oldies all vaccinated miles ahead of any being offered to them and then told that they won't be allowed to travel when those vaccinated will be.
You may have guessed that I have two young adult children in this category and I can tell you that the younger generation are seriously p***ed about it and feel pretty screwed over. Personally I sympathise.
To be fair Graham, if you are of a similar generation to me - we did have the very excellent Why don't you? to tell us how to get best value out out of that cardboard box and piece of string.
Happy days!
Here are my SCVR heat maps for today (prices as at ~12:40pm).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
I agree the valuation for Aquis Exchange (LON:AQX) is very rich so not for the faint hearted investor. As a competitor to AIM and self styled “home for growth companies”, however, I think it is an interesting alternative which seems to be gaining some traction. It’s still at a disadvantage in that many share platforms don’t trade with it electronically so execution is by phone and therefore more expensive but that seems to be changing with the likes of HL and AJ Bell coming online and others likely to follow. I was favourably impressed with the way the recent Samarkand IPO was handled and personally think AIM has become a bit complacent in recent years and could benefit from a bit of competition. Whether, as it aspires, it turns out to be a U.K. (or even pan European) NASDAQ is a long way down the road but it will be interesting to see how it develops.
Gus.
re: Aquis Exchange (LON:AQX) you say "It’s still at a disadvantage in that many share platforms don’t trade with it electronically....". I am not sure that is correct because there is another aspect to this in that as well as their "own" companies they also trade a lot of AIM listed companies. On quite a lot of my (online electronic) trades I have wondered why it has not appeared on the LSE list of trades, looked on the contract note and found that the trade had been on Nex/Aquis. Here are two examples with trades today:
https://www.aquis.eu/aquis-sto...
https://www.aquis.eu/aquis-sto...
Hi sharw.
Re. Aquis Exchange (LON:AQX) electronic dealing capability, I was referring to the commentary in the attached article taken from the Aquis news website.
https://www.aquis.eu/largest-r...
Also, I’ve been told by my main broker, Charles Stanley Direct, that I can currently only trade in Samarkand (OFEX:SMK) shares by phone which is quite a bit more expensive per trade than online.
Gus.
Hi gus
Thanks for the link relating to Aquis Exchange (LON:AQX) It is very unclear but looks to me as if they are talking only about shares traded only on their exchange (prefixed OFEX). What is not fathomable is whether there is a Chinese wall between trading that set and trading the shares whose main listing is on AIM, which is what I quoted experience of. Both sets they inherited from Nex.
£ROO Just Eat Takeaway.com Nv (LON:JET) you can see where Deliveroo got its market cap guess from as Just Eat is £9.8Bn
£ROO, Just Eat Takeaway.com Nv (LON:JET), make Bigdish (LON:DISH) look like a bargain. Only Joking, recommend staying clear of all 3.
DYOR
BSV
Just Eat Takeaway.com Nv (LON:JET) would have been profitable if it didn't have one-off merger costs.
EBITDA is growing well and top line growth is solid with expansion into many new markets.
They now enter a new city every 3 months and run a marketplace business model as they only deliver 15% themselves.
It requires a judgement on future market size and growth organically and in new markets to value, rather than the value of something like BP in a mature market.
These early stage industries and companies can grow the bottom line exponentially. You need to make an assumption on that and factor that in to any DCF of the business.
Just Eat received $2.3bn offer for their Brazil business alone due to the potential size of the market but turned it down.
It's not everyone's cup of tea as it seems risky but personally I think Just Eat is cheap atm.
Deliveroo is a very different business though, it delivers all orders so little leverage other than data. The IPO pricing was a mess, free offers were used to boost sales pre-IPO and Amazon sold down their stake.
I'm coming to agree with you on Cloudcall (LON:CALL) . I also remember an exchange we had on these pages some months ago when I mis-heard them quoting their LTV:CAC ratio as 10 and you correctly hearing 7 and confirming with the company that was the number he had used. In today's report that historic 2019 number is given as 5.4 and they say they are doing "over 5". So I am confused.
Can anyone explain why there are no Quality Value Momentum StockRanks numbers for Coral Products (LON:CRU) please? (Substantial long term holder and pleased it's having quite a rally.)
Hi Roger,
I have found just put a question in on the green face thingy in the bottom right hand corner (old laptop, new site, using some version of Windows or other).
Folks there are very helpful and sometimes can give very good answers, or just say data provision...
Tommy
Bonkers, in my opinion, that Aquis has a market cap of over £150m and is loss making when the Guernsey Stock Exchange (renamed The International Stock Exchange Group or TISEG) makes annual net profits of approx £4 million, a market cap of £26m, a P/E ratio of 6.5 & an EV/Ebit ratio of 3 ! Oh and it pays an annual dividend of about 7% ! Plus it was a recent ten bagger and is still very lowly rated.
Hi Joe
Looked on iWeb, and probably me just using an antiquated dealer service, but it cannot even find it, then again neither can this site when I search...
Tommy
Hi Tommy,
Here's the link to their website : https://www.tisegroup.com/mark... You won't find TISEG listed on the London Stock Exchange or here on Stockopedia as their shares are listed on their own exchange, the Guernsey Stock Exchange. There is a market for their shares and anyone can buy them. You'll need to contact TISEG's official broker, Ravenscroft. They're based in Guernsey and are the market maker for the shares. Their website is : www.ravenscroftgroup.com. TISEG is a fantastic little company in my opinion, monopolistic position (as most exchanges are) with strong recurring revenues. The KPI for them is how many listed securities there are on their exchange, that's how you judge their performance. They've been steadily rising for a while now.
Good luck,
Joe.
Jack, I see Gattaca (LON:GATC) is down 20% today, so maybe Ferrexpo (LON:FXPO) was not such a bad decision afterall.
Another IPO today was £MEAL Parsley Box
"The fundraising, which was significantly oversubscribed and well supported by customers raised gross proceeds of £5 million for the Company and £12 million for selling shareholders. At the placing price of 200p, the Company's market cap is approximately £83.8 million".
Three hours in, plenty of small sellers below 190p. I like the idea of the product but did not buy via Primary Bid. Too racy a price for me. Inside shareholders cashing in etc.
Nearly four years since this IPO "the Placing raised £102.7m of gross proceeds at a Placing Price of 161 pence: £92.1 million of gross proceeds for the Selling Shareholders and £10.6 million of gross proceeds for the Company". Which stock?
£QUIZ now just 12p. I reckon some of these IPO's where insiders are selling at the float price is a quick route to the poor house myself!
Paul,
Re: Topps Tiles (LON:TPT)
"Refers to Topps' goal of accounting for £1 in every £5 spent on tiles and associated products in the UK by 2025, thereby increasing its market share to 20% from approximately 17% at present."
This was in the update this morning and it's not the first time I have seen it - Doesn't strike me much as a selling point, what's that, a 15% increase in sales between now and 2025 !!!!!!!!
Maybe I've read it wrong or missed something !
Maybe it assumes they will get above that 7% or so margin average ?
Hardly small cap but, for interest, Deliveroo having a torrid first days trading. Currently just below 300p compared with 390p offer price.
Its easy to see whether Deliveroo is overpriced or underpriced.
Just compare it to Just Eat (LON:JE.)
Very similar business models. Marketplace that connects restaurants, underpaid workers, and customers. Maybe attach a bit of premium to Deliveroo over Just Eat?
As £ROO isn't making any profits, you can just compare on Revenue multiples against Just Eat (LON:JE.) and see where that lands in terms of valuation....
There is nothing on Stockopedia for Just Eat for some reason?
The ticker has changed to JET Just Eat Takeaway.com Nv (LON:JET)
Thanks, maybe Stocko could put the information on the old ticker screen.
Question already answered - sorry
I would argue that comparing £ROO to Just Eat Takeaway.com Nv (LON:JET) is justifying one silly price by reference to another silly price. I agree with the Stocko decription of JET as a Sucker Stock.
Doesn't mean it is a suckered stock. That is just a guide.
Many early stage companies are ranked the same way, it doesnt mean they won't generate strong returns as the bottom line matures as expenditure for growth slows down.
Plus500 has been +90 stock for a year and has been stuck around 1300-1500 range. I bought £TW when stockopedia ranked it at 34 because the momentum dropped so much back last April at 115p-ish. It is now 180p.....
Deliveroo deliver 100% vs Just Eat Takeaway.com Nv (LON:JET) 15% so it has much higher operational leverage.
Just Eat is also leading or second in all markets but the US.
I would have a premium on Just Eat Takeaway.com Nv (LON:JET) and quite a decent one.
.
Bought Gattaca (LON:GATC) a month ago.
Star performer for me.
Compensated for all my losses in the Big Miners. I dumped them.
As we enter a new AI assisted age, we should not forget all this tech is created, installed, operated, and monitored by people.
Who supplies the people?
Well, in part, by the recruitment agencies which understand the people on its books as well as the needs of their client companies.
And let's be clear, all companies will be using AI software, or techniques, or systems to some extent in the coming years. The main shortage is people.
How did I find Gattaca? Via Stocko!
Bingo!!!
.
The share price was 140p at the time of your post.
Just half an hour later it dropped to 120p - not a lucky momentum for you, hopefully it will bounce back.
NXR - Would look very cheap if annualised EPS based on 2nd half of 18.2p was 36.4p. Any thoughts on divi?
Hi zipstuck (love the username!!),
NXR - Would look very cheap if annualised EPS based on 2nd half of 18.2p was 36.4p.
Well, I don't think that's a valid way to value £NXR because H2 would have seen a degree of catch up sales, deferred from lockdown in H1.
It's a bit like Scs (LON:SCS) (I hold) - the usual seasonality there has completely reversed, because sales were deferred by lockdown, then a huge catching up bonanza occurred.
Hence I think we could get carried away, and over-value things, if we take a bumper, catch-up half year, and double it to forecast for a full year that's unrealistically high.
That said, if NXR does 26p in FY 03/2021, which looks likely, then we should probably now be valuing the shares on FY 03/2022 forecasts. Maybe 30p+ EPS? PER of 10-12 gives 300-360p price target, not much above current price of 270p, so personally I don't see enough % upside to want to buy now.
Regards, Paul.
On Bigblu Broadband (LON:BBB)
As a customer I swapped from satellite to 4G, it's quicker and cheaper. That's what stops me getting excited. There are areas that can't get 4G of course but it's a better service for those who can, and I suspect most who can't get cable broadband could get 4G.
Satellite is mainly for Australia it seems, the UK solution is fixed and wireless supported by UK govt funding
You would be surprised by Elon's SpaceX is serving homes in parts of the the UK and with very fast speeds.
We live in rural Sussex and are years away from getting decent a fibre connection. I signed up to the SpaceX beta last month and hey presto - our download speeds have gone from 6Mbps to 200Mbps with ~40ms latency!! Took 5 mins to install (get out of the box and plug in) and it 'just works'. No digging up roads, laying cables, etc. (And yes - I appreciate rockets were sent into space at some massive ecological cost).
How much does SpaceX beta cost? I have seen £75 + VAT quoted.
4G is poor around here, can't even get mobile phones calls sometimes.
My broadband is around 35mb and is fairly stable, cost is about £26 pm.
Just started checking out Starlink for Devon. They claim they hope to be able to start service in late 2021. But costs are £490 setup and £89pcm.
My ADSL link is going to have to keep me going for a while yet. Much as I'm infuriated by Openreach who never got round to upgrading our local cabinet 5 years after the exchange was updated for FTC, and who now say - oh that's stone age tech we don't do that anymore - but have absolutely no interest in laying fibre to the house, copper just about does what I need for now.
Thanks, those costs are far too high for me. Speed is not a great issue for me, the current speeds are good enough, to do what I want on the internet, costs however are an issue. No fibre around here either.
Maybe these costs will come down in the future?
Re discussions on Starlink
Of course it depends on what mobile reception is like where you are but have you considered mobile broadband?
I live in East Sussex - BT can only supply broadband down the 'phone line at 250Kb/sec (no, that's not a typo) so we use Three. A SIM located in a router and usually gives us speeds of between 25 Mb/sec and 30 Mb/sec at a cost of £17.46 per month. Not always as fast as that but never had problems with watching Netflix, Amazon Prime, iPlayer etc. No buffering involved.
Yes I considered mobile but the signal is not good enough here, even my mobile does not work half the time. I get 35mbps so not too bad.
Did you set this up yourself?
I live in Monmouthshire and I use a company called Country Connect, as I was only getting around 2mb with Sky.
Yes. It’s totally plug and play. The only thing it doesn’t do (that BT do) is the ‘guaranteed wireless in every room’ offer. Not a problem for us but if you are heavily invested in BT’s Wi-fi then you might find you need some expert help. Buyer beware.
Wish I could say the same for Pimlico in goddamn central London! That said, at previous addresses and in previous countries, my friends would look at me in horror that I’d paid an extra £5 per month to have unlimited data while ditching the £25 to £30 per month wifi agreement.
Paul, be good to hear your thoughts on Cloudcall (LON:CALL), which I think you hold too (or used to). Final results still promising an improving picture and a recent placing.
I know I am late on the placing and you may have discussed this yesterday. But I have just got home from an unplanned hospital visit and haven't yet gone back over what I have missed in the last couple of days.
Having rummaged through the results today for Cloudcall (LON:CALL) there's not much new news IMO. Still on track for the year, on track for EBITDA breakeven for 2023. No new-new products to announce, no unexpected sales or market changes that hasn't been flagged up before.
Fundamentally the huge issue they have is that they've set themselves an EBITDA breakeven target, only on a monthly level, in CY2023!
My mistake has been not to exit the share earlier this year at higher prices. But I still have conviction that when I compare on a Revenue multiple basis, compared to US small tech shares, Cloudcall (LON:CALL) is cheap. Also my theory is that with such a big list of US investors on the top 10 list, it is probably only a matter of time before they move to a US listing, either conventionally or through a SPAC.
(I hold)
Morning Paul and Jack
I'd really appreciate your thoughts on James Halstead (LON:JHD) who have reported this morning
My thoughts on £JHD.....solid results considering the background. To be flat on revenue and up slightly on profit and cash is really impressive for this sort of industry during covid.
Having said that I feel the price is where it should be, or even slightly expensive.
To me it's one for the coffee can, although it's unlikely to be a multi bagger you should sleep soundly.
James Halstead (LON:JHD) - it's over £1bn market cap, so not a small cap, and it's not a company where I have any particular insights. Sorry about that.
I can't fathom why it's on such a high PER, given that it looks ex-growth? Very good quality scores mind you.
Paul,
James Halstead (LON:JHD) has a fantastic dividend record, one is treated like one of the Halstead family as a shareholder.
James Halstead (LON:JHD) - I think the high valuation is a reflection of Business Property Relief for AIM shares. JHD is very much a blue chip AIM company, so is widely held by IHT avoidance scheme promoters on the same basis as "Nobody ever got fired for buying IBM kit"........
There are a number of similar AIM companies where I believe the valuation is similar - and self-sustaining, until it isn't..........
Sumo (LON:SUMO) - here we go again - headline shows basic eps 1.08p, consensus is 7p - panic. It is not until we get to the middle of the financial report that we find "adjusted basic earnings per share was 7.93p" - phew. This presentation really is annoying.
Paul will recall that he was confused by the same thing at Venture Life (LON:VLG) last week where it was even worse - buried in note 5 to the a/cs.
Good point sharw, thanks.
As a general rule, I think companies should present their numbers in a way which is consistent with broker analysis.
Everybody knows that brokers consult closely with companies, when preparing research, so why can't they work together to present numbers in an aligned way?
I remember John MacArthur of Tracsis (LON:TRCS) giving an excellent presentation to an investor evening, years ago, saying that the broker forecasts are the company's forecasts! We just have this silly system where everyone has to pretend that broker numbers are somehow independent of the company. Another area that needs reform.
Regards, Paul.
Hi Paul
Taking your point even further, I would rather companies shared their forecasts directly with EVERYONE at the same time, not just their broker and/or analysts.
Incidentally analysts (who actually publish the forecasts) aren't allowed to speak with the broking team (who know too much), and controls are meant to be in place to enforce this, but they probably do.
I think it's unfair that anyone should have any sort of advantage over anyone else, especially for something as simple as a company-directed forecast.
Cheers
A
EDIT: Just to add that I don't know too much about how brokers/analysts/forecasts work, and the above is all from a chat with a friend who works in an IR department, so I would assume it's correct.
Might be worth taking a look at the results of small cap satellite broadband provider Bigblu Broadband (LON:BBB) .
https://www.investegate.co.uk/...
Quite a lot of moving parts in 2020 including the disposal of a chunk of their European business at a significant premium to book value and further investment in their residual core businesses. Net effect is the company is now positive cash and most of the performance KPIs are starting to move in the right direction.
Like for like revenue growth on a constant currency basis of 4.3% (FY19: 3.0%)
· Total revenue increased 1.3% to £27.2m (FY19: £26.8m)
· Adjusted EBITDA increased 29.7% to £6.2m (FY19: £4.8m)
· Adjusted PAT improved to a profit of £1.3m (FY19: profit £0.3m)
· Adjusted EPS of 2.7p (FY19: loss 0.1p)
· Adjusted Operating cash inflow of £3.8m (FY19: £0.7m). Adjusted Free cash outflow of £3.1m (FY19: £3.7m) following capital investment of £5.6m and before exceptional items of £0.5m
Interesting business that fills a need (broadband access to remote areas where fixed link costs are prohibitive) and which appears to be getting some traction. Interesting shareholder group too.
Gus.
Bigblu Broadband (LON:BBB)
do bigblu derive a big chunk of their income from satellite transmissions ref broadband?
If they do i would be more than worried that Starlink may blow them out of the water - you know who (google does if you don't !) has done it again it seems. Starlink already have over 1,2000 satellites in space doing their thing - judging by the you tube reviews it seems very much that the starlink system delivers exactly as promised (and then some) straight out of the box. I don't really see how anyone can compete short term again Starlnk if i am being honest ref satellite transmitted broadband.
Ok there is room for multiple providers here and its presumably a semi monopoly type industry where its probably in no ones interests to start a price war may leave room for others to thrive but i suspect very soon starlink will be majorly dissruptive to anyone earning their buck in this area.
I think starlink is now available in some parts of the uk - i doubt it will be long before they have full uk coverage.
Apologies if this post seems like an advert for the competition.
agree absolutely (see my post up the page re SpaceX - I meant the subsid Starlink. We have a near neighbor in a 'blackspot' who has struggled in darkest Essex (actually not far from Braintree) who has switched and says its brilliant.
Not really rmillaree - most of these broadband satellite companies purchase wholesale, so they will buy capacity from Starlink, Avanti and other Satellite operators and then bundle up broadband deals and sell them on. So in future you may well find that your Bigblu Broadband (LON:BBB) connection is actually via Starlink as an example. I know Bigblu Broadband (LON:BBB) already buy from a few as I asked this question ages ago.
Looks like a transformational update from #BBB BigBlu Broadband this morning? Net debt to net cash position. EPS hugely up. Customer growth, rev growth. Seems to be doing very well in Australia and lots of government support for rollout here in the UK
Morning Paul and Jack,
Would love to know your thoughts on Gattaca (LON:GATC) (i hold) interim results today.
Morning Cdog!
Jack is just about to publish a section on Gattaca (LON:GATC) (I think we both hold).
I'll be looking next at:
Topps Tiles (LON:TPT)
Wincanton (LON:WIN)
and Cloudcall (LON:CALL) (I hold) .
Regards, Paul.
My morning smallcap tweet:
Oxford Biodynamics (LON:OBD) Simigon (LON:SIM) Eden Research (LON:EDEN) Time Out (LON:TMO) Hydrodec (LON:HYR) Topps Tiles (LON:TPT) Norcros (LON:NXR) Mobile Streams (LON:MOS) NMCN (LON:NMCN) Sopheon (LON:SPE) Fuller Smith & Turner (LON:FSTA), DP Poland (LON:DPP), Cloudcall (LON:CALL)
Oxford BioDynamics (OBD) supply and resale agreement for the manufacture and sale of the new EpiSwitch® Explorer Array Kit for which Agilent will supply a custom-made SurePrint G3 CGH Microarray. The kit "simultaneously interrogates almost 1 million 3D genomic sites, providing over ten times more high-value data points than conventional methods." [SP=96.5 Cap=89m]
SimiGon (SIM) guides FY(Dec) rev down 34% and net adj loss c. $1.8m ($1.14m) after 'resilient' H2. Outlook - no figure but "encouraged by the changes in the simulation and training environment". [SP=5.62 Cap=3m]
Eden Research (EDEN) bio-fungicide authorised in Spain for use on a range of new crops for the control of a larger number of fungal pathogens. It's "a meaningful increase in Eden's addressable market". [SP=15.2 Cap=58m]
Time Out (TMO) [last night] £15m placing at 35p, a 17% discount, to keep the lights on. Also £1.4m raised via PrimaryBid. [SP=40.7 Cap=115m]
HydroDec (HYR) shares cancelled after being suspended for max 6 months. Co intends to offer a matched bargain facility. Has reached agreement, too late, on a $6.75m refinancing package and repayment arrangements for US$4.3m loan. [SP=3.35 Cap=1m]
Topps Tiles (TPT) Q2 rev down 17% LFL and margins lower. "Well positioned for growth" as lockdown ends. [SP=69.13 Cap=135m]
Norcros (NXR) FY(Mar) U/L profit guidance hiked £3m to at least £31m. [SP=256 Cap=207m]. I hold.
Mobile Streams (MOS) rows partnership with, and provides funding to, early stage business Quanta Media. £500k max in converts. "It is now likely that MOS will be able to drive [more?] extra revenue from its legacy business as initially thought, whilst Quanta has also confirmed it should be able to utilise its iGaming platform to drive additional revenue." [SP=0.24 Cap=5m]
NMCN (NMCN) refinancing talks continue. [SP=298.95 Cap=31m]
Sopheon (SPE) new CEO, old CEO becomes exec chmn. [SP=868 Cap=91m]
Fuller,Smith&Turner (FSTA) £54m placing at 830p, a 10% discount, to strengthen BS. [SP=870 Cap=281m]
In line: DP Poland (LON:DPP) Cloudcall (LON:CALL)
Morning Paul & Jack, would love your thoughts on Sumo (LON:SUMO) (I hold) looks like an excellent set of results to me, I am hoping the momentum in this sector continues when the world re-opens.
The Outlook statement from Sumo (LON:SUMO) certainly reads well:
·
Advancing technology and new platforms fuelling market trends, bolstering publisher confidence to increase the scope and spend on games and underpinning the Group's long-term growth
·
Global demand for quality premium content is constrained only by industry capacity
·
Ongoing Group focus on increasing headcount organically and via acquisition
·
Strong acquisition pipeline with a number of targets being actively pursued
·
Very strong pipeline of business development opportunities on major new projects, with both existing and new clients
·
A number of interesting Own-IP concepts being explored
·
Investment in the development of Secret Mode for its mid to long-term success
·
Strong visibility with 85% of Sumo Digital's budgeted development fees for FY21 contracted or near-contracted5 at end February 2021 (FY20: 73% at 31 March 2020) and, on a broadly comparable basis, Pipeworks is at 50%, similar level as the prior year
·
The Board views the opportunities for the Group in the year ahead and beyond extremely positively
Hi,
Sumo (LON:SUMO) I read the results and was not impressed - lots of improved numbers under dubious headings (EBITDA stuff) and a reduced cash and EPS results which is real.
I bailed on the dot of 8am and got the small rise which was lucky as they have now dropped.
They maybe a good long-term bet, but there are a few other companies out there that I'd rather invest in over the next 12months.
Obviously still a possible take-over target but I generally don't hold stocks on this basis.
Yes I agree on Sumo (LON:SUMO) results, disappointing, I probably should have sold out as well. Similar to MPAC (LON:MPAC) yesterday which I also hold.
Morning Lefty99,
Re Sumo (LON:SUMO) - I tend not to cover gaming stocks, as I don't really have any insights or experience in the sector, so I would just be regurgitating the RNS, which is a bit pointless. It's been a good sector for investors in recent years, just not one I know anything about.
Regards, Paul.
Sorry Paul, I understand.
Was a very interesting Mello presentation on Sumo (LON:SUMO) 14th December, on the back of which I put a few into the bottom draw. I don't know if these Mello presentations are recorded and still available for viewing.
Sumo (LON:SUMO) at Mello - you're lucky - 14/12 is one of the free samples: https://melloevents.com/mm-recording-christmas-show/
Feeling robbed now sharw! I paid for it!
Morning Paul I'm not sure if this is on your list but would welcome your analysis if possible. £SEE Half year results
Financial Highlights:
· Operational revenue of A$18.1m (H1 2020: A$15.8m) reflecting comparative growth of 15% on previous period. Underlying revenue growth using constant currencies is 19% year on year (exchange rate as at 1 July 2020).
o Aftermarket (Fleet and Off-Road) revenue grew by 17% to A$15m (H1 2020: A$12.9m)
o Annualised Recurring Revenues including royalties of A$15.5m, representing growth of 17.4% (H1 2020: A$13.2m)
o OEM (Automotive and Aviation) revenue of A$3.1m (H1 2020: A$2.97m), representing a 5% increase on previous period
· Net loss of A$16.8m, representing an improvement of 33% compared with the same period last year (H1 2020: A$24.9m)
· Cash at 31 December 2020 of A$52.3m (31 December 2019: A$47.4m)
Hi Tony1249,
I followed Seeing Machines (LON:SEE) for years, but gave up on it because it never seems to get anywhere near breakeven, let alone profitability. So there's not really any point in me reviewing the figures.
£376m mkt cap strikes me as completely ludicrous. It rests entirely on hopes for future financial success, which I can't measure or meaningfully comment on.
It's one of the stocks that always seems on the cusp of a sales breakthrough, that never happens, despite a big pipeline. A bit like Srt Marine Systems (LON:SRT) these stocks keep promising jam tomorrow for years.
Regards, Paul.
Thanks Paul, I appreciate your valid comments.
Regards, Tony
Norcros (LON:NXR)
it’s vey late in the year for norcross to be making material adjustments to estimated earnings for the year. Year end is 31st March and as recently as 3rd March they confirmed underlying profit will be minimum of £28 million.
They have today revised this figure by over 10% quite a big change in less than a month - the good news is they now expect £31 mill minimum- underlying profit.
To add to the good news they have confirmed they will end the year will no net debt - wowsers - they started the year with £36.4 million of net debt !!