Small Cap Value Report (Weds 4 Jan 2023) - HEIQ, CNC

Good morning from Paul (hardly any news, so Graham's doing other stuff today). There's hardly any news today, so this report is now finished.
We're braced for a very busy month, with lots of 2022 trading updates about to hit us, some of which are bound to be profit warnings, given current tough macro conditions.
Agenda
Paul's Section:
Hospitality sector - the Propel daily news email today contains alarming news for trading in Dec 2022 for late night bar operators - a flash survey of 200 nightclubs and bars shows that revenues were down 20% on pre-covid (Dec 2019). That’s going to leave many struggling to survive in 2023. This whole sector looks really grim at the moment, with reduced demand colliding with much higher costs (especially wages and energy). It’s difficult to see much changing any time soon - the days of generous Govt support measures seem to be over, and disposable incomes seem likely to remain under pressure. So I think we need to brace for many bars going bust in 2023, and the ones remaining just hoping to gain more market share in a smaller market. It's far too expensive to eat/drink out these days, in my opinion. Hence I'm very worried about this whole sector.
Heiq (LON:HEIQ) - a nasty profit warning from this innovative fabrics group, which has missed its 2022 numbers by a long way, citing a plunge in demand in Q4. We've never liked this share here at the SCVR, and now the company is loss-making, it's difficult to see any bull case at all. On the plus side, the balance sheet looks robust overall, with net cash. Although inventories & receivables look too high, so there might be some nasties lurking in those. It's just a punt now really, on a possible recovery, so might be of interest to traders? For me though, I'll continue avoiding it, so a thumbs down I'm afraid, on fundamentals.
Concurrent Technologies (LON:CNC) - a rather underwhelming update for 2022, with both H1 and now H2 only being just above breakeven. The cash pile has depleted a lot too, although credible reasons are provided (inventory build due to supply chain problems), hence that should reverse in future. The main interest here is a bulging order book, so a much better performance is credibly expected in 2023. I think the valuation looks solidly underpinned for now, although further upside would need out-performance against existing forecasts to justify it.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Heiq (LON:HEIQ)
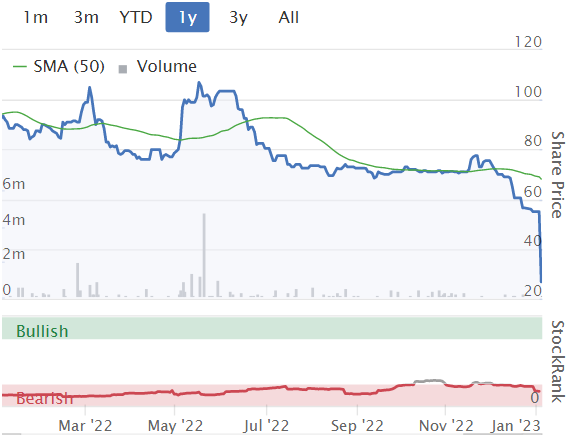
55p (pre market open) - update at 08:53: down 52% to 26.5p
Market cap £77m - update: £37m now, so £40m wiped off the value of the company today.
This company floated in Dec 2020, reversing into a listed shell called Auctus Growth.
I’ve only reviewed HEIQ twice, most recently being underwhelmed by interims here on 29 Sept 2021. We didn’t write about HEIQ in 2022 at all, as the figures didn’t look of interest. Interims to 6/2022 showed another fall in operating profit, to only $1.2m. It expressed “cautious optimism” that FY 12/2022 forecasts would be met.
Today’s news is this -
HeiQ Plc (LSE: HEIQ), a leading company in materials innovation and hygiene technologies, announces a trading update for its year ended 31 December 2022 (FY 2022), as well as the acquisition of Tarn-Pure Holdings Ltd.
I’ll summarise today’s update (profit warning) -
Q3 trading “remained reasonable”
Q4 saw “significant deterioration” in demand.
Reasons?
- Customers over-stocked, and themselves saw reduced demand.
- China especially bad, with sales down 50% vs forecast (blames regional covid lockdowns)
- Brands “more hesitant” to buy innovative products - delayed orders for new products.
Revised guidance - FY 12/2022 revenues to be $54-55m, c.20% below market expectations. Gross margin also lower at c.47-48%.
Now loss-making - expecting $(2.5)m to $(3.5)m loss before tax for the year. This compares with profits of $2.7m in 2021, and $7.1m in 2020. So a very poor trend.
Stockopedia is showing broker consensus at a $4.1m profit after tax for FY 12/2022, so this is a big miss today, ending up loss-making.
Also note that HEIQ made a $1.2m PBT in H1, so that means H2 is a loss of $(3.7)m to $(4.7)m - clearly bad news.
This guidance is preliminary, and subject to audit, as I would expect coming immediately after the year end.
A small acquisition is also mentioned, for £850k.
Outlook - I’d say this is not great, but not a disaster either - if it can strip out a lot of cost, then returning to profit in FY 12/2023 would be a relatively OK outcome - if that happens of course, which it might not (I wouldn't rely on anything management say, given the track record of over-confidence) -
The Industry expects global markets to continue to experience low demand for at least another six to nine months.
The Company also expects trading for FY 2023 to be below market guidance, with anticipated sales and gross margins maintained at FY 2022 levels.
Given the macroeconomic headwinds the Company has started to implement cost savings and will continue to review and adapt its cost basis with the objective of returning to profit before tax in FY 2023.
Is it going bust? I’d say no. The last balance sheet, at 6/2022 is quite strong, with cash of $9.5m, less $2.2m in borrowings.
I do have concerns over both inventories & receivables looking too high at 6/2022. The interims commentary says receivables reduced after the period end, but that some Chinese distributors were paying slowly - that worries me, because today's slow payments often develop into tomorrow's defaults.
Overall though, I’d say the balance sheet looks strong enough to weather a period of poor trading, so no immediate concerns here.
My opinion - how on earth do we value HEIQ shares? It now seems as if the previous big profit in 2020 was a one-off, and it’s now loss-making, and having to cut costs to target breakeven. So the bull case (which was always wobbly in my opinion, see our archive here) has gone out of the window now.
Looking back at my notes, this SCVR from 27 Jan 2021 is interesting - where a presentation by management spectacularly back-fired, with the share price plunging the next day by 23%. I remember it actually, and commented at the time here that a one-off good year didn’t convince me at all that the company was worth c.£200m.
So HEIQ looks like yet another opportunistic float at peak earnings, stuffing investors with over-priced shares that subsequently have gradually collapsed, as profits melted away, now into losses.
For that reason, I don’t think I’d be interested in investing in this share at any price really - I’m not convinced it has a viable business, and I see the poor financial track record (despite plenty of ramping about the company’s potential) as off-putting.
It’s a possible recovery situation, but why would we want to take the risk of things getting worse?
Note the very low StockRank of 16, and the “Sucker Stock” classification on Stockopedia. It also only qualified for 1 screen - the Beneish M-Score Screen for short selling (worth a look actually, it's here).
Hence it has to be a thumbs down from me.
The share price is down 53% at the time of writing, at 25.5p, so it’s a difficult decision for shareholders, whether to just ditch it and move on, or tuck away and hope for a recovery at some stage - not entirely a bad idea, given that solvency risk isn’t an issue (assuming that the accounts are true).
Concurrent Technologies (LON:CNC)
77.5p (up 7% at 10:27)
Market cap £57m
We looked at CNC 3 times in 2022, so I’ve just re-read our articles here to get up to speed quickly. I liked the strong balance sheet, and saw positive potential. Although supply chain problems blunted performance, with only breakeven for H1 to 6/2022, but upbeat outlook comments indicating good interest in, and orders for, new products.
Here’s the latest news today -
Concurrent Technologies Plc (AIM: CNC), a world-leading specialist in the design and manufacture of high-end embedded computer systems and boards for critical applications, is pleased to announce an update on trading for the year ending 31 December 2022 ("FY22").
Revenues c.10% ahead of market expectations of £16m, so that’s about £17.6m actual revenues, which gives us a split of £7.4m H1, and £10.2m H2, a useful improvement in H2.
Profit before tax “at least in line with market expectations” of £0.1m - hmmm, not very exciting, so that’s effectively breakeven in H1 and breakeven in H2.
Supply chain - shortages extended lead times, causing delays to product manufacturing & hence revenues. Inventories increased to smooth over shortages.
Although they’re not out of the woods -
Whilst overall supply chains are seeing a degree of recovery, the Company is in many cases dependent on some very specific components, and hence FY23 forecasts remain prudently cautious.
Cash position - has deteriorated a lot, but for reasonable-sounding reasons. Note that cash was £9.3m at 6/2022, so this is a big fall in H2 -
Cash was depleted throughout the year as a result of the Company's declared strategy of investing in R&D, systems, and growth of its home markets in the US and UK. The additional investment in components holdings to mitigate supply shortages, resulted in a cash low point at the end of FY22, at a value of circa £4M.
With the increased shipping of product in November and December 2022, the Company anticipates strong cash generation at the start of FY23, with further episodes of cash generation as components become more available
I think that’s OK, and am happy with the explanations given for the temporary drop in cash. It’s good to be in a position where there was a decent cash surplus to start with, which has absorbed these issues without increasing risk.
Growth strategy confirmed, both organic and by acquisitions.
Order book - so far, I’ve been underwhelmed with this trading update, but the order book details sound much more positive. With c.50% gross margins, it’s easy to see how revenues could step up once supply shortages ease, resulting in a nice operationally geared boost to profits -
Following a record order intake in FY21 of £25M, the Company is proud to announce order intake for FY22 in excess of £31M, an increase of over 25%. The FY22 closing backlog was also very strong, in excess of £26M. These figures indicate that, as supply chains ease, the Company has potential for significant revenue growth. A further cause for optimism is that the Company expects to run double shifts throughout Q1 FY23, maintaining its increased capacity.
2022 order intake of >£31m compares very favourably indeed with reported revenues of c.£17.6m. A closing order book of >£26m means that I imagine 2023 revenues should be strongly up on the £17.6m in 2022. Definite grounds for expecting a much better 2023, based on firm orders, not just hope. I like that!
Dividends - nothing for 2022, but that looks a temporary issue, given that previously divis have been fairly generous. So I would invest on the basis that divis should return in 2023, that looks a reasonable assumption taking everything into account.
Broker update - many thanks to Cenkos for an update note, which pencils in £22.1m revenues, and £2.7m adj PBT for FY 12/2023. That looks achievable to me, and might even be beaten, given the strong closing order book more than covering the full year’s forecast for 2023.
I don’t find PER valuations particularly useful in situations like this, where profit is rebounding from a breakeven starting point, as the potential range of outcomes can be quite wide. But it’s worth reasonableness-testing the numbers. In this case, Cenkos estimates 3.7p adj EPS, on what I think looks quite conservative, which is a PER of 21x - not cheap, but shareholders will no doubt be expecting that the forecasts are beaten, a not unreasonable assumption in my view.
My opinion - this looks pretty good. I think I’ll give it a thumbs up, since the downside risk seems so well covered by the big order book, and upbeat comments about demand for new products.
I also like the strong balance sheet, so no risk of insolvency or dilution (unless they decide to do an acquisition that needs funding).
Purely looking at the numbers & commentary, I think this share looks worthy of readers doing the more detailed research necessary to assess what the company’s longer-term potential might be.
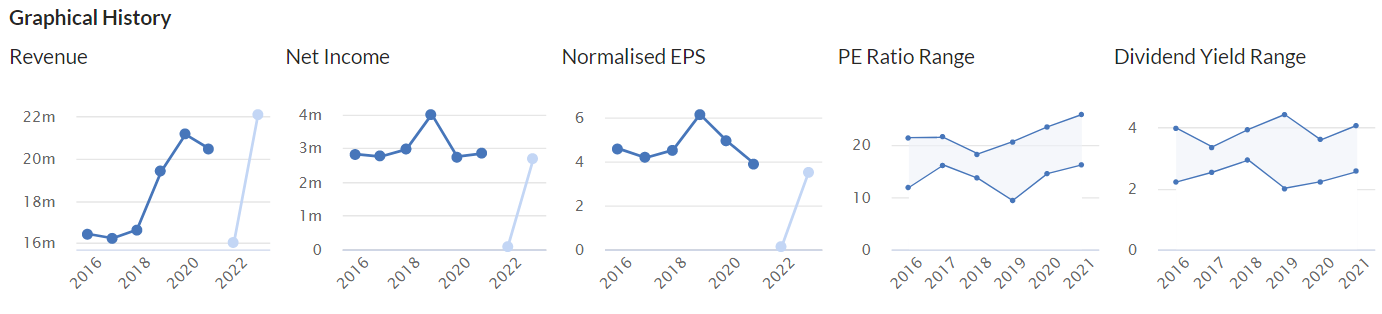
As the Stockopedia graphs below show, in the past it’s been a steady performer, but not much evidence of growth. It could get more exciting if management’s growth plans do result in a faster pace of profit growth. It needs that to happen, as the £57m market cap currently is quite hefty for a company that has only produced typically £3m pa net profits in the past.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Further to comments including mine on PROCOOK (LON:PROC) ) I bought a copy of the most recent accounts for the large minority shareholder, Fackelmann GMBH, which is in he same line of business and has built a stake. After reading these accounts I am not convinced that they have the firepower to buy the whole company, assuming that the controlling family would want a lot more than the current market cap, and in the end I decided that it is well-nigh impossible for a private investor to do more than guess at the outcome here. I also think the next trading update could be bad news. Therefore I have sold for a small gain.
Can I respectfully ask if there is a current issue on Stocko with regard to News items on selected companies no longer being e mailed to my account automatically, as they have been previously ? Had a similar issue pre christmas which I brought to the attention of the team via the green blob , following which it was shortly rectified. Now back to no e mails again.
Hello Rutland, I hadn't noticed the absence but there it is. But I was getting weary of the number of RNS by companies buying back their own shares so won't be missing them for now.
I receive e-mail RNS notifications from the LSE website (FOC) for all my holdings. The deluge of little importance ones daily gets a bit wearisome but it's easy enough to just skim and delete these and hopefully find the important ones. I wouldn't be without it and view it as just another of the active investor chores.
SCS (LON:SCS) (I hold) Hi Paul and Graham. First post after 1yr Stockopedia subscriber. Was gobsmacked when an advert for SCS popped up on the TV offering interest free credit on purchases. Does this mean they have abandoned the thrifty policy of customers paying up front for furniture purchases?
I believe in that situation the finance company would pay SCS upfront instead of the customer, so shouldn't make any difference.
Good morning Paul - you promised a 'mystery share' in your 31.12 podcast...did I miss it not sure? Is it Rotala (LON:ROL) ?
yes to Rotala (LON:ROL) i hold and could not buy more earlier!
Hi filiporoger99,
Yes that's right, the mystery share for the last week of 2022 was Rotala (LON:ROL) - it's a special situation, and very tiny/illiquid. I think it looks interesting after the big property disposal has transformed its balance sheet, and the valuation seems attractively low. Although it's the type of share that could languish for years, as obscure micro caps often do!
Regards, Paul.
Thank you Paul for your reminder on how to set up the tickers.
No need to apologise over Boohoo (LON:BOO) or Hostmore (LON:MORE) as I have only myself to blame. I had always avoided Fashion but was convinced that Boohoo had bought so many iconic names very cheaply they would become iconic themselves.
With Hostmore I did not do enough research and I allowed the Podcasts from the two top guys at Hostmore to persuade me this was a better business than it has turned out to be.
Happy new year to everyone and let's hope 2023 brings a bit more cheer. 2022 was obviously very challenging but pleased to have generated a positive 4% return (having been down 20% at one point). I held a few UK property companies and retailers which obviously got hammered. But this was offset by my diversified portfolio of investment trusts where I regularly switch positions to capture the best discounts. Sterling weakness also helped as most of my funds are global. My energy names (Glencore, BP and Shell) also did well
Looking ahead I'm very optimistic given current valuations, although expect things to remain volatile in short term. I'm currently invested in the following areas where I think there is tremendous value on a long term view:
Life insurers - such as Phoenix group (LON:PHNX) Legal & General (LON:LGEN) Aviva (LON:AV.) very generous and secure dividends, and a beneficiary of higher rates - the whole sector just looks too cheap in my view.
Property companies - these clearly face headwinds but this is more than priced in and balance sheets look rock solid to see them through the tough times. Holdings include MJ GLEESON (LON:GLE) Morgan Sindall (LON:MGNS) SEGRO (LON:SGRO) Forterra (LON:FORT)
A few deep value names trading below NAV or on very low PEs - Vertu Motors (LON:VTU) Hargreaves Services (LON:HSP) Smiths News (LON:SNWS) SCS (LON:SCS)
A variety of energy and resource names where I am still bullish £BP Shell (LON:SHEL) Central Asia Metals (LON:CAML)
Cheap investment trusts - mainly in the private equity space where discounts are still around 40%
Litigation - this area has been very disappointing for several years but am hopeful they could finally deliver in 2023 - I hold Burford Capital (LON:BUR) and Manolete Partners (LON:MANO)
Also very good value in bonds now so hold some through ishares ETFs - these should also act as a nice hedge if equity markets continue to tank (this wasn't the case in 2022 but this really was an outlier and think bond will be a lot more resilient this year as inflation starts to ease).
Yay! You're in the rare "Positive 2022" club!
I also hold Phoenix group (LON:PHNX) but have also been tracking Aviva and Legal & General. I chose Phoenix because of their strength in consolidating closed books, as well as acquiring DB pensions, which I expect there to be more activity going forwards. But purely on the insurance category, which of the three do you have the most conviction on?
I am also actively monitoring property companies. Different names to the ones you quote - the usual big housebuilding suspects like Barratt, Taylor Wimpey, etc. Do you see specific property sectors as attractive rather than the whole, hence your more specialist picks?
FWIW I think there is still alot of trading pain to come for the big housebuilders in the next few months, but the market seems to be too efficient in marking down their prospects already, that the bad news looks priced in. Still, what is cheap can get cheaper with further bad news, so I am waiting for that final capitulation, as the housebuilders have been retailer investor favourites for a while, and their capitulation usually gives some good share price dislocations.
Bonds - corporate or government? UK or any specific overseas countries?
Well only positive on a nominal basis - still someway behind inflation and hoping this year will be a lot more fruitful!
On life insurers, Legal & General is probably my preferred pick as I think it has the best growth prospects, including a strongly performing fund management business. It also has its own capital division which develops a range of assets (everything from renewable energy infrastructure to housebuilding) to back its liabilities - I think this gives it a bit of a competitive advantage, although I still like Phoenix and Aviva and happy to hold those too.
Yes I see value across the whole property sector, everything from REITs to housebuilders, as well as things like brick manufacturers. I think all the housebuilders look good value, but I chose Gleeson due to their focus on discount homes (which in theory should make them more resilient, although whether that works out in practice is another thing).
I think industrial property still has good growth prospects, hence recently buying Segro on a 40% discount. However much more cautious on offices and retail property so continue to avoid those areas.
Bonds - I think investment grade corporate bonds give the best balance between an attractive yield but with low default risk. Not so keen on high yield as I think defaults there could rise. I hold the ishares US corporate bond ETF (the GBP hedged version as I think the USD looks very expensive now - the ticker is LQGH).
As we start the New Year a huge thank you to Paul, Graham and all the team at Stockopedia.
I do not know how you do it all Paul and I love your cheerful nature even when things are going pear shaped as in 2022.
It is 19 years ago this month I opened my Account with Hargreaves Lansdown. Last year was very challenging and I finished 14.9% down on the year.
The negatives were Polymetal down 85% and Ferrexpo down 68% on the Russian invasion of Ukraine on 24th Feb. Fortunately both are small positions and in the last 7 years I have done very well on both shares.
The real disasters are BOOHOO -89%, should have had a Stop Loss, MORE -91% but only 3% of my portfolio and Saga which is a long term hold for me.
Successes have been Entain,my No.1 position, ITV were my average cost per share is 64p, K3C now sold, Mitie, Newmont and Black Rock Gold & General sold last January.
Sorry Paul I have forgotten the new set up for the tickers hence I have used the full name!
Hi portugull,
Yes, sorry again about Boohoo (LON:BOO) and Hostmore (LON:MORE) they were absolutely dire in 2022, along with the whole eCommerce sector.
Sorry Paul I have forgotten the new set up for the tickers hence I have used the full name!
It's dead easy. All you do is type the "at" symbol key, then a box pops up which will be self-explanatory when you do it.
Regards, Paul.
Not a small cap but I think that Marks and Spencer (LON:MKS) looks like a good value opportunity. I have recently been into a few stores after decades of not shopping in Marks and Spencer (LON:MKS) and I have been really impressed with the quality of their men's clothing ranges and the prices for that quality (perhaps because I'm getting old!). I have been to Southampton West End, Kensington and Chelsea and Oxford Street stores. They are currently trading on 0.22 of sales and below tangible book (0.89) - I believe that Marks and Spencer (LON:MKS) will benefit from the UK high street problems and will gain market share as well as being able to pick up brands at a low cost. I think what the management have been doing is quite impressive and the share price is very undervalued. Opinions welcome!
Marks and Spencer (LON:MKS) has been on my watchlist radar for quite a while now, but never gotten cheap enough to my buy price (c.100p) to pull the trigger. I'm not too fussed though; the SP hasn't gone anywhere for a while, suggesting the market thinks the same.
The problem I have with large caps, is that passive index buying (ETFs, funds, etc) keep the price of companies artificially high. It is only when there is a negative catalyst (profit warning, issue, etc) that causes the price to decline, then there is a spiral downwards. Caused by funds and ETFs selling as the weighting goes down, short sellings then exacerbate the decline, retail investors throw in the towel, that the price then becomes artificially below the intrinsic value.
So far, that hasn't happened with M&S yet.
I did miss a golden opportunity back in early Oct, due to the wider macro-panic at that point. My buy price then was 95p, and it briefly went below that, but I was a bit busy at that time and didn't act on it quick enough to catch that bottom, before it rebounded.
The counter-argument to investing in M&S though are:
- Broker forecasts expecting another declining year of EPS, for FY Apr24. Do you believe different.
- Dividend yield is low, so you're not adequately compensated for waiting
- There is lots of tangible assets value, but is there a clear and quick path to realising that value
They recently purchased the technology that was behind thread.com, this was a great website that helped men picked clothes, so if they apply this right then it’ll be another string to their bow.
Marks and Spencer (LON:MKS) in Tunbridge Wells has been very busy for months and remains so. The food section is remarkably good value.
This from Heiq (LON:HEIQ) is worrying, if it is indeed more macro consumer slowdown, rather than Heiq finding excuses for its own poor performance:
"HeiQ's customer base (apparel manufacturers) had up to 70% less demand in Q4. HeiQ's sales in China suffered especially, due to pandemic related regional lockdowns and half of the forecasted annual sales did not materialize."
I’m expecting the hospitality sector to struggle too although I do have a position in XP Factory (LON:XPF). Interestingly I tried to book a table at a restaurant here in Kent for this Friday and 3 of my first choices were full! Not what I expected straight after Christmas.
In London tried to book several pubs for dinner on Saturday night. All fully booked, also found strange straight after Christmas. For what it is worth central London was the most packed I've ever seen it around Christmas time too. Barely room to move. I queued for nearly an hour to get into one of our favourite chinese restaurants in China Town in late Dec.
Whether that translates to spend across hospitality I don't know and it may be different in other parts of the country.
A little disappointed with the market reaction to Concurrent Technologies (LON:CNC) RNS this morning only up 3.5% as I write.....however....
Lots of positive vibes which for me reads as a potential future multi bagger if I'm honest, with the company suffering from initial growing pains as the new ex Qinetiq (LON:QQ.) CEO and management team began to turbo charge this business (maybe too much to soon), and the talk now is of short to medium term growth rather than longer as read in previous RNS's.
This particular RNS was the final hurdle for me, and the one that most worried me (as I was fully invested on recent SP lows) as potential supply chain issues continued to linger, but with double shifts being worked for the last two months of the year, and the continuation of double shifts for Q1 of the New Year, they have managed to grow revenue to exceed market expectations with profit in line, and the now 'short term' outlook seems much brighter.
They still have £4 million in cash and seem to be indicating a possible acquisition 'to own more of the technology building blocks in embedded systems' which does sound positive, and perhaps is aimed at further reducing these supply shortages which have plagued the business turn around to date?
The ability to sell domestic products into America with a 'Made in USA stamp' has been achieved and seems very promising.
An order book now at £31 million and with supply chains easing they expect a significant increase in revenue. Will this increase drop to the bottom line with increased costs of double shift working, well time will tell.
Dividends have been dropped for FY22 with the cash being used for R and D and component holding, which I'm comfortable with as product needs to get out the door, and I am happy in this case to take a little pain for future potential growth. I would like to see some decent sized Director buys, come on guys get some skin in the game!
So 2023, the transition continues, although I am now bullish that future trading updates will be positive and therefore happy to be fully invested in this one, as the S.P and forward EPS growth looks on the cheap side.
As always DYOR, and best of luck!
(I Hold)
Just to add re Concurrent Technologies (LON:CNC) that I understand that much of the inventory build up is not just in component stocks but in almost completed boards that are awaiting the last few components to complete. So that is going to have eaten up a lot of cash but should unwind quite quickly as component shortages ease.
I hold.
Does this mean you've had a change in thoughts on XP Factory (LON:XPF) ?
Hi Yman,
Does this mean you've had a change in thoughts on XP Factory (LON:XPF) ?
No, I'm sitting tight on XPF long-term, whilst aware of the short term sector risk, because it's doing something different - experiential leisure (competitive gaming), and a lot of the sites are franchised, which helps protect the central company (it still receives royalties on sales, even if business is slow). It opened so many new sites this year, that operationally things are bound to have seen teething problems.
Whereas I'm not interested in investing in any conventional bars at the moment, as they must all be struggling. Nightcap (LON:NGHT) shares have really cratered I see, as also have Various Eateries (LON:VARE) and Revolution Bars (LON:RBG) (I cannot understand why the CEO did a big recent acquisition, funded by debt, which looked bonkers in the current macro environment).
J D Wetherspoon (LON:JDW) also very weak, I've been meaning to review that one, but couldn't find the time, as it's not a simple one to analyse, with freeholds, and debt to investigate carefully.
Regards, Paul.
EDIT: TripAdvisor reviews for Boom Battle Bars (the most interesting part of XPF) are generally very good, considering people are usually only motivated to write something on TripAdvisor if they've either had a very good, or very bad experience! So to my mind, anything above 4/5 overall is a strong result.
Thanks for the quick reply, i notice your local Bournemouth Boom is busy when looking at the online booking site, which also mirrors most other Booms when i have checked online over weekends/Xmas period so hopefully bodes well.
I would be tempted to put XP Factory (LON:XPF) in the same sort of camp as Hollywood Bowl (LON:BOWL) and Ten Entertainment (LON:TEG), whose results have been pretty stellar, if not a little surprising. If they can keep the pricing keen they have an advantage over conventional pubs IMHO.
In the current climate throwing axes is one of my mornings first thoughts :-D
I don't hold any of the above (or an axe) currently.
Just throwing in my tuppence, as an operator in hospitality.
I can corroborate that sentiment in the sector is at rock bottom, with many operators struggling. But it's also important not to generalise too much.
If you are an undifferentiated, me-to, nothing really special kind of operation, carrying too much debt or too high lease costs: then yes, you could be in real trouble (Hostmore (LON:MORE)? The latest leaks anout how the energy support package is to be drastically cut, may be the final nail in the coffin for some, and there could even be casualties before then, as Christmas trade form many has been at best poor, if not dire. We have now had 3 Christmases ruined. But look, if your whole business depends on 3-4 weeks of trade, then maybe....?
But (and I can only speak for myself and another private co I have invested in) - if you are "special" to your customers, a real and/or a reasonably affordable treat, fixed your energy costs maybe back in 2021, and are not over rented, you should be ok, if not thriving.
As at the end of Nov, we (a group of 5 entertainment venues, mainly comedy clubs, but also now offering more diverse shows), we were +5% (sales) vs 2019, and site ebitda +14%, albeit with some help from continuing rates reductions. My December figs should be available to me any day and will be poor, denting the FY, but I'm hoping to hold on to a +ve outcome overall, which I am pretty happy with, given how both Jan (Omicron) and Dec were compromised.
Good/well run operators, like cream, rise to to the top, even thrive.
I'm a bit sceptical about the new wave of competitive socialising. Barriers to entry are low and there's been a bit of a gold rush - I'm seeing overcapacity building, and a possible reconing. Crappy golf operators are already failing. I haven't done a deep dive on the likes of XPP but I'd be a bit wary. You go to these places once out of curiosity but do you go regularly? I do wonder whether the management shake up announced today at Nightcap (LON:NGHT) may be a response to poor performance, but I was quite deeply sceptical about this somewhat hurried buy/build anyway, it semed too opportunistic. I'm actually less sceptical than Paul on Revolution Bars (LON:RBG), but this is mainly because, at least for now, Rob Pitcher is highly regarded, and I think the deal was sensibly priced for what was a well regarded group. I quite like Fulham Shore (LON:FUL), for the longer haul.
Like housebuilders, there will be a time, possibly soon, where it could pay to take some positions in leisure and hosiitality, it's probably not right now, and will certainly be a case of making very careful selections.
Well done Mark
At least 80% of my companies performed well operationally in 2022 yet my portfolio finished down 27%. It would have been worse were it not for helpful currency exposures, but even that benefit dramatically unwound in the final stretch. My portfolio consists almost exclusively of long term hold, quality names - debt free, high returns, expensive - so the results were consistent with soaring bond yields and a rotation into energy stocks.
Am I happy to lose that value? Of course not. Am I worried about the companies I own, or their sectors? Not in the least. 80% of them are awarded a wide or narrow moat in the Morningstar tables,the remainder being mostly too small for Morningstar to have a view. 100% are driven by secular drivers such as the energy transition, digital transformation, ageing populations, Asian middle class, automation.
I don’t have a prediction for this year but I’m persuaded by the bulk of bank analysts who predict a volatile H1 for equities and a better H2. Who cares? As long as the portfolio constituents continue to perform operationally, dividends will be paid or buybacks executed, and the macro will evolve over decades to set asset values, at times favourably, sometimes unfavourably. I’m off hill-walking.
Re hospitality sector - any readers with views which are best and likely to ride it out. presume RBG will struggle, and major pubs cos will be OK?
IMO the hospitality sector is the one most likely to fail. In his most recent article Edmund Shing has highlighted those sectors most likely to provide positive returns. It seems a wasteful exercise investigating investment in hospitality where there are so many headwinds.
thank you
Thoughts not predictions. My return over 2022 was -9%. This is includes living expenses. My targets are much higher and my defensive investments were disappointing Volvere (LON:VLE) -8%, Sherborne Investors (Guernsey) C (LON:SIGC) -22.6%, BT (LON:BT.A) -35%. Yellow Cake (LON:YCA) was up 5%. A smaller investment but huge loss was Hostmore (LON:MORE) -90%. I managed to trade gains other larger stocks like Imperial Brands (LON:IMB), SSE (LON:SSE), Fresnillo (LON:FRES), £IGG.
Going into 2023 I will avoid the temptation to make a prediction. The market is always tough because the unexpected tends to happen...and normally this shapes the year. Most of the time, I think I read 80%, the market is positive 12 months later. So I'm inclined to worry less about the market and concentrate on investments. I think as returns could well be low positive being invested is fairly critical otherwise you risk mistiming to a poor return.
I have 5-6 decent size positions in Sherborne Investors (Guernsey) C (LON:SIGC), BT (LON:BT.A) , Volvere (LON:VLE), Yellow Cake (LON:YCA) and then Serica Energy (LON:SQZ) and £FRES. I have also bought some bonds esp in. my SIPP where mid single digit returns are plenty enough.
2023 is the first year in perhaps 20 where the market fell in the previous year, you have decent single digit bond yields available and many stocks sub 10x to buy. This seems a decent backdrop to invest with a high single digit expected return. I believe this should beat inflation but time will tell. I think inflation as reported is much less of an issue for retired people as an IFA would lead you to believe. Pretty much all expenditure is discretionary that can be adjusted and economised. It may affect lifestyle but not as much as feared.
Without making a grand prediction for the year I would argue the backdrop is favourable. It seems rather popular to expect a lurch down... maybe, maybe not. We do seem very well hedged for an event that surely won't be as dramatic as a result. Isn't everyone expecting earnings expectations to fall?
Dont confuse this last point with you shouldn't worry about falling earnings. £BT.A disappointed in 2022 esp at cash flow and pension. This makes the balance sheet less robust to cost overruns on Capex...and therefore the stock im more worried about although priced so attractively Im inclined to run. I also believe the pension cut off date last September was particularly bad timing. So what should be defensive was disappointing. Prospects for a decent buyback at the end of the Capex cycle would be very positive IMO.
Best of luck in 2023 finding the gems. Obviously looking back returns would always have been better if I had cut some losses earlier...Im also less sure that's the case looking forward. We will see.
RDHOWARTH - Thank you. I have similar thoughts. And also similar performance -9% in 2022 from a totally different selection of companies.
Thoughts from the Illisfolio. I have been fully invested throughout and at the end of 2022 have just about put in every penny I could find down the back of the sofa - short of a few months living expenses in the bank (I have some quite chunky dividends landing soon so that should not be a problem).
2022 was a game of 3 halves for me. After the sell off at the end of 2021 my portfolio recovered somewhat in Q1 giving me a totally misleading expectation for the coming storm.
Q2 and Q3 were relentless on a daily basis, as prices ground downwards leaving me down -30%. And mentally more like down 100% or more. Those were difficult days, with difficult decisions, as I exited a few stocks reinvesting what little I retreived in a more focused portfolio of larger holdings - my top 3 MS International (LON:MSI) Ecora Resources (LON:ECOR) and Macfarlane (LON:MACF) are just over 50% of my portfolio. With Zytronic (LON:ZYT) Vianet (LON:VNET) Airea (LON:AIEA) James Fisher And Sons (LON:FSJ) and Portmeirion (LON:PMP) these 8 stocks account for 84% of my portfolio. They are all companies that I have watched, researched and invested in for years - in some cases decades.
I did say in this place during Q4 that the relentless fall in my portfolio appeared to have bottomed out. That attracted some different views and robust responses! And the next downturn is always around the next corner. Also the market is not homogenous. Conditions in the mainly industrial/tech microcaps I invest in are generally different from most of the market. But its the performance of the companies I invest in that interests me most. During the year most of them have shown signs of improving while their share prices have been falling but that reversed somewhat in Q4 with a near 30% rise - leaving me still down 9%.
As well as the roller coaster ride through the year its been one of extremes between individual investments as this chart of the risers and fallers shows
The few holdings culled during the year are not shown. I said goodbye to longterm holdings like Eleco (LON:ELCO) and a couple of right shockers like Made.Com (LON:MADE) - yes I know, I'm disappointed in me as well! and Shield Therapeutics (LON:STX) - Will I never learn? I might just have done this time? It was a big lesson, delivered with a serious kicking!
The chart is not in order of holding size but also its not far off. The near 30% rise in Q4 is concentrated in a few of my largest holdings while the largest losses over the year are in my smallest holdings. That could just be luck? Or it could be down to the work I've put in during the difficult times over most of the year? Or both? 2023 may help to reveal which it is?
In particular the rise in MS International (LON:MSI) my largest holding is not unexpected, it was extremely undervalued, and arguably remains good value, but as always the timing has been a surprise and so there is definitely an element of luck in the loss for the year being -9% rather than -30% or worse that results from the timings!
It's definitely a psychological boost because I had seriously begun to doubt my abilities, despite my longterm track record.
So I am probably more positive entering 2023 than I've been for quite some while - it's interesting that my positive outlooks contrasts with a generally more negative outlook? That's probably because my largest holdings are quality companies, profitable, mainly but not all cash-rich, well invested in products and facilities with good prospects. Certainly some are neglected. Others very contrarian, but I expect them to prosper and think they are very undervalued by the market. With tailwinds of exchange rate, falling freight, semiconductor component and forward energy prices. I can't say the same for the market as a whole or the economy unfortunately.
It's clear that I don't know what the future holds. I do tend to be glass-half-full, but if the last year has taught me anything - it's to pay much more attention to the downside and capital preservation. It's not my winners that caused my problems!
Just my thoughts on saying good-riddance to 2022 in so many ways. I wish us all a happier and much more prosperous 2023 - thank you to all of you who have contributed in this place, you are an exceptional community, all of you, and I feel very much at home here,
cheers
Mark
My morning smallcap tweet: RNS stop and search
hVIVO (LON:HVO) Heiq (LON:HEIQ) Gfinity (LON:GFIN) Cyanconnode Holdings (LON:CYAN) Concurrent Technologies (LON:CNC) MaxCyte (LON:MXCT)
◄hVIVO (HVO)► wins £5.2m RSV human challenge study, will be booked in 2023-4. [SP=11.7 Cap=79m]
◄HeiQ (HEIQ)► warns FY-Dec rev $54-55m, c.20% below market expectations. Guides pretax loss $ 2.5m-3.5m. Blames China covid, world macro, high stocks at customers. Also guides FY23 below market guidance, Buys Tarn-Pur (a UK-based intellectual property company holding critical EU and UK regulatory registrations to sell elemental copper and elemental silver for use in disinfecting hygiene applications) for £850k in cash and shares. [SP=54.45 Cap=76m]
◄Gfinity (GFIN)► Athlos Tournament Platform to be integrated into games from leading global mobile game operator, Playgendary, [SP=0.52 Cap=7m]
◄CyanConnode (CYAN)► wins Indian order for 983k Omnimesh Modules plus metering HW and SW. No £££. [SP=14.5 Cap=35m]
◄Concurrent Technologies (CNC)► guides FY-Dec rev c.10% ahead of market expectations (£16m) and pretax at least in line (£0.1m). Order intake over £31m. [SP=71.9 Cap=53m]
◄MaxCyte (MXCT)► sells strategic platform license to Catamaran Bio, a biotechnology company developing novel, off the-shelf chimeric antigen receptor (CAR)-NK cell therapies. No £££. [SP=432.8 Cap=522m]
Morning Paul/Graham, any thoughts on hVIVO (LON:HVO) another contract win,trading update end of this month, a steady stream of contract wins over the last year & yet the share price has collapsed in that time, getting tipped now heavily in the press, be interesting to see what actual profits appear from these revenues
hVIVO (LON:HVO) has been pretty clear on profitability. 13-15% ebitda margins currently with scope to rise towards 20% over next few years. Trading confirmed as in-line.
95% of revenues for next year forecast are already contracted so I can easily see a beat coming on here. But even on just existing forecasts that will translate to ebitda of around £9m. They have net cash of circa £23m. Cash estimate to go up £5-6m so strong free cashflow generation after any investments in the business.
Market cap = £78m less £23m cash = EV £55m so on an EV/EBITDA multiple of 5 or 6 looks pretty miserly for a growing business that is a world leader/ best in class at what it does.
Simon Thompson from IC recently did a 22 page detailed note on the company in November last year. One of the comparisons was with other companies in the sector like Ergomed, Cambridge Cognition and Ixico and how favourably hVIVO compares to their valuations.
Thanks - that's interesting. I've heard the same comparison to Ergomed a few times but I'd hesitate to compare them directly. Yes, they are both CRO's but operate quite different spheres and as such the operating margin at Ergomed is a bit higher, which would likely command a premium in my view.
Don't get me wrong, I believe hVIVO (LON:HVO) is significantly undervalued and hold a long position in it accordingly. Brokers (if thats worth anything at all) have very different price targets of 21-44p so a wide spread of thinking.
For me personally I consider margins can comfortably get to the 17 or 18% level in the next couple of years. Revenues can get closer to £75m so I think they can generate £13m ebitda and drop £8-9m to net cashflows. Given the moat and quantity of data they produce they should be able to commercialise that quite significantly too but I leave that at zero for now.
I look for an EV/EBITDA multiple of 8 - 10. Current EV is £50m but should be £45m in a years time so I think they have room to treble which puts my target in the middle of the two brokers provided they continue to execute well. There is additional value in the business that they may be able to extract too as a bonus though.
Simon Thompson from IC recently did a 22 page detailed note on the company in November last year
Very helpful to know but I’ve been through all the November 22 issues and found no mention of hVIVO (LON:HVO) at all. did you mean Nov 21?
Very helpful to know but I’ve been through all the November 22 issues and found no mention of hVIVO (LON:HVO) at all. did you mean Nov 21?
It was on Alpha, Nov 17th.
timarr
Ah. That’s why I missed it. Thank you. Cancelled my Alpha sub last October owing to endless screens I could do for myself and not much else going for it - apart from that article. Poor timing on my part! Generally I avoid the small cap tips because of low liquidity at my position size but hVIVO (LON:HVO) looks surprisingly liquid for a sub £100m cap. I like the CRO space and hold Iqvia Holdings (NYQ:IQV) and Medpace Holdings (NSQ:MEDP) plus Ergomed (LON:ERGO.
Ah. That’s why I missed it. Thank you. Cancelled my Alpha sub last October owing to endless screens I could do for myself and not much else going for it - apart from that article.
If you're an IC subscriber Alpha is currently free to access - at least it still is for me ...
timarr
Alpha is currently free to access
Found it thanks. But sadly no access granted
An upbeat post close TU from Concurrent Technologies (LON:CNC) this morning